1. Introduction
The recent turmoil in global markets has led formerly enthusiastic supporters of globalization to re-examine its benefits to the economy and society (Bhagwati, Reference Bhagwati2013). The globalization phenomenon – which can be described as ‘an increase in the extent to which individuals and institutions transact or exchange with others based in nation states other than their own, or otherwise influence them through their economic and social behaviour’ (CEPR, 2002) – has received some blame for the dislocation following the financial crisis of 2008 and the more recent ‘Brexit’Footnote 1 vote. More recently, concerns have been raised regarding the distributional effects of globalization; however, questions regarding the effects of globalization on growth itself remain. The complex, multidimensional nature of globalization necessitates great care in properly accounting for its economic impact. One key area of interest in both the theoretical and empirical literature is the question: ‘Does globalization have a significant effect on economic growth?’ In a recent paper, Grossman and Helpman (2015) outline a variety of theoretical arguments linking globalization to economic growth such as: increased capital accumulation and foreign investment, international technological spillovers and knowledge diffusion, increased scale and competition forces that underlie globalization. The authors stress the need for empirical studies to further investigate the channels through which the effects of globalization might affect the economy.
This paper attempts to make some progress towards achieving this objective by focusing explicitly on the impact of the economic dimension of globalization and poses a variant of the above question, which is: ‘Do institutions moderate the effects of economic globalization on real economic growth?’ The term ‘moderate’ means ‘to interact with economic globalization in a way that discernibly or significantly alters globalization's effect on economic growth’. From an econometric viewpoint, the hypothesis of moderating effects of institutions on globalization is inferred through the use of interaction effects (Ozer-Balli and Sørensen, 2012). Understanding the dynamics of economic globalization is a worthy objective since among the three major dimensions of globalization (economic, social and political) the economic dimension is considered a central pillar of economic policy. Moreover, underlying economic forces often permeate the social and political spheres. Therefore, understanding the interactions between institutions and economic globalization is fundamental to grasping the broader impact of these two variables on the economy. Economic globalization is defined by Dreher (Reference Dreher2006) as: ‘being characterized by long distance flows of goods, capital and services as well as information and perceptions that accompany market exchanges’. By definition therefore, the clear and far-reaching policy relevance of economic globalization makes it an interesting candidate for the present study.
Institutions have been conceptualized by North (Reference North1981; Reference North1990) as ‘a set of rules, compliance procedures, and moral and ethical behavioural norms designed to constrain the behaviour of individuals’. The empirical literature has identified numerous institutions that influence economic growth, including governance, law enforcement, justice, regulations, tax administration, and institutions that manage monetaryFootnote 2 and fiscal policies. The seminal paper of Acemoglu, Johnson and Robinson (Reference Acemoglu, Johnson and Robinson2001) exemplifies the modern economic literature linking institutions to economic development and has spurred much research on the issue (Dollar and Kraay, Reference Dollar and Kraay2003; Góes, Reference Góes2016). The research has been aided and abetted by the emergence of datasets providing quantitative measures of institutional quality. Despite these parallel efforts linking institutions and globalization to economic growth, it is remarkable that little research exists exploring the interaction between institutions and globalization in jointly affecting economic growth. The goal of this paper is to make a contribution towards filling this void.
Careful theoretical arguments have been made identifying the many and varied channels through which globalization could potentially impact the economy. Recently, Grossman and Helpman (Reference Grossman and Helpman E2015) posit that globalization: (1) integrates peoples and cultures, facilitating the flow of knowledge across borders, leading to increased productive efficiency and innovation; (2) enables the integration of product markets via international trade, widening market possibilities while counterbalancing scale and competition effects; (3) affects the distribution of input and output prices, which in turn affects the costs of innovations and the relative attractiveness of alternative directions for industrial research; and (4) promotes interactions that have implications for technological diffusion. The authors state, however, that ‘the empirics have not kept pace’ in verifying the relative importance of these channels. Interestingly, institutions have also been shown to affect the channels mentioned by Grossman and Helpman (Reference Grossman and Helpman E2015) and could therefore possibly strengthen or dampen globalization's effect (Anderlini et al., Reference Anderlini, Felli, Immordino and Riboni2013; Chang et al., Reference Chang, Kaltani and Loayza2009; Hartman et al., Reference Hartmann, Guevara, Jara-Figueroa, Aristarán and Hidalgo2017).
One key consideration in exploring the effects of economic globalization on economic growth is whether the expected effects operate through changes or levels. The question ‘Are more economically globalized countries expected to grow faster?’ explores the hypothesis that the level of globalization, rather than the rate of change in the level of globalization, is the proximate cause of real economic growth. Alternatively, one could hypothesize that changes in the level of globalization are the important causal factor driving real growth. A related issue is whether the effect of globalization, however specified, is expected to produce a long- or short-run impact on real GDP growth. Ideally this ambiguity should be settled by appealing to the theoretical literature. The literature however is not explicit on the first issue. The earliest theories of trade outline the nature and elucidate the potential sources of the gains from specialization and trade, but do not specify how trade openness or globalization should be measured. Therefore, ambiguity regarding whether variations in globalization levels or differences should matter for growth continues (Grossman and Helpman, Reference Grossman and Helpman E2015; Potrafke, Reference Potrafke2015; Romer, Reference Romer2010). This paper adopts an agnostic approach; allowing for either specification.
Moreover, within the context of neoclassical models of the Solow–Swan tradition, one might expect a change in the level of globalization to produce a medium-run growth boost due to realizing gains from greater efficiency, but in the long run countries would grow in line with their long-run growth path. Under a variety of new growth models, however, levels of openness could also have long-run effects on a economy's growth path – more open economies would grow faster, for reasons already stated. By this same token, one can infer that variations in the changes in globalization levels over time (first-differenced globalization) could have growth-related implications through the rate of accrual of the gains from trade due to scale and knowledge- or technology-related spillover effects. Potrafke (Reference Potrafke2015) notes that, although the latter channel has not been sufficiently distilled in the theoretical literature, globalization in both the levels and rates of growth have been used as explanatory variables in empirical models. Sampson (Reference Sampson2016) exemplifies a recent theoretical contribution on this issue.
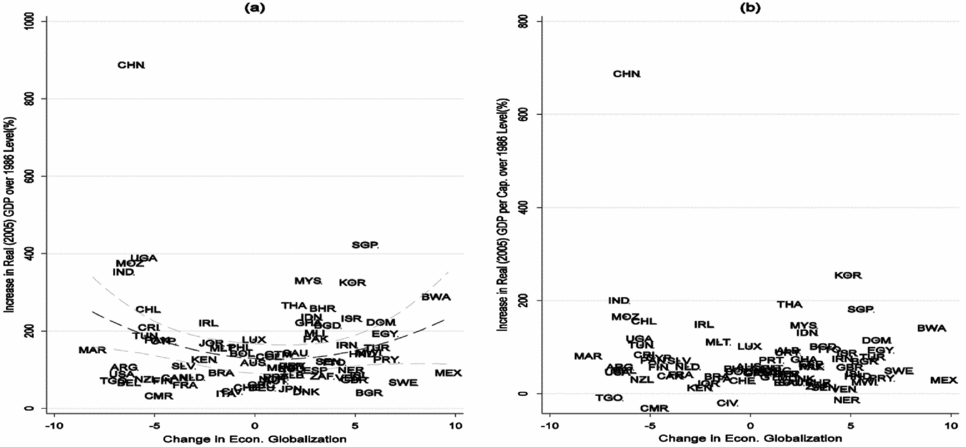
Figure 1 shows the relationship between changes in economic globalization and real GDP between the years 1986 and 2010. Economic globalization is measured using the KOF index (Dreher, Reference Dreher2013). The choice of globalization index is an important consideration as stated by Potrafke (Reference Potrafke2015), who emphasizes the multi-dimensionality of both the KOF index and the concept of globalization as one desirable feature of the index. Another advantage is the coverage of the index, since it covers 207 countries over the period 1970–2013. On the other hand, the measurement of trade openness – one component of the economic globalization sub-index – of the KOH globalization index has been criticized by Pritchett (Reference Pritchett1996). Moreover, Potrafke (Reference Potrafke2015) contains a more general discussion of the shortcomings of a variety of globalization measures. Despite these shortcomings, the theoretical appeal of the index, its broad coverage over the review period and its wide applicability and use make it suitable for the current analysis.
Economic Progress and Globalization: panel (a): Scatterplot showing the divergent relationship between percent change in real GDP (measured in 2005 values) and the change in economic globalization as measured by the Dreher (2013) Index between the years 1986 and 2010. Figure 1, panel (b): Scatterplot showing the relationship between changes in real GDP per capita (measured in 2005 values and change in economic globalization as measured by the Dreher (2013) index. Source: KOH (Dreher, 2013) and World Development Indicators (WDI).3

In panels (a) and (b) of the figure, the y-axis measures the change in total real value of GDP and change in real GDP per capita between 1986 and 2010 respectively. The x-axes of both panels measure the change in economic globalization as measured by the Dreher (Reference Dreher2013) index. Both panels support the notion that a highly heterogeneous relationship exists between changes in real economic growth (however measured) and changes in economic globalization between countries. Interestingly, countries like Morocco (MAR), India (IND), China (CHN) and the United States have de-globalized economically over the period of interest (1986–2010). This observation highlights the complex dynamics of globalization. A more detailed analysis reveals that while in the cases of China and the USA, social globalization (not shown in the figure) has experienced strong trend increases over the period of interest, economic globalization has experienced periods of strong decline, which was the case post-global financial crisis in 2008. In contrast, Mexico (MEX), Botswana (BWA) and Sweden (SWE) represent counterexamples, increasing in economic globalization over the period of interest.Footnote 4
Another interesting observation from Figure 1 is that there is no simple linear relationship between the level of economic growth (however measured) and the change in globalization. Among countries that have become more economically globalized, Botswana (BWA), Singapore (SGP) and Korea (KOR) have experienced notable increases in real GDP over the period. On the other hand Bulgaria (BGR) and Sweden (SWE), despite increased openness, have not experienced such high growth rates. Among countries that have de-globalized China (CHN), Uganda (UGA) and India (IND) have experienced significantly more positive economic growth results than Morocco (MAR), Argentina (ARG) and the United States of America (USA). Interestingly, the variation in economic growth outcomes across countries decreases markedly in the neighbourhood of the ‘zero’ change in economic globalization mark on the x-axis towards the centre of panels (a) and (b). This result implies that there is a lower dispersion in growth outcomes for countries with very small positive or negative changes in their levels of globalization over the period. The apparent heteroscedasticity conditional on the change in economic globalization in Figure 1 may imply that policies aimed at increasing or decreasing the degree of economic globalization within an economy involve risks directly related to the degree of globalization. Removing China from the sample, the spread appears relatively greater in the region of the panels depicting a greater degree in global integration. Panel (b) also reflects the within-sample heterogeneity and also demonstrates that when population growth rates are taken into account, the graphical pattern of heteroscedasticity conditional on the degree of change in economic globalization observed in panel (a) is less obvious.
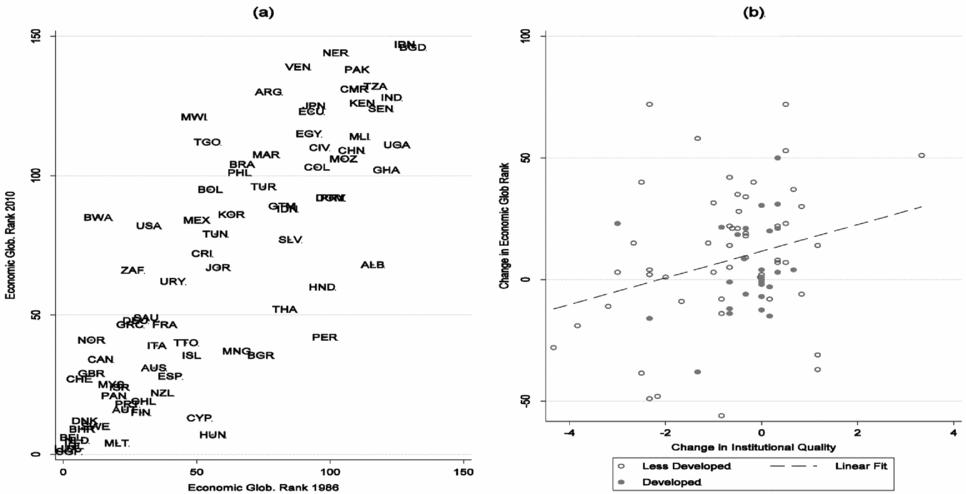
Panel (a) of Figure 2 highlights the changing trends in economic globalization over the review period. The scatterplot plots the global rank of each of the 82 countries in 1986 against the analogous ranking in 2010. Note that countries were ranked using the full KOH (2013) index, which also takes into account political and social dimensions of globalization. The panel reveals that there is a positive and direct relationship between the 1986 and 2010 rankings. A simple interpretation of this finding is that there is a tendency for highly globalized countries in 1986 to remain highly globalized towards the end of the sample period. This can be confirmed by the fact that most developed countries are clustered near to the origin, indicating a high rank in both 1986 and 2010. Panel (a) reveals, however, that relatively greater ‘churning’ within globalization rankings tends to occur between countries ranked in the 50 to 100 range of the rankings; a region comprised of less developed countries. The figure also reveals that the period has seen significant reversals in rankings for countries such as USA, Botswana (BWA) and South Africa (ZAF). The converse is true for Peru (PER), Mongolia (MNG), Bulgaria (BGR) and Thailand (THA), which have all become markedly and relatively more globalized.
Economic Globalization and Institutional Quality:panel (a): Scatterplot showing the positive relationship between overall (international) country rank in globalization in 1986 and globalization country rank in 2010. Figure 2, panel (b): Scatterplot showing the relationship between changes in overall (international) economic globalization rank and changes in institutional quality between 1986 and 2010. Here, institutional quality is measured as the simple average of the score for civil liberty (Freedom House Dataset), political rights (Freedom House Dataset) and law and order (ICRG). Sources: Freedom House Dataset,5 International Country Risk Guide (ICRG) Dataset;6 KOF Index: see Dreher, 2013.

Panel (b) of Figure 2 depicts a scatterplot of the change in country rank of economic globalization between the years 1986 and 2010 and the change in institutional quality. There appears to be a positive relationship between both variables – implying that countries that have moved up the rankings on the globalization index – that have increased their relative levels of globalization – tended also to have improved the quality of their institutions. This is an interesting finding, which suggests that there may well be some interaction between changes in institutional quality and globalization.
To understand the positive relationship depicted in the diagram it is important to note that, given the coding of the institutional variables:Footnote 7 (1) political rights (PR) (2) civil liberties (CR) and (3) law and order (LO) – negative changes in the quality of institutions as measured by the new index (average) represent an improvement in the quality of institutions. Studying the figure more closely it becomes apparent that the greatest gains in institutional quality have been made by developing countries. On the other hand, the sample also captures relatively developed countries such as Cyprus (CYP), Malta (MLT) and South Korea (KOR), which experienced significant improvements in institutional quality between 1986 and 2010. Clearly, the plot cannot establish a causal relationship between the institutional change and change in globalization variables; the nature and direction of causality and the whether their joint distribution impacts growth outcomes are all areas of interest, which this paper will now explore. One should note however that while there is a hint of positive relationship between the two variables, Figure 2, panel (b) suggests a relatively weak one.
The available economic literature on the effect of institutions on economic growth has established a positive relationship between institutions and economic growth (Acemoglu and Robinson, Reference Acemoglu and Robinson2010; Iqbal and Daly, Reference Iqbal and Daly2014; Mauro, Reference Mauro1995; Rodrik et al., Reference Rodrik, Subramanian and Trebbi2004). Sceptics of the institutional view (Sachs, Reference Sachs2003) emphasize the relative importance of ecology and geography over institutions in economic development. However, Nunn and Puga (Reference Nunn and Puga2012) have taken a more nuanced stance, arguing that geography has historically played a key role in shaping institutions themselves and that this fact directly explains the income differences between countries. Regardless of the variant of the argument, the link between institutions and growth has been well established. In particular, the economic literature has identified numerous institutions that affect economic growth such as governance, law enforcement, justice, civil liberties, regulations, tax administration and institutions that manage monetary and fiscal policies. Given the wide variety of institutions that have been found to have economic importance it is perhaps striking that the channels through which these institutions affect economic growth have not been fully explored.
Moers (Reference Moers1999) has posited that a broader measure of institutions has the strongest effect on economic growth. Corroborating and extending this earlier result, Acemoglu et al. (Reference Acemoglu, Johnson and Robinson2001; Acemoglu and Johnson, Reference Acemoglu and Johnson2005; Acemoglu and Robinson, Reference Acemoglu and Robinson2008) show that the quality of institutions has a stronger effect on long-term than on short-run growth. Meón and Weill (2010) present evidence that institutional factors influence total factor productivity and that countries with better institutions tend to exhibit higher productivity. Empirical studies investigating the link between institutions and economic growth have also tended to use instrumental variable techniques to investigate the relationship between institutions and economic performance (Acemoglu et al., Reference Acemoglu, Johnson and Robinson2001; Rodrik et al., Reference Rodrik, Subramanian and Trebbi2004). A similar approach is adopted within this paper. Unlike the strategies employed in the aforementioned papers, however, an intuitive, two-stage approach is employed to arrive at a proxy for institutional quality. The process of finding an appropriate instrument for institutional quality adopted here involves (1) a simple correlation analysis to identify summary institutional quality measures and then (2) applying dimensionality reduction techniques using key institutional variables selected from the correlation analysis in the first stage in order to generate the instrument.
Section 2, which follows, outlines the empirical strategy employed within this study to test whether institutions interact with economic globalization to affect economic growth. In Section 3, important issues such as the data sources used for the analysis and how the variables are measured are discussed in greater detail. Summary descriptive statistics and correlation analysis results are also presented in Section 3, after which estimation results for fixed effect and dynamic panel estimation are presented in Section 4. Section 5 then outlines the conclusions and policy implications of the paper.
2. Empirical strategy
Estimation
In order to perform an empirical test of the hypothesis that institutions moderate the effect of economic globalization, this paper adopts the generalized methods of moments (GMM) method. According to Roodman (Reference Roodman2009a), two-step system GMM estimation enables panel data model estimation in situations in which the data-generating process is dynamic, as is the case with economic growth, where we expect past realizations of the dependent variable to contain information about its contemporaneous values. Moreover the GMM estimator has desirable properties in situations where there may be arbitrarily distributed country fixed effects as one is bound to expect in country panel datasets. Crucially also, the GMM estimator allows for endogeneity among the regressors, while providing the additional flexibility of allowing for estimation under circumstances where there is a possibility that regressors within the model may be predetermined but not strictly endogenous. One added feature of the system GMM approach is that it obviates the need to find instrumental variables external to the model to control for the endogeneity. Given these merits of the system GMM approach, the estimation method is applied to the model and data since it addresses the major empirical issues associated with cross-country datasets. Formally, therefore, the empirical model estimated in this paper can be written as:
 $$\begin{eqnarray}
{\hbox{\it Gr}}{o_{i,t}} &=& {\gamma _0}{\hbox{\it initGD}}{P_i} + {\gamma _1}Gr{o_{i,t - 1}} + {\gamma _2}{\hbox{\it Ins}}{t_{it}} + {\gamma _3}Glo{b_{i,t}} + {\gamma _4}{\hbox{\it Ins}}{t_{it}}{\rm{*}}\, {\hbox{\it Glo}}{b_{i,t}} \nonumber\\
&&+ \gamma _4^{\rm{'}}C{V_{i,t}} + {\rm{\ }}{u_i} + {\rm{\ }}{v_{it}}
\end{eqnarray}$$
 $$\begin{eqnarray*}
i = 1,2, \ldots 82\quad \quad {\rm{and}}\quad \quad t = 1,2, \ldots 5
\end{eqnarray*}$$
In the equation of the dynamic model equation displayed in equation (1) – the dependent variable Gro i, t refers to real GDP per capita growth in country i at time t. Note that i runs from 1 to 82 reflecting the fact that there are 82 countries in the sample that are individually listed in Table 1. The time index, on the other hand runs from 1 to 5, since 5-year averages of annual data collected for each country over the period 1986–2010 were used. The initGDP variable refers to the log of initial GDP per capita (note that this is real GDP per capita at 2005 prices divided by population in year 1 of each sub-period).The time index represents 5-year averages of the time series data collected for each country between the years 1986 and 2010. The regressor Gro i, t − 1 reflects the dynamic nature of the model as it is the lagged dependent variable for each country and time period. Year dummy variables are included within our regression specifications in order to control for temporal effects. The Windmeijer (Reference Windmeijer2005) finite sample correction is employed in all two-stage GMM specifications in order to mitigate the downward bias of two-step GMM standard errors.
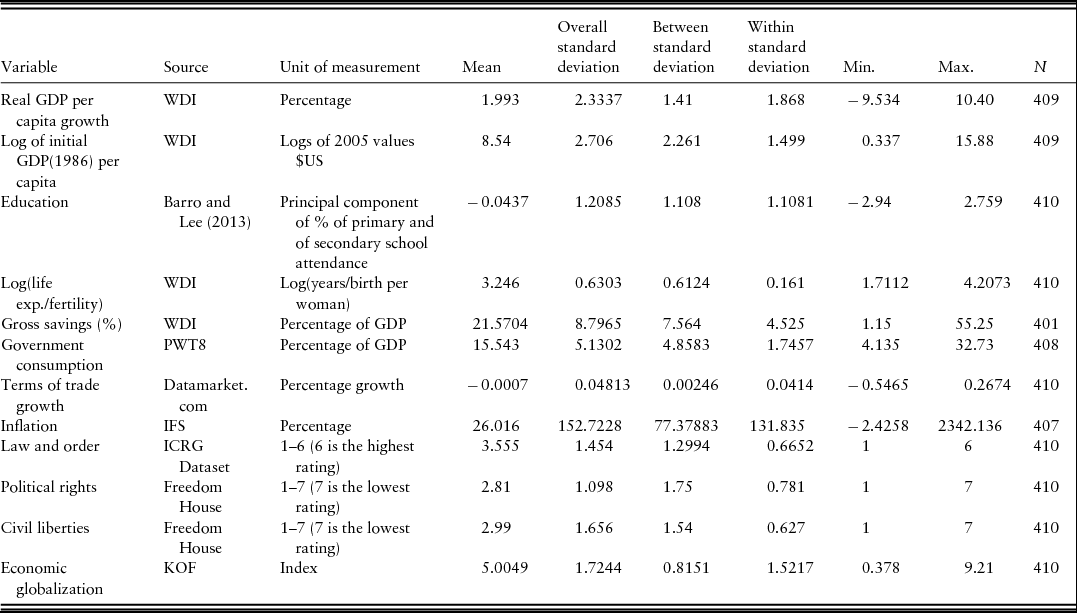
Variable descriptions, summary statistics and list of countries

Developed countries: AUS = Australia, AUT = Austria, BEL = Belgium, CAN = Canada, CHE = Switzerland, CYP = Cyprus, DEU = Germany, DNK = Denmark, ESP = Spain, FIN = Finland, FRA = France, GBR = United Kingdom, GRC = Greece, IRL = Ireland, ISL = Iceland, ITA = Italy, JPN = Japan, KOR = Korea, LUX = Luxembourg, MLT = Malta, NLD = Netherlands, NOR = Norway, NZL = New Zealand, PRT = Portugal, SGP = Singapore, SWE = Sweden, USA = United States of America.
Less developed countries: ALB = Albania, ARG = Argentina, BGD = Bangladesh, BGR = Bulgaria, BHR = Bahrain, BOL = Bolivia, BRA = Brazil, BWA = Botswana, CHL = Chile, CHN = China, CIV = Cote d'Ivoire, CMR = Cameroon, COL = Colombia, CRI = Costa Rica, DOM = Dominican, ECU = Ecuador, EGY = Egypt, GHA = Ghana, GTM = Guatemala, HND = Honduras, HUN = Hungary, IDN = Indonesia, IND = India, IRN = Iran, ISR = Israel, JOR = Jordan, KEN = Kenya, MAR = Morocco, MEX = Mexico, MLI = Mali, MNG = Mongolia, MOZ = Mozambique, MWI = Malawi, MYS = Malaysia, NAM = Namibia, NER = Niger, PAK = Pakistan, PAN = Panama, PER = Peru, PHL = Philippines, PRY = Paraguay, RUS = Russia, SAU = Saudi Arabia, SEN = Senegal, SLV = El Salvador, TGO = Togo, THA = Thailand, TTO = Trinidad, TUN = Tunisia, TUR = Turkey, TZA = Tanzania, UGA = Uganda, URY = Uruguay, VEN = Venezuela, ZAF = South Africa.
Sources: Barro and Lee, Reference Barro and Lee2013; Datamarket;Footnote 9 Freedom House: see Figure 2; IFS Dataset;Footnote 10 KOF Index: see Dreher, Reference Dreher2013; Penn World Table (PWT8);Footnote 11 WDI: see Figure 1.
Institutions and economic globalization
The Instit and Glob i, t variables in equation (1) capture the effect of the quality of institutions on real economic growth using institutional and globalization variables respectively. Note that the institutional quality variable enters the specification of equation (1) in levels. This specification tests the hypothesis that the level or degree of institutional quality affects real per capita economic growth. The actual implementation of the model will also include among the regressors changes in institutional quality: that is, the first difference of Instit that is included as a robustness check of the specification, making allowance for a test of the hypothesis that changes in institutional quality, is an additional causal factor driving economic growth. Note however that in a practical sense changes in institutional quality would reasonably, a priori, be expected to occur gradually.
Importantly, two datasets are combined to arrive at an estimate for the instrument for the set of institutional variables used in the study – the ICRG dataset and the Freedom House dataset. The political risk table of the ICRG comprises 12 institutional measures that affect the political risk rating of a country. These indicators are: government stability, socio-economic conditions, investment profile, internal conflict, external conflict, corruption, military in politics, religious tensions, law and order, ethnic tensions, democratic accountability and bureaucracy quality. After a correlation analysis of the 12 variables from the ICRG dataset, the law and order (LO) index is retained since, LO is highly correlated with most other variables. In particular, LO's pairwise correlations with socio-economic conditions (0.61), internal conflict (0.71), corruption (0.68), military in politics (0.70), and bureaucratic quality (0.71) are all high and significant. This suggests that including LO ensures that information about the various other variables highly correlated with the index will also be included – by extension- within the empirical model. The empirical specification also includes among the institutional variables civil liberties (CL) and political rights (PR), which are taken from the Freedom House dataset. The CL and PR indices were included in the specification to ensure that the extent of protection of individual freedoms and political involvement from government restriction and encroachment in each country- period was also taken into account. Moreover, in a recent paper by Alfonso-Gil, Lacalle-Calderón and Sánchez-Mangas (Reference Alfonso-Gil, Lacalle-Calderón and Sánchez-Mangas2014), the authors provide persuasive empirical evidence that movements towards higher levels of civil liberty between 1850 and 2010 are associated with higher economic growth rates.
To capture the variations in globalization, the 2013 version of the well-known KOF Index of globalization dataset by Dreher (Reference Dreher2006) is employed. The economic globalization index from the KOF dataset that is used is comprised of two major components (1) data on actual flows; such as trade flows, foreign direct investment (the sum of both inward and outward FDI), portfolio investments and income payments to foreign nationals; (2) data on restrictions on flows such as hidden import barriers, mean tariff rate, taxes on international trade and capital account restrictions. According to the author (Dreher, Reference Dreher2006), the rather broad-based approach is meant to capture the degree of integration within the global economy. Both institution and globalization proxies are treated as standard endogenous variables within the two-step GMM estimation framework (Roodman, Reference Roodman2009a).
Additional control variables (CV i, t ) are added to the model in order to capture other factors, which are noted in the literature to be related to economic growth. In particular, variables such as primary- and secondary-level educational attainment are added to capture the effect of human capital. Health, longevity and demographic factors are captured via the two variables: life expectancy and fertility rates. Gross savings as a percentage of GDP along with inflation are also included, with the latter variables serving as a proxy of financial stability. In addition, the share of government spending relative to GDP is also included, in line with the recent academic and policy debate regarding the possible effects of the size of government and government spending on economic growth outcomes. The sources of all variables as well as their descriptive statistics are presented in Table 1. The descriptive statistics are discussed more fully in the following section.
3. Data, measurement and sources
Data on globalization and institutions are combined to form a panel dataset of 82 countries spanning the period 1986–2010, comprised of 5-year period averages of the variables. Table 1 contains a list of the countries included within the sample along with a brief description of the variables and their summary statistics.
Real GDP per capita values for the countries within the dataset were obtained from the World Development Indicators (WDI) dataset. The log of initial GDP per capita was generated by combining the 1986 value of real GDP from the WDI dataset and population figures from the same source. The gross savings rate, life expectancy and fertility variables were also sourced from the WDI. The latter two variables have featured heavily in the growth literature as key determinants of economic growth (see Weil, Reference Weil, Aghion and Durlauf2014 for a comprehensive review of the growth literature). For estimation purposes, life expectancy and fertility rates are combined (life expectancy/fertility) and logged to capture the balance in demographic changes within a country. A higher value of this variable indicates a greater degree of demographic transition.
LO, PR and civil liberties (CL) are the variables used to capture institutional quality. LO – obtained from the ICRG dataset – takes values between 1 and 6 (inclusive), with 6 representing the highest degree of law and order.Footnote 8 CL and PR, both obtained from the Freedom House dataset, are both measured on a scale ranging from 1–7 (inclusive) with countries enjoying the highest levels of CL and PR being ranked at 1, while countries with poor CL and PR records are ranked closer to 7.
Inflation data from the International Financial Statistics (IFS) dataset are included among the regressors as a proxy for financial stability. Primary school attainment levels – measured as a proportion of the population – are sourced from the Barro and Lee dataset (Reference Barro and Lee2013) and capture the notion that human capital (or skill levels) may affect economic growth: a salient point ubiquitously made in both the theoretical and empirical literature (see Benos and Zotou, Reference Benos and Zotou2014 for a relatively recent review). Also included among the variables are terms of trade growth, sourced from the Datamarket datase (which provides greater coverage than the WDI dataset). Terms of trade are linked to economic growth outcomes through arguments related to the Prebisch–Singer HypothesisFootnote 12 (Prebisch, Reference Prebisch1950; Singer, 1950) or through the Harberger–Laursen–Metzler effect (Harberger, Reference Harberger1950; Laursen and Metzler, Reference Laursen and Metzler1950; Misztal, Reference Misztal2010).
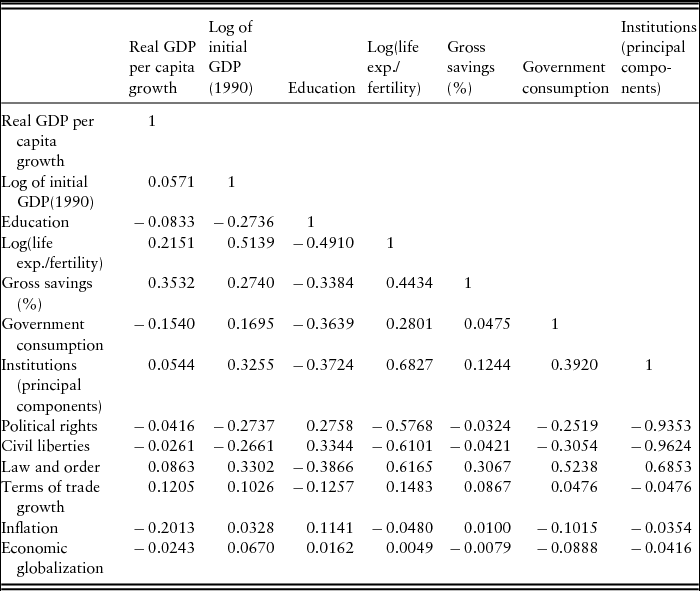
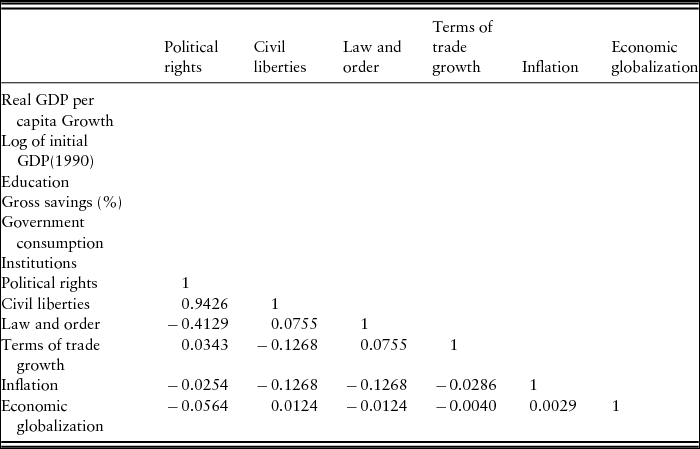
Tables 2a and 2b depict pairwise correlations between the variables included within the empirical model. In general, the correlations have the expected signs. For example, there is a positive relationship between economic growth and the savings rate; a result axiomatic of many theories of economic growth and development. Similarly per capita real economic growth is also positively correlated to terms of trade growth and the demographics variable (life expectancy/fertility rate). This is an interesting finding relating to Przeworksi (Reference Przeworski2000) who presents some evidence that demographic factors affect economic growth. Przeworksi (Reference Przeworski2000) links this finding to democratic institutions; suggesting that democracies have appreciably lower birth rates (and higher life expectancy), lower population growth and thus, ceteris paribus, higher growth of GDP per capita explained by higher levels of human capital and female empowerment. More recently, An and Jeon (Reference An and Jeon2006) also find evidence of a relationship between demographic variables and economic growth.
Pairwise correlations

Pairwise correlations (continued from Table 2a)

The inflation rate – which serves as a proxy for financial stability – is negatively related to real economic growth per capita and foreign direct investment. As expected there is a strong relationship between initial GDP and the demographic variable indicating the expected strong and positive correlation between high life expectancy and GDP per capita.
On the other hand, Tables 2a and 2b also reveal seemingly counterintuitive correlations. For example, Table 2a reveals a negative correlation between the proportion of the population attaining at least a primary level of education and per capita GDP growth, which is the opposite result to what would be expected in the long run. This pairwise correlation, however, is less than 1%. Interestingly too, there is a negative relationship between both PR and CL, and real GDP. A negative correlation can also be observed between the following institutional variables: initial GDP, the demographic variable, government consumption and FDI. This may seem counterintuitive but is merely a function of how the variables are measured. Recall that these variables are measured with a score of 1 representing a high degree of civil liberty and political freedom. Recalling this fact, the correlations are consistent with expectations.
Of far greater concern is the unacceptably high correlation between PR and CL in the estimation sample (0.94). Including variables with such high correlations could lead to a range of problems ranging from wrong signs on coefficient estimates to lack of statistical power. This problem is overcome by employing the principal components (PCA) method in order to extract the principal component with the highest variance, orthogonal to all institutional variables resulting in one composite institutional quality variable proxy. The composite variable is henceforth referred to as ‘institutions’, and is included among the regressors in the estimation of equation (1). After applying the PCA methodology, it is discovered that the first principal component generated from PCA analysis captures 76.1% of the total variance, and is therefore used as the institutional quality proxy. For inferential purposes, it should be noted that the institutions proxy has a high correlation with CL (-0.962), PR (-0.935) and LO (0.686).
4. Results
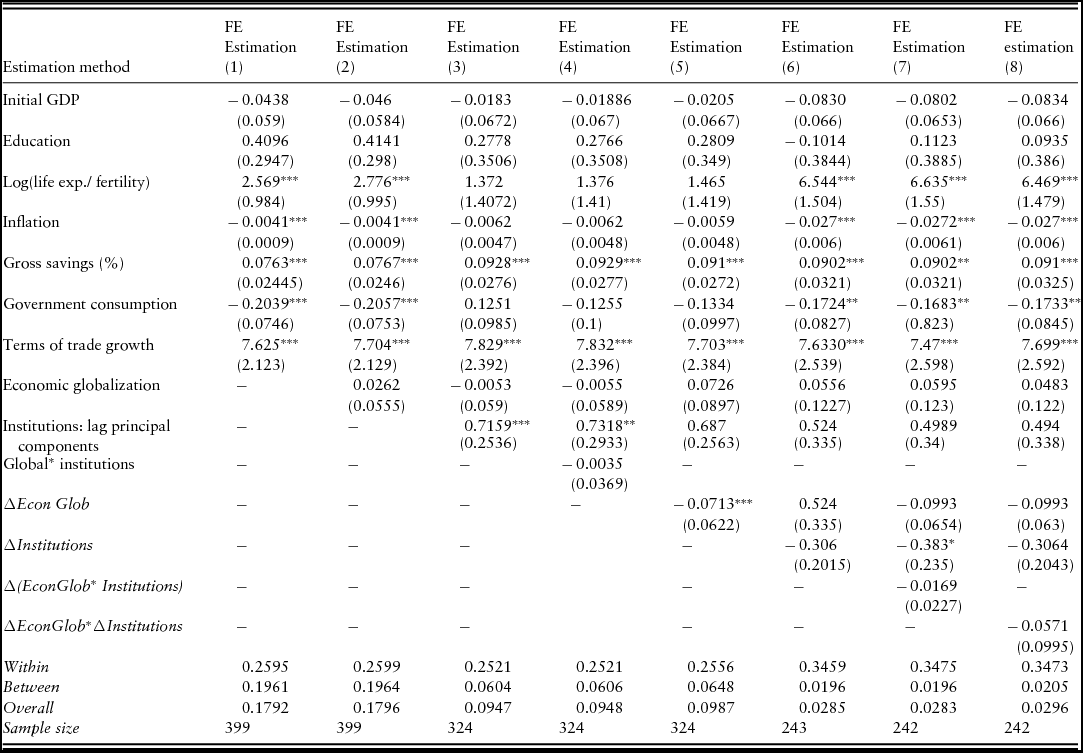
Table 3a below presents the estimation results for the empirical model estimated using the panel fixed effects method and including the composite ‘institutions’ variable. The dependent variable across all regressions is real GDP per capita growth. Column 1 of the table displays coefficient estimates of the baseline empirical model: estimated without economic globalization and proxies for institutions, and without interaction effects between these variables.
Fixed effects estimates: full sample

*** statistically significant at the 1% level; ** statistically significant at the 5% level; * statistically significant at the 10% level.
A review of the signs of the coefficients in Column 1 reveals that they accord with a priori expectations. The coefficient on gross savings rate is highly statistically significant, indicating that higher savings rate positively affects growth. This result is consistent with both the ‘neoclassical’ and ‘new growth’ flavours of the theoretical models of economic growth. Similarly, the coefficient on terms of trade growth is also positively related to real GDP per capita growth and is statistically significant. The coefficient on the demography variable, specified as the log of life expectancy divided by fertility rates, is also positive and significant. In general, we expect more developed countries to undergo (or to have undergone) demographic transition. This corroborates aforementioned findings by Przeworksi (Reference Przeworski2000) and An and Jeon (Reference An and Jeon2006).
On the other hand, the results of the fixed effect panel regression in Column 1 reveal that higher levels of government spending and inflation (which represents a proxy for financial instability) have a negative and statistically significant effect on real GDP per capita growth. In contrast, education does not have a statistically significant effect on real GDP per capita growth. The estimation results depicted in Column 2 of Table 3a reveal that adding economic globalization to the model does not change the sign and significance of the variables included in specification presented in Column 1. Moreover, the coefficient on the newly included regressor is not statistically significant, implying that there are limited effects of economic globalization on the real GDP per capita growth within our sample.
The specification of the model in Column 3 includes, along with the globalization variable, the proxy for institutional quality among the regressors. The institutional quality variable is entered with a lag to capture the idea that changes in institutions can have a delayed impact on the economy. Note the loss of one observation for each country due to the use of the lag of the institutions variable. Column 3 reveals that the institutions variable (as measured by the first principal component of all the institution variables) is positively related to real GDP per capita growth. The high level of statistical significance of the coefficient reinforces a priori expectations that good institutions are favourable to economic growth. Recall that the ‘institutions’ variable was constructed such that it is positively related to the rule of law and negatively related to CL and PR. It can therefore be inferred from the results that, ceteris paribus, strengthening institutions in favour of the rule of law has had a positive effect on real GDP per capita growth.
The specification presented in Column 4 includes a multiplicative interaction term derived by multiplying the level of globalization by the institutional quality proxy. The statistical insignificance of the resulting coefficient suggests that institutional quality and economic globalization do not interact to affect real GDP per capita economic growth within the sample. In Column 5, the additional variable, change in globalization (∆Econ Glob), attempts to capture the possible effects of the first difference of economic globalization on real per capita GDP growth. The variable is both negative and statistically significant at the 1% level of significance, implying that, in general, countries advancing at a faster rate towards globalization have possibly experienced lower growth levels. However, this result is not robustly supported across the remaining specifications in which (∆Econ Glob) is included.
Columns 6–8 of Table 3a add the variables (1) ∆Institutions (2) ∆(EconGlob* Institutions) and (3) ∆EconGlob*∆Institutions respectively. None of these variables, when added to the set of regressors, are statistically significant in explaining real GDP per capita growth. Both the ∆Institutions variable and interaction effects – however specified – are statistically insignificant. Notably, the overall R-squared for the regressions including the new variables are relatively smaller in magnitude than the R-squared values of displayed in Columns 1–5. While results of Columns 5 suggest a negative effect on changes in globalization on real per capita growth the low R-squared value suggests poor explanatory power. In sum, therefore, fixed effect regression analysis provides very little evidence that institutions interact with economic globalization to affect real GDP growth.
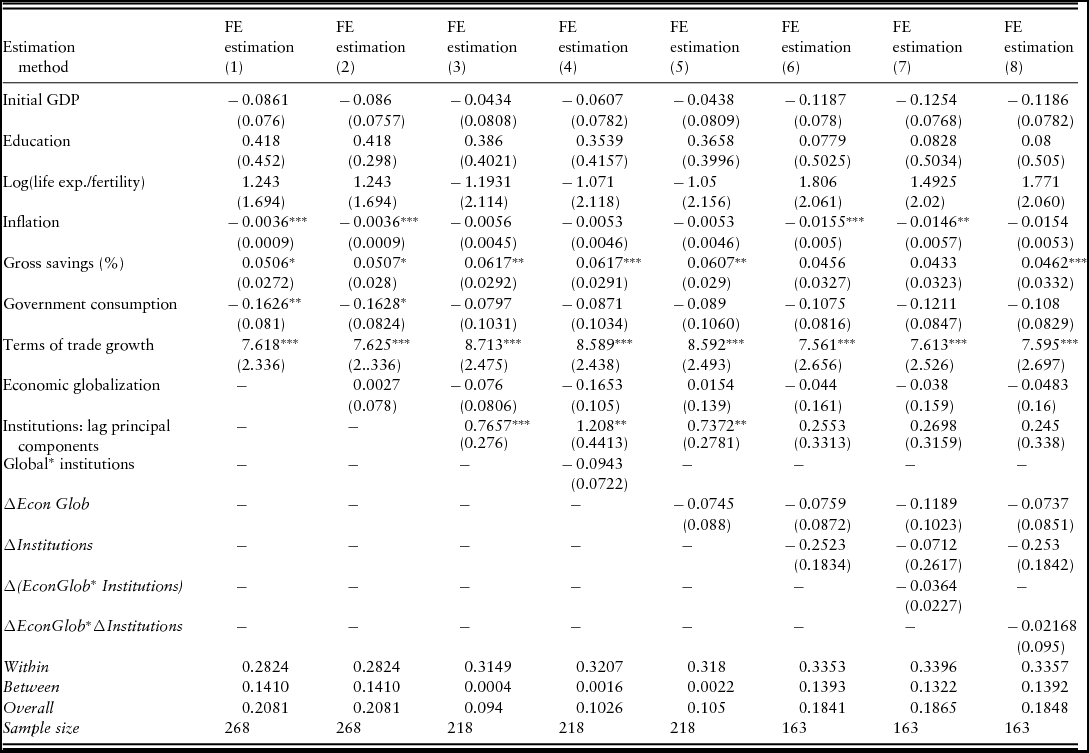
Table 3b mirrors the regression specifications shown in Table 3a. However, Table 3b restricts the dataset to developing countries only. A list of developing countries within the sample is depicted in Table 1 and is based on the International Monetary Fund (IMF) classification. The estimates of the most naïve specification presented in Column 1 of Table 3b reveal that savings and terms of trade growth are both statistically significant and positively related to real per capita GDP growth, while inflation and government spending are both statistically significant and have the opposite effect, fully corroborating results from Table 3a on the full dataset.
Fixed effects estimates: developing country sub-sample

*** statistically significant at the 1% level; ** statistically significant at the 5% level; * statistically significant at the 10% level.
Qualitatively, the statistical importance of the demographic variable in affecting the real GDP per capita outcome differs between the full and developing country sub-sample. Recall that Columns 1, 2, 6, 7 and 8 of Table 3a depict positive and statistically significant coefficients for the demographic variable, which are in stark contrast with the results of Table 3b. This result suggests that variations in life expectancy relative to fertility rates were not influential in explaining growth outcomes in developing countries over the review period. Furthermore, none of the coefficients on globalization-related variables are statistically significant in Table 3b. This is fairly consistent with the result in Table 3a. Gross savings as a percentage of GDP are statistically significant and positively signed in the restricted sample of developing countries across most specifications of Table 3b, as in Table 3a.
Higher savings rates therefore support growth in both developed and developing countries. Similarly, the negative sign on the government consumption coefficient across all specifications in Table 3b matches closely earlier findings in Table 3a. The institutional quality variable is again statistically significant and positive in Columns 3 and 4 of Table 3b, mirroring the earlier results. The coefficient is also robustly significant when the change in economic globalization variable is added in Column 5, implying that institutional quality is a marginally more crucial factor in determining growth outcomes in less developed economies.
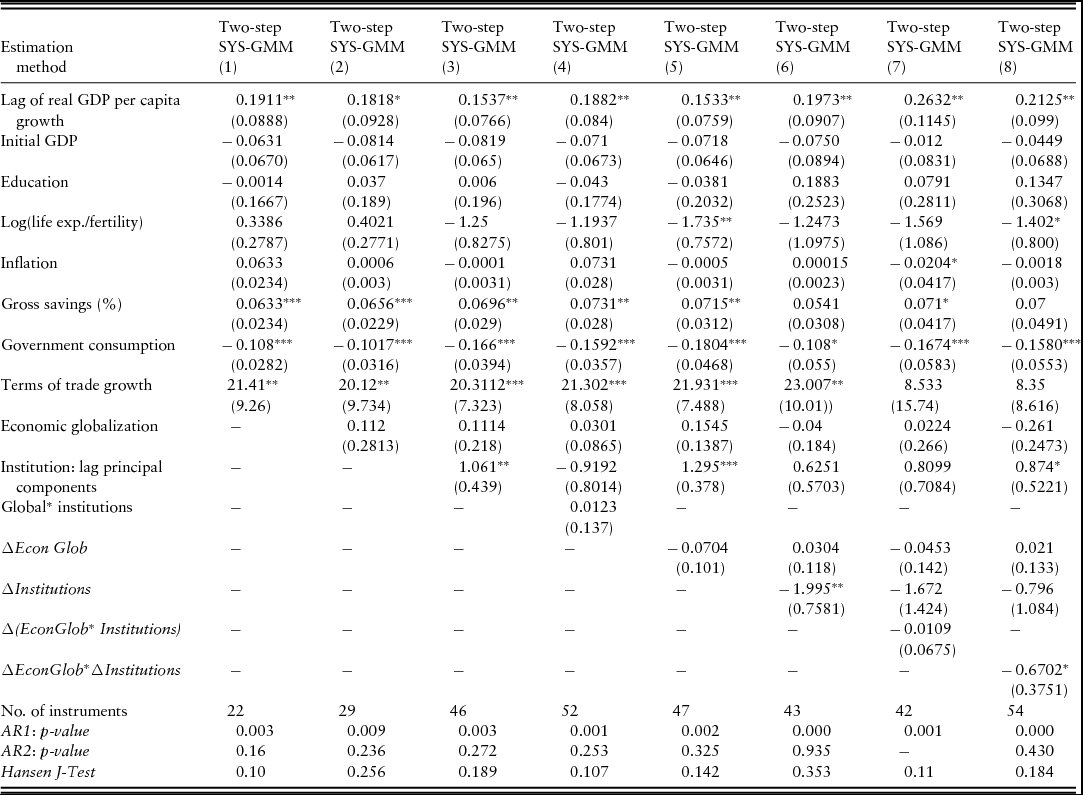
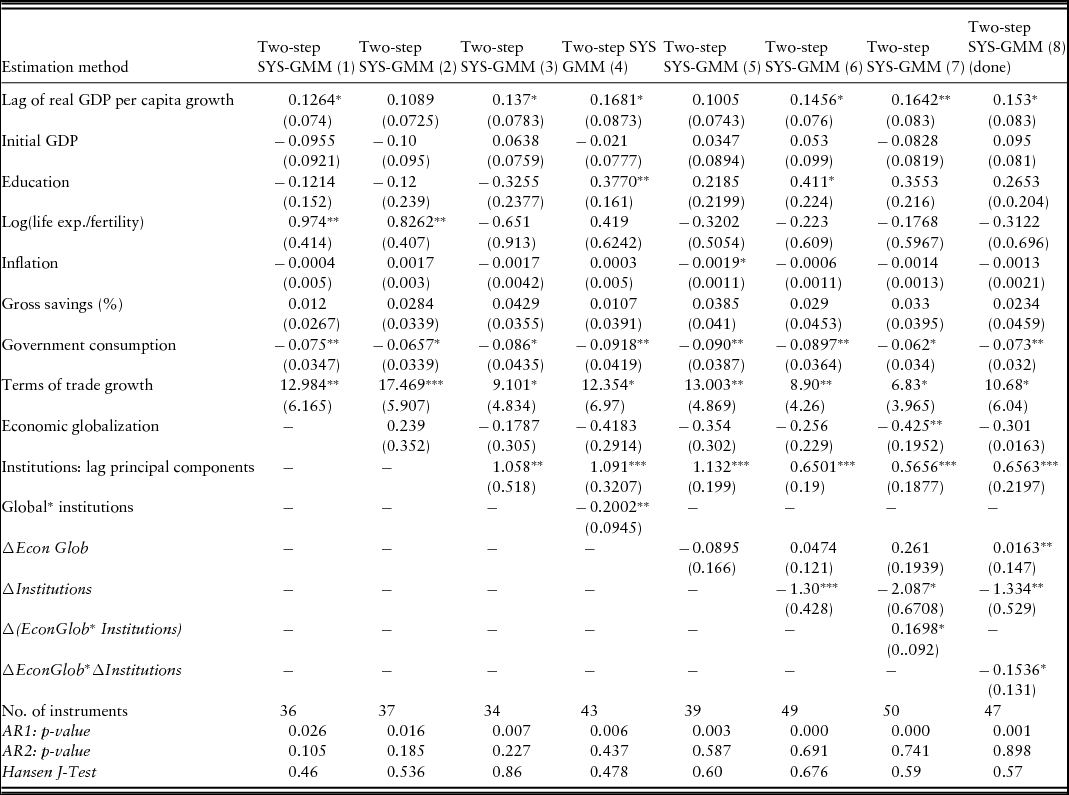
Table 4a presents analogous, two-step dynamic panel system GMM estimates. Estimating the model using the system GMM approach offers the advantage of allowing for endogeneity between independent variables and the real per capita economic growth. As described by Roodman (Reference Roodman2009a), the GMM method achieves this goal by using variables internal to the model as instruments. In order to capture the dynamics within the sample lagged of real per capita GDP, growth is now included among the regressors and is treated as a predetermined variable. Two-step GMM was used to estimate the model's coefficients and the Windmeijer (Reference Windmeijer2005) correction has been applied to all standard errors presented in both Table 4a and Table 4b. Institutional quality and economic globalization are treated as potentially endogenous variables under the GMM specification and the maximum lag-length of 3 is chosen to avert the problem of instrument proliferation and its undesirable consequences (see, for example, Roodman, Reference Roodman2009b).
System GMM estimates: dynamic estimation – full sample

*** statistically significant at the 1% level; ** statistically significant at the 5% level; * statistically significant at the 10% level.
System GMM estimates: dynamic estimation – developing country sub-sample

*** statistically significant at the 1% level; ** statistically significant at the 5% level; * statistically significant at the 10% level.
Column 1 of Table 4a mirrors closely the specification used for the corresponding columns of Tables 3a and 3b. The coefficient estimate on the newly introduced lagged dependent variable is statistically significant at the 5% level indicating that its inclusion is justified. In addition, the coefficient on the gross savings variable is statistically significant at the 1% level, corroborating earlier results that the gross savings variable is a positive and statistically significant determinant of real GDP per capita growth. Both sign and magnitude of the coefficient estimate on the gross savings coefficient matches the results from the fixed effect estimates of Tables 3a and 3b. The finding that both lagged real GDP growth per capita and savings are fairly robust, statistically significant determinants of real GDP per capita growth is robust across most specifications in Table 4a.
Column 1 of the table also reveals statistically significant coefficients for terms of trade growth and government consumption variables. These empirical results corroborate earlier findings that terms of trade growth are statistically significant and positively related to real GDP per capita economic growth, whereas government share of spending has the opposite effect. The latter result implies a possible ‘crowding-out effect’ in economies where excessive government participation has a negative effect on real per capita growth. This finding is consistent with the empirical results of Afonso and Furceri (Reference Afonso and Furceri2008) and Fölster and Henrekson (Reference Fölster and Henrekson2001) based on Barro's (Reference Barro1990) model, which implies that as the size of government increases distortionary effects resulting from high taxes and public burrowing, diminishing returns on public capital, rent seeking and bureaucratic inefficiencies tend to dominate.
Columns 2–8 also support the finding of a negative and highly statistically significant relationship between increased government spending and real GDP growth per capita growth. The coefficient on the terms of trade growth variable also exhibits a robustly positive effect on real GDP per capita growth. This supports the hypothesis that increasingly favourable terms of trade have a positive and significant effect on real per capita economic growth, and corroborates earlier findings. Demographic factors also appear to be statistically significant for certain specifications of the model (Columns 5 and 7) when regression results are based on the complete sample.
Addressing the results for the two key variables of interest – economic globalization and institutional quality – Table 4a reveals that the institutional quality variable is also statistically significant for the specifications of the model depicted in Columns 3, 5 and 8. The positive sign of the coefficient implies that institutional quality is positively related to real per capita GDP growth, corroborating the earlier results from the fixed-effects specification. Interestingly, it can be observed that while the positive sign of the coefficient on institutional quality is mostly positive across all specifications of the model, the statistical significance of the coefficient varies. Overall, the results suggest a statistically significant role for institutional quality in affecting real GDP per capita growth. On the other hand, the coefficients on the economic globalization variables across all specifications are again mostly statistically insignificant.
Table 4b presents system GMM estimates for the restricted sample of developing countries. The results follow a similar pattern to those presented in Table 4a. Overall, the table corroborates earlier findings that the important variables driving real GDP growth outcomes across the developing country sample are: (1) terms of trade growth, which has a positive and statistically significant effect, and (2) government consumption, which is highly significant across all specifications but has a negative effect on real GDP per capita growth. While the coefficient on the institutional quality variable proved to be statistically significant and positively signed for only some specifications of the empirical models depicted in Tables 3a, 3b and 4a, the coefficient is highly statistically significant and positively signed across all specifications of the models results in Table 4b. This result highlights the critical importance of good institutions for real per capita economic growth in developing countries. Remembering that the proxy for institutional quality bears a strong positive correlation to LO and is strong negatively correlated to PR and CL we can infer that, within the sample, countries that have seen improvements in the quality of the institutions favouring the rule of law have tended to realize significantly more favourable outcomes in terms of real growth per capita.
By way of contrast, it is noteworthy that the coefficient on the economic globalization variable, expressed in levels, is statistically insignificant across all specifications, except in Column 7 of the table, again emphasizing that institutional quality appears to play a superior role to economic globalization in influencing the growth outcomes of developing countries.
The differenced institutional quality variable, which in introduced in Column 6, is also statistically significant across specifications in Columns 6–8 of Table 4b. Interestingly, all the coefficients have negative signs, which indicates that changes in institutional quality or in the balance between the rule of law, PR and CL can have a statistically significant effect on real GDP per capita growth.
While the results of Table 4b imply that the level of economic globalization does not play an important role for real growth per capita for the developing country sub-sample, the differenced economic globalization variable, for the first time, is statistically significant in the specification displayed in Column 8 of the table at the 5% level. This result however is not robustly returned across alternative specifications. In addition, Table 4b reveals that, for developing countries, the interaction effects of institutional quality and economic globalization have a statistically significant effect on real GDP per capita across all specifications where these interaction effects between institutional quality and globalization have been included.
Overall therefore, the weight of the empirical evidence across both fixed effects and dynamic GMM panel estimation results indicates that the quality of institutions, rather than economic globalization, is a relatively more important and robust causal factor driving real growth outcomes after accounting for endogeneity. This result holds when the model is applied to both the general dataset and in the developing country sub-sample. Regarding interaction effects between economic globalization and institutions, the empirical evidence presented here is not supportive of the hypothesis that the variable influences real per capita growth in general. However, there is some evidence that the hypothesis holds, with the sub-sample of developing countries providing some evidence to this effect.
5. Conclusion
Is globalization's effect on growth moderated by institutional quality? This paper investigates this question using a panel dataset of 82 countries over the period 1986–2010. One major goal of this paper is to bridge the gap between the separate strands of literature on (1) the relationship between institutions and economic growth and (2) the relationship between economic globalization and economic growth and development, using methods that account for endogeneity between institutions, economic globalization and real growth.
The analysis reveals that there is continuous churning in the level of globalization between countries with no simple, clear linear relationship between the level of globalization and the degree of economic development. The results also reveal larger risks (greater dispersion) in economic growth outcomes for countries that experience relatively large changes (positive or negative) in the level of globalization over fixed periods. While the direct effects of institutional quality on economic growth are robust across all specifications and samples, there is no evidence that institutions moderate the effect of economic globalization on real GDP per capita growth as a general rule. However for developing countries institutions appear to be of greater importance in interacting with globalization to determine economic outcomes. On the other hand, institutions were found to have a robustly positive effect on economic growth in general.
One policy implication of the findings of the empirical analysis in this paper is that policy-makers and institutions involved in promoting economic development should aim to strike a more optimal balance between pro-growth institutional reforms and globalization-oriented reforms, in order to create a more conducive environment for real, sustainable global economic growth and development. This emphasis is even more critical within a developing country context where both institutions and globalization interact to affect growth. In this regard, there is some evidence that there has been a paradigm shift in the approach taken by major multilateral institutions involved in economic development. In particular, the World Bank and the IMF have both adopted a ‘good governance agenda’. This paradigm shift in development policy has aimed to change the model of development from one that focuses on reducing government size and bureaucracy – replacing it with a new ‘effective’ paradigm, which requires that the state should play a more critical role in managing and regulating the market and civil society. The findings of this paper suggest the need for yet broader and deeper support by these multilateral agencies for institutions promoting CL, PR and importantly the rule of law. These institutional pillars are the primary institutions that form the basis of real economic growth – on the basis of the analysis presented in this paper.
This study faces a limitation due to the inherent shortcomings in measuring globalization. Moreover, the focus of the study on only the economic dimension of globalization implies that other important dimensions of the globalization phenomenon, such as the political and social dimensions, are not directly modelled. It is entirely possible that other dimensions of globalization might indeed also have been consequential to real economic growth outcomes over the review period. Although exploring these additional dimensions are worthy goals for future research endeavours, an in-depth study of these other dimensions are beyond the scope of the current paper.