


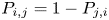


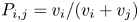


1. Introduction and summary
We consider a competition involving  $r$ teams, where each individual game involves two teams, and where each game between teams
 $i$ and
 $j$ is, independent of results of other games, won by
 $i$ with probability
 $P_{i,j} = 1 - P_{j,i}$. We suppose that some games may have already been played, that team
 $i$ currently has a total of
 $b_i$ wins,
 $i=1, \ldots , r,$ and that
 $i$ and
 $j \neq i$ are scheduled to play an additional
 $n(i,j) = n(j,i)$ games. We let
 $W(i,j)$ be the number of these
 $n(i,j)$ games in which
 $i$ beats
 $j$. With
 $W(i,i) = 0$ for notational convenience, also let
 $W_i = \sum _{j } W(i,j)$ be the total number of additional games won by team
 $i$.
In Section 2, we show for any constants  $a_t, t \neq i,$ that
 $P( W_i \geq \max _{t \neq i} (W_t + a_t ) \,|\,W_i = k)$ is an increasing function of
 $k$, and that
 $W_i |W_j=k$ is, for
 $i \neq j,$ stochastically decreasing in
 $k$.
In Section 3, we consider the random variable  $\max _i W_i$ and obtain bounds on its tail distribution.
In Section 4, we consider the Bradley–Terry special case model, which assumes that team  $i$ has a positive value
 $v_i, \, i = 1, \ldots , r$, and that
 $P_{i,j} = {v_i}/{(v_i + v_j)}$. We show that
 $P(W_i \geq k)$ is an increasing function of
 $v_i$ and a decreasing function of
 $v_j, j \neq i,$ and that whereas
 $P(W_i \geq \max _{t \neq i} (W_t + a_t ) )$ is an increasing function of
 $v_i,$ it need not be true, even when all
 $n(i,j) = n,$ that it is a decreasing function of
 $v_j, j \neq i$ or that
 $P( W_i \geq \max _{t \neq i} (W_t + a_t ) |W_j = k)$ is a decreasing function of
 $k$ when
 $j \neq i$. We then focus on the case where all
 $n(i,j) =n,$ and show in this case that
 $v_i > v_j$ implies that
 $P( W_i \geq \max _{t \neq i} W_t + a) > P( W_j \geq \max _{t \neq j} W_t + a)$.
In Section 5, we present efficient simulation techniques for estimating all the win probabilities  $P( W_i \geq \max _{t \neq i} (W_t + a_t ))$ as well as
 $P( W_i \geq \max _{t \neq i} (W_t + a_t ) \,|\,W_i = k)$.
Most of the literature involving competitions between teams assumes that a fixed number of losses eliminates a team from further competition. Indeed the majority consider the knockout format, in which a single loss eliminates the team. Many knockout models assume that each of the teams is given a position, and then specify a structure defining the sequence of games to be played. For instance, a structure with  $r=6$ players might in round 1 have a match between those in positions
 $1$ and
 $2$ and one between those in positions
 $3$ and
 $4$; round 2 might involve a game between the round 1 winners as well as a game between the teams in positions
 $5$ and
 $6$; the two winners in round
 $2$ games would then play in round
 $3$ to determine the winner of the tournament. Many of the models assume a Bradley–Terry model for team strengths, and also that the team positions are randomly and uniformly determined. Such knockout models are said to have a random structured format.
Chung and Hwang [Reference Chung and Hwang3] proved, for any random structured format, that if  $v_i > v_j$, then the probability that team
 $i$ wins the knockout tournament is greater than the probability that team
 $j$ wins. Maurer [Reference Maurer12] was interested in determining the random structured format that maximized the probability that the best team (i.e., the one with a maximal value of
 $v_i$) wins the tournament and gave the result when
 $v_1>v = v_2 = v_3 =\cdots = v_n$. Cao and Ross [Reference Cao and Ross2] considered the format where the teams are randomly permuted, the first two then playing a game, with the winner playing the next in line, and so on, with the overall winner being the team that wins the last game. Assuming a Bradley–Terry model, bounds on the win probabilities of each team were given in [Reference Cao and Ross2]. A different type of random knockout tournament was considered in Adler et al. [Reference Adler, Cao, Karp, Pekoz and Ross1], where it was assumed that the number of matches in each round was fixed, and that the matchup of teams in any round was totally random. That is, if there are
 $m_i$ games in round
 $i,\ \sum _i m_i = r-1,$ then the
 $2m_1$ teams that play in round
 $1$ are randomly chosen from all
 $r$ teams and then randomly paired up. The winners of this round, along with the
 $r-2m_1$ teams that did not play in round
 $1,$ then move to round
 $2$, where
 $2m_2$ of them are randomly chosen and randomly paired to play round
 $2$ games, and so on. Assuming a Bradley–Terry model, it was shown that if
 $v_1 = \max _i v_i,$ that
 $P(1 \ \text {wins the tournament}) \geq {v_1}/{\sum _{i=1}^{r} v_i}$. Bounds on the win probabilities of the other teams is also given in [Reference Adler, Cao, Karp, Pekoz and Ross1]. Some other papers studying knockout tournaments are David [Reference David4], Glenn [Reference Glenn6], Hennessy and Glickman [Reference Hennessy and Glickman7], Horen and Riezman [Reference Horen and Riezman8], Hwang [Reference Hwang9], and Marchand [Reference Marchand10].
Double elimination tournaments are similar to knockout tournaments, with the difference being that teams are eliminated not after their first loss but after they have lost twice. Edwards [Reference Edwards5] discusses such tournaments. Round robin type tournaments, where each team plays each of the other teams once, have also been studied (see, e.g., [Reference Moser and Harary13,Reference Saarinen, Tovey and Goldsmith17,Reference Searls18]), but they typically assume only a few teams.
2. General model: structural results
We consider the general  $P_{i,j}$ model, with our first objective being to show that a team's conditional probability of having the most wins is an increasing function of the number of wins of that team. To establish this, we will use Efron's theorem.
Lemma 1 (Efron's Theorem)
If  $X_1, \ldots , X_r$ are independent log-concave random variables, then
 $(X_1, \ldots , X_r) \,|\, \sum _{t=1}^{r} X_t = k$ is stochastically increasing in
 $k$. That is, for any component-wise increasing function
 $g(x_1, \ldots , x_r)$
 $$E\left[g(X_1, \ldots, X_r) \left|\, \sum_{t=1}^{r} X_t = k\right.\right] \ \text{is increasing in}\ k$$
Let  $\textbf {{W}}_{-i} = (W_1, \ldots , W_{i-1}, W_{i+1}, \ldots , W_r)$.
Proposition 1  ${\mathbf {W}}_{-i} \,| \,W_i = k$ is stochastically decreasing in
 $k$.
Proof. Fix  $i$. For
 $s \neq i,$ let
 $W^{*}_s = n(s,i) + \sum _{t \neq i} W(s,t)$ be the number of wins of team
 $s$ against all teams aside from
 $i$ plus the number of times team
 $s$ plays team
 $i$. (Thus,
 $W_s = W^{*}_s - W(i,s)$.) Then, if
 $g$ is an increasing function,
 \begin{align} & E[g( { \mathbf{W}}_{{-}i} ) \,|\,W_i = k, W^{*}_s = w^{*}_s, s \neq i ] \nonumber\\ & \quad = E[ g(w^{*}_1 - W(i,1), \ldots, w^{*}_r - W(i,r) )\,|\, W_i = k, W^{*}_s = w^{*}_s, s \neq i ] \nonumber\\ & \quad= E[ g(w^{*}_1 - W(i,1), \ldots, w^{*}_r - W(i,r) )\,|\, W_i = k ] \end{align}
where (1) follows because  $(W^{*}_s, s \neq i )$ is independent of
 $(W(i,1), \ldots , W(i,r))$. Because
 $W(i,s), s \neq i$ are independent binomial, and thus log-concave, random variables, it follows from (1) and Efron's theorem that
 $E[g( {\mathbf {W}}_{-i} ) \,|\,W_i = k, W^{*}_s = w^{*}_s, s \neq i]$ is a decreasing function of
 $k$, and thus that
 $E[g( { \mathbf {W}}_{-i} ) \,|\,W_i = k, W^{*}_s , s \neq i ]$ is too. Taking expectations, given
 $W_i = k$, now yields that
 $E[g( {\mathbf {W}}_{-i} )\, |\,W_i = k] = E[E[g({\mathbf {W}}_{-i})\,|\,W_i = k, W^{*}_s, s \neq i]\,|\, W_i = k]$ is a decreasing function of
 $k$.□
Corollary 1 For given constants  $a_t, t \neq i,$
 $$P\left(W_i \geq \max_{t \neq i} (W_t + a_t )\,|\,W_i = k\right)\quad \text{is an increasing function of}\ k.$$
Proof.
 \begin{align*} P\left( W_i \geq \max_{t \neq i} (W_t + a_t ) \,|\,W_i = k\right) & = P\left( \max_{t \neq i} (W_t + a_t ) \leq k \,|\,W_i = k\right)\\ & \leq P\left( \max_{t \neq i} (W_t + a_t ) \leq k + 1 \,|\,W_i = k\right) \\ & \leq P\left( \max_{t \neq i} (W_t + a_t ) \leq k + 1 \,|\,W_i = k + 1\right) \quad \text{by Proposition 1}\\ & = P\left( W_i \geq \max_{t \neq i} (W_t + a_t ) \,|\,W_i = k+1\right) \end{align*}
□
Remark Because team  $j$ ends up with a total of
 $b_j + W_j$ wins, Proposition 1 shows that the probabilities that no team wins more games than team
 $i$ and that team
 $i$ uniquely has the most wins both increase in the number of wins of
 $i$. (Set
 $a_t = b_t-b_i$ for the former, and
 $a_t = b_t-b_i+1,$ for the latter result.)
Corollary 2
(a)
 ${\mathbf {W}}_{-i} \,| \,W_i \geq k$ and ${\mathbf {W}}_{-i} \,| \,W_i \leq k$ are both stochastically decreasing in $k$.
(b)
${\mathbf {W}}_{-i} \,|\, W_i \geq k \, \leq _{\rm st} \, {\mathbf {W}}_{-i} \, \leq _{\rm st} \, {\mathbf {W}}_{-i} \,|\, W_i \leq k$


Proof. Let  $g$ be an increasing function of
 $r-1$ components. Also, let
 $f(s) = E[g( { \mathbf {W}}_{-i} ) \,|\,W_i = s],$ and note that
 $f$ is, by Proposition 1, a decreasing function. Now,
 \begin{align*} E[g( { \mathbf{W}}_{{-}i} ) \,|\,W_i \geq k] & = \sum_{s=0}^{k} E[g( { \mathbf{W}}_{{-}i} ) \,|\,W_i =s] P(W_i = s\,|\,W_i \geq k)\\ & = \sum_{s=0}^{k} f(s) P(W_i = s\,|\,W_i \geq k) \\ & = E[f(W_i(k))] \end{align*}
where  $W_i(k)$ is a random variable distributed as
 $W_i\,|\,W_i \geq k$. Because
 $W_i(k)$ stochastically increases in
 $k$ (i.e.,
 $W_i(k+1) \geq _{\rm st} W_i(k),$) and
 $f$ is decreasing, it follows that
 $E[f(W_i(k))]$ decreases in
 $k,$ showing that
 ${\mathbf {W}}_{-i} \,| \,W_i \geq k$ is stochastically decreasing in
 $k$. The proof that
 ${\mathbf {W}}_{-i} \,| \,W_i \leq k$ is stochastically decreasing in
 $k$ is similar. Letting
 $n_i$ denote the total number of games played by team
 $i$, part (b) follows from part (a) since
 $${\mathbf{W}}_{{-}i} |W_i \geq 0 = _{\rm st} {\mathbf{W}}_{{-}i} \, =_{\rm st} \, {\mathbf{W}}_{{-}i} |W_i \leq n_i$$
□
3. The maximum number of wins
In this section, we show how to bound  $P(\max _i W_i > k)$. To begin, note that
 $W_i$ is the sum of
 $n_i = \sum _{j: j \neq i} n(i,j)$ independent Bernoulli random variables. Now, in general, the probability mass function of the sum of independent Bernoulli random variables
 $X_1, \ldots , X_m,$ with parameters
 $p_1, \ldots , p_m,$ can be recursively computed by letting
 \begin{equation} P_i(j) = P( X_1 + \cdots + X_i = j ), \quad j \leq i \end{equation}
Then, starting with  $P_1(0) = 1 - p_1, \, P_1(1) = p_1,$ recursively compute using
 $$P_i(j) = P_{i-1}(j-1) p_i + P_{i-1}(j) (1-p_i )\,, \quad j \leq i, \, i = 2, \ldots, m$$
This enables us to compute the probability mass function of  $W_i$ for each
 $i=1, \ldots , r$.
Remark Computing the mass function of  $W_i$ by using that it is the sum of
 $n_i$ independent Bernoulli random variables and then using the preceding recursion appears to be computationally faster than computing it by using that
 $W_i$ is the sum of
 $r-1$ independent binomial random variables and then using an analogous recursion for such a sum.
We can also compute the joint mass function of  $W_i$ and
 $W_j$. For instance, for the joint mass function of
 $W_1$ and
 $W_2$ first compute
 $\,P_1^{*}(j), j = 0, \ldots , n_1 - n(1,2)$ and
 $\,P_2^{*}(j), j = 0, \ldots , n_2 - n(1,2),$ the probability mass functions of the number of additional wins of team
 $1$ against all teams aside from
 $2$, and of the number of additional wins of team
 $2$ against all teams aside from
 $1$. Then use
 $$P(W_1 = u, W_2 = v) = \sum_{j=0} ^{n(1,2)} {n(1,2) \choose j} P_{1,2}^{j} P_{2,1}^{n(1,2) - j} P_1^{*}(u-j) P_2^{*}(v-n(1,2) +j)$$
To bound  $P( \max _i W_i > k),$ use that
 $P( \max _i W_i > k) = P( \cup _i \{W_i > k\})$. From Boole's inequality and the conditional expectation inequality, we obtain the bounds
 \begin{equation} \sum_{i=1}^{r} \frac{ P(W_i > k) }{ 1 + \sum_{j \neq i} P(W_j > k\,|\,W_i > k) } \leq P\left( \max_i W_i > k\right) \leq \sum_{i=1}^{r} P(W_i > k) \end{equation}
where the conditional expectation bound (see [Reference Pekoz and Ross14] for details on this bound) can be computed by using that
 $$P(W_j > k\,|\,W_i > k) = \sum_{u> k} \sum_{v > k} P(W_i = u, W_j = v) / P(W_i > k) .$$
A computationally simpler lower bound can be obtained by letting, for  $j=1, \ldots , r$,
 $X_j$ be the indicator of the event that
 $W_j > k,$ and defining
 ${\mathbf {X}}_{-i} = (X_1, \ldots , X_{i-1}, X_{i+1}, \ldots , X_r)$. Now, (b) of Corollary 2 implies that
 ${\mathbf {X}}_{-i} \,|\,X_i = 1$ is stochastically smaller than
 ${\mathbf {X}}_{-i}$. But, from Proposition 2 of [Reference Ross16], this implies that
 $P( \sum _{i=1}^{r} X_i = 0) \leq \prod _{i=1}^{r} P(X_i = 0)$. Consequently,
 $$P\left( \max_i W_i \leq k\right) \leq \prod_{i=1}^{r} P(W_i \leq k)$$
Thus, we obtain
Proposition 2
 $$1 - \prod_{i=1}^{r} P(W_i \leq k) \leq P\left( \max_i W_i > k\right) \leq \sum_{i=1}^{r} P(W_i > k)$$
Example 1 Suppose that  $n(i,j) = r=10,$ and that all
 $p_{i,j} = 1/2$. That is, there are
 $10$ teams with each pair of teams playing
 $10$ times, and with each game being equally likely to be won by either team. Thus,
 $W_i$ is binomial with parameters
 $90$ and
 $1/2$. Using that
 $$p_k \equiv P(W_i > k) = \left\{\begin{array}{ll} 0.000210, & \text{if} \ k=60\\ 0.013151, & \text{if} \ k=55\\ 0.036275, & \text{if} \ k=53\\ 0.123053, & \text{if} \ k=50 \end{array}\right.$$
and that Proposition 2 yields that  $1 - (1 - p_k)^{10} \leq P( \max _i W_i > k) \leq 10 p_k$, we see that
 \begin{align*} & 0.002098 \leq P\left( \max_i W_i > 60\right) \leq 0.00210 \\ & 0.123994 \leq P\left( \max_i W_i > 55\right) \leq 0.13151\\ & 0.308915 \leq P\left( \max_i W_i > 53\right) \leq 0.36275 \\ & 0.731012 \leq P\left( \max_i W_i > 50\right) \leq 1.23053 \end{align*}
4. The Bradley–Terry special case
Suppose now that  $P_{i,j} = {v_i}/{(v_i + v_j)}$,
 $i \neq j$. That is, consider the Bradley–Terry model.
Proposition 3
(a)
$P(W_i \geq k)$ is a strictly increasing function of $v_i,$ and a strictly decreasing function of $v_t, t \neq i$.(b)
$P( W_i \geq \max _{t \neq i} (W_t + a_t ) )$ is an increasing function of $v_i$.


Proof. (a) Note that  $W_i$ is the sum of
 $\sum _{j} n(i,j)$ independent Bernoulli random variables, of which
 $n(i,j)$ have parameter
 ${v_i}/{(v_i + v_t)}$,
 $t \neq i$. Because
 ${v}/{(v + v_t)}$ increases in
 $v$ and decreases in
 $v_t,$ it thus follows that
 $W_i$ stochastically increases in
 $v_i$ and stochastically decreases in
 $v_t,\ t \neq i$.
The proof of (b) follows by a coupling argument. Consider two scenarios: the first in which team  $i$ has value
 $v_i$ and the second in which team
 $i$ has value
 $v'_i,$ where
 $v'_i < v_i$. In both scenarios player
 $j, j \neq i,$ has value
 $v_j$. Couple the results of all games not involving team
 $i$ to be equal in the two scenarios, and couple the results of games involving team
 $i$ so that a win of team
 $i$ in the second scenario implies a win in the first scenario. Consequently, if
 $W_i \geq \max _{t \neq i} (W_t + a_t )$ in the second scenario, then it is also true in the first scenario, thus proving (b).□
Let us suppose for the rest of this section that all  $n(i,j) = n$. That is, each pair of teams play the same number of games.
Proposition 4 Suppose  $n(i,j) = n.$ If
 $v_i > v_j$, then
 $P(W_i \geq k) > P(W_j \geq k), \ k > 0$.
Proof. This follows by a simple coupling argument.□
For a given player  $i,$ let
 ${\mathbf {w}} = (w_1, \ldots , w_{r-1})$ be the vector of its opponent's values in the decreasing order; that is, the
 $r-1$ opponents of
 $i$ have values
 $w_1 \geq w_2 \geq \cdots \geq w_{r-1}$. Say that the opponent value vector
 ${\mathbf {w}}$ majorizes the opponent value vector
 ${\mathbf {w'}} ,$ written
 ${\mathbf { w}} \geq _m {\mathbf {w'}},$ if
 $w_1 + \cdots + w_j \geq w'_1 + \cdots + w'_j$,
 $j = 1, \ldots , r-2$ and
 $w_1 + \cdots + w_{r-1} = w'_1 + \cdots + w'_{r-1}$. We now show that the number of wins of a given player stochastically increases as the values of its opponents become more spread in the sense of majorization.
Proposition 5 Suppose each pair plays  $n$ games. For fixed
 $v_i,$ if
 $N_i({\mathbf {w}} )$ is the total number of wins of
 $i$ when the opponent vector is
 ${\mathbf {w}},$ then
 $N_i({\mathbf {w}}) \geq _{\rm st} N_i({\mathbf {w'}} )$ when
 ${\mathbf {w}} \geq _m{\mathbf {w'}}$.
Proof. It follows by the Schur–Ostrowski theorem (see [Reference Marshall and Olkin11]) that it suffices to prove the result when  $i$ has only two opponents. Suppose first that
 $n=1$ so that
 $i$ plays exactly one game with each of the other two players. Suppose the opponent values are
 $w_1 = a+x$,
 $w_2 = a - x$,
 $0 \leq x \leq a$. Then,
 $$P(N_i(a+x, a-x) \geq 1) = 1- \frac{a+x}{a+x+v_i } \frac{a-x}{a-x +v_i } = 1 - \frac{ a^{2} - x^{2}}{ (a+v_i)^{2} - x^{2}} ,$$
is an increasing function of  $x$. Furthermore,
 $$P(N_i(a+x, a-x) \geq 2) = \frac{v_i}{a+x+v_i } \frac{v_i}{a-x +v_i } = \frac{ v_i^{2}}{ (a+v_i)^{2} - x^{2}}$$
is also an increasing function of  $x$, proving the result when
 $n=1$. When
 $n > 1,$ consider
 $i's$ games against
 $1$ and
 $2$ in
 $n$ pairs. That is, for each
 $j=1, \ldots , n,$ consider the number of wins of
 $i$ in its
 $j$th games against
 $1$ and
 $2$. Because stochastic monotonicity is preserved under convolution, it follows that the total number of wins of
 $i$ is stochastically increasing in
 $x$.□
Corollary 3 Suppose each pair plays  $n$ games. Let
 $\text {Bin}(m, p )$ be a binomial random variable with parameters
 $m, p$. If
 $\bar {w} = { \sum _{j=1}^{r-1} w_j }/{(r-1)},$
 $$N_i({\mathbf{w}} ) \geq_{\rm st} \text{Bin}(n(r-1), \bar{w} )$$
Proof. Follows from Proposition 5 because  ${\mathbf {w}} \geq _m(\bar {w}, \ldots , \bar {w})$.□
Remarks
1. A function
$g({\mathbf {w}})$ having the property that $g({\mathbf {w}}) \geq g({\mathbf {w'}})$ whenever ${\mathbf {w}} \geq _m {\mathbf {w'}}$ is said to be a Schur convex function. If the inequality is reversed, then it said to be a Schur concave function.2. There is no analog of Proposition 5 when it comes to the probability that
$i$ has the most number of wins. That is, if $P^{*}_i({\mathbf {w}})$ is the probability that $i$ wins at least as many games as any other player, then $P^{*}_i({\mathbf {w}})$ is not necessarily either a Schur convex or a Schur concave function. For instance, suppose $r=4$, $v_i = n = 1$, $\sum _{j=1}^{3} w_j = 6$. Then, $P^{*}_i(2,2,2) = 1/27 + 3(1/3)^{2}(2/3)(3/4) = 11/54,$ whereas $P^{*}_i(3,3,0) = 1/16 + 2(1/4)(3/4)(1/2) = 1/4,$ and $P^{*}_i(6,0,0) = 1/7$. (It is also true that the probability that $i$ wins strictly more games than any other player need not be either Schur convex or concave.)


The following example shows that, for  $r>2,$ the probability that
 $i$ wins the most, or the unique most number of games is not necessarily a decreasing function either of
 $v_j$ or of the given value of
 $W_j,$ for
 $j \neq i$.
Example 2 Suppose  $r=3,$ and that
 $v_1 = 9$,
 $v_2 = 4$. Then, when
 $n=1$, it is easy to check that
 $$P(W_1 \geq \max(W_2, W_3) ) = \left\{ \begin{array}{ll} 0.7338, & \text{if} \ v_3 = 1\\ 0.7343, & \text{if} \ v_3 = 2 \end{array}\right.$$
When  $n=2,$ condition on
 $W(1,2), W(1,3)$ to obtain
 \begin{align*} & P(W_1 > \max(W_2, W_3) ) \\ & \quad =P( W(1,2)=W(1,3) = 2) + P(W(1,2) = 1, W(1,3) = 2) \left(1-\left(\frac{v_2}{v_2 + v_3}\right)^{2} \right) \\ & \qquad + P( W(1,2)= 2, W(1,3) = 1) \left(1-\left(\frac{v_3}{v_2 + v_3}\right)^{2} \right) \\ & \quad = \left(\frac{v_1}{v_1 + v_2}\right)^{2} \left(\frac{v_1}{v_1 + v_3}\right)^{2} + \frac{ 2v_1^{3} v_2}{(v_1+v_2)^{2} (v_1+v_3)^{2}} \left(1-\left(\frac{v_2}{v_2 + v_3}\right)^{2} \right)\\ & \qquad + \frac{ 2v_1^{3} v_3}{(v_1+v_2)^{2} (v_1+v_3)^{2}} \left(1-\left(\frac{v_3}{v_2 + v_3}\right)^{2} \right) \end{align*}
This gives, when  $v_1=9$,
 $v_2 = 4,$ that
 $$P(W_1 > \max(W_2, W_3) ) = \left\{\begin{array}{ll} 0.5953, & \text{if} \ v_3 = 1\\ 0.6060, & \text{if} \ v_3 = 2 \end{array}\right.$$
Before giving an example illustrating that  $P(W_1 > \max (W_2, W_3) \,|\,W_3=k)$ need not be a decreasing function of
 $k$, note first the interesting result, when all
 $n(i,j) = n,$ that conditional on
 $W_i = 1$, the probability that the lone win of
 $i$ was against
 $j$ is proportional to
 $1/v_j$. To verify this, note that
 \begin{align*} P(W(i,j) = 1, W_i = 1) & = n \frac{v_i}{v_i + v_j} \left( \frac{v_j}{v_i + v_j} \right)^{n-1} \prod_{k \neq i, j} \left( \frac{v_k}{v_i + v_k} \right)^{n}\\ & = \frac{ n v_i}{v_j} \prod_{k \neq i} \left(\frac{v_k}{ (v_k + v_i)}\right)^{n} \end{align*}
which gives that
 $$P(W(i,j) = 1\,|\,W_i = 1) = \frac{ 1/v_j} { \sum_{k \neq i} 1/v_k}$$
Now, when  $n=1$,
 $v_1 = 9$,
 $v_2 = 4$,
 $v_3=1$
 $$P(W_1 \geq \max(W_2, W_3) |W_3=k) = \left\{\begin{array}{ll} 0.6923, & \text{if} \ k=0\\ 0.9053, & \text{if} \ k=1 \end{array}\right.$$
where the  $W_3 =1$ case is computed by conditioning on who
 $3$ beat. Since this will be
 $2$ with probability
 $v_1/(v_1+v_2),$ we obtain
 $$P(W_1 \geq \max(W_2, W_3)\, |\,W_3=1) = \frac{v_1}{v_1 + v_2} + \frac{v_2}{v_1 + v_2} \frac{v_1}{v_1 + v_2}$$
When  $n=2$,
 $v_1 = 9$,
 $v_2 = 4$,
 $v_3=1$
 $$P(W_1 > \max(W_2, W_3) |W_3=k) = \left\{\begin{array}{ll} 0.4793, & \text{if} \ k=0\\ 0.7742, & \text{if} \ k=1 \end{array}\right.$$
where the  $W_3 = 1$ case is computed by conditioning on who
 $3$ beat, giving
 $$P(W_1 > \max(W_2, W_3) \,|\,W_3=1) = \frac{v_2}{v_1 + v_2} \left(\frac{v_1}{v_1+v_2}\right)^{2} + \frac{v_1}{v_1 + v_2} \left(1 - \left(\frac{v_2}{v_1+v_2}\right)^{2} \right)$$
Remark In the case where  $v_i = v_i$,
 $v_j = \alpha w_j$,
 $j \neq i,$ the probability that
 $i$ has the most number of wins is a decreasing function of
 $\alpha$. To prove this, consider two scenarios, the first where
 $\alpha = \alpha _1$ and the second where
 $\alpha = \alpha _2,$ where
 $\alpha _1 > \alpha _2$. Because, for
 $i \notin \{k,j\},$ the probability that
 $k$ wins when playing
 $j$ is the same in both scenarios, we can couple the results of all games not involving
 $i$ so that their results are identical in both scenarios. We can also couple all games involving
 $i$ so that if
 $i$ wins a game in scenario two, then it also wins that game in scenario one. In this way, we see that
 $i's$ probability of having the most wins is larger in scenario one than in scenario two.
Proposition 6 Suppose  $n(i,j) = n.$ If
 $v_i > v_j,$ then for any integer
 $a \leq {nr}/{2},$
 $$P\left( W_i \geq \max_{t \neq i} W_t + a\right) > P\left( W_j \geq \max_{t \neq j} W_t + a\right).$$
Proof. Fix  $i$ and
 $j$, and suppose that
 $v_i > v_j$. Let
 $A_s = \{ W_s \geq \max _{t \neq s} W_t + a \},$ and let
 $N_{i,j}$ denote the number of events
 $A_i, A_j$ that occur. Then, for
 $k = i, j$
 $$P(A_k) = P(N_{i,j} = 2) + P(A_k\,|\, N_{i,j} = 1) P(N_{i,j} = 1)$$
Consequently,
 $$P(A_i) > P(A_j) \Leftrightarrow P ( A_i\,|\, N_{i,j} = 1) > P ( A_j\,|\, N_{i,j} = 1)$$
Suppose that  $N_{i,j} = 1,$ and let
 $I=i, J = j$ if
 $A_i$ occurs and let
 $I=j, J = i$ if
 $A_j$ occurs. For a given vector
 ${\mathbf {w}} = (w, w_0(t), w_1(t), t \neq i,j),$ let
 $H({\mathbf {w}}) = \{ W(I,J) = w, W(I, t) = w_0(t), W(J, t) = w_1(t), t \neq i,j \}$. Also, let
 $w_I = w+ \sum _{t \neq i,j} w_0(t)$ and
 $w_J = n-w + \sum _{t \neq i,j} w_1(t)$.
Suppose, from now, that  ${\mathbf {w}}$ is such that
 $P(H({\mathbf {w}}) |N_{i,j} = 1) > 0,$ and note that this implies that
 $w_I > w_J$. With
 $E_{i,j} = \{ W(i,j) = w, W(i, t) = w_0(t), W(j, t) = w_1(t), t \neq i,j \},$ we have, upon letting
 $C = {n \choose w} \prod _{t \neq i,j} {n \choose w_0(t) }{ n \choose w_1(t)},$ that
 \begin{align*} P(E_{i,j})& = C \left(\frac{v_i}{v_i + v_j}\right)^{w} \left(\frac{v_j}{v_i + v_j}\right)^{n-w}\\ & \quad \times \prod_{t \neq i,j} \left( \frac{v_i}{v_i + v_t}\right)^{w_0(t) } \left( \frac{v_t}{v_i + v_t}\right)^{n-w_0(t) } \left( \frac{v_j}{v_j + v_t}\right)^{w_1(t) } \left( \frac{v_t}{v_j + v_t}\right)^{n-w_1(t) }\\ & = C K({\mathbf{w}}) v_i^{w+ \sum_{t \neq i,j} w_0(t) } v_j^{n-w + \sum_{t \neq i,j} w_1(t) } \\ & = C K({\mathbf{w}}) v_i^{w_I} v_j^{w_J} \end{align*}
where
 $$K({\mathbf{w}}) = \frac{ \prod_{t \neq i,j} v_t^{2n - w_0(t) - w_1(t) } }{ (v_i + v_j)^{n} \prod_{t \neq i,j} (v_t+v_i)^{n} (v_t+v_j)^{n} }$$
Because, given  $N_{i,j} = 1$,
 $A_i$ and
 $A_j$ are mutually exclusive, we have that
 $$P(A_i \, | \, H({\mathbf{w}}), N_{i,j} = 1) = \frac{ P(E_{i,j}) } { P(E_{i,j}) +P(E_{j,i}) }$$
Because  $v_i > v_j$ and
 $w_I > w_J$, we see that
 $$\frac{ P(E_{i,j}) } {P(E_{j,i}) } = \left( \frac{ v_i}{v_j} \right)^{w_I - w_J} > 1$$
Hence, for any  ${\mathbf {w}}$ for which
 $P(H({\mathbf {w}}) |N_{i,j} = 1) > 0,$ we have that
 $P(A_i \, | \, H({\mathbf {w}}), N_{i,j} = 1) > P(A_j \, | \, H({\mathbf {w}}), N_{i,j} = 1)$. Taking expectations, conditional on
 $N_{i,j} = 1,$ gives that
 $P ( A_i| N_{i,j} = 1) > P ( A_j| N_{i,j} = 1)$, which proves the result.
Remarks
1. In Proposition 6, the condition on
$a$ is included because if $a > {nr}/{2}$, then $P( W_i \geq \max _{t \neq i} W_t + a) = 0$ for all $i$.2. One might at first think that Proposition 6 is a simple consequence of Proposition 3(b) by the following argument. Suppose two scenarios, where in scenario one
$v_i = v_j = v$ and in scenario two that $v_i = v'$, $v_j = v,$ where $v'> v$. In both scenarios, $v_k, k \neq i,j,$ are the same. Now, letting the superscript indicate the scenario, we have that $P( W^{1}_i \geq \max _{t \neq i} W^{1}_t + a) = P( W^{1}_j \geq \max _{t \neq j} W^{1}_t + a)$ and, by Proposition 3(b), that $P( W^{2}_i \geq \max _{t \neq i} W^{2}_t + a) > P( W^{1}_i \geq \max _{t \neq i} W^{1}_t + a) ,$ enabling us to conclude that $P( W^{2}_i \geq \max _{t \neq i} W^{2}_t + a) > P( W^{1}_j \geq \max _{t \neq j} W^{1}_t + a).\,$ However because, as seen in Example 2, it is not necessarily true that $\,P( W^{1}_j \geq \max _{t \neq j} W^{1}_t + a) \geq P( W^{2}_j \geq \max _{t \neq j} W^{2}_t + a),$ we cannot conclude (as would be needed to prove Proposition 6) that $P( W^{2}_i \geq \max _{t \neq i} W^{2}_t + a) > P( W^{2}_j \geq \max _{t \neq j} W^{2}_t + a)$.


5. Efficient simulation
In this section, we show how to effectively simulate some of the probabilities of interest.
5.1. Simulation estimation of $P( W_j \geq \max _{i \neq j} (W_i + a_i) |W_j = k)$ for fixed $j$ and all $k$


For notational convenience, let  $j=1$ and suppose that we are interested in using simulation to estimate, for all
 $k=0, \ldots , n_1,$
 $$P_k \equiv P\left( W_1 \geq \max_{i =2, \ldots, r} (W_i + a_i) \,|\,W_1 = k\right)$$
To begin (the  $n_1 = \sum _{j \neq 1} n(1,j)$ games of player
 $1$, for example, say that game
 $i$ is the
 $i$th game of player
 $1$ against player
 $2$ for
 $i=1, \ldots , n(1,2);$ game
 $n(1, 2) + i$ is the
 $i$th game of player
 $1$ against player
 $3$ for
 $i=1, \ldots , n(1,3);$ and so on. Let
 $X_i$ be the indicator for the event that player
 $1$ wins game
 $i, i = 1, \ldots , n_1,$ and let
 $p_i = P_{1,o_i},$ where
 $o_i$ is the opponent of player
 $1$ in game
 $i$. Now, for
 $S_i \equiv X_1 + \cdots + X_i$, use the recursion of Section 3 to determine the values
 $$P_i(j) = P( S_i = j),\quad j \leq i, \ i = 1, \ldots, n_1.$$
Also, let  $C_i$ be the set of indices of games between
 $1$ and
 $i, \;i = 2, \ldots , r$.
Each simulation run yields an unbiased estimate of all values  $P_1, \ldots , P_{n_1}$. A simulation run is as follows:
• Generate the values of the
${ r-1 \choose 2}$ independent binomial random variables $W(i, j)$ for $1< i< j,$ and, for $i=2, \ldots , r,$ let $W^{*}_i = \sum _{j: 1< i < j} W(i,j) + \sum _{j: 1< j < i} (n(i,j) - W(j,i) )$. Thus, $W^{*}_i$ is the simulated value of the number of games that $i$ wins against all teams aside from team $1$.• Generate
$n_1$ independent uniform $(0, 1)$ random variables $U_1, \ldots , U_{n_1}$.• For each
$k, k \leq n_1,$ we now show how to generate the values of $X^{k}_1, \ldots , X^{k}_{n_1},$ random variables whose distribution is the conditional distribution of $X_1, \ldots , X_{n_1}$ given that $S_{n_1} = k$. Using that
set$$P(X_{n_1} = 1\,|\, S_{n_1} = k) = \frac{ p_{n_1} P_{n_1 - 1}(k-1)}{ P_{n_1}(k) }$$
Let$$X^{k}_{n_1} = \left\{\begin{array}{ll} 1, & \text{if} \ \, U_{n_1} < \dfrac{ p_{n_1} P_{n_1 - 1}(k-1) }{ P_{n_1}(k) } \\ 0, & \text{if} \ \,\text{otherwise} \end{array}\right.$$
$x^{k}_{n_1}$ be the generated value of $X^{k}_{n_1}$.
Suppose that the values
$X^{k}_{n_1} = x^{k}_{n_1}, \ldots , X^{k}_{j+1}=x^{k}_{j+1}$ have been generated. Let $s^{*}_{j+1} = x^{k}_{n_1} + \cdots +x^{k}_{j+1},$ and use that
to generate the value of\begin{align*} P(X_j = 1\,|\, X^{k}_{n_1} = x^{k}_{n_1}, \ldots, X^{k}_{j+1}=x^{k}_{j+1}, S_{n_1} = k) & = P(X_j = 1\,|\, S_j = k - s^{*}_{j+1})\\ & =\frac{ p_{j} P_{j-1}(k- s^{*}_{j+1} -1 )} { P_j(k- s^{*}_{j+1} ) } \end{align*}
$X^{k}_j,$ by setting
Let$$X^{k}_{j} = \left\{\begin{array}{ll} 1, & \text{if} \ \, U_{j} < \dfrac{ p_{j} P_{j-1}(k- s^{*}_{j+1} -1 )} { P_j(k- s^{*}_{j+1} ) } \\ 0, & \text{if} \ \, \text{otherwise} \end{array}\right.$$
$x^{k}_{j}$ be the generated value of $X^{k}_j$. Continue until all values $x^{k}_1, \ldots , x^{k}_{n_1}$ have been determined.• Recall that
$C_i$ is the set of indices of the games that $1$ plays against $i$, and let $W^{k}(1,i) = \sum _{j \in C_i} x^{k}_j,$ and $W^{k}_i = W^{*}_i + n(i,1) - W^{k}(1,i),\ i > 1$. Now let
It is easy to see that$$I_k = I\left\{ k \geq \max_{i > 1} (W^{k}_i + a_i)\right\}$$
$I_k$ is an unbiased estimate of $P_k$.• It is not necessary to repeat the preceding for all
$k$. Using that $P(X_i = 1\,|\,S_i = t)$ is, by Efron's theorem, an increasing function of $t$, it follows from the fact that we are using the same values of $W^{*}_i, i > 1,$ and the same uniforms $U_1, \ldots , U_{n_1}$ to estimate all quantities $P_2, \ldots , P_r$ that $X^{k}_{j}$ will, for all $j$, be increasing in $k$ and thus that $I_k$ will be increasing in $k$. Hence, if it results that $I_k = 1$, then we should set $I_j = 1$ for all $j \geq k,$ or if it results that $I_k = 0$, then we should set $I_j = 0$ for all $j \leq k$. Doing this greatly reduces the computation necessary to obtain unbiased estimates for all $P_k, k=0, \ldots , n_1$.Multiple simulation runs should be performed and the estimate of
$P_k$ is the average value of $I_k$ obtained.


5.2. Simulation estimation of $P( W_1 \geq \max _{i \neq 1} (W_i+ a_i) )$

To estimate  $P \equiv P( W_1 \geq \max _{i \neq 1} (W_i+ a_i) ) ,$ we suggest using the same procedure as in the previous subsection. That is, first do the preliminary work of computing the values
 $P_i(j), \ j \leq i, \, i = 1, \ldots , n_1$. Then, in each simulation run generate the values
 $I_k, 0 \leq k \leq n_1$. Letting
 $k^{*} = \min \{k: I_k = 1\},$ and using that
 $$P = \sum_{k=0}^{n_1} P\left( W_1 \geq \max_{i \neq 1} (W_i+ a_i) \,|\,W_1= k\right) P_{n_1}(k)$$
it follows that  $P(W_1 \geq k^{*}) = \sum _{k=k^{*}}^{n_1} P_{n_1}(k) \,$ is an unbiased estimate of
 $P$. Averaging this value over many simulation runs gives the estimate.
5.3. Simulation estimation of $P( W_i \geq \max _{t \neq i} (W_t + a_{t} ) )$ for all $i$


In this case, we suggest generating the  ${r \choose 2}$ independent binomials
 $W(i, j), i < j,$ and setting
 $\,W_i = \sum _{i< j} W(i,j) + \sum _{j < i} (n(i,j) - W(j,i)) ,\ i = 1, \ldots , r$. Then use the estimator
 $I_i = I\{ W_i \geq \max _{t \neq i} (W_t + a_{t} ) ) \}$ along with
 $W_i$ as a control variable. That is, the estimate of
 $P( W_i \geq \max _{t \neq i} (W_t + a_{t} ) )$ from a given run is
 $I_i + c_i(W_i - \sum _{j \neq i} n(i,j) P_{i,j} ),$ where the appropriate value of
 $c_i$ is determined from the simulation data (see [Reference Ross15]).
Funding statement
This material is based on work supported by, or in part, by the National Science Foundation under contract/grant CMMI1662442.
Conflict of interest
The authors declare no conflict of interest.


