1 The asset-pricing model
Cochrane (Reference Cochrane2001) shows that the market price of an asset that provides a random cash flow at some future time T satisfies the following recursive formula

where:
• P t is the price of the asset at time t (t⩽T−1)
• E t[.] is the conditional expectation based on information at time t
• Z t+1 is the single-period stochastic discount factor at time t+1
The economic interpretation of the stochastic discount factor is as follows: Z t+1 will be high in states of the world where the marginal utility of consumption is also high. This will occur in times of economic hardship, when aggregate consumption is lower than expected. It follows that the present value of cash flows contingent on such states of the world will be high, as indicated by equation (1). The reverse is true for prosperous states of the world, when aggregate consumption is higher than expected.
To derive a practical pricing method from equation (1), we need to link the stochastic discount factor to measurable economic variables. We shall assume that Z t+1 is a function of the total wealth in the economy. Although this is not easy to measure in itself, a method of estimating the change in this wealth will suffice for the purpose of asset pricing. We assume that this change is given by the return on a representative equity portfolio, which we shall refer to as the ‘market portfolio’.
We now define the following variables:
• M t is the value of the market portfolio at time t
• P t is the value of an arbitrary asset A at time t
• B t is the value of a risk-free bond at time t
• δt+1M is the random force of return on the market portfolio between time t and t+1
• δt+1A is the random force of return on asset A between time t and t+1
• μR is the risk-free force of return
For the market portfolio, asset A and the risk-free bond we can write:

We assume that δtM and δtA are both independent and identically distributed normal random variables, so that

We allow that δtM and δtA may be correlated over the same time period and define

We now assume that the stochastic discount factor is related to the return on the market portfolio by a function of the form

where g and h are constants.
The single-period pricing formula given in equation (1) must be valid for all assets and all portfolios. We now apply it, in turn, to the market portfolio, asset A and the risk-free bond.

which from the properties of the log-normal distribution gives

Applying the pricing formula to asset A and the risk-free bond gives


Eliminating e g between equations (2) and (3) gives

Eliminating e g between equations (2) and (4) gives

And eliminating h between equations (5) and (6) gives

Equation (7) is the standard formula of the Capital Asset Pricing Model expressed in terms of log-returns. From the properties of the log-normal distribution, μA+½σA2 is the expected return on asset A expressed as a force of interest and μM+½σM2 is the same for the market portfolio.
Having obtained a formula for μA, the price of asset A can be expressed as an expected present value. From the properties of the log-normal distribution, the conditional distribution of ln(P T) at time t is given by

Taking conditional expectations of both sides of the above equation gives

The numerator of equation (8) is equivalent to the median value of the conditional distribution for P T, while the denominator is a discount factor for the period T–t using the force of interest μA. From the properties of the log-normal distribution, μA is the geometric mean of the return on asset A expressed as a force of interest.
2 The link between equity returns and wage inflation
Looking at an individual stock, it is widely accepted that the change in earnings per share is the main factor driving its market price (Elton and Gruber, Reference Elton and Gruber1995). The ‘equity market’ is simply a portfolio of individual stocks weighted by market capitalization, so the arguments are broadly the same. In the short term, the influence of earnings on the level of the market may be obscured by variations in the price/earnings ratio, but in the long term, the decisive factor will be earnings growth. Shiller (Reference Shiller1989) uses a moving average of real earnings as a measure of fundamental value for the equity market.
By ‘earnings’ we mean the profit available for distribution to the ordinary shareholders. The mechanism linking profit growth to equity returns is fairly obvious, but is there a similar connection between profits and wages? On first inspection, we might expect a company paying higher wages to make lower profits, and vice versa. If this naïve reasoning were correct, however, we would be hard pressed to explain the growth in wages that has occurred in industrialized countries, which has gone hand-in-hand with capital accumulation and profit growth.
At the micro level, there are businesses making ‘above-normal’ profits and businesses making ‘below normal’ profits as part of the natural process of competition and adjustment that occurs in a capitalist economy. The more profitable businesses are generally in their favourable position because they are serving their customers better than their competitors or operating within an expanding industry. In either event, the natural impulse for the managers of a successful business is to invest and expand, which involves employing more factors of production, one of which is labour. And an increase in the demand for labour should, other things being equal, bid up the wages of workers.
The growth of a single business may have only a small effect on wages. But a growing economy is characterized by a general growth in profits brought about by the accumulation of capital, i.e. the expanding businesses outnumber the contracting ones. In such circumstances, the actions of individual businesses will bid up the average level of wages, provided that the rate of capital accumulation exceeds the rate of growth in the number of workers. Thus, the factor driving up wages is the increasing scarcity of workers relative to capital, or as von Mises (Reference von Mises1949) wrote:
What raises wage rates is an increase in capital exceeding the increase in population or, in other words, an increase in the per-head quota of capital invested.
Statistical evidence
Growth in profits is the causal agent influencing both equity returns and wage growth. The timing of the effects brought about by profit growth, however, is potentially very different. Equity prices are influenced by expected profits. If profits are expected to rise, perhaps because the economy is emerging from a recession, it is likely the equity market will anticipate this change. The situation is very different for the labour market. At the end of a recession, we would expect unemployment to be relatively high, so the increasing demand for labour would have a relatively small effect on wages. The most rapid growth in wages is likely to occur after the economic expansion has continued for some time, when unemployment is low and the labour market is tight.Footnote 1
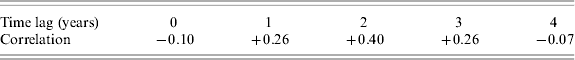
Putting these arguments together, it follows that the correlation between equity returns and wage growth should occur only after a significant time lag; that is, current equity returns should be positively correlated with future wage growth.
Estimated correlation coefficients for real wage growth and real equity returns, lagged by annual periods of up to four years, are shown in Table 1. These were derived from UK data over the period 1946–2005, taken from Barclays Capital Equity Index, the Retail Prices Index, the Average Earnings Index, and various other UK wage indices prior to 1963.Footnote 2 To be consistent with the pricing model described in Section 1, these growth rates were expressed as log-returns before the correlations were calculated.
Correlation of real equity return with real wage growth

The standard error in a correlation coefficient estimated from N years' data is 1/√N, thus the estimated correlations for time lags of one and three years are on the borderline of significance at the 5% level. Table 1 provides reasonable evidence that real equity returns are positively correlated with real wage growth after time lags of between one and three years, which is consistent with our understanding of the fundamental economics.
3 Modelling the return on an asset providing a cash flow linked to final salary
Let:
• S t=salary of an individual at time t
• V t=value at time t of a cash flow payable at time T equal to S T
• δt+1S=random force of salary growth between time t and t+1
• δt+1V=random force of return on V t between time t and t+1
We assume that

The relationship between δtS and δtV is deduced from


By definition V T=S T, hence

Based on the evidence outlined in the previous section, we now propose that δtS is related to recent returns on the equity market by the following formula

where:
• μS is the unconditional expectation of the force of salary growth
• D is the duration in years over which salary growth and equity returns are correlated
• a j is the parameter linking salary growth and equity return at a time-lag of j years
• εtS is the random noise term for the force of salary growth between t−1 and t
Taking the unconditional covariance of each side of equation (10) with δt−kM gives

Our assumption that δtM is i.i.d. implies that the only non-zero term in the above summation occurs when j=k, hence

where c k is the correlation between δtS and δt−kM.
Covariance of salary-linked asset with the market portfolio
Taking the conditional covariance of each side of equation (9) with δt+1M gives

Our assumption that δtV is i.i.d implies that the only non-zero term in the left summation occurs when k=t+1, hence

Using equation (10) to substitute for δkS in the above equation gives

The only non-zero term in the inner summation occurs when k−j=t+1, hence

If T>D, the above equation can be re-written as

And using equation (11), the beta of the salary-linked asset can be expressed as

Variance of return on salary-linked asset
It is necessary to estimate the unconditional variance, σV2, in order to determine μV from the CAPM formula given by equation (7). Taking the conditional variance of both sides of equation (9) gives

As δtV is assumed to be i.i.d., the left summation simplifies to the sum of the unconditional variances, to give

Using equation (10) to substitute for δkS gives

As δtM and εtS are i.i.d. and uncorrelated to each other, the double-summation above can be expressed as a linear combination of their unconditional variances. For T≫D, the following approximation holds

And using equation (11) to substitute for a j gives

An expression for the variance of the error term is obtained by taking the unconditional variance of both sides of equation (10)

Using equation (11) to substitute for a j gives

And eliminating the variance of the error term between equations (13) and (14) gives

4 Fitting the model to UK data
As investors are interested in the real value of their future wealth, we assume that the pricing model derived in Section 1 is framed in real currency units (i.e. net of price inflation). It follows that our parameter estimates should be derived from real returns. The following parameter estimates were obtained from UK data over the period 1946–2005:

The parameter for the real risk-free return, μR, should be the real redemption yield on a risk-free, long-dated, zero-coupon bond, giving a payout indexed in line with price inflation. The nearest UK equivalent would be the British government index-linked stock redeemable in 2055, which currently offers a real annual redemption yield of 1.1%,Footnote 3 so we shall assume:

Inserting the estimated parameters into equation (12) gives

From equation (15) we obtain

And from equation (7) we obtain

Thus, the discount rate that should be used to value the salary-linked asset is about 0.5% per annum above the risk-free return. This small difference is because the estimated beta of the salary-linked asset is only 0.086. If we examine the formula for the beta, we see that

The beta of the salary-linked asset is small, because the standard deviation of real salary growth is estimated to be less than one-eighth the standard deviation of the real return on the market portfolio. This results in a small risk premium, in spite of the relatively high long-term correlation between equity returns and salary growth.
5 Conclusion
Estimating the market value of final salary pension liabilities has become necessary because of pension accounting standards that require unfunded pension liabilities to be disclosed at fair value. As no market exists for these liabilities, pricing models from financial economics are required to estimate a fair price for them.
Recent standards – such as SFA8 87, IRS 19, and FRS 17 – have prescribed discount rates linked to the market yield on investment grade corporate bonds to produce a notional market value for the pension liabilities. This approach incorporates an ad hoc adjustment for default risk, but makes no allowance for Beta risk arising from the positive covariance of pension liabilities with the equity market.
We have shown that allowing for Beta risk requires an addition of approximately 0.5% per annum (or 50 basis points) to the discount rate. Although this is small compared with the equity risk premium, it would make a significant difference to the value of the pension liabilities disclosed by a plan sponsor in its financial statements.
6 Postscript: A note on the pricing model
The pricing model used in this paper assumes that real returns on any tradable asset are independent and identically distributed. This is the simplest model of an efficient market (Fama, Reference Fama1965) and it seems unlikely that a workable pricing model could be formulated in the absence of market efficiency. An inefficient market is one in which some investors are behaving sub-optimally, while the assumption underpinning most financial pricing models is that the market has attained an equilibrium in which all investors have maximized the expected utility of their future consumption (or wealth).
However, empirical research now suggests that equity returns, when measured over long periods, are not independently and identically distributed. Shiller (Reference Shiller1989) postulates that the equity market overreacts to information causing ‘excess volatility’ in the short run and mean reversion in the long run. Hirschey (Reference Hirshey2003) concurs, writing:
Both short-run and long-run rates of return in a perfectly efficient stock market follow a random walk … Stock market evidence and behavioural finance research on the overreaction hypothesis, however, are consistent with a predictable process of long-term return reversal in stock market returns.
This implies that the equity risk premium varies over time, rather than being a constant, as assumed in this paper. It would be highest towards the end of a bear market, when the market has overreacted to bad news, and lowest towards the end of a bull market, when the market has overreacted to good news. The difficulty with such a phenomenon, as noted by Campbell and Viceria (Reference Campbell and Viceira2002), is its implication that all investors should increase the equity weighting of their portfolios at a time when the supply of equities (as measured by market capitalization) has fallen. This is clearly inconsistent with a general equilibrium. A way of resolving this difficulty, while preserving the assumption of rational behaviour, is to assume that risk preferences vary over time in accordance with the ‘habit formation’ conjecture of Campbell and Cochrane (Reference Campbell and Cochrane1999) . Thus, investors would be unusually risk-averse at the end of a bear market and unusually risk-tolerant at the end of a bull market.
What are the implications of a time-varying equity risk premium for the appropriate discount for salary-linked cash-flows? The net supply of salary-linked assets is zero (the asset of a pension plan member being the liability of an investor). To maintain a zero optimal weighting in the wealth portfolio, the discount rate would have to move in the same direction as the equity risk premium. The extent of this movement is difficult to gauge because the parameters affecting the Beta would probably also be time-varying in such a market. The figure of 50 basis points derived in this paper perhaps gives us an ‘average’ for the whole market cycle and an indication of the order of magnitude. The derivation of a time-varying discount rate would evidently require a new model incorporating mean-reverting equity returns and time varying risk preferences.