International organizations have become increasingly important actors in international politics. They have proliferated, expanded in membership, acquired new legal enforcement powers, and extended their reach into the details of domestic political economy in their member states. A few, including the International Monetary Fund (IMF, or simply the Fund), command significant resources and wield considerable authority. Some critics have argued that these international organizations are sufficiently autonomous to create a democratic deficit at the international level, as they pursue a vision of “undemocratic liberalism.”Footnote 1 Other critics have argued that international organizations are nothing more than instruments in the hands of powerful states.Footnote 2
These critiques, of course, cannot simultaneously be true, and both run into difficulties. The puzzle that the rogue-agency view cannot explain is why the principals have chosen to delegate so much authority. In principal-agent terms, this view posits that both screening and monitoring have failed: the principals are unable to select agents with preferences similar to their own, and are unable or unwilling to exert effective control. In this case, rational principals should refuse to delegate.Footnote 3 I find little support for the best developed of the rogue-agency theories, which are derived from a public choice perspective.Footnote 4 The puzzle that the power politics school is unable to explain is why weaker states participate in international organizations, if their policies simply reflect the preferences of the powerful. In order for institutions to be useful to powerful states, they must elicit voluntary participation, which means that there must be sufficient agreement about common purposes that weaker states can expect to benefit from cooperation.
This essay develops an alternative view, which I call informal governance. International organizations operate according to two parallel sets of rules: formal rules, which embody consensual procedures, and informal rules, which allow exceptional access for powerful countries. In this view, the danger embodied in delegation is not that the agency will run out of control, but that it will be captured by the most powerful state in the system. Consequently, states will only agree to delegate extensive powers to international organizations when they expect to share broadly similar objectives. During ordinary times, the organization produces predictable policies that express the consensus view of its most influential members, and it enjoys broad discretion within its zone of delegation. However, the leading state—the “G1,” as the United States is often called within the IMF—may intervene and assume temporary control when urgent strategic objectives override its interest in the organization's long-term goals. Informal governance practices allow it to retain decisive influence in the organization while shedding most of the formal levers of power. The other leading states tolerate these practices, so long as they are not exploited too frequently, because they make the institution more valuable to the United States and make it less inclined to exercise outside options. Informal influence must be exercised with discretion, however, in order to avoid undermining the legitimacy of the organization; and there is growing evidence that the United States has created a crisis of legitimacy in the IMF and other international organizations by abusing its privileged role.
I test hypotheses derived from this model for the case of the IMF using newly available data on the conditionality of IMF programs from 1992–2002. The implication for the IMF is that one should expect conditionality—the packages of policy reforms that countries promise to undertake to receive financial support from the Fund—to reflect long-term economic policy priorities during normal times in ordinary countries, but to reflect U.S. interference during crises in politically important countries. Two corollaries follow from the argument that the motivation for the United States to intervene is to provide a favor to a valued client. First, U.S. intervention should reduce, rather than increase, conditionality. Second, because countries draw on their reserves of influence with the United States only when the stakes are high, the effects of U.S. influence should appear only when IMF support is particularly important to the borrower. I find support for each of these hypotheses. Furthermore, the strength of U.S. intervention depends on the institutional capacity of the borrower, which I interpret to mean that U.S. intervention depends on the balance of influence between the aid recipient and the donor.
I introduce three methodological innovations. First, the dependent variable measures the substantive scope of conditionality, rather than the raw number of conditions. I show that IMF programs vary considerably in substantive focus, and that their breadth responds to domestic political constraints. Second, I use a bivariate probit with partial observability model of participation in IMF programs to generate measures of bargaining power. Third, I introduce a new measure of state capacity, which is derived from the pattern of missing data reported to the IMF.
Informal Governance
The degree of the IMF's autonomy is controversial. The IMF was not designed to be the independent world central bank that Keynes envisaged; from the beginning, its members, most notably the United States, expressed a preference for a member-controlled organization rather than a supranational one.Footnote 5 However, the Fund's management and staff have gradually gained autonomy from the shareholding countries represented on the Executive Board, and critics of the IMF fear that this autonomy goes too far.Footnote 6
Conditionality is not stipulated in the IMF's Articles of Agreement and was originally instituted at the insistence of the United States, over the objections of the rest of the membership. After the collapse of the Bretton Woods system of fixed-exchange rates, the Fund reinvented itself as an agency with extensive involvement in the politics of development, and managing conditionality became a more important part of its mandate. As late as the 1970s, only 26 percent of IMF loan disbursements involved substantial conditionality, but the Latin American debt crisis in the 1980s and the expansion of lending to Africa increased this figure to 66 percent by the end of the 1980s.Footnote 7 In the subsequent decade covered by the present study, the number of conditions specified in an IMF program steadily climbed as the Fund sought to manage the transition from state planning to the market in former communist countries and grappled with the importance of financial sector issues in the East Asian crisis. At the same time, the scope of conditionality ventured into areas of domestic economic structure and policies outside the Fund's traditional purview and competence. The bureaucratic rent-seeking view,Footnote 8 which is inspired by public choice analysis and influences prominent policy recommendations such as the Meltzer Commission Report,Footnote 9 views this as an expression of an organizational interest in promoting mission creep.
An alternative critique assumes that international organizations simply reflect the interests of a few powerful states, or of one. An impressive amount of corroborating evidence indicates that major shareholders are able to skew the distribution of IMF loans and to subsequently undermine the enforcement of conditionality.Footnote 10 Similarly, countries that enjoy special relationships with major IMF shareholders may be able to avoid extensive conditionality when they borrow from the Fund.Footnote 11 In almost all cases, the evidence indicates that the powerful shareholder exercising influence over the IMF is the United States.Footnote 12
One interpretation consistent with this evidence is that the IMF is simply a tool in the U.S. arsenal. The IMF's Articles of Agreement, its system of indirect representation of members, its formal lending criteria, and its weighted voting mechanism—its formal governance institutions, in short—are components of a polite fiction that hides its true purpose. To the extent that these arrangements matter at all, they are epiphenomenal, because they reflect the distribution of power.Footnote 13 The puzzle for this power-politics interpretation, however, is explaining why weak states consent to participate. Why should weak states participate in an arrangement skewed toward the interests of the strong, and why should secondary powers tolerate an arrangement that disproportionately favors the leader of the system?
I propose informal governance as an alternative model. The building blocks of the argument are: (1) legitimacy defined in terms of voluntary participation; (2) conditional delegation; (3) common long-term interests and conflicting short-term interests; and (4) formal and informal governance of international organizations.
In order for international institutions to serve anyone's interests, they must enjoy minimal legitimacy, because they must elicit voluntary participation. Institutions are useful in order to coordinate expectations, define rules, and facilitate collective action when there are common interests to be achieved through collaboration. In order for this to be the case, institutions have to be designed in such a way that all of their members benefit from participating, if not in every instance, at least in expectation. From this perspective, the design of international organizations depends at least as much on the distribution of interests in the issues at stake as it does on the nature of the transaction costs involved.Footnote 14 The allocation of voting rights has to balance the fact that more powerful states have more attractive outside options, while even weak states must be offered enough to prefer participation over exit. The formal allocation of voting rights does not fully describe the distribution of authority within the institution, because powerful states can exert informal influence. However, formal rules and standard procedures determine the status quo that prevails when the leading state chooses not to intervene, and it cannot intervene too often without undermining the value of the organization.
This implies that IMF decision making follows a two-track model, which I term conditional delegation. In ordinary times, the United States and other shareholders have no compelling interest in intervening in the details of conditionality, and the Fund creates policies autonomously. The major shareholders have a common interest in promoting prudent macroeconomic management, market-oriented economic reforms, and trade openness, and the Fund is a technocratic agency with staff selection procedures that lead it to pursue these objectives, so there is no need to monitor its daily activities closely. Delegation is optimal for the principals because the agent's type is known. However, the shareholders also have fluctuating short-term strategic interests in particular countries, and for the system leader these interests can be sufficiently intense to override its economic policy preferences. In order to make delegation and consensual decision making tolerable for the United States, therefore, the other leading states acquiesce in an arrangement that allows the United States to assume temporary control of the organization when its core interests are affected.
This arrangement may lead to opportunism, so delegating more authority to international organizations increases the danger that the institution will be captured by the leading state. I illustrate this below with reference to the IMF, but it has broad implications for the theory of delegation that differ from the received wisdom.Footnote 15 Whereas functionalist theories of delegation emphasize variations in transaction costs and deliberate design of institutions to balance the costs imposed by agency and collective action, this view suggests that variations in delegation respond to variations in the intensity of long-term conflicts of interest. Where conflict of interest is perceived as systematic and lasting, as in trade, weaker states will be reluctant to delegate much rulemaking authority to agencies that subsequently might be captured by their stronger rivals. Indeed, one sees that the World Trade Organization (WTO) has much more limited autonomy than the IMF. The WTO is limited to adjudicating disputes about the application of existing rules, rather than to making rules, and the legalization of the WTO dispute resolution procedure was vigorously resisted by developing countries, which anticipated—correctly, as it turns out—that panels would rarely rule in their favor.Footnote 16 Similarly, European states have delegated substantial authority to the European Union in areas where they have broadly congruent interests but have allowed it only a limited role in setting foreign policy, where national differences are deeper and more lasting. In this view, the relative autonomy of international financial institutions is not a result of disagreement among the major shareholders,Footnote 17 but of the fundamental agreement of the shareholders on the general principles of financial stabilization, market openness, and liberal economic reform.
This is not to say that there is no conflict among the major players in international finance, but rather that the conflict has less to do with the content of the rules than with when to make exceptions to them. In particular cases, shareholders may find it convenient to use IMF programs as an inexpensive form of foreign aid.Footnote 18 In an emergency, the IMF can mobilize more resources and act more expeditiously than the U.S. Agency for International Development, and the IMF can lend without U.S. congressional approval. The United States has drawn on its influence at the Fund to attempt to induce recipient governments to support its foreign policy objectives, and at times has pressured the Fund to be lenient because it has been reluctant to risk destabilizing friendly regimes. Although the United States shares an interest in stabilizing the global economy with the other Group of 7 (G-7) countries, it disagrees with them about how important other interests are—such as strategic objectives in the Middle East—that are extraneous to the concerns of international finance but temporarily come into conflict with the long-term objectives of the IMF. Common long-term interests in promoting economic development and open markets suffer when the Fund's priorities are subordinated to other objectives, because this undermines the credibility of the loans-for-reforms contract.
How does a country that holds only 17 percent of the voting power in an organization exercise a controlling interest in its activities? The United States does this through informal participation, in a way that is similar to the way minority shareholders can control publicly held corporations if they exert sufficient effort. The smaller shareholders are content to free-ride, because they know that their interests are unlikely to come into conflict with those of the United States in most cases. Furthermore, the United States has an overwhelming advantage over other states in its capacity to participate informally in IMF decision making, and the informal practices of the Fund amplify that advantage. In particular, two practices that might appear to strengthen the Fund's autonomy—unanimity voting and the centralization of information—in reality serve as back doors that allow the United States to exert a controlling influence.
According to the IMF's formal procedures, the managing director exercises a remarkable degree of gatekeeping power and proposal power as chair of the Executive Board. Voting on the Executive Board is almost always unanimous, and amendments are not allowed to country-lending items because they have been negotiated with country authorities before they are brought to the Board for ratification. In effect, the managing director can control the agenda and choose the most preferred policy from the feasible set. However, informal participation allows influential shareholders to control the substance of the management proposal, assuming the formal proposal-setting prerogatives of the chair for themselves. This allows the United States to exert effective control by participating much more actively than the other shareholders. The United States has a tremendous organizational advantage over other countries because it has a more extensive diplomatic corps, particularly important private financial institutions, numerous advantages in gathering information, and all of the advantages of having the IMF located in the U.S. capital, in addition to issuing the international reserve currency and commanding the resources of a superpower. With the exception of France and England, which exercise substantial influence in their respective spheres in Africa, the United States is usually the only active participant.
These advantages are increased by rules that centralize information. There are extensive formal rules that insulate the design of conditionality from participation by shareholders through their executive directors. Except for the borrower's representative, executive directors do not participate in missions to countries or the negotiation of programs. In addition, they are not privy to the confidential documents that are key to the negotiations, the mission briefs that determine the parameters of the negotiator's discretion and the back-to-office reports about the progress of negotiations.Footnote 19 This centralization of information generally prevents executive directors from influencing conditionality, but it does not prevent the United States from being fully informed. For example, the U.S. executive director routinely interviews chiefs of mission before and after missions to Latin American countries. In extraordinary cases such as Mexico, Russia, Indonesia, and Korea, senior U.S. Treasury officials were intimately involved in the details of the negotiations.Footnote 20 Confidentiality provides the IMF management with an information advantage over the Executive Board and a measure of autonomyFootnote 21 but simultaneously allows the United States to centralize control.
The model of informal governance is broadly consistent with the power politics view that international organizations reflect U.S. influence, but it generates several testable hypotheses that are not implied by that perspective. First, the model predicts that variation in delegation reflects variation in conflicts of long-term interests, so that institutions such as the IMF, which preside over issues in which conflicts of interest are short-term, should enjoy substantial autonomy within their zones of delegation. Second, it predicts that U.S. influence should be exercised to reduce conditionality, rather than to expand it, because the incentive for participating in the process is to accommodate the interests of an important client. An alternative possibility is that U.S. intervention takes a form similar to trade policy, and that narrow, well-organized private-sector interests lobby to insert conditions into programs.Footnote 22 To the contrary, the informal governance model assumes that private-sector interests in developed countries are generally well-served by the default option of allowing the Fund to develop policy autonomously, so interest groups have weak incentives to organize. The United States participates when its security or broader strategic interests become involved, because these interests are not ordinarily represented in IMF objectives.
Third, the model predicts that U.S. participation in program design should be skewed toward strategically important countries. Using informal influence to roll back conditionality is costly because it overrides long-term U.S. economic interests and undermines the legitimacy of the IMF. Consequently, it will only be done on behalf of important countries, when foreign policy objectives override economic analysis. In Argentina in 2001, for example, the U.S. State Department and National Security Council pushed for extending loans, while the U.S. Treasury was initially reluctant.Footnote 23 Fourth, these strategic interests only become operative when securing IMF financing becomes a high priority for the borrower. The U.S. motive for intervening in the Fund's operations is to respond to a client state's request for support. From a borrower's perspective, influence with the United States is a valuable resource, which should only be drawn down when the stakes are high. Thus, the effects of the borrower's strategic importance should be conditional on the borrower's external vulnerability. Together, the hypotheses that U.S. influence should be used selectively, that that it should reduce conditionality, that it should only be available to important countries, and that it should only be used when those countries are vulnerable make possible a sharp test of the informal governance model.
Alternative Hypotheses
Implicit or explicit in most critiques of IMF autonomy is a bureaucratic rent-seeking view of international institutions: the Fund is an autonomous agent that seeks to maximize conditionality, and once released from Pandora's box, it exploits opportunities for conditional lending to promote its own influence in the international system.Footnote 24 This parallels arguments that the European Commission and the European Court of Justice have acted strategically to promote European integration and the influence of European institutions, sometimes over the objections of national governments.Footnote 25 The principals, in this view, are unable or unwilling to monitor the behavior of their agent very closely, so the Fund enjoys wide latitude to select loan recipients and to design conditionality.Footnote 26 Expanding the number of loan recipients and the invasiveness of its preferred policy reforms makes the IMF a more vital player in the international economy, and thereby promotes the careers and improves the outside options of its employees. Furthermore, some argue that the Fund has an interest in expanding the number of policy variables that it attempts to control and choosing policy targets that are difficult to monitor in order to prevent effective monitoring by its own principals.Footnote 27 The IMF has the most discretion to determine the scope and nature of conditionality when a country's short-term economic prospects critically depend on receiving IMF financial support. Therefore, if the IMF attempts to maximize conditionality, the conditions should be most extensive when borrowers are most vulnerable. I test this proposition with the null hypothesis that rather than attempting to maximize conditionality, the IMF negotiates an optimal package of reforms based on a technical conception of conditionality, reflecting national circumstances.Footnote 28 In this case, conditionality need not be associated with the Fund's bargaining leverage.
A domestic-politics variant of this approach focuses on agency problems within the borrowing country, emphasizing that Fund policies undermine political participation and representation in the countries to which the IMF lends. In this view, governments participate in Fund programs to escape accountability to voters or otherwise evade domestic political constraints. Critics have argued that governments engage in IMF programs to gain leverage vis-à-vis domestic opponents, using the programs to depress real wages and transfer wealth to economic elites.Footnote 29 For example, a government might negotiate a program with the IMF that represents its true preferences but then blame the Fund for imposing these policies on it against its will. This allows the government to confront domestic actors that are not privy to the negotiations with a fait accompli—they must either support the government's program in spite of their misgivings or forfeit IMF support—while making it more difficult to organize punishment. The testable implication of this argument is that governments have incentives to accept more intrusive conditions if they are constrained by legislative opposition or numerous coalition members, because conditions are a means for leaders to nullify the constraints of domestic politics. The null hypothesis—also an influential view—is that the borrowing country prefers fewer conditions and will exercise any leverage it has to reduce the scope of conditionality.Footnote 30 In this view, represented by the literature on two-level games, domestic constraints represent bargaining leverage and should be associated with less intrusive forms of conditionality.Footnote 31
Describing IMF Conditionality
Twenty-five years ago, Williamson summarized the charges of the IMF's critics as including a doctrinaire adherence to free markets, insensitivity to individual country conditions, and the overriding of national sovereignty.Footnote 32 The Fund continues to be criticized for applying one-size-fits-all policy prescriptions without sensitivity to context, ignoring borrowers' domestic political constraints, and promoting the interests of major shareholding governments (or their elites) at the expense of borrowing countries' needs.Footnote 33 Especially following the Asian crisis, the IMF was faulted for conditionality that sought to control too many policy variables, many of which extended beyond its traditional areas of competenceFootnote 34; moreover critics claimed, such conditionality did not help and may even have hurt economic prospects.Footnote 35 Sympathetic insiders and the Fund itself have conceded that conditionality may, as a consequence of these shortcomings, have been superficially implemented, requiring a shift to greater “ownership” of reform by country authorities and “streamlining” of its content.Footnote 36
Much of this debate has taken place in the absence of quantitative data about the content of conditionality. This article uses a new data set extracted from the IMF's Monitoring of Agreements Database (MONA), which covers the ninety-six countries that participated in IMF programs between 1992 and 2002. I reorganized the data in terms of country-month units. Thus, for each country-month, I identify whether the country was participating in an IMF program and, if so, what performance criteria were currently applicable. The database codes IMF conditionality in nineteen categories, representing the most frequently applied types, ranging from fiscal and monetary policy to exchange rate restrictions and structural reforms.
The data measure quantitative macroeconomic performance criteria and structural benchmarks, which are the key yardsticks of compliance with conditionality. Performance criteria are formal conditions that must be met by a corresponding test date, or officially be waived by the Executive Board in the event of noncompliance, in order for scheduled disbursements to be made under IMF programs. Benchmarks are more specific structural reforms, such as privatization, deregulation, and tax reform, that are used to determine a country's compliance with a program but do not automatically call for suspending IMF support in the event of nonfulfillment. This measure of conditionality excludes prior actions, which are conditions that must be met before the Executive Board approves a program. Excluding prior actions means that I focus on the elements of conditionality that a country promises to implement in the future when it contracts with the Fund, rather than on policy concessions that have been implemented to obtain a program.
The dependent variable of primary interest is the number of categories of conditions subject to test in a particular review. This measure of conditionality captures the scope—or, to the Fund's critics, the intrusiveness—of conditionality. This definition of conditionality focuses on the range of obligations that constrain country authorities at any given point in time. This measure of conditionality has advantages over assessments of conditionality that depend, for example, on letters of intent.Footnote 37 As IMF authors have emphasized, conditionality evolves over the course of a program in response to country policies and unanticipated events, so the scope of a program contained in a letter of intent may give a misleading snapshot of what is really a moving target.Footnote 38
In an average month, six categories of conditions were subject to test at the next review; about two-thirds of the time, at least two and no more than ten types of conditions were under review. In about 11 percent of program months, no conditions were tested because the program remained open after the final review. Figure 1 illustrates the variation in the number of categories of conditionality applied. For the statistical analysis of conditionality reported below, I include only observations that fall on test dates to avoid inflating the number of observations.
Scope of conditionality (frequencies of country-months in which each number of categories of conditions applied)

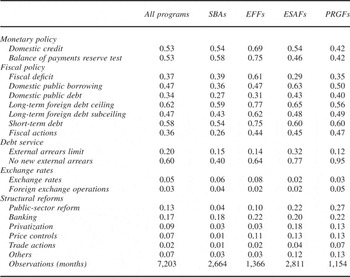
Table 1 illustrates the substantive variety of IMF conditionality. Some aspects of IMF conditionality are very consistent: domestic credit is constrained and reserve targets are set about half the time, and there is almost always some limit on public debt or government spending, although the forms of those restrictions vary. There is a strong emphasis on avoiding foreign debt arrears. Some programs involve extensive regulation of public spending, taxation, borrowing, and the maturity structure of domestic and foreign debt, while others simply set deficit targets. However, the frequent criticism that the IMF systematically promoted fixed-exchange rate regimes in the 1990s is not supported by the data on conditionality.Footnote 39 To the contrary, the data support a different criticism: the Fund is too neutral with respect to exchange rate policy, and allows itself to be captured by country authorities that are determined to defend overvalued exchange rates, as happened in Russia in 1998, Brazil in 1999, and Argentina in 2001.Footnote 40 Although structural conditions of some sort are being tested 43 percent of the time, even this coarse breakdown of structural reforms into six categories indicates that structural conditionality varies enormously across countries. In fact, the way I have aggregated the data understates the case. Experience with the raw data reveals that many structural reforms are very country-specific and refer to proper names of institutions and organizations to be reformed, so a sixfold categorization of structural reforms exaggerates the similarity of conditions across countries.
Coverage of conditions under IMF programs, 1992–2002

Notes:
SBAs = stand-by facilities. EFFs = extended fund facilities. ESAFs = extended structural adjustment facilities. PRGFs = poverty reduction and growth facilities.
The scope of conditionality varies across types of IMF programs. Stand-by facilities (SBAs) are typically one- to two-year programs offered to middle-income borrowers, and they test an average of five categories of conditions per month; extended Fund facilities (EFFs) are typically three-year arrangements with more ambitious goals, and they average seven test categories. Extended structural adjustment facilities (ESAFs) and poverty reduction and growth facilities (PRGFs) are long-term programs for poor countries, and their average levels of conditionality were intermediate between the other two. The replacement of the ESAF program by the PRGF ushered in new poverty-reduction targets and increased the emphasis on debt arrears, but otherwise generally scaled back the application of conditionality.
A principal components analysis of the categories did not reveal any clear pattern of clustering of types of conditions; thus, it is not the case that conditionality follows typical patterns. Rather, conditions are applied idiosyncratically and apparently in response to local circumstances. Only one significant component emerged, and it reflected the number of categories applied, so in the analysis that follows I use the number of categories of conditions as a measure of the breadth of conditionality.
Participation in IMF Programs
The content of conditionality in IMF programs is the subject of bargaining between the Fund and the borrower, and this theoretical setting has implications for the appropriate econometric strategy. Because bargaining involves the strategic use of threats to block agreement, I use data on which countries participate in IMF programs to generate proxies for bargaining power, which I subsequently use to test for bargaining effects. I first estimate the probability of participating in an IMF program. I use a bivariate probit model with partial observability, which, unlike single-equation selection models, captures the fact that participation depends on decisions made both by the IMF and by the borrowing country.Footnote 41 This is a model of onset of IMF programs, so the estimation sample excludes months in which a program is already in place. The model generates two predicted marginal probabilities: the probability that a country applies to the IMF for support and the probability that the IMF is willing to approve a program. These probabilities can be interpreted as measures of expected utilities that the researcher cannot observe: governments that are motivated to accept IMF financing are more likely to apply, and countries that the IMF or its principals have incentives to support are more likely to be approved.Footnote 42 The predicted probabilities therefore measure the bargaining power of the borrower and the Fund, respectively. In the second stage of the analysis, I analyze the substantive scope of conditionality. I employ a negative binomial event count model, where the dependent variable is the number of categories of conditions that apply at each test date during a program.
The dependent variable in the first stage of the analysis is an indicator variable coded 1 when a country participates in a program and 0 when it does not. I treat this variable, z, as the product of two decisions: d i,tG, the government's decision to participate; and d i,tIMF, the IMF's decision to approve a program. One observes z i,t = 1, only when d i,tG = 1 and d i,tIMF = 1. The sample includes only observations in which there is no prior program in force, so the model explains program initiation.
The government's value of participating in an IMF-supported program is expressed by the latent equation:

Similarly, the IMF's value of participation is:

The probability of observing z = 1 is the probability that both latent variables are positive, where the disturbance terms (ɛi,t) are distributed normally with correlation ρ. If Φ denotes the bivariate standard normal distribution, then the probability of program initiation is:

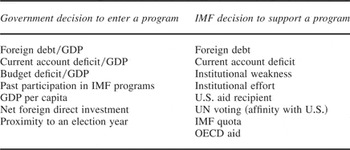
Several macroeconomic and domestic political variables, as well as time series controls, are assigned to both equations, implying that they influence both decisions (see Table 3, below). For example, an extensive literature on participation in IMF programs finds that the level of foreign reserves, changes in reserves, and changes in the exchange rate are correlated with program initiation. In addition, I allow for the degree of democracy, the number of countries participating in programs, and the government's legislative support, left-right policy inclinations, and number of coalition partners to influence both decisions. At this point, however, a set of priors is needed to identify the latent equations, which allows one to distinguish the country's decision to apply for a program from the IMF's decision to extend support. Multiple identification restrictions are required for global identification.Footnote 43 I identify the model by assigning the variables specified in Table 2 to only one equation.
Identifying conditions

To make the results comparable to previous work, I follow Przeworski and Vreeland, and VreelandFootnote 44 in assigning several macroeconomic aggregates normalized by gross domestic product (GDP) to the government's decision, while assigning the same aggregates in absolute terms to the IMF's approval decision.Footnote 45 The substantive import of this assumption is that the IMF may have special concerns about the impact of a country's instability on international markets that the country's own government does not share. I expect that governments' interest in participating in programs depends on the frequency of past participation, which allows for the possibility of recidivism.Footnote 46 In addition, governments of poorer countries and those that are not sustained by substantial inflows of foreign direct investment should have more interest in participating in a program. Furthermore, I expect that governments will be more willing to assume the political risks of unpopular policies shortly after winning an election.Footnote 47
An important identifying assumption for the approval equation is that the IMF's willingness to extend a program depends on a country's technical capacity to implement one, but a country's interest in participating does not. I derive a measure of institutional capacity from the pattern of missing data in the information reported to the IMF and published in International Financial Statistics.Footnote 48 Principal components analysis of the pattern generates two variables. institutional weakness is measured by the first principal component of the missing data, which captures the overall prevalence of missing data. The second principal component has a mix of positive and negative loadings, and a larger value appears to represent the institutional effort that countries make to comply with IMF reporting standards.Footnote 49 In addition, following a growing literature that shows that IMF lending depends on ties with the United States and other leading IMF shareholders, I allow for the possibility that the Fund's willingness to support a program will be affected by U.S. foreign aid to the borrowing country, the association in UN voting patterns between the potential borrower and the United States, and development aid from other countries of the Organization for Economic Cooperation and Development (OECD).Footnote 50 Also, the size of a country's claim on IMF resources (IMF quota) may affect the Fund's willingness to extend a program.
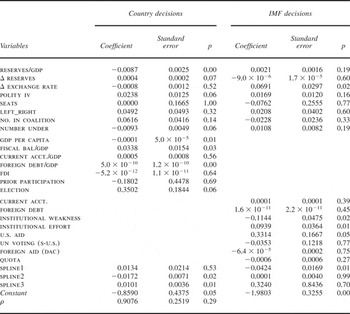
The results, presented in Table 3, indicate that country decisions to apply for IMF support are related to long-term capital needs, macroeconomic vulnerability, and the timing of elections. All else equal, poorer countries (those with lower per capita incomes) are more likely to seek IMF assistance. Foreign exchange reserves play an important role in seeking IMF support. The average country in the sample held 3.5 percent of GDP in reserves, but a country that held one standard deviation more in reserves, or 65.5 percent of GDP, was 54 percent less likely to apply for an IMF program. Higher foreign debt also appears to motivate countries to turn to the Fund, but the quantitative effect is small. A larger fiscal deficit (smaller fiscal balance) appears to steer a country away from the Fund, suggesting that governments expect conditionality to be onerous in a situation of rising public debt.Footnote 51 The average country in the sample had a budget deficit of 1.6 percent of GDP, but a country that had a deficit one standard deviation greater, or 5.5 percent, was 14 percent less likely to apply for a Fund program. Similarly, although low reserves move a country toward a Fund program, countries with deteriorating foreign reserves appear to be reluctant borrowers (p = .07). Domestic political constraints appear to weigh heavily on borrowers' minds, because a government is 42 percent more likely to apply in the year after it has won an election. Democracies, however, show more interest in program participation, suggesting congruence between democracy and economic reforms.
Participation in IMF programs, 1990–2002 (full model)

Notes:
Partial observability bivariate probit. Robust standard errors are adjusted for clustering by country. Number of observations = 14,440 (country months).
Recipients of U.S. aid are 39 percent more likely to have their programs approved. Strikingly, aid from other members of the OECD does not have a discernible influence on IMF decisions to approve programs. institutional weakness, measured by the prevalence of missing data, is negatively related to IMF decisions to extend programs, implying that general weakness in institutional capacity reduces the IMF's willingness to support a program. A onestandard deviation increase in the prevalence of missing data reduces the probability of program approval by 28 percent. Conversely, a government that makes an effort to comply with IMF reporting standards raises the probability that it will be approved for a program: the variable institutional effort is positively related to program approval, with a onestandard deviation shift increasing the probability that the Fund grants a program by 16 percent. Finally, countries that have substantially devalued their exchange rates, or that have recently suffered from exchange rate crises, are more likely to be approved for IMF programs, perhaps because program targets are more likely to be achieved.
These results support one hypothesis derived from the bureaucratic rent-seeking perspective: governments prefer to wait until after elections to turn to IMF programs, to avoid electoral accountability for the short-term pain of reforms. However, several other bureaucratic rent-seeking hypotheses are rejected. Vreeland argues that governments with large numbers of coalition members should be eager to participate in IMF programs to commit themselves to carry out reforms that would otherwise be blocked by veto playersFootnote 52; in contrast, the IMF should be less interested in initiating programs under those circumstances. I find no support for either hypothesis. Vreeland further argues that the Fund's interest in pushing loans should be reflected in a decreasing probability of extending new programs when many countries are concurrently participating, as its interest in expanding its influence becomes satiated and its resources become tightly stretched. I find no such effect.
In sum, countries are eager to apply when their need for emergency financing is severe, but reluctant when the rates of change of macroeconomic aggregates indicate that the Fund will prescribe tough fiscal and monetary discipline. Democracies are more likely to apply for programs, but will generally wait until after an election to come to grips with politically risky reforms. The probability that the IMF will approve a program is higher when the borrower is a recipient of U.S. foreign aid, when the country has high levels of institutional capacity and also makes an effort to collect the data that the IMF requires, and when the borrower's currency has recently depreciated. These results provide a plausible basis for using the predicted probabilities as measures of the interest of the borrower and the willingness of the IMF, respectively, to initiate an IMF program.
The Scope of Conditionality
The dependent variable is the number of categories of conditions subject to test in the current month, ranging from 0 to 19, and I use a negative binomial event count model to analyze variation in the scope of conditionality.Footnote 53 Observations are defined whenever new information about conditionality appears in the data set: when a new program is initiated, when a program review occurs, and when a disbursement is scheduled or actually takes place.
Informal Governance
I have shown above that countries receiving U.S. foreign aid were more likely to be approved for IMF programs. I now turn to a more direct test of this hypothesis, and I find that countries receiving substantial amounts of U.S. foreign aid are also subject to dramatically reduced degrees of conditionality. This effect, indeed, is substantively important enough to overwhelm the effects of all other factors in the countries that are the largest aid recipients. This is not the full story, however. Closer examination of these effects indicates that the United States intervenes in the design of conditionality selectively, rather than systematically. The Fund enjoys conditional delegation of authority to design conditionality. The United States becomes involved only when an important borrower has a pressing need for IMF support, and is less willing to intervene on behalf of countries with weak institutional capacity.
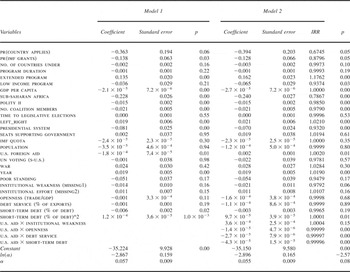
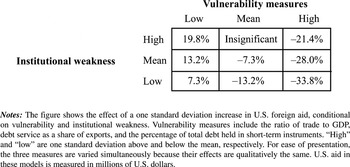
The first model presented in Table 4 indicates that U.S. aid is associated with narrower conditionality. The second model interacts U.S. foreign aid with three measures of vulnerability: trade openness (reflecting dependence on continued access to international markets), debt service and short-term debt (representing rollover risk), and institutional weakness. These interactive effects require interpretation, so Figure 2 presents substantive effects of the variables based on Model 2.
Conditionality under IMF Programs, 1990–2002

Notes:
Negative binomial regression. Number of observations = 2794. Bootstrap estimates = 500 repetitions.
Effects of U.S. foreign aid on scope of conditionality

The entries in the cells are the substantive effects of an increase in U.S. foreign aid by one standard deviation; because of the interactions, these effects depend on the vulnerability and institutional capacity of the borrower. U.S. aid is associated with reduced conditionality, but only when countries are at least as vulnerable as the average program participant—that is, when debt service is at least 18 percent of exports, at least 10 percent of debt is short term (has a maturity of one year or less), and trade accounts for at least two-thirds of GDP. I interpret this to indicate that the influence represented by aid is a resource both for the United States and for the aid recipient, and recipients are reluctant to spend this resource when it is not necessary to do so. When they are not vulnerable, aid recipients choose not to draw on their influence by calling on the United States to influence the Fund. When vulnerability is high, however, the effect of U.S. influence can be large. In a high-capacity state with high vulnerability, a one standard deviation increase in U.S. aid has the effect of reducing the scope of conditionality by one-third.
On the other hand, borrowers that are less vulnerable than the average program participant according to all three measures are subject to greater conditionality: the estimates indicate that the effect of one standard deviation of U.S. aid in a low-capacity state with low vulnerability is to expand the scope of conditionality by about 20 percent. When the United States does not interfere on behalf of a country that has substantial latent influence, the Fund management may seize the opportunity to impose a robust set of conditions that will provide strong grounds for suspending financing in the future in the event of noncompliance. It is important to note, however, that the number of observations of IMF programs in cells with low vulnerability on all dimensions is relatively small and, hence, this effect refers to relatively few recipients of IMF support.
The United States appears to be less willing to intervene on behalf of low-capacity states (those with substantial missing data), which are more highly penalized for aid when not vulnerable and less advantaged by their influence with the United States when vulnerable. This suggests that the substantive significance of U.S. foreign aid depends on the strength of the recipient state. Strong states are nearly equals, and the fact that they are important enough to the United States to receive aid indicates that they have leverage that they can use to demand concessions. Weak states in Africa, by contrast, may depend on foreign aid for 10 percent of GDP and as much as two-thirds of government consumption, and are in no position to make demands.
A simple association of U.S. foreign aid with narrower conditionality might be attributed to omitted variables, such as state capacity or wealth. I have controlled for the obvious suspects; nevertheless, the conditional effects predicted by the informal governance model provide more conclusive evidence. The informal governance model provides a causal mechanism to explain why U.S. influence is turned on or off by international financial vulnerability, and it is difficult to explain such conditional effects in terms of an omitted variable.
IMF Objectives
As noted above, the bivariate probit model employed at the selection stage generates two predicted probabilities: the marginal probability that a country applies to the IMF for support, and the marginal probability that the IMF is willing to approve a program. I use these predicted values as measures of bargaining power.Footnote 54 The bureaucratic rent-seeking model offers a clear-cut prediction about the first of these variables: the IMF imposes the maximum possible level of conditionality, so countries that are motivated to accept IMF support are compelled to accept more conditions.Footnote 55 The results contradict this expectation, however. Countries that are eager to receive loans accept no more restrictions than those that are reluctant. Instead, I see a pattern in which the IMF imposes more conditions on reluctant borrowers and fewer on countries that are eager to participate. Perhaps IMF staff judge that countries that are highly motivated to seek IMF loans also have strong internal incentives to carry out reforms without explicit IMF conditionality, and that it is the reluctant reformers who require extensive surveillance. Indeed, formal work has shown that under conditions of incomplete information it is optimal to use more flexible forms of conditionality when the borrower is believed to be motivated to reform, in order to take advantage of local knowledge.Footnote 56 For present purposes, however, it is significant that the IMF refrains from imposing maximum levels of conditionality when it has the opportunity to do so; this behavior is inconsistent with the image of an out-of-control agency seeking to expand its influence.
The effects of the probability of program approval are consistent with a bargaining model—programs that the Fund is inclined to approve carry fewer conditions—but a bargaining model suggests that the interpretation of these effects depends on the factors that make program approval likely. The bureaucratic rent-seeking perspective predicts that the IMF should offer programs with fewer conditions when its organizational incentives make it disposed to make loans, which would account for the association between a high probability that the IMF grants a program and reduced conditionality.Footnote 57 However, the results of the first-stage analysis did not support bureaucratic rent-seeking hypotheses about the IMF's motivations for making loans.Footnote 58 On the other hand, the research design makes possible a direct test of the causal mechanism of informal governance. I found above that the most impressive influence on the IMF's willingness to lend was whether a country was a recipient of U.S. foreign aid; now I find that countries that were likely to be granted programs were constrained on fewer policy dimensions. This gives the coefficient in the second stage an interpretation consistent with the earlier findings about the constraining effect of U.S. aid: the United States intervenes to ensure favorable treatment for valued allies, and this undermines the Fund's bargaining position. Countries that are favored in the distribution of IMF programs receive more attractive terms because they know that the Fund's threat to withhold support if they do not accept its policy recommendations is not credible.
Another important dimension of bargaining power is the borrower's need for external financing. Countries that use a large portion of their exports for debt service and that owe a large proportion of their foreign debt in short-term instruments (resulting in greater rollover risk of external financing) should be particularly dependent on nonmarket sources of financing. Indeed, I found above that countries with significant external debt are more likely to seek IMF support, and should therefore be willing to accept more conditions in return for that support. The IMF, on the other hand, aware of its strong bargaining position, should be able to push for far-reaching reforms in this situation.Footnote 59 The bureaucratic rent-seeking perspective indicates that the Fund should exploit these opportunities to extract extensive reform commitments. Similarly, countries with more open economies are likely to be more vulnerable to international supply and demand shocks, and the IMF should therefore enjoy a bargaining advantage.
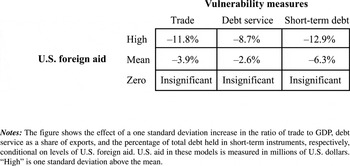
The results again reject these expectations, however.Footnote 60 When these forms of vulnerability have any effect, it is to reduce rather than to increase the incidence of conditionality. As discussed above, vulnerability interacts with U.S. foreign aid in determining the conditionality outcome, so a complete discussion of the effects of vulnerability requires evaluation of these interaction effects. Figure 3 explores the substantive effects of various measures of vulnerability, which depend on the level of U.S. foreign aid. In each column, one vulnerability measure varies by one standard deviation while the others are held constant.
Effects of vulnerability on scope of conditionality

In no case do countries receive more ambitious program targets because they are dependent on foreign trade, are heavily indebted, or are in imminent need of debt restructuring; if these factors affect conditionality, it is only to reduce it. Thus, contrary to popular criticisms of Fund policies during the East Asian crisis of 1997, international vulnerability has not, on average, led to more conditionality. When the IMF faces a particularly vulnerable country, it typically refrains from imposing the maximum possible degree of conditionality. However, none of the three variables that indicate vulnerability has any effect on conditionality in countries that receive no U.S. foreign aid, which implies that vulnerability affects conditionality only because it triggers the latent effects of U.S. influence. In countries that do receive generous amounts of U.S. aid, these forms of vulnerability are reflected in substantially reduced degrees of conditionality. Countries that are both vulnerable to sudden stops of financing and influential in the United States find ways to bring their influence to bear on the IMF, and this is reflected in the pattern of conditionality.
The effect of one form of vulnerability appears to support the bureaucratic rent-seeking view, but the two-stage research design provides explanatory leverage that suggests an alternative explanation. Poor countries receive programs with more extensive conditions. Dreher and JensenFootnote 61 have a similar finding and argue that poor countries have a weak bargaining position and are compelled to accept more conditions. If so, I ought to find this result reflected through the effects of my measures of bargaining power. I do indeed find that poor countries more actively seek support, which appears to support the view that the IMF is able to insist on extensive reforms when the recipient has intense need for a program. However, as noted above, the motivated borrowers that actively seek support are subject to less extensive conditionality, rather than more, which contradicts the bureaucratic rent-seeking hypothesis. Thus, the effect of poverty cannot act through bargaining. Instead, the most plausible interpretation is that IMF staff believe that sweeping reforms are more appropriate or necessary in low-income countries than in middle-income countries.
Borrower Objectives
The effects of domestic political conditions and state capacity, furthermore, reject the domestic variant of the bureaucratic rent-seeking hypothesis, which held that governments use the Fund strategically to misrepresent their preferences to voters. To the contrary, the evidence points to conventional bargaining effects, with bargaining strength deriving from domestic constraints. First, countries with democratic institutions receive markedly fewer conditions: an increase of one standard deviation on the Polity scale, or 5.5 points on a 21-point scale, results in an 8 percent decrease in the number of categories of conditions. This finding is subject to two possible interpretations, both consistent with a bargaining hypothesis. It may be that the Fund is sensitive to the criticism that its conditionality endangers the fragile, new democracies in many borrowing countries. Alternatively, it could be that democratic governments insist on more lenient programs because they face more domestic policymaking constraints than authoritarian governments. In either case, the IMF apparently accommodates the constraints of democratic politics.
Controlling for the degree of democracy, presidential systems receive 7 percent fewer conditions than parliamentary democracies. This effect is consistent with a two-level bargaining interpretation: presidents lack some of the institutional advantages for legislating reform that prime ministers enjoy, and domestic weakness is associated with international bargaining power.Footnote 62 Again, this evidence contradicts the hypothesis that presidents generally turn to the Fund to tie their hands vis-à-vis the legislature because they lack the legislative powers of prime ministers. Certain presidents have clearly done this—Russia's Boris Yeltsin comes to mind—but in the aggregate, presidents bargain with the Fund and use divided government as an excuse to limit their concessions. Yeltsin used this strategy, as well.
Political coalitions, which play an insignificant role in determining participation in IMF programs, nevertheless figure prominently in program design. Fragmented coalition governments constrain, rather than expand, the scope of conditionality. Each additional party added to a coalition government reduces the breadth of conditionality by approximately 2 percent. In addition, governments with leftist ideologies receive less expansive reform programs. Leftist governments are more resistant to expansive proposals for sweeping reform, and the bargaining outcome reflects their preferences. I see no evidence that left-wing governments are particularly anxious to establish credibility or to avoid the policy consequences of populist electoral mandates.Footnote 63
Finally, state capacity variables provide further evidence of bargaining. Controlling for per capita income levels, the weak states in sub-Saharan Africa received 21 percent fewer conditions. Lending facilities with concessional interest rates (SAF, ESAF, and PRGF), available only to low-income countries with generally weak states, are associated with approximately 6 percent narrower conditionality. Furthermore, countries with one standard deviation lower administrative capacity than the mean received 4 percent fewer conditions. This may indicate that IMF staff advocate narrower programs because more ambitious ones would be likely to fail, or it may indicate that countries with weak states leverage their weaknesses into bargaining strength. In either case, weak states bargain for reduced conditionality rather than using the IMF as a cover to implement expansive reforms.
Conclusions
The trade-off between autonomy and legitimacy dominates proposals to reform the IMF and to redistribute voting shares among its members, but the debate is inadequately informed by empirical data. Academic and popular treatments alike assume that IMF conditionality is inflexible, failing to take into account the economic circumstances in which countries find themselves, and failing to adjust to the political realities on the ground that may make dangerous nonsense of idealistic policy reforms. Policy briefs representing the bureaucratic rent-seeking view see the IMF as excessively autonomous, with a tendency to mission creep. This study rejects these conclusions. I find that conditionality varies widely, and that the Fund refrains from maximizing the scope of conditionality when countries are most in need of IMF resources. In addition, whether by design or by necessity, conditionality accommodates domestic political constraints. The evidence suggests that the dangers of an autonomous IMF have been greatly overstated, and that the limitations on the Fund's autonomy are a more serious concern. The Fund typically exercises autonomy, but that autonomy can be revoked when the United States exercises its informal influence over the process of program design. This intervention distorts the application of conditionality and contributes to the IMF's credibility problems. The danger posed by delegating powers to international organizations is that they will be captured by the most powerful state in the system.
This analysis supports four specific hypotheses derived from a model of informal governance. U.S. intervention should reduce, rather than increase, conditionality; intervention should be used selectively, rather than systematically; intervention should only be offered to strategically important countries; and intervention should be limited to countries that are vulnerable enough to seek it. Countries that enjoy the strong support of the IMF's largest shareholder, the United States, enjoy a substantial bargaining advantage because the IMF cannot credibly threaten to withhold support from them. A direct test of these causal links confirms this interpretation: countries that receive U.S. aid are 39 percent more likely to be offered IMF programs, and countries that are more likely to be offered a program accept fewer categories of conditions.
Associations between variables are susceptible to multiple interpretations, so conditional hypotheses are tighter tests of models. The model implies that countries are reluctant to draw on their reserves of influence with the United States when their need for financing is not urgent, leaving the IMF free to negotiate conditionality according to its own objectives. This hypothesis is confirmed by the result that U.S. aid only constrains conditionality when the borrowing country is relatively vulnerable to international shocks compared to the sample of program participants. Furthermore, international vulnerability is found to reduce, rather than increase, the application of conditionality—but only in countries that receive U.S. foreign aid. I describe this situation as conditional delegation: the IMF is autonomous when the borrower is unimportant to the United States or the borrower is unwilling to spend the influence needed to call upon U.S. assistance in dealing with the Fund. The effect of U.S. aid is similarly weakened when the borrower has weak institutional capacity, indicating that the relationship between aid donors and recipients depends on the strength of the recipient state. Strong states can bargain with the United States on a more nearly equal footing; weak states accept what they must.
If correct, the informal governance model offers an explanation for the crisis of legitimacy currently facing the IMF. In recent years the United States has exerted influence in ways that undermined the legitimacy of the IMF in a series of high-profile cases involving Mexico, Russia, Ukraine, Indonesia, Korea, Brazil, Argentina, and Turkey. Many of these missteps took place in phases of IMF programs other than the design of conditionality—for example, in the cases of Mexico and Korea, the amount of access to IMF resources was critical. In the cases of Russia, Ukraine, Argentina, and Turkey, U.S. pressure led the IMF to relax the enforcement of conditionality, which provided temporary relief to unstable governments, but ultimately caused these countries' economic policies to fail. Meanwhile, although borrowing governments appreciated U.S. help managing the Fund, resentment grew over the political and economic quid pro quos that the United States extracted in return for its leverage.
As a consequence, most of these countries and many others have chosen to exit the IMF-sponsored insurance regime and self-insure against international financial risks by undervaluing their exchange rates and accumulating international reserves. The Fund lives on the interest it charges on its loans and now finds itself virtually without customers, so it has announced plans to cut its payroll by 15 percent. For the United States, the consequence of the IMF's unpopularity is the loss of a convenient conduit of influence. The abuse of informal governance procedures tends to undermine the legitimacy of international institutions, and the exploitation of asymmetric interdependence tends to lead to its erosion. For the international system, the consequence of the IMF's legitimacy crisis is the weakening of a key advocate for open markets, economic reform, and financial stability.