



1. Introduction
It is known [Reference Perman, Pitman and Yor41, Reference Pitman44, Reference Pitman46, Reference Pitman47, Reference Pitman and Yor54] that random partitions of the integers  $[n]\,:\!=\,\{1,\ldots,\,{:}\,{\raise-1.5pt{=}}\, n\}$, say
 $\{C_{1},\ldots,C_{K_{n}}\}$, with
 $K_{n}\leq n$ unique blocks and sizes
 $n_{j}=|C_{j}|$, can be generated by sampling n variables conditionally from independent and identical random discrete distributions of the form
 $F(y)=\sum_{\ell=1}^{\infty}P_{\ell}\textbf{1}_{\{U_{\ell}\leq y\}}$, where the collection
 $(U_{\ell})$ are independent and identically distributed (i.i.d.)
 $\textrm{Uniform}[0,1]$ random variables independent of
 $(P_{\ell})\in \mathcal{P}_{\infty}=\{\textbf{s}=(s_{1},s_{2},\ldots)\,:\,s_{1}\ge s_{2}\ge\cdots\ge 0 {\mbox { and }} \sum_{i=1}^{\infty}s_{i}=1\}$.
 $\mathcal{P}_{\infty}$ denotes the space of mass partitions summing to 1 [Reference Bertoin5, Reference Kingman31, Reference Pitman47]. Here we are interested in cases where the distribution of
 $(P_{\ell})$ may be derived from that of a stable subordinator, say
 $\textbf{T}_{\alpha}\,:\!=\,(\hat{T}_{\alpha}(t)\,:\,t\ge 0)$, of index
 $\alpha\in(0,1)$. Set
 $\hat{T}_{\alpha}(1)\,:\!=\,T_{\alpha}$, where
 $T_{\alpha}$ is a positive stable random variable having Laplace transform
 $\mathbb{E}[{\mbox e}^{-\lambda T_{\alpha}}]={\mbox e}^{-\lambda^{\alpha}}$ and density denoted as
 $f_{\alpha}(t).$ Now, following [Reference Kingman31, Reference Perman, Pitman and Yor41, Reference Pitman46, Reference Pitman47], let
 $(\Delta_{\ell})$ denote the ranked jumps of the subordinator
 $\textbf{T}_{\alpha}$, with corresponding Lévy density
 $\rho_{\alpha}(s)=\alpha s^{-\alpha-1}/\Gamma(1-\alpha)$, and construct
 $(P_{\ell}\,:\!=\,\Delta_{\ell}/T_{\alpha})\in \mathcal{P}_{\infty}.$ In this case,
 $(P_{\ell})\sim \textrm{PD}(\alpha,0),$ where
 $\textrm{PD}(\alpha,0)$ denotes the Poisson–Dirichlet distribution with parameters
 $(\alpha,0)$ [Reference Pitman and Yor54]. For
 $K_{n}=k$, the probability of
 $\{C_{1},\ldots,C_{{k}}\}$ is given by what is referred to as the exchangeable partition probability function (EPPF),
 \begin{equation}p_{\alpha}(n_{1},\ldots,n_{k})=\frac{\alpha^{k-1}\Gamma(k)}{\Gamma(n)}\prod_{j=1}^{k}(1-\alpha)_{n_{j}-1},\end{equation}
where, for any non-negative number x,  $(x)_n = x(x+1)\cdots(x+n-1) = {\Gamma(x+n)}/{\Gamma(x)}$ denotes the Pochhammer symbol. The EPPF (1.1) and its two-parameter extension [Reference Pitman42, Reference Pitman43], defined for
 $\theta>-\alpha$,
 \begin{equation}p_{\alpha,\theta}(n_{1},\ldots,n_{k})=\frac{\alpha\big(\frac{\theta}{\alpha}\big)_k}{(\theta)_n} \frac{\Gamma(n)}{\Gamma(k)} p_{\alpha}(n_{1},\ldots,n_{k}),\end{equation}
derived from the two-parameter Poisson–Dirichlet distribution  $(P_{\ell})\sim\textrm{PD}(\alpha,\theta)$ [Reference Pitman and Yor54], constitute the most tractable and notable class of EPPFs that exhibit an infinite Gibbs or product form [Reference Pitman47]. The EPPF (1.2) is obtained by replacing
 $T_{\alpha}$ in the above discussion with another variable
 $T_{\alpha,\theta}$ having density
 $f_{\alpha,\theta}(t)=t^{-\theta}f_{\alpha}(t)/\mathbb{E}[T^{-\theta}_{\alpha}]$. Furthermore, it corresponds to random partitions generated by the two-parameter Chinese restaurant process with law denoted as
 $\textrm{CRP}(\alpha,\theta)$. An important quantity, derived from (1.2), is the probability of the number of blocks
 $K_n = k$, denoted in the
 $\textrm{PD}(\alpha,\theta)$ case as
 $\mathbb{P}_{\alpha,\theta}^{(n)}(k)=\mathbb{P}_{\alpha,\theta}(K_n = k)$ with
 \begin{equation}\mathbb{P}_{\alpha,\theta}^{(n)}(k)= \frac{\alpha({\theta}/{\alpha})_k}{(\theta)_n} \frac{\Gamma(n)}{\Gamma(k)} \mathbb{P}_{\alpha,0}^{(n)}(k),\end{equation}
where  $\mathbb{P}_{\alpha,0}^{(n)}(k)=\frac{\alpha^{k-1}\Gamma(k)}{\Gamma(n)} S_\alpha(n,k)$, with
 $S_\alpha(n,k) = \frac{1}{\alpha^k k!} \sum_{j=1}^k (-1)^j \binom{k}{j} (-j\alpha)_n$ denoting the generalized Stirling number of the second kind. See [Reference Pitman45, Reference Pitman47] for more details in relation to the derivation of
 $\mathbb{P}_{\alpha,\theta}^{(n)}(k)$. Theorem 3.8 and Corollary 3.9 of [Reference Pitman47, pp. 68–69], and more generally [Reference Pitman46, Proposition 13], show that, as
 $n\rightarrow \infty$,
 $n^{-\alpha}K_{n}\rightarrow T^{-\alpha}_{\alpha,\theta}$ almost surely (a.s.). Within this context,
 $T^{-\alpha}_{\alpha,\theta}$ is referred to as the
 $\alpha$-diversity of
 $\textrm{PD}(\alpha,\theta)$.
 $\textbf{T}_{\alpha}$ may be interpreted as the inverse of the local time process
 $(L_{t},t\ge 0)$ of a general Bessel process of dimension
 $2-2\alpha$, which corresponds to Brownian motion when
 $\alpha=1/2$ [Reference Perman, Pitman and Yor41, Reference Pitman47, Reference Pitman and Yor53, Reference Pitman and Yor54]. See [Reference Pitman47, p. 88] for a general description related to the present context. Following [Reference Perman, Pitman and Yor41, Reference Pitman47, Reference Pitman and Yor54],
 $T^{-\alpha}_{\alpha,\theta}$ (or a version having the same distribution) may be interpreted in terms of the local time spent at 0 up to time 1 of a generalized Bessel bridge. See [Reference Perman, Pitman and Yor41, Section 3, Theorem 3.8, Lemma 3.11, Definition 3.14, Corollary 3.15] for more details. We will refer to such variables
 $T^{-\alpha}_{\alpha,\theta}$ as
 $\alpha$-diversity/local times.
 $T^{-\alpha}_{\alpha},$ with density
 $g_{\alpha}(z)\,:\!=\,f_{\alpha}(z^{-\frac1\alpha})z^{-\frac{1}\alpha-1}/\alpha$, is often referred to as having a Mittag–Leffler distribution. Hence,
 $T^{-\alpha}_{\alpha,\theta}$, or any variable equivalent in distribution, is said to be a generalized Mittag–Leffler variable with distribution denoted as
 $\textrm{ML}(\alpha,\theta)$, and it has the power-biased density
 $g_{\alpha}$,
 \begin{equation}g_{\alpha,\theta}(z)=\frac{z^{\frac\theta\alpha}g_{\alpha}(z)}{\mathbb{E}[T^{-\theta}_{\alpha}]}.\end{equation}
See [Reference Devroye11, Reference Devroye and James12] for its simulation and other properties. Note that  $(\tilde{P}_{\ell})\sim \textrm{GEM}(\alpha,\theta)$ denotes the size-biased rearrangement of
 $(P_{\ell})\sim \textrm{PD}(\alpha,\theta)$. See [Reference Feng15, Reference Pitman42, Reference Pitman43, Reference Pitman47, Reference Pitman and Yor54] for further descriptions and the relations between these various concepts. Throughout this paper,
 $G_{a}$ denotes a
 $\textrm{Gamma}(a,1)$ variable, and
 $\beta_{a,b}$ denotes a
 $\textrm{Beta}(a,b)$ variable.
1.1. Mittag–Leffler Markov chains
Variables having generalized Mittag–Leffler distributions  $\textrm{ML}(\alpha,\theta)$ arise in various Pólya urn and random graph/tree growth models [Reference Aldous1, Reference Bloem-Reddy and Orbanz7, Reference Goldschmidt and Haas17, Reference Haas, Miermont, Pitman and Winkel20, Reference Haas, Pitman and Winkel21, Reference James25, Reference James and Ross27-Reference Janson, Kuba and Panholzer29, Reference Peköz, Röllin and Ross37-Reference Peköz, Röllin and Ross39, Reference Rembart and Winkel56, Reference Rembart and Winkel57]. Of interest to us are Markov chains,
 $\textbf{Z}\,:\!=\,(Z_{r},r\ge 0)$, arising in those references in the case where
 $Z_{0}\sim \textrm{ML}(\alpha,\theta)$ and the marginal distribution of each
 $Z_{r}$ is
 $\textrm{ML}(\alpha,\theta+r)$. Furthermore, there is a sequence of random variables
 $(B_{j},j\ge 1)$ defined, for each integer j, as
 $B_{j}=Z_{j-1}/Z_{j}$, and hence there is the exact relation
 $Z_{j-1}=Z_{j}\times B_{j}$, where remarkably the
 $B_{j}$ are independent
 $\textrm{Beta}\big(\frac{\theta+\alpha+j-1}{\alpha},\frac{1-\alpha}{\alpha}\big)$ variables, and
 $(B_{1},\ldots,B_{j})$ is independent of
 $Z_{j}$, for
 $j=1,2,\ldots$ In these cases, the sequence may be referred to as a Mittag–Leffler Markov chain with law denoted as
 $\textbf{Z}\sim \textrm{MLMC}(\alpha,\theta)$ [Reference Rembart and Winkel56]. The Markov chain is described prominently in various generalities, i.e. ranges of
 $\alpha$ and
 $\theta$ [Reference Goldschmidt and Haas17, Reference Haas, Miermont, Pitman and Winkel20, Reference James24, Reference James25, Reference Rembart and Winkel56], characterized by a stationary transition density
 $Z_{r} \mid Z_{r-1}=z$ given by, for
 $y>z$,
 \begin{equation}\mathbb{P}(Z_{r}\in \textrm{d} y \mid Z_{r-1}=z)/\textrm{d} y = \frac{\alpha {(y-z)}^{\frac{1-\alpha}{\alpha}-1}yg_{\alpha}(y)}{\Gamma\big(\frac{1-\alpha}{\alpha}\big)g_{\alpha}(z)}.\end{equation}
We are further interested in cases where we can couple  $\textbf{Z}\sim \textrm{MLMC}(\alpha,\theta)$ with a nested family of mass partitions
 $((P_{\ell,r}),r\ge 0)$. That is, when
 $(P_{\ell,0})\sim\textrm{PD}(\alpha,\theta),$
 $Z_{0}$ is its
 $\alpha$-diversity/local time and induces
 $(P_{\ell,r})\sim\textrm{PD}(\alpha,\theta+r),$ with
 $Z_{r}\sim\textrm{ML}(\alpha,\theta+r)$ as its
 $\alpha$-diversity/local time; additionally, we require that
 $(B_{1},\ldots, B_{r})$ is independent of
 $(P_{\ell,r})$ for
 $r=1,2,\ldots$ Such nested families may be constructed by fragmentation operations on spaces of mass partitions
 $\mathcal{P}_{\infty}$ [Reference Dong, Goldschmidt and Martin13]. Hence, in these cases, we shall write
 $((P_{\ell,r}),Z_{r});\ r\ge 0)\sim\textrm{MLMC}_{\textrm{frag}}(\alpha,\theta)$, and this distributional notation for
 $\textbf{Z}$ appears in [Reference James and Ross27]. More details will be given in Section 3.
1.2. Preliminaries on Poisson–Kingman distributions and Gibbs partitions
We now describe the more general class of EPPFs constituting Gibbs partitions, as derived and discussed in [Reference Gnedin and Pitman16, Reference Pitman46, Reference Pitman47], called Poisson–Kingman (PK) partitions. Those works showed that sampling from  $(P_{\ell})\mid T_{\alpha}=t$ with law
 $\textrm{PD}(\alpha\mid t)$ leads to a general class of random partitions that have an infinite Gibbs (product) structure as a characterizing feature. Specifically, the law of
 $\{C_{1},\ldots,C_{{k}}\} \mid T_{\alpha}=t$ can be expressed as
 \begin{equation}p_{\alpha}(n_{1},\ldots,n_{k} \mid t)=\mathbb{G}_{\alpha}^{(n,k)}(t)\prod_{j=1}^{k}(1-\alpha)_{n_{j}-1},\end{equation}
where
 \begin{equation*}\mathbb{G}_{\alpha}^{(n,k)}(t) =\frac{\alpha^{k}t^{-n}}{\Gamma(n-k\alpha)f_{\alpha}(t)}\left[\int_{0}^{t}f_{\alpha}(v)(t-v)^{n-k\alpha-1}\,\textrm{d} v\right].\end{equation*}
As in [Reference Pitman46], for any non-negative function h(t) satisfying  $\mathbb{E}[h(T_{\alpha})]=1$, we may mix
 $\textrm{PD}(\alpha \mid t)$ over the density,
 $\gamma(\textrm{d} t)/\textrm{d} t\,:\!=\,h(t)f_{\alpha}(t)$, to obtain an infinite class of distributions for the Gibbs random partitions. We shall write
 \begin{equation}(P_\ell) \sim \textrm{PK}_{\alpha}(\gamma)=\int_{0}^{\infty}\textrm{PD}(\alpha \mid t)\gamma(\textrm{d} t)=\int_{0}^{\infty}\textrm{PD}\Big(\alpha \mid s^{-\frac{1}{\alpha}}\Big)h\Big(s^{-\frac{1}{\alpha}}\Big)g_{\alpha}(s) \, \textrm{d} s.\end{equation}
For instance,  $\textrm{PD}(\alpha,\theta)$ arises when
 $\gamma(\textrm{d} t)=f_{\alpha,\theta}(t)\,\textrm{d} t$, which is obtained by setting
 $h(t)=t^{-\theta}/\mathbb{E}[T^{-\theta}_{\alpha}]$. Integrating over (1.6) with respect to
 $\gamma(\textrm{d} t)$ leads to the EPPF of the PK partitions (see [Reference Pitman47, Theorem 4.6] and [Reference Gnedin and Pitman16, Theorem 12]), expressed as
 \begin{equation}p^{[\gamma]}_{\alpha}(n_{1},\ldots,n_{k})=V_{n,k}\frac{\alpha^{1-k}\Gamma(n)}{\Gamma(k)}p_{\alpha}(n_{1},\ldots,n_{k}),\end{equation}
where  $V_{n,k}=\int_{0}^{\infty}\mathbb{G}_{\alpha}^{(n,k)}(t)\gamma(\textrm{d} t)$. Naturally, evaluation of (1.8) relies very much on the form of
 $\mathbb{G}_{\alpha}^{(n,k)}(t)$. Pitman (see [Reference Pitman46, Section 8] and [Reference Pitman47, Section 4.5, p. 90]) developed the Brownian case of
 $\alpha=1/2$, which in many respects is the most remarkable, and showed that the EPPF in that case can be expressed explicitly in terms of Hermite functions or, equivalently, confluent hypergeometric functions. For a general
 $0<\alpha<1$, it is nonetheless non-trivial to obtain a representation of
 $\mathbb{G}_{\alpha}^{(n,k)}(t)$ in terms of special functions or other transcendental functions, a question posed in [Reference Pitman47, Problem 4.3.3, p. 87]. An answer was provided by Theorems 2.1 and 3.1 of [Reference Ho, James and Lau22]. Using representations in [Reference Schneider58, Reference Schneider, Albeverio, Blanchard and Streit59], alternative expressions of
 $\mathbb{G}_{\alpha}^{(n,k)}(t)$ were given in terms of Fox H functions for any general
 $\alpha$, and in terms of readily computable Meijer G functions for the case of
 $\alpha={m}/r$, with co-prime integers
 $m<r$. See [Reference Mathai, Saxena and Haubold34] and references therein, as well as [Reference Ho, James and Lau22], for more on these special functions, especially their connections to fractional calculus.
A distributional interpretation follows from expressing (1.6) as
 \begin{equation}p_{\alpha}(n_{1},\ldots,n_{k}|t)=\frac{f^{(n-k\alpha)}_{\alpha,k\alpha}(t)}{f_{\alpha}(t)}\times p_{\alpha}(n_{1},\ldots,n_{k}),\end{equation}
where  $f^{(n-k\alpha)}_{\alpha,k\alpha}(t)$ denotes the conditional density of
 $T_{\alpha} \mid K_{n}=k$ when
 $K_{n}\sim\mathbb{P}_{\alpha,0}^{(n)}(k)$, and it corresponds to the densities of random variables equivalent in distribution to a variable denoted as
 $Y^{(n-k\alpha)}_{\alpha,k\alpha}$, such that
 \begin{equation}Y^{(n-k\alpha)}_{\alpha,k\alpha}\overset{\textrm{d}}=\frac{T_{\alpha,k\alpha}}{\beta_{k\alpha,n-k\alpha}}\overset{\textrm{d}}=\frac{T_{\alpha,n}}{\beta^{\frac1\alpha}_{k,\frac{n}{\alpha}-k}},\end{equation}
where the variables in the ratios are independent. The equalities in distribution can be read from [Reference James23, (2.11)]. The expression  $\Big(T_{\alpha,n}\,\beta^{-\frac1\alpha}_{k,\frac{n}{\alpha}-k}\Big)^{-\alpha}=T^{-\alpha}_{\alpha,n}\,\beta_{k,\frac{n}{\alpha}-k}$ also arises in [Reference Favaro, Lijoi, Mena and Prünster14, Proposition 2] as the conditional
 $\alpha$-diversity of a
 $\textrm{PD}(\alpha,0)$ distribution. As such, one may represent (1.8) as
 \begin{equation}p^{[\gamma]}_{\alpha}(n_{1},\ldots,n_{k})=\mathbb{E}\left[h\left(Y^{(n-k\alpha)}_{\alpha,k\alpha}\right)\right]p_{\alpha}(n_{1},\ldots,n_{k}),\end{equation}
where the expectation is also identical to  $\mathbb{E}[h(T_{\alpha}) \mid K_{n}=k]$. Although the
 $\textrm{PD}(\alpha,\theta)$ class of models dominates the broad literature, there has been significant interest in the general class of Gibbs partitions [Reference Bacallado, Battiston, Favaro and Trippa3, Reference Caron and Fox8, Reference De Blasi, Favaro, Lijoi, Mena, Prünster and Ruggiero10, Reference Griffiths and Spanò19, Reference Ho, James and Lau22, Reference Lomeli, Favaro and Teh33, Reference Pitman and Yakubovich52]. Our exposition takes another viewpoint of this general class, as we begin to describe next.
1.3. Outline
The results in [Reference Gnedin and Pitman16, Reference Ho, James and Lau22, Reference Pitman46], coupled with refinements in this work, allow us to describe explicit distributions and establish scaled limit theorems for myriad random partitions of [n], and related constructions based on  $(P_{\ell})\sim \textrm{PK}_{\alpha}(\gamma)$. For instance, it is known from [Reference Pitman46, Proposition 13] (see also [Reference Pitman47]) that if
 $K_{n}$ is the number of blocks in a partition of [n] generated by a
 $\textrm{PK}_{\alpha}(\gamma)$ sampling scheme, then, as
 $n\rightarrow \infty$,
 $n^{-\alpha}K_{n}\rightarrow T^{-\alpha}$ a.s., where T has distribution
 $\gamma(\textrm{d} t)/\textrm{d} t=h(t)f_{\alpha}(t)$. In general, however, those results have not been exploited to provide insights in terms of interpretations, or in fact how to utilize the general framework of Gibbs partitions in novel ways, for what would otherwise be interesting exotic random processes. More specifically, for a given choice of
 $\gamma$, how does one interpret
 $(P_{\ell})\sim \textrm{PK}_{\alpha}(\gamma)$ in (1.7)? For example, if
 $\gamma$ corresponds to
 $T_{\alpha} \mid Y=y$,
 $(P_{\ell})\sim \textrm{PK}_{\alpha}(\gamma)$ does not necessarily equate to the distribution of
 $(P_{\ell}) \mid Y=y$. As another example, [Reference Peköz, Röllin and Ross40, (1.2)] describes a class of Pólya urn models based on randomized discrete inter-arrival times that induce random limits corresponding to a broad class of distributions denoted as
 $\textrm{UL}(v,(a_{k})_{\{k\ge 1\}})$. It is a simple matter to select
 $\gamma$ with this distribution, and thus achieve comparable limits; however, there is no immediate interpretation of
 $(P_{\ell})$, etc.
In order to give some insights into issues of novel usage and distributional interpretations of the Gibbs partitions, this paper presents broad-based intertwined themes which we first sketch below. Section 2 shows that  $\mathbb{G}_{\alpha}^{(n,k)}(t)$ may be expressed in terms of Riemann–Liouville fractional operators of orders
 $\nu=n-k\alpha$, for
 $k=1,\ldots n$, and then shows how Gibbs partitions can be used in the decomposition of certain special functions. Results are then obtained for the case of general
 $\nu>0$, which connects to various distributional results and identities, including known results for
 $\textrm{PD}(\alpha,\theta)$ derived from a different perspective. Section 3 presents generalizations of results for
 $((P_{\ell,r},Z_{r});\ r\ge 0)\sim \textrm{MLMC}_{\textrm{frag}}(\alpha,\theta)$ when
 $(P_{\ell,0})\sim \textrm{PK}_{\alpha}(\gamma)$, under the fragmentation regime described in [Reference Dong, Goldschmidt and Martin13]. We use a special identity for products of related beta distributions that arise in the
 $\textrm{MLMC}(\alpha,\theta)$ case, developed in Proposition 2.3, to illustrate interesting mixture representations. Section 4 presents applications of the general developments in Sections 2 and 3 to the case of generalized Mittag–Leffler functions derived from the Laplace transform of
 $\textrm{ML}(\alpha,\theta)$ variables. Section 4.1 describes decompositions of these special functions. Sections 4.2 and 4.3 offer distributional interpretations of the results in Section 4.1 in terms of PK distributions based on conditioning
 $(P_{\ell}) \sim \textrm{PD}(\alpha,\theta)$ on Poisson point process counts over random intervals depending on the relevant
 $\textrm{ML}(\alpha,\theta)$ variables.
2. Connections to Riemann–Liouville fractional operators
We present some results from the viewpoint of fractional integrals indexed by  $f_{\alpha}$ and a parameter
 $\nu>0$. In particular, a simple change of variable allows us to express
 $\alpha^{-k}t^{n}f_{\alpha}(t)\mathbb{G}_{\alpha}^{(n,k)}(t)$ as
 \begin{align}\left(I^{n-k\alpha}_+{f_{\alpha}}\right){(t)} &=\frac{1}{\Gamma(n-k\alpha)}\int_{0}^{t}f_{\alpha}(v){(t-v)}^{n-k\alpha-1}\,\textrm{d} v \nonumber\\[3pt] &=\frac{\mathbb{E}\big[{(t-T_{\alpha})}^{n-k\alpha-1}\textbf{1}_{\{T_{\alpha}<t\}}\big]}{\Gamma(n-k\alpha)}.\end{align}
Replacing  $f_{\alpha}(t)$ with any integrable function f(t), we see that these equations arise as special cases of right-sided Riemann–Liouville fractional operators of orders
 $\nu=n-k\alpha$, for
 $k=1,\ldots n$, defined by
 \begin{equation*}\left(I^{\nu}_+{{f}}\right){(t)}= \frac{1}{\Gamma(\nu)} \int_0^t f(u) (t-u)^{\nu-1} \, \textrm{d} u.\end{equation*}
The left-sided counterpart defined by
 \begin{equation*}\left(I^{\nu}_-{f}\right){(t)}= \frac{1}{\Gamma(\nu)} \int_t^\infty f(u) (u-t)^{\nu-1} \, \textrm{d} u \end{equation*}
can also be considered, though we omit further discussion for brevity. The identity (2.1) leads to natural connections to the field of fractional calculus, wherein the interplay between special functions, probability theory, in particular as it relates to size-biased sampling, and fractional operator theory is illustrated. Noting that  $\mathbb{G}_{\alpha}^{(1,1)}(t)=1$ leads to the equation
 \begin{equation*}\alpha \Big(I^{1-\alpha}_+{f_\alpha}\Big){(t)}=tf_{\alpha}(t),\end{equation*}
which identifies  $f_{\alpha}(t)$ as the unique solution to a particular Abel equation involving general functions f(t) [Reference Jedidi, Simon and Wang30, Reference Pakes35, Reference Schneider, Albeverio, Blanchard and Streit59]. In addition, as can be read from [Reference Pitman46, (18), (19)], the equation and its unicity arise as a special case of properties of infinitely divisible variables [Reference Steutel and van Harn60], and are directly related to size-biased sampling with
 $n=1$. Using (1.9) and (2.1), the conditional density of
 $T_\alpha \mid K_{n}=k$ when
 $K_{n}\sim \mathbb{P}_{\alpha,0}^{(n)}(k)$ can be expressed as
 \begin{equation}{f}^{(n-k\alpha)}_{\alpha,k\alpha}(t)=\frac{\alpha \Gamma(n)}{\Gamma(k)}t^{-n}\Big(I^{n-k\alpha}_+{f_\alpha}\Big){(t)}.\end{equation}
Hence, we have the relation
 \begin{equation*}\Gamma(n)\sum_{k=1}^{n}\mathbb{P}^{(n)}_{\alpha,0}(k)\frac{\big(I^{n-k\alpha}_+{f_\alpha}\big){(t)}}{\Gamma(k)}=t^{n-1}\big(I^{1-\alpha}_+{f_\alpha}\big){(t)}=\frac{t^{n}f_{\alpha}(t)}\alpha .\end{equation*}
2.1. Decomposition of special functions
One of the unexploited features of the Gibbs partitions, beyond the case of inducing various distributions over partitions, is that it provides a method of obtaining decompositions for a host of special functions connected to  $f_{\alpha}$. We further note that while these decompositions will now be shown to arise from basic probabilistic principles, their derivations from other perspectives would not be so transparent.
Lemma 2.1. Let  $\varphi(t)$ denote an arbitrary non-negative function such that
 $\mathbb{E}[\varphi(T_{\alpha})]<\infty$. Set
 $h(t)=\varphi(t)/\mathbb{E}[\varphi(T_{\alpha})]$, and thus
 $\gamma(\textrm{d} t)/\textrm{d} t=h(t)f_{\alpha}(t)$. For each
 $n\ge 1$ there is the decomposition
 \begin{equation}\mathbb{E}[\varphi(T_{\alpha})]=\sum_{k=1}^{n}\,\mathbb{E}[\varphi(T_{\alpha}) \mid K_{n}=k]\,\mathbb{P}_{\alpha,0}(K_{n}=k),\end{equation}
where  $\mathbb{E}[\varphi(T_{\alpha}) \mid K_{n}=k]$ can be expressed as
 \begin{equation}\mathbb{E}\bigg[\varphi\bigg(Y^{(n-k\alpha)}_{\alpha,k\alpha}\bigg)\bigg]=\frac{\alpha \Gamma(n)}{\Gamma(k)}\int_{0}^{\infty}\varphi(t)t^{-n}\big(I^{n-k\alpha}_+{f_\alpha}\big){(t)}\,\textrm{d} t.\end{equation}
Then,
(i)
 $V_{n,k}\,:\!=\,\displaystyle\int_{0}^{\infty}\mathbb{G}_{\alpha}^{(n,k)}(t)\gamma(\textrm{d} t)=\frac{\alpha^{k-1}\Gamma(k)}{\Gamma(n)} \times\frac{\mathbb{E}[\varphi(T_{\alpha}) \mid K_{n}=k]}{\mathbb{E}[\varphi(T_{\alpha})]} ; $
-
(ii)
$\mathbb{E}[\varphi(T_{\alpha}) \mid K_{n}=k]$ can be expressed as
\begin{equation*}\frac{k\alpha}{n}\mathbb{E}[\varphi(T_{\alpha}) \mid K_{n+1}=k+1]+\bigg(1-\frac{k\alpha}{n}\bigg)\mathbb{E}[\varphi(T_{\alpha}) \mid K_{n+1}=k].\end{equation*}


Proof. Equations (2.3), (2.4), and statement (i) follow from the conditional distribution of  $T_{\alpha} \mid K_{n}=k$ as expressed in (1.10), and its density representation in (2.2). Statement (ii) follows from (i) due to backward recursion [Reference Gnedin and Pitman16, Definition 3 or (8)]:
 $V_{n,k} = (n-k\alpha) V_{n+1,k} + V_{n+1, k+1}$, for
 $n=1,2,\ldots$,
 $k=1,2,\ldots,n$, with
 $V_{1,1}=1$.
Remark 2.1. When not considering constructions for  $V_{n,k}$, both (2.3) and (2.4) apply for any integrable real- or complex-valued function
 $\varphi$.
A study of the general class  $\left(I^{\nu}_+{f_\alpha}\right){(t)}$ follows, which connects to various distributional results and identities, including known results for
 $\textrm{PD}(\alpha,\theta)$ derived from a different perspective. See Proposition 2.1 and Remark 2.3 for connections between
 $I^{\nu}_+f_{\alpha}$ and results in [Reference Bertoin and Yor6, Reference James23, Reference Pitman48].
2.2. Properties of $I^{\nu}_+f_{\alpha}$, $\nu > 0$


Throughout, let  $(\tau_{\alpha}(t)\,:\,t\ge 0)$ denote a generalized gamma subordinator with Lévy density
 $\alpha s^{-\alpha-1}{\mbox e}^{-s}/\Gamma(1-\alpha)$. We next provide a study of
 $I^{\nu}_+f_{\alpha}$ for general index
 $\nu>0$, where we derive a subordinator representation which is used to exploit and connect results in [Reference Pitman and Yor54, Proposition 21] and related literature on size-biased sampling in the
 $\textrm{PD}(\alpha,\theta)$ setting.
Theorem 2.1. Select  $h(t)\ge 0$ such that
 $h(t)f_{\alpha}(t)$ is the density of a random variable T, implying
 $\mathbb{E}[h(T_{\alpha})]=1$. Let
 $(\tau_{\alpha}(t)\,:\,0\leq t\leq \lambda^{\alpha}+G_{\frac{\nu}{\alpha}})$ denote a generalized gamma subordinator over a random interval
 $[0,\lambda^{\alpha}+G_{\frac{\nu}{\alpha}}]$. Then, for any
 $\nu,\lambda>0$, we have
 \begin{equation}\int_{0}^{\infty}\textrm{e}^{-\lambda t}h(t) \left(I^{\nu}_+{f_\alpha}\right){(t)} \,\textrm{d} t = \frac{1}{\lambda^{\nu}\textrm{e}^{\lambda^{\alpha}}}\int_{0}^{\infty}\int_{0}^{\infty}h(u+s)f^{(\nu)}_{\alpha,\lambda}(u,s)\,\textrm{d} u\,\textrm{d} s,\end{equation}
where, for a fixed  $\lambda$,
 $f^{(\nu)}_{\alpha,\lambda}(u,s)=\lambda^{\nu}u^{\nu-1}\textrm{e}^{-\lambda u}/\Gamma(\nu) \times \big(\textrm{e}^{\lambda^{\alpha}}\textrm{e}^{-\lambda s}f_{\alpha}(s)\big)$ corresponds to the density of the conditionally independent pair of random variables
 \begin{equation}\bigg(\frac{G_{\nu}}{\lambda},\frac{\tau_{\alpha}(\lambda^{\alpha})}{\lambda}\bigg)\overset{\textrm{d}}=\bigg(\frac{\tau_{\alpha} \big(\lambda^{\alpha}+G_{\frac{\nu}{\alpha}}\big)-\tau_{\alpha}(\lambda^{\alpha})}{\lambda},\frac{\tau_{\alpha}(\lambda^{\alpha})}{\lambda}\bigg).\end{equation}
Hence, we can define the sum as a random process  $(\tilde{T}_{\alpha,\nu}(\lambda);\ \lambda>0)$ by the sum of the random variables in (2.6). Specifically,
 $\tilde{T}_{\alpha,\nu}(\lambda)$ is defined as
 \begin{equation}\frac{\tau_{\alpha}\big(\lambda^{\alpha}+G_{\frac{\nu}{\alpha}}\big)}{\lambda}=\frac{\tau_{\alpha}(\lambda^{\alpha})}{\lambda}\times\frac{\tau_{\alpha}(\lambda^{\alpha}+G_{\frac{\nu}{\alpha}})}{\tau_{\alpha}(\lambda^{\alpha})}=\frac{\tau_{\alpha}\big(\lambda^{\alpha}+G_{\frac{\nu}{\alpha}}\big)}{{\left(\lambda^{\alpha}+G_{\frac{\nu}{\alpha}}\right)}^{\frac1\alpha}}\times{\bigg(\frac{\lambda^{\alpha}+G_{\frac{\nu}{\alpha}}}{\lambda^{\alpha}}\bigg)}^{\frac1\alpha}.\end{equation}
The variables separated by  $\times$ are not independent for fixed
 $\lambda$.
Proof. Equation (2.5) is obtained by noting that the left-hand side can be expressed as  $\int_{0}^{\infty}\big[\int_{s}^{\infty}(t-s)^{\nu-1}h(t){\mbox e}^{-\lambda t}\,\textrm{d} t\big]f_{\alpha}(s)\,\textrm{d} s/\Gamma(\nu)$. In order to obtain the representation in (2.6), first the independent increment property of subordinators gives
 $\tau_{\alpha} (\lambda^{\alpha}+G_{\frac{\nu}{\alpha}})-\tau_{\alpha}(\lambda^{\alpha})$ independent of
 $\tau_{\alpha}(\lambda^{\alpha})$. Furthermore,
 $\tau_{\alpha} (\lambda^{\alpha}+G_{\frac{\nu}{\alpha}})-\tau_{\alpha}(\lambda^{\alpha})\overset{\textrm{d}}=\tau_{\alpha}(G_{\frac{\nu}{\alpha}})$. We can then appeal to [Reference Pitman and Yor54, Proposition 21] to obtain
 $\tau_{\alpha}(G_{\frac{\nu}{\alpha}})\overset{\textrm{d}}=G_{\nu}$, which is otherwise easy to verify.
Corollary 2.1. For a fixed  $\lambda>0$, the random variable
 $\tilde{T}_{\alpha,\nu}(\lambda)$ defined in (2.7) has a density in t as
 \begin{equation}\frac{\lambda^{\nu}\textrm{e}^{\lambda^{\alpha}}}{\Gamma\big(\frac{\nu}{\alpha}\big)}\textrm{e}^{-\lambda t}\int_{0}^{1}f_{\alpha}\Big(tu^{\frac{1}{\alpha}}\Big)u^{\frac{1-\nu}{\alpha}-1}{(1-u)}^{\frac{\nu}{\alpha}-1} \, \textrm{d} u,\end{equation}
and its Laplace transform is, for  $y>0$,
 $\mathbb{E}\big[\textrm{e}^{-y\tilde{T}_{\alpha,\nu}(\lambda)}\big]={\big(1+\frac y\lambda\big)}^{-\nu}\textrm{e}^{\lambda^{\alpha}-(\lambda+y)^{\alpha}}.$
(i) When the density (2.8) is exponentially tilted by
$\textrm{e}^{-yt}$ for a fixed $y>0$, the corresponding random variable can be represented as $\tilde{T}_{\alpha,\nu}(\lambda+y)$.-
(ii) Let
$G_{1}$ denote an Exp(1)-distributed variable independent of $T_{\alpha}$. Then, for $\nu=1-\alpha$, the density of $\tilde{T}_{\alpha,1-\alpha}(\lambda)$, described by (2.8), agrees with the density of $T_{\alpha} \mid G_{1}/T_{\alpha}=\lambda$, specified as $\lambda^{1-\alpha}t \big(\textrm{e}^{\lambda^{\alpha}}\textrm{e}^{-\lambda t} f_{\alpha}(t)\big)/\alpha$. This yields the known identity
which corresponds to the result
\begin{equation*}\frac{1}{\Gamma\big(\frac{1-\alpha}{\alpha}\big)}\int_{0}^{1}f_{\alpha}\Big(tu^{\frac{1}{\alpha}}\Big){(1-u)}^{\frac{1-\alpha}{\alpha}-1} \, \textrm{d} u = \frac{1}{\alpha}tf_{\alpha}(t),\end{equation*}
$T_{\alpha}=T_{\alpha,1}\times \beta^{-\frac{1}{\alpha}}_{1,\frac{1-\alpha}{\alpha}}$ in, for instance, the case $\big(T^{-\alpha}_{\alpha},T^{-\alpha}_{\alpha,1},\ldots\big)\sim \textrm{MLMC}(\alpha,0)$.


Proof. The density and the Laplace transform are straightforward. The result in (i) follows readily from the density in (2.8). The identity in (ii) can be deduced from a careful reading of [Reference Perman, Pitman and Yor41, Reference Pitman and Yor53]; see, in particular, [Reference Pitman and Yor53, Remark 3.6 and (3.q)], which yields the appropriate form of the conditional density.
Remark 2.2. Note that  $G_{1}/T_{\alpha}\overset{\textrm{d}}=G^{\frac{1}{\alpha}}_{1}$. In addition to [Reference Perman, Pitman and Yor41, Reference Pitman and Yor53], this variable arises in many instances with various interpretations. See [Reference Chaumont and Yor9] and [Reference James23, (2.24), p. 1324] for generalities and related references.
2.2.1. Gamma randomization and subordinator representations
Throughout the remainder of this work, let  $(\textbf{e}_{\ell})$ denote a collection of i.i.d. Exp(1) variables, and let
 $\big(\Gamma_{\ell}\,:\!=\,\sum_{k=1}^{\ell}\textbf{e}_{k},\ell \ge 1\big)$ denote the arrival times of a standard Poisson process. A recent treatment in [Reference Pitman49], applied to the case of species sampling models derived from
 $\textbf{T}_{\alpha}$, i.e. sampling from
 $F(y)=\sum_{\ell=1}^{\infty}P_{\ell}\textbf{1}_{\{U_{\ell}\leq y\}}$, where
 $(P_{\ell})\sim \textrm{PD}(\alpha,0)$, shows that a mixed Poisson process
 $\big(N_{T_{\alpha}}(\lambda)=\sum_{j=1}^{\infty}\textbf{1}_{\{{\Gamma_{j}}/{T_{\alpha}}\leq \lambda\}},\break \lambda\ge 0\big)$, where
 $(\Gamma_{\ell})$ are independent of
 $T_{\alpha}(1)\,:\!=\,T_{\alpha}$, has an interpretation as the number of animals/customers arriving up to time
 $\lambda$. Since
 $T_{\alpha}(1)=\sum_{\ell=1}^{\infty}\Delta_{\ell}$, it can be interpreted as the total abundance of animals when each
 $\Delta_{\ell}$ is interpreted as the (ranked) abundance of type
 $\ell$. Notice that
 $\Gamma_{1}/T_{\alpha}\overset{\textrm{d}}=G^{\frac{1}{\alpha}}_{1}$, and
 \begin{equation}\mathbb{P}(T_{\alpha}\in \textrm{d} t \mid N_{T_{\alpha}}(\lambda)=1)=\mathbb{P}(T_{\alpha}\in \textrm{d} t \mid \Gamma_{1}/T_{\alpha}=\lambda)=\mathbb{P}(\tilde{T}_{\alpha,1-\alpha}(\lambda)\in \textrm{d} t),\end{equation}
indicating that  $\tilde{T}_{\alpha,1-\alpha}\bigg(G^{\frac{1}{\alpha}}_{1}\bigg)\overset{\textrm{d}}=T_{\alpha}$. See an earlier version of this work and [Reference James26], both following [Reference Pitman49], for results related to
 $I^{n-k\alpha}_+f_{\alpha}$ corresponding to when
 $N_{T_{\alpha}}(\lambda)=n$. Consider now, for
 $G_{1+\theta}$ independent of
 $T_{\alpha,\theta}$, the variable
 $G_{1+\theta}/T_{\alpha,\theta}\overset{\textrm{d}}=G^{\frac{1}{\alpha}}_{\frac{\theta+\alpha}{\alpha}}$. Then, from [Reference James26, Corollary 3.4] (see also [Reference Dong, Goldschmidt and Martin13], [Reference Pitman and Yor54, Proposition 2.1]), or by direct integration over
 $\lambda$ in (2.9),
 \begin{equation*}\mathbb{P}\bigg(\tilde{T}_{\alpha,1-\alpha}\bigg(G^{\frac{1}{\alpha}}_{\frac{\theta+\alpha}{\alpha}}\bigg)\in \textrm{d} t\bigg)=\mathbb{P}(T_{\alpha,\theta}\in \textrm{d} t).\end{equation*}
We now provide a result for  $I^{\nu}_+f_{\alpha}$ for general
 $\nu>0$ and a general gamma variable.
Proposition 2.1. For any  $\omega>0$, let
 $G_{\frac{\omega}{\alpha}}$ be a gamma random variable with parameters
 $\big(\frac{\omega}{\alpha},1\big)$, which is independent of
 $\tilde{T}_{\alpha,\nu}(\lambda)$, and let
 $Y^{(\nu)}_{\alpha,\omega}\overset{\textrm{d}}=\tilde{T}_{\alpha,\nu}(G_{\frac{\omega}{\alpha}})$ be a random variable such that
 $Y^{(\nu)}_{\alpha,\omega} \mid G_{\frac{\omega}{\alpha}}=\lambda$ satisfies the distributional dynamics in (2.7). Then, there are variables constructed on the same space, denoted as
 ${T}^{-\alpha}_{\alpha,\nu}\sim \textrm{ML}(\alpha,\nu)$, independent of
 $\beta_{\omega,\nu}\sim \textrm{Beta}(\omega,\nu)$, and
 $T^{-\alpha}_{\alpha,\omega+\nu}\sim \textrm{ML}(\alpha,\nu+\omega)$, independent of
 $\beta_{\frac{\omega}{\alpha},\frac{\nu}{\alpha}}\sim \textrm{Beta}\big(\frac{\omega}{\alpha},\frac{\nu}{\alpha}\big)$, such that, for
 $Z^{(\frac{\nu}{\alpha})}_{\alpha,\omega}={\big(Y^{(\nu)}_{\alpha,\omega}\big)}^{-\alpha}$, we have the exact representation
 \begin{equation}Z^{(\frac{\nu}{\alpha})}_{\alpha,\omega}=T^{-\alpha}_{\alpha,\omega}\times \beta^{\alpha}_{\omega,\nu}=T^{-\alpha}_{\alpha,\omega+\nu}\times \beta_{\frac{\omega}{\alpha},\frac{\nu}{\alpha}}.\end{equation}
Proof. We can choose  $Y^{(\nu)}_{\alpha,\omega}=\tilde{T}_{\alpha,\nu}(G_{\frac{\omega}{\alpha}})$. The result follows by applications of [Reference Pitman and Yor54, Proposition 21] and the beta-gamma algebra. For more specifics, see [Reference Pitman and Yor54, (98)–(100), p. 877].
Remark 2.3. Proposition 2.1 reveals a (surprising to us) connection between the general  $I^{\nu}_+f_{\alpha}$ and random variables apearing in [Reference Bertoin and Yor6, Reference James23]; see also [Reference Patie36]. In particular, the variables
 $Z^{(\frac{\nu}{\alpha})}_{\alpha,\omega}$ indexed by
 $(\nu,\omega)$ correspond to the entire range of variables given in [Reference Bertoin and Yor6, Lemma 6, (10)], and agree also, in full generality, with the identity in [Reference James23, (2.11), p. 8]. So, from a distributional perspective, (2.10) is not new, except for the subordinator representation which leads to pointwise equalities. However, [Reference Pitman48] also develops an equivalent variation of (2.10) in the case of
 $\textrm{PD}(\alpha,\theta)$ interval partitions, employing the subordinator representation.
In relation to  $I^{\nu}_+f_{\alpha}$, we now give equivalent expressions of the densities of the random variables in (2.10).
Proposition 2.2. Let  $f^{(\nu)}_{\alpha,\omega}(t)$ denote the density of
 $Y^{(\nu)}_{\alpha,\omega}$, defined via
 $Z^{(\frac{\nu}{\alpha})}_{\alpha,\omega}={\left(Y^{(\nu)}_{\alpha,\omega}\right)}^{-\alpha}$ in (2.10).
(i) Using the form of the density indicated by
$T_{\alpha,\omega}/\beta_{\omega,\nu}$, it follows that, for $\omega>0$,
(2.11)where
\begin{equation}{f}^{(\nu)}_{\alpha,\omega}(t)=\frac{\alpha \Gamma(\nu+\omega)}{\Gamma\big(\frac{\omega}{\alpha}\big)}t^{-(\nu+\omega)}\left(I^{\nu}_+{f_\alpha}\right){(t)}\end{equation}
$\alpha{\Gamma(\omega)\mathbb{E}[T^{-\omega}_{\alpha}]}={\Gamma\big(\frac{\omega}{\alpha}\big)}$.
-
(ii) Using (2.8), an alternate form of
$f^{(\nu)}_{\alpha,\omega}(t)$ is obtained as
(2.12)
\begin{equation}\frac{\alpha \Gamma(\nu+\omega)}{\Gamma\big(\frac{\nu}{\alpha}\big)\Gamma\big(\frac{\omega}{\alpha}\big)}t^{-(\nu+\omega)}\int_{0}^{1}f_{\alpha}\Big(tu^{\frac{1}{\alpha}}\Big)u^{\frac{1-\nu}{\alpha}-1}{(1-u)}^{\frac{\nu}{\alpha}-1} \, \textrm{d} u.\end{equation}
-
(iii) Combining (2.11) and (2.12) yields, for
$\nu>0$,
\begin{equation*}\left(I^{\nu}_+{f_{\alpha}}\right){(t)}=\frac{1}{\Gamma\big(\frac{\nu}{\alpha}\big)}\int_{0}^{1}f_{\alpha}\Big(tu^{\frac{1}{\alpha}}\Big)u^{\frac{1-\nu}{\alpha}-1}{(1-u)}^{\frac{\nu}{\alpha}-1} \, \textrm{d} u.\end{equation*}


We now demonstrate how we can use Proposition 2.2 to recover results in the  $\textrm{PD}(\alpha,\theta)$ setting. Recall that under
 $\textrm{PD}(\alpha,\theta)$ the distribution of
 $K_{n}$ is given by
 $\mathbb{P}^{(n)}_{\alpha,\theta}(k)$ defined in (1.3). It follows that a joint distribution of
 $(T_{\alpha,\theta},K_{n})$ is proportional to
 $t^{-\theta}f^{(n-k\alpha)}_{\alpha,k\alpha}(t)\mathbb{P}^{(n)}_{\alpha,\theta}(k)$, and hence, from (2.11),
 $f^{(n-k\alpha)}_{\alpha,\theta+k\alpha}(t)$ is the conditional density of
 $(T_{\alpha,\theta} \mid K_{n}=k)$ and, from Proposition 2.1, corresponds to the density of the random variables
 \begin{equation}Y^{(n-k\alpha)}_{\alpha,\theta+k\alpha}\,:\!=\,\frac{T_{\alpha,\theta+k\alpha}}{\beta_{\theta+k\alpha,n-k\alpha}}=\frac{T_{\alpha,\theta+n}}{\beta^{\frac1\alpha}_{\frac{\theta}{\alpha}+k,\frac{n}{\alpha}-k}}.\end{equation}
Randomizing (2.13) with  $K_{n}\sim \mathbb{P}^{(n)}_{\alpha,\theta}$ in place of k, and using the distributional properties of an
 $\textrm{MLMC}(\alpha,\theta)$, leads to a perhaps not so well-known identity involving products of independent beta variables appearing in the related literature:
 \begin{equation}T^{-\alpha}_{\alpha,\theta}\overset{\textrm{d}}={T^{-\alpha}_{\alpha,\theta+n}}\,{\prod_{j=1}^{n}\beta_{\frac{\theta+\alpha+j-1}{\alpha},\frac{1-\alpha}{\alpha}}}\overset{\textrm{d}}={T^{-\alpha}_{\alpha,\theta+n}}\,{\beta_{\frac{\theta}{\alpha}+K_{n},\frac{n}{\alpha}-K_{n}}}.\end{equation}
Now, as pointed out in [Reference James24, Proposition 6.6(iii)], (2.14) results in the distributional equality
 \begin{equation}\prod_{j=1}^{n}\beta_{\frac{\theta+\alpha+j-1}{\alpha},\frac{1-\alpha}{\alpha}}\overset{\textrm{d}}=\beta_{\frac{\theta}{\alpha}+K_{n},\frac{n}{\alpha}-K_{n}},\end{equation}
leading to the following result, which will be used in the next section.
Proposition 2.3. The density of the product of independent beta random variables  $\prod_{j=1}^{n}\beta_{\frac{\theta+\alpha+j-1}{\alpha},\frac{1-\alpha}{\alpha}}$, arising, for instance, under an
 $\textrm{MLMC}(\alpha,\theta)$ distribution, can be expressed as
 \begin{equation}\sum_{k=1}^{n}\mathbb{P}^{(n)}_{\alpha,\theta}(k)f_{\beta_{\frac{\theta}{\alpha}+k,\frac{n}{\alpha}-k}}(u).\end{equation}
Remark 2.4. Let  $\alpha={1}/{m}$, for
 $m=2,3,\ldots$ In the
 $\textrm{MLMC}\big(\frac{1}{m},\theta\big)$ case of (2.15), for
 $\theta>-1/m$ we have the following distributional identity:
 \begin{equation}\prod_{j=1}^{n}\beta^{m}_{m(\theta+j-1)+1,m-1}\overset{\textrm{d}}=\prod_{i=1}^{m-1}\beta_{\theta+\frac{i}{m},n}.\end{equation}
As special cases, when  $\alpha=1/2$ we have the easily deduced fact that
 $\prod_{j=1}^{n}\beta^{2}_{2(\theta+j)-1,1}\overset{\textrm{d}}=\beta_{\theta+\frac{1}{2},n}$, and when
 $\alpha=1/3$,
 $\prod_{j=1}^{n}\beta^{3}_{3(\theta+j)-2,2}\overset{\textrm{d}}=\beta_{\theta+\frac{1}{3},n}\times\beta_{\theta+\frac{2}{3},n}$. Equation (2.17) follows from representations of
 $\textrm{ML}\big(\frac{1}{m},\theta\big)$ variables in terms of beta and gamma variables (see [Reference James23, Section 8] and related references discussed there), the identity (2.14), and beta-gamma algebra.
3. Mittag–Leffler Markov chains under $\textrm{PK}_{\alpha}(\gamma)$

As discussed in Section 1.1, Markov chains  $\textbf{Z}\sim \textrm{MLMC}(\alpha,\theta)$ arise by various constructions in the literature, and do not completely determine the law of a collection
 $((P_{\ell,r}),Z_{r};\ r\ge 0)$. Here we recall that
 $((P_{\ell,r}),Z_{r};\ r\ge 0)\sim \textrm{MLMC}_{\textrm{frag}}(\alpha,\theta)$ may arise from iteration of the
 $\textrm{PD}(\alpha,1-\alpha)$ single-block size-biased fragmentation operation described in [Reference Dong, Goldschmidt and Martin13], when the law of
 $(P_{\ell,0})\sim \textrm{PD}(\alpha,\theta)$. This section provides distributional properties of nested families
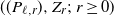 $((P_{\ell,r}),Z_{r};\ r\ge 0)$ induced by fragmentation operations described in [Reference Dong, Goldschmidt and Martin13] when, in general,
 $(P_{\ell,0})\sim\textrm{PK}_{\alpha}(\gamma)$. This should be particularly useful in cases where
 $\textrm{PK}_{\alpha}(\gamma)$ can be interpreted. Simplifications and various decompositions are facilitated by Proposition 2.3. As in [Reference Dong, Goldschmidt and Martin13], for
 $(P_{\ell})\in \mathcal{P}_{\infty}$, let
 $\tilde{P}_{1}$ denote its first size-biased pick and let
 $(P_{\ell})_{1}\,:\!=\,(P_{\ell})\setminus\tilde{P}_{1}$ denote the remainder. A
 $\textrm{PD}(\alpha,1-\alpha)$ fragmentation of
 $(P_{\ell})$ is defined as
 \begin{equation*}\widehat{\textrm{Frag}}_{\alpha,1-\alpha}\big((P_{\ell})\big)\,:\!=\,\textrm{Rank}\big((P_{\ell})_{1},\tilde{P}_{1}(Q_{\ell})\big)\in \mathcal{P}_{\infty},\end{equation*}
where, independent of  $(P_{\ell})$,
 $(Q_{\ell})\sim \textrm{PD}(\alpha,1-\alpha),$ and
 $\textrm{Rank}({\cdot})$ denotes the ranked rearrangement. Let
 $\big(\big(Q^{(j)}_{\ell}\big);\ j\ge 1\big)$ denote an independent collection of
 $\textrm{PD}(\alpha,1-\alpha)$ mass partitions defining a sequence of independent fragmentation operators
 $\big(\widehat{\textrm{Frag}}^{(j)}_{\alpha,1-\alpha}({\cdot});\ j\ge 1\big)$. It follows from [Reference Dong, Goldschmidt and Martin13] that a version of the family
 $((P_{\ell,r}),Z_{r};\ r\ge 0)\sim \textrm{MLMC}_{\textrm{frag}}(\alpha,\theta)$ may be constructed by the recursive fragmentation, for
 $r=1,2,\ldots\,$,
 \begin{equation}(P_{\ell,r})=\widehat{\textrm{Frag}}^{(r)}_{\alpha,1-\alpha}\big((P_{\ell,r-1})\big)=\widehat{\textrm{Frag}}^{(r)}_{\alpha,1-\alpha}\circ\cdots\circ \widehat{\textrm{Frag}}^{(1)}_{\alpha,1-\alpha}\big((P_{\ell,0})\big),\end{equation}
when  $(P_{\ell,0})\sim \textrm{PD}(\alpha,\theta)$. These operations may also be described in terms of nested partitions of [n] [Reference Bertoin5, Section 3.1.1], and there is a corresponding sequence of block counts
 $(K_{n,r}\ge 0)$, non-decreasing in
 $r\ge 0$, such that jointly
 $n^{-\alpha}(K_{n,r}\ge 0)\rightarrow \textbf{Z}$ as
 $n\rightarrow \infty$.
We next describe the marginal (joint) law of  $(Z_{r};\ r\ge 0)$ when
 $(P_{\ell,0})\sim \textrm{PK}_{\alpha}(\gamma)$. Suppose that
 $\textbf{Z}\sim \textrm{MLMC}(\alpha,0)$ with accompanying
 $(B_{j}=Z_{j-1}/Z_{j},j\ge 1)$, which is a collection of independent variables such that, for each
 $j\ge 1$,
 $B_{j}\sim \textrm{Beta}\big(\frac{\alpha+j-1}{\alpha},\frac{1-\alpha}{\alpha}\big)$. A description of the distribution of
 $\textbf{Z} \mid Z_{0}=y $ is obtained from (1.5). Setting the density of
 $Z_{0}$ to
 $h(y^{-\frac{1}{\alpha}})g_{\alpha}(y)$ leads to a description of the distribution of
 $\textbf{Z}\sim \textrm{MLMC}^{[\gamma]}(\alpha)$ and, using the change of variable, this distribution is characterized by the joint density of
 $(B_{1},\ldots, B_{r},Z_{r})$ given as
 \begin{equation*}\prod_{i=1}^{r}f_{\beta_{\frac{\alpha+i-1}{\alpha},\frac{1-\alpha}{\alpha}}}(b_{i})\,h\bigg(s^{-\frac{1}{\alpha}}\prod_{j=1}^{r}b^{-\frac{1}{\alpha}}_{j}\bigg)\,g_{\alpha,r}(s),\end{equation*}
where  $g_{\alpha,r}(s)$ is the density of an
 $\textrm{ML}(\alpha,r)$ variable as defined in (1.4). It follows that when
 $Z_{0}$ has density
 $h(y^{-\frac{1}{\alpha}})g_{\alpha}(y)$,
 $Z_{r}$ has a marginal density,
 \begin{equation}g^{(r)}_{\textrm{frag}_{\alpha}}(s;\ \gamma)\,:\!=\,\mathbb{E}\bigg[h\bigg(s^{-\frac1\alpha} \prod_{i=1}^{r}\beta^{-\frac1\alpha}_{\frac{\alpha+i-1}{\alpha},\frac{1-\alpha}{\alpha}}\bigg)\bigg]g_{\alpha,r}(s)=h^{(r)}_{\textrm{frag}_{\alpha}}(s^{-\frac{1}{\alpha}})g_{\alpha}(s),\end{equation}
where  $h^{(0)}_{\textrm{frag}_{\alpha}}(t)=h(t)$ and
 $h^{(r)}_{\textrm{frag}_{\alpha}}(t)= {{t}^{-r}} \mathbb{E}\bigg[h\bigg(t\displaystyle \prod_{i=1}^{r}\beta^{-\frac1\alpha}_{\frac{\alpha+i-1}{\alpha},\frac{1-\alpha}{\alpha}}\bigg)\bigg]/\mathbb{E}[T^{-r}_{\alpha}],$ for
 $r=1,2,\ldots$ This means that, for each integer r, the corresponding
 $Z_{r}^{-\frac{1}{\alpha}}$ has density
 \begin{equation}\gamma^{(r)}_{\textrm{frag}_{\alpha}}(\textrm{d} t)/\textrm{d} t = h^{(r)}_{\textrm{frag}_{\alpha}}(t)f_{\alpha}(t)=\mathbb{E}\bigg[h\bigg(t\prod_{i=1}^{r} \beta^{-\frac1\alpha}_{\frac{\alpha+i-1}{\alpha},\frac{1-\alpha}{\alpha}}\bigg)\bigg]f_{\alpha,r}(t).\end{equation}
We next formally establish that the marginal distribution of each  $(P_{\ell,r})$ is
 $\textrm{PK}_{\alpha}(\gamma^{(r)}_{\textrm{frag}_{\alpha}})$ when otherwise they have joint distribution as if they were constructed from (3.1) in the case where
 $(P_{\ell,0})\sim \textrm{PK}_{\alpha}(\gamma)$.
Proposition 3.1. Consider  $((P_{\ell,r}),Z_{r};\ r\ge 0)\sim \textrm{MLMC}_{\textrm{frag}}(\alpha,0)$, formed by the fragmentation operations in (3.1) when
 $(P_{\ell,0})\sim \textrm{PD}(\alpha,0)$. If
 $(P_{\ell,0})\sim \textrm{PK}_{\alpha}(\gamma)$, the distribution of
 $((P_{\ell,r}),Z_{r};\ r\ge 0)$ is denoted as
 $ \textrm{MLMC}^{[\gamma]}_{\textrm{frag}}(\alpha)$ such that, for each r and for
 $\gamma^{(r)}_{\textrm{frag}_{\alpha}}$ described in (3.3),
 $(P_{\ell,r})$ has marginal distribution
 \begin{equation*}\textrm{PK}_{\alpha}\big(\gamma^{(r)}_{\textrm{frag}_{\alpha}}\big)=\int_{0}^{\infty}\textrm{PD}\Big(\alpha \mid s^{-\frac1\alpha}\Big)g^{(r)}_{\textrm{frag}_{\alpha}}(s;\ \gamma) \, \textrm{d} s,\end{equation*}
with  $\alpha$-diversity/local time
 $Z_{r}$ having density
 $g^{(r)}_{\textrm{frag}_{\alpha}}(s;\ \gamma)$ defined in (3.2).
Proof. The proof of this result is essentially the same for any  $r\ge 1$. As such, we will verify the result for
 $r=1$. Here,
 $(P_{\ell,1})=\widehat{\textrm{Frag}}^{(1)}_{\alpha,1-\alpha}\big((P_{\ell,0})\big)$, where
 $(P_{\ell,0})\sim \textrm{PK}_{\alpha}(\gamma)$, and, independent of this,
 $\big(Q^{(1)}_{\ell}\big)\sim\textrm{PD}(\alpha,1-\alpha)$. Let
 $\mathbb{E}^{(\alpha,0)}_{(\alpha,1-\alpha)}$ denote the expectation with respect to the joint law of
 $\big((P_{\ell,0}),\big(Q^{(1)}_{\ell}\big)\big)$ when
 $(P_{\ell,0})\sim \textrm{PD}(\alpha,0)$. Then, when
 $(P_{\ell,0})\sim \textrm{PK}_{\alpha}(\gamma)$, the distribution of
 $(P_{\ell,1})$ is characterized, for a measurable function
 $\Omega$, by
 \begin{equation}\mathbb{E}^{(\alpha,0)}_{(\alpha,1-\alpha)}\bigg[\Omega\bigg(\widehat{\textrm{Frag}}^{(1)}_{\alpha,1-\alpha}\big((P_{\ell,0})\big)\bigg)h\Big(Z^{-\frac{1}{\alpha}}_{0}\Big)\bigg].\end{equation}
The random variables in (3.4) follow the  $\textrm{MLMC}_{\textrm{frag}}(\alpha,0)$ dynamics where
 $B_{1}\sim \textrm{Beta}\big(1,\frac{1-\alpha}{\alpha}\big)$ is independent of
 $(P_{\ell,1})=\widehat{\textrm{Frag}}^{(1)}_{\alpha,1-\alpha}((P_{\ell,0}))\sim \textrm{PD}(\alpha,1)$. Note that
 $Z_{0}=Z_{1}\times B_{1}$, with
 $Z_{1}\sim \textrm{ML}(\alpha,1)$. Hence, with these specifications we can write the expression in (3.4) as
 \begin{equation*}\mathbb{E}\Big[\Omega((P_{\ell,1}))h\Big(Z^{-\frac{1}{\alpha}}_{1}B^{-\frac{1}{\alpha}}_{1}\Big)\Big]=\int_{0}^{\infty}\mathbb{E}[\Omega((P_{\ell,1})) \mid Z_{1}=s]g^{(1)}_{\textrm{frag}_{\alpha}}(s;\ \gamma) \, \textrm{d} s.\end{equation*}
The equality follows by noting that, under the  $\textrm{MLMC}_{\textrm{frag}}(\alpha,0)$ distribution,
 $(P_{\ell,1})\sim \textrm{PD}(\alpha,1)$ and, given
 $Z_{1}=s$,
 $B_{1}=b$, has law
 $\textrm{PD}\big(\alpha \mid s^{-\frac{1}{\alpha}}\big)$ to conclude the result.
3.1. $\textrm{MLMC}^{[\gamma]}_{\textrm{frag}}(\alpha)$ EPPFs and partitions of [n]

Recall the interpretation of the random variables  $Y^{(n-k\alpha)}_{\alpha,\theta+k\alpha}$ in (2.13) with corresponding densities
 $f^{(n-k\alpha)}_{\alpha,\theta+k\alpha}(t)$. Define
 $\Phi^{(\frac{n}{\alpha}-k)}_{\alpha,\frac{\theta}{\alpha}+k}(0)=\mathbb{E}\Big[h\Big(Y^{(n-k\alpha)}_{\alpha,\theta+k\alpha}\Big)\Big],$ where
 $\Phi^{(\frac{n}{\alpha}-k)}_{\alpha,k}(0)=\int_{0}^{\infty}h(t)f^{(n-k\alpha)}_{\alpha,k\alpha}(t)\,\textrm{d} t =V_{n,k}\frac{\alpha^{1-k}\Gamma(n)}{\Gamma(k)}$. Here, for
 $r=0,1,2,\ldots$, we use
 \begin{equation}\Phi^{(\frac{n}{\alpha}-k)}_{\alpha,\frac{r}{\alpha}+k}(r)=\int_{0}^{\infty}\mathbb{E}\bigg[h\bigg(t\prod_{i=1}^{r}\beta^{-\frac1\alpha}_{\frac{\alpha+i-1}{\alpha},\frac{1-\alpha}{\alpha}}\bigg)\bigg]f^{(n-k\alpha)}_{\alpha,r+k\alpha}(t) \, \textrm{d} t,\end{equation}
and we have the identity
 \begin{equation}\sum_{k=1}^{n}\mathbb{P}^{(n)}_{\alpha,r}(k)\Phi^{(\frac{n}{\alpha}-k)}_{\alpha,\frac{r}{\alpha}+k}(r)=\mathbb{E}\big[h^{(r)}_{\textrm{frag}_{\alpha}}(T_{\alpha})\big]=1.\end{equation}
We now provide a description of the corresponding EPPFs and the distributions of the number of blocks for the nested sequence of random partitions of [n].
Proposition 3.2. Consider  $((P_{\ell,r}),Z_{r};\ r\ge 0)\sim \textrm{MLMC}^{[\gamma]}_{\textrm{frag}}(\alpha)$, where
 $(P_{\ell,0})\sim\textrm{PK}_{\alpha}(\gamma)$. Then, for each
 $r\ge 0$, the
 $\textrm{PK}_{\alpha}(\gamma^{(r)}_{\textrm{frag}_{\alpha}})$ partition of [n], with number of blocks
 $K_{n,r}=k$, has an EPPF which can be expressed as
 \begin{equation*}\Phi^{(\frac{n}{\alpha}-k)}_{\alpha,\frac{r}{\alpha}+k}(r)\times p_{\alpha,r}(n_{1},\ldots,n_{k}).\end{equation*}
Hence, the distribution of  $K_{n,r}$ is
 $\mathbb{P}^{(n)}_{\alpha,r}(k)\Phi^{(\frac{n}{\alpha}-k)}_{\alpha,\frac{r}{\alpha}+k}(r),$ for
 $k=1,\ldots,n$. Furthermore, as
 $n\rightarrow \infty$,
 $n^{-\alpha}K_{n,r}\overset{\textrm{a.s.}}\rightarrow Z_{r}$, where
 $Z_{r}$ has density (3.2).
Proof. The derivation of the EPPF, and hence the distribution of  $K_{n,r}$, follows by using (1.11) as applied to (3.3) in conjunction with (3.5) and (3.6). The asymptotic behavior follows as a particular instance of [Reference Pitman46, Proposition 13]; see also [Reference Pitman47, Lemma 13].
Remark 3.1. For clarity, for  $r=0$,
 $\Phi^{(\frac{n}{\alpha}-k)}_{\alpha,k}(0)\times p_{\alpha,0}(n_{1},\ldots,n_{k})$ is equivalent to
 $p^{[\gamma]}_{\alpha}(n_{1},\ldots,n_{k})$ in (1.11) for a
 $\textrm{PK}_{\alpha}(\gamma)$ partition of [n], and hence the distribution of the corresponding number of blocks,
 $K_{n,0}$, may be expressed as
 \begin{equation}\mathbb{P}^{[\gamma]}_{\alpha}(K_{n,0}=k)=\mathbb{P}^{(n)}_{\alpha,0}(k)\Phi^{(\frac{n}{\alpha}-k)}_{\alpha,k}(0).\end{equation}
3.2. Mixture representations for $\textrm{MLMC}^{[\gamma]}_{\textrm{frag}}(\alpha)$

We now use Proposition 3.2 to obtain mixture representations and identify related Poisson–Kingman models. See Remark 2.4 for other possible simplifications in those special cases, in particular for  $\alpha=1/2$. For each fixed
 $r=1,2,\ldots$ and
 $j=1,\ldots, r$, define the probability measures
 \begin{equation}\gamma^{(r,j)}_{\textrm{frag}_{\alpha}}(\textrm{d} t)/\textrm{d} t = \frac{\mathbb{E}\bigg[h\bigg(t\beta^{-\frac1\alpha}_{j,\frac{r}{\alpha}-j}\bigg)\bigg]}{\Phi^{(\frac{r}{\alpha}-j)}_{\alpha,j}(0)}f_{\alpha,r}(t),\end{equation}
where  $\Phi^{(\frac{r}{\alpha}-j)}_{\alpha,j}(0)=\mathbb{E}\Big[h\Big(Y^{(r-j\alpha)}_{\alpha,j\alpha}\Big)\Big]=V_{r,j}\frac{\alpha^{1-j}\Gamma(r)}{\Gamma(j)}$ from the previous section.
Proposition 3.3. Consider  $((P_{\ell,r}),Z_{r};\ r\ge 0)\sim \textrm{MLMC}^{[\gamma]}_{\textrm{frag}}(\alpha)$, where
 $(P_{\ell,0})\sim\textrm{PK}_{\alpha}(\gamma)$. Then, for each fixed
 $r=1,2,\ldots\,$,
 \begin{equation*}(P_{\ell,r})\sim\textrm{PK}_{\alpha}\big(\gamma^{(r)}_{\textrm{frag}_{\alpha}}\big)=\sum_{j=1}^{r}\mathbb{P}^{[\gamma]}_{\alpha}(K_{r,0}=j)\textrm{PK}_{\alpha}\big(\gamma^{(r,j)}_{\textrm{frag}_{\alpha}}\big),\end{equation*}
where  $\mathbb{P}^{[\gamma]}_{\alpha}(K_{r,0}=j)=\mathbb{P}^{(r)}_{\alpha,0}(j)\Phi^{(\frac{r}{\alpha}-j)}_{\alpha,j}(0)$ is identical to (3.7) with (r, j) in place of (n,k). Furthermore, for
 $j=1,\ldots,r$,
 $\textrm{PK}_{\alpha}(\gamma^{(r,j)}_{\textrm{frag}_{\alpha}})$ is the distribution of a mass partition
 $\big(P^{(j)}_{\ell,r}\big)$ defined as in (1.7) with mixing measure specified in (3.8). Hence, the EPPF of a
 $\textrm{PK}_{\alpha}\big(\gamma^{(r,j)}_{\textrm{frag}_{\alpha}}\big)$ partition of [n], with number of blocks
 $K^{(j)}_{n,r}=k$, can be expressed as
 \begin{equation*}\frac{\mathbb{E}\bigg[h\bigg(Y^{(n-k\alpha)}_{\alpha,r+k\alpha}\beta^{-\frac1\alpha}_{j,\frac{r}{\alpha}-j}\bigg)\bigg]}{\Phi^{(\frac{r}{\alpha}-j)}_{\alpha,j}(0)}\times p_{\alpha,r}(n_{1},\ldots,n_{k}).\end{equation*}
Proof. With regards to Proposition 3.2, apply a special case of the identity in (2.15),  $\prod_{j=1}^{r}\beta_{\frac{\alpha+j-1}{\alpha},\frac{1-\alpha}{\alpha}}\overset{\textrm{d}}=\beta_{K_{r},\frac{r}{\alpha}-K_{r}},$ where its density is given in (2.16) of Proposition 2.3, taking the form
 $\sum_{i=1}^{r}\mathbb{P}^{(r)}_{\alpha,0}(j)f_{\beta_{j,\frac{r}{\alpha}-j}}(u)$, to the expression in (3.3). The remainder follows from appropriate normalization and the same procedure for deriving the EPPF of a PK distribution.
Remark 3.2. We have the identity
 \begin{equation*}\Phi^{(\frac{n}{\alpha}-k)}_{\alpha,\frac{r}{\alpha}+k}(r)=\sum_{j=1}^{r}\mathbb{P}^{(r)}_{\alpha,0}(j)\mathbb{E}\bigg[h\bigg(Y^{(n-k\alpha)}_{\alpha,r+k\alpha}\beta^{-\frac1\alpha}_{j,\frac{r}{\alpha}-j}\bigg)\bigg].\end{equation*}
4. Mittag–Leffler function Gibbs classes
4.1. Decomposing generalized Mittag–Leffler functions in terms of scaled Prabhakar functions
As mentioned in the introduction, the Mittag–Leffler function plays an important role in fractional calculus as described in [Reference Gorenflo, Kilbas, Mainardi and Rogosin18]. Here we show that the Mittag–Leffler function and its generalizations pertinent to the  $\textrm{PD}(\alpha,\theta)$ distribution can be decomposed in terms of scaled versions of Prabhakar functions [Reference Prabhakar55], defined in the most general form as
 \begin{equation}{\tilde{\textrm{E}}}^{\kappa}_{\rho,\mu}(\!-\lambda)=\sum_{\ell=0}^{\infty}\frac{{(-\lambda)}^{\ell}}{\ell!}\frac{(\kappa)_{\ell}}{\Gamma(\rho\ell+\mu)},\end{equation}
where  $\rho,\mu,\kappa\in \mathbb{C}, $ and
 $\textrm{Re}(\rho)>0$. See [Reference Gorenflo, Kilbas, Mainardi and Rogosin18, Chapter 5] for more discussion on these functions. Recall that the Mittag–Leffler function may be defined by
 \begin{equation*}\textrm{E}_{\alpha,1}(-\lambda)=\mathbb{E}\big[\textrm{e}^{-\lambda T^{-\alpha}_{\alpha}}\big]=\sum_{\ell=0}^{\infty}\frac{{(-\lambda)}^{\ell}}{\Gamma(\alpha\ell+1)}=\mathbb{E}\big[\textrm{e}^{-\lambda^{1/\alpha}X_{\alpha}}\big],\end{equation*}
where, for  $T'_{\alpha}\overset{\textrm{d}}=T_{\alpha}$ and otherwise independent,
 $X_{\alpha}\,:\!=\,{T_{\alpha}}/{T'_{\alpha}}.$ Remarkably, although
 $T_{\alpha}$ does not have a simple density, except for
 $\alpha=1/2$, [Reference Zolotarev61] (see also [Reference Barlow, Pitman and Yor4, Reference Lamperti32, Reference Pitman and Yor53] and [Reference Chaumont and Yor9, Exercise 4.2.1]) shows that the density of
 $X_{\alpha}$ is, for
 $y>0$,
 \begin{equation*}f_{X_{\alpha}}(y)=\frac{\sin(\pi\alpha)}{\pi}\frac{y^{\alpha-1}}{y^{2\alpha}+2\cos(\pi\alpha)y^{\alpha}+1} . \end{equation*}
Adjusting the notation slightly, [Reference James23, Section 3] showed that, for  $\theta>-\alpha$,
 \begin{equation}\mathbb{E}\big[\textrm{e}^{-\lambda T^{-\alpha}_{\alpha,\theta}}\big]=\mathbb{E}\big[\textrm{e}^{-\lambda^{1/\alpha}X_{\alpha,\theta}}\big]=\textrm{E}^{(\frac{\theta}{\alpha}+1)}_{\alpha,\theta+1}(\!-\lambda),\end{equation}
where  $X_{\alpha,\theta}\,:\!=\,T_{\alpha}/T_{\alpha,\theta}$ is the Lamperti variable studied in [Reference James23], and
 \begin{equation*}\textrm{E}^{(\frac{\theta}{\alpha}+1)}_{\alpha,\theta+1}(-\lambda)=\sum_{\ell=0}^{\infty}\frac{{(-\lambda)}^{\ell}}{\ell!}\frac{\Gamma\big(\frac{\theta}{\alpha}+1+\ell\big)\Gamma(\theta+1)}{\Gamma\big(\frac{\theta}{\alpha}+1\big)\Gamma(\alpha\ell+\theta+1)},\qquad\theta>-\alpha,\end{equation*}
which further reduces to  $\textrm{E}^{(\frac{\theta}{\alpha})}_{\alpha,\theta}(-\lambda)$, for
 $\theta>0$. We now extend these results for the case of general
 $\omega$ and
 $\nu$.
Proposition 4.1. Consider the random variables  $Z^{(\frac{\nu}{\alpha})}_{\alpha,\omega}$ defined in (2.10). Their Laplace transforms are equal to
 \begin{equation}\textrm{E}^{(\frac{\omega}{\alpha})}_{\alpha,\omega+\nu}(-\lambda)=\sum_{\ell=0}^{\infty}\frac{{(-\lambda)}^{\ell}}{\ell!}\frac{\Gamma\big(\frac{\omega}{\alpha}+\ell\big)\Gamma(\omega+\nu)}{\Gamma\big(\frac{\omega}{\alpha}\big)\Gamma(\alpha\ell+\omega+\nu)},\end{equation}
and may be expressed as special instances of scaled versions of Prabhakar functions. That is,  $\textrm{E}^{(\frac{\omega}{\alpha})}_{\alpha,\omega+\nu}(-\lambda)=\Gamma(\omega+\nu){\tilde{\textrm{E}}}^{\frac{\omega}{\alpha}}_{\alpha,\omega+\nu}(-\lambda)$.
Proof. Using (4.2),
 \begin{equation*}\mathbb{E}\Big[\textrm{e}^{-\lambda Z^{(\frac{\nu}{\alpha})}_{\alpha,\omega}}\Big]=\mathbb{E}\Big[\textrm{e}^{-\lambda^{1/\alpha}{\beta^{1/\alpha}_{\frac{\omega}{\alpha},\frac{\nu}{\alpha}}} X_{\alpha,\omega+\nu}}\Big]=\mathbb{E}\Big[\textrm{E}^{(\frac{\omega+\nu}{\alpha}+1)}_{\alpha,\omega+\nu+1}\big(-\lambda {\beta_{\frac{\omega}{\alpha},\frac{\nu}{\alpha}}}\big)\Big].\end{equation*}
The result is obtained by substituting  $\mathbb{E}\big[{\beta^{\ell}_{\frac{\omega}{\alpha},\frac{\nu}{\alpha}}}\big]=\dfrac{\Gamma\big(\frac{\omega+\nu}{\alpha}\big)\Gamma\big(\frac{\omega}{\alpha}+\ell\big)}{\Gamma\big(\frac{\omega}{\alpha}\big)\Gamma\big(\frac{\omega+\nu}{\alpha}+\ell\big)}.$
We now show that the generalized Mittag–Leffler functions can be expressed in terms of special cases of the previous result.
Proposition 4.2. Following Lemma 2.1, set  $\varphi(t)=\textrm{e}^{-\lambda t^{-\alpha}}t^{-\theta}/\mathbb{E}[T^{-\theta}_{\alpha}]$. Then,
 $\mathbb{E}[\varphi(T_{\alpha})]=\textrm{E}^{(\frac{\theta}{\alpha}+1)}_{\alpha,\theta+1}(-\lambda)$, and there is the decomposition, for each fixed
 $\lambda>0$,
 \begin{equation*}\textrm{E}^{(\frac{\theta}{\alpha}+1)}_{\alpha,\theta+1}(-\lambda)=\sum_{k=1}^{n}\mathbb{P}^{(n)}_{\alpha,\theta}(k)\textrm{E}^{(\frac{\theta}{\alpha}+k)}_{\alpha,\theta+n}(-\lambda)=\mathbb{E}_{\alpha,\theta}\Big[\textrm{E}^{(\frac{\theta}{\alpha}+K_{n})}_{\alpha,\theta+n}(-\lambda)\Big],\end{equation*}
where  $\textrm{E}^{(\frac{\theta}{\alpha}+k)}_{\alpha,\theta+n}(-\lambda)=\mathbb{E}\Big[\textrm{E}^{(\frac{\theta+n}{\alpha})}_{\alpha,\theta+n}\big(-\lambda {\beta_{\frac{\theta}{\alpha}+k,\frac{n}{\alpha}-k}}\big)\Big]$ can be expressed as
 \begin{equation*}\textrm{E}^{(\frac{\theta}{\alpha}+k)}_{\alpha,\theta+n}(-\lambda)=\sum_{\ell=0}^{\infty}\frac{{(-\lambda)}^{\ell}}{\ell!}\frac{\Gamma\big(\frac{\theta}{\alpha}+k+\ell\big)\Gamma(\theta+n)}{\Gamma\big(\frac{\theta}{\alpha}+k\big)\Gamma(\alpha\ell+\theta+n)},\end{equation*}
as read from (4.3).
Proof. The result follows by combining Proposition 4.1 with Lemma 2.1 to obtain
 \begin{equation*}\mathbb{E}[\varphi(T_{\alpha}) \mid K_{n}=k]=\mathbb{E}\Big[\textrm{e}^{-\lambda Z^{(\frac{n-k\alpha}{\alpha})}_{\alpha,\theta+k\alpha}}\Big]\times \frac{\mathbb{E}[T^{-\theta}_{\alpha} \mid K_{n}=k]}{\mathbb{E}[T^{-\theta}_{\alpha}]},\end{equation*}
where  $\mathbb{E}[T^{-\theta}_{\alpha} \mid K_{n}=k]={\Gamma(n) \Gamma\big(\frac\theta\alpha+k\big)}/[{\Gamma(k) \Gamma(\theta+n)}]$.
4.2.
$\textrm{PD}(\alpha,\theta)$ masses conditioned on Poisson counts over intervals $[0,\lambda L_{\alpha,\theta}]$


In this section we use the notation  $L_{\alpha,\theta}\,:\!=\,T^{-\alpha}_{\alpha,\theta}\sim \textrm{ML}(\alpha,\theta)$ to denote the
 $\alpha$-diversity/local time, where local time means more specifically that
 $L_{\alpha,\theta}\,:\!=\,L_{1}$ is the local time at 0 until time 1 under a
 $\textrm{PD}(\alpha,\theta)$ distribution. See [Reference Pitman and Winkel50, Section 3] for this notation within the context of regenerative
 $\textrm{PD}(\alpha,\theta)$ interval partitions of [0, 1]. As a reminder,
 $L_{\alpha,\theta}$ has density
 $g_{\alpha,\theta}(s)\propto s^{\frac{\theta}{\alpha}}g_{\alpha}(s)$ given by (1.4). It is clear from Lemma 2.1 that, for each fixed
 $\lambda>0$, the generalized Mittag–Leffler functions in Proposition 4.2 can be connected to a
 $\textrm{PK}_{\alpha}(\gamma)$ distribution, where
 $h(t)=\varphi(t)/\mathbb{E}[\varphi(T_{\alpha})]$ with
 $\varphi(t)=\textrm{e}^{-\lambda t^{-\alpha}}t^{-\theta}/\mathbb{E}[T^{-\theta}_{\alpha}]$. Hence, under this choice of h(t), we have the densities
 \begin{equation}\gamma(\textrm{d} t)/\textrm{d} t = \frac{\textrm{e}^{-\lambda t^{-\alpha}}f_{\alpha,\theta}(t)}{\textrm{E}^{(\frac{\theta}{\alpha}+1)}_{\alpha,\theta+1}(-\lambda)}, \qquad g^{(0)}_{\alpha,\theta}(s \mid \lambda)\,:\!=\,\frac{\textrm{e}^{-\lambda s}g_{\alpha,\theta}(s)}{\textrm{E}^{(\frac{\theta}{\alpha}+1)}_{\alpha,\theta+1}(-\lambda)}.\end{equation}
We will show here that these densities correspond to conditional distributions of  $T_{\alpha,\theta}$ and
 $L_{\alpha,\theta}\,:\!=\,T^{-\alpha}_{\alpha,\theta}$, respectively. We write
 $(P_{\ell,0}(\lambda))\sim \mathbb{L}^{(0)}_{\alpha,\theta}(\lambda)$ to denote a mass partition having a PK distribution specified by (4.4), expressed as
 \begin{equation}\mathbb{L}^{(0)}_{\alpha,\theta}(\lambda)\,:\!=\,\int_{0}^{\infty}\textrm{PD}\big(\alpha \mid s^{-\frac1\alpha}\big)\,g^{(0)}_{\alpha,\theta}(s \mid \lambda)\,\textrm{d} s.\end{equation}
It is our desire to provide a plausible interpretation of this model.  $g^{(0)}_{\alpha,\theta}(s \mid \lambda)$ has the exponentially tilted density of
 $L_{\alpha,\theta}\,:\!=\,T^{-\alpha}_{\alpha,\theta}$, which corresponds to the density of the local time until time 1 or the
 $\alpha$-diversity in this setting. For all
 $\theta>-\alpha$, it is generally a power-biased and exponentially tilted density of
 $g_{\alpha}$. Hence, although not having the same interpretation as
 $N_{{T}_{\alpha}}(\lambda)$ described in Section 2.2.1, [Reference Pitman49] suggests that the general distributional form of
 $g^{(0)}_{\alpha,\theta}(s \mid \lambda)$ can be obtained by conditioning
 $L_{\alpha,\theta}$, or, more generally,
 $(P_{\ell})\sim \textrm{PD}(\alpha,\theta)$, on the mixed Poisson process
 \begin{equation}\bigg(N_{L_{\alpha,\theta}}(t)=\sum_{\ell=1}^{\infty}\textbf{1}_{\{{\Gamma_{\ell}}/L_{\alpha,\theta}\leq t\}},\, t\ge 0\bigg).\end{equation}
That is to say, for each fixed  $\lambda$,
 $N_{L_{\alpha,\theta}}(\lambda)$ counts the number of points of a Poisson process,
 $(\Gamma_{\ell})$, in the random interval
 $[0,\lambda L_{\alpha,\theta}]$, and otherwise
 $(\Gamma_{\ell}/L_{\alpha,\theta},\ell\ge 1)$ can be interpreted as arrival times. We shall assume that
 $(\Gamma_{\ell})$ is independent of
 $(P_{\ell})$, and thus
 $(P_{\ell}) \mid L_{\alpha,\theta}=s,N_{L_{\alpha,\theta}}(\lambda)=j$ has distribution
 $\textrm{PD}(\alpha \mid s^{-\frac{1}{\alpha}})$, as desired. Throughout, we will use the following easily verified facts by conditioning on
 $L_{\alpha,\theta}$. First, for fixed
 $\lambda$, and for
 $j=0,1,\ldots$,
 \begin{equation}\mathbb{P}(N_{L_{\alpha,\theta}}(\lambda)=j,L_{\alpha,\theta}\in \textrm{d} s)=\frac{\lambda^{j}}{j!}s^{j} \textrm{e}^{-\lambda s}g_{\alpha,\theta}(s) \, \textrm{d} s,\end{equation}
and for  $j=1,2,\ldots$,
 \begin{equation}\mathbb{P}\left(\frac{\Gamma_{j}}{L_{\alpha,\theta}}\in \textrm{d}\lambda,L_{\alpha,\theta}\in \textrm{d} s\right)/\textrm{d}\lambda=\frac{\lambda^{j-1}}{(j-1)!}s^{j} \textrm{e}^{-\lambda s}g_{\alpha,\theta}(s) \, \textrm{d} s.\end{equation}
The next result, which follows from (4.7) and (4.8), describes the marginal distribution of the mixed Poisson process that illustrates a specific case of the Poisson switching identity described in [Reference Pitman49, Lemma 4.5].
Proposition 4.3. For  $\theta>-\alpha$ and
 $j=0,1,\ldots\,$,
 \begin{equation*}\mathbb{P}(N_{L_{\alpha,\theta}}(\lambda)=j)=\frac{\lambda^{j}\mathbb{E} \big[T^{-(\theta+j\alpha)}_{\alpha}\big]}{j!\mathbb{E}[T^{-\theta}_{\alpha}]}\textrm{E}^{(\frac{\theta}{\alpha}+j+1)}_{\alpha,\theta+j\alpha+1}(-\lambda),\end{equation*}
which is the same as  $(\lambda/j)\mathbb{P}(\Gamma_{j}/L_{\alpha,\theta}\in \textrm{d}\lambda)/\textrm{d}\lambda$, for
 $j\neq 0$. Furthermore, this implies
 \begin{equation*}\mathbb{E}[T^{-\theta}_{\alpha}]=\frac{\Gamma\big(\frac{\theta}{\alpha}+1\big)}{\Gamma({\theta}+1)}=\sum_{j=0}^{\infty}\frac{\lambda^{j}\Gamma\big(\frac{\theta}{\alpha}+j+1\big)}{j!\Gamma({\theta}+j\alpha+1)}\textrm{E}^{(\frac{\theta}{\alpha}+j+1)}_{\alpha,\theta+j\alpha+1}(-\lambda).\end{equation*}
The next result describes how the distributions of the form in (4.4) and (4.5) may be obtained by conditioning on  $(N_{L_{\alpha,\theta}}(t),t\ge 0)$.
Proposition 4.4. Suppose that, for  $\theta>-\alpha$,
 $(P_{\ell})\sim\textrm{PD}(\alpha,\theta)$, with
 $\alpha$-diversity/local time
 $L_{\alpha,\theta}\sim\textrm{ML}(\alpha,\theta)$. Then, distributions of the form in (4.4) and (4.5) may be obtained by conditioning on the mixed Poisson process
 $(N_{L_{\alpha,\theta}}(t),t\ge 0)$, described in (4.6), as follows.
(i) For
$j=0,1,2,\ldots,$ the density $g^{(0)}_{\alpha,\theta+j\alpha}(s \mid \lambda) \, \textrm{d} s$ is equal to
\begin{equation*}\mathbb{P}\big(L_{\alpha,\theta}\in \textrm{d} s \mid N_{L_{\alpha,\theta}}(\lambda)=j\big)=\mathbb{P}\big(L_{\alpha,\theta+j\alpha}\in \textrm{d} s \mid N_{L_{\alpha,\theta+j\alpha}}(\lambda)=0\big).\end{equation*}
-
(ii) The density of
$L_{\alpha,\theta} \mid \Gamma_{j}/L_{\alpha,\theta}=\lambda$ is given by $g^{(0)}_{\alpha,\theta+j\alpha}(s \mid \lambda)$, for $j=1,2,\ldots$ -
(iii)
$(P_{\ell}) \mid N_{L_{\alpha,\theta}}(\lambda)=j\sim\mathbb{L}^{(0)}_{\alpha,\theta+j\alpha}(\lambda)$, for $j=0,1,2,\ldots$


Proof. Statements (i) and (ii) follow from (4.7), (4.8), and Proposition 4.3, using additionally the fact that  $s^{j}g_{\alpha,\theta}(s)\propto g_{\alpha,\theta+j\alpha}(s).$ Statement (iii) follows from (i) and (ii), since
 $(P_{\ell}) \mid L_{\alpha,\theta}=s,N_{L_{\alpha,\theta}}(\lambda)=j$ has distribution
 $\textrm{PD}(\alpha \mid s^{-\frac{1}{\alpha}})$.
Remark 4.1. For  $G_{\delta}\sim \textrm{Gamma}(\delta,1)$ independent of
 $(P_{\ell})\sim\textrm{PD}(\alpha,\theta)$, we can show that
 $(P_{\ell}) \mid G_{\delta}/L_{\alpha,\theta}=\lambda\sim\mathbb{L}^{(0)}_{\alpha,\theta+\delta\alpha}(\lambda)$, for any
 $\delta>0$, by similar arguments.
The next result follows from Proposition 4.2 and Lemma 2.1.
Proposition 4.5. Suppose that  $(P_{\ell,0}(\lambda))\sim \mathbb{L}^{(0)}_{\alpha,\theta}(\lambda)$, specified by (4.5); then, its corresponding EPPF of a partition of [n] is given by
 \begin{equation}p^{(0)}_{\alpha,\theta}(n_{1},\ldots,n_{k} \mid \lambda)=\frac{\textrm{E}^{(\frac{\theta}{\alpha}+k)}_{\alpha,\theta+n}(-\lambda)}{\textrm{E}^{(\frac{\theta}{\alpha}+1)}_{\alpha,\theta+1}(-\lambda)}p_{\alpha,\theta}(n_{1},\ldots,n_{k}),\end{equation}
with the distribution of  $K_{n,0}(\lambda)$, denoting the corresponding number of blocks, given by
 \begin{equation}\mathbb{P}_{\alpha,\theta}(K_{n,0}(\lambda)=k)=\frac{\textrm{E}^{(\frac{\theta}{\alpha}+k)}_{\alpha,\theta+n}(-\lambda)}{\textrm{E}^{(\frac{\theta}{\alpha}+1)}_{\alpha,\theta+1}(-\lambda)}\mathbb{P}^{(n)}_{\alpha,\theta}(k).\end{equation}
Furthermore,  $\lim_{n\rightarrow \infty}n^{-\alpha}K_{n,0}(\lambda)=Z_{0}(\lambda)$ a.s., where
 $Z_{0}(\lambda)$ has density
 $g^{(0)}_{\alpha,\theta}(s \mid \lambda)$.
Remark 4.2. For any  $\theta>-1/2$,
 $L^{2}_{\frac{1}{2},\theta}\overset{\textrm{d}}=4G_{\theta+\frac12}$, and hence
 $g^{(0)}_{\frac{1}{2},\theta}(x \mid \lambda)\propto x^{2\theta}\textrm{e}^{-\lambda x-\frac{1}{4}x^{2}}$ corresponds, up to a scale, to a power-biased and exponentially tilted Raleigh distribution. Interestingly,
 $g^{(0)}_{\frac{1}{2},\theta+\frac{j}{2}}(x \mid \lambda)$ corresponds to densities of distributions denoted by
 $\textrm{UL}\big(2\theta+j+1,\big(\frac{\lambda}{2\theta+j+1},\frac{1/2}{2\theta+j+1}\big)\big)$ arising as special cases in [Reference Peköz, Röllin and Ross40, Example 3.9, p. 199].
4.3. Fragmentation processes $\textrm{MLMC}^{[\gamma]}_{\textrm{frag}}(\alpha)$ derived from $(P_{\ell,0}(\lambda))\sim\mathbb{L}^{(0)}_{\alpha,\theta}(\lambda)$


We now apply the general results for fragmentation processes in Section 3 to the case where  $(P_{\ell,0}(\lambda))\sim\mathbb{L}^{(0)}_{\alpha,\theta}(\lambda)$. Among other possible descriptions from the previous section, the distributional results below may correspond to the following scenario. Suppose that
 $((P_{\ell,r}),Z_{r};\ r\ge 0)\sim \textrm{MLMC}_{\textrm{frag}}(\alpha,\theta)$; then
 $((P_{\ell,r}),Z_{r};\ r\ge 0) \mid N_{Z_{0}}(\lambda)=0$, where
 $Z_{0}\,:\!=\,L_{\alpha,\theta}$ has the distribution described in Proposition 4.6 below.
Proposition 4.6. Suppose that, for  $\lambda>0$,
 $\big((P_{\ell,r}(\lambda)),Z_{r}(\lambda);\ r\ge 0\big)\sim \textrm{MLMC}^{[\gamma]}_{\textrm{frag}}(\alpha)$, with
 $\gamma$ specified by (4.4). Then,
 $(P_{\ell,0}(\lambda))\sim\mathbb{L}^{(0)}_{\alpha,\theta}(\lambda)$ and, for
 $r=1,2,\ldots$,
 \begin{equation*}(P_{\ell,r}(\lambda))=\widehat{\textrm{Frag}}^{(r)}_{\alpha,1-\alpha}\big((P_{\ell,r-1}(\lambda))\big)\sim\mathbb{L}^{(r)}_{\alpha,\theta}(\lambda)=\int_{0}^{\infty}\textrm{PD}\big(\alpha \mid s^{-\frac1\alpha}\big)\,g^{(r)}_{\alpha,\theta}(s \mid \lambda)\,\textrm{d} s,\end{equation*}
where
 \begin{equation}g^{(r)}_{\alpha,\theta}(s \mid \lambda)\,:\!=\,\frac{\mathbb{E}\big[\exp\big\{{-}\lambda s\prod_{i=1}^{r}\beta_{\frac{\theta+\alpha+i-1}{\alpha},\frac{1-\alpha}{\alpha}}\big\}\big]}{\textrm{E}^{(\frac{\theta}{\alpha}+1)}_{\alpha,\theta+1}(-\lambda)}g_{\alpha,\theta+r}(s)\end{equation}
is the density of  $Z_{r}(\lambda)$. The EPPF of a partition of [n] can be expressed as
 \begin{equation}\frac{\mathbb{E}\left[\textrm{E}^{(\frac{\theta+r}{\alpha}+k)}_{\alpha,\theta+r+n}\big({-}\lambda\prod_{i=1}^{r}\beta_{\frac{\theta+\alpha+i-1}{\alpha},\frac{1-\alpha}{\alpha}}\big)\right]}{\textrm{E}^{(\frac{\theta}{\alpha}+1)}_{\alpha,\theta+1}(-\lambda)}\times p_{\alpha,\theta+r}(n_{1},\ldots,n_{k}).\end{equation}
Letting  $K_{n,r}(\lambda)$ denote the corresponding number of blocks, it follows that as
 $n\rightarrow \infty$,
 $n^{-\alpha}K_{n,r}(\lambda)\overset{\textrm{a.s.}}\rightarrow Z_{r}(\lambda)$.
Proof. In this section,
 \begin{equation*}h^{(r)}_{\textrm{frag}_{\alpha}}(t)=\frac{t^{-(\theta+r)}\mathbb{E}\left[\exp\big\{{-}\lambda t^{-\alpha}\prod_{i=1}^{r}\beta_{\frac{\alpha+i-1}{\alpha},\frac{1-\alpha}{\alpha}}\big\}\prod_{i=1}^{r}\beta^{\frac\theta\alpha}_{\frac{\alpha+i-1}{\alpha},\frac{1-\alpha}{\alpha}}\right]}{\mathbb{E}\big[T^{-\theta}_{\alpha}\big]\,\mathbb{E}\big[T^{-r}_{\alpha}\big]\,\textrm{E}^{(\frac{\theta}{\alpha}+1)}_{\alpha,\theta+1}(-\lambda)}.\end{equation*}
Hence, after some manipulation, it follows that in this case  $g^{(r)}_{\textrm{frag}_{\alpha}}(s;\ \gamma)$, as generally described in (3.2), is equal to
 $g^{(r)}_{\alpha,\theta}(s \mid \lambda)$ defined in (4.11). The remaining results are obtained from Proposition 3.2 and the form of the EPPF in (4.9).
Remark 4.3. Using
 \begin{equation*}\mathbb{E}\left[\prod_{i=1}^{r}\beta^{\ell}_{\frac{\theta+\alpha+i-1}{\alpha},\frac{1-\alpha}{\alpha}}\right]=\prod_{i=1}^{r}\frac{\Gamma\big(\frac{\theta+i}{\alpha}\big)\Gamma\big(\frac{\theta+\alpha+i-1}{\alpha}+\ell\big)}{\Gamma\big(\frac{\theta+\alpha+i-1}{\alpha}\big)\Gamma\big(\frac{\theta+i}{\alpha}+\ell\big)}\end{equation*}
for  $\ell=1,2,\ldots$, the numerator in (4.12) can be explicitly expressed in terms of a
 $3(r+1)$-parametric Mittag–Leffler function (see [Reference Gorenflo, Kilbas, Mainardi and Rogosin18, (6.3.8), p. 162]), which generalizes Prabhakar functions (4.1).
4.3.1. Mixture representations
In this section we consider  $K_{r}\sim \mathbb{P}^{(r)}_{\alpha,\theta}$, corresponding to the number of blocks in a
 $\textrm{PD}(\alpha,\theta)$ partition of [
 $r]=\{1,\ldots,r\}$. Applying the identity (2.15), we have, for any
 $\lambda>0$,
 \begin{equation*} \mathbb{E}\left[\exp\bigg\{{-}\lambda \prod_{i=1}^{r}\beta_{\frac{\theta+\alpha+i-1}{\alpha},\frac{1-\alpha}{\alpha}}\bigg\}\right]=\mathbb{E}_{\alpha,\theta}\big[\textrm{e}^{-\lambda \beta_{\frac{\theta}{\alpha}+K_{r},\frac{r}{\alpha}-K_{r}}}\big]=\sum_{j=1}^{r}\mathbb{P}^{(r)}_{\alpha,\theta}(j) \mathbb{E}\big[\textrm{e}^{-\lambda \beta_{\frac{\theta}{\alpha}+j,\frac{r}{\alpha}-j}}\big] , \end{equation*}
where  $\mathbb{E}\left[\textrm{e}^{-\lambda \beta_{\frac{\theta}{\alpha}+ j,\frac{r}{\alpha}-j}}\right]= {_1F_1\left(\frac{\theta}{\alpha}+j;\ \frac{\theta}{\alpha}+\frac{r}{\alpha};\ -\lambda \right)}$ is a confluent hypergeometric function of the first kind. Hence, the general results in Section 3.2, coupled with the specific results developed for
 $\mathbb{L}^{(r)}_{\alpha,\theta}(\lambda)$, lead to mixture representations involving PK distributions with mixing measures defined by confluent hypergeometric functions as follows. Consider, for each
 $r=1,2,\ldots$ and
 $j=1,\ldots, r$, mass partitions
 $(P^{(j)}_{\ell,r}(\lambda))\sim\mathbb{L}^{(r,j)}_{\alpha,\theta}(\lambda)$, where
 \begin{equation}\mathbb{L}^{(r,j)}_{\alpha,\theta}(\lambda)=\int_{0}^{\infty}\textrm{PD}\big(\alpha \mid s^{-\frac{1}{\alpha}}\big)\,g^{(r,j)}_{\alpha,\theta}(s \mid \lambda)\, \textrm{d} s\end{equation}
with
 \begin{equation}g^{(r,j)}_{\alpha,\theta}(s \mid \lambda)=\frac{_1F_1\big(\frac{\theta}{\alpha}+j;\ \frac{\theta}{\alpha}+\frac{r}{\alpha};\ -\lambda s\big)}{\textrm{E}^{(\frac{\theta}{\alpha}+j)}_{\alpha,\theta+r}(-\lambda)}g_{\alpha,\theta+r}(s).\end{equation}
The next result follows from an application of Proposition 3.3, followed by the results in Propositions 4.5 and 4.6.
Proposition 4.7. Consider the same settings as in Proposition 4.6, and the distributions specified by (4.13) and (4.14). Then, for  $r=1,2,\ldots$ and
 $j=1,\ldots,r$,
 \begin{equation*}(P_{\ell,r}(\lambda))\sim\mathbb{L}^{(r)}_{\alpha,\theta}(\lambda)=\sum_{j=1}^{r}\mathbb{P}_{\alpha,\theta}(K_{r,0}(\lambda)=j)\mathbb{L}^{(r,j)}_{\alpha,\theta}(\lambda),\end{equation*}
where  $\mathbb{P}_{\alpha,\theta}(K_{r,0}(\lambda)=j)$ is specified by (4.10) with integers (r,j) in place of (n,k). The EPPF of
 $\big(P^{(j)}_{\ell,r}(\lambda)\big)\sim\mathbb{L}^{(r,j)}_{\alpha,\theta}(\lambda)$ based on a partition of [n] can be expressed as
 \begin{equation*}\frac{\mathbb{E}\left[\textrm{E}^{\big(\frac{\theta+r}{\alpha}+k\big)}_{\alpha,\theta+n+r}\big(-\lambda\beta_{\frac{\theta}{\alpha}+ j,\frac{r}{\alpha}-j}\big)\right]}{\textrm{E}^{(\frac{\theta}{\alpha}+j)}_{\alpha,\theta+r}(-\lambda)}p_{\alpha,\theta+r}(n_{1},\ldots,n_{k}),\end{equation*}
where the expectation at the numerator equals
 \begin{equation*}\sum_{\ell=0}^{\infty}\frac{{(-\lambda)}^{\ell}}{\ell!}\frac{\Gamma(\theta+n+r)}{\Gamma(\alpha\ell+\theta+n+r)}\frac{\big(\frac{\theta+r}{\alpha}+k\big)_{\ell}\big(\frac{\theta}{\alpha}+j\big)_{\ell}}{\big(\frac{\theta+r}{\alpha}\big)_{\ell}}.\end{equation*}
Remark 4.4. In the case of  $\alpha=1/2$, regardless of the specification for
 $Z_{0}\sim\gamma$, we have the (joint) distributional result
 $\textbf{Z}\,:\!=\,(Z_{r},r\ge 0)\overset{\textrm{d}}=\Big(2\sqrt{\frac{Z^{2}_{0}}{4} +\sum_{\ell=1}^{r}\textbf{e}_{\ell}},r\ge 0\Big)\sim \textrm{MLMC}^{[\gamma]}\big(\frac{1}{2}\big)$. The case of
 $\textrm{MLMC}\big(\frac{1}{2},\frac{1}{2}\big)$ corresponds, up to a scale, to the components of the line-breaking construction of the Brownian continuum random tree as in [Reference Aldous1, Reference Aldous2] (see also [Reference Peköz, Röllin and Ross39]).
Remark 4.5. We used the notation  $L_{\alpha,\theta}$ to invite possible interpretations of conditioning on
 $N_{L_{\alpha,\theta}}(\lambda)$ within the context of strings of beads
 $([0, L_{\alpha,\theta}],\textrm{d} L^{-1})$, where
 $\textrm{d} L^{-1}$ is a discrete random measure whose ranked masses are
 $\textrm{PD}(\alpha,\theta)$, as discussed in [Reference Pitman and Winkel50, Reference Pitman and Winkel51, Reference Rembart and Winkel57].
Acknowledgements
We thank the anonymous referees for many suggestions to help improve the presentation of this work. LFJ was supported in part by the grants RGC-GRF 16300217 and RGC fintech theme-based research grant project no. T31-604/18-N of the HKSAR.



