I. Introduction
The rationale for public policy intervention lies in the inadequacies of free markets. As unfettered markets fail in allocating resources efficiently, government is called upon to step in and correct such market failures.Footnote 1 The necessary exercise of collective power through government to cure market failures, however, opens up avenues for potential abuse of power, eventually leading to corruption.Footnote 2
Corruption affects markets, allocation of economic resources and society at large. This perspective could be said to be “macro”, and it is projected at capturing the implications of corruption within, and between, markets and society. In fact, empirical data and anecdotal evidence show that the effects of corruption upon the allocation of resources are uncertain. Despite often resulting in sheer deviation from an optimal allocation of resources, corruption can, at times, even promote allocative efficiency of the factors of production (labour and capital) over a limited period of time (dynamic efficiency).Footnote 3
Corruption practices cause the public to bear negative economic consequences (social costs), most likely leading to misallocation of resources, as a mirror-image of what market failures do.Footnote 4 The economic analysis of corruption and bribery shows, in fact, that corruption hinders investment (both domestic and foreign), reduces growth, restricts trade, distorts the size and composition of government expenditure, weakens the financial system, and strengthens the underground economy. As some types of incentives determine market failures, so too incentives influencing non-market organisations (governments) may cause behaviours and outcomes (government supply) that diverge from the socially preferable ones.
In certain circumstances, however, corruption seems to work the opposite way. In fact, its occurrence results in a re-distribution of labour and capital resources that increases total welfare.Footnote 5
Our working hypothesis posits the idea that such circumstances relate to the characteristics of the market in which corruption occurs. The market to our mind means the set of relations between economic actors and social, political, legal, and civil institutions. Such relations form a network by which each player, and each event, sets in motion a chain of positive or negative consequences over the others and over the marketplace as such. The net effects of corruption over the allocation of resources (a chain of either positive or negative consequences) thus depend on the interrelations and interlinkages between corruption and markets.
This network, and the contagion and transmission effects it brings about, closely resembles what is known as “systemic risk” in financial studies. Systemic risk has indeed been thoroughly studied in the ambit of financial markets, where the interconnection between market players is greater than anywhere else. Yet, we are inclined to believe that the theoretical underpinning behind systemic risks lends itself well to interpret the interlinkages that connect corruption occurrence to markets, and the working out of market processes. Further, we deem the financial regulatory engagement with systemic risk – ie macro prudential regulation – an insightful area to look into to push the debate on the legal and economic analysis of corruption towards a new frontier.
The remainder of the paper is structured as follows. The next section displays how corruption sets in motion a series of negative economic consequences. Section III gives an overview of the current economic scholarship, scrutinising the analytical approaches to corruption. The “macro” angle of analysis is introduced and explained in Section IV. Section V deals with systemic risk and macro prudential financial regulation. The article moves on in Section VI to import the systemic risk insights into the policy debate surrounding corruption. It integrates the concept of systemic risk into the policy debate on countering corruption. The article then closes with a brief conclusion.
II. Defining corruption and the negative economic consequences it brings about
Corruption has always been something of a conundrum to economists.Footnote 6 Despite clearly being economic in its nature and principal motivation, ie a personal gain, it is also determined by a wide range of institutional, psychological, cultural, and social factors.Footnote 7 This complexity challenges the narrow assumptions that economics uses to model the behaviour of economic actors. In fact, the concept of “unethical” behaviour is difficult for economists to analyse given their assumption that all individuals and organisations simply pursue self-interest opportunistically.Footnote 8
Corruption takes many different forms, and defining it is one of the most enduring debates in legal and socio-political thoughts.Footnote 9 In fact, a very lively discussion on the precise contours of the phenomenon is still ongoing.Footnote 10
It is interesting to note that the United Nations Convention Against Corruption (UNCAC) lacks a definition of corruption, despite it being the only legally binding universal anti-corruption instrument. On the other hand, Transparency International, until fairly recently, had used two definitions, somehow reflecting the general confusion on the defining characteristic of corruption.Footnote 11
Not only is corruption a thorny and blurred phenomenon, it also affects economies at local (state, regional, municipal), national and international levels. Although it has been common to focus on preventing corruption practices at a global level, for example, by promoting convergence of practices and harmonisation of regulatory tools, it is also particularly necessary to consider how corruption affects micro-transactions at a local level. Public economics often refers to corruption as “the sale by government officials of government property for personal gain”.Footnote 12 Thus, as pointed out by Jain, “it is an act in which the power of public office is used for personal gain, in a manner that contravenes the rules of the game”.Footnote 13 Some version of such definition serves as a starting point for economic modelling. Most economic models, therefore, take a somewhat parsimonious stance, focusing primarily on market corruption and bribery. This view is, however, quite limited in scope, and many situations residing between the private and public-sector escape from being captured. Quite recently, Pellegrini came up with a broader definition: “Corruption is the misuse of entrusted power for private gain; it is behaviour which deviates from the formal duties of a given role because of private-regarding (personal, close family, private clique) pecuniary or status gains; or violates rules against the exercise of certain types of private-regarding influence”.Footnote 14 According to the author, this includes such behaviour as bribery (use of a reward to pervert the judgment of a person in a position of trust); nepotism (bestowal of patronage by reason of ascriptive relationship rather than merit); and misappropriation (illegal appropriation of public resources for private-regarding uses).
Most importantly, the problem of definition is one of analysis. The definition of the concept determines, in fact, what gets modelled and what empiricists look for in the data. In line with previous works,Footnote 15 the data shows that corruption has a strong connection to the national level of income. Reinikka and Smith demonstrate that no reliable assumptions about the nature or extent of a country’s corruption problems can be brought forward on the basis of its location alone.Footnote 16 In fact, according to the mean and range of corruption scores for the different regions, regional groups’ ranges of corruption overlap.
Despite the need to scrutinise the specific causes of corruption in each case, certain factors appear likely to be of general importance in determining the level of corruption in any economy. Such factors are varying and range from “inside” (individual behaviour) to “outside” (market dynamics) ones. This research is particularly concerned with the latter, and the next section encompasses a brief literature review of the economic analysis of corruption.
III. Literature review and analytical approaches to corruption
Although minimising social costs is really what anti-corruption policy is all about, economists, as well as other social scientists and policy analysts, often display a profound ambivalence towards it.Footnote 17 On the one hand, the virtues of public intervention are extolled as a necessary means to increase welfare, as amply reflected and codified in the “theory of market failures”. On the other, conventional economic analysis has been conducted along the working hypothesis that the public sector is invariably correlated with the emergence of corruption, thus blaming how public power is relentlessly exercised.
In fact, despite public institutions being necessarily called upon to deal with issues that cannot be solved solely by market forces, they seem fated to fail in serving their task. This ignites a vicious cycle of the failures of the markets and the failures of the governments, blurring the lines of which failures get to produce which social costs.
Economic analyses of corruption vary in terms of approaches and methodologies to the problem. Some consider determinants of individual decision-making in the general economic, social, and political environment. Others are rather concerned with influences within organisations, focusing on personal motivating and demotivating factors. Another distinction is traditionally made between those who consider corruption to be a consequence of a principal-agent relationship, with agents’ decision to abuse their position of trust, and those who consider corruption to be a consequence of the activities of vested interests.Footnote 18
In reconciling the different angles, public choice economics has approached corruption from the perspective of the optimal and actual conduct of government institutions. In that respect, the seminal contribution by Stigler has been highly influential.Footnote 19 According to his “capture” theory, firms will attempt to corrupt their regulators, or “capture” them, due to the potential for firms to gain from particular forms of regulation that may be in regulators’ power.Footnote 20 From this perspective, strict regulation of standards imposes significant compliance costs on firms, which may form barriers to the entry of new firms and thus reduce the level of competition in the market. This, in turn, permits firms to extract additional “rents”, or unearned surpluses in value, which incumbent firms share.
Along these lines, the law has been viewed as a means to cope with market failures. In fact, the government, and its action through the law, are essential for the protection of the welfare of the general public, given the existence of market failures that can be redressed by corrective government actions.Footnote 21
Despite governments being called upon to counter market failures, there seems to be a consensus among scholars on the emergence of corruption. Government involvement, in fact, appears to inexorably create the potential for rent-seeking from bureaucrats to extract bribes from firms or individuals due to the excess of the value of services over their state-administered price.Footnote 22 At the same time, market privatisation has been championed as a means of countering and preventing the occurrence of corruption. Policies favouring market liberalisation have been advanced by economists and the main international trade and policy-making bodies,Footnote 23 confirming such dialectic between “market forces” and “corruption”.
In their paper, significantly entitled “The Choice between Market Failures and Corruption”, Acemoglu and Verdier come forward with a framework based on four assumptions: (i) Government is a benevolent social planner intervening to correct market failures; (ii) government intervention requires the use of agents – bureaucrats – to collect information, make decisions and implement policies; (iii) these bureaucrats are self-interested, and by virtue of their superior information, hard to monitor; (iv) there is some heterogeneity among bureaucrats. These assumptions simply imply, in the words of the authors, that “when the market failure is important, the optimal allocation of resources will involve a certain degree of government intervention, accompanied by a large government bureaucracy, rents for public employees, misallocation of resources and corruption”. In their eyes, all this “indicates the unavoidable price of dealing with market failures”.Footnote 24
The seminal contribution by Wolf shows that neither markets nor governments can be studied in isolation.Footnote 25 His theoretical model of market and non-market failures captures the complexity of contributing factors determining corruption in real political and economic settings as unable to be neatly classified as either market or government (non-market) failures.Footnote 26 Specifically, he identified several attributes of non-market demand. Most of these relate to the political context that surrounds the activities of the government bureaux, such as increased public awareness of market shortcomings, political organisation and enfranchisement, the tendency for maximising politicians and bureaucrats to be rewarded for propagating interventionist solutions to perceived social problems without reference to the costs of implementation of the high time-discount of political actors.Footnote 27 The inefficiencies and inequities of public institutions are different from, but not less appreciable than, those associated with markets. More specifically, corruption provokes individuals to bear costs produced by the injurers, exactly as happens in the case of negative externalities. When a corrupt practice occurs, in fact, resources are not allocated in such a way as to yield the best output, to the detriment of consumer welfare. As Wolf’s argumentation goes, in both cases, the failures – whether market or non-market – are appraised against the same yardstick, that is, allocative efficiency and distributional equity judged according to some explicit social or ethical norm.
We think that such considerations could be interestingly linked to findings in the area of financial regulation. Importing these findings, in fact, moves the debate further, to approach the interconnections and linkages between the different contributing factors to corruption. The transfer of the nuances developed in the “systemic risk” financial regulation literature to the field of corruption raises questions pertaining to what sorts of connections, between what kinds of institutions, in what kinds of circumstances, would make corruption pose a “systemic risk” leading to such market and non-market failures. In moving in this direction, the next section will zoom out to look at the macro perspective of corruption.
IV. From inside to outside: studying corruption from a “macro” angle
Corruption is a multi-faceted phenomenon caused by a wide array of factors. The elusiveness of corruption makes it difficult for politicians and scholars alike to fully understand the complexity of it. In striving to disentangle the different facets of it, our working hypothesis is based on a fundamental division between two dimensions: “micro” factors and “macro” factors.
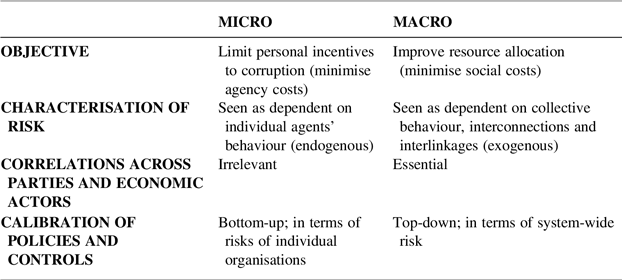
Micro factors comprise key incentives and crucial variables determining the behaviour of those who engage in corrupt practices (individual incentives, rent seeking, inequities in intra- organisational allocation and evaluation of power and privilege, and so on). Corrupt behaviour can arise in a number of different forms, but the agency theory serves as the major theoretical underpinning for most of them.Footnote 28 Traditional microeconomic research into the causes of corruption is based on information economics and agency models, more recently supplemented by empirical studies. Information economics is grounded on two pillars: (i) not all the principals have the same amount of information on their exchange (information asymmetry); and (ii) agents’ actions and their effects are not easy to observe and/or quantify. Under these assumptions, theoretical and empirical research examines potential maverick behaviours of markets and government and suggests measures that could reduce such behaviours at the lowest possible cost.Footnote 29
Macro factors, on the other hand, refer to the dynamic interaction between corruption and the market where corruption occurs. Not only should corruption be defined by referring to the behaviour triggering it, but also, quite significantly, by examining how corruption affects the allocation of economic resources in the marketplace. We claim that this economic, social, and institutional dimension of corruption plays a pivotal role in orientating the efforts of states and international organisations in countering corruption.
Some studies have already taken this “macro” perspective, instead of defining corruption as an individualistic action. Those studies approached corruption as a social deviation (from an optimum).Footnote 30 They analysed the negative impact of corruption on the economic, social, and political development of countries, due, for instance, to the increased transaction costs, the reduction in the efficiency of public services, the distortion of the decision-making process, and the undermining of social values. Empirical research demonstrates that corruption is associated with social costs and inefficiencies.Footnote 31 However, no definitive estimate has been produced of the total impact of corruption in economic terms, due to the variety of specifications of variables of the statistical models used to estimate the costs of corruption.Footnote 32
Further, Shleifer and Vishny study how corruption can result in promoting allocative efficiency. They conclude that corruption might indeed improve bargaining outcomes between agents in the public and private sector, in line with the logic of the Coase theorem. Their study shows that bribery is a cheap way to distribute wealth between politicians and agents in the private sector, and because of this, both parties have an incentive to maximise total wealth. In the absence of bribery, in fact, the politicians would attempt to expropriate wealth in other, less efficient ways, and the resource allocation would become politically motivated and inefficient.Footnote 33
Thus, corruption might increase efficiency by allowing private sector agents to buy their way out of some of the inefficiencies that would otherwise be introduced by politicians. Boycko et al warn, however, that this does not guarantee the best allocation of resources, unless the objectives of politicians and their counterparts in the private sector accurately reflect social welfare in a broader way.Footnote 34 Macro-econometric findings on the relationship between economic cycles and corruption corroborate such uncertainty. On the one hand, data show that corruption is a contribution factor in worsening economic recessions or slowdowns.Footnote 35 On the other, there is proof that recessions help contrasting illegal agreements, as resources become more valuable and competitive pressure increases.Footnote 36
Along the same lines, comprehensive studies have been conducted on the efficiency implications of corruption through its impact on growth and investment, international trade, and development. Arnone and Borlini conclude that corruption generally reduces growth and investment, skews expenditure towards public investment and away from operations and maintenance, and redirects foreign direct investment towards countries with lower corruption.Footnote 37
Treisman argues for more use of experience-based corruption measures, in order to provide a statistical analysis searching for macro determinants of these measures, in comparison with those used in previous studies on perceived corruption measures.Footnote 38 More recently, the same author draws attention to the divergence between perceived corruption measures aggregated by Transparency International (TI) and the World Bank, and the experience-based corruption measures, which survey business managers’ actual experience with corruption.Footnote 39 Past studies have established correlation (both statistically significant or otherwise) between perceived corruption and a wide variety of political, economic, social, and cultural factors. However, the main doubt with respect to these studies is how well the perceived corruption measures reflect cross-national differences in corruption levels, instead of just differences in reputations. Such doubt is backed by numerous studies invalidating the correlation between corruption perception and experience in several countries. A quick statistical test by the author using TI’s perceived and experience-based data shows that while there is a positive correlation between perceived and actual corruption experience in rich democracies and poor autocracies, for the rest of the countries the correlation is much harder to discern. The author does acknowledge the problems plaguing the two types of measures. Perceived corruption measures can suffer from preconceived bias shaped by external influences other than direct information. Experience-based measures may encounter problems such as respondents’ reticence or insincerity, which can lead to underreporting or misleading data. However, the author does not believe that these problems are the cause of the disparity between the two types of measures, pointing out that countries with greater restrictions on freedom of speech and the press and countries where bribery appears to be under-reported do not coincide.
Chen et al carry out empirical analysis of the micro and macro factors affecting how likely bribery is to occur.Footnote 40 The analysis provides statistical evidence suggesting that macro factors do indeed have a significant role in the likelihood of bribery.
On the other hand, next to economic analysis, a range of social sciences literature, notably from criminology and political sciences, has discussed various “macro”-level factors contributing to corruption, including market characteristics.Footnote 41
Notably, Lord and Levi focus mainly on the finances of corruption, more specifically on transnational corporate bribery: what is financed and how the funds are raised, as well as the distribution mechanisms, in the hope that the analysis would provide crucial inputs for formulating effective intervention policies.Footnote 42 The authors classify the aspects of transnational corporate into two types: necessary elements and contingent conditions. The necessary elements consist mainly of micro aspects, pertaining to the actors involved in the act of bribery. The contingent conditions are those that facilitate and shape bribery, which consists mainly of macro aspects of corruption, such as social and legal contexts as well as collaboration among those directly and indirectly involved.
In details, the necessary elements are: (i) legitimate access to the bribery locations/resources; (ii) spatially separated from the ultimate victims, which allows for the decisions to bribe to be rational (grounding acts of bribery in microeconomic theories of economic rationality and individual decision-making); (iii) an appearance of legitimacy.
On the other hand, the contingent conditions amount to: (i) cooperating social/corporate networks (horizontally organised and flexible) of external actors such as accountants or lawyers; (ii) financial institutions willing cooperate with anonymous shell companies (in order to legitimise bribes); (iii) less developed enforcement and infrastructures (which reduce risks and increases the expected value of bribery).
These macro factors shape how the finances of bribery can be – and are – organised, by creating a conducive environment in which bribery can take place should the necessary elements be present. The authors suggest that policies aiming to reduce and prevent bribery should, based on their hypotheses, focus on both the necessary and contingent factors. They contend that it is at the corporation level that intervention policies may work best.
Natural resources management studies elaborated further on this perspective, as a result of the postulation that corruption is the main reason behind the resource curse. Corruption is said to have two main forms: rent-seeking and patronage. According to the rent-seeking perspective, macro factors play a significant role in encouraging rent-seeking behaviours. Economies with bad institutions and ethnic fractionalisation are said to be conducive for rent-seeking. The patronage phenomenon also depends on the quality of institutions of a country. Bad institutions – in this case institutions responsible for the allocation of public resources – once again are said to facilitate the resource curse. Political competition, or the lack thereof, is also another factor that enables patronage behaviours. Natural resource sectors also require complex contractual and technological arrangements, which make it easier to engage in and conceal corruption than in other sectors. The complex networks of private agents and public officials involved also increase the likelihood of corruption. It is the availability of opportunities systemic to natural resource sectors that incentivises the many players, and incentives for corruption emerge at each and every stage of the resource-extracting process. Yet, different natural resource sectors have different sets of incentives for and risks of corruption, suggesting that a one-size-fits-all approach is not recommended.Footnote 43
V. Systemic risk and macro prudential financial regulation
Systemic risk is a complex concept with no clear consensus on its definition, both before and after the financial crisis 2007–2009.Footnote 44 Authorities often perceive systemic risk in terms of financial stability, or, to be more precise, the lack thereof. The US Financial Oversight Council (FSOC), created by the Dodd-Frank Act, views systemic risk as something that affects “the stability of the financial system as a whole, as opposed to the risk facing individual financial institutions or market participants”.Footnote 45 The UK Financial Services Act 2012 defines systemic risk as “a risk to the stability of the UK financial system as a whole or of a significant part of that system”.Footnote 46 Regulation (EU) No 1092/2010 of the European Parliament and of the Council of 24 November 2010 established the European Systemic Risk Board (ESRB), whose objective is to detect “a risk which could seriously jeopardise the orderly functioning and integrity of financial markets or the stability of the whole or part of the Union’s financial system”.Footnote 47 It appears that while legislators recognise the significance of the concept of systemic risk and its considerable relevance to financial stability, these current legal definitions of systemic risk are nebulous and lacking in substance. Such definitions therefore seem to be inadequate in guiding the decision-making process of relevant authorities and providing legal basis for policies.Footnote 48
The economic literature has also been unable to come to an agreement with regard to systemic risk. In a survey on the literature, Benoit et al define systemic risk as the risk of an occurrence of an event that can severely and adversely affect many market participants simultaneously, then spreads through the system.Footnote 49 Smaga surveys 55 general definitions, each of which concerns itself with different aspects of systemic risk.Footnote 50 Reviewing these definitions uncovers several interesting trends. In line with Benoit et al’s definition, the most common features of systemic risk are its large scale and its contagion effects. Before the financial crisis 2007–2009, many definitions emphasised the sudden nature of the triggering event, and a subsequent loss of confidence. After the crisis, however, attention was shifted towards its impact on the real economy, the resulting insolvency/defaults, and its evolving nature.
There is a broad consensus regarding the two dimensions of systemic risk: the time dimension and the cross-sectional dimension.Footnote 51 The time dimension of systemic risk refers to the cyclicality of the business cycle, and how systemic risk builds up and evolves pro-cyclically over time. The cross-sectional dimension refers to the distribution of systemic risk at any point in time. Butzbach interprets this as the degree of interconnectedness of financial institutions.Footnote 52 Freixas et al open up the definition to refer to other negative externalities that are exogenous to the system. These include spill overs following negative events and policies, and sparked a sheer interest in the analysis of contagion, particularly using network models.
As Claudio Borio maintains, macro “is an orientation or perspective of regulatory and supervisory arrangements”.Footnote 53 Macro-perspective means calibrating them from a system-wide or systemic perspective, rather than from that of the safety and soundness of individual institutions on a stand-alone basis. It implies taking a top-down approach and identifying the desirable output for the system as a whole and, from there, eventually deriving the optimum for the individual institutions within it. It means explicitly taking into account the fact that drivers of risk depend on the collective behaviour of the parties and actors in the market.
VI. The application of the concept of ‘systemic risk’ to corruption
In taking this peculiar stance, this orientation or perspective of regulatory arrangements, we move the policy questions to the identification of the causal connection between corruption and market mechanism. This means that our analysis is focusing on sectors and activities that are most affected; ways in which corruption distorts the allocation of the factors of production, ie labour, capital; ways in which corruption hampers the competitiveness of domestic markets and income distribution. In declining to apply this macro-perspective angle, we draw upon the concept of systemic risk, as thoroughly elaborated by the economic and legal literature in the domain of banking and finance. Since the “macro” perspective indeed gained great momentum in the financial sector, we consider it meaningful to integrate ideas from this field into the anti-corruption debate.
So, what would the concept of “interconnectedness” of global financial institutions, a key contributor to systemic risk in financial markets, look like in corruption? What would the mapping of the “architecture” entail? What sorts of connections, between what kinds of institutions, in what kinds of circumstances, would make corruption pose a “systemic risk” of leading to such failures? We proceed and attempt to transfer the nuances developed in the “systemic risk” financial regulation literature to the field of corruption.
In his ground-breaking contribution, Schwarcz asserts that greater focus should be devoted to the marketplace and the relationship between markets and institutions, rather than to the phenomena taking place at the “micro” level. In building up his arguments, he defines systemic risk as the situation where a “trigger event, such as an economic shock or institutional failure, causes a chain of bad economic consequences – sometimes referred to as a domino effect that impact markets”.Footnote 54 In the financial sector, the chain of negative economic consequences occurs because banks are closely intertwined financially.Footnote 55 They lend to and borrow from each other, hold deposit balances with each other, and make payments through the interbank clearing system. Because of this interconnectedness, one bank’s default on an obligation to another may adversely affect that other bank’s ability to meet its obligations to yet other banks, and “so on down the chain of banks and beyond”.Footnote 56 The ultimate objective of a macro-prudential approach to regulation and supervision is thus to avoid or minimise the costs they generate for the real economy.Footnote 57
This perspective lends itself well to an interpretation of some forms of corruption. In fact, corruption sets in motion a chain of economic, institutional, and social costs, nullifying the correct functioning of market mechanisms with potential destructive consequences for the whole economy.
Thus, by synthesising the relevant factors to the purposes of this study, we can reach a working definition of systemic risk: the risk that (i) a corruption act triggers either (X) the failure of a chain of markets or institutions or (Y) a chain of significant (transitory positive or) negative economic consequences, possibly producing social costs and hence (ii) resulting in a miss-allocation of resources (ie increases the cost or decreases the availability of capital, labour, land, and entrepreneurship).
The concept of X is elaborated along the lines of what political scientists, such as Lessig and Thompson, have termed “institutional corruption”, where public bodies have lost their function and public confidence due to institutional corruption.Footnote 58 As explained in Thompson’s book, Ethics in Congress: From Individual to Institutional Corruption, and as developed in a series of articles that extend and refine the idea, “institutional corruption” is defined in contrast to “individual corruption”.Footnote 59 “Individual corruption”, Thompson explains, is the “personal gain or benefit by a public official in exchange for promoting private interests”. “Institutional corruption”, by contrast, is “political gain or benefit by a public official under conditions that in general tend to promote private interests”.
Y indicates the setting in motion of a negative consequences (ie misallocation of resources, factors of production, etc) due to connection and contagion. This element is quite essential, since it moves the focus on effective rules, reliable institutions and effective system of prevention, control, and punishment of deviant behaviour (governance) to whether and how the qualitative characteristics of governance cause the actual spreading of corruptive episodes.
In fact, contagion is inherent to the systemic risk and occurs when systemic risk materialises.Footnote 60 Contagion is the main mechanism through which instability becomes so widespread that a crisis reaches systemic dimensions, resulting in an appreciable misallocation of factors of production and economic resources.
This implies that systemic risk boils down to transmission. The transmission is sequential, in a causal sense, as the triggering event occurs in one point of space (or one economic actor) and moves to another or others, depending on the network of relations connecting all the points (and economic actors) of the ecosystem. As well described by Smaga, “contagion effect can therefore be defined as the probability that the instability of the given institution (instrument, market, infrastructure, financial system sector) will spread to other parts of the system with negative effects”.Footnote 61
The transmission mechanism multiplies the shock, resulting in a domino effect with a negative impact on the overall reallocation of resources (allocative efficiency). Contagion and transmission depend then on the various channels through which the initial shock (trigger event, ie corruption) spreads out.
In that respect, countering systemic risk requires, among other things, the study of the level of “interconnectedness” in a given context, and “interlinkages” between the different actors involved. In order to detect the pattern of diffusion, it is essential to map out what Lessig refers to as “architecture” – that is, the code, protocols, platforms, and structures that determine how firms behave and how policy- and law-makers react.Footnote 62 The set of relations between economic actors and social, political, legal, and civil institutions is indeed essential since it creates the network through which occurrence can ignite systemic risk and provoke social costs. Such architecture consists of a set of rules, institutions and agents who mutually interact in the management of resources. This is in line with the very foundational idea of the law as an instrument used by the state to achieve the community’s chosen collective goals, creating and policing the boundaries of a platform for free and secure interaction between participants.Footnote 63 In that regard, the law is a “facilitator” serving as a connecting point between the different parties and actors of the market. The law hence frames the interactions, generating “the rules of the game” and whether and how each player is dependent on and intertwined with the others.
Gaining a comprehensive understanding of the dynamics through which corruption proliferates within and between markets therefore entails an in-depth analysis of the dynamic interactions between actors and/or systems, and to the operations of forces which produce a constant tension between stability and change within a system. However, those interactions are themselves “complex and intricate, as actors are diverse in their goals, intentions, purposes, norms, and powers”.Footnote 64 This creates a difference in how the “micro” perspective and the “macro” perspective pursue their objectives, characterise risks, appraise correlations across parties and economic actors, and eventually calibrate their policies respectively (see Table 1).
To address common exposures and interlinkages operationally, financial policy-makers and scholars alike studied the contribution of each market player to systemic risk, once a given level of acceptable risk for the system as a whole is selected.Footnote 65 Taking into account elements listed above, one can propose a conceptual model of “macro” analysis of corruption. The model consists of several components. Such components might be considered as the steps of a policy “roadmap” to gauge the intensity and likelihood of “systemic risk”:
triggering event (type of corruption practice, source, duration, scope);
institutions (legal, political, and economic) affected by the triggering event or shock;
channels of contagion (mapping out where the “triggering point” is located and what network of relation revolves around the triggering point);
structural vulnerabilities (mapping out how the “point” or “place” where corruption occurred connects with the network, ie regulatory fragmentation, lack of enforcement mechanisms, peculiarities of the good or service subject of corruption, etc).
The micro and macro perspective to corruption compared

VII. Concluding remarks
This paper surveys a range of issues relating to the law and economics analysis of corruption. The widespread disjunction between “markets” and “corruption” represents something of a puzzle. Up until now very scant interest has been paid to the interdependencies between corruption and the market where corruption occurs. To the contrary, we believe that the formation of law and policy to counter corruption ought to incorporate considerations pertaining to market dynamics.
This study represents the first attempt to conceptualise how corruption relates to the context within which it occurs and thus to formalise a theory of the systemic implications of corruption. From a policy-making perspective, this study demonstrates that a “macro” perspective is as useful for understanding (and consequently addressing) corruption as the (prevailing) “micro” perspective. In fact, some “macro” factors mould the manifestation of the corrupt practice, along with “micro” factors.
Corruption is often undertaken as a means of overcoming efforts to transfer resources through regulation. Corruption tricks the market, and the legal order of the market, to transfer resources to the hands of few at the expense of community. To prevent such phenomena, policies and regulatory engagement need to scrutinise and incorporate the signals and characteristics of the market. The essence of this approach is that corruption is no longer seen as isolated from markets. Rather, the patterns of corruption are materially influenced by how the market is formed and by the set of relations between economic actors.
This innovative entry point of analysis into the policy debate opens up interesting avenues for further research, particularly relating to analytical tools and policy actions to adequately monitor interconnectedness and contagion. This might involve potential contagion channels to be identified and modelled, allowing for the possibility to broadening the range of macroprudential instruments beyond those currently available, which focus almost exclusively on the micro dimension of corruptive phenomena.