


1. Introduction
According to Barlow and Proschan [Reference Barlow and Proschan8], one of the most important aims of reliability theory is to provide researchers with all the necessary tools to understand, estimate, and optimise the lifespan and failure distributions of systems and their components. In reliability theory, ageing is defined as a phenomenon of increasing risk of failure with the passage of time. If the risk of failure is not increasing with age (the ‘old is as good as new’ principle), then there is no ageing in terms of reliability theory, even if the calendar age of a system is increasing. Thus, regular and progressive changes over time do not constitute ageing unless they produce some deleterious outcome (failures). Rausand and Høyland [Reference Rausand and Høyland38] define failure as the event that makes the system behave differently than is desired and expected. ‘Positive ageing’ can be identified in cases where the residual lifetime tends to decrease with increasing age of the system. ‘Negative ageing’ (also known as ‘beneficial ageing’) has the exact opposite effect, but this is a less common situation and has attracted significantly less research interest.
Ageing properties can be employed in order to define different classes of lifetime distributions. Note that the exponential distribution is a member of almost every class, exactly because of its memoryless property. Lifetime distributions can be characterised by their reliability function, their conditional survival function, their failure rate, or their expected value of residual life. These quantities are used to express different notions of ageing, also known as reliability classes. For example, distributions that have either increasing failure rate (IFR) or decreasing failure rate (DFR) have been studied by various researchers, while other notions such as ‘increasing failure rate on average’ (IFRA), ‘new better than used’ (NBU), ‘new worse than used’ (NWU), ‘new better than used in expectation’ (NBUE), ‘new worse than used in expectation’ (NWUE), and ‘decreasing mean residual life’ (DMRL) have also attracted a lot of attention.
The interesting properties of these ageing classes include preservation or closure properties of a given class under the formation of coherent systems of independent components, under convolution or mixture. It is also important to be able to provide reliability bounds and moment inequalities and to test exponentiality against other lifetime distributions. Properties of IFR and DFR have been studied by Barlow and Proschan [Reference Barlow and Proschan8] and Patel [Reference Patel35], while important results for IFRA can be found in Barlow and Proschan [Reference Barlow and Proschan8], Sengupta [Reference Sengupta39], and El-Bassiouny [Reference El-Bassiouny20]. Abouammoh and El-Neweihi [Reference Abouammoh and El-Neweihi1] showed that the NBU class is closed under formation of parallel systems of independent and identically distributed components, while Barlow and Proschan [Reference Barlow and Proschan8] provided probability bounds for NBU, NWU, NBUE, and NWUE. Chen [Reference Cheng and He15] showed that the distributions of these classes may be characterised through certain properties of the corresponding renewal functions; Cheng and He [Reference Cheng and He15] studied reliability bounds on the NBUE and NWUE classes, while Cheng and Lam [Reference Cheng and Lam16] obtained reliability bounds on NBUE from the first two known moments. Bryson and Siddiqui [Reference Bryson and Siddiqui12] proved that IFR (DFR) implies DMRL (IMRL), Abouammoh and El-Neweihi [Reference Abouammoh and El-Neweihi1] proved that DMRL classes are closed under the formation of parallel systems, and Abu-Youssef [Reference Abu-Youssef2] derived a moment inequality that was used by the author to derive a test for testing exponentiality against DMRL (IMRL).
Another important aspect in the study of lifetime distributions is their order relations. These usually define partial orderings which establish a comparison between two lifetime variables in terms of their failure rates, density functions, survival functions, mean residual lives, or other ageing characteristics. Ageing classes can often be characterised by partial orderings. Barlow and Proschan [Reference Barlow and Proschan8] proved that IFR and IFRA classes are characterised by some specific choice of ‘convex ordering’ and ‘star-shaped ordering’ respectively. Partial ordering of lifetime distributions has been studied extensively by various authors (see for example Deshpande et al. [Reference Deshpande, Kochar and Singh18], Kochar and Wiens [Reference Kochar and Wiens23], Singh [Reference Singh41], Fagiuoli and Pellerey [Reference Fagiuoli and Pellerey21], and Shaked and Shanthikumar [Reference Shaked and Shanthikumar40]) because of their applicability in a wide spectrum of different fields, such as econometrics (Whitmore [Reference Whitmore46]), reliability (Barlow and Proschan [Reference Barlow and Proschan8]), queues (Stoyan [Reference Stoyan43]), and other stochastic processes (Ross [Reference Ross37]). Singh and Jain [Reference Singh and Jain42] and Fagiuoli and Pellerey [Reference Fagiuoli and Pellerey21] have proposed an application to stochastic comparison between two devices that are subjected to Poisson shock models.
In many application fields, researchers are often interested in comparing the skewness of two distributions. Van Zwet [Reference Van Zwet45] introduced a new skewness order, the so-called convex transform order. In reliability theory this particular order is used to capture the fact that one distribution is more IFR (increasing failure rate) than another distribution. Kochar and Xu [Reference Kochar and Xu26] proved that a parallel system with heterogeneous exponential component lifetimes is more skewed (according to the IFR order) than a system with independent and identically distributed exponential components. In other words, they proved that a parallel system with homogeneous exponential components ages faster than a system with heterogeneous exponential components in the sense of the ‘smaller in IFR’ property. Many authors have studied orderings of such systems when the parameters of the exponential distributions satisfy certain restrictions (see for example Dykstra et al. [Reference Dykstra, Kochar and Rojo19], Khaledi and Kochar [Reference Khaledi and Kochar22], and Kochar and Xu [Reference Kochar and Xu24], [Reference Kochar and Xu25], among many other authors). Recently, a number of researchers have also studied the case where the exponential distribution is replaced by some generalised versions (see, for example, Balakrishnan et al. [Reference Balakrishnan, Haidari and Masoumifard7] and Bashkar et al. [Reference Bashkar, Torabi and Asadi9]).
Over the last decades there has been increasing interest in generalised partial orderings, and several generalisations can be found in the literature. Some of these new ordering notions led to the creation of new ageing classes. Averous and Meste [Reference Averous and Meste6] and later Fagiuoli and Pellerey [Reference Fagiuoli and Pellerey21] introduced new concepts of partial stochastic ordering, namely  $s{-}\text{FR}$
,
 $s{-}\text{ST}$
,
 $s{-}\text{CV}$
,
 $s{-}\text{CX}$
, and
 $s{-}\text{SFR}$
. For the case where
 $s=1$
or
 $s=2$
the new orderings reduce to well-known stochastic orders. The authors provide relations between the new ordering concepts and classical partial orders, and they also give the definitions of the related classes of lifetime distributions. Nanda et al. [Reference Nanda, Hazra, Al-Mutairi and Ghitany32] introduced new generalised partial orderings, in particular the
 $s{-}{\rm IFR}$
,
 $s{-}{\rm IFRA}$
,
 $s{-}\text{NBU}$
,
 $s{-}\text{NBUFR}$
, and
 $s{-}\text{NBAFR}$
orderings. In their paper they also provide some equivalent representations for each ordering, and they discuss interrelations among these orderings. Again for
 $s=1, 2, 3$
some of these new orderings are equivalent to already known partial stochastic orders. Note that in what follows the IFR ordering will be denoted by
 $1{-}{\rm IFR}$
, following the notation introduced by the references mentioned above. Despite the fact that for higher values of s these partial orderings may not have clear and meaningful interpretations, their mathematical niceness and the fact that they unify existing results make their study very interesting. Nevertheless, one motivation for these extensions can be found in Loh [Reference Loh28], where different types of generalised partial orderings were used in testing for discrepancies in the tails of symmetric distributions.
In ageing literature the usage and application of these new orderings for  $s\geq 3$
have been scarce, possibly due to the lack of an obvious or simple interpretation of the meaningfulness of higher-order relationships. All the
 $s{-}\text{orders}$
depend on an iterative construction that reassigns tail weights suitably, as expressed in Definition 2.1 below. This construction has a close connection with moments of survival lifetime, as is recalled in Lemma 2.1. Higher-order moments of survival lifetime have not yet found much popularity when dealing with ageing problems and characterisations, but this notion has been widely used in economics or finance literature to compare risk policies, portfolio optimisation techniques, or social redistribution of wealth. We should note, however, that in each context the survival moments need an appropriate normalisation, so the translation of conclusions between different frameworks is not necessarily straightforward. As an example, Atkinson [Reference Atkinson5] considered a general family of risk measures to compare the distribution of income. Higher-order survival moments are interpreted, in this context, as the prevailing of the richest over the poorest, an approach often referred to as ‘illfare’, as opposed to ‘welfare’, where the protection of the poorest is given more concern. The same idea is explored later in Muliere and Scarsini [Reference Muliere and Scarsini31], where
 $s{-}\text{Gini}$
type indices are studied in much the same spirit. Here, the tail mass reassignment parameter s is used to address comparison problems between intersecting Lorenz curves. This same idea applied to Lorenz orderings, although for small values of s, is explored in Lando and Bertolli-Basotti [Reference Lando and Bertoli-Barsotti27], where third-order comparisons are used to rank distributions with respect to the role of the left tail of the distribution. Still with economical applications in view, iterated distributions have been used more recently to compare moments of different random variables, helping to decide which one represents a safer or riskier financial application. For instance, Ortobelli et al. [Reference Ortobelli, Rachev, Shalit and Fabozzi34] use a variant of
 $s{-}{\rm IFR}$
(these authors use a different normalisation) to derive order relations between the first differing moments of random variables. In another direction, Rachev and Rüschendorf [Reference Rachev and Rüschendorf36] use higher-order survival moments to characterise approximations between distributions, in connection with Zolotarev ideal metrics. As an application, these authors build distributional approximations such that some predefined lower-order moments coincide. The Zolotarev ideal metrics, hence survival moments, have also been used to prove central limit theorems, with a characterisation of the convergence rate, in Boutsikas and Vaggelatou [Reference Boutsikas and Vaggelatou11].
In this paper, we study some properties of lifetimes that are either  $s{-}{\rm IFR}$
or
 $s{-}{\rm IFRA}$
, and at the same time we are interested in constructing criteria that will enable us to identify whether specific lifetime distributions are ordered via the
 $s{-}{\rm IFR}$
order. One of the main results of this work is that although in general, the
 $s{-}{\rm IFR}$
(or the
 $s{-}{\rm IFRA}$
) ordering is not an inherited trait of distributions, Theorem 3.1 of Kochar and Xu [Reference Kochar and Xu26] is verified for the
 $s{-}{\rm IFR}$
ordering for any positive integer s.
The paper is structured as follows: in Section 2 we provide some definitions and results that will be useful for the rest of the paper, while Sections 3 and 4 refer to properties of distributions that are either  $s{-}{\rm IFR}$
or
 $s{-}{\rm IFRA}$
. In Section 5 we will present an example of distributions that proves that two stochastic orders that were reported in the literature as equivalent are in fact two different concepts. The main results of the paper are concentrated in Sections 6 and 7. In particular, in Section 6 we provide a new criterion for the
 $s{-}{\rm IFR}$
ordering via
 $s{-}{\rm IFRA}$
order, and in Section 7 this new criterion is used to prove ageing properties of parallel systems formed with components that have exponentially distributed lifetimes.
2. Preliminaries
We recall here the basic definitions and representations for tail-weight iterated distributions. These iterated distributions were introduced by Averous and Meste [Reference Averous and Meste6] and initially studied by Fagiuoli and Pellerey [Reference Fagiuoli and Pellerey21]. Let X be a nonnegative random variable with density function  $f_X$
, distribution function
 $F_X$
, and tail function
 $\overline{F}_X=1-F_X$
.
Definition 2.1. For each  $x\geq 0$
, define
 \begin{equation}\overline{T}_{X,0}(x)=f_{X}(x)\quad \mbox{and}\quad \widetilde{\mu}_{X,0}=\int_0^\infty \overline{T}_{X,0}(t)\,dt=1.\end{equation}
For each  $s\geq 1$
, define the
 $s-\text{iterated}$
distribution
 $T_{X,s}$
by its tail
 $\overline{T}_{X,s}=1-T_{X,s}$
as follows:
 \begin{equation}\overline{T}_{X,s}(x)=\frac{1}{\widetilde{\mu}_{X,s-1}}\int_{x}^\infty\overline{T}_{X,s-1}(t)\,dt,\quad \mbox{where}\quad \widetilde{\mu}_{X,s}=\int_0^\infty \overline{T}_{X,s}(t)\,dt.\end{equation}
Moreover, we extend the domain of definition of each  $\overline{T}_{X,s}$
by defining
 $\overline{T}_{X,s}(x)=1$
for
 $x<0$
.
The distribution  $\overline{T}_{X,2}$
is also known as the equilibrium distribution of X, and plays an important role in ageing relations (see, for example, Chatterjee and Mukherjee [Reference Chatterjee, Mukherjee, Balakrishnan, Rao and North-Holland13]) and in renewal theory (see Cox [Reference Cox17]). Hence, the iteration process above defines, for each
 $s\geq 1$
,
 $\overline{T}_{X,s}$
as the equilibrium distribution of a random variable with tail
 $\overline{T}_{X,s-1}$
. Although the definitions are introduced in a recursive way, a closed form representation for the iterated distributions is available.
Lemma 2.1. (Lemma 2 and Remark 3 in Arab and Oliveira [Reference Arab and Oliveira3]) The tails  $\overline{T}_{X,s}$
may be represented as
 \begin{equation}\overline{T}_{X,s}(x)=\frac{1}{\mathbb{E} X^{s-1}}\int_x^\infty f_{X}(t)(t-x)^{s-1}\,dt.\end{equation}
The  $s-$
iterated distribution moments are given by
 \begin{equation}\widetilde{\mu}_{X,s}=\frac{1}{s}\frac{\mathbb{E} X^{s}}{\mathbb{E} X^{s-1}}.\end{equation}
Note that (2.3) may be rewritten as
 \begin{equation}\overline{T}_{X,s}(x)=\frac{1}{\mathbb{E} X^{s-1}}\mathbb{E}(X-x)_+^{s-1},\end{equation}
where  $(X-x)_+=\max(0,X-x)$
is the residual lifetime at age x. Therefore, the
 $s-$
iterated distribution may be interpreted as the normalised survival moment of order
 $s-1$
.
One of the simplest and most common notions of ageing is defined through the monotonicity of the failure rate function of a distribution,
 \[\frac{f_X(x)}{1-F_X(x)}=\frac{\overline{T}_{X,0}(x)}{\overline{T}_{X,1}(x)}.\]
The direct verification of this monotonicity is, in general, not a simple task, as for many distributions the tail does not have an explicit closed representation, or at least not a manageable one. Having defined iterated distributions, it becomes natural to proceed likewise with respect to the failure rate functions, as defined in Nanda et al. [Reference Nanda, Hazra, Al-Mutairi and Ghitany32] and also studied in Arab and Oliveira [Reference Arab and Oliveira3].
Definition 2.2. For each  $s\geq 1$
and
 $x\geq 0$
, define the
 $s-$
iterated failure rate function as
 \begin{equation*}r_{X,s}(x)=\frac{\overline{T}_{X,s-1}(x)}{\int_x^\infty\overline{T}_{X,s-1}(t)\,dt}=\frac{\overline{T}_{X,s-1}(x)}{\widetilde{\mu}_{X,s-1}\overline{T}_{X,s}(x)}.\end{equation*}
It is obvious that for  $s=1$
we find the failure rate of X to be
 $r_{X,1}(x)=\frac{f_{X}(x)}{\overline{F}_{X}(x)}$
; hence the monotonicity of the failure rate is expressed as the monotonicity of
 $r_{X,1}$
. We may extend this monotonicity notion by considering the
 $s-$
iterated distribution, as done in Averous and Meste [Reference Averous and Meste6], Fagiuoli and Pellerey [Reference Fagiuoli and Pellerey21], and Nanda et al. [Reference Nanda, Hazra, Al-Mutairi and Ghitany32], among many other references.
Definition 2.3. For  $s=1,2,\ldots$
, the nonnegative random variable X is said to be
1.
 $s{-}{\rm IFR}$
(resp.
$s{-}{\rm DFR}$
) if
$r_{X,s}$
is increasing (resp. decreasing) for
$x\geq 0$
;
2.
$s{-}{\rm IFRA}$
(resp.
$s{-}{\rm DFRA}$
) if
$\frac{1}{x}\int_0^x r_{X,s}(t)\,dt$
is increasing (resp. decreasing) for
$x>0$
.


The above-mentioned references introduce a few other monotonicity notions, but we refer only to the ones to be addressed in the present paper. Note that it follows easily from the definition above that the  $s{-}{\rm IFR}$
monotonicity of a random variable X implies that the variable is also
 $s{-}{\rm IFRA}$
.
We introduce next the order relations to be addressed.
Definition 2.4. Let  $\mathcal{F}$
denote the family of distribution functions F such that
 $F(0)=0$
, let X and Y be nonnegative random variables with distribution functions
 $F_X,F_Y\in\mathcal{F}$
, and let
 $s\geq 1$
be an integer.
1. The random variable X (or its distribution
$F_X$
) is said to be smaller than Y (or its distribution
$F_Y$
) in
$s{-}{\rm IFR}$
order, and we write
$X\leq_{s{-}{\rm IFR}}Y$
(or equivalently
$F_X\leq_{s{-}{\rm IFR}}F_Y$
), if
$c_s(x)=\overline{T}_{Y,s}^{-1}(\overline{T}_{X,s}(x))$
is convex.2. The random variable X (or its distribution
$F_X$
) is said to be smaller than Y (or its distribution
$F_Y$
) in
$s{-}{\rm IFRA}$
order, and we write
$X\leq_{s{-}{\rm IFRA}}Y$
(or equivalently
$F_X\leq_{s{-}{\rm IFRA}}F_Y$
), if
$t_s(x)=\frac{1}{x}c_s(x)$
is increasing (this is also known as
$c_s(x)$
being star-shaped).


Fagiuoli and Pellerey [Reference Fagiuoli and Pellerey21] and Nanda et al. [Reference Nanda, Hazra, Al-Mutairi and Ghitany32] concentrated on establishing relations between the ordering notions defined. It is useful to note that these order relations define partial order relations in the equivalence classes of  $\mathcal{F}$
corresponding to the equivalence relation
 $F\sim G$
defined by
 $F(x)=G(kx)$
for some
 $k>0$
. In case of families of distributions that have a scale parameter, this allows one to choose the parameter in the most convenient way.
The exponential distribution plays an important role when dealing with ageing notions. Besides being a fixed point with respect to the iteration procedure, comparability with the exponential, either in the  $s{-}{\rm IFR}$
or
 $s{-}{\rm IFRA}$
sense, is equivalent to
 $s{-}{\rm IFR}$
or
 $s{-}{\rm IFRA}$
monotonicity, as proved by Nanda et al. [Reference Nanda, Hazra, Al-Mutairi and Ghitany32] (see Theorems 3.2 and 4.3).
Theorem 2.1. Let X be a random variable with distribution function  $F_X\in\mathcal{F}$
and Y a random variable with exponential distribution.
1.
$X\leq_{s{-}{\rm IFR}}Y$
(resp.,
$Y\leq_{s{-}{\rm IFR}}X$
) if and only if X is
$s{-}{\rm IFR}$
(resp., X is
$s{-}{\rm DFR}$
).2.
$X\leq_{s{-}{\rm IFRA}}Y$
(resp.,
$Y\leq_{s{-}{\rm IFRA}}X$
) if and only if X is
$s{-}{\rm IFRA}$
(resp., X is
$s{-}{\rm DFRA}$
).


As an immediate consequence of the above, we have the following comparison results.
Corollary 2.1. Let X and Y be random variables with distribution functions  $F_X,F_Y\in\mathcal{F}$
, and
 $s\geq 1$
an integer. If X is
 $s{-}{\rm IFR}$
and Y is
 $s{-}{\rm DFR}$
, then
 $X\leq_{s{-}{\rm IFR}}Y$
. The same holds upon replacing IFR and DFR by IFRA and DFRA, respectively.
A general characterisation of the above order relations is given below (see Propositions 3.1 and 4.1 in Nanda et al. [Reference Nanda, Hazra, Al-Mutairi and Ghitany32]).
Theorem 2.2. Let X and Y be random variables with distribution functions  $F_X,F_Y\in\mathcal{F}$
.
1.
$X\leq_{s{-}{\rm IFR}}Y$
if and only if for any real numbers a and b,
$\overline{T}_{Y,s}(x)-\overline{T}_{X,s}(ax+b)$
changes sign at most twice, and if the change of sign occurs twice, it is in the order ‘
$+,-,+$
’ as x traverses from 0 to
$+\infty$
.2.
$X\leq_{s{-}{\rm IFRA}}Y$
if and only if for any real number a,
$\overline{T}_{Y,s}(x)-\overline{T}_{X,s}(ax)$
changes sign at most once, and if the change of sign occurs, it is in the order ‘
$-,+$
’ as x traverses from 0 to
$+\infty$
.


Remark 2.1. The previous result differentiates the two order relationships by describing when faster ageing of an operating system is detectable. Indeed, Theorem 2.2 states that the ordering with respect to  $s{-}{\rm IFR}$
means that the different ageing rates are still detectable if the starting operating time for the different systems is not simultaneous. The fact that Theorem 2.2, for the
 $s{-}{\rm IFRA}$
ordering, does not include a shift in the argument implies that the star-shaped transform ordering compares the ageing rates of operating systems assuming they started operating at the same time.
Remark 2.2. As mentioned in Remark 25 in Arab and Oliveira [Reference Arab and Oliveira3], it is enough to verify the characterisations in Theorem 2.2 only for  $a>0$
.
The above characterisation requires explicit expressions for the tails of the iterated distributions, which are often not available. Computationally tractable characterisations for deciding about the actual comparison of general distributions were studied in Arab and Oliveira [Reference Arab and Oliveira3]. We quote the characterisation proved in Theorem 27 and Corollary 29 of [Reference Arab and Oliveira3].
Theorem 2.3. Let X and Y be random variables with absolutely continuous distributions with densities  $f_X$
and
 $f_Y$
and distribution functions
 $F_X,F_Y\in\mathcal{F}$
, respectively. Suppose that for every pair of constants
 $a>0$
and
 $b\in\mathbb{R}$
, either the function
 \begin{equation*}H_s(x)=\frac{1}{\mathbb{E} Y^{s-1}}f_Y(x)-\frac{a^{s}}{\mathbb{E} X^{s-1}}f_X(ax+b)\end{equation*}
or the function
 \begin{equation*}H_{s-1}(x)=\frac{1}{\mathbb{E} Y^{s-1}}\overline{F}_Y(x)-\frac{a^{s-1}}{\mathbb{E} X^{s-1}}\overline{F}_X(ax+b)\end{equation*}
changes sign at most twice as x traverses from 0 to  $+\infty$
, and if the change of sign occurs twice, it is in the order ‘
 $+,-,+$
’. Then
 $F_X\leq_{s{-}{\rm IFR}}F_Y$
.
The functions  $H_s$
and
 $H_{s-1}$
may, respectively, be replaced by
 \begin{equation*}P_s(x)=\log f_Y(x)-\log f_X(ax+b)+\log\frac{\mathbb{E} X^{s-1}}{a^{s}\mathbb{E} Y^{s-1}}\end{equation*}
and
 \begin{equation*}P_{s-1}(x)=\log \overline{F}_Y(x)-\log\overline{F}_X(ax+b)+\log\frac{\mathbb{E} X^{s-1}}{a^{s-1}\mathbb{E} Y^{s-1}}.\end{equation*}
The next statement provides a criterion to verify the  $s{-}{\rm IFRA}$
order relation. We do not include a proof, as this follows from reproducing the arguments presented in Arab and Oliveira [Reference Arab and Oliveira3] for the proof of the previous result.
Theorem 2.4. Let X and Y be random variables with absolutely continuous distributions with densities  $f_X$
and
 $f_Y$
and distribution functions
 $F_X,F_Y\in\mathcal{F}$
, respectively. If, for every
 $a>0$
and
 $b=0$
, either of the functions
 $H_s(x)$
or
 $H_{s-1}(x)$
changes sign at most once as x traverses from 0 to
 $+\infty$
, and if, whenever the change of sign occurs, it is in the order ‘
 $-,+$
’, then
 $F_X\leq_{s{-}{\rm IFRA}}F_Y$
. The functions
 $H_s$
and
 $H_{s-1}$
may, respectively, be replaced by
 $P_s(x)$
and
 $P_{s-1}(x)$
.
As indicated in Theorem 2.2, the control of the sign variation of  $\overline{T}_{Y,s}(x)-\overline{T}_{X,s}(ax+b)$
is crucial in characterising the
 $s{-}{\rm IFR}$
and
 $s{-}{\rm IFRA}$
orderings. This function is obtained after integration of the function
 $H_s$
or
 $H_{s-1}$
defined in Theorems 2.3 and 2.4. Below, we quote a result about sign variation after integration which was used in Arab and Oliveira [Reference Arab and Oliveira3] for the proof of Theorem 2.3, and which is an important tool for our results below.
Lemma 2.2. (Lemma 26 in Arab and Oliveira [Reference Arab and Oliveira3]) Let f and g be two real-valued functions defined on  $[0,\infty)$
such that
 \begin{equation*} g(x)=\int_{x}^\infty f(t)\,dt.\end{equation*}
Assume that, as x traverses from 0 to  $+\infty$
, f(x) changes sign in one of the following orders: ‘
 $-,+$
’ or ‘
 $+,-$
’ or ‘
 $+,-,+$
’ or ‘
 $-,+,-,+$
’. Then g(x), as x traverses from 0 to
 $\infty$
, has sign variation equal to every possible final part of the sign variation of f(x).
The lifetime of a parallel system is expressed as the maximum of the lifetimes of its components. When these components have exponentially distributed lifetimes, the distribution function of the system’s lifetime is expressed as a linear combination of exponential terms. Later, it will be important to be able to count and localise the roots of such expressions. The following result will play an important role in this aspect.
Theorem 2.5. (Theorem 1 in Shestopaloff [Reference Shestopaloff44]) Let  $n\geq 0$
,
 $p_0>p_1>\cdots>p_n>0$
, and
 $\alpha_j\ne0$
,
 $j=0,1,\ldots,n$
, be real numbers. Then the function
 $f(t)=\sum_{j=0}^n\alpha_jp^t_j$
has no real zeros if
 $n=0$
, and for
 $n\geq 1$
has at most as many real zeros as there are sign changes in the sequence of coefficients
 $\alpha_0,\alpha_1,\alpha_2,\ldots,\alpha_n$
.
3. Hereditary monotonicity properties
A common feature of iterated monotonicity properties is that of being hereditary with respect to the iteration parameter. However, the hereditary property does not hold for all the order relations defined, as we will be showing below by an example. We quote first the hereditary property for monotonicity of the iterated failure rate.
Lemma 3.1. Let X be a nonnegative random variable. For every integer  $s\geq 1$
, the following relations hold.
a) If X is
$s{-}{\rm IFR}$
, then X is
${(s+1)-}{\rm IFR}$
.b) If X is
$s{-}{\rm DFR}$
, then X is
${(s+1)-}{\rm DFR}$
.


This result is included in Theorem 2 in Navarro and Hernandez [Reference Navarro and Hernandez33]. It implies that, for most distributions, it is enough to verify the  ${1-}{\rm IFR}$
or the
 ${1-}{\rm DFR}$
property. Exhibiting distributions that do not have lower iterated monotonicity but satisfy it after a few iteration steps usually requires a suitable modification of known families of distributions. Such an example, using fattened-tail Pareto distributions, was given in Example 9 in Arab and Oliveira [Reference Arab and Oliveira3]. This suggests a way to construct distributions with failure rates that become monotone only after a few iteration steps. The example below shows the same effect for a distribution that is IFR, instead.
Example 3.1. Let X be a nonnegative random variable with density function
 \[f(x)= \frac{(x^2+c)e^{-x}}{c+2}.\]
It is easily verified that
 \begin{equation*}\overline{T}_{X,1}(x)=\frac{(x^2+2x+2+c)e^{-x}}{c+2}, \qquad \overline{T}_{X,2}(x)=\frac{(x^2+4x+6+c)e^{-x}}{6+c},\end{equation*}
and
 \begin{equation*} r_{X,1}(x)=\frac{f(x)}{\overline{T}_{X,1}(x)}=\frac{x^2+c}{x^2+2x+2+c}, \qquad r_{X,2}(x)=\frac{6+c}{2+c}\!\times\!\frac{x^2+2x+2+c}{x^2+4x+6+c}.\end{equation*}
Differentiating, we find
 \begin{equation*} r_{X,1}^{\prime}(x)=\frac{2x^2+4x-2c}{\left(x^2+2x+2+c\right)^2}, \qquad r_{X,2}^{\prime}(x)=\frac{6+c}{2+c}\!\times\!\frac{2x^2+8x+4-2c}{\left(x^2+4x+6+c\right)^2}.\end{equation*}
By choosing  $c\in(0,2)$
we obtain
 $r_{X,1}$
that starts decreasing and eventually becomes increasing, while
 $r_{X,2}$
is increasing. That is, X is not
 ${1-}{\rm IFR}$
but is
 ${2-}{\rm IFR}$
. Moreover, it is also easy to verify that X is not
 ${1-}{\rm IFRA}$
.
Let us now look at the hereditary property for  $s{-}{\rm IFRA}$
monotonicity, to show that the situation is quite different from what happens with
 $s{-}{\rm IFR}$
monotonicity.
Proposition 3.1. Let  $Y_1$
and
 $Y_2$
be independent exponential random variables with mean 1 and
 $1/\lambda$
, respectively, where
 $\lambda\neq 1$
, and define
 $Y=\max(Y_1,Y_2)$
. Then Y is
 ${1-}{\rm IFRA}$
, but it is neither
 ${2-}{\rm IFRA}$
nor
 ${2-}{\rm DFRA}$
. Moreover, there exists
 $s_0>2$
such that Y is
 $s{-}{\rm DFR}$
for every
 $s\geq s_0$
.
Proof. Observe first that
 \begin{equation*}\overline{T}_{Y,s}(x)=\frac{1}{c(s,\lambda)}\left(e^{-x}+\frac{e^{-\lambda x}}{\lambda^{s-1}}-\frac{e^{-(\lambda+1) x}}{(\lambda+1)^{s-1}}\right),\end{equation*}
where
 \[c(s,\lambda)=1+\frac{1}{\lambda^{s-1}}-\frac{1}{(\lambda+1)^{s-1}}.\]
To prove that Y is  ${1-}{\rm IFRA}$
, we need to verify that
 \begin{equation*}-t_1(x)=\frac{\log(\overline{T}_{Y,1}(x))}{x}\end{equation*}
is decreasing. Taking into account Theorem 2.2, we need to prove that  $H(x)=e^{-x}+e^{-\lambda x}-e^{-(1+\lambda) x}-e^{-ax}$
changes sign at most once, in the order ‘
 $+,-$
’, for every
 $a>0$
(note that we are here interested in proving the function is decreasing, while Theorem 2.2 characterised increasingness). Moreover, note that, for every
 $x\geq 0$
,
 $\overline{T}_{Y,1}(x)\geq e^{-x}$
, so it is enough to consider
 $a<1$
. Hence the sign pattern of the coefficients means that, according to Theorem 2.5, H has at most two real roots. Moreover, we have that
 $\lim_{x\rightarrow+\infty}H(x)=0^-$
,
 $H(0)=0$
, and
 $H^\prime(0)=a>0$
, so it follows that the second root does exist and is positive; consequently the sign variation of H(x) is ‘
 $+,-$
’. Therefore, we have proved that Y is
 ${1-}{\rm IFRA}$
.
To prove the second statement, we verify that
 \begin{equation*}t_2(x)=\frac{-\log(\overline{T}_{Y,2}(x))}{x}\end{equation*}
is not monotone. Indeed, we have
 \begin{equation*}\lim_{x\rightarrow0}t_2(x)=\frac{1}{1+\frac{1}{\lambda}-\frac{1}{1+\lambda}}<1,\qquad\mbox{and}\qquad\lim_{x\rightarrow+\infty}t_2(x)=1.\end{equation*}
We verify now that the equation  $t_2(x)=1$
has one positive solution. Rewrite this as
 \begin{equation*}t_2(x)=1\quad\Leftrightarrow\quad P(x)=\left(\frac{1}{\lambda+1}-\frac{1}{\lambda}\right)e^{-x}+\frac{e^{-\lambda x}}{\lambda}-\frac{e^{-(1+\lambda)x}}{1+\lambda}=0.\end{equation*}
Again from Theorem 2.5, P has at most two real roots. As  $P(0)=0$
,
 $P^\prime(0)>\frac{1}{\lambda}-\frac{1}{\lambda+1}>0$
, and
 $\lim_{x\rightarrow+\infty} P(x)=0^-$
, there exists a strictly positive second root.
For the final statement, we want to prove the monotonicity of
 \begin{equation*}r_{Y,s}(x)=\frac{\overline{T}_{Y,s-1}(x)}{\widetilde{\mu}_{Y,s-1}\overline{T}_{Y,s}(x)},\end{equation*}
which coincides with the monotonicity of
 \begin{equation*}N(x)=\frac{e^{-x}+\frac{e^{-\lambda x}}{\lambda^{s-2}}-\frac{e^{-(\lambda+1) x}}{(\lambda+1)^{s-2}}}{e^{-x}+\frac{e^{-\lambda x}}{\lambda^{s-1}}-\frac{e^{-(\lambda+1) x}}{(\lambda+1)^{s-1}}}.\end{equation*}
We look at the numerator of  $N^\prime(x)$
, which after some algebraic manipulation may be written as
 \begin{equation*}Q(x)=-\frac{(\lambda-1)^2}{\lambda^{s-1}}e^{-(\lambda+1)x}+\frac{\lambda^2}{(\lambda+1)^{s-1}}e^{-(\lambda+2)x}+\frac{1}{(\lambda^2+\lambda)^{s-1}}e^{-(2\lambda+1)x}.\end{equation*}
Of course, the sign of  $N^\prime(x)$
coincides with the sign of Q(x). Notice that if
 $\lambda>1$
, we have
 $\lambda+1<\lambda+2<2\lambda+1$
, while the two last terms interchange when
 $\lambda<1$
. Hence it follows from Theorem 2.5 that Q has at most one real root. Moreover,
 $\lim_{x\rightarrow+\infty}Q(x)=0^-$
. Therefore, if
 $Q(0)>0$
the sign variation of Q in
 $(0,+\infty)$
is ‘
 $+,-$
’, and if
 $Q(0)<0$
the sign variation is ‘
 $-$
’. We have that
 \begin{equation*}Q(0)=\frac{\lambda^{s+1}+1-(\lambda-1)^2(1+\lambda)^{s-1}}{(\lambda^2+\lambda)^{s-1}},\end{equation*}
and this, as a function of s, will eventually become negative, as the numerator has a negative coefficient for  $\lambda^s$
, the largest power in that expression.
The following is an immediate consequence of Example 3.1 and Proposition 3.1.
Corollary 3.1. The  $s{-}{\rm IFRA}$
monotonicity does not have the hereditary property.
4. Simple failure rate monotonicity properties
This section presents simple properties of IFR or DFR distributions that are not of hereditary nature. We first highlight some improvements on classical moment bounds that may be derived from the iterated failure rate monotonicity.
Proposition 4.1. Let X be a random variable with distribution function  $F_X\in\mathcal{F}$
and density function
 $f_X$
, and let
 $s>3$
.
1. If X is
$s{-}{\rm IFR}$
, then
\begin{equation*}\left(1-\frac{1}{s-1}\right)\mathbb{E}(X-x)_+^{s-3}\mathbb{E}(X-x)_+^{s-1}\leq\left(\mathbb{E}(X-x)_+^{s-2}\right)^2\leq\mathbb{E}(X-x)_+^{s-3}\mathbb{E}(X-x)_+^{s-1}.\end{equation*}
2. If X is
$s{-}{\rm DFR}$
, then
\begin{equation*}\left(\mathbb{E}(X-x)_+^{s-2}\right)^2\leq\left(1-\frac{1}{s-1}\right)\mathbb{E}(X-x)_+^{s-3}\mathbb{E}(X-x)_+^{s-1}.\end{equation*}


Proof. A direct application of the Hölder inequality justifies the upper bound in the  $s{-}{\rm IFR}$
case. Both the lower bound in the
 $s{-}{\rm IFR}$
and the upper bound in the
 $s{-}{\rm DFR}$
case follow by requiring the appropriate sign in the numerator of
 $r_{X,s}^\prime$
and taking into account (2.4) and (2.5).
Remark 4.1. Note that the previous result, in the case of DFR distributions, provides a bound for the  $s-2$
moment of the residual life at age x that is sharper than what is given by the Hölder inequality. For the case of IFR distributions, Proposition 4.1 together with the Hölder inequality gives a sharp interval for the
 $s-2$
moment of the residual life at age x.
We now have a look at the iterated failure rate properties of parallel systems. The lifetime of such a system is expressed mathematically as the maximum of the lifetimes of each one of the components; this has already been used to provide an example illustrating the nonhereditary nature of IFRA monotonicity (see Proposition 3.1). We recall here a well-known property of the monotonicity of parallel systems and derive a few simple consequences.
Proposition 4.2. Let  $X_1,\ldots,X_n$
be independent and identically distributed
 ${1-}{\rm IFR}$
random variables, with distribution function
 $F\in\mathcal{F}$
and density function f. Then
 $X_{(n)}=\max(X_1,\ldots,X_n)$
is
 $s{-}{\rm IFR}$
, for every
 $s\geq 1$
.
Proof. Taking into account Lemma 3.1, it is enough to verify that  $X_{(n)}$
is
 ${1-}{\rm IFR}$
. Writing
 \[r_{X_{(n)},1}(x)=\frac{nF^{n-1}(x)}{1+F(x)+\cdots+F^{n-1}(x)}\frac{f(x)}{1-F(x)},\]
the conclusion is immediate.
Remark 4.2. Although the result presented above, i.e. the property that parallel systems of identical  ${1-}{\rm IFR}$
units are also
 ${1-}{\rm IFR}$
, is known (see for example [Reference Barlow and Proschan8]), we present its proof for the sake of completeness. Note that, to the best of our knowledge, this is a new approach for the proof of this particular property. An alternative proof for
 $n=2$
can be found in Example A.11 in Marshall and Olkin [Reference Marshall and Olkin30].
An easy consequence follows if we form the parallel system with components after a few iteration steps.
Corollary 4.1. Let X be an  $s{-}{\rm IFR}$
random variable, for some
 $s\geq1$
, with distribution function
 $F\in\mathcal{F}$
and density function f. Let
 $Y_{(n)} = \max(Y_1,\ldots,Y_n)$
, where the
 $Y_i$
are independent with tail function
 $\overline{T}_{X,s}(x)$
. Then
 $Y_{(n)}$
is
 $s{-}{\rm IFR}$
, for every
 $s\geq 1$
.
A related result was proved in Theorem 2.2 in Abouammoh and El-Neweihi [Reference Abouammoh and El-Neweihi1], which we quote here presented in a slightly more general wording.
Proposition 4.3. Let  $X_1,\ldots,X_n$
be independent and identically distributed
 $s{-}{\rm IFR}$
random variables, for some
 $s\geq 2$
, with distribution function
 $F\in\mathcal{F}$
. Let
 $Y_{(n)} = \max(Y_1,\ldots,Y_n)$
, where
 $Y_i$
are independent with tails
 $\overline{T}_{X,s-1}(x)$
. Then
 $Y_{(n)}$
is
 $s{-}{\rm IFR}$
.
The original statement by Abouammoh and El-Neweihi [Reference Abouammoh and El-Neweihi1] considers only the case where  $s=2$
. The above version follows immediately by the hereditary property of
 $s{-}{\rm IFR}$
monotonicity. Both results prove the iterated monotonicity of maxima based on distributions constructed after some iteration steps. The statement in Proposition 4.3 has a more straightforward practical interpretation.
5. Nonhereditary property of the
$s{-}{\rm IFR}$
ordering

We now have a look at hereditary properties of the  $s{-}{\rm IFR}$
ordering. We shall prove that, unlike what happens with
 $s{-}{\rm IFR}$
monotonicity, the ordering relation is not an hereditary property. For the discussion, we need to recall one more stochastic order relation (see Section 4.B.2 in Shaked and Shanthikumar [Reference Shaked and Shanthikumar40]).
Definition 5.1. Let X and Y be random variables with distribution functions  $F_X,F_Y\in\mathcal{F}$
. The random variable X is said to be more DMRL than Y, and we write
 $X\leq_{{\rm DMRL}}Y$
, if
 \begin{equation*}d(x)=\frac{\overline{T}_{Y,2}(\overline{T}_{Y,1}^{-1}(x))}{\overline{T}_{X,2}(\overline{T}_{X,1}^{-1}(x))}\end{equation*}
is decreasing.
The following relation with failure rate order holds.
Theorem 5.1. (Theorem 4.B.20 in Shaked and Shanthikumar [Reference Shaked and Shanthikumar40]) Let X and Y be random variables with distribution functions  $F_X,F_Y\in\mathcal{F}$
. If
 $X\leq_{{1-}{\rm IFR}}Y$
, then
 $X\leq_{{\rm DMRL}}Y$
.
Nanda et al. [Reference Nanda, Hazra, Al-Mutairi and Ghitany32] mention in their Remark 3.1, without proof, that the DMRL order is equivalent to the  ${2-}{\rm IFR}$
order. An immediate consequence of this remark is that if
 $X\leq_{{1-}{\rm IFR}}Y$
then
 $X\leq_{s{-}{\rm IFR}}Y$
for any
 $s\geq 2$
. Indeed, once it is proved that
 $X\leq_{{1-}{\rm IFR}}Y$
, Theorem 4.B.20 in Shaked and Shanthikumar [Reference Shaked and Shanthikumar40] implies that
 $X\leq_{{\rm DMRL}}Y$
; hence, according to the remark of Nanda et al. [Reference Nanda, Hazra, Al-Mutairi and Ghitany32],
 $X\leq_{{2-}{\rm IFR}}Y$
. If we define now
 $X^\ast_2$
with tail function
 $\overline{T}_{X,2}$
, and
 $Y^\ast_2$
with tail function
 $\overline{T}_{Y,2}$
, the previous order relation means that
 $X^\ast_2\leq_{{1-}{\rm IFR}}Y^\ast_2$
. Therefore, iterating once again, and applying Theorem 4.B.20 from Shaked and Shanthikumar [Reference Shaked and Shanthikumar40] and the above-mentioned remark, it follows that
 $X^\ast_2\leq_{{2-}{\rm IFR}}Y^\ast_2$
, which is just a rewriting of
 $X\leq_{{3-}{\rm IFR}}Y$
. Repeating the above construction, it would follow that
 $X\leq_{s{-}{\rm IFR}}Y$
for every
 $s\geq 1$
. However, the equivalence mentioned in Remark 3.1 of Nanda et al. [Reference Nanda, Hazra, Al-Mutairi and Ghitany32] is, in general, not true. We can prove the stated equivalence only when one of the random variables is exponentially distributed. The construction of a counterexample for the general result requires a very careful choice of distribution functions, as described below in Proposition 5.2.
Proposition 5.1. Let X be a random variable with distribution function  $F_X\in\mathcal{F}$
and Y a random variable with exponential distribution. Then
 $X\leq_{{2-}{\rm IFR}}Y$
if and only if
 $X\leq_{{\rm DMRL}}Y$
.
Proof. Taking into account the comments after Definition 2.4, it is enough to consider the case where Y has mean 1. Then we have that  $\overline{T}_{Y,1}(x)=\overline{T}_{Y,2}=e^{-x}$
. Therefore
 $X\leq_{{\rm DMRL}}Y$
is equivalent to
 \begin{equation*}d(x)=\frac{\overline{T}_{Y,2}(\overline{T}_{Y,1}^{-1}(x))}{\overline{T}_{X,2}(\overline{T}_{X,1}^{-1}(x))}=\frac{x}{\overline{T}_{X,2}(\overline{T}_{X,1}^{-1}(x))} \end{equation*}
being decreasing. On the other hand,  $X\leq_{{2-}{\rm IFR}}Y$
is equivalent to
 $c_2(x)=\overline{T}_{Y,2}^{-1}(\overline{T}_{X,2}(x))$
being convex, or, alternatively, to
 $c_2^\prime$
being increasing. Differentiating,
 \begin{equation*}c_2^\prime(x)=\frac{\overline{T}_{X,1}(x)}{\overline{T}_{Y,2}(\overline{T}_{Y,1}^{-1}(\overline{T}_{X,2}(x)))}=\frac{\overline{T}_{X,1}(x)}{\overline{T}_{X,2}(x)}.\end{equation*}
Hence  $X\leq_{{2-}{\rm IFR}}Y$
is equivalent to
 $c_2^\prime(\overline{T}_{X,1}^{-1}(x))=d(x)$
being decreasing, which proves the equivalence.
As an immediate consequence, we have the hereditary property of the  $s{-}{\rm IFR}$
order with respect to exponentially distributed random variables. This proves the remark of Nanda et al. [Reference Nanda, Hazra, Al-Mutairi and Ghitany32] for the particular choice of the exponential as the reference distribution.
Corollary 5.1. Let X be a random variable with distribution function  $F_X\in\mathcal{F}$
and Y a random variable with exponential distribution. If, for some
 $s\geq 1$
,
 $X\leq_{s{-}{\rm IFR}}Y$
, then
 $X\leq_{{(s+1)-}{\rm IFR}}Y$
.
However, the same hereditary property does not hold when comparing general random variables with respect to the  $s{-}{\rm IFR}$
ordering. That is, Remark 3.1 in Nanda et al [Reference Nanda, Hazra, Al-Mutairi and Ghitany32] is, in general, not true, as is proven in the proposition that follows.
Proposition 5.2. Neither the  ${1-}{\rm IFR}$
nor the DMRL order implies the
 ${2-}{\rm IFR}$
order.
Proof. Given  $c_1,c_2>0$
, we say that a random variable X has branched Pareto distribution with parameters
 $c_1,c_2$
,
 $X\sim{\rm BP}(c_1,c_2)$
, if its survival function is
 \begin{equation*}\overline{T}_{X,1}(x)=\frac{c_1^2}{(x+c_1)^2}{\mathbb{I}}_{[0,c_1]}(x)+\frac{(c_1+c_2)^2}{4(x+c_2)^2}{\mathbb{I}}_{(c_1,+\infty)}(x).\end{equation*}
Explicit expressions for the 2-iterated distribution and for the corresponding inverse functions are
 \begin{equation*}\begin{array}{l}\displaystyle\overline{T}_{X,2}(x)=\frac{4}{3c_1+c_2}\left(\frac{c_1^2}{x+c_1}+\frac{c_2-c_1}{4}\right){\mathbb{I}}_{[0,c_1]}(x)+\frac{(c_1+c_2)^2}{(3c_1+c_2)(x+c_2)}{\mathbb{I}}_{(c_1,+\infty)}(x), \\ \\\displaystyle\overline{T}_{X,1}^{-1}(x)=\left(\frac{c_1+c_2}{2\sqrt{x}}-c_2\right){\mathbb{I}}_{[0,\frac14]}(x)+ \left(\frac{c_1}{\sqrt{x}}-c_1\right){\mathbb{I}}_{(\frac14,+\infty)}(x), \\ \\\displaystyle\overline{T}_{X,2}^{-1}(x)=\left(\!\frac{(c_1+c_2)^2}{(3c_1+c_2)x}-c_2\!\right){\mathbb{I}}_{[0,\frac{c_1+c_2}{3c_1+c_2}]}(x)+\left(\!\frac{4c_1^2}{(3c_1+c_2)x-(c_2-c_1)}-c_1\!\right){\mathbb{I}}_{(\frac{c_1+c_2}{3c_1+c_2},+\infty)}(x).\end{array}\end{equation*}
Moreover,
 \begin{equation*}\overline{T}_{X,2}(\overline{T}_{X,1}^{-1})(x)=\frac{2(c_1+c_2)\sqrt{x}}{3c_1+c_2}{\mathbb{I}}_{[0,\frac{1}{4}]}(x)+\frac{4}{3c_1+c_2}\left( c_1\sqrt{x}+\frac{c_2-c_1}{4}\right){\mathbb{I}}_{(\frac{1}{4},+\infty)}(x),\end{equation*}
and
 \begin{equation*}\overline{T}_{X,1}(\overline{T}_{X,2}^{-1})(x)=\frac{(3c_1+c_2)^2}{4(c_1+c_2)^2} x^2{\mathbb{I}}_{[0,\frac{c_1+c_2}{3c_1+c_2}]}(x)+\frac{((3c_1+c_2)x-(c_2-c_1))^2}{16c_1^2}{\mathbb{I}}_{(\frac{c_1+c_2}{3c_1+c_2},+\infty)}(x).\end{equation*}
Choosing suitably the parameters  $c_1$
and
 $c_2$
, we obtain the counterexample. A possible choice is
 $X\sim{\rm BP}(5,10)$
and
 $Y\sim{\rm BP}(2,6)$
. For these parameters, we find
 \begin{equation*}d(x)=\frac{10}{9}{\mathbb{I}}_{[0,\frac14)}(x)+\frac{25\left( 2\sqrt{x}+1\right)}{12\left( 5\sqrt{x}+\frac{5}{4}\right)}{\mathbb{I}}_{[\frac14,+\infty)}(x),\end{equation*}
which is decreasing,
 \begin{equation*}c_2^\prime(x)=\frac{81}{100}{\mathbb{I}}_{[0,\frac35]}(x)+\frac{9x^2}{(5x-1)^2}{\mathbb{I}}_{(\frac35,\frac23]}(x)+\frac{4(3x-1)^2}{(5x-1)^2}{\mathbb{I}}_{(\frac23,1]}(x),\end{equation*}
which is not monotone, and
 \begin{equation*}c_1(x)=\overline{T}_{Y,1}^{-1}(\overline{T}_{X,1})(x)=\left(\frac{2(x+5)}{5}-2\right){\mathbb{I}}_{[0,5]}(x)+\left(\frac{8(x+10)}{15}-6\right){\mathbb{I}}_{(5,+\infty)}(x),\end{equation*}
which is convex.
6. A criterion for
$s{-}{\rm IFR}$
ordering and a first application

We have recalled (see Theorem 2.3) the criterion introduced by Arab and Oliveira [Reference Arab and Oliveira3] to establish the  $s{-}{\rm IFR}$
order between two different random variables, and we have mentioned, in Theorem 2.4, the straightforward extension to establish the
 $s{-}{\rm IFRA}$
order. The criterion introduced in Theorem 2.3 was used in Arab and Oliveira [Reference Arab and Oliveira3] to establish the iterated order within the families of gamma or Weibull distributions. The proofs given in Arab and Oliveira [Reference Arab and Oliveira3] required a careful analysis of the sign variation of
 \begin{equation*}P_s(x)=\log f_Y(x)-\log f_X(ax+b)+\log\frac{\mathbb{E} X^{s-1}}{a^{s}\mathbb{E} Y^{s-1}}\end{equation*}
(or of  $P_{s-1}$
, defined in Theorem 2.3). A close look at those proofs shows that the difficult cases to handle always correspond to
 $b<0$
, where a correct positioning of the roots is needed. So it would be quite useful if we could reduce the need to verify the criterion of Theorem 2.3 to only the case
 $a>0$
and
 $b\geq 0$
. We can obtain such a simplification with the help of the
 $s{-}{\rm IFRA}$
ordering.
Theorem 6.1. Let X and Y be random variables with distribution functions  $F_X,F_Y\in\mathcal{F}$
, respectively. If
 $X\leq_{s{-}{\rm IFRA}}Y$
and the criterion from Theorem 2.3 is verified for
 $b\geq0$
, then
 $X\leq_{s{-}{\rm IFR}}Y$
.
Proof. To prove that  $X\leq_{s{-}{\rm IFR}}Y$
, we need to verify that
 $c_s(x)=\overline{T}_{Y,s}^{-1}(\overline{T}_{X,s}(x))$
is convex, or, equivalently, that
 $\overline{T}_{X,s}^{-1}(\overline{T}_{Y,s}(x))$
is concave. Taking into account Theorem 20 in Arab and Oliveira [Reference Arab and Oliveira3], this is equivalent to verifying that
 $V(x)=\overline{T}_{X,s}^{-1}(\overline{T}_{Y,s}(x))-(ax+b)$
has, for every pair of real numbers a and b, at most the sign variation ‘
 $-,+,-$
’. The assumption
 $X\leq_{s{-}{\rm IFRA}}Y$
means that
 $\frac{c_s(x)}{x}$
is increasing, or, equivalently, that
 \begin{equation*}\frac{\overline{T}_{X,s}^{-1}(\overline{T}_{Y,s}(x))}{x}\end{equation*}
is decreasing. For  $x>0$
, the sign variation of V(x) is the same as the sign variation of
 \begin{equation*}\frac{V(x)}{x}=\left(\frac{\overline{T}_{X,s}^{-1}(\overline{T}_{Y,s}(x))}{x}-a\right)-\frac{b}{x}.\end{equation*}
The expression in the parentheses is decreasing, and for  $b<0$
,
 $\frac{b}{x}$
is increasing. Therefore
 $\frac{V(x)}{x}$
has at most one root, so the proof is concluded.
We may now prove a comparison result ordering two distributions, one from the Weibull family and the other from the gamma family.
Proposition 6.1. If  $\alpha>1$
, then
 ${\rm Weibull}(\alpha,\theta_1)\leq_{s{-}{\rm IFR}}\Gamma(\alpha,\theta_2)$
for every
 $s\geq 1$
.
Proof. Choose X with  ${\rm Weibull}(\alpha,1)$
distribution with density
 $f_X(x)=\alpha x^{\alpha-1}e^{-x^\alpha}$
, and Y with
 $\Gamma(\alpha,1)$
distribution with density
 $f_Y(x)=\frac{1}{\Gamma(\alpha)}x^{\alpha-1}e^{-x}$
. We are taking
 $\theta_1=\theta_2=1$
, as these are scale parameters, so their value does not affect the order relation between the random variables. We want to prove that
 $X\leq_{s{-}{\rm IFR}}Y$
. Put
 $V_s(x)=\overline{T}_{Y,s}(x)-\overline{T}_{X,s}(ax+b)$
. We will now analyse the sign variation of
 $V_s$
for
 $x\geq 0$
.
Step 1. The
$s{-}{\rm IFRA}$
ordering. In the definition of
$V_s$
, take
$b=0$
. Then we have
implying that
\begin{equation*}P_s(x)=-(\alpha-1)\log(a)-x+a^\alpha x^\alpha-\log(\alpha\Gamma(\alpha))+\log\frac{\mathbb{E} X^{s-1}}{a^s\mathbb{E} Y^{s-1}},\end{equation*}
$\lim_{x\rightarrow+\infty}P_s(x)=+\infty$
, and
$P_s^\prime(x)=-1+a^\alpha\alpha x^{\alpha-1}$
, so the sign variation of
$P_s^\prime$
is ‘
$-,+$
’, and the monotonicity of
$P_s$
is ‘
$\searrow\nearrow$
’. If
$P_s(0)<0$
, the sign variation of
$P_s$
is ‘
$-,+$
’, so, using Lemma 2.2, the sign variation of
$V_s$
is at most ‘
$-,+$
’. If
$P_s(0)\geq 0$
, the sign variation of
$P_s$
may be ‘
$+,-,+$
’. The function
$V_s$
is obtained by integrating the function
$H_s$
given in Theorem 2.3, so, again based on Lemma 2.2, and taking into account that
$V_s(0)=0$
, the sign variation of
$V_s$
is at most ‘
$-,+$
’. Therefore, we have proved that
$X\leq_{s{-}{\rm IFRA}}Y$
.Step 2. The
$s{-}{\rm IFR}$
ordering. We consider now
$V_s$
with
$a>0$
and
$b>0$
. Then we have
\begin{equation*}P_s(x)=(\alpha-1)\left(\log x-\log(ax+b)\right)-x+(ax+b)^\alpha-\log(\alpha\Gamma(\alpha))+\log\frac{\mathbb{E} X^{s-1}}{a^s\mathbb{E} Y^{s-1}}.\end{equation*}


It is obvious that  $\lim_{x\rightarrow+\infty}P_s(x)=+\infty$
. Differentiating, we have that
 \begin{equation*}P_s^\prime(x)=\frac{\alpha-1}{x}-\frac{a(\alpha-1)}{ax+b}-1+a\alpha(ax+b)^{\alpha-1}=\frac{N_s(x)}{x(ax+b)},\end{equation*}
where  $N_s(x)=a\alpha x(ax+b)^\alpha-ax^2-bx+b(\alpha-1)$
. Hence, as we will be considering x such that the denominator is positive, the sign of
 $P_s^\prime$
is determined by the sign of
 $N_s$
. Differentiating
 $N_s$
, we obtain
 $N_s^{\prime\prime\prime}(x)=a^3\alpha^2(\alpha-1)(ax+b)^{\alpha-3}\bigl(a(\alpha+1)x+3b\bigr)$
. Therefore,
 ${\rm sgn}(N_s^{\prime\prime\prime})={\rm sgn}\bigl(a(\alpha+1)x+3b\bigr)$
. As
 $a(\alpha+1)x+3b\geq 0$
, it follows that
 $N_s^{\prime\prime\prime}(x)\geq 0$
; hence
 $N_s^{\prime\prime}$
is increasing. We have that
 $\lim_{x\rightarrow+\infty}N_s^{\prime\prime}(x)=+\infty$
, and
 $N_s^{\prime\prime}(0)=2a(a\alpha^2b^{\alpha-1}-1)$
; this last quantity may be either positive or negative. Looking now at
 $N_s^\prime$
, we have
 $N_s^\prime(+\infty)=+\infty$
, and
 $N_s^\prime(0)=b(a\alpha b^{\alpha-1}-1)$
, which may be either positive or negative, irrespective of the sign of
 $N_s^{\prime\prime}$
at the origin. Finally, we have
 $N_s(0)=b(\alpha-1)>0$
and
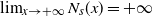 $\lim_{x\rightarrow+\infty}N_s(x)=+\infty$
. The table below summarises the maximum sign variation possibilities, taking into account the behaviour just described.

As  ${\rm sgn}(P_s^\prime)={\rm sgn}(N_s)$
, it follows that the possible monotonicities for
 $P_s$
are ‘
 $\nearrow$
’ or ‘
 $\nearrow\searrow\nearrow$
’. Going back to the expression for
 $P_s$
, we verify that
 $\lim_{x\rightarrow0^+}P_s(x)=-\infty$
and
 $\lim_{x\rightarrow+\infty}P_s(x)=+\infty$
; therefore the possible sign variations of
 $P_s$
are ‘
 $-,+$
’ or ‘
 $-,+,-,+$
’. Based again on Lemma 2.2, for the first case it follows that the possible sign variations for
 $V_s$
are ‘
 $-,+$
’ or ‘
 $+$
’, while in the second case, the possible sign variations for
 $V_s$
are ‘
 $-,+,-,+$
’, ‘
 $+,-,+$
’, ‘
 $-,+$
’, or ‘
 $+$
’. Taking into account that
 $V_s(0)=1-\overline{T}_{X,s}(b)\geq0$
, actually only the sign variations starting at positive values are possible; that is, the possibilities are ‘
 $+$
’ or ‘
 $+,-,+$
’, so the proof is concluded.
Remark 6.1. The proof of the comparison just described may be approached using Theorem 2.3, that is, the same methodology as in Arab and Oliveira [Reference Arab and Oliveira3]. In this case we would need to describe the sign variation also for the case  $b<0$
, and this can only be successfully completed assuming
 $\alpha>2$
, since we need to have a precise characterisation of the location of the roots of
 $V_s$
in order to derive the appropriate control of the sign variation of this function.
Using the criterion proved in Theorem 6.1, we may complete the comparison within the gamma or the Weibull families of distributions which was partially given in Propositions 30–33 in Arab and Oliveira [Reference Arab and Oliveira3]. We state here the complete result.
Theorem 6.2. Let  $\alpha^\prime>\alpha>0$
.
1. If
$X\sim\Gamma(\alpha^\prime,\theta_1)$
and
$Y\sim\Gamma(\alpha,\theta_2)$
then
$X\leq_{s{-}{\rm IFR}}Y$
.2. If
$X\sim{\rm Weibull}(\alpha^\prime,\theta_1)$
and
$Y\sim{\rm Weibull}(\alpha,\theta_2)$
then
$X\leq_{s{-}{\rm IFR}}Y$
.


Proof. Given Propositions 30–33 in Arab and Oliveira [Reference Arab and Oliveira3], we only need to consider the case where  $1>\alpha^\prime>\alpha>0$
. The result follows from repeating the steps for the proof of Proposition 6.1, with the arguments used in Propositions 30 and 32 in Arab and Oliveira [Reference Arab and Oliveira3].
Remark 6.2. The treatment of the case  $1>\alpha^\prime>\alpha>0$
was out of reach of the methodology used in [Reference Arab and Oliveira3], exactly because of the difficulty of handling the sign variation of the function
 $V_s$
when
 $b<0$
.
7. Failure rate ordering of exponentially distributed parallel systems
We now apply our results to prove extended ordering relations among parallel systems with components that have exponentially distributed lifetimes. We will be extending Theorem 3.1 by Kochar and Xu [Reference Kochar and Xu26], where these authors prove that a parallel system where the components have the same exponential distribution ages faster than a same-sized system where the components have exponential lifetimes with different mean values. We will be using the criterion introduced in Theorem 6.1 to extend, for general  $s\geq 1$
, this ageing characterisation of parallel systems proved by Kochar and Xu [Reference Kochar and Xu26].
Throughout this section we take
 \begin{align}\begin{array}{ll@{\qquad}l}X=\max(X_1,X_2),& \; & \text{where}\, X_1\, \text{and}\, X_2\, \text{are\, independent\, mean}\, 1\, \\ & & \text{exponentially\, distributed};\\Y=\max(Y_1,Y_2),& &{\text{where}\, Y_1\, \text{is\, mean\, 1\, exponentially\, distributed},\, Y_2\, \text{is}\,}\\ & & {\text{mean}\, 1/}\lambda < {1\, \text{exponentially\, distributed,\, and}\, Y_1,\, Y_2\,}\\ &&\text{are\, independent.}\end{array}\end{align}
The choice made for the mean values of the components’ lifetimes is not really essential, but makes our proofs easier to explain. The only important fact is that  $X_1$
and
 $X_2$
have the same mean. Indeed, taking into account the comments after Definition 2.4, we may always renormalise the variables to reduce to the present case. This section studies the
 $s-$
iterated failure rate order between X and Y. The main tool for the analysis is the result about roots of polynomials of exponentials recalled in Theorem 2.5.
As already mentioned in course of the proof of Proposition 3.1, it is easily verified that
 \begin{equation*}\overline{T}_{Y,s}(x)=\frac{1}{c(s,\lambda)}\left(e^{-x}+\frac{e^{-\lambda x}}{\lambda^{s-1}}-\frac{e^{-(\lambda+1) x}}{(\lambda+1)^{s-1}}\right),\end{equation*}
where
 \begin{equation*}c(s,\lambda)=1+\frac{1}{\lambda^{s-1}}-\frac{1}{(\lambda+1)^{s-1}}.\end{equation*}
The tail of the distribution of X is obtained by replacing  $\lambda$
by 1 in these expressions.
For sake of readability, we will present the various partial results leading to the comparison of X and Y in  $s{-}{\rm IFR}$
order in a series of propositions.
Proposition 7.1. Let X and Y be defined as in (7.1). For every  $s\geq 1$
and
 $x\geq 0$
, we have
 $\overline{T}_{X,s}(x)\geq\overline{T}_{Y,s}(x)$
.
Proof. Define
 \begin{align*}U_s(x)&=\overline{T}_{X,s}(x)-\overline{T}_{Y,s}(x) \\[3pt] & = \frac{2^s e^{-x}-e^{-2x}}{2^s-1}-\frac{1}{c(s,\lambda)}\left(e^{-x}+\frac{e^{-\lambda x}}{\lambda^{s-1}}-\frac{e^{-(\lambda+1) x}}{(\lambda+1)^{s-1}}\right) \\[3pt] &=\left(\frac{2^s}{2^s-1}-\frac{1}{c(s,\lambda)}\right)e^{-x}-\frac{e^{-2x}}{2^s-1} -\frac{e^{-\lambda x}}{c(s,\lambda)\lambda^{s-1}} +\frac{e^{-(\lambda+1)x}}{c(s,\lambda)(\lambda+1)^{s-1}}.\end{align*}
We are considering  $\lambda>1$
, so the signs of the coefficients of
 $U_s$
, after ordering decreasingly with respect to the exponents, are ‘
 $+,-,-,+$
’ (the signs of the coefficients of
 $e^{-\lambda x}$
and
 $e^{-2x}$
are the same, so we do not need to consider two cases). So, taking into account Theorem 2.5,
 $U_s$
has at most two real roots. One root is easily located, as
 $U_s(0)=0$
. Moreover, notice that
 $\lim_{x\rightarrow-\infty}U_s(x)=+\infty$
, the limit being governed by the sign of the coefficient of
 $e^{-x}$
, while
 $\lim_{x\rightarrow+\infty}U_s(x)=0^+$
, this limit being governed by the sign of the coefficient of the exponential with the smallest exponent. In order to locate the remaining root, we need to differentiate: for
 $k<s$
, we have
 \begin{equation*}U_s^{(k)}(x)=(-1)^k\left[\frac{2^s e^{-x}-2^ke^{-2x}}{2^s-1}-\frac{1}{c(s,\lambda)}\left(e^{-x}+\frac{e^{-\lambda x}}{\lambda^{s-1-k}}-\frac{e^{-(\lambda+1) x}}{(\lambda+1)^{s-1-k}}\right)\right],\end{equation*}
and
 \begin{equation*}U_s^{(s)}(x)=(-1)^s\left[\frac{2^s e^{-x}-2^se^{-2x}}{2^s-1}-\frac{1}{c(s,\lambda)}\left(e^{-x}+\lambda e^{-\lambda x}-(\lambda+1)e^{-(\lambda+1) x}\right)\right].\end{equation*}
Hence the signs of the coefficients of the exponentials alternate with each differentiation, and  $U_s^{(s)}(0)=0$
. It is now convenient to separate into two cases.
s even: The signs of the coefficients in
$U_s^{(s)}$
are ‘
$+,-,-,+$
’, implying that
$\lim_{x\rightarrow-\infty}U_s^{(s)}(x)=+\infty$
,
$\lim_{x\rightarrow+\infty}U_s^{(s)}(x)=0^+$
, and
$U_s^{(s)}$
has at most two real roots. As
$U_s^{(s)}(0)=0$
, depending on the location of the second root, the sign variation in
$(0,+\infty)$
of
$U_s^{(s)}$
may be either ‘
$+$
’ or ‘
$-,+$
’. The sign of
$U_s^{(s-1)}(0)$
is not determined, and the signs of the limits at
$\pm\infty$
are reversed with respect to
$U_s^{(s)}$
, so we need to consider the two possibilities leading to the following possible situations:


Therefore there are only two possible sign variations for
$U_s^{(s-1)}$
when
$x\in(0,+\infty)$
: ‘
$-$
’ or ‘
$+,-$
’. We may now proceed to characterise the possible sign variations in
$(0,+\infty)$
of
$U_s^{(s-2)}$
, repeating the above arguments. Again, notice that it is not possible to determine the sign of
$U_s^{(s-2)}(0)$
, so the possibilities are as follows:


We find for the sign variation in
$(0,+\infty)$
of
$U_s^{(s-2)}$
exactly the same behaviour as for
$U_s^{(s)}$
, so we may repeat the arguments above to find that
$U_s^\prime$
has the same sign variation in
$(0,+\infty)$
as
$U_s^{(s-1)}$
; that is, it is either ‘
$-$
’ or ‘
$+,-$
’. Going back to
$U_s$
, recall that
$\lim_{x\rightarrow-\infty}U_s(x)=+\infty$
,
$\lim_{x\rightarrow+\infty}U_s(x)=0^+$
, and
$U_s(0)=0$
. This behaviour does not allow for the case of
$U_s^\prime$
being always negative, so the sign variation of
$U_s^\prime$
is ‘
$+,-$
’, which implies that
$U_s(x)\geq 0$
for every
$x\geq 0$
.s odd: For this case, we have that the signs of the coefficients in
$U_s^{(s)}$
are ‘
$-,+,+,-$
’,
$\lim_{x\rightarrow-\infty}U_s^{(s)}(x)=-\infty$
,
$\lim_{x\rightarrow+\infty}U_s^{(s)}(x)=0^-$
,
$U_s^{(s)}(0)=0$
, and
$U_s^{(s)}$
has at most two real roots. Therefore the only possible sign variation in
$(0,+\infty)$
for
$U_s^{(s)}$
is ‘
$+,-$
’, which is what we found for the
$s-1$
derivative in the previous case. Hence, repeating the arguments, we find the same conclusion; that is, again,
$U_s(x)\geq 0$
for every
$x\geq 0$
.


Corollary 7.1. Let X and Y be defined as in (7.1). Then
 \begin{equation*}\frac{\overline{T}_{Y,s}^{-1}\overline{T}_{X,s}(x)}{x}\leq 1\end{equation*}
for every  $x>0$
.
Proof. We have just proved that  $\overline{T}_{X,s}(x)\geq\overline{T}_{Y,s}(x)$
, which, as
 $\overline{T}_{Y,s}$
is a decreasing function, implies that
 $\overline{T}_{Y,s}^{-1}\overline{T}_{X,s}(x)\leq x$
; hence the result is proved.
Proposition 7.2. Let X and Y be defined as in (7.1). For every  $s\geq 1$
,
 $X\leq_{s{-}{\rm IFRA}}Y$
.
Proof. We need to prove that
 \begin{equation*}t_s(x)=\frac{\overline{T}_{Y,s}^{-1}(\overline{T}_{X,s}(x))}{x} \end{equation*}
is increasing for  $x\geq 0$
, or, equivalently, that the sign variation in
 $(0,+\infty)$
of
 $t_s(x)-a$
is at most ‘
 $-,+$
’. The previous corollary means that we need only to consider
 $0<a\leq 1$
. This is still equivalent to proving that, for the described choice of a,
 $\overline{T}_{X,s}(x)-\overline{T}_{Y,s}(ax)$
behaves, at most, as ‘
 $+,-$
’. Reversing this expression, this is equivalent to proving that
 $V_s(x)=\overline{T}_{Y,s}(x)-\overline{T}_{X,s}(ax)$
behaves, at most, as ‘
 $-,+$
’, now for
 $a>1$
. This is the same formulation as in Theorem 2.2 with a reduced scope for the choice of a. To write the expression explicitly, we have
 \begin{equation*}V_s(x)=\frac{1}{c(s,\lambda)}\left(e^{-x}+\frac{e^{-\lambda x}}{\lambda^{s-1}}-\frac{e^{-(\lambda+1) x}}{(\lambda+1)^{s-1}}\right)-\frac{2^s e^{-ax}-e^{-2ax}}{2^s-1}.\end{equation*}
We will be using Theorem 2.5 to identify the maximum number the roots of  $V_s$
, then proceed in a similar way as before to locate them and infer the sign variation of the function. As in the proof of Proposition 7.1, we start by differentiating to obtain
 \begin{equation*}V_s^{(s)}(x)=(-1)^s\left[\frac{1}{c(s,\lambda)}\left(e^{-x}+\lambda e^{-\lambda x}-(\lambda+1)e^{-(\lambda+1) x}\right)-2^sa^s\frac{e^{-ax}-e^{-2ax}}{2^s-1}\right],\end{equation*}
so we have  $V_s^{(s)}(0)=0$
. To apply Theorem 2.5, we need to order decreasingly with respect to the exponents the exponential terms in
 $V_s$
, which means we need to separate into several cases, depending on the location of a with respect to
 $\lambda$
, and verify in each case that the sign variation of
 $V_s$
is at most ‘
 $-,+$
’. Recall that both these parameters are larger than or equal to 1.
Case 1:
$1<a<2a<\lambda<\lambda+1$
. As previously, we need to treat separately the cases where s is even and where s is odd.
s even: The sign pattern of the coefficients in
$V_s$
and in
$V_s^{(s)}$
is now ‘
$+,-,+,+,-$
’, indicating that each function has at most three real roots. Moreover, this sign pattern implies that
$\lim_{x\rightarrow-\infty}V_s^{(s)}(x)=-\infty$
,
$\lim_{x\rightarrow+\infty}V_s^{(s)}(x)=0^+$
, and
$V_s^{(s)}(0)=0$
. Therefore the maximum possible sign variation for
$V_s^{(s)}$
on
$(0,+\infty)$
is ‘
$+,-,+$
’. As before, the sign of
$V_s^{(s-1)}(0)$
is not determined, so we need to analyse each possibility. Recall that the coefficient signs and the signs at each limit when
$x\rightarrow\pm\infty$
are reversed with each differentiation, meaning that
$\lim_{x\rightarrow-\infty}V_s^{(s-1)}(x)=+\infty$
and
$\lim_{x\rightarrow+\infty}V_s^{(s-1)}(x)=0^-$
. Taking this into account, the possibilities are as follows:


To proceed to the analysis of
$V_s^{(s-2)}$
, notice first that the sign of this function at the origin is not determined, and that
$\lim_{x\rightarrow-\infty}V_s^{(s-2)}(x)=-\infty$
,
$\lim_{x\rightarrow+\infty}V_s^{(s-2)}(x)=0^+$
. Therefore the possible sign variations are as follows:


This means that the maximum possible sign variation for
$V_s^{(s-2)}$
is the same as for
$V_s^{(s)}$
; hence we may recurse on the argument to arrive at the conclusion that the maximum possible sign variation for
$V_s^\prime$
on
$(0,+\infty)$
is ‘
$-,+,-$
’. Taking into account that
$V_s(0)=0$
,
$\lim_{x\rightarrow-\infty}V_s(x)=-\infty$
,
$\lim_{x\rightarrow+\infty}V_s(x)=0^+$
, and
$V_s$
has at most three real roots, its sign variation in
$(0,+\infty)$
can be at most ‘
$-,+$
’.s odd: The sign pattern of the coefficients in
$V_s^{(s)}$
is now ‘
$-,+,-,-,+$
’, and
$\lim_{x\rightarrow-\infty}V_s^{(s)}(x)=+\infty$
,
$\lim_{x\rightarrow+\infty}V_s^{(s)}(x)=0^-$
, and
$V_s^{(s)}(0)=0$
. This means that the maximum possible sign variation for
$V_s^{(s)}$
on
$(0,+\infty)$
is now ‘
$-,+,-$
’, which corresponds to the behaviour of the
$s-1$
derivative in the previous case, so the same conclusion still holds.Therefore, for this case we have verified that the sign variation in
$(0,+\infty)$
of
$V_s$
is at most ‘
$-,+$
’.


Case 2:
$1<a<\lambda<2a<\lambda+1$
. The sign pattern of the coefficients coincides with the one observed in the previous case, so the result also holds in this case.Case 3:
$1<a<\lambda<\lambda+1<2a$
. The sign pattern of the coefficients of the function
$V_s$
is now ‘
$+,-,+,-,+$
’; hence there could exist up to four real roots. Of course, we still have
$V_s(0)=0$
, so we need to locate the remaining roots. Because of the number of possible roots, a direct application of the arguments in the previous cases with
$V_s$
does not allow us to draw conclusions about a sign variation compatible with
$s{-}{\rm IFRA}$
order. Note that in this case we have
$a>\frac{\lambda+1}{2}$
, so for every fixed
$x\geq 0$
,
$\overline{T}_{X,s}(ax)<\overline{T}_{X,s}(\frac{\lambda+1}{2}x)$
; therefore
$V_s(x)=\overline{T}_{Y,s}(x)-\overline{T}_{X,s}(ax)>V_{\ast,s}(x)=\overline{T}_{Y,s}(x)-\overline{T}_{X,s}(\frac{\lambda+1}{2}x)$
. We shall prove that
$V_{\ast,s}(x)\geq 0$
for
$x\geq0$
, so the same holds for
$V_s$
. Rewriting
$V_{\ast,s}$
, with the exponentials already ordered decreasingly with respect to their exponents, we have
The coefficient of the last exponential is easily seen to be positive, so the sign pattern of the coefficients in
\begin{align*}V_{\ast,s}(x)&=\frac{1}{c(s,\lambda)}e^{-x} -\frac{2^s}{2^s-1}e^{-\frac{(\lambda+1)}{2}x} +\frac{1}{c(s,\lambda)\lambda^{s-1}}e^{-\lambda x}\\ &\quad +\left(\frac{1}{2^s-1}-\frac{1}{c(s,\lambda)(\lambda+1)^{s-1}}\right)e^{-(\lambda+1)x}.\end{align*}
$V_{\ast,s}$
is ‘
$+,-,+,+$
’; hence, besides having
$V_{\ast,s}(0)=0$
, we have
$\lim_{x\rightarrow-\infty}V_{\ast,s}(x)=+\infty$
and
$\lim_{x\rightarrow+\infty}V_{\ast,s}(x)=0^+$
. Moreover, taking into account Theorem 2.5,
$V_{\ast,s}$
has at most two real roots. To complete the study of the sign variation we need, as before, to separate the cases based on the value of s.
s even. Repeating the arguments above, the sign pattern for the coefficients of
$V_{\ast,s}^{(s)}$
is the same as for
$V_{\ast,s}$
. Therefore we may repeat the arguments used in the course of the proof of Proposition 7.1 for the case where s is even, to derive that
$V_{\ast,s}(x)\geq 0$
; hence
$V_s(x)\geq 0$
for every
$x\geq 0$
.s odd. As in the proof of Proposition 7.1, this corresponds to the behaviour of the
$s-1$
derivative when s is even, so the result holds in this case.
Case 4:
$1<\lambda<a<2a<\lambda+1$
. The sign pattern of the coefficients, after ordering the exponentials, is ‘
$+,+,-,+,-$
’, meaning that there are at most three real roots. This is exactly the same sign pattern we found in Case 1 above. So, repeating the arguments from Case 1, the same sign variation for
$V_s$
follows.Case 5:
$1<\lambda<a<\lambda+1<2a$
. This is the simplest case to analyse. The sign pattern for the coefficients of
$V_s$
is ‘
$+,+,-,-,+$
’, implying that there are at most two real roots,
$\lim_{x\rightarrow-\infty}V_s(x)=+\infty$
, and
$\lim_{x\rightarrow+\infty}V_s(x)=0^+$
. This is easily seen to be compatible with two possible sign variations in
$(0,+\infty)$
: ‘
$-,+$
’ or ‘
$+$
’.Case 6:
$1<\lambda<\lambda+1<a<2a$
. This case produces the same sign pattern for the coefficients as Case 5, so the same conclusion about the sign variation of
$V_s$
follows.


Thus we have verified that in all possible cases, the sign variation of  $V_s$
is at most ‘
 $-,+$
’; hence, for
 $x\geq 0$
,
 $t_s(x)$
is increasing. The proposition is proved.
The previous result establishes the  $s{-}{\rm IFRA}$
order, so we may now proceed to the proof of the
 $s{-}{\rm IFR}$
relation between these two random variables.
Theorem 7.1. Let X and Y be defined as in (7.1). For every  $s\geq 1$
,
 $X\leq_{s{-}{\rm IFR}}Y$
.
Proof. The plan for the proof is the same as for Proposition 7.2. The difference here is that we will be interested in proving the convexity of the relevant functions and we will not be able to automatically locate one of their roots. Taking into account Theorem 2.2, Remark 2.2, and Theorem 6.1, it is sufficient to verify that  $V_s(x)=\overline{T}_{Y,s}(x)-\overline{T}_{X,s}(ax+b)$
changes sign at most twice, in the order ‘
 $+,-,+$
’, for every
 $a>0$
and
 $b\geq 0$
. The case
 $b=0$
was treated in Proposition 7.2, so we may assume in the sequel that
 $b>0$
. Although the function is similar to the one considered in Proposition 7.2, one should notice that now
 $V_s(0)=1-\overline{T}_{X,s}(b)>0$
. Of course, the sign patterns of the coefficients are similar, but we must take into account the extra terms
 $e^{-b}$
and
 $e^{-2b}$
.
We start by writing out explicitly the expressions for  $V_s$
and its s-order derivative
 $V_s^{(s)}$
:
 \begin{equation*}\begin{array}{l}\displaystyle V_s(x)=\frac{1}{c(s,\lambda)}\left(e^{-x}+\frac{e^{-\lambda x}}{\lambda^{s-1}}-\frac{e^{-(\lambda+1) x}}{(\lambda+1)^{s-1}}\right)-\frac{2^s e^{-(ax+b)}-e^{-2(ax+b)}}{2^s-1}, \\ \\\displaystyle V_s^{(s)}(x)=(-1)^s\left[\frac{1}{c(s,\lambda)}\left(e^{-x}+\lambda e^{-\lambda x}-(\lambda+1)e^{-(\lambda+1) x}\right)-2^sa^s\frac{e^{-(ax+b)}-e^{-2(ax+b)}}{2^s-1}\right].\end{array}\end{equation*}
Note that
 \begin{equation*}V_s^{(s)}(0)=\frac{(-1)^{s+1}2^s a^se^{-b}(1-e^{-b})}{2^s-1},\end{equation*}
which has the same sign as  $(-1)^{s+1}$
when
 $b>0$
.
Case 1:
$1<a<2a<\lambda<\lambda+1$
. The sign pattern of the coefficients, after ordering the exponentials in decreasing order of their exponents, is ‘
$+,-,+,+,-$
’, so
$V_s$
has at most three real roots. Moreover,
$\lim_{x\rightarrow-\infty}V_s(x)=-\infty$
and
$\lim_{x\rightarrow+\infty}V_s(x)=0^+$
, so, recalling that
$V_s(0)>0$
, it follows that the sign variation of
$V_s$
on
$(0,+\infty)$
is either ‘
$+$
’ or ‘
$+,-,+$
’.Case 2:
$1<a<\lambda<2a<\lambda+1$
. This case is treated exactly like the previous one.Case 3:
$1<a<\lambda<\lambda+1<2a$
. As before, this case requires a more careful analysis, as the number of possible roots is larger. The sign pattern of the coefficients of the function
$V_s$
is now ‘
$+,-,+,-,+$
’, so we may have up to four real roots for
$V_s$
, and
$\lim_{x\rightarrow-\infty}V_s(x)=+\infty$
,
$\lim_{x\rightarrow+\infty}V_s(x)=0^+$
. We again separate according to s being even or odd.
s even. In this case, we have
$V_s^{(s)}(0)<0$
, so the sign variation in
$(0,+\infty)$
of
$V_s^{(s)}$
is either ‘
$-,+,-,+$
’ or ‘
$-,+$
’. Now, taking into account that each differentiation step reverses all signs, and that, with the exception of the s-order derivative, the signs of the derivatives at the origin are not determined, we have the following possibilities for the sign variations:


Hence the maximum possible sign variation for
$V_s^{(s-2)}$
on
$(0,+\infty)$
is the same as for
$V_s^{(s)}$
, so we repeat the argument to obtain that the maximum possible sign variation for
$V_s^\prime$
on
$(0,+\infty)$
is ‘
$+,-,+,-$
’. Therefore the monotonicity of
$V_s$
is ‘
$\nearrow\searrow\nearrow\searrow$
’, which, recalling that
$V_s(0)>0$
, implies that the sign variation of
$V_s$
may be ‘
$+$
’ or ‘
$+,-,+$
’.s odd. Now we have
$V_s^{(s)}(0)>0$
, which, taking into account the signs for
$V_s^{(s)}$
at
$\pm\infty$
, implies a sign variation, on
$(0,+\infty)$
, of ‘
$+,-$
’ or ‘
$+,-,+,-$
’. That is, we find the same behaviour as for the
$s-1$
derivative in the previous case, so the same conclusion about the sign variation of
$V_s$
follows.


Case 4:
$1<\lambda<a<2a<\lambda+1$
. This case exhibits the same behaviour as Case 1 above, so the same conclusion holds.Case 5:
$1<\lambda<a<\lambda+1<2a$
. The sign pattern of the coefficients of
$V_s$
, after ordering the exponentials in the usual way, is ‘
$+,+,-,-,+$
’, implying that there are at most two real roots,
$\lim_{x\rightarrow-\infty}V_s(x)=+\infty$
, and
$\lim_{x\rightarrow+\infty}V_s(x)=0^+$
. As
$V_s(0)>0$
, the only possibilities for the sign variation for
$V_s$
on
$(0,+\infty)$
are ‘
$+$
’ and ‘
$+,-,+$
’.Case 6:
$1<\lambda<\lambda+1<a<2a$
. This case exhibits the same behaviour as the previous one.Case 7:
$0<a<1$
. In this case, regardless of the actual value of a, the sign pattern of the coefficients is ‘
$-,+,+,+,-$
’, so
$\lim_{x\rightarrow-\infty}V_s(x)=-\infty$
and
$\lim_{x\rightarrow+\infty}V_s(x)=0^-$
. As
$V_s(0)>0$
, the only possible sign variation on
$(0,+\infty)$
is ‘
$+,-$
’.


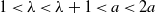


We have verified that, for all relevant choices of the parameters a and b, the assumptions of Theorem 2.2 are satisfied, so it follows that  $X\leq_{s{-}{\rm IFR}}Y$
.
Remark 7.1. Our Theorem 7.1 above partially extends Theorem 3.1 in Kochar and Xu [Reference Kochar and Xu26] to iterated failure rate ordering. The extension is only partial, as Theorem 7.1 deals only with maxima between two random variables, while Kochar and Xu’s result deals with arbitrary families of variables.
In the result that follows, we compare the ageing properties of a parallel system with n components with independent and identically distributed exponential lifetimes, to those of a parallel system with k components with independent and identically distributed exponential lifetimes, assuming that  $k<n$
.
Proposition 7.3. Let  $X_1,\ldots,X_m$
,
 $m\geq 3$
, be independent random variables with exponential distribution with mean
 $1/\lambda$
, and let
 $Y_1,\ldots,Y_k$
,
 $2\leq k<m$
, be independent exponential random variables with mean
 $1/\beta$
. If
 $X_{(m)}=\max(X_1,\ldots,X_m)$
and
 $Y_{(k)}=\max(Y_1,\ldots,Y_k)$
, then
 $X_{(m)}\leq_{{1-}{\rm IFR}}Y_{(k)}$
Proof. As the parameters  $\lambda$
and
 $\beta$
are scale parameters, we may take
 $\lambda=\beta=1$
. The random variables
 $X_m$
and
 $Y_k$
have the following tail distributions:
 $\overline{F}_m(x)=1-(1-e^{-x})^m$
,
 $\overline{F}_k(x)=1-(1-e^{-x})^k$
, respectively. The proposition follows from proving that
 $c_1(x)=\overline{F}^{-1}_k(\overline{F}_m)=-\log(1-(1-e^{-x})^{\frac{m}{k}})$
is convex. As
 $c_1(x)$
is differentiable, the convexity is characterised by the nonnegativeness of the second derivative. Computing derivatives, and taking into account that the sign of
 $c_1^{\prime\prime}$
is determined by the sign of its numerator, it can be seen that the sign of
 $c_1^{\prime\prime}$
is the same as the sign of
 \begin{equation*}Q(x)=\frac{m}{k}e^{-x}+(1-e^{-x})^{\frac{m}{k}}-1.\end{equation*}
This is positive for every  $x\geq 0$
and
 $2\leq k<m$
, so the conclusion follows.
As an immediate consequence, we have the following ordering for the order statistics.
Corollary 7.2. Let  $X_1,\ldots,X_n$
,
 $n\geq 3$
, be independent random variables with exponential distribution with mean
 $1/\lambda$
, and for each
 $k=2,\ldots,n$
, define
 $X_{(k)}=\max(X_1,\ldots,X_k)$
. Then
 $X_{(n)}\leq_{{1-}{\rm IFR}}X_{(n-1)}\leq_{{1-}{\rm IFR}}\cdots\leq_{{1-}{\rm IFR}}X_{(2)}$
.
Remark 7.2. Kochar and Xu [Reference Kochar and Xu26] mention an unsolved problem for which they announce having empirical evidence, although no mathematical proof could be obtained. This unsolved problem is stated as follows: let  $X_i$
be independent exponentially distributed variables with means
 $1/\lambda_i$
, and let
 $Y_i$
be independent exponentially distributed variables with means
 $1/\theta_i$
. If
 $(\lambda_1,\ldots,\lambda_n)\prec(\theta_1,\ldots,\theta_n)$
, in the sense of Definition A.1 in Marshal and Olkin [Reference Marshall and Olkin29], i.e.
 $\sum_{i=1}^k\lambda_{(i)}\geq\sum_{i=1}^k\theta_{(i)}$
for
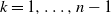 $k=1,\ldots,n-1$
, and
 $\sum_{i=1}^n\lambda_i=\sum_{i=1}^n\theta_i$
where
 $\lambda_{(1)}\leq \lambda_{(2)}\leq\cdots\leq\lambda_{(n)}$
, then one should expect
 $\max(X_1,\ldots,X_n)\leq_{{1-}{\rm IFR}}\max(Y_1,\ldots,Y_n)$
. For this particular conjecture, we have evidence that it is in general not true for iterated failure rate order as long as the iteration parameter s is greater than or equal to 2. We provide an example where this ordering does not hold. Let
 $X_1$
and
 $X_2$
be independent exponential random variables with means
 $1/\lambda_i$
,
 $i=1,2$
, and let
 $Y_1$
and
 $Y_2$
be independent exponential random variables with means
 $1/\theta_i$
,
 $i=1,2$
. Assume, without loss of generality, that
 $\lambda_1\leq \lambda_2$
and
 $\theta_1\leq\theta_2$
, and that
 $(\lambda_1,\lambda_2)\prec(\theta_1,\theta_2)$
(i.e.
 $\lambda_1+\lambda_2 = \theta_1+\theta_2$
and
 $\lambda_1\geq \theta_1$
). Write, for simplicity,
 $X=\max\{X_1,X_2\}$
and
 $Y=\max\{Y_1,Y_2\}$
, and consider
 $V_s(x)=\overline{T}_{Y,s}(x)-\overline{T}_{X,s}(ax)$
, where
 $a>0$
. If we choose the parameters
 $(s,\frac{\lambda_1}{\lambda_2},\frac{\theta_2}{\theta_1}, a) = (2,0.34,11,2.89)$
, the sign variation of
 $V_s(x)$
is ‘
 $-,+,-$
’, so, by Theorem 2.2, X and Y are not comparable with respect to the
 ${2-}{\rm IFRA}$
order; hence they cannot be comparable with respect to the
 ${2-}{\rm IFR}$
order. The particular choice of parameters made above gives rise to a family of possible choices for the vectors
 $(\lambda_1,\lambda_2)$
and
 $(\theta_1,\theta_2)$
leading to counterexamples. Indeed, taking into account the order relation
 $(\lambda_1,\lambda_2)\prec(\theta_1,\theta_2)$
, it follows that
 $(\lambda_1,\lambda_2,\theta_1,\theta_2)=\frac{1}{1474}(408,1200,134,1474)\vartheta$
, with
 $\vartheta>0$
, generates a whole family of counterexamples for the conjecture when the iteration parameter s is 2. Like Kochar and Xu, we cannot find a counterexample for the case
 $s=1$
, nor provide a proof for such a result.
Acknowledgements
This work was partially supported by the Centre for Mathematics of the University of Coimbra - UIDB/00324/2020, funded by the Portuguese Government through FCT/MCTES.
The authors express their gratitude to the anonymous referees and the associate editor for their careful reading and suggestions, which helped improve on an earlier version of this paper.


