

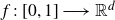


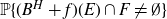


1. Introduction
Hitting probabilities describes the probability that a given stochastic process will ever reach some state or set of states F. To find upper and lower bounds for the hitting probabilities in terms of the Hausdorff measure and the capacity of the set F, is a fundamental problem in probabilistic potential theory. For d-dimensional Brownian motion B, the probability that a path will ever visit a given set
 $F\subseteq\mathbb{R}^{d}$
, is classically estimated using the Newtonian capacity of F. Kakutani [
Reference Kakutani16
] was the first to establish this result linking capacities and hitting probabilities for Brownian motion. He showed that, for all
 $x\in\mathbb{R}^{d}$
and compact set F
 \[\mathbb{P}_{x}\{B(0,\infty)\cap F\neq\emptyset\} \gt 0 \quad \Longleftrightarrow \quad \text{Cap}\left(F\right) \gt 0,\]
where Cap denotes the capacity associated to the Newtonian and logarithmic kernels (
 $\left|\cdot\right|^{2-d}$
, if
 $d\geq 3$
and
 $\left|\log\left(1/\cdot\right)\right|$
, if
 $d=2$
) respectively. The similar problem has been considered by Peres and Sousi [
Reference Peres and Sousi24
] for d-dimensional Brownian motion B with
 $d\geq2$
with a drift function f. They showed that for a
 $(1/2)$
-Hölder continuous function
 $f\,:\,\mathbb{R}^{+}\longrightarrow\mathbb{R}^{d}$
there is a positive constant
 $c_2$
such that for all
 $x\in\mathbb{R}^{d}$
and all closed set
 $F\subseteq\mathbb{R}^{d}$
 \begin{align}\mathsf{c}^{-1}_{1}\text{Cap}_{M}\left(F\right)\leq\mathbb{P}_{x}\{(B+f)(0,\infty)\cap F\neq\emptyset\}\leq \mathsf{c}_{1}\text{Cap}_{M}\left(F\right),\end{align}
where
 $\text{Cap}_{M}\left(\cdot\right)$
denotes the Martin capacity, see for example [
Reference Mörters and Peres23
]. At the heart of their method is the strong Markov property. It is noteworthy that since Kakutani’s characterisation, considerable efforts have been carried out to establish a series of extensions to other processes, on the one hand, and, secondly, for a restricted subset
 $E\subset (0,\infty)$
. This has given rise to a large and rapidly growing body of scientific literature on the subject. To cite a few examples, we refer to Xiao [
Reference Xiao28
] for developments on hitting probabilities of Gaussian random fields and fractional Brownian motion; to Pruitt and Taylor [
Reference Pruitt and Taylor26
] and Khoshnevisan [
Reference Khoshnevisan17
] for hitting probabilities results for general stable processes and Lévy processes; to Khoshnevisan and Shi [
Reference Khoshnevisan and Shi18
] for hitting probabilities of the Brownian sheet; to Dalang and Nualart [
Reference Dalang and Nualart6
] for hitting probabilities for the solution of a system of nonlinear hyperbolic stochastic partial differential equations; to Dalang, Khoshnevisan and Nualart [
Reference Dalang, Khoshnevisan and Nualart7
,
Reference Dalang, Khoshnevisan and Nualart8
], for hitting probabilities for the solution of a non-linear stochastic heat equation with additive and multiplicative noise respectively; to Xiao [
Reference Xiao29
] Biermé, Lacaux and Xiao [
Reference Biermé, Lacaux and Xiao1
] for hitting probabilities of anisotropic Gaussian random fields.
An important remark should be made, Kakutani’s characterisation is not common to all the processes and this is generally due to process dependency structures. Thus the lower and upper bounds on hitting probabilities are obtained respectively in terms of capacity and Hausdorff measure of the product set
 $E\times F$
. In this light, we cite Chen and Xiao result [
Reference Chen and Xiao4
] which is actually an improvement of results established by Xiao [
Reference Xiao29
, theorem 7·6] and by Biermé, Lacaux and Xiao [
Reference Biermé, Lacaux and Xiao1
, theorem 2·1] on hitting probabilities of the
 $\mathbb{R}^{d}$
-valued Gaussian random field X satisfying conditions
 $(C_{1})$
and
 $(C_{2})$
(see Xiao [
Reference Xiao29
] for precise definition) through the following estimates
 \begin{equation*}\mathsf{c}_2^{-1}\mathcal{C}^d_{\rho_{\mathbf{d}_X}}(E\times F)\leq\mathbb{P}\{X(E)\cap F\neq\emptyset\}\leq \mathsf{c}_2\mathcal{H}_{\rho_{\mathbf{d}_{X}}}^{d}(E\times F),\end{equation*}
where
 $E\subseteq[a,1]^{N}$
,
 $a\in(0,1)$
and
 $F\subseteq\mathbb{R}^{d}$
are Borel sets and
 $\mathsf{c}_2$
is a constant which depends on
 $[a,1]^{N}$
, F and H only.
 $\mathcal{C}^d_{\rho_{\mathbf{d}_{X}}}({\cdot})$
and
 $\mathcal{H}_{\rho_{\mathbf{d}_{X}}}^{d}({\cdot})$
denotes the Bessel–Riesz type capacity and the Hausdorff measure with respect to the metric
 $\rho_{{\mathbf{d}_{X}}}$
, defined on
 $\mathbb{R}_+\times\mathbb{R}^d$
by
 $\rho_{{\mathbf{d}_{X}}}\left((s,x),(t,y)\right)\,:\!=\,\max \left\{\mathrm{d}_X(s,t),\lVert x-y\rVert \right\}$
where
 $\mathrm{d}_X$
is the canonical metric of the Gaussian process X. Both of these terms are defined in the sequel. We emphasise that fractional Brownian motion belongs to the class of processes that satisfy the conditions
 $(C_{1})$
and
 $(C_{2})$
. See Xiao [
Reference Xiao29
] for information on the conditions
 $(C_{1})$
and
 $(C_{2})$
.
The similar issue for a multifractional Brownian motion
 $B^{H({\cdot})}$
governed by a Hurst function
 $H({\cdot})$
and drifted by a function f with the same Hölder exponent function
 $H({\cdot})$
was investigated by Chen [
Reference Chen5
, theorem 2·6]. The hitting probabilities estimates upper and lower were given in terms of
 $\mathcal{H}^d_{\rho_{\mathrm{d}_{\underline{H}}}}(E\times F)$
and
 $\mathcal{C}_{\rho_{\mathrm{d}_{\overline{H}}}}^d(E\times F)$
respectively. The metrics
 $\mathrm{d}_{\underline{H}}$
and
 $\mathrm{d}_{\overline{H}}$
are defined by
 $|t-s|^{\underline{H}}$
and
 $|t-s|^{\overline{H}}$
respectively, where
 $\underline{H}$
and
 $\overline{H}$
are the extreme values of the Hurst function
 $H({\cdot})$
. Consequently, for the fractional Brownian
 $B^H$
of Hurst parameter H (H is now time-independent), Chen’s result can be formulated as follows
 \begin{align}\mathsf{c}_3^{-1}\,\mathcal{C}^d_{\rho_{\mathbf{d}_{H}}}(E\times F)\leq\mathbb{P}\{(B^H+f)(E)\cap F\neq\emptyset\}\leq \mathsf{c}_3\mathcal{H}_{\rho_{\mathbf{d}_{H}}}^{d}(E\times F),\end{align}
for any H-Hölder continuous drift f. What we notice in both above-mentioned results (1·1) and (1·2) is that the drift f has H as the Hölder exponent which is out of reach for fractional Brownian paths. This brings us to consider the sensitivity problem of the above estimates with respect to the Hölder exponent of the drift. More precisely, could we obtain the same results when the drift f is
 $(H-\varepsilon)$
-Hölder continuous for any
 $\varepsilon \gt 0$
small enough?
Our first objective in this work is to give an answer to this issue. First of all, we seek to provide some general results on Hausdorff measures and capacities that will be relevant to reaching our main goal. Precisely, we established some upper bounds for the Hausdorff measure (resp. lower bounds for the Bessel–Riesz capacity) of the product set
 $E\times F$
by means of a suitable Hausdorff measure (resp. Bessel–Riesz capacity) of one of the component sets E and F in a general metric space. If either E or F is “reasonably regular” in the sense of having equal Hausdorff and Minkowski dimensions, the bounds become as sharp as possible. This constitutes the content of Section 2.
As a consequence, we obtain practical and appropriate bound estimates of hitting probabilities for fractional Brownian motion with H-Hölder continuous drift
 $B^H+f$
involving only Hausdorff measure (for upper bound) and Bessel–Riesz capacity (for lower bound) of E or F, which we believe are of independent interest. All of this and related details make up the content of Section 3.
Given Sections 2 and 3, in Section 4 we address the sensitivity question posed above and the answer is negative. The idea is to look for drifts, linked with potential theory, that are Hölder continuous without reaching the Hölder regularity of order H. To be more specific, we seek drifts with a modulus of continuity of the form
 $\mathsf{w}(x)= x^H\,\ell(x)$
, where
 $\ell$
is a slowly varying function at zero in the sens of Karamata satisfying
 $\underset{x\rightarrow 0}{\limsup}\,\ell(x)=+\infty$
, and having close ties to hitting probabilities. The potential candidates that best match the requested features are the paths of Gaussian processes with covariance function satisfying
 \begin{align*} \mathbb{E}\left(B^{\delta_{\theta_H}}_0(t)-B^{\delta_{\theta_H}}_0(s)\right)^2=\delta_{\theta_H}^2(|t-s|) \quad\text{ for all $t,s\in [0,1]$},\end{align*}
for some regularly varying function function
 $\delta_{\theta_H}(r)\,:\!=\, r^H\, \ell_{\theta_H}(r)$
such that its slowly varying part
 $\ell_{\delta_{\theta_H}}$
satisfies
 $\underset{r\rightarrow 0}{\limsup}\,\ell(r)=+\infty$
. Indeed, on the one hand the paths of such Gaussian processes are continuous with an almost sure uniform modulus of continuity given by
 $\delta_{\theta_H}(r)\log^{1/2}(1/r)$
up to a deterministic constant and, most of all, we are going to take advantage of the hitting estimates already established for such processes on the other. Based on a result due to Taylor [
Reference Taylor27
] on the relationship between Hausdorff measure and capacity and using the estimates established in Section 2, we construct two sets E and F and a drift f, chosen amongst the candidates listed above, for which the inequalities in (1·2) are not satisfied.
From this follows another question which will be dealt with in Section 5: what about the hitting probabilities for general measurable drift?
In view of the lack of information about the roughness of the drift f it is difficult to carry out upper and lower bounds on hitting probabilities even for regular sets E and F. We were only able to tackle the issue of hitting probabilities when F is a single point, for a thorough explanation see Remark 5·4. The idea is to use information provided by the graph
 $Gr_E(f)=\{(t,f(t)) \,:\, t\in E\}$
of f over the Borel set E in order to investigate the hitting probabilities. We establish, for a general measurable drift, upper and lower bounds on hitting probabilities of the type
 \begin{align}\mathsf{c}_4^{-1}\mathcal{C}^{d}_{\rho_{\mathbf{d}_{H}}}(Gr_E(f))\leq \mathbb{P}\left\lbrace \exists t\in E \,:\, (B^H+f)(t)=x\right\rbrace\leq \mathsf{c}_4\, \mathcal{H}_{\rho_{\mathbf{d}_{H}}}^{d}(Gr_E(f)).\end{align}
In connection with our previous work [
Reference Erraoui and Hakiki9
] on whether the image
 $(B^H + f) (E)$
has a positive Lebesgue measure
 $\lambda_d(B^H + f)(E)$
we have relaxed, thanks to the estimation above, the main assumption
 $\dim_{\rho_{\mathbf{d}_{H}}}(Gr_E(f)) \gt d$
in [
Reference Erraoui and Hakiki9
, theorem 3·2]. Indeed, we show that the weaker condition
 $\mathcal{C}_{\rho_{\mathbf{d}_{H}}}^{d}(Gr_E(f)) \gt 0$
is sufficient to provide
 $\lambda_d\left(B^H+f\right)(E) \gt 0$
with positive probability.
The study of the polarity of points for processes with drift f began in the 1980s with the seminal work of Graversen [
Reference Graversen12
] on planar Brownian motion B. In his paper, Graversen showed that for any
 $\beta \lt 1/2$
there exists a
 $\beta$
-Hölder continuous function f such that
 $ B + f $
hits points. This result was later sharpened by Le Gall [
Reference Le Gall19
] who proved that points are polar for
 $B+f$
when f is
 $1/2$
-Hölder continuous. Mountford generalised these results to one-dimensional stable processes
 $X_{\alpha}$
,
 $\alpha \in (0,2)$
. Specifically, for
 $\alpha \gt 1$
he showed that
 $X_{\alpha}+f$
hits points for any Borel function f, and for
 $\alpha \lt 1$
for any continuous function the range of
 $ X_{\alpha} + f $
is almost surely of positive Lebesgue measure. Subsequently, Evans [
Reference Evans10
] strengthened Mountford’s second result by proving that for Lévy processes whose paths are almost surely real-valued jump functions, the negligible set is independent of f.
Section 6 is devoted to stress the link between the Hausdorff dimension
 $\dim(E)$
of E and the polarity of points for
 $(B^H+f)\vert_E$
(the restriction of
 $B^H+f$
to the subset
 $E\subset (0,\infty)$
). This will be done through the above estimates (1·2) (with F a single point) and (1·3) as we explain in more detail below. First when f is H-Hölder continuous the above estimates (1·3) take the following form
 \begin{align}\mathsf{c}_5^{-1}\, \mathcal{C}^{Hd}(E)\leq \mathbb{P}\left\lbrace \exists t\in E \,:\, (B^H+f)(t)=x\right\rbrace\leq \mathsf{c}_5\, \mathcal{H}^{Hd}(E).\end{align}
Hence the first conclusion that we can draw is: if
 $\dim(E) \gt Hd$
then
 $(B^H+f)\vert_E$
hits points, and if
 $\dim(E) \lt Hd$
then
 $(B^H+f)\vert_E$
doesn’t hit points, i.e. points are polar for
 $(B^H+f)\vert_E$
. It is thus obvious that
 $\dim(E)=Hd$
is the critical dimension case. We show that this case is undecidable, in the sense that we construct two Borel sets
 $E_1,E_2\subset [0,1]$
such that
 $\dim(E_1)=\dim(E_2)=Hd$
for which
 $\left(B^H+f\right)\lvert_{E_1}$
hits points but
 $\left(B^H+f\right)\lvert_{E_2}$
doesn’t. This suggest that the roughness provided by the H-Hölder continuity of the drift f is insufficient to allow
 $(B^{H}+f)\lvert_E$
to hits points for general set E in the critical dimension case and as foreseeable question: could this be done by adding little more roughness? The idea is to take advantage of the lower bound of the hitting probabilities in (1·3) by looking for drifts for which
 $\mathcal{C}^{d}_{\rho_{\mathbf{d}_{H}}}(Gr_E(f)) \gt 0$
even for the critical case
 $\dim(E)=Hd$
. Again, as before, we use independent Gaussian process of type
 $B^{\delta_{\theta_H}}$
to construct drifts with slightly more roughness than that provided by H-Hölder continuity and for which the last condition must be satisfied. With an appropriate choice of ingredients, especially the kernel defining the capacity with respect to the potential theory associated to
 $B^{\delta_{\theta_H}}$
, to satisfy the assumptions of Taylor’s result [
Reference Taylor27
] we construct drifts f, that are
 $(H-\varepsilon)$
-Hölder continuous for all small
 $\varepsilon \gt 0$
without reaching order H, and allowing
 $(B^H+f)\lvert_E$
to hit points. We can safely say that the same method can be used in the case
 $\dim(E) \lt Hd$
. Namely, we can construct a drift
 $f\,:\,[0,1]\rightarrow \mathbb{R}^d$
which is
 $(\alpha-\varepsilon)$
-Hölder continuous for all small
 $\varepsilon \gt 0$
, with
 $\alpha\,:\!=\,\dim(E)/d \lt H$
, such that
 $(B^H+f)\vert_E$
hits points.
Now we introduce some useful notations throughout the paper.
 $|.| $
denotes the usual metric on
 $\mathbb{R}_+$
and
 $\lVert \cdot \rVert$
is the Euclidean norm on
 $\mathbb{R}^d$
. For functions f,g,
 $f\asymp g$
means that there exists a constant
 $\mathsf{c}\geq 1$
such that
 $\mathsf{c}^{-1}g({\cdot})\leq f({\cdot})\leq \mathsf{c}\,g({\cdot})$
.
2. Preliminaries on Hausdorff measures and capacities
In this section, we would like to consider some comparison results that are intended to provide upper bound for the Hausdorff measure (resp. lower bound of the Bessel–Riesz capacity) of a product set
 $G_1\times G_2$
in terms of the Hausdorff measures (resp. in terms of capacity) of each of the component
 $G_1$
and
 $G_2$
with appropriate orders. Such results might be useful in studying the problem of hitting probabilities for
 $B^H+f$
. First of all, we need to recall definitions of Hausdorff measures as well as Bessel–Riesz capacities in a general metric space.
Let
 $(\mathscr{X},\rho)$
be a bounded metric space,
 $\beta \gt 0$
and
 $G \subset {\mathscr{X}}$
. We define the
 $\beta$
-dimensional Hausdorff measure of G with respect to the metric
 $\rho$
as
 \begin{align} {}\mathcal{H}_{\rho}^{\beta}(G)=\lim_{\delta \rightarrow 0}\inf \left\{\sum_{n=1}^{\infty}\left(2 r_{n}\right)^{\beta}\,:\, G \subseteq \bigcup_{n=1}^{\infty} B_{\rho}\left(r_{n}\right), r_{n} \leqslant \delta\right\}, {}\end{align}
where
 $B_{\rho}(r)$
denotes an open ball of radius r in the metric space
 $({\mathscr{X}},\rho)$
. The Hausdorff dimension of G in the metric space
 $(X,\rho)$
is defined to be
 \begin{align}\dim_{\rho}(G)=\inf\{\beta \gt 0\,:\, \mathcal{H}_{\rho}^{\beta}(G)=0\}\, \text{ for all $G\subset {\mathscr{X}}$}.\end{align}
The usual
 $\beta$
-dimensional Hausdorff measure and the Hausdorff dimension in Euclidean metric are denoted by
 $\mathcal{H}^{\beta}$
and
 $\dim({\cdot})$
, respectively. Moreover,
 $\mathcal{H}^{\beta}$
is assumed equal to 1 whenever
 $\beta\leq 0$
.
We introduce now the Minkowski dimension of
 $E\subset ({\mathscr{X}},\rho)$
. Let
 $N_{\rho}(E,r)$
be covering number, that is the smallest number of open balls of radius r required to cover E. The lower and upper Minkowski dimensions of E are respectively defined as
 \begin{equation*} {}\begin{aligned} {}&\underline{\dim}_{\rho,M}(E)\,:\!=\, \liminf_{r\rightarrow 0^+}\frac{\log N_{\rho}(E,r)}{\log(1/r)},\\ {}&\overline{\dim}_{\rho,M}(E)\,:\!=\, \limsup_{r\rightarrow 0^+}\frac{\log N_{\rho}(E,r)}{\log(1/r)}. {}\end{aligned} {}\end{equation*}
Equivalently, the upper Minkowski dimension of E can be characterised by
 \begin{align} {}\overline{\dim}_{\rho,M}(E)=\inf\{\gamma \,:\, \exists\, C\in \mathbb{R}_+\, \text{ such that } N_{\rho}(E,r)\leqslant Cr^{-\gamma} \text{ for all } r \gt 0 \}. {}\end{align}
In the Euclidean case, the upper Minkowski dimension will be denoted by
 $\overline{\dim}_{M}$
.
Let
 $\varphi_{\alpha}\,:\,(0,\infty)\rightarrow (0,\infty)$
be the function given by
 \begin{align} {}\varphi_{\alpha}(r)=\left\{\begin{array}{ll}{r^{-\alpha}} & {\text { if } \alpha \gt 0,} \\ {\log \left(\frac{e}{r \wedge 1}\right)} & {\text { if } \alpha=0,} \\ {1} & {\text { if } \alpha \lt 0.}\end{array}\right. {} {}\end{align}
The Bessel–Riesz type capacity of order
 $\alpha$
on the metric space
 $({\mathscr{X}},\rho)$
is defined by
 \begin{align} {}\mathcal{C}_{\rho}^{\alpha}(G)=\left[\inf _{\mu \in \mathcal{P}(G)} \int_{\mathscr{X}} \int_{\mathscr{X}} \varphi_{\alpha}(\rho(u,v)) \mu(d u) \mu(d v)\right]^{-1}, {}\end{align}
where
 $\mathcal{P}(G)$
is the family of probability measures carried by G.
We note that for
 $\alpha \lt 0$
we have
 $\mathcal{C}_{\rho}^{\alpha }(G)=1$
for any nonempty G. The usual Bessel–Riesz capacity of order
 $\alpha$
in the Euclidean metric will be denoted by
 $\mathcal{C}^{\alpha}$
.
Now let
 $\left({\mathscr{X}_i},\rho_i\right)$
 $i=1,2$
be two metric spaces. Let
 $\rho_3$
be the metric on
 $\mathscr{X}_1\times \mathscr{X}_2$
given by
 $$ {} \rho_3\left((u,x),(v,y)\right)=\max\{\rho_1(u,v),\rho_2(x,y)\}.$$
The following proposition if the main result of this section.
Proposition 2·1. Let
 $\alpha \gt 0$
and
 $G_i \subset \mathscr{X}_i$
,
 $i=1,2$
.
-
(i) If
 $G_1$
supports a probability measure
$\mu$
that satisfies (2·6)for some positive constants
\begin{align} {} {}\mu\left(B_{\rho_1}\left(a,r\right)\right)\leq \unicode{x1D588}_{1}\,r^{\gamma} \,\, \ for\ all\ a\ \in G_1,\ and\ all\quad 0 \lt r \leq diam(G_1),\end{align}
$\unicode{x1D588}_{1}$
and
$\gamma$
, then there exists a constant
$\unicode{x1D588}_{2} \gt 0$
such that (2·7)
\begin{align} \mathcal{C}_{\rho_2}^{\alpha-\gamma}(G_{2})\leq \unicode{x1D588}_{2}\,\mathcal{C}_{\rho_3}^{\alpha}(G_1\times G_2). {} {}\end{align}
-
(ii) If there exist constants
$\gamma^{\prime} \lt \alpha$
and
$ \unicode{x1D588}_3 \gt 0$
such that (2·8)
\begin{align}N_{\rho_1}(G_1,r)\leq \unicode{x1D588}_3\, r^{-\gamma^{\prime}} \ for\ all \, \quad 0 \lt r \leq diam(G_1),\end{align}


then we have
 \begin{align} \mathcal{H}_{\rho_3}^{\alpha}(G_1\times G_2)\leq\, \unicode{x1D588}_{4} \mathcal{H}_{\rho_2}^{\alpha-\gamma^{\prime}}(G_2),\end{align}
for some constant
 $\unicode{x1D588}_4 \gt 0$
.
Similar estimates hold true if we assume that
 $G_2$
verifies assumptions (i) and (ii). That is there exist positive constants
 $\unicode{x1D588}_{5}$
and
 $\unicode{x1D588}_{6}$
such that
 \begin{align} \mathcal{C}_{\rho_1}^{\alpha-\gamma}(G_{1})\leq \unicode{x1D588}_{5}\,\mathcal{C}_{\rho_3}^{\alpha}(G_1\times G_2), {}\\[-12pt] \nonumber {}\end{align}
 \begin{align} \mathcal{H}_{\rho_3}^{\alpha}(G_1\times G_2)\leq\, \unicode{x1D588}_{6} \mathcal{H}_{\rho_1}^{\alpha-\gamma^{\prime}}(G_1).\end{align}
Remark 2·2.
-
1. By the mass distribution principle, we get from assertion (i). that
$\dim_{\rho_1}(G_1)\geq \gamma$
. -
2. Using the characterisation of the upper Minkowski dimension (2·3) we obtain from assertion (ii). that
$ \overline{\dim}_{\rho_1,M}(G_1)\leq \gamma^{\prime}$
and
$\mathcal{H}_{\rho_1}^{\gamma^{\prime}}(G_1) \lt \infty$
. Hence by the Frostman’s energy method [
Reference Bishop and Peres3
, theorem 6·4·6 p.173] we immediately have
$\mathcal{C}_{\rho_1}^{\gamma^{\prime}}(G_1)=0$
.
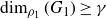


The following lemma will help us to establish (2·7) (resp. (2·10)).
Lemma 2·3. Let
 $(\mathscr{X},\rho)$
be a bounded metric space and
 $\mu$
a probability measure supported on
 $\mathscr{X}$
satisfying
 \begin{align} \mu\left(B_{\rho}(u,r)\right) \leq C_1 r^{\kappa} \quad \text{ for all $\,u\in \mathscr{X}$ and $\,r \gt 0$,}\end{align}
for some positive constants
 $C_1$
and
 $\kappa$
. Then for any
 $\theta \gt 0$
, there exists
 $C_2 \gt 0$
such that
 \begin{align} I(r)\,:\!=\,\sup_{v \in \mathscr{X}}\int_{\mathscr{X}}\frac{\mu(du)}{\left(\max\{\rho(u,v),r\}\right)^{\theta}}\leq C_2\, \varphi_{\theta-\kappa}(r),\end{align}
for all
 $r\in (0,\mathrm{diam}(\mathscr{X}))$
.
Proof of Proposition
2·1. We start by proving (i). Let us suppose that
 $\mathcal{C}_{\rho_2}^{\alpha-\gamma}(G_2) \gt 0$
, otherwise there is nothing to prove. It follows that for
 $\eta \in (0,\mathcal{C}_{\rho_2}^{\alpha-\gamma}(G_2))$
there is a probability measure m supported on
 $G_2$
such that
 \begin{align}\mathcal{E}_{\rho_2,\alpha-\gamma}(m)\,:\!=\,\int_{G_2}\int_{G_2}\varphi_{\alpha-\gamma}(\rho_2(x,y))\,m(dx)m(dy)\leq \eta^{-1}.\end{align}
Since
 $\mu \otimes m$
is a probability measure on
 $G_1 \times G_2$
, then applying Fubini’s theorem and Lemma 2·3 we obtain
 \begin{align}\begin{aligned} \mathcal{E}_{\rho_3,\alpha}(\mu \otimes m)&= \int_{G_1\times G_2} \int_{G_1\times G_2} \frac{\mu\otimes m(dudx) \mu\otimes m(dvdy)}{(\rho_3\left((u,x),(v,y)\right))^{\alpha}}\\ &\leq C_2\int_{G_2}\int_{G_2}\varphi_{\alpha-\gamma}(\rho_2(x,y))\,m(dx)m(dy)\leq C_2\,\eta^{-1}.\end{aligned}\end{align}
Consequently we have
 $\mathcal{C}_{\rho_3}^{\alpha}(G_1\times G_2)\geq C_2^{-1}\,\eta$
. Then we let
 $\eta\uparrow\mathcal{C}_{\rho_2}^{\alpha-\gamma}(G_2)$
to conclude that the inequality in (2·7) holds true.
Now let us prove (ii). Let
 $\zeta \gt \mathcal{H}_{\rho_2}^{\alpha-\gamma^{\prime}}(G_2)$
be arbitrary. Then there is a covering of
 $G_2$
by open balls
 $B_{\rho_2}(x_{n},r_n)$
of radius
 $r_n$
such that
 \begin{align}G_2 \subset \bigcup_{n=1}^{\infty} B_{\rho_2}(x_{n},r_{n}) \quad \text { and } \quad \sum_{n=1}^{\infty} (2r_{n})^{\alpha-\gamma^{\prime}} \leq \zeta. {}\end{align}
For all
 $n\geq 1$
, let
 $B_{\rho_1}(u_{n,j},r_n)$
,
 $j=1,...,N_{\rho_1}(G_1,r_n)$
be a family of open balls covering
 $G_1$
. It follows that the family
 $B_{\rho_1}(u_{n,j},r_n)\times B_{\rho_2}(x_{n},r_n),\,j=1,...,N_{\rho_1}(G_1,r_n)$
,
 $n \geq 1$
gives a covering of
 $G_1\times G_2$
by open balls of radius
 $r_n$
for the metric
 $\rho_3$
.
It follows from (2·8) and (2·16) that
 \begin{align} {} {}\sum_{n=1}^{\infty} \sum_{j=1}^{N_{\rho_1}(G_1, r_n)}\left(2 r_{n}\right)^{\alpha} \leq \unicode{x1D588}_{3}\,2^{\gamma^{\prime}}\, \sum_{n=1}^{\infty} (2r_{n})^{\alpha-\gamma^{\prime}} \leq \unicode{x1D588}_{3}\,\,2^{\gamma^{\prime}}\, \zeta. {} {}\end{align}
Letting
 $\zeta\downarrow\mathcal{H}_{\rho_2}^{\alpha-\gamma^{\prime}}(G_2)$
, the inequality in (2·9) follows with
 $\unicode{x1D588}_{4}=\unicode{x1D588}_{3}\,\,2^{\gamma^{\prime}}$
.
In the following we give a sufficient condition ensuring hypotheses (i) and (ii) of Proposition 2·1.
Proposition 2·4. The following condition
 $$ 0 \lt \gamma \lt \dim_{\rho_1}(G_1)\leq \overline{\dim}_{\rho_1,M}(G_1) \lt \gamma^{\prime} \lt \alpha,$$
Proof. (i) (resp. (ii)) is a direct consequence of Frostman’s Theorem (resp. the characterisation (2·3))
It is well known that Hausdorff and Minkowski dimensions agree for many Borel sets E. Often this is linked on the one hand to the geometric properties of the set, on the other hand it is a consequence of the existence of a sufficiently regular measure. Among the best known are Ahlfors–David regular sets defined as follows.
Definition 2·5. Let
 $(\mathscr{X},\rho)$
be a bounded metric space,
 $\gamma \gt 0$
and
 $G\subset \mathscr{X}$
. We say that G is
 $\gamma$
-Ahlfors–David regular if there exists a finite positive Borel measure
 $\mu$
supported on G and positive constant
 $\unicode{x1D588}_{\gamma}$
such that
 \begin{align} {} {}\unicode{x1D588}_{\gamma}^{-1}\,r^{\gamma}\leq\mu\left(B_{\rho}\left(a,r\right)\right)\leq\unicode{x1D588}_{\gamma}\,r^{\gamma}\,\,\ \text{for all a}\ \in G,\ \text{and all} \, \quad 0 \lt r \leq1.\end{align}
For a Borel set
 $E\subset \mathbb{R}^n$
satisfying the condition (2·18) with
 $\rho$
is the euclidean metric of
 $\mathbb{R}^n$
, it is shown in [
Reference Mattila21
, theorem 5·7, p.80] that
 $$ \gamma=\dim(E)=\underline{\dim}_M(E)=\overline{\dim}_M(E).$$
This statement still true in a general metric space
 $(\mathscr{X},\rho)$
, it suffices to go through the same lines of the proof of the euclidean case. Here we provide some examples of such sets.
Examples 2·1
-
(i) If E is the whole interval I then the condition (2·18) is satisfied with
$\gamma=1$
. This leads to the conclusion that the measure
$\mu$
can be chosen as the normalized Lebesgue measure on I. -
(ii) The Cantor set
$C(\lambda)$
,
$0 \lt \lambda \lt 1/2$
, subset of I with
$\mu$
is the
$\gamma$
-dimensional Hausdorff measure restricted to
$C(\lambda)$
, where
$\gamma=\dim C(\lambda)=\log(2)/\log(1/\lambda)$
. For more details see [
Reference Mattila21
, theorem 4·14 p.67]. In general, self similar subsets of
$\mathbb{R}$
satisfying the open set condition are standard examples of Ahlfors–David regular sets, see [
Reference Hutchinson14
].


The following proposition states that when
 $G_1$
(resp.
 $G_2$
) is
 $\gamma_1$
-Ahlfors–David regular set (resp.
 $\gamma_2$
-Ahlfors–David regular set), then inequalities (2·7) and (2·9) of Proposition 2·1 are checked for
 $\gamma=\gamma^{\prime}=\gamma_1$
(resp. for
 $\gamma=\gamma^{\prime}=\gamma_2$
).
Proposition 2·6. Let
 $\alpha \gt 0$
, and assume that
 $G_1$
is
 $\gamma_1$
-Ahlfors–David regular set.
-
(i) If
$\gamma_1\leq \alpha$
then (2·19)
\begin{align} \mathcal{C}_{\rho_2}^{\alpha-\gamma_1}(G_{2})\leq \unicode{x1D588}_{7}\,\mathcal{C}_{\rho_3}^{\alpha}(G_1\times G_2). \end{align}
-
(ii) If
$\gamma_1 \lt \alpha$
then(2·20)
\begin{align} \mathcal{H}_{\rho_3}^{\alpha}(G_1\times G_2)\leq\, \unicode{x1D588}_{8} \mathcal{H}_{\rho_2}^{\alpha-\gamma_1}(G_2).\end{align}


Similar estimates hold true under the assumption
 $G_2$
is
 $\gamma_2$
-Ahlfors–David regular set. Precisely we have
 \begin{align} \mathcal{C}_{\rho_1}^{\alpha-\gamma_2}(G_{1})\leq \unicode{x1D588}_{9}\,\mathcal{C}_{\rho_3}^{\alpha}(G_1\times G_2), \end{align}
 \begin{align} \mathcal{H}_{\rho_3}^{\alpha}(G_1\times G_2)\leq\, \unicode{x1D588}_{10} \mathcal{H}_{\rho_1}^{\alpha-\gamma_2}(G_1).\end{align}
Proof. In order to prove (2·19) and (2·20) it is sufficient to check that conditions (2·6) and (2·8) are satisfied with
 $\gamma=\gamma^{\prime}=\gamma_1$
. Firstly, (2·6) is no other than the right inequality in (2·18). On the other hand, let
 $0 \lt r\leq 1$
and
 $P_{\rho_1}(G_1,r)$
be the packing number, that is the greatest number of disjoint balls
 $B_{\rho_1}(x_j,r)$
with
 $x_{j}\in G_1$
. The left inequality of (2·18) ensures that
 $$ \unicode{x1D588}_{\gamma_1}^{-1}\, P_{\rho_1}(G_1,r)\, r^{\gamma_1}\leq \sum_{j=1}^{P_{\rho_1}(G_1,r)}\mu\left(B_{\rho_1}(x_j,r)\right)=\mu (G_1)\leq 1.$$
Using the well-known fact that
 $N_{\rho_1}(G_1,2\,r)\leq P_{\rho_1}(G_1,r)$
, we obtain the desired estimation (2·8).
Remark 2·7. Notice that when both
 $G_i$
,
 $i=1,2$
are
 $\gamma_i$
-Ahlfors David regular sets for some constant
 $\gamma_i \gt 0$
, then there exist two positive constants
 $\unicode{x1D588}_{11}$
and
 $\unicode{x1D588}_{12}$
such that
 \begin{align} & \mathcal{C}_{\rho_3}^{\gamma_1+\gamma_2}(G_1\times G_2)\geq \unicode{x1D588}_{11}\,\mathcal{C}_{\rho_2}^{\gamma_2}(G_{2})\vee \mathcal{C}_{\rho_1}^{\gamma_1}(G_{1}) \nonumber \\ & \quad \text{ and }\quad \mathcal{H}_{\rho_3}^{\gamma_1+\gamma_2}(G_1\times G_2)\leq \unicode{x1D588}_{12}\,\mathcal{H}_{\rho_2}^{\gamma_2}(G_{2})\wedge \mathcal{H}_{\rho_1}^{\gamma_1}(G_{1}).\end{align}
3. Hitting probabilities for fractional Brownian motion with deterministic regular drift
Let
 $H \in (0,1)$
and
 $B^{H}_0=\left\lbrace B^{H}_0(t),t \geq 0\right\rbrace $
be a real-valued fractional Brownian motion of Hurst index H defined on a complete probability space
 $(\Omega,\mathcal{F},\mathbb{P})$
, i.e. a real valued Gaussian process with stationary increments and covariance function given by
 $$ \mathbb{E}(B^{H}_0(s)B^{H}_0(t))=\frac{1}{2}(|t|^{2H}+|s|^{2H}-|t-s|^{2H}).$$
Let
 $B^{H}_1,...,B^{H}_d$
be d independent copies of
 $B^{H}_0$
. The stochastic process
 $B^{H}=\left\lbrace B^{H}(t),t\geq 0\right\rbrace $
given by
 \[ {}B^{H}(t)=(B^{H}_1(t),....,B^{H}_d(t)), {}\]
is called a d-dimensional fractional Brownian motion of Hurst index
 $H \in (0,1)$
.
For
 $\mathbf{d}$
a metric on
 $\mathbb{R}_+$
, we define on
 $\mathbb{R}_+\times\mathbb{R}^d$
the metric
 $\rho_{\mathbf{d}}$
as follows
 \begin{align}\rho_{\mathbf{d}}((s,x),(t,y))=\max\{\mathbf{d}\left(t,s\right),\|x-y\|\}\quad \forall (s,x), (t,y)\in \mathbb{R}_+\times\mathbb{R}^d.\end{align}
We denote by
 $\mathbf{d}_{H}$
the canonical metric of
 $B^H$
given by
 \begin{align} \mathbf{d}_{H}(s,t)\,:\!=\,|t-s|^H \, \quad \text{for all } s,t \in \mathbb{R}_+.\end{align}
The associated metric
 $\rho_{\mathbf{d}_{H}}$
on
 $\mathbb{R}_+\times \mathbb{R}^d$
is called the parabolic metric.
Let
 ${\mathbf{I}} = [a, b]$
, where
 $a \lt b \in (0,1]$
are fixed constants. For
 $\alpha\in (0,1)$
,
 $C^{\alpha}(\mathbf{I})$
is the space of
 $\alpha$
-Hölder continuous function
 $f \,:\, [a,b] \longrightarrow \mathbb{R}^d $
equipped with the norm
 \begin{align} {} {}\lVert f \rVert_{\alpha}\,:\!=\, \sup_{s\in \mathbf{I}} \lVert f(s) \rVert +\underset{\substack{s, t \in \mathbf{I} \\ s \neq t}}{\sup}\dfrac{\lVert f(t)-f(s) \rVert}{|t-s|^{\alpha}} \lt +\infty. {}\end{align}
First we state the following result, which is easily deduced from [ Reference Chen5 , theorem 2·6].
Theorem 3·1. Let
 $\{B^H(t), t\in [0,1]\}$
be a d-dimensional fractional Brownian motion and
 $f \in C^{H}\left(\mathbf{I}\right)$
. Let
 $F\subseteq \mathbb{R}^d$
and
 $E\subset \mathbf{I}$
are two compact subsets. Then there exist a constant
 $c\geq 1$
depending on
 $\mathbf{I}$
, F, H and f only, such that
 \begin{align}c^{-1}\mathcal{C}_{\rho_{\mathbf{d}_{H}}}^{d}(E\times F)\leq \mathbb{P}\{(B^H+f)(E)\cap F\neq \emptyset \}\leq c\,\,\mathcal{H}_{\rho_{\mathbf{d}_{H}}}^{d}(E\times F).\end{align}
The aim of this section is to provide the hitting probabilities estimates for some particular sets E and F. Such estimates would be helpful in the next section to establish a kind of of sharpness of the H-Hölder regularity of the drift f in Theorem 3·1.
3.1. Hitting probabilities estimates when E is
$\beta$
-Ahlfors–David regular set

First let us recall that, when E is an interval, [
Reference Chen and Xiao4
, corollary 2·2] ensures that there exists a constant
 $ \mathsf{c}\geq 1$
depending only on E, F and H such that
 $$ \mathsf{c}^{-1}\,\mathcal{C}^{d-1/H}(F)\leq \mathbb{P}\left\{ B^H(E)\cap F\neq \emptyset \right\}\leq \mathsf{c} \,\mathcal{H}^{d-1/H}(F),$$
for any Borel set
 $F\subseteq \mathbb{R}^d$
. Our next goal is to establish similar estimates for
 $(B^H+f)$
when E be a
 $\beta$
-Ahlfors–David regular set.
Proposition 3·2. Let
 $B^H$
, f, E and F as in Theorem 3·1 with
 ${E\subset \left(\mathbf{I},|.| \right)} $
is a
 $\beta$
-Ahlfors–David regular for some
 $\beta\in (0,1]$
. Then there is a positive constant
 $\mathtt{c}_{2}$
which depends on E, F, H,
 $K_f$
and
 $\beta$
, such that
 \begin{align} {} {}\mathtt{c}_{2}^{-1}\, \mathcal{C}^{d-\beta/H}(F)\leq \mathbb{P}\{(B^H+f)(E)\cap F\neq \emptyset \}\leq \mathtt{c}_{2}\,\mathcal{H}^{d-\beta/H}(F). {} {}\end{align}
Proof. Three cases are to be discussed here: (j)
 $\beta \lt Hd$
, (jj)
 $\beta =Hd$
and (jjj)
 $\beta \gt Hd$
. Let us point out first that for the lower bound, the interesting cases are (j) and (jj) while for the upper bound it is the case (j) which requires proof. Using Proposition 2·6 with
 $X_1=E$
,
 $\rho_1(s,t)=|t-s|^H$
,
 $X_2=\mathbb{R}^d$
,
 $\rho_2(x,y)=\|x-y\|$
, and
 $\alpha=d$
, we get the first case (j). For the case (jj) we only use Proposition 2·6 (i).
Following the same pattern as above we get the following corollary.
Corollary 3·3. Let
 $B^H$
, E and F as in Proposition 3·2. Then there is a positive constant
 $\mathtt{c}_{3}$
which depends on E, F, H and
 $\beta$
, such that
 \begin{align}\mathtt{c}_{3}^{-1}\, \mathcal{C}^{d-\beta/H}(F)\leq \mathbb{P}\{B^H(E)\cap F\neq \emptyset \}\leq {} {}\mathtt{c}_{3}\,\mathcal{H}^{d-\beta/H}(F).\end{align}
Remark 3·4.
-
(i) We note that [ Reference Chen and Xiao4 , corollary 2·2] corresponds to the particular case
$E=\mathbf{I}$
for which
$\beta=1$
. -
(ii) For less regular set E, with
$0 \lt \beta \lt \dim(E)\leq \overline{\dim}_M(E) \lt \beta^{\prime} \lt Hd$
, we can derive, as a consequence of (2·7) and (2·9) of Proposition 2·1, Proposition 2·4 and Theorem 3·1, the following weaker estimates (3·7)where
\begin{align} {} {}\mathtt{c}_1^{-1}\,\mathcal{C}^{d-\beta/H}(F)\leq \mathbb{P}\{(B^H+f)(E)\cap F\neq \emptyset \}\leq \mathtt{c}_1\,\mathcal{H}^{d-\beta^{\prime}/H}(F), {} {}\end{align}
$\mathtt{c}_{1}$
is a positive constant depends only on E, F, H,
$\mathrm{K}_f$
,
$\beta$
and
$\beta^{\prime}$
.


3.2. Hitting probabilities estimates when F is
$\gamma$
-Ahlfors–David regular

Now we get parallel results to those given in Proposition 3·2, emphasizing regularity properties of F instead of E. If
 ${F\subset \left( \mathbb{R}^d,\lVert \cdot \rVert\right) } $
is a
 $\gamma$
-Ahlfors–David regular, we have the following result, which could be proven similarly to Proposition 3·2 by making use of (2·21) and (2·22).
Proposition 3·5. Let
 $B^H$
, f, E and F as in Theorem 3·1, such that F is a
 $\gamma$
-Ahlfors–David regular compact subset of
 $[-M,M]^d$
for some
 $\gamma \in (0,d]$
. Then there is a positive constant
 $\mathtt{c}_{5}$
which depends on E, F, H,
 $\mathrm{K}_f$
and
 $\gamma$
only, such that
 \begin{align}\mathtt{c}_{5}^{-1}\, \mathcal{C}^{H(d-\gamma)}(E)\leq \mathbb{P}\{(B^H+f)(E)\cap F\neq \emptyset \}\leq \mathtt{c}_{5}\,\mathcal{H}^{H(d-\gamma)}(E).\end{align}
Corollary 3·6 Let
 $B^H$
, E and F as in Proposition 3·5. Then there is a positive and constant
 $\mathtt{c}_{6}$
which depends on E, F, H and
 $\gamma$
, such that
 \begin{align}\mathtt{c}_{6}^{-1}\, \mathcal{C}^{H(d-\gamma)}(E)\leq \mathbb{P}\{B^H(E)\cap F\neq \emptyset \}\leq {} {}\mathtt{c}_{6}\,\mathcal{H}^{H(d-\gamma)}(E).\end{align}
Remark 3·7. Similarly to Remark 3·4-(ii), for less regular set F, with
 $0 \lt \gamma \lt \dim(F)\leq \overline{\dim}_M(F) \lt \gamma^{\prime} \lt d$
, we have
 \begin{align}\mathtt{c}_{4}^{-1}\, \mathcal{C}^{H(d-\gamma)}(E)\leq \mathbb{P}\{(B^H+f)(E)\cap F\neq \emptyset \}\leq \mathtt{c}_{4}\,\mathcal{H}^{H(d-\gamma^{\prime})}(E),\end{align}
where
 $\mathtt{c}_{4}$
is a positive constant which depends on E, F, H,
 $\mathrm{K}_f$
,
 $\gamma$
and
 $\gamma^{\prime}$
.
4. Sharpness of the Hölder regularity of the drift:
This subsection brings to light the essential role of the H-Hölder regularity assumed on the drift f in the following sense: the result of Theorem 3·1 fails to hold when the deterministic drift f has a modulus of continuity
 $\mathsf{w}({\cdot})$
satisfying
 $$ r^H=o\left(\mathsf{w}(r)\right) \,\,\text{and}\,\, \mathsf{w}(r)=o\left(r^{H-\iota}\right) \,\,\text{when}\,\, r\rightarrow 0 \,\,\text{for all}\,\, \iota\in (0,H).$$
In this respect, we have to introduce some tools allowing us to reach our target.
Let
 $\mathscr{L}$
be the class of all continuous functions
 $\mathsf{w}\,:\,[0, 1] \rightarrow(0, \infty)$
,
 $\mathsf{w}(0)=0$
, which are increasing on some interval
 $(0, r_0]$
with
 $r_0 = r_0(\mathsf{w})\in (0,1)$
. Let
 $\mathsf{w}\in \mathscr{L}$
be fixed. A continuous function f is said to belong to the space
 $C^{\mathsf{w}}(\mathbf{I})$
if and only if
 $$ \sup _{\substack{s, t \in \mathbf{I} \\ s \neq t}} \frac{|f(s)-f(t)|}{\mathsf{w}(|s-t|)} \lt \infty .$$
It is obvious that the space
 $C^{\mathsf{w}}(\mathbf{I})$
is a Banach space with the norm
 $$ \|f\|_{\mathsf{w}}=\sup_{s \in \mathbf{I}}|f(s)|+\sup _{\substack{s, t \in \mathbf{I} \\ s \neq t}} \frac{|f(s)-f(t)|}{\mathsf{w}(|s-t|)}.$$
For
 $\alpha\in (0,1)$
and
 $\mathsf{w}(t)=t^\alpha$
,
 $\,C^{\mathsf{w}}(\mathbf{I})$
is nothing but the usual space
 $C^{\alpha}(\mathbf{I})$
.
Let
 $x_0\in(0,1]$
and
 $l\,:\,(0, x_0]\rightarrow \mathbb{R}_+$
be a slowly varying function at zero in the sens of Karamata (cf. [
Reference Bingham, Goldie and Teugels2
]). It is well known that l has the representation
 \begin{align} l(x)=\exp\left(\eta(x) + \int_{x}^{x_0}\frac{\varepsilon(t)}{t}dt\right), \end{align}
where
 $\eta,\varepsilon \,:\, [0,x_0)\rightarrow \mathbb{R}$
are Borel measurable and bounded functions such that
 $$ \lim_{x\rightarrow 0}\eta(x)=\eta_0\in (0,\infty) \quad \text{ and } \quad \lim_{x\rightarrow 0}\varepsilon(x)=0. $$
An interesting property of slowly varying functions which gives some intuitive meaning to the notion of “slow variation” is that for any
 $\tau \gt 0$
we have
 \begin{align} {} {}x^{\tau}\, l(x) \rightarrow 0 \quad \text{ and } x^{-\tau}\,l(x)\rightarrow \infty \quad \text{ as } x\rightarrow 0. \end{align}
It is known from Theorem 1·3·3 and Proposition 1·3·4 in [
Reference Bingham, Goldie and Teugels2
] and the ensuing discussion that there exists a function
 $\mathcal{C}^{\infty}$
near zero
 $\tilde{l}\,:\,(0,x_0]\rightarrow {\mathbb{R}}_+$
such that
 $l(x)\thicksim \tilde{l}(x)$
when
 $x\rightarrow 0$
, and
 $\tilde{l}({\cdot})$
has the following form
 \begin{align} \tilde{l}(x)=\mathsf{c}\,\exp\left( \int_{x}^{x_0}\frac{\tilde{\varepsilon}(t)}{t}dt\right), \end{align}
for some positive constant
 $\mathsf{c}$
and
 $\tilde{\varepsilon}(x) \rightarrow 0$
. Such function is called normalized slowly varying function (Kohlbecker 1958), and in this case
 \begin{align} \tilde{\varepsilon}(x)=-x\, \tilde{\ell}^{\prime}(x)/\tilde{\ell}(x) \quad \text{for all } \,x\in (0,x_0). \end{align}
A function
 $\mathsf{v}_{\alpha,{\ell}}\,:\,[0, x_0]\rightarrow \mathbb{R}_+$
is called regularly varying function at zero with index
 $\alpha \in (0,1)$
if and only if there exists a slowly varying function
 ${\ell}$
, called the slowly varying part of
 $\mathsf{v}_{\alpha,\ell}$
, such that
 \begin{align} \mathsf{v}_{\alpha,{\ell}}(0)=0 \quad \text{ and } \quad \mathsf{v}_{\alpha,{\ell}}(x)=x^{\alpha}\,{\ell}(x),\quad x\in (0,x_0). \end{align}
 $\mathsf{v}_{\alpha,\ell}$
is called a normalised regularly varying if its slowly varying part is normalised slowly varying at zero. In the rest of this work, since the value of
 $x_0$
is unimportant because
 $\tilde{\ell}(x)$
and
 $\tilde{\varepsilon}(x)$
may be altered at will for
 $x\in (x_0,1]$
, one can choose
 $x_0=1$
without loss of generality. Furthermore, we will only consider normalised regularly/slowly varying function.
Here are some interesting properties of normalized regularly varying functions. Let
 $\mathsf{v}_{\alpha,\ell}$
be a normalised regularly varying at zero with normalized slowly varying part l.
Lemma 4·1.
-
(i) There exists small enough
$x_1 \gt 0$
such that
$$ \lim_{x\downarrow 0}\mathsf{v}_{\alpha,\ell}^{\prime}(x)=+\infty\quad \text{ and }\quad \mathsf{v}_{\alpha,\ell}({\cdot}) \,\,\text{ is increasing on $(0,x_1]$}. $$
-
(ii) If in addition we assume that l is a
$\mathcal{C}^{2}$
function such that (4·6)where
\begin{align} {}\liminf_{x\downarrow 0}x\,\varepsilon^{\prime}(x)=0, \end{align}
$\varepsilon$
is given by (4·4). Then there exists small enough
$x_2 \gt 0$
such that
$\mathsf{v}_{\alpha,\ell}$
is increasingly concave on
$(0,x_2]$
. Moreover for all
$x_3\in (0,x_2)$
and all
$\mathsf{c} \gt 0$
small enough there exists
$r_0 \lt x_3$
such that
$$ \mathsf{v}_{\alpha,\ell}(t)-\mathsf{v}_{\alpha,\ell}(s)\leq \textbf{c}\, \mathsf{v}_{\alpha,\ell}(t-s) \quad \text{ for all $s,t\in [x_3,x_2]$ such that $0 \lt t-s \lt r_0$}. $$


Proof.
-
(i) It stemmed from
and (4·2).
$$ \mathsf{v}_{\alpha,\ell}^{\prime}(x)=x^{\alpha-1}\,\ell(x)\,\left(\alpha-\varepsilon(x)\right), $$
-
(ii) It is easy to check that

 $$ \mathsf{v}_{\alpha,\ell}^{\prime\prime}(x)= x^{\alpha-2}\, \ell(x)\left[ \left(\alpha-1-\varepsilon(x)\right)\left(\alpha-\varepsilon(x)\right)-x\,\varepsilon^{\prime}(x)\right].$$
(4·2) and hypothesis (4·6) ensure that
 $\lim_{x\downarrow 0}\mathsf{v}_{\alpha,\ell}^{\prime\prime}(x)=-\infty$
. Then there exists
 $x_2 \gt 0$
small enough such that
 $\mathsf{v}_{\alpha,\ell}^{\prime}(x) \gt 0$
and
 $\mathsf{v}_{\alpha,\ell}^{\prime\prime}(x) \lt 0$
for all
 $x\in (0,x_2]$
. Thus
 $\mathsf{v}_{\alpha,\ell}$
is increasingly concave on
 $(0,x_2]$
.
For the rest, let
 $x_3 \in (0,x_2]$
and
 $\mathsf{c} \gt 0$
be arbitrary. Let
 $s \lt t\in (x_3,x_2)$
and
 $r \lt x_3$
, then using the monotonicity of
 $\mathsf{v}_{\alpha,\ell}^{\prime}$
we have for
 $0 \lt t-s \lt r$
that
 \begin{align}\frac{\mathsf{v}_{\alpha,\ell}(t)-\mathsf{v}_{\alpha,\ell}(s)}{\mathsf{v}_{\alpha,\ell}(t-s)} \leq \frac{\mathsf{v}_{\alpha,\ell}^{\prime}(x_3)}{\mathsf{v}_{\alpha,\ell}^{\prime}(r)}. \end{align}
Since
 $\lim_{x\downarrow 0}\mathsf{v}_{\alpha,\ell}^{\prime}(x)=+\infty$
, we can choose
 $r_0$
to be smallest r guaranteeing that the term
 $\mathsf{v}_{\alpha,\ell}^{\prime}(x_3)/\mathsf{v}_{\alpha,\ell}^{\prime}(r)$
will be smaller than
 $\textbf{c}$
. This completes the proof.
Remark 4·2. As a consequence of the Lemma 4·1, for any normalised regularly varying at zero
 $\mathsf{v}_{\alpha,\ell}$
that checks the condition (4·6),
 $(s,t)\mapsto \mathsf{v}_{\alpha,\ell}(|t-s|)$
defines a metric on
 $[a,x_2]^2$
.
Let
 $\ell$
be a normalised slowly varying function at zero. Now we consider the continuous function
 $\mathsf{w}_{H,l}$
given by
 \begin{align} \mathsf{w}_{H,\ell}(0)=0 \quad \text{ and } \quad \mathsf{w}_{H,\ell}(x)= x^H\,\ell(x)\, \log^{1/2}(1/x), \quad x\in (0,1].\end{align}
It is easy to see that
 $\ell(x)\, \log^{1/2}(1/x)$
stills a normalised slowly varying satisfying (4·3) with
 $\bar{\varepsilon}({\cdot})=\varepsilon({\cdot})-\log^{-1}(1/\cdot)/2$
. Hence assertion 1 of Lemma 4·1 provides that
 $\mathsf{w}_{H,\ell}$
is increasing on some interval
 $(0,x_1]$
with
 $x_1\in (0,1)$
. Therefore
 $\mathsf{w}_{H,\ell}\in \mathscr{L}$
.
If we assume in addition that
 $\ell$
satisfies
 \begin{align} {}\underset{x\rightarrow 0}{\limsup}\,\,\ell(x)\log^{1/2}(1/x)=+\infty,\end{align}
then the following inclusions hold
 \begin{align}C^{H}(\mathbf{I})\subsetneq C^{\mathsf{w}_{H,\ell}}(\mathbf{I})\subsetneq \underset{\tau \gt 0}{\bigcap} C^{H-\tau}(\mathbf{I}).\end{align}
Let
 $\theta_H$
be the normalised regularly varying function defined in (7·1) with a normalized slowly varying part that satisfies;
 \begin{align} {} {}\left\{ \begin{array}{l} {} {} {}\text{(i)}\quad \underset{x\rightarrow+\infty}{\liminf}\,\,L_{\theta_{H}}(x)=0,\quad \underset{x\rightarrow+\infty}{\limsup}\,\,L_{\theta_{H}}(x) \lt +\infty;\\ {} {} {}\\ \text{(ii)}\,\,\, \underset{x\rightarrow +\infty}{\limsup} \,\,x\, \varepsilon^{\prime}_{\theta}(x)=0. {} {}\end{array}\right. {}\end{align}
Here are some examples of normalised slowly varying functions for which the above conditions are satisfied
 \[ L_{\theta_{H}}(x)=\log^{-{\beta}}\left(x\right), \quad L_{\theta_{H}}(x)=\exp\left(-\log^{\alpha}\left(x\right)\right), \quad \alpha \in (0,1) {\text{ and } \beta \gt 0}.\]
In what follows, we will adopt the following notation
 \begin{align}{ \ell_{\theta_H}({\cdot})\,:\!=\,\mathsf{c}_H^{1/2}\,L^{-1/2}_{\theta_{H}}(1/\cdot)}.\end{align}
Now let us give the main result of this section.
Theorem 4·3. Let
 $\{B^H(t), t\in [0,1]\}$
be a d-dimensional fractional Brownian motion. Then there exist a function
 $f\in C^{\mathsf{w}_{H,{\ell_{\theta_H}}}}(\mathbf{I})\setminus C^{H}\left(\mathbf{I}\right)$
, and compact sets
 $E\subset \mathbf{I}$
and
 $F\subset \mathbb{R}^d$
such that
 \begin{align} {} \mathcal{C}_{\rho_{\mathbf{d}_{H}}}^{d}\left(E\times F\right)=\mathcal{H}_{\rho_{\mathbf{d}_{H}}}^d\left(E\times F\right)=0 \quad \text{ and } \quad \mathbb{P}\left\{(B^H+f)(E)\cap F\neq \varnothing \right\} \gt 0. {} \end{align}
In other words (3·4) fails to hold.
Remark 4·4
-
(i) It is worthwhile mentioning that
$C^{\mathsf{w}_{H,\ell_{\theta_H}}}(\mathbf{I})$
verifies (4·10) as
${\ell_{\theta_H}({\cdot})}$
defined in (4·12) meets the condition (4·9) via the first term in assertion (i) of (4·11), i.e.
$\underset{x\rightarrow+\infty}{\liminf}\,\,L_{\theta_{H}}(x)=0$
. -
(ii) It follows from the fact (4·10) that the drift f in Theorem 4·3 belongs to
$\underset{{\tau \gt 0}}{\bigcap}\,C^{H-\tau}\left(\mathbf{I}\right)\setminus C^{H}\left(\mathbf{I}\right)$
.


Before drawing up the proof we provide the tools to be used. Let
 $\delta_{\theta_H}$
be the function given by the representation (7·3). Theorem 7·3·1 in [
Reference Marcus and Rosen20
] tells us that
 $\delta_{\theta_H}$
is normalised regularly varying with index H with a slowly varying part
 $\ell_{\delta_{\theta_H}}$
that satisfies
 \begin{align} {} {}\ell_{\theta_H}(h)\thicksim \ell_{\delta_{\theta_H}}(h)\quad \text{as $h\rightarrow 0$}.\end{align}
For more details see (7·6). Now we consider another probability space
 $(\Omega^{\prime},\mathcal{F}^{\prime},\mathbb{P}^{\prime})$
on which we define the real valued centered Gaussian process with stationary increments
 $B_0^{\delta_{\theta_H}}$
, satisfying
 $B_0^{\delta_{\theta_H}}(0)=0$
a.s. and
 \begin{align} {}\mathbb{E}^{\prime}\left(B_0^{\delta_{\theta_H}}(t)-B_0^{\delta_{\theta_H}}(s)\right)^2=\,\delta_{\theta_H}^2(|t-s|)\quad \text{ for all $t,s\in [0,1]$}.\end{align}
Proposition 7·1 gives a way to construct this process and Theorem 7·2 provides us its modulus of continuity, that is
 $B_0^{\delta_{\theta_H}}\in C^{\mathsf{w}_{H,{\ell_{\theta_H}}}}(\mathbf{I})$
 $\mathbb{P}^{\prime}$
-almost surely. The d-dimensional version of the process
 $B^{\delta_{\theta_H}}_0$
is the process
 $B^{\delta_{\theta_H}}(t)\,:\!=\,(B^{\delta_{\theta_H}}_1(t),....,B^{\delta_{\theta_H}}_d(t))$
, where
 $B^{\delta_{\theta_H}}_1,...,B^{\delta_{\theta_H}}_d$
are d independent copies of
 $B^{\delta_{\theta_H}}_0$
. Let Z be the d-dimensional mixed process defined on the product space
 $(\Omega\times\Omega^{\prime},\mathcal{F}\times\mathcal{F}^{\prime},\mathbb{P}\otimes\mathbb{P}^{\prime})$
by
 \begin{align} {}Z(t,(\omega,\omega^{\prime}))=B^H(t,\omega)+B^{\delta_{\theta_H}}(t,\omega^{\prime}) \text{ for all } t\in [0,1] \text{ and } (\omega,\omega^{\prime})\in \Omega\times\Omega^{\prime}. \end{align}
It is easy to see that the components of
 $Z=(Z_1,...,Z_d)$
are independent copies of a real valued Gaussian process
 $Z_0= B_0^H+ B^{\delta_{\theta_H}}_0$
on
 $(\Omega\times\Omega^{\prime},\mathcal{F}\otimes\mathcal{F}^{\prime},\mathbb{P}\otimes\mathbb{P}^{\prime})$
. Furthermore we have
 $$ \widetilde{\mathbb{E}}\left(Z_0(t)-Z_0(s)\right)^2=\mathsf{v}_{2H,1+\ell_{{\delta_{\theta_H}}}^2}(|t-s|)\,:\!=\,|t-s|^{2H}\left(1+\ell_{{\delta_{\theta_H}}}^2(|t-s|)\right),$$
where
 $\widetilde{\mathbb{E}}$
denotes the expectation under the probability measure
 $\widetilde{\mathbb{P}}\,:\!=\,\mathbb{P}\otimes \mathbb{P}^{\prime}$
.
Using the assertion i. of (4·11) and (4·14) we obtain the following
Lemma 4·5. There exists a constant
 $q \gt 1$
such that
 \begin{align} {} q^{-1}\,\mathsf{v}_{2H,\, {\ell^2_{\theta_H}}}(h)\leq \widetilde{\mathbb{E}}\left(Z_0(t+h)-Z_0(t)\right)^2 \leq q\,\,\mathsf{v}_{2H,\, {\ell^2_{\theta_H}}}(h),\end{align}
for all
 $h\in [0,1]$
and
 $t\in [0,1]$
.
For simplicity, we denote by
 $\mathbf{d}_{H,\ell_{\delta_{\theta_H}}}$
and
 $\mathbf{d}_{H,(1+\ell_{\delta_{\theta_H}}^2)^{1/2}}$
the canonical metrics of
 $B^{\delta_{\theta_H}}$
and Z respectively. A consequence of the previous lemma these canonical metrics are strongly equivalents to the metric
 $(s,t)\mapsto \mathbf{d}_{H,{\ell_{\theta_H}}}(t,s)\,:\!=\,\mathsf{v}_{H,\,{\ell_{\theta_H}}}(|t-s|)$
, leading to the strong equivalence of the metrics
 $\rho_{\mathbf{d}_{H,\ell_{\delta_{\theta_H}}}}$
,
 $\rho_{\mathbf{d}_{H,(1+\ell_{\delta_{\theta_H}}^2)^{1/2}}}$
and
 $\rho_{\mathbf{d}_{H,{\ell_{\theta_H}}}}$
. Hence, their associated capacities are also equivalents.
Proof of Theorem
4·3. Let us consider the Gaussian process Z stated above. Using condition (4·11) we infer that
 ${\ell_{\theta_H}({\cdot})}$
satisfies (4·6). Then Lemma 4·1 ensures that
 $\mathsf{v}_{H,{\ell_{\theta_H}({\cdot})}}$
verifies [13, hypothesis 2·2]. Let
 $M \gt 0$
, applying [13, theorem 4·1] and the fact that
 $\rho_{\mathbf{d}_{H,(1+\ell_{\delta_{\theta_H}}^2)^{1/2}}}$
and
 $\rho_{\mathbf{d}_{H,{\ell_{\theta_H}}}}$
are strongly equivalent, there exist a positive constant
 $\mathsf{c}_1$
depending only on
 $\mathbf{I}$
and M such that
 \begin{align} \widetilde{\mathbb{P}}\left\{Z(E)\cap F\neq \emptyset\right\}\geq \,\mathsf{c}_1\,\mathcal{C}_{\rho_{\mathbf{d}_{H,{\ell_{\theta_H}}}}}^{d}(E\times F),\end{align}
for any compact sets
 $E\subset \mathbf{I}$
and
 $F\subset [-M,M]^d$
. Let
 $ 0 \lt \gamma \lt d$
and fix a
 $\gamma$
-Ahlfors–David regular set
 $F_{\gamma}\subset [-M,M]^d$
. Then by using (2·21) with
 $\rho_1=\mathbf{d}_{H,{\ell_{\theta_H}}}$
and
 $\rho_3=\rho_{\mathbf{d}_{H,{\ell_{\theta_H}}}}$
and (2·22) with
 $\rho_1=\mathbf{d}_{H}$
and
 $\rho_3=\rho_{\mathbf{d}_{H}}$
, we obtain
 \begin{align}\mathcal{C}_{\rho_{\mathbf{d}_{H,{\ell_{\theta_H}}}}}^{d}(E\times F_{\gamma})\geq\, \mathsf{c}_2^{-1}\, \mathcal{C}_{\mathbf{d}_{H,{\ell_{\theta_H}}}}^{ d-\gamma}(E) \quad \text{ and }\quad \mathcal{H}_{\rho_{\mathbf{d}_{H}}}^d(E\times F_{\gamma})\leq\, \mathsf{c}_{2}\, \mathcal{H}^{H(d-\gamma)}(E),\end{align}
for all compact
 $\,E\subset \mathbf{I}$
and for some constant
 $\mathsf{c}_2 \gt 0$
. Now it is not difficult to see that the functions
 $h(t)\,:\!=\,t^{H(d-\gamma)}$
and
 $$ \Phi(t)= 1/\mathsf{v}^{d-\gamma}_{H,{\ell_{\theta_H}}}(t)=1/\mathsf{v}_{H\left(d-\gamma\right),{\ell_{\theta_H}^{\left(d-\gamma\right)}}}(t),$$
satisfy the hypotheses of [
Reference Taylor27
, theorem 4] which allow us to conclude that there exists a compact set
 $E_{\gamma}\subset \mathbf{I}$
such that
 \begin{align}\mathcal{H}^{H(d-\gamma)}(E_{\gamma})=0\quad \quad \text{ and } \quad \quad \mathcal{C}_{\mathbf{d}_{H,{\ell_{\theta_H}}}}^{ d-\gamma}(E_{\gamma}) \gt 0.\end{align}
Consequently, combining (4·19) and (4·20), we have
 \begin{align}\mathcal{H}_{\rho_{\mathbf{d}_{H}}}^d(E_{\gamma}\times F_{\gamma})=0 \quad \text{ and }\quad \widetilde{\mathbb{P}}\left\{Z(E_{\gamma})\cap F_{\gamma}\neq \emptyset\right\}\geq\, (\mathsf{c}_1/\mathsf{c}_2)\, \mathcal{C}_{\mathbf{d}_{H,{\ell_{\theta_H}}}}^{d-\gamma}(E_{\gamma}) \gt 0.\end{align}
Now the remainder of the proof is devoted to the construction of a drift f satisfying (4·13). As a consequence of Fubini’s theorem, we have
 \begin{equation*}\mathbb{E}^{\prime}\left(\mathbb{P}\left\{(B^H+B^{\delta_{\theta_H}}(\omega^{\prime}))(E_{\gamma})\cap F_{\gamma}\neq \emptyset \right\}-\mathsf{c}_3\, \mathcal{C}_{\mathbf{d}_{H,{\ell_{\theta_H}}}}^{d-\gamma}(E_{\gamma})\right) \gt 0,\end{equation*}
for some fixed positive constant
 $\mathsf{c}_3\in (0,\mathsf{c}_1/\mathsf{c}_2)$
, leading to
 \begin{align}\mathbb{P}^{\prime}\left\{\omega^{\prime}\in \Omega^{\prime}\,:\,\mathbb{P}\left\{(B^H+B^{\delta_{\theta_H}}(\omega^{\prime}))(E_{\gamma})\cap F_{\gamma}\neq \emptyset \right\} \gt \mathsf{c}_3\,\mathcal{C}_{\mathbf{d}_{H,{\ell_{\theta_H}}}}^{ d-\gamma}(E_{\gamma})\right\} \gt 0.\end{align}
We therefore choose the function f among of them. Hence we get the desired result.
5. Hitting points
As mentioned previously in the introduction our goal in this section is to shed some light on the hitting probabilities for general measurable drift. The resulting estimates are given in the following.
Theorem 5·1. Let
 $\{B^H(t)\,:\, t\in [0,1]\}$
be a d-dimensional fractional Brownian motion with Hurst index
 $H\in (0,1)$
. Let
 $f\,:\, [0,1]\rightarrow \mathbb{R}^d$
be a bounded Borel measurable function and let
 $E\subset \mathbf{I}$
be a Borel set. Then for any
 $M \gt 0$
there exists a constant
 $ \textbf{c}_1\geq 1$
such that for all
 $x\in [-M,M]^d$
we have
 \begin{align} \textbf{c}_1^{-1}\mathcal{C}_{\rho_{\mathbf{d}_{H}}}^{d}(Gr_E(f))\leq \mathbb{P}\left\lbrace \exists\, t\in E : (B^H+f)(t)=x\right\rbrace\leq \textbf{c}_1\, \mathcal{H}_{\rho_{\mathbf{d}_{H}}}^{d}(Gr_E(f)). {} {}\end{align}
The following lemmas are very valuable to prove Theorem 5·1
Lemma 5·2 [
Reference Biermé, Lacaux and Xiao1
, lemma 3·1]. Let
 $\{B^H(t)\,:\, t\in [0,1]\}$
be a fractional Brownian motion with Hurst index
 $H\in (0,1)$
. For any constant
 $M \gt 0$
, there exists positive constants
 $ \textbf{c}_2$
and
 $\varepsilon_0 \gt 0$
such that for all
 $r\in (0,\varepsilon_0)$
,
 $t\in \mathbf{I}$
and all
 $x\in [-M,M]^d$
,
 \begin{align} {}\mathbb{P}\left(\inf _{ s\in I,|s-t|^H\leq r}\|B^H(s)-x\| \leqslant r\right) \leqslant \textbf{c}_2\, r^{d}. {} {}\end{align}
Lemma 5·3 [
Reference Biermé, Lacaux and Xiao1
, lemma 3·2]. Let
 $B^H$
be a fractional Brownian motion with Hurst index
 $H\in (0,1)$
. Then there exists a positive constant
 $ \textbf{c}_3$
such that for all
 $\epsilon \in (0,1)$
,
 $s,t\in \mathbf{I}$
and
 $x,y\in \mathbb{R}^d$
we have
 \begin{align}\int_{\mathbb{R}^{2d}}e^{-i(\langle\xi,x\rangle+\langle\eta,y\rangle)}&\exp\left(-\dfrac{1}{2}(\xi,\eta)\left(\varepsilon I_{2d}+\text{Cov}(B^{H}(s),B^{H}(t))\right)(\xi,\eta)^{T}\right)d\xi d\eta \nonumber\\& \leq \dfrac{ \textbf{c}_{3}}{\left(\rho_{\mathbf{d}_{H}}((s,x),(t,y))\right)^{d}},\end{align}
where
 $\Gamma_{\varepsilon}(s,t)\,:\!=\,\varepsilon\,I_2+\text{Cov}(B^H_0(s),B^H_0(t))$
,
 $I_{2d}$
and
 $I_2$
are the identities matrices of order 2d and 2 respectively,
 $Cov(B^H(s),B^H(t))$
and
 $Cov(B^H_0(s),B^H_0(t))$
denote the covariance matrix of the random vectors
 $(B^H(s),B^H(t))$
and
 $(B^H_0(s),B^H_0(t))$
respectively, and
 $(\xi,\eta)^T$
is the transpose of the row vector
 $(\xi,\eta)$
.
Proof of Theorem
5·1. We start with the upper bound. Choose an arbitrary constant
 $\gamma \gt \mathcal{H}_{\rho_{\mathbf{d}_{H}}}^d(Gr_E(f))$
, then there is a covering of
 $Gr_E(f)$
by balls
 $\{B_{\rho_{\mathbf{d}_{H}}}((t_i,y_i),r_i), i\geq 1\}$
in
 $\mathbb{R}_+\times\mathbb{R}^d$
such that
 \begin{align} {} {}Gr_E(f)\subseteq \bigcup_{i=1}^{\infty}B_{\rho_{\mathbf{d}_{H}}}((t_i,y_i),r_i)\quad \text{ and }\quad \sum_{i=1}^{\infty}(2r_i)^{d} \leq \gamma. {} {}\end{align}
Let
 $\delta_0$
and M being the constants given in Lemma 5·2. We assume without loss of generality that
 $r_i \lt \delta_0$
for all
 $i \geq 1$
. Let
 $x\in [-M,M]^d$
, it is obvious that
 \begin{align} {} {}& \left\{ \exists s\in E \,:\, (B^{H}+f)(s)=x \right\} \subseteq \\& \qquad \qquad \bigcup_{i=1}^{\infty} \left\{ \exists\,\left(s,f(s)\right)\in\left(t_{i}-r_{i}^{1/H},t_{i}+r_{i}^{1/H}\right)\times B(y_{i},r_{i})\text{ s.t. }(B^{H}+f)(s)=x\right\}.\nonumber {} {}\end{align}
Since for every fixed
 $i\geq 1$
we have
 \begin{align}& \left\{ \exists\,\left(s,f(s)\right)\in\left(t_{i}-r_{i}^{1/H},t_{i}+r_{i}^{1/H}\right) \times B(y_{i},r_{i})\text{ s.t. }(B^{H}+f)(s)=x\right\} \nonumber\\ {}& \quad \qquad \quad \qquad \quad \qquad \quad \qquad \quad \quad \qquad \subseteq \left\{ \inf_{|s-t_i|^{H} \lt r_i }\|B^H(s)-x+y_i\|\leq r_i \right\}, {} {}\end{align}
then we get from [ Reference Biermé, Lacaux and Xiao1 , lemma 3·1] that
 \begin{align} {} {}& \mathbb{P}\left\{ \exists\,\left(s,f(s)\right)\in\left(t_{i}-r_{i}^{1/H},t_{i}+r_{i}^{1/H}\right) \times B(y_{i},r_{i})\text{ s.t. }(B^{H}+f)(s)=x\right\} \nonumber\\ & \qquad \qquad \qquad \qquad \qquad \qquad \qquad \qquad \quad \leq\mathbb{P}\left\{ \inf_{|s-t_{i}|^{H} \lt r_{i}}\|B^{H}(s)-x+y_{i}\|\leq r_i\right\} \nonumber\\ {} {}& \qquad \qquad \qquad \qquad \qquad \qquad \qquad \qquad \quad \leq \textbf{c}_{2}\,r_{i}^{d},\end{align}
where
 $ \textbf{c}_4$
depends on H,
 $\mathbf{I}$
, M and f only. Combining (5·4)-(5·7) we derive that
 $$ \mathbb{P}\left\lbrace \exists s\in E \,:\, (B^H+f)(s)=x\right\rbrace\leq 2^{-d} \textbf{c}_{2}\, \gamma.$$
Let
 $\gamma\downarrow \mathcal{H}_{{\rho_{\mathbf{d}_{H}}}}^{d}(Gr_E(f))$
, the upper bound in (5·1) follows.
The lower bound in (5·1) holds from the second moment argument. We assume that
 $\mathcal{C}_{\rho_{\mathbf{d}_{H}}}^{d}(Gr_E(f)) \gt 0$
, then let
 $\sigma$
be a measure supported on
 $Gr_E(f)$
such that
 \begin{align} {} {}\mathcal{E}_{\rho_{\mathbf{d}_{H}},d}(\sigma)=\int_{Gr_E(f)}\int_{Gr_E(f)}\frac{d\sigma(s,f(s))d\sigma(t,f(t))}{\rho_{\mathbf{d}_{H}}((s,f(s)),(t,f(t)))^{d}}\leq \frac{2}{\mathcal{C}_{\rho_{\mathbf{d}_{H}}}^{d}(Gr_E(f))}. {} {}\end{align}
Let
 $\nu$
be the measure on E satisfying
 $\nu\,:\!=\,\sigma\circ P_1^{-1} $
where
 $P_1$
is the projection mapping on E, i.e.
 $P_1(s,f(s))=s$
. For
 $n\geq 1$
we consider a family of random measures
 $\nu_n$
on E defined by
 \begin{align} {} {}\int_{E} g(s) \nu_{n}(d s) &=\int_{E} (2 \pi n)^{d / 2} \exp \left(-\frac{n\|B^H(s)+f(s)-x\|^2}{2}\right) g(s) \nu(d s) \nonumber {} {}\\ {} {}&=\int_{E} \int_{\mathbb{R}^{d}} \exp \left(-\frac{\|\xi\|^{2}}{2 n}+i\left\langle\xi, B^H(s)+f(s)-x\right\rangle\right) g(s) d \xi \nu(d s), {} {}\end{align}
where g is an arbitrary measurable function on
 $\mathbb{R}_+$
. Our aim is to show that
 $\left\lbrace \nu_n, n\geq 1\right\rbrace $
has a subsequence which converges weakly to a finite measure
 $\nu_{\infty}$
supported on the set
 $\{s\in E \,:\, B^H(s)+f(s)=x\}$
. To carry out this goal, we will start by establishing the following inequalities
 \begin{align} {} {}\mathbb{E}(\|\nu_n\|)\geqslant \textbf{c}_{5},\quad \quad \mathbb{E}(\|\nu_n\|^2)\leqslant \textbf{c}_{3} \mathcal{E}_{\rho_{\mathbf{d}_{H}},d}(\sigma), {} {}\end{align}
which constitute together with the Paley–Zygmund inequality the cornerstone of the proof. Here
 $\|\nu_n\|$
denotes the total mass of
 $\nu_n$
. By (5·9), Fubini’s theorem and the use of the characteristic function of a Gaussian vector we have
 \begin{align} {} {}\mathbb{E}(\|\nu_n\|)& =\int_{E}\int_{\mathbb{R}^{d}}e^{-i\left\langle \xi,x-f(s)\right\rangle }\exp\left(-\frac{\|\xi\|^{2}}{2n}\right)\mathbb{E}\left(e^{i\left\langle \xi,B^{H}(s)\right\rangle }\right)\,d\xi\,\nu(ds)\nonumber\\ {} {}& =\int_{E}\int_{\mathbb{R}^{d}}e^{-i\left\langle \xi,x-f(s)\right\rangle }\exp\left(-\frac{1}{2}\left(\frac{1}{n}+s^{2H}\right)\|\xi\|^{2}\right)\,d\xi\,\nu(ds)\nonumber\\ {} {}& =\int_{E}\left(\frac{2\pi}{n^{-1}+s^{2H}}\right)^{d/2}\exp\left(-\frac{\|x-f(s)\|^{2}}{2\left(n^{-1}+s^{2H}\right)}\right)\,\nu(ds)\nonumber\\ {} {}& \geq\int_{E}\left(\frac{2\pi}{1+s^{2H}}\right)^{d/2}\exp\left(-\frac{\|x-f(s)\|^{2}}{2s^{2H}}\right)\,\nu(ds)\nonumber\\ {} {}&\geq \textbf{c}_{5} \gt 0. {} {}\end{align}
Since f is bounded,
 $x\in [{-}M,M]^d$
and
 $\nu$
is a probability measure we conclude that
 $ \textbf{c}_{5}$
is independent of
 $\nu$
and n. This gives the first inequality in (5·10).
We will now turn our attention to the second inequality in (5·10). By (5·9) and Fubini’s theorem again we obtain
 \begin{align} {} {}\mathbb{E}\left(\|\nu_{n}\|^{2}\right) & =\int_{E}\int_{E}\nu(ds)\nu(dt)\int_{\mathbb{R}^{2d}}e^{-i(\left\langle \xi,x-f(s)\right\rangle +\left\langle \eta,x-f(t)\right\rangle )} \nonumber\\ {} {}& \quad \times\exp(-\frac{1}{2}(\xi,\eta)(n^{-1}I_{2d}+Cov(B^{H}(s),B^{H}(t)))(\xi,\eta)^{T})d\xi d\eta \nonumber\\ {} {}& \quad \leqslant \textbf{c}_{3}\int_{Gr_{E}(f)}\int_{Gr_{E}(f)}\frac{d\sigma(s,f(s))d\sigma(t,f(t))}{(\max\{|t-s|^{H},\|f(t)-f(s)\|\})^{d}}= \textbf{c}_{3}\,\mathcal{E}_{\rho_{\mathbf{d}_{H}},d}(\sigma) \lt \infty, {} {}\end{align}
where the first inequality is a direct consequence of Lemma 5·3. Plugging the moment estimates of (5·10) into the Paley–Zygmund inequality (c.f. Kahane [
Reference Kahane15
, p.8]), allows us to confirm that there exists an event
 $\Omega_0$
of positive probability such that, for all
 $\omega\in \Omega_0$
,
 $(\nu_n(\omega))_{n\geq 1}$
admits a subsequence converging weakly to a finite positive measure
 $\nu_{\infty}(\omega)$
supported on the set
 $\{s\in E \,:\, B^H(\omega,s)+f(s)=x\}$
, satisfying the moment estimates in (5·10). Hence we have
 \begin{align}\mathbb{P}\left\{\exists s\in E: (B^H+f)(s)=x\right\}\geq \mathbb{P}\left(\|\nu_{\infty}\| \gt 0\right)\geq \frac{\mathbb{E}(\|\nu_{\infty}\|)^2}{\mathbb{E}(\|\nu_{\infty}\|^2)}\geq \frac{ \textbf{c}_5^2}{ \textbf{c}_3\mathcal{E}_{\rho_{\mathbf{d}_{H}},d}(\sigma)}. {} {}\end{align}
Combining this with (5·8) yields the lower bound in (5·1). The proof is completed.
Remark 5·4. We mention that the covering argument used to prove the upper bound in (5·1) can also serve to show that for any Borel set
 $F\subset\mathbb{R}^d$
, there exists a positive constant
 $ \textbf{c}$
such that
 \begin{align}\mathbb{P}\left\lbrace (B^H+f)(E)\cap F\neq \emptyset \right\rbrace\leq \textbf{c}\, \mathcal{H}_{\widetilde{\rho}_H}^d(Gr_E(f)\times F). {} {}\end{align}
Here
 $\mathcal{H}_{\widetilde{\rho}_{\mathbf{d}_{H}}}^{\alpha}(\centerdot)$
is the
 $\alpha$
-dimensional Hausdorff measure on the metric space
 $(\mathbb{R}_+\times\mathbb{R}^d\times\mathbb{R}^d,\widetilde{\rho}_{\mathbf{d}_{H}})$
, where the metric
 ${\widetilde{\rho}_{\mathbf{d}_{H}}}$
is defined by
 \begin{align*}\widetilde{\rho}_{\mathbf{d}_{H}}((s,x,u),(t,y,v))\,:\!=\,\max\{|t-s|^H,\|x-y\|,\|u-v\|\}.\end{align*}
But it seems hard to establish a lower bound in terms of
 $\mathcal{C}_{\widetilde{\rho}_H}^{d}(Gr_E(f)\times F)$
even for Ahlfors–David regular set F.
As a consequence of Theorem 5·1, we obtain a weaker version of [Reference Erraoui and Hakiki9, theorem 3·2]
Corollary 5·5 Let
 $B^H$
, f, and E as in Theorem 5·1. Then:
-
(i) if
$\,\mathcal{C}_{\rho_{\mathbf{d}_{H}}}^{d}(Gr_E(f)) \gt 0$
then
$\,\lambda_d\left((B^H+f)(E)\right) \gt 0$
with positive probability; -
(ii) if
$\mathcal{H}_{\rho_{\mathbf{d}_{H}}}^{d}(Gr_E(f))=0$
then
$\,\lambda_d\left((B^H+f)(E)\right)=0$
almost surely.


Proof. Integrating (5·1) of Theorem 5·1 over all cube
 $[-M,M]^d$
,
 $M \gt 0$
with respect Lebesgue measure
 $\lambda_d$
, we obtain that
 \begin{align} (2M)^d\, \textbf{c}_1^{-1}\mathcal{C}_{\rho_{\mathbf{d}_{H}}}^{d}(Gr_E(f))& \leq \mathbb{E}\left[\lambda_d\left([-M,M]^d\cap (B^H+f)(E)\right)\right] \nonumber \\ & \leq (2M)^d\, \textbf{c}_1\, \mathcal{H}_{\rho_{\mathbf{d}_{H}}}^{d}(Gr_E(f)). \end{align}
Therefore if
 $\mathcal{C}_{\rho_{\mathbf{d}_{H}}}^{d}(Gr_E(f)) \gt 0$
we obtain
 $$ \mathbb{E}\left[\lambda_d\left((B^H+f)(E)\right)\right] \gt 0.$$
Hence
 $\lambda_d\left((B^H+f)(E)\right) \gt 0$
with positive probability, which finishes the proof of (i). On the other hand, if
 $\mathcal{H}_{\rho_{\mathbf{d}_{H}}}^{d}(Gr_E(f))=0$
we obtain that
 $\lambda_d\left([-n,n]^d \cap (B^H+f)(E)\right)=0$
a.s. for all
 $n\in \mathbb{N}^{*}$
. Then we have
 $\lambda_d\left((B^H+f)(E)\right)=0$
a.s. Hence the proof of (ii) is completed.
Remark 5·6
-
(i) Let
$\dim_{\rho_{\mathbf{d}_{H}}}({\cdot})$
be the Hausdorff dimension in the metric space
$( \mathbb{R}_+\times \mathbb{R}^d,\rho_{\mathbf{d}_{H}})$
defined in (2·2). There is a close relationship between
$\dim_{\rho_{\mathbf{d}_{H}}}({\cdot})$
and H-parabolic Hausdorff dimension
$\dim_{\Psi, H}({\cdot})$
, used in Peres and Sousi [
Reference Peres and Sousi25
] and in Erraoui and Hakiki [
Reference Erraoui and Hakiki9
], expressed by See [ Reference Erraoui and Hakiki9 , remark 2·2].
$$ \dim_{\Psi, H}(.)\equiv H \times\dim_{\rho_{\mathbf{d}_{H}}}(.).$$
-
(ii) The previous corollary is a weaker version of [ Reference Erraoui and Hakiki9 , theorem 3·2] in the following sense: According to [ Reference Peres and Sousi25 , theorem 1·2.] and (i) we have
Therefore [ Reference Erraoui and Hakiki9 , theorem 3·2.] asserts that, if
$$ \dim(B^H+f)(E)=\frac{\dim_{\Psi,H}(Gr_E(f))}{H}\wedge d=\dim_{\rho_{\mathbf{d}_{H}}}(Gr_E(f))\wedge d.$$
$\dim_{\rho_{\mathbf{d}_{H}}}(Gr_E(f)) \gt d$
then
$\lambda_d(B^H+f)(E)) \gt 0$
almost surely. On the other hand, Corollary 5·5 (i) ensures, under the condition
$\mathcal{C}_{\rho_{\mathbf{d}_{H}}}^{d}(Gr_E(f)) \gt 0$
, that
$\lambda_d(B^H+f)(E)) \gt 0$
only with positive probability. It is well known from Frostman’s Lemma that the condition
$\mathcal{C}_{\rho_{\mathbf{d}_{H}}}^{d}(Gr_E(f)) \gt 0$
is weaker than
$\dim_{\rho_{\mathbf{d}_{H}}}(Gr_E(f)) \gt d$
.


6. Application to polarity
Let
 $E\subset \mathbf{I}$
. We say that a point
 $x\in \mathbb{R}^d$
is polar for
 $(B^H+f)\vert_{E}$
, the restriction of
 $(B^H+f)$
to E, if
 \begin{align} {}\mathbb{P}\left\{ \exists \, t\in E\,:\, (B^H+f)(t)=x\right\}=0.\end{align}
Otherwise, x is said to be non-polar for
 $(B^H+f)\vert_{E}$
. In other words,
 $(B^H+f)\vert_{E}$
hits the point x.
It is noteworthy that, when
 $f\in C^{H}(\mathbf{I})$
, the hitting probabilities estimates in (5·1) becomes
 \begin{align} {} \textbf{c}_1^{-1}\mathcal{C}^{Hd}(E)\leq \mathbb{P}\left\lbrace \exists t\in E : (B^H+f)(t)=x\right\rbrace\leq \textbf{c}_1\, \mathcal{H}^{Hd}(E).\end{align}
See also [
Reference Chen5
, corollary 2·8]. Consequently, all points are non-polar (resp. polar) for
 $(B^H+f)\vert_{E}$
when
 $\dim(E) \gt Hd$
(resp.
 $\dim(E) \lt Hd$
). However, the critical dimensional case, which is the most important and not easy to deal with, is
 $\dim(E)=Hd$
. This is undecidable in general as illustrated in the following
Proposition 6·1. Let
 $\{B^{H}(t) : t \in [0,1]\}$
be a d-dimensional fractional Brownian motion of Hurst index
 $H\in (0,1)$
such that
 $H d \lt 1$
. Let
 $f\,:\,[0,1]\rightarrow \mathbb{R}^d$
be a H-Hölder continuous function and
 $E\subset \mathbf{I}$
be a Borel set. Then there exist two Borel subsets
 $E_1$
and
 $E_2$
of
 $\mathbf{I}$
such that
 $\dim(E_1)=\dim(E_2)=H\,d$
and for all
 $x\in \mathbb{R}^d$
we have
 $$ {}\mathbb{P}\left\{\exists s\in E_1\,:\, (B^H+f)(s)=x\right\}=0 \quad \text{and} \quad \mathbb{P}\left\{\exists s\in E_2\,:\, (B^H+f)(s)=x\right\} \gt 0. {}$$
The following Lemma is helpful in the proof of Proposition 6·1.
Lemma 6·2 Let
 $\alpha\in (0,1)$
and
 $\beta \gt 1$
. Let
 $E_1$
and
 $E_2$
are two Borel subsets of
 $\,\mathbf{I}$
supporting two probability measures
 $\nu_1$
and
 $\nu_2$
respectively, that satisfy
 \begin{align} {}\mathsf{c}_1^{-1} r^{\alpha}\log^{\beta}(e/r)\leq \nu_1\left([a-r,a+r]\right)\leq \mathsf{c}_1 r^{\alpha}\log^{\beta}(e/r)\quad \text{ for all $r\in (0,1)$, $a\in E_1$},\end{align}
and
 \begin{align} {}\mathsf{c}_2^{-1} r^{\alpha}\log^{-\beta}(e/r)\leq \nu_2\left([a-r,a+r]\right)\leq \mathsf{c}_2 r^{\alpha}\log^{-\beta}(e/r)\quad \text{ for all $r\in (0,1)$, $a\in E_2$},\end{align}
for some positive constants
 $\mathsf{c}_1$
and
 $\mathsf{c}_2$
. Then we have
 $$ \dim(E_1)=\dim(E_2)=\alpha$$
and
 \begin{align} {}\mathcal{H}^{\alpha}(E_1)=0 \quad\text{and}\quad \mathcal{C}^{\alpha}(E_2) \gt 0.\end{align}
See Appendix B for examples of such measures
 $\nu_1$
and
 $\nu_2$
.
Proof. First, let us start by proving that
 $\dim(E_1)=\dim(E_2)=\alpha$
. Indeed, for all
 $t \in [0,1]$
and
 $n\in \mathbb{N}$
we denote by
 $I_n(t)$
the nth generation, half open dyadic interval of the form
 $[\dfrac{j-1}{2^n},\dfrac{j}{2^n})$
containing t. Then, by using (6·3) and (6·4), it is easy to check that
 \begin{align} {} {}\lim_{n\rightarrow \infty}\frac{\log \nu_1(I_n(t))}{\log(2^{-n})}=\lim_{n\rightarrow \infty}\frac{\log \nu_2(I_n(t))}{\log(2^{-n})}=\alpha. {}\end{align}
Therefore, by Billingsley Lemma [
Reference Bishop and Peres3
, lemma 1·4·1, p. 16] we have
 $\dim(E_1)=\dim(E_2)=\alpha$
.
Now we are going to look at (6·5). Let
 $r\in (0,1]$
and
 $P_{|.|}(E_1,r)$
be the packing number of
 $E_1$
. The lower bound in (6·3) leads via
 $$ {}\mathsf{c}_1^{-1}\,r^{\alpha}\, \log^{\beta}(e/r)\, P_{|.|}(E_1,r)\leq \sum_{j=1}^{P_{|.|}(E_1,r)}\nu_1(I_j)=\nu_1(E_1)=1, {}$$
to
 \[ {} {}P_{|.|}(E_{1},r)\leq\mathsf{c}_{1}^{\,}r^{-\alpha}\,\log^{-\beta}(e/r). {} {}\]
So using the well-known fact that
 $N_{|.|}(E_1,2r)\leq P_{|.|}(E_1,r)$
, we may deduce that
 $$ N_{|.|}(E_1,r)\leq \mathsf{c}_1\, 2^{\alpha}\,r^{-\alpha}\, \log^{-\beta}(2e/r),\,\, \forall r\in (0,1).$$
Therefore, it is not hard to make out that
 $$ {}\mathcal{H}^{\alpha}(E_1)\leq \, \limsup_{r\rightarrow 0}(2r)^{\alpha}\, N_{|.|}(E_1,r)=0, {}$$
which gives the first outcome of (6·5). On the other hand, to show that
 $\mathcal{C}^{\alpha}(E_2) \gt 0$
it is sufficient to prove that
 $$ \sup_{t\in E_2}{\displaystyle\int}_{E_2}\frac{\nu_2(ds)}{|t-s|^{\alpha}} \lt \infty.$$
Indeed, we first assume without loss of generality that
 $\kappa=\mathrm{diam}(E_2) \lt 1$
. Now since
 $\nu_2$
has no atom, then for any
 $t \in E_2$
we have
 \begin{align} {} {}& {\displaystyle\int}_{E_2}\frac{\nu_2(ds)}{|t-s|^{\alpha}}=\sum_{j=0}^{\infty} {\displaystyle\int}_{\{s:|t-s|\in (\kappa 2^{-(j+1)},\kappa 2^{-j}]\}}\frac{\nu_2(ds)}{|t-s|^{\alpha}} \nonumber \\ & \quad \leq \sum_{j=0}^{\infty} \kappa^{-\alpha} 2^{\alpha\,(j+1)}\nu_2\left([t-\kappa\,2^{-j},t+\kappa\,2^{-j}]\right)\nonumber\\ {} {}& \quad \leq 2^{\alpha}\mathsf{c}_2\,\sum_{j=0}^{\infty}\frac{1}{\log^{\beta}(e\,2^j/\kappa)\,}, {}\end{align}
which is finite independently of t. Hence
 $\mathcal{E}_{\alpha}(\nu_2) \lt \infty$
and therefore
 $\mathcal{C}^{\alpha}(E_2) \gt 0$
.

Against this background, it is worthy to note that, according to (6·2) and Proposition 6·1, the H-Hölder regularity of the drift f is insufficient to guarantee the non-polarity of points for
 $(B^H+f)\lvert_E$
for a Borel set
 $E\subset [0,1]$
such that
 $\dim(E)= Hd$
which implicitly involves the need for a bite of drift roughness. Namely, the drift f will be chosen, as in the previous section, to be (
 $H-\varepsilon$
)-Holder continuous for all
 $\varepsilon \gt 0$
without reaching order H. On the other hand in accordance to Theorem 5·1, for a general measurable drift f, a sufficient condition for
 $(B^H+f)\vert_{E}$
to hits all points is
 $\mathcal{C}_{\rho_{\mathbf{d}_{H}}}^{d}(Gr_E(f)) \gt 0$
. The overall point of what follows is to provide some examples of drifts satisfying this last condition with a Borel set E whose distinctive feature is
 $\dim(E)=Hd$
.
Given a slowly varying function at zero
 $\ell:(0,1]\,\rightarrow {\mathbb{R}}_+$
we associate to it the kernel
 $\Phi_{H,\ell}({\cdot})$
defined as follows
 \begin{align} {}\Phi_{H,\ell}(r)\,:\!=\,r^{-Hd}\,\ell^{-d}(r)\,\left(1+\log\left(1\vee\ell(r)\right)\right).\end{align}
Let
 $\pmb{\theta_H}$
be the normalised regularly varying function defined in (7·1) with a normalised slowly varying part
 $L_{\pmb{\theta_H}}$
. As previously, we consider the normalised regularly varying function at zero
 $\delta_{\pmb{\theta_H}}$
, with index H and normalised slowly varying part
 $\ell_{\delta_{\pmb{\theta_H}}}$
, satisfying (7·4) and, on the space
 $(\Omega^{\prime},\mathcal{F}^{\prime},\mathbb{P}^{\prime})$
, the d-dimensional Gaussian process with stationary increments
 $B^{\delta_{\pmb{\theta_H}}}(t)\,:\!=\,\left( B^{\delta_{\pmb{\theta_H}}}_1(t),....,B^{\delta_{\pmb{\theta_H}}}_d(t)\right), t\in [0,1]$
, where
 $B^{\delta_{\pmb{\theta_H}}}_1,...,B^{\delta_{\pmb{\theta_H}}}_d$
are d independent copies of
 $B^{\delta_{\pmb{\theta_H}}}_0$
defined in (7·8). The following lemma will be useful afterwards.
Lemma 6·3. There exists a positive constant
 ${\mathsf{c}}_3$
such that
 \begin{align} {} {}\mathbb{E}^{\prime}\left[\left(\max\left\lbrace t^H,\lVert B^{\delta_{\pmb{\theta_H}}}(t)\rVert \right\rbrace \right)^{-d}\right]\leq \mathsf{c}_3\, \Phi_{H,\ell_{\delta_{\pmb{\theta_H}}}}(t), \quad \forall t\in (0,t_0), {}\end{align}
for some
 $t_0\in (0,1)$
.
Proof. First we note that, since
 $B^{\delta_{\pmb{\theta_H}}}(t)$
is a d-dimensional Gaussian vector, the term on the left-hand side of (6·9) has the same distribution as
 $t^{-Hd}\left(\max\left\lbrace 1,\ell_{\delta_{\pmb{\theta_H}}}(t)\lVert N\rVert\right\rbrace \right)^{-d}$
, where N is a d-dimensional standard normal random vector. Due to simple calculations we obtain
 \begin{align*} {}\begin{array}{l} {} {}\mathbb{E}^{\prime}\left[\left(\max\left\lbrace 1,\ell_{\delta_{\pmb{\theta_{H}}}}(t)\lVert N\rVert\right\rbrace \right)^{-d}\right] {} {}=\mathbb{P}^{\prime}\left[\lVert N\rVert\leq\ell_{\delta_{\pmb{\theta_{H}}}}^{-1}(t)\right]+\ell_{\delta_{\pmb{\theta_{H}}}}^{-d}(t)\mathbb{E}^{\prime}\left[\dfrac{1}{\lVert N\rVert^{d}}1\!\!1_{\lbrace\lVert N\rVert \gt \ell_{\delta_{\pmb{\theta_{H}}}}^{-1}(t)}\right]\\ {} {}= \left(2\pi\right)^{-d/2}\,\left({\displaystyle\int}_{\left\{ \lVert y\rVert\leq\ell_{\delta_{\pmb{\theta_{H}}}}^{-1}(t)\right\} }\,e^{-\lVert y\rVert^{2}/2}dy+\ell_{\delta_{\pmb{\theta_{H}}}}^{-d}(t){\displaystyle\int}_{\left\{ \lVert y\rVert \gt \ell_{\delta_{\pmb{\theta_{H}}}}^{-1}(t)\right\} }\,\frac{e^{-\lVert y\rVert^{2}/2}}{\lVert y\rVert^{d}}dy\right)\\ {} {}\\ {} {}\leq\mathsf{c}_{4}\,\ell_{\delta_{\pmb{\theta_{H}}}}^{-d}(t)\left(1+{\displaystyle\int}_{\ell_{\delta_{\pmb{\theta_{H}}}}^{-1}(t)}^{\infty}\dfrac{e^{-r^{2}/2}}{r}\,dr\right)\\ {} {}\leq\mathsf{c}_{4}\,\ell_{\delta_{\pmb{\theta_{H}}}}^{-d}(t)\left(1+{\displaystyle\int}_{1\wedge\ell_{\delta_{\pmb{\theta_{H}}}}^{-1}(t)}^{1}r^{-1}\,dr+{\displaystyle\int}_{1}^{\infty}\frac{e^{-r^{2}/2}}{r}\,dr\right)\\ {} {}\\ {} {}\leq\mathsf{c}_{4}\,\ell_{\delta_{\pmb{\theta_{H}}}}^{-d}(t)\left(1-\log\left(1\wedge\ell_{\delta_{\pmb{\theta_{H}}}}^{-1}(t)\right)\right)\leq\mathsf{c}_{4}\,\ell_{\delta_{\pmb{\theta_{H}}}}^{-d}(t)\left(1+\log\left(1\vee\ell_{\delta_{\pmb{\theta_{H}}}}(t)\right)\right). {}\end{array} {}\end{align*}
Lemma 6·4.
Let E be a Borel set of [0, 1]. If
 $\mathcal{C}_{\Phi_{H,\ell_{\delta_{\pmb{\theta_H}}}}}(E) \gt 0$
, then
 $\mathbb{P}^{\prime}$
-almost surely
 $$ \mathcal{C}_{\rho_{\mathbf{d}_{H}}}^{d}\left(Gr_E(B^{\delta_{\pmb{\theta_H}}})\right) \gt 0. $$
Proof. Firstly, the assumption
 $\mathcal{C}_{\Phi_{H,\ell_{\delta_{\pmb{\theta_H}}}}}(E) \gt 0$
ensures that there exists a probability measure
 $\nu$
supported on E with finite energy, i.e.
 $$ {}\mathcal{E}_{\Phi_{H,\ell_{\delta_{\pmb{\theta_H}}}}}(\nu)={\displaystyle\int}_E{\displaystyle\int}_E \Phi_{H,\ell_{\delta_{\pmb{\theta_H}}}}(|t-s|)\nu(dt)\nu(ds) \lt \infty. {}$$
Let
 $\mu_{\omega^{\prime}}$
be the random measure defined on
 $Gr_E(B^{\delta_{\pmb{\theta_H}}})$
by
 $$ {}\mu_{\omega^{\prime}}(G)\,:\!=\,\nu\{s\,:\, (s,B^{\delta_{\theta_0}}(\omega^{\prime},s))\in G\} \quad \text{ for all } G\subset Gr_E(B^{\delta_{\pmb{\theta_H}}}(\cdot,\omega^{\prime})). {}$$
Hence
 $\mathbb{P}^{\prime}$
-almost surely we have
 \[ {}\begin{array}{c} {} {}\mathcal{E}_{\rho_{\mathbf{d}_{H}},d}(\mu_{\omega^{\prime}})\,:\!=\, {\displaystyle\int}_{Gr_{E}(B^{\delta_{\pmb{\theta_{H}}}})}{\displaystyle\int}_{Gr_{E}(B^{\delta_{\pmb{\theta_{H}}}})}\frac{d\mu_{\omega^{\prime}}(s,B^{\delta_{\pmb{\theta_{H}}}}(s))d\mu_{\omega^{\prime}}(t,B^{\delta_{\pmb{\theta_{H}}}}(t))}{\max\left\{ \lvert t-s\lvert^{Hd},\lVert B^{\delta_{\pmb{\theta_{H}}}}(t)-B^{\delta_{\pmb{\theta_{H}}}}(s)\rVert^{d}\right\} }\\ {} {}\\ {} {}={\displaystyle\int}_{E}{\displaystyle\int}_{E}\frac{\nu(ds)\nu(dt)}{\max\left\{ \lvert t-s\lvert^{Hd},\lVert B^{\delta_{\pmb{\theta_{H}}}}(t)-B^{\delta_{\pmb{\theta_{H}}}}(s)\rVert^{d}\right\} }. {}\end{array} {}\]
Therefore, in order to achieve the goal it is sufficient to show that
 $\mathcal{E}_{\rho_{\mathbf{d}_{H}},d}(\mu_{\omega^{\prime}}) \lt \infty$
for
 $\mathbb{P}^{\prime}$
-almost surely, which can be done by checking
 $\mathbb{E}^{\prime}\left[\mathcal{E}_{\rho_{\mathbf{d}_{H}},d}(\mu_{\omega^{\prime}})\right] \lt \infty$
. Indeed, using Fubini’s theorem with the stationarity of increments and Lemma 6·3 we obtain
 \begin{align} {} {}\begin{aligned} {} {} {}\mathbb{E}^{\prime}\left[ \mathcal{E}_{\rho_{\mathbf{d}_{H}},d}(\mu_{\omega^{\prime}})\right] {} {} {}&= \mathbb{E}^{\prime}\left[{\displaystyle\int}_{E}{\displaystyle\int}_{E}\frac{1}{\max\left\{ \lvert t-s\lvert^{Hd},\lVert B^{\delta_{\pmb{\theta_{H}}}}(t)-B^{\delta_{\pmb{\theta_{H}}}}(s)\rVert^{d}\right\} }\nu(ds)\nu(dt)\right]\\ {} {} {}&={\displaystyle\int}_E{\displaystyle\int}_E \mathbb{E}^{\prime}\left[\frac{1}{\max\left\{\lvert t-s\lvert^{Hd}, \lVert B^{\delta_{\pmb{\theta_{H}}}}(|t-s|)\rVert^d \right\}}\right]\nu(ds)\nu(dt)\\ {} {} {}&\leq \mathsf{c}_3\,\mathcal{E}_{\Phi_{H,\ell_{\delta_{\pmb{\theta_H}}}}}(\nu) \lt \infty. {} {}\end{aligned} {}\end{align}
Thus
 $\mathcal{C}_{\rho_{\mathbf{d}_{H}}}^{d}\left(Gr_E(B^{\delta_{\pmb{\theta_H}}})\right) \gt 0$
 $\mathbb{P}^{\prime}$
-almost surely.
Remark 6·5. Notice that in both of Lemmas 6·3 and 6·4 we lose nothing by changing
 $\ell_{\delta_{\theta_H}}({\cdot})$
by
 $\ell_{\theta_H}({\cdot})=\mathsf{c}_{H}\,L_{\theta_{H}}^{-1/2}(1/\cdot)$
, due to the fact that
 $\ell_{\delta_{\theta_H}}(h)\thicksim \ell_{\theta_H}(h)$
as
 $h\rightarrow 0$
.
The following result is the consequence of the two previous lemmas.
Proposition 6·6. Let
 $\{B^{H}(t) \,:\, t \in [0,1]\}$
be a d-dimensional fractional Brownian motion of Hurst index
 $H\in (0,1)$
. If
 $\mathcal{C}_{\Phi_{H,\ell_{\delta_{\pmb{\theta_H}}}}}(E) \gt 0$
, then there exists a continuous function
 $f\in C^{\mathsf{w}_{H,{\ell_{\theta_H}}}}(\mathbf{I})\setminus C^{H}\left(\mathbf{I}\right)$
such that
 \begin{align} {} {}\mathbb{P}\left\{\exists t\in E \,:\, (B^{H}+f)(t)=x\right\} \gt 0, {}\end{align}
for all
 $x\in \mathbb{R}^d$
.
Proof. We start the proof by recalling that Theorem 7·2 provides the modulus of continuity of
 $B^{\delta_{\pmb{\theta_H}}}$
that is
 $B^{\delta_{\pmb{\theta_H}}}\in C^{\mathsf{w}_{H, {\ell_{\theta_H}}}}(\mathbf{I})$
,
 $\mathbb{P}^{\prime}$
-almost surely. Now applying Theorem 5·1 we deduce that for
 $\mathbb{P}^{\prime}$
-almost surely there is a positive random constant
 $C=C(\omega^{\prime}) \gt 0$
such that
 $$ {}\mathbb{P}\left\{ \exists s\in : (B^H+B^{\delta_{\pmb{\theta_H}}}(\omega^{\prime}))(s)=x \right\}\geq C\, \mathcal{C}_{\rho_{\mathbf{d}_{H}}}^{d}\left(Gr_E\,B^{\delta_{\pmb{\theta_H}}}(\cdot,\omega^{\prime})\right) \gt 0. {}$$
Hence, by choosing f to be one of the trajectories of
 $B^{\delta_{\pmb{\theta_H}}}$
we get the desired result.
Remark 6·7. It is worthwhile mentioning that
 $C^{\mathsf{w}_{H,{\ell_{\theta_H}}}}(\mathbf{I})$
verifies (4·10) as
 ${{\ell_{\theta_H} ({\cdot})}}$
meets the condition (4·9) via assertion (i) of (4·11).
Consequently we have the following outcome:
Corollary 6·8. Let
 $\{B^{H}(t) : t \in [0,1]\}$
be a d-dimensional fractional Brownian motion of Hurst index
 $H\in (0,1)$
. Assume that
 $L_{\pmb{\theta_H}}$
, the normalised slowly varying part of
 $\pmb{\theta_H}$
, satisfies (4·11). Then there exist a Borel set
 $E\subset \mathbf{I}$
, such that
 $$ \dim(E)=Hd \quad \text{ and }\quad \mathcal{H}^{Hd}(E)=0,$$
and a function
 $f\in C^{\mathsf{w}_{H,{\ell_{\theta_H}}}}(\mathbf{I})\setminus C^{H}\left(\mathbf{I}\right)$
, such that all points are non-polar for
 $(B^H+f)\vert_E$
.
Remark 6·9. Similarly to Theorem 4·3, Corollary 6·8 confirms also the sharpness of the Hölder regularity assumption made on the drift f in (6·2).
Proof of Corollary
6·8. (7·6) with
 $\underset{x\rightarrow +\infty}{\liminf} \,L_{\pmb{\theta_H}}(x)=0$
imply that
 $$ \underset{x\rightarrow 0}{\limsup} \,\ell_{\delta_{\pmb{\theta_H}}}(x)= \underset{x\rightarrow 0}{\limsup} \,\ell_{\pmb{\theta_H}}(x)=+\infty. $$
Thus applying once again [
Reference Taylor27
, theorem 4] with the functions
 $h(t)\,:\!=\,t^{H d}$
and
 $\Phi(t)=\Phi_{H,\ell_{\delta_{\pmb{\theta_H}}}}(t)$
we infer that there exists a compact set
 $E\subset \mathbf{I}$
such that
 $$ {}\mathcal{H}^{H d}(E)=0 \quad \text{ and } \quad \mathcal{C}_{\Phi_{H,\ell_{\delta_{\pmb{\theta_H}}}}}(E) \gt 0. {}$$
Finally Proposition 6·6 gives us the function that we are looking for, that is
 $f\in C^{\mathsf{w}_{H,{\ell_{\theta_H}}}}(\mathbf{I})$
for which
 $(B^H+f)\vert_E$
hits all points.
7. Appendixes
7.1. Appendix A
In this section, we would like to investigate existence of a Gaussian process with stationary increments
 $B^{\delta_{\theta}}$
with increments variance
 $\delta_{\theta}({\cdot})$
, we also provides the uniform modulus of continuity for
 $B^{\delta_{\theta}}$
. First, let
 $\alpha \in (0,1)$
and
 $\theta_{\alpha}\,:\,\mathbb{R}_+\rightarrow \mathbb{R}_+$
be a
 $\mathcal{C}^{\infty}$
normalised regularly varying function at infinity with index
 $2\alpha+1$
in the sense of Karamata of the form
 \begin{align}\theta_{\alpha}(x)=x^{2\alpha+1}\, L_{\theta_{\alpha}}(x),\end{align}
with
 $L_{\theta_{\alpha}}({\cdot})$
is the normalised slowly varying part given as follows
 \begin{align}L_{\theta_{\alpha}}(x)=\mathtt{c}_1\exp\left({\displaystyle\int}_{x_0}^x\frac{\varepsilon_{\theta_{\alpha}}(t)}{t}dt\right) \quad \text{for all $x\geq x_0$},\end{align}
and
 $L_{\theta_{\alpha}}(x)=\mathtt{c}_1$
for all
 $x\in (0,x_0)$
, where
 $\mathtt{c}_1$
is a positive constant. It is quite simple to check that
 $$ \varepsilon_{\theta_{\alpha}}(x)=x\,L_{\theta_{\alpha}}^{\prime}(x)/L_{\theta_{\alpha}}(x) \quad \text{for all $x\geq x_0$}.$$
Let
 $\delta_{\theta_{\alpha}}\,:\, \mathbb{R}_+\rightarrow \mathbb{R}_+$
be the continuous function defined by
 \begin{align}\delta^2_{\theta_{\alpha}}(h)\,:\!=\,\frac{2}{\pi}{\displaystyle\int}_{0}^{\infty}(1-\cos(x\,h))\frac{dx}{\theta_{\alpha}(x)}=\frac{4}{\pi}{\displaystyle\int}_{0}^{\infty}\sin^2\left(\frac{x\,h}{2}\right)\frac{dx}{\theta_{\alpha}(x)}.\end{align}
The special properties of the function
 $\theta_{\alpha}$
make it easy to verify that
 $\delta_{\theta_{\alpha}}$
is well-defined. Moreover, it follows from [
Reference Marcus and Rosen20
, theorem 7·3·1] that
 $\delta^2_{\theta_{\alpha}}$
is a normalised regularly varying function at zero with index
 $2\alpha$
such that
 \begin{align}{\delta^2_{\theta_{\alpha}}(h)}\thicksim {h^{2\alpha}\,\ell^2_{\theta_{\alpha}}(h)} \quad \text{ as $h\rightarrow 0$},\end{align}
where
 \begin{align}{\ell_{\theta_{\alpha}}(h)\,:\!=\,\mathtt{c}^{1/2}_{\alpha}\,L^{-1/2}_{\theta_{\alpha}}(1/h)}\quad \text{ and }\quad \mathtt{c}_{\alpha}\,:\!=\,\frac{4}{\pi}{\displaystyle\int}_0^{\infty}\frac{\sin^2 s/2}{s^{2\alpha+1}}ds .\end{align}
Hence
 $\delta_{\theta_{\alpha}}$
is normalised regularly varying at zero of index
 $\alpha$
, whence there exists
 $\ell_{\delta_{\theta_{\alpha}}}\,:\,(0,1]\rightarrow \mathbb{R}_+$
be normalised slowly varying at zero such that
 $\delta_{\theta_{\alpha}}(h)=h^{\alpha}\,\ell_{\delta_{\theta_{\alpha}}}(h)=\mathsf{v}_{\alpha,\ell_{\delta_{\theta_{\alpha}}}}(h)$
for all
 $h\in [0,1]$
. Therefore (7·4) ensures that
 \begin{align}\quad \ell_{\delta_{\theta_{\alpha}}}(h) \thicksim \ell_{\theta_{\alpha}}(h)=\mathsf{c}_{\alpha}^{1/2} L_{\theta_{\alpha}}^{-1/2}(1/h)\quad \text{as $h \rightarrow 0$}.\end{align}
In the following, we give a method for constructing real Gaussian centered processes with stationary increments such that their increments variance are given by
 $\delta_{\theta_{\alpha}}^2$
.
Proposition 7·1. Let
 $\alpha \in (0,1)$
and
 $\theta_{\alpha}$
be the normalised regularly varying function given in (7·1). Then there exists a one-dimensional centered Gaussian process
 $B_0^{\delta_{\theta_{\alpha}}}$
on
 $\mathbb{R}_+$
such that for all
 \begin{align} {}\delta_{\theta_{\alpha}}^2(h)=\mathbb{E}\left(B_0^{\delta_{\theta_{\alpha}}}(t+h)-B_0^{\delta_{\theta_{\alpha}}}(t)\right)^2 \quad \text{ for all t}\ \geq 0\ and\ h\ \geq 0.\end{align}
Proof. First, let
 $\mu$
be the measure on
 ${\mathbb{R}}_{+}$
defined by
 $\mu(dx)=\left(\pi \theta_{\alpha}(x)\right)^{-1}\textbf{1}_{{\mathbb{R}}_+}(x)\,dx$
. Let
 $\mathcal{W}_1$
and
 $\mathcal{W}_2$
be two independent Brownian motion on
 ${\mathbb{R}}_{+}$
. Now we consider the Gaussian processes
 $B_0^{\delta_{\theta_{\alpha}}}$
represented as follows
 \begin{align} {}B^{\delta_{\theta_{\alpha}}}_0(t)\,:\!=\,{\displaystyle\int}_0^{\infty}\frac{(1-\cos xt )}{\left(\pi\,\theta_{\alpha}(x)\right)^{1/2}}\,\mathcal{W}_1(dx)+{\displaystyle\int}_0^{\infty} \frac{\sin xt}{\left(\pi\,\theta_{\alpha}(x)\right)^{1/2}}\,\mathcal{W}_2(dx).\end{align}
A simple calculation gives
 \begin{align} {}\mathbb{E}\left[(B^{\delta_{\theta_{\alpha}}}_0(t+h)-B^{\delta_{\theta_{\alpha}}}_0(t))\right]^2=2{\displaystyle\int}_{0}^{\infty}(1-\cos(x\,h))\mu(dx)=\delta^2_{\theta_{\alpha}}(h).\end{align}
Using (7·4) we get the following useful estimates helping us to provide uniform modulus of continuity of
 $B^{\delta_{\theta_{\alpha}}}$
: there exist
 $h_0 \gt 0$
and a constant
 $q\geq 1$
such that
 \begin{align}q^{-1}\,h^{2\alpha}\,{\ell_{\theta_{\alpha}}^2(h)} \leq \mathbb{E}\left[B^{\delta_{\theta_{\alpha}}}_0(t+h)-B^{\delta_{\theta_{\alpha}}}_0(t)\right]^2\leq q\,h^{2\alpha}\,{\ell_{\theta_{\alpha}}^2(h)},\end{align}
for all
 $t\in {\mathbb{R}}_+$
and
 $h\in [0,h_0)$
.
Notice that, due to (7·10), all results of our interest are not sensitive to changing
 $\ell_{\delta_{\theta_{\alpha}}}$
by
 $\ell_{\theta_{\alpha}}$
. On the other hand, using
 $\ell_{\theta_{\alpha}}$
instead of
 $\ell_{\delta_{\theta_{\alpha}}}$
is especially important when the regularity condition (4·11) on
 $L_{\theta}({\cdot})$
is needed. Such condition leads to (4·6) for
 $\ell_{\theta}({\cdot})$
, which is required for Lemma 4·1. The following result is about the uniform modulu of continuity of the Gaussian process
 $B^{\delta_{\theta_{\alpha}}}$
Theorem 7·2. Let
 $B^{\delta_{\theta_{\alpha}}}\,:\!=\,(B^{\delta_{\theta_{\alpha}}}_1(t),....,B^{\delta_{\theta_{\alpha}}}_d(t))$
be a d-dimensional Gaussian process, where
 $B^{\delta_{\theta_{\alpha}}}_1,...,B^{\delta_{\theta_{\alpha}}}_d$
are d independent copies of
 $B^{\delta_{\theta_{\alpha}}}_0$
. Let
 $\,0 \lt a \lt b \lt 1$
and
 $\mathbf{I}\,:\!=\,[a,b]$
. Then
 $B^{\delta_{\theta_{\alpha}}}\in C^{\mathsf{w}_{{\alpha,{\ell_{\theta_{\alpha}}}}}}(\mathbf{I})$
a.s. with
 $\mathsf{w}_{\alpha,{\ell_{\theta_{\alpha}}}}$
defined by
 \begin{align} {}\mathsf{w}_{{\alpha,{\ell_{\theta_{\alpha}}}}}(r)\,:\!=\,\,r^{\alpha}\,{\ell_{\theta_{\alpha}}(r)}\log^{1/2}(1/r).\end{align}
In other words, there is an almost sure finite random variable
 $\eta=\eta(\omega)$
, such that for almost all
 $\omega \in \Omega$
and for all
 $0 \lt r\leq \eta(\omega)$
, we have
 \begin{align} {}\underset{\substack{s,t \in \mathbf{I}\\ |t-s|\leq r}}{\sup}\left\lVert B^{\delta_{\theta_{\alpha}}}(t)-B^{\delta_{\theta_{\alpha}}}(s)\right\rVert \leq \,\mathtt{c}_1\, \mathsf{w}_{\alpha,{\ell_{\theta_{\alpha}}}}(r),\end{align}
where
 $\mathtt{c}_1$
is a universal positive constant.
Proof. First, we start by considering the function
 \begin{align} {}\widetilde{\mathsf{w}}_{\alpha,{\ell_{\theta_{\alpha}}}}(r)= r^{\alpha}\,{\ell_{\theta_{\alpha}}(r)}\,\log^{1/2}(1/r)\,+{\displaystyle\int}_0^r \frac{u^{\alpha}\,{\ell_{\theta_{\alpha}}(u)}}{u[\log 1 / u]^{1 / 2}} d u.\end{align}
It is simple to verify that
 $\widetilde{\mathsf{w}}_{\alpha,{\ell_{\theta_{\alpha}}}}({\cdot})$
is well defined in a neighbourhood of zero with
 $\lim_{r\rightarrow 0} \widetilde{\mathsf{w}}_{\alpha,{\ell_{\theta_{\alpha}}}}(r)=0$
. Since
 $B^{\delta_{\theta_{\alpha}}}$
satisfies (7·10), then it follows from [
Reference Marcus and Rosen20
, theorem 7·2·1, p. 304] that
 $\widetilde{\mathsf{w}}_{{\alpha,{\ell_{\theta_{\alpha}}}}}({\cdot})$
is a uniform modulus of continuity of
 $B^{\delta_{\theta_{\alpha}}}$
. That is there exists a constant
 $\mathtt{c}_{2} \geq 0$
such that
 \begin{align} {}\limsup_{\eta \rightarrow 0} \sup _{\substack{|u-v| \leq \eta \\ u, v \in I}} \frac{\lVert B^{\delta_{\theta_{\alpha}}}(u)-B^{\delta_{\theta_{\alpha}}}(v)\rVert}{{\widetilde{\mathsf{w}}_{\alpha,{\ell_{\theta_H}}}}(\eta)} \leq \mathtt{c}_{2} \quad a . s .\end{align}
Hence there exists an almost surely positive random variable
 $\eta_0$
such that for all
 $0 \lt \eta \lt \eta_0$
, we have
 \begin{align} {}\sup _{\substack{|u-v| \leq \eta \\ u, v \in I}} \left\lVert B^{\delta_{\theta_{\alpha}}}(u)-B^{\delta_{\theta_{\alpha}}}(v)\right\rVert \leq \mathtt{c}_{2}\, \widetilde{\mathsf{w}}_{\alpha,{\ell_{\theta_H}}}(\eta).\end{align}
The presence of an integral in (7·13) suggests that the modulus of continuity is artificial, which leads to seek a simpler and more practical one. So it is easy to check, by using Hopital’s rule argument, that
 $$ {\displaystyle\int}_0^r \frac{u^{\alpha}\,{\ell_{\theta_H}(u)}}{u(\log 1 / u)^{1 / 2}} d u= o\left( r^{\alpha}\,{\ell_{\theta_H}(r)} \right).$$
Therefore there exists
 $r_0 \gt 0$
such that
 $$ \widetilde{\mathsf{w}}_{\alpha,L^{-1/2}_{\theta_{\alpha}}(1/\cdot)}(r)\leq 2\,r^{\alpha}\,{\ell_{\theta_H}(r)}\,\log^{1/2}(1/r)=2\, \mathsf{w}_{\alpha,{\ell_{\theta_H}}}(r)\quad \text{ for all} r \lt r_0.$$
Hence using this fact and (7·15), we obtain that almost surely
 \begin{equation*} {}\sup _{\substack{u, v \in \mathbf{I} \\ |u-v| \leq \eta }} \left\lVert B^{\delta_{\theta_{\alpha}}}(u)-B^{\delta_{\theta_{\alpha}}}(v)\right\rVert \leq 2\,\mathtt{c}_{2}\,\mathsf{w}_{\alpha,{\ell_{\theta_H}}}(\eta) \quad \text{ for all $\eta \lt \eta_0 \wedge r_0$},\end{equation*}
which completes the proof.
Remark 7·3. It is noteworthy that (7·4) ensures
 $C^{\mathsf{w}_{\delta_{\theta_{\alpha}}}}(\mathbf{I}) \equiv C^{\mathsf{w}_{\alpha,{\ell_{\theta_H}}}}(\mathbf{I})$
, where
 $\mathsf{w}_{\delta_{\theta_{\alpha}}}({\cdot})=\delta_{\theta_{\alpha}}({\cdot})\ log^{1/2}(1/\cdot)$
.
7.2. Appendix B
Our aims here are twofold: first, to provide a proof of Lemma 2·3, and second, to present examples of probability measures
 $\nu_1$
and
 $\nu_2$
supported on two Borel sets
 $E_1$
and
 $E_2$
respectively, and satisfying (6·3) and (6·4).
Proof of Lemma
2·3. Without loss of generality we can assume that
 $\mathrm{diam}(\mathscr{X})=1$
. Three cases need to be discussed here: (i)
 $\theta \lt \kappa$
, (ii)
 $\theta = \kappa$
and (iii)
 $\theta \gt \kappa$
. For the first case
 $\theta \lt \kappa$
, we have to show only that
 $$ \underset{r\in (0,1)}{\sup}I(r) \lt \infty.$$
Indeed, for any
 $v\in X$
we have
 \begin{align*} \int_{\mathscr{X}} \frac{\mu(du)}{\left(\max\{\rho(u,v),r\}\right)^{\theta}}&\leq \int_{\mathscr{X}}\frac{\mu(du)}{\rho(u,v)^{\theta}}=\sum_{j=1}^{\infty}\int_{\{u:\rho(u,v)\in (2^{-j},2^{-j+1}]\}}\frac{\mu(du)}{\rho(u,v)^{\theta}}\\ &\leq \sum_{j=1}^{\infty}2^{j\theta}\mu\left(B_{\rho}(v,2^{-j+1})\right)\leq C_1\,2^{\kappa} \sum_{j=1 }^{\infty}2^{-j(\kappa-\theta)} \lt \infty. \end{align*}
Now for
 $\theta\geq \kappa$
, we have first
 $$ I(r)\leq \underset{\,:\!=\,I_1(r)}{\underbrace{\sup_{v\in \mathscr{X}}\int_{\{u: \rho(u,v) \lt r \}}\frac{\mu(du)}{r^{\theta}}}} + \underset{\,:\!=\,I_2(r)}{\underbrace{\sup_{v\in \mathscr{X}}\int_{\{u:\rho(u,v)\geq r\}}\frac{\mu(du)}{\rho(u,v)^{\theta}}}} $$
with
 $r\in \left(0,1\right)$
. By using (2.12) we get
 \begin{align} I_1(r)\leq C_1\, r^{\kappa-\theta}. \end{align}
For estimating
 $I_2(r)$
, we set
 $j(r)\,:\!=\,\inf\{j\,:\, 2^{-j}\leq r\}$
. Then we have
 \begin{align} \{u:\rho(u,v)\geq r\}\subset \bigcup_{j=1}^{j(r)}\{u:2^{-j}\leq \rho(u,v) \lt 2^{-j+1}\}. \end{align}
Simple calculations and (2.12) ensures that for any
 $v\in \mathscr{X}$
we have
 \begin{align} \int_{\{u:\rho(u,v)\geq r\}}\frac{\mu(du)}{\rho(u,v)^{\theta}}&\leq \sum_{j=1}^{j(r)}2^{j\,\theta}\mu\left(\{u: 2^{-j}\leq \rho(u,v) \lt 2^{-j+1}\}\right)\nonumber\\ &\leq C_1\, 2^{\kappa}\sum_{j=1}^{j(r)}2^{j(\theta-\kappa)}. \end{align}
It follows from the definition of j(r) that
 $2^{-j(r)}\leq r \lt 2^{-j(r)+1}$
. Then, for
 $\theta=\kappa$
we get easily that
 \begin{align} I_1(r)\leq C_1 \quad \text{ and } \quad I_2(r)\leq C_3\,\log(e/r)=C_3\,\varphi_{\theta-\kappa}(r). \end{align}
Hence we get the desired estimation for the case (ii). For the last case
 $\theta \gt \kappa$
, we use a comparison with a geometric sum in (7·18) to obtain
 \begin{align} I_2(r)\leq C_4\, r^{\kappa-\theta}. \end{align}
Putting (7·16) and (7·20) all together, the estimation (2·13) follows.
For the second aim, let
 $\varphi$
be a continuous increasing function on
 $\mathbb{R}_+$
, such that
 \begin{align}\varphi(0)=0\quad \text{and} \quad \varphi(2x) \lt 2\varphi(x)\quad \text{for all $x\in (0,x_0)$},\end{align}
for some
 $x_0\in (0,1)$
. Our aims is to construct a Cantor type set
 $E_{\varphi}\subset (0,x_0)$
which support a probability measure
 $\nu_{\varphi}$
with the property
 $\nu_{\varphi}([a-r,a+r])\asymp \varphi(r)$
.
Proposition 7·4. Let
 $\varphi$
be a function satisfying (7·21). Then there exists a Borel set
 $E_{\varphi}\subset [0,x_0]$
which support a probability measure
 $\nu$
such that
 \begin{align} {}c_1^{-1}\,\varphi(r)\leq \nu([a-r,a+r])\leq c_1\,\varphi(r) \quad \text{for all} \, r\in [0,x_0] \, \text{and} \, a\in E_{\varphi}.\end{align}
Proof. We will construct a compact set
 $E_{\varphi}$
inductively as follows: Let
 $I_0\subset [0,x_0)$
be a closed interval of length
 ${l}_0 \lt x_0$
. First, let
 $l_1\,:\!=\,\varphi^{-1}\left(\varphi(l_0)2^{-1}\right)$
, and let
 $I_{1,1}$
and
 $I_{1,2}$
two subintervals of
 $I_0$
with length
 $l_1$
. For
 $k\geq 2$
, we construct inductively a family of intervals
 $\{I_{k,j}\,:\,j=1,...,2^{k}\}$
, in the following way: let
 $l_k\,:\!=\,\varphi^{-1}\left(\varphi(l_0)2^{-k}\right)$
and the intervals
 $I_{k,1},...,I_{k,2^k}$
are constructed by keeping two intervals of length
 $l_k\,$
from each interval
 $I_{k-1,i}$
 $i=1,\ldots,2^{k-1}$
of the previous iteration. We define
 $E_{\varphi,k}$
to be the union of the intervals
 $\left(I_{k,j}\right)_{j=1,...,2^k}$
of each iteration. The compact set
 $E_{\varphi}$
is defined to be the limit set of this construction, namely
 \begin{align} {} {}E_{\varphi}\,:\!=\,\bigcap_{k=1}^{\infty}E_{\varphi,k}. {}\end{align}
Now we define a probability measure
 $\nu$
on
 $E_{\varphi}$
, by the mass distribution principle [
Reference Falconer11
]. Indeed, for any
 $k\geq 1$
let us define
 \begin{align} {} {}\nu(I_{k,i})=2^{-k} \quad \text{ for $i=1,\ldots,2^k$} {}\end{align}
and
 $\nu\left([0,1] \setminus E_{\varphi,k}\right)=0$
. Then by [
Reference Falconer11
, proposition 1·7],
 $\nu$
is a probability measure supported on
 $E_{\varphi}$
. For
 $a\in E_{\varphi}$
and
 $0 \lt \eta \lt \varphi(l_0)$
small enough. Let k be the smallest integer such that
 $\varphi(l_0)\,2^{-(k+1)} \lt \eta\leq \varphi(l_0)\,2^{-k}$
, then it is not hard to check that the interval
 $[a-\varphi^{-1}(\eta),a+\varphi^{-1}(\eta)]$
intersects at most 3 intervals
 $I_{k,i}$
, and contains at least one interval
 $I_{k+1,j}$
. Therefore, using (7.24) we obtain
 \begin{align} {} {}(1/2\varphi(l_0))\,\eta {} {} {} {}\leq\nu\left([a-\varphi^{-1}(\eta),a+\varphi^{-1}(\eta)]\right)\leq {} {}(6/\varphi(l_0))\,\eta. {}\end{align}
By making a change of variable
 $r\,:\!=\,\varphi^{-1}(\eta)$
, we get the desired result.
Now, we can remark that examples of measures
 ${\nu}_1$
and
 $\nu_2$
satifying (6·3) and (6·4) respectively, could be deduced from Proposition 7.4 with the functions
 $\varphi_1(r)\,:\!=\,r^{\alpha}\,\log^{\beta}(e/r)$
and
 $\varphi_2(r)\,:\!=\,r^{\alpha}\,\log^{-\beta}(e/r)$
for
 $\alpha \in (0,1)$
and
 $\beta \gt 1$
.
Acknowledgements
We would like to thank the two anonymous referees for their thorough review of the manuscript and their valuable feedback. We are particularly grateful to one of them for pointing out references [ Reference Evans10 , Reference Graversen12 , Reference Mountford22 ], which represent some of the earliest work on the polarity of points and functions for planar Brownian motion and one-dimensional stable processes.



