

I. Introduction
There is considerable disagreement about how taxes, especially high marginal tax rates on those with high incomes, influence economic performance and the distribution of income. This essay uses cross-country data on changes in marginal tax rates since 1980 to examine this topic. Section II uses economic theory to analyze the linkage between marginal tax rates and economic performance and considers a number of factors that complicate the measurement of that impact. Section III presents data on the top marginal tax rates during 1980–2002 for seventy-seven countries with a personal income tax and analyzes how changes in these rates influenced economic growth during 1990–2002. Section IV focuses on how reductions in marginal tax rates, particularly the highest rates, influence income inequality and the share of the personal income tax paid by various income groups. The final section summarizes the findings of this study.
II. Marginal Tax Rates and Economic Performance
From an economic viewpoint, marginal tax rates are considered particularly important because they affect the incentives of individuals to earn additional income. As marginal tax rates rise, individuals get to keep less and less of their additional earnings.
High marginal tax rates influence economic performance in at least three major ways. First, high marginal rates discourage work effort. As taxes reduce the amount of additional earnings that one is permitted to keep, individuals tend to work and earn less. People will adjust in various ways. Some—for example, those with a working spouse—may drop out of the labor force. Others will respond by working fewer hours per week, perhaps by quitting a second job. Still others will decide to take more lengthy vacations, forgo overtime opportunities, retire earlier, or forget about pursuing that promising but risky business venture. In some cases, high tax rates will even drive highly productive citizens to other countries where taxes are lower. For example, when the incomes of athletes, skilled professionals, and business entrepreneurs are not country-dependent, such people often relocate from high-tax to low-tax countries.
Second, high marginal tax rates distort price signals and encourage individuals to substitute less-desired but tax-deductible goods for nondeductible ones that are more desired. Goods and services may be tax-deductible either as the result of the design of the tax structure or because they appear as a legitimate business expense. In both cases, the personal costs of purchasing the deductible items will be lower than both society's cost of supplying the items and the cost of purchasing nondeductible goods of similar price. The high marginal rates have an unintended secondary effect that is often overlooked: they make tax-deductible items cheap for those confronting the high rates. The higher an individual's effective marginal tax rate, the lower the personal cost of the deductible item. This incentive structure accompanying high marginal rates will induce persons in high-tax brackets to spend excessively on plush offices, professional conferences held in favorite vacation spots, business entertainment, luxury cars used for business purposes, and numerous other deductible items. Those in high tax brackets will often purchase such items even when they are valued less than their production costs. Scarce resources are wasted producing goods that are not valued as much as other things that could have been produced and, as a result, living standards will fall short of their potential.
Third, high tax rates will reduce the incentives of people to invest in both physical and human capital. When tax rates are high, foreign investors will look for other places to put their money, and domestic investors will look for investment projects abroad where taxes are lower. High marginal rates will also reduce the incentive to invest in education and skill development. After all, high tax rates mean that investors in human capital, like their physical-capital counterparts, are unable to capture a substantial share of the returns from their investment. Furthermore, domestic investors will direct more of their investments into hobby businesses (like collecting antiques, raising horses, or giving golf lessons) that may not earn much money but are enjoyable and have tax-shelter advantages. This too, will divert resources away from projects with higher rates of return but fewer tax-avoidance benefits. Again, scarce capital will be wasted and resources channeled away from their most productive uses.
In summary, theory indicates that high marginal tax rates will reduce the supply of both labor and capital, and will adversely affect the efficiency of resource use. These negative side-effects are likely to be particularly strong when marginal tax rates are exceedingly high. Thus, one would expect countries with high marginal tax rates to grow less rapidly and fail to realize their full potential. Similarly, one would expect that reductions in marginal tax rates would enhance economic growth. This is particularly true if the initial marginal rates are quite high, say 50 percent or more.
While theory predicts that there will be a negative relationship between marginal tax rates and the growth rate of an economy, it also suggests several factors that will complicate measurement of the linkage. First, there is the difference between the short-run and long-run response to a change in marginal rates. To the extent that an increase in marginal tax rates reduces the supply of labor and capital, it will tend to slow the growth of real gross domestic product (GDP). These responses will take time, however, and the short-run response may be a misleading indicator of what will happen in the long run. Clearly, the labor supply response will generally be smaller in the short run than in the long run. For example, most people who have previously trained and developed skills for a career of market work are likely to remain in the labor force even if higher marginal tax rates substantially reduce the return from their prior investment. Thus, the short-run labor supply response to a change in marginal tax rates is likely to be small. This is consistent with the empirical findings. Most studies of this topic estimate that the elasticity of labor supply is between 0.1 and 0.2.1
The elasticity of labor supply is equal to the percent change in the number of hours worked divided by the percent change in the wage rate. Thus, if a 10 percent reduction in wages led to a 1 percent reduction in hours worked, the elasticity of labor supply would be 0.1 (1 percent divided by 10 percent). For empirical estimates of the elasticity of labor supply, see Thomas MaCurdy, David Green, and Harry Paarsch, “Assessing Empirical Approaches for Analyzing Taxes and Labor Supply,” Journal of Human Resources 25 (Summer 1990): 415–490; Robert Triest, “The Effects of Income Tax Deductions on Labor Supply When Deductions are Endogenous,” Review of Economics and Statistics 74 (January 1992): 91–99; and Thomas J. Kniesner and James P. Ziliak, The Effects of Recent Tax Reforms on Labor Supply (Washington, DC: American Enterprise Institute, 1998).
In the long run, however, the labor supply response will be larger, perhaps substantially larger. As a result of the high marginal rates, future labor force participants have less incentive to invest and acquire the education and training required for high-paying jobs, particularly if those jobs are stressful and difficult to perform. In contrast, people have more incentive to prepare for jobs that are interesting and provide substantial nonpecuniary, and therefore untaxed, benefits. With time, adjustments of this type will tend to reduce the quality and productivity of the labor force by larger and larger amounts. But they are likely to take a decade or more and, as a result, a lengthy period will pass before the full labor supply response will be observed. The recent work of economist Edward Prescott, the 2004 Nobel Prize winner, indicates that the long-run negative impact of higher tax rates on labor supply is substantially greater than the short-run estimates. Prescott uses marginal tax differences between France and the United States to derive estimates for the labor supply response over lengthy periods. He finds that differences in marginal tax rates between France and the United States explain nearly all of the 30 percent shortfall of labor inputs in France relative to the United States.2
Prescott concludes: “I find it remarkable that virtually all of the large difference in labor supply between France and the United States is due to differences in tax systems. I expected institutional constraints on the operation of labor markets and the nature of the unemployment benefit system to be more important. I was surprised that the welfare gain from reducing the intratemporal tax wedge is so large.” See Edward C. Prescott, “Richard T. Ely Lecture: Prosperity and Depression,” American Economic Review, Papers and Proceedings 92, no. 2 (May 2002): 1–15, at p. 9.
Second, the linkage between marginal tax rates and GDP growth may be weakened because GDP figures will often fail to register the negative impact of the price distortions accompanying high marginal tax rates. GDP registers the expenditures and costs of the goods and services produced even if these costs exceed the value derived by the consumer. If taxpayers purchase deductible items that they value less than their cost because their personal cost is low, the full costs of such items will nonetheless be added to GDP. For example, if a business owner in a 60 percent marginal tax bracket purchases a $50,000 automobile for business-related use, the transaction will add $50,000 to GDP even if the purchaser values it at only $25,000. Because GDP records the costs of production rather than the value to the consumer, both GDP and its growth rate will understate the adverse side-effects of high marginal tax rates.
Third, the linkage between marginal tax rates and GDP growth may also be weakened by the pattern of government expenditures. Several countries impose high marginal tax rates in order to derive revenues that are utilized to subsidize child-care services, retirement benefits, and payments to persons not working. Suppose that a country increases its marginal tax rates in order to subsidize child-care services for working-age parents. While the higher marginal tax rates tend to reduce labor supply, subsidies for child-care services act as an offsetting factor by making it less costly for adults with children to engage in market work. The net effect on labor supply is likely to be small. Further, the policy change will increase the share of child-care services provided by the government (and market suppliers) relative to the share supplied within the household sector. Because the former adds to GDP but the latter does not, the higher taxes that subsidize and provide child-care services may actually increase income as measured by GDP.
Alternatively, suppose that taxes are increased in order to provide more generous benefits to retirees and/or unemployed workers. The more generous retirement benefits would encourage more workers to retire earlier, and the more generous unemployment benefits would lead to more lengthy periods of job search and higher rates of unemployment. Both of these expenditures would tend to reduce the effective supply of labor and thereby reinforce the impact of the higher marginal tax rates. In contrast with the expenditures on child-care services, these expenditures would tend to amplify the negative relationship between higher marginal tax rates and the quantity of labor supplied. Thus, variations in the pattern of expenditures accompanying differences in marginal tax rates will also influence both labor supply and the expected impact on the growth rate of income as measured by real GDP.
The impact of marginal tax rates will be greatest in the highest tax brackets. It is in the high tax brackets where changes in tax rates will exert their largest effects on both labor supply and tax-avoidance activities. Furthermore, as the Laffer curve analysis indicates, marginal tax rates can be pushed so high that they will actually reduce the revenues derived from the tax.3
The Laffer curve is used to show that increases in tax rates will, after a point, result in reduced tax revenues. See James M. Buchanan and Dwight R. Lee, “Politics, Time, and the Laffer Curve,” Journal of Political Economy 90, no. 4 (1982): 816–19; and James M. Buchanan and Dwight R. Lee, “Tax Rates and Tax Revenues in Political Equilibrium: Some Simple Analytics,” Economic Inquiry 20, no. 3 (1982): 344–54.
III. Changes in Top Marginal Tax Rates and Economic Growth
A. Marginal tax rates, 1980–2002
We have collected data for seventy-seven countries that levied a personal income tax throughout 1980–2002.4
The original source of the marginal tax rate data is Price Waterhouse Coopers, Individual Taxes: A Worldwide Summary (Hoboken, NJ: John Wiley and Sons, various years). The top marginal tax rates reported here include rates that apply at the subnational level if applicable.
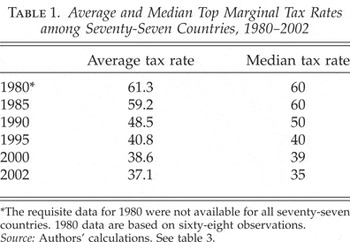
Average and Median Top Marginal Tax Rates among Seventy-Seven Countries, 1980–2002

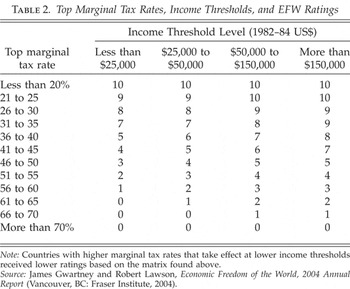
High marginal tax rates will exert less impact on economic performance if they apply only at extremely high levels of income.5
The data for the United States illustrate why it is important to consider both the top rate and the income threshold at which it applies. The top marginal tax rate and the income threshold at which it begins to apply (in both current and 2004 dollars) are shown below for the United States for various years since 1963. Note that in 1963 the top marginal rate in the U.S. was 91 percent, but that rate only applied to incomes in excess of $2.46 million (measured in terms of 2004 prices). Thus, very few people confronted this rate. The top rate was cut to 70 percent by 1965, where it remained until 1980. By 1980, the income threshold for the top rate was much lower (about $494,000 in terms of 2004 prices), and far more taxpayers faced the top rate than in the early 1960s. A lower top marginal rate can be more restrictive than a higher one if the lower rate begins to apply at a substantially lower income threshold.

James Gwartney and Robert Lawson, Economic Freedom of the World, 2004 Annual Report (Vancouver, BC: Fraser Institute, 2004). Initially published in 1995, this report presents data on thirty-eight different variables designed to measure the consistency of a nation's institutions and policies with economic freedom. The report covers over 120 countries.
Top Marginal Tax Rates, Income Thresholds, and EFW Ratings

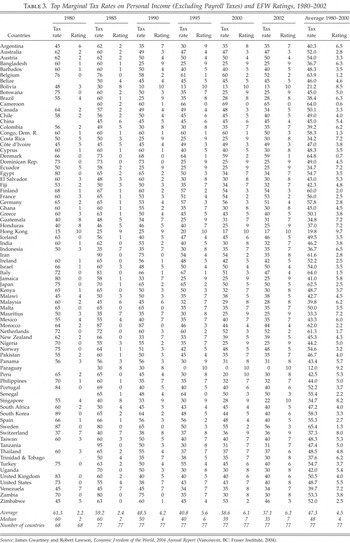
Top Marginal Tax Rates on Personal Income (Excluding Payroll Taxes) and EFW Ratings, 1980–2002

B. Changes in tax rates and growth
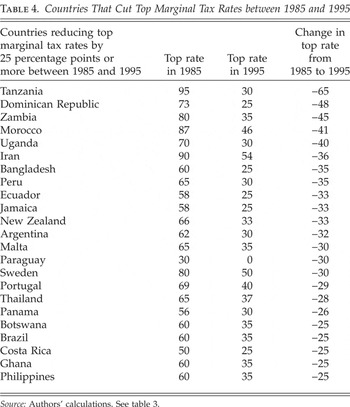
The dramatic changes in the highest marginal tax rates during the last two decades provide something like a natural experiment. Some countries maintained top marginal rates at high levels during the 1980s and most of the 1990s. For example, Austria, Denmark, France, Finland, Germany, Italy, Japan, and the Netherlands made only modest rate reductions while maintaining top marginal rates of 50 percent or more throughout the 1980–1995 period. In contrast, other countries made substantial reductions in their top marginal rates during this period. Table 4 provides a list of the countries that reduced their top marginal rates by 25 percentage points or more between 1985 and 1995. With the exceptions of Iran, Morocco, and Sweden, all of these countries had top marginal rates of 40 percent or less in 1995. This list of major tax cutters is highly diverse. It includes countries from all regions of the world. It includes low-income developing countries such as Tanzania, Zambia, and Bangladesh, as well as high-income industrial countries like New Zealand and Sweden. In some cases, the economies of the tax cutters had high growth rates prior to 1985. Botswana and Thailand provide examples. In other cases, like Peru, Ecuador, and Ghana, the top rates were slashed against a backdrop of dismal economic performance.
Countries That Cut Top Marginal Tax Rates between 1985 and 1995

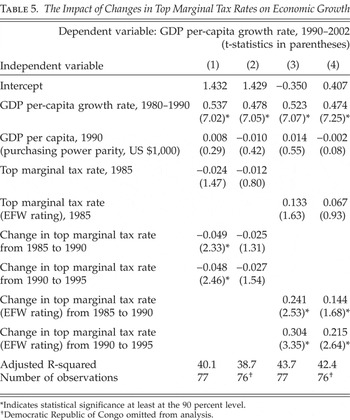
If marginal tax rates impact growth, countries that reduce their marginal rates should grow more rapidly than those that do not. Table 5 uses regression analysis to investigate the linkage between changes in top marginal rates and economic growth for all of the seventy-seven countries with a personal income tax. The dependent variable is the growth rate of real per-capita GDP during 1990–2002. Growth of real per-capita GDP during the 1980s, per-capita GDP at the beginning of the period, and the initial top marginal tax rate (or the EFW marginal tax rating equivalent) are included in the model as control variables.
The Impact of Changes in Top Marginal Tax Rates on Economic Growth

The inclusion of the variable for growth during the 1980s is particularly important. It should capture many of the key institutional and cultural factors that influence cross-country differences in long-term growth. To put this another way, factors like political stability, an evenhanded legal system, a well-educated and highly skilled labor force, and sound monetary, financial, and trade institutions that resulted in strong growth during the 1980s are also likely to exert a positive impact on growth during the 1990s. Correspondingly, institutional and cultural factors that resulted in weak growth during the 1980s will also tend to retard growth during the 1990s.7
Other researchers have used similar techniques in an effort to hold other things constant. For example, when analyzing the impact of changes in the top state income tax rates on income growth, Holcombe and Lacombe compared the growth of per-capita income in counties on state borders with income growth in adjacent counties across the state border. This border-matching technique made it possible for them to hold constant many factors such as climate, culture, and proximity to markets that might also influence the growth of income. Their findings indicate that over the thirty-year period from 1960 to 1990, states that raised their top income tax rates more than their neighbors had slower income growth and, on average, a 3.4 percent reduction in per-capita income. See Randall G. Holcombe and Donald J. Lacombe, “The Effect of State Income Taxation on Per Capita Income Growth,” Public Finance Review 32, no. 3 (May 2004): 292–312.
A t-ratio is a statistic that allows one to estimate the probability that a statistical result has simply occurred by chance. A “high” t-statistic indicates a low probability (p-value) that a given result is by chance, and, in such a case, the result is said to be “statistically significant.” How high the t-statistic has to be is somewhat subjective, but t-ratios with corresponding p-values under 10 percent are generally considered statistically significant. A t-ratio of 7.0 (given the sample size in the model) would correspond with a p-value of essentially zero—meaning we are virtually certain that the result is not the product of chance alone.
In this section, we are most interested in the variables that reflect changes in marginal tax rates. In regressions 1 and 2 in table 5, these marginal tax rate changes are measured by the percentage point change during 1985–1990 and 1990–1995. In regressions 3 and 4, the change in marginal rates is measured by the change in the EFW marginal tax rating during the same two periods. Because the EFW measure considers both the marginal tax rate and the income level at which the rate applies, it is a more refined measure than the rate change alone. The higher ratings are indicative of lower marginal tax rates (and initial application of high marginal rates at higher income levels), so the rating variables will have positive signs if lower top marginal rates enhance growth.
In regression 1, both the change in the top marginal rate during 1985–1990 and the change during 1990–1995 were negative and significant. Regression 1 implies that, holding the other variables of the model constant, a 10 percentage point reduction in the top marginal rate is associated with approximately a 0.5 percentage point increase in long-term growth. The R-squared implies that the model represented by regression 1 accounts for 40 percent of the variation in the growth rate of GDP among the seventy-seven countries during 1990–2002.
However, an outlier observation for the Democratic Republic of the Congo exerted a strong influence on the regression.9
The average annual growth rate of per-capita GDP for the Democratic Republic of the Congo was minus 2.0 percent during the 1980s and minus 7.2 percent during 1990–2002. The latter figure was, by far, the worst growth record of any country in our study. Because Congo also maintained a high (60 percent) marginal tax rate throughout the period, it exerted a strong impact on the marginal tax rate coefficients of the regression.
Regressions 3 and 4 are identical to 1 and 2 except that the EFW marginal tax rating is substituted for the top marginal rates in the case of both the change variables and the initial (1985) top marginal tax rate. In regression 3, a one-unit increase in the rating between 1985 and 1990 enhances growth during the 1990s by 0.241 percentage points. A one-unit increase in the rating between 1990 and 1995 is associated with a 0.304 percentage point increase in growth during 1990–2002. The substitution of the EFW marginal tax rating, which takes both marginal tax rates and the income threshold at which they begin to apply into account, increases the explanatory power of the model. Nonetheless, Congo continues to exert disproportional influence. In order to avoid misleading results from this source, the model is re-run with the omission of Congo. These results are presented in regression 4. In this regression, both of the changes in the marginal tax ratings (from 1985 to 1990, and from 1990 to 1995) remain statistically significant. A one-point change in the EFW rating reflects a 5 percentage point change in the top marginal tax rate, holding the income level at which the rate applies constant. Thus, the coefficients of 0.144 for the rating change during 1985–1990 and 0.215 for the change during 1990–1995 indicate that a 10 percentage point reduction in a country's top marginal rate increases the annual rate of long-term growth by around 0.3 or 0.4 percentage points. The model represented by regression 4 accounts for 42.4 percent of the variation in growth rates among the seventy-six countries (omitting Congo).10
Neither the initial (1990) per-capita GDP nor the marginal tax rate prior to the change (1985) in marginal rates was significant in this model. To the extent that low per-capita GDP and high marginal tax rates influence growth, the effects would be present in the 1980s as well as the 1990s. Thus, the insignificance of these variables merely indicates that they did not influence growth in the 1990s, over and above their impact on growth during the 1980s.
Clearly, these estimates do not indicate that changes in marginal tax rates are a growth panacea. They do suggest, however, that changes in marginal rates, particularly rates that are exceedingly high, influence the growth rate of an economy. Interestingly, these estimates are in line with the experience of the United Kingdom, the United States, and New Zealand, the three high-income industrial countries that have cut their top rates from the 60 to 70 percent range to 40 percent or less since 1980.11
The United Kingdom and the United States are not included among the countries of table 4 because they had two major tax reductions since 1980 and one of them occurred prior to 1985. The United Kingdom reduced its top rate from 83 percent to 60 percent in 1980 and then sliced it to 40 percent in 1988. The top marginal rate in the United Kingdom has remained at 40 percent since 1988. The United States cut its top rate from 70 percent to 50 percent in 1981, and then reduced it to approximately 30 percent in 1987–1988. The top rate in the U.S. has been both increased and decreased modestly since 1988, but it has remained below 40 percent during all of this period. New Zealand's major tax change occurred during 1988–1989, when the top rate was cut from 66 percent to 33 percent, and the rate has remained below 40 percent since that time.
Of course, our results are subject to the usual limitations accompanying cross-country regression analysis, particularly bias emanating from an inability to control for other factors influencing growth. To the extent that countries reducing their marginal rates between 1985 and 1995 were more likely than the non–tax cutters to adopt other growth-enhancing reforms, the estimates presented here will overstate the impact of the changes in the top tax rates. However, there are also biases in the opposite direction. As we discussed above, real GDP (and its growth rate) will fail to register several of the negative side-effects accompanying high marginal tax rates. This is particularly true of those side-effects associated with price distortions and tax-avoidance activities. Because the estimates presented here use the growth figures for real GDP as a measure of the negative side-effects of high marginal rates, they will understate the negative impact of the high marginal rates.
IV. Marginal Tax Rates, Income Inequality, and Tax Payments
A. Theoretical considerations
Tax cuts are often more or less across-the-board because, from a political viewpoint, rates in the lower income brackets will have to be cut in order to make the cuts in the top brackets politically feasible. Thus, it is important to understand that across-the-board cuts in marginal tax rates will have different incentive effects up and down the income distribution. Suppose that a government with graduated income tax rates ranging from a low of 15 percent to a high of 75 percent reduced tax rates across the board by one-third. The top tax rate would then fall from 75 percent to 50 percent. After the tax cut, taxpayers in the highest tax bracket who earn an additional $100 would get to keep $50 rather than only $25, a 100 percent increase in their take-home wage at the margin. These taxpayers will have a strong incentive to earn more taxable income after the rate reduction, and the revenues collected from them will decline by substantially less than a third. In fact, given the huge increase in their incentive to earn, the revenues collected from taxpayers formerly confronting such high marginal rates may actually increase, an outcome suggested by the Laffer curve.
Meanwhile, the same one-third rate reduction will cut the bottom tax rate only from 15 percent to 10 percent. In this range, the tax cut means that an additional $100 in gross pay increases take-home pay by $90 instead of $85, only a 5.9 percent increase. Because cutting the 15 percent rate to 10 percent exerts only a small effect on the incentive to earn in the lower tax (and lower income) brackets, the incomes of persons in these marginal tax brackets will be largely unchanged. Thus, the taxable income base of persons in the lower tax brackets will not be altered much by the tax cut. Therefore, in contrast with the situation in high tax brackets, tax revenue will decline by almost the same percentage as tax rates in the lowest tax brackets.
The bottom line is that when all rates are cut by approximately the same percentage, the increase in the incentive to earn will be greatest in the upper tax (and income) brackets. There will be two major side-effects of this change in the incentive structure. First, income inequality will increase. Predictably, the incomes of those in the high tax brackets will expand by larger amounts than those in the lower tax brackets. Some of this increase in income will reflect a decline in tax-avoidance activities, and some of it will reflect the substitution of work for leisure. Both will show up as an increase in the observed income of persons in the upper tax and upper income brackets.
Second, a larger share of the income tax will be paid by high-income taxpayers. Because the tax cut will increase the incentive to earn more in high-income brackets than in low-income brackets, taxable income will expand more and the taxes paid will decline less in the upper income brackets. When the top marginal rates are extremely high, taxes collected from the high-income taxpayers may even increase after a tax cut. Even if this is not the case, however, a larger share of the income tax will still be collected from those with high incomes.
B. Marginal tax rates and the distribution of income: Empirical evidence
If our analysis is correct, even across-the-board rate reductions will lead to an increase in income inequality. If the rate reductions are greater in the high tax brackets than in the lower brackets, the expected increase in income inequality will be even greater. Thus, countries that reduce their highest rates by substantial amounts should experience increases in income inequality. Reliable data on the distribution of income are unavailable for many of the seventy-seven countries that comprise the central data base of this study. Furthermore, even when income distribution data are available, there are often serious problems with comparability across countries.12
Several factors reduce the comparability of income distribution data across countries and time periods. Sometimes the underlying figures are based on income, and in other cases they are based on consumption expenditures. Sometimes the income figures are for households, and in other cases they are for individuals. Sometimes the figures are derived from national samples, while in other instances they only reflect figures for urban (or rural) dwellers. Some data are after-tax and some are before-tax. Thus, extreme care must be exercised in this area.
Comparable data are available for the United States both before and after the major personal income tax cuts that have occurred since 1960. Data are also available for other countries, including several that reduced their rates substantially during the 1985–1995 period. These data can be compared with data from countries that have persistently maintained high marginal tax rates. These comparisons will shed light on the relationship between high marginal tax rates and income inequality.
In the United States, the personal income tax is the largest single source of revenue for the federal government. The marginal rate structure of the income tax is progressive; taxpayers with larger incomes face higher marginal and average tax rates. However, the structure of the rates has changed substantially since 1960. In the early 1960s, there were twenty-four marginal tax brackets ranging from a low of 20 percent to a high of 91 percent. The Kennedy-Johnson tax cut was roughly an across-the-board proportional rate reduction. The 91 percent top rate was sliced to 70 percent, and the 20 percent rate was cut to 14 percent. In 1981, the first tax cut of the Reagan years reduced the top rate from 70 percent to 50 percent, and the lowest rate was cut from 14 percent to 10 percent. The second Reagan tax cut sliced the top marginal rate to approximately 30 percent beginning in 1988. The top rate was increased to 33 percent in 1991, and two years later it was increased again to 39.6 percent, but the tax reductions during the administration of George W. Bush rolled the top rate back to 35 percent. Thus, since the late 1980s, Americans with the highest incomes have paid sharply lower top marginal tax rates—rates in the 30 to 40 percent range, compared to top rates of 91 percent in the early 1960s and 70 percent prior to 1981.
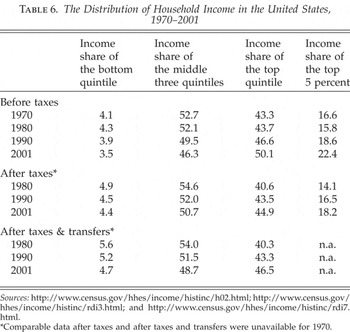
What has happened to the distribution of income in the United States? Table 6 provides income distribution data for the U.S. since 1970 and distributional data after taxes (and after taxes and transfers) since 1980. The distribution of income before taxes and transfer payments (e.g., welfare and Social Security payments) can be very different from the distribution after taxes and transfers. Since the system tends to tax more from higher-income households and give more through transfers to lower-income households, the distribution of income will be more equal after taxes and transfers than before. In 2001, the before-tax income share of the top quintile was approximately fourteen times that of the bottom quintile. After taxes, the ratio of the income share of the top quintile to the share of the bottom quintile was approximately ten to one.
The Distribution of Household Income in the United States, 1970–2001

Second, income inequality in the United States has increased, and most of that increase has taken place since 1980. Between 1970 and 1980, there was little change in the before-tax distribution of income. In fact, the income share of the bottom quintile rose slightly (from 4.1 percent in 1970 to 4.3 percent in 1980), while the share of the top 5 percent of earners declined (from 16.6 percent to 15.8 percent) during the decade. Since 1980, however, the situation has been dramatically different. The income share of the bottom quintile fell from 4.3 percent in 1980 to 3.5 percent in 2001. Over the same period, the income share of the top quintile of earners rose from 43.7 percent to 50.1 percent, an increase of 6.4 percentage points. Furthermore, the increase in the income share of the top group was entirely the result of the higher incomes registered by the top 5 percent of earners. Between 1980 and 2001, the income share of the top 5 percent rose from 15.8 percent to 22.4 percent, an increase of 6.6 percentage points. This increase more than accounts for the larger income share of the top quintile.
The changes in the distribution of income after taxes (and after taxes and transfers) followed a similar path. In both cases, the income share of the bottom quintile declined during the 1980s and 1990s, and the share of the top quintile rose during both decades. Likewise, the growth of income among the top 5 percent of earners accounted for almost all of the increase in the after-tax income share of the top quintile.
The increase in income inequality in the U.S. may have other contributing causes. Other researchers have argued that increased trade openness and/or demographic changes, particularly the increase in the number of both single-parent and dual-earner households, have contributed to the increase in inequality.13
For information on the linkage between trade openness and income inequality, see Gary Burtless, “International Trade and the Rise in Earnings Inequality,” Journal of Economic Literature 33, no. 2 (June 1995): 800–816; and the symposium on “Income Inequality and Trade,” Journal of Economic Perspectives 9, no. 3 (Summer 1995).
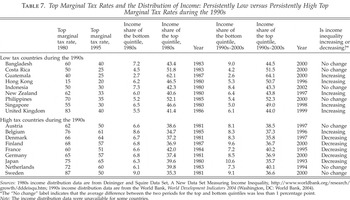
Table 7 presents data on the share of household income derived by the top and bottom quintiles in the 1980s and the 1990s–2000s. These figures are presented for (1) countries with persistently low (40 percent or less) top marginal tax rates during the 1990s and (2) countries with persistently high (50 percent or more) top rates during the 1980s and 1990s.14
All countries in these two categories for which comparable household income distribution data could be obtained are included here.
Top Marginal Tax Rates and the Distribution of Income: Persistently Low versus Persistently High Top Marginal Tax Rates during the 1990s

Two things stand out with regard to the pattern of the data in table 7. First, the income inequality of the countries in the persistently low tax category is greater than for those in the persistently high tax group. In the late 1990s, the income share of the top quintile of earners was 43 percent or more in all of the countries in the low top marginal rate group. In contrast, the income share of the top quintile was between 35 percent and 41 percent for all of the countries in the high tax group.
Second, the general trend appears to be toward more income inequality in the low-tax countries but less inequality in countries with high top marginal rates. Income inequality rose in five of the nine low-tax countries, while the other four experienced no significant change. In contrast, five of the nine high-tax countries registered a reduction in income inequality during the period, and there was no discernible change in three others. An increase in income inequality was observed in only one (Belgium) of the countries in the high-tax group.
From our perspective, the figures for New Zealand and the United Kingdom are particularly interesting. Among the high-income industrial countries, these two countries (along with the United States) made the largest tax cuts during the 1980s. New Zealand reduced its top rate from 66 percent to 33 percent during 1987–1989. In the United Kingdom, the top marginal rate was reduced from 83 percent to 60 percent in 1980 and to 40 percent in 1988, and the lower rate has been maintained ever since. As table 7 shows, the income share derived by the highest quintile of earners increased in both countries. In New Zealand, the income share of the top quintile rose from 40.6 percent in the early 1980s to 43.8 percent in the late 1990s. In the United Kingdom, the share of the top quintile jumped from 41.4 percent in the 1980s to 44 percent in the late 1990s. Like the figures for the U.S., the income distribution data for New Zealand and the United Kingdom indicate that substantial reductions in the highest marginal rates will lead to rapid income growth in the upper income brackets and an increase in the observed income inequality.
We should make one final point about the empirical linkage between lower top tax rates and income inequality: Comparisons of the periods before and after rate reductions will tend to overstate the change in economic inequality. To some extent, the empirical data reflect the fact that the rate reductions increase the visibility of the income of the highest earners. High tax rates encourage tax-avoidance activities that tend to conceal income, broadly defined to include leisure, pleasurable activities, and ability to purchase many goods at a low personal cost. For example, when tax rates are high, those confronting the high rates take more of their “income” in the form of low-cost luxury offices and automobiles, business-related vacations in exotic places, pleasurable hobby business activities, interest on tax-free municipal bonds, and similar activities that conceal their true income. As lower rates make these activities less profitable, those with high incomes shift away from them. As they do so, their money income increases and their overall income becomes more visible. In turn, this makes it look like their overall income has increased by a larger amount than is really the case.
C. Changes in marginal tax rates and the taxes paid by those with high incomes
As we previously discussed, an analysis of the incentive structure associated with tax cuts indicates that a roughly proportional reduction in tax rates will increase both income levels and the share of taxes collected from high-income taxpayers. Because the income base will be more responsive in the upper income brackets, the share of taxes collected from those with high incomes may increase even if their rates are reduced more than proportionally.
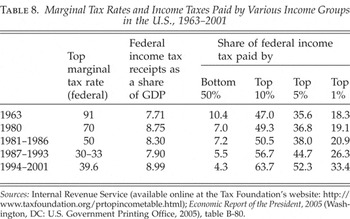
Table 8 provides data related to this proposition for the United States. The share of the personal income tax collected from those with high incomes is indicated for various periods from 1963, when the top federal rate was 91 percent, through 1994–2001, when the top federal rate was 39.6 percent. These data show that the share of the personal income tax paid by high-income Americans has increased substantially since 1963, and the increase has been particularly sharp since 1980. The top 1 percent of earners paid 33.4 percent of the personal income tax during 1994–2001, up from 19.1 percent in 1980 and 18.3 percent in 1963. The top 10 percent of earners paid 63.7 percent of the personal income tax during 1994–2001, compared to 49.3 percent in 1980 and 47 percent in 1963. At the same time, the share of the personal income tax paid by the bottom half of income earners has steadily fallen from 10.4 percent of the total in 1963 to 7 percent in 1980 and just 4.3 percent during 1994–2001. In addition to reducing the highest marginal tax rates, the tax reforms of the 1980s also increased both the standard deduction and personal exemption allowances by substantial amounts. This means that Americans are now able to earn more income before they face any tax liability. In 2001, for example, 30 percent of those filing an income tax return had no tax liability whatsoever.15
Many tax filers actually received funds on net from the IRS as the result of the Earned Income Tax Credit, a program adopted in 1975 that provides a subsidy to the working poor. The tax share data of table 8 reflect only tax liability; they do not include income transfers resulting from tax credits. If these payments to taxpayers were taken into consideration, the net taxes paid by the bottom half of income recipients would have been less than 1 percent in 2002. Thus, the data of table 8 actually understate the reduction in the net share of taxes paid by the bottom half of income recipients during recent decades.
Marginal Tax Rates and Income Taxes Paid by Various Income Groups in the U.S., 1963–2001

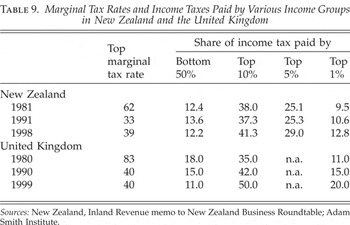
Table 9 presents the share of income taxes collected from high-income earners before and after major cuts in the top marginal rates for New Zealand and the United Kingdom, the two other high-income countries that have substantially reduced their top marginal rates. The pattern for both countries is similar to that of the United States. As the top marginal rate in both countries was reduced from more than 60 percent in the early 1980s to 40 percent or less during the 1990s, the share of income taxes collected from those with high incomes increased. In New Zealand, the top 5 percent of earners paid 29 percent of the personal income tax in 1998, compared to 25.1 percent in 1981. The top 1 percent paid 12.8 percent of the personal income tax in 1998, up from 9.5 percent in 1981. In the United Kingdom, the shift of the tax burden toward those with high incomes was even more dramatic. In 1999, the top 10 percent of earners paid 50 percent of the personal income tax in the United Kingdom, up from 35 percent in 1980. Correspondingly, the share paid by the top 1 percent of income recipients jumped from 11 percent in 1980 to 20 percent in 1999. At the same time, the share of the income tax paid by the bottom half of the income distribution declined substantially from 18 percent in 1980 to 11 percent in 1999.
Marginal Tax Rates and Income Taxes Paid by Various Income Groups in New Zealand and the United Kingdom

The figures for the United States, New Zealand, and the United Kingdom indicate that the income base in high tax brackets—those with marginal rates of 50 percent or more, for example—is highly responsive to rate reductions. As a result, exceedingly high marginal rates can be reduced with little or no loss of revenue. In fact, in extreme cases, more revenue may be collected at the lower rates. In turn, the rapid growth of observed incomes and tax revenues in the upper brackets makes rate reductions for other taxpayers possible. This is precisely what has happened in the United States and the United Kingdom, and to a lesser extent in New Zealand. As the share of the personal income tax paid by those in the upper tax brackets has risen, the share paid by the bottom half of taxpayers has fallen. Perhaps policymakers, at least in these three countries, have found a way to soak the rich: keep their marginal tax rates relatively modest, at 40 percent or less.
V. Conclusion
Our findings indicate that high marginal tax rates, particularly rates of 50 percent or more, exert an adverse impact on long-term economic growth. We estimate that a 10 percentage point reduction in a country's top marginal tax rate will enhance the country's long-term annual growth rate of real GDP by approximately three-tenths of a percentage point.
Economic theory indicates that the incentive effects of a proportional reduction in marginal tax rates will be greatest in the upper income brackets. Therefore, even an across-the-board rate cut will result in larger income increases among those with the highest incomes. Thus, reductions in high marginal tax rates will tend to increase observed income inequality. Our findings are supportive of this view. The income share of the highest group of earners tended to increase following major reductions in the highest marginal tax rates.
However, because of the stronger incentive effects accompanying rate cuts in the upper income and highest tax brackets, across-the-board tax reductions will tend to increase the share of taxes paid by those with the highest incomes and will tend to reduce the share paid by low- and middle-income earners. Even if the rate cuts are greater in the upper brackets, the share of taxes paid by the “rich” may increase. This is even more likely to occur if the rate cuts are also coupled with increases in the personal exemption and/or standard deduction (the income a taxpayer is permitted to earn without a tax liability). The experience of the United States is consistent with this view. Compared to the situation in 1980, when the top marginal tax bracket was 70 percent, the share of the personal income tax paid by those with high incomes has been substantially greater in the United States since 1987, even though the top federal income tax rate has been less than 40 percent throughout the latter period. The records of New Zealand and the United Kingdom, the other two high-income countries that dramatically reduced their highest marginal tax rates in the 1980s, are also supportive of this view. In both cases, the share of the personal income tax paid by those with the highest incomes increased following the lowering of the top rates.
In brief, our findings indicate that high marginal tax rates—rates of 50 percent and above, for example—retard economic growth. Lowering these rates will increase income inequality, but it will also tend to shift the payment of personal income taxes away from low- and middle-income households toward those with the highest incomes.