


1. INTRODUCTION
In classical ruin theory, it is assumed that the surplus process constitutes a random walk. This assumption might not be realistic because serial correlation can be observed in the annual earnings of an insurance company.
In view of this empirical finding, Gerber [2] used an autoregressive (AR) model for the annual earnings. Results for the probability of ruin were obtained. Gerber [3] generalized the results to models with annual earnings being an autoregressive moving average (ARMA) model. In both articles, it was assumed that the adjustment coefficient existed and there was no investment income earned on the existing surplus.
Another way to model the surplus process is to express it in terms of premiums received and claims paid. In a recent article by Yang and Zhang [6] they used two separate series to model premiums received and claims paid. In this article, we consider a model that can be considered as a modification to Gerber's model. The model includes investment income on surplus and uses the technique of martingale theory developed in Yang [5] to obtain the bounds for ruin probability. Note that Yang and Zhang [6] only used the AR(1) process to model both series, so their model is not a generalization of that in Gerber [2,3]. Also, it is assumed that the premium process and the claim process are independent. It is reasonable to assume that using information of both claim and premium series to predict the future value of one series can lower the variance of prediction compared with using only information of one series. We propose to model this by using Granger's causal model. That model includes the possibility of having causality between premium and claim processes in Granger's sense. We also propose to use more general time series models than AR(1). See Granger [4] for details of Granger's causal model. Another justification for using past values of claims that can predict premium better is that, as we know, companies often charge a credibility premium based on the past performance of clients. It is also believed that an increase in premium income might reflect an increase in exposure, which also increases the potential claim amount.
The rest of this article is organized as follows: In Section 2 the framework of the model is presented. In Section 3 we prove results on bounds for ruin probability under models in which both premium and claim processes are moving average (MA) processes. It serves as a building block for a more general model. In Section 4 the results are extended to the Granger's simple causal model. In Section 5 we give some examples. First, we will show that the model of Yang and Zhang [6] is a special case of the new model. Second, we will show that certain credibility models can be described using the new model. Section 6 includes some discussion on this model.
2. THE MODEL
We describe Un, the company's discounted surplus at time n, in the form

where u = U0 is the initial surplus and Gj is the gain of the company in the jth year discounted to the beginning of year j and v = (1 + i)−1 is the discount factor, where i is the 1-year interest rate.
We suppose that

where Xn is the annual premium received in the nth year, Yn is the annual claim paid in the nth year, and ρ1 and ρ2 are factors for discounting the quantities to the beginning of the year.
In Gerber [2,3] it is assumed that i = 0. It is immaterial when the payment is made within a year, so ρ1 = ρ2 = 1. In Yang and Zhang [6], it is assumed that the premium is received at the beginning of the year and the claim is paid at the end of the year, so ρ1 = 1 and ρ2 = v. Since we are considering the aggregate income and expense of an insurance company, it might be better to assume that the premium and the claim arrive at more than one time point throughout a year. If we assume that the premium and the claim are received uniformly and continuously within a year, ρ1 = ρ2 = ρ and

Let

denote the time of ruin. If Ut > 0 for all t, we write T = ∞. We are interested in finding the probability of ruin (i.e.,

).
3. MODELS WITH BOTH CLAIM AND PREMIUM ARE MOVING AVERAGE PROCESSES
In this section we consider the case where both premium and claim processes are moving average processes.


We assume that W1, W2, … are independent and identically distributed random variables having generic random variable

. Z1, Z2, … are independent and identically distributed random variables having generic random variable

. Also, {Wt} and {Zt} are independent for all t. We have to specify the initial values w0,w−1,…,w−p+1,z0,z−1,…, z−q+1. Let


We assume the existence of an adjustment coefficient that is the positive solution, R, of

We need two assumptions on the αi's and βi's.


Condition (10) is assumed so that the derivative of the left-hand side of (9) with respect to R evaluated at R = 0 is negative; this guarantees that the positive solution R exists. Condition (11) is essentially equivalent to the net profit condition

Inequality (12) is a sufficient condition for the ruin probability being less than one. The converse is not true for i > 0 because the insurance company also receives interest as a source of income. For i = 0, conditions (10) and (11) are equivalent. In that case, Ut tends to infinity almost surely when t tends to infinity. For i > 0, we conjecture that Ut will converge to a finite random variable like the case considered in Boogaert, Haezendonck, and Delbaen [1].
Let

be the σ-field generated by {Wi; i = 1,2,…, n} and {Zi; i = 1,2,…, n}; that is,

We have the following results.
Lemma 1:

where

is a

-supermartingale.
Proof:

The inequality in the second to last line follows from Jensen's inequality, as vn−1 ≤ 1 and −xvn−1 is a convex function for x > 0. █
We need one more lemma before giving the main result.
Lemma 2: Let

Then

, is a

-supermartingale.
Proof:

Similarly,

From (1), (2), (17), and (18), we have

rearranging terms, we have

Therefore

which is a constant. Multiplying both sides of (20) by −R and taking the exponential, we have

Since exp{−Rs0} is a constant and

, is a

-supermartingale by Lemma 1, then

, is a

-supermartingale. █
Now we state one of the main results in this article.
Theorem 1:

Proof: By Lemma 2,

, is a

-supermartingale. Let n0 be a positive integer; then T ∧ n0 is a bounded

-stopping time. By Doob's optional stopping theorem,

which implies

Let n0 → ∞; by the monotone convergence theorem,

The ruin probability is a function of p + q + 1 variables: u,w0,w−1,…, w−p+1,z0,z−1,…, z−q+1. Note that equality holds in (15) when i = 0, so
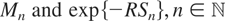
, are martingales. Therefore, it is plausible that equality holds in (23), but we need a stronger condition to facilitate the proof.
Suppose W and Z have finite support; that is,


for some

.
Corollary 1: If (26) and (27) hold in addition to other conditions stated earlier and i = 0,

Proof: Now

, is a

-martingale. Let n0 be a positive integer. Then for all

, similar to (24) we have

Let n0 → ∞; the first term on the right-hand side of (29) converges as earlier by the monotone convergence theorem and the second term converges to zero by the dominated convergence theorem because it is bounded by the constant

We can find conditions other than conditions (26) and (27) such that the second term on the right-hand side of (29) is bounded. For example, if α1,…, αp ≥ 0 and β1,…, βq ≤ 0, X and Z are positive random variables with infinite support. The second term on the right-hand side of (29) is bounded by one. In such cases, Corollary 1 still holds because the dominated convergence theorem can be applied in the proof.
So far we have assumed that p and q are finite. To prove the result in the next section, we need to extend our result to the infinite number of lag terms case. In this case, the number of initial values is still finite because we cannot collect information for infinite periods in reality. We set Wt = Zt = 0 for t less than the earliest time of the available information. Previous results still hold for this case if some further conditions are satisfied. First, we need the following conditions:

We also need (10) and (11) to be satisfied with p and q being replaced by infinity, and we need St to be convergent. Sufficient conditions for this are

and

Conditions (32) and (33) essentially imply (31).
4. GRANGER'S SIMPLE CAUSAL MODEL
Granger [4] proposed a notion of causality in time series models. The use of the causal model attempts to lower the variance of predicted values compared to the models without causality. This model has useful applications because in many real-world economic situations, some economic variables tend to affect the value of other variables. So using past data of several variables to predict the future value of a series might be more accurate than using past data of the variable that we want to predict. In this article we will adopt the bivariate simple causal model to describe the dynamics of the premium process and the claim process.
The premium process {Xt} and the claim process {Yt} can be expressed as


respectively, where W and Z are defined as earlier.
We have specified past data of premium and claim for m years, (i.e., x0,x−1,…, x−m+1,y0,y−1,…, y−m+1).
Let ∪ be the time shift operator (i.e., ∪Xt = Xt−1) and let

Note that all constant terms of polynomials a(x),b(x),c(x), and d(x) are zero. Then (34) and (35) can be expressed in matrix form:

We give some definitions of causality for this model as stated in Granger [4].
Definition: For a bivariate time series model described by (37), we have the following:
- Yt causes Xt provided that b(∪) is not the zero polynomial.
- Xt causes Yt provided that c(∪) is not the zero polynomial.
- There is a feedback relationship between Xt and Yt if both Xt causes Yt and Yt causes Xt.
For the model in Yang and Zhang [6], we have a(∪) = b∪, b(∪) = 0, c(∪) = 0, and d(U) = aU, where 0 < a < 1 and 0 < b < 1. So Xt and Yt do not have causal relationship in Granger's sense. Let


Since the constant term of μ(∪) is always one, A−1 exists and

From (37) and (40) we have


We make some assumptions about the coefficients of a(x), b(x), c(x), and d(x):
1. All of the solutions of the equation μ(x) = 0 lie outside the unit circle of the complex plane.
2.

3.

Since μ(0) = 1 and, by assumption 1, μ(v) > 0 and μ(1) > 0, (44) and (45) are essentially the same as (10) and (11). Let a*(x) and b*(x) have coefficients ak* and bk*, defined as the expansion of partial fractions:


ak* and bk* converge because of assumption 1. Equation (43) becomes

We set Wt = Zt = 0 for t ≤ −m; using (41) and (42), we obtain Xt = Yt = 0 for t ≤ −m. We can uniquely determine w0,w−1,…,w−m+1,z0,z−1,…, z−m+1 from x0,x−1,…, x−m+1,y0,y−1,…, y−m+1 by (34) and (35).
From the expansion of partial fractions in (45) and (46), we can see that ak* and bk* tend to zero exponentially. So (31)–(33) are satisfied.
We can obtain results for ruin probabilities using the result in Section 3 by replacing αk and βk by ak* and bk*, respectively. We can also formulate the result in terms of ak,bk,ck, and dk.
We obtain the adjustment coefficient by (9) with


We also need to express St in terms of ak,bk,ck, and dk. Let Xtd and Ytd be deterministic components of Xt and Yt, respectively. From (34) and (35), we set ak = bk = ck = dk = 0 for k > m, then we have


Observe that

Let


From (51) and (52), we have


From (49), (50), (53), (57), and (58), we have

We obtain the desired expression for s0 in terms of ak, bk, ck, and dk. Let

From the results of Section 3, we have

, is a

-supermartingale and

If (26) and (27) are satisfied and i = 0,

Note that the ruin probability is a function of initial surplus and past values of the premium and claim.
5. EXAMPLES
5.1. The Yang–Zhang Model
We consider the model in Yang and Zhang [6]. The model can be written as

where 0 < a < 1 and 0 < b < 1. Furthermore, ρ1 = 1 and ρ2 = v. We can easily check that assumption 1 in Section 4 holds because 0 < a < 1 and 0 < b < 1. Suppose that

; then both (44) and (45) hold.
We have α = 1/(1 − bv) and β = v/(1 − av); so from (9), (49), and (50) the adjustment coefficient R satisfies


We can obtain the bound for ruin probability, which is a function of u, x0, and y0. Since the definition of Un in Yang and Zhang [6] is the accumulated value of surplus after time n, so our result gives the same expression as Yang and Zhang [6] if we have taken this into account.
The Yang–Zhang model can be thought of as a model for changing exposure of a company, where a proportion of customers in a year will stay to the next year and a random number of new customers will arrive.
5.2. Credibility Model
Next we consider a credibility model. For simplicity, let the annual claim Yi be nonnegative, independent, and identically distributed with generic random variable Y. We assume that the company charges a credibility premium that is a combination of a manual rate Pd and the average of past n claims, for 0 < Z < 1 being the credibility factor:

We have a(∪) = c(∪) = d(∪) = 0 and b(∪) = (Z/n)(∪ + ··· + ∪n). Clearly, assumption 1 in Section 4 is satisfied. Let i = 0 such that ρ1 = ρ2 = 1 for simplicity. If

, then (45) and (46) hold.
From (9), (49), and (50), the adjustment coefficient R satisfies

Suppose R′ is the adjustment coefficient for the case in which a constant premium Pd is received each year and an annual claim amount follows Yi. Then the adjustment coefficient R for the credibility model is

We also have

Since

which satisfies β1,…, βn ≤ 0, Corollary 1 holds and the ruin probability is a function of u,y0,…, y−n+1.
6. DISCUSSIONS
The model presented in this article can have applications other than in the insurance sector. We can treat the premium process as an input process of any system and the claim process as an output process of that system. The system can be monetary reserve or stock of a commodity, where we are interested in its surplus after some time. We can apply the results in Sections 3 and 4 to find out the probability that the reserve will ever become negative.
In the article, we assumed that the dynamics of the premium and claim are given. In reality, we do not know the exact parameters and we need to estimate them from past data. The estimation will be subject to error and the result for ruin probabilities will also be an estimated value.
In Gerber [2,3], he considered an alternative coordinate that can express the ruin probabilities in terms of Ut. Since UT ≤ 0 and Ut > 0 for all t ≤ T − 1, by imposing some conditions, a Lundberg-type inequality can be found. In our model, because the two series have different coefficients, we cannot find the ruin probability in terms of Ut and we cannot guarantee that

.
For the results presented in this article we need to assume that the adjustment coefficient, R, exists, similar to the result in Yang and Zhang [6]. We can obtain a nonexponential bound when the adjustment coefficient does not exist.
Acknowledgment
The work described in this article was partially supported by a grant from the Research Grants Council of the Hong Kong Special Administrative Region, China (Project No. HKU 7050/05P).


