


1. MOTIVATION
Among scalar stochastic processes of the autoregressive moving average (ARMA) type, three are of particular interest: complex ARMA or (as we shall say) CARMA(p,q) processes, the real parts of such processes, which we shall call Re CARMA(p,q) processes, and the familiar real-valued ARMA(p′,q′) processes. The main problem considered here is whether, given a weakly stationary Re CARMA(p,q) process, we can find a spectrally equivalent ARMA(p′,q′) process: that is, an ARMA process with the same autocovariance function (ACF) and spectrum. To this question we return a positive answer.
Motives for studying the relationship between these three types of model are as follows. (i) The complex numbers form the largest (in a sense explained by Bell, 1945, pp. 254–255) number field, where theoretical results and concepts often take simple forms not apparent in the real case. The fundamental theorem of algebra, important in the study of the roots of ARMA processes, is one example. Another is the ability of the function ψt, where ψ is a complex parameter and t is time, to model exponential growth (or decay), or cyclical behavior, or a combination of the two, according to how the modulus and phase of ψ are chosen. This allows an integrated treatment of cyclicality and growth, whereas the approach using only real parameters tends to try to model them separately. For such reasons, possible maps between the CARMA and ARMA worlds offer to help us bridge the demands of theory and practice. Whether real-part mappings from CARMA processes yield exactly the ARMA class (or, e.g., a larger one) is therefore an interesting and natural question. (ii) More specifically, the ability of a Re CARMA formulation to model cyclical behavior in an illuminating way is evident from one well-known special case (discussed subsequently). In this instance at least the Re CARMA model has an alternative and equivalent but somewhat opaque ARMA reformulation.
These abstract and specific observations both raise the question of whether every Re CARMA has an ARMA equivalent. An answer is given in Theorem 1 in Section 3, which states that every weakly stationary Re CARMA(p,q) process has a weakly stationary ARMA(2p,p + q) representation, or a simpler one. The theorem identifies two possible types of simplification, root cancellation (affecting the AR and MA parts of the model equally) and “MA simplification” (affecting only the MA part). Root cancellation and/or MA simplification in the ARMA process can occur even when there is none in the parent CARMA process.
The special case of a CARMA or Re CARMA model mentioned earlier is the stochastic cycle model (SCM) described, for instance, by Harvey (1989, p. 39). This can be defined as the vector AR(1) process Zt = ΦZt−1 + εt, where

,

, 0 ≤ ρ < 1,

and the εt are all zero-mean, are uncorrelated across time, and have the time-invariant variance matrix σ2I2 (as discussed in the next section). The SCM is most naturally viewed as a CARMA process. Explicitly, let Zt ≡ Xt + iYt, εt ≡ ζt + iηt, and φ ≡ ρeiω. Then Zt = φZt−1 + εt, where φ is a complex parameter and {εt} is a sequence of complex innovations. So Zt follows a CARMA(1,0) or CAR(1) process. In the SCM, Xt but not Yt is observed; thus interest centers on Xt, which follows a Re CAR(1) process. Seen from the Re CAR(1) point of view, the ACF of Xt is easy to obtain. First we find the ACF of Zt, which turns out to be γZ(k) ≡ E(Zt Zt−k) = [2σ2/(1 − φφ)]φk when k ≥ 0, γZ(−k) = γZ(k). The ACF of Xt = Re Zt is then given by equation (3) in Section 2, yielding γX(k) = σ2[ρ|k|/(1 − ρ2)] cos kω, a damped cosine wave, evaluated at discrete intervals. The simplicity of this form of ACF indicates the theoretical importance of the SCM or Re CAR(1) model and illustrates its usefulness in modeling cyclicality. One should note in particular the close relation between the autoregressive parameter φ and the factor ρk cos kω = Re(φk) in the ACF. Harvey (1989, p. 69) points out that Xt follows a real-coefficient ARMA(2,1) process. The real formulation is however less natural than the Re CAR(1) formulation, because it uses a parametrization that renders mysterious the striking decaying-cosine nature of the ACF. This confirms that complex parameters can be more appropriate than real ones when cycles are present.
2. MOMENT SPECIFICATION
One important aspect of the SCM requires comment, namely, the special form σ2I2 it assumes for the variance matrix Σ of (ζt,ηt). We explain this assumption with respect to weakly stationary complex linear processes generally. If we are interested in the ACF and spectrum of Zt only, Σ need not be specified in detail. All that matters is the quantity E(εtεt) = tr Σ, a single real parameter. However if (as in the SCM and other Re CARMA models) we require the spectrum of Re Zt, then we need all the entries in Σ. To see that this is so consider the real n × 1 vector linear process

where E(εt) = 0n and E(εsεt′) = 0n×n if s ≠ t. The ACF of Zt is given by

, and γX(k) (where Xt is the first entry in Zt) is the top-left entry in Γ(k). The expression for Γ(k) is not particularly tractable. It becomes more so if the matrices involved commute. One method of making them do so is obviously to set n = 1 and choose all parameters real (thus in particular Ψj = ψj, a scalar). A variant of this approach, commonly adopted in theoretical work (see, e.g., Brockwell and Davis, 1987, p. 112), is (still with n = 1) initially to allow the ψj and εt to be complex and replace the third equation in (1) by E(εtεt) = σ2 but to confine the analysis to situations where Zt is real-valued. Thus Zt and Re Zt, and of course their ACFs and spectra, coincide. This simplicity comes at a price, because the requirement for the ψjεt−j to be real implies that the parameters and innovations must either both be purely real or both be purely imaginary, excluding most of the richness that a complex parametrization can yield.
The method used in the SCM to gain full access to the fertile possibilities of a complex parametrization is to set n = 2 and rely on the isomorphism between complex numbers a + ib, where a and b are real, and matrices of the form

. This isomorphism occurs because the operation of multiplying any complex number x + iy by the fixed number a + ib can be associated with the linear transformation that maps the point (x,y) on the Argand diagram to (ax − by, bx + ay). If the 2 × 2 matrices Ψj and Σ have this special structure, allowing us to associate them bijectively with the scalars ψj and σ2, respectively, then Γ(k) is mapped to the complex scalar

. Because Σ is symmetric, σ2 must in this case be real, and hence we must have Σ = σ2I2, explaining the form chosen in the SCM. To obtain the SCM from (1), one sets

, corresponding to the complex scalar (ρeiω)j.
The assumption Σ = σ2I2 is therefore a natural one to impose on complex linear processes, and we shall impose it in defining all CARMA and therefore Re CARMA models. This decision yields the striking simplification that if the complex innovation εt = ζt + iηt, where ζt and ηt are real, then E(εt2) = E(ζt2 − ηt2 + 2iζtηt) = 0; thus E(εsεt) = 0 whether or not s = t. Consequently for any complex linear process obeying Σ = σ2I2, we have

whether or not k = 0. From this result we can quickly derive the ACF of Xt ≡ Re Zt = ½(Zt + Zt), using γX(k) = ¼E [(Zt + Zt)(Zt−k + Zt−k)] = ¼E [Zt Zt−k + Zt Zt−k + Zt Zt−k + Zt Zt−k] . The first and last terms vanish. Because γZ(k) = γZ(−k) we obtain

By similar means we can show that if Yt = Im Zt, then γY(k) = γX(k). Thus Xt and Yt have the same ACF and spectrum. More generally, the ACF and spectrum of the real-part process are not affected by subjecting all the Zt to a constant rotation about the origin: if, for all t, Wt = Re(αZt), where α lies on the unit circle, then γW(k) = γX(k).
3. MAIN RESULTS
Our problem is, given a Re CARMA process, to see whether a spectrally equivalent ARMA process exists. Let us define suitable terminology for this enquiry. Informally speaking, an ARMA process may be defined by the relation A(L)Xt = B(L)ζt, involving two polynomials A and B in the lag operator L and a concept of white noise innovations ζt. (Usually A and B would be notated Φ and Θ, but here we reserve these symbols for the polynomials associated with CARMA processes. Given Φ and Θ, we shall show how to construct A and B.) In defining ARMA and CARMA models we shall be concerned with the class of polynomials P with complex coefficients. By P we mean the polynomial whose coefficients are conjugate to the corresponding coefficients in P. Thus P has real coefficients iff P = P. We denote the unit circle in the complex plane by Ω. If all roots of P lie outside Ω, we shall say that P is a spectral polynomial, because of its role in defining the spectrum of a stationary AR or invertible MA process. If P(0) = 1 we shall say that P is standardized (thus no standardized polynomial can have 0 as a root). If two polynomials have no common roots, we shall say that they are coprime (polynomials).
Let

be the set of integers. Let

, where the ζt are real-valued random variables with a common expectation 0 and a common variance and are uncorrelated across different time periods. Then we shall say that ζ is real white noise. We shall henceforth denote doubly infinite discrete sequences of random variables using notation such as {ζt}.
DEFINITION 1. Let A and B be standardized coprime spectral polynomials of degree p and q, respectively, with real coefficients, and let σ2 be a nonnegative real number. Then we shall say that the triple (A,B,σ2) is a normal specification of a (real) ARMA(p,q) process, namely, the process A(L)Xt = B(L)ζt, where {ζt} is real white noise with variance σ2.
Here and in similar contexts later we shall elide slightly and say that the triple defines a “normal ARMA(p,q) process,” though really it is the representation rather than the process that is normal. The word normal emphasizes that A and B are spectral and that there is no root cancellation. To define CARMA processes, taking into account our previous discussion of the moment specification, let {εt} be a complex-valued random sequence such that, if Re εt = ζt and Im εt = ηt, then (i) {ζt} and {ηt} are both real white noise, with a common variance σ2; (ii) all members of {ζt} are uncorrelated with all members of {ηt}. Then we shall say that {εt} is complex white noise with component variances σ2. Note that although all real numbers are complex numbers, it is not true that real white noise is complex white noise, except in the degenerate case of zero variance.
DEFINITION 2. Let Φ and Θ be standardized coprime spectral polynomials of degree p and q, respectively (with complex coefficients). Then we shall say that the triple (Φ,Θ,σ2) defines a normal CARMA(p,q) process, namely, the process Φ(L)Zt = Θ(L)εt, where {εt} is complex white noise with component variances σ2. If {Zt} follows this process and Xt = Re Zt, we shall say that Xt follows a normal Re CARMA(p,q) process.
Evidently, all ARMA processes are Re CARMA: the case when all parameters are real. Our major interest here is in whether all Re CARMA processes are also ARMA.
THEOREM 1. Let (Φ,Θ,σ2), where σ2 > 0, define a normal CARMA(p,q) process {Zt} and hence a normal Re CARMA(p,q) process {Xt} = {Re Zt}. Then {Xt} is spectrally equivalent to some normal ARMA(2p − c,p + q − v − c) process, where c is the number of roots (properly counted) of Φ that are either real or come in complex conjugate pairs (or, equivalently, c is the degree of the highest degree polynomial with real coefficients that divides Φ) and 0 ≤ v ≤ p + q − c.
As mentioned earlier, root cancellation in the ARMA process can occur even though Φ and Θ are coprime. Whether it does so depends only on Φ. The theorem may be illustrated with reference to the SCM. In the parent CARMA process, Φ(τ) = 1 − φτ, Θ(τ) = 1, p = 1, and q = 0. The general case is that there is an ARMA(2p,p + q) or ARMA(2,1) representation, as stated by Harvey (1989). If φ is purely imaginary, v = 1, “MA simplification” occurs, and the real-part process is AR(2) rather than ARMA(2,1). The other possible type of simplification, root cancellation, occurs iff the roots 1/φ and 1/φ of Φ and Φ, respectively, are equal: if so, φ is real and c = 1. In this case Xt is of course AR(1).
In view of Theorem 1, the class of weakly stationary ARMA processes is spectrally equivalent to the class of Re CARMA processes. This raises the question of which parametrization (or perhaps mixture of parametrizations) is to be preferred in a given context. In Section 5 we show that if cycles are present a Re CARMA formulation can be a natural way to approach the modeling problem.
4. PROOF OF THEOREM 1
To prove Theorem 1 we must show that there is an ARMA process with the same spectrum as {Re Zt}. The demonstration is constructive. Let Zt follow the normal CARMA(p,q) process defined by (Φ,Θ,σ2). The ACF γZ of Zt is defined by γZ(k) ≡ E(Zt Zt−k) = γZ(−k) and its spectrum by

where τ = e−iλ and λ is real. We have used

, with a corresponding result for Φ, and the fact that E(εtεt) = 2σ2. Let Xt be the real part of Zt, with ACF γX(k) ≡ E(Xt Xt−k). Using (3), the spectrum of {Xt} is

where the denominator and numerator terms are


Because by assumption Φ and Θ lack unit roots, (6) shows that N(1) = 2|Φ(1)|2|Θ(1)|2 is real and positive.
To show that Xt has an ARMA(2p − c,p + q − v − c) representation, we first show that D(τ) and N(τ) can be written in the forms A1(τ)A1(1/τ) and (apart from a scaling constant) B1(τ)B1(1/τ), respectively, where A1 and B1 are real-coefficient standardized spectral polynomials of degree 2p and p + q − v, respectively, where 0 ≤ v ≤ p + q. Then we show that the c common roots of A1 and B1 are just the common roots of Φ and Φ. Finally we construct the required real-coefficient spectral polynomials A and B, yielding the required normal representation (A,B,σ′2), where A is of degree 2p − c, B is of degree p + q − v − c, and A, B are coprime. This will complete the proof.
Beginning then with the denominator D(τ), define A1(τ) ≡ Φ(τ)Φ(τ). Then D(τ) = A1(τ)A1(1/τ), where A1(τ) is of degree 2p, satisfies A1(0) = 1 because Φ(0) = 1, and has real coefficients because

. Its roots are the same as those of Φ, together with their complex conjugates; therefore they all lie outside the unit circle Ω.
We now turn to N(τ). We need to construct a real-coefficient, standardized polynomial B1, and a real scalar κ > 0, such that N(τ) = κB1(τ)B1(1/τ). The degree of B1 depends on N as follows. Evidently N(1/τ) = N(τ) if τ ≠ 0. Thus N(τ) is of the form

. Degeneracy arises if one or more leading coefficients np+q, np+q−1,… in this expression are zero. The term N cannot vanish identically, because we showed earlier that N(1) is real and positive. Consequently there must be a smallest nonnegative integer v for which np+q−v is nonzero; thus v is the largest integer such that τp+q−vN(τ) is a polynomial. Define P(τ) ≡ τp+q−vN(τ). Then P is of degree 2(p + q − v) and P(0) = np+q−v ≠ 0. Because N(τ) = N(1/τ) for τ ≠ 0, it follows that if r is any root of P, then so is its reciprocal 1/r. (For this reason, polynomials such as P are known as reciprocal polynomials. They are also known as palindromic polynomials, because the coefficient of τj equals the coefficient of τ2(p+q−v)−j.) The polynomial P must have equal numbers of roots inside and outside Ω and no root at 0. It cannot have roots on Ω, for if there were such a root r, the property P(r) = 0 = rp+q−vN(r) would imply, because r ≠ 0, N(r) = 0. An r on Ω would satisfy 1/r = r; hence (6) would yield

Because both terms would be nonnegative, they would both have to be zero. In particular the first term would yield |Φ(r)|2|Θ(r)|2 = 0, implying that either Φ(r) = 0 or Θ(r) = 0. Thus either Φ or Θ would have a root on Ω, contradicting our assumption that they are both spectral. Thus the roots of P can be partitioned into the p + q − v that lie outside Ω, which we call r1,…, rp+q−v (unless v = p + q, when P is a constant), and the p + q − v inside, namely, 1/r1,…,1/rp+q−v. Define

(or B1 ≡ 1 if p + q = v: we adopt the usual convention that empty products have the value 1) so that B1 is standardized and spectral. It follows that
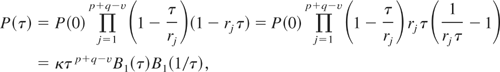
where

, and so N(τ) = κB1(τ)B1(1/τ) as required, and κ ≠ 0.
Next we show that the polynomial B1 has real coefficients. From (6), N(τ) = Φ(τ)Φ(1/τ)Θ(1/τ)Θ(τ) + Φ(1/τ)Φ(τ)Θ(τ)Θ(1/τ) = N(τ) for all τ ≠ 0, implying that N, and therefore P, has real coefficients. A polynomial with real coefficients can be expressed as a product of linear and quadratic factors, all with real coefficients. Let rj be a root of B1 and therefore of P. If it is the root of one of the linear factors of P, it must be real. If it is a root of one of the quadratic factors, it must either be real or can be paired, if it is nonreal, with its complex conjugate rj, which has the same magnitude. Because this magnitude exceeds 1, rj must also be a root of B1. Thus all roots of B1 are either real or come paired with their complex conjugates in the definition of B1. It follows that B1 is, like P, a product of linear and quadratic factors, each with real coefficients, and therefore that B1 has real coefficients. To evaluate κ note that for τ = 1 we obtain κ = N(1)/B1(1)2, which we now know to be well defined because B1(1) is real and nonzero. Because N(1) is real and positive, it follows that κ is also real and positive. Because from (4) we require

we obtain

for the innovation variance of the ARMA process.
Now we discuss the possibility of root cancellation. First note that this can happen even though Φ and Θ are coprime; for instance we saw that it does so in the SCM if φ is real. In fact (returning to the general case) the c common roots r1,…, rc of A1 and B1 are the common roots of N and D exceeding 1 in magnitude, and these in turn are just the common roots of Φ and Φ. To prove this latter statement, note first that if r is a common root of Φ and Φ then |r| > 1 and r is a root of both D and N, as we can see from (5) and (6). Conversely, if |r| > 1 and r is a root of both D and N, then it is a root of Φ or Φ (not of Φ(1/τ)Φ(1/τ), because of its magnitude). If it is a root of Φ then from (6) it is a root of the first term of N and hence must be a root of the second term. It cannot be a root of Θ(1/τ)Φ(1/τ), because of its magnitude, or of Θ(τ), because this violates the assumption that Φ and Θ are coprime. Hence it must be a root of Φ also. Similarly, if it is a root of Φ it must be a root of Φ.
Using these c common roots, define

and B(τ) = B1(τ)/C(τ). Because each root of C is a root of both Φ and Φ, either it must be real or it can be paired with another root that is its complex conjugate. Consequently the polynomial C has real coefficients. The polynomials A and B inherit from A1 and B1 the properties of being standardized, spectral, and coprime, and they have real coefficients because A1, B1, and C have real coefficients. We have shown that the spectrum of Re Zt is that of the normal ARMA(2p − c,p + q − v − c) process A(L)Xt = B(L)ζt, where ζt is real white noise with variance σ′2. This completes the proof of Theorem 1. █
5. POSSIBLE APPLICATIONS
The CARMA-Re CARMA-ARMA framework suggests a natural generalization of the stochastic cycle approach to situations where there is more than one cycle. If, for instance, the sample spectrum showed the presence of two distinct cycles with known frequencies ω1 and ω2, one could try to model the process in question as the real part of Zt = W1,t + W2,t, where W1,t and W2,t are independent and follow CAR(1) processes, with autoregressive parameters ρ1 eiω1 and ρ2 eiω2, respectively. According to the results of Granger and Morris (1976), which seem to extend straightforwardly to CARMA processes, Zt would then be CARMA(2,1). Hence according to Theorem 1, the real-part process Xt would except in degenerate cases be ARMA(4,3). More generally, a sum of s cycles would be ARMA(2s,2s − 1); however if the ωj were known we would need to estimate only the s moduli ρj and the s innovation variances of the component cycles.
In cases where cycles form only part of the model, and where real ARMA models and their usual extensions are used to capture the noncyclical components, Theorem 1 seems to suggest as one possibility setting up Re CARMA-type models in which some but not all complex parameters are restricted to be real. As the theorem states, this can be achieved by placing restrictions on the AR polynomial Φ in the form of assigning Φ some real roots or some conjugate pairs of complex roots. The consideration of such an approach to stationary and nonstationary time series modeling is outside the scope of this note.


