1. Introduction
It is well established in the literature that flexible price monetary models of closed economies display belief-driven cyclical fluctuations under high degrees of relative risk aversion [Farmer (Reference Farmer1997); Farmer (Reference Farmer1999, Section 11)]. This paper shows that openness in terms of diversified currency holdings by agents entirely removes cyclical fluctuations of this kind, no matter whether domestic and foreign currencies exhibit substitutability or complementary, or are independent to each other.
As a result of financial liberalization and globalization, there have been increasing opportunities for agents to hold multiple currencies and foreign currency denominated deposits and to use them as a means of payment, a store of value, and/or a unit of account. Such a phenomenon, dubbed currency substitution, is now common in the global economy.Footnote 1 It is particularly evident in high-inflation countries in which domestic residents switch to holdings of foreign currencies that are not prone to inflationary pressures, for example, Latin America countries during the 1980s and the 1990s [Savastano (Reference Savastano1992); Airaudo (Reference Airaudo2014)]. The rise of cryptocurrencies in recent years highlights the issue of currency substitution, considering that these currencies may one day serve as alternative means of payments and reduce the demand for fiat currencies [He (Reference He2018)].
Despite the significance of currency substitution, there are only a few papers working on the implication of it on a nation’s aggregate stability.Footnote 2 Earlier works have found exchange rate indeterminacy under substitutable currencies.Footnote 3 Uribe (Reference Uribe1997) shows that, in the presence of network effects in the process of adopting an alternative means of payment, multiple steady states and equilibrium indeterminacy are more likely to occur. Dupor (Reference Dupor2000) demonstrates that the single-country determinacy result of Leeper (Reference Leeper1991), Sims (Reference Sims1994), and Woodford (Reference Woodford1994, Reference Woodford1995) under a nominal interest rate peg does not survive in a multi-country, multi-currency setting, no matter whether currencies are perfect substitutes or not substitutable across countries. Tandon and Wang (Reference Tandon and Wang1999); Tandon and Wang (Reference Tandon and Wang2003) find that the following may give rise to the emergence of multiple equilibria: (1) concern by agents for the possibility that the government may impose capital controls that increase the transaction cost of using foreign currencies or (2) concern by agents that the domestic currency could lose its function as a store of value. Airaudo (Reference Airaudo2014) shows under imperfect capital mobility that equilibrium indeterminacy can occur even if currencies are imperfect substitutes.
It is thus clear that, when incorporating into the model particular types of friction such as restrictions on the use of domestic and/or foreign currencies as a means of payment, uncertainties about the stance of government policies that cause transaction costs of using domestic and/or foreign currencies, and imperfect world capital market, the existing literature tends to point to the result that currency substitution is detrimental for domestic aggregate stability. This paper singles out the role of currency substitution and shows that diversified currency holdings themselves serve as an automatic stabilizer that mitigates belief-driven cyclical fluctuations.
To highlight the mechanism that diversified currency holdings create a stabilizing effect that removes the possibility of indeterminacy, I start off by analyzing a simplified version of the indeterminate closed economy of Farmer (Reference Farmer1997) and then prove that equilibrium indeterminacy disappears when diversified currency holdings are allowed. Specifically, I consider that agents derive positive utility from consumption, leisure hours, and holdings of real money balances. Consumption and real money balances may display as Edgeworth substitutes or complements, or are additively separable in the household’s preferences. Simple as it is, the model allows me to analytically derive the necessary and sufficient conditions for the closed economy’s steady state to display endogenous cyclical fluctuations or saddle-path stability. In particular, for endogenous business fluctuations to occur, it requires that the share of consumption in the household’s subutility function is lower than a critical value and that the coefficient of relative risk aversion is above a threshold level; otherwise, equilibrium uniqueness is ensured.
I then extend the closed economy to become a small-open economy by allowing holdings of both domestic and foreign currencies by domestic agents. In this amended model, the domestic country exhibits net financial outflows and a current account surplus. I show that the small-open-economy model exhibits a unique steady state. In addition, when the foreign inflation rate is lower than the domestic long-run inflation rate, saddle-path stability of the model’s steady state is guaranteed no matter whether domestic and foreign currencies are Edgeworth substitutes, complements, or independent. Hence, belief-driven cyclical fluctuations originally present in the domestic country are entirely removed in the presence of diversified currency holdings. This determinacy result is distinct from that derived in the literature. For instance, considering a foreign inflation rate lower than the domestic inflation rate, Airaudo (Reference Airaudo2014) quantitatively shows that equilibrium indeterminacy arises under an imperfect world capital market.
When by contrast the foreign inflation rate is higher than the domestic long-run inflation rate, I show analytically that belief-driven cyclical fluctuations are impossible when (i) the degree of currency substitution is lower than a critical value or (ii) the degree of currency substitution exceeds that critical value and the coefficient of relative risk aversion is below a threshold level. Even when the degree of currency substitution exceeds the critical value and the coefficient of relative risk aversion is above the threshold level, the quantitative analysis shows that, to be compatible with indeterminacy, it requires levels of the foreign inflation rate that are too high to square with data. Equilibrium indeterminacy is thus extremely hard to occur in this case.
I also find that the higher the degree of openness in terms of diversified currency holdings (measured by a lower share of domestic currency in total liquidity services), the higher the requisite level of the foreign inflation rate for indeterminacy will be. This implies that it is more difficult for equilibrium indeterminacy to occur when the degree of openness increases. Moreover, I show that the minimum level of the foreign inflation rate that guarantees equilibrium indeterminacy increases when the degree of currency substitution and/or the coefficient of relative risk aversion falls.
I further demonstrate in Section 4 that Section 3’s result, in which currency substitution operates like an automatic stabilizer that mitigates belief-driven cyclical fluctuations in a small-open economy, is robust to the inclusion of agents’ access to a world capital market to borrow from or to lend to the rest of the world. I first show that, when domestic agents are able to freely borrow/lend in a perfect world capital market at an exogenously constant nominal interest rate, local indeterminacy ceases to occur. I next show that, if the world capital market is imperfect, and if the domestic agent faces a borrowing/lending rate increasing in the aggregate stock of net foreign debt, then (i) determinacy is impossible when the domestic agent does not hold the foreign currency and (ii) as the degree of openness in terms of diversified currency holdings increases, the requisite level of the foreign inflation rate for equilibrium indeterminacy rises, making belief-driven cyclical fluctuations more difficult to occur. I further find that the possibility of equilibrium indeterminacy declines when the elasticity of the risk premium with respect to net foreign debt rises, which corresponds to a decline in the upper bound for the stock of net foreign debt. An important policy implication of my analysis is that setting a sufficiently low upper bound for the stock of net foreign debt is desirable as it can help stabilize the domestic economy by alleviating business fluctuations caused by agents’ animal spirits.
In the related literature, Huang et al. (Reference Huang, Meng and Xue2018) show how integration into the world capital market (especially the structure of the borrowing rate) relieves concerns about aggregate instability resulting from the implementation of Schmitt-GrohÉ and Uribe’s (1997a) formulation of the balanced-budget rule. Huang et al. (Reference Huang, Meng and Xue2018) highlight the roles of international trade factors, including the elasticity of substitution between home and foreign goods and the degree of openness in terms of home consumers’ preferences over imported goods, at reducing the scope of indeterminacy. Chen (Reference Chen2018) shows how international borrowing produces a destabilizing effect that increases the possibility of belief-driven aggregate fluctuationsFootnote 4 and how the scope of equilibrium indeterminacy is affected by the debt-to-capital ratio coefficient in the borrowing rate schedule, currency denomination of the international bonds, and monetary regimes. This paper complements the existing literature by showing that openness in terms of diversified currency holdings operates as an automatic stabilizer that promotes domestic aggregate stability.
The remainder of this paper is organized as follows. Section 2 describes the closed economy model and analytically and graphically examines the model’s local dynamics. Section 3 analyzes the theoretical interrelations between currency substitution and the small-open-economy model’s local stability properties. Section 4 incorporates into Section 3’s model a world capital market in which domestic agents finance a shortage of funds or lend surplus funds. Section 5 concludes.
2. Closed economy
There is a unit measure of identical competitive firms. The representative firm produces real output y according to the linear production technology:
 $y=h$
, where h is labor inputs. Under the assumption that the labor market is perfectly competitive, profit maximization of the firm leads to
 $w=1$
, where w is the real wage.
The economy is also populated by a unit measure of identical infinitely-lived households. Each household is endowed with one unit of time and maximizes:
 \begin{equation}\int_{0}^{\infty }\overbrace{\left( v-\frac{h^{1+\gamma }}{1+\gamma }\right)}^{u}e^{-\rho t}dt,\, \end{equation}
where
 $\gamma \geq 0$
denotes the inverse of the intertemporal elasticity of substitution in labor supply,
 $\rho $
 $>0$
is the subjective rate of time preference, and the subutility function v is given by
 \begin{equation}v=\left\{\begin{array}{c}\frac{\left( c^{a}m^{1-a}\right) ^{1-\sigma }-1}{1-\sigma } \\a\log c+\left( 1-a\right) \log m\end{array}\right. ,\,\ \text{if \ }\begin{array}{c}\sigma \neq 1 \\\sigma =1\end{array}, \end{equation}
where c is the consumption,
 $m\equiv M/P$
denotes real money balances, with M and P, respectively, representing the stock of nominal money balances and the price level,
 $\sigma >0$
is the coefficient of relative risk aversion that measures the curvature of v, and
 $a\in \left( 0,1\right) $
is the share of consumption in the household’s subutility function v. The above formulation of the subutility function v follows those of Obstfeld (Reference Obstfeld1985) and Chang and Lai (Reference Chang and Lai2000), among others.
The household’s instantaneous utility function, u, given by (1), is increasing and strictly concave with respect to consumption, real money balances, and labor hours. It is straightforward to show that, when
 $\sigma=1$
, the household’s preference exhibits additive separability between consumption and real money balances, and hence the marginal utility of c is independent of m (
 $u_{cm}=0$
). When
 $\sigma >\left( <\right) $
1, the marginal utility of consumption increases (decreases) with respect to real money balances (
 $u_{cm}<\left( >\right) 0$
), indicating that c and m are Edgeworth substitutes (complements), and hence the model becomes an asset substitution model (a transactions service model) [Wang and Yip, Reference Wang and Yip1992]. Under (1), the inverse of the intertemporal elasticity of substitution in consumption, defined as the response of consumption growth to the return on real assets, equals
 $\Sigma \equiv 1-a\left( 1-\sigma\right) >0$
, and
 $\Sigma \gtreqqless 1$
, when
 $\sigma \gtreqqless 1$
.
Note that the adoption of the money-in-the-utility-function (MIUF) approach given by (1) allows me to derive more general results since under this monetary approach c and m can exhibit complementarity or substitutability, or be separated from each other in the utility function. Instead, in the Clower-Lucas cash-in-advance (CIA) approach, more money holdings allow for more consumption purchases. Consumption and real money balances thus exhibit perfect complementarity.
The representative household faces the budget constraint:
 \begin{equation}\dot{m}=wh-c-\pi m+\tau , \end{equation}
where
 $\pi (\equiv \dot{P}/P)$
denotes the inflation rate, and
 $\tau $
is real lump-sum transfers from the government.
The first-order conditions for the representative household with respect to the indicated variables and the associated transversality conditions (TVC) are
 \begin{eqnarray}c &:&a\left( c^{a}m^{1-a}\right) ^{1-\sigma }/c=\lambda , \end{eqnarray}
 \begin{eqnarray}h &:&h^{\gamma }/\lambda =w, \end{eqnarray}
 \begin{eqnarray}m &:&\left( 1-a\right) \left( c^{a}m^{1-a}\right) ^{1-\sigma}/m-\pi \lambda =\rho \lambda -\dot{\lambda}, \end{eqnarray}
 \begin{eqnarray}\text{TVC} &:&\lim_{t\rightarrow \infty }e^{-\rho t}\lambda m=0, \end{eqnarray}
where
 $\lambda $
is the shadow value of wealth. Equation (4) states that the marginal benefit of consumption equals its marginal cost, which is the marginal utility of having an additional real dollar. Equation (5) equates the marginal disutility of labor to the real wage rate. Equation (6) governs the evolution of the shadow value of wealth and (7) is the transversality condition.
Note from (5) that the slope of the labor supply curve equals
 $\gamma $
and that the labor demand curve is a horizontal line (
 $w^{d}=1$
). To guarantee the existence of labor market equilibrium, it thus requires a strictly positive value of
 $\gamma (>0)$
.
The central bank keeps the nominal money stock growing at a constant rate:
 $\mu \neq 0$
,
 $\forall t$
. Nominal money supply thus evolves through time according to:
 \begin{equation}\textrm{M}{(t)}=M_{0}e^{\mu t},\,\,\,M_{0}>0\,\,\,\text{given,} \end{equation}
and the resulting seigniorage is returned to households as a lump-sum transfer; hence,
 $\tau =\mu m$
.
Clearing in the money and goods markets implies that:
 \begin{equation}\dot{m}=\left( \mu -\pi \right) m\text{ \ \ and \ \ }y=c. \end{equation}
To facilitate the analysis of the model’s local stability properties, I make the following logarithmic transformation of variables:
 $\hat{x}\equiv \log(x)$
, where
 $x=\{m,y,h,c,\lambda \}$
. The model’s equilibrium conditions can be collapsed into the following single differential equation in the shadow value of wealth
 $\hat{\lambda}$
that describes the equilibrium dynamics:
 \begin{equation}\overset{\cdot }{\hat{\lambda}}=\Phi +\frac{\gamma \left( \sigma -\Sigma\right) \left( 1-a\right) a^{\frac{1}{\Sigma -\sigma }-1}}{\Delta }\exp \left[ \frac{\sigma +\gamma }{\left( \sigma -\Sigma \right) \gamma }\hat{\lambda}\right] , \end{equation}
where
 $\Delta \equiv \left( 1+\gamma \right) \Sigma +\left( 1-\sigma \right)\gamma \gtrless 0$
and
 $\Phi =\frac{\left( \Sigma -\sigma \right) \gamma\left( {\mu}+\rho \right) }{\Delta }$
. The remaining endogenous variables can then be derived accordingly. In particular, it can be shown that
 $\hat{m}=\frac{\left( \Sigma +\gamma \right) \hat{\lambda}-\log \left(a^{\gamma }\right) }{\left( \Sigma -\sigma \right) \gamma }$
,
 $\hat{y}=\hat{h}=\hat{c}=\frac{\hat{\lambda}}{\gamma }$
, and
 $\pi =\frac{\left( \Sigma-\sigma \right) \gamma {\mu}+\left( \Sigma +\gamma \right) \left\{ \frac{1-a}{a}\exp \left[ \hat{c}-\hat{m}\right] -\rho \right\} }{\Delta }$
.
It is straightforward to show that the model exhibits a unique interior steady state given by (45)–(48). In terms of the local dynamics around the model’s steady state, I linearize (10) around the steady state and find that its local stability property is governed by the eigenvalue:
 \begin{equation}e=\frac{\left( \gamma +\sigma \right) \left( \mu +\rho \right) }{\Delta }\gtrless 0,\,\,\ \text{if}\,\,\ \Delta \gtrless 0. \end{equation}
Since the shadow value of wealth
 $\hat{\lambda}$
is a nonpredetermined jump variable, the unique steady state of the model displays saddle path stability and equilibrium uniqueness if and only if
 $\Delta >0$
, which guarantees a positive eigenvalue:
 $e>0$
. If
 $\Delta <0$
, then the eigenvalue e is negative, and hence the steady state is a locally indeterminate sink that can be exploited to generate endogenous cyclical fluctuations driven by agents’ self-fulfilling expectations or sunspots.
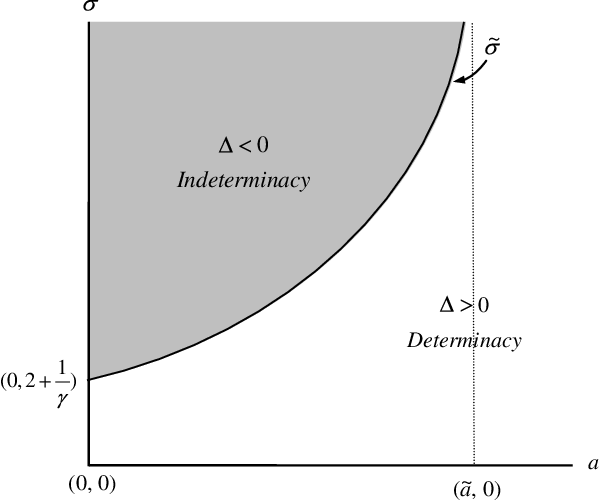
Given the analytical result in (11), Figure 1 depicts the combinations of the preference parameters a and
 $\sigma $
that graphically characterize the model’s local stability properties, where the positively-sloped convex locus
 $\tilde{\sigma}\equiv 1+\frac{1}{\tilde{a}-a}>1$
divides the regions labeled as “ sink” and “ saddle”.
Footnote 5
Accordingly, I establish the following proposition.
Regions of Equilibrium (In)determinacy: Closed Economy.

Proposition 1 In a monetary closed economy,
-
(i) when the share of consumption in the subutility function v is higher than the critical value
 $\tilde{a}\equiv \frac{\gamma }{1+\gamma }\in \left( 0,1\right) $
, there is no possibility of equilibrium indeterminacy;
-
(ii) when the share a is below the critical level
$\tilde{a}$
, the economy possesses an (in)determinate steady state if and only if the coefficient of relative risk aversion
$\sigma $
is below (above) the threshold level
$\tilde{\sigma}\equiv 1+\frac{1}{\tilde{a}-a}>1$
, where
$\tilde{\sigma}$
increases with the share
$a $
.


The above analytical result that a sufficiently high value of
 $\sigma $
is necessary and sufficient to generate equilibrium indeterminacy is qualitatively the same as the results obtained in the related literature. Specifically, under a more general household utility function where c, h, and m display nonseparability in the household’s preferences, Farmer (Reference Farmer1997, pp. 604–605) numerically shows that the value of
 $\sigma $
larger than unity is necessary to generate indeterminate equilibria. Farmer (Reference Farmer1999, Section
 $11.5$
) then finds that for the Clower-Lucas cash-in-advance (CIA) economy in discrete time to display an indeterminate steady state, the value of
 $\sigma $
needs to be higher than 2.
The household’s instantaneous utility function, u, given by (1), is a special case of that in Farmer (Reference Farmer1997, p. 575) since here I consider that only c and m display nonseparability in the household’s preferences. Under this formulation for the household’s preferences, I am able to analytically derive that equilibrium indeterminacy is impossible if
 $a>\tilde{a}=\frac{\gamma }{1+\gamma }$
. When considering the value of
 $\gamma =2$
that Chetty et al. (Reference Chetty, Guren, Manoli and Weber2011); Chetty et al. (Reference Chetty, Guren, Manoli and Weber2012) recommend, I derive that this critical value is
 $\tilde{a}=\frac{2}{3}$
. When
 $a<\tilde{a}\left( =\frac{2}{3}\right) $
, Figure 1 illustrates that the locus of
 $\tilde{\sigma}$
intersects the vertical axis at the value of
 $2.5$
. In addition, under a given value of
 $a<\tilde{a}$
, increasing the value of
 $\sigma $
such that it passes through the critical value
 $\tilde{\sigma}$
turns the steady state from a saddle into a sink.
To understand the intuition behind the above indeterminacy result, I first re-express (10) as
 \begin{equation}\overset{\cdot }{\hat{\lambda}}=\rho -\overbrace{\left( R-\pi \right) }^{r},\end{equation}
where R denotes the model’s implied nominal interest rate that equals the marginal utility of holding money balances divided by the shadow value of wealth,
 $\frac{u_{m}}{u_{c}}=\left( 1-a\right) a^{\frac{1}{\Sigma -\sigma }-1}\exp \left[ \frac{\left( \sigma +\gamma \right) \hat{c}}{\sigma -\Sigma }\right] $
, and
 $\pi =\Phi +\frac{\left( \Sigma +\gamma \right) R}{\Delta }$
is the equilibrium inflation rate. I next start the economy from its steady state where
 $\overset{\cdot }{\hat{\lambda}}=0$
and
 $\hat{\lambda}$
is at its steady-state value
 $\hat{\lambda}^{s}$
and then consider a slight deviation caused by agents’ anticipation about a higher future shadow value of wealth. Acting upon this belief, households will decrease today’s consumption in exchange for wealth accumulation. Equation (12) indicates that the consequential effect on the evolution of
 $\hat{\lambda}$
is through the impact of
 $\hat{c}$
on R and
 $\pi $
.
First, when
 $\sigma >({<})$
1, substitutability (complementarity) between c and m leads the households to increase (decrease) their money holdings when they reduce consumption. Under diminishing returns of the marginal utility of real money balances, the equilibrium nominal interest rate consequently declines (rises):
 $\frac{\partial R}{\partial \hat{c}}\gtrless0 $
, when
 $\sigma \gtrless 1$
. This tends to raise (reduce) the shadow value of wealth via (12).
Two opposing forces interact to determine the effect of
 $\hat{c}$
on
 $\pi $
. First, the decline in
 $\hat{c}$
, by raising the shadow value of wealth, encourages labor supply.
Footnote 6
The supply of output thus increases and the inflation rate declines. Second, when
 $\sigma >({<})$
1, substitutability (complementarity) between c and m leads to an increase (decrease) in
 $\hat{m}$
when
 $\hat{c}$
falls. By deriving from (4) that
 $\frac{\partial \hat{\lambda}}{\partial \hat{m}}\lessgtr 0$
, if
 $\sigma \gtrless 1$
, I infer that: (i) when
 $\sigma >1$
, the rise in
 $\hat{m}$
decreases the shadow value of wealth; this shrinks the labor supply, thereby reduces aggregate supply of output and boosts the inflation rate; (ii) when
 $\sigma >1$
, the decline in
 $\hat{m}$
reduces the shadow value of wealth; therefore, the inflation rate rises in this case as well. By combining the two opposing forces that
 $\hat{c}$
exerts on
 $\pi $
, the inflation rate thus may rise or fall, depending on the associated parameters, a,
 $\sigma $
, and
 $\gamma $
:
 $\frac{\partial \pi }{\partial \hat{c}}\gtrless 0$
, when
 $\Delta \left( \sigma -1\right) \gtrless0 $
.
As a result, when
 $1<\tilde{\sigma}<\sigma $
such that
 $\Delta <0$
, since R declines while
 $\pi $
rises, the real interest rate falls. Equation (12) indicates that this will lead to an increase in the next period’s shadow value of wealth, validating agents’ initial anticipation of a higher future shadow value of wealth. When
 $1<\sigma <\tilde{\sigma}$
such that
 $\Delta >0$
, the drops in both R and
 $\pi $
cause a rise in the real interest rate r.
Footnote 7
As a result, the next period’s shadow value of wealth declines, and agents’ initial expectations about a higher future shadow value of wealth are therefore not validated as a self-fulfilling equilibrium. Third, when
 $0<\sigma <1$
(hence
 $\Delta >0$
), the increases in both R and
 $\pi $
raise the real interest rate r. Hence, the next period’s shadow value of wealth falls, and agents’ initial anticipation thus cannot be self-fulfilling. Finally, when
 $\sigma=1 $
, the household’s preference exhibits additive separability between c and m. It is straightforward to derive that in this case the shadow value of wealth remains unchanged over time:
 $\hat{\lambda}=\log \left( a^{\frac{\gamma }{1+\gamma }}\right) $
. Thus, belief-driven business fluctuations will not occur.
3. Small open economy under diversified currency holdings
The preceding section analytically shows that a simplified version of the monetary closed economy of Farmer (Reference Farmer1997) displays an indeterminate steady state when the share of consumption in the subutility function v is lower than a critical value, and when the coefficient of relative risk aversion exceeds a threshold level. Building on the closed-economy model, this section allows for holdings of both domestic and foreign currencies by domestic agents; the economy therefore becomes a small-open economy (SOE). Using this modified model, I will show how diversified currency holdings serve as an automatic stabilizer that mitigates belief-driven cyclical fluctuations. Footnote 8
I consider that domestic agents produce and consume a single traded good, the foreign price of which is given in the world market. In the absence of any impediments to trade, the law of one price continuously holds. By denoting P as the domestic price level,
 $P^{\ast }$
as the world price level, and E as the nominal exchange rate, the law of one price can be described in percentage change terms as
 \begin{equation}\pi =\pi ^{\ast }+\varepsilon , \end{equation}
where
 $\pi (\equiv \dot{P}/P)$
is the inflation rate of the good in terms of the domestic currency,
 $\pi ^{\ast }(\equiv \dot{P}^{\ast }/P^{\ast })$
is the inflation rate of the good in terms of the foreign currency, and
 $\varepsilon (\equiv \dot{E}/E)$
is the depreciation rate of the domestic currency. Moreover
 $\pi ^{\ast }$
is assumed to be exogenously given to the SOE, while
 $\pi $
and
 $\varepsilon $
are endogenously determined [see, Turnovsky (Reference Turnovsky1997, p. 18) and Airaudo (Reference Airaudo2014), among others].
3.1 Firms and households
As in the closed economy, domestic real output is produced using a linear technology:
 $y=h$
. Under the assumption that the labor market is perfectly competitive, profit maximization of the representative firm leads to:
 $w=1$
.
Let F denote the stock of nominal foreign currency, and
 $f\equiv F/P^{\ast }$
is real foreign currency balances. The subutility function v shown in (2) is modified as follows:
Footnote 9
 \begin{equation}v=\left\{\begin{array}{c}\frac{\left( c^{a}l^{1-a}\right) ^{1-\sigma }-1}{1-\sigma } \\a\log c+\left( 1-a\right) \log l\end{array}\right. ,\,\ \text{if \ }\begin{array}{c}\sigma \neq 1 \\\sigma =1\end{array}, \end{equation}
where l represents real liquidity services that are a composite of real domestic currency, m, and real foreign currency, f, in the constant-elasticity-of-substitution (CES) functional form [Chen et al. (Reference Chen, Tsaur and Chou1981); Miles (Reference Miles1978, Reference Miles1981); Imrohoroglu (Reference Imrohoroglu1996)]:
 \begin{equation}l=\left[ \delta m^{\theta }+\left( 1-\delta \right) f^{\theta }\right] ^{\frac{1}{\theta }}, \end{equation}
where the parameter
 $\delta \in \left( 0,1\right) $
is the share of domestic currency in total liquidity. When
 $\delta =1$
, I recover the subutility function v for the closed economy, as shown in (2). In this case, there is no incentive for households to hold the foreign currency since they derive zero utility from it. The parameter
 $\delta $
therefore captures the degree of openness in terms of diversified currency holdings, where a lower value of
 $\delta $
represents a higher degree of openness.
The parameter
 $\theta <1$
presenting in (15) measures the degree of currency substitution. Specifically, the elasticity of substitution between m and f equals
 $\frac{1}{1-\theta }>0$
. A larger value of
 $\theta $
thus represents a higher degree of substitution between the currencies. When
 $\theta \rightarrow -\infty $
, the elasticity of substitution approaches 0, and l approaches the Leontief form:
 $l=\min\left( m,f\right) $
; in this case, m and f display perfect complementarity. When
 $\theta \rightarrow 0$
, the elasticity of substitution approaches 1, and l approaches the Cobb-Douglas form:
 $l=m^{\delta}f^{1-\delta }$
; in this case, m and f are imperfect substitutes. When
 $\theta \rightarrow 1$
, the elasticity of substitution approaches infinite, and l is linear in m and f:
 $l=\delta m+\left( 1-\delta \right) f$
; and m and f are therefore perfect substitutes.
The instantaneous utility function (1) under the subutility function (14) is increasing and strictly concave with respect to c,
 $m$
, f, and h. When
 $\sigma =1$
, the household’s preference exhibits additive separability between consumption and real liquidity services; hence, the marginal utility of c is independent of m and f:
 $u_{cm}=u_{cf}=0$
. When
 $\sigma >\left( <\right) $
1, not only c and m but also c and f are Edgeworth substitutes (complements):
 $u_{cm}<\left(>\right) 0$
and
 $u_{cf}<\left( >\right) 0$
, if
 $\sigma >\left( <\right) $
1. Finally, if
 $\theta >\left( <\right) \Sigma -\sigma $
, then m and f display Edgeworth substitutability (complementarity):
 $u_{mf}<\left(>\right) 0$
, if
 $\theta >\left( <\right) \Sigma -\sigma $
.
In the presence of diversified currency holdings, the budget constraint faced by the representative household, (3), is modified as follows:
 \begin{equation}\dot{m}+\dot{f}=wh-c-\pi m-\pi ^{\ast }f+\tau ,\,\,\,f_{0}>0\,\,\,\text{given.} \end{equation}
It is straightforward to derive the following first-order conditions for the representative household and the associated TVC:
 \begin{eqnarray}c &:&\overbrace{a\left( c^{a}l^{1-a}\right) ^{1-\sigma }/c}^{u_{c}}=\lambda , \end{eqnarray}
 \begin{eqnarray}h &:&h^{\gamma }/\lambda =w, \end{eqnarray}
 \begin{eqnarray}m &:&\overbrace{\frac{\left( 1-a\right) \alpha c\lambda }{am}}^{u_{m}}-\pi \lambda =\rho \lambda -\dot{\lambda}, \end{eqnarray}
 \begin{eqnarray}f &:&\overbrace{\frac{\left( 1-a\right) \left( 1-\alpha\right) c\lambda }{af}}^{u_{f}}-\pi ^{\ast }\lambda =\rho \lambda -\dot{\lambda}, \end{eqnarray}
 \begin{eqnarray}\text{TVC} &:&\lim_{t\rightarrow \infty }e^{-\rho t}\lambda m=\lim_{t\rightarrow \infty }e^{-\rho t}\lambda f=0, \end{eqnarray}
where
 $\alpha \equiv \delta \left( \frac{m}{l}\right) ^{\theta }\in \left(0,1\right) $
. With (17), equations (19) and (20) lead to the no arbitrage condition between holdings of domestic and foreign currencies:
 \begin{equation}\overbrace{\frac{\left( 1-a\right) \alpha c}{am}}^{\frac{u_{m}}{u_{c}}=R}-\pi =\overbrace{\frac{\left( 1-a\right) \left( 1-\alpha \right) c}{af}}^{\frac{u_{f}}{u_{c}}}-\;\pi^{\ast }, \end{equation}
from which the equilibrium domestic inflation rate is determined as
 $\pi=\pi ^{\ast }+\frac{\left( 1-a\right) c}{a}\left( \frac{\alpha }{m}-\frac{1-\alpha }{f}\right) $
. In turn, the law of one price (13) determines the depreciation rate of the domestic currency
 $\varepsilon =\pi-\pi ^{\ast }$
.
Note that (22) holds in equality as I concentrate on the interior equilibrium whereby both currencies are held. In this situation, the representative household chooses its holdings of m and f such that it derives the same levels of net (after-inflation tax) marginal benefits from holding domestic and foreign currencies:
 $\frac{u_{m}}{u_{c}}-\pi =\frac{u_{f}}{u_{c}}-\pi ^{\ast }$
. However, when domestic and foreign currencies are displayed as Edgeworth substitutes, there can be an equilibrium where either f or m is zero. For example, a sufficiently high level of
 $\pi $
(
 $\pi ^{\ast }$
) will make the left-hand side of (22) lower (higher) than the right-hand side of (22), and consequently, the household will not hold the domestic (foreign) currency.
Footnote 10
3.2 Government and the central bank
Under a regime of flexible exchange rates, foreign reserves are constant over time. Following AgÉnor and Montiel (Reference AgÉnor and Montiel2015, pp. 357–359), I normalize the constant level of reserves to zero. Accordingly, by denoting
 $D $
as the nominal stock of domestic credit that grows at the constant rate
 $\mu =\dot{D}/D\neq 0$
, changes in the real money balances are equal to changes in the real domestic credit stock, that is,
 \begin{equation}\dot{m}/m=\dot{d}/d=\mu -\pi , \end{equation}
where
 $d(\equiv D/P)$
is the real stock of domestic credit. As in Section 2, the government distributes seigniorage to the representative household as a lump-sum transfer. The flow budget constraint of the government is thus given by:
 $\tau =\mu m$
.
By putting together the household’s budget constraint (16), the evolution of real money balances (23), the government’s budget constraint
 $\tau =\mu m$
, the production technology
 $y=h$
, and the firm’s optimization
 $w=1$
, the SOE’s consolidated budget constraint is obtained as follows:
 \begin{equation}\dot{f}=y-c-\pi ^{\ast }f, \end{equation}
which equates net financial outflows driven by holdings of the foreign currency to current account surplus.
3.3 Analysis of dynamics
It is straightforward to show that the model possesses a unique interior steady state given by (49)–(55). In the neighborhood of the steady state, the model’s equilibrium conditions can be approximated by the following log-linear dynamical system:
 \begin{equation}\left[\begin{array}{c}\overset{\cdot }{\hat{m}} \\\overset{\cdot }{\hat{f}} \\\overset{\cdot }{\hat{\lambda}}\end{array}\right] =\underbrace{\left[\begin{array}{ccc}\Gamma _{1} & \Gamma _{2} & \frac{\mu -\pi ^{\ast }}{\Sigma } \\\frac{\Xi \Pi \left( \sigma -\Sigma \right) }{\left( 1+\Xi \right) \Sigma }& \frac{\Pi \left( \sigma -\Sigma \right) }{\left( 1+\Xi \right) \Sigma }-\pi ^{\ast } & \frac{\pi ^{\ast }+\Pi }{\gamma }+\frac{\Pi }{\Sigma } \\\frac{\rho +\mu }{1+\Xi }\left( 1-\theta +\frac{\sigma \Xi }{\Sigma }\right)-\Gamma _{1} & \frac{\rho +\mu }{1+\Xi }\left( \theta -1+\frac{\sigma }{\Sigma }\right) -\Gamma _{2} & \frac{\pi ^{\ast }+\rho }{\Sigma }\end{array}\right] }_{\mathbf{J}}\left[\begin{array}{c}\hat{m}-\hat{m}^{s} \\\hat{f}-\hat{f}^{s} \\\hat{\lambda}-\hat{\lambda}^{s}\end{array}\right] ,\,\,\ \hat{f}_{0}\,\text{given,} \end{equation}
where
 $\Xi =\left[ \frac{\delta }{1-\delta }\left( \frac{\pi ^{\ast }+\rho }{\mu +\rho }\right) ^{\theta }\right] ^{\frac{1}{1-\theta }}>0$
,
 $\Pi =\frac{a\left( \pi ^{\ast }+\rho \right) \left( 1+\Xi \right) }{1-a}>0$
, and
 \begin{eqnarray*}\Gamma _{1} &\equiv &\frac{\left( 1-\theta +\frac{\sigma \Xi }{\Sigma }\right) \mu +\left( 1-\theta \right) \left( 1+\Xi \right) \rho -\Xi \left(\theta -1+\frac{\sigma }{\Sigma }\right) \pi ^{\ast }}{1+\Xi }, \\\Gamma _{2} &\equiv &\frac{\left( \theta -1+\frac{\sigma }{\Sigma }\right)\mu -\left( 1-\theta \right) \left( 1+\Xi \right) \rho +\left[ \frac{\sigma}{\Sigma }+\Xi \left( 1-\theta \right) \right] \pi ^{\ast }}{1+\Xi }.\end{eqnarray*}
It follows that the determinant and trace of the model’s Jacobian matrix
 $\mathbf{J}$
are
 \begin{equation}Det\left( \mathbf{J}\right) =\frac{\left( \theta -1\right) \left( \rho +\mu\right) \left( \rho +\pi ^{\ast }\right) \left( \frac{\sigma }{\gamma }+1\right) \left( \Pi +\pi ^{\ast }\right) }{\Sigma }<0, \end{equation}
and
 \begin{equation}Tr\left( \mathbf{J}\right) =\underbrace{\left( 1-\theta +\frac{\sigma \Xi }{\Sigma }\right) }_{\left( +\right) }\frac{\mu -\pi ^{\ast }}{1+\Xi }+\left(2-\theta \right) \rho +\left( 1-\theta \right) \pi ^{\ast }\gtreqqless 0.\end{equation}
Since both the initial foreign price of the single traded good, denoted as
 $P_{0}^{\ast }$
, and the foreign inflation rate
 $\pi ^{\ast }$
, are exogenously given to the SOE, the foreign price level
 $P^{\ast }\left(t\right) =P_{0}^{\ast }e^{\pi ^{\ast }t}$
is constrained to adjust continuously. It thus follows that the stock of real foreign currency
 $f(=F/P^{\ast })$
is a nonjump predetermined variable, and that the initial real stock of foreign currency held by domestic residents,
 $f_{0}$
, is an exogenously given initial condition. On the contrary, since both the domestic inflation rate
 $\pi $
and the initial domestic price level, denoted as
 $P_{0}$
, are endogenously determined, the domestic price level
 $P\left( t\right) =P_{0}e^{\pi t}$
can jump instantaneously. As a result, the stock of real domestic currency
 $m\equiv M/P$
is a jump variable without an initial condition. Note from (22) that, with real consumption c and the domestic inflation rate
 $\pi $
both instantly adjusting, no arbitrage between holdings of domestic and foreign currencies by the agent can be achieved under a freely-jumping m and a predetermined f.
Given that the first-order dynamical system (25) possesses one predetermined variable
 $\hat{f}$
, and both
 $\hat{m}$
and
 $\hat{\lambda}$
are nonpredetermined jump variables, the economy displays saddle-path stability and equilibrium uniqueness if and only if one of the eigenvalues of
 $\mathbf{J}$
has a negative real part, and two of the remaining have positive real parts. When two or more eigenvalues have negative real parts, the steady state is a locally indeterminate sink that can be exploited to generate endogenous business cycle fluctuations driven by agents’ self-fulfilling expectations or sunspots. The steady state becomes a source when all eigenvalues have positive real parts. In the remainder of this section, I examine the local dynamics of the model’s steady state in two parametric configurations.
3.3.1 When
$\pi ^{\ast }< \mu $

Since in the steady state the domestic inflation rate
 $\pi ^{s}$
is equal to the nominal money growth rate
 $\mu $
, in this specification where
 $\pi^{\ast }<\mu $
, the foreign inflation rate is lower than the long-run domestic inflation rate. It follows immediately from (27) that that the Jacobian
 $\mathbf{J}$
displays a positive trace
 $\left( Tr\left( \mathbf{J}\right) >0\right) $
. Together with the fact in (26) that the model’s determinant is negative
 $\left( Det\left( \mathbf{J}\right)<0\right) $
, this indicates that the Jacobian
 $\mathbf{J}$
has one stable (negative) root and two unstable (positive) roots. The model’s unique steady state thus exhibits saddle-path stability and equilibrium uniqueness. Accordingly, I establish the following proposition.
Proposition 2 For a small-open monetary economy where diversified currency holdings are allowed, if the foreign inflation rate is lower than the long-run domestic inflation rate, then belief-driven cyclical fluctuations originally present in the domestic country are entirely removed.
3.3.2 When
$\pi ^{\ast }> \mu $

For this parametric configuration, the foreign inflation rate is higher than the long-run domestic inflation rate. I rewrite (27) as
 \begin{equation}Tr\left( \mathbf{J}\right) =\underbrace{\left( 1-\theta +\frac{\sigma \Xi }{\Sigma }\right) \frac{\mu }{1+\Xi }+\left( 2-\theta \right) \rho }_{\left(+\right) }+\underbrace{\frac{\Xi \left( 1-a\right) \left( 1-\theta \right)\pi ^{\ast }}{\left( 1+\Xi \right) \Sigma }}_{\left( +\right) }\cdot \Theta ,\end{equation}
where
 \begin{equation}\Theta \equiv \frac{\left( 1-a\right) \left( 1-\theta \right) -\left[1-a\left( 1-\theta \right) \right] \sigma }{\left( 1-a\right) \left(1-\theta \right) }\gtreqqless 0. \end{equation}
It is straightforward to show that, when
 $\theta <\underline{\theta }\equiv\frac{a-1}{a}<0$
, the bracket
 $\left[ 1-a\left( 1-\theta \right) \right] $
in the numerator of
 $\Theta $
, given by (29), has a negative sign. It follows that
 $\Theta >0$
, and hence the Jacobian matrix
 $\mathbf{J}$
possesses a positive trace
 $\left( Tr\left( \mathbf{J}\right) >0\right) $
. Adding this with the fact that
 $Det\left( \mathbf{J}\right) <0$
, I find that in the present case where
 $\theta <\underline{\theta }$
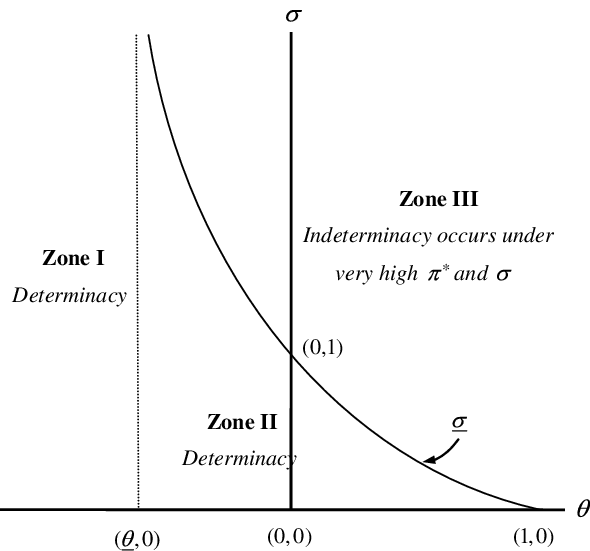
, the model’s steady state displays only one stable (negative) eigenvalue. Hence, equilibrium uniqueness is ensured. This case is illustrated as Zone I of Figure 2.
Regions of Equilibrium (In)determinacy: SOE and
 $\pi^{*}>\vec{\mu.}$

I then turn to the case where
 $\theta >\underline{\theta }$
. Here, a positive
 $\left[ 1-a\left( 1-\theta \right) \right] $
is derived, and hence the numerator of
 $\Theta $
has an ambiguous sign. I then derive from (29) that
 $\Theta \gtreqqless 0$
, if
 $\sigma \lesseqqgtr \underline{\sigma }\equiv \frac{\left( 1-a\right) \left( 1-\theta \right) }{1-a\left(1-\theta \right) }$
. Thus, when
 $\theta >\underline{\theta }$
and
 $\sigma <\underline{\sigma }$
, positive values of both
 $\Theta $
and
 $Tr\left(\mathbf{J}\right) $
are guaranteed, implying that the model possesses a determinate steady state. This case is illustrated as Zone II of Figure 1.
Footnote 11
Zone III in Figure 1 represents the case where
 $\theta >\underline{\theta }$
and
 $\sigma >\underline{\sigma }$
(hence,
 $\Theta <0$
), and the steady state displays
 $Det\left( \mathbf{J}\right) <0$
and
 $Tr\left( \mathbf{J}\right) \gtreqqless 0$
. Since structural and policy parameters enter the Jacobian matrix J in highly nonlinear manners, I am unable to analytically identify the number of (un)stable roots. In what follows, I quantitatively investigate the local stability properties of the steady state locating in Zone III.
Per the parameterization that is commonly adopted in the RBC-based indeterminacy literature, the time discount rate
 $\rho $
is set equal to
 $0.01$
. Recall that one needs a strictly positive value of the inverse of the intertemporal elasticity of substitution in labor supply,
 $\gamma $
, for guaranteeing the existence of labor market equilibrium;
 $\gamma $
is thus calibrated to be 2 [Chetty et al. (Reference Chetty, Guren, Manoli and Weber2011, Reference Chetty, Guren, Manoli and Weber2012)]. The domestic inflation rate is set at 4% per year, implying that
 $\mu $
equals
 $0.04/4$
. Finally, under the calibrated value of
 $\gamma $
, Figure 1 shows that equilibrium indeterminacy is possible in Section 2’s closed economy only when
 $a<\tilde{a}=\frac{\gamma }{1+\gamma }=\frac{2}{3}$
. To test the power of diversified currency holdings in mitigating belief-driven cyclical fluctuations, the preference parameter a is chosen to be
 $0.5$
(
 $<\frac{2}{3}$
). It follows that the minimum level of
 $\sigma $
such that indeterminacy arises in the closed economy equals
 $\tilde{\sigma}=7$
. In addition, the critical value of
 $\underline{\theta }=\frac{a-1}{a}$
equals
 $-1$
; hence, only the cases associated with
 $\theta >-1$
need to be examined.
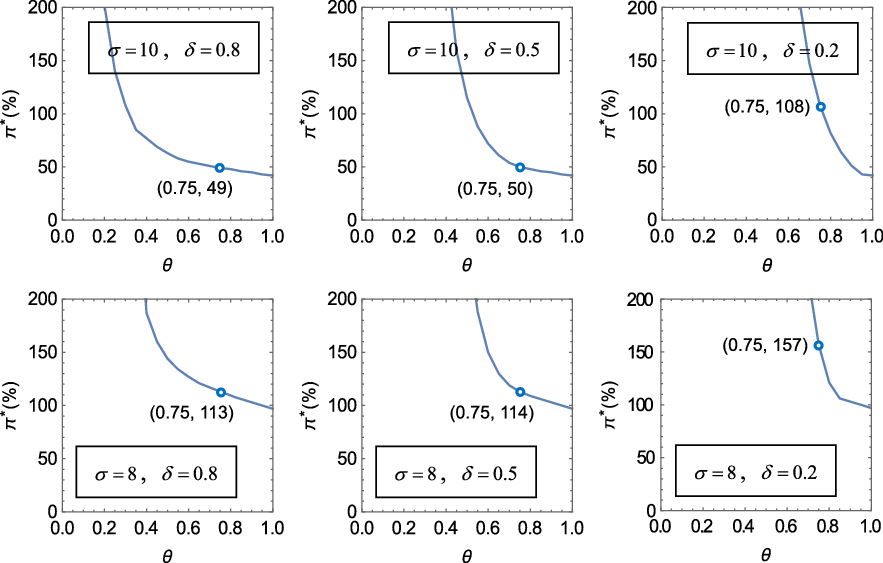
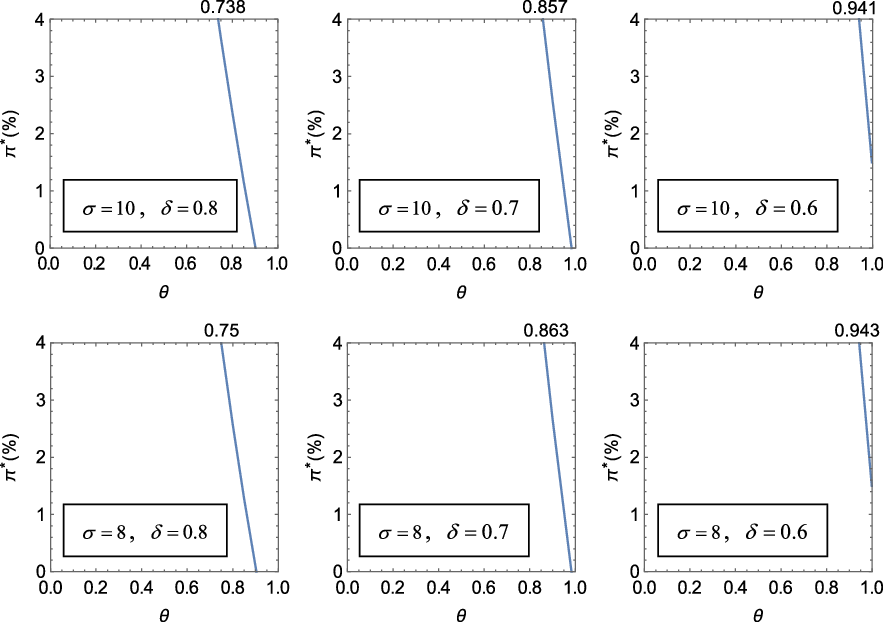
Given the baseline parameter values, Figure 3 plots for various combinations of
 $\sigma $
and
 $\delta $
the minimum value of the annual foreign inflation rate
 $\pi ^{\ast }$
needed for equilibrium indeterminacy as a function of the degree of currency substitution,
 $\theta $
, when the model’s steady state is located in Zone III of Figure 1. The two rows of Figure 3, respectively, illustrate the case of
 $\sigma =10$
and 8. In particular, while the literature finds that the estimate of the coefficient of relative risk aversion,
 $\sigma $
, can range from 0 to around 30, the general consensus is that it is below 10.
Footnote 12
Under the calibrated values of
 $\rho $
,
 $\gamma $
,
 $\mu $
, and a, belief-driven cyclical fluctuations are impossible when
 $\sigma $
is below 7. I therefore show in the figure the cases of
 $\sigma =10$
and
 $8 $
only. On the other hand, a lower value of the share of domestic currency in total liquidity,
 $\delta $
, represents a higher degree of openness in terms of diversified currency holdings. The three columns of Figure 3 thus correspond to the situations in which the degree of openness is low (
 $\delta=0.8$
), medium (
 $\delta =0.5$
), and high (
 $\delta =0.2$
), respectively.
Requisite
 $\pi$
* for Indeterminacy: Zone III of Figure 2.

It is obvious that each of the panels in Figure 3 displays a negative nexus between the requisite level of
 $\pi ^{\ast }$
for indeterminacy and the degree of currency substitution,
 $\theta $
. Moreover, for any combination of
 $\sigma $
,
 $\delta $
, and
 $\theta $
, the value of
 $\pi ^{\ast }$
above which equilibrium indeterminacy occurs is too high to square with data. In particular, in each of the panels in Figure 3, the lowest requisite level of
 $\pi ^{\ast }$
for indeterminacy is observed when
 $\theta\rightarrow 1$
. I numerically derive that, when
 $\theta \rightarrow 1$
, this level of
 $\pi ^{\ast }$
equals 42% (97%) when
 $\sigma =10$
(8), for
 $\delta =0.8$
,
 $0.5$
, and
 $0.2$
. This means that, when
 $\theta \rightarrow 1$
, the minimum level of
 $\pi ^{\ast }$
that guarantees equilibrium indeterminacy does not change to variations in
 $\delta $
, but increases when
 $\sigma $
falls.
When
 $\theta <1$
, the requisite level of
 $\pi ^{\ast }$
for indeterminacy does change to variations in
 $\delta $
and/or
 $\theta $
. First, under a given level of
 $\sigma $
, each of the rows of Figure 3 illustrates that the requisite level of
 $\pi ^{\ast }$
for indeterminacy rises faster as
 $\theta $
declines, if
 $\delta $
takes on a lower value. Based on the related literature’s estimation, Airaudo (Reference Airaudo2014) sets a degree of currency substitution that implies
 $\theta =0.75$
. When taking
 $\sigma =10$
and
 $\theta =0.75$
as an example, the top panel of Figure 2 shows that the model’s steady state turns from a saddle into a locally indeterminate sink when
 $\pi ^{\ast }\geq 49\%$
, 50%, or 108%, if
 $\delta =0.8$
,
 $0.5$
, or
 $0.2$
. Since an increase in the degree of openness in terms of diversified currency holdings raises the minimum level of
 $\pi ^{\ast }$
that guarantees equilibrium indeterminacy, it makes belief-driven fluctuations more difficult to occur.
Next, under a given level of
 $\delta $
, each of the columns of Figure 3 shows that the requisite level of
 $\pi ^{\ast }$
for indeterminacy rises faster as
 $\theta $
declines, if
 $\sigma $
takes on a lower value. Taking
 $\delta =0.8$
and
 $\theta =0.75$
as an example, the requisite level of
 $\pi^{\ast }$
for indeterminacy is 49% (113%) if
 $\sigma =10$
(8). Recall that belief-driven cyclical fluctuations are impossible when
 $\sigma $
is below 7. Because both a high
 $\pi ^{\ast }$
and a high
 $\sigma $
are sources of equilibrium indeterminacy, when
 $\sigma $
is above 7, the minimum level of
 $\pi ^{\ast }$
that guarantees equilibrium indeterminacy decreases when
 $\sigma $
becomes higher. The above results are summarized in the following proposition.
Proposition 3 For a small-open monetary economy where diversified currency holdings are allowed, if the inflation rate of the foreign country is higher than the long-run domestic inflation rate, then:
-
(i) belief-driven cyclical fluctuations originally present in the domestic country are entirely removed when
$\theta <\underline{\theta }$
, or when
$\underline{\theta }<\theta <1$
and
$\sigma <\underline{\sigma }$
, where
$\underline{\theta }=\frac{a-1}{a}<0$
and
$\underline{\sigma }=\frac{\left( 1-a\right) \left( 1-\theta\right) }{1-a\left( 1-\theta \right) }<1$
; -
(ii) when
$\underline{\theta }<\theta <1$
and
$\underline{\sigma }<\sigma $
, indeterminacy occurs at very high foreign inflation rates and the coefficient of relative risk aversion; in this case, the higher the degree of openness in terms of diversified currency holdings and/or the lower the coefficient of relative risk aversion is, the higher the requisite level of the foreign inflation rate will be.


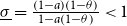


3.3.3 Discussion
Under the calibrated values of
 $\rho $
,
 $\gamma $
,
 $\mu $
, and a, Proposition 1 states that the closed economy displays belief-driven business fluctuations when
 $\sigma $
is higher than the threshold level
 $\tilde{\sigma}=1+\frac{1}{\tilde{a}-a}=7$
. Proposition 2 then shows that, by allowing diversified currency holdings by agents, equilibrium indeterminacy becomes impossible when the foreign inflation rate is lower than the domestic long-run inflation rate. This is distinct from the indeterminacy result obtained in the literature. For instance, under an imperfect world capital market and a Taylor-type rule on the nominal government bonds rate, Airaudo’s (2014) quantitative analysis considering
 $\pi ^{\ast }=2\%<6.4\%=\pi $
shows that indeterminacy occurs.
Proposition 3 presents that even when
 $\pi ^{\ast }>\pi $
, equilibrium indeterminacy is impossible when the model’s steady state is located in Zone I or II of Figure 2, and it is extremely unlikely to occur when the steady state is located in Zone III of Figure 2 since the requisite level of
 $\pi^{\ast }$
for indeterminacy is too high to square with data.
The above discussion demonstrates that diversified currency holdings themselves create a stabilizing effect that eliminates the possibility of endogenous cyclical fluctuations. To understand the intuition behind the determinacy result under currency substitution, I present in what follows the evolution of the shadow value of wealth:
 \begin{equation}\overset{\cdot }{\hat{\lambda}}=\rho -\overbrace{\frac{\left( 1-a\right)\left( 1-\delta \right) }{a}\exp \left[ \frac{\log \left( a\right) +\left[\Sigma \left( 1-\theta \right) -\sigma \right] \hat{l}-\Sigma \left(1-\theta \right) \hat{f}-\hat{\lambda}}{\Sigma }\right] }^{u_{f}}+\pi ^{\ast}, \end{equation}
where the second term on the right-hand side is the nominal return on holding the foreign currency, that is, the marginal utility of the foreign currency,
 $u_{f}$
.
I start the economy from its steady state, where
 $\overset{\cdot }{\hat{\lambda}}=0$
and
 $\hat{\lambda}$
is at its steady-state value
 $\hat{\lambda}^{s}$
, and then consider a slight deviation caused by agents’ anticipation about a higher future shadow value of wealth. Acting upon this belief, households will decrease today’s consumption in exchange for the accumulation of wealth.
When
 $\sigma >1$
, consumption and the foreign currency are Edgeworth substitutes (
 $u_{cf}<0$
). Hence, when cutting
 $c_{t}$
, households will increase f. Since the marginal utility of the foreign currency exhibits diminishing returns, the nominal return on holding the foreign currency falls. This tends to raise the next period’s shadow value of wealth. However, currency substitution will offset this positive effect on
 $\overset{\cdot }{\hat{\lambda}}$
, thereby preventing agents’ anticipation from being self-fulfilling. Specifically, recall that m and f display substitutability (complementarity), if
 $\theta >(<)\Sigma $
. When
 $\theta>\Sigma $
, substitutability between m and f leads households to reduce
 $m $
when they increase f. Because
 $u_{mf}<0$
, the decline in
 $m_{t}$
raises the nominal return on holding f, which offsets the original decline in the nominal return on holding f. By contrast, when
 $\theta <\Sigma $
, complementarity between m and f leads households to raise m when they increase f. Since
 $u_{mf}>0$
, the rise in m increases the nominal return on holding f; the original decline in the nominal return on holding f is therefore offset.
When
 $\sigma <1$
, c, and f display complementarity (
 $u_{cf}>0$
). Hence, when c drops upon agents’ animal spirits, f falls as well. Diminishing returns of
 $u_{f}$
then lead to a higher nominal return on holding f, which in turn causes a decline in the next period’s shadow value of wealth. Again, this negative effect on
 $\overset{\cdot }{\hat{\lambda}}$
will be offset by currency substitution. Specifically, when
 $\theta >\Sigma $
, substitutability between m and f leads households to raises m when they reduce f. Because
 $u_{mf}<0$
, the increase in m shrinks the nominal return on holding f. By contrast, when
 $\theta <\Sigma $
, complementarity between m and f leads households to reduce m when they cut f. Since
 $u_{mf}>0$
, the drop in m reduces the nominal return on holding f.
Finally, when
 $\sigma =1$
, the household’s preference exhibits additive separability between c and f. Since f does not change upon agents’ animal spirits, it is clear from (30) that the nominal return on holding the foreign currency (
 $u_{f}$
) remains unchanged, and hence belief-driven business fluctuations will not occur.
4. International borrowing and lending
Building upon Section 3’s SOE model with diversified currency holdings, this section further incorporates households’ access to a world capital market in order to borrow or lend internationally by issuing or purchasing foreign bonds. Let B denote the stock of nominal net foreign debt denominated in the foreign currency. If
 $B>(<)0$
, then the domestic country is a net debtor (creditor) in the world capital market. The budget constraint faced by the representative household is given by
 \begin{equation}\dot{m}+\dot{f}-\dot{b}=wh-c-\pi m-\pi ^{\ast }f-\left( R^{\ast }-\pi ^{\ast}\right) b+\tau ,\,\,\,f_{0},b_{0}>0\,\,\,\text{given,} \end{equation}
where
 $b\equiv B/P^{\ast }$
is the real stock net foreign debt, and
 $R^{\ast }$
is the nominal interest rate at which the household borrows or lends in the world capital market. Other model features, including the representative firm’s, the central bank’s, and the government’s behavior, are the same as those described in Section 3.
The representative household chooses a sequence
 $\left\{ c,h,m,f,b\right\}_{t=0}^{\infty }$
so as to maximize its lifetime utility (1), with the subutility function v and the liquidity services function l, respectively, defined in (14) and (15), subject to its budget constraint (31), and taking
 $\left\{ w,\pi ,R^{\ast },\pi^{\ast },\,f_{0},b_{0}\right\} $
as given. The first-order necessary conditions for c, h, m, f, as well the transversality conditions for m and f are the same as those given by (17)–(21). The first-order condition for b is
 \begin{equation}\left( R^{\ast }-\pi ^{\ast }\right) \lambda =\rho \lambda -\dot{\lambda},\end{equation}
and the associated transversality condition is
 $\lim_{t\rightarrow \infty}e^{-\rho t}\lambda b=0$
. Thus, in addition to the no arbitrage condition between holdings of domestic and foreign currencies given by (22), I have the following equation, which is essentially the SOE’s interest-rate parity:
 \begin{equation}R^{\ast }-\pi ^{\ast }=\overbrace{\frac{\left( 1-a\right) \alpha c}{am}}^{\frac{u_{m}}{u_{c}}=R}-\;\pi . \end{equation}
The above equation is also the decision rule that the representative household borrows/lends in the world capital market. In particular, as a debtor, the household borrows from the rest of the world such that the marginal cost of international borrowing (
 $R^{\ast }-\pi ^{\ast }$
) equals the net marginal benefit it derives when using the funds raised from the world capital market to finance its holdings of domestic and foreign currencies (
 $\frac{u_{m}}{u_{c}}-\pi =\frac{u_{f}}{u_{c}}-\pi ^{\ast }$
). On the other hand, as a creditor, the household lends to the rest of the world such that the net marginal benefits from holding foreign bonds and domestic and foreign currencies are equal to each other.
With the household’s budget constraint (31), the production technology
 $y=h$
, the firm’s optimization
 $w=1$
, the central bank’s behavior described by (23), and the government’s budget constraint
 $\tau=\mu m$
, I obtain the following consolidated budget constraint of the SOE:
 \begin{equation}\dot{f}-\dot{b}=y-c-\pi ^{\ast }f-\left( R^{\ast }-\pi ^{\ast }\right) b,\end{equation}
which states that net financial outflows are driven by holdings of both the foreign currency (f) and net foreign debt (b), and that the SOE’s current account balance equals the balance of trade plus the balance on services that consists of interest payment on net foreign debt.
4.1 Perfect world capital market
I first consider the case where the world capital market is perfect in the sense that domestic households of the SOE can freely borrow from or lend to the rest of the world at an exogenously given and constant risk-free interest rate
 $R^{\ast }=\bar{R}^{\ast }$
. The analysis below will show that indeterminacy and self-fulfilling expectations do not occur. This finding is in line with that obtained in Huang et al. (Reference Huang, Meng and Xue2018, Section 3.1) where diversified currency holdings are not allowed.
When
 $R^{\ast }=\bar{R}^{\ast }$
, the Euler equation, given by (32), is expressed as
 \begin{equation}\overset{\cdot }{\hat{\lambda}}=\rho -\bar{r}^{\ast }, \end{equation}
where
 $\bar{r}^{\ast }\equiv \bar{R}^{\ast }-\pi ^{\ast }$
is the exogenously given world risk-free real interest rate. With
 $\bar{r}^{\ast }$
and the rate of time preference
 $\rho $
both being exogenously given constants from the standpoint of the SOE, in order for (35) to imply a finite interior steady-state value for the shadow value of real net financial assets (
 $\hat{\lambda}$
), the following restriction has to be imposed:
Footnote 13
 \begin{equation}\rho =\bar{r}^{\ast }\text{, \ \ }\forall t. \end{equation}
This further implies that
 $\overset{\cdot }{\hat{\lambda}}=0$
for all t, so that
 $\hat{\lambda}=\hat{\lambda}^{s}$
is constant over time. Moreover, as is widely known in the literature on SOE real business cycle models with a perfect world capital market in continuous time, (35) displays a zero eigenvalue. In the context of labor hours being the only production input, the constancy of
 $\hat{\lambda}$
in turn implies the constancy of hours worked (
 $\hat{h}=\hat{y}^{s}$
) over time.
The dynamics of the economy are governed by the following 2-dimensional system with one initial condition on
 $\hat{b}_{0}$
:
 \begin{eqnarray}\overset{\cdot }{\hat{m}} &=&\mu -\pi , \end{eqnarray}
 \begin{eqnarray}\overset{\cdot }{\hat{b}} &=&\exp [\hat{h}-\hat{b}]-\exp [\hat{c}-\hat{b}]-\pi ^{\ast }\exp [\hat{f}-\hat{b}]+\rho -\frac{f}{b}\frac{d\hat{f}}{d\hat{m}}\overset{\cdot }{\hat{m}}, \end{eqnarray}
where
 $\pi =\pi (\hat{m})$
,
 $\hat{c}=\hat{c}(\hat{m})$
, and
 $\hat{f}=\hat{f}(\hat{m})$
, with the partial derivatives
 $\frac{d\pi }{d\hat{m}}=\frac{\left(\pi +\rho \right) \left( \theta -1\right) \sigma }{\sigma \left( 1-\alpha\right) +\left( 1-\theta \right) \alpha \Sigma }<0$
,
 $\frac{d\hat{c}}{d\hat{m}}=\frac{\alpha \left( \Sigma -\sigma \right) \left( 1-\theta \right) }{\sigma \left( 1-\alpha \right) +\left( 1-\theta \right) \alpha \Sigma }$
, and
 $\frac{d\hat{f}}{d\hat{m}}=\frac{\alpha \left[ \left( 1-\theta \right)\Sigma -\sigma \right] }{\sigma \left( 1-\alpha \right) +\left( 1-\theta\right) \alpha \Sigma }$
. For the same reason as in the case of the stock of real foreign currency, since the foreign price level
 $P^{\ast }$
is constrained to adjust continuously, the stock of real net foreign debt,
 $b=B/P^{\ast }$
, is a nonjump predetermined variable with an initial condition
 $\hat{b}_{0}>0$
[see Turnovsky (Reference Turnovsky1997), among many others].
It is straightforward to show that the steady-state expressions of
 $\hat{m}^{s}$
,
 $\hat{y}^{s}$
,
 $\hat{c}^{s}$
,
 $\pi ^{s}$
,
 $\hat{\lambda}^{s}$
, and
 $\alpha ^{s}$
are the same as those given by (50)–(55), which are all functions of
 $\hat{f}^{s}$
. However, the model’s equilibrium conditions are unable to pin down the steady-state level of net foreign debt. By imposing
 $\overset{\cdot }{\hat{m}}=\overset{\cdot }{\hat{b}}=0$
on (37)–(38), I obtain that
 $\hat{f}^{s}$
is the solution to the following quadratic equation:
 \begin{equation}\hat{f}^{s}=F(\hat{f}^{s})\equiv \frac{\bar{r}^{\ast }\log (\hat{b}^{s})}{\Pi +\pi ^{\ast }}+\Omega (\hat{f}^{s})^{-\frac{\sigma }{\gamma }},\end{equation}
where
 $\Omega \,{\equiv}\, \frac{1}{\Pi +\pi ^{\ast }}\big\{ \frac{a}{\Pi^{\Sigma }}\big[ \delta \big( \frac{\Xi \bar{R}^{\ast }}{\mu +\rho }\big) ^{\theta }\,{+}\,1\,{-}\,\delta \big] ^{\frac{\Sigma -\sigma }{\theta }}\big\} ^{\frac{1}{\gamma }}\,{>}\,0$
,
 $F(\infty)\,{=}\,\frac{\bar{r}^{\ast }\log (\hat{b}^{s})}{\Pi +\pi ^{\ast }}\,{>}\,0$
,
 $F^{\prime }=-\frac{\sigma }{\gamma }\Omega (\hat{f}^{s})^{-\frac{\sigma }{\gamma }-1}<0$
,
 $F^{\prime \prime }=\frac{\sigma }{\gamma }\left( \frac{\sigma }{\gamma }+1\right) \Omega (\hat{f}^{s}){}^{-\frac{\sigma }{\gamma }-2}>0$
, and
 $F(0)\rightarrow \infty$
. Hence, under any arbitrarily specified value for the initial level of the stock of net foreign debt
 $\hat{b}^{s}=\hat{b}_{0}$
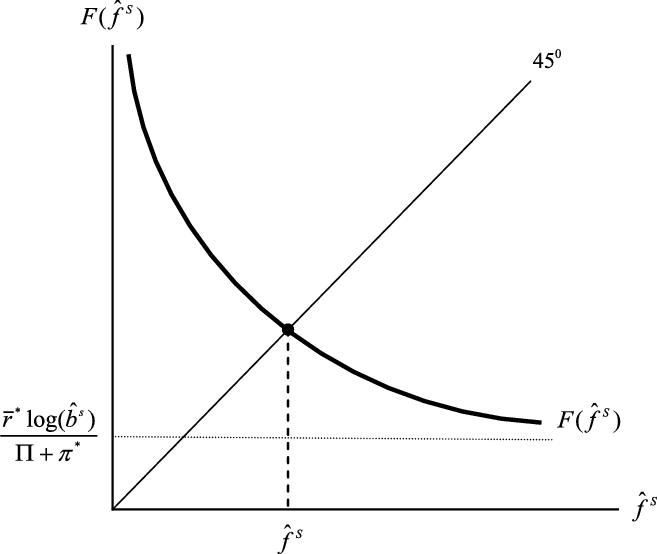
, Figure 4 illustrates that the equilibrium
 $\hat{f}^{s}$
is uniquely determined and located from the intersection of
 $F(\hat{f}^{s})$
and the 45-degree line. Such a property of multiplicity of steady states resulting from multiplicity of the equilibrium stock of net foreign debt is another widely known feature of SOE real business cycle models with a perfect world capital market [Lubik (Reference Lubik2007)].
Existence of a Steady State: SOE with Foreign Debt.

In terms of a steady state’s local stability properties, since the dynamical system (37)–(38) contains only one initial condition on
 $\hat{b}_{0}$
, a unique rational expectations equilibrium requires one root with a negative real part. More than one root with a negative real part implies equilibrium indeterminacy and sunspot equilibria, and all roots with positive real parts indicate nonexistence of a rational expectations equilibrium. I obtain from (37)–(38) that the two eigenvalues are
 $-\frac{d\pi }{d\hat{m}}>0$
and
 $\rho >0$
, respectively. Hence, the following proposition is established.
Proposition 4 For a small-open monetary economy where both diversified currency holdings and borrowing lending in a perfect world capital market are allowed, the model exhibits a unique steady state that is a source, and hence local indeterminacy will not occur.
Note, however, that the above proposition implies any trajectory that diverges away from the completely unstable steady state may settle down to a limit cycle or to some more complicated attracting sets.
4.2 Imperfect world capital market
The preceding subsection’s analysis shows that the model under a perfect world capital market suffers from problems of a zero eigenvalue and multiplicity of steady states. The literature has proposed various solutions for avoiding the zero-root problem.
Footnote 14
In contrast with the proceeding subsection’s analysis, I adopt here the approach of a debt-elastic interest rate risk premium for net foreign debt. As a result, domestic households of the SOE are now postulated to be able to borrow or lend in an imperfect world capital market at an interest rate
 $R^{\ast }$
that increases with the aggregate stock of net foreign debt [see, Turnovsky (Reference Turnovsky1997, p. 43), AgÉnor (Reference AgÉnor1997), Schmitt-GrohÉ and Uribe (Reference Schmitt-GrohÉ and Uribe2003), Lubik (Reference Lubik2007), and Huang et al. (Reference Huang, Meng and Xue2018), among others], that is,
 \begin{equation}R^{\ast }=\bar{R}^{\ast }+p\big(\bar{b}\big) ,\text{ \ \ }p^{\prime}\left( \cdot \right) >0, \end{equation}
where
 $\bar{R}^{\ast }$
is the same fixed world risk-free nominal interest rate shown previously, and
 $p\big(\bar{b}\big) $
is a country-specific interest rate risk premium that is taken as given by domestic households.
Footnote 15
Since agents are assumed to be identical, in equilibrium aggregate per capita stock of net foreign debt equals individual stock of net foreign debt; that is,
 $\bar{b}=b$
.
Under (40), the model’s equilibrium conditions can be collapsed into the following autonomous dynamical system:
 \begin{eqnarray}\overset{\cdot }{\hat{m}} &=&\mu -\pi , \end{eqnarray}
 \begin{eqnarray}\overset{\cdot }{\hat{b}} &=&\frac{\exp [\hat{h}-\hat{b}]-\exp [\hat{c}-\hat{b}]-\pi ^{\ast }\exp [\hat{f}-\hat{b}]+\rho -\frac{f}{b}\frac{\partial \hat{f}}{\partial \hat{m}}\overset{\cdot }{\hat{m}}-\left( 1+\frac{f}{b}\frac{\partial \hat{f}}{\partial \hat{\lambda}}\right) \overset{\cdot }{\hat{\lambda}}}{1+\frac{f}{b}\frac{\partial \hat{f}}{\partial \hat{b}}}, \end{eqnarray}
 \begin{eqnarray}\overset{\cdot }{\hat{\lambda}} &=&\rho -\bar{r}^{\ast }-p(b) .\end{eqnarray}
Here,
 $\pi =\pi (\hat{m},\hat{b},\hat{\lambda})$
,
 $\hat{h}=\hat{h}(\hat{\lambda})$
,
 $\hat{c}=\hat{c}(\hat{m},\hat{b},\hat{\lambda})$
, and
 $\hat{f}=\hat{f}(\hat{m},\hat{b},\hat{\lambda})$
, with the partial derivatives provided in the online appendix.
It is clear from (43) that, because of the debt-elastic interest rate, the shadow value of real financial assets (
 $\hat{\lambda}$
) now depends on an endogenous variable b. The zero root problem is thereby resolved. In addition, in the steady state where
 $\overset{\cdot }{\hat{\lambda}}=0$
, equation (43) with
 $p\left( \cdot \right) $
strictly increasing in b implies the existence of a unique steady-state level of net foreign debt:
 \begin{equation}b^{s}=p^{-1}\left( \rho -\bar{r}^{\ast }\right) . \end{equation}
With this
 $b^{s}$
,
 $F(\infty)\equiv\frac{\bar{r}^{\ast }\log (\hat{b}^{s})}{\Pi +\pi ^{\ast }}$
shown in Figure 4 is uniquely determined. As a result, the steady-state value of
 $\hat{f}^{s}$
determined by the intersection of
 $F(\hat{f}^{s})$
and the 45-degree line exists and is unique. The remaining endogenous variables
 $\{\hat{m}^{s},\hat{y}^{s},\hat{c}^{s},\pi ^{s},\hat{\lambda}^{s},\alpha ^{s}\}$
are then uniquely determined according to (50)–(55). Hence, a debt-elastic interest rate also resolves the problem of steady-state multiplicity.
In terms of the steady state’s local dynamics, I analytically compute the Jacobian matrix of the dynamical system (41)–(43) evaluated at
 $(\hat{m}^{s},\hat{b}^{s},\hat{\lambda}^{s})$
and find that it is hard to derive the analytical condition for (in)determinacy.
Footnote 16
Hence, I resort to a numerical method to show how the minimum value of the annual foreign inflation rate
 $\pi ^{\ast }$
needed for equilibrium indeterminacy depends on the degree of currency substitution (
 $\theta $
), the degree of openness in terms of diversified currency holdings (
 $\delta $
), and the elasticity of the risk premium with respect to net foreign debt (
 $\varepsilon $
).
I first follow Nason and Rogers (Reference Nason and Rogers2006) in postulating a linear interest rate risk premium function:
 $p\left( b\right) =\varepsilon b$
; this is also the risk premium function adopted by Airaudo (Reference Airaudo2014) when carrying out the quantitative analysis.
Footnote 17
A larger coefficient
 $\varepsilon =p^{\prime }\left( \cdot\right) >0$
in the risk premium function indicates how more sensitively the risk premium responds to a deterioration in the borrower’s credit quality (i.e. an increase in b). It follows that the steady-state level of net foreign debt is:
 $b^{s}=\left( \rho -\bar{r}^{\ast }\right) /\varepsilon $
. Hence, an increase in the risk-free real interest rate
 $\bar{r}^{\ast }$
by raising the borrowing cost reduces the stock of net foreign debt. A higher elasticity of the risk premium with respect to net foreign debt (
 $\varepsilon $
) also reduces the amount borrowed, since it represents a stronger punishment to borrowers’ credit quality deteriorations.
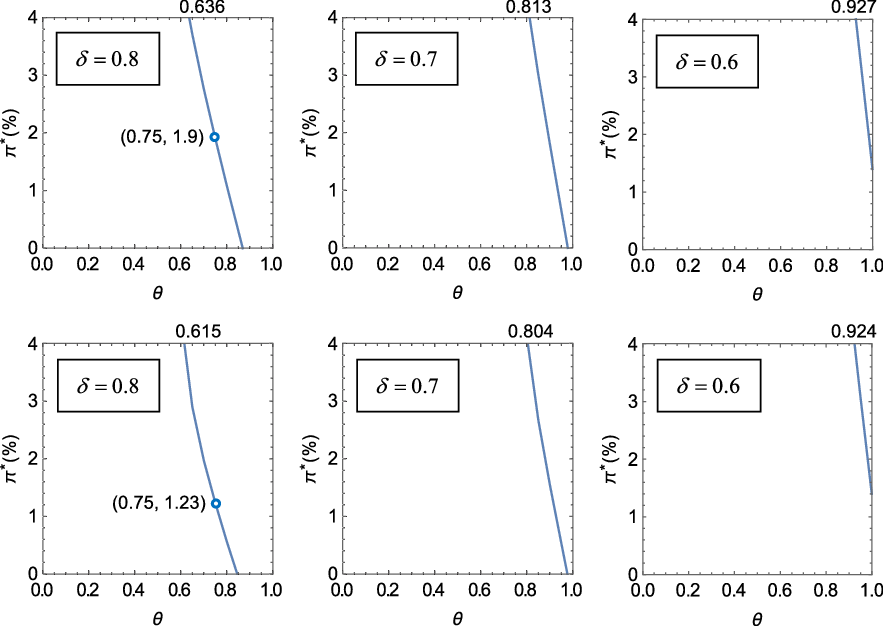
I first present in Figure 5 the benchmark case where
 $\varepsilon $
takes on the value of
 $0.1$
[Airaudo (Reference Airaudo2014)]. In addition to the baseline calibration of
 $\rho =0.01$
,
 $\gamma =2$
,
 $\mu =0.04/4$
, and
 $a=0.5$
, the world risk-free nominal interest rate
 $\bar{R}^{\ast }$
is set equal to
 $0.04/4$
[Schmitt-GrohÉ and Uribe (Reference Schmitt-GrohÉ and Uribe2003); Huang et al. (Reference Huang, Meng and Xue2018)]. This value of
 $\bar{R}^{\ast }$
further restricts the foreign inflation rate to be lower than
 $0.04/4$
, so as to ensure a nonnegative risk-free real interest rate,
 $\bar{r}^{\ast }=\bar{R}^{\ast }-\pi ^{\ast }$
. The calibrated values of
 $\varepsilon $
,
 $\rho $
, and
 $\bar{R}^{\ast }$
, along with the highest possible value of
 $\pi ^{\ast }=0.04/4$
, imply an upper bound for the net foreign debt, denoted as
 $\bar{b}=10\%$
. As in Figure 3, Figure 5 contains two rows (
 $\sigma =10$
and 8). However, since under the baseline calibration indeterminacy will not occur when
 $\delta <0.51$
, the three columns of Figure 4, respectively, present the cases where
 $\delta =0.8$
,
 $0.7$
, and
 $0.6$
.
Requisite
 $\pi^*$
for Indeterminacy: Foreign Debt under
 $\varepsilon=0.1\;(\bar{b}=10\%).$

As in Figure 3 where international borrowing and lending are absent, Figure 5 depicts that the requisite level of
 $\pi ^{\ast }$
for indeterminacy: (i) rises when the degree of currency substitution
 $\theta $
falls; (ii) rises when
 $\delta $
falls (meaning that the degree of openness in terms of diversified currency holdings increases); and (iii) slightly increases when the value of
 $\sigma $
declines from 10 to 8. In these cases, belief-driven cyclical fluctuations become more difficult to occur.
Figure 5 clearly reveals that, when the degree of currency substitution
 $\theta $
is sufficiently high, indeterminacy can occur under very low rates of foreign inflation. A comparison between Figures 3 and 5 thus highlights that, in line with the finding of Chen (Reference Chen2018), domestic agents’ access to an imperfect world capital market to borrow/lend internationally may increase the possibility of equilibrium indeterminacy and sunspot equilibria. The benchmark results shown in Figure 4 indicate that equilibrium indeterminacy is impossible when
 $\theta =0.75$
and when the share of domestic currency in total liquidity
 $\delta \leq 0.8$
.
I next present in Figure 6 cases where the elasticity of the risk premium with respect to foreign debt (
 $\varepsilon $
) takes on lower values, implying higher levels of the upper bound for the net foreign debt
 $\bar{b}$
. The top and bottom panels, respectively, illustrate the cases where
 $\varepsilon =0.02$
and
 $0.01$
, and their corresponding
 $\bar{b}$
are 50% and 100%. It is evident that as
 $\varepsilon $
declines and
 $\bar{b}$
rises, the minimum level of foreign inflation for belief-driven fluctuations to occur falls. This implies that setting a sufficiently low upper bound for the stock of net foreign debt
 $\bar{b}$
(or a sufficiently high
 $\varepsilon $
) can help stabilize the domestic economy by mitigating cyclical fluctuations caused by agents’ animal spirits.
Requisite
 $\pi^*$
for Indeterminacy: Foreign Debt under
 $\sigma=8$
. Top Panel:
 $\sigma=0.02\;(\bar{b}=50\%)$
; Bottom Panel:
 $\sigma=0.01\;(\bar{b}=100\%)$
.

The above finding on the stabilizing role of an increase in
 $\varepsilon $
is consistent with that obtained in Chen (Reference Chen2018). As I highlight in the top panel of Figure 6 where
 $\varepsilon $
reduces to
 $0.02$
and
 $\bar{b}$
increases to 50%, a value of
 $\theta =0.75$
allows for the occurrence of equilibrium indeterminacy only if the degree of openness in terms of diversifies currency holdings is low (
 $\delta =0.8$
) and if the annual foreign inflation rate is above
 $1.9\%$
. Likewise, the bottom panel depicts that, when
 $\varepsilon $
further reduces to
 $0.01$
and
 $\bar{b}$
increases to 100%, equilibrium indeterminacy occurs under
 $\theta =0.75$
when
 $\delta =0.8$
and
 $\pi ^{\ast }>1.23\%$
.
Finally, when
 $\delta \rightarrow 1$
such that domestic agents in the SOE do not hold the foreign currency, determinacy is impossible in the calibrated version of the SOE for all nonnegative values of the foreign inflation rate. Figure 5 illustrates that, as is true in Figure 5, when the degree of openness in terms of diversified currency holdings increases (
 $\delta $
falls), it requires a higher foreign inflation rate for equilibrium indeterminacy to occur. This subsection’s analysis thus demonstrates that Section 3’s result, in which currency substitution operates as an automatic stabilizer that alleviates aggregate fluctuations in a SOE, is robust to the inclusion of an imperfect world capital market where domestic agents finance a shortage of funds or lend surplus funds.
5. Conclusion
I herein show that diversified currency holdings stabilize Farmer’s (1997) indeterminate money-in-the-utility-function closed economy. The stabilizing effect of diversified currency holdings on domestic aggregate stability is robust to the inclusion of a world capital market in which domestic agents are able to finance a shortage of funds or lend surplus funds, and to whether domestic and foreign currencies are Edgeworth substitutes or complements, or are additively separable in the household’s preferences.
The paper can be extended in several directions. For example, it would be worthwhile to incorporate capital accumulation and to analyze two-country models of international trade [Nishimura and Shimomura (Reference Nishimura and Shimomura2002); Nishimura and Shimomura (Reference Nishimura and Shimomura2006); Nishimura et al. (Reference Nishimura, Venditti and Yano2010); Huang et al. (Reference Huang, Meng and Xue2018); Huang et al. (Reference Huang, Meng and Xue2017)]. I can also incorporate features that are commonly adopted in the new-Keynesian literature, such as nominal price/wage rigidities and investment adjustment costs, among others. In addition, I may follow Özbilgin (2012) to consider firms financing their working capital by borrowing in the international capital market. Finally, it would be worth analyzing the effect of diversified currency holdings on the domestic country’s aggregate stability within overlapping generations (OLG) models. In particular, it is widely known that an OLG closed economy with finitely lived agents easily displays a continuum of equilibria. Footnote 18 In a two-country model, Karaken and Wallace (Reference Karaken and Wallace1981) find another implication of an OLG model that leads to exchange rate indeterminacy under unrestricted portfolio choices of fiat monies. These possible extensions will allow me to further enhance the understanding of the dynamic (in)stability effects of currency substitution. I plan to pursue these research projects in the future.
Acknowledgements I would like to thank William A. Barnett (Editor), Roger Farmer (Co-Editor), two anonymous referees, Been-Lon Chen, Yiting Li, Pei-Ju Liao, Chia-Hui Lu, Partha Sen, Etsuro Shioji, Yi-Chan Tsai, Chien-Chiang Wang, and seminar participants at the International Conference on Public Economic Theory, Chinese Economic Association in North America at the ASSA Meetings, National Taiwan University, National Taipei University, and Tunghai University for helpful comments and suggestions.
Supplementary materials. To view supplementary material for this article, please visit http://dx.doi.org/10.1017/ S136510052100047X.
A. Appendix
This appendix presents the steady-state solutions of endogenous variables for Section 2’s closed economy and Section 3’s SOE under diversified currency holdings. The steady state of the closed economy is characterized by
 \begin{eqnarray}\hat{m}^{s} &=&\log \left[ a^{a\left( 1-\sigma \right) -\gamma }\left( \frac{1-a}{\mu +\rho }\right) ^{\Sigma +\gamma }\right] ^{\frac{1}{\gamma +\sigma }}, \end{eqnarray}
 \begin{eqnarray}\hat{y}^{s} &=&\hat{h}^{s}=\hat{c}^{s}=\log \left[ a^{a\left( 1-\sigma\right) +\sigma }\left( \frac{1-a}{\mu +\rho }\right) ^{\Sigma -\sigma }\right] ^{\frac{1}{\gamma +\sigma }}, \end{eqnarray}
 \begin{eqnarray}\pi ^{s} &=&\mu , \end{eqnarray}
 \begin{eqnarray}\hat{\lambda}^{s} &=&\log \left[ \frac{a^{\frac{1}{\Sigma -\sigma }-1}\left(1-a\right) }{\mu +\rho }\right] ^{\frac{\left( \Sigma -\sigma \right) \gamma}{\gamma +\sigma }}. \end{eqnarray}
For Section 3’s SOE, I obtain that
 \begin{eqnarray}\hat{f}^{s} &=&\log \left[ \frac{a}{\Pi ^{\Sigma }\left( \Pi +\pi ^{\ast}\right) ^{\gamma }}\right] ^{\frac{1}{\gamma +\sigma }}+\log \left\{ \delta \left[ \frac{\Xi \left( \pi ^{\ast }+\rho \right) }{\mu +\rho }\right]^{\theta }+1-\delta \right\} ^{\frac{\Sigma -\sigma }{\left( \gamma +\sigma\right) \theta }}, \end{eqnarray}
 \begin{eqnarray}\hat{m}^{s} &=&\hat{f}^{s}+\log \left[ \frac{\Xi \left( \pi ^{\ast }+\rho\right) }{\mu +\rho }\right] , \end{eqnarray}
 \begin{eqnarray}\hat{y}^{s} &=&\hat{h}^{s}=\hat{f}^{s}+\log \left( \Pi +\pi ^{\ast }\right) , \end{eqnarray}
 \begin{eqnarray}\hat{c}^{s} &=&\hat{f}^{s}+\log \left( \Pi \right) , \end{eqnarray}
 \begin{eqnarray}\pi ^{s} &=&\mu , \end{eqnarray}
 \begin{eqnarray}\hat{\lambda}^{s} &=&\gamma \hat{f}^{s}+\log \left( \Pi +\pi ^{\ast }\right)^{\gamma }, \end{eqnarray}
 \begin{eqnarray}\alpha ^{s} &=&\frac{\Xi }{1+\Xi }. \end{eqnarray}