1. Introduction
The term complex networks usually refers to various large real-world networks, occurring in diverse fields of science, that appear to exhibit very similar graph theoretical properties. These include having a constant average degree, a so-called power-law degree sequence, clustering and ‘small distances’. In this paper we study a random graph model that was recently proposed as a model for complex networks and has the above properties. We refer to it as the Krioukov–Papadopoulos–Kitsak–Vahdat–Boguñá model, or KPKVB model, after its inventors [Reference Krioukov15]. We should however point out that many authors simply refer to the model as ‘hyperbolic random geometric graphs’ or even ‘hyperbolic random graphs’. In the KPKVB model a random geometric graph is constructed in the hyperbolic plane. We use the Poincaré disk representation of the hyperbolic plane, which is obtained when the unit disk  ${\mathbb D} = \{(x,y) \in \mathbb{R}^2 \colon x^2 +
y^2 \lt 1\}$ is equipped with the metric given by the differential form
 $\,\mathrm{d}
s^2 = 4{(\!\,\mathrm{d} x^2 + \,\mathrm{d} y^2)}/{(1-x^2-y^2)^2}$. (This means that the length of a curve
 $\gamma \colon [0,1]\to{\mathbb D}$ under the metric is given by
 $2 {\int_0^1}({\sqrt{(\gamma_1'(t))^2+(\gamma_2'(t))^2}}
/{(1-\gamma_1^2(t) -\gamma_2^2(t))}){\,\mathrm{d}}t$.) For an extensive, readable introduction to hyperbolic geometry and the various models and properties of the hyperbolic plane, we refer the reader to [Reference Stillwell17]. Throughout this paper we will represent points in the hyperbolic plane by polar coordinates
 $(r,\vartheta)$, where
 $r \in [0,\infty)$ denotes the hyperbolic distance of a point to the origin and
 $\vartheta$ denotes its angle with the positive x-axis.
We now discuss the construction of the KPKVB random graph. The model has three parameters: the number of vertices N and two additional parameters  $\alpha, \nu > 0$. Usually the behavior of the random graph is studied for
 $N \to \infty$ for a fixed choice of
 $\alpha$ and
 $\nu$. We start by setting
 $R = 2\log(N/\nu)$. Inside the disk
 $\mathcal{D}_R$ of radius R centered at the origin in the hyperbolic plane we select N points, independent from each other, according to the probability density f on
 $[0,R] \times ({-}\pi, \pi]$ given by
 \[
f(r,\vartheta) = \frac{1}{2\pi} \frac{\alpha \sinh(\alpha r)} {\cosh(\alpha
R)-1}, \qquad r \in [0,R],\, \vartheta \in ({-}\pi,\pi].
\]
We call this distribution the  $(\alpha,R)$-quasi uniform distribution. For
 $\alpha=1$, this corresponds to the uniform distribution on
 $\mathcal{D}_R$. We connect points if and only if their hyperbolic distance is at most R. In other words, two points are connected if their hyperbolic distance is at most the (hyperbolic) radius of the disk that the graph lives on. We denote the random graph we have thus obtained by
 $G(N;\,\alpha,\nu)$.
As observed by Krioukov et al. [Reference Krioukov15] and rigorously shown by Gugelmann et al. [Reference Gugelmann, Panagiotou, Peter and Czumaj10], the degree distribution follows a power law with exponent  $2\alpha+1$, the average degree tends to
 $2{\alpha ^2}\nu /\pi {(\alpha - {\textstyle{1 \over 2}})^2}$ when
 $\alpha > {\textstyle{1 \over 2}}$, and the (local) clustering coefficient is bounded away from zero a.a.s. (Here and in the rest of the paper a.a.s. stands for asymptotically almost surely, meaning with probability tending to 1 as
 $N\to\infty$.) Earlier works of the first author with Bode and Fountoulakis [Reference Bode, Fountoulakis and Müller4] and Fountoulakis [Reference Fountoulakis and Müller7] established the ‘threshold for a giant component’: when
 $\alpha \lt 1,$ there is always a unique component of size linear in N no matter how small
 $\nu$ (and hence the average degree) is; when
 $\alpha > 1,$ all components are sublinear no matter the value of
 $\nu$; and when
 $\alpha=1,$ there is a critical value
 $\nu_{\text{c}}$ such that, for
 $\nu \lt \nu_{\text{c}},$ all components are sublinear and, for
 $\nu > \nu_{\text{c}},$ there is a unique linear sized component (all of these statements holding a.a.s.). Whether or not there is a giant component when
 $\alpha=1$ and
 $\nu=\nu_{\text{c}}$ remains an open problem.
In another paper of the first author with Bode and Fountoulakis [Reference Bode, Fountoulakis and Müller5] it was shown that  $\alpha={{\textstyle{1 \over 2}}
}$ is the threshold for connectivity: for
 $\alpha
\lt {{\textstyle{1 \over 2}}
},$ the graph is a.a.s. connected; for
 $\alpha>{{\textstyle{1 \over 2}}
},$ the graph is a.a.s. disconnected; and when
 $\alpha={{\textstyle{1 \over 2}}
},$ the probability of being connected tends to a continuous, nondecreasing function of
 $\nu$ which is identically 1 for
 $\nu \geq \pi$ and strictly less than 1 for
 $\nu \lt \pi$.
Friedrich and Krohmer [Reference Friedrich and Krohmer8] studied the size of the largest clique as well as the number of cliques of a given size. Bläsius et al. [Reference Bläsius, Friedrich, Krohmer, Laue, Sankowski, Zaroliagis and Dagstuhl3] and Boguña et al. [Reference Boguñá, Papadopoulos and Krioukov6] considered fitting the KPKVB model to data using maximum likelihood estimation. Kiwi and Mitsche [Reference Kiwi and Mitsche14] studied the spectral gap and related properties, and Bläsius et al. [Reference Bläsius, Friedrich, Krohmer, Sankowski, Zaroliagis and Dagstuhl2] considered the treewidth and related parameters of the KPKVB model.
Abdullah et al. [Reference Abdullah, Bode and Fountoulakis1] considered typical distances in the graph. That is, they sampled two vertices of the graph uniformly at random from the set of all vertices and considered the (graph-theoretic) distance between them. They showed that this distance between two random vertices, conditional on the two points falling in the same component, is precisely  $(c + o(1))\log \log N$ a.a.s. for
 ${{\textstyle{1 \over 2}}
} \lt \alpha \lt 1$, where
 $c :\!= - 2 \log(2\alpha-1)$.
Here we will study another natural notion related to the distances in the graph, the graph diameter. Recall that the diameter of a graph G is the supremum of the graph distance  $d_G(u,v)$ over all pairs u, v of vertices (so it is infinite if the graph is disconnected). It has been shown previously by Kiwi and Mitsche [Reference Kiwi and Mitsche13] that, for
 $\alpha \in
({{\textstyle{1 \over 2}}
},1),$ the largest component of
 $G(N;\,\alpha,\nu)$ has a diameter that is
 $O((\!\log N)^{8/(1-\alpha)(2-\alpha)} )$ a.a.s. This was subsequently improved by Friedrich and Krohmer [Reference Friedrich, Krohmer and Halldórsson9] to
 $O( (\!\log
N)^{1/(1-\alpha)} )$. Friedrich and Krohmer [Reference Friedrich, Krohmer and Halldórsson9] also gave an a.a.s. lower bound of
 $\Omega(\!\log N)$. We point out that in these upper bounds the exponent of
 $\log N$ tends to
 $\infty$ as
 $\alpha$ approaches 1.
Here we are able to improve the upper bound to  $O(\!\log N)$, which is sharp up to a multiplicative constant. We are able to prove this upper bound not only in the case when
 $\alpha \lt 1$ but also in the case when
 $\alpha=1$ and
 $\nu$ is sufficiently large.
Theorem 1. Let  $\alpha, \nu > 0$ be fixed. If either
(i)
 $\frac12 \lt \alpha \lt 1$ and $\nu > 0$ is arbitrary, or
(ii)
$\alpha = 1$ and $\nu$ is sufficiently large,


then, a.a.s. as  $N\to\infty$, every component of
 $G(N;\, \alpha, \nu)$ has diameter
 $O(\!\log(N))$.
We remark that our result still leaves open what happens for other choices of  $\alpha$ and
 $\nu$ as well as several related questions. See Section 5 for a more elaborate discussion of these.
1.1. Organization of the paper
In our proofs we will also consider a Poissonized version of the KPKVB model, where the number of points is not fixed but is sampled from a Poisson distribution with mean N. This model is denoted  $G_{\mathop{\textrm{Po}}}(N;\,
\alpha, \nu)$. It is convenient to work with this Poissonized version of the model as it has the advantage that the numbers of points in disjoint regions are independent (see, for instance, [Reference Kingman12]).
The paper is organized as follows. In Section 2 we discuss a somewhat simpler random geometric graph  $\Gamma$, introduced in [Reference Fountoulakis and Müller7], that behaves approximately the same as the (Poissonized) KPKVB model. The graph
 $\Gamma$ is embedded into a rectangular domain
 $\mathcal{E}_R$ in the Euclidean plane
 $\mathbb{R}^2$. In Section 3.1 we discretize this simplified model by dissecting
 $\mathcal{E}_R$ into small rectangles. In Section 3.2 we show how to construct short paths in
 $\Gamma$. The constructed paths have length
 $O(\!\log(N))$ unless there exist large regions that do not contain any vertex of
 $\Gamma$. In Section 3.3 we use the observations of Section 3.2 to formulate sufficient conditions for the components of the graph
 $\Gamma$ to have diameter
 $O(\!\log N)$. In Section 4 we show that the probability that
 $\Gamma$ fails to satisfy these conditions tends to 0 as
 $N \to
\infty$. We also translate these results to the KPKVB model, and combine everything into a proof of Theorem 1.
2. The idealized model
We start by introducing a somewhat simpler random geometric graph, introduced in [Reference Fountoulakis and Müller7], that will be used as an approximation of the KPKVB model. Let  $X_1$,
 $X_2$, …
 $\in \mathcal{D}_R$ be an infinite supply of points chosen according to the
 $(\alpha,R)$-quasi uniform distribution on
 $\mathcal{D}_R$ described above. Let
 $G = G(N;\,
\alpha,\nu)$ and
 $G_{\mathop{\textrm{Po}}} = G_{\mathop{\textrm{Po}}}(N;\, \alpha, \nu)$. Let
 $Z \sim \mathop{\textrm{Po}}(N)$ be the number of vertices of
 $G_{\mathop{\textrm{Po}}}$. By taking
 $\{X_1,\ldots,X_N\}$ as the vertex set of G and
 $\{X_1,\ldots,X_Z\}$ as the vertex set of
 $G_{\mathop{\textrm{Po}}}$, we obtain a coupling between G and
 $G_{\mathop{\textrm{Po}}}$.
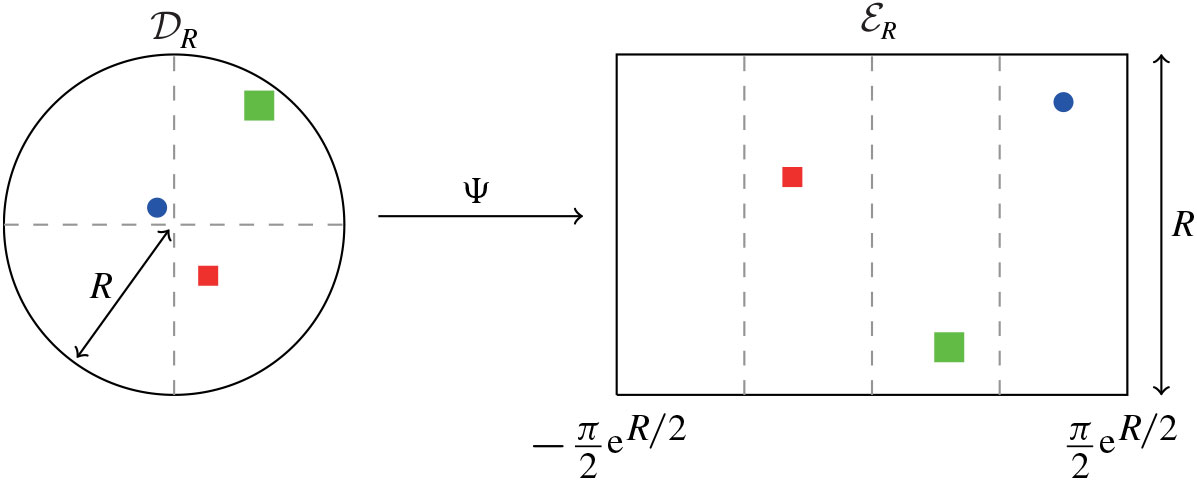
We will compare our hyperbolic random graph to a random geometric graph that lives on the Euclidean plane. To this end, we introduce the map  $\Psi\colon \mathcal{D}_R \to \mathbb{R}^2$ given by
 $\Psi\colon
(r,\vartheta) \mapsto (\vartheta {\frac12} \mathrm{e}^{R/2}, R-r). $ The map
 $\Psi$ works by taking the distance of a point to the boundary of the disk as the y-coordinate and the angle of the point as the x-coordinate (after scaling by
 ${{\textstyle{1 \over 2}}
} \mathrm{e}^{R/2}$). The image of
 $\mathcal{D}_R$ under
 $\Psi$ is the rectangle
 $\mathcal{E}_R =
({-}{\pi}\mathrm{e}^{R/2}/{2} , {\pi}\mathrm{e}^{R/2}/{2} ] \times [0,R] \subset
\mathbb{R}^2$ (see Figure 1).
 $\Psi$ maps
 $\mathcal{D}_R$ to a rectangle
 $\mathcal{E}_R
\subset \mathbb{R}^2$.

On  $\mathcal{E}_R$ we consider the Poisson point process
 $\mathcal{P}_{\alpha, \lambda}$ with intensity function
 $f_{\alpha,\lambda}$ defined by
 $f_{\alpha,\lambda}(x,y) = \lambda
\mathrm{e}^{-\alpha y}$. We will denote by
 $V_{\alpha,\lambda}$ the point set of this Poisson process. We also introduce the graph
 $\Gamma_{\alpha,\lambda}$, with vertex set
 $V_{\alpha,\lambda}$, where points
 $(x,y), (x',y') \in V_{\alpha,\lambda}$ are connected if and only if
 $|x-x'|_{\pi \mathrm{e}^{R/2}} \leq \mathrm{e}^{(y+y')/2}$. Here
 $|a-b|_{d} =
\inf_{k \in \mathbb{Z}} |a-b+kd|$ denotes the distance between a and b modulo d.
If we choose  $\lambda = {\nu \alpha}/{\pi}$ it turns out that
 $V_{\lambda}$ can be coupled to the image of the vertex set of
 $G_{\mathop{\textrm{Po}}}$ under
 $\Psi$ and that the connection rule of
 $\Gamma_{\lambda}$ approximates the connection rule of
 $G_{\mathop{\textrm{Po}}}$. In particular, we have the following result.
Lemma 1. ([Reference Fountoulakis and Müller7, Lemma 27].) Let  $\alpha>{{\textstyle{1 \over 2}}
}$. There exists a coupling such that a.a.s.
 $V_{\alpha, \nu \alpha/\pi}$ is the image of the vertex set of
 $G_{\mathop{\textrm{Po}}}$ under
 $\Psi$.
Let  $\tilde{X}_1$,
 $\tilde{X}_2$,
 $\ldots \in \mathcal{E}_R$ be the images of
 $X_1$,
 $X_2$, … under
 $\Psi$. On the coupling space of Lemma 1, a.a.s. we have
 $V_{\lambda} = \{\tilde{X}_1,
\ldots, \tilde{X}_Z\}$.
Lemma 2. ([Reference Fountoulakis and Müller7, Lemma 30].) Let  $\alpha>{\textstyle{1 \over 2}}
$. On the coupling space of Lemma 1, a.a.s. it holds for
 $1 \leq i,j \leq Z$ that
(i) if
$r_i,r_j \geq {{\textstyle{1 \over 2}}
R}$ and $\tilde{X}_i\tilde{X}_j \in
E(\Gamma_{\alpha,\nu \alpha/\pi})$, then $X_iX_j \in E(G_{\mathop{\textrm{Po}}})$.(ii) if
$r_i,r_j \geq {{\textstyle{3 \over 4}}R}$ then $\tilde{X}_i\tilde{X}_j \in
E(\Gamma_{\alpha,\nu \alpha/\pi})$ if and only if $X_iX_j \in
E(G_{\mathop{\textrm{Po}}})$.


Here  $r_i$ and
 $r_j$ denote the radial coordinates of
 $X_i,X_j \in
\mathcal{D}_R$.
Lemma 2 will prove useful later because, as it turns out, cases (i) and (ii) cover almost all the edges in the graph.
For  ${({A_i})_i}$ and
 ${({B_i})_i}$, two sequences of events with
 $A_i$ and
 $B_i$ defined on the same probability space
 $(\Omega_i,\mathcal{A}_i,{{\mathbb P}}_i)$, we say that
 $A_i$ happens a.a.s. conditional on
 $B_i$ if
 $\mathbb{P}(A_i \ \,\,|\, \ \,
B_i) \to 1$ as
 $i \to \infty$. By a straightforward adaptation of the proofs given in [Reference Fountoulakis and Müller7], we can show the following result.
Corollary 1. The conclusions of Lemmas 1 and 2 also hold conditional on the event  $Z=N$.
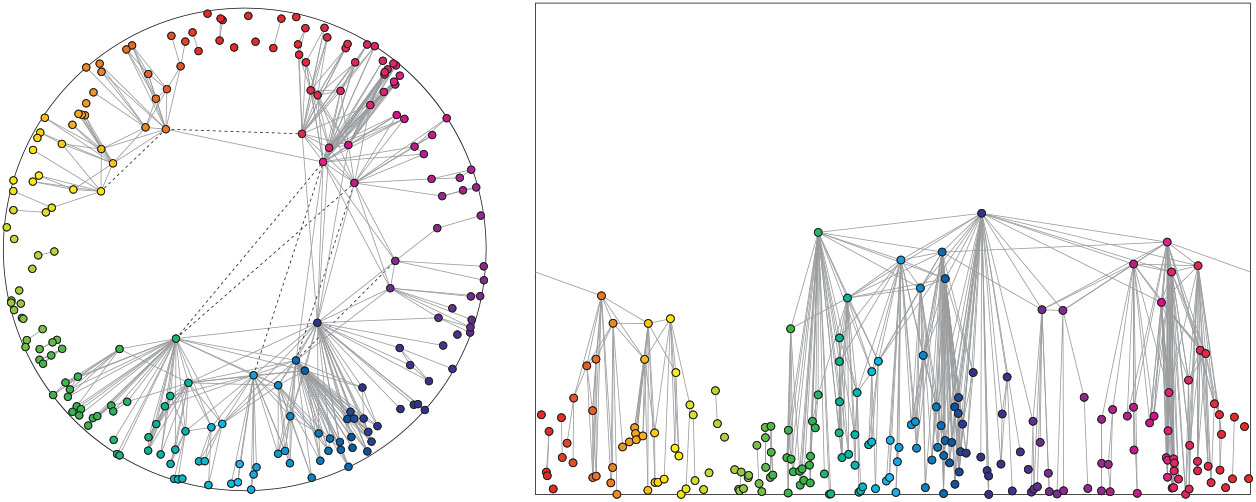
In other words, Corollary 1 states that the probability that the conclusions of Lemmas 1 and 2 fail, given that  $Z=N$, is also o(1). For completeness, we prove this as Lemmas 15 and 16 in Appendix A. An example of
 $G_{\mathop{\textrm{Po}}}$ and
 $\Gamma_{\nu \alpha/\pi}$ is shown in Figure 2.
An example of the Poissonized KPKVB random graph  $G_{\mathop{\textrm{Po}}}$ (left) and the graph
 $\Gamma_{\alpha,\nu \alpha/\pi}$ (right), under the coupling of Lemma 1. The graph
 $G_{\mathop{\textrm{Po}}}$ is drawn in the native model of the hyperbolic plane, where a point with hyperbolic polar coordinates
 $(r,\vartheta)$ is plotted with Euclidean polar coordinates
 $(r,\vartheta)$. Points are colored based on their angular coordinate. Dashed edges indicate edges for which the coupling fails. The parameters used are
 $N=200$,
 $\alpha=0.8,$ and
 $\nu = 1.3$.

3. Deterministic bounds
For the moment, we continue in a somewhat more general setting, where  $V
\subset \mathcal{E}_R$ is any finite set of points and
 $\Gamma$ is the graph with vertex set V and connection rule
 $(x,y) \sim (x',y')\Leftrightarrow|x-x'|_{\pi \mathrm{e}^{R/2}} \leq \mathrm{e}^{(y+y')/2}$.
3.1. A discretization of the model
We dissect  $\mathcal{E}_R$ into a number of rectangles, which have the property that vertices of
 $\Gamma$ in rectangles with nonempty intersection are necessarily connected by an edge. This is done as follows. First, divide
 $\mathcal{E}_R$ into
 $\ell+1$ layers
 $L_0$,
 $L_1$, …,
 $L_{\ell}$, where
 \begin{equation*}
L_i = \{(x,y) \in \mathcal{E}_R\colon i\, {\log}(2) \leq y \lt (i+1) \log(2)\}
\end{equation*}
for  $i \lt \ell$ and
 $L_{\ell} = \{(x,y) \in \mathcal{E}_R\colon y \geq
\ell \log(2)\}$. Here
 $\ell$ is defined by
 \begin{equation}
\ell :\!= \Big\lfloor \frac{\log(6\pi) + R/2}{\log(2)} \Big\rfloor.
\label{eqn1}
\end{equation}(1)
Note that this gives  $6\pi \mathrm{e}^{R/2} \geq 2^{\ell} > 3\pi \mathrm{e}^{R/2}$. We divide
 $L_i$ into
 $2^{\ell-i}$ (closed) rectangles of equal width
 $2^{i-\ell} \pi \mathrm{e}^{R/2} = 2^{i} b$, where
 $b = 2^{-\ell} \pi \mathrm{e}^{R/2}
\in [{\textstyle{1 \over 6}}
,{\textstyle{1 \over 3}}
)$ is the width of a rectangle in the lowest layer
 $L_0$ (see Figure 3). In each layer, one of the rectangles has its left edge on the line
 $x=0$. We have now partitioned
 $\mathcal{E}_R$ into
 $2^{\ell+1}-1 = O(N)$ boxes.
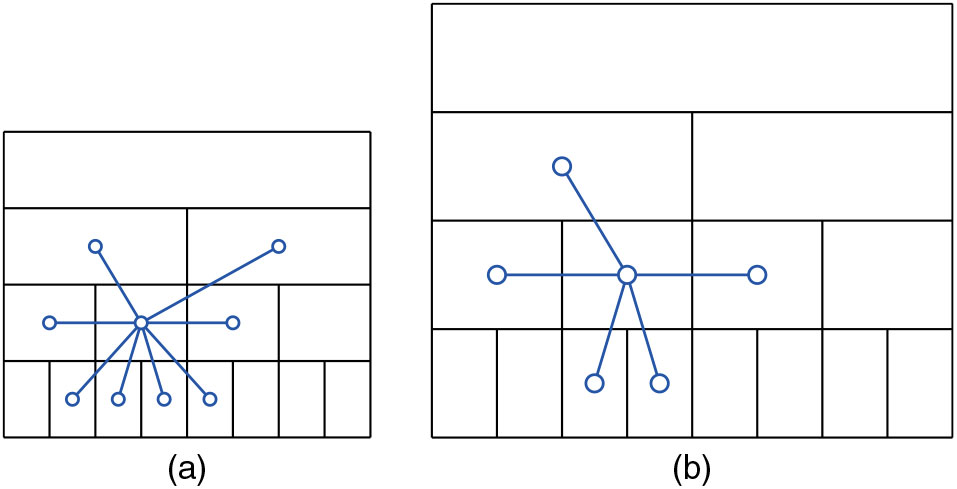
The boxes are the vertices of a graph  $\mathcal{B}$
 $\mathcal{B}$ in which two boxes are connected if they share at least a corner (see Figure 4(a)). Here we identify the left and right edges of
 $\mathcal{E}_R$ with each other, so that (for example) also the leftmost and rightmost box in each layer become neighbors. The dissection has the following properties.
Partitioning  $\mathcal{E}_R$ with boxes. All layers except
 $L_{\ell}$ have height
 $\log(2)$. The boxes in layer
 $L_i$ have width
 $2^i b$, where
 $b \in [\frac16,\frac13)$ is the width of a box in
 $L_0$. The small circles serve as an example of V.

Lemma 3. The following statements hold for  $\mathcal{B}$ and
 $\Gamma$:
(i) if vertices of
$\Gamma$ lie in boxes that are neighbors in $\mathcal{B}$ then they are connected by an edge in $\Gamma$;(ii) the number of boxes that lie (partly) above the line
$y=R/2$ is at most 63.


Proof. We start with (i). Consider two points (x, y) and (x’, y’) that lie in boxes that are neighbors in  $\mathcal{B}$. Suppose that the lowest of these two points lies in
 $L_i$. Then
 $y,y'\geq i\,{\log}(2)$. Furthermore, the horizontal distance between (x, y) and (x’, y’) is at most three times the width of a box in
 $L_i$. It follows that
 \[
|x-x'|_{\pi \mathrm{e}^{R/2}} \leq 3 \cdot 2^i \cdot b \leq 2^i \leq
\mathrm{e}^{(y+y')/2},
\]
so (x, y) and (x’, y’) are indeed connected in  $\Gamma$.
To show (ii), we note that the first layer  $L_i$ that extends above the line
 $y=R/2$ has index
 $i = \lfloor {(R/2)}/{\log 2} \rfloor$. Therefore, we must count the boxes in the layers
 $L_i, L_{i+1}, \ldots, L_{\ell}$, of which there are
 $2^{\ell-i+1} - 1$. We have
 \[
\ell-i+1 = \Big\lfloor \frac{\log(6\pi) + R/2}{\log 2} \Big\rfloor -
\Big\lfloor \frac{R/2}{\log 2} \Big\rfloor + 1 \leq \Big\lceil
\frac{\log(6\pi)}{\log 2} \Big\rceil + 1 = 6,
\]
so there are indeed at most  $2^6-1=63$ boxes that extend above the line
 $y=R/2$.
Let  $\mathcal{B}^\ast$ be the subgraph of
 $\mathcal{B}$ where we remove the edges between boxes that have only a single point in common (see Figure 4(b)). Note that
 $\mathcal{B}^\ast$ is a planar graph and that
 $\mathcal{B}$ is obtained from
 $\mathcal{B}^\ast$ by adding the diagonals of each face ([Reference Kesten11] deals with a more general notation of matching pairs of graphs). We make the following observation (see Figure 5; compare Proposition 2.1 of [Reference Kesten11]) for later reference.
The connection rules of  $\mathcal{B}$ and
 $\mathcal{B}^\ast$. (a) A box with its eight neighbors in
 $\mathcal{B}.$ (b) A box with its five neighbors in
 $\mathcal{B}^\ast$.

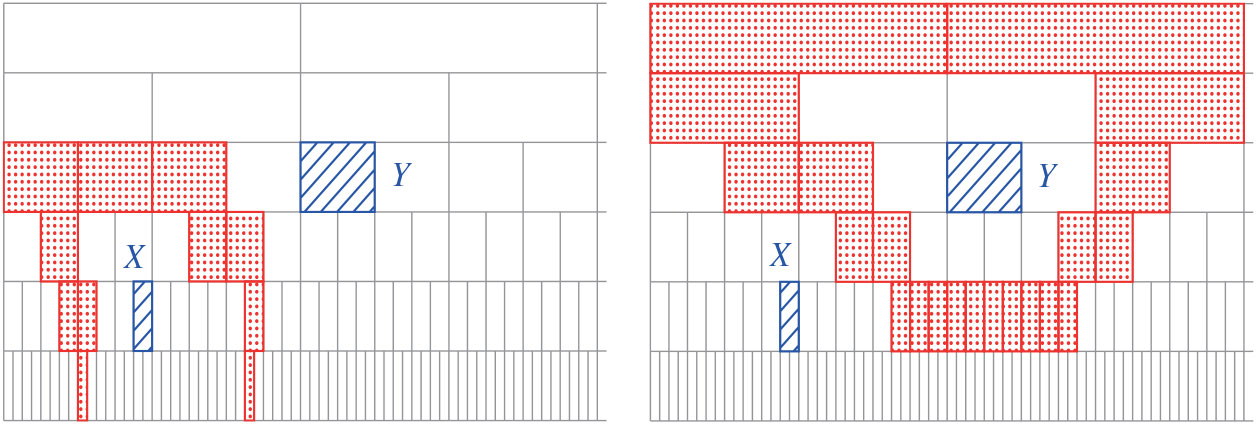
Lemma 4. Suppose that each box in  $\mathcal{B}$ is colored red or blue. If there is no path of blue boxes in
 $\mathcal{B}$ between two blue boxes X and Y, then
 $\mathcal{B}^\ast$ (and, hence, also
 $\mathcal{B}$) contains a walk of red boxes Q that intersects every walk (and, hence, also every path) in
 $\mathcal{B}$ from X to Y.
We leave the straightforward proof of this last lemma to the reader. It can, for instance, be derived quite succinctly from the Jordan curve theorem. A proof can be found in the MSc thesis of the second author [Reference Staps16].
3.2 Constructing short paths
We will use the boxes defined in the previous subsection to construct short paths between vertices of  $\Gamma$. Recall that
 $V \subset
\mathcal{E}_R$ is an arbitrary finite set of points and
 $\Gamma$ is the graph with vertex set V and connection rule
 $(x,y) \sim (x',y')$ if and only if
 $|x-x'|_{\pi \mathrm{e}^{R/2}} \leq \mathrm{e}^{(y+y')/2}$. We will also make use of the dissection into boxes introduced in the previous section. A box is called active if it contains at least one vertex of
 $\Gamma$ and inactive otherwise.
Suppose that x and x′ are two vertices of  $\Gamma$ that lie in the same component. How can we find a short path from x to x′? A natural strategy would be to follow a short path of boxes from the box A containing x to the box A′ containing x′. These boxes are connected by a path L(A, A′) of length at most 2R (see Figure 6(a)). If all the boxes in L(A, A′) are active, Lemma 3(i) immediately yields a path in
 $\Gamma$ from x to x′ of length at most 2R, which is a path of the desired length. The situation is more difficult if we also encounter inactive boxes, and modifying the path to avoid inactive boxes may be impossible because a path of active boxes connecting A to A′ may fail to exist. Nevertheless, it turns out that the graph-theoretic distance between x and x′ can be bounded in terms of the size of inactive regions one encounters when following L(A, A′).
If two blue boxes X and Y are not connected by a path of blue (striped) boxes, then a red (dotted) walk exists that intersects every path in  $\mathcal{B}$ from X to Y (Lemma 4). This walk can be chosen such that it either connects two boxes in
 $L_0$ (left) or is cyclic (right).

(a) Two boxes A, A′ in  $\mathcal{B}$ and the path L(A, A′) that connects them. We can form L(A, A′) by concatenating the shortest paths from A and A′ to the lowest box lying above both A and A′. (b) Active boxes are colored gray and inactive boxes are colored white. The union of L(A, A′) and the inactive components intersecting L(A, A′) is called W(A, A′) and outlined in black.

To make this precise, we define W(A, A′) to be the set of boxes that either lie in L(A, A′) or from which an inactive path (i.e. a path of inactive boxes) exists to a box in L(A, A′) (see Figure 6(b)). Note that W(A, A′) is a connected subset of  $\mathcal{B}$, consisting of all boxes in L(A, A′) and all inactive components intersecting W(A, A′) (by an inactive component we mean a component of the induced subgraph of
 $\mathcal{B}$ on the inactive boxes). The main result of this section is that the graph-theoretic distance between x and x′ is bounded by the size of W(A, A′).
Before we continue, we first recall some geometric properties of the graph  $\Gamma$.
Lemma 5. ([Reference Fountoulakis and Müller7, Lemma 3].) Let x, y, z,  $w \in V$.
(i) If
$xy \in E(\Gamma)$ and z lies above the line segment [x, y] (i.e. [x, y] intersects the segment joining z and the projection of z onto the horizontal axis), then at least one of xz and yz is also present in $\Gamma$.(ii) If xy,
$wz \in E(\Gamma)$ and the segments [x, y] and [z, w] intersect, then at least one of the edges xw, xz, yw, and yz is also present in $\Gamma$. In particular, $\{x,y,z,w\}$ is a connected subset of $\Gamma$.


We now prove a lemma that allows us to compare paths in  $\Gamma$ with walks in
 $\mathcal{B}$. This will enable us to translate information about
 $\Gamma$ (such as that two boxes contain vertices in the same component of
 $\Gamma$) to information about the states of the boxes.
Lemma 6. Suppose that boxes  $X,Y \in \mathcal{B}$ respectively contain vertices
 $x,y \in V$ that lie in the same component of
 $\Gamma$. Then
 $\mathcal{B}$ contains a walk
 $X= B_0, B_1, \ldots, B_n = Y$ with the following property:
(P) if  $B_i$ and
 $B_j$ are active but
 $B_{i+1}, B_{i+2}, \ldots, B_{j-1}$ are not, then
 $\Gamma$ has vertices
 $a \in B_i$,
 $b \in B_j$ that are connected in
 $\Gamma$ by a path of length at most three.
Proof. We prove the statement by induction on the length of the shortest path from x to y in  $\Gamma$.
First suppose that this length is 1, so that there is an edge e connecting x and y. We claim that a walk  $X=B_0, B_1, \ldots, B_n =
Y$ in
 $\mathcal{B}$ exists with the property that if
 $B_i$ is active then
 $B_i$ contains a neighbor of x or y. For this we use Lemma 4. We color a box blue if it is either inactive or active and it contains a neighbor of x or y. All other boxes are colored red. Note that X and Y are blue, because X contains a neighbor of y (namely, x) and Y contains a neighbor of x (namely, y). We intend to show that
 $\mathcal{B}$ contains a blue path from X to Y. Aiming for a contradiction, we suppose that this is not the case. By Lemma 4, there must then exist a red walk
 $S=S_0, S_1,
\ldots, S_m$ that intersects each path in
 $\mathcal{B}$ from X to Y. If we remove S from
 $\mathcal{E}_R$ then
 $\mathcal{E}_R \backslash S$ falls apart in a number of components. Because there is no path in
 $\mathcal{B}$ from X to Y that does not intersect S, X and Y lie in different components. (We say S separates X and Y.) We choose vertices
 $v_i \in V \cap S_i$ for all i (these vertices exist because all red boxes are active; see Figure 7). By Lemma 3(i),
 $v_i$ and
 $v_{i+1}$ are neighbors in
 $\Gamma$ for each i.
Proof of Lemma 6. The edge e of  $\Gamma$ connects vertices x and y. If a red (dotted) walk of boxes exists that separates the boxes containing x and y, then e intersects one of the segments
 $[v_i,v_{i+1}]$,
 $[v_0,v_0'],$ or
 $[v_m,v_m']$. This contradicts the assumption that no red box contains a neighbor of x or y.

We may assume that either  $S_0$ and
 $S_m$ are both boxes in the lowest layer
 $L_0$, or
 $S_0$ and
 $S_m$ are adjacent in
 $\mathcal{B}$ (see Figure 5). In the latter case, we consider the polygonal curve
 $\gamma$ consisting of the line segments
 $[v_0,v_1],
[v_1,v_2], \ldots, [v_m,v_0]$. This polygonal curve consists of edges of
 $\Gamma$. Let us observe that each of these edges passes through boxes in S and maybe also boxes adjacent to boxes in S, but the edges cannot intersect any box that is neither on S nor adjacent to a box of S. So in particular, none of these edges can pass through the box X, because X is not adjacent to a box in S (this box should then have been blue by Lemma 3(i)). From this it follows that
 $\gamma$ also separates x and y. Therefore, the edge e crosses an edge
 $[v_i,v_{i+1}]$ of
 $\Gamma$ (see Figure 7). By Lemma 5(ii), this means that
 $v_i$ or
 $v_{i+1}$ neighbors x or y, which is a contradiction because
 $v_i$ and
 $v_{i+1}$ do not lie in a blue box.
We are left with the case that  $S_0$ and
 $S_m$ lie in the lowest layer
 $L_0$. Let
 $v_0'$ and
 $v_m'$ denote the projections of
 $v_0$ and
 $v_m$, respectively, on the horizontal axis. By an analogous argument, we find that the polygonal line through
 $v_0', v_0, v_1, \ldots, v_m, v_m'$ separates x and y. We now see that e either crosses an edge
 $[v_i,v_{i+1}]$ (we then find a contradiction with Lemma 5(ii)) or one of the segments
 $[v_0,v_0']$ and
 $[v_m,v_m']$ (we then find a contradiction with Lemma 5(i)). From the contradiction we conclude that a blue path must exist connecting X and Y.
We have now shown that if x and y are neighbors in  $\Gamma$, there exists a walk
 $X = B_0, B_1, \ldots, B_n = Y$ such that the
 $B_i$ that are active contain a neighbor of x or y. This means that if
 $B_i, B_{i+1}, \ldots, B_j$ are such that
 $B_i$ and
 $B_j$ are active but
 $B_{i+1}, \ldots, B_{j-1}$ are not, then
 $B_i$ contains a vertex a that neighbors x or y and
 $B_j$ contains a vertex b that neighbors x or y. Now
 $d_{\Gamma}(a,b) \leq 3$ follows from the fact that both a and b neighbor an endpoint of the same edge e. We conclude that if x and y are neighbors in
 $\Gamma$ then a walk satisfying (P) exists.
Now suppose that the statement holds whenever x and y satisfy  $d_{\Gamma}(x,y) \leq k$ and consider two vertices x and y with
 $d_{\Gamma}(x,y) = k+1$. Choose a neighbor y′ of y such that
 $d_{\Gamma}(x,y')=k$. Let Y′ be the active box containing y′. By the induction hypothesis, there exists walks from X to Y′ and from Y′ to Y satisfying (P). By concatenating these two walks, we obtain a walk from X to Y satisfying (P), as desired.
Note that by itself this lemma is insufficient to construct short paths, as the proof is nonconstructive and there is no control over the number of boxes in the walk obtained. Nevertheless, we can use Lemma 6 to prove the main result of this section.
Lemma 7. There exists a constant c such that the following holds (for all finite  $V \subseteq \mathcal{E}_R$ with
 $\Gamma$ constructed as above). If the vertices
 $x, x' \in V$ and the boxes
 $A, A' \in \mathcal{B}$ are such that
(i)
$x \in A$ and $x' \in A'$, and(ii) x, x′ lie in the same component of
$\Gamma$,


then  $d_\Gamma(x,x') \leq c |W(A,A')|$.
Proof. We claim that there is a walk  $S=S_0, S_1, \ldots, S_n$ in
 $\mathcal{B}$ from A to A′ such that
(i) if
$S_i$ and $S_j$ are active but $S_{i+1}, \ldots, S_{j-1}$ are not, then $\Gamma$ has vertices $a \in S_i$, $b \in S_j$ that are connected in $\Gamma$ by a path of length at most three;(ii) if
$S_i$ is active then either $S_i$ itself or an inactive box adjacent to $S_i$ belongs to W(A, A′).


We define  $\mathcal{B}_x$ to be the set of active boxes that contain vertices of the component of
 $\Gamma$ that contains x and x′. By assumption, we have
 $A, A' \in \mathcal{B}_x$. If A and A′ are adjacent the existence of a walk S satisfying (i) and (ii) is trivial, so we assume A and A′ are not adjacent. The proof consists of proving the result for the case that A and A′ are the only boxes in L(A, A′) that belong to
 $\mathcal{B}_x$, and then a straightforward extension to the general case.
If A and A′ are the only boxes in L(A, A′) that belong to  $\mathcal{B}_x$, then the boxes in between A and A′ on L(A, A′) are either inactive, or they are active but contain vertices of a different component of
 $\Gamma$. Therefore, the box B in L(A, A′) directly following A must be inactive and belongs to some inactive component F (recall that an inactive component is a component of the induced subgraph of
 $\mathcal{B}$ on the inactive boxes). We will prove the stronger statement that a walk
 $S=S_0, S_1, \ldots, S_n$ from A to A′ exists satisfying (i) and
(ii’) if  $S_i$ is active then
 $S_i$ is adjacent to a box in F.
By Lemma 6 there exists a walk S from A to A′ satisfying (i). We will modify S such that (ii’) also holds. We proceed in two steps. In step 1 we remove all inactive boxes in S that are not in F. In step 2 we remove all active boxes from S that are not adjacent to a box in F.
Step 1. There is a walk S satisfying (i) that contains no inactive boxes outside F.
We start with the walk S that Lemma 6 provides. This walk satisfies (i). Suppose that S contains some inactive box X not in F (see Figure 8(a)). Because  $B \in F$, there can then be no inactive path in
 $\mathcal{B}$ from X to B. It follows from Lemma 4 that there is an active walk Q that intersects all walks in
 $\mathcal{B}$ from X to B (we apply Lemma 4 with the inactive boxes colored blue and all other boxes colored red). One such walk from X to B is obtained by following S towards A (which is a neighbor of B). Another possible walk is obtained by first following S towards A′ and then following L(A, A′) towards B. We define boxes E and E′ such that Q intersects the walk in
 $\mathcal{B}$ from X to B via S and A in E and the walk in
 $\mathcal{B}$ from X to B via S, A′ and L(A, A′) in E′ (see Figure 8(a)). Because E belongs to S, E also belongs to
 $\mathcal{B}_x$. It follows that E′ also belongs to
 $\mathcal{B}_x$, which implies that E′ lies in S (the boxes in L(A, A′) between A and A′ do not lie in
 $\mathcal{B}_x$ by assumption). We see that Q contains two active boxes E and E′ that lie on either side of X. Because Q contains only active boxes, we can replace the part of S from E to E′ by a walk of active boxes from E to E′. Doing so we find a walk that still satisfies (i) but from which the box X is removed. By repeatedly applying this procedure, we remove all such boxes X from S. The resulting walk satisfies (i) and contains no inactive boxes outside F.
Step 2. There is a walk S satisfying (i) that contains no active boxes outside F′, where F′ is the set of active boxes adjacent to a box in F.
We start with the walk constructed in step 1. Since A is adjacent to B it belongs to F′. Let B′ be the box in L(A, A′) directly preceding A′. We claim that B′ belongs to F. Note that B′ is inactive. We use Lemma 4 to show that an inactive path from B to B′ exists. If such a path would not exist then an active walk Q would exist that intersects all walks from B to B′. In particular, Q would contain an active box in  $L(A,A') \setminus
\{A,A'\}$ (which does not lie in
 $\mathcal{B}_x$, because by assumption A and A′ are the only boxes in L(A, A′) that belong to
 $\mathcal{B}_x$) and an active box in S (which lies in
 $\mathcal{B}_x$, because we know there is a path in
 $\Gamma$ from a vertex in this box to a vertex in A). This is a contradiction, because by Lemma 3(i) there cannot be an active walk between a box in
 $\mathcal{B}_x$ and an active box not in
 $\mathcal{B}_x$. It follows that an inactive path from B to B′ exists, so B′ belongs to F. Furthermore, every box in S that has an inactive neighbor in S also lies in F′, because this inactive neighbor lies in F by step 1.
Now consider active boxes  $S_i, S_{i+1}, \ldots, S_{j}$ in S such that
 $S_i$ and
 $S_j$ lie in F′ but
 $S_{i+1}, \ldots, S_{j-1}$ do not (see Figure 8(b)). We claim that there is a path in F′ from
 $S_i$ to
 $S_j$. Color all boxes in F′ blue and all other boxes red. Then our claim is that
 $\mathcal{B}$ contains a blue path from
 $S_i$ to
 $S_j$. We use Lemma 4 and argue by contradiction. If this blue path would not exist then there would exist a red walk Q that intersects every walk from
 $S_i$ to
 $S_j$. Because
 $S_i$ and
 $S_j$ lie in F′, there exists such a walk that apart from
 $S_i$ and
 $S_j$ contains only boxes in F. Because Q does not contain
 $S_i$ and
 $S_j$ (which are blue) it must contain a box in F. Furthermore, Q also contains one of the active boxes
 $S_{i+1}, \ldots, S_j$. Therefore, Q is a connected set of boxes that contains a box in F and an active box. This implies that Q must also contain a box in F′, which contradicts the fact that Q consists of red boxes. This contradiction shows that there must be a blue path in
 $\mathcal{B}$ from
 $S_i$ to
 $S_j$, i.e. a path in F′ from
 $S_i$ to
 $S_j$. We replace the boxes
 $S_{i+1}, \ldots, S_{j-1}$ of S by this path, thereby removing the boxes
 $S_{i+1}, \ldots,
S_{j-1}$ from S. Repeatedly applying this operation, we remove all active boxes that do not lie in F′ from S. This completes step 2.
The walk constructed in step 2 satisfies (i) and (ii’), so we are now done with the case that L(A, A′) contains no boxes in  $\mathcal{B}_x$ other than A and A′.
Now suppose A and A′ are not the only boxes in L(A, A′) that belong to  $\mathcal{B}_x$; let
 $A=A_0$,
 $A_1$, …,
 $A_n = A'$ be all the boxes in L(A, A′) that belong to
 $\mathcal{B}_x$ (ordered by their position in L(A, A′)). All these boxes contain vertices in the same component of
 $\Gamma$. For all i, we have
 $L(A_i,A_{i+1}) \subset
L(A,A')$ and, furthermore,
 $A_i$ and
 $A_{i+1}$ are the only boxes in
 $L(A_{i},A_{i+1})$ that belong to
 $\mathcal{B}_x$. Therefore, a walk from
 $A_i$ to
 $A_{i+1}$ satisfying (i) and (ii) exists. By concatenating these walks for all i, we find a walk S from A to A′ satisfying (i) and (ii).
We now construct a path in  $\Gamma$ from x to x′ of length at most
 $37|W(A,A')|$. We may assume that the active boxes in S are all distinct, because if S contains an active box twice we can remove the intermediate part of S. The number of active boxes in S is at most
 $9|W(A,A')|$ because each active box in S lies in W(A, A′) or is one of the at most eight neighbors of an inactive box in W(A, A′). Suppose that
 $S_i$ and
 $S_j$ are active boxes in S such that
 $S_{i+1}, \ldots,
S_{j-1}$ are all inactive. Then, for every vertex
 $v \in S_i,$ there is a path in
 $\Gamma$ of length at most four to a vertex in
 $S_j$: by (i), there are vertices
 $a \in S_i$,
 $b \in S_j$ such that
 $d_{\Gamma}(a,b)
\leq 3$ and, furthermore, v and a are neighbors because they lie in the same box. It follows that there is a path of length at most
 $36|W(A,A')|$ from x to a vertex in A′; hence, a path of length at most
 $36|W(A,A')|+1 \leq 37|W(A,A')|$ from x to x′. This shows that we may take
 $c=37$.
3.3. Bounding the diameter
In this subsection we continue with the general setting where  $V
\subseteq \mathcal{E}_R$ is an arbitrary finite set, and
 $\Gamma$ is the graph with vertex set V and connection rule
 $(x,y) \sim (x',y')$ if and only if
 $|x-x'|_{\pi \mathrm{e}^{R/2}} \leq \mathrm{e}^{(y+y')/2}$. Here we will translate the bounds from the previous section into results on the maximum diameter of a component of
 $\Gamma$. We start with a general observation on graph diameters.
Lemma 8. Suppose that  $H_1$ and
 $H_2$ are induced subgraphs of G such that
 $V(G)
= V(H_1) \cup V(H_2)$ (but
 $H_1$ and
 $H_2$ need not be vertex disjoint). If every component of
 $H_1$ has diameter at most
 $d_1$ and
 $H_2$ (is connected and) has diameter at most
 $d_2$, then every component of G has diameter at most
 $2d_1+d_2+2$.
In particular, if  $H_2$ is a clique then every component of G has diameter at most
 $2d_1+3$.
Proof. Let C be a component of G. If C contains no vertices of  $H_2$, then C is a component of
 $H_1$ as well. So in this case C has diameter at most
 $d_1$. If C is not a component of
 $H_1$ then, for any vertex
 $v
\in C,$ there is a path of length at most
 $d_1+1$ from v to a vertex in
 $H_2$. Thus, since there is a path of length at most
 $d_2$ between any two vertices in
 $H_2$, any two vertices
 $u,v \in C$ have distance at most
 $({d_1} + 1) + {d_2} + ({d_1} + 1) = 2{d_1} + {d_2} + 2$ in G, as required.
We let  $\tilde{\ell} :\!= \lfloor R/2\log 2\rfloor-1$ be the largest i such that layer i is completely below the horizontal line
 $y = R/2$; we set
 $\tilde{V} :\!= V \cap \{ y \leq \tilde{\ell} \cdot \log 2 \}$, and we let
 ${\tilde{\Gamma}} :\!= \Gamma[\tilde{V}]$ be the subgraph of
 $\Gamma$ induced by
 $\tilde{V}$. For
 $A, A' \in \mathcal{B},$ we let
 $\tilde{W} = \tilde{W}(A,A')$ denote the set W(A, A′) but corresponding to
 $\tilde{V}$ instead of V. (That is, boxes in layers
 $\tilde{\ell}+1,\dots,\ell$ are automatically inactive. Note that this could potentially increase the size of W substantially.)
The following lemma gives sufficient conditions for an upper bound on the diameter of each component of  $\tilde{\Gamma}$. The lemma also deals with graphs that can be obtained by
 $\tilde{\Gamma}$ by adding a specific type of edges.
Lemma 9. There exists a constant c such that the following holds. Let  ${\tilde{\Gamma}}$ and
 $\tilde{W}$ be as above, and let
 $K = \{(x,y) \in
\mathcal{E}_R \colon y > R/4\}$. Consider the following two conditions:
(i) for any two boxes A and A′, we have
$|\tilde{W}(A,A')| \leq D$ for some D (possibly depending on n);(ii) there is no inactive path (with respect to
$\tilde{V}$) in $\mathcal{B}$ connecting a box in $L_0$ with a box in K.


If (i) holds, then each component of  ${\tilde{\Gamma}}$ has diameter at most
 $c
D$. If, furthermore (ii) holds then, for any graph
 $\Gamma'$ that is obtained from
 ${\tilde{\Gamma}}$ by adding an arbitrary set of edges E′ each of which has an endpoint in K, every component of
 $\Gamma'$ has diameter c D.
Proof. The first statement follows directly from Lemma 7.
If, furthermore (ii) holds, there exists a cycle of active boxes in  $\mathcal{E}_R \backslash K$ that separates K from
 $L_0$. Since vertices in neighboring boxes are connected in
 ${\tilde{\Gamma}}$, this means that there is a cycle in
 ${\tilde{\Gamma}}$ that separates K from
 $L_0$. Every vertex in K lies above some edge in this cycle and, thereby, lies in the component C of this cycle by Lemma 5(i). Thus, every edge of
 $\Gamma'$ that is not present in
 ${\tilde{\Gamma}}$ has an endpoint in the component C of
 ${\tilde{\Gamma}}$.
Let d be the maximum diameter over all components of  ${\tilde{\Gamma}}$. By an application of Lemma 8 (with C as one of the two subgraphs; note that we may assume that no added edge connects vertices in the same component, because this can only lower the diameter), we see that the diameter of
 $\Gamma'$ is at most
 $3d+2$. This proves the second statement (with a larger value of c).
4. Probabilistic bounds
We are now ready to use the results from the previous sections to obtain (probabilistic) bounds on the diameters of components in the KPKVB model. Recall from Section 2 that  $\Gamma_{\alpha,\lambda}$ is a graph with vertex set
 $V_{\alpha,\lambda}$, where two vertices (x, y) and (x′, y′) are connected by an edge if and only if
 $|x-x'|_{\pi
\mathrm{e}^{R/2}} \leq \mathrm{e}^{(y+y')/2}$. Here
 $V_{\alpha,\lambda}$ is the point set of the Poisson process with intensity
 $f_{\alpha,\lambda} =
\mathbf{1}_{\mathcal{E}_R} \lambda \mathrm{e}^{-\alpha y}$ on
 $\mathcal{E}_R =
({-}{\pi}\mathrm{e}^{R/2}/{2} , {\pi}\mathrm{e}^{R/2}/{2} ] \times [0,R] \subset
\mathbb{R}^2$.
Consistently with the previous sections, we define the subgraph  ${\tilde{\Gamma}}_{\alpha,\lambda}$ of
 $\Gamma_{\alpha,\lambda}$, induced by the vertices in
 \[
\tilde{V}_{\alpha,\lambda} :\!= \{(x,y) \in V_{\alpha,\lambda} \colon y \leq
(\tilde{\ell}+1)\log 2\}.
\]
In the remainder of this section all mention of active and inactive (boxes) will be with respect to  $\tilde{V}_{\alpha,\lambda}$.
Our plan for the proof of Theorem 1 is to first show that, for  $\lambda=\nu\alpha/\pi,$ the graph
 ${\tilde{\Gamma}}_{\alpha,\lambda}$ satisfies the conditions in Lemma 9 for some
 $D =
O(R)$. In the final part of this section we spell out how this result implies that a.a.s. all components of the KPKVB random graph
 $G(N,\alpha,\nu)$ have diameter O(R).
We start by showing that Lemma 9(i) is a.a.s. satisfied by  ${\tilde{\Gamma}}_{\alpha,\lambda}$. To do so, we need to estimate the probability that a box is active if V is the point set
 $V_{\alpha,\lambda}$ of the Poisson process above. For
 $0 \leq i \leq
\tilde{\ell}$, let us write
 \begin{equation}
p_i = p_{i,\alpha,\lambda} :\!= {{\mathbb P}}_{\alpha,\lambda} \quad (B\text{ is
active}),
\label{eqn2}
\end{equation}(2)
where  $B \in L_i$ is an arbitrary box in layer
 $L_i$.
Lemma 10. For each  $0 \leq i \lt \tilde{\ell},$ we have
 \[
p_i = 1 - \exp\!\Big[ - b \frac{2^{1-\alpha}}{\alpha} \lambda
2^{(1-\alpha)i} \Big] \geq 1 - \exp\!\Big[ - \frac{1}{12} \lambda
2^{(1-\alpha)i} \Big].
\]
Proof. The expected number of points of  $\tilde{V}_{\alpha, \lambda}$ that fall inside a box B in layer
 $L_i$ satisfies
 \begin{align*}
\mathbb{E}(|B \cap V_{\alpha, \lambda}|) = \int_{i \log(2)}^{(i+1)
\log(2)} \int_{0}^{2^i b} \lambda \mathrm{e}^{-\alpha y} \,\mathrm{d} x \,\mathrm{d} y = \lambda b
\frac{1-2^{-\alpha}}{\alpha} 2^{(1-\alpha)i}.
\end{align*}
Since the number of points that fall in B follows a Poisson distribution and because  $b (1- 2^{-\alpha})/{\alpha} \geq {\textstyle{1 \over 12}}$, the result follows.
Lemma 11. There exists a  $\lambda_0$ such that if
 $\alpha=1$ and
 $\lambda > \lambda_0$ then the following holds. Let E denote the event that there exists a connected subgraph
 $C \subseteq \mathcal{B}$ with
 $|C| > R$ such that at least half of the boxes of C are inactive. Then
 ${{\mathbb P}}_{1,\lambda}(E)
= O(N^{-1000})$.
Proof. The proof is a straightforward counting argument. If C is a connected subset of the boxes graph  $\mathcal{B}$ and
 $A \in C$ is a box of C, then there exists a walk P, starting at A, through all boxes in C, that uses no edge in
 $\mathcal{B}$ more than twice (this is a general property of a connected graph). Since the maximum degree of
 $\mathcal{B}$ is 8, the walk P visits no box more than 8 times. Thus, the number of connected subgraphs of
 $\mathcal{B}$ of cardinality i is no more than
 $|\mathcal{B}| \cdot
8^{8i} = (2^{\ell+1}-1) \cdot 2^{24 i} = \mathrm{e}^{O(R)} \cdot 2^{24 i}$ (using the definition of
 $\ell$ given in 1). Given such a connected subgraph C of cardinality
 $i>R,$ there are
 $\binom{i}{i/2}$ ways to choose a subset of cardinality
 $i/2$. Out of any such subset at most 63 boxes lie above level
 $\tilde{\ell}$ by Lemma 3 and, by Lemma 10, each of the remaining
 $i/2-63
> i/4$ is inactive with probability at most
 $\mathrm{e}^{-\lambda/12}$. This gives
 \begin{align*}
{{\mathbb P}}_{1,\lambda}( E ) & \leq \sum_{i>R} |\mathcal{B}| 8^{8i} \binom{i}{i/2}
\mathrm{e}^{-(i/2-63) \lambda / 12}
\\
& \leq \mathrm{e}^{O(R)} \sum_{i>R} 8^{8i} 2^i \mathrm{e}^{-{i/4} \lambda / 12}
\\
& = \mathrm{e}^{O(R)} O( ( 2^{25} \mathrm{e}^{-\lambda/48} )^R )
\\
& = \exp\![ O(R) - \lambda \Omega(R) ]
\\
& = O( N^{-1000} ),
\end{align*}
where the third and fifth lines follow provided  $\lambda$ is chosen sufficiently large.
Corollary 2. There exist constants c and  $\lambda_0$ such that if
 $\alpha = 1$ and
 $\lambda>\lambda_0$ then
 $$
{{\mathbb P}}_{1,\lambda}( \text{there exist boxes}\ A, A'\ \text{with}\ |\tilde{W}(A,A')|> c
R ) = O( N^{-1000} ).
$$
Proof. We let  $\lambda_0$ be as provided by Lemma 11 and we take
 $c
:\!= 5$. We note that, for every two boxes A, A′, the set
 $\tilde{W}(A,A')$ is a connected set and all boxes except for some of the at most 2R boxes on L(A, A′) must be inactive by definition of
 $\tilde{W}$. Hence, if it happens that
 $|\tilde{W}(A,A')| > 5R$ for some pair of boxes A, A′ then event E defined in Lemma 11 holds. The corollary thus follows directly from Lemma 11.
We now want to show that in the case when  ${{\textstyle{1 \over 2}}
\lt \alpha \lt 1}$ and
 $\lambda > 0$ we also have that, with probability very close to 1,
 ${|\tilde{W}(A,A')| = O(R)}$ holds for all A, A′. Recall that the probability that a box in layer i is inactive is upper bounded by
 $\exp\!({-}{\lambda}
2^{(1-\alpha)i}/{12})$ (this bound now depends on i), which decreases rapidly if i increases. However, for small values of i, this expression could be very close to 1, depending on the value of
 $\lambda$. In particular, we cannot hope for something like Lemma 11 to hold for all
 ${\textstyle{1 \over 2}}
\lt \alpha \lt 1$ and
 $\lambda
> 0$.
To gain control over the boxes in the lowest layers, we merge boxes in the lowest layers into larger blocks. An h-block is defined as the union of a box in  $L_{h-1}$ and all
 $2^h-2$ boxes lying below this box (see Figure 9(a)). In other words, an h-block consists of
 $2^h-1$ boxes in the lowest h layers that together form a rectangle. The following lemma shows that the probability that an h-block contains a horizontal inactive path can be made arbitrarily small by taking h large.
Proof of Lemma 7. (a) Step 1. The walk S satisfies (i) and connects A with A′. If from an inactive box X there is no inactive path to B (dotted line), then there is an active walk Q (dashed line) that connects active boxes E and E′ in S on either side of X. (b) Step 2. The walk S satisfies (i) and contains no inactive boxes outside F. The boxes A,  $S_i$,
 $S_j,$ and A′ (striped) all belong to F′. The proof works by finding a path in F′ from
 $S_i$ to
 $S_j$ (dashed line). In both figures active boxes are colored gray and inactive boxes are colored white.

(a) An h-block (in the figure  $h=5$). An h-block is the union of
 $2^h-1$ boxes in the lowest h layers. (b) Definition of a lonely block (used in the proof of Lemma 13). The lowest h layers are partitioned into h-blocks. An h-block B in W′ is called lonely if both boxes
 $B_1$ and
 $B_2$ lying above it are not in W′. If
 $|W'| > 3$ and B is lonely, one of the blocks adjacent to B contains a horizontal path in W.

Let us denote the probability by
 \begin{equation}
q_h = q_{h,\alpha,\lambda} :\!= {{\mathbb P}}_{\alpha,\lambda}(H\text{ has a
vertical, active crossing}),
\label{eqn3}
\end{equation}(3)
where H is an arbitrary h-block, and a ‘vertical, active crossing’ means a path of active boxes (in  $\mathcal{B}^\ast$) inside the block connecting the unique box in the highest layer to a box in the bottom layer.
Lemma 12. If  $\alpha \lt 1$ and
 $\lambda > 0$ then, for every
 $\varepsilon>0$, there exists an
 $h_0=h_0(\varepsilon,\alpha,\lambda)$ such that
 $q_h > 1-\varepsilon$ for all
 $h_0
\leq h \leq \tilde{\ell}$.
Proof. In the proof that follows, we shall always consider blocks that do not extend above the horizontal line  $y=R/2$ (i.e. boxes in layers
 $h \leq
R/2\log 2-1$) so that we can use Lemma 10 to estimate the probability that a box is active.
An  $(h+1)$-block H consists of one box B in layer
 $L_h$ and two h-blocks
 $H_1$ and
 $H_2$. There is certainly a vertical, active crossing in H if B is active and either
 $H_1$ or
 $H_2$ has a vertical, active crossing. In other words,
 \begin{equation}
q_{h+1} \geq p_h (2 q_h - q_h^2),
\label{eqn4}
\end{equation}(4)
where  $p_h \geq 1 - \exp\![{-}\frac{1}{12} \lambda 2^{(1-\alpha)h} ]$ is the probability that B is active. We choose
 $\delta = \delta(\varepsilon)$ small, to be made precise shortly. Clearly there is an
 $h_0$ such that
 $p_h > 1-\delta$ for all
 $h_0 \leq h \leq \tilde{\ell}$. Thus, it follows from 4 that
 $q_{h+1} \geq f(q_h)$ for all such h, where
 $f(x) =
(1-\delta)(2x-x^2)$. It is easily seen that f has fixed points
 $x = 0,
{(1-2\delta)}/{(1-\delta)}$, that
 $x \lt f(x) \lt {(1-2\delta)}/{(1-\delta)}$ for
 $0 \lt x \lt {(1-2\delta)}/{(1-\delta)}$ and
 ${(1-2\delta)}/{(1-\delta)}
\lt f(x) \lt x$ for
 ${(1-2\delta)}/{(1-\delta)} \lt x \leq 1$. Therefore, using the fact that clearly
 $0 \lt q_{h_0} \lt 1$ (there is, for instance, a strictly positive probability all boxes of the block H are active, respectively inactive), we must have
 $f^{(k)}(q_{h_0} ) \to
{(1-2\delta)}/{(1-\delta)}$ as
 $k\to\infty$, where
 $f^{(k)}$ denotes the k-fold composition of f with itself. Hence, provided we choose
 $\delta=\delta(\varepsilon)$ sufficiently small, there is a
 $k_0=k_0(\varepsilon)$ such that
 $q_{h_0+k} \geq f^{(k)}(q_{h_0}) > 1-\varepsilon$ for all
 $k_0 \leq k \leq
\tilde{\ell} - h_0$.
Lemma 13. For every  $\alpha \lt 1$ and
 $\lambda > 0,$ there exists a
 $c =
c(\alpha,\lambda)$ such that
 \[
{{\mathbb P}}_{\alpha,\lambda}( \text{there exist boxes}\ A\ \text{and}\ A'\ \text{with}\
|\tilde{W}(A,A')| > c R ) = O( N^{-1000} ).
\]
Proof. Let  $p_i$ be as defined in (2) and
 $q_i$ as defined in (3). Let
 $\varepsilon>0$ be arbitrary, but fixed, to be determined later on in the proof. By Lemmas 10 and 12, there exists an h such that
 \[
p :\!= \min\{ q_h, p_i \colon h \leq i \leq \tilde{\ell} \} > 1-\varepsilon.
\]
We now create a graph  $\mathcal{B}'$, modified from the boxes graph
 $\mathcal{B}$, as follows. The vertices of
 $\mathcal{B}'$ are the boxes above layer h, together with the h-blocks. Boxes or blocks are neighbors in
 $\mathcal{B}'$ if they share at least a corner. Note that the maximum degree of
 $\mathcal{B}'$ is at most 8.
Given two boxes  $A, A' \in \mathcal{B},$ we define
 $W'(A,A') \subseteq \mathcal{B}'$ as the natural analogue of
 $\tilde{W}(A,A')$, i.e. the set of all boxes of
 $\tilde{W}(A,A')$ above layer h together with all h-blocks that contain at least one element of
 $\tilde{W}(A,A')$. Note that W′(A, A′) is a connected set in
 $\mathcal{B}'$ and that
 $|W'(A,A')| \geq |\tilde{W}(A,A)| /
(2^h-1)$.
We will say that an h-block B is lonely if the two boxes in  $L_h$ adjacent to B both do not lie in
 $\tilde{W}(A,A')$ (see Figure 9(b)). Observe that if B is lonely then at least one of the two neighbouring blocks must have a horizontal, inactive crossing. This shows that
 \begin{equation}
|\text{blocks without an active, vertical crossing}| \geq
{\textstyle{1 \over 2}}
{|\text{lonely blocks}|}.
\label{eqn5}
\end{equation}(5)
Consider two boxes  $A, A' \in \mathcal{B}$ and assume that
 $|\tilde{W}(A,A')| > c
R$, where c is a large constant to be made precise later. By a previous observation
 $|W'(A,A')| \geq ({c}/{(2^h-1)}) R =:\, d R$. We distinguish two cases.
Case (a): at least  $|W'(A,A')| / 100$ of the elements of W′(A, A′) are boxes (necessarily above layer h). Subtracting the at most 63 boxes of levels
 $\tilde{\ell}+1,\dots, \ell$ and the at most 2R boxes of L(A, A′), we see that at least
 $|W'(A,A)| / 100 - (2R + 63) \geq
|W'(A,A')| / 1000$ boxes of W′(A, A′) must be inactive and lie in levels
 $h, \dots, \tilde{\ell}$. (Here the inequality holds assuming that
 $|W'(A,A')|
\geq d R$ with d sufficiently large.)
Case (b): at most  $|W'(A,A')| / 100$ of the elements of W′(A, A′) are boxes. Hence, at least
 $\frac{99}{100} |W'(A,A')|$ of the elements of W′(A, A′) are h-blocks. Of these, at least
 $\frac{97}{100}
|W'(A,A')|$ blocks must be lonely, since each box of W′ is adjacent to no more than two h-blocks of W′. Thus, by the previous observation 5, at least
 $\frac{97}{200} |W'(A,A')| \geq
|W'(A,A')| / 1000$ elements of W′ are blocks without a vertical, active crossing.
Combining the two cases, we see that either W′ contains  $|W'(A,A')|/1000$ inactive boxes in the levels h, …,
 $\tilde{\ell}$, or W′ contains
 $|W(A,A')|/1000$ blocks without a vertical, active crossing. Summing over all possible choices of A, A′ and all possible sizes of W′(A, A′), we see that
 \begin{align*}
{{\mathbb P}}_{\alpha,\lambda}( \text{there exist}\ A, A'\ \text{with}\ |\tilde{W}(A,A')|> c
R ) & \leq |\mathcal{B}|^2 \sum_{i\geq d R} 8^{8i} (1-p)^{i/1000}
\\
& \leq |\mathcal{B}|^2 \sum_{i\geq d R} ( 8^8 \varepsilon^{1/1000} )^i
\\
& = |\mathcal{B}|^2 O( ( 8^8 \varepsilon^{1/1000} )^{dR} )
\\
& = \exp\![O(R) - d \Omega(R) ]
\\
& = O(N^{-1000}),
\end{align*}
where the factor  $8^{8i}$ in the first line is a bound on the number of connected subsets of
 $\mathcal{B}'$ of cardinality i that contain A, A′; the third line holds provided
 $\varepsilon$ is sufficiently small (
 $\varepsilon \lt
8^{-8000}$ will do); and the last line holds provided c (and, thus, also
 $d = c/(2^h-1)$) was chosen sufficiently large.
We now turn to the proof of (ii) of Lemma 9.
Lemma 14. If either
(i)
$\frac12 \lt \alpha \lt 1$ and $\lambda > 0$ is arbitrary, or(ii)
$\alpha = 1$ and $\lambda$ is sufficiently large,


then it holds with probability  $1-O(N^{-1000})$ that there are no inactive paths in
 $\mathcal{B}$ from
 $L_0$ to
 $K :\!= \{(x,y) \in
\mathcal{E}_R \colon y > R/4\}$.
Proof. Since only the boxes below the line  $y=R/2$ are relevant, we can freely use Lemma 10. Note that an inactive path in
 $\mathcal{B}$ from
 $L_0$ to K would have length at least
 $R/4$ (the height of each layer equals
 $\log 2 \lt 1$) and that it would have a subpath of length at least
 $R/8$ that lies completely in
 $\{(x,y) \colon
y > R/8\}$. Let q be the maximum probability that a box between the lines
 $y=R/8$ and
 $y=R/2$ is inactive. Since there are
 $\exp\!(O(R))$ boxes and at most
 $9^k$ paths of length k starting at any given box, the probability that such a subpath exists is at most
 $\exp\!(O(R)) 9^{R/8}
q^{R/8} = \exp\!(O(R) + \log(q) R/8)$. If
 $\alpha=1$ then
 $q \leq
\exp\!({-}\lambda/12)$, which can be chosen arbitrarily small by choosing
 $\lambda$ sufficiently large. For sufficiently small q, we then have
 $\exp\!(O(R) + \log(q) R/8) \leq \exp\!({-}R/2) = O(N^{-1000})$ and, therefore, such a path does not exist with probability
 $1- O(N^{-1000})$. If
 $\alpha\lt1,$ we have
 $q \leq \exp\!({-}\lambda/12 \cdot 2^{(1-\alpha)R/8})$ and it follows that
 ${\exp\!(O(R) + \log(q) R/8) = \exp\!(O(R) - \lambda/12
\cdot 2^{(1-\alpha)R/8} \cdot R/8) = \exp\!({-}\omega(R))}$, so we can draw the same conclusion.
We are almost ready to finally prove Theorem 1, but it seems helpful to first prove a version of the theorem for  $G_{\mathop{\textrm{Po}}}$, the Poissonized version of the model.
Proposition 1. (Theorem 1 for  $G_{\mathop{\textrm{Po}}}$) If either
(i)
$\frac12 \lt \alpha \lt 1$ and $\nu > 0$ is arbitrary, or(ii)
$\alpha = 1$ and $\nu$ is sufficiently large,


then, a.a.s., every component of  $G_{\mathop{\textrm{Po}}}(N;\, \alpha, \nu)$ has diameter
 $O(\!\log(N))$.
Proof. Let  $\tilde{G}_{\mathop{\textrm{Po}}}$ be the subgraph of
 $G_{\mathop{\textrm{Po}}}$ induced by the vertices of radii larger than
 $R - (\tilde{\ell}+1)\log 2$. (Here
 $\tilde{\ell} :\!= \lfloor
R/2\log 2\rfloor - 1$ is as before.) By the triangle inequality, all vertices of
 $G_{\mathop{\textrm{Po}}}$ with distance at most
 $R/2$ from the origin form a clique. Moreover, by Lemmas 1, 2, and 3, a.a.s. the vertices of
 $G_{\mathop{\textrm{Po}}}$ with radii between
 $R/2$ and
 $R-(\tilde{\ell}+1)\log 2$ can be partitioned into up to 63 cliques corresponding to the boxes above level
 $\tilde{\ell}$. In other words, a.a.s.,
 $\tilde{G}_{\mathop{\textrm{Po}}}$ can be obtained from
 $G_{\mathop{\textrm{Po}}}$ by successively removing up to 64 cliques. Therefore, by up to 64 applications of Lemma 8, it suffices to show that a.a.s. every component of
 $\tilde{G}_{\mathop{\textrm{Po}}}$ has diameter
 $O(\!\log N)$. Again invoking Lemmas 1 and 2 as well as Lemma 9, it thus suffices to show that a.a.s.
 ${\tilde{\Gamma}}_{\alpha,\nu\alpha/\pi}$ satisfies conditions (i) and (ii) of Lemma 9. This is taken care of by Corollary 2 and Lemma 14 in the case when
 $\alpha=1$ and
 $\nu$ is sufficiently large, and Lemmas 13 and 14 in the case when
 $\alpha \lt 1$ and
 $\nu>0$ is arbitrary.
Finally, we are ready to give a proof of Theorem 1.
Proof of Theorem 1. Let us point out that  $G_{\mathop{\textrm{Po}}}$ conditioned on
 $Z=N$ has exactly the same distribution as
 $G = G(N;\, \alpha,\nu)$. We can therefore repeat the previous proof, where we substitute the use of Lemmas 1 and 2 by Corollary 1, but with one important additional difference. Namely, now we have to show that
 ${\tilde{\Gamma}}_{\alpha,\nu\alpha/\pi}$ satisfies conditions (i) and (ii) of Lemma 9 a.a.s. conditional on
 $Z=N$. To this end, let E denote the event that
 ${{\tilde{\Gamma}}_{\alpha,\nu
\alpha/\pi}}$ fails to satisfy one or both conditions. By Corollary 2, respectively Lemma 13, and Lemma 14, we have
 $\mathbb{P}(E) = O(N^{-1000})$. Using the standard fact that
 ${{\mathbb P}}(
\mathop{\textrm{Po}}(N)=N ) = \Omega( N^{-1/2} )$, it follows that
 \[
\mathbb{P}( E \ \,\,|\, \ \, Z=N) \leq \frac{\mathbb{P}(E)}{\mathbb{P}(Z=N)} =
\frac{O(N^{-1000})}{\Omega(N^{-1/2})} = o(1),
\]
as required.
5. Discussion and further work
In this paper we have given an upper bound of  $O(\!\log N )$ on the diameter of the components of the KPKVB random graph, which holds when
 ${\textstyle{1 \over 2}}
\lt \alpha \lt 1$ and
 $\nu > 0$ is arbitrary and when
 $\alpha=1$ and
 $\nu$ is sufficiently large. Our upper bound is sharp up to the leading constant hidden inside the
 $O(\cdot)$-notation.
The proof proceeds by considering the convenient idealized model introduced by Fountoulakis and the first author [Reference Fountoulakis and Müller7], and a relatively crude discretization of this idealized model. The discretization is obtained by dissecting the upper half-plane into rectangles (‘boxes’) and declaring a box active if it contains at least one point of the idealized model. With a mix of combinatorial and geometric arguments, we are then able to give a deterministic upper bound on the component sizes of the idealized model in terms of the combinatorial structure of the active set of boxes, and, finally, we apply Peierls-type arguments to give a.a.s. upper bounds for the diameters of all components of the idealized model and the KPKVB model.
We should also remark that the proof in [Reference Bode, Fountoulakis and Müller5] that  $G(N;\,\alpha,\nu)$ is a.a.s. connected when
 $\alpha \lt {\textstyle{1 \over 2}}
$ in fact shows that the diameter is a.a.s. O(1) in this case. What happens with the diameter when
 $\alpha={\textstyle{1 \over 2}}
$ is an open question.
What happens when  $\alpha > 1$ or
 $\alpha=1$ and
 $\nu$ is arbitrary is another open question. In the latter case our methods seem to break down at least partially. We expect that the relatively crude discretization we used in the current paper will not be helpful here and a more refined proof technique will be needed.
Another natural question is to see whether one can say something about the difference between the diameter of the largest component and the other components. We remark that, by the work of Friedrich and Krohmer [Reference Friedrich, Krohmer and Halldórsson9], the largest component has diameter  $\Omega(\!\log N )$ a.a.s., but their argument can easily be adapted to show that there will be components other than the largest component that have diameter
 $\Omega(\!\log N )$ as well.
Another natural, possibly quite ambitious, goal for further work would be to determine the leading constant (i.e. a constant  $c=c(\alpha,\nu)$ such that the diameter of the largest component is
 $(c+o(1)) \log N$ a.a.s.) if it exists, or indeed even just to establish the existence of a leading constant without actually determining it. We would be especially curious to know if anything special happens as
 $\nu$ approaches
 $\nu_{\text{c}}$.
We have only mentioned questions directly related to the graph diameter here. To the best of our knowledge the study of (most) other properties of the KPKVB model is largely virgin territory.
Appendix A. The proof of Corollary 1
We show that Lemmas 1 and 2 hold when conditioned on  $Z=N$. Recall that we say that an event A happens a.a.s. conditional on B if
 $\mathbb{P}(A \ \,\,|\, \ \, B) \to 1$ as
 $N \to
\infty$.
Lemma 15. (Lemma 1 conditional on  $Z=N$) Let
 $\alpha>\frac12$. On the coupling space of Lemma 1, conditional on
 $Z=N$, a.a.s.
 $V_{\nu \alpha/\pi}$ is the image of the vertex set of
 $G_{\mathop{\textrm{Po}}}$ under
 $\Psi$.
Proof. Write  $V = \{X_1,\ldots,X_Z\}$ and
 $\tilde{V} = V_{\nu \alpha/\pi}$. As in [7], there are independent Poisson processes
 $\mathcal{P}_0$,
 $\mathcal{P}_1$, and
 $\mathcal{P}_2$ on
 $\mathcal{E}_R$ such that
 $\Psi(V) = \mathcal{P}_0 \cup \mathcal{P}_1$,
 $\tilde{\!V} = \mathcal{P}_0
\cup \mathcal{P}_2$ and
 $\mathbb{E}|\mathcal{P}_1|$,
 $\mathbb{E}|\mathcal{P}_2| = o(1)$. We now find that
 \begin{align*}
\mathbb{P}(\tilde{V} = \Psi(V) \ \,\,|\, \ \, Z=N) &= \mathbb{P}(|\mathcal{P}_1| =
|\mathcal{P}_2| = 0 \ \,\,|\, \ \, |\mathcal{P}_0| + |\mathcal{P}_1| = N)
\\
&=
\mathbb{P}(|\mathcal{P}_1| =0\ \,\,|\, \ \, |\mathcal{P}_0| + |\mathcal{P}_1| = N)
\mathbb{P}(|\mathcal{P}_2| = 0)
\end{align*}
because  $\mathcal{P}_0$,
 $\mathcal{P}_1,$ and
 $\mathcal{P}_2$ are independent. From
 $\mathbb{E}|\mathcal{P}_2|=o(1),$ it follows that
 $\mathbb{P}(|\mathcal{P}_2|=0) = 1-o(1)$. Furthermore, since the conditional distribution of a Poisson distributed variable given its sum with an independent Poisson distributed variable is binomial, we have
 $\mathbb{P}(|\mathcal{P}_1| =0\ \,\,|\, \ \, |\mathcal{P}_0| + |\mathcal{P}_1| = N)
= \binom{N}{N} (1 - \mathbb{E}|\mathcal{P}_1|/N )^N = ( 1 - o(1)/N )^N =
1-o(1), $ from which it follows that
 $\mathbb{P}(\tilde{V} = \Psi(V) \ \,\,|\, \ \,
Z=N) = 1-o(1)$.
Lemma 16. (Lemma 2 conditional on  $Z=N$) Let
 $\alpha>\frac12$. On the coupling space of Lemma 1, conditional on
 $Z=N$, a.a.s. it holds for
 $1 \leq i,j \leq Z$ that
(i) if
$r_i,r_j \geq \frac12R$ and $\tilde{X}_i\tilde{X}_j \in
E(\Gamma_{\alpha,\nu \alpha/\pi})$, then $X_iX_j \in E(G_{\mathop{\textrm{Po}}})$;(ii) if
$r_i,r_j \geq \frac34 R$ then $\tilde{X}_i\tilde{X}_j \in
E(\Gamma_{\alpha,\nu \alpha/\pi})$ if and only if $X_iX_j \in
E(G_{\mathop{\textrm{Po}}})$.


Here  $r_i$ and
 $r_j$ denote the radial coordinates of
 $X_i,X_j \in
\mathcal{D}_R$.
Proof. Let A denote the event that (i) or (ii) fails for some  $i,j \leq Z,$ and let B denote the event that (i) or (ii) fails for some
 $i,j \leq
\min(N,Z)$. It follows that
 \begin{equation}
\mathbb{P}(B \ \,\,|\, \ \, Z \geq N) \leq \frac{\mathbb{P}(B)}{\mathbb{P}(Z \geq
N)} \leq \frac{\mathbb{P}(A)}{\mathbb{P}(Z \geq N)} \stackrel{N \to
\infty}{\longrightarrow} \frac{0}{1/2} = 0,
\label{eqn6}
\end{equation}(6)
because  $\mathbb{P}(A) \to 0$ by Lemma 2 and
 $\mathbb{P}(Z \geq N) \to \frac12$ by the central limit theorem. Next, let us observe that
 ${{\mathbb P}}( B \ \,\,|\, \ \, Z = N ) = {{\mathbb P}}( B \ \,\,|\, \ \, Z=N+1 ) =
\cdots$ since the points with index greater than
 $\min(N,Z)$ are irrelevant for the event B. From this, it follows that
 \begin{equation}
{{\mathbb P}}( B \ \,\,|\, \ \, Z \geq N ) = \frac{\sum_{i \geq N} {{\mathbb P}}( B \ \,\,|\, \ \, Z = i )
{{\mathbb P}}( Z=i )}{\sum_{i\geq N} {{\mathbb P}}( Z = i ) } = {{\mathbb P}}(B\ \,\,|\, \ \, Z=N ).
\label{eqn7}
\end{equation}(7)
Combining 6 and 7, we see that  ${{\mathbb P}}( B \ \,\,|\, \ \,
Z = N ) = o(1)$, as desired.
Acknowledgement
We warmly thank Nikolaos Fountoulakis for helpful discussions during the early stages of this project.