Introduction
Sustainability performance has achieved remarkable development over the last few years (Fifka, Reference Fifka2013), increasing so the trend to report such performance via the voluntary disclosure (Clarkson, Li, Richardson, & Vasvari, Reference Clarkson, Li, Richardson and Vasvari2008) in a sustainability report that assesses the three main components of environmental protection, economic growth and social equity (Morimoto, Ash, & Hope, Reference Morimoto, Ash and Hope2005). Moreover, the continuing calls to achieve the disclosure of sustainability performance have led companies beyond sustainability reports, where some of them have begun to combine social and environmental information with financial data in a single document, the integrated reporting, as part of an effective sustainable strategy that meets the need of information demanded by stakeholders (Frías-Aceituno, Rodríguez-Ariza, & García-Sánchez, Reference Frías-Aceituno, Rodríguez-Ariza and García-Sánchez2013). Social and environmental information, both in sustainability reports as in integrated reports, are valuable for investors and their data are incorporated into valuation models, generating benefits such as a lower level of analyst forecast error, a higher firm value and reputation, and a lower cost of equity capital (Dhaliwal, Radhakrishnan, Tsang, & Yang, Reference Dhaliwal, Radhakrishnan, Tsang and Yang2012). However, the upturn in the number of sustainability reports as well as integrated reports has not been accompanied by an increased level of public trust (Hodge, Subramaniam, & Stewart, Reference Hodge, Subramaniam and Stewart2009); the voices of concern about the lack of credibility, transparency and consistency of sustainability reporting have led to the need for assurance processes (Adams & Evans, Reference Adams and Evans2004; Simnett, Vanstraelen, & Chua, Reference Simnett, Vanstraelen and Chua2009). According to the General Reporting Initiative (2006) assurance of sustainability reports is defined as ‘activities designed to result in published conclusions on the quality of the report and the information contained within it’.
Similar to auditing financial information and as a result of stakeholders’ pressure to enhance the credibility of sustainability information, assurance is perceived by external scrutiny as the key element of the social and/or environmental information issued. Regarding this point, assurance may provide credibility and transparency of such information (Adams & Evans, Reference Adams and Evans2004; O’Dywer & Owen, Reference O’Dwyer and Owen2005; Deegan, Cooper, & Shelly, Reference Deegan, Cooper and Shelly2006; Simnett, Vanstraelen, & Chua, Reference Simnett, Vanstraelen and Chua2009). It increases the trust of stakeholders not only in the quality of information but also in the corporate sustainable commitment (Hodge, Subramaniam, & Stewart, Reference Hodge, Subramaniam and Stewart2009; Simnett, Vanstraelen, & Chua, Reference Simnett, Vanstraelen and Chua2009). Moreover, it acts as a monitoring tool of managers (Wong & Millington, Reference Wong and Millington2014), since sustainability reporting can address agency relationships and decrease information asymmetries and uncertainty (Moroney, Windsor, & Aw, Reference Moroney, Windsor and Aw2012). In summary, the voluntary demand for assurance is, in part, intended to increase the credibility of sustainability information (Perego & Kolk, Reference Perego and Kolk2012) as well as to catalyze an effective and constructive dialogue with the company’s stakeholders (KPMG, 2002).
In this context and moreover, the growth of multinational companies in the global marketplace and the importance in the economic and social sphere of emerging countries imply that firms are economic units that operate within contexts formed by a nexus of institutions that affect their behaviour and impose expectations on them (Campbell, Hollingsworth, & Lindberg, Reference Campbell1991; Campbell, Reference Campbell, Hollingsworth and Lindberg2007). That is, organizations operating in countries with similar institutional structures will adopt homogeneous forms of behaviour (La Porta, Lopez-de-Silanes, Shleifer, & Vishny, Reference La Porta, López de Silanes, Shleifer and Vishny1998; Campbell, Reference Campbell, Hollingsworth and Lindberg2007). DiMaggio and Powell (Reference DiMaggio and Powell1983) name this process ‘isomorphism’ and argue that it enhances companies’ stability and survival, facilitating political power and institutional legitimacy. In other words, any company can modify its behaviour towards sustainability practices, disclosure and subsequent assurance according to the social environment in which it develops (Meyer & Rowan, Reference Meyer and Rowan1977). It is expected that the ensuring of legitimacy via sustainability assurance may be strongly influenced by institutional factors (Simnett, Vanstraelen, & Chua, Reference Simnett, Vanstraelen and Chua2009; Kolk & Perego, Reference Kolk and Perego2010; Boiral & Gendron, Reference Boiral and Gendron2011).
Nowadays, however, this approach is reinforced by neo-institutional theory. Following the neo-institutional approach, ensuring corporate long-term survival and social legitimacy may represent one of the major reasons for an organization to adopt an assurance process (DiMaggio & Powell, Reference DiMaggio and Powell1983; Kolk & Perego, Reference Kolk and Perego2010). Similar to the findings of Frías-Aceituno, Rodríguez-Ariza, and García-Sánchez (Reference Frías-Aceituno, Rodríguez-Ariza and García-Sánchez2013) for the disclosure of an integrated report, we assume that assurance may be influenced by external pressures in the search for legitimacy (Kolk & Perego, Reference Kolk and Perego2010), sustainability assurance shows great variability between countries, reflecting the fact that, in line with previous studies (Simnett, Vanstraelen, & Chua, Reference Simnett, Vanstraelen and Chua2009; Kolk & Perego, Reference Kolk and Perego2010; Boiral & Gendron, Reference Boiral and Gendron2011) sustainability assurance may be strongly influenced by institutional factors.
As one of these factors and based on previous studies that consider the legal system at the country level as a key institutional factor (Perego, Reference Perego2009; Martínez-Ferrero & García-Sánchez, Reference Martínez-Ferrero and García-Sánchez2017), companies that are most likely to act in a socially responsible way are those that operate in an institutional setting with a strong legal system aimed at the protection of stakeholders (Campbell, Reference Campbell, Hollingsworth and Lindberg2007; Frías-Aceituno, Rodríguez-Ariza, & García-Sánchez, Reference Frías-Aceituno, Rodríguez-Ariza and García-Sánchez2013; Garcia-Sanchez, Cuadrado-Ballesteros, & Frias-Aceituno, Reference Garcia-Sanchez, Cuadrado-Ballesteros and Frias-Aceituno2016). Smith, Haniffa, and Fairbrass (Reference Smith, Haniffa and Fairbrass2011) evidences that firms located in countries that are more stakeholder-oriented report higher-quality sustainability information since they have social responsibilities beyond shareholder maximization (Kolk & Perego, Reference Kolk and Perego2010). Based on the above, we adopt the evidence of Frías-Aceituno, Rodríguez-Ariza, and García-Sánchez (Reference Frías-Aceituno, Rodríguez-Ariza and García-Sánchez2013) – for integrated reporting – Simnett, Vanstraelen, and Chua, (Reference Simnett, Vanstraelen and Chua2009), Kolk and Perego (Reference Kolk and Perego2010) and Zhou, Simnett, and Green (Reference Zhou, Simnett and Green2013), among others, who report that in countries where stakeholders have a greater influence on corporate decisions, sustainability performance tends to be more informative and companies show a greater preference for adopting an assurance system.
Nonetheless, the effect of country-level factors – and more specifically of stakeholder orientation – on the decision to assure is conditioned by firms’ corporate governance structure (Zhou, Simnett, & Green, Reference Zhou, Simnett and Green2013), since both country and firm factors explain the assurance decision (Francis, Khurana, Martin, & Pereira, Reference Francis2011). Corporate governance is understood as ‘the system by which companies are directed and controlled’ (Cadbury, Reference Cadbury2000), which balances the welfare of all stakeholders and mitigates business risks. In this regard, while Corporate Governance consists of different mechanisms, one of the main ones is the board of directors, which carries out a monitoring role of the management on behalf of the stakeholders (Aguilera, Williams, Conley, & Rupp, Reference Aguilera, Williams, Conley and Rupp2006), ensuring that both financial and social responsibility aims are achieved. The board of directors, as the firm’s governing body, is responsible for safeguarding the interests of the different stakeholders, among other means through the dissemination of information and its subsequent verification, to reduce information-related problems – for example, lack of credibility – and to prevent opportunistic behaviour (Richardson & Welker, Reference Richardson and Welker2001).
Following the description of assurance, corporate governance has been addressed as sets of accountability tools that increase the level of legitimacy (Aguilera et al., Reference Aguilera, Williams, Conley and Rupp2006), establishing the possible complementary or substitutive association among these two concepts. However, despite the wide literature about voluntary disclosure on sustainability issues (Brammer & Pavelin, Reference Brammer and Pavelin2006; Barako & Brown, Reference Barako and Brown2008), limited knowledge exists about the nature, scope and factors of assurance (Kolk & Perego, Reference Kolk and Perego2010; Simnett, Vanstraelen, & Chua, Reference Simnett, Vanstraelen and Chua2009). Accordingly, the aim of this paper is to explore the corporate governance factors associated with voluntary sustainability assurance and, moreover, with the choice of the assurance provider, taking as theoretical background the previous evidence regarding sustainability reporting. Moreover, we will focus on examining stakeholder-oriented countries, since country and firm factors interact in the assurance demand and in the choice of the assurance provider (Doidge, Karolyi, & Stulz, Reference Doidge, Karolyi and Stulz2007; Zhou, Simnett, & Green, Reference Zhou, Simnett and Green2013).
Following these introductory arguments and having described our research aims, the paper is organized as follows. First, we provide a discussion of the studies that examine the role of corporate governance mechanisms in the area of sustainability reporting, assurance and assurance providers, developing our testable propositions. The subsequent section present sample data and the research model of the analysis, followed by the empirical results. Finally, conclusions, contributions and suggestions for future research are provided.
Research Hypotheses
Our study aims to explore the relationship between corporate governance strength as a firm-level factor and the assurance process in a stakeholder-oriented context as a country-level factor. Following our first topic of research, we extend the study of corporate governance strength by examining the choice of the assurance provider.
Demand for sustainability assurance
Board responsibilities extend beyond controlling and monitoring management to ensure that it adopts decisions that are consistent with the organization, aligning the principal and agent interests. The board plays a fundamental role in determining the socially responsible behaviours of an organization and the level of accountability towards the different interest groups (Michelon & Parbonetti, Reference Michelon and Parbonetti2012; Rupley, Brown, & Marshall, Reference Rupley, Brown and Marshall2012). The fulfilment of these tasks is affected by the composition of the board (Goodstein, Gautam, & Boeker, Reference Goodstein, Gautam and Boeker1994) in terms of size, independence and activity (Hang et al., 2007). This study focuses specifically on characteristics such as board size, board independence and activity of the sustainability committee in the analysis of the assurance determinants.
Increasing its size is also followed by an increase in the board’s effectiveness because a high number of directors provide the experience and diversity needed to control the corporate activities proposed by the board (García Sánchez, Rodríguez Domínguez, & Gallego Álvarez, Reference García Sánchez, Rodríguez Domínguez and Gallego Álvarez2011). A large board may seat directors with different characteristics regarding expertise, training, dependence links, independence and so on (Dalton, Daily, Ellstrand, & Johnson, Reference Dalton, Daily, Ellstrand and Johnson1998). Thus, a board should ideally be of sufficient size to include members who, in concert, fill all these often separate roles in the assurance demand. From the above we can conclude that larger boards possess more experience regarding sustainable strategies and their reporting and verification (Allegrini & Greco, Reference Allegrini and Greco2013). On this line, the complexity of management control as well as of ensuring the accuracy of the information provided requires the presence of a considerable number of directors (García Sánchez, Rodríguez Domínguez, & Gallego Álvarez, Reference García Sánchez, Rodríguez Domínguez and Gallego Álvarez2011) to address the issues raised by various stakeholders.
Moreover, by increasing in size, board members help by linking organizations to their external environment and secure critical resources, including prestige and legitimacy (Pearce & Zahra, Reference Pearce and Zahra1992; Mintzberg, Reference Mintzberg1993). In agreement with the legitimacy goal and the findings regarding sustainability disclosure, we expect larger boards to show a greater assurance demand.
Meanwhile, board independence guarantees the necessary checks and balances to enhance board effectiveness in the control of firm activities (Franks, Mayer, & Renneboog, Reference Franks, Mayer and Renneboog2001). Independent directors – professionals who are totally independent of the management – are viewed as a reliable mechanism capable of diffusing agency conflicts since they assure the board’s independence from the management (Patelli & Prencipe, Reference Patelli and Prencipe2007). Moreover, they are seen as an accountability mechanism because their role is to help ensure that companies are pursuing the interests not only of their shareholders but also of their stakeholders (Haniffa & Cooke, Reference Haniffa and Cooke2005).
The previous evidence relating to the association between board independence and the promotion of sustainable actions and their reporting is vast. Although the evidence is not conclusive, much of it agrees in pointing out that a greater proportion of independent directors increases the focus on social and environmental issues and information disclosure (Barako & Brown, Reference Barako and Brown2008; Rupley, Brown, & Marshall, Reference Rupley, Brown and Marshall2012). In general, the theoretical framework defends this positive association based on (i) their greater capability of balancing financial versus non-financial goals (Haniffa & Cooke, Reference Haniffa and Cooke2005); (ii) their strong stakeholder orientation; (iii) the decrease in information asymmetries and litigation risks; and, moreover, (iv) the protection of their reputation (Lim, Matolcsy, & Chow, Reference Lim, Matolcsy and Chow2007). Thus, independent directors exhibit greater concern about social and environmental issues, being more sensitive to stakeholders’ demands (Ibrahim, Howard, & Angelidis, Reference Ibrahim, Howard and Angelidis2003), which we expect will increase the assurance systems of sustainability reporting, improving the quality of the information disclosed (Herda, Taylor, & Winterbotham, Reference Herda, Taylor and Winterbotham2014).
Moreover, since sustainability assurance acts as a legitimacy tool (Simnett, Vanstraelen, & Chua, Reference Simnett, Vanstraelen and Chua2009), it can be expected that independent directors show a greater preference for sustainable issues, their reporting and their subsequent assurance, to ensure the legitimacy of their actions.
In addition, as independent directors are economic agents whose decisions are influenced by their own interests (Ravina & Sapienza, Reference Ravina and Sapienza2010), they have incentives to report sustainable information of which the truthfulness is confirmed by external professionals, meaning reporting is assured. Consequently, they have limited involvement in the company’s daily operations and need to provide additional checks on the management’s behaviour to protect their reputational capital. Therefore, in general, assurance serves to protect independent directors by decreasing the chance that errors and omissions will exist in the sustainability statement (Kolk & Perego, Reference Kolk and Perego2010). On this line, Amran, Lee, and Devi (Reference Amran, Lee and Devi2014) defends the idea that external directors encourage a firm to develop a mechanism in order to achieve a higher degree of accountability and transparency.
As the third strength factor of the board, one of the activities that the board may carry out to manage sustainability actions, reporting and assurance is to establish a corporate social responsibility (CSR) or sustainability committee (Michelon & Parbonetti, Reference Michelon and Parbonetti2012). This specific committee aims to address social and environmental issues from the risk perspective and commitment to stakeholders’ demands (Liao, Luo, & Tang, Reference Liao, Luo and Tang2015). The active strategic focus on addressing stakeholders’ demands is based on the experience, skill and knowledge of the members of such a committee (Amran, Lee, & Devi, Reference Amran, Lee and Devi2014).
Their responsibilities and duties include both assisting the management in strategy formulation and reviewing the social and environmental development and growth, integrating the sustainable aspect into the firm’s daily activity and reviewing its reporting strategy (Post, Preston, & Sachs, Reference Post, Preston and Sachs2002), which, nowadays, includes the assurance process. Thus, the creation of a CSR committee that deals with sustainability issues to face the legitimacy problem may be seen an effective mechanism to improve the sustainability reporting (Adnan Reference Adnan2009) providing more credible non-financial reporting through the dissemination of an external assurance statement.
In this regard, Liao, Luo, and Tang (Reference Liao, Luo and Tang2015) finds that the existence of an environmental (or sustainability) committee reflects a firm’s proactivity regarding such issues, leading to a more transparent and credible disclosure (Peters & Romi, Reference Peters and Romi2012). However, the literature is almost inexistent and is limited to Kend’s (Reference Kend2015) research on Australian and UK firms and Peters and Romi’s (Reference Peters and Romi2015) study of US firms. Kend (Reference Kend2015) defends the assertion that an active sustainability committee positively affects the decision to produce an assured sustainability report. Also on this subject, Peters and Romi (Reference Peters and Romi2015) point out that environmental committees containing directors with related experience positively influence the adoption of an assurance system. They are likely to influence the extent of the monitoring and controlling role for sustainability issues, including the demand for assurance processes to provide confidence on this kind of information. Therefore, we expect that an active sustainability committee is associated with greater diligence, showing greater interest in the promotion of social and environmental actions in its reporting and, as a result, in greater transparency to the outside by an external assurance process.
Based on all of the above arguments, a greater assurance demand can be expected from companies with greater corporate governance strength manifested in a larger and more independent board and more active sustainability committees. Moreover, focusing on our sample of analysis, the positive effect of the institutional environment – the stakeholder orientation level – can be amplified by the strength of corporate governance (Zhou, Simnett, & Green, Reference Zhou, Simnett and Green2013).
Hence, the following hypothesis is proposed:
The strength of the board is positively related to sustainability assurance in stakeholder-oriented countries.
Demand for an assurance provider
In addition to the previous research hypothesis, we analyze the impact of the boards’ strength on the assurance provider, since the choice of the third-party assurance provider is a management issue that is subject to the board’s decision. In the case of sustainability assurance, there has been considerable growth in specialist companies in the assurance process (Hodge, Subramaniam, & Stewart, Reference Hodge, Subramaniam and Stewart2009). In general accountancy/auditing firms, engineering firms and sustainability consultants provide external assurance services. The debate is focused on accountants versus non-accountants, since auditing firms have traditionally carried out the verification of financial statements.
Previous research about the type of assurance provider and the quality of external verification agrees that a higher level of credibility is given to accounting professionals (traditionally known as the Big-4 auditing firms) by investors (Pflugrath, Roebuck, & Simnett, Reference Pflugrath, Roebuck and Simnett2011). Accountancy firms are subject to independent and professional conduct requirements (Peters & Romi, Reference Peters and Romi2015), providing more detailed and consistent statements, transferring auditing techniques to the assurance process (Power, Reference Power2003) and being more effective monitors as a result of their reputational capital (Simnett, Vanstraelen, & Chua, Reference Simnett, Vanstraelen and Chua2009). Moreover, their skills, abilities and competences have been widely recognized in the market for financial auditing, which is perfectly transferable to the sustainability assurance market (Hodge, Subramaniam, & Stewart, Reference Hodge, Subramaniam and Stewart2009), increasing investors’ trust in their credibility.
Meanwhile, engineering and consultancy firms as assurance providers of qualitative statements have greater subject matter expertise on specific sustainability issues (Huggins, Green, & Simnett, Reference Huggins, Green and Simnett2011), providing assurance statements that are more informative, complete and clear (Hasan, Roebuck, & Simnett, Reference Hasan, Roebuck and Simnett2003). As fundamental difference from accountancy firms, they include recommendations and comments on processes and systems (Deegan, Cooper, & Shelly, Reference Deegan, Cooper and Shelly2006). Nonetheless, they do not benefit from the independence of accountancy firms (Huggins, Green, & Simnett, Reference Huggins, Green and Simnett2011) and their global knowledge of multidisciplinary industries and multiple jurisdictions (Simnett, Vanstraelen, & Chua, Reference Simnett, Vanstraelen and Chua2009).
Focusing on the topic of this research, the strength of corporate governance (board size and independence, among others) is positively related to the demand for high audit quality (Cohen, Holder-Webb, Nath, & Wood, Reference Cohen, Holder-Webb, Nath and Wood2011). Thus, a more effective and stronger board – those characterized by a larger size, greater independence and an active sustainability committee – will choose an assurance provider who is able to offer a more credible assurance statement to the market stakeholders. In this regard, general studies note that accountants are preferred to assure sustainability reports because of the professional attributes of expertise and objectivity projected by their profession (Gray, Reference Gray2000; Knechel, Wallage, Eilifsen, & Van Praag, Reference Knechel, Wallage, Eilifsen and Van Praag2006). The training received by accountants provides them with relevant skills that are not available to other practitioners, allowing an understanding of matters of evidence, communication and information systems, with independence in mind (Gray, Reference Gray2000). According to literature on financial auditing, it is expected that the assurance developed by Big-4 auditing firms is higher quality than that of other assurers (Francis, Reference Francis2004). Thus, it is anticipated that the Big-4 auditing firms tend to issue accurate reports and produce high-quality outcomes.
Although the literature is limited, Beasly and Petroni (2001) observe that independent directors play a fundamental role in the choice of accountancy firms that employ a brand name to guarantee audit quality and reduce the consequences associated with financial disclosures. This can be supported by the previous research by Carcello, Hermanson, Neal, and Riley (Reference Carcello, Hermanson, Neal and Riley2002), which points out that external directors show greater willingness to pay for additional audits and even more for higher-quality audits. Finally, the existence and diligence of a sustainability committee appears to be positively related to the assurance from the accounting profession to provide higher-quality assurance services (Kend, Reference Kend2015; Peters & Romi, Reference Peters and Romi2015).
Finally, and again focusing on our stakeholder-oriented sample, Simnett, Vanstraelen, and Chua, (Reference Simnett, Vanstraelen and Chua2009) finds that companies located in countries that are more stakeholder oriented show a greater tendency to choose an assurance provider from the accountancy profession. At the same time, Zhou, Simnett, and Green (Reference Zhou, Simnett and Green2013) shows the preference of assurance by Big-4 audit firms for those companies registered in stakeholder-oriented countries, an effect that is more prevalent in firms with a strong governance structure.
Based on this, the demand for assurance provided by the accountancy profession in stakeholder-oriented countries is expected to be strong in companies with large and more independent boards, with sustainability committees that are more active. Thus, the following hypothesis is suggested:
The strength of the board is positively related to sustainability assurance provided by the accountancy profession in stakeholder-oriented countries.
Method
Data
The data source was formed based on an initial selection of the world’s largest 2,000 listed firms provided by ForbesFootnote 1 , a selection that is widely employed in prior research. We based the composition of our sample on the information that is available in two databases: Thomson One AnalyticsFootnote 2 for the accounting and financial information (e.g., total assets, leverage, market-to-book ratio, etc.) provided in consolidated financial statements; and the Ethical Investment Research Service (EIRISFootnote 3 ), for data on sustainability reports. We complemented this information by a review of these reports published by each company on their website because of there has been a continuing growth in terms of the media used for disclosure sustainability information, particularly the internet (Fifka, Reference Fifka2013).
The sample procedure is as follows: for the initial largest 2,000 firms, we included their economic, financial and accounting data obtained from Thomson One Analytics, excluding financial firms since their specific characteristics in terms of equity make them non-comparable with non-financial firms (La Porta, Lopez‐de‐Silanes, & Shleifer, Reference La Porta, Lopez‐de‐Silanes and Shleifer2002). This exclusion meant that our sample was composed, at this stage, of 1,560 international non-financial listed companies. Then, we combined information of these firms with data available on the EIRIS database and on the company website, resulting in a sample composed of 1,260 companies in the period 2007–2014.
Nevertheless, this study is focused on environments that are more stakeholder oriented, this civil law sample offers an opportunity to understand how countries’ stakeholder orientation as a strong legal environment affects the impact of corporate governance aspects on the decision to assure and the choice of assurance provider. Thus, from the previous 1,560 international non-financial listed companies, we restrict our sample of analysis to different civil law countries. The choice of the country corresponds to the breakdown by La Porta, Lopez-de-Silanes, Shleifer, and Vishny (Reference La Porta, Lopez-de-Silanes, Shleifer and Vishny1997) and previous studies (Kolk & Perego, Reference Kolk and Perego2010; Hillier, Pindado, De Queiroz, & De La Torre, Reference Hillier, Pindado, De Queiroz and De La Torre2011), which analyze the stakeholder orientation by comparing common and civil law countries. According to La Porta et al. (Reference La Porta, López de Silanes, Shleifer and Vishny1998), investors often enjoy greater protection of their interests in countries with a common law system in which a company is considered as an instrument to create and maximize shareholder value. Meanwhile, countries based on the civil law system show greater commitment to and orientation towards a coalition of several participants (Simnett, Vanstraelen, & Chua, Reference Simnett, Vanstraelen and Chua2009; Frías-Aceituno, Rodríguez-Ariza, & García-Sánchez, Reference Frías-Aceituno, Rodríguez-Ariza and García-Sánchez2013). Civil law countries show a greater preference for economic, social and environmental aspects and so on for their disclosures (Frías-Aceituno, Rodríguez-Ariza, & García-Sánchez, Reference Frías-Aceituno, Rodríguez-Ariza and García-Sánchez2013), which is applicable to the assurance process.
At this stage, the final sample was composed of 610 international companies listed that operate in civil law countries for the period 2007–2014. The sample, consisting of 3,241 observations, is unbalanced because full data were not available for all the companies and for all the years. The firms are from different activity sectors – financial, basic materials, industrial, utilities, services industry, construction, retail, transportation and telecommunications – and different civil law countries – Belgium, Denmark, Finland, France, Germany, Italy, Japan, the Netherlands, Norway, Spain, Sweden and Switzerland.
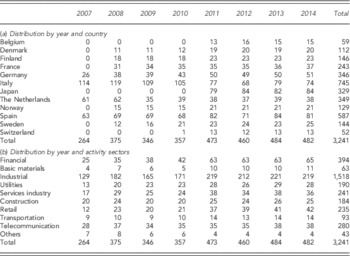
Table 1 shows the sample distribution by year and country on the one hand and by year and activity sector on the other. Panel (a) shows that the higher percentages refer to the years 2013 and 2014, making up for almost 30% of the observations. In relation to geographic diversity, almost 23% of the observations belong to firms located in Italy, followed by 18.11% accounted for by Spanish firms and by 10.68% accounted for by German firms. The remaining observations are evenly distributed throughout the other countries and years analyzed. Among the activity sectors, Panel (b) reports that the industrial sector (i.e., manufacturing firms) is the most represented in the sample (46.84% of observations) while the rest of the sectors are evenly represented.
Sample distribution

Note. Sample of 610 firms in the period 2007–2014. The sample is unbalanced because companies are not in all periods, resulting in 3,241 observations.
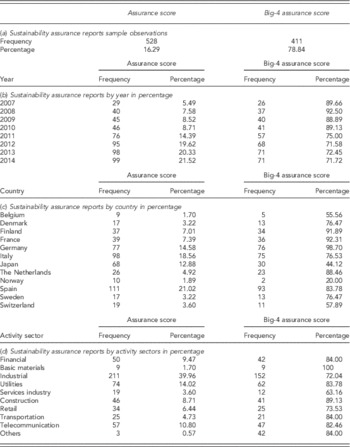
Following the description of the sample by year, country and industry, Table 2 shows for each of them the frequency of sustainability reports verified by an assurance process and the frequency of assurance being provided by the accountancy profession. First of all, Panel (a) reports that out of 3,241 observations from our sample of 610 international companies, 528 sustainability reports are accompanied by assurance representing 16.29% of the total. Moreover, out of those 528 sustainability reports 411 assured their reports have been externally verified by the so-called Big-4 audit firms, reflecting the higher market assurance share of the accountancy profession in comparison with other assurance providers, such as smaller audit firms, consultancy or engineering firms.
Sustainability assurance reports distribution

Note. Sample of 610 firms in the period 2007–2014. The sample is unbalanced because companies are not in all periods, resulting in 3,241 observations.
Regarding the year frequency, Panel (b) shows the increase from around 5.45% of sustainability reports in 2007 to almost 22% in 2014. This panel supports the previous data of the KPMG (2013) report analyzing the increase in the amount of sustainability reports that are certified by an assurance provider. Companies are adopting the assurance process to clarify their sustainability reports and to increase their transparency and credibility, despite its non-mandatory aspect. Meanwhile, the sustainability assurance market is strongly dominated by the Big-4 audit firms, supporting the relevance of their reputational capital (Simnett, Vanstraelen, & Chua, Reference Simnett, Vanstraelen and Chua2009; O’Dwyer, Owen, & Unerman, Reference O’Dwyer, Owen and Unerman2011). Simnett, Vanstraelen, & Chua (Reference Simnett, Vanstraelen and Chua2009) research show that those companies located in more stakeholder-oriented countries have a greater preference for choosing assurance statements developed by the accountancy profession (Big-4 firms). However, the year of the highest proportion of reports verified by the accounting profession is 2008 (over 90%); decreasing the following years. As Kolk and Perego (Reference Kolk and Perego2010) report, the accountancy profession has been experiencing a decline as a result of the increased number of other kind of third-party providers, such as engineering and consultancy firms.
Regarding the country distribution, Panel (c) shows that there is substantial variation across countries. Note the list of countries where the assurance rate is higher is headed by Spain followed by Italy, both accounting for about 20% of the assured reports. Meanwhile, the assurance of sustainability reports remains limited in Norwegian and Belgian firms. For the assurance market, the countries that are most likely to choose the accountancy profession to assure their sustainability reports are Germany (almost all of the assured reports) and France (92.31%), while Norwegian companies prefer to obtain assurance services from consultants or engineering firms (around 20%).
Finally, regarding the activity sector distribution, Panel (d) also shows a variation among them. More specifically, statistics indicate that the adoption of assurance statements is highest in the industrial sector (almost 40%), followed by utility firms (about 14% of the reports verified) which are more exposed to environmental and social risks, with the subsequent need for increasing the credibility of such information. In alignment with Cho et al. (2014) findings, the assurance demand is positively linked to more environmentally sensitive industries, for example industrial or even financial sectors. Meanwhile, the accountancy profession dominates the assurance market for firms operating in the basic materials (100%) and construction (around 90%) sectors.
Research model
The analysis of propositions could be performed by estimating two models: the first relates the corporate governance determinants to the adoption of sustainability assurance while the second proposition associates such determinants with the choice of the assurance provider.
For Model 1 and in order to test our first proposition concerning the impact of board aspects on the companies’ decision to assure their sustainability reports, we regress assurance on measures of board size, independence and the activity of the sustainability committee, while controlling for individual boards’ characteristics (diversity and duality), individual firms’ characteristics (size, profitability and growth) and activity sector, country and year effects.
Specifically, we estimate the following panel data regression (Model 1):
 $$\eqalignno{ {\rm Prob}\left( {{\rm Assurance}} \right)\,&{\rm {\equals}\,\alpha }_{{\rm 0}} {\rm {\plus}\alpha }_{{\rm 1}} Board\_Size_{{it}} {\rm {\plus}\alpha }_{{\rm 2}} Board\_Size\_2_{{it}} {\rm {\plus}\alpha }_{{\rm 3}} \,\%\,Indep_{{it}} {\rm {\plus}\alpha }_{{\rm 4}} Sust\_Com\_Act_{{it}} \cr &{\rm {\plus}\alpha }_{{\rm 5}} Diversity_{{it}} {\rm {\plus}\alpha }_{{\rm 6}} Duality_{{it}} {\rm {\plus}\alpha }_{{\rm 7}} Size_{{it}} {\rm {\plus}\alpha }_{{\rm 8}} Profitabilty_{{it}} {\rm {\plus}\alpha }_{{\rm 9}} Growth_{{it}} \cr & {\rm {\plus}}\mathop{\sum}\limits_{j{\rm \,{\equals}\,10}}^{{\rm 19}} {{\rm \alpha }_{j} Industry_{i} {\rm {\plus}}\mathop{\sum}\limits_{k{\rm \,{\equals}\,20}}^{{\rm 31}} {{\rm \alpha }_{k} Country_{i} } {\rm {\plus}}} \mathop{\sum}\limits_{n{\rm \,{\equals}\,32}}^{{\rm 39}} {{\rm \alpha }_{n} Year_{t} {\rm {\plus}\mu }_{{it}} {\rm {\plus}\eta }_{i} } $$
where i goes from company 1 to company 610; t takes the values of the years from 2007 to 2014; j goes from activity sector 1 to activity sector 10; k goes from country 1 to country 12; α represents the estimating parameters; η i, represents the unobservable heterogeneity; and μ it represents the classical error term. ‘Assurance’ is a dummy variable coded 1 if a firm’s sustainability report is assured and 0 otherwise. This is the common measure in management and accounting research (Simnett, Vanstraelen, & Chua, Reference Simnett, Vanstraelen and Chua2009; Fernandez-Feijoo, Romero, & Ruiz, Reference Fernandez-Feijoo, Romero and Ruiz2014; Herda, Taylor, & Winterbotham, Reference Herda, Taylor and Winterbotham2014; Wong & Millington, Reference Wong and Millington2014; Peters & Romi, Reference Peters and Romi2015). ‘Board_Size’ represents the board size measured as the total number of directors of the board (de Andrés & Vallelado, Reference de Andrés and Vallelado2008; Michelon & Parbonetti, Reference Michelon and Parbonetti2012). ‘Board_Size_2’ is captured as the square of the previous variable to test a possible non-linear relationship (Dwivedi & Jain, Reference Dwivedi and Jain2005; Garcia-Sanchez, Cuadrado-Ballesteros, & Sepulveda, Reference Garcia-Sanchez, Cuadrado-Ballesteros and Sepulveda2014). This means that the general behaviour of the board may be different when the number of directors passes a specific threshold. ‘%Indep’ represents the independence of the board captured as the percentage of non-executive directors over the total number of directors (de Andrés & Vallelado, Reference de Andrés and Vallelado2008; Khan, Muttakin, & Siddiqui, Reference Khan, Muttakin and Siddiqui2013; Liao, Luo, & Tang, Reference Liao, Luo and Tang2015) and ‘Sust_Com_Act’ represents the activity of the sustainability committee by capturing the total number of meetings held each year (Allegrini & Greco, Reference Allegrini and Greco2013; Kend, Reference Kend2015; Peters & Romi, Reference Peters and Romi2015). Some control variables are included to avoid biased results. Regarding the board’s characteristics, ‘Diversity’ represents the board diversity captured as the percentage of female and foreign directors in the total number of directors (Barako & Brown, Reference Barako and Brown2008; Samaha et al., 2012; Frías-Aceituno, Rodríguez-Ariza, & García-Sánchez, Reference Frías-Aceituno, Rodríguez-Ariza and García-Sánchez2013) and ‘Duality’ is measured as 1 if the CEO is the chairman of the board and 0 otherwise (Michelon & Parbonetti, Reference Michelon and Parbonetti2012; Peters & Romi, Reference Peters and Romi2015). Regarding the firm’s characteristics (Simnett, Vanstraelen, & Chua, Reference Simnett, Vanstraelen and Chua2009; Kolk & Perego, Reference Kolk and Perego2010; Khan, Muttakin, & Siddiqui, Reference Khan, Muttakin and Siddiqui2013; Liao, Luo, & Tang, Reference Liao, Luo and Tang2015; Peters & Romi, Reference Peters and Romi2015), ‘Size’ represents the firm size calculated as the natural logarithm of the total assets; ‘Profitability’ represents the corporate profitability calculated as the return on assets ratio, computed as the income before extraordinary items scaled by the total assets on 31 December for each year studied; and ‘Growth’ represents the firm’s growth opportunities calculated as the market-to-book ratio. Finally, Industry j are k dummy variables that represent the different k activity sectors in which the companies of the sample operate; ‘Country k ’ are j dummy variables that represent the different j countries of the sample; and ‘Year t ’ are t dummy variables that represent the t years of the sample.
To test our second proposition concerning the impact of board aspects on the companies’ choice to hire an accountancy firm to assure their sustainability reports externally and independently, we regress the accountancy profession (Big-4 audit firms) on measures of board size, independence and the activity of the sustainability committee, while controlling for individual board characteristics (diversity and duality), firm characteristics (size, profitability and growth) and activity sector, country and year effects.
Specifically, we estimate the following panel data regression (Model 2):
 $$\eqalignno{ {\rm Prob}\left( {{\rm Big{\minus}4}} \right)\,&{\rm {\equals}\,\beta }_{{\rm 0}} {\rm {\plus}\beta }_{{\rm 1}} Board\_Size_{{it}} {\rm {\plus}\beta }_{{\rm 2}} Board\_Size\_2_{{it}} {\rm {\plus}\beta }_{{\rm 3}} \,\%\,Indep_{{it}} {\rm {\plus}} {\rm \beta }_{{\rm 4}} Sust\_Com\_Act_{{it}} \cr &{\rm {\plus}\beta }_{{\rm 5}} Diversity_{{it}} {\rm {\plus}\beta }_{{\rm 6}} Duality_{{it}} {\rm {\plus}\beta }_{{\rm 7}} Size_{{it}} {\rm {\plus}\beta }_{{\rm 8}} Profitabilty_{{it}} {\rm {\plus}\beta }_{{\rm 9}} Growth_{{it}} \cr & {\rm {\plus}}\mathop{\sum}\limits_{j\,{\rm {\equals}\,10}}^{{\rm 19}} {{\rm \beta }_{j} Industry_{i} {\rm {\plus}}\mathop{\sum}\limits_{k\,{\rm {\equals}\,20}}^{{\rm 31}} {{\rm \beta }_{k} Country_{i} {\rm {\plus}}\mathop{\sum}\limits_{n\,{\rm {\equals}\,32}}^{{\rm 39}} {{\rm \beta }_{n} Year_{t} {\rm {\plus}\mu }_{{it}} {\rm {\plus}\eta }_{i} } } } $$
where β represents the estimating parameters and ‘Big-4’ is a dummy variable that takes the value 1 when a company discloses its sustainability report with an assurance statement provided by professional accountants (Big-4 audit firms: PricewaterhouseCoopers, Ernst & Young, Deloitte and KPMG), and the value 0 otherwise. That is, it takes the value 0 if the assurance is provided by small accountancy firms (non-Big-4 audit firm) and by an environmental engineering or third-party consultancy firm (Mock, Strohm, & Swartz, Reference Mock, Strohm and Swartz2007; Kolk & Perego, Reference Kolk and Perego2010; Moroney, Windsor, & Aw, Reference Moroney, Windsor and Aw2012; Casey & Grenier, Reference Casey and Grenier2015).
The econometric models used are based on dependence techniques for panel data. The use of a panel data set allows us to overcome the limitations of cross-sectional models, especially their low explanatory capacity, which is closely related to the period of analysis considered. Panel data models provide greater consistency and explanatory power by considering several time periods. In addition, this technique allows us to control for unobservable heterogeneity, which refers to the particular behaviour and characteristics of each company included in the sample. These characteristics differ among companies but are invariant over time, making it difficult to measure them because they are unobservable to the researchers. However, if we do not take them into account, the results could be biased.
We apply different regression models to the panel data, for which the decision regarding which analysis technique to use depends on the nature of the dependent variable. Because the dependent variables proposed for this study related to assurance and assurance providers – ‘Assurance’ and ‘Big-4’ – are dummy variables that take values of 0 and 1, it is necessary to use a panel data methodology that is appropriate for variables presenting 0 and 1 values. As Frías-Aceituno, Rodríguez-Ariza, and García-Sánchez, (Reference Frías-Aceituno, Rodríguez-Ariza and García-Sánchez2013) argumented, for categorical variables, it is inappropriate to use linear regression because the response values are not measured on a ratio scale and the error terms are not normally distributed. In addition, the linear regression model can generate as predicted values any real number ranging from negative to positive infinity, whereas a categorical variable can only present a limited number of discrete values within a specific rang (Hair, Black, Babin, & Anderson, Reference Hair, Black, Babin and Anderson1998).
Thus, the analytical technique is based on a logistic (logit) regression model, a binary probability model widely adopted in sustainability assurance (Fernandez-Feijoo, Romero, & Ruiz, Reference Fernandez-Feijoo, Romero and Ruiz2014; Herda, Taylor, & Winterbotham, Reference Herda, Taylor and Winterbotham2014; Peters and Romi, 2014; Simnett, Vanstraelen, & Chua, Reference Simnett, Vanstraelen and Chua2009). Specifically, the binomial or binary logistic regression deals with situations in which the observed outcome for a dependent variable can have only two possible types, like the dependent variable in this study. Then, this technique is well suitable for this case, where the phenomenon to be explained can only be measured as 0 and 1 alternatives. That is, for example, a first possibility is that the firm assures its sustainability report (our dependent variable codes as 1), while a second possibility is that the firm does not externally verified its sustainability report (our dependent variable so codes as 0). Logistic regression measures the relationship between the categorical dependent variable and one or more independent variables, which are usually (but not necessarily) continuous, using probability scores as the predicted values of the dependent variable. Thus, it treats the same set of problems as probit regression using similar techniques; the first assumes a logistic function and the second a standard normal distribution function. Specifically, logistic regression is used to predict the odds of being a case based on the values of the independent variables (predictors). The odds are defined as the probability that a particular outcome is a case divided by the probability that it is a non-case.
Results
Descriptive results
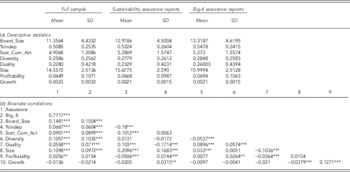
Table 3 shows the descriptive statistics and the bivariate correlations between the variables used in this study. The descriptive statistics are shown in Panel (a), breaking down the sample into three parts: (i) the full sample; (ii) only companies that assure their sustainability reporting; and (iii) only companies that select a Big-4 audit firm to assure their sustainability reporting. It can be observed that there are about 11 board members on average, increasing to 12 or 13 when considering only companies that assure their sustainability reporting. Similarly, the percentage of independent directors is around 50% in the full sample, increasing to 52% for companies that assure sustainability reports and 54% for companies that purchase assurance services from a Big-4 audit firm. Sustainability committee meetings do not differ greatly between the three samples; in general, such committees tend to meet approximately five times a year. Diversity also increases with assurance services – that is, the full sample has a 25% mean of female and foreign directors, which increases to >28% in assured companies. However, the mean of duality does not differ greatly between companies that do and do not assure their sustainability reporting. The mean values of corporate size, profitability and market-to-book ratio are also shown in Panel (a).
Descriptive statistics and bivariate correlations

Note. Sample of 610 firms in the period 2007–2014. The sample is unbalanced because companies are not in all periods, resulting in 3,241 observations.
Assurance is a dummy variable coded 1 if a firm’s sustainability report is assured and 0 otherwise; Big_4 is a dummy variables coded 1 if a firm’s sustainability report is assured by an accountancy firm and 0 if is assured by small accountancy firms (non-Big-4 audit firm), consultant or engineering firms. Board_Size represents the board size measures as the total number of directors of the board; %Indep represents the independence of the board captured as the percentage of non-executive directors over the total number of directors; Sust_Com_Act represents the activity of the sustainability committee by capturing the total number of meetings held in each year; Diversity represents board diversity captured as the percentage of women and foreigners directors over the total number of directors; Duality is measured as 1 if the CEO is the chairman of the board, and 0 otherwise; Size represents the firm size calculated as the natural logarithm of total assets; Profitability represents the corporate profitability calculate as the return on assets ratio, computed as income before extraordinary items scaled by the total assets on December 31 for each year studied; Growth represents the firm’s growth opportunities calculated as the market-to-book ratio.
***,**Significant at 1, 5 and 10% levels, respectively.
Panel (b) shows the bivariate correlations. The coefficients obtained for board characteristics and corporate characteristics are low, suggesting that the multicollinearity problem is not likely to be biased by these factor in the estimation of our two logistics models. Only the correlation between the variables Assurance and Big-4 is relatively high and statistically relevant at the 99% confidence level, suggesting that sample companies tend to purchase assurance services from a Big-4 firm. Finally, we can observe that the variables Assurance and Big-4 are positively related to board characteristics, in line with the previous hypotheses.
Corporate governance determinants of the adoption of sustainability assurance and the choice of assurance provider
The model set-up must be based on theoretical considerations and data adjustment. On panel data models, the discussion focuses on the analysis of individual effects, which are considered unobservable and constant factors in time that are specific to each individual and can be correlated with the explanatory variables (e.g., the diversity of the board or its activity). According to this, individual effects have been discussed in the literature as fixed effects – when the individual effects are correlated with the explanatory variables – and random effects – when there is no such correlation. Such consideration conditions fixed or random effects analysis and inference made with the model. To select the most appropriate estimator for our model (fixed or random) we will use the Hausman’s test. This test compares the β obtained by the estimator of fixed and random effects, identifying whether the differences between them are significant or not. Therefore, first, it is estimated by the less efficient but consistent method (fixed effects) and later by the efficient and consistent estimator (random effects). In both cases the matrix weight should be homoscedastic. This statistical test is obtained by calculating the differences between the β-weighted variance.
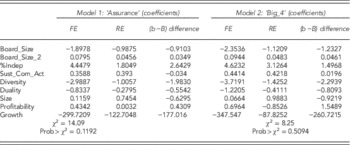
Thus, regardless of the treatment of the individual effects (fixed or random) we must do the two types of estimates described above in order to compare fixed and random effects by the Hausman’s test (as it can be observed in Table 4). The null hypothesis verifies the existence of no correlation between the individual effects and the explanatory variables (Ho: difference in coefficients is not systematic). If Prob>χ2 is >0.05, Ho is rejected, i.e., there is no correlation between individual effects and the explanatory variables, indicating that the random estimator should be used. Otherwise, when Prob>χ2 is <0.05 the fixed effects estimator would be the most appropriate. That is, when it is not rejected, the higher degree of efficiency in the estimation leads to the use of the random-effects model.
Fixed and random effects

Note. Hausman’s test.
Sample of 610 firms in the period 2007–2014. The sample is unbalanced because companies are not in all periods, resulting in 3,241 observations.
Assurance is a dummy variable coded 1 if a firm’s sustainability report is assured and 0 otherwise; Big_4 is a dummy variables coded 1 if a firm’s sustainability report is assured by an accountancy firm and 0 if is assured by small accountancy firms (non-Big-4 audit firm), consultant or engineering firms. Board_Size represents the board size measures as the total number of directors of the board; Board_Size_2 is captured as the square of the total number of directors to test a possible non-linear relationship. %Indep represents the independence of the board captured as the percentage of non-executive directors over the total number of directors; Sust_Com_Act represents the activity of the sustainability committee by capturing the total number of meetings held in each year. Controls include board and corporate aspects. Regarding board aspects: Diversity represents board diversity captured as the percentage of women and foreigners directors over the total number of directors; and Duality is measured as 1 if the CEO is the chairman of the board, and 0 otherwise.
Regarding corporate aspects: Size represents the firm size calculated as the natural logarithm of total assets; Profitability represents the corporate profitability calculate as the return on assets ratio, computed as income before extraordinary items scaled by the total assets on December 31 for each year studied; and Growth represents the firm’s growth opportunities calculated as the market-to-book ratio.
b=consistent under Ho (null hypothesis) and Ha (alternative hypothesis); B: inconsistent under Ha, efficient under Ho; FE: fixed effects; Ho: difference in coefficients not systematic; RE: random effects.
Examining values of the Hausman’s test for fixed and random effects in Models 1 and 2, the random-effects model was used for both models (Prob>χ2=0.1192 in Model 1; Prob>χ2=0.5094 in Model 2). This estimator was chosen after an analysis of the Hausman’s test, which suggested that there is no systematic difference between random effects and fixed effects (Prob>χ2>0.05). The random-effects model is more appropriate when there is no correlation between fixed effects and model variables, enabling to obtain more efficient coefficients. Furthermore, it assumes that the variables are non-random and not correlated with the explanatory variables (Green, Reference Green1999). Moreover, the random-effects model is more efficient (the variance of the estimate is low) but less consistent than the fixed-effects model. In other words, it is more accurate for calculating the parameter value but this may be more biased than the fixed-effects model. From a statistical point of view, the utilization of fixed effects’ panel data is a reasonable method because they always provide consistent results but may not be the most efficient model to run. Random effects show better results for p-values since they are more efficient estimators; therefore, random effects should be used if there is statistical justification. Moreover, using random effect estimators, logistic regression controls individual heterogeneity, taking into account that the companies are observed at different times.
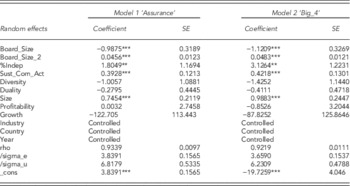
Based on this estimator, Table 5 provides the results of logistic regression Models 1 and 2 using random effects. Every coefficient is displayed with standard errors clustered by company. The results for Model 1 indicate that the probability of a company assuring its sustainability reporting decreases with the board size (α1=−0.9875, p<.01), meaning that the higher the number of directors, the lower the probability of assuring sustainability reporting. However, this trend changes, as the coefficient of board size squared shows (α2=0.0456, p<.01), suggesting a U-shaped relationship between the number of directors on the board and the probability of assuring sustainability reports. The minimum of such a quadratic relationship is 10.8259;Footnote 4 thus, the negative effect of the board size on the dependent variable turns positive when the number of directors is around 11. In terms of the independence and activity of the board, the empirical results indicate that the probability of assuring sustainability reporting increases with the number of independent directors (α3=1.8049, p<.05) as well as with the number of meetings of the sustainability committee (α4=0.3928, p<.01).
The impact of board characteristics on sustainability assurance and the type of assurance provider

Note. Sample of 610 firms in the period 2007–2014. The sample is unbalanced because companies are not in all periods, resulting in 3,241 observations.
Assurance is a dummy variable coded 1 if a firm’s sustainability report is assured and 0 otherwise; Big_4 is a dummy variables coded 1 if a firm´s sustainability report is assured by an accountancy firm and 0 if is assured by small accountancy firms (non-Big-4 audit firm), consultant or engineering firms. Board_Size represents the board size measures as the total number of directors of the board; Board_Size_2 is captured as the square of the total number of directors to test a possible non-linear relationship; %Indep represents the independence of the board captured as the percentage of non-executive directors over the total number of directors; Sust_Com_Act represents the activity of the sustainability committee by capturing the total number of meetings held in each year. Controls include board and corporate aspects. Regarding board aspects: Diversity represents board diversity captured as the percentage of women and foreigners directors over the total number of directors; and Duality is measured as 1 if the CEO is the chairman of the board, and 0 otherwise.
Regarding corporate aspects: Size represents the firm size calculated as the natural logarithm of total assets; Profitability represents the corporate profitability calculate as the return on assets ratio, computed as income before extraordinary items scaled by the total assets on December 31 for each year studied; and Growth represents the firm’s growth opportunities calculated as the market-to-book ratio.
We also include industry, country and time indicators. Industry j are k dummy variables that represent the different k activity sectors in which the companies of the sample operate; Country k are j dummy variables that represent the different j countries of the sample; and Year t are t dummy variables that represent the t years of the sample.
***,**Significant at 1, 5 and 10% levels, respectively.
The empirical results obtained for Model 2 are similar to those for Model 1. The findings suggest that the probability of purchasing assurance services from a Big-4 firm decreases with the board size, but this relationship becomes contrary from a minimum number of directors, concretely around 12Footnote 5 (β1=−1.1209, p<.01; β2=0.0483, p<.01). These findings suggest a U-shaped relationship between the board size and the decision to select a professional accountant to assure sustainability information. The results also suggest that board independence and the activity of the CSR committee affect positively the probability of purchasing assurance services from a Big-4 firm (β3=3.1264, p<.05; β4=0.4218, p<.01).
According to the hypotheses proposed in this study, the empirical findings suggest that the strength of the board in terms of size, independence and activity of the CSR committee are positively related to the probability of assuring sustainability information, especially when these services are provided by a Big-4 firm (Hang et al., 2007). Larger boards have more diverse experiences and knowledge, which broaden the traditional financial aims to other interests, such as social and environmental practices (García Sánchez, Rodríguez Domínguez, & Gallego Álvarez, Reference García Sánchez, Rodríguez Domínguez and Gallego Álvarez2011). However, the reporting is not sufficient at this moment and directors could be interested in the assurance of such information with the aim of gaining prestige, reputation and legitimation in the market (Pearce & Zahra, Reference Pearce and Zahra1992; Mintzberg, Reference Mintzberg1993). Moreover, according to our findings such a positive relationship appears from around 11 directors, suggesting a U-shaped relationship.
Our results also indicate that a higher number of independent directors increase the probability of purchasing sustainability assurance services, especially those provided by a Big-4 audit firm. Independent directors tend to be focused on sustainability issues; then, the probability of reporting increases (Barako & Brown, Reference Barako and Brown2008; Rupley, Brown, & Marshall, Reference Rupley, Brown and Marshall2012). Furthermore, since independent directors are economic agents, they have their own interests (Ravina & Sapienza, Reference Ravina and Sapienza2010), so they should be interested in reporting assured information with the aim of increasing their reputation in terms of truthfulness and credibility. The higher quality that has traditionally characterized financial auditing provided by a Big-4 firm (Gray, Reference Gray2000; Francis, Reference Francis2004; Cohen, et al., Reference Cohen, Holder-Webb, Nath and Wood2011) leads independent directors to prefer their services for assuring sustainability information.
Our findings provide evidence that a sustainability committee also plays a fundamental role in the decision of assuring these kinds of reports. More specifically, the empirical results are in accordance with Kend (Reference Kend2015) and Peters and Romi (Reference Peters and Romi2015), who noted a positive relationship between the activity of the sustainability/environmental committee and the adoption of assurance systems in Australia and the USA, respectively. Additionally to Kend (Reference Kend2015) and Peters and Romi (Reference Peters and Romi2015), we not only study the decision regarding assuring versus not assuring sustainability information, but the decision concerning the assurance provider (accountant vs. non-accountant). Our results indicate that the more active committees tend to prefer a Big-4 firm to non-accounting professionals.
Conclusions
The main purpose of this research is to understand the corporate governance factors influencing the assurance of sustainability reports and the choice of assurance providers in civil law countries, which are more stakeholder oriented. Following this purpose, the paper develops and tests models of how corporate governance aspects in general and the strength of the board in particular influence firms’ adoption of assurance statements and the choice of assurance provider in stakeholder-oriented countries. In sum, it investigates how board size, independence and activity of sustainability committees and assurance aspects are related.
Using an international sample of 610 companies from the period 2007–2014, we provide evidence of the complementary effect between corporate governance strength and assurance issues. Specifically, it appears as predicted that companies registered in stakeholder-oriented countries are more likely to have assured reports if they have a large and independent board as well as an active sustainability committee. Moreover, such board aspects positively influence the choice of the accountancy profession to assure sustainability reports.
In conclusion, we evidence the positive association between voluntary assurance demand and board characteristics, providing that assurance and corporate governance can act as a complementary mechanism to solve agency problems and to satisfy the demands of a broader set of stakeholders. In addition, country-level and firm-level factors interact in the decision on sustainability assurance and, even further, in the choice of the accountancy profession to provide this statement. Such complementary association between the effectiveness of the board and the assurance demand is particularly important for companies belonging to stakeholder-oriented countries.
Our study makes a number of important contributions to the existing literature. First of all, it contributes to the literature by extending and developing the research on the growing topic of assurance services. Assurance is a relatively new research topic, and it is an increasingly common practice to ensure the credibility of sustainability reports (KPMG, 2013). Furthermore, this research is extended by examining the type of assurance provider because this paper provides an empirical examination of the sustainability assurance market at the international level. Thereby, it contributes to the understanding of the corporate demand for assurance and the literature’s focus on its determinants and consequences, as well as the choice of assurance providers (Simnett, Vanstraelen, & Chua, Reference Simnett, Vanstraelen and Chua2009; Kolk & Perego, Reference Kolk and Perego2010).
Additionally, this paper contributes to the growing scholarship by extending and developing the prior research on the topic of assurance services for sustainability reports and its institutional aspects (Simnett, Vanstraelen, & Chua, Reference Simnett, Vanstraelen and Chua2009; Kolk & Perego, Reference Kolk and Perego2010; Perego & Kolk, Reference Perego and Kolk2012; Weber, 2014; Peters & Romi, Reference Peters and Romi2015). Our findings contribute to the neo-institutional theory by identifying external pressures – such as stakeholder orientation – and explaining how they affect organizations in their decision to adopt an assurance system for sustainability reports. In this regard, while several papers analyze country-level factors for the assurance demand and the choice of assurance provider (Simnett, Vanstraelen, & Chua, Reference Simnett, Vanstraelen and Chua2009; Kolk & Perego, Reference Kolk and Perego2010; Zhou, Simnett, & Green, Reference Zhou, Simnett and Green2013) we complement this previous literature by examining corporate governance factors, which are identified by Cohen and Simnett (Reference Cohen and Simnett2015) as a necessary research line. Similar to the complementary role that Doidge, Karolyi, and Stulz (Reference Doidge, Karolyi and Stulz2007) find for country-level investor protection and firm-level governance, we evidence that the strength of corporate governance aspects related to board size, independence and the activity of the sustainability committee is positively associated with the assurance demand. This expands the previous complementary effect between corporate governance and sustainability disclosure (Michelon & Parbonetti, Reference Michelon and Parbonetti2012; Allegrini & Greco, Reference Allegrini and Greco2013) to the assurance market, for which the evidence is null.
Furthermore, this paper offers new insights because it expands: (i) the widely analyzed evidence of the role of corporate governance factors in the area of sustainability reporting (e.g., Barako & Brown, Reference Barako and Brown2008; Allegrini & Greco, Reference Allegrini and Greco2013; Liao, Luo, & Tang, Reference Liao, Luo and Tang2015); (ii) the growing research on the determinants of sustainability assurance (Cheng et al., 2014); and (iii) the literature about CSR, the assurance demand and assurance provider market which, further, is biased towards the context of US or UK firms (Clarkson et al., Reference Clarkson, Li, Richardson and Vasvari2008; Fifka, Reference Fifka2013; Liao, Luo, & Tang, Reference Liao, Luo and Tang2015; Kend, Reference Kend2015). In this respect, we adopt an international approach rather than a single-country or region approach (e.g., Tagesson, Blank, Broberg, & Collin, Reference Tagesson, Blank, Broberg and Collin2009 for a sample of Swiss firms; Da Silva Montero & Aibar-Guzman, Reference da Silva Monteiro and Aibar‐Guzmán2010 for a sample of Portuguese firms). While previous studies of sustainability assurance conduct a cross-section analysis, our study adopts a panel data approach that allows comparison among countries and years. Thus, our international sample solves the limitation that was suggested by Fifka (Reference Fifka2013) who pointed out that the largest body of literature has been produced in the UK and USA, in industrialized, emerging and developing countries.
As far as we know, the theoretical or practical references that exist related to sustainability assurance, assurance providers and corporate governance are basically limited to the studies by Kend (Reference Kend2015) and Peters and Romi (Reference Peters and Romi2015). However, we complement them in a number of respects. First, while Peters and Romi (Reference Peters and Romi2015) only assess the influence of the environmental committee on the assurance, we focus on several corporate governance aspects. Second, we expand their sample of US, UK and Australian firms to an international level with a study of 12 countries. We also increase the period of analysis until 2014, which allows us to consider the years of the greatest increase in assurance demand.
Our evidence contributes from the theoretical standpoint on different approaches. It contributes to the agency theory, because assurance and corporate governance mitigate the agency conflict between principal and agent. Results are consistent with the complementary effect between the strength of the board and the adoption of an assurance statement provided by the accountancy profession, that is, by Big-4 audit firms. Legitimacy theory is also adopted in this paper. Following this theory, assurance and good corporate governance practices are considered as the necessary tools to satisfy the social demands that ensure the survival of the firm in coalition with the objectives of the community in which it is located. Finally, and based on our stakeholder-oriented countries, we adopt the neo-institutional approach, whereby the previous legitimacy varies according to the institutional environment in which companies operate. This leads to homogeneous patterns of behaviour for companies that operate in countries with similar institutional structures (DiMaggio & Powell, Reference DiMaggio and Powell1983).
The results of this study contribute to managerial practices and to policy making in several ways. On the one hand, our results suggest that directors can use external assurance as a legitimation tool that ensures firm survival in the long term, as well as a mechanism of effective communication between the firm and its stakeholders. Moreover, our findings allow the identification of the board size as effectively focused on the assurance process. From the practical point of view, it is necessary to know the proportion of external versus internal directors to satisfy the different stakeholder demands for more credible information, as well as the benefits from the creation of a sustainability committee. Moreover, for stakeholders and shareholders, assurance increases the credibility, transparency and reliability of voluntary information issued by companies. In addition, since a broader set of stakeholders is demanding more effective, credible and transparent sustainability information, our empirical evidence can help regulators and policy makers to adopt an appropriate balance of laws, legislative reforms and enforcement not only for governance aspects but also for the assurance system.
Nonetheless, this research is subject to some limitations related to the following aspects, and therefore, the results presented and their implications should be considered only preliminary. First, although it is one of the remarkable contributions of the study, the use of an international database generates divergence of information. Due to the limited information available in the different databases used, the sample is restricted to specific countries, following limitations reported by Fifka (Reference Fifka2013). The higher presence of firms with a specific civil country law, such as Italy (around 23%), could reflect the country bias within the sample. In addition, the main objective of this paper is to determine the effect of several board aspects of the demand of assurance and the type of assurance provider in stakeholder-oriented countries. But other institutional factors have been omitted, such as corporate governance systems, legal aspects, level of investor protection or cultural systems, and so on. Furthermore, regarding the sample procedure, its composition starts from the world’s largest 2,000 listed firms provided by Forbes; that is, the sample is restricted to large listed companies, ignoring the small and medium enterprises. Future studies could replicate the present study and examine the impact of board aspects on assurance by including small and medium enterprises firms, additional countries and increasing the time period (considering 2015), and even more, by determining the possible impact of other institutional aspects.
Second, we cannot forget the self-reporting bias in the sample selection since our sample is restricted to those companies that choose to report their sustainability practices via a voluntary report. Despite only a few major companies have begun to integrate sustainability issues and all their statements into a separate document (Eccles & Krzus, Reference Eccles and Krzus2010), we have not examined those companies. For this reason, our sample is biased to companies that report sustainability information in a single document, limiting the generalizability of our results by not considering the integrated report and the possibility to audit the social and environmental information contained therein. In view of this limitation, this paper could be affected by biases associated with the omission of variables related to integrated reporting. Future research could make an attempt to offer a quality proxy for integrated reporting.
Third, another limitation is the assurance measure, which is based on a dummy variable (yes/no), although it is the most generalized measurement for it (Simnett, Vanstraelen, & Chua, Reference Simnett, Vanstraelen and Chua2009; Kolk & Perego, Reference Kolk and Perego2010; Peters and Romi, 2014). In this regard, we only examine whether board characteristics can influence the assurance demand and the type of assurance provider, without examining other assurance aspects such as the quality of the assurance or the assurance scope. For example, the mere adoption of an assurance process does not imply a high level of quality, as it is a multidimensional construct that is affected by several dimensions or factors (Francis, Reference Francis, Khurana, Martin and Pereira2011). Future research could make an attempt to offer a quality proxy for sustainability assurance and to expand the findings here reported to the study of the assurance quality; that is, for example by examining the following question: does board size impact on the assurance quality? Moreover, it would be interesting for future studies to not only include other assurance factors that may be affected by board characteristics but also to determine how such assurance engagement could influence user perceptions of corporate reputation or market valuation, among other aspects.
Fourth, we have considered as assurance providers two groups: the Big-4 as large traditional auditing firms and others, where we included small accountancy firms as well as consultancy and engineering firms. Given the absence of information, we cannot examine the difference between the Big-4 and small accountancy firms. To solve this issue and given the market of assurance is not restricted to auditing firms, future studies can replicate this study in order to examine the impact of board aspects on the election of Big-4, small accountancy firms or consultancy/engineering firms.
As our final standpoint and revising other literature about the topic, it would be necessary to take into consideration the role that may be played by media and then, by stakeholder pressures in the assurance of sustainability or integrated reports (similar to Brammer & Pavelin, Reference Brammer and Pavelin2008); companies can demand assurance services to Big-4 or other third parties as a result of the greater media and stakeholders pressure in order to increase the credibility of information. These aspects must be taken into account in future studies.
Acknowledgements
The authors wish to acknowledge the financial support of the Ministry of Science and Innovation for the research project ECO2013-43838P and of the Multidisciplinary Institute of Enterprise (MIE) of the University of Salamanca. Any errors included in this paper are sole responsibility of the authors.