1 Introduction
Over the past 15 years, a substantial body of 401(k) savings research has posited a number of reasons why employees participate (or fail to participate) in voluntary 401(k) arrangements. These include neoclassical explanations, such as employee budget constraints, the incentive effect of employer matching contributions, and the desire by employees for tax-deferred savings, as well as behavioral explanations, including procrastination, peer effects and choice overload. Meanwhile, recent efforts to understand household financial decision-making more broadly have focused on the critical role played by financial knowledge and the awareness of retirement plan features. Finally, in the context of banking and other financial decisions, the role of trust has emerged as an important determinant of financial behavior, particularly among low-income households. Overall, it appears that financial decision-making is influenced by a complex set of factors, yielding to both neoclassical and behavioral explanations. The goal of this paper is to provide a deeper understanding of how important these different factors are to the 401(k) participation decision.
Our current effort uses a very unique dataset that combines both survey and administrative data and is the first attempt to extend issues of both knowledge of plan features and trust to the domain of 401(k) savings behavior. Moreover, our research takes place in the context of a significant change occurring in the nature of 401(k) plan design, motivated by behavioral findings regarding employee inertia and the importance of default and framing effects on employee savings. Increasingly, employers offering 401(k) plans are availing themselves of a plan design strategy known as automatic enrollment, under which eligible workers have 401(k) contributions automatically deducted from their paychecks, with the legal right to opt-out if they choose.Footnote 1 This reframing of the savings decision, from a positive to a negative election, improves plan participation rates dramatically. At the same time, it is still the case that among certain demographic groups within the population of eligible workers, as many as 20% choose to exercise their opt-out rights and quit an automatic enrollment plan (Madrian and Shea, Reference Madrian and Shea2001; Nessmith et al., Reference Nessmith, Utkus and Young2007).
As a result, two types of non-savers have emerged today in the U.S. 401(k) system: ‘non-joiners’, those who fail to join voluntary 401(k) arrangements; and ‘quitters’, those who exercise their opt-out rights under an automatic enrollment regime. This development raises an intriguing set of questions about the dynamics of 401(k) savings behavior. For example, within each type of plan, do the same types of factors influence participation levels? In addition, do neoclassical models help explain the variations between participants and non-participants (either quitters or non-joiners) within both types of plans – or are broader factors such as trust important as well? The goal of this paper is to paint a more complete picture of the 401(k) savings decision in the context of both voluntary and automatic enrollment plans. We rely on administrative and survey data drawn from three large firms sponsoring 401(k) plans, two offering automatic enrollment plans and one offering a voluntary enrollment plan. The survey data permit us to delve into the psychological motivations behind employee savings decisions, which would not be possible with administrative data alone. This unique combination is an important distinguishing feature of this study.
Before summarizing our findings, the reader should be aware of several important assumptions that frame our interpretation of the results. First, we assume that 401(k) participation is desirable. Second, while it is not necessarily irrational to not trust financial institutions, we assume that if a lack of trust leads to 401(k) non-participation and if improving trust levels increases participation then individuals will benefit. That said, we acknowledge that there exist several strong counterarguments to our assumptions.Footnote 2 Therefore, the reader should bear this in mind when considering our conclusions and may choose to interpret the results differently. Moreover, this article does not examine any of the potential negative effects on household well-being of increased trust in financial institutions or investing in an employer's 401(k).
In our results, we find a strong correlation between knowledge of plan features and participation in both types of plans. While the direction of causality between plan knowledge and participation cannot be determined in this study, our findings raise interesting research questions for the future. For example, do individuals participate because they are aware of their plan's features, such as the specifics about their plan match or do they learn about these features through their participation in the plan? It is feasible that people who take time to study the plan features understand their benefits better and become more likely to enroll in their plans. It is also feasible that, over time, exposure to plan statements and other correspondence contributes to learning and awareness. If the former is true, then our results provide motivation for educational programs and communication strategies that emphasize the plan features available and their benefits to participants. If the latter is true and in light of research suggesting the importance of learning in financial decision-making, then our results provide further support for automatic enrollment and even more persistent approaches to automatic enrollment, such as the periodic re-enrollment of quitters.Footnote 3
Our study also finds that trust plays a critical role in shaping employee savings behavior in automatic enrollment plans. Specifically, we find that participants who do not trust financial institutions are more likely to quit automatic enrollment plans. Our findings underscore the fact that even the highly successful reframing strategies, such as automatic enrollment, can have limitations in the face of lack of trust – an aspect of decision-making that has not been included in prior 401(k) research. As a result, our findings highlight the importance of trust-building efforts, principally through communications and education programs, as a potential remedy. Finally, our findings present a promising avenue for future research. Given recent economic events, the number of individuals reporting mistrust in financial institutions may have increased since our survey. Therefore, more research into the influence of recent events on trust and financial decisions could be interesting.
This paper is organized as follows. After a literature review in the next section, the third section of the paper turns to our administrative data, and the fourth to our survey instrument and measures of literacy and trust. The fifth section presents our econometric analysis, and a final section concludes.
2 Literature review
Most prior research on the 401(k) savings decision has been centered on straightforward neoclassical lifecycle models, using either administrative or survey data, and considering employee choices in a voluntary enrollment setting.Footnote 4 Overall, the research using administrative data suggests that three key demographic variables are positively related to 401(k) participation – income, age and job tenure. Several theories have been suggested to explain the positive income and plan participation relationship. For instance, low-income households may participate less than higher income households because they are more likely to be financially constrained (i.e. a simple positive elasticity of saving with respect to income); they face lower (or negative) tax rates and derive little (or no) tax benefit from 401(k) savings; or they need to save less because of the progressive benefits structure of Social Security. In terms of age, a general lifecycle model suggests age-related variation in savings. As employees age, the importance of savings may become more salient, making participation in a retirement plan more likely. Job tenure is also strongly linked to 401(k) plan participation. One reason may be that longer-tenured employees find plan participation more attractive due to the vesting of benefits over time; another may be a growing familiarity, over time, with the employer's retirement plan.
Workplace financial education programs have been linked to improved 401(k) savings outcomes (Bernheim and Garrett, Reference Bernheim and Garrett2003; Nyce, Reference Nyce2005), although financial literacy levels per se have not been incorporated in 401(k) savings models. Outside the domain of 401(k) plans, Moore (Reference Moore2003) finds that less financially literate individuals are less likely to engage in positive financial behaviors (e.g. paying bills on time, budgeting and tracking expenses and saving/investing money out of every paycheck). Moore (Reference Moore2003) also suggests that individuals with low financial literacy are naïve when it comes to evaluating financial options. Using special modules from the Dutch National Bank Household Survey, van Rooij et al. (Reference van Rooij, Lusardi and Alessi2007) find that individuals with low literacy are significantly less likely to invest in stocks. Alternatively, Lusardi and Mitchell (Reference Lusardi and Mitchell2006) demonstrate that those with higher financial literacy are more likely to save and invest in more complex assets, using data from older households in the Health and Retirement Study. In addition, Behrman et al. (Reference Behrman, Mitchell, Soo and Bravo2010) find using an instrumental variable approach and data from the Chilean Social Protection Survey that financial literacy has even stronger effects on wealth outcomes than found in linear regression models. Finally, in the 401(k) domain, using an experimental approach, Agnew and Szykman (Reference Agnew and Szykman2005) suggest that individuals with lower levels of financial literacy are more likely to take a default plan investment option when making asset allocations than individuals with higher levels of financial literacy.
Knowledge of a retirement plan's specific features, as opposed to measures of general financial literacy, may also be related to increased savings behavior. Choi et al. (Reference Choi, Laibson and Madrian2005) found that only 21% of 401(k) participants contributing below their plan's match threshold knew their plan's match rate, compared to 41% of those above the match threshold. Furthermore, Chan and Stevens (Reference Chan and Stevens2008) find that individuals who are better informed about the retirement benefits of their pensions are more responsive to those benefits. Those who are ill informed show no significant response to actual pension incentives. Interestingly, the authors find evidence that the ill-informed group do react to incentives that do not exist. They are responding to their perceived, but incorrect, beliefs about the benefits.
Finally, a well-known stream of research supports the influence of behavioral biases on 401(k) decisions and suggests that employees may not be behaving as standard neoclassical decision agents.Footnote 5 The automatic enrollment findings noted above indicate that a simple reframing of the 401(k) savings decision from a positive to a negative election can elicit substantially higher plan participation rates. Prior researchers have noted other behavioral biases (including procrastination) in a variety of other retirement plan decisions (Choi et al., Reference Choi, Laibson, Madrian, Metrick, McCaffrey and Slemrod2006). For example, ‘choice overload’ (as measured by the number of plan investment options) may discourage plan participation (Sethi-Iyengar et al., Reference Sethi-Iyengar, Huberman, Jiang, Mitchell and Utkus2004) or encourage more conservative investing (Iyengar and Kamenica, Reference Iyengar and Kamenica2010). In addition, an individual's own savings behavior can be influenced by the effects of peer groups (Duflo and Saez, Reference Duflo and Saez2003).
In this paper, we expand our understanding of 401(k) savings behavior by examining the role of trust. While one can argue that trust can be irrational or rational, it has been shown to have an influence on other financial behaviors.Footnote 6 A distrust of financial institutions has been shown to influence general financial behavior, particularly among households in the lower socio-economic strata. Poorer individuals have a culture of distrust of financial institutions and consciously avoid doing business with them (Bertrand et al., Reference Bertrand, Mullainathan and Shafir2006; Szykman et al., Reference Szykman, Rahtz, Plater and Goodwin2005). In a focus group conducted by Szykman et al. (Reference Szykman, Rahtz, Plater and Goodwin2005), respondents expressed feelings of alienation as well as an underlying belief that banks cannot be trusted to do the right thing. The respondents also stated that they avoided doing business with banks because of these perceptions. Finally, Guiso et al. (Reference Guiso, Sapienza and Zingales2008) found that lack of trust can explain why some people do not invest in the stock market.Footnote 7 Additionally, they find that countries with low stock participation rates have low trust levels.
Broadly speaking the prior literature on 401(k) savings behavior advances three distinct models of individual decision-making.
2.1 Model 1: Neoclassical agents
According to this model, non-savers, regardless of the type of retirement plan offered, are viewed as forward-looking, rational agents. Their decision not to save in a 401(k) plan is rationally explained by income-related budget constraints, their own preferences for tax-deferred savings, and by recognition that savings is unnecessary given the presence of Social Security benefits. If this model explains participant behavior, then trust and all plan knowledge variables should be unrelated to plan participation. In addition, automatic enrollment should not influence savings behavior.
2.2 Model 2: Information costs
In this model, non-savers may be impeded by a lack of information on basic financial concepts and plan features, as well as by the transaction costs needed to accumulate that information. They are rational agents hindered by information or financial literacy constraints. If this model explains behavior, then knowledge of plan features should be significantly related to participation. A complete test of this model requires evidence of direct causality from plan knowledge to participation and not vice versa. In this model, trust should not be significant and automatic enrollment may have an influence.
2.3 Model 3: Behavioral biases
Under behavioral theories of 401(k) decision-making, non-savers are impeded by psychological biases (such as procrastination) that may interfere with a purely rational assessment of retirement savings choices. Automatic enrollment would be expected to have an influence. Trust, whether rationally or irrationally based, is another psychological factor that may influence behavior. A significant relationship between trust and participation would support this model. These models are not necessarily mutually exclusive. For example, List (Reference List2004) finds that prospect theory adequately explains the behavior of inexperienced consumers, whereas those with extensive market experience react more in line with neoclassical predictions. It is thus possible that elements of 401(k) savings behavior are explained by all three models. Indeed, both the prior empirical evidence, as well as our new findings, suggest that a complex set of factors – rational, information-constrained and behavioral – are all linked to 401(k) savings.
3 Administrative and survey data
Our current study is based on administrative and survey data from three 401(k) savings plans. Administrative data, including employee demographics and plan behavior, were extracted from Vanguard recordkeeping systems under restricted access conditions in mid-2006.Footnote 8 The three plans were chosen based on similar plan features, including the availability of employer matching contributions and the presence of similar-sized investment menus, in order to minimize the impact of plan-specific design variation.Footnote 9 What distinguishes the plans from one another is their use of automatic versus voluntary enrollment. Plans A and B have an automatic enrollment feature: eligible employees receive communication materials notifying them that they are automatically enrolled after a given period of employment – 90 days in the case of Plan A, 2 months in the case of Plan B. Plan C is a voluntary enrollment plan; eligible employees receive communication materials inviting them to join the plan on employment.
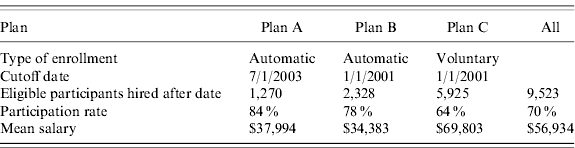
Table 1 summarizes important plan characteristics. Plan A and Plan B instituted automatic enrollment in 2003 and 2001, respectively, for new hires only. As a result, our analysis is restricted to individuals hired after the ‘cut-off date’ when automatic enrollment was introduced in each plan. (For the voluntary plan, we set the cut-off date to equal Plan B.) Our sample size for the administrative data set, from which our survey respondents are drawn, is 9,523.
Plan and employee characteristics
This table reports general statistics for all the plan participants, including survey respondents and non-respondents. In addition, it includes the type of enrollment each plan uses and the cutoff date for the data collection.
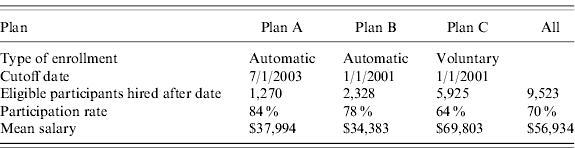
As expected based on prior studies, the automatic enrollment plans have higher participation rates than the voluntary enrollment plan – 84% (Plan A) and 78% (Plan B) versus 64% (Plan C).Footnote 10 This difference is even more striking given the substantially lower incomes of the participants in the automatic enrollment plans (mean salary of $37,994 for Plan A and $34,383 for Plan B versus $69,803 for Plan C). We believe that these descriptive statistics underscore the strong effect of automatic enrollment on savings choices.
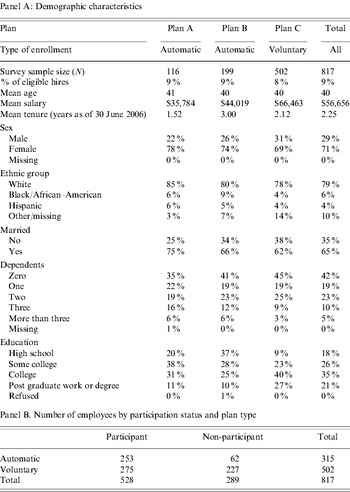
To obtain our literacy and trust measures, we administered a telephone survey during the month of August in 2006 to a random subset of the individuals drawn from the administrative dataset.Footnote 11 Panel A of Table 2 presents summary statistics for the 817 survey respondents. As in the overall administrative dataset, survey respondents from Plans A and B, the automatic enrollment plans, have a lower mean salary than the voluntary enrollment plan, Plan C. Plan C participants, besides having higher wages, also have higher levels of educational attainment: the proportion of post-graduate education is more than double in Plan C than in Plan A and Plan B, and only 9% of Plan C respondents have just completed high school (or less), versus 20% and 37% in the two automatic enrollment plans. Due to the differences in demographic characteristics between the automatically enrolled and voluntary enrollment groups, we will limit our discussions to comparisons within each group.
Survey respondents characteristics
Panel A reports important demographic statistics for each plan and all the plans combined (‘Total’ column on the far right) for respondents only. Panel B breaksdown the number of respondents for each participant status/plan type category.

In implementing the survey, our aim was to reach at least 250 respondents in four categories: in a voluntary or automatic enrollment plan, and participating or not participating. Given the small total number of automatic enrollment non-participants, however, we were able to reach only 62 of such employees. Panel B of Table 2 presents the number of respondents in each category.
4 Plan knowledge and trust measures
To assess individuals’ knowledge of their 401(k) plan features we asked three basic questions regarding the availability of an employer match, the actual value of the match and the presence or absence of a loan feature. All three plans offered a match but each plan offered a different match schedule. Both automatic plans featured more difficult to recall tiered match rates compared to the single-tiered match schedule offered in the voluntary plan.Footnote 12 Given the complexity of some of the match schedules, we constructed two measures of match awareness. The first measure (match correct) equals one if the individual correctly identified each match rate and the associated percent of salary. The second measure (match close) equals one if the individual either mentioned one of the match rates or the percent of salary that is matched. Thus, match close is much easier for an employee to recall. A correct response indicates that a respondent is more familiar with the match policy, but may not remember all the specific details of the policy. Finally, two of the plans offered loans and one did not. We asked each participant whether they were aware if loans were available and coded their responses accordingly.
Our trust measure was based on the extent of respondents’ agreement or disagreement with the following statement: ‘For the most part, financial institutions are trustworthy’. Often trust measures in other studies are based on broad statements, such as whether the respondents are trusting of other people. But, such instruments have been criticized as being too vague and perhaps unrelated to specific behaviors (Glaeser et al., Reference Glaeser, Laibson, Scheinkman and Soutter2000). Our approach (following Alesina and La Ferrara, Reference Alesina and La Ferrara2002) is to focus on trust in financial institutions.Footnote 13 As with our financial literacy indicator, we created a binary measure of trust. ‘Low trust’ respondents are those who disagree or strongly disagree with the idea of trusting financial institutions; ‘high trust’ are all others.Footnote 14
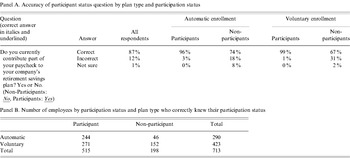
Table 3 presents the responses to a question regarding participation status. Interestingly, several individuals incorrectly report whether they are participating or not. Non-participants appear more likely to misreport their status. For example, 18% of the automatically enrolled non-participants thought they were participating and 8% were not sure. In addition, 31% of the voluntary non-participants thought they were actively enrolled. These individuals could easily skew our results. For example, lack of trust cannot be a contributing factor to non-participation if the individual does not know they are not participating.Footnote 15 Therefore, we have eliminated those who incorrectly reported their participation status from the remainder of the analysis and reduced the sample size from 817 to 713. Table 3, Panel B reports the new sample sizes for each type of plan and participation status.
Accuracy of self-reported participation status
Panel A reports the percentage of employees that accurately report their participation status by plan type and actual participation status. Panel B reports the new sample sizes for the analysis after removing employees that incorrectly report their participation status.

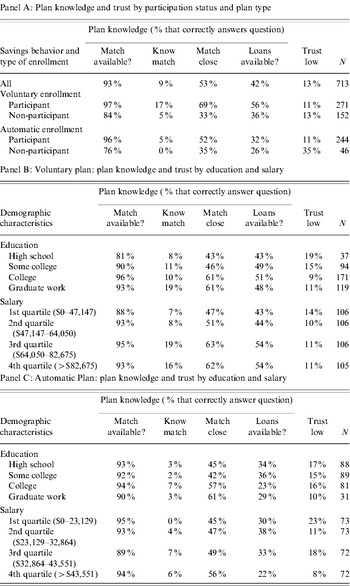
Table 4 provides summary statistics for our plan knowledge and trust measures using the smaller sample. As shown in Panel A, voluntary enrollment participants answer questions related to plan features more accurately than do non-participants (non-joiners) in the same plan. A similar pattern is found between participants and non-participants (quitters) in the automatic enrollment plan group. However, caution is needed when interpreting these figures as the sample size is very small for the quitters in automatic enrollment category. Furthermore, we cannot determine causality between knowledge of specific plan features and participation with our data. Conceivably, individuals who participate may learn about the plan over time resulting in higher number of correct answers, suggesting causality from participation to plan knowledge. Alternatively, individuals could choose to join or not quit the plan because they are aware of the benefits, suggesting causality in the reverse direction.
Plan knowledge and trust measures by participation status, plan type, education and salary
These tables breakdown the percentage of the sample answering plan feature related questions correctly and trust categories by plan type, participation status, education and salary. Individuals with low trust either strongly disagreed or disagreed to the statement ‘For the most part, financial institutions are trustworthy.’ Sample sizes of each category are reported in the far right column.

Percentages may not sum to 100% due to rounding.
Regarding trust, the percentage of individuals in the low-trust category is higher for non-participants in both the voluntary and automatically enrolled participants. However, once again small samples size could be an issue and more advanced techniques are needed to test significance.
Panel B of Table 4 analyzes plan knowledge questions and trust measures by level of educational attainment and salary for the voluntary plan only. As might be expected, a high school education (or less) or a salary in the lower-income quartiles appears generally associated with lower levels of accuracy related to the match-specific questions and trust. On the other hand, those with higher salary or education levels appear more likely to answer the loan question correctly. Despite improvements in accuracy for the match questions and higher levels of trust with education and salary, more than a few individuals in both the high education and top salary quartile exhibit ignorance regarding the features of the plans and express feelings of mistrust. For example, only 19% of individuals with graduate level training knew their match rate exactly and only 61% came close. In addition, less than half knew they had a loan feature or not. Finally, just over 1 in 10 of respondents in the top quartile of salary have low levels of trust in financial institutions.Footnote 16 Thus, education and salary are not perfectly related to trust.
Panel C of Table 4 reports the same statistics for automatically enrolled plans. For the most part, the same type of relative patterns emerges as in the voluntary plan except for awareness of the loan feature. The percentage aware of the loan feature generally decreases with education and salary for the automatically enrolled plan in contrast to the voluntary plan.
5 Econometric analysis
The descriptive statistics in the previous section suggests that both plan literacy and trust may play a role in 401(k) savings decisions. In this section, we assess the relationship between the employee plan participation decision using several probit regressions relating an employee's plan participation decision to a variety of demographic measures and our trust and plan knowledge indicators. Specifically our models are of the following form:
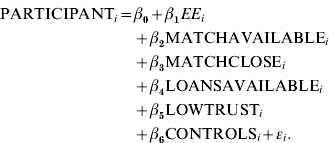
In equation (1), the dependent variable PARTICIPANT equals 1 if the ith eligible employee is participating in the plan, otherwise 0; EEi is a vector of demographic variables for the ith eligible employee in our survey, which includes age, salary, marital status, number of dependents, job tenure, education and race/ethnicity. Our education variables do not include information regarding past economics classes. Future research could benefit from more details related to past courses taken by individuals that specifically address financial literacy topics. MATCHAVAILABLEi, MATCHCLOSEi and LOANSAVAILABLEi are dummy variables that equal one if individual i correctly answered the associated plan feature question and zero if not. LOWTRUSTi is a dummy variable indicating whether participant i fell into the low-trust category or not. CONTROLSi is a vector of controls that include dummy variables related to the accuracy of the participant i's response to two general literacy questions and a stock market belief question.Footnote 17 A plan dummy is also included in the automatically enrolled group regressions to control for possible plan-specific effects. We pool respondents from Plans A and B into a single regression for automatic enrollment; the respondents from Plan C are in a separate regression for voluntary enrollment. We do not pool all the plans together because the binary choice to participate is fundamentally different (either opt in or opt out) depending on the enrollment method and the samples are different in terms of education and salary.
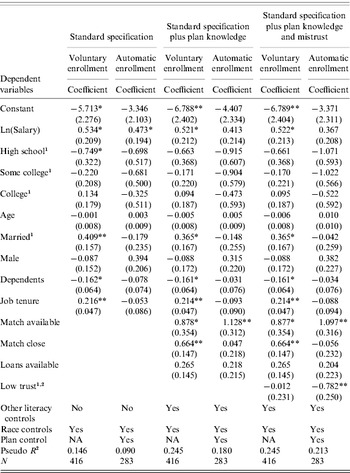
In Table 5, the first set of results is for a standard specification of 401(k) plan participation based on prior studies. The coefficients and their standard errors are shown. Not surprisingly, in the standard specification for voluntary enrollment, we find that the probability of participation increases when salary increases, job tenure increases or the participant is married versus not married. On the other hand, lower levels of education and additional dependent children reduce the probability of participation. Meanwhile, in the standard specification model under automatic enrollment, none of these demographic variables has a positive relationship to plan participation except for salary. This result is consistent with the finding from prior research that automatic enrollment tends to equalize savings behavior across various demographic groups.
Probit regressions for survey sample
This table reports the coefficients from a probit regression. The dependent variable is a binary variable that equals one if the employee participated in his 401(k) plan or equals zero if he did not. Ln(Salary) is the natural log of salary measured in dollars. High school, some college, college are dummy variables for education (omitted category is graduate work). Age is measured in years. Male is a dummy variable that equals one if the employee is male. Married is a dummy variable that equals one if the respondent is married. Dependents is equal to the number of children or elderly living in the household not including the spouse and Job tenure is the years employed. Match available, Match close and Loans available are dummy variables that equal one if the employee correctly answers these questions about plan features. Low trust is equal to 1 if the employee strongly disagrees or disagrees to the statement ‘For the most part, financial institutions are trustworthy’. Race is controlled for with dummy variables. The results are not significant and not reported for space reasons. Robust standard errors are reported in parentheses. **, * indicate a significance of 1% and 5%, respectively.

1 These variables are dummy variables.
2 Eighteen individuals who did not answer the trust question were coded as low trust equals zero. Excluding these 18 from the analysis did not qualitatively change the results.
The second specification adds plan knowledge dummies as separate explanatory variables. In the standard specification with our plan knowledge measures under voluntary enrollment, several demographic variables – salary, job tenure, marriage and number of dependents – remain significant. Two of the plan knowledge variables, match available and match close, are significant demonstrating a relationship between participation and knowledge of these features. Meanwhile, under the same specification with automatic enrollment, the demographic effects remain insignificant and only the match available variable is significant. Under both voluntary and automatic enrollment models, the addition of the new plan knowledge and control variables improves the regressions pseudo-R 2s over the standard specification without those variables.
The final specification adds the trust variable to the specification. In both the voluntary enrollment and automatic enrollment specifications, the same variables included in the second specification remain significant. However, in the new regressions, low trust is only significant in the regression associated with the automatically enrolled plans. It is not clear as to why trust is not a factor in the voluntary plan. One explanation is that the samples are fundamentally different. From the summary statistics, the voluntary sample includes higher-educated and higher-salaried employees. In fact, the first three salary quartiles of the automatically enrolled group (those earning less than $43,551) would fall into the first quartile of the voluntary plan (under $47,147). In addition, the voluntary group has only 37 participants with a high school or less education and 119 with graduate-level experience. This contrasts with 88 and 31 participants for the automatically enrolled group, respectively. Perhaps trust is a larger issue in lower-educated, lower-salaried employees, and so its effects are not evident in the voluntary plan where there is less representation of this population. It is also possible that the voluntary employees are in an industry that tends to attract employees that hold more favorable outlooks on financial institutions than the industries associated with the automatically enrolled employees. These explanations need to be tested with more data from additional plans. However, the significance of trust in the automatic enrollment regressions is a noteworthy result because it does show that trust can be an important factor in savings and investment decisions related to retirement.
Taken together, our findings suggest a multi-faceted model of employee savings in 401(k) plans, consistent with models of neo-classical decision agents, information costs and behavioral biases. Our final specification confirms both a neoclassical model for voluntary enrollment, linking savings behavior to various demographic variables such as salary, as well as a behavioral model, in which automatic enrollment eliminates much of these demographic variations. Beyond these explanations, however, our results underscore the importance of behavioral measures such as trust in explaining retirement savings behavior. Furthermore, the results reveal a relationship between plan knowledge and participation that should be explored more to determine causality. If later research demonstrates that plan knowledge leads to participation, then our results are consistent with a model of decision agents constrained by access to appropriate financial information. If causality runs in the other direction, then our results support research suggesting learning through experience. Both have important policy implications. Finally, the significance of trust confirms a new dimension of decision-making in 401(k) savings choices that may or may not be rational, namely, a lack of trust in financial institutions, particularly, but not exclusively, among employees with lower wages and lower levels of educational attainment.
6 Conclusions
Prior research on 401(k) savings behavior has focused on the importance of neoclassical models in explaining variation in savings behavior, or on behavioral biases such as procrastination as impediments to rational decision-making. Automatic enrollment, in particular, has emerged as a response by employers and policymakers to findings of employee procrastination in retirement savings. The strategy is being adopted by employers in the U.S., with active encouragement in the Pension Protection Act of 2006, in an effort to improve savings behavior through default or reframing effects. This paper highlights the importance of two other factors – plan knowledge and trust – in 401(k) savings decisions, and assesses their impact depending on whether the decision is framed as a positive (voluntary) or negative (automatic enrollment) one.
In particular, in voluntary savings arrangements, both demographic characteristics and plan knowledge relate to participation in a 401(k) plan. Specifically, awareness of a 401(k) match and some idea of the specifics of the match correlate with participation. Whether this is because individuals have learned about their plan features through experience or this knowledge drove their participation is not known and should be evaluated in future research. In automatic enrollment arrangements, which tend to minimize demographic variations in savings behavior, what stands out is the role of trust in financial institutions, along with knowledge of an available plan match. As in the voluntary plan, the causality between plan knowledge and participation is unknown. Therefore, taken together, our results cannot reject either a rational information costs model of decision-making (some employees are impeded in their decision-making simply by a lack of adequate financial information) or a behavioral bias theory (some employees are influenced substantially by trust and the framing of the enrollment decision). Furthermore, our trust finding demonstrates that some employees may be influenced by the psychological level of trust they have in financial institutions. This finding is new to 401(k) research, and may also more broadly influence retirement and other savings behavior.
Overall, our findings extend the richness of our understanding of the complex factors underlying savings choices and present further avenues for research. The earliest empirical models of 401(k) savings focused exclusively on voluntary savings choices. Furthermore, they relied on a neoclassical lifecycle framework and incorporated demographic factors, such as age and income, as important related variables. In subsequent studies of automatic enrollment, this approach was extended to include behavioral biases such as procrastination. Our findings contribute to the literature by suggesting an even more nuanced model. First, models of voluntary savings choice ought to incorporate plan knowledge variables as separate, and powerful, explanatory variables. They must also investigate the direction of causality of these variables. Second, even with the introduction of automatic enrollment, which eliminates most of the demographic variation in savings choices, low trust in financial institutions stands out as critical explanation of non-saving behavior. In addition, the significance of the match available variable suggests that once again there may be a link between participation and awareness of plan details that should be explored.
On a practical and policy level, the significance of plan knowledge variables raises important implications that hinge on causality. If plan knowledge leads to participation, then our findings underscore the importance of plan education programs and plan design strategies that focus on raising plan awareness among targeted groups of employees. If causality runs in the opposite direction, then our findings support remedial strategies such as considering changing plan design. In particular, periodically re-enrolling those who quit automatic enrollment arrangements – under the assumptions that plan knowledge and understanding savings and investing may change over time with learning, and that such employees, if re-enrolled, may choose not to quit the second or third time around.
Furthermore, as automatic enrollment becomes more widespread, plan sponsors and policymakers may come to view enrollment communications and 401(k) plan literacy programs generally as superfluous, and quitters as purely rational agents making calculated choices about their future. An alternative view arising from our study is that plan enrollment communications by employers – and retirement education generally by community groups and the government – becomes even more essential in raising plan awareness, and reducing quit rates under automatic enrollment.
Our findings also highlight the need for strategies to bolster trust in financial institutions. These include employers and community groups adopting social marketing approaches, such as electing a plan or retirement savings advocate, introducing a trusted peer program or offering seminars designed to increase understanding and trust of financial institutions.
In summary, what emerges from our findings, and the now extensive body of prior research, is a complex and nuanced model of 401(k) retirement savings. It is no longer sufficient to explain savings behavior in terms of purely neoclassical lifecycle models. Literacy effects appear to be pervasive. Even a behaviorally motivated reframing of savings choices under automatic enrollment, while extremely effective, still leaves some room for improvement among a vulnerable subset of employees, those exhibiting mistrust of financial institutions. Our findings suggest several possible avenues for future research, including the ways in which employers, community groups and governments can effectively improve understanding of basic retirement savings concepts and determining the causality between plan knowledge and participation. Furthermore, our sample size of non-participants in automatic enrollment plans was limited in this analysis. While our econometric results were significant, more research on larger samples would be useful to confirm our findings. Additionally, if trust levels in financial institutions drop due to the recent economic events, the long-term repercussions may be far-reaching and long lasting. Therefore, research focusing on how overall trust affects all financial decisions, including retirement decision-making, is now even more important and necessary.