



1 Introduction
Managing financial risk attracts much attention from researchers and market practitioners, which contributes to the high volume of trading volatility derivatives in real markets, since it is an easy way to trade volatility and hedge risk. Volatility swaps, as one important volatility derivative, have received considerable attention. A number of authors have worked on the pricing of a volatility swap.
Volatility swaps can be mainly classified into two categories according to the sampling method, that is, continuously sampled and discretely sampled ones. In the first category, general model independent results are presented by Carr and Lee [Reference Carr and Lee7, Reference Carr and Lee8], while other authors focus on pricing volatility swaps under different stochastic volatility models [Reference Elliott, Siu and Chan12, Reference Grünbichler and Longstaff14, Reference Heston and Nandi18, Reference Howison, Rafailidis and Rasmussen20]. Despite their appealing results, the underlying assumption is not consistent with practice, as volatility swaps traded in real markets are usually discretely sampled. This can cause mis-valuation problems if one makes use of these results, as suggested by a number of authors [Reference Elliott and Lian11, Reference Little and Pant24].
To properly reflect the discrete sampling effect and be closer to financial reality, it is very popular to consider the valuation of discretely sampled volatility swaps. In particular, Zhu and Lian [Reference Zhu and Lian29] presented an analytical pricing formula for volatility swaps under the well-known Heston model [Reference Heston19]. Despite their appealing results, the study of pricing volatility swaps should not be stopped, since the Heston model is not perfect for modelling the underlying dynamics. For example, the square root specification for the so-called volatility of volatility is generally rejected as a model of stock index returns [Reference Andersen, Benzoni and Lund1, Reference Pan26], while evidence of the substantial nonlinear mean-reverting property for a volatility process has been provided by a number of authors (for example, Bakshi et al. [Reference Bakshi, Ju and Ou-Yang2]). All of these drawbacks have led to the development of different modifications to the Heston model, trying to incorporate more stochastic factors. These variations have also been applied in volatility derivative pricing, including a regime switching Heston model [Reference Elliott and Lian11], Heston model with stochastic interest rate [Reference Cao, Lian and Roslan4, Reference Cao, Roslan and Zhang6, Reference He and Zhu16] and Heston model with stochastic interest rate as well as regime switching [Reference Cao, Roslan and Zhang5]. A hybrid constant elasticity of variance (CEV) and stochastic volatility model were adopted by Cao et al. [Reference Cao, Kim and Zhang3], while stochastic volatility was combined with the Hawkes jump-diffusion process by Liu and Zhu [Reference Liu and Zhu25]. A general framework for variance swap pricing under stochastic volatility models with jumps was established by Cui et al. [Reference Cui, Kirkby and Nguyen10].
Recently, multi-factor stochastic volatility models have started to gain attention, because they have been shown to provide a better fit to market data [Reference Christoffersen, Heston and Jacobs9]. In fact, there have already been various results on the pricing of volatility derivatives under multi-factor stochastic volatility models. For example, for variance swap pricing, Pun et al. [Reference Pun, Chung and Wong27] considered a combination of multi-factor stochastic volatility and jumps, while Wu et al. [Reference Wu, Jia, Yang and Liu28] introduced the stochastic interest rate into a double Heston stochastic volatility model. A double exponential Ornstein–Uhlenbeck stochastic volatility was adopted by Kim and Kim [Reference Kim and Kim22]. Both variance and volatility swaps were valued under a two-factor Heston model with an additional regime switching factor [Reference He and Zhu17] and a multi- factor Heston stochastic volatility model [Reference Issaka21]. Being quite similar to these multi-factor stochastic volatility models, another trend for introducing additional stochastic factors is to make the parameters of stochastic volatility models as random variables to increase the flexibility of the model. Belonging to this category, Lee et al. [Reference Lee, Kim and Kim23] considered multiscale stochastic volatility of volatility, while He and Chen [Reference He and Chen15] introduced a stochastic long-run variance level into the risk-neutralized Heston model and obtained a closed-form solution for European option prices.
In this paper, we focus on pricing volatility swaps under the model proposed by He and Chen [Reference He and Chen15], which assumes a stochastic long-run variance level under the risk-neutralized Heston model. Although the considered model is much more complicated than the original Heston model due to the involvement of an additional stochastic source, we have still successfully obtained an analytical pricing formula for volatility swaps, based on the forward characteristic function of the underlying price derived in closed form. The contribution of this paper can be summarized from two aspects. On the one hand, we present an analytical formulation of the forward characteristic function under the considered model, which has not been presented before. This leads to an analytical solution being available for volatility swap prices. In this case, computational time can be significantly reduced and computational accuracy can be greatly improved, compared with the case to which numerical methods have to be resorted. On the other hand, we demonstrate the significant impact of the introduced stochastic long-run variance level under the risk-neutralized Heston model with synthetic and calibrated model parameters.
The rest of the paper is organized as follows. In Section 2, the adopted model is briefly introduced, and the forward characteristic function of the underlying price is derived, followed by the closed-form pricing formula for volatility swaps. In Section 3, numerical experiments are conducted to show various properties of the newly derived formula. Concluding remarks are given in Section 4.
2 Closed form solution
In this section, the modified Heston model proposed by He and Chen [Reference He and Chen15] will be briefly introduced, after which the price of discretely sampled volatility swaps will be worked out based on the derived forward characteristic function of the underlying price.
2.1 The modified Heston model
We start with a filtered probability space
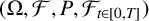 $(\Omega ,\mathcal {F},P,\mathcal {F}_{t\in [0,T]})$
, which describes the uncertainty of the economy, with P representing a probability measure (typically a risk-neutral measure considered in this paper) and T denoting a finite time horizon. All stochastic processes involved are assumed to be
 $\mathcal {F}_{t\in [0,T]}$
adapted. Let
 $\{S_t, t\geq 0\}$
and
 $ \{v_t, t\geq 0\}$
denote the underlying price and the volatility process, respectively. The modified Heston model under the risk-neutral measure is characterized as
 $$ \begin{align} \begin{aligned} \frac{dS_t}{S_t}&=r\,dt+\sqrt{v_t}\,dW_{t}^{1}, \\ dv_t&=k(\bar{v}+\theta_t-v_t)dt+\sigma_1\sqrt{v_t}\,dW_{t}^{2}, \\ d\theta_t&=\lambda \,dt+\sigma_2\,dW_{t}^{3}, \end{aligned} \end{align} $$
where
 $W_{t}^{1}$
,
 $W_{t}^{2}$
and
 $W_{t}^{3}$
are standard Brownian motions [Reference He and Chen15]. We further assume that
 $W_{t}^{3}$
is independent of
 $W_{t}^{1}$
and
 $W_{t}^{2}$
, with
 $dW_{t}^{1}dW_{t}^{2}=\rho \, dt$
. We remark that following a number of different authors including Heston [Reference Heston19], we analyse the model in terms of the risk-neutralized volatility process instead of the “true” process under the physical measure throughout the paper, since the risk-neutralized process exclusively determines prices. Therefore, we know that k,
 $\bar {v}$
,
 $\theta _t$
and
 $\sigma $
respectively represent the mean reversion speed, constant part of the long-run variance level, stochastic part of the long-run variance level at time t (stochastic long-run variance level for short hereafter) and volatility of volatility, associated with the risk-neutralized volatility process. The stochastic part
 $\theta _t$
can actually be viewed as corrections to the constant part due to outside information, which can explain the independence between
 $W_{t}^{3}$
and the other two Brownian motions. We also note that this model will degenerate to the Heston model if both
 $\lambda $
and
 $\sigma _2$
take the value of zero, in which case
 $\theta _t$
becomes a constant.
2.2 Volatility swaps
For the completeness of this paper, we first sketch the derivation of a general formula for the delivery price in a volatility swap contract, while the full details can be found in the existing literature [Reference He and Zhu17].
One of the most popular measures of the realized volatility
 $\sigma _R$
can be specified as
 $$ \begin{align*} \sigma_R=100\sqrt{\frac{\pi}{2NT}}\sum_{i=1}^{N}\bigg|\frac{S_{t_i}-S_{t_{i-1}}}{S_{t_{i-1}}}\bigg|, \end{align*} $$
where
 $t_i,\, i=0,\ldots ,N$
, represents the ith observation time of the realized volatility with
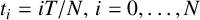 $t_i=iT/N,\, i=0,\ldots ,N$
. According to the risk-neutral pricing rule, as well as the fact that the value of volatility swaps should equal to zero when it is entered, we obtain
 $$ \begin{align*} K=E(\sigma_R)=\sqrt{\frac{\pi}{2NT}}\sum_{i=1}^{N}E\bigg(\bigg|\frac{S_{t_i}-S_{t_{i-1}}}{S_{t_{i-1}}}\bigg||S_0,v_0,\theta_0\bigg). \end{align*} $$
If we assume that
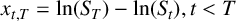 $x_{t,T}=\ln (S_T)-\ln (S_t), t<T$
with the current time being 0, and let
 $p(x_{t_{i-1},t_i})$
be the probability density function of the stochastic variable
 $x_{t_{i-1},t_i}$
, the target expectation can be calculated as
 $$ \begin{align} E\bigg(\bigg|\frac{S_{t_i}-S_{t_{i-1}}}{S_{t_{i-1}}}\bigg||S_0,v_0,\theta_0\bigg)&=\int_{0}^{\infty}(e^{x_{t_{i-1},t_i}}-1)p(x_{t_{i-1},t_i})\,dx_{t_{i-1},t_i} \nonumber \\ &\quad +\int_{-\infty}^{0}(-e^{x_{t_{i-1},t_i}}+1)p(x_{t_{i-1},t_i})\,dx_{t_{i-1},t_i}. \end{align} $$
We further define
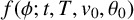 $f(\phi ;t,T,v_0,\theta _0)$
as the conditional forward characteristic function of
 $x_{t,T}$
. By making use of the Gil–Pelaez theorem [Reference Gil-Pelaez13] that relates the characteristic function and the cumulative function of a random variable, we obtain
 $$ \begin{align*} P_{1,i}\triangleq\int_{0}^{\infty}p(x_{t_{i-1},t_i})\,dx_{t_{i-1},t_i}=\frac{1}{2}+\frac{1}{\pi}\int_{0}^{\infty}\operatorname{Re}\bigg[\frac{f(\phi;t_{i-1},t_i,v_0,\theta_0)}{j\phi}\bigg]\,d\phi \end{align*} $$
and
 $$ \begin{align*} P_{2,i}&\triangleq \int_{0}^{\infty}e^{x_{t_{i-1},t_i}}p(x_{t_{i-1},t_i})\,dx_{t_{i-1},t_i}\nonumber\\ &=f(-j;t_{i-1},t_i,v_0,\theta_0)\bigg\{\frac{1}{2}+\frac{1}{\pi}\int_{0}^{\infty}\operatorname{Re}\bigg[\frac{f(\phi-j;t_{i-1},t_i,v_0,\theta_0)}{j\phi f(-j;t_{i-1},t_i,v_0,\theta_0)}\bigg]\,d\phi\bigg\}, \end{align*} $$
where
 $\operatorname {Re}(\cdot )$
denotes the real part of the argument. In this case, equation (2.2) can be further simplified as
 $$ \begin{align*} E\bigg(\bigg|\frac{S_{t_i}-S_{t_{i-1}}}{S_{t_{i-1}}}\bigg||S_0,v_0,\theta_0\bigg)&=(1-2P_{1,i})-f(-j;t_{i-1},t_i,v_0,\theta_0)(2P_{2,i}-1)\nonumber\\ &=\frac{2}{\pi}\int_{0}^{\infty}\operatorname{Re}\bigg[\frac{f(\phi-j;t_{i-1},t_i,v_0,\theta_0)-f(\phi;t_{i-1},t_i,v_0,\theta_0)}{j\phi}\bigg]\,d\phi. \end{align*} $$
Therefore, it is clear that our task is converted into finding the conditional forward characteristic function
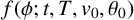 $f(\phi ;t,T,v_0,\theta _0)$
, the solution to which is presented in the following proposition.
Proposition 2.1. If the underlying asset price
 $S_t$
follows the dynamics (2.1), then the conditional forward characteristic function can be derived as
 $$ \begin{align*} f(\phi;t,T,v_0,\theta_0)=e^{C(\phi;\tau)+\bar{C}(\phi;t)+\bar{D}(\phi;t)v_0+\bar{E}(\phi;t)\theta_0} \end{align*} $$
with
 $\tau =T-t$
, and
 $$ \begin{align*} &\bar{D}(\phi;t)=\frac{2k}{\sigma_1^2}\frac{1}{1-(1-2k/\sigma_1^2D(\phi;\tau))e^{kt}},\\[2pt]&\bar{E}(\phi;t)=E(\phi;\tau)+\frac{2k}{\sigma_1^2}\bigg\{kt-\ln\bigg(1-\bigg(1-\frac{2k}{\sigma_1^2D(\phi;\tau)}\bigg)e^{kt}\bigg)+\ln\bigg(\frac{2k}{\sigma_1^2D(\phi;\tau)}\bigg)\bigg\},\\[2pt]&\bar{C}(\phi;t)=\frac{1}{2}\sigma_2^2\int_{0}^{t}\bar{E}^2(\phi;s)\,ds+\lambda\int_{0}^{t}\bar{E}(\phi;s)\,ds+\bar{v}[\bar{E}(\phi;t)-E(\phi;\tau)],\\[2pt]&C(\phi;\tau)=\bar{v}E+jr\phi\tau+\frac{1}{2}\sigma_2^2\int_{0}^{\tau}E^2(\phi;s)\,ds+\lambda\int_{0}^{\tau}E(\phi;s)\,ds,\\[2pt]&D(\phi;\tau)=\frac{d-(\,\rho\sigma_1j\phi-k)}{\sigma_1^2}\frac{1-e^{d\tau}}{1-ge^{d\tau}},\\[2pt]&E(\phi;\tau)=\frac{k}{\sigma_1^2}\bigg\{[d-(\,\rho\sigma_1j\phi-k)]\tau-2\ln\bigg(\frac{1-ge^{d\tau}}{1-g}\bigg)\bigg\},\\[2pt]&d=\sqrt{(\,\rho\sigma_1j\phi-k)^2+\sigma_1^2(j\phi+\phi^2)}, \\[2pt]&g=\frac{(\,\rho\sigma_1j\phi-k)-d}{(\,\rho\sigma_1j\phi-k)+d}. \end{align*} $$
The proof of this proposition is left in the Appendix.
Having worked out the conditional forward characteristic function, the final solution of the delivery price K can be expressed as
 $$ \begin{align*} K=100\sqrt{\frac{\pi}{2NT}}\int_{0}^{\infty}\sum_{i=1}^{N}\operatorname{Re} \bigg[\frac{f(\phi-j;t_{i-1},t_{i},v_0,\theta_0)-f(\phi;t_{i-1},t_i,v_0,\theta_0)}{j\phi}\bigg]\,d\phi. \end{align*} $$
By now, we have derived the closed-form pricing formula for volatility swaps under the modified Heston model. In the next section, the accuracy of our newly derived formula will be verified by comparing numerical results obtained from our formula and those through Monte Carlo simulation [Reference He and Zhu17]. Also, we will show the difference caused by the introduction of the stochastic long-run variance level through the comparison of our results and those under the Heston model [Reference Zhu and Lian29].
3 Numerical experiments and examples
In this section, numerical experiments are carried out to study the properties of volatility swap prices under the modified Heston model. In particular, we first show the accuracy of our formula by comparing numerical results obtained with our formula and those from Monte Carlo simulation. With confidence in our formula, we further show the influence of introducing the stochastic long-run variance level into the volatility process by comparing volatility swap prices under our adopted model and the original Heston model. As mentioned earlier, we focus on analysing the model with risk-neutralized parameters instead of the “true” ones, since the risk-neutralized process actually determines prices, as pointed out by Heston [Reference Heston19]. In addition, all of our calculations in this paper are done on a laptop with the following specifications: Intel(R) Core(TM), i5-1135G7 CPU@2.40 GHz and 16.0 GB of RAM.
What is presented in Table 1 is the comparison of volatility swap prices obtained through our formula (Ours) with those from Monte Carlo (MC) simulation. The MC simulation is implemented with 500 000 sample paths, and it is accompanied by a 98% confidence interval provided in the parentheses. One can clearly observe from this table that our results are quite close to those obtained through MC simulation. We also provide the absolute relative error (RE) between the two prices to demonstrate the accuracy of our formula. It is not difficult to find that the maximum absolute relative error in this test case is only 0.06%, which implies that our formula is accurate. However, the CPU time cost by our formula (
 $t_1$
) is far less than that consumed by MC simulation (
 $t_2$
). It should be remarked that the CUP time cost by our formula reported here measures the computational time when the involved integrals are computed using the trapezoidal rule. It can be highly reduced if one uses some software built-in functions, such as
 $integral$
in MATLAB.
Our prices versus Monte Carlo prices.

Once we are confident of our formula, the pricing performance of our model is compared with that of the Heston model, the dynamics of which are specified as
 $$ \begin{align*} \frac{dS}{S}&=r\;dt+\sqrt{v}\;dW_{t}^{1}, \\ dv&=k(\,\widetilde{v}-v)\,dt+\sigma\sqrt{v}\;dW_{t}^{2}. \end{align*} $$
Note that if we make
 $\widetilde {v}=\bar {v}+\theta _0$
, and let
 $\lambda $
and
 $\sigma _2$
be equal to zero, our model would become exactly the same as the Heston model. Thus, it is not difficult to deduce that with all the other corresponding parameters being the same, our results will approach the results under the Heston model when the values of
 $\lambda $
and
 $\sigma _2$
approach zero. To smoothly show this phenomenon, we introduce a scale parameter z, which varies within [0,1]. We then assume that
 $\lambda =\bar {\lambda }z$
and
 $\sigma _2=\bar {\sigma }_2z$
, so that the two prices could be depicted with respect to z, which is shown in Figure 1. As expected, our price will be the same as the Heston price (the star line that is very closed to the x-axis) when
 $z=0$
, while they can become quite different when z takes large values.
Comparison of our prices and Heston prices with different value of the scale parameter. Parameters are
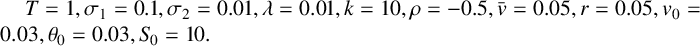 $T=1, \sigma _1=0.1, \sigma _2=0.01, \lambda =0.01, k=10, \rho =-0.5, \bar {v}=0.05, r=0.05, v_0=0.03, \theta _0=0.03, S_0=10.$

With the time to expiry being unchanged and the sampling frequency being altered, a similar phenomenon could be observed in Figure 2 that our price is always lower than the Heston price under the current parameter settings. This can be explained by the negative value of
 $\lambda $
, which contributes to the decrease in the long-run variance level of the risk-neutralized volatility and thus the lower volatility swap prices. We also observe that both prices are the decreasing function of the sampling frequency. In other words, the delivery price of a volatility swap would decrease if sampling times per year are increased.
Comparison of our prices and Heston prices with different value of the time to expiry. Parameters are
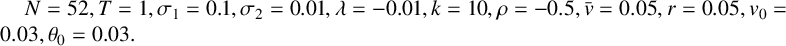 $N=52, T=1, \sigma _1=0.1, \sigma _2=0.01, \lambda =-0.01, k=10, \rho =-0.5, \bar {v}=0.05, r=0.05, v_0=0.03, \theta _0=0.03.$

As shown in Figure 3, the delivery price of volatility swaps under the Heston model is a monotonic increasing function of the time to expiry, while that under our model shows an increasing trend before it starts to decrease. This is in fact reasonable, as the negative value of
 $\lambda $
typically leads to a smaller long-run variance level of the risk-neutralized volatility, and this can result in the decrease of the realized volatility as well as the delivery price when the time to expiry is large.
Comparison of our prices and Heston prices with different value of the sampling frequency. Parameters are
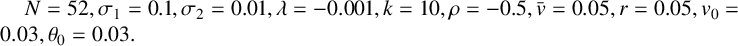 $N=52, \sigma _1=0.1, \sigma _2=0.01, \lambda =-0.001, k=10, \rho =-0.5, \bar {v}=0.05, r=0.05, v_0=0.03, \theta _0=0.03.$

All the above sensitivity analysis was carried out by setting the corresponding parameters of both models to be the same. One may also be interested in whether the two models would behave differently when the parameters are calibrated to real market data. Therefore, we make use of the parameters calibrated to European options written on the S&P 500 index from He and Chen [Reference He and Chen15] for calculating the delivery prices of volatility swaps under both models. With the calibrated parameters for our model being
 $k=5.4897, \theta _0=0.0523, \sigma _1=0.7751, \lambda =0.0822, \sigma _2=0.0074, \rho =-0.7439, v_0=0.0342$
, and for the Heston model being
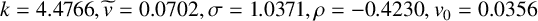 $k=4.4766, \widetilde {v}=0.0702, \sigma =1.0371, \rho =-0.4230, v_0=0.0356$
, the results with respect to different sampling frequency are presented in Figure 4. We observe that there is a large difference between the two models, and such difference is further widened when the sampling frequency increases. A similar phenomenon is shown in Figure 5, where the delivery prices are plotted against different time to expiry. With the lifetime of the contract being larger, a greater gap between the two model prices is generated. We then conclude that the inclusion of a stochastic long-run variance level in the risk-neutralized volatility process can make a significant difference in volatility swap prices. Thus, the adopted model can serve as an alternative to the Heston model in practice when pricing volatility swaps.
Market test with different sampling frequency.

Market test with different time to expiry.

4 Conclusion
In this paper, we present a closed-form pricing formula for discretely sampled volatility swaps under the modified Heston model, after successfully working out the forward characteristic function of the underlying price. The newly derived formula is shown to be accurate through numerical comparison with the results from the Monte Carlo simulation. The influence of introducing the stochastic long-run variance level into the risk-neutralized Heston model on volatility swap prices is also shown to be significant, implying that the modified Heston model may serve as a competitor to the Heston model for volatility swap pricing.
Acknowledgements
This work was supported by Zhejiang Provincial Natural Science Foundation of China (No. LQ22A010010), the National Natural Science Foundation of China (No. 12101554), the Fundamental Research Funds for Zhejiang Provincial Universities (No. GB202103001) and A Project Supported by Scientific Research Fund of Zhejiang Provincial Education Department (No. Y202147703). The authors would also like to gratefully acknowledge the anonymous referees’ constructive comments and suggestions, which greatly improved the quality and presentation of the manuscript.
Appendix
Following is the proof of Proposition 2.1.
Proof. According to the tower rule of expectation, the conditional forward characteristic function
 $f(\phi ;t,T,v_0,\theta _0)$
can be calculated as
 $$ \begin{align*} f(\phi;t,T,v_0,\theta_0)&=E(e^{\kern2pt j\phi x_{t,T}}|v_0,\theta_0)\nonumber\\ &=E[E(e^{\kern2pt j\phi x_{t,T}}|v_t,\theta_t)|v_0,\theta_0].\nonumber \end{align*} $$
As a result, the calculation of
 $f(\phi ;t,T,v_0,\theta _0)$
can be divided into two steps, that is, the inner expectation and outer expectation. If we define
 $$ \begin{align*} h(\phi;\tau,v_t,\theta_t)=E(e^{\kern2pt j\phi x_{t,T}}|v_t,\theta_t), \end{align*} $$
as the inner expectation with
 $\tau =T-t$
, then h can be formulated as
 $$ \begin{align*} h(\phi;\tau,v_t,\theta_t)=e^{C(\phi;\tau)+D(\phi;\tau)v_t+E(\phi;\tau)\theta_t+j\phi x_{t,t}}, \end{align*} $$
according to the results in [Reference He and Chen15]. With the expressions of
 $C(\phi ;\tau )$
,
 $D(\phi ;\tau )$
and
 $E(\phi ;\tau )$
, the forward characteristic function
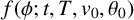 $f(\phi ;t,T,v_0,\theta _0)$
can be expressed as
 $$ \begin{align} f(\phi;t,T,v_0,\theta_0)&=E(e^{C(\phi;\tau)+D(\phi;\tau)v_t+E(\phi;\tau)+\theta_t+j\phi x_{t,t}}|v_0,\theta_0),\nonumber\\ &=e^{C(\phi;\tau)}E(e^{D(\phi;\tau)v_t+E(\phi;\tau)\theta_t}|v_0,\theta_0), \end{align} $$
by noticing the fact that
 $x_{t,t}=0$
. Hence, what remains is to work out the expectation shown in equation (A.1). If we define
 $$ \begin{align*} m(\phi;0,t,v_0,\theta_0)=E(e^{D(\phi;\tau)v_t+E(\phi;\tau)\theta_t}|v_0,\theta_0),\end{align*} $$
the Feynman–Kac theorem shows that m should satisfy
 $$ \begin{align}\left\{ \begin{array}{@{}lll} \displaystyle\frac{\partial m}{\partial s}+\frac{1}{2}\sigma_{1}^{2}v\frac{\partial^{2}m}{\partial v^2}+\frac{1}{2}\sigma_{2}^{2}\frac{\partial^{2}m}{\partial\theta^2}+k(\bar{v}+\theta-v)\frac{\partial m}{\partial v}+\lambda\frac{\partial m}{\partial\theta},&&\\[.5cm] m(\phi;0,t,v_0,\theta_0)=e^{D(\phi;\tau)v+E(\phi;\tau)\theta}.&& \end{array} \right. \end{align} $$
With careful observation of the expression for the terminal condition, we further assume that
 $$ \begin{align*} m(\phi;s,t,v_s,\theta_s)=e^{\bar{C}(\phi;t)+\bar{D}(\phi;t)v+\bar{E}(\phi;t)\theta}, \end{align*} $$
and substitute it into the partial differential equation (A.2). In this case, we could also obtain three ordinary differential equations (ODEs):
 $$ \begin{align*} \frac{\partial \bar{D}}{\partial\tau}&=\frac{1}{2}\sigma_1^2\bar{D}^2-k\bar{D},\nonumber\\ \frac{\partial \bar{E}}{\partial\tau}&=k\bar{D},\nonumber\\ \frac{\partial \bar{C}}{\partial\tau}&=\frac{1}{2}\sigma_2^2\bar{E}^2+\lambda\bar{E}+k\bar{v}\bar{D},\nonumber \end{align*} $$
with the terminal condition
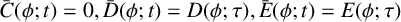 $\bar {C}(\phi ;t)=0, \bar {D}(\phi ;t)=D(\phi ;\tau ), \bar {E}(\phi ;t)=E(\phi ;\tau )$
. We could reach the final solution by solving these three ODEs. This completes the proof of the proposition.



