


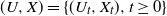



1. Introduction
Last passage times have received considerable attention in the recent literature. For instance, in the classic ruin theory (which describes the capital of an insurance company), the moment of ruin is considered as the first time the process is below level zero. However, in more recent literature, the last passage time below zero is treated as the moment of ruin, and the Cramér–Lundberg process has been generalized to spectrally negative Lévy processes (see, for example, [Reference Chiu and Yin14]). Moreover, in [Reference Paroissin and Rabehasaina36], spectrally positive Lévy processes are used for degradation models, and the last passage time above a fixed boundary is considered the failure time.
Let
 $X=\{X_t,t\geq 0 \}$
be a spectrally negative Lévy process. For any
 $t\geq 0$
and
 $x\in \mathbb{R}$
, we define
 $g_t^{(x)}$
as the last time that the process is below x before time t, that,
 \begin{align*}g_t^{(x)}=\sup\{0\leq s\leq t\,:\, X_s \leq x \},\end{align*}
with the convention
 $\sup \emptyset=0$
. We simply denote
 $g_t\,:\!=\,g_t^{(0)}$
for all
 $t\geq 0$
.
A similar version of this random time is studied in [Reference Revuz and Yor41] (see Chapter XII.3), namely the last hitting time of zero, before any time
 $t\geq 0$
, to describe excursions straddling a given time. It is also shown that this random time at time
 $t=1$
follows the arcsine distribution. The last hitting time of zero plays an essential role in the study of Azéma’s martingale (see [Reference Azéma and Yor4]). In [Reference Salminen42], the distribution of the last hitting time of a moving boundary is found.
It is well known that spectrally negative Lévy processes are often used to model the surplus of an insurance company (see [Reference Chan13], [Reference Huzak, Perman, Šikić and Vondraček22], [Reference Huzak, Perman, Šikić and Vondraček23], and [Reference Klüppelberg, Kyprianou and Maller25], among many others). The random variable
 $g_t$
provides essential information regarding the insurance company’s solvency. For instance, a large value of
 $U_t\,:\!=\,t-g_t$
(the time of the current positive excursion away from zero) indicates that the insurance company’s capital has not fallen below zero for a considerable amount of time, suggesting that the company is currently able to meet debts and financial obligations.
Lévy processes are also widely used in financial modelling. For instance, there is considerable work in the literature that adopts markets driven by Lévy processes (see [Reference Cont and Tankov16], [Reference Kyprianou, Schoutens and Wilmott27], and [Reference Schoutens44], among many others). Assume that a stock price is given by
 $Y_t=\exp(X_t)$
; then it is of interest for an investor to know when is the last time, before the time
 $t\geq 0$
, that the stock price is below a certain level
 $y^*>0$
. That is, the investor is interested in knowing the value of
 $g_t^{({\log}(y^*))}$
.
In [Reference Leland32] and [Reference Manso, Strulovici and Tchistyi33], it is assumed that equity holders endogenously choose the time of the bankruptcy of a firm. They suppose that the performance measure of the firm can be modelled by a time-homogeneous diffusion
 $Y=\{Y_t,t\geq 0 \}$
. Then the time of the bankruptcy is determined by the optimal stopping problem
 \begin{align*}\sup_{{\tau \in \mathcal{T}}} \mathbb{E}\left(\int_0^{\tau }\mathrm{e}^{-rt}[\delta(Y_t)-c(Y_t)]{d} t\bigg| Y_t=y \right),\end{align*}
where c(y) is the coupon rate that the firm must pay to the debt holders, and
 $\delta(y)$
is the payout rate received by the firm. The performance Y measures the ability of the firm to serve its future debt obligations and can be taken to be financial ratios, stock prices or credit ratings. Note that given a certain level
 $k\geq 0$
, the current positive excursion above the level k, given by
 $V_t^{(k)}=t-\sup\{0\leq s\leq t\,:\, Y_s\geq k \}$
, also provides information about the performance of the firm. Indeed, large values of
 $V_t^{(k)}$
suggest that the firm has been able to meet its obligations for a long time without a negative dividend rate. Hence, the default time of the firm can be generalized to consider the process
 $(V,Y)=\{(V_t,Y_t), t\geq 0 \}$
as its performance measure, where Y can be taken to be an exponential Lévy process.
On the other hand, when the pricing of American-type options is necessary to solve optimal stopping problems (see, for example, [Reference Jacka24], [Reference Kyprianou, Schoutens and Wilmott27], [Reference Mordecki34], and [Reference Mordecki35]), and it is known that they are intimately related to free-boundary problems (see, for example, Chapter III in [Reference Peskir and Shiryaev38]), their solution often requires techniques that involve a Markovian approach and applications of Itô’s formula. Hence, an explicit expression for the infinitesimal generator of the process is needed. Moreover, in more recent literature, the development of fluctuation identities allowed the use of the ‘guess and verify’ approach to solving optimal stopping problems driven by Lévy processes (see, for example, [Reference Alili and Kyprianou1], [Reference Avram, Kyprianou and Pistorius3], and [Reference Kyprianou and Surya28]). Hence, given the importance of the random time
 $g_t$
, it is relevant to be able to solve optimal stopping problems of the form
 \begin{align*}\sup_{{\tau \in \mathcal{T}}} \mathbb{E}\left( \mathrm{e}^{-r\tau}f(g_{\tau},\tau,X_{\tau})+\int_0^{\tau} \mathrm{e}^{-r\tau } G(g_s,s,X_s)\rm{d} s\right).\end{align*}
Indeed, in [Reference Baurdoux and Pedraza8], an optimal stopping of the form above arises when predicting
 $g_{\infty}$
with stopping times in an
 $L_p$
sense. In Section 4.1, we also propose an optimal stopping problem that generalizes the work of [Reference Leland32] and [Reference Manso, Strulovici and Tchistyi33] on corporate bankruptcy. Hence, it is relevant to derive path properties of the process
 $\{ (g_t,t,X_t), t\geq 0\}$
.
The process
 $\{ g_t,t\geq 0\}$
is non-decreasing and hence is a process of finite variation, implying that it belongs to the class of semimartingales. Then Itô’s formula for the process
 $\{ (g_t,t,X_t), t\geq 0 \}$
is well known (see, for example, [Reference Protter39], Theorem 7.33 on pp. 81–82 or [Reference Cohen and Elliott15], Theorem 14.2.4 on p. 345) and is given for any function
 $F\,:\,\mathbb{R}^3 \mapsto \mathbb{R}$
in
 $C^{2,2,2}$
by
 \begin{align*}&F(g_{t}, t,X_t)\\&=F(g_0,0,X_0) +\int_{0}^{t} \frac{\partial F}{\partial \gamma} (g_{s-},s,X_{s-}) \rm{d} g_s+ \int_{0}^{t } \frac{\partial F }{\partial t} (g_{s},s,X_{s}) \rm{d} s\\&\qquad\hspace{-0.5cm}+\int_{0}^{t} \frac{\partial F }{\partial x} (g_{s-},s,X_{s-})\rm{d} X_s+\frac{1}{2} \sigma^2 \int_{0}^{t } \frac{\partial^2 F }{\partial x^2} (g_{s},s,X_{s})\rm{d} s\\& \qquad\hspace{-0.5cm} +\sum_{0 < s\leq t} \left( F(g_{s},s,X_{s}) -F(g_{s-},s,X_{s-})-\frac{\partial }{\partial \gamma} F(g_{s-},s,X_{s-}) \Delta g_s-\frac{\partial F}{\partial x} (g_{s-},s,X_{s-}) \Delta X_s \right).\end{align*}
Note that using the local time-space formula given in [Reference Peskir37] (see Theorem 3.2), we can assume that
 $F \in C^{1,1,i}$
, where
 $i=2$
if X is of infinite variation, and
 $i=1$
otherwise. Moreover, the formula above is given in terms of the jumps of the processes
 $\{ g_t,t\geq 0\}$
and X, and it does not reflect the dependence between
 $g_t$
and
 $X_t$
. Indeed, some of the jumps of
 $\{ g_t,t\geq 0\}$
occur when X jumps to
 $(\!-\!\infty,0)$
from the positive half line. Moreover, when a Brownian motion component is included in the dynamics of X, the stochastic process
 $\{g_t,t\geq 0 \}$
has infinitely many (small) jumps due to creeping. These facts imply that, to obtain a more explicit version of Itô’s formula, a careful study of the trajectory of
 $t\mapsto g_t$
is required in terms of the excursions of X away from zero.
On the other hand, we show that
 $\{ (g_t,t, X_t), t\geq 0 \}$
belongs to the family of strong Markov processes (see Proposition 3.1), and it is of interest to find its infinitesimal generator. It turns out that for Feller processes a general form of their infinitesimal generator is known. For instance, from [Reference Revuz and Yor41] (see Theorem VII.1.13 on p. 289) we know that if Z is a Feller process in
 $\mathbb{R}^d$
, with d a positive integer, and if
 $B\subset \mathbb{R}^d$
is any relative compact set, then there exist functions
 $\sigma_{ij}$
,
 $b_i$
and c on B and a kernel
 $\nu$
such that for any function
 $F\in C^{2}$
with compact support and
 $z\in B$
,
 \begin{align*}\mathcal{A}_Z F (z)&=c(z)F(z)+\sum_{i=1}^d b_i(z) \frac{\partial }{\partial z_i} F(z) +\sum_{i,j=1}^d \sigma_{ij}(z)\frac{\partial^2}{\partial z_i \partial z_j}F(z)\\& \qquad + \int_{\mathbb{R}^d \setminus \{0\}} \left( F(y) -F(z)- \sum_{i=1}^d (y_i-z_i) \frac{\partial }{\partial z_i} F(z) \right)\nu(z,\rm{d} y).\end{align*}
However, more explicit expressions for an Itô formula and the infinitesimal generator are required in applications (for example, in optimal stopping and free boundary problems). In this work (see Theorem 3.1 and Corollary 3.1), we give an expression for Itô's formula and the infinitesimal generator of the process
 $\{ (g_t,t,X_t), t\geq 0\}$
in terms of the dynamics of X only.
We also consider, for any
 $t\geq 0$
, the random variable
 $U_t=t-g_t$
, the time of the current positive excursion away from zero. Then, having in mind the derivation of expressions for the potential measure of
 $(U,X)=\{(U_t,X_t),t\geq 0 \}$
and its joint Laplace transform at an exponential time, we also derive an explicit formula, in terms of the positive and negative excursions of X, for functionals of the process (U, X) of the form
 \begin{align*}\mathbb{E}_{u,x}\left(\int_0^{\infty} \mathrm{e}^{-qr} K(U_r,X_r)\rm{d} r\right),\end{align*}
for some function K satisfying some conditions (see Theorem 3.2), where
 $q\geq 0$
and
 $\mathbb{P}_{u,x}$
is the measure for which
 $(U_0,X_0)=(u,x)$
in view of the Markov property of (U, X). The reader can find applications of these results in [Reference Baurdoux and Pedraza8], which concerns the optimal prediction of the last zero of a spectrally negative Lévy process and where the solution is given in terms of the process (U, X). We also apply these results in Section 4 to solve a general optimal stopping problem.
This paper is organized as follows. In Section 2, we collect some fluctuation identities of spectrally negative Lévy processes. Section 3 is dedicated to defining the last zero process, for which its basic properties are shown. Moreover, a derivation of Itô’s formula, infinitesimal generator and formula for the expectation of a functional of (U, X) are the main results of this section (see Theorems 3.1 and 3.2 and Corollary 3.1). Then the results mentioned above are applied to find formulas for the joint Laplace transform of (U, X) at an exponential time, and a density for its q-potential measure is found. In Section 4, we solve an optimal stopping problem (see Theorem 4.1) driven by (U, X). In particular, in Example 4.1, we propose an optimal stopping problem applied to corporate bankruptcy that depends on the trajectory of (U, X). We also describe some optimal prediction problems of the last zero of the process. In this section, we emphasize the importance of the results developed in Section 3. Lastly, in Section 5, we include the main proofs of the paper.
2. Preliminaries
Let
 $(\Omega,\mathcal{F}, \mathbb{F}, \mathbb{P})$
be a filtered probability space, where
 $\mathbb{F}=\{\mathcal{F}_t,t\geq 0 \}$
is a filtration that is naturally enlarged (see Definition 1.3.38 of [Reference Bichteler11]). A Lévy process
 $X=\{X_t,t\geq 0 \}$
is an almost surely càdlàg process that has independent and stationary increments such that
 $\mathbb{P}(X_0=0)=1$
. From the stationary and independent increments property, the law of X is characterized by the distribution of
 $X_1$
. We hence define the characteristic exponent of X,
 $\Psi(\theta)\,:\!=\,-\log(\mathbb{E}(\mathrm{e}^{\mathrm{i}\theta X_1}))$
. The Lévy–Khintchine formula guarantees the existence of constants
 $\mu \in \mathbb{R}$
,
 $\sigma\geq 0$
and a measure
 $\Pi$
concentrated on
 $\mathbb{R}\setminus \{0\}$
with the property that
 $\int_{\mathbb{R}} (1\wedge x^2) \Pi(\rm{d} x)<\infty$
(called the Lévy measure) such that
 \begin{align*}\Psi(\theta)= \mathrm{i} \mu\theta +\frac{1}{2}\sigma^2 \theta^2-\int_{\mathbb{R}} (\mathrm{e}^{\mathrm{i} \theta y}-1-\mathrm{i} \theta y\mathbb{I}_{\{|y|<1 \}})\Pi(\rm{d} y).\end{align*}
Moreover, from the Lévy–Itô decomposition we can write
 \begin{align*}X_t=\sigma B_t-\mu t+\int_{[0,t]}\int_{(\!-\!\infty,-1)\cup (1,\infty)} x N(\rm{d} s\times \rm{d} x)+\int_{[0,t]}\int_{(-1,1)} x( N(\rm{d} s\times \rm{d} x)-\rm{d} s\Pi(\rm{d} x)),\end{align*}
where N is a Poisson random measure on
 $\mathbb{R}^+\times \mathbb{R}$
with intensity
 $\rm{d} t \times \Pi(\rm{d} x)$
and
 $B=\{ B_t,t\geq 0 \}$
is an independent standard Brownian motion. We now state some properties and facts about Lévy processes. The reader can refer, for example, to [Reference Bertoin10], [Reference Kyprianou29], [Reference Sato43] for more details. Every Lévy process X is also a strong Markov
 $\mathbb{F}$
-adapted process. Moreover, Lévy processes satisfy a stronger property. Indeed, for any stopping time
 $\tau$
we define, on the event
 $\{ \tau<\infty\}$
, the quantity
 $\widetilde{X}_t= X_{\tau+t}-X_t$
, for each
 $t\geq 0$
. Then, on the event
 $\{ \tau<\infty\}$
, the process
 $\widetilde{X}=\{\widetilde{X}_t,t\geq 0 \}$
is independent of
 $\mathcal{F}_{\tau}$
, has the same law as X and is a Lévy process. For all
 $x\in \mathbb{R}$
, denote by
 $\mathbb{P}_x$
the law of X when started at the point
 $x\in \mathbb{R}$
, that is,
 $\mathbb{E}_x(\!\cdot\!)=\mathbb{E}(\!\cdot\!|X_0=x)$
. Due to the spatial homogeneity of Lévy processes, the law of X under
 $\mathbb{P}_x$
is the same as that of
 $X+x$
under
 $\mathbb{P}$
.
The process X is a spectrally negative Lévy process if it has no positive jumps (
 $\Pi(0,\infty)=0$
) with no monotone paths. We now state some important properties and fluctuation identities of spectrally negative Lévy processes, which will be useful in later sections (see Chapter VII in [Reference Bertoin10] or Chapter 8 in [Reference Kyprianou29] for details).
Due to the absence of positive jumps, we can define the Laplace transform of
 $X_1$
. We denote by
 $\psi(\beta)$
the Laplace exponent of the process, that is,
 $\psi(\beta)=\log(\mathbb{E}(\mathrm{e}^{\beta X_1}))$
. Then for all
 $\beta \geq 0$
,
 \begin{align*}\psi(\beta)=-\mu\beta +\frac{1}{2}\sigma^2 \beta^2+\int_{(\!-\!\infty,0)} (\mathrm{e}^{\beta y}-1-\beta y\mathbb{I}_{\{y>-1 \}})\Pi(\rm{d} y).\end{align*}
It can be shown that
 $\psi$
is an infinitely differentiable and strictly convex function on
 $(0,\infty)$
that tends to infinity at infinity. In particular,
 $\psi'(0\!+\!)=\mathbb{E}(X_1)\in [\!-\!\infty,\infty)$
determines the value of X at infinity. When
 $\psi'(0\!+\!)>0$
the process X drifts to infinity (that is,
 $\lim_{t \rightarrow \infty} X_t=\infty$
), when
 $\psi'(0\!+\!)<0$
, X drifts to minus infinity, and the condition
 $\psi'(0\!+\!)=0$
implies that X oscillates (that is,
 $\limsup_{t\rightarrow \infty} X_t =-\liminf_{t\rightarrow \infty} X_t=\infty$
). We also define the right-inverse of
 $\psi$
,
 \begin{align*}\Phi(q)=\sup\{\beta\geq 0\,:\, \psi(\beta)=q \}, \quad q\geq 0.\end{align*}
The process X has paths of finite variation if and only if
 $\sigma=0$
and
 $\int_{(-1,0)} |x| \Pi(\rm{d} x)<\infty$
, otherwise X has paths of infinite variation. In the latter case, we have that X can be just written as a drift process minus a subordinator,
 \begin{align}X_t=d t+\int_{[0,t]}\int_{(\!-\!\infty,0)} x N(\rm{d} s\times \rm{d} x),\end{align}
where
 \begin{align*}d=-\mu -\int_{(-1,0)} x\Pi(\rm{d} x).\end{align*}
Since X cannot have monotone paths, we necessarily have that
 $d>0$
. Define
 $\tau_a^+$
as the first passage time above the level
 $a>0$
,
 \begin{align*}\tau_a^+=\inf\{t>0\,:\, X_t>a \},\end{align*}
where here and throughout the paper, we use the usual convention that
 $\inf\emptyset=\infty$
. Then, for any
 $a>0$
and
 $q\geq 0$
, the Laplace transform of
 $\tau_a^+$
is given by
 \begin{align}\mathbb{E}(\mathrm{e}^{-q \tau_a^+}\mathbb{I}_{\{\tau_a^+<\infty \}})=\mathrm{e}^{-\Phi(q)a}.\end{align}
An essential family of functions for spectrally negative Lévy processes are the scale functions,
 $W^{(q)}$
. For all
 $q\geq 0$
, the scale function
 $W^{(q)}\,:\,\mathbb{R} \mapsto \mathbb{R}_+$
is such that
 $W^{(q)}(x)=0$
for all
 $x<0$
and it is characterized on the interval
 $[0,\infty)$
as a strictly increasing and continuous function with Laplace transform given by
 \begin{align}\int_0^{\infty} \mathrm{e}^{-\beta x} W^{(q)}(x)\rm{d} x=\frac{1}{\psi(\beta)-q}, \quad \text{for } \beta >\Phi(q).\end{align}
For the case
 $q=0$
we simply denote
 $W=W^{(0)}$
. When X has paths of infinite variation,
 $W^{(q)}$
is continuous on
 $\mathbb{R}$
and
 $W^{(q)}(0)=0$
for all
 $q\geq 0$
, otherwise we have
 $W^{(q)}(0)=1/d$
, where
 $d>0$
. As to the behaviour of
 $W^{(q)}$
at infinity, for
 $q\geq 0$
we have
 $\lim_{x\rightarrow \infty} \mathrm{e}^{-\Phi(q)x}W^{(q)}(x)=\Phi'(q)$
.
There are some important fluctuation identities of Lévy processes in terms of the scale functions. In particular, we list some that will be useful in later sections. Denote by
 $\tau_x^-$
the first time X is strictly below the level
 $x\leq 0$
, that is,
 \begin{align*}\tau_x^-=\inf\{t > 0\,:\, X_t < x \}.\end{align*}
The Laplace transform of
 $\tau_a^+$
, on the event of hitting the level
 $a>0$
before entering the set
 $(\!-\!\infty,0)$
, is given by
 \begin{align}\mathbb{E}_x\left(\mathrm{e}^{-q\tau_a^+} \mathbb{I}_{\{ \tau_a^+< \tau_0^-\}} \right)=\frac{ W^{(q)}(x)}{W^{(q)}(a)}\end{align}
for any
 $x\leq a$
. The joint Laplace transform of
 $\tau_0^-$
and
 $X_{\tau_0^-}$
is
 \begin{align}\mathbb{E}_x(e^{-q \tau_0^-+\beta X_{\tau_0^-}} \mathbb{I}_{\{\tau_0^- < \infty \}})=\mathrm{e}^{\beta x} \mathcal{I}^{(q,\beta)}(x)\end{align}
for all
 $x>0$
,
 $q\geq 0$
and
 $\beta\geq 0$
, where the function
 $\mathcal{I}^{(q,\beta)}$
is given by
 \begin{align}\mathcal{I}^{(q,\beta)}(x)\,:\!=\,1+(q-\psi(\beta)) \int_0^x \mathrm{e}^{-\beta y} W^{(q)}(y) \rm{d} y-\frac{q-\psi(\beta)}{\Phi(q)-\beta} \mathrm{e}^{-\beta x}W^{(q)}(x), \quad x\in \mathbb{R}.\end{align}
When
 $\beta=\Phi(q)$
, for some
 $q\geq 0$
, we understand the equation above in the limiting sense, that is,
 \begin{align*}\mathcal{I}^{(q,\Phi(q))}(x)=1-\psi'(\Phi(q)+) \mathrm{e}^{{\kern-.5pt}{-}\Phi(q) x}W^{(q)}(x), \quad x\in \mathbb{R}.\end{align*}
Since X has only negative jumps, we have that it only creeps upwards, that is,
 \begin{align} \mathbb{P}(X_{\tau_x^+}=x |\tau_x^+<\infty )=1\end{align}
for any
 $x>0$
. Moreover, X creeps downwards if and only if
 $\sigma>0$
and we have
 \begin{align} \mathbb{P}_x(X_{\tau_0^-}=0,\tau_0^-<\infty)=\frac{\sigma^2}{2}\left(W'(x)-\Phi(0)W(x) \right)\end{align}
for any
 $x>0$
. Denote by
 $\sigma_x^-$
the first time the process X is below or equal to the level x, that is,
 \begin{align}\sigma_x^-=\inf\{t>0\,:\, X_t \leq x \}.\end{align}
For
 $t\geq 0$
, let
 $\underline{X}_t=\inf_{0\leq s\leq t}X_s$
and let
 $\mathbf{e} _q$
be an exponential random variable (independent of X) with mean
 $1/q$
, for
 $q\geq 0$
. Since
 \begin{align*}\mathbb{E}(\mathrm{e}^{-q \sigma_{x}^-}\mathbb{I}_{\{\sigma_x^- <\infty\}})=\mathbb{P}(\mathbf{e} _q >\sigma_x^-)=\mathbb{P}(\underline{X}_{\mathbf{e} _q} \leq -x)\end{align*}
for all
 $x \leq 0$
, and since the random variable
 $\underline{X}_{\mathbf{e} _q}$
is continuous on
 $(\!-\!\infty,0)$
, we have that, for any
 $x>0$
, the stopping times
 $\sigma_x^-$
and
 $\tau_x^-$
have the same distribution. When X is of infinite variation, X instantly enters the set
 $(\!-\!\infty,0)$
, while in the finite variation case there is a positive time before the process enters it. That implies that in the infinite variation case
 $\tau_0^-=\sigma_0^-=0$
almost surely. Note that in the finite variation case, since 0 is irregular for
 $(\!-\!\infty,0]$
(see the discussion on p. 157 in [Reference Kyprianou29]) and due to equation (2.8), we have that
 $\sigma_0^-=\tau_0^->0$
 $\mathbb{P}$
-almost surely.
Let
 $q>0$
and
 $a\in \mathbb{R}$
. The q-potential measure of X killed on exiting
 $(\!-\!\infty,a]$
is absolutely continuous with respect to Lebesgue measure with a density given by
 \begin{align} \mathrm{e}^{-\Phi(q)(a-x)}W^{(q)}(a-y) -W^{(q)}(x-y), \quad x,y\leq a.\end{align}
Similarly, the q-potential measure of X killed on exiting
 $[0,\infty)$
,
 \[\int_0^{\infty} \mathrm{e}^{-qt} \mathbb{P}_x(X_t \in \rm{d} y,t< \tau_0^-)\rm{d} t,\]
is absolutely continuous with respect to Lebesgue measure, and it has density given by
 \begin{align}\mathrm{e}^{-\Phi(q) y}W^{(q)}(x) -W^{(q)}(x-y) \quad x,y\geq 0.\end{align}
We have that the stochastic process
 \begin{align*}\{ \mathrm{e}^{-q(t\wedge \tau_0^-\wedge \tau_a^+)} W^{(q)}(X_{t\wedge \tau_0^-\wedge \tau_a^+}), t\geq 0\}\end{align*}
is a martingale under
 $\mathbb{P}_x$
, for any
 $a\in (0,\infty]$
,
 $q\geq 0$
and
 $x\in \mathbb{R}$
.
We close this section by stating a version of Itô’s formula available in the literature applied to spectrally negative Lévy processes that will be used in the sequel. Let
 $F:\mathbb{R}^2\mapsto \mathbb{R}$
and a set
 $D\subset \mathbb{R}^2$
with its closure denoted by
 $\bar{D}$
. We say that F is
 $C^{j_1,j_2}$
in
 $\bar{D}$
, for
 $j_1,j_2 \in \{0,1,2,\ldots\}$
, if F restricted to D coincides with a function
 $F_1:\mathbb{R}^2\mapsto \mathbb{R}$
which is
 $C^{j_1,j_2}$
on
 $\mathbb{R}_+\times \mathbb{R}$
. Suppose that X is any spectrally negative Lévy process.
Let
 $i=1$
if X is of finite variation, and
 $i=2$
otherwise. From [Reference Peskir37] (see Theorem 3.2 for the local time-space formula for general semimartingales) we deduce that if
 $F:\mathbb{R}^2 \mapsto \mathbb{R}$
is a continuous function such that, for some
 $b\in \mathbb{R}$
, F is
 $C^{1,i}$
on
 $[0,\infty)\times (\!-\!\infty,b]$
and on
 $[0,\infty)\times [b,\infty)$
, the following change-of-variable formula holds:
 \begin{align}&F(t,X_t)\nonumber\\&=F(0,X_0)+\int_0^{t} \frac{1}{2}\left( \frac{\partial F}{\partial t}(s,X_{s-}+)+\frac{\partial F}{\partial t}(s,X_{s-}-) \right) \rm{d} s \nonumber\\&\qquad+\int_0^{t} \frac{1}{2}\left( \frac{\partial F}{\partial x}(s,X_{s-}+)+\frac{\partial F}{\partial x}(s,X_{s-}-) \right) \rm{d} X_s \nonumber\\&\qquad+\frac{1}{2}\sigma^2 \int_0^{t} \frac{1}{2}\left( \frac{\partial^2 F}{\partial x^2}(s,X_{s-}+)+\frac{\partial^2 F}{\partial x^2}(s,X_{s-}-) \right) \rm{d} s\nonumber\\ &\qquad+ \int_{[0,t]}\int_{(\!-\!\infty,0)}\left[F(s,X_{s-}+y)-F(s,X_{s-})\vphantom{\frac{\partial F}{\partial x}}\right.\nonumber \\ &\qquad \left.-\frac{1}{2}\left( \frac{\partial F}{\partial x}(s,X_{s-}+)+\frac{\partial F}{\partial x}(s,X_{s-}-) \right)y \right]N(\rm{d} s\times \rm{d} y)\nonumber\\ &\qquad+ \frac{1}{2} \int_0^t \left( \frac{\partial F}{\partial x}(s,X_{s-}+)-\frac{\partial F}{\partial x}(s,X_{s-}-) \mathbb{I}_{\{ X_{s-}=b, X_s=b\}} \right) \rm{d} L^b_s(X),\end{align}
where
 $L_s^b(X)$
is the local time of X at the level b given in terms of the Tanaka formula, namely,
 \begin{align}|X_t-b|&=|X_0-b|+\int_0^t \text{sign}(X_{s-}-b)\rm{d} X_s+L_t^b(X) \nonumber\\&\qquad +\int_{[0,t]}\int_{(\!-\!\infty,0)} \left[|X_{s-}+y-b|-|X_{s-}-b|-\text{sign}(X_{s-}-b)y \right] N(\rm{d} s \times \rm{d} y).\end{align}
3. The last zero process
Let X be a spectrally negative Lévy process. Recall that
 $g_t^{(x)}$
is the last time that the process is below x before time t, that is,
 \begin{align*}g_t^{(x)}=\sup\{0\leq s\leq t\,:\, X_s \leq x \},\end{align*}
with the convention
 $\sup \emptyset=0$
. We simply denote
 $g_t\,:\!=\,g_t^{(0)}$
, for all
 $t\geq 0$
. For any stopping time
 $\tau$
, the random variable
 $g_{\tau}^{(x)}$
is
 $\mathcal{F}_{\tau}$
measurable. In particular, we get that
 $\{g_t^{(x)}, t\geq 0 \}$
is adapted to the filtration
 $\{\mathcal{F}_t,t\geq 0 \}$
. Moreover, it is easy to show that for a fixed
 $x\in \mathbb{R}$
, the stochastic process
 $\{ g_t^{(x)},t\geq 0\}$
is non-decreasing and right-continuous with left limits. Similarly, for a fixed
 $t\geq 0$
, the mapping
 $x\mapsto g_t^{(x)}$
is non-decreasing and almost surely right-continuous with left limits.
It can easily be seen that the process
 $\{g_t,t\geq 0\}$
is not a Markov process, particularly not a Lévy process. However, the strong Markov property holds for the three-dimensional process
 $\{(g_t,t, X_t),t\geq 0 \}$
. We postpone its proof to Section 5.
Proposition 3.1. The process
 $\{ (g_t,t,X_t),t\geq 0 \}$
is a strong Markov process with respect to the filtration
 $\{\mathcal{F}_t,t\geq 0 \}$
with state space given by
 $E_g=\{ (\gamma,t,x) \,:\, 0\leq \gamma < t \text{ and } x > 0\}\cup \{ (\gamma,t,x) : 0 \leq \gamma=t \text{ and } x\leq 0\}$
. Moreover, we have that for any measurable positive function
 $h\,:\, E_g \mapsto \mathbb{R}$
, any
 $s\geq 0$
and any stopping time
 $\tau\geq 0$
,
 \begin{align*}\mathbb{E}( h(g_{\tau+s},\tau+s,X_{\tau+s})|\mathcal{F}_{\tau})=f_s(g_{\tau},\tau,X_{\tau}),\end{align*}
where for any
 $(\gamma,t,x)\in E_g$
,
 \begin{align}f_s(\gamma,t ,x)&=\mathbb{E}_x(h(\gamma,t+s, X_s)\mathbb{I}_{\{ \sigma_0^->s\}})+\mathbb{E}_x(h(g_s+t,t+s, X_s)\mathbb{I}_{\{ \sigma_0^-\leq s\}}).\end{align}
In the spirit of the above proposition, we define, for
 $(\gamma,t,x)\in E_g$
, the probability measure
 $\mathbb{P}_{\gamma,t,x}$
in the following way: for every measurable and positive function h we set
 \begin{align*}\mathbb{E}_{\gamma,t,x}(h(g_{t+s},t+s,X_{t+s}))\,:\!=\,\mathbb{E} \left( h(g_{t+s},t+s,X_{t+s})\bigg|(g_t,t,X_t)=(\gamma,t,x) \right)=f_s(\gamma,t ,x),\end{align*}
where
 $f_s$
is given in (3.1). Then we can write
 $\mathbb{P}_{\gamma,t,x}$
in terms of
 $\mathbb{P}_x$
as
 \begin{align}\mathbb{E}_{\gamma,t,x}(h(g_{t+s},t+s,X_{t+s}))=\mathbb{E}_x(h(\gamma,t+s, X_s)\mathbb{I}_{\{ \sigma_0^->s\}})+\mathbb{E}_x(h(g_s+t,t+s, X_s)\mathbb{I}_{\{ \sigma_0^-\leq s\}}).\end{align}
Define
 $U_t=t-g_t$
as the length of the current excursion above the level zero. As a direct consequence of the form of
 $f_s$
given in (3.1), we have that the process
 $\{(U_t,X_t),t\geq 0 \}$
is also a strong Markov process with state space given by
 $E=[(0,\infty)\times (0,\infty)]\cup \{ (0,x)\in \mathbb{R}^2 \,:\, x\leq 0\}$
. Indeed, let
 $f:E\mapsto \mathbb{R}$
be any positive measurable function; taking
 $h(\gamma,t,x)=f(t-\gamma,x)$
in (3.1), we obtain that
 \begin{align*}f_{s}(\gamma,t,x)&=\mathbb{E}_x(h(\gamma,t+s, X_s)\mathbb{I}_{\{ \sigma_0^->s\}})+\mathbb{E}_x(h(g_s+t,t+s, X_s)\mathbb{I}_{\{ \sigma_0^-\leq s\}})\\&=\mathbb{E}_x(f(t-\gamma+s, X_s)\mathbb{I}_{\{ \sigma_0^->s\}})+\mathbb{E}_x(f(U_s, X_s)\mathbb{I}_{\{ \sigma_0^-\leq s\}})\\&=f_s(0,t-\gamma,x).\end{align*}
From this, we deduce that
 \begin{align*}\mathbb{E}(f(U_{\tau+s},X_{\tau+s})|\mathcal{F}_{\tau})=f_s(g_{\tau},\tau,X_{\tau} )=f_s(0,U_{\tau},X_{\tau} )=\mathbb{E}(f(U_{\tau+s},X_{\tau+s})|\sigma(U_{\tau},X_{\tau})).\end{align*}
Hence, we can define a probability measure
 $\mathbb{P}_{u,x}$
, for all
 $(u,x)\in E$
, by
 \begin{align}\mathbb{E}_{u,x}(f(U_s,X_{s}))=\mathbb{E}_x(f(u+ s, X_s)\mathbb{I}_{\{ \sigma_0^->s\}})+\mathbb{E}_x(f(U_s, X_s)\mathbb{I}_{\{ \sigma_0^-\leq s\}}),\end{align}
for any positive and measurable function f.
Remark 3.1. We know that, for any
 $x\in \mathbb{R}$
, the stochastic process
 $\{ g_t^{(x)}, t\geq 0 \}$
has non-decreasing paths. That directly implies that
 $g_t^{(x)}$
is a process of finite variation, and then it has a countable number of jumps. Moreover, by a close inspection of the definition of
 $g_t^{(x)}$
, we notice that
 $g_t^{(x)}=t$
on the set
 $\{t\geq 0\,:\, X_t \leq x\}$
, it is flat when X is in the set
 $(x,\infty)$
and it has a jump when X enters the set
 $(\!-\!\infty,x]$
. Moreover, if X is a process of infinite variation, we know that the set of times X visits the level x from above may be infinite with positive probability. That implies that when X is of infinite variation,
 $t\mapsto g_t^{(x)}$
may have an infinite number of arbitrary small jumps with positive probability.
In the following theorem, we give a more explicit expression for the Itô formula for the process
 $(g_t,t, X_t)$
in terms of the random measure N. Note that this formula will be helpful later in deriving the infinitesimal generator of
 $(g_t,t, X_t)$
. The reader can find its proof in Section 5.2.1.
Theorem 3.1. (Ito’s formula.) Let X be any spectrally negative Lévy process, we define
 $i=1$
if X is of finite variation, and
 $i=2$
otherwise. Let
 $F\,:\,\bar{E}_g \mapsto \mathbb{R}$
be a continuous function that satisfies the following assertions.
-
(i) The mapping
 $(t,x)\mapsto F(t,t,x)$
is
$C^{1,i}$
on
$[0,\infty)\times(\!-\!\infty,0]$
, for all
$t\geq 0$
.
-
(ii) F is
$C^{0,1,i}$
on
$\{(\gamma,t,x)\in \mathbb{R}_+^2\times \mathbb{R}: 0\leq \gamma\leq t \textit{ and } x\geq 0 \}$
. -
(iii) If
$\sigma>0$
, then F is such that
$\lim_{h\downarrow 0} F(\gamma,t,h)=F(t,t,0)$
, for all
$0\leq \gamma\leq t$
, and (3.4)for all
\begin{align}\frac{\partial F}{\partial x}(t,t,0\!+\!)=\frac{\partial F }{\partial x}(t,t,0\!-\!)\end{align}
$t\geq 0$
.


Then we have the following version of Itô’s formula for the three-dimensional process
 $\{(g_t,t,X_t),t\geq 0\}$
:
 \begin{align}F(g_{t}, t,X_t)&=F(g_0,0,X_0) +\int_{0}^{t} \frac{\partial F_g }{\partial t } (s,X_{s-})\mathbb{I}_{\{g_{s-}=s \}}\rm{d} s+ \int_{0}^{t} \frac{\partial F }{\partial t} (g_{s-},s,X_{s-})\mathbb{I}_{\{ g_{s-} < s\}} \rm{d} s\nonumber\\&\quad+\int_{0}^{t} \frac{\partial F }{\partial x} (g_{s-},s,X_{s-})\rm{d} X_s+\frac{1}{2} \sigma^2 \int_{0}^{t } \frac{\partial^2 F }{\partial x^2} (g_{s},s,X_{s})\rm{d} s\nonumber\\& \quad +\int_{[0,t] } \int_{(\!-\!\infty,0)} \left[ F(g_{s},s,X_{s^-}+y) -F(g_{s-},s,X_{s-})-y\frac{\partial F}{\partial x} (g_{s-},s,X_{s-}) \right]N(\rm{d} s\times \rm{d} y)\nonumber\\&=F(g_0,0,X_0)+ \int_{0}^{t} \frac{\partial F_g }{\partial t } (s,X_{s-})\mathbb{I}_{\{g_{s-}=s \}}\rm{d} s+ \int_{0}^{t} \frac{\partial F }{\partial t} (g_{s-},s,X_{s-})\mathbb{I}_{\{ g_{s-} < s\}} \rm{d} s \nonumber\\&\quad+\int_{0}^{t}\frac{\partial F }{\partial x} (g_{s-},s,X_{s-})\rm{d} X_s+\frac{1}{2} \sigma^2 \int_{0}^{t} \frac{\partial^2 F}{\partial x^2} (g_{s-},s,X_{s-}) \rm{d} s\nonumber\\& \quad +\int_{[0,t] } \int_{(\!-\!\infty,0)} \left[ F(s,s,X_{s-}+y) -F(s,s,X_{s-})-y\frac{\partial F }{\partial x} (s,s,X_{s-}) \right]\mathbb{I}_{\{g_{s-}=s \}}N(\rm{d} s\times \rm{d} y)\nonumber\\&\quad+\int_{[0,t]}\int_{(\!-\!\infty,0)} \left[F(g_{s-},s,X_{s-}+y)-F(g_{s-},s,X_{s-})-y\frac{\partial F }{\partial x} (g_{s-},s,X_{s-})\right]\nonumber\\&\quad\quad\quad \times \mathbb{I}_{\{X_{s-}+y >0 \}}\mathbb{I}_{\{ g_{s-} < s\}} N(\rm{d} s\times \rm{d} y)\nonumber \\&\quad+ \int_{[0,t]}\int_{(\!-\!\infty,0)} \left[F(s,s,X_{s-}+y)-F(g_{s-},s,X_{s-})-y\frac{\partial F }{\partial x} (g_{s-},s,X_{s-}) \right]\nonumber\\&\quad\quad\quad \times \mathbb{I}_{\{X_{s-}+y \leq 0 \}} \mathbb{I}_{\{ g_{s-} < s\}}N(\rm{d} s\times \rm{d} y),\end{align}
where
 $ F_g(t,x)\,:\!=\, F(t,t,x)$
for
 $t \geq 0$
and
 $x\leq 0$
.
Remark 3.2.
-
(i) When
$\sigma>0$
, the Brownian motion part of X implies that X can visit the interval
$(\!-\!\infty,0]$
by creeping. That means that
$t\mapsto g_t$
has two types of jumps: those as a consequence of X jumping from the positive half line to
$(\!-\!\infty,0)$
and those as a consequence of creeping. The limit condition imposed for F and (3.4) (when
$\sigma>0$
) ensure that the jumps due to the Brownian component vanish. Otherwise, a more careful analysis involving the local time needs to be done. -
(ii) Note that the limit condition imposed on F, when
$\sigma>0$
, comes naturally when we have functions that depend on expectations of the process
$\{ (g_t,t,X_t), t\geq 0\}$
. For example, if f is a bounded continuous function, we have that satisfies that
\begin{align*}F(\gamma,t,x)&\,:\!=\,\mathbb{E}_{\gamma,t,x}(f(g_{t+s},t+s,X_{t+s}))\\&=\mathbb{E}_x(f(\gamma,t+s, X_s)\mathbb{I}_{\{ \sigma_0^->s\}})+\mathbb{E}_x(f(g_s+t,t+s, X_s)\mathbb{I}_{\{ \sigma_0^-\leq s\}})\end{align*}
$\lim_{h\downarrow 0} F(\gamma,t,h)=F(t,t,0)$
for all
$\gamma\leq t$
and
$s>0$
, when
$\sigma>0$
.
-
(iii) Note that the proof relies on applying the appropriate version of Itô’s formula to F on the regions of
$E_g$
where
$x>0$
and
$x<0$
. So analogous results would be obtained if we relax the regularity conditions of F and apply an appropriate version of Itô’s formula (see, for example, Theorem IV.70 in [Reference Protter39], Theorem 3.2 in [Reference Peskir37] or Theorem 7 in [Reference Kyprianou and Surya30]). For instance, it is possible to use Theorem 3.2 in [Reference Peskir37] to obtain the same result as in Theorem 3.1 by replacing condition (3.4) with the more restrictive condition It turns out that for some applications in optimal stopping condition (3.4) is satisfied, whereas the condition above fails as it is found in Proposition 4.1 and Remark 4.2.
\begin{align*}\frac{\partial F}{\partial x}(\gamma,t,0\!+\!)=\frac{\partial F }{\partial x}(t,t,0\!-\!) \quad \text{for each }0\leq \gamma\leq t.\end{align*}


Following the definition of [Reference Revuz and Yor41] (see Definition VII.1.8 on p. 285), we say that F belongs to the domain of the extended infinitesimal generator of the process
 $Z_t=(g_t,t,X_t)$
if there exists a Borel function
 $f\,:\,E_g\mapsto \mathbb{R}$
such that
 $\int_0^{t}|f(X_s)| \rm{d} s<\infty$
almost surely, for all
 $t>0$
, and
 \begin{align*}F(g_t,t,X_t)-F(g_0,0,X_0)-\int_0^{t} f(g_s,s,X_s)\rm{d} s\end{align*}
is a
 $\mathbb{P}_{\gamma,t,x}$
-right-continuous martingale, for each
 $(\gamma,t,x)\in E_g$
. If such a function exists, we write
 $\mathcal{A}_{Z}F(\gamma,t,x)=f(\gamma,t,x)$
and call it the extended infinitesimal generator.
Now that we have a more explicit version of Itô’s formula for the three-dimensional process
 $(g_t,t, X_t)$
in terms of the Poisson random measure N, we are in a position to state an explicit formula for its extended infinitesimal generator. The following corollary follows directly from equation (3.5) and standard arguments, so its proof is omitted (see, for example, Proposition 2.4 in [Reference Lamberton and Mikou31], Proposition 8.16 in [Reference Cont and Tankov16] or the proof of Theorem 6.7.4 in [Reference Applebaum2]).
Corollary 3.1. Suppose that X and F satisfy the conditions of Theorem 3.1 and further assume that F and its derivatives are bounded functions. Then the infinitesimal generator
 $\mathcal{A}_Z$
of the process
 $Z_t=(g_t,t,X_t)$
is given by
 \begin{align}\mathcal{A}_Z F (\gamma,t,x) &=\frac{\partial F_g }{\partial t} (t,x) \mathbb{I}_{\{x\leq 0 \}}+\frac{\partial F}{\partial t} (\gamma,t,x)\mathbb{I}_{\{x> 0 \}} -\mu \frac{\partial F }{\partial x} (\gamma,t,x)+ \frac{1}{2} \sigma^2 \frac{\partial^2 F}{\partial x^2} (\gamma,t,x) \nonumber\\& \quad + \int_{(\!-\!\infty,0)} \left( F(\gamma,t,x+y) -F(\gamma,t,x)-y\mathbb{I}_{\{y>-1\}}\frac{\partial F}{\partial x} (\gamma,t,x) \right)\mathbb{I}_{\{x+y >0 \}}\Pi(\rm{d} y)\nonumber\\& \quad + \int_{(\!-\!\infty,0)} \left( F(t,t,x+y) -F(t,t,x)-y\mathbb{I}_{\{y>-1\}}\frac{\partial F }{\partial x} (t,t,x) \right)\mathbb{I}_{\{x\leq 0 \}}\Pi(\rm{d} y)\nonumber\\& \quad + \int_{(\!-\!\infty,0)} \left( F(t,t,x+y)-F(\gamma,t,x)-y\mathbb{I}_{\{y>-1\}} \frac{\partial F }{\partial x} (\gamma,t,x) \right)\mathbb{I}_{\{x>0 \}}\mathbb{I}_{\{x+y <0 \}}\Pi(\rm{d} y) \end{align}
for all
 $(\gamma,t,x) \in E_g$
.
Recall from Remark 3.1 that the behaviour of
 $g_t$
(and then
 $U_t$
) can be determined from the excursions of X away from zero. The following theorem provides a formula to calculate an integral involving the process
 $\{(U_t, X_t), t\geq 0 \}$
with respect to time in terms of the excursions of X above and below zero.
Theorem 3.2. Let
 $q\geq 0$
and X be a spectrally negative Lévy process and
 $K:E\mapsto \mathbb{R}$
be a left-continuous function in each argument. Assume that there exists a non-negative function
 $C:\mathbb{R}_+ \times \mathbb{R} \mapsto \mathbb{R}$
such that
 $u\mapsto C(u,x)$
is a monotone function for all
 $x\in \mathbb{R}$
,
 $|K(u,x)|\leq C(u,x)$
and
 $\mathbb{E}_{u,x}\left( \int_0^{\infty} \mathrm{e}^{-qr } C(U_r,X_r+y) \rm{d} r\right)<\infty$
for all
 $(u,x)\in E$
and
 $y\in \mathbb{R}$
. Then we have, for any
 $(u,x)\in E$
, that
 \begin{align}\mathbb{E}_{u,x}\left(\int_0^{\infty}\mathrm{e}^{-qr} K(U_r,X_r) \rm{d} r \right)&=K^+(u,x)+\int_{-\infty}^0 K(0,y) \left[\Phi'(q)\mathrm{e}^{-\Phi(q)(y-x)} -W^{(q)}(x-y)\right] \rm{d} y \nonumber\\&\qquad+ [\Phi'(q)\mathrm{e}^{\Phi(q)x}-W^{(q)}(x)]\lim_{\varepsilon \downarrow 0 } \frac{K^+(0,\varepsilon)}{ W^{(q)}(\varepsilon)},\end{align}
where
 $K^+$
is given by
 \begin{align*}K^+(u,x)=\displaystyle{\mathbb{E}_x\left( \int_0^{\tau_0^-}\mathrm{e}^{-qr}K(u+r,X_r)\rm{d} r \right)}, \quad (u,x)\in E.\end{align*}
In particular, when
 $u=x=0$
we have that
 \begin{align*}\mathbb{E}\left(\int_0^{\infty}\mathrm{e}^{-qr} K(U_r,X_r) \rm{d} r \right) &=\int_{-\infty}^{0}\!K(0,y)\left[\Phi'(q)\mathrm{e}^{-\Phi(q) y} -W^{(q)}(\!-\!y)\right] \rm{d} y +\Phi'(q) \lim_{\varepsilon \downarrow 0 } \frac{ K^+(0,\varepsilon)}{ W^{(q)}(\varepsilon)}.\end{align*}
Remark 3.3. From the proof of Theorem 3.2, we can find an alternative representation for formula (3.7) as a limit in terms of excursions of X above and below zero divided by a normalization term. Indeed, for
 $(u,x)\in E$
,
 \begin{align*}\mathbb{E}_{u,x}&\left(\int_0^{\infty}\mathrm{e}^{-qr} K(U_r,X_r) \rm{d} r \right)\\&=K^+(u,x)+ \lim_{\varepsilon \downarrow 0 } \mathbb{E}_{x}\left( \mathbb{I}_{\{ \tau_0^-<\infty\}} \mathrm{e}^{-q \tau_0^-} K^-(X_{\tau_0^-}-\varepsilon) \right) \nonumber\\&\qquad+ \left[\Phi'(q)\mathrm{e}^{\Phi(q) x}- W^{(q)}(x) \right] \lim_{\varepsilon \downarrow 0 }\frac{ \mathbb{E}_{\varepsilon}\left( \mathbb{I}_{\{ \tau_0^-<\infty\}} \mathrm{e}^{-q \tau_0^-} K^-(X_{\tau_0^-}-\varepsilon) \right)+K^+(0,\varepsilon) }{ W^{(q)}(\varepsilon)},\end{align*}
where
 $K^-$
is given by
 \begin{align}K^-(x)=\displaystyle{\mathbb{E}_x\left( \int_0^{\tau_0^+}\mathrm{e}^{-qr}K(0,X_r)\rm{d} r \right)},\end{align}
for all
 $x\in \mathbb{R}$
.
3.1. Applications of Theorem 3.2
We now consider applications of Theorem 3.2. We first calculate the joint Laplace transform of
 $(U_{\mathbf{e} _q},X_{\mathbf{e} _q})$
, where
 $\mathbf{e} _q$
is an exponential time with parameter
 $q>0$
independent of X.
Corollary 3.2. Let X be a spectrally negative Lévy process. Let
 $q>0$
and
 $\alpha \in \mathbb{R}$
,
 $\beta \geq 0$
such that
 $q>\psi(\beta) \vee (\psi(\beta)-\alpha)$
. We have that for all
 $(u,x)\in E$
,
 \begin{align}\mathbb{E}_{u,x}&\left( \mathrm{e}^{-\alpha U_{\mathbf{e} _q}+\beta X_{\mathbf{e} _q} } \right)\nonumber\\&=\frac{q\mathrm{e}^{\beta x}}{q-\psi(\beta)}+\mathrm{e}^{\Phi(q) x }\Phi'(q)\left[ \frac{q}{\Phi(q+\alpha)-\beta}-\frac{q}{\Phi(q)-\beta}\right]\nonumber\\&\qquad +\mathrm{e}^{\beta x}q \int_0^{x} \mathrm{e}^{-\beta y} [W^{(q)}(y)-\mathrm{e}^{-\alpha u} W^{(q+\alpha)}(y) ]\rm{d} y \nonumber\\&\qquad + \frac{q}{\Phi(q+\alpha)-\beta} \left[\mathrm{e}^{-\alpha u} W^{(q+\alpha)}(x)-W^{(q)}(x)\right].\end{align}
Proof. Consider the function
 $K(u,x)=\mathrm{e}^{-\alpha u +\beta x}$
for all
 $(u,x)\in E$
. We have that K is a continuous function and
 $K(u,x)\leq \mathrm{e}^{-(\alpha \wedge 0) u+\beta x}$
for all
 $(u,x)\in E$
. Taking
 $q>0$
such that
 $q> \psi(\beta)\vee (\psi(\beta)-\alpha)=\psi(\beta)-(\alpha \wedge 0)$
, we see that
 \begin{align*}\mathbb{E}_x\left(\int_0^{\infty} \mathrm{e}^{-qr} \mathrm{e}^{-(\alpha \wedge 0) (u+r) +\beta X_r} \rm{d} r \right)&= \mathrm{e}^{\beta x-(\alpha \wedge 0)u}\int_0^{\infty}\mathrm{e}^{-(q+(\alpha \wedge 0)-\psi(\beta))r} \rm{d} r\\&=\frac{\mathrm{e}^{\beta x-(\alpha \wedge 0)u}}{ q+(\alpha \wedge 0)-\psi(\beta)}<\infty,\end{align*}
for all
 $u\geq 0$
and
 $x\in \mathbb{R}$
. Then for all
 $u> 0$
and
 $x> 0$
we have, by Fubini’s theorem and from equation (2.11), that
 \begin{align*}K^+(u,x)&=\mathbb{E}_x\left( \int_0^{\tau_0^-}\mathrm{e}^{-qr}\mathrm{e}^{-\alpha (u+r)+\beta X_r}\rm{d} r \right)\\&=\mathrm{e}^{-\alpha u} \int_{(0,\infty)} \mathrm{e}^{\beta y}\int_0^{\infty} \mathrm{e}^{-(q+\alpha) r} \mathbb{P}_x(X_r\in \rm{d} y ,r<\tau_0^- )\rm{d} r \\&=\mathrm{e}^{-\alpha u} \int_{0}^{\infty} \mathrm{e}^{\beta y}\left[ \mathrm{e}^{-\Phi(q+\alpha) y}W^{(q+\alpha)}(x)-W^{(q+\alpha)}(x-y) \right] \rm{d} y \\&= \frac{\mathrm{e}^{-\alpha u} W^{(q+\alpha)}(x)}{\Phi(q+\alpha)-\beta}-\mathrm{e}^{-\alpha u}\mathrm{e}^{\beta x} \int_0^{x} \mathrm{e}^{-\beta y} W^{(q+\alpha)}(y) \rm{d} y.\end{align*}
Similarly, we calculate for any
 $x\in \mathbb{R}$
,
 \begin{align*}\int_{-\infty}^{0}\mathrm{e}^{\beta y}\left[\mathrm{e}^{\Phi(q) (x-y)}\Phi'(q) -W^{(q)}(x-y)\right] \rm{d} y& = \Phi'(q)\mathrm{e}^{\Phi(q)x} \int_0^{\infty}\mathrm{e}^{-(\beta -\Phi(q))y }\rm{d} y \nonumber\\&\quad-\mathrm{e}^{\beta x}\int_x^{\infty} \mathrm{e}^{-\beta y}W^{(q)}(y)\rm{d} y \\& = \frac{\Phi'(q)\mathrm{e}^{\Phi(q)x}}{\beta -\Phi(q)}-\frac{\mathrm{e}^{\beta x}}{\psi(\beta)-q} \nonumber\\&\quad+\mathrm{e}^{\beta x}\int_0^x \mathrm{e}^{-\beta y}W^{(q)}(y)\rm{d} y,\end{align*}
where the last equality follows from equation (2.3) and the last integral is understood as 0 when
 $x<0$
. Then from (3.7) we get that for all
 $(u,x)\in E$
,
 \begin{align*}&\mathbb{E}_{u,x}\left(\int_0^{\infty}\mathrm{e}^{-qr} \mathrm{e}^{-\alpha U_{r}+\beta X_{r} }\rm{d} r \right)\\&\quad=\frac{\mathrm{e}^{-\alpha u} W^{(q+\alpha)}(x)}{\Phi(q+\alpha)-\beta}-\mathrm{e}^{-\alpha u}\mathrm{e}^{\beta x} \int_0^{x} \mathrm{e}^{-\beta y} W^{(q+\alpha)}(y) \rm{d} y +\frac{\Phi'(q)\mathrm{e}^{\Phi(q)x}}{\beta -\Phi(q)}-\frac{\mathrm{e}^{\beta x}}{\psi(\beta)-q} \nonumber\\&\qquad +\mathrm{e}^{\beta x}\int_0^x \mathrm{e}^{-\beta y}W^{(q)}(y)\rm{d} y \\&\qquad +\mathrm{e}^{\Phi(q)x}\mathcal{I}^{(q,\Phi(q))}(x)\lim_{\varepsilon \downarrow 0 } \frac{ 1}{\psi'(\Phi(q)+) W^{(q)}(\varepsilon)} \left[\frac{ W^{(q+\alpha)}(\varepsilon)}{\Phi(q+\alpha)-\beta}-\mathrm{e}^{\beta \varepsilon} \int_0^{\varepsilon} \mathrm{e}^{-\beta y} W^{(q+\alpha)}(y) \rm{d} y \right]\\&\quad=\frac{\mathrm{e}^{-\alpha u} W^{(q+\alpha)}(x)}{\Phi(q+\alpha)-\beta}-\mathrm{e}^{-\alpha u}\mathrm{e}^{\beta x} \int_0^{x} \mathrm{e}^{-\beta y} W^{(q+\alpha)}(y) \rm{d} y +\frac{\Phi'(q)\mathrm{e}^{\Phi(q)x}}{\beta -\Phi(q)}-\frac{\mathrm{e}^{\beta x}}{\psi(\beta)-q}\nonumber\\&\qquad+\mathrm{e}^{\beta x}\int_0^x \mathrm{e}^{-\beta y}W^{(q)}(y)\rm{d} y +\mathrm{e}^{\Phi(q)x} \left[ 1-\psi'(\Phi(q)+) \mathrm{e}^{-\Phi(q) x}W^{(q)}(x) \right] \frac{\Phi'(q)}{\Phi(q+\alpha)-\beta},\end{align*}
where in the last equality we used the fact that
 $\Phi'(q)=1/\psi'(\Phi(q)+)$
,
 $W^{(q)}{(x)}$
is non-negative and strictly increasing on
 $[0,\infty)$
for all
 $q\geq 0$
, and that
 \begin{align*}\lim_{\varepsilon \downarrow 0} \frac{W^{(q+\alpha)}(\varepsilon)}{W^{(q)}(\varepsilon)}=1.\end{align*}
The latter fact follows from the representation
 $W^{(q)}(x)=\sum_{k=0}^{\infty}q^k W^{*(k+1)}(x)$
and the estimate
 $W^{*(k+1)}(x)\leq x^k/k! W(x)^{k+1}$
(see equations (8.28) and (8.29) in [Reference Kyprianou29, pp.241--242]. Rearranging the terms and using that
 \begin{align*}\mathbb{E}_{u,x}\left( \mathrm{e}^{-\alpha U_{\mathbf{e} _q}+\beta X_{\mathbf{e} _q} } \right)=q\mathbb{E}_{u,x}\left(\int_0^{\infty}\mathrm{e}^{-qr} \mathrm{e}^{-\alpha U_{r}+\beta X_{r} }\rm{d} r \right),\end{align*}
for all
 $(u,x)\in E$
, we obtain the desired result.
Remark 3.4. Note that from formula (3.9) we can recover some known expressions for spectrally negative Lévy processes. If we take
 $\alpha=0$
, we obtain, for all
 $\beta \geq 0$
,
 $q>\psi(\beta)\vee 0$
and
 $x\in \mathbb{R}$
, that
 \begin{align*}\mathbb{E}_x(\mathrm{e}^{\beta X_{\mathbf{e} _q}})=\frac{q \mathrm{e}^{\beta x}}{q-\psi(\beta)}.\end{align*}
On the other hand, for any
 $\theta\geq 0$
,
 $q\geq 0$
and
 $x\in \mathbb{R}$
we have that
 \begin{align*}\mathbb{E}_x(\mathrm{e}^{-\theta g_{\mathbf{e} _q}})=\int_0^{\infty}q\mathrm{e}^{-qt} \mathbb{E}_x(\mathrm{e}^{-\theta g_t})\rm{d} t=\int_0^{\infty}q\mathrm{e}^{-(q+\theta)t} \mathbb{E}_x(\mathrm{e}^{\theta U_t})\rm{d} t =\frac{q}{q+\theta} \mathbb{E}_x(\mathrm{e}^{\theta U_{\mathbf{e} _{q+\theta}}}),\end{align*}
where
 $\mathbf{e} _{q+\theta}$
is an exponential random variable with parameter
 $q+\theta$
. The result coincides with that found in [Reference Baurdoux5] (see Theorem 2).
Let
 $q>0$
, we consider the q-potential measure of (U, X) given by
 \begin{align*}\int_0^{\infty} \mathrm{e}^{-qr }\mathbb{P}_{u,x}(U_r \in \rm{d} v, X_r \in \rm{d} y) \rm{d} r\end{align*}
for
 $(u,x),(v, y)\in E$
. From the fact that
 $U_t=0$
if and only if
 $X_t\leq 0$
for any
 $t>0$
, we have that for
 $(u,x)\in E$
and
 $y\leq 0$
,
 \begin{align*}\int_0^{\infty} \mathrm{e}^{-qr }\mathbb{P}_{u,x}(U_r =0, X_r \in \rm{d} y) \rm{d} r=\int_0^{\infty} \mathrm{e}^{-qr }\mathbb{P}_{x}( X_r \in \rm{d} y) \rm{d} r.\end{align*}
In the next corollary, we find an expression for a density when
 $v,x>0$
.
Corollary 3.3. Let X be a spectrally negative Lévy process and
 $q>0$
. The q-potential measure of (U,X) has density given by
 \begin{align}\int_0^{\infty} \mathrm{e}^{-qr }\mathbb{P}_{u,x}(U_r \in \rm{d} v, X_r \in \rm{d} y) \rm{d} r&=\mathrm{e}^{-q(v-u)}\mathbb{P}_x(X_{v-u} \in \rm{d} y, v-u<\tau_0^-) \mathbb{I}_{\{v> u \}} \rm{d} v\nonumber\\&\qquad +\left[\mathrm{e}^{\Phi(q) x}\Phi'(q)-W^{(q)}(x) \right] \frac{y}{v} \mathrm{e}^{-qv}\mathbb{P}(X_{v} \in \rm{d} y) \rm{d} v\end{align}
for all
 $(u,x)\in E$
and
 $v,y>0$
. In particular, when
 $u=x=0$
we have that
 \begin{align*}\int_0^{\infty} \mathrm{e}^{-qr }\mathbb{P}(U_r \in \rm{d} v, X_r \in \rm{d} y) \rm{d} r&=\Phi'(q) \frac{y}{v} \mathrm{e}^{-qv}\mathbb{P}(X_{v} \in \rm{d} y) \rm{d} v.\end{align*}
Proof. Let
 $0<u_1<u_2$
and
 $0<x_1<x_2$
and define the sets
 $A=(u_1,u_2]$
and
 $Y=(x_1,x_2]$
. Then the function
 $K(u,x)=\mathbb{I}_{\{ u\in A, x\in Y \}}$
is left-continuous and bounded from above by
 $C(x)=\mathbb{I}_{\{x\in Y\}}$
. Moreover, we have that for
 $q>0$
and
 $x\in \mathbb{R}$
,
 \begin{align*}\mathbb{E}_x\left(\int_0^{\infty}\mathrm{e}^{-qr} \mathbb{I}_{\{X_r \in Y \}} \rm{d} r \right)<\infty.\end{align*}
First, we calculate for all
 $u,x>0$
such that
 $u<u_1$
,
 \begin{align*}K^+(u,x)=\mathbb{E}_{u,x}\left(\int_0^{\tau_0^-} \mathrm{e}^{-qr}\mathbb{I}_{\{ U_r \in A, X_r \in Y\}} \rm{d} r \right)=\int_{A} \int_{Y} \mathrm{e}^{-q(r-u)}\mathbb{P}_x(X_{r-u} \in \rm{d} y, r-u<\tau_0^-) \rm{d} r.\end{align*}
For every
 $x\leq 0$
we have that
 \begin{align*}K^-(x)= \mathbb{E}_{u,x}\left(\int_0^{\tau_0^+} \mathrm{e}^{-qr}\mathbb{I}_{\{ U_r \in A, X_r \in Y\}} \rm{d} r \right)=0.\end{align*}
Hence, for all
 $(u,x)\in E$
we obtain that
 \begin{align*}\mathbb{E}_{u, x}&\left(\int_0^{\infty} \mathrm{e}^{-qr} \mathbb{I}_{\{U_r \in A, X_r \in Y \}} \rm{d} r \right)\\&=\int_{A} \int_Y \mathrm{e}^{-q(r-u)}\mathbb{P}_x(X_{r-u} \in \rm{d} y, r-u<\tau_0^-) \rm{d} r\\&\qquad + \mathrm{e}^{\Phi(q) x}\left[1-\psi'(\Phi(q)\!+\!) \mathrm{e}^{-\Phi(q) x}W^{(q)}(x) \right] \lim_{\varepsilon \downarrow 0 } \int_{A} \int_Y \frac{\mathrm{e}^{-qr}\mathbb{P}_{\varepsilon}(X_{r} \in \rm{d} y, r<\tau_0^-) }{ \psi'(\Phi(q)+) W^{(q)}(\varepsilon)} \rm{d} r.\end{align*}
We calculate the limit on the right-hand side of the equation above. Denote by
 $\mathbb{P}_{\varepsilon}^{\uparrow}$
the law of X starting from
 $\varepsilon$
conditioned to stay positive. We have, for all
 $x\in \mathbb{R}$
and
 $y>0$
, that
 \begin{align*}\lim_{\varepsilon \downarrow 0 } \int_{A} \int_Y \frac{\mathrm{e}^{-qr}\mathbb{P}_{\varepsilon}(X_{r} \in \rm{d} y, r<\tau_0^-) }{ \psi'(\Phi(q)+) W^{(q)}(\varepsilon)} \rm{d} r&=\lim_{\varepsilon \downarrow 0 } \frac{W(\varepsilon)}{ \psi'(\Phi(q)+) W^{(q)}(\varepsilon)} \int_{A} \int_Y \frac{\mathrm{e}^{-qr}\mathbb{P}^{\uparrow}_{\varepsilon}(X_{r} \in \rm{d} y) }{ W(y)} \rm{d} r \\&=\frac{1}{ \psi'(\Phi(q)+) } \int_{A} \int_Y \frac{\mathrm{e}^{-qr}\mathbb{P}^{\uparrow}(X_{r} \in \rm{d} y) }{ W(y)} \rm{d} r,\end{align*}
where the first equality follows from the definition of
 $\mathbb{P}^{\uparrow}$
(see, for example, Section VII.3, equation (6) in [Reference Bertoin10]) and the last equality follows since
 $\lim_{\varepsilon \downarrow 0} W(\varepsilon)/W^{(q)}(\varepsilon)=1$
and
 $\mathbb{P}_{\varepsilon}^{\uparrow}$
converges to
 $\mathbb{P}^{\uparrow}$
in the sense of finite-dimensional distributions (see Proposition VII.3.14 in [Reference Bertoin10]). Moreover, we have for all
 $y,r>0$
that
 $\mathbb{P}^{\uparrow}(X_r\in \rm{d} y)= yW(y)\mathbb{P}(X_r \in \rm{d} y)/r$
(see Corollary VII.3.16 in [Reference Bertoin10]). Therefore, we obtain for all
 $(u,x)\in E$
that
 \begin{align*}\mathbb{E}_{u,x}\left(\int_0^{\infty} \mathrm{e}^{-qr} \mathbb{I}_{\{U_r \in A, X_r \in Y \}} \rm{d} r \right)&=\int_{A} \int_Y \mathrm{e}^{-q(r-u)}\mathbb{P}_x(X_{r-u} \in \rm{d} y, r-u<\tau_0^-) \rm{d} r\\&\qquad + \left[\Phi'(q) \mathrm{e}^{\Phi(q) x}-W^{(q)}(x) \right] \int_{A} \int_Y \frac{y}{r}\mathrm{e}^{-qr} \mathbb{P}(X_{r} \in \rm{d} y) \rm{d} r,\end{align*}
where we also used the fact that
 $\Phi'(q)=1/\psi'(\Phi(q)\!+\!)$
. The proof is now complete.
Remark 3.5.
Bingham [Reference Bingham12] showed that the q-potential measure of X has a density that is absolutely continuous with respect to the Lebesgue measure. This can be demonstrated by moving the killing barrier on the q-potential measure killed on entering the set
 $(\!-\!\infty,0]$
(see (2.11)) and taking limits. Alternatively, it can be deduced by taking limits on (3.7). Moreover, Corollary 3.3 provides an alternative method for finding the density mentioned above. For this, we use Kendall’s identity (see, for example, Corollary VII.3 in [Reference Bertoin10]) given by
 \begin{align}r\mathbb{P}(\tau_z^+ \in \rm{d} r) \rm{d} z=z\mathbb{P}(X_r \in \rm{d} z) \rm{d} r\end{align}
for all
 $r,z \geq 0$
. Indeed, let
 $u,y>0$
and
 $x\in \mathbb{R}$
; integrating (3.10) with respect to the variable v, we obtain that
 \begin{align*}\int_0^{\infty} \mathrm{e}^{-qr} &\mathbb{P}_x(X_r \in \rm{d} y) \rm{d} r\\&=\int_{(0,\infty)} \int_0^{\infty} \mathrm{e}^{-qr }\mathbb{P}_{u,x}(U_r \in \rm{d} v, X_r \in \rm{d} y) \rm{d} r \\&=\int_0^{\infty}\!\! \mathrm{e}^{-qv}\mathbb{P}_x(X_{v} \in \rm{d} y, v<\tau_0^-) \rm{d} v \!+ \int_0^{\infty}\!\left[\mathrm{e}^{\Phi(q) x}\Phi'(q)-W^{(q)}(x) \right] \frac{y}{v} \mathrm{e}^{-qv}\mathbb{P}(X_{v} \in \rm{d} y) \rm{d} v \\&=[\mathrm{e}^{-\Phi(q) y}W^{(q)}(x) \!-\!W^{(q)}(x-y)] \rm{d} y + \!\left[\mathrm{e}^{\Phi(q) x}\Phi'(q)-W^{(q)}(x) \right] \! \int_0^{\infty}\!\! \mathrm{e}^{-q v} \mathbb{P}(\tau_y^+ \in \rm{d}v)\rm{d} y ,\end{align*}
where the last equality follows from (2.11) and (3.11). Hence, using the formula for the Laplace transform of
 $\tau_y^+$
(see equation (2.2)) we have that
 \begin{align*}\int_0^{\infty} \mathrm{e}^{-qr} \mathbb{P}_x(X_r \in \rm{d} y) \rm{d} r=\left( \mathrm{e}^{\Phi(q) (x-y)}\Phi'(q) -W^{(q)}(x-y)\right) \rm{d} y.\end{align*}
4. Applications to optimal stopping/prediction problems
4.1. Optimal stopping problems
This section uses the results developed in the previous sections to solve a general optimal stopping problem. For the sake of simplicity, we will assume that X is a spectrally negative process with a Gaussian component. That is, we assume that
 $\sigma>0$
. We take
 $r\geq 0$
and let G be a continuous function on E such that
 \begin{align}\mathbb{E}_{u,x}\left(\int_0^{\infty} \mathrm{e}^{-rs}|G(U_s,X_s)|\rm{d} s \right)<\infty\end{align}
for all
 $(u,x)\in E$
. We further assume that there exists a value
 $x_G<0$
such that
 $G(0,x)<0$
for all
 $x<x_G$
with
 $\lim_{x\rightarrow -\infty}G(0,x)<0$
, and
 $G(u,x)\geq 0$
for all
 $(u,x)\in E$
such that
 $x\geq x_G$
. We also assume that the function
 \begin{align*}K^+(u,x)\,:\!=\,\mathbb{E}_x\left(\int_0^{\tau_0^-} \mathrm{e}^{-rs}G(u+s,X_s)\rm{d} s \right)\end{align*}
is
 $C^{1,2}$
on
 $[0,\infty)\times[0,\infty)$
.
We consider the optimal stopping problem
 \begin{align}V(u,x)=\sup_{\tau \in \mathcal{T}} \mathbb{E}_{x,u}\left(\int_0^{\tau}\mathrm{e}^{-rs}G(U_s,X_s)\rm{d} s \right),\end{align}
where
 $\mathcal{T}$
is the set of all stopping times of X. Note that our assumptions suggest that it is never optimal to stop when X is taking positive values, and since G is negative for
 $x<x_G$
, we should stop as soon as X is below a value
 $z^*<x_G$
, for
 $|z^*|$
sufficiently large. The following theorem confirms this notion.
Theorem 4.1. Under the conditions stated above, we have that an optimal stopping time for (4.2) is given by
 \begin{align*}\tau_{z^*}^-=\inf\{t>0\,:\, X_t\leq z^* \},\end{align*}
where
 $z^* \in (\!-\!\infty,0)$
is characterized as the unique solution for z in
 $(\!-\!\infty,0)$
to the equation
 \begin{align*}\int_{(0,\infty)}\int_0^{\infty} G(v, y) \frac{y}{v}\mathrm{e}^{-rv}\mathbb{P}(X_{v} \in \rm{d} y) \rm{d} v+\int_{z}^0 G(0,y) \mathrm{e}^{-\Phi(r) y}\rm{d} y=0.\end{align*}
We have that
 $z^*<x_G$
, where we recall that
 $x_G=\inf\{x\in \mathbb{R}: G(0,x) \geq 0 \}<0$
. Moreover, the value function is given by
 \begin{align*}V(u,x)= K^+(u,x) \!-\!W^{(r)}(x)\!\int_{(0,\infty)}\!\int_0^{\infty} G(v, y) \frac{y}{v}\mathrm{e}^{-rv}\mathbb{P}(X_{v} \in \rm{d} y) \rm{d} v-\int_{z^*}^0 G(0,y)W^{(r)}(x-y) \rm{d} y,\end{align*}
for all
 $(u,x)\in E$
. Furthermore, there is smooth fit at
 $z^*$
, that is,
 $\frac{\partial}{\partial x} V(0,z^*+)=\frac{\partial}{\partial x} V(0,z^*-)$
.
We have the following remark regarding some of the assumptions in Theorem 4.1.
Remark 4.1.
-
(i) Condition (4.1) ensures that the optimal stopping problem is well posed and can be relaxed without affecting our results. If the function K is a bounded function, we see that (4.1) is satisfied whenever
$r>0$
. Moreover, if there exist values
$\alpha > 0$
and
$\beta\geq 0$
such that
$|G(u, x)|\leq \alpha \mathrm{e}^{\beta x}$
, then (4.1) holds whenever
$r>\psi(\beta)$
(see Remark 3.4). -
(ii) The condition imposed on G concerning
$x_G$
ensures that an optimal solution is given in terms of the constant barrier
$z^*\in (\!-\!\infty,0)$
. For instance, if
$G(u,x)\geq 0$
for all
$(u,x)\in E$
, the stopping time
$\tau\equiv \infty$
is always optimal. On the other hand, if we allow that
$G(u,x)<0$
, for some values
$u>0$
and
$x>0$
, the optimal solution may be of the form
$\tau_D=\inf \{t\geq 0: (U_t, X_t)\in D \}$
, where
$D\subset E$
and
$D\cap [(0,\infty)\times (0,\infty)] \neq \emptyset$
, and a more careful analysis needs to be done (see, for example, Section 4.2).


The proof of Theorem 4.1 relies on finding, with the help of the potential measure of (U, X) given in Corollary 3.3, a semi-explicit expression of the function
 $V_z(u,x)=\mathbb{E}_{u,x}\left(\int_0^{\tau_z^-} G(U_s,X_s)\rm{d} s \right)$
, for each
 $z\leq 0$
. Then, due to the properties of the scale functions
 $W^{(r)}$
and applying the version of the Itô formula derived in Theorem 3.1, we see that the two conditions given in Lemma 5.4 are satisfied. The reader should also note that formula (3.7) helped prove that condition (3.4) is satisfied for V. The proof is postponed to Section 5.3.
Motivated by Example 4.1 below, we have the following proposition as an application of Theorem 4.1. Its proof is postponed to Section 5.4.
Proposition 4.1. Let X be any spectrally negative Lévy process with
 $\sigma>0$
. Take
 $\beta \geq 0$
,
 $K\in (0,1)$
and
 $r>\psi(1)+\beta$
. We consider the optimal stopping problem
 \begin{align*}V(u,x)&=\sup_{{\tau \in \mathcal{T}}}\mathbb{E}_{u,x}\left( \int_0^{\tau } \mathrm{e}^{-rs}[\mathrm{e}^{X_t +\beta U_s}-K]\rm{d} s \right),\quad (u,x)\in E.\end{align*}
Then the stopping time
 \begin{align*}\tau_{z^*}^-=\inf\{t>0\colon X_t\leq z^* \}\end{align*}
is an optimal stopping time, where
 $z^*$
is the unique solution on
 $(\!-\!\infty,0)$
to the equation
 \begin{align}\frac{\mathrm{e}^{-(\Phi(r)-1)z}}{\Phi(r)-1}-\frac{K\mathrm{e}^{-\Phi(r)z}}{\Phi(r)}+\frac{1}{\Phi(r-\beta)-1}-\frac{1}{\Phi(r)-1}=0.\end{align}
Moreover, the value function takes the form
 \begin{align*}V(u,x)&= \mathrm{e}^{\beta u} \left[ \frac{W^{(r-\beta)}(x)}{\Phi(r-\beta)-1} -\int_0^x \mathrm{e}^y W^{(r-\beta)}(x-y)\rm{d} y \right] +K\int_0^xW^{(r)}(y)\rm{d} y-\frac{K}{\Phi(r)}W^{(r)}(x)\\&\qquad-W^{(r)}(x)\left[\frac{1}{\Phi(r-\beta)-1}-\frac{K}{\Phi(r)} \right]-\int_{z^*}^0 [\mathrm{e}^{y}-K]W^{(r)}(x-y) \rm{d} y\end{align*}
for every
 $(u,x)\in E$
.
We have the following remark on the above proposition regarding some particular cases and how our results match the current literature.
Remark 4.2.
-
(i) Here, it can be checked that the value function satisfies the condition
$\frac{\partial V}{\partial x }(u,0\!+\!)=\frac{\partial V}{\partial x} V(u,0\!-\!)$
only for the case
$u=0$
. -
(ii) Note that when
$\beta=0$
, we see from (4.3) that the value
$z^*$
takes the form Moreover, when Y is a geometric Brownian motion with mean m and volatility
\begin{align*}z^*=\log\left( \frac{\Phi(r)-1}{\Phi(r)}K\right).\end{align*}
$\sigma>0$
(that is,
$\mu=m-\sigma^2/2$
and
$\Pi\equiv 0$
), we recover the value of
$z^*$
, when
$r>m$
, found in [Reference Leland32] (see also Section III.C in [Reference Quah and Strulovici40]). Indeed, in this case we have that for any
$q\geq 0$
, An easy calculation shows that
\begin{align*}\Phi(q)=\frac{1}{\sigma^2 }\left( \sqrt{\mu^2+2q\sigma^2}-\mu \right).\end{align*}
where for any
\begin{align*}z^*=\log\left( \frac{\xi(r)}{\xi(r)+1}\left(1-\frac{m}{r}\right)K\right),\end{align*}
$q\geq 0$
,
\begin{align*}\xi(q)=\frac{1}{\sigma^2 }\left( \sqrt{\mu^2+2q\sigma^2}+\mu \right).\end{align*}


We then present a setting where the result above becomes relevant.
Example 4.1. Following the model of corporate bankruptcy in [Reference Leland32] and [Reference Manso, Strulovici and Tchistyi33] (see also Section III.C in [Reference Quah and Strulovici40]), we consider that equity holders endogenously choose the bankruptcy time. Suppose that the performance of a firm
Footnote
1
at time
 $t\geq 0$
is given by
 $Y_t=\exp(X_t)$
, where X is a spectrally negative Lévy process such that
 $\sigma > 0$
. The performance measure
 $Y_t$
is normalized such that the values above the level 1 are considered good company performance, whereas values below 1 indicate a negative rating. Then we consider, for
 $t\geq 0$
,
 $V_t=t-\sup\{0\leq s\leq t\,:\, Y_s\leq 1 \}=t-U_t$
, the length of time since the last time the company performed poorly. Large values of
 $V_t$
can be interpreted as the firm’s financial stability.
Suppose that, until bankruptcy, the firm must pay a coupon rate c(v, y) to debt holders and receive a payout rate
 $\delta(v, y)$
in terms of the performance y and v, the current excursion above the level 1. Then the time of bankruptcy is determined by the optimal stopping problem
 \begin{align}V(u,x)&=\sup_{{\tau \in \mathcal{T}}}\mathbb{E}_{u,x}\left( \int_0^{\tau } \mathrm{e}^{-rs}[\delta(U_s,\mathrm{e}^{X_t})-c(U_s,\mathrm{e}^{X_t})]\rm{d} s \right),\end{align}
where
 $r\geq 0$
is the risk-free interest rate. Note that if
 $\delta(U_s,\mathrm{e}^{X_s})$
is lower than
 $c(U_s,\mathrm{e}^{X_s})$
, equity holders have a negative dividend rate. Then the firm will keep operating with a negative dividend rate if the firm’s prospects are good enough to compensate for the negative losses. Otherwise, the firm will stop operations, and bankruptcy will be declared.
We then see from Proposition 4.1 that, upon taking
 $\delta(v, y)=y\mathrm{e}^{\beta v}$
and
 $c(v, y)=K$
in (4.4), with K,
 $\beta$
and r as in Proposition 4.1, we conclude that the bankruptcy of the company occurs when
 $Y_t=\exp(X_t)$
crosses below the level
 $\mathrm{e}^{z^*}$
.
4.2. Optimal prediction problems
Let X be a stochastic process with state space in
 $\mathbb{R}$
and let
 $\theta$
be a last passage time of X, that is,
 $\theta =\sup\{t\geq 0: X_t\in A \}$
, where
 $A\subset \mathbb{R}$
. The recent literature has solved the problem of finding a stopping time approximating a specific last passage time. There are, for example, various papers in which the approximation is in the
 $L_1$
sense. That is, the following optimal prediction problem is solved:
 \begin{align}\inf_{\tau \in \mathcal{T}} \mathbb{E}(|\tau-\theta|).\end{align}
To mention a few: [Reference du Toit, Peskir and Shiryaev19] predicted the last zero of a Brownian motion with drift in a finite horizon setting; [Reference du Toit and Peskir18] predicted the time when the ultimate maximum at time
 $t=1$
is attained for a Brownian motion with drift; [Reference Shiryaev45] focused on the last time of the attainment of the ultimate maximum of a Brownian motion and proceeded to show that it is equivalent to predicting the last zero of the process in this setting; [Reference Glover, Hulley and Peskir21] predicted the time when a transient diffusion attains its ultimate minimum; [Reference Glover and Hulley20] predicted the last passage time of a level
 $z > 0$
for an arbitrary nonnegative time-homogeneous transient diffusion; [Reference Baurdoux and Van Schaik9] predicted the time at which a Lévy process attains its ultimate supremum; [Reference Baurdoux, Kyprianou and Ott6] predicted when a positive self-similar Markov process attains its path-wise global supremum or infimum before hitting zero for the first time; and [Reference Baurdoux and Pedraza7] predicted the last zero of a spectrally negative Lévy process.
From here onwards, consider X to be a spectrally negative Lévy process that drifts to infinity and let
 $g=\sup\{ t\geq 0\,:\, X_t\leq 0\}$
, the last zero of X. The problem (4.5) can be generalized to any convex function
 $d\,:\,\mathbb{R}_+ \times \mathbb{R}_+ \mapsto \mathbb{R}_+$
. That is, under the assumption that
 $\mathbb{E}(d(0,g))<\infty$
, consider the optimal prediction problem
 \begin{align}V_d=\inf_{\tau \in \mathcal{T}} \mathbb{E}(d(\tau,g)).\end{align}
As is in the case for problem (4.5), problem (4.6) cannot be solved using standard techniques of optimal stopping (cf. [Reference Peskir and Shiryaev38]) since the random variable g depends on the whole path of the process X and hence is only
 $\mathcal{F}$
measurable. However, the following lemma provides an equivalence between the optimal prediction problem above and an optimal stopping problem driven by the process
 $\{(g_t,t, X_t),t\geq 0\}$
.
Lemma 4.1. Let X be a spectrally negative Lévy process drifting to infinity and
 $d\,:\,\mathbb{R}_+ \times \mathbb{R}_+ \mapsto \mathbb{R}_+$
a convex function such that
 $\mathbb{E}(d(0,g))<\infty$
. We have for each
 $\tau \in \mathcal{T}$
,
 \begin{align*}\mathbb{E}(d(\tau,g))&=\mathbb{E}\left( \int_0^{\tau} G_d(g_s,s,X_s) \rm{d} s+d(0,g)\right),\end{align*}
where
 $G_d(\gamma,s,x)=\frac{\partial }{\partial x} d_+(s,\gamma)\psi'(0\!+\!)W(x)+\mathbb{E}_{x}\frac{\partial }{\partial x} d_+(s,g+s) \mathbb{I}_{\{g>0\}})$
and
 $\frac{\partial }{\partial x} d_+$
is the right-derivative with respect to the first argument of d.
Proof. Let
 $\tau \in \mathcal{T}$
. Using the integral representation of convex functions, we obtain that
 \begin{align*}\mathbb{E}(d(\tau,g))&=\mathbb{E}\left( \int_0^{\tau} \frac{\partial }{\partial x} d_+(s,g)\rm{d} s+d(0,g)\right),\end{align*}
where
 $\frac{\partial }{\partial x} d_+$
is the right-derivative of d with respect to its first coordinate. Then, using Fubini’s theorem and the tower property for conditional expectation, we see that
 \begin{align*}\mathbb{E}\left( \int_0^{\tau} \frac{\partial }{\partial x} d_+(s,g)\rm{d} s\right)&= \int_0^{\infty} \mathbb{E}\left[\mathbb{I}_{\{ s\leq \tau\}} \mathbb{E}\left( \frac{\partial }{\partial x} d_+(s,g) \bigg|\mathcal{F}_s\right) \rm{d} s\right] \\&=\mathbb{E}\left[\int_0^{\tau} \mathbb{E}\left( \frac{\partial }{\partial x} d_+(s,g) \bigg|\mathcal{F}_s\right) \rm{d} s \right]. \\\end{align*}
Hence, we proceed to find an expression for the conditional expectation inside the last integral. From the strong Markov property of the process
 $\{(g_t,t,X_t),t\geq 0\}$
we have that
 \begin{align*}\mathbb{E}\left( \frac{\partial }{\partial x} d_+(s,g) \bigg|\mathcal{F}_s\right)&=\mathbb{E}_{g_s,s,X_s} \left( \frac{\partial }{\partial x} d_+(s,g)\right).\end{align*}
From (3.2), we have that for
 $(\gamma,s,x)\in E_g$
,
 \begin{align*}\mathbb{E}_{\gamma,s,x} \left( \frac{\partial }{\partial x} d_+(s,g)\right)&=\mathbb{E}_{x} \left( \frac{\partial }{\partial x} d_+(s,\gamma)\mathbb{I}_{\{\tau_0^-=\infty \}}\right)+\mathbb{E}_{x} \left( \frac{\partial }{\partial x} d_+(s,g+s)\mathbb{I}_{\{\tau_0^-<\infty \}}\right)\\&=\frac{\partial }{\partial x} d_+(s,\gamma) \psi'(0\!+\!)W(x)+\mathbb{E}_x\left(\frac{\partial }{\partial x} d_+(s,g+s)\mathbb{I}_{\{ g>0\}}\right)\\&=G_d(\gamma,s,x).\end{align*}
Thus, for any
 $s\geq 0$
,
 \begin{align*}\mathbb{E}\left( \frac{\partial }{\partial x} d_+(s,g) \bigg|\mathcal{F}_s\right)=G_d(g_s,s,X_s).\end{align*}
The result then follows.
The lemma above directly implies that solving the optimal prediction problem (4.6) is equivalent to solving the optimal stopping problem
 \begin{align}\inf_{\tau \in \mathcal{T}} \mathbb{E}_{\gamma,t,x}\left[ \int_0^{\tau} G_d(g_{s+t},s+t,X_{s+t}) \rm{d} s \right],\end{align}
for each
 $(\gamma,t,x)\in E_g$
. In [Reference Baurdoux and Pedraza8], the case when
 $d(x,y)=|x-y|^p$
with
 $p>1$
is solved, that is, g is approximated by a stopping time using an
 $L_p$
distance. In this case, problem (4.7) reads
 \begin{align}V(u,x)=\inf_{\tau \in \mathcal{T}}\mathbb{E}_{u,x}\left( \int_0^{\tau} G(U_s,X_s)\rm{d} s \right),\end{align}
for
 $(u,x)\in E$
, where
 $G(u,x)=u^{p-1}\psi'(0\!+\!)W(x)-\mathbb{E}_x(g^{p-1})$
. Although in [Reference Baurdoux and Pedraza8] a rather general spectrally negative Lévy process is considered (only integrability conditions on the Lévy measure are imposed), we include here the main results (see Theorem 3.3 in [Reference Baurdoux and Pedraza8]) when X is a Brownian motion with positive drift (with Gaussian coefficient
 $\sigma>0$
). It is shown that an optimal stopping time for (4.8) is given by
 \begin{align*}\tau_D=\inf\{t\geq 0\,:\, X_t\geq b(U_t) \},\end{align*}
where b is a strictly positive, non-increasing and continuous function such that
 $\lim_{u\rightarrow\infty } b(u)=0$
and
 $\lim_{u\downarrow 0}b(u)=\infty$
. Moreover, the function b and the value V(0, 0) are characterized as the only solution to the non-linear equations
 \begin{align*}0&=V(0, 0)\frac{\sigma^2}{2}W'(b(u))+ \mathbb{E}_{b(u)}\left( \int_0^{\tau_0^-} G(u+s,X_s) \mathbb{I}_{\{X_s < b(u+s) \}}\rm{d} s \right),\\0&=V(0, 0)\frac{\sigma^2}{2}W''(0\!+\!)+\frac{\partial}{\partial x} \mathbb{E}_{x}\left( \int_0^{\tau_0^-} G(u+s,X_s) \mathbb{I}_{\{X_s < b(u+s) \}}\rm{d} s \right)\bigg|_{x=0,u=0}\nonumber\\&\qquad+\int_{[0,\infty)} \mathbb{E}_{-u}(g^{p-1}) W(\rm{d} u),\end{align*}
where b is considered in the class of continuous functions bounded by below by
 $h(u)\,:\!=\,\inf\{x\geq 0\,:\, G(u,x)\geq 0 \}$
and
 $V(0, 0)<0$
.
Note that properties of the stochastic process (U, X) were needed to derive the above result. For instance, the Markov property of (U, X) is crucial to solving the optimal stopping problem (4.8) using the standard theory of optimal stopping. Moreover, the explicit version of the infinitesimal generator (3.6) and formula (3.7) played a crucial role in deriving the non-linear equations presented above. In particular, given the unusual shape of the set E, (3.7) gives us a method to show that there is smooth pasting at the point (0, 0) for the function V, which allowed us to propose a characterization of the value V(0, 0).
5. Main proofs
This section is dedicated to presenting the main proofs of this paper. We start with the proof of Proposition 3.1.
5.1. Proof of Proposition 3.1
From the definition of
 $g_t$
, it is easy to note that for all
 $t\geq 0$
, we have
 $X_t \leq 0$
if and only if
 $g_t=t$
, from which we obtain that
 $(g_t,t, X_t)$
can take only values in
 $E_g$
. We now proceed to show the strong Markov property holds. Consider a measurable positive function
 $h: E_g \mapsto \mathbb{R}$
. Then we have for any stopping time
 $\tau$
and
 $s\geq 0$
,
 \begin{align*}\mathbb{E}( h(g_{\tau+s},\tau+s,X_{\tau+s})|\mathcal{F}_{\tau})&=\mathbb{E}(h(g_{\tau} \vee \sup\{ r\in [\tau,s+\tau]\,:\, X_{r} \leq 0 \},\tau+s,X_{\tau+s} )|\mathcal{F}_{\tau})\\&=\mathbb{E}( h(g_{\tau} \vee \sup\{ r\in [\tau,s+\tau]\,:\, \widetilde{X}_{r-\tau}+X_{\tau} \leq 0 \},\tau+s,\widetilde{X}_s+X_{\tau} )|\mathcal{F}_{\tau}),\end{align*}
where
 $\widetilde{X}_r=X_{r+\tau}-X_{\tau}$
and
 $a\vee b\,:\!=\,\max\{ a,b \}$
for any
 $a,b\in \mathbb{R}$
. Using the strong Markov property for Lévy processes and the fact that
 $g_{\tau}$
and
 $X_{\tau}$
are
 $\mathcal{F}_{\tau}$
measurable, we obtain that
 \begin{align*}\mathbb{E}( h(g_{\tau+s},\tau+s,X_{\tau+s})|\mathcal{F}_{\tau})=f_s(g_{\tau},\tau,X_{\tau}),\end{align*}
where for any
 $x\in \mathbb{R}$
and
 $0\leq \gamma \leq t$
, the function
 $f_s$
is given by
 \begin{align*}f_s(\gamma,t ,x)&=\mathbb{E}_x( h(\gamma \vee \sup\{ r\in [t,s+t]: X_{r-t} \leq 0 \},t+s,X_s )).\end{align*}
Note that, on the event
 $\{\sigma_{0}^->s\}$
, the set
 $\{ r\in [t,s+t]: X_{r-t} \leq 0 \}=\emptyset$
. Then
 $\gamma \vee \sup\{ r\in [t,s+t]\,:\, X_{r-t} \leq 0 \}=\gamma$
, where we used the convention that
 $\sup \emptyset =0$
. Otherwise, in the event
 $\{\sigma_{0}^-\leq s\}$
, we have that
 $\{ r\in [t,s+t]\,:\, X_{r-t} \leq 0 \}\neq \emptyset$
and then
 $\sup\{ r\in [t,s+t]\,:\, X_{r-t} \leq 0 \} \geq t\geq \gamma$
. Hence, we have that, in the event
 $\{\sigma_{0}^-\leq s\}$
,
 \begin{align*}\gamma \vee \sup\{ r\in [t,s+t]\,:\, X_{r-t} \leq 0 \}&=\sup\{ r\in [t,s+t]\,:\, X_{r-t} \leq 0 \}\\&=t+\sup\{ r\in [0,s]\,:\, X_{r} \leq 0 \}\\&=t+g_s.\end{align*}
Therefore, for any
 $x\in \mathbb{R}$
and
 $0\leq \gamma \leq t$
, the function
 $f_s$
takes the form
 \begin{align*}f_s(\gamma,t ,x)&=\mathbb{E}_x(h(\gamma,t+s, X_s)\mathbb{I}_{\{ \sigma_0^->s\}})+\mathbb{E}_x(h(g_s+t,t+s, X_s)\mathbb{I}_{\{ \sigma_0^-\leq s\}}).\end{align*}
On the other hand, similar calculations lead us to
 \begin{align*}\mathbb{E}( h(g_{\tau+s},\tau+s,X_{\tau+s})|\sigma(g_{\tau},\tau,X_{\tau}))=f_s(g_{\tau},\tau,X_{\tau}).\end{align*}
Hence, for any measurable positive function h, we obtain
 \begin{align*}\mathbb{E}( h(g_{\tau+s},\tau+s,X_{\tau+s})|\mathcal{F}_{ \tau})&=\mathbb{E}( h(g_{\tau+s},\tau+s,X_{\tau+s})|\sigma(g_{\tau},\tau,X_{\tau})).\end{align*}
Therefore, we conclude that the process
 $\{ (g_t,t,X_t),t\geq 0 \}$
is a strong Markov process.
5.2. Perturbed Lévy process
Suppose that X is a spectrally negative Lévy process of finite variation. Then, with probability 1, it takes a positive amount of time to cross below 0, that is,
 $\tau_0^->0$
 $\mathbb{P}$
-almost surely. Hence, stopping at the consecutive times at which X is below zero and together with the ideas mentioned in Remark 3.1, we can fully describe the behaviour of
 $g_t$
and then derive the results in Theorems 3.1 and 3.2. However, when X is of infinite variation, it is well known that the closure of the set of zeros of X is perfect and nowhere dense, and the approach mentioned is no longer useful (since we have that
 $\tau_0^-=0$
 $\mathbb{P}$
-almost surely). Therefore, we use a perturbation method to exploit the idea applicable to finite variation processes. This method, which is mainly based on the work of [Reference Dassios and Wu17] and [Reference Revuz and Yor41] (see Theorem VI.1.10), consists of constructing a new ‘perturbed’ process
 $X^{(\varepsilon)}$
(for
 $\varepsilon$
sufficiently small) that approximates X, with the property that
 $X^{(\varepsilon)}$
visits the level zero a finite number of times before any time
 $t\geq 0$
. Then we approximate
 $g_t$
by the corresponding last zero process of
 $X^{(\varepsilon)}$
.
We formally describe the construction of the ‘perturbed’ process
 $X^{(\varepsilon)}$
. Let
 $\varepsilon>0$
, and define the stopping times
 $\rho_{1,\varepsilon}^-=0$
and, for any
 $k \geq 1$
,
 \begin{align*}\rho_{k,\varepsilon}^+&\,:\!=\,\inf\{ t>\rho_{k,\varepsilon}^-\,:\, X_t \geq \varepsilon \},\\\rho_{k+1,\varepsilon}^-&\,:\!=\,\inf\{ t>\rho_{k,\varepsilon}^+\,:\, X_t < 0\},\end{align*}
where we use the usual convention that
 $\inf \emptyset=\infty$
. We define the auxiliary process
 $X^{(\varepsilon)}=\{X_t^{(\varepsilon)} ,t\geq 0 \}$
, where for
 $t\geq 0$
,
 \begin{align}X_t^{(\varepsilon)}=\left\{\begin{array}{l@{\quad}l}X_t-\varepsilon, & \rho_{k,\varepsilon}^-\leq t< \rho_{k,\varepsilon }^+, \\X_t, & \rho_{k,\varepsilon}^+\leq t < \rho_{k+1,\varepsilon }^- . \\\end{array}\right.\end{align}
In Figure 1 we include a sample path of the process
 $X^{(\varepsilon)}$
compared with the original process X.
Left: Sample path of X. Right: Sample path of the perturbed process
 $X^{(\varepsilon)}$
. The vertical lines correspond to the sequence of stopping times
 $\{(\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^+),k\geq 1 \}$
.

It is straightforward from the definition of
 $X^{(\varepsilon)}$
that
 $X_t -\varepsilon \leq X_t^{(\varepsilon)} \leq X_t$
, and that
 $X^{(\varepsilon)} \uparrow X $
uniformly when
 $\varepsilon \downarrow 0$
, that is,
 \begin{align*}\lim_{\varepsilon \downarrow 0} \sup_{t\geq 0} |X_t^{(\varepsilon)}-X_t|=0.\end{align*}
In addition, we define the last zero process
 $g_{\varepsilon,t}$
associated to the process
 $X^{(\varepsilon)}$
, that is,
 \begin{align*}g_{\varepsilon,t}=\sup\{0\leq s\leq t\,:\, X_s^{(\varepsilon)}\leq 0 \}\end{align*}
for
 $\varepsilon>0$
and
 $t\geq 0$
. The inequality
 $g_t\leq g_{\varepsilon,t} \leq g_t^{(\varepsilon)}$
holds for all
 $t\geq 0$
. Taking
 $\varepsilon\downarrow 0$
, and by the right-continuity of
 $x\mapsto g_t^{(x)}$
, we obtain that
 $ g_{\varepsilon,t} \downarrow g_t$
when
 $\varepsilon \downarrow 0$
for all
 $t\geq 0$
. Moreover, we have that
 $t-g_{\varepsilon,t}\,=\!:\,U_{\varepsilon,t} \uparrow U_t$
when
 $\varepsilon \downarrow 0$
for all
 $t\geq 0$
.
Recall that the local time at the level
 $a\in \mathbb{R}$
,
 $L^a=\{L_t^a,t\geq 0 \}$
, is a continuous process defined in terms of the Itô–Tanaka formula (see, for example, Theorem IV.68 on p. 216 in [Reference Protter39] and (2.13)) and its measure
 $\rm{d} L_t^a$
is carried by the set
 $\{s\geq 0: X_{s-}=X_s=a \}$
. For ease of notation, we denote
 $L_t=L_t^0$
for every
 $t\geq 0$
, the local time at the level zero. In this case (see, for example, Corollary IV.1 on p. 219 in [Reference Protter39]), we have that for any bounded and measurable function g,
 \begin{align*}\int_{-\infty}^{\infty} L_t^a g(a)\rm{d} a=\sigma \int_0^t g(X_s) \rm{d} s, \quad \text{almost surely}.\end{align*}
For each
 $\varepsilon>0$
and
 $t\geq 0$
, we define
 \begin{align*}M_t^{(\varepsilon)}=\sum_{k=1}^{\infty} \mathbb{I}_{\{\rho_{k,\varepsilon}^- < t \}}.\end{align*}
Note that
 $M_t^{(\varepsilon)}-1$
is the number of downcrossings of the level zero at time
 $t> 0$
of the process
 $X_t^{(\varepsilon)}$
. It turns out that
 $M_t^{(\varepsilon)}$
works as an approximation of the local time at zero in some sense. We have the following lemma. The proof follows an argument similar to that in [Reference Revuz and Yor41] (see Theorem VI.1.10 on p. 227).
Lemma 5.1. Suppose that X is a spectrally negative Lévy process. Then for all
 $t\geq 0$
,
 \begin{align*}\lim_{\varepsilon \downarrow 0}\varepsilon M_t^{(\varepsilon)} =\frac{1}{2} L_t \quad \textit{in probability}.\end{align*}
Proof. From the Meyer–Itô formula (see, for example, Theorems IV.68 and IV.70 in pp. 216 and 218 in [Reference Protter39]) we know that
 \begin{align*}X_t^+=X_0^++\int_{(0,t]} \mathbb{I}_{\{X_{s-}>0\}}\rm{d} X_s +\int_{(0,t]} \int_{(\!-\!\infty,0)} (X_{s-}+y)^- \mathbb{I}_{\{X_{s-}>0\}} N(\rm{d} s \times \rm{d} y)+\frac{1}{2} L_t,\end{align*}
where
 $x^+$
and
 $x^-$
are the positive and negative part, respectively, of x defined by
 $x^+=\max\{ x,0\}$
and
 $x^-=-\min\{x,0\}$
. Hence, for
 $t\geq 0$
and
 $1 \leq k\leq M_t^{(\varepsilon)}$
we get that
 \begin{align*}X_{\rho_{k,\varepsilon}^+ \wedge t}^+ -X_{\rho_{k,\varepsilon}^-}^+&=\int_{(\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^+\wedge t]} \mathbb{I}_{\{X_{s-}>0\}}\rm{d} X_s +\int_{(\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^+ \wedge t]} \int_{(\!-\!\infty,0)} (X_{s-}+y)^- \mathbb{I}_{\{X_{s-}>0\}} N(\rm{d} s \times \rm{d} y)\\&\qquad +\frac{1}{2} (L_{\rho_{k,\varepsilon}^+ \wedge t}-L_{\rho_{k,\varepsilon}^-}).\end{align*}
From the definition of the stopping times
 $\rho_{k,\varepsilon}^-$
, we have that
 $X_r>0$
when
 $r\in [\rho_{k,\varepsilon}^+, \rho_{k+1,\varepsilon}^-)$
for some
 $k \geq 1$
, and, since L is continuous and only charge points in the set of zeros of X, we have that
 $L_{\rho_{k,\varepsilon}^+}=L_{\rho_{k+1,\varepsilon}^-}$
and
 $L_{t \wedge \rho_{M_t^{(\varepsilon)},\varepsilon}^+}=L_t$
. Hence, using a telescopic sum and the fact that
 $g_{\varepsilon,r-}=r$
if and only if
 $r \in (\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^+]$
, for some
 $k\geq 1$
, we have that
 \begin{align*}X_{t \wedge \rho_{M_t^{(\varepsilon)},\varepsilon}^+}^+ &-X_{\rho_{M_t^{(\varepsilon)},\varepsilon}^-}^+ +\sum_{k=1}^{M_t^{(\varepsilon)}-1} (X_{\rho_{k,\varepsilon}^+}^+ -X_{\rho_{k,\varepsilon}^-}^+ ) \\& =\int_{(0,t]} \mathbb{I}_{\{ g_{\varepsilon,s-}=s\}}\mathbb{I}_{\{X_{s-}\gt 0\}}\rm{d} X_s +\int_{(0,t]} \int_{(\!-\!\infty,0)} (X_{s-}+y)^- \mathbb{I}_{\{g_{\varepsilon,s-}=s\}} \mathbb{I}_{\{X_{s-}\gt 0\}} N(\rm{d} s \times \rm{d} y)\nonumber\\&\qquad+\frac{1}{2} L_t.\end{align*}
Thus, since
 $X_{\rho_{k,\varepsilon}^-}\leq 0$
and
 $X_{\rho_{k,\varepsilon}^+}=\varepsilon$
on the event
 $\{\rho_{k,\varepsilon}^+<\infty \}$
for all
 $k\geq 1$
, we obtain that for any
 $t\geq 0$
and
 $\varepsilon>0$
,
 \begin{align*}X_{t \wedge \rho_{M_t^{(\varepsilon)},\varepsilon}^+}^+ & +\varepsilon (M_t^{(\varepsilon)}-1) \\& =\int_{(0,t]} \mathbb{I}_{\{ g_{\varepsilon,s-}=s\}}\mathbb{I}_{\{X_{s-}\gt 0\}}\rm{d} X_s +\int_{(0,t]} \int_{(\!-\!\infty,0)} (X_{s-}+y)^- \mathbb{I}_{\{ g_{\varepsilon,s-}=s\}} \mathbb{I}_{\{X_{s-}\gt 0\}} N(\rm{d} s \times \rm{d} y)\nonumber\\ &\qquad+\frac{1}{2} L_t.\end{align*}
Note that
 $0\leq X_{t \wedge \rho_{M_t^{(\varepsilon)},\varepsilon}^+}^+ \leq \varepsilon$
and then
 $\lim_{\varepsilon \downarrow 0} X_{t \wedge \rho_{M_t^{(\varepsilon)},\varepsilon}^+}^+=0$
. Moreover, from the inequality
 $g_t\leq g_{\varepsilon,t} \leq g_t^{(\varepsilon)}$
we see that
 \begin{align*}\mathbb{I}_{\{g_{t-}^{(\varepsilon)} < t \}}\leq \mathbb{I}_{\{g_{\varepsilon,t-} < t \}}\leq \mathbb{I}_{\{g_{t-} < t \}}\end{align*}
for any
 $t > 0$
and
 $\varepsilon>0$
. Thus, since
 $g_{t-}^{(\varepsilon)} \downarrow g_{t-}$
when
 $\varepsilon \downarrow 0$
, and the mapping
 $x\mapsto \mathbb{I}_{\{ x < t \}}$
is right-continuous, for fixed
 $t>0$
, we conclude that
 $\lim_{\varepsilon \downarrow 0} \mathbb{I}_{\{g_{\varepsilon,t-} < t \}}=\mathbb{I}_{\{g_{t-} < t \}}$
for all
 $t>0$
. Therefore, from the dominated convergence theorem for stochastic integrals (see, for example, Theorems IV.15 and IV.32 on pp. 166 and 176 in [Reference Protter39]), we have that the first term on the right-hand side of the equation above converges to 0 uniformly on compacts in probability, that is, for all
 $t> 0$
,
 \begin{align*}\sup_{{0\leq s\leq t}} \left|\int_{(0,s]} \mathbb{I}_{\{ g_{\varepsilon,r-}=r\}}\mathbb{I}_{\{X_{r-} > 0\}}\rm{d} X_r \right|\end{align*}
converges to 0 in probability when
 $\varepsilon \downarrow 0$
. Note that, for all
 $s\geq 0$
, we have that
 $(X_{s-}+y)^- \mathbb{I}_{\{ g_{\varepsilon,s-}=s\}} \mathbb{I}_{\{X_{s-}>0\}} \leq (X_{s-}+y)^- \mathbb{I}_{\{X_{s-}>0\}}$
and that
 \begin{align*} \int_{(0,t]} \int_{(\!-\!\infty,0)} (X_{s-}+y)^- \mathbb{I}_{\{X_{s-} > 0\}} N(\rm{d} s \times \rm{d} y) < \infty,\end{align*}
for all
 $t\geq 0$
. Then, by the dominated convergence theorem,
 \begin{align*}\lim_{\varepsilon \downarrow 0}\int_{(0,t]} \int_{(\!-\!\infty,0)} (X_{s-}+y)^- \mathbb{I}_{\{g_{\varepsilon,s-}=s\}} \mathbb{I}_{\{X_{s-}>0\}} N(\rm{d} s \times \rm{d} y)=0,\end{align*}
for any
 $t\geq 0$
. Thus, for fixed
 $t\geq 0$
, we have that
 $\varepsilon M_t^{(\varepsilon)}$
converges to
 $L_t/2$
in probability when
 $\varepsilon \downarrow 0$
.
Remark 5.1. For all
 $\varepsilon>0$
fixed, we can describe the paths of the process
 $\{ g_{\varepsilon,t},t\geq 0\}$
in terms of the stopping times
 $\{ (\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^+),k\geq 1\}$
. When
 $X_{t}^{(\varepsilon)}\leq 0$
we have that
 $\rho_{k,\varepsilon}^- \leq t <\rho_{k,\varepsilon}^+$
, for some
 $k\geq 1$
, and then
 $g_{\varepsilon,t}=t$
. Similarly, when
 $X_t^{(\varepsilon)} > 0$
, there exists
 $k\geq 1$
such that
 $\rho_{k,\varepsilon}^+ \leq t <\rho_{k+1,\varepsilon}^-$
, and hence
 $g_{\varepsilon,t}=\rho_{k,\varepsilon}^+$
. The reader can refer to Figure 1 for a graphical representation of this fact.
We now state the following proposition for stopped processes that will be of use in the proof of Theorem 3.1. We introduce some additional notation: for any
 $-\infty\leq b < a\leq \infty$
and any stopping time
 $\tau$
, we define the stopping time
 \begin{align*}T_{a,b,\tau}=\inf\{t\geq \tau\,:\, X_t\notin [b,a) \}.\end{align*}
We also recall that
 $i=1$
if X is of finite variation and
 $i=2$
when X is of infinite variation.
Proposition 5.1. Suppose that X is any spectrally negative process. Take
 $-\infty\leq b < a\leq \infty$
and define
 $C=[0,\infty)\times (b,a)$
. Let
 $F\,:\,\mathbb{R}_+\times \mathbb{R} \mapsto \mathbb{R}$
be a function such that F is
 $C^{1,i}$
on
 $\bar{C}$
and, if
 $a<\infty$
, we assume that F satisfies
 $\lim_{h \downarrow 0} F(t,a-h)=F(t,a)$
for all
 $t\geq 0$
. Further, if
 $\sigma>0$
and
 $b>-\infty$
, assume that
 $\lim_{h\downarrow 0}F(t,b+h)=F(t,b)$
for all
 $t\geq 0$
. Then, for any stopping time
 $\tau$
and
 $t\geq 0$
, we have
 \begin{align}F(t\wedge T_{a,b,\tau}&,X_{t\wedge T_{a,b,\tau}})\nonumber\\&= F(t\wedge \tau ,X_{t\wedge \tau})+\int_{t\wedge \tau}^{t\wedge T_{a,b,\tau}} \frac{\partial F}{\partial t}(s,X_{s-})\rm{d} s+\int_{(t\wedge \tau, t\wedge T_{a,b,\tau}]} \frac{\partial F}{\partial x} (s,X_{s-})\rm{d} X_s \nonumber\\&\qquad +\!\frac{1}{2}\sigma^2 \int_{t\wedge \tau}^{t\wedge T_{a,b,\tau}} \frac{\partial^2 F}{\partial x^2} (s,X_{s-})\rm{d} s \nonumber\\&\qquad+\!\int_{(t\wedge \tau,t\wedge T_{a,b,\tau}]} \!\int_{(\!-\!\infty,0)}\![F(s,X_{s-}+y)-F(s,X_{s-})-y \frac{\partial F}{\partial x} (s,X_{s-}) ]N(\rm{d} s\times \rm{d} y).\end{align}
Proof. We first note that
 $t\wedge \tau \leq t\wedge T_{a,b,\tau} $
and that the statement trivially holds when
 $t\leq \tau$
or when
 $X_{\tau} \notin [b,a) $
, as
 $T_{a,b,\tau}=\tau$
in the latter case. Moreover, if X is of infinite variation and
 $X_{\tau}=b$
, it can also be easily seen that
 $T_{a,b,\tau}=\tau$
. Further, from the Markov property we see that if
 $a<\infty$
,
 \begin{align*}\mathbb{P}(X_{ T_{a,b,\tau} }>a,X_{\tau}\in [b,a), T_{a,b,\tau}<\infty)=\mathbb{E}\left[\mathbb{I}_{\{X_{\tau}\in [b,a), T_{a,b,\tau}<\infty \}} \mathbb{P}_{X_{\tau} }( X_{ \tau_a^+ \wedge \tau_b^-} >a )\right]=0,\end{align*}
where we used that
 $X_{\tau_a^+}=a$
with probability 1 on the event
 $\{ 0<\tau_a^+ < \infty\}$
and
 $X_{\tau_b^-}\leq b$
on the event
 $\{0<\tau_b^-<\infty \}$
, whenever
 $b>-\infty$
. Moreover, if
 $\sigma=0$
and
 $b>-\infty$
, we deduce by the strong Markov property that
 \begin{align*}\mathbb{P}(X_{ T_{a,b,\tau} }=b,X_{\tau}\in (b,a), T_{a,b,\tau} < \infty)&=\mathbb{E}\left[ \mathbb{I}_{\{X_{\tau}\in (b,a) \}} \mathbb{P}_{X_{\tau} }( X_{ \tau_b^-} =b, \tau_b^- < \tau_a^+ )\right]\\&\leq \mathbb{E}\left[ \mathbb{I}_{\{X_{\tau}\in (b,a) \}} \mathbb{P}_{X_{\tau} }( X_{ \tau_b^-} =b, \tau_b^- < \infty )\right]\\&=0,\end{align*}
where we used that
 $X_{\tau_b^-}=b$
with positive probability, on the event
 $\{0< \tau_b^- < \infty\}$
, only when
 $\sigma>0$
(see (2.8)). Similarly, when X is of finite variation, we can see that
 $\mathbb{P}(X_{ T_{a,b,\tau} }=b, T_{a,b,\tau}<\infty,X_{\tau}=b)=0$
. We define the auxiliary function
 \begin{align*}\widehat{F}(t,x)=\left\{\begin{array}{l@{\quad}l}F(t,a\!-\!),\, & t\geq 0 \text{ and } x\geq a,\\F(t,x),\, & t\geq 0 \text{ and } b < x < a,\\F(t,b\!+\!), \,& t\geq 0 \text{ and } x\leq b.\end{array}\right.\end{align*}
Hence, we have that
 $\widehat{F}$
is continuous on
 $\mathbb{R}_+\times \mathbb{R}$
and is such that
 $\widehat{F}$
is
 $C^{1,i}$
on
 $\bar{C}$
,
 $\widehat{F}$
is
 $C^{1,i}$
on
 $\bar{D}_1$
and
 $\widehat{F}$
is
 $C^{1,i}$
on
 $\bar{D}_2$
, where
 $D_1=[0,\infty)\times (a,\infty)$
and
 $D_2=[0,\infty)\times (\!-\!\infty,b)$
. Using that
 $F(t,a)=F(t,a-)$
and
 $F(t,b+)=F(t,b)$
, when
 $\sigma>0$
, we see that
 \begin{align*}F(t\wedge T_{a,b,\tau},X_{t\wedge T_{a,b,\tau}})&=F(t,X_{t})\mathbb{I}_{\{t < T_{a,b,\tau} \}} +F(T_{a,b,\tau},a)\mathbb{I}_{\{T_{a,b,\tau} \leq t \}}\mathbb{I}_{\{X_{T_{a,b,\tau}} =a \}}\\&\quad +F( T_{a,b,\tau},b)\mathbb{I}_{\{T_{a,b,\tau}\leq t \}}\mathbb{I}_{\{X_{T_{a,b,\tau}}=b \}}\nonumber\\&\quad +F( T_{a,b,\tau},X_{ T_{a,b,\tau}})\mathbb{I}_{\{T_{a,b,\tau}\leq t \}}\mathbb{I}_{\{X_{T_{a,b,\tau}} < b \}}\\&=\widehat{F}(t\wedge T_{a,b,\tau},X_{t\wedge T_{a,b,\tau}})+[F( T_{a,b,\tau},X_{T_{a,b,\tau}})\nonumber\\&\quad -F(T_{a,b,\tau},b+)]\mathbb{I}_{\{T_{a,b,\tau}\leq t \}}\mathbb{I}_{\{X_{T_{a,b,\tau}} < b \}}\\&=\widehat{F}(t\wedge T_{a,b,\tau},X_{t\wedge T_{a,b,\tau}})\\&\quad +\int_{(t\wedge \tau ,t\wedge T_{a,b,\tau}]}\int_{(\!-\!\infty,0)}[F( s,X_{ s-}+y)\nonumber\\&\quad -F(s,b+)]\mathbb{I}_{\{X_{s-}+y \leq b\}} N(\rm{d} s \times \rm{d} y).\end{align*}
Thus, applying the version for multiple curves of formula (2.12) (see Remarks 2.2 and 3.3 in [Reference Peskir37]) at the times
 $t\wedge T_{a,b,\tau}$
and
 $t\wedge \tau$
respectively, upon using that
 $L_{t\wedge T_{a,b,\tau}}^a=L_{t\wedge \tau}^a$
and
 $L_{t\wedge T_{a,b,\tau}}^b=L_{t\wedge \tau}^b$
as the local time is continuous and
 $X_{s-}\in (b,a)$
for
 $s\in ( \tau,t\wedge T_{a,b,\tau})$
when
 $\tau < t$
and
 $\tau < T_{a,b,\tau}$
, we obtain that
 \begin{align*}\widehat{F}&(t\wedge T_{a,b,\tau},X_{t\wedge T_{a,b,\tau}})\\&= \widehat{F}(t\wedge \tau,X_{t\wedge \tau})+\int_{t\wedge \tau}^{t\wedge T_{a,b,\tau}} \frac{\partial \widehat{F}}{\partial t}(s,X_{s-})\rm{d} s+\int_{(t\wedge \tau, t\wedge T_{a,b,\tau}]} \frac{\partial \widehat{F}}{\partial x} (s,X_{s-})\rm{d} X_s\nonumber\\&\quad+\frac{1}{2}\sigma^2 \int_{t\wedge \tau}^{t\wedge T_{a,b,\tau}} \frac{\partial^2 \widehat{F}}{\partial x^2} (s, X_{s-}) \rm{d} s\\&\quad+\int_{(t\wedge \tau,t\wedge T_{a,b,\tau}]} \int_{(\!-\!\infty,0)}[\widehat{F}(s,X_{s-}+y)-\widehat{F}(s,X_{s-})-y \frac{\partial \widehat{F}}{\partial x} (s,X_{s-}) ]N(\rm{d} s\times \rm{d} y)\\&= F(t\wedge \tau,X_{t\wedge\tau})+\int_{t\wedge \tau}^{t\wedge T_{a,b,\tau}} \frac{\partial F}{\partial t}(s,X_{s-})\rm{d} s+\int_{(t\wedge \tau, t\wedge T_{a,b,\tau}]} \frac{\partial F}{\partial x} (s,X_{s-})\rm{d} X_s\nonumber\\&\quad+\frac{1}{2}\sigma^2 \int_{t\wedge \tau}^{t\wedge T_{a,b,\tau}} \frac{\partial^2 F}{\partial x^2} (s, X_{s-}) \rm{d} s\\&\quad+\int_{(t\wedge\tau,t\wedge T_{a,b,\tau}]} \int_{(\!-\!\infty,0)}[F(s,X_{s-}+y)-F(s,X_{s-})-y \frac{\partial F}{\partial x} (s,X_{s-}) ]\mathbb{I}_{\{X_{s-}+y> b \}}N(\rm{d} s\times \rm{d} y)\\&\quad+\int_{(t\wedge\tau,t\wedge T_{a,b,\tau}]} \int_{(\!-\!\infty,0)}[F(s,b+)-F(s,X_{s-})-y \frac{\partial F}{\partial x} (s,X_{s-}) ]\mathbb{I}_{\{ X_{s-}+y\leq b\}}N(\rm{d} s\times \rm{d} y).\end{align*}
Therefore, we obtain the desired result by combining the two equations above.
5.2.1. Proof of Theorem 3.1
We first assume that F and its derivatives are bounded. It is easy to see that for each
 $\varepsilon>0$
we have
 $\sup_{n\geq 0} \rho_{k,\varepsilon}^-=\infty$
. Then, for each
 $t\geq 0$
and
 $\varepsilon>0$
, there exists a value
 $n\geq 1$
such that
 $\rho_{n,\varepsilon}^-\leq t< \rho_{n+1,\varepsilon}^-$
, so that
 $M_{t}^{(\varepsilon)}=n$
. We consider the case when
 $X_t>0$
(we omit the proof of the case when
 $X_t\leq 0$
as it is similar). Then, for any
 $\varepsilon>0$
sufficiently small, there exists a value
 $n\geq 1$
(depending on the value of
 $\varepsilon$
) such that
 $\rho_{n,\varepsilon}^+ \leq t <\rho_{n+1,\varepsilon}^-$
. Note that in this case we have that
 $X_{t}^{(\varepsilon)}>0$
and
 $g_{\varepsilon,t}=\rho_{n,\varepsilon}^+$
. Using a telescopic sum, we obtain that
 \begin{align*}F(g_{\varepsilon,t},t,X_t^{(\varepsilon)})&=F(g_{\varepsilon,0},0,X^{(\varepsilon)}_0+\varepsilon)+\sum_{k=1}^{M_t^{(\varepsilon)}}[ F(g_{\varepsilon,\rho_{k,\varepsilon}^-},\rho_{k,\varepsilon}^-,X^{(\varepsilon)}_{\rho_{k,\varepsilon}^-})-F(g_{\varepsilon,\rho_{k,\varepsilon}^-},\rho_{k,\varepsilon}^-,X^{(\varepsilon)}_{\rho_{k,\varepsilon}^-}+\varepsilon)]\\&\qquad +\sum_{k=1}^{M_t^{(\varepsilon)}}[ F(g_{\varepsilon,\rho_{k,\varepsilon}^+},\rho_{k,\varepsilon}^+,X^{(\varepsilon)}_{\rho_{k,\varepsilon}^+}-\varepsilon)-F(g_{\varepsilon,\rho_{k,\varepsilon}^-},\rho_{k,\varepsilon}^-,X^{(\varepsilon)}_{\rho_{k,\varepsilon}^-})]\\&\qquad +\sum_{k=1}^{M_t^{(\varepsilon)}}[ F(g_{\varepsilon,\rho_{k,\varepsilon}^+},\rho_{k,\varepsilon}^+,X^{(\varepsilon)}_{\rho_{k,\varepsilon}^+})-F(g_{\varepsilon,\rho_{k,\varepsilon}^+},\rho_{k,\varepsilon}^+,X^{(\varepsilon)}_{\rho_{k,\varepsilon}^+}-\varepsilon)]\\&\qquad +\sum_{k=1}^{M_t^{(\varepsilon)}-1}[ F(g_{\varepsilon,\rho_{k+1,\varepsilon}^-},\rho_{k+1,\varepsilon}^-,X^{(\varepsilon)}_{\rho_{k+1,\varepsilon}^-}+\varepsilon)-F(g_{\varepsilon,\rho_{k,\varepsilon}^+},\rho_{k,\varepsilon}^+,X^{(\varepsilon)}_{\rho_{k,\varepsilon}^+})]\\&\qquad+[F(g_{\varepsilon,t},t,X^{(\varepsilon)}_t)-F(g_{\varepsilon,\rho_{M_{t}^{(\varepsilon)},\varepsilon}^+},\rho_{M_{t}^{(\varepsilon)},\varepsilon}^+,X^{(\varepsilon)}_{\rho_{M_{t}^{(\varepsilon)},\varepsilon}^+})].\end{align*}
From Remark 5.1 we know that
 $g_{\varepsilon,\rho_{k,\varepsilon}^-}=\rho_{k,\varepsilon}^- $
and
 $g_{\varepsilon,\rho_{k,\varepsilon}^+}=\rho_{k,\varepsilon}^+$
for all
 $k\geq 1$
. Thus, from the definition of
 $X^{(\varepsilon)}$
(see (5.1)) we see that
 \begin{align}F\big(g_{\varepsilon,t},t,X_t^{(\varepsilon)}\big)&=F\big(g_{\varepsilon,0},0,X^{(\varepsilon)}_0+\varepsilon\big)+\sum_{k=1}^{M_t^{(\varepsilon)}} \left[ F\big(\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^-,X_{\rho_{k,\varepsilon}^-}-\varepsilon \big)-F\big(\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^-,X_{\rho_{k,\varepsilon}^-}\big)\right]\nonumber\\&\qquad +\sum_{k=1}^{M_t^{(\varepsilon)}}[ F(\rho_{k,\varepsilon}^+,\rho_{k,\varepsilon}^+,X_{\rho_{k,\varepsilon}^+}-\varepsilon)-F(\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^-,X_{\rho_{k,\varepsilon}^-}-\varepsilon)]\nonumber\\&\qquad +\sum_{k=1}^{M_t^{(\varepsilon)}}[ F(\rho_{k,\varepsilon}^+,\rho_{k,\varepsilon}^+,X_{\rho_{k,\varepsilon}^+})-F(\rho_{k,\varepsilon}^+,\rho_{k,\varepsilon}^+,X_{\rho_{k,\varepsilon}^+}-\varepsilon)]\nonumber\\&\qquad +\sum_{k=1}^{M_t^{(\varepsilon)}-1}[ F(\rho_{k+1,\varepsilon}^-,\rho_{k+1,\varepsilon}^-,X_{\rho_{k+1,\varepsilon}^-})-F(\rho_{k,\varepsilon}^+,\rho_{k,\varepsilon}^+,X_{\rho_{k,\varepsilon}^+})]\nonumber\\&\qquad+[F(\rho^+_{M_{t}^{(\varepsilon)},\varepsilon},t,X_t)-F(\rho_{M_{t}^{(\varepsilon)},\varepsilon}^+,\rho_{M_{t}^{(\varepsilon)},\varepsilon}^+,X_{\rho_{M_{t}^{(\varepsilon)},\varepsilon}^+})].\end{align}
We first show that the sum of the terms on the second, fourth and last lines on the right-hand side of the equation above converges in probability to the terms on the right-hand side of (3.5).
Lemma 5.2. Under the assumptions of Theorem 3.1 and further assuming that F and its derivatives are bounded, we have that
 \begin{align}\lim_{\varepsilon \downarrow 0}&\bigg[\sum_{k=1}^{M_t^{(\varepsilon)}}[ F(\rho_{k,\varepsilon}^+,\rho_{k,\varepsilon}^+,X_{\rho_{k,\varepsilon}^+}-\varepsilon)-F(\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^-,X_{\rho_{k,\varepsilon}^-}-\varepsilon)]\nonumber\\&\qquad+\sum_{k=1}^{M_t^{(\varepsilon)}-1}[ F(\rho_{k+1,\varepsilon}^-,\rho_{k+1,\varepsilon}^-,X_{\rho_{k+1,\varepsilon}^-})-F(\rho_{k,\varepsilon}^+,\rho_{k,\varepsilon}^+,X_{\rho_{k,\varepsilon}^+})]\nonumber\\&\qquad+[F(\rho^+_{M_{t}^{(\varepsilon)},\varepsilon},t,X_t)-F(\rho_{M_{t}^{(\varepsilon)},\varepsilon}^+,\rho_{M_{t}^{(\varepsilon)},\varepsilon}^+,X_{\rho_{M_{t}^{(\varepsilon)},\varepsilon}^+})]\bigg]\nonumber\\&= \int_{0}^{t} \frac{\partial F_g }{\partial t } (s,X_{s-})\mathbb{I}_{\{g_{s-}=s \}}\rm{d} s+ \int_{0}^{t} \frac{\partial F }{\partial t} (g_{s-},s,X_{s-})\mathbb{I}_{\{ g_{s-} < s\}} \rm{d} s+\int_{0}^{t}\frac{\partial F }{\partial x} (g_{s-},s,X_{s-})\rm{d} X_s \nonumber\\&\qquad+\frac{1}{2} \sigma^2 \int_{0}^{t} \frac{\partial^2 F}{\partial x^2} (g_{s-},s,X_{s-}) \rm{d} s\nonumber\\& \qquad +\!\int_{[0,t] } \int_{(\!-\!\infty,0)} \!\left[ F(s,s,X_{s-}+y) -F(s,s,X_{s-})-y\frac{\partial F }{\partial x} (s,s,X_{s-}) \right]\mathbb{I}_{\{g_{s-}=s \}}N(\rm{d} s\times \rm{d} y)\nonumber\\&\qquad+\int_{[0,t]}\int_{(\!-\!\infty,0)} \left[F(g_{s-},s,X_{s-}+y)-F(g_{s-},s,X_{s-})-y\frac{\partial F }{\partial x} (g_{s-},s,X_{s-})\right]\nonumber\\&\qquad\qquad\qquad \times \mathbb{I}_{\{X_{s-}+y >0 \}}\mathbb{I}_{\{ g_{s-} < s\}} N(\rm{d} s\times \rm{d} y) \nonumber\\&\qquad+ \int_{[0,t]}\int_{(\!-\!\infty,0)} \left[F(s,s,X_{s-}+y)-F(g_{s-},s,X_{s-})-y\frac{\partial F }{\partial x} (g_{s-},s,X_{s-}) \right]\nonumber\\&\qquad\qquad\qquad \times \mathbb{I}_{\{X_{s-}+y \leq 0 \}} \mathbb{I}_{\{ g_{s-} < s\}}N(\rm{d} s\times \rm{d} y)\end{align}
in probability.
Proof. We recall that
 $E_g=\{ (\gamma,t,x) \, :\, 0\leq \gamma < t \text{ and } x>0\}\cup \{ (\gamma,t,x) \,:\, 0 \leq \gamma=t \text{ and } x\leq 0\}$
. We define the auxiliary function
 $\widetilde{F}\,:\,\mathbb{R}_2^+\times \mathbb{R}\mapsto \mathbb{R}$
via
 \begin{align*}\widetilde{F}(\gamma,t,x)=\left\{\begin{array}{l@{\quad}l}F(\gamma,t,x), & (\gamma,t,x)\in \bar{E}_g,\\F(t,t,x), & (\gamma,t,x)\in (\mathbb{R}_2^+\times \mathbb{R}) \setminus \bar{E}_g.\end{array} \right.\end{align*}
Note that, in particular, we have that
 $\widetilde{F}(\gamma,t,x)=F(t,t,x)$
for any
 $\gamma,t\geq 0$
and
 $x\leq 0$
. Hence, since
 $X_{\rho_{k+1,\varepsilon}^-}\leq 0$
for all
 $k\leq M_t^{(\varepsilon)}-1$
, we can write
 \begin{align*}\sum_{k=1}^{M_t^{(\varepsilon)}-1}&\left[ F\left(\rho_{k+1,\varepsilon}^-,\rho_{k+1,\varepsilon}^-,X_{\rho_{k+1,\varepsilon}^-}\right)-F\left(\rho_{k,\varepsilon}^+,\rho_{k,\varepsilon}^+,X_{\rho_{k,\varepsilon}^+}\right)\right] \\&\qquad+\left[F\left(\rho^+_{M_{t}^{(\varepsilon)},\varepsilon},t,X_t\right)-F\left(\rho_{M_{t}^{(\varepsilon)},\varepsilon}^+,\rho_{M_{t}^{(\varepsilon)},\varepsilon}^+,X_{\rho_{M_{t}^{(\varepsilon)},\varepsilon}^+}\right)\right]\\&=\sum_{k=1}^{M_t^{(\varepsilon)}}\left[ \widetilde{F}\left(\rho_{k,\varepsilon}^+,\rho_{k+1,\varepsilon}^- \wedge t,X_{\rho_{k+1,\varepsilon}^- \wedge t}\right)-\widetilde{F}\left(\rho_{k,\varepsilon}^+,\rho_{k,\varepsilon}^+,X_{\rho_{k,\varepsilon}^+}\right)\right].\end{align*}
From the assumptions on F, we see that for fixed
 $\gamma\geq 0$
, the mapping
 $(t,x)\mapsto \widetilde{F}(\gamma,t,x)$
is
 $C^{1,i}$
on
 $[\gamma,\infty)\times [0,\infty)$
. Moreover, if
 $\sigma>0$
, since
 $\lim_{h\downarrow 0} F(\gamma,t,h)=F(t,t,0)$
for all
 $0\leq \gamma \leq t$
, we see that
 $ \lim_{h\downarrow 0} \widetilde{F}(\gamma,t,h)=\widetilde{F}(\gamma,t,0)$
for all
 $\gamma\geq 0$
and
 $t\geq 0$
. Applying Itô's formula (see Proposition 5.1) to
 $s\mapsto \widetilde{F}(\rho_{k,\varepsilon}^+,s , X_{s}) $
on time intervals of the form
 $(\rho_{k,\varepsilon}^+ \wedge t,\rho_{k+1,\varepsilon}^-\wedge t]$
, for each
 $k\leq M_t^{(\varepsilon)}$
, we deduce that
 \begin{align*}&\sum_{k=1}^{M_t^{(\varepsilon)}}[ \widetilde{F}(\rho_{k,\varepsilon}^+,\rho_{k+1,\varepsilon}^- \wedge t,X_{\rho_{k+1,\varepsilon}^- \wedge t})-\widetilde{F}(\rho_{k,\varepsilon}^+,\rho_{k,\varepsilon}^+,X_{\rho_{k,\varepsilon}^+})]\\&=\sum_{k=1}^{M_t^{(\varepsilon)}} \left[ \int_{\rho_{k,\varepsilon}^+}^{\rho_{k+1,\varepsilon}^- \wedge t} \frac{\partial \widetilde{F} }{\partial t} (\rho_{k,\varepsilon}^+,s,X_{s-}) \rm{d} s +\int_{(\rho_{k,\varepsilon}^+,\rho_{k+1,\varepsilon}^- \wedge t]} \frac{\partial \widetilde{F} }{\partial x} (\rho_{k,\varepsilon}^+,s,X_{s-}) \rm{d} X_s \right]\\&\qquad +\sum_{k=1}^{M_t^{(\varepsilon)}} \frac{1}{2}\sigma^2\int_{\rho_{k,\varepsilon}^+}^{\rho_{k+1,\varepsilon}^- \wedge t} \frac{\partial^2 \widetilde{F} }{\partial x^2} (\rho_{k,\varepsilon}^+,s,X_{s-}) \rm{d} s \\&\qquad+\sum_{k=1}^{M_t^{(\varepsilon)}} \int_{(\rho_{k,\varepsilon}^+,\rho_{k+1,\varepsilon}^- \wedge t]} \int_{(\!-\!\infty,0)} \left[\widetilde{F}(\rho_{k,\varepsilon}^+,s,X_{s-}+y)-\widetilde{F}(\rho_{k,\varepsilon}^+,s,X_{s-}) -y\frac{\partial \widetilde{F}}{\partial x} ( \rho_{k,\varepsilon}^+,s,X_{s-}) \right]\\&\qquad\qquad\qquad\times N(\rm{d} s\times \rm{d} y).\end{align*}
From the definition of
 $\widetilde{F}$
and since
 $g_{\varepsilon,s-} < s$
if and only if
 $s\in (\rho_{k,\varepsilon}^+, \rho_{k+1,\varepsilon}^-]$
for some
 $k\geq 1$
(in this case
 $g_{\varepsilon,s-}=\rho_{k,\varepsilon}^+$
and
 $X_{s-}^{(\varepsilon)}=X_{s-}$
), we have that
 \begin{align*}&\sum_{k=1}^{M_t^{(\varepsilon)}}[ \widetilde{F}(\rho_{k,\varepsilon}^+,\rho_{k+1,\varepsilon}^- \wedge t,X_{\rho_{k+1,\varepsilon}^- \wedge t})-\widetilde{F}(\rho_{k,\varepsilon}^+,\rho_{k,\varepsilon}^+,X_{\rho_{k,\varepsilon}^+})]\\&= \int_{0}^{t} \frac{\partial F }{\partial t} (g_{\varepsilon,s-},s,X_{s-}^{(\varepsilon)})\mathbb{I}_{\{ g_{\varepsilon,s-} < s\}} \rm{d} s +\int_{0}^{t} \frac{\partial F }{\partial x} (g_{\varepsilon,s-},s,X_{s-}^{(\varepsilon)})\mathbb{I}_{\{ g_{\varepsilon,s-} < s \}} \rm{d} X_s \\&\qquad + \frac{1}{2}\sigma^2\int_{0}^{t} \frac{\partial^2 F }{\partial x^2} (g_{\varepsilon,s-},s,X_{s-}^{(\varepsilon)})\mathbb{I}_{\{ g_{\varepsilon,s-} < s\}} \rm{d} s \\&\qquad+\int_{[0,t]}\int_{(-\infty,0)} \left[F(g_{\varepsilon,s-},s,X_{s-}^{(\varepsilon)}+y)-F(g_{\varepsilon,s-},s,X_{s-}^{(\varepsilon)})-y\frac{\partial F }{\partial x} (g_{\varepsilon,s-},s,X_{s-}^{(\varepsilon)})\right]\\&\qquad\qquad\qquad \times \mathbb{I}_{\{X_{s-}^{(\varepsilon)}+y >0 \}}\mathbb{I}_{\{ g_{\varepsilon,s-} < s\}} N(\rm{d} s\times \rm{d} y) \\&\qquad+ \int_{[0,t]}\int_{(-\infty,0)} \left[F(s,s,X_{s-}^{(\varepsilon)}+y)-F(g_{\varepsilon,s-},s,X_{s-}^{(\varepsilon)})-y\frac{\partial F }{\partial x} (g_{\varepsilon,s-},s,X_{s-}^{(\varepsilon)}) \right]\\&\qquad\qquad\qquad \times \mathbb{I}_{\{X_{s-}^{(\varepsilon)}+y \leq 0 \}} \mathbb{I}_{\{ g_{\varepsilon,s-}< s\}}N(\rm{d} s\times \rm{d} y).\end{align*}
Similarly, since
 $(t,x)\mapsto F(t,t,x)$
is
 $C^{1,i}$
on
 $[0,\infty)\times (\!-\!\infty,0]$
and F is continuous on
 $E_g$
, we can apply Proposition 5.1 on intervals of the form
 $(\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^+\wedge t]=(\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^+]$
, upon noticing that
 $X_s-\varepsilon\leq 0$
for all
 $s\in (\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^+]$
, to see that
 \begin{align*}&\sum_{k=1}^{M_t^{(\varepsilon)}}[ F(\rho_{k,\varepsilon}^+,\rho_{k,\varepsilon}^+,X_{\rho_{k,\varepsilon}^+}-\varepsilon)-F(\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^-,X_{\rho_{k,\varepsilon}^-}-\varepsilon)]\\&=\sum_{k=1}^{M_t^{(\varepsilon)}}\left[ \int_{\rho_{k,\varepsilon}^-}^{\rho_{k,\varepsilon}^+ } \frac{\partial F_g }{\partial t } (s,X_{s-}-\varepsilon)\rm{d} s+\int_{(\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^+] }\frac{\partial F }{\partial x} (s,s,X_{s-}-\varepsilon)\rm{d} X_s \right.\end{align*}\begin{align*}&\quad \left.+\frac{1}{2} \sigma^2 \int_{\rho_{k,\varepsilon}^-}^{\rho_{k,\varepsilon}^+ } \frac{\partial^2 F}{\partial x^2} (s,s,X_{s-}-\varepsilon)\rm{d} s\right]\\& \quad +\sum_{k=1}^{M_t^{(\varepsilon)}}\int_{(\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^+] } \int_{(\!-\!\infty,0)} \left[ F(s,s,X_{s-}+y-\varepsilon) \vphantom{\frac{\partial F }{\partial x}}\right.\nonumber\\&\quad\left.-F(s,s,X_{s-}-\varepsilon)-y\frac{\partial F }{\partial x} (s,s,X_{s-}-\varepsilon) \right]N(\rm{d} s\times \rm{d} y)\\&= \int_{0}^{t} \frac{\partial F_g }{\partial t } (s,X_{s-}^{(\varepsilon)})\mathbb{I}_{\{g_{\varepsilon,s-}=s \}}\rm{d} s+\int_{0}^{t}\frac{\partial F }{\partial x} (s,s,X_{s-}^{(\varepsilon)})\mathbb{I}_{\{g_{\varepsilon,s-}=s \}}\rm{d} X_s \\&\quad+\frac{1}{2} \sigma^2 \int_{0}^{t} \frac{\partial^2 F}{\partial x^2} (s,s,X_{s-}^{(\varepsilon)}) \mathbb{I}_{\{g_{\varepsilon,s-}=s \}}\rm{d} s\\& \quad +\int_{[0,t] } \int_{(\!-\!\infty,0)} \left[ F(s,s,X_{s-}^{(\varepsilon)}+y) -F(s,s,X_{s-}^{(\varepsilon)})-y\frac{\partial F }{\partial x} (s,s,X_{s-}^{(\varepsilon)}) \right] \mathbb{I}_{\{g_{\varepsilon,s-}=s \}}N(\rm{d} s\times \rm{d} y),\end{align*}
where we recall that
 $F_g(t,x)=F(t,t,x)$
for
 $t\geq 0$
and
 $x\leq 0$
. Therefore, we conclude that
 \begin{align*}&\sum_{k=1}^{M_t^{(\varepsilon)}}[ F(\rho_{k,\varepsilon}^+,\rho_{k,\varepsilon}^+,X_{\rho_{k,\varepsilon}^+}-\varepsilon)-F(\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^-,X_{\rho_{k,\varepsilon}^-}-\varepsilon)]\\&\qquad+\sum_{k=1}^{M_t^{(\varepsilon)}-1}[ F(\rho_{k+1,\varepsilon}^-,\rho_{k+1,\varepsilon}^-,X_{\rho_{k+1,\varepsilon}^-})-F(\rho_{k,\varepsilon}^+,\rho_{k,\varepsilon}^+,X_{\rho_{k,\varepsilon}^+})]\\&\qquad+[F(\rho_{M_{t}^{(\varepsilon)}},t,X_t)-F(\rho_{M_{t}^{(\varepsilon)},\varepsilon}^+,\rho_{M_{t}^{(\varepsilon)},\varepsilon}^+,X_{\rho_{M_{t}^{(\varepsilon)},\varepsilon}^+})]\\&= \int_{0}^{t} \frac{\partial F_g }{\partial t } (s,X_{s-}^{(\varepsilon)})\mathbb{I}_{\{g_{\varepsilon,s-}=s \}}\rm{d} s+ \int_{0}^{t} \frac{\partial F }{\partial t} (g_{\varepsilon,s-},s,X_{s-}^{(\varepsilon)})\mathbb{I}_{\{ g_{\varepsilon,s-} < s\}} \rm{d} s+\int_{0}^{t}\frac{\partial F }{\partial x} (g_{\varepsilon,s-},s,X_{s-}^{(\varepsilon)})\rm{d} X_s \\&\qquad+\frac{1}{2} \sigma^2 \int_{0}^{t} \frac{\partial^2 F}{\partial x^2} (g_{\varepsilon,s-},s,X_{s-}^{(\varepsilon)}) \rm{d} s\\& \qquad +\int_{[0,t] } \int_{(\!-\!\infty,0)} \left[ F(s,s,X_{s-}^{(\varepsilon)}+y) -F(s,s,X_{s-}^{(\varepsilon)})-y\frac{\partial F }{\partial x} (s,s,X_{s-}^{(\varepsilon)}) \right]\mathbb{I}_{\{g_{\varepsilon,s-}=s \}}N(\rm{d} s\times \rm{d} y)\\&\qquad+\int_{[0,t]}\int_{(\!-\!\infty,0)} \left[F(g_{\varepsilon,s-},s,X_{s-}^{(\varepsilon)}+y)-F(g_{\varepsilon,s-},s,X_{s-}^{(\varepsilon)})-y\frac{\partial F }{\partial x} (g_{\varepsilon,s-},s,X_{s-}^{(\varepsilon)})\right]\\&\qquad\qquad\qquad \times \mathbb{I}_{\{X_{s-}^{(\varepsilon)}+y >0 \}}\mathbb{I}_{\{ g_{\varepsilon,s-} < s\}} N(\rm{d} s\times \rm{d} y) \\&\qquad+ \int_{[0,t]}\int_{(\!-\!\infty,0)} \left[F(s,s,X_{s-}^{(\varepsilon)}+y)-F(g_{\varepsilon,s-},s,X_{s-}^{(\varepsilon)})-y\frac{\partial F }{\partial x} (g_{\varepsilon,s-},s,X_{s-}^{(\varepsilon)}) \right]\\&\qquad\qquad\qquad \times \mathbb{I}_{\{X_{s-}^{(\varepsilon)}+y \leq 0 \}} \mathbb{I}_{\{ g_{\varepsilon,s-} < s\}}N(\rm{d} s\times \rm{d} y).\end{align*}
Hence, since we are assuming that F and its derivatives are continuous and bounded, by using the mean value theorem when X is of finite variation, Taylor’s theorem when X is of infinite variation, and the dominated convergence theorem for stochastic integrals (see, for example, Theorems IV.15 and IV.32 on pp. 166 and 176 in [Reference Protter39]) we conclude that (5.4) indeed holds.
Next, to complete the proof of Theorem 3.1, we show the existence of a sequence such that the remaining terms on the right-hand side of (5.3) converge to zero almost surely.
Lemma 5.3 Under the assumptions of Theorem 3.1 and further assuming that F and its derivatives are bounded and that
 $\Pi(\!-\!\infty,0)<\infty$
, we have that there exists a sequence
 $\{ \varepsilon_n, n\geq 0\}$
converging to zero such that
 \begin{align*}\lim_{n\rightarrow\infty}\bigg[\sum_{k=1}^{M_t^{(\varepsilon_n)}}&[ F(\rho_{k,\varepsilon_n}^-,\rho_{k,\varepsilon_n}^-,X_{\rho_{k,\varepsilon_n}^-}-\varepsilon_n)-F(\rho_{k,\varepsilon_n}^-,\rho_{k,\varepsilon_n}^-,X_{\rho_{k,\varepsilon_n}^-})]\\&\qquad +\sum_{k=1}^{M_t^{(\varepsilon_n)}}[ F(\rho_{k,\varepsilon_n}^+,\rho_{k,\varepsilon_n}^+,X_{\rho_{k,\varepsilon_n}^+})-F(\rho_{k,\varepsilon_n}^+,\rho_{k,\varepsilon_n}^+,X_{\rho_{k,\varepsilon_n}^+}-\varepsilon_n)]\bigg] =0\end{align*}
almost surely.
Proof. For any
 $s>0$
and
 $\varepsilon>0$
, we define the stopping time
 \begin{align*}\tau_{\varepsilon,s}^+\,:\!=\,\inf\{ t\geq s\,:\, X_t\geq \varepsilon\}.\end{align*}
By using that
 $\rho_{1,\varepsilon}^-=0$
(by definition), that N is the Poisson random measure of the jumps of X and by rearranging some of the terms, we see that
 \begin{align*}\sum_{k=1}^{M_t^{(\varepsilon)}}&[ F(\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^-,X_{\rho_{k,\varepsilon}^-}-\varepsilon)-F(\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^-,X_{\rho_{k,\varepsilon}^-})] \nonumber\\&\quad+\sum_{k=1}^{M_t^{(\varepsilon)}}[ F(\rho_{k,\varepsilon}^+,\rho_{k,\varepsilon}^+,X_{\rho_{k,\varepsilon}^+})-F(\rho_{k,\varepsilon}^+,\rho_{k,\varepsilon}^+,X_{\rho_{k,\varepsilon}^+}-\varepsilon)] \\&= F(0,0,X_0-\varepsilon)-F(0,0,X_0)+F(\rho_{1,\varepsilon}^+,\rho_{1,\varepsilon}^+,\varepsilon)-F(\rho_{1,\varepsilon}^+,\rho_{1,\varepsilon}^+,0) \\&\quad+\sum_{k=2}^{M_t^{(\varepsilon)}}[ F(\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^-,X_{\rho_{k,\varepsilon}^-}-\varepsilon)-F(\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^-,X_{\rho_{k,\varepsilon}^-})] \mathbb{I}_{\{ X_{\rho_{k,\varepsilon}^-}<0\}}\\&\quad +\sum_{k=2}^{M_t^{(\varepsilon)}}[ F(\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^-,-\varepsilon)-F(\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^-,0)] \mathbb{I}_{\{ X_{\rho_{k,\varepsilon}^-}=0\}}\\&\quad +\sum_{k=2}^{M_t^{(\varepsilon)}}[ F(\rho_{k,\varepsilon}^+,\rho_{k,\varepsilon}^+,\varepsilon)-F(\rho_{k,\varepsilon}^+,\rho_{k,\varepsilon}^+,0)] \mathbb{I}_{\{ X_{\rho_{k,\varepsilon}^-}<0\}}\nonumber\\&\quad+[ F(\rho_{k,\varepsilon}^+,\rho_{k,\varepsilon}^+,\varepsilon)-F(\rho_{k,\varepsilon}^+,\rho_{k,\varepsilon}^+,0)]\mathbb{I}_{\{ X_{\rho_{k,\varepsilon}^-}=0\}}\\&=F(0,0,X_0-\varepsilon)-F(0,0,X_0)+F(\rho_{1,\varepsilon}^+,\rho_{1,\varepsilon}^+,\varepsilon)-F(\rho_{1,\varepsilon}^+,\rho_{1,\varepsilon}^+,0)\\&\quad +\int_{[0,t]} \int_{(\!-\!\infty,0)}[ F(s,s,X_{s-}+y-\varepsilon)-F(s,s,X_{s-}+y)] \mathbb{I}_{\{ X^{(\varepsilon)}_{s-}+y<0\}} \mathbb{I}_{\{ X_{s-}^{(\varepsilon)}>0\}} N(\rm{d} s \times \rm{d} y)\\&\quad +\int_{[0,t]} \int_{(\!-\!\infty,0)}[ F(\tau_{\varepsilon,s}^+,\tau_{\varepsilon,s}^+,\varepsilon)-F(\tau_{\varepsilon,s}^+,\tau_{\varepsilon,s}^+,0)] \mathbb{I}_{\{ X^{(\varepsilon)}_{s-}+y<0\}} \mathbb{I}_{\{ X_{s-}^{(\varepsilon)}>0\}} N(\rm{d} s \times \rm{d} y)\\&\quad +\int_0^t[ F(s,s,-\varepsilon)-F(s,s,0)+ F(\tau_{\varepsilon,s}^+,\tau_{\varepsilon,s}^+,\varepsilon)-F(\tau_{\varepsilon,s}^+,\tau_{\varepsilon,s}^+,0)] \mathbb{I}_{\{ X_{s}=0\}}\rm{d} M_s^{(\varepsilon)}.\end{align*}
We then show that the integrals with respect to the Poisson random measure N converge to zero. Since
 $X_s^{(\varepsilon)}\leq X_{s}$
for all
 $s>0$
, and on the event
 $\{ X_{s-}^{(\varepsilon)}>0 \}$
, we have that
 $X_{s-}^{(\varepsilon)}=X_{s-}$
and we see that
 \begin{align*}&\left|\int_{[0,t]} \int_{(\!-\!\infty,0)}[ F(s,s,X_{s-}+y-\varepsilon)-F(s,s,X_{s-}+y)] \mathbb{I}_{\{ X^{(\varepsilon)}_{s-}+y<0\}} \mathbb{I}_{\{ X_{s-}^{(\varepsilon)}>0\}} N(\rm{d} s \times \rm{d} y)\right|\\&\qquad\leq \int_{[0,t]} \int_{(\!-\!\infty,0)}\left| F(s,s,X_{s-}+y-\varepsilon)-F(s,s,X_{s-}+y)\right|\mathbb{I}_{\{ X^{(\varepsilon)}_{s-}+y<0\}} \mathbb{I}_{\{ X_{s-}^{(\varepsilon)}>0\}} N(\rm{d} s \times \rm{d} y)\\&\qquad\leq 2M\int_{[0,t]} \int_{(\!-\!\infty,0)}\mathbb{I}_{\{ X_{s-}+y<0\}} \mathbb{I}_{\{ X_{s-}>0\}} N(\rm{d} s \times \rm{d} y)\\&\qquad<\infty,\end{align*}
where we used that F is bounded, say, by a constant
 $M>0$
and that
 $\Pi(\!-\!\infty,0)<\infty$
so the last integral is finite. Hence, by the dominated convergence theorem and the continuity of F, we have that
 \begin{align*}\lim_{\varepsilon\downarrow 0}\int_{[0,t]} \int_{(\!-\!\infty,0)}[ F(s,s,X_{s-}+y-\varepsilon)-F(s,s,X_{s-}+y)] \mathbb{I}_{\{ X^{(\varepsilon)}_{s-}+y<0\}} \mathbb{I}_{\{ X_{s-}^{(\varepsilon)}>0\}} N(\rm{d} s \times \rm{d} y)=0\end{align*}
almost surely. Similarly, we can see that
 \begin{align*}\lim_{\varepsilon \downarrow 0}\int_{[0,t]} \int_{(\!-\!\infty,0)}[ F(\tau_{\varepsilon,s}^+,\tau_{\varepsilon,s}^+,\varepsilon)-F(\tau_{\varepsilon,s}^+,\tau_{\varepsilon,s}^+,0)] \mathbb{I}_{\{ X^{(\varepsilon)}_{s-}+y<0\}} \mathbb{I}_{\{ X_{s-}^{(\varepsilon)}>0\}} N(\rm{d} s \times \rm{d} y)=0\end{align*}
almost surely. On the other hand, since we are assuming that
 $x\mapsto F(t,t,x)$
is differentiable on
 $[0,\infty)$
and on
 $(\!-\!\infty,0]$
we have that
 \begin{align*}&\left|\int_0^t[ F(s,s,-\varepsilon)-F(s,s,0)+ F(\tau_{\varepsilon,s}^+,\tau_{\varepsilon,s}^+,\varepsilon)-F(\tau_{\varepsilon,s}^+,\tau_{\varepsilon,s}^+,0)] \mathbb{I}_{\{ X_{s}=0\}}\rm{d} M_s^{(\varepsilon)} \right| \\&\qquad\leq \int_0^t\int_0^{\varepsilon} \left|\frac{\partial F}{\partial x} (\tau_{\varepsilon,s}^+,\tau_{\varepsilon,s}^+,y)-\frac{\partial F}{\partial x}(s,s,-y) \right|\mathbb{I}_{\{ X_{s}=0\}} \rm{d} y \rm{d} M_s^{(\varepsilon)} \\& \qquad \leq \varepsilon ( M_{t}^{(\varepsilon)}-1) \sup\nolimits{_{(s,y)\in [0,t]\times [0,\varepsilon]}}\left\{ \left|\frac{\partial F}{\partial x} (\tau_{\varepsilon,s}^+,\tau_{\varepsilon,s}^+,y)-\frac{\partial F}{\partial x}(s,s,-y) \right|\mathbb{I}_{\{ X_{s}=0\}} \right\}.\end{align*}
Note that X creeps downwards only when
 $\sigma>0$
, so then the first term above vanishes when
 $\sigma=0$
. Henceforth, we assume that
 $\sigma>0$
. From Lemma 5.1 we know that
 $\varepsilon M_t^{(\varepsilon)}$
converges to
 $L_t/2$
in probability when
 $\varepsilon\downarrow 0$
. Hence, there exists a subsequence
 $\{\varepsilon_n,n\geq 0 \}$
convergent to zero such that
 $\varepsilon_n M_t^{(\varepsilon_n)}$
converges to
 $L_t/2$
almost surely. Thus, we see that
 \begin{align*}\lim_{n\rightarrow \infty} &\left|\int_0^t[ F(s,s,-\varepsilon_n)-F(s,s,0)+ F(\tau_{\varepsilon_n,s}^+,\tau_{\varepsilon_n,s}^+,\varepsilon_n)-F(\tau_{\varepsilon_n,s}^+,\tau_{\varepsilon_n,s}^+,0)] \mathbb{I}_{\{ X_{s}=0\}}\rm{d} M_s^{(\varepsilon)} \right|\\& \leq \lim_{n\rightarrow \infty} \varepsilon_n ( M_{t}^{(\varepsilon_n)}-1) \sup\nolimits{_{(s,y)\in [0,t]\times [0,\varepsilon_n]}}\left\{ \left|\frac{\partial F}{\partial x} (\tau_{\varepsilon_n,s}^+,\tau_{\varepsilon_n,s}^+,y)-\frac{\partial F}{\partial x}(s,s,-y) \right|\mathbb{I}_{\{ X_{s}=0\}}\right\}\\&=0\end{align*}
almost surely, where we used that for each
 $s>0$
, on the event
 $\{X_s=0 \}$
, we have
 $\lim_{\varepsilon \downarrow 0} \tau_{\varepsilon,s}^+=s$
almost surely, and that
 $(s,y)\mapsto \frac{\partial F}{\partial x}(s,s,y)$
is continuous in
 $[0,\infty)\times \mathbb{R}$
when
 $\sigma>0$
. Indeed, assumptions (i) and (ii) imply that
 $F(t,t,x)=F_1(t,x)$
for every
 $t\geq 0$
and
 $x> 0$
and
 $F(t,t,x)=F_2(t,x)$
for
 $t\geq 0$
and
 $x<0$
, where
 $F_1$
and
 $F_2$
are some
 $C^{1,1}$
functions on
 $[0,\infty)\times \mathbb{R}$
. Moreover, from the above facts and the mean value theorem we have that for any
 $h>0$
, there exists a value
 $c_h\in (0,h)$
such that
 \begin{align*}\lim_{h\downarrow 0}\frac{F(t,t,h)-F(t,t,0)}{h}=\lim_{h\downarrow 0}\frac{\partial F}{\partial x}(t,t,c_h)=\frac{\partial F}{\partial x} F(t,t,0\!+\!)\end{align*}
for any
 $t\geq 0$
. Similarly,
 \begin{align*}\lim_{h\downarrow 0}\frac{F(t,t,-h)-F(t,t,0)}{-h}=\frac{\partial F}{\partial x} F(t,t,0\!-\!).\end{align*}
Thus, from assumption (3.4), we have that
 $\frac{\partial F}{\partial x}(t,t,0)$
exists for all
 $t\geq 0$
. It follows that
 \begin{align*}\frac{\partial F_1}{\partial x}(t,0)=\frac{\partial F}{\partial x} (t,t,0\!+\!) =\frac{\partial F}{\partial x} (t,t,0)=\frac{\partial F}{\partial x} (t,t,0\!-\!)=\frac{\partial F_2}{\partial x}(t,0)\end{align*}
for all
 $t\geq 0$
. Then we can write
 \begin{align*}\frac{\partial F}{\partial x}F(t,t,x)&=\mathbb{I}_{\{x\geq 0 \}}\frac{\partial F_1}{\partial x}(t,x)+\mathbb{I}_{\{x< 0 \}}\frac{\partial F_2}{\partial x}(t,x)\\&=\mathbb{I}_{\{x> 0 \}}\frac{\partial F_1}{\partial x}(t,x)+\mathbb{I}_{\{x\leq 0 \}}\frac{\partial F_2}{\partial x}(t,x)\end{align*}
for any
 $t\geq 0$
and
 $x\in \mathbb{R}$
. Therefore, from the equation above it can be easily seen that
 $(s,y)\mapsto \frac{\partial F}{\partial x}(s,s,y)$
is continuous in
 $[0,\infty)\times \mathbb{R}$
as claimed. The conclusion holds.
Hence, when
 $\Pi(\!-\!\infty,0)<\infty$
, we deduce that there exists a subsequence
 $\{\varepsilon'_{n}, n\geq 0 \}$
, convergent to zero such that the limits in Lemmas 5.2 and 5.3 hold almost surely. Thus, following an argument similar to that in [Reference Applebaum2] (see proof of Theorem 4.4.7 on p. 226), from (5.3) along the subsequence
 $\{\varepsilon'_{n}, n\geq 0 \}$
and taking
 $n\rightarrow \infty$
, we deduce, when F and its derivatives are bounded, that
 \begin{align*}F(g_{t}, t,X_t)&=F(g_0,0,X_0)+ \int_{0}^{t} \frac{\partial F_g }{\partial t } (s,X_{s-})\mathbb{I}_{\{g_{s-}=s \}}\rm{d} s+ \int_{0}^{t} \frac{\partial F }{\partial t} (g_{s-},s,X_{s-})\mathbb{I}_{\{ g_{s-} < s\}} \rm{d} s \\&\quad+\int_{0}^{t}\frac{\partial F }{\partial x} (g_{s-},s,X_{s-})\rm{d} X_s+\frac{1}{2} \sigma^2 \int_{0}^{t} \frac{\partial^2 F}{\partial x^2} (g_{s-},s,X_{s-}) \rm{d} s\\& \quad +\int_{[0,t] } \int_{(\!-\!\infty,0)} \left[ F(s,s,X_{s-}+y)\vphantom{\frac{\partial F }{\partial x}}\right. \nonumber\\&\quad\left.-F(s,s,X_{s-})-y\frac{\partial F }{\partial x} (s,s,X_{s-}) \right]\mathbb{I}_{\{g_{s-}=s \}}N(\rm{d} s\times \rm{d} y)\\&\quad+\int_{[0,t]}\int_{(\!-\!\infty,0)} \left[F(g_{s-},s,X_{s-}+y)-F(g_{s-},s,X_{s-})-y\frac{\partial F }{\partial x} (g_{s-},s,X_{s-})\right]\\&\quad\qquad\qquad \times \mathbb{I}_{\{X_{s-}+y >0 \}}\mathbb{I}_{\{ g_{s-} < s\}} N(\rm{d} s\times \rm{d} y) \\&\quad+ \int_{[0,t]}\int_{(\!-\!\infty,0)} \left[F(s,s,X_{s-}+y)-F(g_{s-},s,X_{s-})-y\frac{\partial F }{\partial x} (g_{s-},s,X_{s-}) \right]\\&\quad\qquad\qquad \times \mathbb{I}_{\{X_{s-}+y \leq 0 \}} \mathbb{I}_{\{ g_{s-} < s\}}N(\rm{d} s\times \rm{d} y)\end{align*}
with probability 1. For the case when
 $\Pi$
is any Lévy measure we know from Corollary 4.3.10 in [Reference Applebaum2] that there exists a sequence
 $\{ A_n,n\geq 1\}$
with
 $\Pi(A_n)<\infty$
, for each
 $n\geq 1$
, and
 $A_n \uparrow (-1,0)$
when
 $n\rightarrow \infty$
, such that
 $\lim_{n\rightarrow } X_{t}^{(n)}=X_t$
uniformly on compacts in probability, where
 \begin{align*}X_t^{(n)}=\sigma B_t-\mu t+\int_{[0,t]}\int_{(\!-\!\infty,-1)} x N(\rm{d} s\times \rm{d} x)+\int_{[0,t]}\int_{(-1,0)\cap A_n} x( N(\rm{d} s\times \rm{d} x)-\rm{d} s\Pi(\rm{d} x)).\end{align*}
Hence, the result above is valid for the process
 $X^{(n)}=\{X_t^{(n)},t\geq 0\} $
and, by taking
 $n\rightarrow \infty$
along a subsequence for which
 $X_t^{(n)}$
converges to
 $X_t$
almost surely, the result follows for the process X. The general case, when F and its derivatives are not necessarily bounded, follows by a standard stopping-time argument. Moreover, from the fact that
 $g_t$
is continuous on the set
 $\{ t\geq 0\colon g_{t-}=t \text{ or } (g_{t-}<t \text{ and } X_t>0)\}$
, we obtain the first equality in (3.5). Lastly, the case when
 $X_t\leq 0$
, is similar and the proof is omitted.
5.2.2. Proof of Theorem 3.2
We recall that for any
 $\varepsilon>0$
and
 $r\geq 0$
,
 \begin{align*}U_{\varepsilon,r}=r-g_{\varepsilon,r}=r-\sup\{0\leq s\leq r\,:\, X^{(\varepsilon)}_s\leq 0 \}.\end{align*}
First, note that, since
 $|K(U_s,X_s)|\leq C(U_s,X_s)$
for all
 $s\geq 0$
and
 $\mathbb{E}_{u,x}\left(\int_0^{\infty} \mathrm{e}^{-qr} C(U_r,X_r+y) \rm{d} r\right)<\infty$
for all
 $(u,x)\in E$
and
 $y\in \mathbb{R}$
, we have that
 $K^+$
and
 $K^-$
are finite. Moreover, since
 $u\mapsto C(u,x)$
is monotone for all
 $x\in \mathbb{R}$
and non-negative, we have that for all
 $r\geq 0$
and
 $\varepsilon>0$
,
 \begin{align*} |K(U_{\varepsilon,r},X_r^{(\varepsilon)})|\leq C(U_{\varepsilon,r},X_r^{(\varepsilon)})\leq C(U_r,X_r)+C(U_r,X_r-\varepsilon)+C(U_r^{(\varepsilon)},X_r)+C(U_r^{(\varepsilon)},X_r-\varepsilon),\end{align*}
where
 $U_r^{(\varepsilon)}=r-g_t^{(\varepsilon)}=r-\sup\{0\leq s\leq r\,:\, X_s \leq \varepsilon \}$
and we used that
 $U_t\geq U_{\varepsilon,t} \geq U_t^{(\varepsilon)}$
, for all
 $t\geq 0$
. It follows from integrability of
 $\mathrm{e}^{-qr}C(U_r,X_r+y)$
with respect to the product measure
 $\mathbb{P}_{u,x} \times \rm{d} r$
, for all
 $(u,x)\in E$
, by dominated convergence theorem and left-continuity in each argument of K that for
 $x\leq 0$
,
 \begin{align*}\mathbb{E}_{x}\left(\int_0^{\infty}\mathrm{e}^{-qr} K(U_{r},X_r) \rm{d} r \right)=\lim_{\varepsilon \downarrow 0} \mathbb{E}_{x}\left(\int_0^{\infty}\mathrm{e}^{-qr} K(U_{\varepsilon,r},X_r^{(\varepsilon)}) \rm{d} r \right),\end{align*}
where we note that for
 $x\leq \varepsilon$
,
 $X^{(\varepsilon)}_0=X_0-\varepsilon=x-\varepsilon$
and
 $U_{\varepsilon,0}=0$
, under
 $\mathbb{P}_x$
. Then we calculate the right-hand side of the equation above. We define the auxiliary function
 \begin{align*}J^{(\varepsilon)}(x)\,:\!=\,\mathbb{E}_x\left(\int_0^{\infty}\mathrm{e}^{-qr} K(U_{\varepsilon,r},X_r^{(\varepsilon)}) \rm{d} r \right), \quad x\leq \varepsilon.\end{align*}
Fix
 $\varepsilon>0$
and take any
 $x\leq \varepsilon$
. Then we can write
 \begin{align}J^{(\varepsilon)}(x)&=\mathbb{E}_x\left(\int_0^{\rho_{1,\varepsilon}^+} \mathrm{e}^{-qr} K(0,X_r-\varepsilon)\rm{d} r \right)+\mathbb{E}_x\left(\mathbb{I}_{\{\rho_{1,\varepsilon}^+<\infty \}}\int_{\rho_{1,\varepsilon}^+}^{\infty}\mathrm{e}^{-qr} K(U_{\varepsilon,r},X_r^{(\varepsilon)}) \rm{d} r \right)\nonumber\\&=K^-(x-\varepsilon)+\int_{0}^{\infty} \mathbb{E}_x\left(\mathbb{I}_{\{\rho_{1,\varepsilon}^+<\infty \}}\mathrm{e}^{-q(r+\rho_{1,\varepsilon}^+)} K(U_{\varepsilon,r+\rho_{1,\varepsilon}^+},X_{r+\rho_{1,\varepsilon}^+}^{(\varepsilon)})\right) \rm{d} r ,\end{align}
where we recall that
 $K^-$
is given in (3.8), and the last equality follows by Fubini’s theorem. By using that
 $g_{\varepsilon,t}=t$
, when
 $t\in [\rho_{k,\varepsilon}^-,\rho_{k,\varepsilon}^+]$
, and
 $g_{\varepsilon,t}=\rho_{k,\varepsilon}^+$
, when
 $t\in [\rho_{k,\varepsilon}^+,\rho_{k+1,\varepsilon}^-)$
, for some
 $k\geq 1$
, we obtain that for any
 $r> 0$
,
 \begin{align*}\mathbb{E}_x&\left(\mathbb{I}_{\{\rho_{1,\varepsilon}^+<\infty \}}\mathrm{e}^{-q(r+\rho_{1,\varepsilon}^+)} K(U_{\varepsilon,r+\rho_{1,\varepsilon}^+},X_{r+\rho_{1,\varepsilon}^+}^{(\varepsilon)})\right)\\&=\sum_{k=1}^{\infty}\mathbb{E}_x\left(\mathbb{I}_{\{\rho_{1,\varepsilon}^+<\infty \}}\mathrm{e}^{-q(r+\rho_{1,\varepsilon}^+)} K(r+\rho_{1,\varepsilon}^+-\rho_{k,\varepsilon}^+,X_{r+\rho_{1,\varepsilon}^+}) \mathbb{I}_{\{\rho_{k,\varepsilon}^+ \leq r+\rho_{1,\varepsilon}^+ < \rho_{k+1,\varepsilon}^-\}}\right)\\&\qquad+\sum_{k=1}^{\infty}\mathbb{E}_x\left(\mathbb{I}_{\{\rho_{1,\varepsilon}^+<\infty \}} \mathrm{e}^{-q(r+\rho_{1,\varepsilon}^+)} K(0,X_{r+\rho_{1,\varepsilon}^+}-\varepsilon) \mathbb{I}_{\{\rho_{k+1,\varepsilon}^- \leq r+\rho_{1,\varepsilon}^+ < \rho_{k+1,\varepsilon}^+\}}\right)\\&=\mathbb{E}_x\left(\mathbb{I}_{\{\rho_{1,\varepsilon}^+<\infty \}}\mathrm{e}^{-q \rho_{1,\varepsilon}^+} \right) \sum_{k=1}^{\infty} \mathbb{E}_{\varepsilon}\left( \mathrm{e}^{-qr} K(r-\rho_{k,\varepsilon}^+,X_{r}) \mathbb{I}_{\{\rho_{k,\varepsilon}^+ \leq r < \rho_{k+1,\varepsilon}^-\}}\right)\\&\qquad+\mathbb{E}_x\left(\mathbb{I}_{\{\rho_{1,\varepsilon}^+<\infty \}} \mathrm{e}^{-q\rho_{1,\varepsilon}^+} \right) \sum_{k=1}^{\infty} \mathbb{E}_{\varepsilon}\left( \mathrm{e}^{-qr} K(0,X_{r}-\varepsilon) \mathbb{I}_{\{\rho_{k+1,\varepsilon}^- \leq r < \rho_{k+1,\varepsilon}^+\}}\right)\\&=\mathrm{e}^{-\Phi(q) (\varepsilon-x)} \mathbb{E}_{\varepsilon}\left( \mathrm{e}^{-qr} K(U_{\varepsilon,r},X_{r}^{(\varepsilon)}) \right),\end{align*}
where the second equality follows by applying the strong Markov property at time
 $\rho_{1,\varepsilon}^+$
and the last from (2.2) and the definition of
 $U_{\varepsilon,r}$
and
 $X^{(\varepsilon)}_r$
. Hence, substituting the expression above into (5.5), we deduce that for any
 $x\leq \varepsilon$
,
 \begin{align}J^{(\varepsilon)}(x)&=K^-(x-\varepsilon)+\mathrm{e}^{-\Phi(q) (\varepsilon-x)} \int_{0}^{\infty} \mathbb{E}_{\varepsilon}\left( \mathrm{e}^{-qr} K(U_{\varepsilon,r},X_{r}^{(\varepsilon)}) \right) \rm{d} r\nonumber\\&=K^-(x-\varepsilon)+\mathrm{e}^{-\Phi(q) (\varepsilon-x)} J^{(\varepsilon)}(\varepsilon).\end{align}
On the other hand, using a similar argument and that
 $\rho_{2,\varepsilon}^-=\tau_0^-$
under
 $\mathbb{P}_{\varepsilon}$
, we obtain that
 \begin{align*}J^{(\varepsilon)}(\varepsilon)&=K^+(0,\varepsilon)+\mathbb{E}_{\varepsilon}\left( \mathbb{I}_{\{ \tau_0^-<\infty\}}\mathrm{e}^{-q\tau_0^-} J^{(\varepsilon)}( X_{\tau_0^-}) \right)\\&=K^+(0,\varepsilon)+\mathbb{E}_{\varepsilon}\left( \mathbb{I}_{\{ \tau_0^-<\infty\}}\mathrm{e}^{-q\tau_0^-} K^-(X_{\tau_0^-}-\varepsilon)\right)+\mathbb{E}_{\varepsilon}\left( \mathbb{I}_{\{ \tau_0^-<\infty\}}\mathrm{e}^{-q\tau_0^-}\mathrm{e}^{-\Phi(q) (\varepsilon-X_{\tau_0^-})} \right)J^{(\varepsilon)}(\varepsilon)\\&=K^+(0,\varepsilon)+\mathbb{E}_{\varepsilon}\left( \mathbb{I}_{\{ \tau_0^-<\infty\}}\mathrm{e}^{-q\tau_0^-} K^-(X_{\tau_0^-}-\varepsilon)\right)+\mathcal{I}^{(q,\Phi(q))}(\varepsilon)J^{(\varepsilon)}(\varepsilon),\end{align*}
where the second equality follows by (5.6) and from
 $X_{\tau_0^-}\leq 0$
, on the event
 $\{\tau_0^-<\infty \}$
, and the last equality follows from (2.5). Hence, solving for
 $J^{(\varepsilon)}(\varepsilon)$
in the expression above, we obtain that
 \begin{align*}J^{(\varepsilon)}(\varepsilon)&=\frac{1}{1-\mathcal{I}^{(q,\Phi(q))}(\varepsilon) }\left[ K^+(0,\varepsilon)+\mathbb{E}_{\varepsilon}\left( \mathbb{I}_{\{ \tau_0^-<\infty\}}\mathrm{e}^{-q\tau_0^-} K^-(X_{\tau_0^-}-\varepsilon)\right)\right].\end{align*}
If we further substitute the expression found for
 $J^{(\varepsilon)}(\varepsilon)$
into (5.6), we deduce that for any
 $x\leq \varepsilon$
,
 \begin{align*}J^{(\varepsilon)}(x)= K^-(x-\varepsilon)+ \frac{\mathrm{e}^{-\Phi(q) (\varepsilon-x)}}{1-\mathcal{I}^{(q,\Phi(q))}(\varepsilon) }\left[ K^+(0,\varepsilon)+\mathbb{E}_{\varepsilon}\left( \mathbb{I}_{\{ \tau_0^-<\infty\}}\mathrm{e}^{-q\tau_0^-} K^-(X_{\tau_0^-}-\varepsilon)\right)\right].\end{align*}
Therefore, by the dominated convergence theorem we have that for all
 $x\leq 0$
,
 \begin{align*}\mathbb{E}_x&\left(\int_0^{\infty}\mathrm{e}^{-qr} K(U_r,X_r) \rm{d} r \right)\\&= \lim_{\varepsilon \downarrow 0 }\left\{ K^-(x-\varepsilon)+\frac{\mathrm{e}^{-\Phi(q) (\varepsilon-x)}}{ 1-\mathcal{I}^{(q,\Phi(q))}(\varepsilon)} \left[ \mathbb{E}_{\varepsilon}\left( \mathbb{I}_{\{ \tau_0^-<\infty\}} \mathrm{e}^{-q \tau_0^-} K^-(X_{\tau_0^-}-\varepsilon) \right)+K^+(0,\varepsilon) \right] \right\} .\end{align*}
Using Fubini’s theorem and equation (2.10) we have that for all
 $x<0$
,
 \begin{align}K^-(x)=\int_{(\!-\!\infty,0)}K(0,y) \int_0^{\infty} \mathrm{e}^{-qr} \mathbb{P}_x(X_r\in \rm{d} y, r<\tau_0^+) \rm{d} r\nonumber\\=\int_{-\infty}^0 K(0,y) [\mathrm{e}^{\Phi(q)x}W^{(q)}(-y) -W^{(q)}(x-y)] \rm{d} y.\end{align}
Recall that we are assuming that K is bounded by a non-negative integrable function C. Then we have that for any
 $y<0$
and
 $x<0$
,
 \begin{align*}|K(0,y) [\mathrm{e}^{\Phi(q)x}W^{(q)}(-y) -W^{(q)}(x-y)]|\leq C(0,y) [\mathrm{e}^{\Phi(q)x}W^{(q)}(-y) -W^{(q)}(x-y)].\end{align*}
Moreover, we have that the quantity on the right-hand side of the equation above is integrable since for any
 $x<0$
,
 \begin{align*}C^-(x)\,:\!=\, \mathbb{E}_x\left(\int_0^{\tau_0^+} \mathrm{e}^{-qr}C(0,X_r)\rm{d} r \right)<\mathbb{E}_x\left(\int_0^{\infty} \mathrm{e}^{-qr}C(U_r,X_r)\rm{d} r \right)<\infty\end{align*}
and
 \begin{align*}C^-(x)=\int_{-\infty}^0 C(0,y) [\mathrm{e}^{\Phi(q)x}W^{(q)}(-y) -W^{(q)}(x-y)] \rm{d} y,\end{align*}
where we used Fubini’s theorem and equation (2.10). Furthermore, it can be seen (see, for example, the proof of Theorem 8.1 in [Reference Kyprianou29]) that for any
 $q>0$
and
 $y<0$
, the mapping
 $x\mapsto \mathrm{e}^{-\Phi(q)x}W^{(q)}(x-y)$
is non-decreasing. Thus, for any
 $x<0$
and any
 $x_1<x_2<0$
such that
 $x\in [x_1,x_2]$
,
 \begin{align*}C^-(x)&= \mathrm{e}^{\Phi(q) x}\int_{-\infty}^0 C(0,y) [W^{(q)}(-y) -\mathrm{e}^{-\Phi(q)x}W^{(q)}(x-y)] \rm{d} y\\&\leq \mathrm{e}^{\Phi(q) x}\int_{-\infty}^0 C(0,y) [W^{(q)}(-y) -\mathrm{e}^{-\Phi(q)x_1}W^{(q)}(x_1-y)] \rm{d} y\\&\leq \mathrm{e}^{\Phi(q) (x_2-x_1)}C^{-}(x_1).\end{align*}
Hence, since W is continuous on
 $(0,\infty)$
and by the dominated convergence theorem, we deduce that
 $K^-$
is a continuous function. Thus, we have that for any
 $x\leq 0$
,
 \begin{align}\mathbb{E}_x&\left(\int_0^{\infty}\mathrm{e}^{-qr} K(U_r,X_r) \rm{d} r \right)\nonumber\\&= K^-(x)+\lim_{\varepsilon \downarrow 0 } \frac{\mathrm{e}^{-\Phi(q) (\varepsilon-x)}}{ 1-\mathcal{I}^{(q,\Phi(q))}(\varepsilon)} \left[ \mathbb{E}_{\varepsilon}\left( \mathbb{I}_{\{ \tau_0^-<\infty\}} \mathrm{e}^{-q \tau_0^-} K^-(X_{\tau_0^-}-\varepsilon) \right)+K^+(0,\varepsilon) \right] .\end{align}
We then proceed to find the limit on the right-hand side of the equation above. For any
 $x>0$
and
 $\varepsilon>0$
, we deduce from Fubini’s theorem and equations (2.5) and (5.7) that
 \begin{align*}&\mathbb{E}_{x}\left( \mathbb{I}_{\{ \tau_0^-<\infty\}} \mathrm{e}^{-q \tau_0^-} K^-(X_{\tau_0^-}-\varepsilon) \right)\\&= \mathrm{e}^{\Phi(q)(x-\varepsilon)}\mathcal{I}^{(q,\Phi(q))}(x) \int_{-\varepsilon}^0 K(0,y) W^{(q)}(-y)\rm{d} y \\&\quad +\int_{-\infty}^{-\varepsilon}K(0,y)\left[\mathrm{e}^{\Phi(q)(x-\varepsilon)}\mathcal{I}^{(q,\Phi(q))}(x) W^{(q)}(-y)\right.\nonumber\\ &\quad\left.- \mathbb{E}_x\left(\mathbb{I}_{\{\tau_0^-<\infty \}} \mathrm{e}^{-q\tau_0^-}W^{(q)}(X_{\tau_0^-}-\varepsilon-y)\right) \right] \rm{d} y.\end{align*}
Let
 $x,\varepsilon>0$
and
 $y<-\varepsilon$
. From the monotone convergence theorem and (2.4) we have that
 \begin{align}\mathbb{E}_x&\left(\mathbb{I}_{\{\tau_0^-<\infty \}} \mathrm{e}^{-q\tau_0^-}W^{(q)}(X_{\tau_0^-}-\varepsilon-y)\right)\nonumber\\&=\lim_{a\rightarrow \infty} \mathbb{E}_x\left(\mathbb{I}_{\{\tau_0^-<\tau_a^+ \}} \mathrm{e}^{-q\tau_0^-}W^{(q)}(X_{\tau_0^-}-\varepsilon-y)\right)\nonumber\\&=\lim_{a\rightarrow \infty} \mathbb{E}_x\left( \mathrm{e}^{-q\tau_0^-\wedge \tau_a^+ } W^{(q)}(X_{\tau_0^-\wedge \tau_a^+}-\varepsilon-y)\right)\!-\!\lim_{a\rightarrow \infty} \mathbb{E}_x\!\left( \mathbb{I}_{\{\tau_a^+ < \tau_0^- \}} \mathrm{e}^{-q \tau_a^+ } W^{(q)}(a-\varepsilon-y)\right)\nonumber\\&=\lim_{a\rightarrow \infty} \mathbb{E}_{x-\varepsilon -y}\left( \mathrm{e}^{-q\tau_{-\varepsilon -y}^-\wedge \tau_{a-\varepsilon-y}^+ } W^{(q)}(X_{\tau_{-\varepsilon-y}^-\wedge \tau_{a-\varepsilon-y}^+})\right)-\lim_{a\rightarrow \infty} W^{(q)}(a-\varepsilon-y)\frac{W^{(q)}(x)}{W^{(q)}(a)}\nonumber\\&=W^{(q)}(x-\varepsilon-y)-\mathrm{e}^{-\Phi(q)(\varepsilon+y)} W^{(q)}(x),\end{align}
where the last equality follows since, for any
 $a\geq 0$
, the process
 $\mathrm{e}^{-q(t\wedge \tau_0^-\wedge \tau_a^+)}W^{(q)}(X_{t\wedge \tau_0^-\wedge \tau_a^+})$
is a martingale, from the optional sampling theorem (note that
 $\tau_{-\varepsilon-y}^-\leq \tau_0^-$
) and since
 $\lim_{a \rightarrow \infty} W^{(q)}(a-z)/W^{(q)}(a)=\mathrm{e}^{-\Phi(q)z}$
for
 $z\leq a$
and
 $a\geq 0$
(see Exercises 8.5 and 8.12 in [Reference Kyprianou29]).
Hence, we obtain that for any
 $x>0$
and
 $\varepsilon>0$
,
 \begin{align*}&\mathbb{E}_{x}\left( \mathbb{I}_{\{ \tau_0^-<\infty\}} \mathrm{e}^{-q \tau_0^-} K^-(X_{\tau_0^-}-\varepsilon) \right)\\&= \mathrm{e}^{\Phi(q)(x-\varepsilon)}\mathcal{I}^{(q,\Phi(q))}(x) \int_{-\varepsilon}^0 K(0,y) W^{(q)}(-y)\rm{d} y \\&\quad +\int_{-\infty}^{-\varepsilon}K(0,y)\left[\mathrm{e}^{\Phi(q)(x-\varepsilon)}\mathcal{I}^{(q,\Phi(q))}(x) W^{(q)}(-y) -W^{(q)}(x-\varepsilon-y)\right.\nonumber\\&\quad\left.+ \,\mathrm{e}^{-\Phi(q)(\varepsilon+y)} W^{(q)}(x) \right] \rm{d} y.\end{align*}
In particular, when
 $x=\varepsilon$
we obtain that
 \begin{align*}&\mathbb{E}_{\varepsilon}\left( \mathbb{I}_{\{ \tau_0^-<\infty\}} \mathrm{e}^{-q \tau_0^-} K^-(X_{\tau_0^-}-\varepsilon) \right)\\&= \mathcal{I}^{(q,\Phi(q))}(\varepsilon) \int_{-\varepsilon}^0 K(0,y) W^{(q)}(-y)\rm{d} y \\&\qquad +\int_{-\infty}^{-\varepsilon}K(0,y)\left( [\mathcal{I}^{(q,\Phi(q))}(\varepsilon)-1] W^{(q)}(-y) +\mathrm{e}^{-\Phi(q)(\varepsilon+y)} W^{(q)}(\varepsilon) \right) \rm{d} y.\end{align*}
Thus, for any
 $\varepsilon>0$
and
 $x\leq 0$
,
 \begin{align*} & \frac{\mathrm{e}^{-\Phi(q) (\varepsilon-x)}}{ 1-\mathcal{I}^{(q,\Phi(q))}(\varepsilon)} \mathbb{E}_{\varepsilon}\left( \mathbb{I}_{\{ \tau_0^-<\infty\}} \mathrm{e}^{-q \tau_0^-} K^-(X_{\tau_0^-}-\varepsilon) \right)\\&\quad=\frac{\mathrm{e}^{-\Phi(q) (\varepsilon-x)}}{ 1-\mathcal{I}^{(q,\Phi(q))}(\varepsilon)} \mathcal{I}^{(q,\Phi(q))}(\varepsilon) \int_{-\varepsilon}^0 K(0,y) W^{(q)}(-y)\rm{d} y \\&\qquad +\frac{\mathrm{e}^{-\Phi(q) (\varepsilon-x)}}{ 1-\mathcal{I}^{(q,\Phi(q))}(\varepsilon)} \int_{-\infty}^{-\varepsilon}K(0,y)\left( [\mathcal{I}^{(q,\Phi(q))}(\varepsilon)-1] W^{(q)}(-y) +\mathrm{e}^{-\Phi(q)(\varepsilon+y)} W^{(q)}(\varepsilon) \right) \rm{d} y\\&\quad= \Phi'(q)\frac{\mathrm{e}^{\Phi(q) x}}{ W^{(q)}(\varepsilon)} \int_{-\varepsilon}^0 K(0,y) W^{(q)}(-y)\rm{d} y-\mathrm{e}^{-\Phi(q) (\varepsilon-x)} \int_{-\varepsilon}^0 K(0,y) W^{(q)}(-y)\rm{d} y \\&\qquad- \mathrm{e}^{-\Phi(q) (\varepsilon-x)}\int_{-\infty}^{-\varepsilon}K(0,y)\left( W^{(q)}(-y) -\Phi'(q)\mathrm{e}^{-\Phi(q)y} \right) \rm{d} y,\end{align*}
where we used that
 $ 1-\mathcal{I}^{(q,\Phi(q))}(\varepsilon)= [\Phi'(q)]^{-1} \mathrm{e}^{-\Phi(q) \varepsilon}W^{(q)}(\varepsilon) $
. Moreover, by using that
 $W^{(q)}$
is increasing on
 $(0,\infty)$
we see that
 \begin{align*}0\leq \left|\lim_{\varepsilon \downarrow 0} \Phi'(q)\frac{\mathrm{e}^{\Phi(q) x}}{ W^{(q)}(\varepsilon)} \! \int_{-\varepsilon}^0\! K(0,y) W^{(q)}(-y)\rm{d} y \right|\leq \lim_{\varepsilon \downarrow 0}\Phi'(q)\frac{\mathrm{e}^{\Phi(q) x}}{ W^{(q)}(\varepsilon)} W^{(q)}(\varepsilon)\! \int_{-\varepsilon}^0 \!|K(0,y)| \rm{d} y=0.\end{align*}
Thus, we conclude that for any
 $x\leq 0$
,
 \begin{align*}\lim_{\varepsilon \downarrow 0} & \frac{\mathrm{e}^{-\Phi(q) (\varepsilon-x)}}{ 1-\mathcal{I}^{(q,\Phi(q))}(\varepsilon)} \mathbb{E}_{\varepsilon}\left( \mathbb{I}_{\{ \tau_0^-<\infty\}} \mathrm{e}^{-q \tau_0^-} K^-(X_{\tau_0^-}-\varepsilon) \right)\\&=- \mathrm{e}^{\Phi(q) x}\int_{-\infty}^{0}K(0,y)\left( W^{(q)}(-y) -\Phi'(q)\mathrm{e}^{-\Phi(q)y} \right) \rm{d} y.\end{align*}
Substituting the expression above into (5.8) and using the expression obtained for
 $K^-(x)$
in (5.7), we deduce that for any
 $x\leq 0$
,
 \begin{align}\mathbb{E}_x&\left(\int_0^{\infty}\mathrm{e}^{-qr} K(U_r,X_r) \rm{d} r \right)\nonumber\\&= K^-(x)+\lim_{\varepsilon \downarrow 0 } \frac{\mathrm{e}^{-\Phi(q) (\varepsilon-x)}}{ 1-\mathcal{I}^{(q,\Phi(q))}(\varepsilon)} \left[ \mathbb{E}_{\varepsilon}\left( \mathbb{I}_{\{ \tau_0^-<\infty\}} \mathrm{e}^{-q \tau_0^-} K^-(X_{\tau_0^-}-\varepsilon) \right)+K^+(0,\varepsilon) \right]\nonumber \\&=\int_{-\infty}^0 K(0,y) [\Phi'(q)\mathrm{e}^{-\Phi(q)(y-x)} -W^{(q)}(x-y)] \rm{d} y+ \Phi'(q)\mathrm{e}^{\Phi(q) x}\lim_{\varepsilon \downarrow 0 } \frac{K^+(0,\varepsilon)}{ W^{(q)}(\varepsilon)}.\end{align}
For the case when
 $u>0$
and
 $x>0$
, using the expression above and the strong Markov property, we obtain that
 \begin{align*}\mathbb{E}_{u,x}&\left(\int_0^{\infty}\mathrm{e}^{-qr} K(U_r,X_r) \rm{d} r \right)\\&=\mathbb{E}_x\left(\int_0^{\tau_0^-}\mathrm{e}^{-qr} K(u+r,X_r) \rm{d} r \right)+\mathbb{E}_{x}\left(\mathbb{I}_{\{\tau_0^-<\infty \}}\int_{\tau_0^-}^{\infty}\mathrm{e}^{-qr} K(U_r,X_r) \rm{d} r \right)\\&=\mathbb{E}_x\left(\int_0^{\tau_0^-}\mathrm{e}^{-qr} K(u+r,X_r) \rm{d} r \right)+\mathbb{E}_{x}\left(\mathbb{I}_{\{\tau_0^-<\infty \}} \mathrm{e}^{q \tau_0^-} \mathbb{E}_{X_{\tau_0^-}}\left[\int_{0}^{\infty}\mathrm{e}^{-qr} K(U_r,X_r) \rm{d} r \right] \right)\\&=K^+(u,x)\\&\quad+\int_{-\infty}^0 K(0,y) \left[\Phi'(q)\mathrm{e}^{-\Phi(q)y} \mathbb{E}_{x}\left(\mathbb{I}_{\{\tau_0^-<\infty \}}\mathrm{e}^{-q\tau_0^-} \mathrm{e}^{\Phi(q) X_{\tau_0^-}} \right)\right. \nonumber\\&\quad\left.- \mathbb{E}_{x}\left(\mathbb{I}_{\{\tau_0^-<\infty \}}\mathrm{e}^{-q\tau_0^-} W^{(q)}(X_{\tau_0^-}-y) \right)\right] \rm{d} y\\&\quad+ \Phi'(q)\mathbb{E}_{x}\left(\mathbb{I}_{\{\tau_0^-<\infty \}}\mathrm{e}^{-q\tau_0^-} \mathrm{e}^{\Phi(q) X_{\tau_0^-}} \right)\lim_{\varepsilon \downarrow 0 } \frac{K^+(0,\varepsilon)}{ W^{(q)}(\varepsilon)}\\&=K^+(u,x)\\&\quad+\int_{-\infty}^0 K(0,y) \left[\Phi'(q)\mathrm{e}^{-\Phi(q)y} \mathrm{e}^{\Phi(q)x}\mathcal{I}^{(q,\Phi(q))}(x) -W^{(q)}(x-y)+\mathrm{e}^{-\Phi(q)y} W^{(q)}(x)\right] \rm{d} y\\&\quad+ \Phi'(q)\mathrm{e}^{\Phi(q)x}\mathcal{I}^{(q,\Phi(q))}(x)\lim_{\varepsilon \downarrow 0 } \frac{K^+(0,\varepsilon)}{ W^{(q)}(\varepsilon)}\\&=K^+(u,x)+\int_{-\infty}^0 K(0,y) \left[\Phi'(q)\mathrm{e}^{-\Phi(q)(y-x)} -W^{(q)}(x-y)\right] \rm{d} y\\&\quad+ [\Phi'(q)\mathrm{e}^{\Phi(q)x}-W^{(q)}(x)]\lim_{\varepsilon \downarrow 0 } \frac{K^+(0,\varepsilon)}{ W^{(q)}(\varepsilon)},\end{align*}
where the penultimate equality follows from (2.5) and (5.9) and the last by substituting the value of
 $\mathcal{I}^{(q,\Phi(q)}(x)$
(see (2.6)). Lastly, since
 $W^{(q)}(x)=0$
for
 $x<0$
,
 $W^{(q)}(0)=0$
when X has paths of infinite variation and
 $W^{(q)}(0)>0$
when X has paths of finite variation, we note that the expression above coincides with (5.10) when
 $x\leq 0$
. In other words, the expression above is valid for any
 $(u,x)\in E$
. The proof is now complete.
5.3. Proof of Theorem 4.1
We first state a verification lemma that provides sufficient conditions for the optimality of a given candidate solution
 $\tau^*$
.
Lemma 5.4. Suppose that
 $\tau^*$
is candidate solution to the optimal stopping problem and let
 $V^*$
be its corresponding value function,
 $V^*(u,x)= \mathbb{E}_{x,u}\left(\int_0^{\tau^*}\mathrm{e}^{-rs}G(U_s,X_s)\rm{d} s \right)$
. Assume that the following assertions hold.
-
(i)
$V^*(u,x)\geq 0$
for all
$(u,x)\in E$
. -
(ii) For each
$(u,x)\in E$
and
$N>0$
, the stochastic process
$\{Z_{t\wedge \tau_N^+}, t\geq 0 \}$
is a supermartingale under the measure
$\mathbb{P}_{u,x}$
, where
\begin{align*}Z_t=\mathrm{e}^{-rt}V^*(U_t,X_t)+\int_0^t \mathrm{e}^{-rs}G(U_s,X_s)\rm{d} s.\end{align*}


Then
 $V=V^*$
and the stopping time
 $\tau^*$
is an optimal stopping time for (4.2).
Proof. From the definition of V, we deduce that
 $V\geq V^*$
. On the other hand, due to the optimal sampling theorem we have that, for any
 $t\geq 0$
,
 $N>0$
and any stopping time
 $\tau \in \mathcal{T}$
, the stopped process
 $Z_{t\wedge \tau \wedge \tau_N^+ }$
is a supermartingale. This implies that for any
 $t\geq 0$
,
 $N>0$
and
 $\tau \in \mathcal{T}$
,
 \begin{align*}V^*(u,x) &\geq \mathbb{E}_{u,x}\left(\mathrm{e}^{-r(T\wedge \tau)} V^*(U_{T\wedge \tau },X_{T\wedge \tau})+\int_0^{T\wedge \tau } \mathrm{e}^{-rs}G(U_s,X_s)\rm{d} s\right)\\ &\geq \mathbb{E}_{u,x}\left( \int_0^{T\wedge \tau}\mathrm{e}^{-rs} G(U_s,X_s)\rm{d} s\right),\end{align*}
where
 $T=t\wedge \tau_N^+$
and the last inequality follows since
 $V^*\geq 0$
, by assumption. From the dominated convergence theorem we conclude (see (4.1)), by taking
 $t,N\rightarrow \infty$
in the equation above, that
 \begin{align*}V^*(u,x) \geq \mathbb{E}_{u,x}\left( \int_0^{\tau}\mathrm{e}^{-rs} G(U_s,X_s)\rm{d} s\right)\end{align*}
for all
 $(u,x)\in E$
and
 $\tau \in \mathcal{T}$
. Hence, we have that
 $V\leq V^*$
, implying that
 $V=V^*$
. Therefore, the supremum in (4.2) is attained by
 $\tau^*$
as claimed.
For
 $z\leq 0$
fixed, we define the function
 \begin{align*}V_z(u,x)\,:\!=\,\mathbb{E}_{x,u}\left(\int_0^{\tau_z^-}\mathrm{e}^{-rs}G(U_s,X_s)\rm{d} s \right),\end{align*}
for
 $(u,x)\in E$
. The following lemma gives a semi-explicit expression for
 $V_z$
in terms of the scale functions.
Lemma 5.5. For any
 $z< 0$
and
 $(u,x)\in E$
such that
 $x\geq z$
we have that
 \begin{align}V_z(u,x)&=K^+(u,x) + \left[\mathrm{e}^{\Phi(r)z}W^{(r)}(x-z)-W^{(r)}(x) \right]\int_{(0,\infty)}\int_0^{\infty} G(v, y) \frac{y}{v}\mathrm{e}^{-rv}\mathbb{P}(X_{v} \in \rm{d} y) \rm{d} v\nonumber\\&\qquad+\mathrm{e}^{\Phi(r) z}W^{(r)}(x-z)\int_{z}^{0} G(0,y) \mathrm{e}^{-\Phi(r) y}\rm{d} y -\int_{z}^{0} G(0,y)W^{(r)}(x-y)\rm{d} y.\end{align}
Proof. Note that for any
 $(u,x)\in E$
,
 \begin{align*}V_z(u,x)=\mathbb{E}_{x,u}\left(\int_0^{\tau_z^-}\mathrm{e}^{-rs}G(U_s,X_s)\mathbb{I}_{\{X_s>0 \}}\rm{d} s \right)+\mathbb{E}_{x}\left(\int_0^{\tau_z^-}\mathrm{e}^{-rs}G(0,X_s)\mathbb{I}_{\{X_s\leq 0 \}}\rm{d} s \right),\end{align*}
where the two terms on the right-hand side are finite due to equation (4.1). Using equation (2.11) and Fubini’s theorem, we deduce that for any
 $x\geq z$
,
 \begin{align*}\mathbb{E}_{x}\left(\int_0^{\tau_z^-}\mathrm{e}^{-rs}G(0,X_s)\mathbb{I}_{\{X_s\leq 0 \}}\rm{d} s \right)&=\mathbb{E}_{x-z}\left(\int_0^{\tau_0^-}\mathrm{e}^{-rs}G(0,X_s+z)\mathbb{I}_{\{X_s+z\leq 0 \}}\rm{d} s \right)\\&=\int_{(0,-z]} \!\! G(0,y+z) \int_0^{\infty} \mathrm{e}^{-rs}\mathbb{P}_{x-z}\left(X_s\in \rm{d} y, s<\tau_0^- \right)\rm{d} s\\&=\int_{0}^{-z} \!\! G(0,y+z) \left[ \mathrm{e}^{-\Phi(r) y}W^{(r)}(x-z) \!-\!W^{(r)}(x-z-y) \right]\rm{d} y\\&=\mathrm{e}^{\Phi(r) z}W^{(r)}(x-z)\int_{z}^{0} G(0,y) \mathrm{e}^{-\Phi(r) y}\rm{d} y \nonumber\\&\quad-\int_{z}^{0} G(0,y)W^{(r)}(x-y)\rm{d} y.\end{align*}
On the other hand, from the strong Markov property, we have that for
 $(u,x)\in E$
such that
 $x\geq z$
,
 \begin{align*}\mathbb{E}_{x,u}\left(\int_0^{\tau_z^-}\mathrm{e}^{-rs}G(U_s,X_s)\mathbb{I}_{\{X_s>0 \}}\rm{d} s \right)&=H(u,x)-\mathbb{E}_{x}(\mathrm{e}^{-r \tau_z^-}\mathbb{I}_{\{\tau_z^- <\infty \}} H(0,X_{\tau_z^-})),\end{align*}
where
 \begin{align}H(u,x)&\,:\!=\,\mathbb{E}_{u,x}\left(\int_0^{\infty} \mathrm{e}^{-rs}G(U_s,X_s)\mathbb{I}_{\{X_s>0 \}}\rm{d} s \right).\end{align}
It follows from (4.1) that
 $|H(u,x)|<\infty$
for all
 $(u,x)\in E$
. Hence, by using the potential measure of (U, X) given in Corollary 3.3, we see that for any
 $(u,x)\in E$
,
 \begin{align}H(u,x)&=\int_{(0,\infty)}\int_0^{\infty} G(v, y) \int_0^{\infty}\mathrm{e}^{-rs}\mathbb{P}_{u,x}(X_s\in \rm{d} y, U_s\in \rm{d} v) \rm{d} s \nonumber\\&=\int_{(0,\infty)}\int_u^{\infty} G(v, y)\mathrm{e}^{-r(v-u)}\mathbb{P}_x(X_{v-u}\in \rm{d} y,v-u<\tau_0^-)\rm{d} v\nonumber\\&\qquad + \left[\mathrm{e}^{\Phi(r) x}\Phi'(r)-W^{(r)}(x) \right]\int_{(0,\infty)}\int_0^{\infty} G(v, y) \frac{y}{v}\mathrm{e}^{-rv}\mathbb{P}(X_{v} \in \rm{d} y) \rm{d} v \nonumber\\&=K^+(u,x) + \left[\mathrm{e}^{\Phi(r) x}\Phi'(r)-W^{(r)}(x) \right]\int_{(0,\infty)}\int_0^{\infty} G(v, y) \frac{y}{v}\mathrm{e}^{-rv}\mathbb{P}(X_{v} \in \rm{d} y) \rm{d} v . \end{align}
Thus, by using (2.5) and since
 $K^+(0,x)=0=W^{(q)}(x)$
when
 $x<0$
, we deduce that for any
 $x\in \mathbb{R}$
,
 \begin{align*}&\mathbb{E}_{x}(\mathrm{e}^{-r \tau_z^-}\mathbb{I}_{\{\tau_z^- <\infty \}} H(0,X_{\tau_z^-}))\nonumber\\&\quad=\Phi'(r)\mathbb{E}_x\left(\mathrm{e}^{-r\tau_z^-+\Phi(r) X_{\tau_z^-}} \mathbb{I}_{\{\tau_z^-<\infty \}}\right) \int_{(0,\infty)}\int_0^{\infty} G(v, y) \frac{y}{v}\mathrm{e}^{-rv}\mathbb{P}(X_{v} \in \rm{d} y) \rm{d} v \end{align*}\begin{align}&\quad=\Phi'(r)\mathbb{E}_{x-z}\left(\mathrm{e}^{-r \tau_0^-+ \Phi(r) (X_{\tau_0^-}+z)}\mathbb{I}_{\{\tau_0^-<\infty \}} \right)\nonumber\\&\qquad\times\left[ \int_{(0,\infty)}\int_0^{\infty} G(v, y) \frac{y}{v}\mathrm{e}^{-rv}\mathbb{P}(X_{v} \in \rm{d} y) \rm{d} v \right]\nonumber\\&\quad=\left(\Phi'(r) \mathrm{e}^{\Phi(r)x} -\mathrm{e}^{\Phi(r)z}W^{(r)}(x-z) \right) \int_{(0,\infty)}\int_0^{\infty} G(v, y) \frac{y}{v}\mathrm{e}^{-rv}\mathbb{P}(X_{v} \in \rm{d} y) \rm{d} v.\end{align}
Therefore, we get that
 \begin{align*}\mathbb{E}_{x,u}&\left(\int_0^{\tau_z^-}\mathrm{e}^{-rs}G(U_s,X_s)\mathbb{I}_{\{X_s>0 \}}\rm{d} s \right)\\&=H(u,x)-\mathbb{E}_{x}(\mathrm{e}^{-r \tau_z^-}\mathbb{I}_{\{\tau_z^- <\infty \}} H(0,X_{\tau_z^-}))\\&=K^+(u,x) + \left[\mathrm{e}^{\Phi(r)z}W^{(r)}(x-z)-W^{(r)}(x) \right]\int_{(0,\infty)}\int_0^{\infty} G(v, y) \frac{y}{v}\mathrm{e}^{-rv}\mathbb{P}(X_{v} \in \rm{d} y) \rm{d} v\end{align*}
for any
 $(u,x)\in E$
. The result follows.
For optimal stopping problems it is common to choose candidate solutions to satisfy the principle of smooth fit. Recall that we are assuming that
 $\sigma>0$
so that, in this case,
 $W^{(r)}$
is
 $C^2$
on
 $(0,\infty)$
with
 $W^{(r)\prime}(0\!+\!)=2/\sigma^2$
(see, for example, Theorem 3.10 and Lemma 3.2 in [Reference Kyprianou, Kuznetsov and Rivero26]). Then, by differentiating
 $V_z(u,x)$
with respect to x, we obtain for
 $z<x<0$
that
 \begin{align*}\frac{\partial}{\partial x} V_z(0,x)&=\mathrm{e}^{\Phi(r)z}W^{(r)\prime}(x-z)\left[\int_{(0,\infty)}\int_0^{\infty} G(v, y) \frac{y}{v}\mathrm{e}^{-rv}\mathbb{P}(X_{v} \in \rm{d} y) \rm{d} v\right. \nonumber\\ &\qquad\left.+\int_{z}^0 G(0,y) \mathrm{e}^{-\Phi(r) y}\rm{d} y\right]\\&\qquad -\int_{z}^x G(0,y)W^{(r)\prime}(x-y) \rm{d} y.\end{align*}
Then, by letting
 $x\downarrow z$
, we see that the equation
 \begin{align*}\frac{\partial}{\partial x} V_z(0,z\!+\!)=0\end{align*}
is satisfied if and only if z solves the equation
 \begin{align*}\int_{(0,\infty)}\int_0^{\infty} G(v, y) \frac{y}{v}\mathrm{e}^{-rv}\mathbb{P}(X_{v} \in \rm{d} y) \rm{d} v +\int_{z}^0 G(0,y) \mathrm{e}^{-\Phi(r) y}=0.\end{align*}
That is, if
 $z=z^*$
. In the following lemma, we verify that the characterization of
 $z^*$
given in the statement of Theorem 4.1 indeed holds and that condition (i) given in Lemma 5.4 holds when
 $z\geq z^*$
.
Lemma 5.6. For
 $z\leq 0$
, we define the function
 \begin{align*}f(z)=\int_{(0,\infty)}\int_0^{\infty} G(v, y) \frac{y}{v}\mathrm{e}^{-rv}\mathbb{P}(X_{v} \in \rm{d} y) \rm{d} v+\int_{z}^0 G(0,y) \mathrm{e}^{-\Phi(r ) y}\rm{d} y.\end{align*}
Then the equation
 $f(z)=0$
has a unique solution
 $z^*$
on
 $(\!-\!\infty,0)$
such that
 $z^*\leq y_0$
. Moreover, we have that
 $V_z(u,x)\geq 0$
for all
 $z\geq z^*$
and
 $(u,x)\in E$
.
Proof. From Corollary 3.3 and by assumption (4.1) we know that
 \begin{align*}0\leq\, f(0)&=\int_{(0,\infty)}\int_0^{\infty} G(v, y) \frac{y}{v}\mathrm{e}^{-rv}\mathbb{P}(X_{v} \in \rm{d} y) \rm{d} v\\&=\frac{1}{\Phi'(r)}\mathbb{E}\left(\int_0^{\infty} \mathrm{e}^{-rs}G(U_s,X_s)\mathbb{I}_{\{X_s>0 \}}\rm{d} s \right)<\infty.\end{align*}
On the other hand, since G(0,y) is non-positive on
 $(\!-\!\infty,y_0)$
, we have that f(z) is increasing on
 $(\!-\!\infty,y_0)$
with
 $f(z)>0$
for all
 $ y_0\leq z\leq 0$
and
 $\lim_{y\rightarrow -\infty}f(z)=-\infty$
, where the latter follows due to the assumption
 $\lim_{y\rightarrow -\infty }G(0,y)<0$
. Then, due to the continuity of f, we see that the equation
 $f(z)=0$
has a unique solution
 $z^*$
on
 $(\!-\!\infty,y_0)$
.
Next, we proceed to show the statement on
 $V_z$
. Since G(u, x) is non-negative for all
 $(u,x)\in E$
such that
 $x\geq y_0$
, we see that
 $V_z(x,u)\geq 0$
for all
 $(u,x)\in E$
and
 $z\geq y_0$
. Taking
 $z<0$
and
 $(u,x)\in E$
such that
 $x>z$
, we see from (5.11) that
 \begin{align*}\frac{\partial }{\partial z} V_z(u,x)=f(z)\frac{\partial }{\partial z} (\mathrm{e}^{\Phi(r)z}W^{(r)}(x-z)).\end{align*}
Note that we can write
 $\mathrm{e}^{\Phi(r)z}W^{(r)}(x-z)=\mathrm{e}^{\Phi(r)x}W_{\Phi(r)}(x-z)$
, where
 $W_{\Phi(r)}$
is the r-scale function under the measure
 $\mathbb{P}^{\Phi(r)}$
(see, for example, the proof of Theorem 8.1 in [Reference Kyprianou29]). Then we see that the mapping
 $z \mapsto \mathrm{e}^{\Phi(r)z}W^{(r)}(x-z)$
is non-increasing on
 $\mathbb{R}$
, and then
 $\frac{\partial }{\partial z} V_z(u,x)\leq 0$
for all
 $(u,x) \in E$
and
 $ z^*\leq z < 0$
such that
 $x>z$
. We conclude that, for
 $(u,x)\in E$
fixed such that
 $x>z^*$
, the mapping
 $z\mapsto V_z(x,u)$
is non-increasing on
 $[z^*,x\wedge 0)$
. Hence,
 \begin{align*} V_z(x,u)\geq \lim_{z\uparrow x\wedge 0}V_z(u,x)\geq 0\end{align*}
for any
 $z^*\leq z\leq 0$
and
 $(u,x)\in E$
such that
 $x>z$
. The proof is now complete.
For ease of notation, we denote
 $V^*=V_{z^*}$
. Note that for any
 $(u,x)\in E$
,
 \begin{align}V^*(u,x)= K^+(u,x) \!-\!W^{(r)}(x)\!\int_{(0,\infty)}\int_0^{\infty} \!G(v, y) \frac{y}{v}\mathrm{e}^{-rv}\mathbb{P}(X_{v} \in \rm{d} y) \rm{d} v-\int_{z^*}^0 \!G(0,y)W^{(r)}(x-y) \rm{d} y.\end{align}
Next, we show that the supermartingale property holds for
 $V^*$
.
Lemma 5.7. For any
 $N>0$
we have that the process
 $\{ Z_{t\wedge \tau_N^+}^*, t\geq 0\}$
is a supermartingale under
 $\mathbb{P}_{u,x}$
, for each
 $(u,x)\in E$
, where
 \begin{align*}Z_t^{*}=\mathrm{e}^{-rt}V^*(U_t,X_t)+\int_0^t \mathrm{e}^{-rs} G(U_s,X_s)\rm{d} s.\end{align*}
Proof. Due to the fact that X is of infinite variation, we have that
 $\mathbb{P}(\tau_0^-=0)=1$
and
 $W^{(r)}$
is continuous on
 $\mathbb{R}$
. Thus,
 $V_z$
is continuous on E and
 $\lim_{h\downarrow 0} V^*(u,h)=V^*(0, 0)$
for any
 $u\geq 0$
. Moreover, since we are assuming that
 $\sigma>0$
, we have that
 $W^{(r)}\in C^2(0,\infty)$
with
 $W^{(r)\prime}(0\!+\!)=2/\sigma^2$
(see Lemma 3.2 and Theorem 3.10 in [Reference Kyprianou, Kuznetsov and Rivero26]). Hence, we have that
 $V_z(u,x)$
is a
 $C^{1,1}$
function on
 $[0,\infty)\times [0,\infty)$
and the second derivative
 $\frac{\partial^2}{\partial x^2} V^*(u,x)$
exists and is continuous on
 $(0,\infty)$
for all
 $u\geq 0$
(recall that we are assuming that
 $K^+$
is a
 $C^{1,2}$
function on
 $[0,\infty)\times [0,\infty)$
). On the other hand, for
 $z^*<x<0$
we have that
 \begin{align}\frac{\partial}{\partial x} V^*(0,x)&=\int_{z^*}^x G(0,y)W^{(r)\prime}(x-y) \rm{d} y,\end{align}
 \begin{align}\frac{\partial^2}{\partial x^2} V^*(0,x)&=\int_{z^*}^x G(0,y)W^{(r)\prime \prime}(x-y) \rm{d} y+G(0,x)W^{(r)\prime}(0\!+\!).\end{align}
Hence, we see that
 $V_z$
is a
 $C^1$
function on
 $(\!-\!\infty,0]$
and its second derivative exists and is continuous on
 $(\!-\!\infty,0]\setminus \{z^*\}$
. Furthermore, by applying formula (3.7) to H(0, 0) (see equation (5.12)) and from (5.13) we see that
 \begin{align}\Phi'(r)\int_{(0,\infty)}\int_0^{\infty} G(v, y) \mathrm{e}^{-rv} \frac{y}{v}\mathbb{P}(X_{v} \in \rm{d} y) \rm{d} v &=H(0, 0)=\lim_{\varepsilon\downarrow 0} \frac{K^+(0,\varepsilon)}{\psi'(\Phi(r)) W^{(r)}(\varepsilon)}\nonumber\\ &=\Phi'(r)\frac{\sigma^2}{2}\frac{\partial }{\partial x} K^+(0,0\!+\!).\end{align}
Hence, from the equality above and (5.15) we deduce that
 \begin{align*}\frac{\partial}{\partial x} V^*(0,0\!+\!)=\frac{\partial}{\partial x} V^*(0,0\!-\!).\end{align*}
It can easily be seen that the process
 $\{ Z_{t\wedge \tau_{z^*}^-}^*,t\geq 0 \}$
is a martingale. Hence, by using standard arguments (cf. Section III.7.2 in [Reference Peskir and Shiryaev38] or Proposition 2.4 in [Reference Lamberton and Mikou31]), we deduce that
 \begin{align}\mathcal{A}_{U,X}(V^*)(u,x)+G=rV^*\end{align}
for all
 $(u,x)\in E$
such that
 $x\geq z^*$
, where from Corollary 3.1 we obtain that
 \begin{align*}\mathcal{A}_{(U,X)}(V^*)(u,x)&=\frac{\partial}{\partial u}V^*(u,x)\mathbb{I}_{\{x>0 \}}-\mu \frac{\partial}{\partial x} V^*(u,x)+\frac{1}{2}\sigma^2 \frac{\partial^2}{\partial x^2} V^*(u,x) \\&\quad +\int_{(\!-\!\infty,0)} \left( V^*(u,x+y) -V^*(u,x)-y\mathbb{I}_{\{y>-1\}}\frac{\partial }{\partial x} V^*(u,x) \right)\mathbb{I}_{\{x+y >0 \}}\Pi(\rm{d} y)\\& \quad + \int_{(\!-\!\infty,0)} \left( V^*(0,x+y) -V^*(0,x)-y\mathbb{I}_{\{y>-1\}}\frac{\partial }{\partial x} V^*(0,x) \right)\mathbb{I}_{\{x\leq 0 \}}\Pi(\rm{d} y)\\& \quad + \! \int_{(\!-\!\infty,0)}\! \left( V^*(0,x+y)-V^*(0,x)-y\mathbb{I}_{\{y>-1\}} \frac{\partial }{\partial x}V^*(u,x) \right)\mathbb{I}_{\{x>0 \}}\mathbb{I}_{\{x+y <0 \}}\Pi(\rm{d} y).\end{align*}
Hence, for any
 $(u,x)\in E$
,
 $t\geq 0$
and
 $N>0$
, by applying the version of Itô’s formula derived in Theorem 3.1 and letting
 $T=t \wedge \tau_N^+$
, we deduce that, under
 $\mathbb{P}_{u,x}$
,
 \begin{align*}\mathrm{e}^{-rT}&V^*(U_T,X_T)\\&=V^*(u,x)-\int_0^T \mathrm{e}^{-rs}rV^*(U_s,X_s)\rm{d} s + \int_{0}^{T } \mathrm{e}^{-rs}\frac{\partial }{\partial u} V^*(U_s,X_{s})\mathbb{I}_{\{ X_s>0\}} \rm{d} s\\&\qquad+\int_{0}^{T}\mathrm{e}^{-rs} \frac{\partial }{\partial x} V^*(U_{s-},X_{s-})\rm{d} X_s+\frac{1}{2} \sigma^2 \int_{0}^{T } \mathrm{e}^{-rs}\frac{\partial^2 }{\partial x^2} V^*(U_{s},X_{s})\rm{d} s\\\end{align*}
 \begin{align*}& \qquad +\int_{[0,T] }\mathrm{e}^{-rs} \int_{(\!-\!\infty,0)} \left( V^*(U_{s},X_{s^-}+y) -V^*(U_{s-},X_{s-})\right.\nonumber\\&\qquad \left.-y\frac{\partial }{\partial x} V^*(U_{s-},X_{s-}) \right)N(\rm{d} s\times \rm{d} y)\\&=M_{T}-\int_0^T \mathrm{e}^{-rs}[\mathcal{A}_{(U,X)}(V^*)(U_s,X_s)-rV^*(U_s,X_s)]\rm{d} s \\&=M_{T}-\int_0^T \mathrm{e}^{-rs}G(U_s,X_s)\mathbb{I}_{\{X_s>z^* \}}\rm{d} s,\end{align*}
where
 $\{ M_{t\wedge \tau_N^+}, t\geq 0\}$
is a martingale and the last equality follows since
 $V^*(0,x)=0$
for all
 $x\leq z^*$
and then
 $\mathcal{A}_{U,X}(V^*)(0,x)=0$
for all
 $x\leq z^*$
. Hence, we deduce that, for each
 $t\geq 0$
and
 $N>0$
,
 \begin{align*}Z^*_{t\wedge \tau_N^+}&=\mathrm{e}^{-r(t\wedge \tau_N^+)}V^*(U_{t\wedge \tau_N^+},X_{t\wedge \tau_N^+})+\int_0^{t\wedge \tau_N^+}\mathrm{e}^{-rs} G(U_s,X_s) \rm{d} s\\ &=M_{t\wedge \tau_N^+}+\int_0^{t\wedge \tau_N^+} \mathrm{e}^{-rs}G(0,X_s)\mathbb{I}_{\{X_s\leq z^* \}}\rm{d} s.\end{align*}
Hence, since
 $G(0,x)\leq 0$
for all
 $x\leq z^*\leq y_0$
, we conclude that
 $\{Z_{t\wedge \tau_N^+}^*,t\geq 0\}$
is a supermartingale as claimed.
Then the statements in Theorem 4.1 follow from Lemmas 5.4, 5.6 and 5.7. Finally, note from (5.16) that the smooth fit property holds in this case.
5.4. Proof of Proposition 4.1
Note that the optimal stopping problem is of the form (4.2), with
 $G(u,x)=\mathrm{e}^{x+\beta u}-K$
. From the definition of
 $\psi$
and since
 $U_s\leq u+s$
under
 $\mathbb{P}_{u,x}$
, for any
 $(u,x)\in E$
, we have that the assumption
 $r>\psi(1)+\beta$
implies that
 \begin{align*}\mathbb{E}_{u,x}\left(\int_0^{\infty} \mathrm{e}^{-rs}|G(U_s,X_s)|\rm{d} s \right)&\leq \mathrm{e}^x\mathbb{E}\left(\int_0^{\infty} \mathrm{e}^{-rs}\mathrm{e}^{X_s+\beta(u+s)}\rm{d} s \right)+\frac{K}{r}\\&=\frac{\mathrm{e}^{x+\beta u}}{r-\psi(1)-\beta} +\frac{K}{r} < \infty.\end{align*}
Due to (2.11) we see that for any
 $x>0$
and
 $u>0$
,
 \begin{align*}K^+(u,x)&=\mathbb{E}_{x}\left(\int_0^{\tau_0^-} \mathrm{e}^{-rs}[\mathrm{e}^{X_s+\beta(u+s) }-K]\rm{d} s\right)\\&=\int_{(0,\infty)} \mathrm{e}^{\beta u}\mathrm{e}^{y} \int_{0}^{\infty}\mathrm{e}^{-(r-\beta) s} \mathbb{P}_x(X_s \in \rm{d} y,s<\tau_0^-)\rm{d} s-\frac{K}{r}[1-\mathbb{E}_x(\mathrm{e}^{-r\tau_0^-}\mathbb{I}_{\{\tau_0^-<\infty\}})]\\&=\mathrm{e}^{\beta u} \left[ \frac{W^{(r-\beta)}(x)}{\Phi(r-\beta)-1} -\int_0^x \mathrm{e}^y W^{(r-\beta)}(x-y)\rm{d} y \right] +K\int_0^xW^{(r)}(y)\rm{d} y-\frac{K}{\Phi(r)}W^{(r)}(x),\end{align*}
where we used that
 $\Phi(r-\beta)>1$
due to the assumption
 $r>\psi(1)+\beta$
and since
 $\Phi$
is the right-inverse of
 $\psi$
. On the other hand,
 \begin{align*}\int_z^{0}G(0,y) \mathrm{e}^{-\Phi(r)y}\rm{d} y= \int_z^{0}[\mathrm{e}^y-K] \mathrm{e}^{-\Phi(r)y}\rm{d} y=\frac{\mathrm{e}^{-(\Phi(r)-1)z}-1}{\Phi(r)-1}-K\frac{\mathrm{e}^{-\Phi(r)z}-1}{\Phi(r)}.\end{align*}
By differentiating
 $K^+$
(see (5.18)) or by using Kendall’s identity (see (3.11)), we can easily see that
 \begin{align*}\int_{(0,\infty)}\int_0^{\infty} G(v, y) \frac{y}{v}\mathrm{e}^{-rv}\mathbb{P}(X_{v} \in \rm{d} y) \rm{d} v &=\frac{1}{\Phi(r-\beta)-1}-\frac{K}{\Phi(r)}.\end{align*}
Then from Theorem 4.1 we know that
 $\tau_{z^*}^-$
is optimal, where in this case
 $z^*$
is the unique solution on
 $(\!-\!\infty,0)$
to the equation
 \begin{align*}\frac{\mathrm{e}^{-(\Phi(r)-1)z}}{\Phi(r)-1}-\frac{K\mathrm{e}^{-\Phi(r)z}}{\Phi(r)}+\frac{1}{\Phi(r-\beta)-1}-\frac{1}{\Phi(r)-1}=0.\end{align*}
Lastly, from Theorem 4.1, we see that the value function is given by
 \begin{align*}V(u,x)&= K^+(u,x) -W^{(r)}(x)\int_{(0,\infty)}\int_0^{\infty} \! G(v, y) \frac{y}{v}\mathrm{e}^{-rv}\mathbb{P}(X_{v} \in \rm{d} y) \rm{d} v-\int_{z^*}^0 \!G(0,y)W^{(r)}(x-y) \rm{d} y\\&=\mathrm{e}^{\beta u} \left[ \frac{W^{(r-\beta)}(x)}{\Phi(r-\beta)-1} -\int_0^x \mathrm{e}^y W^{(r-\beta)}(x-y)\rm{d} y \right] +K\int_0^xW^{(r)}(y)\rm{d} y-\frac{K}{\Phi(r)}W^{(r)}(x)\\&\qquad-W^{(r)}(x)\left[\frac{1}{\Phi(r-\beta)-1}-\frac{K}{\Phi(r)} \right]-\int_{z^*}^0 [\mathrm{e}^{y}-K]W^{(r)}(x-y) \rm{d} y,\end{align*}
for any
 $(u,x)\in E$
. The proof is now complete.
Acknowledgements
The authors would like to thank two anonymous referees for their helpful comments and suggestions.
Funding information
There are no funding bodies to thank relating to this creation of this paper.
Competing interests
There were no competing interests to declare which arose during the preparation or publication process of this paper.



