1. Introduction
A stock loan is a financial derivative which provides an alternative for stock owners to obtain liquidity without selling their stocks. Since the value of a stock is subject to the fluctuations of the market, the value of the stock loan is affected by market conditions such as economic growth trends. Therefore, the assumption of constant volatility under the standard Black–Scholes (BS) framework, which is used in much of the existing literature on stock loan problems, is inadequate at times [Reference Huang, Forsyth and Labahn7, Reference Yao, Zhang, Zhou, Yan, Yin and Zhang24].
There are various extension studies in the literature of stock loans incorporating a nonconstant volatility. For example, the stochastic volatility model by Wong and Wong [Reference Wong and Wong20] and their exponential Levy model [Reference Wong and Wong21], and the work of Liang et al. [Reference Liang, Nie and Zhao10] extend the perpetual stock loan valuation under the Levy model to include stock loans with various dividend distributions.
In recent years, various stock loan models with regime-switching have also emerged in the literature. The regime-switching models allow key parameters of the stock to respond to the market dynamics based on the market mode (or “regime”) which switches among a finite number of states [Reference Yao, Zhang, Zhou, Yan, Yin and Zhang24], such that these models are able to capture the market dynamics more accurately than others [Reference Liu, Zhang and Yin11]. However, analytical solutions are only available for some special cases, including the stock loans of European style or American style with infinite maturity. Prager and Zhang [Reference Prager and Zhang17] introduced a regime-switching model for the finite maturity European-style stock loans, with the stock dynamics switching between geometric Brownian motion and mean-reversion. Zhang and Zhou [Reference Zhang and Zhou27] studied American-type perpetual stock loans under a two-state regime-switching economy, with the states representing the economic conditions, good and bad. The value of their stock loan is governed by a system of coupled BS equations and an analytic solution is obtained using the variational inequality method.
In practice, stock loans have finite maturities and flexible times for redemption of the stock, such that a typical stock loan resembles a finite maturity American call option. The finite horizon and American feature make an analytic solution of finite maturity stock loans unattainable. The additional complexity due to the uncertainty of states makes it even harder to price stock loans under a regime-switching economy. Because of the resemblance of the stock loans to American options, we refer to the literature for the valuation of American options under regime-switching volatility. While there exist closed-form solutions for European options with regime-switching, such as those presented in [Reference Buffington, Elliott and Pasik-Duncan3, Reference Mamon and Rodrigo15, Reference Naik16, Reference Zhu, Badran and Lu28], there is no analytical solution for the American counterpart owing to the presence of free boundaries, except for perpetual options as presented in [Reference Guo and Zhang5]. Naturally, one is “forced” to look for approximations in the form of either analytical or numerical approximations. There are various numerical approaches, including the tree method [Reference Yuen and Yang26], finite element methods [Reference Holmes, Yang and Zhang6, Reference Yang23], and the penalty method [Reference Khaliq and Liu9]. To the best of our knowledge, the only analytical approximation method for American options with regime-switching in finite maturity is that of Buffington and Elliott [Reference Buffington and Elliot2]. The price of an American option with regime-switching is decomposed into a European option part and an extra part as the result of American-style privilege. However, the implementation of the method in [Reference Buffington and Elliot2] is not straightforward, and it could be possibly time-consuming. From a practical point of view, it is more valuable to have a method that produces results in a timely manner. The semi-analytic approximation developed by Lu and Putri [Reference Lu and Putri14] provides a good balance since it produces an approximate solution efficiently for the original problem, which is not computationally tractable and is difficult to solve directly. Therefore, in this work, we utilize the approximation technique of Lu and Putri [Reference Lu and Putri14] to develop our solution for stock loans under a two-state regime-switching economy.
The rest of the paper is organized as follows. Section 2 establishes the governing equation system for stock loans with regime-switching volatility. In Section 3, our solution procedure is discussed. Section 4 presents some numerical examples to illustrate the effects of the loan parameters on the optimal exit prices, the stock loan values and the service fees under a regime-switching economy. The conclusion is given in Section 5.
2. The stock loan formulation
In this study, the stock loan is set in a two-state regime-switching economy, where the stock (underlying) volatility switches between two states, growth and recession. Thus, the stock price dynamics can be described as follows:
 $$ \begin{align*} dS=(r-\delta)S \,dt + \sigma_{X}S\,dW_t, \end{align*} $$
where
 $W_t$
is the standard Wiener process, S is the price of the underlying asset, t is the current time, r is the risk-free interest rate and
 $\delta $
is the constant continuous dividend rate. X is a continuous-time Markov chain with a finite state space,
 $$ \begin{gather*} X= \begin{cases} 1 \quad \text{when the economy is in growth}\\ 2 \quad \text{when the economy is in recession}, \end{cases} \end{gather*} $$
so
 $\sigma _X$
stands for the asset volatility in state X, and
 $\sigma _1> \sigma _2$
. The Markov chain X has a generator matrix
 $$ \begin{align*} \left( \begin{array}{@{}cc} -\xi_{12} & \xi_{12} \\ \xi_{21} & -\xi_{21} \end{array} \right)\end{align*} $$
with the transition rate from state i to state j being
 $\xi _{ij}>0$
,
 $i, j = 1, 2$
. Further,
 $W_t$
and X are assumed to be independent.
Let
 $V_i(S,t; \sigma _i)$
be the value of the stock loan in state i with finite maturity T. We assume that the risk associated with the regime-switching is diversifiable, so it is not priced separately as in [Reference Boyle and Draviam1, Reference Lu and Putri14, Reference Naik16, Reference Yi25, Reference Zhu, Badran and Lu28]. Therefore, by utilizing Itô’s lemma [Reference Itô8] and the principle of risk-neutral valuation, we derive the following coupled partial differential equations (PDEs) under the BS framework:
 $$ \begin{align*} \frac{\partial V_{1}}{\partial t} + \frac{1}{2} \sigma_{1}^{2} S^{2} \frac{\partial^{2} V_{1}}{\partial S^{2}} + (r-\delta) S \frac{\partial V_{1}}{\partial S} - r V_{1} &= \xi_{12}(V_1-V_2), \\[5pt] \frac{\partial V_{2}}{\partial t} + \frac{1}{2} \sigma_{2}^{2} S^{2} \frac{\partial^{2} V_{2}}{\partial S^{2}} + (r-\delta) S \frac{\partial V_{2}}{\partial S} - r V_{2} &= \xi_{21}(V_2-V_1). \end{align*} $$
The condition at the boundary
 $S=0$
and the final condition are the same for both
 $V_1$
and
 $V_2$
, that is, for
 $i =1, 2$
,
 $$ \begin{align*}V_i(0,t) = 0 \quad\text{and}\quad V_i(S,T) = \text{max}(S-qe^{\gamma T}, 0),\end{align*} $$
where q is the initial loan amount and
 $\gamma $
is the loan interest rate.
Since the stock loan is of American-type, similar to the case in [Reference Lu and Putri14], there are two different optimal exit boundaries corresponding to the two volatility states. Let
 $S_{fi}$
be the optimal exit price for state i for
 $i=1, 2$
. A stock loan behaves like an American call (see, for example, [Reference Lu and Putri12, Reference Xia and Zhou22]), such that at the optimal exit boundary
 $S=S_{fi}(t)$
, the value of the stock loan should take its intrinsic value
 $$ \begin{align*}V_i(S_{fi},t)= S_{fi} - qe^{\gamma t}.\end{align*} $$
However, the optimal boundary
 $S_{fi}(t)$
, which is not known in advance, needs to be solved as part of the solution. Therefore, an additional condition is needed:
 $$ \begin{align*} \frac{\partial V_{i}}{\partial S}(S_{fi},t) = 1. \end{align*} $$
This condition, which is called the smooth pasting condition, indicates that the partial derivative is continuous across the optimal exit boundary, and financially it reflects the optimal value of the loan contract for the holder, who has the right to exit the contract at the optimal boundary [Reference Wilmott, Howison and Dewynne19].
It is known that the higher the volatility of the underlying asset, the higher the option price for both calls and puts. For an American call, the increased option value means that the option can be exercised later, which implies a higher optimal exercise price, such that
 $S^{BS}_{f1}> S^{BS}_{f2}$
for
 $\sigma _1> \sigma _2$
, where
 $S^{BS}_{fi}$
is the optimal exercise price from the standard BS model. Under a regime-switching economy, it is expected that
 $S_{f2}< S_{f1}$
, but owing to the potential of the economy state to switch from state 1 to state 2, or vice versa,
 $ S_{f1} < S^{BS}_{f1}$
and
 $S_{f2}> S^{BS}_{f2} $
so that
 $S^{BS}_{f2} < S_{f2}< S_{f1} < S^{BS}_{f1}$
. This result is reported in [Reference Buffington and Elliot2, Reference Lu and Putri14, Reference Yang23] for American calls under a regime-switching economy. It is, therefore, reasonable to assume the same is true for stock loan contracts which behave like American calls with time-dependent strike, and it is proved by Zhang and Zhou [Reference Zhang and Zhou27] for perpetual stock loans with regime switching. For finite maturity stock loans, it becomes obvious in dimensionless variables as can be seen in the next section. Thus, the pricing domain is divided into two regions: the common continuation region
 $(0\leq S\leq S_{f2})$
and the transition region
 $(S_{f2}\leq S \leq S_{f1})$
. We derive the complete BS-type PDE systems as follows.
In the common continuation region, the value of the stock loan could be
 $V_1(S, t)$
or
 $V_2(S,t)$
depending on the volatility state. The values of the stock loan,
 $V_1$
and
 $V_2$
, satisfy the following PDE system:
 $$ \begin{align} \begin{cases} \dfrac{\partial V_{1}}{\partial t} + \dfrac{1}{2} \sigma_{1}^{2} S^{2} \dfrac{\partial^{2} V_{1}}{\partial S^{2}} + (r-\delta) S \dfrac{\partial V_{1}}{\partial S} - r V_{1} =\xi_{12}(V_{1}-V_{2})\\[4pt] V_{1}(0,t)=0\\[4pt] V_{1}(S,T)=\text{max}(S-qe^{\gamma T},0)\\[4pt] \dfrac{\partial V_{2}}{\partial t} + \dfrac{1}{2} \sigma_{2}^{2} S^{2} \dfrac{\partial^{2} V_{2}}{\partial S^{2}} + (r-\delta) S \dfrac{\partial V_{2}}{\partial S} - r V_{2}=\xi_{21}(V_{2}-V_{1})\\[4pt] V_{2}(0,t)=0\\[4pt] V_{2}(S,T)=\text{max}(S-qe^{\gamma T},0)\\[4pt] V_{2}(S_{f2}(t),t)=S_{f2}-qe^{\gamma t}\\[4pt] \dfrac{\partial V_{2}}{\partial S}(S_{f2}(t),t)=1. \end{cases} \quad 0\leq S\leq S_{f2} \end{align} $$
In the transition region,
 $V_2(S,t)$
takes the intrinsic value, that is,
 $S-qe^{\gamma t}$
, so the loan value
 $V_1$
satisfies the PDE system
 $$ \begin{align} \begin{cases} \dfrac{\partial V_{1}}{\partial t} + \dfrac{1}{2} \sigma_{1}^{2} S^{2} \dfrac{\partial^{2} V_{1}}{\partial S^{2}} + (r-\delta) S \dfrac{\partial V_{1}}{\partial S} - r V_{1}=\xi_{12}(V_{1}-(S-qe^{\gamma t}))\\[3pt] V_{1}(S,T)=\text{max}(S-qe^{\gamma T},0), \quad S_{f2}\leq S \leq S_{f1}\\[3pt] V_{1}(S_{f1}(t),t)=S_{f1}(t)-qe^{\gamma t} \\[3pt] \dfrac{\partial V_{1}}{\partial S}(S_{f1}(t),t)=1.\\[3pt] \end{cases} \end{align} $$
To ensure the continuity and smoothness of
 $V_{1}$
at the intersection of the two regions,
 $S=S_{f2}$
, the following conditions are enforced:
 $$ \begin{align} \begin{aligned} \lim_{S \to S_{f2}^{-}} V_{1}&=\lim_{S \to S_{f2}^{+}} V_{1}, \\ \lim_{S\to S_{f2}^{-}} \dfrac{\partial V_{1}}{\partial S}&=\lim_{S\to S_{f2}^{+}} \dfrac{\partial V_{1}}{\partial S}. \end{aligned} \end{align} $$
Theoretically, the solutions to the PDE systems (2.1) and (2.2) with (2.3) would give rise to the values of the stock loan and its optimal exit prices. However, not only are the PDE systems linear owing to the unknown optimal boundaries, the “strike” is also time dependent, in addition to the coupling of the systems. As it is well known that the analytical solution of the BS PDE only exists for the simplest case, we attempt to find an analytical approximation to the solution instead.
3. Solution procedure
First, we apply the following transformation of variables to the PDE systems (2.1) and (2.2), and condition (2.3):
 $$ \begin{align*}S = X{qe^{\gamma t}}, \ S_{fi}= X_{fi}qe^{\gamma t}, \ V_{i}(S,t) = U_{i}(X,\tau)\ {qe^{\gamma t}},\quad t=T-\tau, \ i =1, 2.\end{align*} $$
The resulting systems of equations are:
 $$ \begin{align} &\begin{cases} -\dfrac{\partial U_{1}}{\partial \tau} + \dfrac{1}{2} \sigma_1^{2} X^{2} \dfrac{\partial^{2} U_{1}}{\partial X^{2}} + (r- \gamma -\delta) X \dfrac{\partial U_{1}}{\partial X} - (r-\gamma)U_{1}=\xi_{12}(U_{1}-U_{2})\\[3pt] U_{1}(0,\tau)=0\\[3pt] U_{1}(X,0)=\text{max}(X-1,0)\\[3pt] -\dfrac{\partial U_{2}}{\partial \tau} + \dfrac{1}{2} \sigma_2^{2} X^{2} \dfrac{\partial^{2} U_{2}}{\partial X^{2}} + (r-\gamma-\delta) X \dfrac{\partial U_{2}}{\partial X} - (r-\gamma)U_{2}=\xi_{21}(U_{2}-U_{1})\\[3pt] U_{2}(0,\tau)=0\\[3pt] U_{2}(X,0)=\text{max}(X-1,0)\\[3pt] U_{2}(X_{f2},\tau)=X_{f2}-1 \\[3pt] \dfrac{\partial U_{2}}{\partial X}(X_{f2},\tau)=1, \end{cases} \end{align} $$
where
 $\tau \in [0, T]$
,
 $X \in [0, X_{f2}]$
, and
 $$ \begin{align} \begin{cases} -\dfrac{\partial U_{1}}{\partial \tau} + \dfrac{1}{2} \sigma_1^{2} X^{2} \dfrac{\partial^{2} U_{1}}{\partial X^{2}} + (r-\gamma-\delta) X \dfrac{\partial U_{1}}{\partial X} - (r-\gamma)U_{1}=\xi_{12}[U_{1}-(X-1)]\\[3pt] U_{1}(X,0)=X-1\\[3pt] U_{1}(X_{f1},\tau)=X_{f1}-1 \\[3pt] \dfrac{\partial U_{1}}{\partial X}(X_{f1},\tau)=1,\end{cases} \end{align} $$
where
 $\tau \in [0, T]$
,
 $X \in [X_{f2}, X_{f1}]$
.
The continuity conditions are as follows:
 $$ \begin{align} \begin{aligned} \lim_{X\to X_{f2}^{-}} U_{1}&=\lim_{X\to X_{f2}^{+}} U_{1}, \\ \lim_{X\to X_{f2}^{-}} \dfrac{\partial U_{1}}{\partial X}&=\lim_{X\to X_{f2}^{+}} \dfrac{\partial U_{1}}{\partial X}. \end{aligned}\end{align} $$
Clearly, if the term
 $r-\gamma $
in systems (3.1) and (3.2) is replaced by
 $\bar r$
, the resulting systems are the same as those in [Reference Lu and Putri14] for the corresponding American option problem. It is worth noting that
 $\overline {r}$
could take a negative value since the loan interest rate
 $\gamma $
is usually higher than the risk-free interest rate r for the loan contract to make financial sense. As a result, unlike American call options, stock loans could reach optimality for some parameter range even when no dividend is paid (see the works of Dai and Xu [Reference Dai and Xu4], and Lu and Putri [Reference Lu and Putri12]). Thus, we follow the techniques developed in [Reference Lu and Putri14] to obtain our solution for the stock loan PDE systems. For ease of reading, we recap some of the important steps here.
We apply the Laplace transform to the PDE systems in (3.1) and (3.2) as well as the conditions in (3). The pricing PDE systems are transformed into a set of ordinary differential equations (ODEs) in Laplace space. The solutions of the ODE system as the result of the Laplace transform of the PDE system (3.1) are:
 $$ \begin{align} \bar{U}_{1}(X, p)= \begin{cases} A_{1}X^{k_{1}}+A_{2}X^{k_{2}}+ A_{3}X^{k_{3}}+A_{4}X^{k_{4}}+\phi(X,p) &\text{if}\ 1<X\leq X_{f2}\\ A_{5}X^{k_{3}}+A_{6}X^{k_{4}} &\text{if}\ 0 \leq X\leq 1,\\ \end{cases} \end{align} $$
 $$ \begin{align} \bar{U}_{2}(X, p)= \begin{cases} B_{1}X^{k_{1}}+B_{2}X^{k_{2}}+ B_{3}X^{k_{3}}+B_{4}X^{k_{4}}+\phi(X,p) &\text{if}\ 1<X\leq X_{f2}\\ B_{5}X^{k_{3}}+B_{6}X^{k_{4}} &\text{if}\ 0 \leq X\leq 1, \end{cases} \end{align} $$
where
 $$ \begin{align*}\phi(X,p)=\dfrac{1}{p+\delta}X-\dfrac{1}{p+\overline{r}},\end{align*} $$
and
 $k_{1}<k_{2}<0<k_{3}<k_{4}$
are the roots of the quartic indicial equation for the ODE system;
 $A_{i}$
and
 $B_{i}$
,
 $i = 1, 2, 3 \ldots 6$
, are some constants in Laplace space.
The solution of the ODE in Laplace space corresponding to the PDE system (3.2) in the transition region is
 $$ \begin{align} \bar{U}_{1}(X, p)=m_{1}X^{\gamma_{1}}+m_{2}X^{\gamma_{2}}+ \psi_1 X - \psi_2, \quad X_{f2} \le X \le X_{f1}, \end{align} $$
where
 $$ \begin{align*}\psi_1 = \dfrac{p+\xi_{12}}{p(p+\delta+\xi_{12})}, \quad \psi_2 = \dfrac{p+\xi_{12}}{p(p+r+\xi_{12})},\end{align*} $$
 $m_1$
and
 $m_2$
are integration constants, and
 $\gamma _{1}$
and
 $\gamma _2$
are the solutions to the indicial equation of the ODE.
Applying all the necessary conditions of the PDE system to solutions (3.4)–(3.6), after some tedious algebraic manipulations we obtain the following coupled equation system for the computation of
 $\bar {X}_{f1}$
and
 $\bar {X}_{f2}$
, the optimal exit prices in Laplace space:
 $$ \begin{align} \begin{pmatrix} (p\bar{X}_{f1})^{-\gamma_{1}} & 0 \\ 0 & (p\bar{X}_{f1})^{-\gamma_{2}}\\ \end{pmatrix} F_{1}(p\bar{X}_{f1}) = \begin{pmatrix} (p\bar{X}_{f2})^{-\gamma_{1}} & 0 \\ 0 & (p\bar{X}_{f2})^{-\gamma_{2}}\\ \end{pmatrix} F_{2}(p\bar{X}_{f2}), \end{align} $$
where functions
 $F_1$
and
 $F_2$
are listed in the Appendix.
Equation (3.7) is the end of the analytical approach; the highly nonlinear equation has to be solved numerically. However, only a simple MATLAB solver, fsolve, is needed for the solution of the nonlinear equation. Once equation (3.7) is solved for
 $\bar {X}_{f1}$
and
 $\bar {X}_{f2}$
, it is routine to compute solutions
 $\bar {U}_{1}(X, p)$
and
 $\bar {U}_{1}(X, p)$
from equations (3.4)–(3.6). A numerical inversion scheme (the Stehfest method [Reference Stehfest18]) is used to obtain the optimal exit prices and the values of the stock loans in the original space. It is then straightforward to calculate the fair service fees.
4. Numerical experiments
In this section, numerical examples are presented to show the effects of the volatility states on the optimal exit prices, stock loan values and service fees. The effects of different loan parameters on basic properties of the stock loans are also explored. Our calculations are carried out using MATLAB R2015a on an Intel(R) Core(TM)2 Quad CPU Q9550 @2.38GHz RAM 8 GB on a Windows 7 Enterprise Service Pack 1 system.
4.1. Perpetual stock loans
To validate our solution technique, we present a comparison of the results of our calculations for maturity T tending to infinity with those from the analytic method in [Reference Zhang and Zhou27], for a perpetual American-style stock loan under a regime-switching economy. For the purpose of comparison, the same parameters are used as in [Reference Zhang and Zhou27].
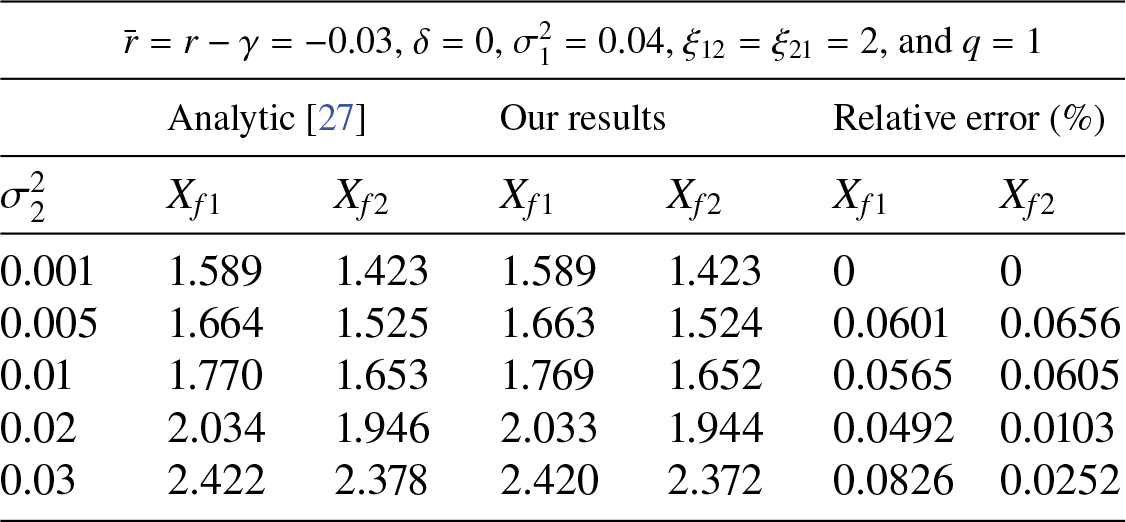
Table 1 shows the dimensionless optimal exit prices for various values of
 $\sigma _{2}^2$
with a fixed
 $\sigma _{1}^2$
value. As shown in the table, the relative errors are far less than 0.1%, indicating the accuracy of our method for the calculation of the optimal exit price of perpetual stock loans.
Dimensionless optimal exit price of a perpetual stock loan.

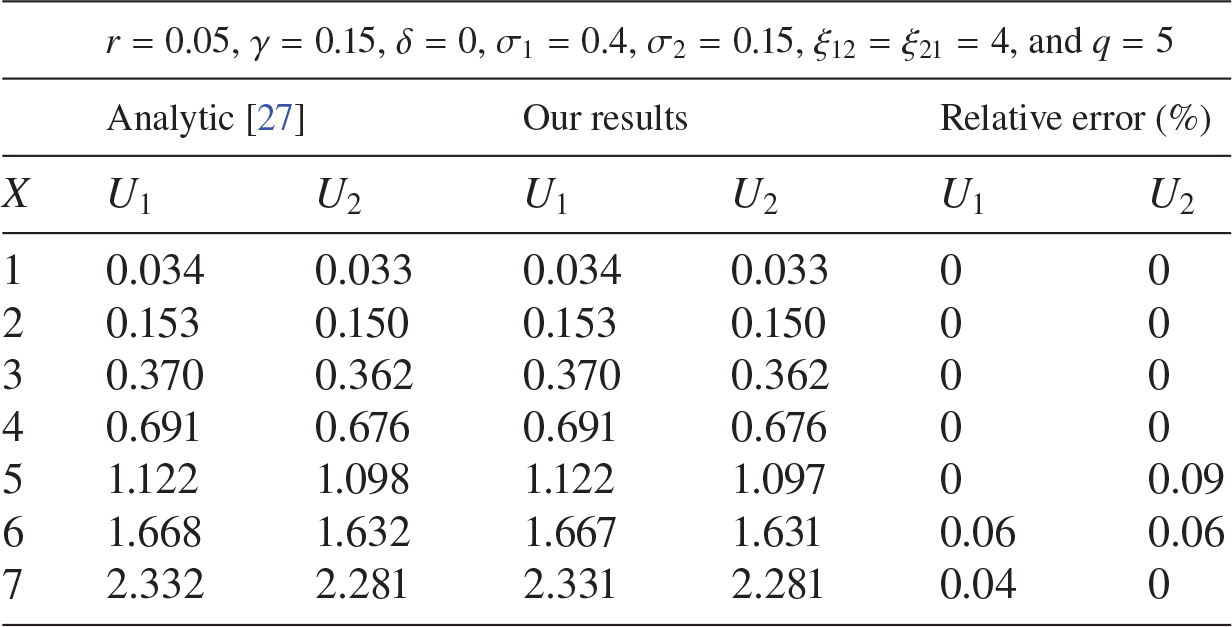
The values of perpetual American stock loans under a regime-switching economy are also calculated and compared with those obtained in [Reference Zhang and Zhou27], as shown in Table 2. Again, there is good agreement between our results and those obtained by the analytical method, with maximum relative error less than
 $0.1\%$
.
Dimensionless perpetual stock loan value at
 $t=0$
.

4.2. Finite maturity stock loans
Having validated the accuracy of our method in the previous section, we present our calculations of the optimal exit prices, values and fair service fees of a finite maturity stock loan under a regime-switching economy in dimensional variables.
4.2.1. Optimal exit prices
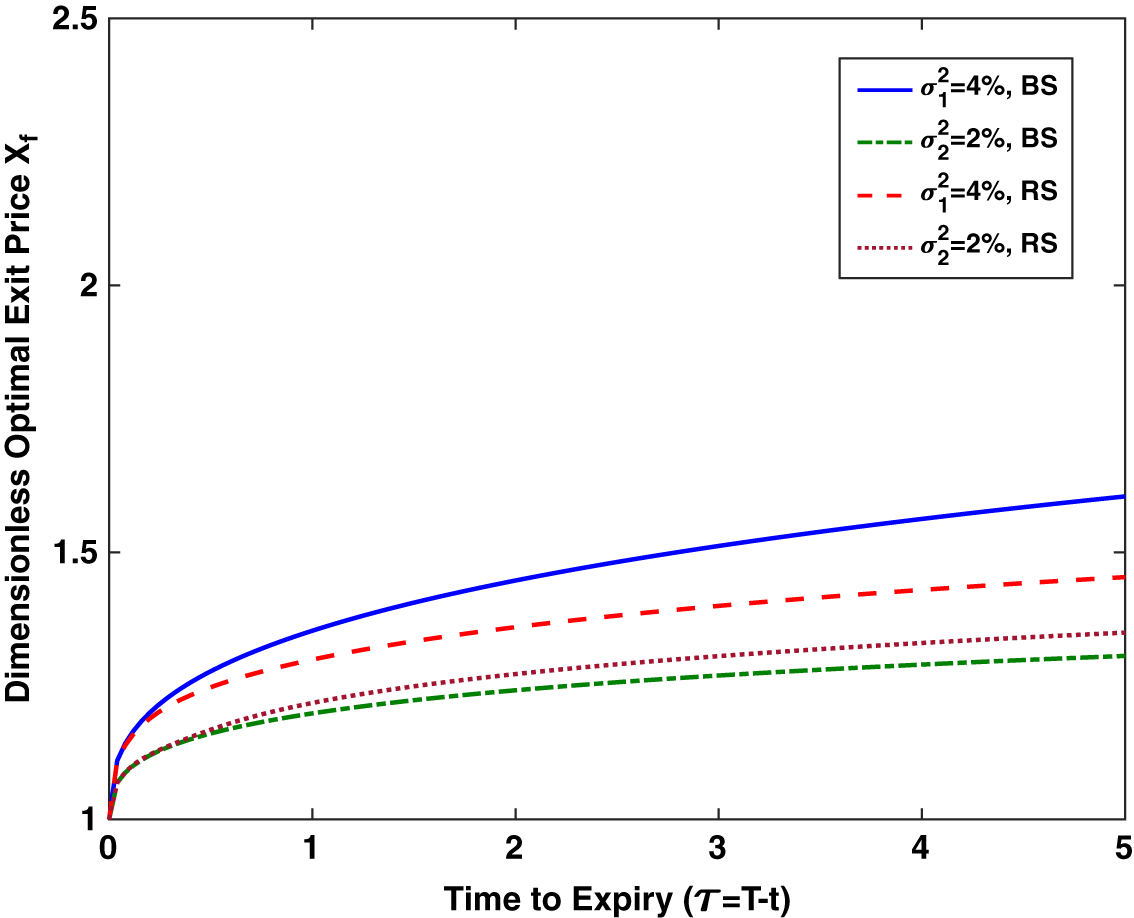
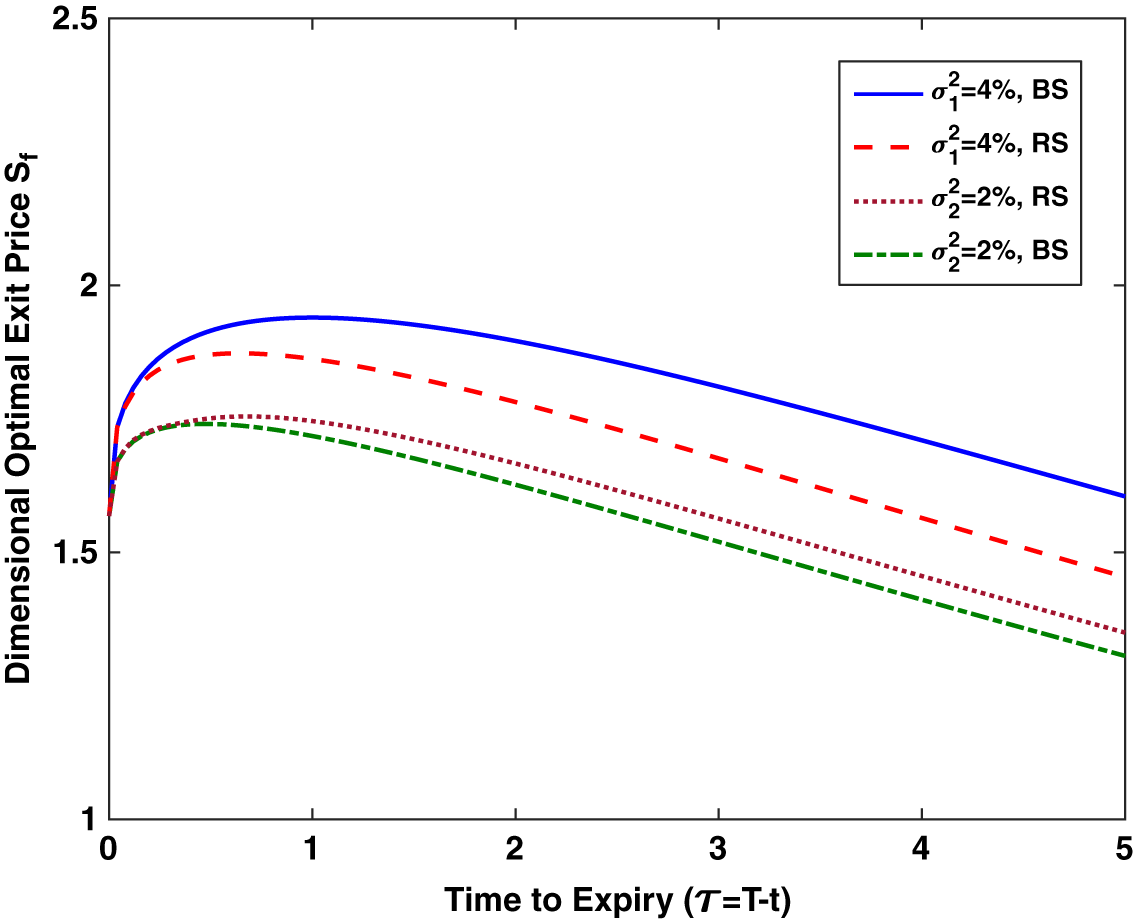
We first present a comparison of the optimal exit prices under a regime-switching economy with those under the standard BS framework (Figures 1 and 2). The parameters used in the computation are, unless otherwise stated,
 $\bar {r}= r - \gamma = -0.03$
,
 $\delta =0$
,
 $\sigma _{1}^{2}=0.04$
,
 $\sigma _{2}^{2}=0.02$
,
 $\xi _{12}=\xi _{21} = 2$
,
 $q=1$
, and
 $T=5$
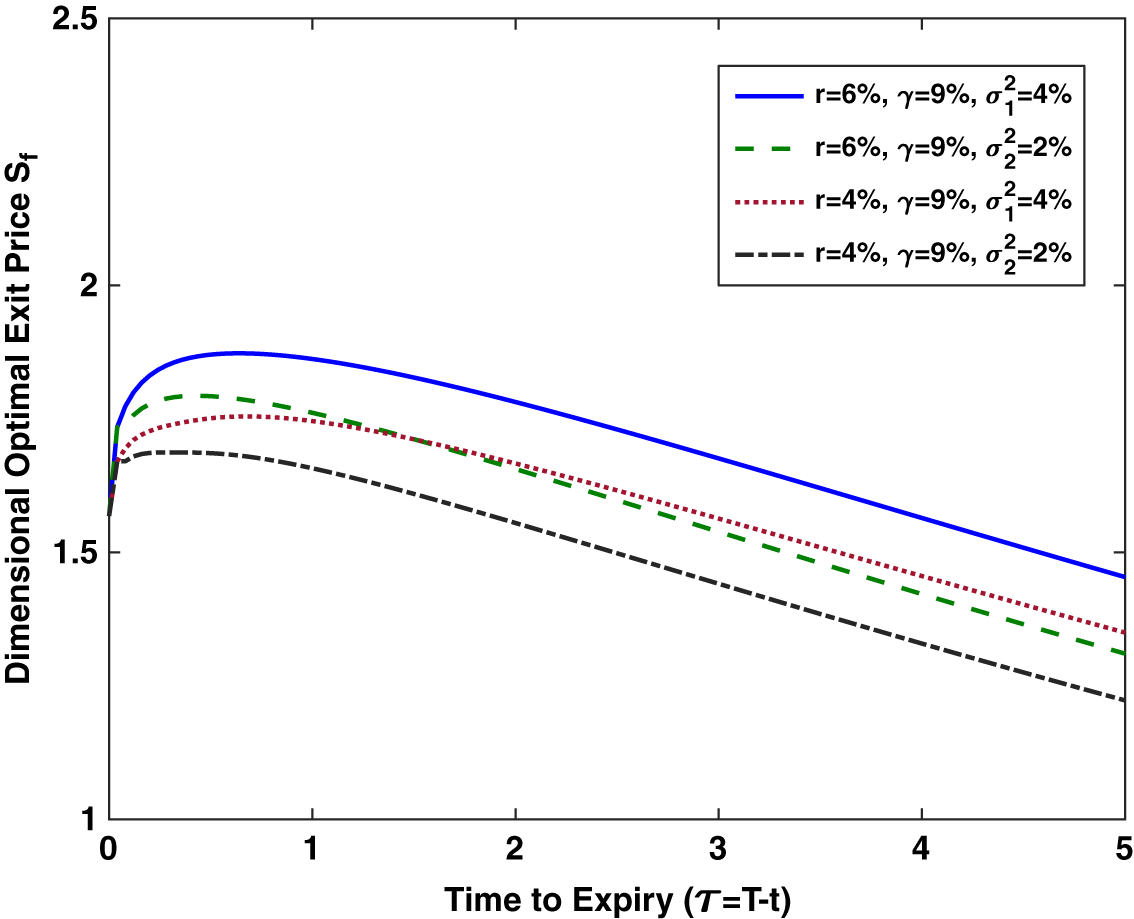
. As expected, the curves of the optimal exit prices for the higher volatility are above the ones for the lower volatility, and the ones with regime-switching volatility are bounded in-between by the ones with constant volatility (the standard BS model).
Dimensionless optimal exit price.

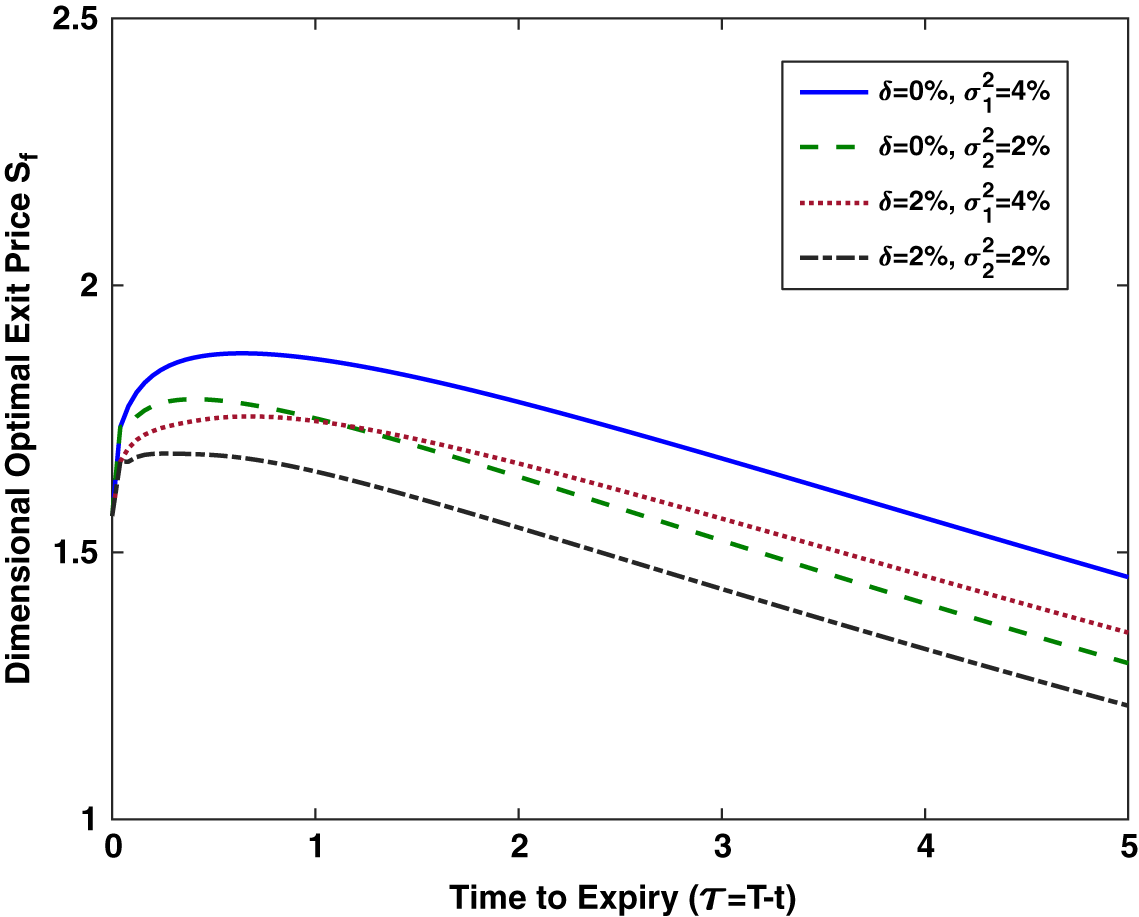
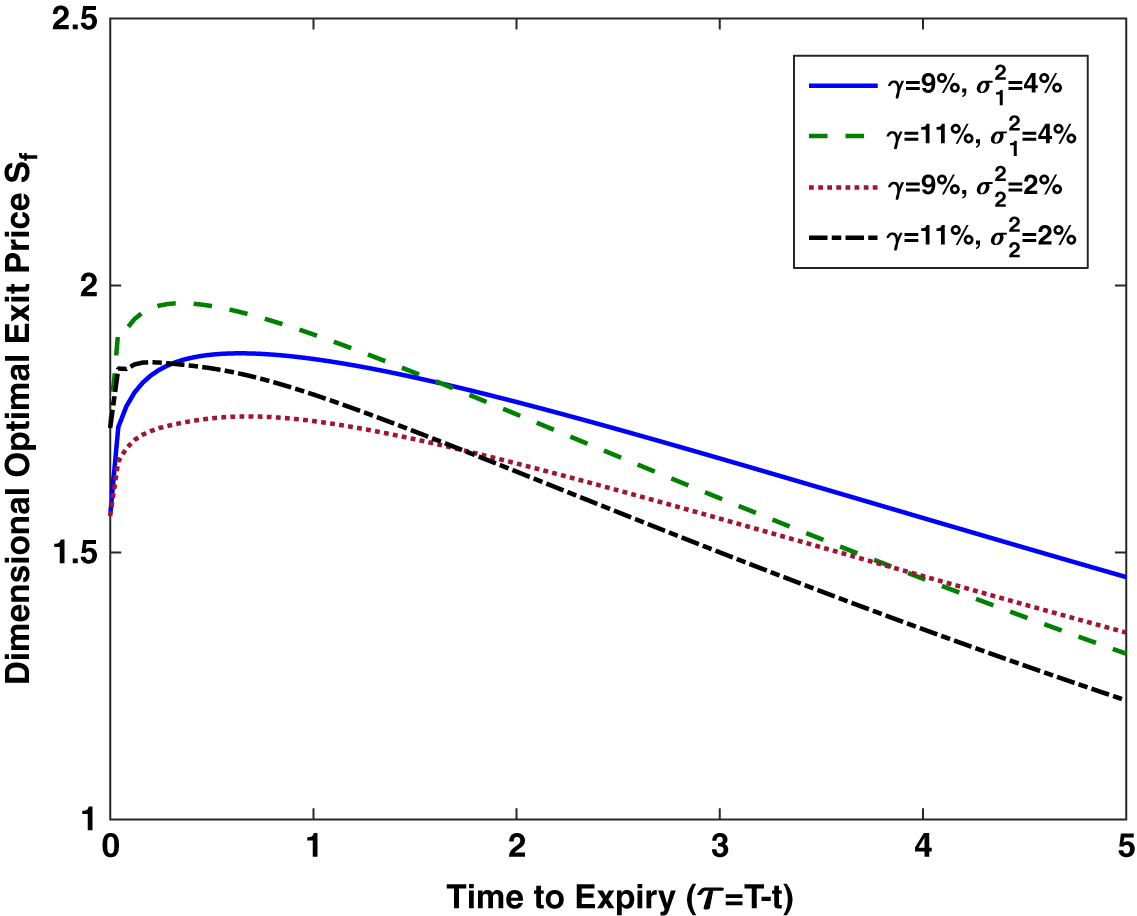
Dimensional optimal exit price.

Under a regime-switching economy, the dimensionless optimal exit prices for stock loans follow the same trend as those for American call options—the dimensionless optimal exit price
 $X_{fi}$
is finite and monotonically increasing with respect to time to expiry (Figure 1). However, unlike an American call, a stock loan can reach optimality even when no dividend is paid for the underlying stock, as long as
 $r < \gamma $
for standard stock loans, which is true for financially viable stock loan settings [Reference Dai and Xu4, Reference Lu and Putri12]. It is also worth pointing out that the dimensional optimal exit price
 $S_{fi}$
is not monotonic with respect to time (Figure 2). This is is due to the two competing factors: the time-dependent “strike” (
 $qe^{\gamma t},\ t\in [0, T]$
) and the “call” nature of the loan near expiry as discussed in [Reference Lu and Putri13]. Since the dimensional optimal exit price increases with time, the longer the loan contract, the higher the optimal exit price near maturity. Nevertheless, a stock loan contract should always have a finite maturity, such that its optimal exit price will remain finite.
Figure 3 displays the optimal exit prices for different values of r, with
 $\gamma $
fixed at
 $0.09$
and all other parameters the same as before. Clearly, when the risk-free interest rate r is lower, the optimal exit price is also less compared with the one for higher r at the same volatility, consistent with the trend for American calls.
Optimal exit price with regime-switching volatility for different risk-free interest rates.

The optimal exit prices for different dividend rates are presented in Figure 4, with other parameters as stated before. Again, as for American call options, higher dividend rates correspond to lower optimal exit prices. The stock price is expected to drop by the dividend amount on the ex-dividend date, so a higher amount of dividend paid will lead to a lower optimal exit price and a lower value of the stock loans.
Optimal exit price with regime-switching volatility for different dividend rates.

Figure 5 depicts the optimal exit prices corresponding to different loan interest rates
 $\gamma $
. It is interesting to note that the curves of the optimal prices under the same economy state intersect. This is a unique feature of the stock loans. A stock loan behaves like an American call, whose optimal exercise price increases if the strike price is higher. On the one hand, the time-dependent “strike” of a stock loan increases exponentially with the loan interest rate
 $\gamma $
, so the optimal exit price for the loan with higher
 $\gamma $
(higher strike) increases at a faster rate. On the other hand, the initial value of the loan with higher
 $\gamma $
is lower, and so is its optimal exit price. As a result, both optimal prices increase at first, with the rate of increase dominated by
 $\gamma $
, so the initially lower optimal price surpasses the other optimal price at some time during the lifetime of the loan,
 $[0, T]$
, and eventually both decrease to lower values close to the time of maturity.
Optimal exit price with regime-switching volatility for different loan interest rates.

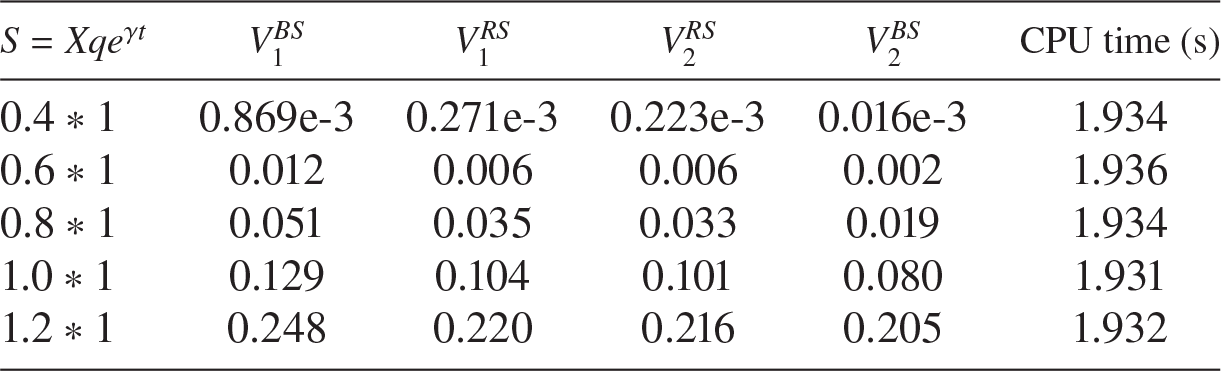
Value of stock loan with regime-switching (
 $RS$
) volatility at
 $t=0$
.

Value of stock loan with regime-switching (
 $RS$
) volatility at
 $t=2$
.

4.2.2. Stock loan values
Here we present a comparison of the values of stock loans under a regime-switching economy and under the BS framework at different times for the following loan parameters:
 $r=0.06$
,
 $\gamma =0.09$
,
 $\delta =0$
,
 $\sigma _{1}^{2}=0.04$
,
 $\sigma _{2}^{2}=0.02$
,
 $\xi _{12}=\xi _{21} = 2$
,
 $q=1$
and
 $T=5$
.
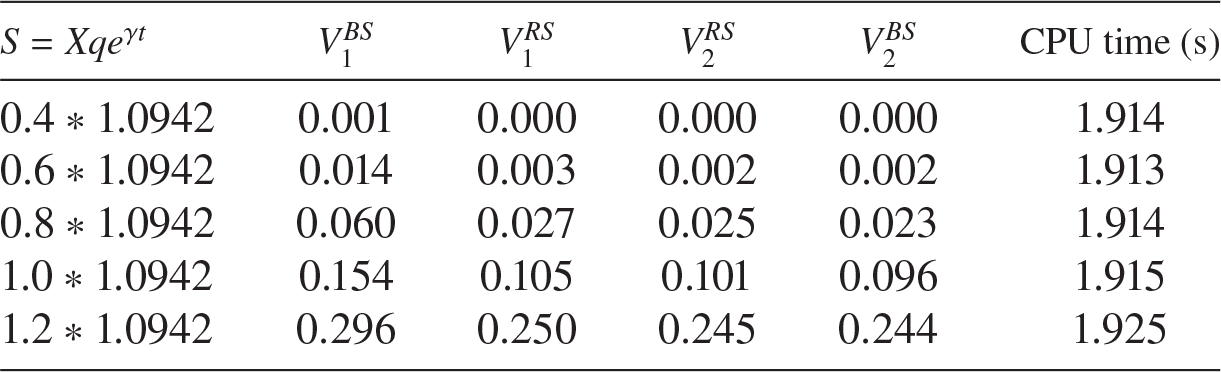
As shown in Tables 3 and 4, the values of the stock loans under a regime-switching economy are bounded by those under the BS model, that is,
 $V_{2}^{BS}<V_{2}^{RS}<V_{1}^{RS}~<~V_{1}^{BS}$
. This makes financial sense, because while the economy is in state 1 (growth), there is always a possibility that it will go into state 2 (recession) during the life of the loan contract, so that
 $V_{1}^{RS} < V_{1}^{BS}$
. Similarly, there is always a chance of the economy moving to state 1 from state 2, so that
 $V_{2}^{RS}> V_{2}^{BS}$
.
Although the computation is carried out on a relatively slow computer, the time used to calculate a value of stock loan is still less than 2 s. Considering that the computation time includes the calculation of the optimal exit prices, our technique is efficient compared with purely numerical methods such as finite difference methods and simulation methods.
4.2.3. Fair service fees
So far we have seen that under a regime-switching economy, the value of stock loans is affected by the probability of changes in the state of the economy. Naturally, the fair service fee is also dependent on the state of the economy, and it can be computed in a similar way to that for the standard stock loan [Reference Lu and Putri12]. The service fee is determined at the beginning of the contract based on the initial value of the stock loan, and it can be calculated as
 $c_{i}=V_{i0}-(S_{0}-q)$
, where
 $c_i$
is the fair service fee in state i of the economy when the contract is made,
 $S_0$
is the initial value of the collateral stock, q is the loan principal, and
 $V_{i0}$
is the initial value of the stock loan in state i. Since a stock loan has a greater value in a state of higher volatility, for a loan of the same amount, the fair service fee is higher if the loan is established in the state of growth, and vice versa.
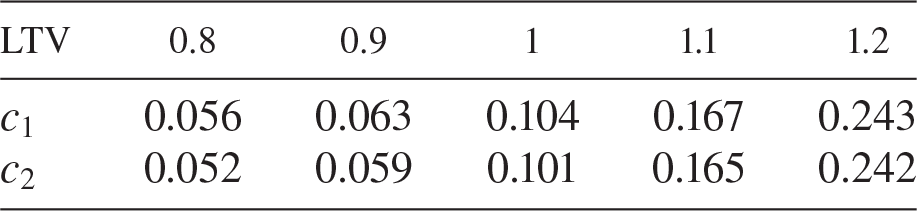
Table 5 lists the fair service fees corresponding to various loan-to-value (LTV) ratios, where LTV=
 $q/S_{0}$
. A larger loan amount requires a higher service fee as the lender bears more risk. A stock loan contract under a regime-switching economy is marketable for any LTV
 $> q/S_{f1}=0.740 $
if the economy is initially in state 1, and LTV
 $>q/S_{f2}=0.687$
if the economy is in state 2.
Fair service fee under regime-switching economy (
 $T=5$
and
 $S_0=1$
).

5. Conclusion
In this paper, we have formulated a pricing system for a stock loan under a regime-switching economy, and solved the resulting PDEs by using the approach developed by Lu and Putri [Reference Lu and Putri14] for the corresponding American option problem. Our results could help the lender to decide on a marketable stock loan and its fair service fee, and help the borrower to decide on an exit strategy, when the state of the economy is subject to change.
The work presented here is for a “standard” stock loan in the sense that the dividend payment is collected by the lender, and paid back to the borrower at maturity or upon exit from the loan. It can also be extended to stock loans with other dividend payment distributions (see the work of Dai and Xu, and Lu and Putri [Reference Dai and Xu4, Reference Lu and Putri12]).
Appendix. Functions
 $\boldsymbol {F}_{\mathbf {1}}$
and
$\boldsymbol {F}_{\mathbf {2}}$


Here we list the functions
 $F_1$
and
 $F_2$
, and other constants in equation (3.7).
 $$ \begin{align*} F_1(p\bar{X}_{f1})=a_{1}+a_{2}(p\bar{X}_{f1}), \end{align*} $$
 $$ \begin{align*} a_{1} = \dfrac{1}{\gamma_{2}-\gamma_{1}} \begin{pmatrix} -\gamma_{2} \\ \gamma_{1} \\ \end{pmatrix}\bigg(\dfrac{1}{p}-\psi_{2}\bigg), \end{align*} $$
 $$ \begin{align*} a_{2} = \dfrac{\psi_{1}}{\gamma_{2}-\gamma_{1}} \begin{pmatrix} \gamma_{2}-1 \\ 1-\gamma_{1}\\ \end{pmatrix}\bigg(\dfrac{1}{p}-\psi_{1}\bigg), \end{align*} $$
 $$ \begin{align*} F_2(p\bar{X}_{f2})=b_{1}+b_{2}(p\bar{X}_{f2})+b_{3}\begin{pmatrix} (p\bar{X}_{f2})^{k3} & 0 \\ 0 & (p\bar{X}_{f2})^{k4} \\ \end{pmatrix} \begin{pmatrix} A_{3} \\ A{4} \\ \end{pmatrix}, \end{align*} $$
 $$ \begin{align*} b_{1} =- \begin{pmatrix} 1 & 1 \\ \gamma_{1} & \gamma_{2} \\ \end{pmatrix}^{-1} \left[ \begin{pmatrix} 1 & 1 \\ k_{1} & k_{2} \\ \end{pmatrix} \begin{pmatrix} l_{1} & l_{2} \\ l_{1}k_{1} & l_{2}k_{2} \\ \end{pmatrix}^{-1} \begin{pmatrix} \dfrac{r}{p(p+r)} \\ 0 \\ \end{pmatrix} + \begin{pmatrix} \dfrac{p}{p(p+r)}-{\psi_{2}} \\ 0 \\ \end{pmatrix} \right], \end{align*} $$
 $$ \begin{align*} b_{2} = \begin{pmatrix} 1 & 1 \\ \gamma_{1} & \gamma_{2} \\ \end{pmatrix}^{-1} \left[\begin{pmatrix} 1 & 1 \\ k_{1} & k_{2} \\ \end{pmatrix} \begin{pmatrix} l_{1} & l_{2} \\ l_{1}k_{1} & l_{2}k_{2} \\ \end{pmatrix}^{-1} \begin{pmatrix} \dfrac{\delta}{p(p+\delta)} \\ \dfrac{\delta}{p(p+\delta)} \\ \end{pmatrix} + \begin{pmatrix} \dfrac{p}{p(p+\delta)}-{\psi_{1}} \\ \dfrac{p}{p(p+\delta)}-{\psi_{1}} \\ \end{pmatrix}\right], \end{align*} $$
 $$ \begin{align*} b_3 =- \begin{pmatrix} 1 & 1 \\ \gamma_{1} & \gamma_{2} \\ \end{pmatrix}^{-1} \left[\begin{pmatrix} 1 & 1 \\ k_{1} & k_{2} \\ \end{pmatrix} \begin{pmatrix} l_{1} & l_{2} \\ l_{1}k_{1} & l_{2}k_{2} \\ \end{pmatrix}^{-1} \begin{pmatrix} l_{3} & l_{4} \\ l_{3}k_{3} & l_{4}k_{4} \\ \end{pmatrix}-\begin{pmatrix} 1 & 1 \\ k_{3} & k_{4} \\ \end{pmatrix}\right]. \end{align*} $$