INTRODUCTION
Financial models of asset pricing traditionally have not done a very good job of explaining observed variation in stock prices. The failure seems to stem from an inability of pricing models to generate sufficient variation in implied price-dividend ratios. For instance, the constant discount factor present value model with a random walk process for dividends implies a constant price-dividend ratio, whereas the observed series shows great fluctuations over time (Leroy and Porter, 1981; Shiller, 1981).
One method to generate nonconstant price-dividend ratios in this model is to entertain solutions to asset prices that do not satisfy the transversality condition. Such solutions that are rational and depend only on the fundamentals of the model and not on any extraneous factors (such as calendar time) are termed as rational intrinsic bubbles by Froot and Obstfeld (1991).
In the linear present value model with exogenous dividends as the only fundamentals, intrinsic bubbles turn out to be nonlinear deterministic functions of dividends. Their nonlinear nature allows bubble solutions to generate nonconstant price-dividend ratios, and allows them to capture excess sensitivity of stock prices to movements in dividends. However, the nonlinear nature of bubbles also implies that they are explosive in nature. With high values of dividends the bubble component of stock prices will be very large. This remains an unsatisfactory feature of bubble solutions to the present value model.
Recent literature suggests that the degree of nonlinearity required to generate observed variation in a data series is reduced when one accounts for any fat tails that may exist in the empirical distributions of the data (Bidarkota, 2000). There is a long and celebrated literature documenting fat tails in stock prices, going back to early work by Mandelbrot (1963). McCulloch (1996) provides a summary of evidence on fat tails in stock prices. In a more recent paper, Lux and Sornette (2002) demonstrate theoretically that stock prices driven by processes with rational bubble components exhibit fat tails.
Mandelbrot (1963) advocated the use of stable distributions for modeling these fat tails. McCulloch (1996) provides a comprehensive survey on the financial applications of stable distributions. These distributions are the natural extensions of Gaussian distributions, which are widely used on account of their convenience and ease of analytical tractability. Gaussian errors are also often motivated by their Central Limit attributes. If financial markets evolve as an outcome of several individually unimportant decisions of a large number of investors, then one may appeal to the Central Limit Theorem and assume that stock prices can be modeled as Gaussian processes. However, exactly the same argument holds in the stable case as well since the Generalized Central Limit Theorem dictates that the limiting distribution of such a process must belong to the more general class of stable distributions of which the Gaussian is just one member (Zolotarev, 1986).
In this paper, we study rational intrinsic bubbles in the constant discount factor present value model where the only exogenous fundamentals (dividends) evolve as a random walk stochastic process with innovations that have stable distributions.1
The associate editor notes whether the “assumption of risk neutrality is particularly implausible when there are fat tails.” This is a good point that merits investigation in the context of an asset pricing model such as that of Lucas (1978) that allows for risk aversion on the part of investors and a fat tailed process for dividends (as, for instance, in Bidarkota and McCulloch 2003 or Bidarkota and Dupoyet 2006). However, it is not obvious whether intrinsic bubbles (defined as price paths that satisfy a present value-type equation but violate the transversality condition) can exist theoretically in the Lucas (1978) model. Recent work by Kamihigashi (1998) shows the necessity of the transversality condition in dynamic stochastic optimization models under very general conditions, and hence that bubbles are a marginal phenomenon in such models (see also Montrucchio and Privileggi 2001).
Driffill and Sola (1998) also study intrinsic bubbles in the present value model, assuming that dividends follow a Markov switching process proposed by Hamilton (1989). They find that the incremental explanatory power of the bubble component over the present value fundamental component is significantly reduced when discrete regime changes are allowed in the mean and volatility of the dividends process. Ackert and Hunter (1999) demonstrate that the nonlinear relationship between stock prices and dividends may also arise from management decisions regarding dividend payouts.
Alternative rationalizations, such as fads and periodically collapsing bubbles, also have been proposed for the failure of the present value model, as in Blanchard (1979), Evans (1991), and Brooks and Katsaris (2005).
The paper is organized as follows. We set out the present value model for stock prices in Section 2 and describe what we mean by the fundamental solution and a bubble solution. In Section 3 we derive the fundamental stock price and the bubble under the assumption that dividends evolve as a random walk process with stably distributed innovations. We also compare this solution with that obtained under a Gaussian random walk for dividends. In Section 4, we undertake an empirical study to determine to what extent the present value model, with and without the bubble components, explains the observed variation in stock prices in stable and Gaussian settings. We summarize our main findings in the concluding section.
THE PRESENT VALUE MODEL
The present value model with a constant discount rate is given by:

Here, Pt is the real price of a share at the beginning of period t, Dt are the real dividends per share paid out over period t, r is the nonstochastic and constant discount rate, Et is the mathematical expectation, conditioned on information available at the start of period t.
On forward iteration, the present value equation yields:

One solution to stock prices in the above equation, denoted
, is obtained by imposing the transversality condition:

Imposing the transversality condition on equation (2) gives:

Thus, this equation provides the fundamental value of the stock price. One specifies an exogenous stochastic process for dividends and evaluates
.
There exist other solutions to the present value model given in equation (1) that do not satisfy the transversality condition in equation (3). For instance, let
be any sequence of random variables that satisfy:

One can easily show that
satisfies equation (1) but violates equation (3) for all Bt≠0.
If Bt is constructed as a function of the fundamentals alone, that is, as a function of the dividends Dt alone in the present value model of equation (1), it is termed an intrinsic rational bubble by Froot and Obstfeld (1991). Intrinsic bubbles turn out to be a nonlinear function of dividends. Their exact functional form depends on the assumed stochastic process for the dividends.
SOLUTION TO THE MODEL
In this section, we obtain an exact analytical solution for the present value stock price
when the dividend growth rate follows a random walk with drift with innovations drawn from the family of stable distributions. The Gaussian random walk emerges as a special case. We also derive conditions under which a posited functional form for Bt satisfies all the conditions for a rational intrinsic bubble.
Specification of the Dividends Process
We assume that log-dividends stochastically evolve according to the law of motion:

Here, S(α, β, c, 0) represents a stable distribution with characteristic exponent α, skewness parameter β, scale parameter c, and location parameter set to zero. Appendix A defines these distributions and lists some of their properties.
For s≥t, equation (6) implies that:

Substituting this into the solution for the fundamental stock price given in equation (4) yields:

In deriving equation (8), we assume that Dt is contained in the information set available at the start of period t on which the expectations Et are based.
Finiteness of Conditional Expectations
Given the iid nature of the innovations {ξt} to the dividends process, the expectations term on the right hand side of equation (8) reduces to:

When {ξt} is iid normal, each of the conditional expectations on the right-hand side of the above equation are finite and are given by the moment generating function. Under most commonly used fat-tailed distributions including the Student-t, such conditional expectations are generally infinite. This point has been noted by Geweke (2001) in a more general setting. Thus, when {ξt} is iid nonnormal stable, that is, when the exponent α characterizing these innovations is less than 2, each of the conditional expectations is generally infinite. An exception occurs when the skewness parameter β=−1 (see Appendix A). Equation (A8) gives the formulas for the conditional expectations under β=−1.
In the remainder of this paper, we are forced to work with stable distributions with β=−1. One could in principle avoid having to impose β=−1 by truncating the stable distributions, or dampening them as in Bidarkota and Dupoyet (2006). However, in this case, one cannot derive an analytical formula for the present value stock price
as is done in the next subsection, nor can one obtain a parametric form for the bubble component B(Dt) as is done subsequently.
Solving for the Present Value Stock Price
Thus, under the assumption that dividends evolve according to the stochastic process given in equation (6) with β=−1, one can now derive the present value stock price by evaluating the right hand side of equation (8). The expression for
differs in the case when the characteristic exponent α=1 from that when α≠1.2
This arises because of two reasons. One reason is that the expressions for EeX differ in the two cases (see equation (A.8) in Appendix A). A second reason is that when we aggregate iid random variables with stable distributions, the expressions for the location parameter δ for the aggregate random variable also differ in the two cases (see equation (A.7) in Appendix A).
Appendix B shows that the present value stock price is given by:

where:

For convergence of the infinite summation in equation (8), we need\break
.
Intrinsic Rational Bubbles
Let us postulate that intrinsic rational bubbles take the form given in Froot and Obstfeld (1991):

Here, λ>0 for the bubble to grow with an increase in dividends and a0>0 to ensure non-negativity of stock prices.
Appendix C shows that the functional form for the intrinsic bubble in equation (12) satisfies equation (5) defining a bubble, provided that λ is chosen to satisfy:

The inequality
can be used to show that λ>1 whenever the characteristic exponent α>1.
Solution under Gaussian Random Walk
If the process for dividend growth rates is a Gaussian random walk plus drift, that is, if the innovations in equation (6) were Gaussian, then the solution for the present value stock price is easily obtained by setting α=2 in equations (10) and (11). One can readily show that the expression obtained for the stock prices in this case is identical to the one given in Froot and Obstfeld (1991).
The conditions needed for convergence of the price-dividend ratio as well as the conditions for B(Dt) to be a rational intrinsic bubble are also identical to those in Froot and Obstfeld (1991).
EMPIRICAL ASSESSMENT OF THE MODEL
Characteristics of the Data
All data series used are taken from Shiller's (1989) data appendix. The nominal stock prices are annual series of January values of the Standard and Poor Composite Stock Price Index (series 1 in Shiller's dataset). The nominal dividend series are dividends per share (series 2 in Shiller's dataset). The producer price index is used as the deflator to obtain real values (series 5 in Shiller's dataset). Although the data series are available through the year 1999, we restrict ourselves to year 1988. This allows us to compare our results with those of Froot and Obstfeld (1991). Also, in the 1990s, many firms increasingly used stock buybacks instead of dividends to pay out funds to shareholders. Although all three series are available going back to 1871, we start the series in 1900 because Froot and Obstfeld (1991) use data starting at this time point. They provide reasons for omitting data from the earlier three decades.
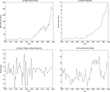
Summary statistics (not reported) on real dividend growth rates indicate strong and statistically significant leptokurtosis, and negative skewness. Normality is strongly rejected. This provides the basis for our empirical specification that follows in the next subsection. Figure 1 plots the real stock prices, real dividends and their growth rates, and the price-dividend ratios.

Plots of raw data
Econometric Specification
The empirical evaluation of the present value model requires specification of an exogenous stochastic process for dividends. From equation (6) and with the assumed β=−1, we get:

From the discussion immediately following equation (5), a complete solution to the present value model can be written as:

This satisfies the present value model given by equation (1) but violates the transversality condition given in equation (3) for all Bt≠0. Using equations (10), (12), and (13), one can write:

This can be rewritten after dividing through by Dt as:
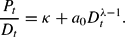
Motivated by this, one can then write down an econometric model for the stock price-dividend ratio:

where b0, b1, λ>0. The error term ηt is assumed to be independent of the innovations ξt, and of the dividends Dt, at all leads and lags. We follow standard practice in the literature by augmenting the stock price obtained by solving the present value equation with a regression residual when taking the model to the data. As noted by Hamilton (1986), the regression residual ηt captures omitted variables such as time-varying real interest rates, risk premia, and changes in tax laws.
The empirical assessment of the present value model proceeds with estimation of equations (14) and (18), subject to:

The null hypothesis of no bubbles implies that b0=κ and b1=0, whereas the alternative hypothesis of a bubble implies that b0=κ and b1>0.
Random Walk Model Estimates for Real Dividends
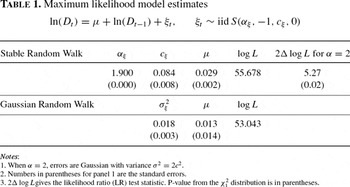
Table 1 presents empirical results on maximum likelihood estimates of equation (14). The first panel reports results on fitting a random walk with stable innovations to real dividends and the second panel reports results on fitting a Gaussian random walk. An LR test for α=2 (i.e., a test for Gaussian random walk as opposed to stable random walk) is easily rejected at better than the 5% significance level. Thus, the process for dividends adopted in the paper is an improvement over a Gaussian random walk used in Froot and Obstfeld (1991).

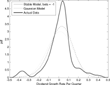
Figure 2 plots the unconditional distributions of the fitted stable and Gaussian models, along with the kernel density. As the plots suggest, the stable model provides a better fit to the kernel density. At the same time, it does not appear to be a great departure from the Gaussian distribution despite the skewness parameter being maximally negative, that is, β=−1. This is a consequence of the fact the α estimate of 1.90 is so close to 2, the value for Gaussian distributions.

Probability distributions of real dividend growth rates.
Following Froot and Obstfeld (1991), the constant discount factor is chosen to be r=0.086.3
This value of the discount rate exceeds the growth rate of dividends μ reported in Table 2. As argued by Hall (2001), the possibility of a bubble component growing at a rate r that exceeds the growth rate of fundamentals (dividends) may be unsustainable/impossible in a model with rational forward-looking agents. We thank an anonymous referee for raising this point.
is calculated to be 19.43. This agrees closely with the mean price-dividend ratio of 21.59. Solving the nonlinear equation (19) yields λ=1.92.

Estimates for a Gaussian random walk for dividends imply a price-dividend ratio κ of only 14.65, considerably below the empirically observed ratio. The exponent defining the bubble component λ is higher at 2.50.4
As equation (19) indicates, λ is implicitly a deterministic function of the discount factor r, and the estimated dividends process parameters. The discount factor is set to a value of 0.086, whereas the dividend process parameters are estimated from data. This means λ would have estimation error associated with it. It is not conceptually obvious how one may design a test to statistically compare values of λ obtained alternatively with stable and Gaussian dividends process parameters. A further technical difficulty arises from the highly nonlinear nature of Equation (19) that implicitly determines λ in terms of the dividends process parameters.
A test for no cointegration between Pt−κDt and
is rejected in both the stable and Gaussian cases in favor of cointegration, indicating a long run nonlinear relationship between stock prices and dividends, as in Ma and Kanas (2004).
Thus, the stable model for dividends implies a constant theoretical price-dividend ratio that is close to the empirically observed mean. The Gaussian model also implies a constant theoretical price-dividend ratio but its value is low when compared to the empirically observed mean.
Also, the stable model gives a bubble component that is considerably less nonlinear (as measured by the value of the exponent λ) than that under the Gaussian model. This is in accord with the fact that accounting for fat tails reduces the degree of nonlinearity required to explain observed variation in price-dividend ratios (see, for instance, Bidarkota, 2000).
Price-Dividend Ratio Regression Results
As noted at the end of subsection (4b), the empirical evaluation of the present value model could proceed by estimating equations (14) and (18), subject to the restriction given in equation (19). One could estimate all the parameters of the model jointly, by simultaneous estimation of the two equations. Or, alternatively, one could estimate equation (14) first, set b0=κ and λ equal to the value obtained by solving equation (19), and then estimate equation (18).
In what follows, we always estimate equations (14) and (18) individually rather than simultaneously. We set the exponent on the bubble term λ at its value obtained by solving equation (19). Froot and Obstfeld (1991) do estimate the price-dividend ratio regression this way and also alternatively by estimating λ along with the other parameters of equations (14) and (18) simultaneously. However, their inferences on the statistical significance of the bubble component in the two instances are qualitatively similar.
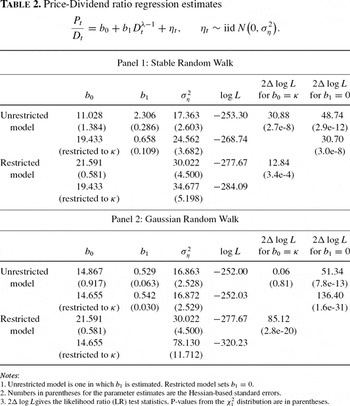
Table 2 presents empirical results on maximum likelihood estimation of the nonlinear price-dividend regression given in equation (18). The first panel presents regression results for a stable random walk process for dividends and the second panel presents regression results for a Gaussian random walk process. Results are presented both for an unrestricted model in which the coefficient on the bubble component b1 is estimated and a restricted model in which we set b1=0. Furthermore, within the unrestricted and restricted models, results are presented both for a version in which the intercept term b0 is estimated as a free parameter and a restricted model in which we set b0=κ.
For the fully unrestricted model, we find from the first row that the intercept term b0 is estimated to be 11.03. This is considerably lower than the theoretical price-dividend ratio κ of 19.43. The likelihood ratio (LR) test indicates that the estimated b0 is statistically significantly different from κ. The coefficient on the bubble component b1 is estimated to be 2.31. The LR test for b1=0 is strongly rejected.
Panel 2 presents regression results with a Gaussian random walk process for dividends. The estimated b0 of 14.87 is now much closer in value to the theoretical price-dividend ratio κ of 14.65 under a Gaussian random walk for dividends but much lower than the empirically observed mean price-dividend ratio of 21.59. In contrast to the results in panel 1 the hypothesis that b0=κ is not rejected in this case. This inference is reached by Froot and Obstfeld (1991) with the Gaussian random walk dividend process as well. The coefficient on the bubble component b1 is lower at only 0.53. However, once again, one can easily reject the absence of bubbles.
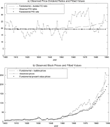
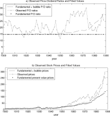
Figures 3–4 plot the observed price-dividend ratios and prices, along with the fitted values from the unrestricted models in panels 1 and 2 of Table 2, respectively, with b0 restricted to be equal to κ. The contribution of the fundamental present value component and that of the bubble in accounting for observed variation in P/D ratios and stock prices is clearly evident in the figures. As the first panels of the two figures indicate, the stable model gives a better fit to the long run observed average P/D ratios than the Gaussian model. As the second panels of the two figures indicate, the fundamental stock price from the stable model tracks the observed stock prices much more closely than the Gaussian model. With the fundamental and the bubble components combined providing very similar overall fit across the stable and Gaussian models, it follows that the role of the bubble component is diminished in the stable setup. This conclusion is in line with the one reached by Driffill and Sola (1998) who also find a diminished role for the bubble once discrete regime changes are entertained for the exogenous dividends process.

Results with stable random walk.

Results with Gaussian random walk.
Discussion of Results
The P/D regression results reported in Table 2 and discussed in the previous subsection indicate that we can reject the null hypothesis of the absence of bubbles across both panels in Table 2. This inference is robust to whether or not we impose b0=κ in the P/D regressions. This conclusion is in line with the inference in Froot and Obstfeld (1991). Thus, accounting for fat tails does not affect the qualitative outcome of testing for the absence of bubbles.
An important difference between our results with and without fat tails is the estimate of the exponent on the bubble component λ. As reported in subsection (4c), the Gaussian random walk for log-dividends yields an estimate for λ of 2.50 whereas the estimate implied by the stable random walk is only 1.92. This is in line with our contention that accounting for fat tails reduces the degree of nonlinearity of the bubble term needed to explain observed variation in stock prices.
As Figures 3 and 4 vividly illustrate, the fundamental present value stock price tracks the observed stock prices more closely with fat tails than without. Thus, accounting for fat tails reduces the discrepancy between the observed and fundamental present value stock prices, thereby diminishing the role for bubbles.
CONCLUSIONS
We studied the present value model with a constant discount factor. The exogenous dividends are assumed to evolve as a random walk with innovations drawn from the family of stable distributions. We derived an analytical formula for the present value stock price in such a setting. Further extending the analysis in Froot and Obstfeld (1991) that developed a Gaussian framework, we derived a functional form for intrinsic bubble that violates the transversality condition.
We estimated the model with annual U.S. stock price and dividends data over the last century. Our statistical rejection of the absence of a bubble component in annual U.S. stock price data is unchanged when we account for fat tails in dividends and stock price data. However, accounting for fat tails leads to an intrinsic bubble component that is less nonlinear, and consequently less explosive, than in the Gaussian setup. Fat tails also lead to a lower discrepancy between the observed and present value model implied fundamental stock prices, thereby diminishing the role of intrinsic bubbles in explaining observed variation in stock prices.
APPENDIX A
STABLE DISTRIBUTIONS AND THEIR PROPERTIES
This section draws heavily from McCulloch (1996). Stable distributions S(x; α, β, c, δ) are determined by four parameters. The location parameter δ∈(−∞, ∞) shifts the distribution to the left or right, whereas the scale parameter c∈(0, ∞) expands or contracts it about δ, so that

The standard stable distribution function has c=1 and δ=0. If a random variable X has a stable distribution, it is represented as X∼S(α, β, c, δ).
The characteristic exponent α∈(0, 2] governs the tail behavior, and therefore the degree of leptokurtosis. When α=2, the normal distribution results, with variance 2c2. For α<2, the variance is infinite. When α>1, E(X)=δ; but if α≤1, the mean is undefined.
The skewness parameter β∈[−1, 1] is defined such that β>0 indicates positive skewness. If β=0, the distribution is symmetric stable. As α↑2, β loses its effect and becomes unidentified.
Stable distributions are defined most concisely in terms of their log-characteristic functions:

where

is the log-characteristic function for S(α, β, 1, 0).
When α<2, stable distributions have tails that behave asymptotically like x−α and give the stable distributions infinite absolute population moments of order greater than or equal to α.
Let X∼S(α, β, c, δ) and a be any real constant. Then (A.2) implies:

Let X1∼(α, β1, c1, δ1) and X2∼(α, β2, c2, δ2) be independent drawings from stable distributions with a common α. Then Y=X1+X2∼S(α, β, c, δ), where


When β1=β2, β equals their common value, so that Y has the same shaped distribution as X1 and X2. This is the “stability” property of stable distributions that leads directly to their role in the central limit theorem, and makes them particularly useful in financial portfolio theory. When β1≠β2, β lies between β1 and β2.
For α<2 and β>−1, the long upper Paretian tail of X∼S(α, β, c, δ) makes EeX infinite. However, when β=−1,

This formula greatly facilitates asset pricing under log-stable uncertainty.
See also Zolotarev (1986, p. 112) and McCulloch (1996).
APPENDIX B
DERIVATION OF THE PRESENT VALUE STOCK PRICE
From equation (8),

Substituting equation (9) into the above equation yields:

From equation (6), ξt∼iid S(α, β, c, 0). With β=−1 assumed in the derivation of equation (10) and using equation (A.8) in Appendix A, we get:

Substituting equation (B.3) into equation (B.2) yields:

This can be rewritten as:

The infinite summation in the above equation converges only if
. In this case, from the sum of an infinite geometric progression, we find:

or

where:

APPENDIX C
INTRINSIC BUBBLES UNDER STABLE RANDOM WALK PLUS DRIFT
From equation (12),

Now, B(Dt) is a rational intrinsic bubble if it satisfies equation (5), which is given as:

Equation (6) implies that:

Therefore,

From equation (6), ξt∼iid S(α, β, c, 0). With β=−1 and λ>0, equation (A.4) from Appendix A yields ξt∼iid S(α, −1, λc, 0). Using equation (A.8) in Appendix A, we get:

Now, using equation (C.1) one can write the right-hand side of equation (C.2) as:

Substituting equation (C.4) into equation (C.6) yields:

Now, substituting equation (C.5) into equation (C.7) gives:

Thus, equation (C.2) is satisfied, provided that:

An earlier version of this paper was circulated as “Intrinsic Bubbles and Fat Tails in Stock Prices” by Prasad V. Bidarkota. We thank J. Huston McCulloch, Jonathan Hill, participants at the FIU Department of Economics seminar, the associate editor, and two anonymous referees for several excellent comments and suggestions. Any errors are our own.