1 Introduction
Disagreement over the exact contribution of asset allocation policy to portfolio performance has been evident in financial literature since the seminal papers of Brinson, Hood, and Beebower (Reference Brinson, Hood and Beebower1986) and Brinson, Singer, and Beebower (Reference Brinson, Singer and Beebower1991). Using quarterly returns of 91 and 82 US pension funds respectively, they state that more than 90% of the variability of the returns obtained over time is determined by the variation of the strategic policy. Therefore, the active management abilities – market timing and security selection – turn out to have a residual relevance in order to explain the variability of pension fund returns over time.
However, these findings have often been misinterpreted by academics and professional investors causing a controversy that stems from using the same results to answer the inappropriate questions.Footnote 1 In this sense, Jahnke (Reference Jahnke1997) argues that Brinson et al. (Reference Brinson, Hood and Beebower1986, Reference Brinson, Singer and Beebower1991) analyse the wrong question, focusing on the return variability explained by asset allocation rather than on the level of return.Footnote 2 More recently, Nuttall (Reference Nuttall2000) and Jahnke (Reference Jahnke2000) state that Brinson et al. studies bear responsibility for the confusion surrounding the matter because they provide unclear conclusions in their results.
Hensel, Ezra, and Ilkiw (Reference Hensel, Ezra and Ilkiw1991) show that the results found in Brinson et al. studies are a consequence of the variation of capital markets, not of the strategic policy allocated by each pension fund. Moreover, they claim that the importance put down to asset allocation depends on the benchmark used for the comparison. Ibbotson and Kaplan (Reference Ibbotson and Kaplan2000: 29) support this finding, concluding from the evidence that the importance of asset allocation to explain variability of returns over time is a case of ‘rising tide lifting all boats’.
Finally, Ibbotson, and Kaplan (Reference Ibbotson and Kaplan2000) clarify the misinterpretation by addressing three different questions to determine the importance of strategic asset allocation:
1 How much of the variability of returns over time is explained by asset allocation?Footnote 3
2 How much of the variation in returns among funds is explained by differences in strategic policy?
3 What proportion of the level of return is explained by asset allocation?
In order to answer these questions and therefore determine the contribution of asset allocation to fund performance, Ibbotson and Kaplan (Reference Ibbotson and Kaplan2000) analyse ten years of monthly returns for 94 US balanced mutual funds and five years of quarterly returns for 58 pension funds. They perform three different analyses, and find that strategic policy explains, on average, about 90% of the variability of returns over time, about 40% of the variation in returns among funds, and about 100% of the total return obtained.
Nuttall (Reference Nuttall2000) confirms that Ibbotson and Kaplan's paper (Reference Ibbotson and Kaplan2000) clarifies the controversy surrounding the importance of asset allocation in fund performance, but Jahnke (Reference Jahnke2000) states that none of the above three questions actually addresses what the investor is really interested in: what are the consequences of asset allocation and active management decisions on portfolio performance?
In this sense we agree with Nuttall (Reference Nuttall2000), considering that the research carried out by Ibbotson and Kaplan (Reference Ibbotson and Kaplan2000) clarifies the controversy surrounding this topic by addressing different approaches to analyse the importance of asset allocation. On the other hand, the analysis of the return that active management adds to the mere passive tracking of the strategic policy portfolio, allows us to deduce the consequences of asset allocation and active management on portfolio performance.
Following Ibbotson and Kaplan's (Reference Ibbotson and Kaplan2000) approach, a sample of 51 German and Swiss balanced mutual funds is analysed by Drobetz and Köhler (Reference Drobetz and Köhler2002), with results indicating that asset allocation explains about 80% of the first question, about 60% of the second, and about 130% of the third.
Asset allocation is also an important topic for individual investors. In this sense, and following the study of Ibbotson and Kaplan (Reference Ibbotson and Kaplan2000), we perform this analysis by using defined contribution personal pension plans due its importance in the Spanish pension market.
On applying the methodology suggested by these authors, we find evidence of a higher contribution of asset allocation to the unexplored Spanish pension plan performance than the results provided by them. These significant differences justify the analysis of this issue in other industries less developed than the US, such as the Spanish one, in order to get a broader perspective and fill a gap in financial literature.
Our study also provides an original contribution to the topic by improving the knowledge of the effects of survivorship bias and look-ahead bias in the importance of strategic policy to portfolio performance. The aforementioned studies do not consider the implications of their biased datasets on their findings. However, our unbiased dataset allows us to analyse these possible effects on the findings previously shown in financial literature.
In addition to this novel contribution, our work analyses significant factors such as fund size and money colour, which explain differences in the importance of asset allocation in the performance obtained by a pension plan. In this sense, our findings show that asset allocation is slightly more important in large equity pension plans than in small-sized plans. Furthermore, we have evidence that asset allocation is slightly more relevant in global equity pension plans than in plans investing locally in Euro zone equities.
The paper is organized as follows. Section 2 provides a brief description of the Spanish pension industry and the database used in our research. The three different questions addressed by Ibbotson and Kaplan (Reference Ibbotson and Kaplan2000) are analysed in the three following sections. Finally, the conclusions of our study are summarized in the last section of the paper.
2 Spanish pension industry and data
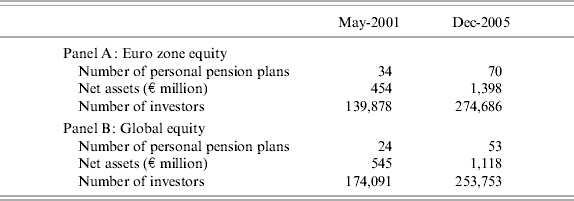
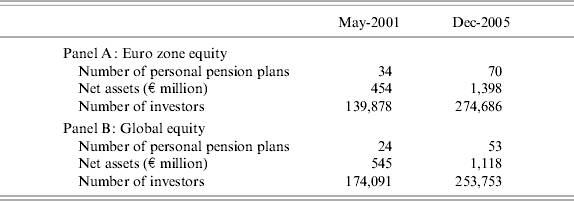
The dataset includes the monthly returns of all Spanish personal pension plans investing locally in Euro zone equities and all those plans investing in global equitiesFootnote 4 from May 2001 to December 2005. More specifically, a total of 73 and 56 respective pension plans are included in our research. Table 1 presents a summary of statistics related to the Spanish personal pension plans at the beginning and at the end of the time period analysed.
The Spanish pension system gathers a public system that provides coverage once the employees are retired and a private system that individual investors can voluntarily subscribe to for some contingencies such as retirement, disability, widowhood, and serious illness, among others.
Summary of statistics of Spanish personal pension plan samples
Source: INVERCO.
Personal pension plans (defined contribution plans by law) have been considered in our study in contrast to occupational and associate pension plans,Footnote 5 due its importance in the market representing approximately 80% of the investors and 60% of the money managed in the Spanish private pension industry.
At the end of the sample period, about €73,000 million were invested in Spanish private pension plans, representing 5.5% of Spanish family savings.Footnote 6 Likewise, over 9 million investors put their money in these portfolios, with an annual growth rate of over 13.8%. Total investment in Spanish pension funds and insurances represents 26% of the GDP. This percentage is a long way off British, French, and Dutch figures, but it is similar to those in Finland, Norway, and Austria.
On the other hand, some differences are observed when comparing our database with those used in the aforementioned studies. Firstly, our database also considers the pension plans disappearing during the time period analysed. Secondly, all existing plans are included in the dataset regardless of the number of observations. Thus, the results of this paper are free of survivorship bias and look-ahead bias.
3 The importance of asset allocation on the variability of returns over time
Previous studies in financial literature estimate the asset allocation policy considering two different sources of information: the historical portfolio holdings and that obtained from the application of Sharpe's return-based style analysis (RBSA).
Once the asset allocation is estimated, custom benchmarks are constructed in order to regress the performance of the portfolio against the performance of the custom benchmark, reporting the R2.
The procedure that we have followed consists in estimating the asset allocation policy by using RBSA proposed by Sharpe as in the study of Ibbotson and Kaplan (Reference Ibbotson and Kaplan2000). Then, we regress directly the performance obtained by the portfolio (total return) against the performance obtained by the asset allocation policy (policy return) without constructing a custom benchmark. This approach is more direct and leads to the same results.
The variability of returns over time explained by asset allocation is obtained by regressing each pension plan's total return against its policy returns, reporting the R2 coefficient.
The policy return of a pension plan i in the period t, PR it, is calculated by the tracking of the strategic weights of the basic assets allocated by the pension plan. These policy weights are obtained applying the ‘style analysis’ methodology proposed by Sharpe (Reference Sharpe1992), requiring only the historical monthly returns obtained by the pension plans included in the study and the k benchmarks representing the basic types of assets that may form part of the portfolio. Thus, the policy return for a given plan i in month t is calculated using the following equation
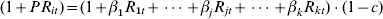
where:
PR it is the policy return of pension plan i in month t after deducting the cost of replicating the strategic asset policy through indexed funds.
R jt is the return of the benchmark of the basic asset type j in month t.
βj is the style factor or policy weight of the basic asset type j; j=1, …, k
c is the monthly cost of replicating the policy mix.Footnote 7
The style factors, βj, representing the strategic policy allocated in the basic asset j by pension plan i are obtained from minimizing the residual variance of the following equation (2), requiring that these style factors to add up to 1 and that they are non-negative.
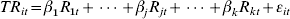
where:
TR it is the total return of pension plan i in month t.
εit is the residual return not explained by the model.
Following the seminal work of Sharpe (Reference Sharpe1992), the representative benchmarks of the strategic assets included in the model must be exclusive (not including any securities that already form part of any other benchmark considered in the model), exhaustive (as many strategic assets as possible should be included in the model), and they must also be independent in order to obtain significant and satisfactory results.
Lobosco and DiBartolomeo (Reference Lobosco and DiBartolomeo1997) and Buetow et al. (Reference Buetow, Johnson and Runkle2000) point out that these requirements of Sharpe (Reference Sharpe1992) are a qualitative description of an appropriate selection of the benchmarks to avoid linearity problems in the strategic assets included in the model. The above authors also show that the accuracy of the style analysis is not necessarily improved by adding further benchmarks.
By following these model requirements in order to address an appropriate style analysis representative of the policy weights allocated by Spanish equity personal pension plans, we consider Spanish Treasury Bills 1-day repos to be the representative benchmark of cash investment, and also MSCI European Monetary Union Index and MSCI World Index to be those benchmarks representing the different investment vocation of the two samples of Spanish equity pension plans considered in the database.
Initially we considered a very exhaustive style model including several benchmarks representing different stock markets such as Spain, Europe, Euro zone, and World as well as different Spanish and European fixed-income and cash benchmarks, in order to consider all basic asset types existing in the portfolio holdings of the plans.
We have chosen a model that only includes equities and cash to avoid the problems that arise when the benchmarks considered present multicollinearity. Therefore, our model is a consequence of a balance between exhaustivity (that lead us to incorporate other asset classes), exclusivity, and independence.
Thus, we have only kept the three most representative benchmarks regarding the investment vocation of the pension plans analysed.
In this way, both style models fulfil Sharpe's (Reference Sharpe1992) benchmark requirements.Footnote 8 Thus, the models proposed for Euro zone and global equity personal pension plans are as follows
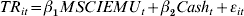
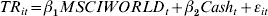
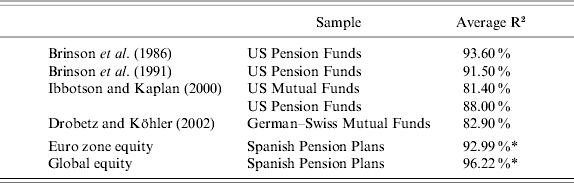
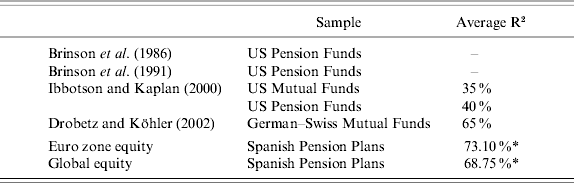
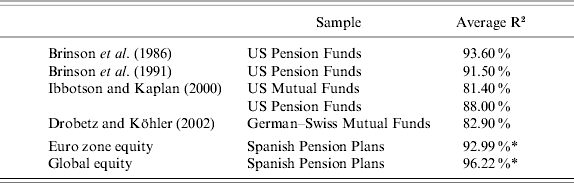
Table 2 shows the adjusted-R2 coefficientsFootnote 9 obtained from the style analysis for the equally weighted portfolios considering all surviving pension plans with at least 36 observations of both equity pension plan samples included in our database to obtain results comparable with previous findings in the financial literature. This table also presents the findings obtained in prior empirical works.
Results of time-series regression studies
Note: * Adjusted R2.
Table 2 shows that our results confirm the evidence previously found in the literature, with more than 90% of the variability of Spanish equity pension plan returns over time explained by the variability of policy returns. This result is similar for the two different investment vocations considered in our database.
A similar result found in previous literature is the higher R2 observed in those studies analysing pension funds, which may indicate that pension fund managers are less active than mutual fund managers. Thus, pension fund managers closely adhere to the strategic policy, deviating only marginally from the mere passive tracking of the benchmarks representing the strategic assets.
The influence of some biases on asset allocation
An interesting contribution of this paper is the evaluation of the incidence of several well-known biases in financial literature, such as survivorship bias and look-ahead bias, in the most controversial question: the importance of asset allocation in the variability of returns over time. As far as we know, this analysis has not yet been carried out in this type of research.Footnote 10
In this sense, Carhart et al. (Reference Carhart, Carpenter, Lynch and Musto2002) make the distinction between survivor bias and look-ahead bias. Survivor bias is caused by only including the funds that exist at the end of the sample period, whereas look-ahead bias appears when a certain period of time is required for funds to be included in the sample.
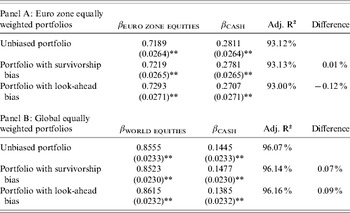
By making a comparison between the adjusted R2 of the unbiased portfolios and the portfolios that only include those plans with at least 36 observations, the influence of look-ahead bias on the importance of asset allocation in the variability of total returns over time is determined. On the other hand, the comparison between the unbiased portfolios and the portfolios containing surviving plans allows us to see the incidence of survivorship bias in the analysis carried out. These results are shown in Table 3.
The influence of survivorship and look-ahead biases
This table contains two panels, A and B, showing style factors, the adjusted R2 of the time series, and the incidence of the biases in Euro zone and global equally weighted portfolios, respectively. Furthermore, each panel has three sections: the first one includes information for the unbiased portfolios, the second one includes information for the portfolios with survivorship bias, and the third one contains the portfolios affected by look-ahead bias.

Notes: The values in brackets represent the standard deviation by Lobosco and DiBartolomeo (Reference Lobosco and DiBartolomeo1997).
* Significantly different from zero at a level of 5%.
** Significantly different from zero at a level of 1%.
A similar incidence of survivorship bias can be observed in both investment vocations. The consideration of surviving pension plansFootnote 11 leads to a slightly higher adjusted R2, thereby increasing the importance attributed to asset allocation to explain the variability of returns over time, whereas the impact of look-ahead is not clear because this bias is negative in Euro zone equity plans but positive in pension plans investing in global equities.
The small differences obtained in the adjusted R2 coefficients indicate that the impact of these biases detected in previous literature are irrelevant in our research.
The influence of fund size and ‘money colour’ on asset allocation
Another original approach of this study is the analysis of the contribution of some significant factors – fund size and investment vocation – to the importance of asset allocation in the variability of returns over time.
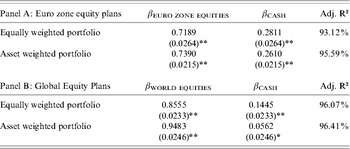
Firstly, in order to test the significance of fund size, we consider equally weighted portfolios and portfolios weighted for total assets. Secondly, in order to analyse the importance of the distance effect or ‘money colour’, we compare the results obtained by the two different investment vocations of the Spanish plans analysed. These results are shown in Table 4.
Style factors and R2 of time-series analysisFootnote +
Beta coefficients represent the strategic style allocated in the three different benchmarks representative of the basic assets included in Sharpe's style analysis and applied to Spanish equity pension plans. The adjusted R2 coefficient gathers the variability of the returns over time explained by the strategic asset allocation shown by the beta coefficients obtained in the analysis.

Notes:+ Unbiased portfolios.
The values in brackets represent the standard deviation by Lobosco and DiBartolomeo (Reference Lobosco and DiBartolomeo1997).
* Significantly different from zero at a level of 5%.
** Significantly different from zero at a level of 1%.
Table 4 shows a higher adjusted R2 in portfolios weighted for assets than in those equally weighted, indicating that asset allocation is more important in large equity pension plans in order to explain the variation of returns over time. However, this difference is not very significant, especially in global equity plans.
A higher adjusted R2 is also observed in those pension plans investing in global equities, showing that asset allocation is more important in global equity plans than in Euro zone equity plans in order to explain the variability of returns over time. This finding can be explained by the high style factor in the global equity benchmark, providing evidence that these pension plans allocate a more aggressive strategic policy than Euro zone plans. However, the difference between the two investment vocations is not significant, especially for large pension plans.
4 The importance of asset allocation on the variation in returns among plans
Another approach to assess the importance of asset allocation on pension plan performance is to determine how much of the variation in returns among plans is explained by differences in the strategic policies allocated by the personal pension plans analysed.
Following the methodology proposed by Ibbotson and Kaplan (Reference Ibbotson and Kaplan2000), a cross-sectional regression of compound monthly total returns (TR i) on compound monthly policy returns (PR i) for the entire period is worked out. These compound rates of return for each plan i are calculated as follows
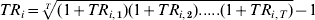
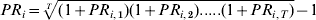
where:
TR i (PR i) is the compound monthly total (policy) return on plan i over the entire period of analysis.
TR i,t (PR i,t) is the total (policy) return of plan i in month t.
T is the number of monthly returns, t=1, 2, …, T.
The cross-sectional R2 coefficient of the analysis reports the variability of returns among Spanish personal pension plans, explained by the different strategic policies allocated. If all plans perfectly followed the same passive asset allocation policy, there would be no variation among plans, whereas if all plans were invested passively with a wide range of asset allocation policies, all the variations in returns would be attributable to strategic policy.
Accordingly, the two factors that drive the cross-sectional R2 are the differences between the plan's asset allocation policies and the differences in the degree of active management.Footnote 12
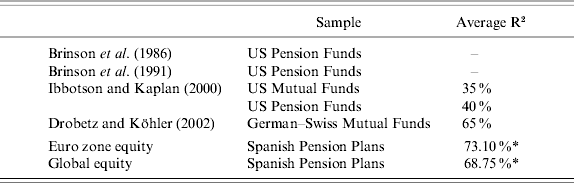
Table 5 shows the R2 coefficients obtained from the cross-sectional regression carried out in our samples, as well as the findings shown in prior research.
Results of cross-section regression studies
Notes: * Adjusted R2.
Our results are free of survivorship bias but they present look-ahead bias in order to obtain statistically significant results, whereas prior studies present both biases.Footnote 13
The R2 coefficients are 73.10% and 68.75% for Euro zone and global equity pension plans respectively, which implies that asset allocation explains, on average, approximately 70% of the variation of returns across plans, providing evidence that Spanish pension plans engaged to only a small extent in active management, especially pension plans investing in Euro zone equities, where a slightly higher R2 can be observed. These percentages are much higher than those obtained by Ibbotson and Kaplan (Reference Ibbotson and Kaplan2000), but similar to those of Drobetz and Köhler (Reference Drobetz and Köhler2002).
5 The importance of asset allocation on the level of return
Most of the misinterpretations of Brinson et al. (Reference Brinson, Hood and Beebower1986, Reference Brinson, Singer and Beebower1991) results stem from answering this question with their findings. In order to give an appropriate answer for the Spanish pension market, the contribution of asset allocation on the level of return is analysed by applying two different methods.
Firstly, the percentage of total return explained by policy return is calculated for each pension plan as the ratio of compound monthly policy return (PR i) divided by the compound monthly total return (TR i).
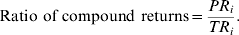
This ratio is originally proposed by Stevens, Surz, and Wimer (Reference Stevens, Surz and Wimer1999) being applied in other works, such as those of Ibbotson and Kaplan (Reference Ibbotson and Kaplan2000) and Drobetz and Köhler (Reference Drobetz and Köhler2002). A pension plan passively tracking its strategic policy will have a ratio of one, whereas it will be larger (less) than one if the active management of the pension plan underperforms (outperforms) its strategic policy. Thus, this ratio is a performance measure that indicates the value added by active management to the strategic policy.
In spite of the use of this ratio in prior research, we have detected two inconsistencies. The first one is the interpretation of the ratio when some or both of the terms (PR i, TR i) are negative, and the second one is the problem arising when one of the terms tends to zero, implying that the ratio will tend to zero or infinity. Thus, this ratio does not have universal validity because its value depends on the magnitudes and signs of the terms and therefore ratios shown in different studies should not be compared.
The ratios obtained in our analysis are 1377.94% and 64.80% for Euro zone and global equity pension plans, respectively. The result achieved in Euro zone pension plans is due to the second problem mentioned above. On the other hand, the result revealed by global equity pension plans shows that active management in Spanish global equity pension plans is adding value to the mere passive tracking of their strategic policy.
Following the methodological suggestion of De Roon et al. (Reference De Roon, Nijman and Ter Horst2004) and Harri and Brorsen (Reference Harri and Brorsen2004), the second method to check whether active asset management can add value to Spanish equity personal pension plan returns is the estimation of β0 parameter, the return that active management adds to the mere passive tracking of the strategic policy portfolio and its comparison with the management and custodial fees charged by these pension plans.Footnote 14 Thus, the total return of a pension plan is calculated using a variation of equation (2)
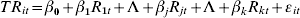
where:
β0 is an estimate of the return that active management adds to the policy portfolio.
De Roon et al. (Reference De Roon, Nijman and Ter Horst2004) show that a positive (negative) value of β0 implies that a pension plan outperforms (underperforms) the style portfolio and therefore active management obtains an excess (negative) return relative to the mere passive tracking of the benchmark portfolio only if a perfect style portfolio is found, which implies that the residual variance of the style model is zero. This requirement is satisfied in our models with adjusted R2 coefficients near to one.
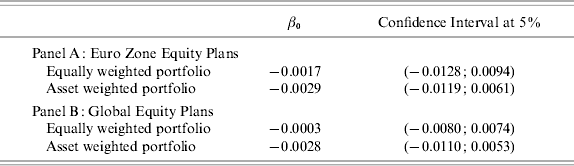
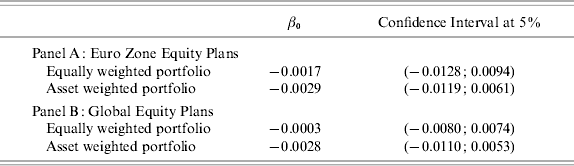
The results of the estimations of the return that active management adds to the policy portfolio and their confidence intervals are presented in Table 6.
β0 coefficients and confidence intervalsFootnote *
Note: * The figures presented in this table correspond to unbiased portfolios.
Negative values of β0 are obtained in all portfolios considered, regardless of the investment vocation; however, these coefficients are not statistically significant.
It is important to take into account that the value subtracted in the global equally weighted portfolio is lower than the average fees charged by these plans. Therefore, global pension plan managers are adding value to the mere passive tracking of their strategic policy. This finding confirms the result achieved by the ratio of compound returns (64.80%). On the other hand, the value subtracted in the Euro zone equally weighted portfolio is slightly higher than the average fees charged by these pension plans.
More negative values of β0 are also observed in portfolios weighted for assets, showing that the value added by active management of large pension plan managers is lower than in the rest of the Spanish equity pension plans.
Finally, Table 6 provides evidence that the values of the average fees charged by Spanish equity pension plans fall inside the confidence intervals of β0. These results allow us to claim that management and custodial fees are not statistically different to the value that active management subtracts from the passive tracking of the strategic portfolio.
The previous result shows that the return difference between Spanish pension plans and the mere passive tracking of the benchmarks representing the strategic assets is appropriately explained by the management costs.
6 Conclusions
The evidence shows a higher contribution of asset allocation in the variability of returns over time in Spanish equity pension plans than in those obtained in other more developed pension industries analysed in previous literature, such as the US market, thereby justifying this kind of analysis on emerging markets, such as the Spanish one.
Our research finds that, on average, more than 90% of variability of returns over time is explained by the strategic policy allocated by Spanish equity pension plans.
The study of significant factors, such as fund size and ‘money colour’ on determining the importance of asset allocation on the variability of returns over time, indicates that asset allocation is not only a little more important in large equity pension plans, it is also slightly more important in those plans with an investment vocation in global equities. However, the relevance of asset allocation in those plans investing in Euro zone equities is also quite significant.
Furthermore, this paper provides an original contribution to the literature by analysing the effects of survivorship bias and look-ahead bias in the importance of strategic policy to portfolio performance, showing that these biases have a very small impact on the conclusions obtained.
On the other hand, the high percentage of the variation of returns across plans explained by strategic allocation indicates that Spanish pension plans engaged very little in active management, with the importance of active management abilities – timing or stock picking – being modest in terms of the variability of returns among Spanish equity pension plans.
Finally, our findings show that the return added by active management is not enough to make up for the management costs charged by Spanish equity pension plans. Thus, the return difference between Spanish pension plans and the mere passive tracking of the benchmarks representing the strategic assets is appropriately explained by these management costs.
Acknowledgements
The authors would like to express their thanks to Financial Group Ibercaja for the award of Project 268-96, to the University of Zaragoza for the award of Projects 268-128 and 268-147 and to the Ministry of Science for the award of Project SEJ2006-04208 with European FEDER funds.
Laura Andreu is also grateful for the funds provided by the research programme CAI Europe. Possible errors are the exclusive responsibility of the authors.