



1 Introduction
1.1 Background
In this paper, we study the question of selection in ergodic optimization. Given a dynamical system
 $(X,T)$
, ergodic theory describes almost all orbits, with respect to some/any invariant probability. The thermodynamic formalism is a way to select particular invariant measure(s): one fixes some potential
 $A:X\to \mathbb {R}$
and one considers the measure(s) maximizing the free energy
 $$ \begin{align*}P(\beta\cdot A):=\sup_{\mu\ T\text{-}\mathrm{inv}}\bigg\{h_{\mu}(T)+\beta\cdot\int A\,d\mu\bigg\},\end{align*} $$
where
 $h_{\mu }(T)$
is the Kolmogorov entropy and
 $\beta $
is a real parameter, corresponding to the inverse of the temperature in statistical mechanics. Such a measure is called an equilibrium state (for
 $\beta A$
). This formalism has been introduced in the Dynamical Systems settings in the 1970s, mainly by Sinai, Ruelle, and Bowen.
Ergodic optimization is another way to select particular invariant measures. Instead of maximizing the free energy, one simply maximizes the integral of the potential: an invariant (probability) measure
 $\mu $
is A-maximizing if it satisfies
 $$ \begin{align*}m(A):=\sup_{\nu\ T\text{-}\mathrm{inv}}\int A\,d\nu=\int A\,d\mu.\end{align*} $$
The existence of equilibrium states usually follows from upper-semi-continuity for the entropy, whereas the existence of maximizing measures simply follows from continuity on the compact convex set of invariant probabilities.
Furthermore, there is a relation between equilibrium states and maximizing measures: any accumulation point for the equilibrium state
 $\mu _{\beta A}$
as
 $\beta $
goes to
 $+\infty $
is an A-maximizing measure. It is also known (see [Reference Contreras11]) that if
 $(X,T)$
is uniformly hyperbolic, then generically in the Lipschitz topology for the potential, the family of equilibrium states
 $\mu _{\beta A}$
converges to the unique A-maximizing measure which is supported on a periodic orbit.
The question of selection in ergodic theory deals with the residual case. In the case of the existence of several maximizing measures, is there convergence for
 $\mu _{\beta A}$
(as
 $\beta \to +\infty $
) and/or what makes it that some accumulation point (usually called a ground state in statistical mechanics) is selected instead of another one?
Despite that residual sets may be considered as small, we emphasize that it is usually extremely easy to find A which admits several maximizing measures: pick any two disjoints invariant compact subsets
 $K_{1}$
and
 $K_{2}$
, and consider the potential
 $A:=-d(\cdot\,, K_{1}\cup K_{2})$
. The question of selection is thus meaningful.
About selection, little is known. If
 $(X,T)$
is a subshift of finite type and if A is locally constant, then convergence to a ground state holds as the temperature goes to zero (see [Reference Brémont8, Reference Leplaideur20]). On the one hand, there are Lipschitz potentials where
 $\mu _{\beta A}$
does not converge (see [Reference Bissacot, Garibaldi and Thieullen6, Reference Chazottes and Hochman10, Reference Coronel and Rivera-Letelier14]). In [Reference Leplaideur21], it is proved that (under certain hypothesis) flatness of the potential closed to the Aubry set determines which pieces may support ground states. On the other hand, in [Reference Baraviera, Lopes and Mengue4], it was proved that the knowledge of the potential in a neighborhood of the Aubry set is not sufficient to determine the result of selection. In [Reference Baraviera, Leplaideur and Lopes3], all the difficulty of the selection appeared: equilibrium states are usually obtained via an operator (called the transfer or the Ruelle–Perron–Frobenius operator) and are constructed from its eigenfunction and eigenmeasure (see below). Therein, it is shown that the eigenmeasure selects one piece, whereas the eigenfunction selects the other piece of the Auby set. Then, considering the value of the potential ‘in the middle’ as a parameter, the ground state may change as this parameter changes. A complete description of the limit depending on the parameter was given and the main point was that this selection process was strongly discontinuous. The main reason for that is that the phase diagram results from Max-Plus formalism, explaining the discontinuities.
Several properties and relations between equilibrium states and maximizing measures may be understood from convex analysis. The pressure function
 $\beta \mapsto P(\beta A)$
is convex and, hence, its slope is increasing. This is related to the fact that accumulation points for
 $\mu _{\beta A}$
are A-maximizing. Furthermore, the graph of the pressure admits an asymptote as
 $\beta \to +\infty $
of the form
 $h_{\mathrm {max}}+\beta m(A)$
, where
 $h_{\mathrm {max}}$
is the maximal entropy among A-maximizing measures. Some of these properties are re-explained below. We mention [Reference Buzzi, Kloeckner and Leplaideur9] for further descriptions of how thermodynamic formalism, including freezing phase transition (that is, as
 $\beta \to +\infty $
) is related to convex analysis. Other references concerning Ergodic Optimization and zero temperature limits are [Reference Baraviera, Leplaideur and Lopes2, Reference Baraviera, Lopes and Thieullen5, Reference Contreras, Lopes and Thieullen12, Reference Conze and Guivarc’h13, Reference Garibaldi and Lopes15, Reference Jenkinson16, Reference Kempton18, Reference Kucherenko and Quas19, Reference Mengue23, Reference Mengue24].
Our first result (see Theorem A) shows that if the Aubry set is a subshift of finite type, then the pressure converges exponentially fast to its asymptote. In [Reference Conze and Guivarc’h13], an upper-bound in
 $O(1/\beta ^{2})$
was proved. In [Reference Kucherenko and Quas19], a lower is given and we emphasize that our result is related to Question (iii) therein. More precisely, we show that the exponential rate is the unique eigenvalue of a transition matrix within the Max-Plus formalism, where entries are related to the Peierl’s barrier of the potential between the different pieces of the Aubry set.
Our second result (see Theorem B) studies, in the case of Walters potentials, the stability of the selection under small perturbation of the potential. In that case, Theorem A holds and we show that if the perturbation goes faster to zero than how the pressure goes to its asymptote, then the selection does not change.
1.2 Settings and results
In the following,
 $X\subseteq \{0,1,\ldots ,d\}^{\mathbb {N}}$
is a subshift of finite type given by an aperiodic matrix. Additionally, X, equipped with the metric d defined by
 $$ \begin{align*}d((x_{0},x_1,x_2,x_3,\ldots),(y_{0},y_1,y_2,y_3,\ldots)) = \theta^{\min\{i\,|\,x_i\neq y_i\}},\,\theta \in (0,1),\end{align*} $$
is a compact space. The shift map
 $\sigma :X \to X$
is defined by
 $$ \begin{align*}\sigma(x_{0},x_1,x_2,x_3,\ldots) = (x_{1},x_2,x_3,x_4,\ldots).\end{align*} $$
In the special case
 $d=2$
, the full-2-shift is denoted by
 $X_{2}$
. Points in X are also called infinite words and, hence,
 $X_2$
is the set of all infinite words with 0 and 1. If
 $a_{0},\ldots , a_{n}$
are digits or letters in
 $\{0,1,\dots , d\}$
, the cylinder
 $[a_{0},\ldots ,a_{n}]$
is the set of points
 $ x\in X$
such that
 $x_{i}=a_{i}$
for
 $0\le i\le n$
.
Given a Lipschitz continuous function
 $A:X \to \mathbb {R}$
, we denote by
 $|A|_\infty =\sup _{x\in X} |A(x)|$
the supremum norm of A and by
 $\mathrm {Lip}(A) = \sup _{x\neq y} ({|A(x)-A(y)|}/{d(x,y)})$
the Lipschitz constant of A. The Lipschitz norm is
 $|\,\cdot\, |_{\infty }+\mathrm {Lip}(\cdot)$
.
The transfer operator
 $L_A$
is defined by
 $$ \begin{align*}L_{A}(\psi)(x) = \sum_{\sigma(z) =x}e^{A(z)}\psi(z).\end{align*} $$
We refer to [Reference Bowen and Chazottes7] for the complete study of this operator. It acts on
 ${\mathcal C}(X)$
and on the space
 ${\mathcal C}^{0+1}(X)$
of Lipschitz continuous functions. Its spectral radius
 $\unicode{x3bb} _{A}$
(for
 $|\,\cdot\, |_{\infty }$
-norm) is a single dominating eigenvalue on
 ${\mathcal C}^{0+1}(X)$
. It also turns out to be equal to
 $e^{P(A)}$
. The associated one-dimensional eigenspace is
 $\mathrm{span}(H_{A})$
, where
 $H_{A}$
is Lipschitz continuous, positive, and uniquely determined up to some normalization. The dual operator
 $L_{A}^{*}$
for the
 $|\,\cdot\,|_{\infty }$
-norm acts on the set of measures and
 $\nu _{A}$
is the unique probability satisfying
 $L_{A}^{*}(\nu _{A})=\unicode{x3bb} _{A}\nu _{A}$
. It is referred to as the eigenmeasure or the conformal measure.
The usual normalization for
 $H_{A}$
is
 $\int H_{A}\,d\nu _{A}=1$
, but for Theorem B, we shall choose another normalization.
We now recall some standard concepts on ergodic optimization for symbolic dynamics. We refer to [Reference Baraviera, Leplaideur and Lopes2, Reference Baraviera, Lopes and Thieullen5, Reference Contreras, Lopes and Thieullen12, Reference Garibaldi and Lopes15] for more details. We point out that the central role of Lagrangian-inspired methods in the technical apparatus has been introduced to ergodic optimization for expanding maps in [Reference Contreras, Lopes and Thieullen12].
The set of
 $\sigma $
-invariant probabilities is denoted by
 ${\mathcal M}(\sigma )$
. We set
 $$ \begin{align*}m(A):=\max_{\mu\in{\mathcal M}(\sigma)}\int A\,d\mu.\end{align*} $$
Any measure realizing this supremum is called A-maximizing or maximizing for A. We denote by
 ${\mathcal M}_{\mathrm {max}}(A)$
the set of A-maximizing measures.
A calibrated subaction for A is a Lipschitz continuous function
 $V:X\to \mathbb {R}$
satisfying for every
 $x\in X$
,
 $$ \begin{align*} \max_{\sigma(z)=x} [A(z) + V(z) - V(x) - m(A)] = 0.\end{align*} $$
It is also known (see [Reference Baraviera, Leplaideur and Lopes2] and §2.3.1) that any accumulation point for
 $({1}/{\beta })\log H_{\beta A}$
(and for
 $|\,\cdot\,|_{\infty }$
) is such a calibrated subaction. This was first noticed in [Reference Savchenko26]. Setting
 $g(z):=A(z)+V(z)-V\circ \sigma (z)-m(A)$
, we see that g is a Lipschitz continuous function, cohomologous to A (up to an additive constant) and non-positive. It thus satisfies that
 $m(g)=0$
,
 $P(\beta g) = P(\beta A)-\beta m(A)$
, and the unique equilibrium sate for
 $\beta A$
is also the unique equilibrium state for
 $\beta g$
. Furthermore, an A-maximizing measure is g-maximizing and the converse.
Hence, without loss of generality, one shall assume in this paper that A is non-positive and satisfies
 $m(A)=0$
(except when this assumption is not required for general results on ergodic optimization).
We recall that
 $S_{n}(A)$
stands for the Birkhoff sum
 $A+\cdots +A\circ \sigma ^{n-1}$
.
Definition 1.1. With these notation and assumptions, the Mañé potential associated to A is defined by
 $$ \begin{align*}S(x,y):=\lim_{\epsilon \rightarrow 0}[\sup\{S_n(A)(z)\,|\,n\geq 1,\ \sigma^{n}(z)=y,\ d(x,z)<\varepsilon\}],\end{align*} $$
the Aubry set of A is defined by
 $$ \begin{align*}\Omega:=\{x\in X\, |\, S(x,x) = 0\},\end{align*} $$
and the Mather set is
 $$ \begin{align*}\mathcal{M} = \bigcup_{\mu \in \mathcal{M}_{\mathrm{max}}(A)}\operatorname{supp}(\mu).\end{align*} $$
By definition, it is clear that
 $S(x,y)$
is non-positive and it may assume the value
 $-\infty $
.
Remark 1.2. The Mather set is non-empty (as it contains the support of any accumulation point for
 $\mu _{\beta A}$
) and is contained in the Aubry set (see [Reference Baraviera, Leplaideur and Lopes2, Theorem 3.15]). This shows that the Aubry set is not empty either.
With these settings, our first main result is the following theorem.
Theorem A. Let A be a non-positive and non-constant Lipschitz continuous function satisfying
 $m(A)=0$
. Suppose that the Aubry set
 $\Omega $
is a subshift of finite type with topological entropy h. Then, the limit
 $$ \begin{align} \gamma :=\lim_{\beta\to\infty}\frac{1}{\beta}\log(P(\beta A)-h) \end{align} $$
exists and it is a real number.
Remark 1.3. Note that the case
 $A \equiv 0$
is not relevant, since any measure is maximizing.
In the proof of the above theorem, we show that
 $\gamma $
is the unique eigenvalue in Max-Plus formalism of a matrix that is constructed from an analysis of the Mañé potential between the irreducible components of
 $\Omega $
with maximal entropy (see Proposition 3.10).
We can now deal with the question of selection. The question we are interested in is to know how/if the selections of subaction and measure are stable under perturbations. As we will see, it is easy to exhibit examples where the selections for the family
 $\beta A+B$
differ from the selections for the family
 $\beta A$
. Therefore, our question is which conditions on a family of functions
 $B_{\beta }$
do ensure that
 $\mu _{\beta A+B_{\beta }}$
selects the same ground state as
 $\mu _{\beta A}$
, and
 $({1}/{\beta })\log (H_{\beta A +B_{\beta }})$
selects the same subaction as
 $({1}/{\beta })\log (H_{\beta A})$
?
It turns out that we can give an answer in a special case of potentials for
 $X_{2}$
. For
 $i\in \{0,1\}$
, let
 $f_i:[0,1]\to (-\infty , 0]$
be a Lipshitz function satisfying
 $f_{i}(x)=0$
if and only if
 $x=0$
, and let
 $A:X_2\to (-\infty ,0]$
be the potential defined by
 $$ \begin{align*} A(x)=\begin{cases} f_0( d(x,0^{\infty}))& \text{if } \,x\in [0], \\ f_1( d(x,1^{\infty}))& \text{if }\, x\in [1].\end{cases}\!\!\!\! \end{align*} $$
These potentials belong to the family that was introduced by P. Walters in [Reference Walters27]. They represent a class of functions for which complete computations are possible, which allows to make conjecture for more complicated cases. We emphasize that in that case, the Aubry set is the union of two fixed points
 $\{0^{\infty }, 1^{\infty }\}$
. It is thus a subshift of finite type with topological entropy equal to 0. Hence, Theorem A holds in that case.
We emphasize that our result gives another proof for the convergence of the Gibbs measures associated to these potentials (see [Reference Bissacot, Garibaldi and Thieullen6]) as the temperature goes to zero for the case where convergence holds.
Theorem B. Consider a Lipschitz function
 $A:X_2 \to \mathbb {R}$
satisfying
 $$ \begin{align} A(0^{\infty})=A(1^{\infty})=0,\quad A|_{[01]}=b,\quad A|_{[10]}=d,\quad A|_{[0^n1]} =a_n,\quad A|_{[1^n0]} =c_n \end{align} $$
for negative numbers
 $b,d,\{c_n\}_{n\geq 2}$
, and
 $\{a_n\}_{n\geq 2}$
. Assume
 $H_{\beta A}$
is normalized by
 $H_{\beta A}(0^{\infty })=1$
. Then:
-
(1)
 $\gamma :=\lim _{\beta \to +\infty }({1}/{\beta })\log (P(\beta A))$
exists and it is a negative number;
-
(2) for any
$\delta <\gamma $
, for any family
$(B_{\beta })$
of Lipschitz functions such that
$|B_\beta |_\infty <e^{\beta \delta }$
,
$$ \begin{align*}\lim_{\beta \to \infty} \mu_{\beta A+B_\beta} =\lim_{\beta \to \infty} \mu_{\beta A};\end{align*} $$
-
(3) for any
$\delta <\gamma $
and any
$c\in \mathbb {R}$
, for any family
$(B_\beta )$
such that
$|B_\beta |_\infty <e^{\beta \delta }$
and
$\mathrm {Lip}(B_\beta )<\beta c$
,
$$ \begin{align*}\lim_{\beta \to \infty}\frac{1}{\beta}\log(H_{\beta A+B_\beta})=\lim_{\beta \to \infty}\frac{1}{\beta}\log(H_{\beta A}).\end{align*} $$


Remark 1.4. We emphasize that the perturbations
 $B_{\beta }$
do not need to satisfy a similar hypothesis as A in (2).
Remark 1.5. Assumptions may be released. We let the reader check that we actually only need
 $A(0^{\infty })=A(1^{\infty })=0$
and:
-
(1) A non-positive;
-
(2)
$b+d<0$
; -
(3)
$a_{2}<0$
; -
(4)
$c_{2}<0$
.


For that special case of potentials satisfying (2), the existence of
 $\gamma $
follows from Theorem A, but has also been already proved in [Reference Baraviera, Lopes and Mengue4, Reference Bissacot, Garibaldi and Thieullen6]. Therein, the existence of the limits
 $\lim _{\beta \to \infty } \mu _{\beta A}$
and
 $\lim _{\beta \to \infty }({1}/{\beta })\log (H_{\beta A})$
were also proved. Here, one novelty is that we give another characterization for the limit
 $V:=\lim _{\beta \to \infty } ({1}/{\beta })\log (H_{\beta A})$
in terms of Max-Plus formalism and the main novelty is that we give a condition to get stability.
1.3 Plan of the paper
The paper is organized in the following way.
In §2, we introduce a basic analysis of the problem of selection, and some results that will be useful in the proof of Theorem A and in the study of selection of subaction.
In §3, we prove Theorem A. The proof is divided in subsections to facilitate the reading. Using the fact that a subaction is entirely determined by its values on the Aubry set, we obtain a relation between these values on the irreducible component of the Aubry set in the case where it is a subshift of finite type. In this relation, the speed of convergence of the pressure turns out to be an eigenvalue for a special matrix.
In §4, we prove Theorem B. In the first subsection, we use Theorem A to identify
 $\gamma $
. Proposition 4.2 is the key point to get selection of the subaction. In Proposition 4.11, we show the convergences to limit measures for
 $\mu _{\beta A +B_\beta }$
and
 $\mu _{\beta A}$
. In §A, we give a totally computational example where
 $B_{\beta }$
goes to zero slower than
 $e^{\beta \cdot \gamma }$
and then there is a change of selections.
1.4 Motivations
An initial motivation for the study of selection for perturbed potentials was given from the results in [Reference Lopes, Mengue, Mohr and Souza22]. In such a paper, very similar characterizations concerning zero temperature limits for
 $\mu _{\beta A}$
and
 $H_{\beta A}$
were observed when supposing
 $\tilde {X}=M^{\mathbb {N}}$
, where M is a compact metric space instead a finite set. In this case, the formulation of the Ruelle operator uses a prior probability measure m satisfying
 $\operatorname {supp}(m)=M$
and then
 $L_{A,m}:C(\tilde {X})\to C(\tilde {X})$
is given by
 $L_{A,m}(\psi )(x)=\int _M e^{A(ax)}\psi (ax)\,dm(a)$
.
A natural question concerning this general setting is the dependence of the zero temperature limits with respect to the prior probability measure m that is used to define the operator. The answer is obtained by considering this question in the particular case where
 $M=\{0,1,\ldots ,d\}$
and
 $\tilde {X}=\{0,1,\ldots ,d\}^{\mathbb {N}}$
. For any prior probability
 $m=(p_0,\ldots ,p_d)$
, where
 $p_i>0\,\text { for all } i\in \{0,1,\ldots ,d\}$
, the operator
 $L_{\beta A,m}$
can be written as
 $$ \begin{align*}L_{\beta A,m}(\psi)(x)=\sum_{a=0}^{d}e^{\beta A(ax)}\psi(ax)p_{a} = \sum_{a=0}^de^{\beta A(ax)+\log(p_a)}\psi(ax)\end{align*} $$
for each
 $\beta>0$
. So,
 $L_{\beta A,m}$
is just the usual Ruelle operator associated to the perturbed potential
 $\beta A(x)+\log (p_{x_1})$
, where
 $x=(x_1,x_2,x_3,\ldots )$
. It is easy to construct examples (see Example 2.3) where such perturbation will change the results of selection of subaction and measure. Therefore, the conclusion is that selection of subaction and measure in the setting of [Reference Lopes, Mengue, Mohr and Souza22] depends of the prior measure m. In the case of finite alphabet
 $\{0,1,\ldots ,d\}$
, a natural next step is to study what are the conditions on the perturbation to get equal limits.
A second motivation is to inquire how perturbation could enlarge the class of known potentials for which there is convergence. As it is said above, it is known that convergence occurs as soon as the potential is locally constant. In that case, the Aubry set is a subshift of finite type. It is thus quite natural to inquire if, for a given potential, one can find some sequence of locally constant perturbations, refining the initial potential, with all the same Aubry set, and such that convergence for this family finally yields convergence for the initial potential. This is a research program and one first step is to control how perturbations influence the selection.
2 Auxiliary and preliminary results
2.1 Convexity for the pressure and consequences
Here, we do not necessarily assume that
 $m(A)=0$
holds.
Definition 2.1. For any continuous
 $B:X\to \mathbb {R}$
,
 $$ \begin{align*}P_{A\text{-}\mathrm{max}}(B):=\sup_{\mu \in \mathcal{M}_{\mathrm{max}}(A)} \bigg\{\kern-2pt\int B\,d\mu+h_\mu(\sigma)\bigg\}.\end{align*} $$
Any measure that realizes the maximum is called a A-maximizing equilibrium state for B.
Lemma 2.2. Let A be a Lipschitz function and let
 $B_\beta :X\to \mathbb {R}$
be a family of Lipschitz functions converging uniformly to B. Then, any accumulation point for
 $\mu _{\beta A+B_{\beta }}$
as
 $\beta \to +\infty $
is an A-maximizing equilibrium state for B.
Furthermore, if B is Lipschitz continuous, then
 $\beta \mapsto P(\beta A +B)-\beta m(A)$
is non-increasing and converges to
 $P_{A\text {-}\mathrm {max}}(B)$
.
Proof. The proof here follows ideas present in [Reference Conze and Guivarc’h13]. Let
 $\mu $
be any maximizing measure to A and let
 $\mu _\infty $
be an accumulation measure of
 $\mu _{\beta A +B_\beta }$
. From
 $$ \begin{align*}\beta \int A\, d\mu + \int B_\beta\,d\mu + h(\mu) \leq \beta\int A\, d\mu_{\beta A +B_\beta} + \int B_\beta\,d\mu_{\beta A +B_\beta} + h(\mu_{\beta A +B_\beta}),\end{align*} $$
we conclude that
 $\int A\, d\mu \leq \int A\, d\mu _\infty $
. This proves that
 $\mu _\infty \in M_{\mathrm {max}}(A)$
.
We have also
 $$ \begin{align*}\int B_{\beta}\, d\mu + h(\mu)&\leq P(\beta A + B_\beta) - \beta\int A\, d\mu\\ &= \beta\bigg(\kern-2pt\int A\, d\mu_{\beta A +B_\beta}- \int A\,d\mu\bigg) + \int B_\beta\, d\mu_{\beta A +B_\beta} +h(\mu_{\beta A +B_\beta})\\ &\leq \int B_\beta\, d\mu_{\beta A +B_\beta} +h(\mu_{\beta A +B_\beta}).\end{align*} $$
Using the upper semi-continuity of the entropy, as
 $\beta \to \infty $
,
 $$ \begin{align*}\int B\, d\mu + h(\mu) \leq \int B d\mu_{\infty} +h(\mu_\infty).\end{align*} $$
This yields that
 $\mu _{\infty }$
has maximal pressure among measures in
 $M_{\mathrm {max}}(A)$
.
Let us now assume that B is Lipschitz continuous. We remind that the pressure is defined by
 $$ \begin{align*}P(A):=\mathrm{max}\bigg\{h_{\mu}(\sigma)+ \int A\,d\mu\bigg\},\end{align*} $$
which immediately yields that
 $\beta \mapsto P(\beta A+B)$
is convex. It follows from [Reference Parry and Pollicott25, Proposition 4.10] that
 $$ \begin{align*}\frac{d}{d\beta}P(\beta A +B) = \int A\, d\mu_{\beta A+B}.\end{align*} $$
We can also observe that, by definition of pressure, for any
 $\beta _{0}$
, the line
 $\beta \to h_{\mu _{\beta _{0}A+B}}(\sigma )+\beta \int A\,d\mu _{\beta _{0}A+B}$
is below the graph of the pressure function
 $\beta \to P(\beta A +B)$
and touches it at
 $\beta =\beta _{0}$
.
As
 $$ \begin{align*}\frac{d}{d \beta}[P(\beta A +B) - \beta m(A)] = \int A\, d\mu_{\beta A+B} -m(A) \leq 0,\end{align*} $$
we get that
 $\beta \to P(\beta A +B)-\beta m(A)$
is a non-increasing function. Let
 $\mu _\infty $
be any accumulation point for
 $\mu _{\beta A+B}$
. As, by definition of pressure,
 $$ \begin{align*} P(\beta A+B)-\beta m(A)-\int B\,d\mu_\infty-h_{\mu_\infty}(\sigma)\geq 0,\end{align*} $$
we obtain
 $P(\beta A+B)-\beta m(A)\geq \int B\,d\mu _\infty +h_{\mu _\infty }(\sigma ) $
. However, as the entropy is upper semi-continuous,
 $$ \begin{align*}\lim_{\beta\to +\infty} P(\beta A+B)-\beta m(A) &\leq \limsup_{\beta\to +\infty} \int B\,d\mu_{\beta A+B} +h_{\mu_{\beta A+B}}(\sigma)\\ &\leq \int B\,d\mu_\infty +h_{\mu_\infty}(\sigma).\\[-38pt] \end{align*} $$
2.1.1 Selection depends on B
The next example shows that if
 $B_{\beta }$
does not go to 0, then selection may (easily) change. It is a consequence of Lemma 2.2.
Example 2.3. Set A any non-positive Lipschitz continuous function on
 $X_2$
, negative everywhere except at
 $0^{\infty }$
and
 $1^{\infty }$
. Pick
 $B_{0}$
and
 $B_{1}$
Lipschitz continuous functions such that
 $B_{0}(0^{\infty })>B_{0}(1^{\infty })$
and
 $B_{1}(0^{\infty })<B_{1}(1^{\infty })$
.
It is easy to check that
 $\delta _{0^{\infty }}$
is the unique A-maximizing equilibrium state for
 $B_{0}$
, whereas
 $\delta _{1^{\infty }}$
is the unique A-maximizing equilibrium state for
 $B_{1}$
. Hence,
 $\mu _{\beta A+B_{0}}$
converges to
 $\delta _{0^{\infty }}$
, whereas
 $\mu _{\beta A+B_{1}}$
converges to
 $\delta _{1^{\infty }}$
.
2.1.2 Change of selection even if
$B_{\beta }$
goes to 0

Corollary 2.4. Let
 $A:X_2\to \mathbb {R}$
be a function which is equal to zero at the points
 $0^{\infty }$
and
 $1^{\infty }$
, and negative at the other points. Suppose that
 $\mu _{\beta A} \to \delta _{1^{\infty }}$
. Then, there exists a family of potentials
 $B_{\beta }$
which uniformly converge to
 $0$
and such that
 $\delta _{0^{\infty }}$
is an accumulation point for
 $\mu _{\beta A+B_{\beta }}$
.
Proof. Set
 $D(x)=-d(x,0^{\infty })$
. Then, for any integer
 $n>0$
,
 $\mu _{\beta A+(1/n) D}$
goes to
 $\delta _{0^{\infty }}$
as
 $\beta $
goes to
 $+\infty $
. Therefore, one can find an increasing sequence
 $(\beta _{n})\uparrow +\infty $
such that for any n,
 $$ \begin{align*}\mu_{\beta_{n}A+(1/n) D}([0])\ge 1-\dfrac1n.\end{align*} $$
Let
 $s:\mathbb {R}^+\to \mathbb {R}^+$
be a decreasing function satisfying
 $s(\beta _n)={1}/{n}$
. Then,
 $\mu _{\beta _{n}A+s(\beta _{n})D}$
goes to
 $\delta _{0^{\infty }}$
(as it is the unique invariant measure with support in
 $[0]$
).
2.2 Kinds of Laplace’s methods
We recall the very easy fact.
Lemma 2.5. Let
 $a_{1},\ldots , a_{n}$
be real numbers. Then,
 $$ \begin{align*}\lim_{\beta\to+\infty}\dfrac1\beta\log\bigg(\kern-2pt\sum_{i=1}^{n}e^{\beta a_{i}}\bigg)=\max_{i}a_{i}.\end{align*} $$
Lemma 2.6. (See [Reference Lopes, Mengue, Mohr and Souza22])
Let M be any compact metric space. Let
 $W_{\beta }:M\to \mathbb {R}$
be a family of continuous functions converging uniformly to
 $W:M\to \mathbb {R}$
, as
 $\beta \to +\infty $
. Then, for any finite measure
 $\nu $
with
 $\mbox {supp}\,(\nu ) = M$
,
 $$ \begin{align*} \lim_{\beta \to \infty} \frac{1}{\beta} \log \int_M e^{\beta W_\beta(a)} \,d\nu(a) = \sup_{a\in M}\, W(a). \end{align*} $$
Proof. Let
 $m = \sup \{W(a) \,|\, a \in M\}$
. We first prove
 $$ \begin{align*} \liminf_{\beta \to +\infty} \frac{1}{\beta} \log \int_M e^{\beta W_\beta(a)} \,d\nu(a) \geq m. \end{align*} $$
Given
 $\varepsilon>0$
, let
 $\bar a \in M$
be such that
 $W(\bar a)> m-\varepsilon /2$
. There exist
 $\beta _0$
and
 $\delta $
such that
 $W_\beta (a)> m - \varepsilon $
for any
 $a \in B(\bar a,\delta ) = \{a \,|\, d(a,\bar a)<\delta \}$
and
 $\beta> \beta _0$
.
Therefore, if
 $\beta> \beta _0$
, we have that
 $$ \begin{align*}\int_M e^{\beta W_\beta(a)} \,d\nu(a) \geq \int_{B(\bar a,\delta)} e^{\beta W_\beta(a)}\, d\nu(a)> \nu(B(\bar a,\delta)) e^{\beta(m-\varepsilon)}\end{align*} $$
and then,
 $$ \begin{align*} \frac{1}{\beta} \log \int_X e^{\beta W_\beta(a)} \,d\nu(a)>\frac{1}{\beta}\log(\nu(B(\bar a,\delta))) + m-\varepsilon.\end{align*} $$
We conclude that
 $$ \begin{align*} \liminf_{\beta \to +\infty} \frac{1}{\beta} \log \int_M e^{\beta W_\beta(a)} \,d\nu(a) \geq m. \end{align*} $$
The converse inequality is obtained in the same way: for a given
 $\varepsilon $
, there exists
 $\beta _0$
such that
 $W_\beta (a) < m + \varepsilon $
for any
 $\beta>\beta _0$
and
 $a\in M$
.
2.3 Eigenfunctions and calibrated subactions
2.3.1 Calibrated subaction as limit of eigenfunctions
Lemma 2.7. Let
 $B_\beta :X\to \mathbb {R}$
be a family of Lipschitz functions satisfying:
-
(1)
$\mathrm {Lip}(B_\beta ) \leq \beta c$
for some constant c and any
$\beta $
; -
(2)
${|B_\beta |_\infty }/{\beta }$
converges to zero as
$\beta \to \infty $
.


There exist accumulation points for
 $({1}/{\beta })\log (H_{\beta A+B_{\beta }})$
for the norm
 $|\,\cdot\,|_\infty $
. Any such limit is a calibrated subaction for A.
Proof. It is known that there exists a constant
 $c_1$
such that for any Lipschitz function
 $\phi $
and any
 $x, y\in X$
,
 $$ \begin{align*}e^{-c_1(1+|\phi|_\infty +\mathrm{Lip}(\phi))\,d(x,y)}\le \frac{H_\phi(x)}{H_\phi(y)} \leq e^{c_1(1+|\phi|_\infty +\mathrm{ Lip}(\phi))\,d(x,y)}\end{align*} $$
(see for example [Reference Mengue23, pp. 46–51], also see [Reference Bowen and Chazottes7, Lemma 1.8]). The main point here is that
 $c_{1}$
is a universal constant and does not depend on
 $\phi $
. Actually, it only depends on the mixing rate in X.
This yields that
 $\log H_{\phi }$
is Lipschitz continuous with Lipschitz constant bounded by
 $c_1(1+|\phi |_\infty +\mathrm {Lip}(\phi ))$
. Applying this to
 $\phi :=\beta A+B_{\beta }$
, we get that the family
 $(1/\beta )\log H_{\beta A+B_{\beta }}$
is equicontinuous with bounded Lipschitz norm.
By Arzelà–Ascoli theorem, we conclude that there exists accumulation points for the
 $|\,\cdot\,|_{\infty }$
-norm and they are Lipschitz continuous.
Note the next double-inequality
 $$ \begin{align} P(\beta A)-|B_{\beta}|_{\infty}\le P(\beta A+B_{\beta})\le P(\beta A)+|B_{\beta}|_{\infty}. \end{align} $$
Now, by definition of the eigenfunction, we get that for any
 $x\in X$
,
 $$ \begin{align*}\sum_{\sigma(z)=x} e^{\beta A(z) + B_{\beta}(z) +\log(H_{\beta A +B_\beta}(z)) - \log(H_{\beta A +B_\beta}(x)) - P(\beta A +B_\beta)} =1\end{align*} $$
holds. Taking
 $(1/\beta )\log $
, considering any accumulation point
 $\widetilde V$
for
 $(1/\beta )\log H_{\beta A+B_{\beta }}$
, Lemma 2.6 and (3) yield
 $$ \begin{align*}\sup_{\sigma(z) = x} [A(z) + \tilde{V}(z) - \tilde{V}(x) -m(A) ]=0.\\[-42pt] \end{align*} $$
2.3.2 Calibrated subactions and the Mañé potential
The results in this section are well known in the literature (see [Reference Baraviera, Leplaideur and Lopes2, Reference Baraviera, Lopes and Thieullen5, Reference Contreras, Lopes and Thieullen12, Reference Garibaldi and Lopes15]). Anyway, for the sake of completeness, we will present most of the proofs.
We remind that the Aubry set
 $\Omega $
is non-empty as it contains the Mather set. First, we state a technical lemma.
Lemma 2.8. Let x and y be in X. Let
 $\overline \xi _{n}$
be points such that
 $\overline \xi _{n}\to x$
as n goes to
 $+\infty $
, and for any n, there exists
 $k_{n}$
with
 $k_{n}\to +\infty $
as
 $n\to +\infty $
such that
 $\sigma ^{k_{n}}(\overline \xi _{n})=y$
. Then,
 $$ \begin{align*}S(x,y)\ge\limsup_{n\to+\infty}S_{k_{n}}(A)(\overline\xi_{n}).\end{align*} $$
Proof. Pick
 $\varepsilon>0$
. Let N be such that for every
 $n>N$
,
 $d(x,\overline \xi _{n})<\varepsilon $
. Then,
 $$ \begin{align*}S^{\varepsilon}(x,y):=\sup{\{S_{k}(A)(z),\ \sigma^{k}(z)=y,\ d(x,z)<\varepsilon\}}\ge S_{k_{n}}(A)(\overline\xi_{n})\end{align*} $$
holds as soon as
 $n>N$
holds. This yields, for every
 $\varepsilon $
,
 $ S^{\varepsilon }(x,y)\ge \limsup _{n}S_{k_{n}}(A)(\overline \xi _{n})$
. Hence, doing
 $\varepsilon \downarrow 0$
, we get the result.
Lemma 2.9. The potential A is equal to 0 on
 $\Omega $
.
Proof. By definition, x belongs to
 $\Omega $
if and only if
 $S(x,x)=0$
. Hence,
 $$ \begin{align*} 0\ge A(x)\geq S(x,x)=0.\\[-39pt] \end{align*} $$
Now, we present a very important characterization of calibrated subactions using Mañé potential and Aubry and Mather sets.
Lemma 2.10. For any calibrated subaction V,
 $$ \begin{align*}V(x_0) = \sup_{a\in \mathcal{M}} [V(a) + S(a,x_0)] =\sup_{a\in \Omega} [V(a) + S(a,x_0)]\quad\text{for all } x_0 \in X.\end{align*} $$
Proof. We follow the ideas of [Reference Baraviera, Lopes and Thieullen5]. Let V be any calibrated subaction. As
 $\mathcal {M}\subset \Omega $
holds,
 $$ \begin{align*}\sup_{a\in \mathcal{M}} [V(a) + S(a,x_0)] \leq \sup_{a\in \Omega} [V(a) + S(a,x_0)].\end{align*} $$
As V is a subaction,
 $A +V-V\circ \sigma \leq 0$
and then, for any n and any z,
 $$ \begin{align*}S_{n}(A)(z)+V(z)\le V\circ \sigma^{n}(z).\end{align*} $$
This yields for any
 $a,x_0 \in X$
,
 $S(a,x_0)+V(a)-V(x_0)\leq 0$
and, hence,
 $$ \begin{align*}V(x_0) \geq V(a) + S(a,x_0)\quad\text{for all } a,x_0 \in X\end{align*} $$
holds. This proves that
 $$ \begin{align*}V(x_0) \geq \sup_{a\in \Omega} [V(a) + S(a,x_0)] .\end{align*} $$
Now, we will prove that
 $\sup _{a\in \mathcal {M}} [V(a)\hspace{-1pt} +\hspace{-1pt} S(a,x_0)]\hspace{-0.5pt} \geq\hspace{-0.5pt} V(x_0)$
. Set
 $R_{-}\hspace{-1pt}=\hspace{-1pt}A\hspace{-1pt} +\hspace{-1pt}V\hspace{-1pt} -\hspace{-1pt}V\circ \sigma $
. By definition of calibrated subaction, the following hold:
-
(1)
$R_{-} \leq 0$
; -
(2) there exists a sequence of points
$(x_n)$
such that for every
$n\geq 1$
,
$\sigma (x_n) = x_{n-1}$
and
$R_{-}(x_n) = 0$
.


Let us consider the sequence of probabilities
 $\nu _n = (1/n)\sum _{i=1}^{n}\delta _{x_{i}}$
,
 $n\ge 1$
. Let
 $\nu $
be an accumulation point for the weak* topology as
 $n\to \infty $
, say
 $\nu :=\lim _{n_j\to \infty } \nu _{n_j}$
. As for any continuous function
 $f:X\to \mathbb {R}$
,
 $$ \begin{align*} \int f\circ\sigma\,d\nu &= \lim_{n_j} \frac{1}{n_j}\sum_{i=1}^{n_j}f(\sigma(x_i)) \stackrel{\sigma(x_i) = x_{i-1}}{=} \lim_{n_j} \frac{1}{n_j}\sum_{i=1}^{n_j}f(x_{i-1})\\ &=\lim_{n_j} \frac{1}{n_j}\bigg[f(x_0)-f(x_{n_j})+\sum_{i=1}^{n_j}f(x_{i})\bigg] = \lim_{n_j} \frac{1}{n_j}\bigg[\sum_{i=1}^{n_j}f(x_{i})\bigg]=\int f\,d\nu, \end{align*} $$
then,
 $\nu $
is
 $\sigma$
-invariant.
By construction of
 $R_{-}$
and
 $\nu _n$
, we have
 $\int A\,d\nu _{n}=\int R_{-}\,d\nu _n=0$
and, thus,
 $\int A\,d\nu =0$
. Therefore,
 $\nu $
is A-maximizing.
Now, we fix any point
 $a\in \operatorname {supp}(\nu )$
. Note that a belongs to
 ${\mathcal M}\subset \Omega $
. By definition of support, we have
 $\nu ( \{z|d(z,a)\leq \epsilon \})>0$
for any
 $\epsilon>0$
. It follows that, for arbitrarily large n, we have also
 $\nu _n(\{z:d(z,a)\leq \epsilon \})>0$
, which proves that a is an accumulation point of the sequence
 $(x_n)$
. By considering a subsequence
 $(x_{n_k})$
satisfying
 $x_{n_k}\to a$
,
 $$ \begin{align*} S(a,x_0) &\geq \lim_{n_k\to\infty}[S_{n_k}(A)(x_{n_k}) ]\\ &=\lim_{n_k\to\infty} [S_{n_k}(R_{-})(x_{n_k}) -V(x_{n_k})+V(x_0)]\\ & =V(x_0)-V(a). \end{align*} $$
This proves
 $$ \begin{align*}V(x_0) \leq \sup_{a\in \mathcal{M}} [V(a) + S(a,x_0)].\\[-41pt] \end{align*} $$
Let us recall also a classical result for the Mañé potential.
Lemma 2.11. Let S be the Mañé potential. We have:
-
(1)
$S(x,y)+S(y,z)\le S(x,z)$
for every x, y, z in X; -
(2) for any fixed
$x\in \Omega $
, the map
$y\mapsto S(x,y)$
is Lipschitz continuous; -
(3) if
$S(x,y)+S(y,x)=0$
, then
$S(x,.)=S(y,.)$
; -
(4) if
$\sigma (x)=y$
, then
$S(x,y)=A(x)$
.


Proof. The proof of item (1) follows from a direct analysis of the definition of Mañé potential, making for each possible
 $x'=x_1'\cdots x_l'y \in \sigma ^{-l}(y)\cap B(x,\epsilon )$
and
 $y'=y_1'\cdots y_k'z\in \sigma ^{-k}(z)\cap B(y,\epsilon )$
the comparison with the point
 $x"=x_1'\cdots x_l'y_1'\cdots y_k'z $
using that
 $A\leq 0$
is a Lipschitz function. For item (2), see [Reference Contreras, Lopes and Thieullen12, Proposition 23].
To prove item (3), just observe that
 $S(x,y)+S(y,x)=0$
and
 $S(\cdot,\cdot)\le 0$
yields
 $$ \begin{align*}S(x,y)=S(y,x)=0.\end{align*} $$
Hence, for any
 $z\in X$
,
 $$ \begin{align*}S(x,z) \stackrel{(1)}{\geq} S(x,y)+S(y,z) = S(y,z) \stackrel{(1)}{\geq} S(y,x)+S(x,z) = S(x,z).\end{align*} $$
The proof of item (4) has two steps. First, note that if
 $ z$
is such that
 $\sigma ^{n}(z)=y$
and
 $d(x,z)<\varepsilon $
, then
 $$ \begin{align*}S_{n}A(z)\le A(z)\le A(x)+C\,d(x,z) \le A(x)+C\varepsilon.\end{align*} $$
This yields for any positive
 $\varepsilon $
,
 $$ \begin{align*}S^{\varepsilon}(x,y)=\sup\{S_n(A)(z),\ \sigma^{n}(z)=y,\, d(x,z)<\varepsilon\}\le { A(x)+C\varepsilon}.\end{align*} $$
Doing
 $\varepsilon \downarrow 0$
, we get
 $S(x,y)\le A(x)$
.
However, as
 $\sigma (x)=y$
,
 $$ \begin{align*}\sup\{S_n(A)(z),\ \sigma^{n}(z)=y,\, d(x,z)<\varepsilon\}\ge A(x),\end{align*} $$
which yields the other inequality.
3 Proof of Theorem A
3.1 Initial results
We remind that A is assumed to be Lipschitz continuous, non-positive, non-constant, and satisfying
 $m(A)=0$
. The Aubry set is defined by
 $$ \begin{align*}\Omega:=\{x\in X,\ S(x,x)=0\},\end{align*} $$
where
 $S(\cdot\,,\cdot)$
is the Mañé potential (see Definition 1.1).
First, we give an explicit decomposition of the Aubry set in irreducible components. We follow here [Reference Katok and Hasselblatt17, Exercises session 1.9].
Let us suppose that
 $\Omega \subset X$
is a sub-shift of finite type. In this way, there is a collection
 $\mathcal {C}$
of cylinder sets of length N such that
 $x\in X$
is a point of
 $\Omega $
if and only if
 $\sigma ^{n}(x) \in \bigcup _{C\in \mathcal {C}}C$
for all
 $n\in \{0,1,2,\ldots \}$
. By recoding the alphabet of X (let us denote again
 $\{0,1,\ldots ,d\}$
), we can suppose that
 $N=2$
.
In this way, there is an aperiodic matrix
 $\mathcal {A}_{d\times d},$
with entries in
 $\{0,1\}$
, such that
 $(x_n) \in X$
if and only if
 $\mathcal {A}_{x_ix_{i+1}}=1\,\text { for all } i\in \mathbb {N}$
and a matrix
 $\mathcal {B}_{d\times d},$
with entries in
 $\{0,1\}$
, such that
 $(x_n) \in X$
is a point of
 $\Omega $
if and only if
 $\mathcal {B}_{x_ix_{i+1}}=1\,\text { for all } i\in \mathbb {N}$
. Clearly,
 $\mathcal {A}_{ij}=0 \Rightarrow \mathcal {B}_{ij}=0$
.
Let us denote by
 $F_\Omega \subset \{0,1,\ldots d\}$
the sub-alphabet of
 $\Omega $
, that is,
 $a\in F_\Omega $
if there is
 $(x_n)\in \Omega $
such that
 $a=x_i$
for some i. We say that two letters
 $a,b \in F_\Omega $
are associated if there is
 $n,m$
such that
 $(\mathcal {B}^n)_{ab}>0$
and
 $(\mathcal {B}^m)_{ba}>0$
. In what follows, we will prove that
 $\Omega $
can be decomposed as a finite union of irreducible sub-shifts of finite type where the letters defining each sub-shift are associated.
Proposition 3.1. Under the above setting and notation, and supposing
 $a,b \in F_\Omega $
, if there is k such that
 $(\mathcal {B}^k)_{ab}>0$
, then there is m such that
 $(\mathcal {B}^m)_{ba}>0$
.
Proof. By hypothesis, there is
 $x=(x_1,x_2,x_3,\ldots )=(a,x_2,\ldots ,x_{k+1},b,x_{k+3},\ldots )$
, which is a point of
 $\Omega $
(we can suppose
 $x_2,\ldots ,x_{k+1} \notin \{a,b\}$
). Then,
 $S(x,x) = 0$
and, therefore, there is a sequence of points
 $\overline \xi _{n}:=(x_{N(n)}^n,\ldots ,x_{1}^n,x_1,x_2,x_3,\ldots )\in X, n\in \mathbb {N},$
which converges to x, such that
 $S_{N(n)}(A)(\overline \xi _{n})>-{1}/{n}.$
If
 $\overline \xi _{n} \in \Omega $
for some n such that
 $d(\overline \xi _{n},x)<\theta ^{k+2}$
, then the proof is complete.
Let us suppose by contradiction that
 $\overline \xi _{n} \notin \Omega $
for n large enough. For simplicity, we suppose that for every n,
 $\overline \xi _{n} \notin \Omega $
.
As
 $x \in \Omega $
, we can consider
 $M(n)\le N(n)$
the smallest integer r such that
 $\sigma ^{N(n)-r}(\overline \xi _{n})\notin \Omega $
. That is,
 $$ \begin{align*}\overline z_{n}:=\sigma^{N(n)-M(n)}(\overline\xi_{n})\notin \Omega,\ \sigma(\overline z_{n}):=\sigma^{N(n)-M(n)+1}(\overline\xi_{n})\in \Omega.\end{align*} $$
Then,
 $\overline z_n \in \sigma ^{-1}(\Omega )\setminus \Omega $
. Due to our assumption on
 $\Omega $
and X, this yields that
 $z_{n}$
belongs to a 2-cylinder, say
 $[a'b']$
, that is not eligible for
 $\Omega $
. We can consider a converging subsequence for
 $(\overline z_n)$
. Again, for simplicity, we assume that
 $\overline z_{n}\to z$
holds. Then, we emphasize that z belongs to the same 2-cylinders as the
 $z_{n}$
terms and, hence,
 $z\notin \Omega $
.
However,
 $S_{N(n)}(A)(\overline \xi _{n})=S_{N(n)-M(n)}(A)(\overline \xi _{n})+S_{M(n)}(A)(\overline z_{n})$
and the last two summands are non-positive. This yields
 $$ \begin{align*}0\ge S_{M(n)}(A)(\overline z_{n})\ge S_{N(n)}(A)(\overline \xi_{n})>-\frac{1}{n}.\end{align*} $$
Then, Lemma 2.8 yields
 $0\ge S(z,x)\ge 0$
and, hence,
 $S(z,x)=0$
.
As
 $\overline \xi _{n}$
converges to x and
 $\sigma ^{N(n)-M(n)}(\overline \xi _{n})=\overline z_{n}$
, we get for any positive
 $\varepsilon $
and for any sufficiently large n,
 $$ \begin{align*}S^{\varepsilon}(x,\overline z_{n})\ge S_{N(n)-M(n)}(A)(\overline\xi_{n})>-\frac1n.\end{align*} $$
Then, Lemma 2.8 and Lipschitz continuity in the second variable (note that x belongs to
 $\Omega $
) for
 $S(x,\cdot)$
yield
 $$ \begin{align*}0\ge S(x,z)=\lim_{n}S(x,\overline z_{n})=0.\end{align*} $$
Finally,
 $S(z,z)\ge S(z,x)+S(x,z)=0$
shows that z belongs to
 $\Omega $
, which is a contradiction.
Proposition 3.2. Under the hypotheses of Theorem A, the Aubry set
 $\Omega $
can be decomposed as a finite union of irreducible sub-shifts of finite type
 $$ \begin{align*}\Omega = \Sigma_1 \cup \cdots\cup \Sigma_{L}.\end{align*} $$
Proof. If
 $a \in F_\Omega $
, there is a sequence
 $x=(x_1,x_2,\ldots )$
with some
 $x_i=a$
. Consider
 $b=x_{i+1}$
. By applying the above lemma, there is m such that
 $\mathcal {B}^m_{ba}>0$
. Therefore,
 $\mathcal {B}^{m+1}_{aa}>0$
. Consequently, we get an equivalence relation
 $\sim $
where
 $a\sim b$
if and only if there is n such that
 $(\mathcal {B}^n)_{ab}>0$
. Let us decompose
 $F_\Omega =F_1\cup \cdots \cup F_L$
in equivalence classes. Let
 $\Sigma _i\subset \Omega $
be the irreducible sub-shift of finite type associated to the alphabet
 $F_i$
, that is,
 $\Sigma _i= \Omega \cap F_i^{\mathbb {N}}$
. It follows that
 $\Omega = \Sigma _1 \cup \cdots \cup \Sigma _{L}$
.
Let us consider a decomposition of the Aubry set in irreducible sub-shifts of finite type
 $$ \begin{align*}\Omega = \Sigma_1 \cup \cdots\cup \Sigma_k \cup\Sigma_{k+1}\cup\cdots\cup \Sigma_{L},\end{align*} $$
where
 $\Sigma _i \cap \Sigma _j =\emptyset $
for
 $i\neq j$
,
 $h_{\text {top}}(\Sigma _i) = h$
if
 $i\in \{1,\ldots ,k\}$
, and
 $h_{\text {top}}(\Sigma _i)<h$
if
 $i\in \{k+1,\ldots ,L\}$
.
It follows that
 $A=0$
over the sets
 $\Sigma _i$
, where
 $i\in \{1,\ldots ,L\}$
.
Lemma 3.3. For each
 $i\in \{1,\ldots ,L\},$
the set
 $\sigma ^{-1}(\Sigma _{i})\setminus \Sigma _{i}=\{x\in X| x\notin \Sigma _i,\sigma (x) \in \Sigma _i\}$
is non-empty and compact.
Proof. We start by proving that it is a non-empty set. Indeed, supposing by contradiction that it is empty, we get
 $\sigma ^{-1}(\Sigma _i)\subseteq \Sigma _i$
and consequently
 $\sigma ^{-n}(\Sigma _i)\subseteq \Sigma _i \text { for all } n$
. It follows that
 $\bigcup _{n\in \mathbb {N}}\sigma ^{-n}(\Sigma _i)\subseteq \Sigma _i$
and then
 $A = 0$
over
 $\bigcup _{n\in \mathbb {N}}\sigma ^{-n}(\Sigma _i)$
, which is a dense subset of X. By continuity, we get that A is constant and equal to zero on X, which is a contradiction.
As X is compact, we only need to prove that
 $\sigma ^{-1}(\Sigma _{i})\setminus \Sigma _{i}$
is closed. Let
 $(y_n)$
be a sequence in
 $\sigma ^{-1}(\Sigma _{i})\setminus \Sigma _{i}$
converging to y in X. We will prove that
 $y\in \sigma ^{-1}(\Sigma _{i})\setminus \Sigma _{i}$
.
As
 $\Sigma _{i}$
is a sub-shift of finite type, we can find some positive integer l and a collection of cylinders of length l, say
 ${\mathcal C}$
, coinciding with the admissible words (of length l) for
 $\Sigma _{i}$
. That is that x belongs to
 $\Sigma _{i}$
if and only if for every
 $n\ge 0$
,
 $\sigma ^{n}(x)$
belongs to one of the cylinders in
 ${\mathcal C}$
.
By continuity,
 $\sigma (y_{n})$
converges to
 $\sigma (y)$
. Furthermore,
 $\sigma (y_{n})$
belongs to the closed set
 $\Sigma _{i}$
, by hypothesis, and thus,
 $\sigma (y)$
also belongs to
 $\Sigma _{i}$
.
As
 $y_n\to y$
, we can assume that all the
 $y_{n}$
belong to the same l-cylinder than y. As
 $\sigma (y_n) \in \Sigma _{i}$
and
 $y_n\notin \Sigma _i$
, this cylinder does not belong to the collection
 ${\mathcal C}$
and so
 $y\notin \Sigma _i$
. Therefore,
 $y\in \sigma ^{-1}(\Sigma _{i})\setminus \Sigma _{i}$
.
3.2 Another characterization for the
$\Sigma _{i}$
terms

We recall that the Aubry set
 $\Omega $
is defined as the set of points x satisfying
 $S(x,x)=0,$
where the function S is the Mañé potential.
We define an equivalence relation by
 $$ \begin{align*}x \sim y\iff S(x,y)+S(y,x)=0.\end{align*} $$
Our main result for this section (Proposition 3.4) is that equivalence classes for that relation coincide with the decomposition of
 $\Omega $
in irreducible components.
Proposition 3.4. The irreducible components
 $\Sigma _i$
,
 $i\in \{1,\ldots ,L\}$
, of the Aubry set as a sub-shift of finite type coincide with the classes of equivalence, which are defined by the equation
 $$ \begin{align*}S(x,y)+S(y,x)=0.\end{align*} $$
Proof. Let
 $x=(x_1,x_2,x_3,\ldots )$
and
 $y=(y_1,y_2,y_3,\ldots )$
be points of X.
Step 1. Suppose
 $x,y\in \Sigma _i$
. We show that
 $S(x,y) = 0$
.
As
 $\Sigma _i$
is irreducible, for each n, there exists a word
 $z_1^n,\ldots ,z_{N(n)}^n$
such that
 $$ \begin{align*}\overline\xi_{n} := (x_1,\ldots,x_n, z_1^n,\ldots,z_{N(n)}^n, y_1,y_2,y_3,\ldots) \in \Sigma_i.\end{align*} $$
As
 $\Sigma _i\subset \Omega $
, we get
 $S_{n+N(n)}(A)( \overline \xi _{n}) = 0$
,
 $\lim _{n\to +\infty }\overline \xi _{n}=x$
and
 $\sigma ^{n+N_{n}}(\overline \xi _{n})=y$
. Then, Lemma 2.8 yields
 $$ \begin{align*}0\ge S(x,y) \geq \lim_{n\to +\infty} S_{n+N(n)}(A)( \overline\xi_{n}) = 0.\end{align*} $$
This shows that
 $S(x,y)=0$
holds. Similarly, exchanging the roles for x and y, we get
 $S(y,x)=0$
.
Step 2. The argument follows the same lines as the proof of Proposition 3.1. Suppose
 $S(x,y)+S(y,x) = 0$
. Item (1) in Lemma 2.11 yields
 $S(x,x)=S(y,y)=0$
and, hence,
 $x,y\in \Omega $
.
Let us suppose by contradiction that
 $y\in \Sigma _i$
and
 $x\notin \Sigma _i$
. As
 $S(x,y) = 0$
, there exists a sequence of points
 $\overline \xi _{n}:=(x_{N(n)}^n,\ldots ,x_{1}^n,y_1,y_2,y_3,\ldots )\in X, n\in \mathbb {N},$
which converges to x, such that
 $S_{N(n)}(A)(\overline \xi _{n})>-{1}/{n}.$
As
 $\Sigma _i$
is closed and
 $x\notin \Sigma _i$
, we have that
 $\overline \xi _{n} \notin \Sigma _i$
for n large enough. For simplicity, we suppose that for every n,
 $\overline \xi _{n} \notin \Sigma _i$
.
As
 $y \in \Sigma _i$
and
 $\Sigma _{i}$
is invariant, we can consider
 $M(n)\le N(n)$
such that
 $$ \begin{align*}\overline z_{n}:=\sigma^{N(n)-M(n)}(\overline\xi_{n})\notin \Sigma_{i},\ \sigma(\overline z_{n}):=\sigma^{N(n)-M(n)+1}(\overline\xi_{n})\in \Sigma_{i}.\end{align*} $$
Then,
 $\overline z_n \in \sigma ^{-1}(\Sigma _{i})\setminus \Sigma _{i}$
, which is compact; therefore, there exists a converging subsequence for
 $(\overline z_n)$
. Again, for simplicity, we assume that
 $\overline z_{n}\to z$
holds. Note that
 ${z \in \sigma ^{-1}(\Sigma _{i})\setminus \Sigma _{i}}$
holds. Furthermore,
 $$ \begin{align*}0\ge S_{M(n)}(A)(\overline z_{n})\ge S_{N(n)}(A)(\overline \xi_{n})>-\frac{1}{n}.\end{align*} $$
Then, Lemma 2.8 yields
 $0\ge S(z,y)\ge 0$
and, hence,
 $S(z,y)=0$
.
As
 $\overline \xi _{n}$
converges to x and
 $\sigma ^{N(n)-M(n)}(\overline \xi _{n})=\overline z_{n}$
, we get for any positive
 $\varepsilon $
and for any sufficiently big n,
 $$ \begin{align*}S^{\varepsilon}(x,\overline z_{n})\ge S_{N(n)-M(n)}(A)(\overline\xi_{n})>-\frac1n.\end{align*} $$
Then, Lemma 2.8 and Lipschitz continuity in the second variable for
 $S(x,.)$
yield
 $$ \begin{align*}0\ge S(x,z)=\lim_{n}S(x,\overline z_{n})=0.\end{align*} $$
Finally,
 $S(z,z)\ge S(z,y)+S(y,x)+S(x,z)=0$
shows that z belongs to some
 $\Sigma _{k}$
. So does
 $\sigma (z)$
and, hence,
 $k=i$
and this produces a contradiction.
Lemma 3.5. If V is a calibrated subaction for A, then V is constant on each set
 $\Sigma _i$
.
Proof. Let
 $x,y \in \Sigma _i$
and V be a calibrated subaction. As
 $S(x,y)=S(y,x) = 0$
, by applying Lemma 2.10,
 $$ \begin{align*} V(x) =\sup_{a\in \Omega}[S(a,x)+V(a)] \geq S(y,x) +V(y) = V(y)\end{align*} $$
and
 $$ \begin{align*}V(y) = \sup_{a\in \Omega}[S(a,y)+V(a)] \geq S(x,y) +V(x) = V(x).\\[-42pt]\end{align*} $$
3.3 A Max-Plus formula for the calibrated subaction V
We remember that we are supposing in this section that
 $$ \begin{align*}\Omega = \Sigma_1 \cup \cdots\cup \Sigma_k \cup\Sigma_{k+1}\cup\cdots\cup \Sigma_{L},\end{align*} $$
where
 $\Sigma _i \cap \Sigma _j =\emptyset $
for
 $i\neq j$
,
 $h_{\text {top}}(\Sigma _i) = h$
if
 $i\in \{1,\ldots ,k\}$
, and
 $h_{\text {top}}(\Sigma _i)<h$
if
 $i\in \{k+1,\ldots ,L\}$
.
From now on, let us denote
 $S_{i}(\cdot) := S(x,\cdot),$
where x is any point of
 $\Sigma _i$
(see Lemma 2.11(3)). If
 $\Sigma _{i}$
and
 $\Sigma _{j}$
are two irreducible components of
 $\Omega $
,
 $$ \begin{align*}a_{ij}:=\sup_{x\in \Sigma_{i}}\sup_{y\in \sigma^{-1}(x),y\notin\Sigma_{i}}A(y)+S_{j}(y)=\sup_{y\in \sigma^{-1}(\Sigma_{i})\setminus\Sigma_{i}}A(y)+S_{j}(y).\end{align*} $$
Lemma 3.6. For every
 $i,j,l \in \{1,\ldots ,L\}$
, the next hold:
-
(1)
$-\infty <a_{ij}\le 0$
; -
(2)
$a_{ii}<0$
; -
(3)
$a_{li}+a_{ij}\le a_{lj}$
.


Proof. First, A is non-positive and, thus, so is S. Second, Lemma 2.11 yields each
 $S_{j}$
is Lipschitz continuous and, hence, bounded on the compact set
 $\sigma ^{-1}(\Sigma _{i})\setminus \Sigma _{i}$
(see Lemma 3.3). This also holds for A and, thus, each
 $a_{ij}$
is a real number. This finishes the proof of item (1).
For the proof of item (2), as
 $y\mapsto A({y})+S_{i}(y)$
is continuous on the compact set
 $\sigma ^{-1}(\Sigma _{i})\setminus \Sigma _{i}$
, it attains its maximum.
If
 $y\in \sigma ^{-1}(\Sigma _{i})\setminus \Sigma _{i}$
is such that
 $$ \begin{align*}a_{ii}=A(y)+S_{i}(y),\end{align*} $$
then, setting
 $x:=\sigma (y)$
, we have
 $x\in \Sigma _i$
and
 $a_{ii}=A(y)+S(x,y)$
. By item (4) in Lemma 2.11,
 $S(y,x)=A(y)$
. This yields
 $$ \begin{align*}a_{ii}={A(y)+S(x,y)= S(y,x)+S(x,y)}<0,\end{align*} $$
since
 $y\notin \Sigma _{i}$
(see Proposition 3.4).
For the proof of item (3), if
 $i=l$
, we just need to apply item (2). Suppose then
 $i\neq l$
, and let
 $y_{i}\in \sigma ^{-1}(\Sigma _{i})\setminus \Sigma _{i}$
and
 $y_{l}\in \sigma ^{-1}(\Sigma _{l})\setminus \Sigma _{l}$
be such that
 $$ \begin{align*}a_{ij}=A(y_{i})+S_{j}(y_{i}),\quad a_{li}=A(y_{l})+S_{i}(y_{l}).\end{align*} $$
Set
 $x_{i}:=\sigma (y_{i})\in \Sigma _{i}$
and note that
 $S_{i}(y_{l})=S(x_{i},y_{l})$
holds. Again, Lemma 2.11 yields
 $S(y_{i},x_{i})=A(y_{i})$
. Hence,
 $$ \begin{align*} a_{li}+a_{ij}&= A(y_{l})+S_{i}(y_{l})+A(y_{i})+S_{j}(y_{i})\\ &= A(y_{l})+S(x_{i},y_{l})+S(y_{i},x_{i})+S_{j}(y_{i})\\ &\le A(y_{l})+S_{j}(y_{l})\le a_{lj}.\\[-3pc] \end{align*} $$
Remark 3.7. If V is a calibrated subaction, then it is constant on each set
 $\Sigma _{i}$
(by Lemma 3.5). It thus makes sense to set
 $V(\Sigma _{i})$
and we will use such notation from now on in the present section.
Proposition 3.8. Any accumulation point for
 $ ({1}/{\beta })\log (P(\beta A) - h )$
belongs to
 $]{-}\infty ,0]$
. Furthermore, if
 ${\lim _{\beta _j\to \infty } ({1}/{\beta _j})\log (P(\beta _j A) - h )}=\gamma $
and
 $\lim _{\beta _j\to \infty } ({1}/{\beta _{j}}) \log (H_{\beta _{j}A})=V$
, then,
 $$ \begin{align} \gamma + V(\Sigma_i) = \max_{j\in\{1,\ldots,L\}}V(\Sigma_j)+a_{ij}\quad\text{for all } i\in\{1,\ldots,k\}\end{align} $$
and
 $$ \begin{align} V(\Sigma_i) = \max_{j\in\{1,\ldots,L\}}V(\Sigma_j)+a_{ij}\quad\text{for all } i\in\{k+1,\ldots,L\}.\end{align} $$
Proof. As it is said previously (see Lemma 2.2),
 $\beta \mapsto P(\beta A)-h$
is non-increasing and goes to 0 as
 $\beta \to +\infty $
. Hence,
 $\beta \mapsto \log (P(\beta A)-h)$
is also non-increasing and it is negative for sufficiently large
 $\beta $
. This shows that any accumulation point for
 $(1/\beta )\log (P(\beta A)-h)$
is in
 $[-\infty ,0]$
.
Because V is Lipschitz continuous on
 $\Omega $
, thus bounded, and because all the
 $a_{ij}$
are real numbers, (4) shows that
 $\gamma $
is a real number and, hence,
 $\gamma>-\infty $
.
Let us now consider the Ruelle operator for
 $\beta A$
, given by
 $$ \begin{align*}{L}_{\beta A}(\varphi)(x) = \sum_{y\in \sigma^{-1}(x)}e^{\beta A(y)}\varphi(y).\end{align*} $$
For each
 $i\in \{1,\ldots ,L\}$
, we can also consider the Ruelle operator for the zero potential acting over
 ${\mathcal C}(\Sigma _i)$
:
 $$ \begin{align*}\mathcal{L}_{i}(\varphi)(x) = \sum_{y\in \sigma^{-1}(x),\quad y\in \Sigma_i}\varphi(y),\end{align*} $$
where
 $x\in \Sigma _i$
. As we suppose that
 $\Sigma _i$
is an irreducible sub-shift of finite type, there exists an eigenmeasure
 $\nu _i$
with
 $\mbox {supp}\,(\nu _i) = \Sigma _i$
such that
 $$ \begin{align*}e^{h_i} \int \varphi(x)\,d\nu_i(x) = \int \mathcal{L}_{i}(\varphi)(x) \,d\nu_i(x),\end{align*} $$
where
 $h_i$
is the topological entropy of
 $\Sigma _i$
, which corresponds to the pressure of the zero function on
 $\Sigma _i$
.
We start by supposing
 $i\in \{1,\ldots ,k\}$
. Given
 $x\in \Sigma _i$
,
 $$ \begin{align*}e^{P(\beta A)}H_{\beta A}(x) = \sum_{y\in \sigma^{-1}(x),\,y\in \Sigma_i}e^{\beta A(y)}H_{\beta A}(y) + \sum_{y\in \sigma^{-1}(x),\,y\notin \Sigma_i}e^{\beta A(y)}H_{\beta A}(y)\end{align*} $$
and using that
 $A=0 $
in
 $\Sigma _i$
,
 $$ \begin{align*}e^{P(\beta A)}H_{\beta A}(x)=\mathcal{L}_{i}(H_{\beta A})(x) + \sum_{y\in \sigma^{-1}(x),\,y\notin \Sigma_i}e^{\beta A(y)}H_{\beta A}(y).\end{align*} $$
Integrating both sides with respect to the eigenmeasure
 $\nu _i$
of
 $\mathcal {L}_{i}$
,
 $$ \begin{align*}e^{P(\beta A)}\int H_{\beta A}(x)\,d\nu_i(x) &= \int \mathcal{L}_{i}(H_{\beta A})(x)\,d\nu_i(x)\\ &\quad+ \int\sum_{y\in \sigma^{-1}(x),\,y\notin \Sigma_i}e^{\beta A(y)}H_{\beta A}(y)\,d\nu_i(x),\end{align*} $$
that is,
 $$ \begin{align*}e^{P(\beta A)}\int H_{\beta A}(x)\,d\nu_i(x) &= e^{h}\int H_{\beta A}(x)\,d\nu_i(x)\\ &\quad+ \int\sum_{y\in \sigma^{-1}(x),\,y\notin \Sigma_i}e^{\beta A(y)}H_{\beta A}(y)\,d\nu_i(x).\end{align*} $$
Then,
 $$ \begin{align} (e^{P(\beta A)-h}-1)e^{h}\int H_{\beta A}(x)\,d\nu_i(x) = \int\sum_{y\in \sigma^{-1}(x),\,y\notin \Sigma_i}e^{\beta A(y)}H_{\beta A}(y)\,d\nu_i(x). \end{align} $$
Taking
 $\lim _{\beta _{j}\to +\infty }1/\beta _{j}\log (\cdot )$
in both sides of (6), and considering
 $\lim_{x\to 0} (e^x{\kern-1pt}-{\kern-1pt}1)/x{\kern-1pt}={\kern-1pt}1$
for
 $e^{P(\beta A)}-1$
, we get
 $$ \begin{align} \gamma +0+V(\Sigma_i) = \sup_{x\in \Sigma_i}\sup_{y\in\sigma^{-1}(x),\,y\notin\Sigma_i} A(y) + V(y), \end{align} $$
where for both integrals, we use Lemma 2.6 and that
 $\nu _i$
has full support in
 $\Sigma _i$
.
Now, it follows from Lemmas 2.10 and 3.5 that
 $$ \begin{align*}V(x) = \max_{j\in\{1,\ldots,L\}} V(\Sigma_j) +S_j(x)\end{align*} $$
holds, where
 $S_j$
is the Mañé potential with respect to
 $\Sigma _j$
. Therefore, (7) can be rewritten as
 $$ \begin{align*} \gamma + V(\Sigma_i) &= \sup_{x\in \Sigma_i}\sup_{y\in\sigma^{-1}(x),\,y\notin\Sigma_i} A(y) + \Big(\max_{j\in\{1,\ldots,L\}} V(\Sigma_j) +S_j(y)\Big)\\ &= \sup_{x\in \Sigma_i}\sup_{y\in\sigma^{-1}(x),\,y\notin\Sigma_i} \max_{j\in\{1,\ldots,L\}}( A(y) + V(\Sigma_j) +S_j(y))\\ &= \max_{j\in\{1,\ldots,L\}} \sup_{x\in \Sigma_i}\sup_{y\in\sigma^{-1}(x),\,y\notin\Sigma_i} ( A(y) + V(\Sigma_j) +S_j(y))\\ &= \max_{j\in\{1,\ldots,L\}}V(\Sigma_j)+\Big(\sup_{x\in \Sigma_i}\sup_{y\in\sigma^{-1}(x),\,y\notin\Sigma_i} A(y)+ S_j(y)\Big). \end{align*} $$
Then,
 $$ \begin{align*} \gamma + V(\Sigma_i) = \max_{j\in\{1,\ldots,L\}}V(\Sigma_j)+a_{ij}.\end{align*} $$
The proof for the case
 $i\in \{k+1,\ldots ,L\}$
is similar, except that
 $\gamma $
disappears. Indeed, if
 $\Sigma _{i}$
has entropy
 $h'<h$
, then (6) can be rewritten as
 $$ \begin{align*} (e^{P(\beta A)-h'}-1)e^{h'}\int H_{\beta}(x)\,d\nu_i(x) = \int\sum_{y\in \sigma^{-1}(x),\,y\notin \Sigma_i}e^{\beta A(y)}H_{\beta A}(y)\,d\nu_i(x). \end{align*} $$
The rest of the computations hold, except that
 $\gamma $
has to be removed. Hence,
 $$ \begin{align*} V(\Sigma_{i})=\max_{j\in\{1,\ldots,L\}}V(\Sigma_{j})+a_{ij}. \\[-42pt]\end{align*} $$
3.4 Components with small entropy do not play a role
We remember that
 $h_{\text {top}}(\Sigma _i) = h$
if
 $i\in \{1,\ldots ,k\}$
and
 $h_{\text {top}}(\Sigma _i)<h$
if
 $i\in \{k+1,\ldots ,L\}$
.
Proposition 3.9. If
 $i\in \{k+1,\ldots ,L\}$
, then for every
 $l\in \{1,\ldots ,L\}$
, there exists
 ${j\in \{1,\ldots ,k\}}$
such that
 $$ \begin{align*}V(\Sigma_{i})+a_{li}\le V(\Sigma_{j})+a_{lj}.\end{align*} $$
Proof. From (5) and item (2) of Lemma 3.6, there exists
 $j_{1}\neq i$
such that
 $$ \begin{align} V(\Sigma_{i})=V(\Sigma_{j_{1}})+a_{ij_{1}}.\end{align} $$
Hence, item (3) of Lemma 3.6 yields
 $$ \begin{align*} V(\Sigma_{i})+a_{li} = V(\Sigma_{j_{1}})+a_{ij_{1}}+a_{li} \le V(\Sigma_{j_{1}})+a_{lj_{1}}. \end{align*} $$
If
 $j_{1}\in \{1,\ldots ,k\}$
, then the proposition is proved. If not, then we apply the same reasoning with
 $j_{1}$
instead of i. This produces
 $j_{2}\neq j_{1}$
such that
 $$ \begin{align} V(\Sigma_{j_{1}})=V(\Sigma_{j_{2}})+a_{j_{1}j_{2}}. \end{align} $$
Equations (8) and (9) along with Lemma 3.6 yield
 $$ \begin{align} V(\Sigma_{i})=V(\Sigma_{j_{2}})+a_{ij_{1}}+a_{j_{1}j_{2}}\le V(\Sigma_{j_{2}})+a_{ij_{2}}. \end{align} $$
Again, if
 $j_{2}\in \{1,\ldots ,k\}$
, then we are done. Otherwise, we continue the reasoning. Since there are finitely many components, either we eventually find some
 $j_{l}$
in
 $\{1,\ldots ,k\}$
or some
 $j_{r}$
will be equal to
 $j_l$
with
 $l<r$
. This last case is impossible because we reach a contradiction. Indeed, by applying a similar equation to (9) recursively from
 $j_l$
,
 $$ \begin{align*} V(\Sigma_{j_l})=V(\Sigma_{j_{l+1}})+a_{j_{l}j_{l+1}}=\cdots=V(\Sigma_{j_{r}})+a_{j_{l}j_{l+1}}+\cdots+a_{j_{r-1}j_{r}}. \end{align*} $$
Using that
 $j_r=j_l$
, and applying items (2) and (3) of Lemma 3.6,
 $$ \begin{align*} V(\Sigma_{j_l}) =V(\Sigma_{j_{l}})+a_{j_{l}j_{l+1}}+\cdots+a_{j_{r-1}j_{l}}\leq V(\Sigma_{j_{l}})+a_{j_{l}j_{l}} < V(\Sigma_{j_{l}}),\end{align*} $$
which is a contradiction.
3.5 End of the proof of Theorem A
Proposition 3.10. The limit
 $\gamma = \lim _{\beta \to \infty } ({1}/{\beta })\log (P(\beta A) - h )$
exists. Furthermore, it is the unique eigenvalue for the
 $k\times k$
matrix in the Max-Plus formalism whose entries are the
 $a_{ij}$
terms.
Proof. Suppose that
 $\Omega = \Sigma _1 \cup \cdots \cup \Sigma _k \cup \Sigma _{k+1}\cup \cdots \cup \Sigma _{L}$
, where
 $h_{\text {top}}(\Sigma _i) = h$
if
 $i\in \{1,\ldots ,k\}$
and
 $h_{\text {top}}(\Sigma _i)<h$
if
 $i\in \{k+1,\ldots ,L\}$
. Let
 $\beta _j$
be a sequence such that
 $\lim _{\beta _j\to \infty } ({1}/{\beta _j})\log (P(\beta _j A) - h )=\gamma $
and take a subsequence of this one such that
 $({1}/{\beta _{j_l}})\log (H_{\beta _{j_l}})$
converges for a function V. From (4),
 $\gamma $
is a real number and
 $$ \begin{align*} \gamma + V(\Sigma_i) = \max_{j\in\{1,\ldots,L\}}V(\Sigma_j)+a_{ij}\quad \text{for all } i\in\{1,\ldots,k\}.\end{align*} $$
Applying Proposition 3.9, we get that such a maximum is reached at some
 $j \in \{1,\ldots ,k\}$
and, therefore,
 $$ \begin{align*}\gamma + V(\Sigma_i) = \max_{j\in\{1,\ldots,k\}}V(\Sigma_j)+a_{ij}\quad\text{for all } i\in\{1,\ldots,k\},\end{align*} $$
which in Max-Plus formalism can be rewritten as
 $$ \begin{align} \gamma \otimes \begin{bmatrix} V(\Sigma_1) \\ \vdots \\ V(\Sigma_k) \end{bmatrix} = \begin{pmatrix} a_{11}&a_{12}&\dots&a_{1k}\\\vdots &\vdots &\vdots& \vdots \\ a_{k1}&a_{k2}&\dots&a_{kk}\end{pmatrix}\otimes \begin{bmatrix} V(\Sigma_1) \\ \vdots \\ V(\Sigma_k) \end{bmatrix}. \end{align} $$
Observe that the matrix
 $M=(a_{ij})$
does not depend of the subsequence which defines V and
 $\gamma $
, and all its entries are real numbers. Therefore, [Reference Baccelli, Cohen, Olsder and Quadrat1, Theorem 3.23, p. 111] yields that M has a unique eigenvalue. Hence, the function
 $\beta \to (1/\beta )\log (P(\beta A)-h)$
admits a unique accumulation point and, thus, converges.
Corollary 3.11. Under the hypotheses of Theorem A and supposing that
 $\Omega =\Sigma _1$
is an irreducible sub-shift of finite type,
 $$ \begin{align*}\gamma = \sup_{y\in \sigma^{-1}(\Omega)\setminus \Omega}A(y)+S(x,y)\end{align*} $$
for any point
 $x\in \Omega $
.
Remark 3.12. In the case
 $L=k$
, that is, all the irreducible components have maximal entropy, setting
 $\vec {V}:=(V(\Sigma _{1}),\ldots , V(\Sigma _{k}))$
,
 $\vec {V}$
is an eigenvector for the matrix M. Nevertheless, uniqueness does not necessarily hold. It is thus meaningful to ask for which eigenvectors can be selected.
The question still has meaning if
 $k<L$
and, in that case, the role of components with small entropy is even more unpredictable.
4 Proof of Theorem B
From now on, we consider
 $X=X_{2}$
the full 2-shift. Here, A is a non-positive potential of the form
 $$ \begin{align*}A|_{[01]}=b,\quad A|_{[10]}=d,\quad A(0^{\infty})=A(1^{\infty})=0,\quad A|_{[0^n1]} =a_n,\quad A|_{[1^n0]} =c_n.\end{align*} $$
It is Lipschitz continuous which yields that the series
 $\sum a_{n}$
and
 $\sum c_{n}$
converge. Furthermore, we remind that all numbers b, d,
 $a_{n}$
, and
 $c_{n}$
are negative, which yields that the Aubry set is
 $\{0^{\infty },1^{\infty }\}$
.
In that case, Theorem A holds and we set
 $$ \begin{align*}\gamma:=\lim_{\beta\to+\infty}\dfrac1\beta\log P(\beta A),\end{align*} $$
as periodic orbits are subshift of finite type with zero entropy.
We consider a family
 $(B_{\beta })$
of potentials satisfying
 $|B_\beta |_\infty < e^{\beta \delta },\,\delta <\gamma $
. In the study of selection of subaction, we consider also the hypothesis
 $\mathrm {Lip}(B_\beta ) \leq \beta c$
for some constant c and any
 $\beta $
.
We also remind that
 $H_{\phi }$
stands for the eigenfunction for the potential
 $\phi $
. In the case
 $\phi =\beta A$
, the normalization is
 $$ \begin{align} H_{\beta A}(0^{\infty})=1. \end{align} $$
The section runs as follows: we first give some technical results. Then, we prove the convergence for
 $(1/\beta )\log P(\beta A+B_{\beta })$
and
 $(1/\beta )\log H_{\beta A+B_{\beta }}$
. Finally, we prove the convergence for the measure.
4.1 Technical results
4.1.1 Accumulation points for
$({1}/{\beta })\log (H_{\beta A + B_{\beta }})$

We recall the double-inequality (3),
 $$ \begin{align*}P(\beta A)-|B_{\beta}|_{\infty}\le P(\beta A+B_{\beta})\le P(\beta A)+|B_{\beta}|_{\infty}. \end{align*} $$
Hence, our assumption
 $|B_\beta |_\infty < e^{\beta \delta }, \delta <\gamma $
immediately yields
 $$ \begin{align} \lim_{\beta \to\infty} \frac{1}{\beta}\log(P(\beta A + B_\beta)) = \gamma. \end{align} $$
The next lemma is a re-writing of the computation we did to get (6) and (7).
Lemma 4.1. Suppose
 $\mathrm {Lip}(B_\beta ) \leq \beta c$
for some constant c and any
 $\beta $
, and that
 ${|B_\beta |_\infty < e^{\beta \delta },\,\delta <\gamma} $
. Any accumulation point
 $\widetilde V$
for
 $({1}/{\beta })\log (H_{\beta A+B_{\beta }})$
is a calibrated subaction of A satisfying
 $$ \begin{align*}\gamma = A(10^{\infty}) + \tilde{V}(10^{\infty}) - \tilde{V}(0^{\infty})\end{align*} $$
and
 $$ \begin{align*}\gamma = A(01^{\infty}) + \tilde{V}(01^{\infty}) - \tilde{V}(1^{\infty}).\end{align*} $$
Proof. From Lemma 2.7, there exist convergent sub-sequences and any limit is a calibrated subaction for A. For any x,
 $$ \begin{align*}e^{P(\beta A+B_{\beta})}H_{\beta A+B_{\beta}}(x)=\sum_{y,\ \sigma(y)=x}e^{\beta A(y)+B_{\beta}(y)}H_{\beta A+B_{\beta}}(y).\end{align*} $$
In the special case
 $x=0^{\infty }$
,
 $$ \begin{align*} (e^{P(\beta A +B_\beta)} - e^{B_{\beta}(0^{\infty})})H_{\beta A+B_\beta}(0^{\infty}) = e^{\beta A(10^{\infty})+B_\beta(10^\infty)}H_{\beta A +B_\beta}(10^{\infty}).\end{align*} $$
From (13) and the hypothesis
 $|B_\beta |_\infty <e^{\beta \delta }$
,
 $$ \begin{align*}\lim_{\beta\to+\infty}\frac{1}{\beta}\log(e^{P(\beta A +B_\beta)} - e^{B_{\beta}(0^{\infty})}) = \gamma.\end{align*} $$
Therefore,
 $$ \begin{align*}\gamma+\widetilde V(0^{\infty})=A(10^{\infty})+\widetilde V(10^{\infty}).\end{align*} $$
The proof of
 $\gamma = A(01^{\infty }) + \tilde {V}(01^{\infty }) - \tilde {V}(1^{\infty })$
is similar.
4.1.2 A property for one
$2\times 2$
Max-Plus matrix

Proposition 4.2. Let
 $a,b,c,d$
be real numbers. Let M be the matrix
 $$ \begin{align*}M:=\left(\begin{array}{@{}cc@{}}a+b+d & c+d \\a+b & b+c+d\end{array}\right).\end{align*} $$
Then, its unique eigenvalue (for Max-Plus laws) is given by
 $$ \begin{align*}\unicode{x3bb} = \mathrm{max}\bigg\{a+b+d, b+c+d,\frac{a+b+c+d}{2}\bigg\}.\end{align*} $$
Furthermore, its eigenspace has dimension 1.
Proof. Again, [Reference Baccelli, Cohen, Olsder and Quadrat1, Theorem 3.23, p. 111] yields that M has a unique eigenvalue, say
 $\unicode{x3bb} $
, which is equal to
 $$ \begin{align*}\mathrm{max}\bigg\{a+b+d, b+c+d,\frac{a+b+c+d}{2}\bigg\}.\end{align*} $$
It thus remains to study the dimension of the eigenspace.
Equality
 $$ \begin{align*}\begin{pmatrix}a+b+d & c+d \\a+b & b+c+d\end{pmatrix} \otimes \begin{bmatrix} x\\y\end{bmatrix} = \unicode{x3bb} \otimes \begin{bmatrix}x\\y\end{bmatrix}\end{align*} $$
can be rewritten as
 $$ \begin{align}{} \mathrm{max}\{a+b+d+x, \,\,c+d+y\} &= \unicode{x3bb}+x, \end{align} $$
 $$ \begin{align}\mathrm{max}\{a+b+x,\,\,b+c+d+y\} &= \unicode{x3bb} + y. \end{align} $$
To prove that the eigenspace has dimension 1 means to prove that
 $y-x$
is constant. We consider three cases.
Case 1: If
 $\unicode{x3bb} =a+b+d$
. Equation (14a) yields
 $c+d+y\le a+b+d+x$
. Hence,
 $c+d+y< a+x$
and then
 $b+c+d+y < a+b+x$
.
Using this in (14b), we get
 $ a+b+x=\unicode{x3bb} +y$
and then, as
 $\unicode{x3bb} =a+b+d$
, we get
 $y=x-d$
.
Case 2: If
 $\unicode{x3bb} =b+c+d$
. The computation is the same than in the previous case, up to doing the exchanges
 $$ \begin{align*}a\leftrightarrow c,\ b\leftrightarrow d,\ x\leftrightarrow y.\end{align*} $$
This yields
 $x=y-b$
.
Case 3: If
 $\unicode{x3bb} =({a+b+c+d})/{2}$
. Equation (14a) yields
 $c+d+y\le ((a+b+ c+d)/2)+x$
, which means
 $$ \begin{align*}y\le \dfrac{a+b-c-d}2+x.\end{align*} $$
Conversely, (14b) yields
 $a+b+x\le (({a+b+c+d})/2)+y$
, which means
 $$ \begin{align*}y\ge \dfrac{a+b-c-d}2+x.\end{align*} $$
This finally yields
 $y=x+({a+b-c-d})/2$
.
4.2 Proof of the convergence for
${1}/{\beta }\cdot \log (H_{\beta A+B_{\beta }})$

Here, we prove that perturbation does not affect the selection of the calibrated subaction. Note that Theorem A holds in our case and we shall re-write (11). For that purpose, we have to compute the Mañé potential. For simplicity, we set
 $S_{i}(\cdot ):=S(i^{\infty },\cdot )$
with
 $i=0,1$
.
We let the reader check that the functions
 $S_{i}$
are constant on the 2-cylinders
 $[01]$
and
 $[10]$
with values:
 $$ \begin{align*}S_{0}(10)=b+\sum_{n\ge 2}a_{n},\ S_{0}(01)=\sum_{n\ge 2}a_{n},\end{align*} $$
 $$ \begin{align*}S_{{1}}(10)=\sum_{n\ge 2}c_{n},\ S_{1}(01)=d+\sum_{n\ge 2}c_{n}.\end{align*} $$
Equation (11) yields that any accumulation point V for
 $(1/\beta )\log H_{\beta A}$
satisfies the equation
 $$ \begin{align*}\gamma\otimes \begin{bmatrix}V(0^\infty) \\V(1^\infty)\end{bmatrix}= \left(\begin{array}{@{}cc@{}}A(10)+S_{0}(10) & A(10)+S_{1}(10) \\A(01)+S_{0}(01) & A(01)+S_{1}(01)\end{array}\right)\otimes \begin{bmatrix}V(0^\infty) \\V(1^\infty)\end{bmatrix},\end{align*} $$
which can be rewritten as
 $$ \begin{align} \gamma\otimes \begin{bmatrix}V(0^\infty) \\V(1^\infty)\end{bmatrix}= \left(\begin{array}{@{}cc@{}}d+b+\sum_{n\ge 2}a_n & d+\sum_{n\ge 2}c_n \\b+\sum_{n\ge 2}a_n & b+d+\sum_{n\ge 2}c_n\end{array}\right)\otimes \begin{bmatrix}V(0^\infty) \\V(1^\infty)\end{bmatrix}. \end{align} $$
Equation (15) can be rewritten as
 $$ \begin{align*}\gamma\otimes \begin{bmatrix} V(0^\infty) \\V(1^\infty)\end{bmatrix}=M\otimes \begin{bmatrix} V(0^\infty) \\V(1^\infty)\end{bmatrix},\end{align*} $$
where M satisfies Proposition 4.2, with
 $a:=\sum _{n\geq 2} a_{n}$
and
 $c:=\sum _{n\geq 2} c_{n}$
. This yields
 $$ \begin{align} \gamma=\mathrm{max}\bigg\{\kern-2pt\sum_{n\geq 2} a_{n}+b+d, \,\,\sum_{n\geq 2} c_{n}+b+d,\,\,\frac{\sum_{n\geq 2} a_{n}+\sum_{n\geq 2} c_{n}+b+d}{2}\bigg\}. \end{align} $$
Our condition
 $H_{\beta A}(0^{\infty })=1$
yields
 $V(0^{\infty })=0$
and, as the eigenspace has dimension 1 (see Proposition 4.2), this fixes the value for
 $V(1^{\infty })$
. As
 $\Omega = \{0^\infty ,1^\infty \}$
, applying Lemma 2.10, the calibrated subaction V is determined for any point
 $x\in \{0,1\}^{\mathbb {N}}$
.
Now, we consider the potential
 $\beta A +B_\beta $
. Lemma 4.1 shows that any accumulation point
 $\widetilde V$
for
 $(1/\beta )\log (H_{\beta A+B_{\beta }})$
is a calibrated subaction for A which satisfies
 $$ \begin{align*}\gamma + \tilde{V}(0^{\infty})= A(10^{\infty}) + \tilde{V}(10^{\infty})\end{align*} $$
and
 $$ \begin{align*}\gamma + \tilde{V}(1^{\infty})= A(01^{\infty}) + \tilde{V}(01^{\infty}).\end{align*} $$
By Lemma 2.10, this can be rewritten as
 $$ \begin{align*}\gamma + \tilde{V}(0^{\infty})= A(10^{\infty}) + \max_{i\in\{1,2\}} S_{i^\infty}(10)+\tilde{V}(i^{\infty})\end{align*} $$
and
 $$ \begin{align*}\gamma + \tilde{V}(1^{\infty})= A(01^{\infty}) + \max_{i\in\{1,2\}} S_{i^\infty}(01)+\tilde{V}(i^{\infty}).\end{align*} $$
Then, as in (15),
 $$ \begin{align*}\gamma\otimes \left(\begin{array}{@{}c@{}}\widetilde V(0^\infty) \\\widetilde V(1^\infty)\end{array}\right)= \left(\begin{array}{@{}cc@{}}\displaystyle d+b+\sum_{n\ge 2}a_n &\displaystyle d+\sum_{n\ge 2}c_n \\[12pt] \displaystyle b+\sum_{n\ge 2}a_n &\displaystyle b+d+\sum_{n\ge 2}c_n\end{array}\right)\otimes \left(\begin{array}{@{}c@{}}\widetilde V(0^\infty) \\\widetilde V(1^\infty)\end{array}\right).\end{align*} $$
Using the condition
 $H_{\beta A+B_{\beta }}(0^\infty )=1$
, we have
 $\widetilde V(0^{\infty })=0=V(0^{\infty })$
; therefore, Proposition 4.2 shows that
 $\widetilde V(1^{\infty })=V(1^{\infty })$
. Applying Lemma 2.10, we conclude that
 $\tilde {V} = V$
.
4.3 Proof of the convergence for
$\mu _{\beta A+B_{\beta }}$

4.3.1 The key condition to get convergence
Now, we present some auxiliary results for the study of selection of measure. For any cylinder
 $[\omega ] \subset X$
, let us denote by
 the function satisfying

Lemma 4.3. Let
 $A:X\to \mathbb {R}$
be any Lipschitz function such that
 $\mu _{\beta A}$
converges to a probability
 $\mu _{\infty }$
. Let
 $[\omega ]$
be a fixed cylinder and assume that for any
 $\widetilde \delta <\gamma $
, the one parameter family of functions
 satisfies
 $$ \begin{align*}\limsup_{\beta \to +\infty}\mu_{\beta A + C_\beta}([\omega]) \leq \mu_\infty([\omega])\quad \text{and}\quad \liminf_{\beta \to +\infty}\mu_{\beta A - C_\beta}([\omega]) \geq \mu_\infty([\omega]).\end{align*} $$
Then, for any
 $\widetilde \delta '<\gamma $
and any Lipschitz continuous functions
 $B_\beta $
satisfying
 $|B_\beta |_\infty < e^{\beta \widetilde \delta '}$
,
 $\lim _{\beta \to +\infty }\mu _{\beta A + B_\beta }([\omega ])=\mu _{\infty } ([\omega ])$
holds.
Proof. Let us assume
 $|B_\beta |_\infty <e^{\beta \widetilde \delta '}$
for some
 $\widetilde \delta '<\gamma $
holds. Let
 $\widetilde \delta $
be a real number in
 $(\widetilde \delta ',\gamma )$
, let us fix some cylinder
 $[\omega ]$
. We set
 . By definition of being equilibrium state, the next inequalities hold:
 $$ \begin{align*}\int \beta A + C_{\beta} \,d\mu_{\beta A + C_\beta} + h({\mu_{\beta A + C_\beta}}) \geq \int \beta A + C_{\beta} \,d\mu_{\beta A + B_\beta} + h({\mu_{\beta A + B_\beta}})\end{align*} $$
and
 $$ \begin{align*}\int \beta A + B_{\beta} \,d\mu_{\beta A + C_\beta} + h({\mu_{\beta A + C_\beta}}) \leq \int \beta A + B_{\beta} \,d\mu_{\beta A + B_\beta} + h({\mu_{\beta A + B_\beta}}).\end{align*} $$
This yields
 $$ \begin{align} \int C_\beta - B_\beta \, d\mu_{\beta A + C_\beta} \geq \int C_\beta - B_\beta \, d\mu_{\beta A + B_\beta}. \end{align} $$
Similarly, inequalities
 $$ \begin{align*}\int \beta A + B_{\beta} \,d\mu_{\beta A + B_\beta} + h({\mu_{\beta A + B_\beta}}) \geq \int \beta A + B_{\beta} \,d\mu_{\beta A - C_\beta} + h({\mu_{\beta A - C_\beta}}) \end{align*} $$
and
 $$ \begin{align*} \int \beta A - C_{\beta} \,d\mu_{\beta A + B_\beta} + h({\mu_{\beta A + B_\beta}})\leq \int \beta A - C_{\beta} \,d\mu_{\beta A - C_\beta} + h({\mu_{\beta A - C_\beta}})\end{align*} $$
yield
 $$ \begin{align} \int B_\beta +C_\beta \, d\mu_{\beta A + B_\beta} \geq \int B_\beta +C_\beta \, d\mu_{\beta A - C_\beta}. \end{align} $$
Then,

where we use in the last inequality that
 $\mu _{\beta A+B_{\beta }}$
and
 $\mu _{\beta A+C_{\beta }}$
are probability measures. Since
 $\widetilde \delta '<\widetilde \delta $
, letting
 $\beta \to +\infty $
yields
 $$ \begin{align*}\mu_{\infty}([\omega])\ge \limsup_{\beta\to+\infty}\mu_{\beta A+C_{\beta}}([\omega])\ge \limsup_{\beta\to+\infty}\mu_{\beta A+B_{\beta}}([\omega]).\end{align*} $$
Similarly, using (18), we also get
 $$ \begin{align*} \mu_{\beta A - C_\beta}([\omega])\leq \mu_{\beta A+B_{\beta}}([\omega])+ 2e^{\beta(\widetilde\delta'-\widetilde\delta)}\end{align*} $$
and so
 $$ \begin{align*}\mu_{\infty}([\omega])\le \liminf_{\beta\to+\infty}\mu_{\beta A-C_{\beta}}([\omega])\le \liminf_{\beta\to+\infty}\mu_{{ \beta A+B_{\beta}}}([\omega]).\\[-42pt]\end{align*} $$
Corollary 4.4. Let
 $A:X\to \mathbb {R}$
be any Lipschitz function. Assume that
 $\mu _{\beta A}$
converges to
 $\mu _{\infty }$
and that for any fixed
 $n\in \mathbb {N}$
,
 $\widetilde \delta <\gamma $
and any family of functions
 $C_\beta $
depending on n coordinates and satisfying
 $|C_\beta |_\infty \leq e^{\beta \widetilde \delta }$
,
 $\mu _{\beta A + C_\beta }\to \mu _{\infty }$
holds. Then, for any
 $\widetilde \delta '<\gamma $
and any Lipschitz functions
 $B_\beta $
satisfying
 $|B_\beta |_\infty < e^{\beta \widetilde \delta '}$
, we have
 $\mu _{\beta A + B_\beta }\to \mu _\infty $
.
Proof. The selection of measure is determined by the limits
 $$ \begin{align*}\lim_{\beta \to\infty} \mu_{\beta A +B_\beta}([\omega]),\quad [\omega]\,\text{ is a cylinder}.\end{align*} $$
For each fixed cylinder
 $[\omega ]$
, we can construct a function
 which depends of finite coordinates. By hypothesis,
 $$ \begin{align*}\lim_{\beta \to \infty} \mu_{\beta A + C_\beta}([\omega])=\lim_{\beta \to \infty} \mu_{\beta A - C_\beta}([\omega])=\mu_\infty([\omega]).\end{align*} $$
Then, from Lemma 4.3,
 $$ \begin{align*}\lim_{\beta \to \infty} \mu_{\beta A + B_\beta}([\omega]) =\mu_\infty([\omega]).\\[-42pt]\end{align*} $$
4.3.2 Selection of maximizing measure
Now, we prove the convergence of the measures
 $\mu _{\beta A +B_\beta }$
and
 $\mu _{\beta A}$
, as stated in Theorem B. We will present explicitly the limit measure.
By Lemma 2.2, any accumulation point for
 $\mu _{\beta A+B_{\beta }}$
is A-maximizing and, hence, of the form
 $s\delta _{0^\infty } + (1-s) \delta _{1^\infty }$
, with
 $s\in [0,1]$
. Note that it is sufficient to get that
 $\mu _{\beta A+B_\beta }([0])$
and
 $\mu _{\beta A+B_\beta }([1])$
converge to determine s. As
 $\mu _{\beta A+B_\beta }([1]) = 1-\mu _{\beta A+B_\beta }([0])$
, it is thus sufficient to get that
 $\mu _{\beta A+B_\beta }([0])$
converges. Furthermore, Lemma 4.3 yields that the convergence for
 $\mu _{\beta A+B_\beta }([0])$
follows from the convergence of
 with
 $|C_{\beta }|$
going faster to 0 than
 $e^{\beta \gamma }$
. Therefore, we can suppose that
 $B_\beta $
only depends on the first coordinate and satisfies
 $$ \begin{align*}B_\beta(0)=a_\beta \quad\text{and}\quad B_\beta(1) = 0,\end{align*} $$
with
 $|a_\beta |\leq e^{\beta \delta }$
,
 $\delta <\gamma $
.
Let us set
 $$ \begin{align*}S_{0}(\beta) = \frac{ 1+\sum_{j=1}^{\infty}(j+1)e^{\beta(a_{2}+\cdots+a_{1+j})+ja_\beta-jP(\beta A+B_\beta)}}{1+\sum_{j=1}^{\infty}e^{\beta(a_{2}+\cdots+a_{1+j})+ja_\beta-jP(\beta A+B_\beta)}},\end{align*} $$
 $$ \begin{align*}S_{1}(\beta) = \frac{1+\sum_{j=1}^{\infty}(j+1)e^{\beta(c_{2}+\cdots+c_{1+j})-jP(\beta A+B_\beta)}}{ 1+\sum_{j=1}^{\infty}e^{\beta(c_{2}+\cdots+c_{1+j})-jP(\beta A+B_\beta)}}. \end{align*} $$
The potential
 $\beta A +B_\beta $
does not satisfy (2) because it can be positive in a neighborhood of
 $0^{\infty }$
, while it is equal to zero in
 $1^{\infty }$
, but the same proof of [Reference Baraviera, Lopes and Mengue4, Proposition 6] can be applied to conclude that
 $$ \begin{align*}\mu_{\beta A+B_\beta}([0]) = \frac{S_0(\beta)}{S_0(\beta) + S_1(\beta)} \quad\text{and}\quad \mu_{\beta A+B_\beta}([1]) = \frac{S_1(\beta)}{S_0(\beta) + S_1(\beta)}.\end{align*} $$
In a first step, we prove that the limit for
 ${S_0(\beta )}/{S_1(\beta )}={\mu _{\beta A+B_\beta }([0])}/{\mu _{\beta A+B_\beta }([1])}$
does not depend on
 $a_\beta $
. Second, we prove that such a limit exists. For that purpose, we consider a series of claims. From now on in this section, the notation
 $f(\beta )\sim g(\beta )$
means
 $\lim _{\beta \to +\infty } ({f(\beta )}/{g(\beta )}) = 1.$
Clearly, if
 $S_0(\beta )\sim F(\beta )$
and
 $S_1(\beta ) \sim G(\beta )$
, then
 $\lim _{\beta \to +\infty } ({S_0(\beta )}/{S_1(\beta )}) = \lim _{\beta \to +\infty } ({F(\beta )}/{G(\beta )}).$
The next lemma presents the basic properties of
 $\sim $
which will be used.
Lemma 4.5. For any positive functions
 $f, g$
:
-
(1) if
$\lim _{\beta \to +\infty } f(\beta ) =0$
, then
$(1+f(\beta )+g(\beta ))\sim (1+g(\beta ))$
; -
(2) if
$\lim _{\beta \to +\infty } f(\beta ) =1$
, then
$(1+f(\beta )\cdot g(\beta )) \sim (1+g(\beta ))$
; -
(3) if
$\lim _{\beta \to +\infty } f(\beta ) =1$
and h is a function satisfying
$ (1+g(\beta )) \leq 1+h(\beta ) \leq 1+f(\beta )\cdot g(\beta )$
, then
$(1+h(\beta ))\sim (1+g(\beta ))$
; -
(4) if
$f(\beta ) \sim {f_0}(\beta ) $
, then
$(1+f(\beta )g(\beta ))\sim (1+{f_0}(\beta )g(\beta ))$
.


Proof. The proof of item (1) follows from
 $$ \begin{align*}\lim_{\beta \to+\infty} \frac{1+f(\beta)+g(\beta)}{1+g(\beta)} = 1+\lim_{\beta \to+\infty} \frac{f(\beta)}{1+g(\beta)}=1,\end{align*} $$
because
 $f(\beta )\to 0$
and g is positive.
The proof of item (2) follows from
 $$ \begin{align*}\lim_{\beta \to+\infty} \frac{1+f(\beta)\cdot g(\beta)}{1+g(\beta)} = 1 + \lim_{\beta \to+\infty} \frac{(f(\beta)-1)\cdot g(\beta)}{1+g(\beta)} = 1,\end{align*} $$
because
 $(f(\beta ) -1) \to 0 $
and
 $0<{g(\beta )}/({1+g(\beta )})<1.$
The proof of item (3) is a consequence of item (2). Indeed,
 $$ \begin{align*}1 = \frac{1+g(\beta)}{1+g(\beta)} \leq \frac{1+h(\beta)}{1+g(\beta)} \leq \frac{1+f(\beta)g(\beta)}{1+g(\beta)}\end{align*} $$
and the right-hand side function converges to 1 (because of item (2)).
The proof of item (4) is again a consequence of item (2). We have
 $$ \begin{align*}1+f(\beta)g(\beta) = 1 + \frac{f(\beta)}{{f_0}(\beta)}{f_0}(\beta)g(\beta) \sim 1 + {f_0}(\beta)g(\beta)\end{align*} $$
because, by hypothesis,
 ${f(\beta )}/{{f_0}(\beta )}\to 1$
.
Claim 4.6. We have
 $$ \begin{align} \lim_{\beta \to +\infty} \sum_{j<\beta} (j+1)e^{\beta(a_{2}+\cdots+a_{1+j})+ja_\beta-jP(\beta A+B_\beta)}=0. \end{align} $$
Proof of the claim
Note that
 $P(\beta A+B_\beta )\geq P(\beta A)-e^{\beta \delta }>0$
holds for
 $\beta $
large enough. Hence,
 $$ \begin{align*}0\leq \sum_{j<\beta}(j+1)e^{\beta(a_{2}+\cdots+a_{1+j})+ja_\beta-jP(\beta A+B_\beta)}\leq (\beta+1)^2 e^{\beta\cdot a_{2} +\beta \cdot |a_\beta|}.\end{align*} $$
As
 $a_\beta \to 0$
and
 $a_2<0$
, we conclude (19).
Remark 4.7. We emphasize that this is the unique place where we assume
 $a_{2}<0$
and
 $c_{2}<0$
. Except here, assumptions
 $\sum a_{n}\le 0$
,
 $\sum c_{n}\le 0$
,
 $b+d<0$
and the fact that the Aubry set is
 $\{0^{\infty },1^{\infty }\}$
are sufficient.
It follows from Claim 4.6 and item (1) of Lemma 4.5 that
 $$ \begin{align} S_0(\beta) \sim \frac{ 1+\sum_{j\geq \beta}(j+1)e^{\beta(a_{2}+\cdots+a_{1+j})+ja_\beta-jP(\beta A+B_\beta)}}{1+\sum_{j\geq \beta}e^{\beta(a_{2}+\cdots+a_{1+j})+ja_\beta-jP(\beta A+B_\beta)}}. \end{align} $$
In the following, a stands for
 $\sum a_{n}$
and c stands for
 $\sum c_{n}$
.
Claim 4.8. There exists
 $C>0$
such that for every
 $j\ge 1$
,
 $$ \begin{align*}c\le c_2+\cdots+c_{1+j} \le c+ C\theta^{j}\quad \text{and}\quad a\le a_2+\cdots+a_{1+j} \le a+C\theta^{j}.\end{align*} $$
Proof of the claim
Indeed, as A is Lipschitz, there exists
 $C_0>0$
such that, for
 $n\geq 2$
,
 $$ \begin{align*}-c_n = -A(1^{n}0^\infty) \leq -A(1^{\infty}) + C_0\cdot d(1^n0^\infty,1^{\infty}) = C_0\theta^n.\end{align*} $$
Then, for each
 $j \geq \beta $
,
 $$ \begin{align*}c_2+\cdots+c_{1+j} = \sum_{i=2}^{\infty}c_{i}- \sum_{i=j+2}^{\infty}c_{i}\leq \sum_{i=2}^{\infty} c_{i}+\sum_{i=j+2}^{\infty}C_0\theta^{i}\leq \sum_{i=2}^{\infty}c_{i} + \frac{C_0\theta^{j+2}}{1-\theta}. \end{align*} $$
A similar computation can be used for a terms.
It follows from Claim 4.8 that
 $$ \begin{align*}1+ e^{\beta a}\sum_{j\geq \beta}e^{-jP(\beta A+B_\beta)}&\leq 1+\sum_{j\geq \beta}e^{\beta(a_{2}+\cdots+a_{1+j})-jP(\beta A+B_\beta)}\\ &\leq 1+ e^{\beta C\theta^{\beta}}\cdot e^{\beta a}\sum_{j\geq \beta}e^{-jP(\beta A+B_\beta)}.\end{align*} $$
As
 $\lim _{\beta \to +\infty }e^{\beta C\theta ^{\beta }}= 1$
, applying item (3) of Lemma 4.5,
 $$ \begin{align*} 1+\sum_{j\geq \beta}e^{\beta(a_{2}+\cdots+a_{1+j})-jP(\beta A+B_\beta)} \sim 1+ e^{\beta a}\sum_{j\geq \beta}e^{-jP(\beta A+B_\beta)}.\end{align*} $$
With a similar computation, also
 $$ \begin{align*} 1+\sum_{j\geq \beta}(j+1)e^{\beta(a_{2}+\cdots+a_{1+j})+ja_\beta-jP(\beta A+B_\beta)} \sim 1+e^{\beta a} \sum_{j\geq \beta}(j+1)e^{ja_\beta-jP(\beta A+B_\beta)}.\end{align*} $$
Applying this result in (20),
 $$ \begin{align} S_0(\beta) \sim \frac{ 1+e^{\beta a}\sum_{j\geq \beta}(j+1)e^{ja_\beta-jP(\beta A+B_\beta)}}{1+e^{\beta a}\sum_{j\geq \beta}e^{ja_\beta-jP(\beta A+B_\beta)}}. \end{align} $$
Let us consider now the next step. From simple computations, we get, for any
 $z>0$
and
 $k \in \mathbb {N}$
,
 $$ \begin{align*}\sum_{j=k}^{\infty} e^{-jz} = \dfrac{e^{-kz}}{1- e^{-z}} \quad \mathrm{and} \quad\sum_{j=k}^{\infty} (j+1) e^{-jz} = \frac{e^{-kz}}{1-e^{-z}}\bigg(k+\frac1{1-e^{-z}}\bigg) .\end{align*} $$
Claim 4.9. The following holds:
 $$ \begin{align*}\sum_{j\geq \beta}e^{ja_\beta-jP(\beta A+B_\beta)} \sim \frac{1}{P(\beta A)}\quad and \quad \sum_{j\geq \beta}(j+1)e^{ja_\beta-jP(\beta A+B_\beta)} \sim \frac{1}{(P(\beta A))^2} .\end{align*} $$
Proof of the claim
As
 $\lim _{x\to +\infty }({x}/({1-e^{-x}}))=1$
, if z is a function such that
 $z(\beta )\downarrow 0$
and
 $\beta \cdot z(\beta ) \to 0$
,
 $$ \begin{align*} \sum_{j\geq \beta} e^{-jz(\beta)} = \dfrac{e^{-\beta z(\beta)}}{1- e^{-z(\beta)}} \sim \frac{1}{z(\beta)}.\end{align*} $$
Furthermore,
 $$ \begin{align*}&\sum_{j\geq \beta} (j+1) e^{-jz(\beta)} \\&\quad= \frac{e^{-\beta z(\beta)}}{1-e^{-z(\beta)}}\bigg(\beta+\frac1{1-e^{-z(\beta)}}\bigg) \sim \frac{\beta}{z(\beta)}+\frac{1}{(z(\beta))^2} \sim \frac{\beta z(\beta)+1}{(z(\beta))^2}\sim \frac{1}{(z(\beta))^2}.\end{align*} $$
Finally, we take
 $z(\beta ) = -a_\beta +P(\beta A+B_\beta )$
. Observe that
 $z(\beta ) \sim P(\beta A)$
and
 $\beta \cdot P(\beta A) \to 0$
because
 $P(\beta A)$
and
 $a_{\beta }$
converge exponentially fast to zero, respectively at a rate
 $e^{\beta \cdot\gamma }$
and
 $e^{\beta \cdot\delta }$
with
 $\gamma $
as given in (16) and
 $\delta <\gamma $
.
Claim 4.9, item (4) of Lemma 4.5, and (21) together yield
 $$ \begin{align*}S_0(\beta) \sim \frac{ 1+e^{\beta a}/{(P(\beta A))^2}}{1+e^{\beta a}/{P(\beta A)}}.\end{align*} $$
Similarly,
 $$ \begin{align*}S_1(\beta) \sim \frac{ 1+e^{\beta c}/{(P(\beta A))^2}}{1+e^{\beta c}/{P(\beta A)}}\end{align*} $$
and, therefore,
 $$ \begin{align} \frac{S_{0}(\beta)}{S_{1}(\beta)}\sim \dfrac{(P(\beta A))^2+e^{\beta a}}{P(\beta A)+e^{\beta a}}\dfrac{P(\beta A)+e^{\beta c}}{(P(\beta A))^2+e^{\beta c}}. \end{align} $$
Observe that the right-hand side does not depend of
 $B_\beta $
. Then, the limit of the ratio
 ${\mu _{\beta A +B_\beta }([0])}/{\mu _{\beta A+B_\beta }([1])}={S_{0}(\beta )}/{S_{1}(\beta )}$
does not depend of
 $B_\beta $
. This finally shows that
 $\mu _{\beta A+B_{\beta }}$
converges to the same limit than
 $\mu _{\beta A}$
, if it converges.
The next proposition shows that
 $\mu _{\beta A+B_\beta }$
actually converges and explicitly gives the limit.
Proposition 4.10. Under above hypothesis, concerning
 $B_\beta $
and A:
-
(1) if
$a=c$
, then
$\mu _{\beta A +B_\beta } \to ({\delta _{0^{\infty }}+\delta _{1^{\infty }}})/{2}$
; -
(2) if
$a>c$
and
$a+b+d<c$
, then
$\mu _{\beta A +B_\beta } \to ({\delta _{0^{\infty }}+\delta _{1^{\infty }}})/{2}$
; -
(3) if
$a>c$
and
$a+b+d>c$
, then
$\mu _{\beta A +B_\beta } \to \delta _{0^{\infty }}$
; -
(4) if
$a>c$
and
$a+b+d=c$
, then
$$ \begin{align*} \mu _{\beta A +B_\beta } \to (({10+2\sqrt {5}})/{20})\delta _{0^{\infty }}+(({10-2\sqrt {5}})/{20}) \delta _{1^{\infty }}. \end{align*} $$


We get symmetric results in the case where
 $c>a$
.
Proof. We will consider (22). Furthermore, from (16),
 $$ \begin{align*}\gamma=\mathrm{max}\bigg\{a+b+d, \,\,c+b+d,\,\,\frac{a+c+b+d}{2}\bigg\}.\end{align*} $$
The proof of item (1) is a consequence of (22). In the case where
 $a=c$
, the right-hand side term in (22) equals 1, which yields that
 ${S_{0}(\beta )}/{S_{1}(\beta )}$
goes to 1 as
 $\beta \to +\infty $
.
For the proof of other cases, we consider
 $l(\beta ) := P(\beta A)/e^{\beta \gamma }$
. Then,
 $P(\beta A) = l(\beta ) e^{\beta \gamma }$
and
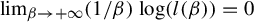 $\lim _{\beta \to +\infty }({1}/{\beta })\log (l(\beta )) =0$
. It follows that for any constant
 $\epsilon>0$
, we have
 $e^{-\beta \epsilon } <l(\beta ) <e^{\beta \epsilon }$
for sufficiently large
 $\beta $
. With such notation, from (22),
 $$ \begin{align*}S_0(\beta)/S_1(\beta)\sim \dfrac{l^2(\beta)e^{2\beta \gamma}+e^{\beta a}}{l(\beta)e^{\beta\gamma}+e^{\beta a}}\dfrac{l(\beta)e^{\beta\gamma}+e^{\beta c}}{l^2(\beta)e^{2\beta \gamma}+e^{\beta c}}.\end{align*} $$
For the proof of item (2), if
 $a>c$
and
 $a+b+d<c$
, then
 $({a+b+d+c})/{2}> a+b+d$
and so
 $\gamma = ({a+b+d+c})/{2}$
. We have also
 $$ \begin{align*}a>c\Rightarrow a>c+b+d \Rightarrow \frac{a}{2} > \frac{c+b+d}{2} \Rightarrow a > \frac{a}{2}+\frac{c+b+d}{2} \Rightarrow a>\gamma\end{align*} $$
and similarly,
 $$ \begin{align*}c>a+ b+d \Rightarrow c>\gamma.\end{align*} $$
As
 $a>\gamma $
and
 $c>\gamma $
, it follows that
 $$ \begin{align*}S_0(\beta)/S_1(\beta)\sim \dfrac{l^2(\beta)e^{2\beta \gamma}+e^{\beta a}}{l(\beta)e^{\beta\gamma}+e^{\beta a}}\dfrac{l(\beta)e^{\beta\gamma}+e^{\beta c}}{l^2(\beta)e^{2\beta \gamma}+e^{\beta c}} \to 1\end{align*} $$
and then
 $\mu _{\beta A +B_\beta } \to ({\delta _{0^{\infty }}+\delta _{1^{\infty }}})/{2}$
.
For the proof of item (3), if
 $a+b+d>c$
, then
 $({a+b+d+c})/{2} < a+b+d$
and then
 $\gamma = a+b+d$
. It follows that
 $c<\gamma <a$
. Then, using any auxiliary number
 $\delta $
such that
 $c<\delta <\gamma $
and
 $2\gamma <\delta $
,
 $$ \begin{align*}S_0(\beta)/S_1(\beta)\kern1.3pt{\sim}\kern1.3pt \dfrac{l^2(\beta)e^{2\beta \gamma}+e^{\beta a}}{l(\beta)e^{\beta\gamma}+e^{\beta a}}\dfrac{l(\beta)e^{\beta\gamma}+e^{\beta c}}{l^2(\beta)e^{2\beta \gamma}+e^{\beta c}} \kern1.3pt{\sim}\kern1.3pt 1\cdot \frac{l(\beta)e^{\beta(\gamma-\delta)}+e^{\beta(c-\delta)}}{l^2(\beta)e^{\beta (2\gamma-\delta)}+e^{\beta (c-\delta)}} \kern1.3pt{\to}\kern1.3pt +\infty.\end{align*} $$
For the proof of item (4), as
 $a+b+d=c$
, we have
 $a+b+d = ({a+b+d+c})/{2}$
and then
 $\gamma =a+b+d = ({a+b+d+c})/{2}$
. In this case,
 $\gamma <a$
and
 $\gamma =c$
. Then, we have
 $$ \begin{align*}S_0(\beta)/S_1(\beta)\sim 1\cdot \dfrac{l(\beta)e^{\beta c}+e^{\beta c}}{l^2(\beta)e^{2\beta c}+e^{\beta c}} \sim \dfrac{l(\beta)+1}{l^2(\beta)e^{\beta c}+1} \sim l(\beta)+1. \end{align*} $$
It remains to study the limit for
 $l(\beta )$
. From [Reference Walters27, Corollary 3.5], we have (here, in the present paper,
 $b_j =b$
and
 $d_j=d$
for any j)
 $$ \begin{align*}e^{2P(\beta A)}=e^{\beta (b+d)}\bigg(1+\sum_{j\geq 1}e^{\beta(a_2+\cdots+a_{1+j})-jP(\beta A)}\bigg)\bigg(1+\sum_{j\geq 1}e^{\beta(c_2+\cdots+c_{1+j})-jP(\beta A)}\bigg) .\end{align*} $$
Applying similar computations as above (to get (22)),
 $$ \begin{align*} e^{2P(\beta A)}\sim e^{\beta (b+d)}\bigg(1+\frac{e^{\beta a}}{P(\beta A)}\bigg)\bigg(1+\frac{e^{\beta c}}{P(\beta A)}\bigg).\end{align*} $$
Then,
 $$ \begin{align*}e^{2P(\beta A)}\sim e^{\beta (b+d)} + \frac{e^{\beta(b+d+c)}}{P(\beta A)} + \frac{e^{\beta(b+d+a)}}{P(\beta A)} + \frac{e^{\beta(b+d+a+c)}}{(P(\beta A))^2}\end{align*} $$
and
 $$ \begin{align*}e^{2P(\beta A)}\sim e^{\beta (b+d)} + \frac{e^{\beta(b+d+c)}}{l(\beta)e^{\beta \gamma}} + \frac{e^{\beta(b+d+a)}}{l(\beta)e^{\beta \gamma}} + \frac{e^{\beta(b+d+a+c)}}{l^2(\beta)e^{2\beta\gamma}}.\end{align*} $$
As
 $e^{2P(\beta A)}\to 1$
and from the hypothesis of item (4), we have
 $\gamma = c = a+b+d = ({a+b+d+c})/{2}$
, so
 $$ \begin{align*}1\sim \frac{1}{l(\beta)} + \frac{1}{l^2(\beta)}.\end{align*} $$
As
 $l(\beta )$
is positive, we obtain
 $l(\beta ) \kern1.3pt{\to }\kern1.3pt ({1\kern1.3pt{+}\kern1.3pt\sqrt {5}})/{2}.$
Finally, we conclude that
 $S_0(\beta )/S_1(\beta )\kern1.3pt{\to} ({3+\sqrt {5}})/{2}$
. Consequently,
 $\mu _{\beta A}([0]) \to ({3+\sqrt {5}})/({5+\sqrt {5}}) = ({10+2\sqrt {5}})/{20}$
and, therefore,
 $\mu _{\beta A}([1]) \to {2}/({5+\sqrt {5}}) = ({10-2\sqrt {5}})/{20}$
.
Remark 4.11. It is noteworthy that knowing A close to
 $0^{\infty }$
and
 $1^{\infty }$
is not sufficient to determine the selection. This has been already pointed out in [Reference Baraviera, Lopes and Mengue4]. Indeed,
 $b+d$
plays a role to determine the limit.
However, we point ouy that in Cases 1 and 2 in Proposition,
 $\gamma $
is given by the length-2 cycle
 $0^{\infty }\to 1^{\infty }\to 0^{\infty }$
in the matrix M, and then
 $\mu _{\infty }$
is
 $\tfrac 12(\delta _{0^{\infty }}+\delta _{1^{\infty }})$
. In Case 3,
 $\gamma $
is given by the length-1 cycle
 $0^{\infty }\to 0^{\infty }$
and the limit measure is
 $\delta _{0^{\infty }}$
. Finally, in Case 4,
 $\gamma $
is given both by length-1 cycle
 $0^{\infty }\to 0^{\infty }$
and length-2 cycle
 $0^{\infty }\to 1^{\infty }\to 0^{\infty }$
, and the limit measure is an asymmetric combination of
 $\delta _{0^{\infty }}$
and
 $\delta _{1^{\infty }}$
.
In all these cases,
 $a\ge c$
and
 $\mu _{\infty }$
contains some positive part of
 $\delta _{0^{\infty }}$
. This confirms that flatness may also be a criteria for selection (see [Reference Leplaideur21]).
A Appendix. About the hypothesis in Theorem B
Consider a Lipschitz function
 $A:X \to \mathbb {R}$
satisfying
 $m(A) = 0$
and suppose there exists the limit
 $\gamma = \lim _{\beta \to +\infty }({1}/{\beta })\log (P(\beta A) - h)$
, where
 $h=\sup _{\mu \in \mathcal {M}_{\mathrm {max}}(A)}h_{\mu }(\sigma )$
. Considering the hypothesis in Theorem B concerning the perturbation, it is natural to ask what happens if
 $B_\beta $
converges to zero slower than
 $e^{\beta \gamma }$
. The next example presents a discussion in this way and we will show a change in the selection of subaction and measure. We assume, in this example, that the eigenfuntions
 $H_\beta $
are normalized by
 $H_\beta (0^{\infty })=1$
.
Example A.1. In this example, we suppose
 $X=\{0,1\}^{\mathbb {N}}$
and consider two numbers
 $\gamma $
and
 $\eta $
satisfying
 $\gamma <\eta <0$
. Let
 $A,B_\beta :\{0,1\}^{\mathbb {N}} \to \mathbb {R}$
be functions which are constant in each 2-cylinder and defined by
 $$ \begin{align*} A(0,1)=A(1,0)=\gamma,\,\ A(0,0) =A(1,1)=0 , \end{align*} $$
 $$ \begin{align*} B_\beta(0,0) = B_\beta(1,0) = B_\beta(0,1)=0 \quad \mathrm{and} \quad B_\beta(1,1) = \log (1+e^{\beta \eta}).\end{align*} $$
We claim that, as
 $\beta $
goes to
 $+\infty $
:
-
(1)
$({1}/{\beta })\log (P(\beta A)) \to \gamma $
; -
(2)
$({1}/{\beta })\log |B_{\beta }|_\infty = \eta $
(then,
$|B_\beta |_\infty $
seems
$e^{\beta \eta }$
with
$\eta>\gamma $
); -
(3)
$({1}/{\beta })\log (H_{\beta A})(1^\infty ) \to 0$
; -
(4)
$({1}/{\beta })\log (H_{\beta A+B_\beta })(1^\infty ) \to \eta -\gamma $
; -
(5)
$\mu _{\beta A} \to \tfrac 12(\delta _{0^\infty }+\delta _{1^\infty })$
; -
(6)
$\mu _{\beta A+B_{\beta }} \to \delta _{1^\infty }$
.


From items (1)–(6), clearly the perturbation
 $B_\beta $
converges to zero exponentially fast, but slower than
 $e^{\beta \gamma }$
, and it changes the results concerning selections of subaction and measure.
To show item (1), in this case, note that Theorem A holds. The matrix M in Proposition 4.2 is then equal to
 $$ \begin{align*}M=\left(\begin{array}{@{}cc@{}}2\gamma & \gamma \\\gamma & 2\gamma\end{array}\right),\end{align*} $$
and its unique eigenvalue for the Max-Plus formalism is
 $\gamma $
. As the entropy for
 $0^{\infty }$
and
 $1^{\infty }$
is zero, we get 1.
To show item (3), note that the eigenfunction associated to
 $\unicode{x3bb} _{\beta A}$
depends just on one coordinate and satisfies

Hence, as by convention
 $H_{\beta A}(0) =1$
,

with
 $\unicode{x3bb} _{\beta }=e^{P(\beta )}$
. Doing
 $(1/\beta )\log $
in this last equality and
 $\beta \to +\infty $
, we get
 $V(1^{\infty })=\lim _{\beta \to \infty }({1}/{\beta })\log (H_{\beta A}(1)) = 0$
.
To show item (5), as A is locally constant, we know that
 $\mu _{\beta A}$
converges (see [Reference Brémont8, Reference Leplaideur20]). Furthermore, symmetry yields
 $\mu _{\beta A} \to ({\delta _{0^{\infty }}+\delta _{1^{\infty }}})/{2}$
.
To show item (2), as
 $\log (1+x) = x[1+o(x)]$
, for x near to
 $0$
,
 $$ \begin{align*}\lim_{\beta\to\infty}\frac{1}{\beta}\log(|B_\beta|_\infty) = \eta.\end{align*} $$
To show item (4), the associated matrix for the Ruelle operator
 $L_{\beta A + B_\beta } $
is given by
 $$ \begin{align*}\left(\begin{array}{@{}cc@{}} 1 & e^{\beta \gamma}\\ e^{\beta \gamma} & 1+e^{\beta \eta}\end{array}\right) \end{align*} $$
with dominating eigenvalue
 $$ \begin{align} \tilde{\unicode{x3bb}}_\beta = 1+\frac{e^{\beta \eta} +\sqrt{ e^{2\beta \eta} + 4e^{2\beta \gamma}}}{2}. \end{align} $$
The associated main eigenfunction depends just on one coordinate and satisfies
 $$ \begin{align*}\tilde{\unicode{x3bb}}_\beta H_{\beta A + B_\beta} (0)=H_{\beta A + B_\beta} (0) + e^{\beta \gamma }H_{\beta A + B_\beta} (1).\end{align*} $$
Hence, using again that
 $H_{\beta A + B_\beta } (0)=1$
, by convention,
 $$ \begin{align} H_{\beta A+B_\beta}(1) = \frac{\tilde{\unicode{x3bb}}_\beta - 1}{e^{\beta \gamma}}= {\frac{e^{\beta \eta} +\sqrt{ e^{2\beta \eta} + 4e^{2\beta \gamma}}}{2e^{\beta \gamma}}}. \end{align} $$
It follows that
 $$ \begin{align*}\lim_{\beta\to\infty} \frac{1}{\beta}\log( H_{\beta A + B_\beta}(1) )= \lim_{\beta \to\infty}\frac{1}{\beta}\log \bigg(\frac{e^{\beta \eta} +\sqrt{ e^{2\beta \eta} + 4e^{2\beta \gamma}}}{2e^{\beta \gamma}}\bigg)=\eta-\gamma>0.\end{align*} $$
To show item (6), consider the normalized function
 $$ \begin{align*}\overline{\beta A + B_\beta}:= \beta A + B_\beta + \log(H_{\beta A+B_\beta}) - \log(H_{\beta A+B_{\beta}} \circ \sigma) - \log(\tilde{\unicode{x3bb}}_\beta).\end{align*} $$
The associated Ruelle operator is identified with the matrix
 $$ \begin{align*}\left( \begin{array}{@{}ccc@{}} \dfrac{1}{\tilde{\unicode{x3bb}}_\beta} & &\dfrac{e^{\beta \gamma}}{H_{\beta A+B_\beta}(1)\tilde{\unicode{x3bb}}_\beta} \\ \dfrac{e^{\beta \gamma}H_{\beta A+B_\beta}(1)}{\tilde{\unicode{x3bb}}_\beta} & &\dfrac{1+e^{\beta \eta}}{\tilde{\unicode{x3bb}}_\beta} \end{array}\right).\end{align*} $$
To study the selection of
 $\mu _\beta = \mu _{\beta A + B_\beta }$
, it is sufficient to study
 $p_0^\beta =\mu _\beta ([0])$
and
 $p_1^\beta = \mu _\beta ([1])$
. As
 $p_0^\beta $
and
 $p_1^\beta $
satisfy
 $$ \begin{align*} \left( \begin{array}{@{}ccc@{}} \dfrac{1}{\tilde{\unicode{x3bb}}_\beta} & &\dfrac{e^{\beta \gamma}}{H_{\beta A+B_\beta}(1)\tilde{\unicode{x3bb}}_\beta} \\ \dfrac{e^{\beta \gamma}H_{\beta A+B_\beta}(1)}{\tilde{\unicode{x3bb}}_\beta} & &\dfrac{1+e^{\beta \eta}}{\tilde{\unicode{x3bb}}_\beta} \end{array}\right) \begin{bmatrix} p_0^\beta \\ \\ p_1^\beta \end{bmatrix} = \begin{bmatrix} p_0^\beta \\ \\ p_1^\beta \end{bmatrix},\end{align*} $$
we have
 $$ \begin{align*}p_0^\beta e^{\beta \gamma}H_{\beta A+B_\beta}(1) + p_1^\beta (1+e^{\beta \eta}) = \tilde{\unicode{x3bb}}_\beta p_1^\beta\end{align*} $$
and so, using that
 $p_1^\beta = 1-p_0^\beta $
,
 $$ \begin{align*}p_0^\beta &= \frac{\tilde{\unicode{x3bb}}_\beta - 1-e^{\beta \eta}}{e^{\beta\gamma}H_{\beta A+B_\beta}(1)+\tilde{\unicode{x3bb}}_\beta - 1-e^{\beta\eta}}\stackrel{({A.2})}{=}\frac{\tilde{\unicode{x3bb}}_\beta - 1-e^{\beta \eta}}{2(\tilde{\unicode{x3bb}}_\beta - 1)-e^{\beta\eta}}\\&\stackrel{({A.1})}{=} \frac{({-e^{\beta \eta} +\sqrt{ e^{2\beta \eta} + 4e^{2\beta \gamma}}})/{2}}{\sqrt{ e^{2\beta \eta} + 4e^{2\beta \gamma}}}=\frac{1}{2}-\frac{e^{\beta \eta}}{2\sqrt{ e^{2\beta \eta} + 4e^{2\beta \gamma}}}.\end{align*} $$
As
 $\eta>\gamma $
, we conclude that
 $\lim _{\beta \to +\infty }p_0^\beta =\tfrac 12-\tfrac 12=0$
and so
 $$ \begin{align*}\lim_{\beta \to \infty}\mu_{\beta A + B_\beta} = \delta_{1^{\infty}}. \end{align*} $$
Remark A.2. It is possible to get similar conclusions as in the above example in the case where
 $B_\beta =B$
does not depend of
 $\beta $
and satisfies
 $$ \begin{align*} B(0,0) = B(1,0) = B(0,1)=0 \quad \mathrm{and} \quad B(1,1)>0. \end{align*} $$
Indeed, just write
 $B(1,1)= \log (1+e^{\eta })$
, where
 $\eta \in \mathbb {R}$
and replace
 $e^{\beta \eta }$
by
 $e^{\eta }$
in the above computations to get
 $\lim _{\beta \to \infty } ({1}/{\beta })\log ( H_{\beta A + B_\beta }(1) )=-\gamma>0$
and
 $\lim _{\beta \to \infty }{\mu _{\beta A + B} = \delta _{1^{\infty }}}.$
Acknowledgements
R.L. and J.M. thank THERMOGAMAS for grant no. ANR-24-CE40-3348. R.L. thanks SynDynAr for grant no. ANR-23-CE40-0024.


