1. Introduction
This Appellate Body decision arose from the complaint by Indonesia against the European Union's antidumping duties on fatty alcohols and their blends.Footnote 1 This case raised several interesting legal issues. The major issue addressed, and the one on which we will focus, has to do with treatment of transfers among affiliates. In this case, the Appellate Body elaborated on the scope of permissible adjustments under Article 2.4 of the Agreement on Interpretation of Article VI of the General Agreement on Tariffs and Trade 1994 (the ‘ADA’), focusing on the ‘mark-up’ allocated by an exporter to a related company as a difference affecting price comparability between the export price and the normal value. Indonesia claimed that the European Union (EU) acted inconsistently with Articles 2.3 and 2.4 of the ADA because the EU made an improper adjustment to the export price of an Indonesian producer for a factor that, according to Indonesia, did not affect price comparability. The question raised was whether a payment made to a company within the same corporate group can be a ‘difference which affects price comparability’ when the payment is substantively analogous to a transfer within a single corporation, which would not ordinarily be considered as such. In other words, will the ‘veil of incorporation’ be pierced in favor of the respondent in an anti-dumping investigation?
2. Background
On 13 August 2010, the EU authorities initiated an anti-dumping investigation of certain fatty alcohols and their blends originating in India, Indonesia, and Malaysia. Of course, the main focus in order to determine whether dumping existed, and the magnitude of any dumping margins, was on the comparison of ‘export price’ with ‘normal value’ on an ‘ex-factory’ basis. In the anti-dumping investigation as it related to Indonesia, the EU authorities made adjustments for what they considered differences in price comparability between the relevant export prices and normal values in accordance with Article 2(10) of the EU Basic Anti-Dumping Regulation (‘BADR’), which seems to implement Article 2(4) of the ADA.
One of the adjustments made by the EU related to payments by one of the Indonesian exporters, PT Musim Mas (PTMM) to Inter-Continental Oils & Fats Pte Ltd (Singapore) (ICOF-S). ICOF-S was a related trading company, ‘wholly controlled by shareholders which also control PTMM’.Footnote 2 PTMM allowed ICOF-S a mark-up for sales made by ICOF-S on behalf of PTMM to customers in the EU. The EU authorities treated the mark-up as a payment for a service on the export side of PTMM's business, for which there was no corresponding price component on the domestic side. The EU authorities thus treated this payment as a difference affecting price comparability for which a downward adjustment to the export price was warranted, increasing the dumping margin.
The condensed time-line of decision-making in this case was as follows.
• 11 May 2011: preliminary anti-dumping duty imposed by EU Council.Footnote 3
• 8 November 2011: definitive anti-dumping duty imposed by EU Council.Footnote 4
• 20 January 2012: PTMM filed an action in the European Union's General Court seeking annulment of the anti-dumping duty.
• 11 December 2012: The applicable definitive anti-dumping duty was amended to reflect recent jurisprudence of the European Court of Justice applying the ‘single economic entity’ (‘SEE’) doctrine. This amendment eliminated duty on one Indonesian producer (‘Ecogreen’) but maintained it on PTMM.
• 30 July 2012: WTO consultations requested.
• 25 June 2013: WTO Panel established.
• 25 June 2015: European General Court issued judgement, dismissing action for annulment of definitive anti-dumping duty, on the basis, inter alia, that PTMM and ICOF-S did not constitute a SEE.Footnote 5
• 26 October 2016: European Court of Justice issued judgement on appeal, upholding General Court dismissal of action for annulment.Footnote 6
• 16 December 2016: Panel Report issued, with ‘business confidential information’ redacted.
• 5 September 2017: Appellate Body Report issued.
3. Economic features
This section briefly describes some of the underlying economic features of the traded products subject to the antidumping measure, related policies, and the WTO dispute – all based on publicly available data.
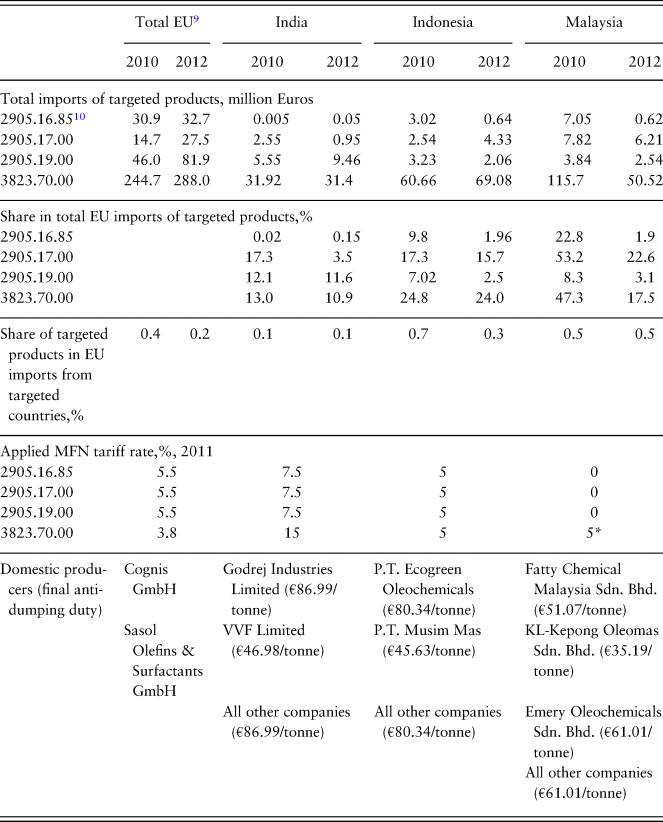
Fatty alcohols are intermediary products mainly used as inputs in the production of fatty alcohol sulphates, fatty alcohol ethoxylates, and fatty alcohol ether sulphates (so-called surfactants), which are used to produce detergents, household, cleaning, and personal care products.Footnote 7 Table 1 summarizes some of the key features of the EU import market of affected products, and policies that affect the imports of these products.
EU fatty alcohols import market associated with the antidumping case

Note:* The Malaysian tariff code has two tariff lines corresponding to CN code 3823.70.00, one with zero tariff rates, the other with 5%.
Petitioners in the EU's antidumping investigation were two domestic producers, Cognis GmbH and Sasol Olefins & Surfactants GmbH, both incorporated under German law with production sites in Germany, France, and Italy and representing more than 25% of total EU production of the affected products. The EU reported that it verified the surveyed information of three EU producers, one EU importer, five users in the EU, two exporting producers in India, two exporting producers in Indonesia and their related traders, and three exporting producers in Malaysia and their related traders.
The EU's applied MFN tariff on imports of affected products ranged from 3.8 to 5.5% in 2011. The definitive dumping margins ranged from 3.3 to 9.3%, with definitive antidumping duties taking the form of specific (per tonne) tariffs ranging from €35.19 (KL-Kepong Oleomas Sdn. Bhd.) to €86.99 (all Indian companies except VVF Limited) per tonne. Two Indonesian companies, PTMM and Ecogreen, faced €45.63 and €80.34 per tonne specific tariffs, respectively. Assuming a unit value of €1,200, these specific tariffs were equivalent to a 3.8 and 6.7% ad valorem tariff for PTMM and Ecogreen, respectively.Footnote 8 For PTMM, this in practice meant doubling of duties paid at the border, from 3.8% MFN rate to about 7.6% to include anti-dumping duties.
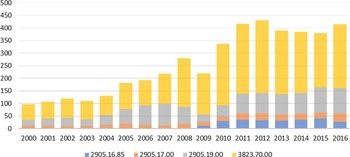
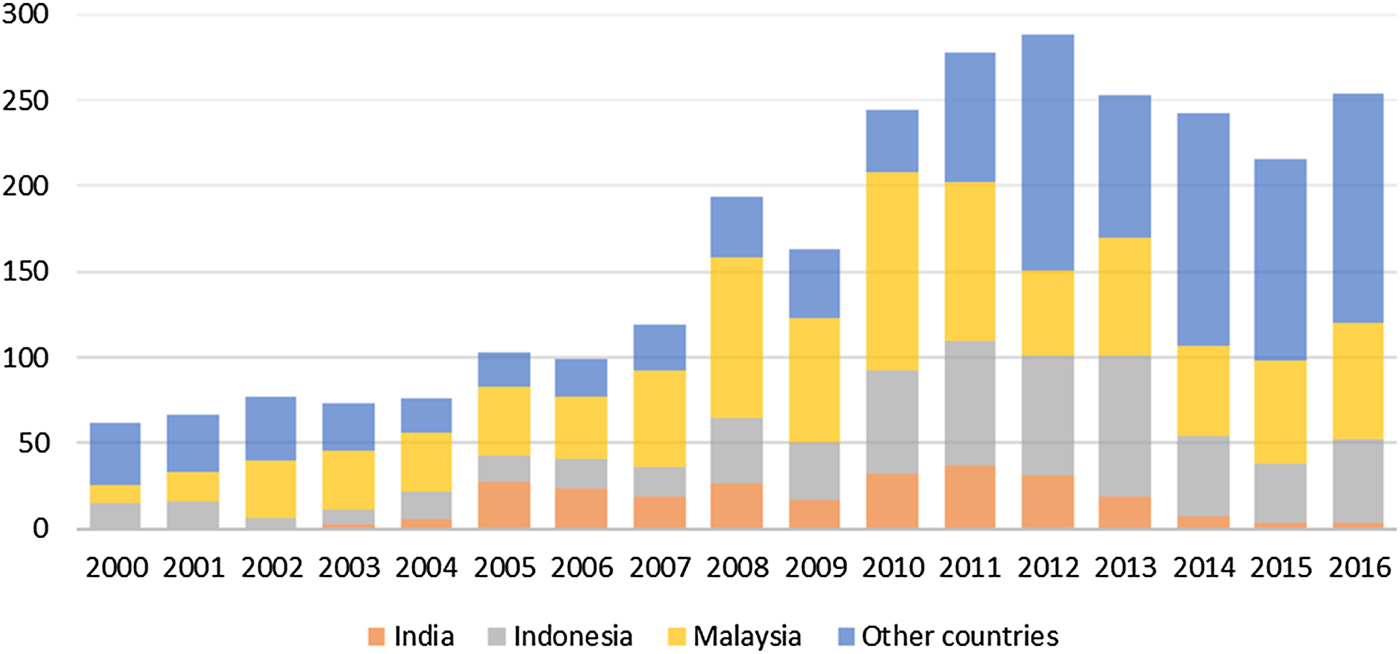
According to trade data that are publicly available at the tariff-line level, the extra-EU imports of the affected products have grown continuously since 2003 (apart from 2009 Great Trade Collapse) to reach €430 million in 2012, quadrupling from their 2003 level (Figure 1). Despite the share of targeted countries accounting for 72.5% in 2010 and 41.3% in 2012, they represented a relatively small share of EU imports from affected countries – about 0.4% in 2010, dropping to 0.2% in 2012. In the case of Indonesia, the share was relatively higher; 0.7% of EU imports from Indonesia were targeted by the antidumping investigation in 2010.
Value of EU imports by affected product (million euros)

Among four targeted products, fatty alcohols (CN 3823.70.00) accounted for the largest proportion of targeted imports, reaching 73% in 2010, followed by saturated monohydric acyclic alcohols (CN 2905.19.00) at about 13%. More specifically for Indonesia, the imports of fatty alcohols accounted for over 85% of imports of targeted products. Therefore, in the rest of the analysis we focus on the market of fatty alcohols classified under CN 3823.70.00.
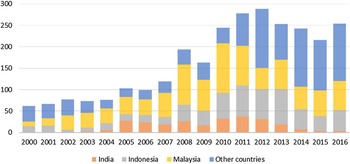
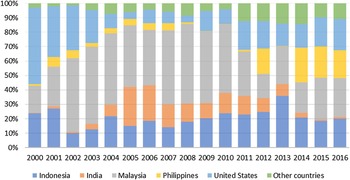
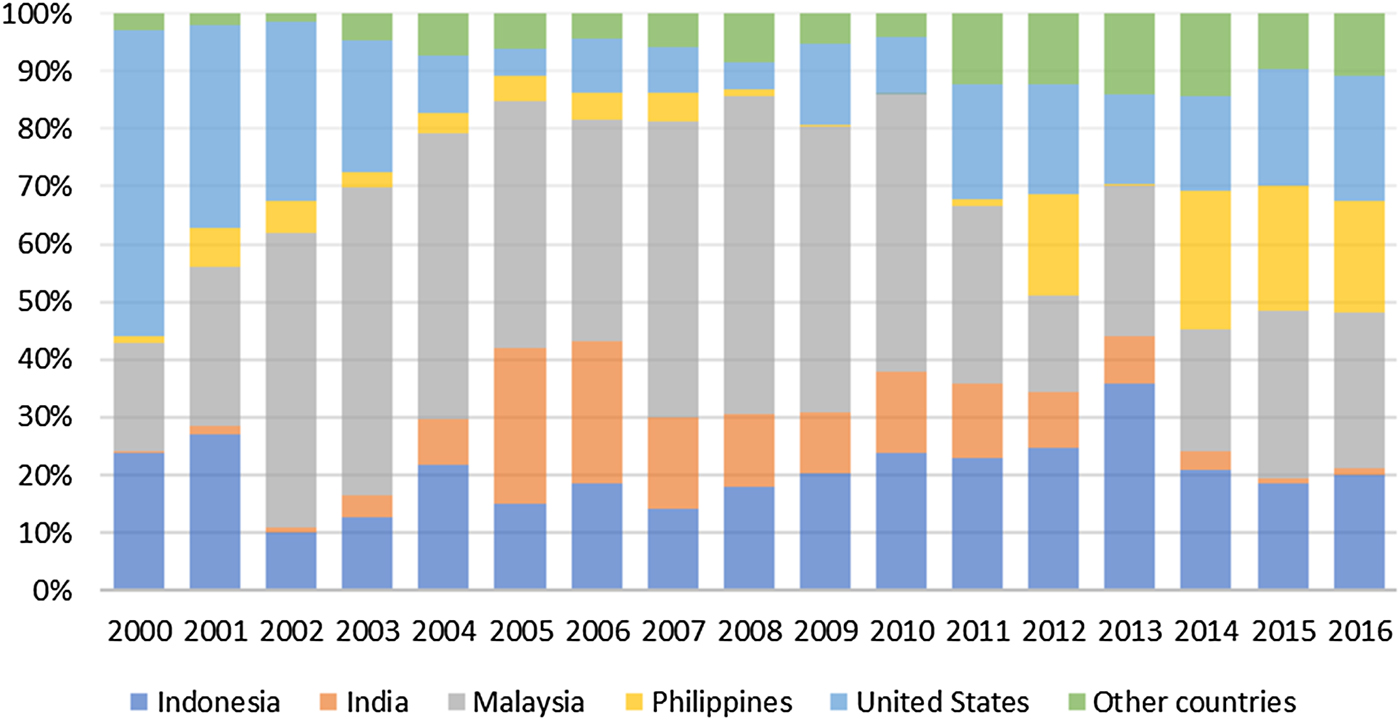
As Figure 2 illustrates, imports from Malaysia contributed greatly to the growth in imports of fatty alcohols up until 2010, accounting for close to half of all extra-EU imports of fatty alcohols in 2010, followed by imports from Indonesia at about 25% of the total value. Despite the imposition of the antidumping measure in 2011, imports from Indonesia continued to grow until 2013, peaking at €82 million or 33% of the import market. A similar pattern is observed in terms of the volume (Figure 3); the antidumping measure swiftly reshaped the import market for fatty alcohols – the share of the three targeted countries in the EU import market for these products was close to 90% in 2010, dropping to about 70% in 2011 and 50% in 2012. At the same time, the volume of fatty alcohols imported from Indonesia continued to rise, peaking at 755,197 tonnes in 2013. Not surprisingly, other major suppliers of the fatty alcohols – most notably United States and Philippines – stepped in to fill the void created by the antidumping measure.
Value of EU imports of fatty alcohols by country (million euros)
Import market shares of fatty alcohols by volume (tonnes) and country
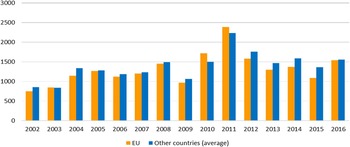
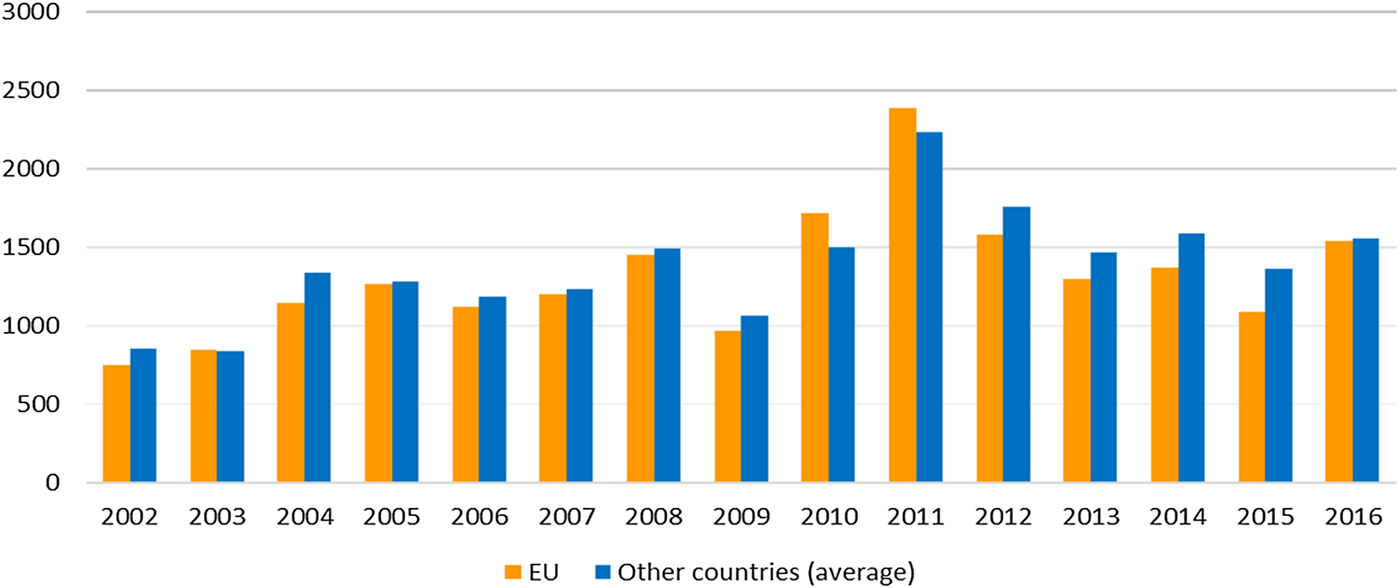
Turning our focus to Indonesia and to gain an insight into the pricing strategy for Indonesian products, we also compute unit values of Indonesian exports of fatty alcohols (at HS 6-digit level) to various destination markets, including the EU. One caveat is worth keeping in mind: we use aggregate level data, thus the unit value is computed as total value of exports by all exporting firms divided by total quantity of exports (in tonnes). Figure 4 shows the unit value of Indonesian exports to the EU and the average unit value for other destination markets. In all years, except 2010 and 2011, the unit value of Indonesian exports to the EU was on average 9% lower than that to other destination markets, suggesting that Indonesian exports might have been priced lower when exported to the EU market. In 2010–2011, the unit values are higher, which appears to coincide with the incorporation of ICOF-S as PTMM's subsidiary in 2009 and the practice of selling to the EU through a related company. We obtain a similar pattern of unit values by relying on imports data reported by Indonesia's trading partners (so-called ‘mirrored data’). Unit values of EU imports from Indonesia are 6–14% higher in 2010–2011 than those of other importing countries.
Unit value of Indonesian exports of fatty alcohols by destination (dollars per tonne)
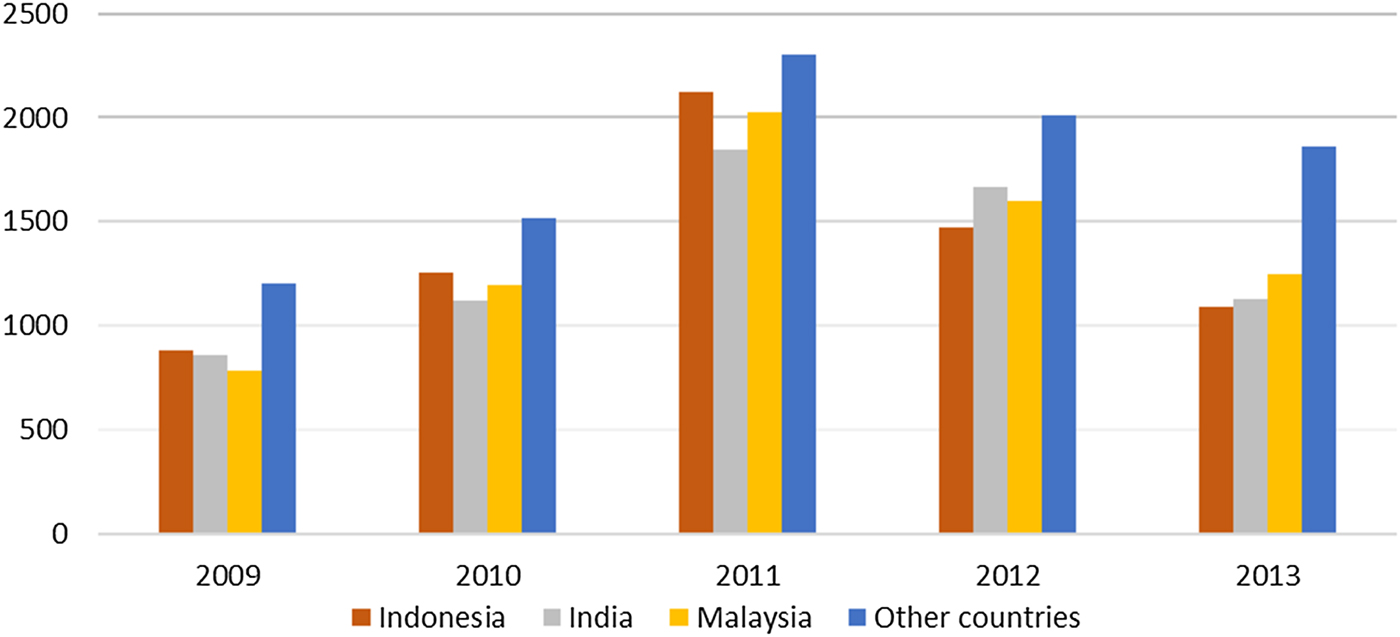
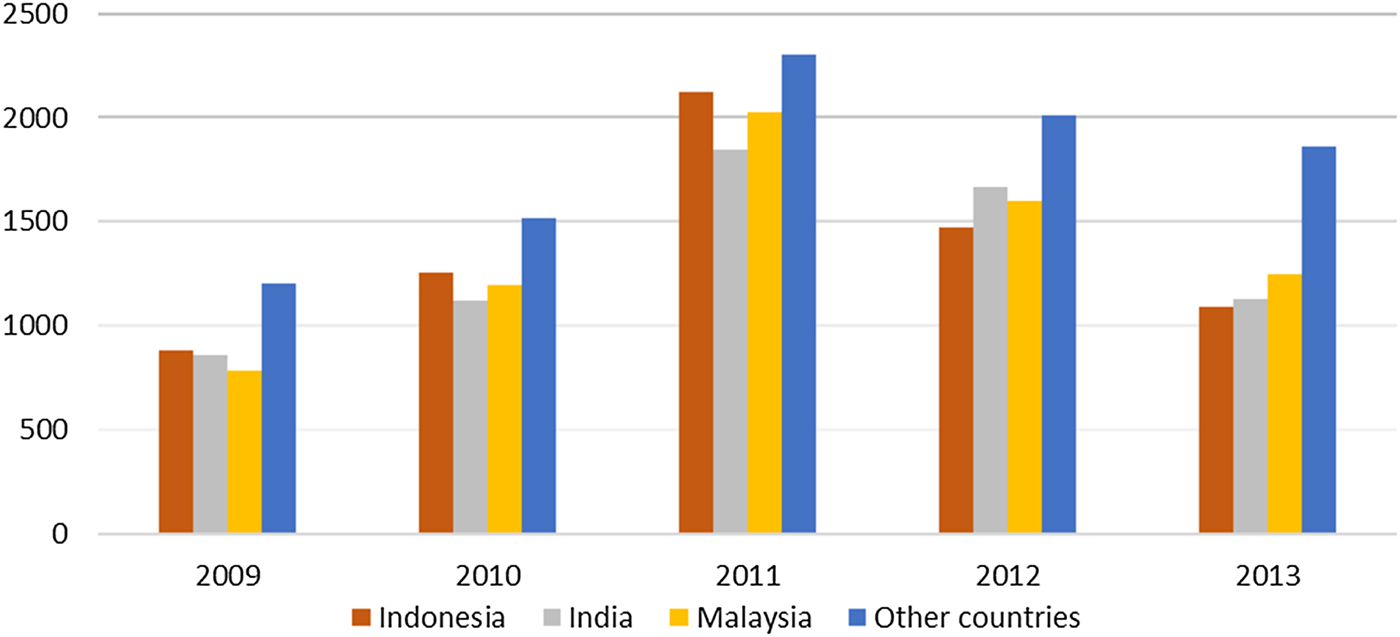
Lastly, even though Indonesian exports to the EU appear to be priced lower than those exported to other destination markets, on the EU market Indonesian products seem to be priced higher relative to products of other targeted countries, with this pattern reversing from 2012 onwards (Figure 5).
Unit value of EU imports of fatty alcohols by source country (euros)
In antidumping investigations, the dumping margin is computed as the difference between the normal value and export price. However, the EU claimed that the export price of PTMM is inflated by the mark-up paid to the related company in Singapore, ICOF-S. To make the normal value comparable to export price, a downward adjustment was made to the export price in the amount of selling, general, and administrative costs of the related company ICOF-S, which resulted in a higher dumping margin. PTMM claimed that such an adjustment is unwarranted since ICOF-S was set up as a related company and any transactions between the two are intra-firm transfers for profit shifting purposes.Footnote 11 Thus, the mark-up paid by PTMM to ICOF-S should be treated as an internal cost.
Let us consider a number of scenarios in which PTMM exports to the EU through a related company ICOF-S, and how the choice of the transfer price could affect the profits earned in both countries. For illustrative purposes, assume it costs PTMM $600 to make a tonne of fatty alcohols and $100 to market, and that it sells for $1,000 abroad (the export price). In the most basic case, PTMM exports to the EU directly without the help of a related company.

When PTMM sells through ICOF-S, a range of scenarios could play out. At one extreme, a transfer price of $600 would designate the consolidated profit of $300 totally to ICOF-S, as follows:

At the other extreme, a transfer price of $900 would designate the combined profit of $300 totally to PTMM, as follows:

One can think of another plausible scenario in which, in anticipation of the dumping investigation, PTMM could have chosen to increase its export price by selling to the EU through ICOF-S, and to offset the loss of the EU market share due to higher prices with corporate tax savings from shifting profits to ICOF-S. Of course, with information on pricing treated as confidential and redacted from the publicly available reports, it is impossible to conclude definitively.
4. Legal analysis
Anti-dumping law involves national procedures pursuant to national rules, and the national procedures and rules must comply with the international law of the WTO, including the ADA and the General Agreement on Tariffs and Trade 1994 (GATT). For the EU, the ‘national’ law is the BADR. Decisions under that regulation involve allocations of burdens of proof, as well as possible appeal to the EU judicial system.
The basic factual issue adjudicated in the EU courts – the existence and implications of PTMM and ICOF-S being parts of a single economic entity (‘SEE’) – was also argued in the WTO, in part because the internal EU law parallels the applicable WTO law. Before analyzing the WTO decision, we analyze the EU decisions. In effect, the lawyers for the Indonesian exporter lost this issue under EU law at the EU level, and sought to re-litigate it as an issue of WTO law. In effect, the WTO panel and Appellate Body accorded a wide margin of deference to the factual determination at the EU level.
4.1 EU decisions
In 2011, the EU authorities had rejected PTMM's claim, which was based on the SEE doctrine of EU competition law, to the effect that no adjustment should be made in relation to PTMM's payment of a mark-up to ICOF-S, based on the EU authorities’ observations that: (i) the mark-up covered export sales only; (ii) domestic sales, as well as some export sales to third countries, are invoiced directly by PTMM, in contrast to the mark-ups received by ICOF-S for export; and (iii) ICOF-S also sells products manufactured by unrelated producers. Based on these behavioral, as opposed to structural, features, PTMM and ICOF-S were not a SEE. The EU authorities also rejected PTMM's factual claim that ICOF-S was involved in PTMM's domestic sales in Indonesia and that, therefore, a corresponding adjustment should have been made to the normal value.Footnote 12
However, on 16 February 2012, the SEE doctrine was extended under EU law to the question of adjustments to the export price under Article 2(10) of the BADR,Footnote 13 in European Court of Justice (‘ECJ’) joined Cases C-191/09 P and C-200/09 P (the ‘Interpipe Judgment’).Footnote 14 Article 2(10)(i) refers to commissions, and states that
An adjustment shall be made for differences in commissions paid in respect of the sales under consideration. The term ‘commissions’ shall be understood to include the mark-up received by a trader of the product or the like product if the functions of such a trader are similar to those of an agent working on a commission basis.
The Interpipe Judgment involved facts and parties unrelated to the PTMM case. The application of the SEE doctrine to transactions between PTMM and ICOF-S would have had the result that intra-group transactions would have been ignored, just as intra-firm transfers were ignored, and so the mark-up paid by PTMM to ICOF-S would have been ignored, and treated as an internal cost. Note that the SEE doctrine ‘pierces the veil’ of separate incorporation of group members.
In the Interpipe Judgment, in order to determine whether the SEE doctrine should be applied to determination of export price, the ECJ examined the purpose of Article 2(10) of the BADR. It found as follows:
In that regard, it is apparent from the wording and broad scheme of Article 2(10) of that regulation that an adjustment to the export price or to the normal value may be made only to take account of differences in relation to factors which affect both prices, such as commissions, that is to say differences in commissions paid in respect of the sales under consideration, and which thus affect their comparability, in order to ensure that the comparison is made at the same level of trade. Therefore, the question of an export price adjustment, in the context of the application of Article 2(10) of the basic regulation, requires, first of all, an examination at the level of trade at which the export price was determined.Footnote 15
Thus,
If a producer exports his products to the European Union through the intermediary of a legally separate undertaking, but over which it holds economic control, the requirement of a finding reflecting the economic reality of the relations between that producer and that sales company militates more in favour of applying the ‘single economic entity’ concept when calculating the export price.Footnote 16
Note the ECJ's interpretative approach. It examines both the wording and ‘broad scheme’ – the text and the context – of the provision. The focus is on the level of trade, and on a search for ‘economic reality’, not on all differences in sale. The fact that a sale is made through an affiliated intermediary does not, by itself, affect the level of trade. Rather, the inference is that the authorities are to look through the intra-group sale in determining the level of trade, and therefore the need for adjustment.
After all, corporations are artificial persons, and in modern practice they are established for a variety of reasons, including transfer pricing to reduce taxes, to reduce tariffs, to launder money, or for other reasons. In order to counter transfer pricing in the anti-dumping field, Article 2.3 of the ADA, and Article 2(9) of the BADR, allow the national authorities to ignore transfer prices and use a constructed export price instead of the nominal price in determining export price. Implicit in Indonesia's argument is the idea that the mark-up to ICOF-S should be ignored, examining instead the first sale to an independent buyer. In other words, ICOF-S should be treated as part of the same SEE as PTMM.
Finally, in the Interpipe Judgment, the ECJ allocated a burden of production, if not also a burden of proof, to the national authorities to show the reason for the proposed adjustment:
where, as in the present case, the Council and the Commission consider that it is appropriate to apply a downward adjustment of the export price, on the ground that a sales company affiliated to a producer carries out functions comparable to those of an agent working on a commission basis, it is the responsibility of those institutions to adduce at the very least consistent evidence showing that that condition is fulfilled.Footnote 17
In Interpipe, the General Court had found that the Commission had not satisfied this burden, and the ECJ deferred to the General Court on the facts.
On the basis of this jurisprudence, PTMM argued that its sales to ICOF-S should be ignored, and that therefore no adjustment should be made under Article 2.10 of BADR in relation to the mark-up to ICOF-S, or as a replacement for that mark-up in the form of a calculated amount for profit and selling, general and administrative expense. However, in the EU revised anti-dumping order, revised to reflect the Interpipe decision, the EU authorities determined that the SEE doctrine did not apply to the relationship between PTMM and ICOF-S.Footnote 18 The EU authorities distinguished between the PTMM case and that of Ecogreen, another producer of fatty alcohols subject to the anti-dumping duty, on the bases of (i) a greater level of export sales by PTMM, (ii) the significance of ICOF-S activities on behalf of unrelated companies, and (iii) the existence of a contract regarding the mark-up. These are essentially the same behavioral issues on which the EU authorities relied prior to Interpipe.
One way of understanding these factors is that they are reasons not to pierce the veil of separate incorporation of ICOF-S, but to treat it as an independent entity, and a commission agent for Article 2.10 BADR (and ADA Article 2.4) purposes, considering the mark-up paid to it as indicative of a different level of trade and so a basis for adjustment.
WTO decisions
At the WTO, Indonesia appealed, inter alia, the Panel's finding that Indonesia had failed to demonstrate that the EU authorities acted inconsistently with Article 2.4 of the ADA by making an improper deduction for a factor that did not affect price comparability. Article 2.4 of the ADA requires ‘a fair comparison’ between export price and normal value, allowing ‘due allowances’ for ‘differences which affect price comparability’.
Indonesia argued at the Panel stage that the EU authorities improperly characterized the mark-up as a trading commission, rather than as a simple ‘internal’ allocation of funds between components of a SEE. Indonesia argued that PTMM and ICOF-S constituted a SEE even though they are formally separate firms, and, therefore, transfers to ICOF-S are comparable to, and should be treated as, intra-firm transfers, and ignored for purposes of making adjustments. In effect, Indonesia argued that this transfer of funds had no non-tax economic substance, and was motivated by tax considerations that cause corporate groups to engage in transfer pricing – artificial pricing – among members of the group.Footnote 19 On that basis, the mark-up could not affect price comparability and should not have been the subject of an adjustment.
Indonesia argued before the Panel that the EU authorities failed to assess whether PTMM and ICOF-S formed a SEE, contrary to an ‘implicit requirement’ of Article 2.4.Footnote 20 Note that Indonesia was making this argument in the WTO proceedings under WTO law, not as a matter of EU law. As the Appellate Body pointed out, the text of Article 2.4 does not contain the words ‘single economic entity’.Footnote 21 The Appellate Body approved the Panel's determination that the existence of a SEE does not mean that the payment of a mark-up between component parties can never affect price comparability under Article 2.4.Footnote 22
As the EU pointed out, ‘Indonesia's claim would mean that the export price of a SEE should be constructed in compliance with Article 2.3, rather than through an adjustment under Article 2.4, however the Panel request does not contain any independent or principal claims based on Article 2.3.’Footnote 23 One might understand Indonesia's argument as suggesting that Article 2.4 can be interpreted based on the principles of Article 2.3.
On the other hand, the EU argued at the panel stage that the existence of a SEE is irrelevant under Article 2.4.Footnote 24 The EU focused on the fact that its investigation showed ‘that a commission was paid by [PTMM] to [ICOF-S] and that it was paid only in relation to export sales. The EU authorities therefore had a sufficient evidentiary basis to adjust the export price’.Footnote 25
In the EU proceedings, PTMM argued that the contract between PTMM and ICOF-S was simply intended to comply with OECD guidelines on transfer pricing for tax purposes,Footnote 26 but the EU authorities found that the terms of the agreement suggested that it was not limited to that function.Footnote 27 In part because the OECD guidelines call for transfer prices to reflect economic reality, the Panel concluded that ‘the characterisation of the Sale and Purchase Agreement between PT Musim Mas and ICOF-S as a transfer pricing agreement does not negate the understanding that it reflects payments for a service provided by ICOF-S to PT Musim Mas and the associated transfer of title to ICOF-S for the products under consideration’.
Note the implication here. If, for tax purposes, intra-group pricing and other sales arrangements must reflect economic reality, constructing an artificial separateness, then for trade purposes the separateness of the contracting entities will, or at least can, be respected. PTMM cannot argue, as it did here, that it is separate from ICOF-S for tax purposes, but not for anti-dumping price calculation purposes. Thus, the EU authorities took the purported economic substance of the agreement for tax purposes to effectively estop PTMM from arguing that this transaction lacked economic substance for trade purposes.
The Panel accepted that the EU authorities had sufficient evidentiary basis for their rejection of PTMM's argument that ICOF-S performed the same functions for domestic sales, and therefore that no adjustment was needed.Footnote 28
Indonesia also argued that the mark-up accorded by PTMM to ICOF-S was an ‘internal allocation of funds within a single economic entity (or between “closely related or intertwined” parties) which does not reflect an actual or genuine expense and is not reflected in the producer's pricing decision [and therefore] cannot be a difference which affects price comparability under Article 2.4 of the Anti-Dumping Agreement’.Footnote 29 This argument seems to be a natural extension of the SEE theory. Again, Indonesia sought to protect the ability of PTMM to argue for one characterization of the relationship for tax purposes, and another for trade purposes.
The Panel rejected the proposition advanced by Indonesia that the existence of a SEE is dispositive of whether the mark-up is a difference that affects price comparability.Footnote 30
The Panel explained that, in its view, the ‘dividing line’ between (a) an internal allocation of funds within a single economic entity which is not reflected in the producer's pricing decision and (b) an expense that is linked to either the export side or the domestic side or to both sides but with different amounts such that price comparability is affected, is dependent on the particular situation and evidence before the investigating authority in a given case where the proper characterization of the payment in question is at issue.Footnote 31
The Appellate Body agreed: ‘the focus of the investigating authority's assessment is not on the nature of the relationship between related companies per se, but rather on whether that relationship can be demonstrated to be a factor that impacts the prices of the relevant transactions’.Footnote 32 The focus under WTO law is behavioral, not structural. Thus, while the SEE concept has independent significance under EU law, it does not under WTO law.Footnote 33
Again, because these related parties are capable of transacting at arm's length, the fact of a SEE does not conclusively mean that the mark-up is not a real commission expense to PTMM. In part because PTMM wants to characterize these expenses as actual expenses for tax purposes, they can be treated as actual expenses for trade purposes.
Interestingly, the Appellate Body rejected Indonesia's argument that its position is supported by the reasoning of the Appellate Body under Article 6.10 of the ADA in EC–Fasteners (China),Footnote 34 where the question for purposes of whether to assign an individual margin of dumping may depend on the relationship between two entities.Footnote 35 So, the determination of whether to respect formal corporate separateness is dependent on the particular provision being applied, even within the ADA.
Indonesia made a related argument that the EU authorities’ deduction for the mark-up led to an asymmetrical comparison between export price and normal value, because the elements deducted from export price – selling, general, and administrative costs (‘SG&A’) of ICOF-S – were not deducted from normal value.Footnote 36 The SG&A was used by the EU authorities as a notional commission payable to ICOF-S, and deducted from export price.
The Panel found that it was not incorrect for the EU authorities to treat the mark-up to ICOF-S as revised to equal its SG&A, as an ‘additional cost and profit’ under Article 2.4, subject to adjustment: ‘we consider that the intervention of downstream participants in the sales chain may result in “additional costs and profit” which are likely to affect price comparability across markets’. Footnote 37 The reason that the EU authorities referred to ICOF-S’ SG&A, instead of the actual mark-up, was because of an assumption that given the common control between PTMM and ICOF-S, the mark-up did not fully reflect the market value of the services provided by ICOF-S.Footnote 38
Thus, the EU authorities found that there can be economic substance in a transaction between related parties, but that the price set in a transaction between related parties may be artificial, and thus can be rejected in favor of a more substantively calculated price. The amount of the adjustment was not at issue in this dispute, but the Appellate Body agreed with the Panel that ‘in circumstances where [a close] relationship exists, investigating authorities would be justified in examining whether the actual value of the expense differs from its reported value’.Footnote 39
In addition, Indonesia complained that the EU had applied the SEE doctrine to Ecogreen in the EU authorities’ post-Interpipe revised determination, while declining to apply it to PTMM. Indonesia argued that the EU authorities relied on ‘meaningless’ factors to determine that ICOF-S was an ‘agent working on a commission basis’. The EU authorities found that the Ecogreen circumstances were similar to those of Interpipe, including low volume of sales to third countries, common ownership, and the nature of functions of the trader and the producer. On the other hand, the EU authorities distinguished Ecogreen from PTMM on the basis of (i) the level of direct export sales made by PTMM, (ii) the significance of ICOF-S’ activities in connection with products from unrelated companies, and (iii) the existence of a contract between PTMM and ICOF-S.Footnote 40 The Panel accepted the EU authorities’ appreciation of these facts.
Moving on to the question of whether a mark-up on sale can be the basis for a price adjustment under Article 2.4 of the ADA, the Panel noted that the list of factors subject to adjustment in Article 2.4 is, as found by the Appellate Body, non-exhaustive.Footnote 41 The Appellate Body in this case agreed.Footnote 42 The Panel also suggested that the burden of proof as to whether a factor affects price comparability under Article 2.4 is allocated to the party subject to investigation, and not to the national authorities.Footnote 43
4. Conclusion
Firms use transfer pricing for a variety of reasons, including reduction of tax liability and reduction of tariff liability. Tax liability can be reduced by under-invoicing in sales from high tax jurisdictions to low tax jurisdictions, or by over-invoicing in sales from low tax jurisdictions to high tax jurisdictions. This is the subject of the OECD Base Erosion and Profit-Shifting initiative. Tariff liability can be reduced by under-invoicing. The WTO Customs Valuation Agreement regulates national responses to tariff liability-motivated transfer pricing. Transfer pricing can also be used to manipulate prices for purposes of reducing anti-dumping duty liability. This is partially addressed by Article 2.3 of the ADA, which references the first resale to an independent buyer. All attacks on transfer pricing effectively ignore the formal separate incorporation of related parties in a corporate group, and thereby ‘pierce the veil’ of separate incorporation for purposes of ignoring nominal prices in favor of ‘arm's length’ prices.
In the present case, the question was first whether the nominal existence of a mark-up paid to ICOF-S should be ignored in favor of the exporter because it was a price within a SEE, or a single corporate group. In effect, Indonesia was arguing that PTMM's transfer price, established for tax purposes, should be ignored for Article 2.4 purposes. In addition, while the EU authorities argued that these prices had economic substance and should not be ignored completely, they ignored the specific amount of PTMM's prices in favor of a calculated price based on SG&A.
The Panel and Appellate Body viewed the question of how to treat related party transactions for purposes of determining adjustments under Article 2.4 as a separate issue. This case raises the question of whether a harmonized approach to transfer pricing across different regulatory areas would be useful to bring greater certainty to international transactions, and to reduce incentives to ‘game’ the system.