


1. Introduction
This paper examines alternative theories in monetary economics that help explain the interaction between monetary policy and securities markets. This subject is important because, increasingly, actuarial education and research has accepted a view of financial markets that relies implicitly on equilibrium theories and the assumption that markets are efficient. This is the case, for example, in much of the extension of corporate finance ideas into pension scheme funding and investment policy and in the use of market values in pension fund and insurance company accounting. Indeed, regulatory capital requirements for both life and non-life insurance companies under the forthcoming Solvency II arrangements will be determined using market values of investments with very limited discretion. Furthermore, much of the material in the CT8 (Financial Economics) subject of the Actuarial Profession's examinations relates to equilibrium theories of financial markets.
These equilibrium theories have their uses and some of the monetary theories discussed below are compatible in every respect with equilibrium theories of financial markets. Indeed, the use of objective information for financial reporting may well be valuable even if equilibrium theories of asset markets do not hold. However, actuaries have a responsibility to take prudent decisions relating to investment, capital allocation and so on. It is therefore helpful to understand how monetary policy can affect equilibrium in financial markets or, indeed, can create disequilibrium conditions. It is useful to consider how the action of specific agents (central banks in the context of our discussion here) may lead to disturbances from equilibrium.
Financial markets involve a continual process of discovery of new information and the absorption of that information into financial market prices. An understanding of the relationship between monetary policy and investment markets may lead us to question or qualify the efficient markets hypothesis with obvious implications for investment decision-making and, possibly, for accounting in financial institutions. At the very least, an understanding of the interactions between monetary policy and financial markets provides an information stream to financial markets which should be taken into account when investment decisions are made. Modelling for management purposes in order to determine investment strategy, funding levels, economic capital and so on can incorporate a variety of underlying assumptions and these should include assumptions about the relationship between monetary policy and investment markets if appropriate.
It can be argued that financial markets respond rapidly to disequilibrium conditions and equilibrium can quickly restore itself after a monetary disturbance because transaction costs are low and information flows rapid in financial markets. This is a plausible view. However, opponents of this view would point out that monetary disturbances may take longer to work through the real economy and financial markets can remain distorted by monetary policy until the effects have been fully transmitted through the real economy.
It is not the purpose of this paper to evaluate different theories of monetary policy and their interaction with financial markets: these remain matters of controversy. This paper presents mainstream theories of monetary policy and draws out the implications that are regarded as most important for actuaries and actuarial research.
The paper begins by looking very briefly at evidence that shows there is a prima facie case for exploring the relationship between monetary policy and investment markets. It then discusses the monetarist transmission mechanism which directly links investment markets with monetary policy: notable work has been undertaken in this area by actuary Gordon Pepper. The paper then examines more widely accepted neo-classical and neo-Keynesian theories of monetary policy. Finally, in the review of monetary theories, Austrian ideas are discussed. These are interesting because of the direct link they posit between monetary policy and investment decision-making and the relationships between these processes and the real economy.
Before concluding, there is a discussion of the implications of the different theories for monetary policy decision-making frameworks. This discussion is particularly relevant in the wake of the financial crash of 2008.
2. Monetary policy and asset prices – a basic empirical relationship
It is generally accepted in the literature that there is an empirical relationship between monetary policy variables and investment market values. Whether that relationship is useful in setting monetary policy is, however, disputed. The empirical relationships vary in magnitude and precise effect but are enduring. They have been discussed, for example, by Meltzer (Reference Meltzer1995); by Jensen and Johnson (Reference Jensen and Johnson1995); and by Ehrmann and Fratzscher (Reference Ehrmann and Fratzscher2004) who show that monetary policy affects the share prices of some types of company substantially more than others.
Comprehensive evidence is provided by Conover et al. (Reference Conover, Jensen and Johnson1999). They describe periods of expansionary (contractionary) monetary policy as being times when interest rates are falling (rising). They estimate the following equation across a number of different countries for the years 1956 to 1995:
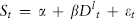 $${{S}_t}\, = \,\alpha \, + \,\beta {{D}^l} _{t} \, + \,{{{\epsilon}}_t}$$
St is the monthly equity return measured in local currency terms and D lt is a dummy variable equal to one if the last interest rate change was an increase and zero if it was a decrease. The results show significant and substantial relationships between the monetary policy stance and asset prices. Examples of values for β with the sample size and t-statistics are given in the table below. All four values for β shown in the table are significantly different from zero at the 5% level except that for the UK which is significantly different from zero at the 1% level:
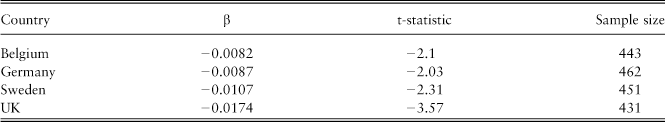
The average investment return differences between periods of expansionary and contractionary monetary policy are very substantial when compounded annually: in the US, for example, the results suggested an average annual return difference of 14%. All but one of the 16 countries studied (the exception being Austria) produced a negative value for β. Twelve out of the 15 countries with a negative value for β produced values that were significant at the 5% level. The results for real returns are very similar to those for nominal returns. This work very much corroborates other work by Jensen and by Conover's co-authors.
These results are important in their own right but, as the authors readily admit, they provide little understanding of cause and effect and, indeed, of the role of monetary policy as opposed to the role of real variables that might, in turn, affect interest rates.Footnote 1 There are at least two possible explanations for these results. One explanation is that changes in monetary policy do affect asset returns (with expansionary monetary policy and low interest rates being associated with higher returns as a result of processes that will be discussed below). It is also possible, however, that a change in interest rates does not signal a change in monetary policy but involves the central bank keeping its monetary policy stance constant given changes in real economic variables that themselves affect interest rates. For example, changes in real variables such as a rise in the level of saving could lead to a change in equity values. The rise in the level of saving may then lead the central bank to reduce interest rates as equilibrium interest rates fall. This explanation would be consistent with schools discussed below that tend to play down the importance of monetary policy for asset prices – especially the neo-classical school.
It is also worth mentioning that the move to inflation targeting regimes by a number of countries in recent years might change the relationships discussed above. This is because, if the central bank is acting in a clear and transparent way, market interest rates will adjust in anticipation of central bank interest rates changing and thus the explanatory power of central bank interest rates in statistical models could be reduced. Econometricians will then have to examine other, more subtle, relationships. Nevertheless, the results of Jensen, Conover et al. and others show that there is at a least prima facie case that those who work in professions linked to financial and investment markets should try to understand the relationship between monetary policy and investment markets. These relationships may be important whatever the direction of causality.
It is also worth noting at this stage that examination of major events suggests a relationship between monetary policy and asset prices. As Dillen and Sellin (Reference Dillen and Sellin2003, page 126) put it: ‘There is a relatively broad consensus that US monetary policy was crucial for the stock market crash of 1929.’ They draw a similar conclusion about the Japanese bubble of the late 1980s. Schwartz and also Greenwood in Booth ed (Reference Booth2009) both suggest that loose monetary policy was an important contributor to the asset price bubble and subsequent financial crash of 2008, though this is disputed by central bankers on both sides of the Atlantic: for example, Bernanke (Reference Bernanke2010) argues that direct linkages between monetary accommodation and the US house price boom that preceded the crash were weak; and Bean et al. (Reference Bean, Paustian, Penalver and Taylor2010) argue that monetary policy only explained part of the growth in house prices before the crash and that it explained a rather smaller part in the US, which was the source of the crisis, than in the UK. Nevertheless, whatever the relative contribution of monetary policy and real factors to movements in asset prices, it is an important area for potential investigation.
3. Monetarism and the transmission mechanism
In terms of the different theories of monetary policy, this paper will begin by discussing monetarist ideas. This is not because they are regarded as more important than other theories but because they lead directly to a discussion of the relationship between monetary policy and investment markets. They therefore provide a useful starting point.
3.1 The fundamental idea of monetarism
The basic idea of monetarism is the quantity theory of money. The specific form of that theory is often represented by the equationFootnote 2 proposed by Fisher: MV = PT (the quantity of money times its velocity of circulation is equal to the price level times the volume of transactions). The identity provides a focus for analysis. It is the relationships between the elements of the identity that are important and which open up legitimate avenues of dispute between economists.
Monetarists would tend to argue that, in normal circumstances, the velocity of money changes in a predictable way. Therefore, an exogenous increase in the quantity of money would lead to an increase in PT. Most monetarists would also argue that, in the long run at least, a rise in the quantity of money would be reflected in a rise in the price level and not in a rise in real national income. From these two propositions comes the conventional monetarist belief that control of the money supply is essential for controlling inflation. There is an excellent discussion of the monetarist exposition of this and the anti-monetarist counter-perspective in two articles in the journal World Economics – Congdon (Reference Congdon2004) and Mayer and Minford (Reference Mayer and Minford2004).
3.2 Key propositions of monetarism
The presidential address of Milton Friedman to the American Economic Association (Friedman, Reference Friedman1968) and a Wincott Lecture in the UK (published as Freidman, 1970) provided important turning points in the intellectual debate between monetarists and their opponents. Naturally, the academic debate was beginning to develop a few years before, but these events and subsequent publications influenced a wider communityFootnote 3. Once again, formal monetary theory began to take as a starting point the proposition that nominal national income (P*T) would be affected by changes in the supply of money rather than those changes being offset by a change in the velocity of circulation. In his exposition of the main monetarist propositions, Friedman (Reference Friedman1970) also anticipated important future theoretical issues that would arise in the following few decades. It is worth restating these because they are highly relevant for a discussion of the relationship between monetary policy and financial markets. The points are also noteworthy because they demonstrate an underlying pragmatism in Friedman's ideas that eventually led to Keynesians, neo-classical economists and monetarists debating the extent and timing of the various forces identified by Friedman rather than whether these forces existed at all.
Specifically, Friedman identified the followingFootnote 4:
1. There is a consistent, though not precise, relationship between the rate of growth of the quantity of money and the rate of growth of nominal national income.
2. There are long and variable lags in this relationship.
3. The change in the rate of growth of nominal income arising from a change in monetary growth typically shows up first in output and hardly at all in prices. There will be upward pressure on prices only as a gap emerges between actual and potential output.
4. Even after allowance for the delay in the effect of monetary growth, the relationship between monetary growth and prices is far from perfect.
5. Inflation is always and everywhere a monetary phenomenon in the sense that it is produced only by a more rapid increase in the quantity of money than in output.
6. The initial effect of a change in the quantity of money is not on income but on the prices of existing financial and physical assets.
7. A change in monetary growth affects interest rates in one direction at first but in the opposite direction later on. Monetary growth tends to lower interest rates at first and then raises interest rates as a result of the effect of changes in actual or expected inflation.
These points and qualifications are important for a number of reasons. They provide the basis for debate between monetarist, Keynesian and neo-classical schools. Secondly, they indicate that changes in monetary policy are “transmitted” through the economy: this transmission mechanism – is a key issue in understanding the relationship between monetary policy and financial markets. Point 6 is clearly important in this regard. Thirdly, the propositions highlight the crucial role of expectations – something that is especially important in thinking about the way in which monetary policy changes affect financial markets. Finally, the link between monetary growth and interest rates is highlighted: clearly, this is also important for understanding the relationship between monetary policy and financial markets – especially as the effect on interest rates may not be the same in the short-term and in the long-term.
A more recent statement of the monetarist position appears in McCallum and Nelson (Reference McCallum and Nelson2010, page 11). They state: “An exogenous change (if it somehow occurred) in the rate of growth of the money stock would, therefore, induce a change of the same magnitude in the inflation rate unless it induced a change in the rate of growth of real transactions or the real interest differential. Neither of these possibilities seems at all likely, so the QTM [quantity theory of money] essentially implies that steady-state inflation rates move one-for-one with steady-state money growth rates.” McCallum and Nelson (Reference McCallum and Nelson2010 e.g. page 29) report strong relationships between money growth and inflation in the long run. The key point, however, is not that there is a perfect, one-for-one relationship between money and inflation: the velocity of money may drift up or down over time for various reasons and changes in regulation and technology may lead to one-off changes in the velocity of money. However, the monetarist position argues that an exogenous shock to money growth will lead – in the long run – to a related change in inflation. The change in money supply will not, itself, lead to a change in velocity of circulation or real national income.
4. Monetarism, the transmission mechanism and asset prices
Current exponents of monetarismFootnote 5 believe that insufficient explicit attention is given to the role of money and the way in which changes in monetary policy are transmitted through the financial and economic system; this, in turn, is also reflected in a lack of emphasis on the way in which monetary policy can affect investment markets. As is clear from the summary of Friedman (Reference Friedman1970), monetarists did not assume a simple, mechanical relationship between the quantity of money and the price level as is often asserted. It was accepted that the way in which changes in monetary policy were transmitted to the price level could vary and that this should be a subject of study.
Modern developments in monetary policy have led to interest rates being regarded as the most important tool of monetary policy. In a modern economy, in normal circumstances, the monetary policy instrument that central banks use is a particular short-term interest rate – effectively the rate of interest at which the central bank lends to the banking system. The supply of money is still affected by the actions of the central bank changing interest rates, but indirectly so. Modern finance theories have tended to rely on assumptions of market clearing and rational expectations that play down the way in which monetary policy changes are transmitted through the economy. Modern theories have also given less emphasis to the role of money balances in the inflationary process and have given more emphasis to the role that interest rates playFootnote 6.
However, there must be a mechanism that transmits monetary policy changes through the economy and investment markets are likely to be part of that mechanism. The key observation made by Fisher was that an increase in the quantity of money – which may be caused by a reduction in central bank interest rates – does not decrease its velocity. There is a cost for individuals, industrial firms and financial institutions when they hold money because it bears no interest. If the quantity of money rises, money balances will be higher, and those who hold money will try to spend those money balances. This, in turn, will affect prices and economic activity. Whilst one individual, company or institution can reduce its money balances, they can only pass the excess to another agent: the system as a whole cannot get rid of the excess money.Footnote 7 Exactly how a rise in the supply of money affects prices and economic activity will depend on who has excess money balances and how they are used – it is the study of the transmission mechanism that leads us to understand this process and see the importance of the relationship between money and asset prices.
Possible methods by which a change in monetary policy can affect the real economy via financial markets in a modern economy are outlined in Mishkin ed. (Reference Mishkin2007). A loosening of monetary policy can raise equity and real estate prices as non-bank financial institutions reduce holdings of money to desired levels as a proportion of their portfolios by buying securities and real estate. This, in turn, can increase real investment for several reasons. For example, the cost of physical assets can become out of line with the price of financial assets (see below); the value of equity in firms’ balance sheets will rise, thus making it easier for firms to borrow; the improved balance sheet position of consumers (as owners of assets) will make it easier for them to borrow and spend; and the higher net wealth of consumers will lead to an increase in their propensity to consume.
Meltzer (Reference Meltzer1995, page 51) describes the process in the following way:
“A monetary impulse that alters the nominal and real stocks of money does more than change a single short-term interest rate or borrowing cost. Monetary impulses change actual and anticipated prices on a variety of domestic and foreign assets. Intermediation and the term structure of interest rates, borrowing and lending, and exchange rates respond.”
Thus, he argues, financial markets become an important conduit as monetary policy changes are transmitted through the economy.
Meltzer argues that asset markets respond more quickly to monetary impulses than the real economy because the cost of information gathering and of transactions in financial markets is lower than the cost of altering the production of goods and services. This is precisely why central banks might regard developments in asset markets as providing a signal of inflation or deflation even if they do not explicitly target asset markets – see below. Using housing markets as an example, Meltzer shows that there is a considerable impact on asset values from changes in monetary policy in various policy environments. Anticipated future changes in economic variables will also affect the transmission mechanism and, as Meltzer makes clear, the way the transmission mechanism is affected will depend on how complete information is and on the costs of acquiring information. If, for example, investors expect that a loosening of monetary policy will lead to higher inflation then the transmission mechanism is likely to lead to a greater rise in demand for real assets than for conventional bonds.
4.1 Non-bank financial institutions and the transmission mechanism
Given that they are the focus of actuarial professional life, it is worthwhile considering the effects of changes in monetary policy on non-bank financial institutions in greater depth.
Financial markets could be an important conduit through which changes in monetary policy are transmitted to the wider economy. It is therefore worth noting the contributions of Congdon who has specifically outlined the distinct role of non-bank financial institutions (insurance companies, pension funds, mutual funds and so on) in this process. Congdon (Reference Congdon2005) looks empirically at the relationship between non-bank money holdings, asset prices and the wider economy. He regards non-bank financial institutions as key to this process. As they invest mainly in securities markets and are the main institutions in which there is an actuarial interest, these ideas are obviously relevant to this paper.
If money holdings of non-bank financial institutions rise, they will, Congdon argues in an extension of the work of the early monetarists, spend that money on financial assets. Keynes understood the potential for such links but his focus was on a much narrower range of assets. This link between money and financial assets can take effect for two reasons. Firstly, as was mentioned above, moneyFootnote 8 yields no return and thus institutions do not want to hold more than is dictated by considerations of liquidity requirements and risk. Secondly, many institutions operate with investment guidelines that will discourage them from increasing the amount of money held. The excess money balances will be spent in securities and real estate markets and this could create, if monetary policy is very loose, an “asset price boom.” As far as bond markets are concerned, this will manifest itself in lower nominal and real long-term interest rates as well as reduced credit spreads. At the same time, there may well be lower short-term interest rates if changes in monetary policy are signalled via short-term interest rates.
It may be thought that this hypothesis, if true, undermines the efficient market hypothesis though it does not undermine the idea that securities are priced efficiently relative to one anotherFootnote 9. Indeed, Pepper (Reference Pepper1994) argues that the influence of money on asset prices requires a qualification of the efficient market hypothesis. The correct way to explain this phenomenon would be as follows: the efficient market hypothesis is a theory of asset values in equilibrium; a monetary bubble involves a disturbance of that equilibrium; this disturbance is then transmitted through securities markets; eventually equilibrium will be restored at a higher price level in both asset markets and the real economy. As Meltzer (Reference Meltzer1995, page 50) puts it: “[B]efore impulses are fully absorbed, relative prices and real output respond to monetary impulses…time is required to distinguish between permanent and transitory impulses and real and nominal impulses.”
Asset prices are, of course, just one channel of transmission. Congdon argues that it is an important channel that is too often ignored. The Austrian theory, discussed below, very much emphasises this mechanism too and specifically emphasises the way in which the transmission of monetary policy through asset markets distorts the real economy. Congdon produces convincing evidence of the impact of non-bank financial institution money holdings in creating asset price booms (and busts). Specifically this includes the boom before the US Great Depression, that before the Japanese malaise and a number of UK episodes. The key relationship, for the UK, is estimated as followsFootnote 10:
Change in composite investment price index Footnote 11% per annum = 2.97 + 0.42(change in non-household money)% per annum + et
R squared = 0.42
Standard error of regression coefficient = 0.06
t statistic for regression coefficient = 7.24
By Congdon's own admission, he did not use the most sophisticated econometric techniques. But there is strong evidence – as well as strong theory – that there is a process here that should not be ignored by institutional investors. Congdon (Reference Congdon2007) points out (see, especially chapters 14 and 15) that there has been a huge expansion of non-bank financial sector balance sheets in the last 40 years but very little change in the ratio of cash held to total assets a ratio which, as many actuaries would recognise, is generally determined by factors such a liability and liquidity requirements. As such, non-banks do not have an infinitely elastic demand for money.
Asset prices are, of course, only the first part of the transmission mechanism (see Congdon, Reference Congdon2007, chapter 14). A monetary-induced rise in asset prices can affect the real economy in various ways (for example, it can lead to more share issues as the relationship between share values and the replacement cost of capital changes; lead to mortgage equity withdrawal and lead to more residential and commercial real estate building as the relationship between house values and land values change). Again, there are strong similarities here between the position taken by broad-money monetarists such as Congdon who emphasise the transmission mechanism and the Austrian school discussed below. However, their methodological approach is so different that neither school is keen to recognise those similarities.
It is important to point out that there is an important distinction between money and credit in this analysis. An increase in credit can be financed in various ways that do not involve an increase in the supply of money.Footnote 12 An important paper by Borio et al. (Reference Borio, Kennedy and Prowse1994) shows that monetary policy was an important determinant of asset prices in the 1970s but, in the 1980s, expansions in credit were more important. Such credit expansions often came about as a result of liberalisation of credit markets which would make it easier for individuals to borrow in order to invest in real assets. Both monetary and credit expansions can take place through the banking system and can therefore be confused with each other.
Congdon's work highlights the role of non-bank financial institutions in the transmission mechanism. There are other potential channels of monetary policy that can affect asset prices. For example, Benanke and Blinder (Reference Benanke and Blinder1992, section IV) suggest that transmission channels through the banking system to asset markets can be important. A tightening of monetary policy could lead to a shortage of liquid funds within banks and this shortage of liquid funds, in the short term, cannot be rectified by reducing bank lending. Instead the shortage will be rectified by the banks selling securities. The opposite process will occur if there is a loosening of monetary policy. This is still important for non-bank financial institutions as it suggests that security prices could deviate from fundamental value during the process of transmission of monetary policy changes.
4.2 Money balances and asset prices – the work of Gordon Pepper
Actuary Gordon Pepper studied relationships between investment markets and monetary aggregates as an investment practitioner. In particular, he used money supply measures extensively in his analysis of the behaviour of bond markets. The ideas have been published in Pepper (Reference Pepper1994), Pepper with Oliver (Reference Pepper and Oliver2006a) and Pepper with Oliver (Reference Pepper and Oliver2006b). Earlier work included two Institute of Actuaries’ Sessional Meeting papers (Pepper, Reference Pepper1970 and Pepper and Thomas, Reference Pepper and Thomas1973) with the former paper dealing mainly with the institutional background.
Pepper and Thomas (Reference Pepper and Thomas1973) considers the issue from the perspectives of practical investors observing how and when transactions take place and how and when expectations are formed. However, a formal theory of the transmission mechanism is consistent with the authors’ observations. The authors argue (Part II) that increases in the money supply lead either to the spending of excess balances on financial assets and therefore lead to lower gilt yields and – with a longer lag – to increases in equity values. The decrease in gilt yields would be reversed in the medium term as expectations of inflation roseFootnote 13.
The authors also suggested that, if increased money balances were spent by individuals or firms on goods and services, rather than by non-bank financial institutions on securities, the initial financial impact of a loosening of monetary policy would be on the equity market. This would be because economic activity would rise before inflation rose, causing both the money and real level of profits and dividends to rise in the short term. The impact on the gilt market would be delayed in this case because the transmission mechanism would not involve financial assets; the only effect on gilts would be a rise in yields because of a rise in inflation expectations.
If the transmission mechanism involves individuals spending increased money balances on goods and services, rather than on financial assets, then the impact on real variables in financial markets is relatively small. Financial markets would merely be reacting to temporary changes in the real economy caused by a change in the money supply. As has been mentioned already, Meltzer (Reference Meltzer1995) suggested that the transmission mechanism was likely to be through financial markets initially because of the lower transactions costs in financial markets as compared with the real economy.
Pepper's theories concerning the influence of monetary policy on financial markets were refined in later work. Pepper with Oliver (Reference Pepper and Oliver2006a), Pepper with Oliver (Reference Pepper and Oliver2006b) and Pepper (Reference Pepper1994) looked at the evidence in much more detail. The key empirical question is whether changes in monetary policy have significant effects on asset markets as a result of the way in which those changes are transmitted through to the economy. Their findings can be summarised as follows:
“The supply of money can be in excess of the demand for money, or less than the demand for money, for prolonged periods. If money is in excess, some of the excess will be spent on existing assets. Conversely, assets will be sold if money is deficient. Purchases of assets for liquidity reasons can, as a result, exceed sales, or vice versa, for several months.” (Pepper with Oliver, Reference Pepper and Oliver2006a, page 19).
The authors recommend that monetary aggregates are monitored and interpreted for the purposes of investment analysis. Interestingly, there is no contradiction here between Pepper's findings and those of the Austrian school (discussed below) or the mainstream monetarist school, though Pepper approaches the subject from a practitioners’ perspective rather than from that of a theoretician. Indeed, the transmission mechanism proposed by the Bank of England (see below) contains elements of the thinking outlined by Pepper. Pepper's theory is less formal but more rooted in the practice of investment analysis. Furthermore, the details of Pepper's work – including, for example, the study of the impact of different definitions of the money supply – is detailed and precise.
The analysis of Pepper and Thomas also came with prescient caveats. These anticipated later developments in theory. For example, they suggested that their analysis might become invalid if the Bank of England attempted to control the money supply – which it did not do so until after their papers were writtenFootnote 14. Secondly, the authors argued that, when the relationships became widely known, they may change.
5. Keynesianism, new-Keynesianism and the neo-classical synthesis
As has been noted, many modern academic models of monetary policy include only a “bit part” for asset markets. These include the neo-classical and new-Keynesian schools which have been synthesised into models that are frequently used within central banks.
Crude Keynesianism, of the sort that arises from extrapolating the ideas in Keynes’ General Theory (Keynes, Reference Keynes1936), cannot deny the monetarist identity. Instead, Keynes argued (e.g., Keynes, Reference Keynes1936, chapters 13–15) that, in some circumstances at least, a change in the supply of money would have no predictable effect on either the volume of transactions or on the price level because there would be an offsetting decrease in the velocity of money (or, equivalently, an increase in the desire of people to hold money balances). It is from this proposition that familiar phrases such as “monetary policy is like string: you can pull on it but you can't push on it” arose. However, as will be noted below, Keynes himself believed strongly that, in normal circumstances, monetary disturbances would lead to changes in nominal national income.
Clearly, monetary policy is ineffective in some circumstances if the traditional Keynesian critique holds. A corollary is that monetary policy will not affect financial markets. Money balances created by the central banks are just held as money balances and the velocity of circulation of money slows down. In such circumstances, it would be argued that other policy tools should be used to influence the price level, employment and output.Footnote 15
Though some economists would take the position that the Keynesian explanation has some validity during a deep depression, it is not widely accepted as a general explanation of the effect of monetary policy in normal times: indeed, Keynes himself did not imply that it should be. Nevertheless, certain underlying assumptions that underlay Keynes’ way of thinking have been taken and developed into a more formal framework of monetary economics often known as “new-Keynesianism”. These ideas also form part of the “neo-classical/new-Keynesian macro-economic synthesis” and are more widely applicable to general economic circumstances. They are, in turn, interesting for our discussion in that they tend to downplay the monetary transmission mechanisms through financial markets. They can therefore be contrasted with theories that do have an explicit role for the transmission mechanism. It is notable that this consensus has become rooted within central banks.
5.1 New-Keynesian models
The basic new-Keynesian approach to monetary policy models three relationships. Firstly, output today (y) is a function of expected output in the next period and the expected real interest rate j (based on the current nominal interest rate (i) and the expected rate of inflation (r)):
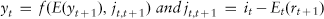 $$ {{y}_t}\, = \,f(E({{y}_{t\, + \,1}}),\,{}{{j}_{t,t\, + \,1}})\,\,and\,{{j}_{t,t\, + \,1}}\, = \,{{i}_t}\,{\rm{ - }}\,{{E}_t}({{r}_{t\, + \,1}}) $$
The second relationship assumes that firms are oligopolistic and that prices adjust slowly in the real economy if there is a change in monetary policy (if all prices changed instantaneously, there would be few real effects from a change in monetary policy). Thirdly, it is assumed that interest rates are determined using a Taylor Rule whereby short-term interest rates are set according to deviations of inflation and output from implicit or explicit target rates so that:
 $${{i}_t}\, = \,f({{\pi }_t},\,{{y}_t}){\rm{.}}$$
This approach does not completely suppress the asset price channel in terms of the transmission of monetary policy changes. However, the asset price channel is very much implicit. The new-Keynesian model reflects the fact that monetary policy – at least in “normal” times – is conducted by adjusting short-term interest rates rather than by controlling the quantity of money directly. As has been noted by Bernanke, the impact of short-term interest rate changes on asset prices are believed to be minor. It should also be noted that expectations play an important role in modern new-Keynesian models – just as they do in neo-classical modelsFootnote 16.
Perhaps the most succinct way of summing up the new-Keynesian approach is as follows: “In particular, we wish to make clear that we adopt the Keynesian approach of stressing nominal price rigidities, but at the same time base our analysis on frameworks that incorporate the recent methodological advances in macroeconomic modeling (hence the term “New”)” (Clarida et al., Reference Clarida, Galí and Gertler1999, page 3). Those recent advances include an important role for expectations within the new-Keynesian models.
Because new-Keynesian models assume nominal rigidities in product and labour markets, any change by the central bank to nominal short-term interest rates will give rise, at least temporarily, to a change in real short-term interest rates – prices will not respond instantaneously. However, it is recognised that, should a central bank persistently try to push inflation above target, there will be no gain in output in the long run, though there will be persistent inflation (Clarida et al., Reference Clarida, Galí and Gertler1999, page 17). The neo-classical insights on the importance of monetary policy institutions being “credible” are also incorporated, as new-Keynesians believe that there will be a better short-run inflation versus output trade off if the central bank is credibleFootnote 17.
As has been noted, the new-Keynesian approach plays down the direct role of money and the transmission mechanism through asset markets and focuses on the real economy. However, some asset market channels are regarded as important by new-Keynesians. These include the relationship between short-term interest rates and long-term interest rates and the subsequent effect on asset prices (see below). Also, a loosening of monetary policy may ease the ability of firms to finance investment (by reducing their interest costs) and encourage banks to lend to firms about which they have less publicly available information (because their interest costs are a lower proportion of cash flows). These could be regarded as “Keynesian” effects because the emphasis is on the way in which a fall in interest rates reduces the costs faced by firms resulting from market imperfections. These so-called “credit channels” are investigated by Ehrmann and Fratzscher (Reference Ehrmann and Fratzscher2004). They find strong evidence that changes in monetary policy affect different types of firms in different ways and, in particular, that those firms that are most financially constrained are affected most by monetary policy. Furthermore, they also find evidence that shares in cyclical companies – that is those firms producing products the demand for which varies the most as economic conditions change – are affected the most by interest rate changes. Again, this would suggest a Keynesian mechanism that ran from the real economy to asset markets rather than the other way round. If monetary policy is loosened, this benefits particular firms and, as such, their share price could increase. This contrasts with – though may work in addition to – the mechanisms suggested by Congdon which work directly via changes in behaviour within financial markets which directly transmit changes in the quantity of money through to the real economy. It is also worth noting that Clarida et al. (Reference Clarida, Galí and Gertler1999, 5.2) mention that sharp, unanticipated interest rate increases might generate financial losses for banks and financial institutions exposed to interest rate risk but this point is not really developed by the authorsFootnote 18.
These ways in which the financial sector are affected by monetary policy are indirect and largely operate through changes in monetary policy operating in the context of a real economy that is not free of frictions. As it happens, these new-Keynesian mechanisms, to some extent, formalise some of the channels mentioned by Pepper. As far as financial market practitioners are concerned, the key variables to consider would not be measures of broad money held by financial institutions but the different effects that changes in interest rates might have on firms that face different business conditions and financial structures. Essentially, this is only of interest to those actuaries involved in investment analysis rather than in the financial management of non-bank financial institutions.
As noted, asset markets are “bit part” players in Keynesian models. In this context, the observation by Clarida et al. op cit (page 44) is interesting:
“A frequently cited reason for why monetary policy should not adhere tightly to a simple rule is the need for flexibility in the event of a financial collapse. In the wake of the October 1987 stock market crash, for example, most economists supported the decision of the Federal Reserve Board to reduce interest rates. This support was based largely on instinct, however, since there is virtually no formal theoretical work that rationalizes this kind of intervention.”
As we shall see below, neo-classical economists would also not incorporate such events into their models. However, in their case, they would be less inclined to demand policy action – based on either instinct or theory.
5.2 The neo-classical school and the sidelining of asset markets
As with the new-Keynesian school, the neo-classical school has relatively little to say about the impact of monetary policy on asset prices and financial markets more generally. Neo-classical thinking emphasises the speed with which changes of policy can be transmitted through the economy, particularly if they are anticipated.
Goodfriend (Reference Goodfriend2002) summarises the neo-classical model as follows – though different notation is used here. Household consumption in the current period (c1) and in the future period (c2) is determined by the market real rate of interest (r) and the consumer's time preference (ρ) as shown by the equation:
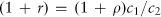 $$({\rm{1}}\, + \,r)\, = \,(1\, + \,\rho ){{c}_1}/{{c}_2}$$
Similarly, labour supply is determined by the household's time constraint, real wages and the preference for work and leisure. Equilibrium output, y* is determined by production technology which determines labour productivity (a) and the profit maximising mark-up (μ*):
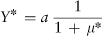 $${{Y}^\ast} \, = a\,\frac{1}{{1\, + \,{{\mu }^\ast} }}$$
The real rate of interest in this model equilibrates household consumption plans and companies’ investment plans. If productivity is expected to rise, for example, households may wish to borrow more and spend more today in order to smooth their real consumption patterns in anticipation of rising real incomes. This raises the real rate of interest so that consumption plans match the expected growth in productivity. The equilibration will also be facilitated by investment plans being reduced as the real rate of interest rises (as a second-order effect) and therefore the growth in productivity slowing.
This model can be used to explain at least part of the consumption boom and low savings rates in both the UK and the US in the lead up to the financial crash of 2008. In both the UK and the US, it was widely believed that productivity growth had increased. This was reflected in the UK government raising its estimate of the sustainable growth rate in the late 1990s. In the US, it was widely believed that improvements in technology had raised productivity growth. The neo-classical model would suggest that individuals would raise consumption and this would put upward pressure on real interest rates in a closed economy. However, the openness of the UK and US economies adds an extra aspect to the process. Capital inflows from countries with high net savings to countries where higher consumption is putting upward pressure on interest rates can keep equilibrium interest rates low and current consumption high in countries where there would otherwise be upward pressure on interest rates.
Whatever the processes in this model, however, it is real factors and not changes in monetary policy that are at the root of rapid movements in asset prices. As Selody and Wilkins (Reference Selody and Wilkins2004, page 4) put it:
“In standard models of the economy, financial markets are assumed to be efficient and free of distortions. Economic agents are assumed to exhibit ‘rational’ (optimising) behaviour. Asset price misalignments are not possible unless economic agents exogenously deviate from their optimal behaviours.”
Followers of these schools therefore look for non-monetary explanations of causes of rapid asset price movements. These can include real factors such as changes in the productivity of capitalFootnote 19 and a small class of self-fulfilling speculative bubbles. Also, increases in world saving will, if capital markets are free, increase asset prices throughout the world – thus, it would be argued, the increase in savings in Asia could have been a real factor in raising asset prices in the early twenty-first century, though they would not have caused the financial crisis in the neo-classical model. Such models of the economy and the role of interest rates in these models do not allow for the possibility that monetary policy will be the cause of substantial investment market disequilibria.
5.3 Neo-classical/new-Keynesian synthesis
The neo-classical and new-Keynesian models have been “synthesised” into models that today form the basis of much thinking within central banks. Both schools, and by implication the synthesis, play down the roles of the quantity of money and the financial sector in the operation of monetary policy. On the other hand, the quantity of money and the financial sector are regarded as crucial in the monetarist and Austrian schools as they were by Keynes himself. For the neo-classical school, changes in monetary policy have no impact on real variables if changes in monetary policy are anticipated – this would include effects on asset markets. In the new-Keynesian school, as Congdon argues (Congdon, Reference Congdon2007, page 13): “In line with their theoretical commitments, they instead advocate that the central bank rate should be set by ‘looking at everything’, although with particular focus on the output gap.” This explains the wide-ranging econometric models used by central banks with only a little emphasis on money itself. More precisely, Congdon could have said that new-Keynesians look at everything but money and asset prices. The focus is very much on the transmission mechanism of money through the real economy, though “credit channels” may also be considered important channels of transmission in some new-Keynesian models.
In the synthesis, many broad principles of the neo-classical school are accepted but stickiness in labour and product markets is assumed so that real variables may respond to a monetary policy shock in the short term. Expectations are crucial in this synthesis and the credibility of the central bank is important in forming expectations. Although this is not the main theme of the article, it is worth developing this point further because it has some relevance for financial markets.
If a central bank has a very strong degree of credibility, so that economic agents believe that it will hit its inflation target, its actions will be anticipated by investment markets. For example, if the inflation target is 2%, then the difference between real interest rates on index-linked bonds and nominal interest rates on conventional gilts is likely to be very close to 2% if the central bank is credibleFootnote 20. If there is a need for the central bank to change interest rates to hit the target, the market will anticipate that change and will reflect future changes in interest rates in the yield curve. The central bank will then behave in a smooth and predictable way and the markets will partly do the central bank's job for it as interest rates rise in the markets to reflect the anticipation that the central bank will act. It is tempting to assume that, once credibility has been achieved, the central bank does not have to do any further workFootnote 21. This is not the case. If the central bank does not react to real shocks where necessary, by changing interest rates, then the inflation target will no longer be hit. However, when the central bank does react there will be much less “noise” – inflation expectations in financial markets should still be close to the target and central bank and market interest rates should be close to each other.
Information about the credibility of the inflation regime can be obtained from asset markets as well as from surveys and from wage movements in labour marketsFootnote 22. Increasingly it is felt that the credibility of central banks is enhanced by making them operationally independent of government and giving them no incentive to raise employment and output in the short run by loosening monetary policy.
Thus, in these models the role of asset markets in communicating monetary shocks is downplayed. Asset markets reflect consistent expectations that the central bank will hit its inflation target. Asset markets can, however, provide important information about inflation expectations and about the credibility of the central bank in achieving its monetary policy objectives but they are not regarded as important in the transmission of changes in monetary policy through the economy.
6. Eclecticism and central banking
On the whole, central banks are eclectic institutions and their committees that set monetary policy often contain external members (or members from a diverse range of institutions). The theories that central banks enunciate reflect this, though very often the starting point is the neo-classical/new-Keynesian consensus.
The primary tool of monetary policy in most advanced economies is the control of short-term interest rates. The quantity of money is not controlled directly but is controlled indirectly by changing short-term interest rates. The money supply is not generally formally modelled or targeted in central banks todayFootnote 23.
It is possible for money to be the main driving force behind inflation and for money to affect asset markets through the transmission mechanism, whilst neither explicitly modelling nor targeting money. Nevertheless, this is a paradox that does deserve further attention. The paradox was examined by Mervyn King, now Governor of the Bank of England, in an article in 2002, and he has referred to it several times since:
“Evidence of the differences in inflation across countries, and changes in inflation over time, reveal the intimate link between money and prices. Economists and central bankers understand this link, but conduct their conversations in terms of interest rates and not the quantity of money…[T]here are real dangers in relegating money to this behind-the-scenes role. Three dangers seem to me particularly relevant to present circumstances. First, there is a danger of neglecting parts of the monetary transmission mechanism that operate through the impact of quantities on risk and term premia of various kinds…My own belief is that the absence of money in the standard models which economists use will cause problems in future.” (King, Reference King2002, pages 176–177).
Writing in 2011, Chrystal and Mizen (Reference Chrystal and Mizen2011 pages 3 and 4) wrote:
“In the inflation targeting regime there was no explicit role for monetary aggregates. Policy decisions were driven by the inflation forecast, which in turn was driven by forecasts of aggregate demand relative to potential aggregate supply. Money would have a role only if it provided information that was helpful for informing the short-term forecast of inflation. In practice the Bank of England's main forecasting model had no role for money. Monetary aggregates were certainly monitored and reported on a monthly basis to the MPC, but there are almost certainly no incidents where a policy decision was influenced by the money numbers where these were conveying a different message from the main forecast.”
In that paper, Chrystal and Mizen demonstrated how money holdings of non-financial corporations and households had a good relationship with inflation. They also argued that money holdings of non-bank financial institutions were less stable, less easy to model but, nevertheless, important in national income determination. Given the role non-bank financial institutions play in asset markets, this provides some corroborating evidence for the Congdon-Pepper view that attention should be paid to the monetary variables in studying asset markets.
The comments by both King and Chrystal and Mizen suggest that there is a real danger that the Bank of England's modelling omits consideration of the most important factor causing inflation because it is difficult to model. This comment could apply to central banks more generally. In principle, it is possible that, in most situations, the forecasting models of the type being used by the Bank of England are effective in predicting inflation over the required short timescale, but that there is a danger that more important underlying long-run forces are ignored. As such, there is also a danger that the process by which inflation is transmitted through the system is not properly modelled or understood and that the impact of monetary policy on asset markets and the effect of asset markets on the real economy may not get the attention they deserve. Congdon would argue that this is precisely the problem that has contributed to asset market booms and busts – including the recent one.
Notwithstanding this, there is a basic transmission mechanism relationship set out descriptively by the Bank of England in Monetary Policy Committee (1999). This transmission mechanism does make reference to asset markets. It is argued that a change in short-term interest rates by the central bank quickly leads to changes in market short-term interest rates. This leads to changes in bank lending: it is this “credit channel” that tends to be emphasised in most central banks. There may or may not be an impact on long-term interest rates resulting from this change in short-term interest rates, depending on how the markets believe future short-term interest rates will be affected by the change to short-term rates (ibid page 4). The direct effect of monetary policy on asset prices is deemed as being through this channel of long-term interest rates. Also, the Bank of England argues, firms benefit from increased cash flow as a result of lower interest rates being paid on short-term debt. Thus lower interest rates could raise company profits directly. Profits could also rise, after a short time lag, as a result of increases in consumer spending. These factors, in turn, may affect equity values.
Thus, this description of the transmission mechanism – more or less bypassing both the role of money and asset markets – is clearly compatible with the neo-classical/new-Keynesian synthesis. Even the combination of the effects described would suggest a comparatively minor impact of monetary policy on asset prices. The direction of the impact on long-term interest rates resulting from changes in short-term interest rates is ambiguous – as the Bank of England's paper points out – and may well be small. Unless there is reason to believe that a change in interest rates is permanent or will have effects on long-term interest rates for other reasons, in this model the long-term cost of equity capital and the real interest rates that would be used for the valuation of long-term investments would be little changed. As such the impact of a change in monetary policy on bond and equity markets would be minor. Any change that does arise is indirect and results directly from changes in interest rates and not from changes in financial institutions’ holdings of money.
Indeed, Monetary Policy Committee (1999) seems to suggest on page 9 that there may be no significant and systematic influence of monetary policy on asset prices: “We have mentioned that monetary policy changes have only indirect effects on interest rates on long-term bonds…The effects on the cost of equity finance are therefore also indirect and hard to predict.” This is particularly likely to be the case if the central bank is following an inflation target and is expected to be successful in hitting the inflation target. Fluctuations in short-term interest rates are then likely to be non-systematic and to have limited implications for long-term rates.
There is an emphasis in the Bank of England model on rational expectations together with a tendency to play down the way in which the transmission of monetary policy affects asset values. It is also compatible with the credit channel of monetary transmission where the main effect of a change in short-term interest rates is on bank lending and the real economy. Changes in asset prices follow the impact of changes in monetary policy on the real economy. The publication shows quite vividly how the Bank of England's own monetary models downplay the role of money (see page 10 onwards) – including the role of money on asset prices – to a greater extent than the immediate past Governor of the Bank of England himself would perhaps regard as desirable.
The US Federal Reserve, like the Bank of England's Monetary Policy Committee, does not have a “house view”. However, the general view – and especially that of the Chairman of the Board, Ben Bernanke – is not unlike that of the Bank of England. Bernanke and Gertler (Reference Bernanke and Gertler2000), for example, discuss monetary policy and asset price volatility. They argue that asset prices are an important determinant of economic activity. However, insofar as asset prices are assumed to deviate from fundamentals in their model, this is not because of the influence of monetary policyFootnote 24. Bernanke and Gertler imply that asset prices should be ignored in monetary policy making because monetary policy has no effect on asset prices and, furthermore, that monetary policy is irrelevant as an indicator for those making judgements about financial market values. As has been mentioned above – changes in interest rates, can affect asset prices directly only to a relatively small degree.
The net result is that, whilst not ignoring asset markets to the same extent as the neo-classical and new-Keynesian theories, central banks do not tend to regard either the quantity of money or asset markets as important indicators or channels of monetary policy. Asset markets are assumed to reflect monetary policy changes largely through the credit channel. There are notes of dissent from this general view – not least that of the former Governor of the Bank of England, Mervyn King.
7. Eclecticism, neo-Keynesianism and quantitative easing
This approach to monetary policy that lies at the heart of central banks’ theorising has been a particular problem during the period of “quantitative easing”. Quantitative easing (QE) can be used as a monetary policy tool when short-term interest rates approach their zero lower bound. It effectively involves direct control of the money supply by creating money to purchase assets. Here, the possibility of a relationship between monetary policy and financial markets should be clear. The instrument of monetary policy becomes direct money creation and the instrument is given effect by purchases in asset markets. This relationship has been recognised by the Bank of England (see Bank of England, 2009, pages 16–17). It is highly unlikely that a transmission mechanism involving asset prices will be irrelevant if monetary policy is being practised through the direct purchase of assets.
The relationship between quantitative easing and asset markets is discussed in Benford et al. (Reference Benford, Berry, Nikolov, Young and Robson2009) and Joyce et al. (Reference Joyce, Tong and Woods2011) and the references thereinFootnote 25. Insofar as QE is used to purchase government fixed-interest securities, the process is likely to reduce yields on those securities (and raise their prices) directly, though there can be leakagesFootnote 26. This effect on securities markets is discerned quite strongly in Joyce et al. (Reference Joyce, Tong and Woods2011). Wider effects of QE on asset markets can come from a variety of sources. Firstly, there may be expectations of an improved economic outlook given that the policy would be followed in order to reduce expectations of deflation (or increase expectations of inflation) and to try to reduce the likelihood of recession. This would influence equity and corporate bond prices. Secondly, asset purchases by the central bank are likely to improve market liquidity. If the asset purchase programme includes the purchase of corporate bonds, the programme should certainly lead to liquidity premia on corporate bonds being reduced and Bank of England (2009) suggests that this has, in fact, happened in practice. Thirdly, there will be a “portfolio rebalancing effect”. Non-bank financial institutions will sell assets for money. Non-banks may then have excess money holdings and rebalance their portfolios by purchasing other assets. The reduction in risk-free yields arising from the focus of the programme on gilt markets may lead to investors buying corporate bonds and equities in this rebalancing process. Corporate bond and equity issuance may result from the lower yields. Joyce et al. (Reference Joyce, Tong and Woods2011) find less strong effects of QE on the prices of non-gilt assets, though they recognise the difficulties of identifying the impact of QE on other assets.
One way of thinking about QE is to regard it as a process by which the central bank can operate monetary policy by manipulating longer-term rather than only very short-term interest rates. QE is therefore likely to affect all real assets indirectly insofar as long-term risk-free interest rates underpin the valuation of other assets. QE might also lead markets to expect low short-term interest rates for a longer period of time.
QE may have a negative influence on long-dated conventional bonds if the transmission of QE through asset markets is expected to raise inflationFootnote 27. More generally, the effects on real assets are likely to be different from the effect on conventional bonds.
The ultimate objective of QE is to stimulate the economy by reducing long-term interest rates and to increase investment and consumption in the ways suggested by Mishkin above. Eventually, equilibrium should be restored at a higher level of nominal national income than would otherwise have pertained and asset prices should find fundamental levels again. However, the whole process takes place directly via transactions by the central bank in asset markets which may then lead investors to rebalance their portfolios so that the created money flows into the economy through a wide range of asset market channels. It is therefore highly likely, in this process, that asset channels will be important and that asset markets will be affected before goods markets though models have not been well developed to quantify this effect (see below).
The mechanism by which QE is able to work is described by Congdon (Reference Congdon2010) in a discussion of various types of liquidity trap. There is a crucial prerequisite for the policy to work which relies on non-bank financial companies that sell their assets to the central bank for newly created money not having an infinitely elastic demand to hold money at the prevailing long bond yield. Non-bank financial companies are the main recipients of the money that is created in the QE process and with which assets are purchased. If non-bank financial companies had an infinite desire to hold this money then nothing would change as a result of QE – the central bank would hold the securities they have purchased and the non-bank financial institutions would hold the money that the central bank created and there would be no further transactions. The success of QE relies on the desire of non-bank financial companies to use the newly created money to rebalance their portfolios and buy assets – corporate bonds, shares, government bonds, and so on. Those who argue that QE will not achieve its objective base that belief on the assumption that risk averse investors will not want to hold long-term bonds because of the risk that long-term interest rates, once they have hit very low levels, will rise. Essentially, this is the liquidity trap of Keynes (Reference Keynes1936) in its broadest definition. The assumption of such a broad liquidity trap would seem to ignore the reality facing long-term investors. The greatest risk for them – given their long-term liabilities – is that of holding cash when long-term interest rates fall (or when equity values rise if unit linked funds are not fully invested). Thus, whilst the liquidity trap envisaged by Keynes is not impossible, it is implausible when one considers the risks faced by long-term investors.
The focus of central banks’ conventional economic models is not well suited to modelling the effects of QE on assets markets and the wider economy. However, there has been work published recently that examines the effect of QE on asset markets. Both Joyce et al. (Reference Joyce, Lasaosa, Stevens and Tong2010) and Joyce et al. (Reference Joyce, Tong and Woods2011) recognise the various possible channels by which QE can affect asset markets that are described above. In Joyce et al. (Reference Joyce, Lasaosa, Stevens and Tong2010) models were used to try to separate the portfolio rebalancing effects (effectively transmission mechanism effects) from the liquidity and broader macro-economic effects of QE. The margins of error surrounding the estimates were very large. The authors are able to conclude that a significant factor in the fall in conventional gilt yields during the period of QE was portfolio rebalancing. However, with regard to other assets, they argued: “it is difficult to disentangle the specific impact of QE purchases from other factors” (page 38) and “our econometric evidence suggests considerable uncertainty about the size of the impact, particularly regarding the impact on equity returns” (page 38). Joyce et al. (Reference Joyce, Tong and Woods2011) suggested effects on output and inflation of the QE that had taken place up to that time of roughly equivalent to a 1.5% to 3% cut in base rates – though with considerable uncertainty surrounding this.
8. Austrian business cycle theory – the central role of investment markets
Austrian theories of monetary policy are not widely taught in standard economics courses. In the eyes of quantitative neo-classical and neo-Keynesian economists who dominate university departments and central banks, Austrian theories suffer from the difficulty that they cannot easily be used for prediction and cannot easily be empirically verified (see de Soto, Reference De Soto2008, for a comparison of the Austrian and neo-classical methods and research agendas). However, these observations do not render the Austrian theories invalidFootnote 28.
Austrian ideas are interesting in the context of this discussion because they explore links between monetary policy mistakes and financial markets that are only implicit in the analysis of other schools of thought. Furthermore, many of the other theoretical frameworks have strong Austrian aspects to them even though these are not formally acknowledged. Credibility is lent to the Austrian understanding of monetary theory by the Nobel Prize citation for F. A. HayekFootnote 29:
“…von Hayek's contributions in the field of economic theory are both profound and original. His scientific books and articles in the twenties and thirties aroused widespread and lively debate. Particularly, his theory of business cycles and his conception of the effects of monetary and credit policies attracted attention and evoked animated discussion. He tried to penetrate more deeply into the business cycle mechanism than was usual at that time. Perhaps, partly due to this more profound analysis, he was one of the few economists who gave warning of the possibility of a major economic crisis before the great crash came in the autumn of 1929.
von Hayek showed how monetary expansion, accompanied by lending which exceeded the rate of voluntary saving, could lead to a misallocation of resources, particularly affecting the structure of capital. This type of business cycle theory with links to monetary expansion has fundamental features in common with the postwar monetary discussion.”
This has obvious relevance to the theme of this paper and it is also noteworthy that F. A. Hayek is the second most frequently cited Nobel Laureate (after Kenneth Arrow) in the Nobel lectures of other Nobel Laureates (see Skarbek, Reference Skarbek2009).
8.1 Austrian monetary theory in outline
Those aspects of Austrian monetary theory that relate monetary policy to financial markets are stated in von Mises (Reference Von Mises1981)Footnote 30. The basic idea is that an expansion of credit by the central bank, achieved by holding interest rates below the level that would prevail as a result of the interplay of supply and demand in the market for savings and investment funds, will lead business people to borrow and invest in more capital-intensive production processes. Modern variants of the theory would also emphasise how holding interest rates low would lead households to spend more on goods that have an investment characteristic such as housing and consumer durablesFootnote 31. Von Mises (Reference Von Mises1981, chapter 19, part 4) explains as follows: “Now if the rate of interest on loans is artificially reduced below the natural rate as established by the free play of the forces operating in the market, then entrepreneurs are enabled and obliged to enter upon longer processes of production.” These theories were then developed with a greater degree of rigour and formalism by Hayek (Reference Hayek1931) and Hayek (Reference Hayek1941).
Inappropriate monetary policy involves the distortion of a price – the rate of interest – which should coordinate the supply of and demand for savings and funds for investment. In the absence of central bank manipulation, interest rates would rise, for example, if there were an increase in demand for funds for investment – as a rise in interest rates would be necessary to draw more savings into the market and to discourage marginal borrowersFootnote 32. If interest rates are held below this equilibrium level by the central bank, there will be an expansion of the money supply and, encouraged by low interest rates, consumers and businesses will spend more on consumer durables and investment projects. This process would explain how “property booms” are often associated with “monetary booms”.
So far, there are similarities between these processes and aspects of the monetarist transmission process. However, for our purposes, there are two important differences between the monetarist and Austrian schools. Firstly, in the period of monetary expansion, the distortion of investment and consumption decisions by interest rates that are too low is the key problem: for monetarists, the possibility that the transmission mechanism might give rise to such distortions is secondary to other considerations. Secondly, Austrians would argue that a recession must follow a monetary boom. This is because the investment projects that have been started in the boom (property building, investment in more capital-intensive production methods, the purchase of consumer durables and so on) either cannot be completed or must be reversed: resources have been misallocated as a result of interest rates being held down and, eventually, this misallocation has to be reversed. This reversal is the process of recession. Thus, whilst both neo-classical economists and monetarists may believe that recession can be more-or-less avoided, even after monetary policy mistakes that have led to a boom, as long as appropriate policies are followed, Austrian economists would not accept this. For Austrians, there is an inevitable contraction after the boom.
As has been noted, and as is clear from the neo-classical model, an increase in saving can also cause a fall in interest rates, a rise in stock market values and a rise in real investment: interest rates are not only affected by monetary policy. However, de Soto would argue (see de Soto Reference De Soto2006, page 459–466) that an increase in genuine saving will generally be insufficiently rapid to cause a stock market to rise rapidly in a bubble-like fashion. There may be a once-and-for-all increase due to real factors but not a continuing boom. On the other hand, a rise in the money supply, which leads to an increase in asset prices can be as rapid as the central bank permitsFootnote 33.
There are several mechanisms by which the rise in money supply can feed into stock market values according to Austrian thinking. Firstly, interest rates fall relative to the level that would be determined by the interaction of savings and funds demanded for investment. Whilst this generally only applies to short-term interest rates, a fall in short-term interest rates can have many indirect effects on the value of a company, not least because it reduces debt servicing costs: this mechanism is no different from those described above. Furthermore, any prospective rise in the general price level may not only raise the nominal value of a firm's investment projects but also reduce the real value of its debt. The fall in interest rates also encourages more capital-intensive methods of production and this raises the value of capital goods generally (the most visible example being the rise in property values and rents). This, in turn, raises the prices of securities which represent claims on the returns generated by capital goods. Rising stock market values provide collateral for further bank credit which can be used to extend leverage and invest further in the stock market. A continual supply of funds provided by the banking system is necessary to fuel the corresponding stock market boom (see de Soto, Reference De Soto2006 pages 459–466).
Many actuaries, especially those steeped in modern financial economics, would be uncomfortable with the lack of mathematical formalism in the Austrian approach. In response, proponents of Austrian theories would argue that the language of mathematics is too precise to articulate the tendencies and subtleties that economic processes involve. We can say that there is a tendency for stock market prices to rise if savings rise or if monetary policy is loose but exactly how this will manifest itself will depend on the inter-dependent actions of millions of people investing trillions of pounds, all reacting subjectively to the very particular information that they can access whilst many other variables are changing simultaneously. Thus we can explain these tendencies, or produce “pattern predictions” using data to help understand the tendencies better, but we cannot model them with the precision that would satisfy a neo-classical economist. In practice, though, monetary booms in different economic conditions can have apparently unique specific effects, whilst being particular examples of a general phenomenon. This is, perhaps, a testament to the validity of this approach.
There are several lessons from the Austrian school that are important for those working in investment markets. The main ones are as follows:
• Stock market prices will be affected by the volume of saving in an economy or by changes in expectations about productivity.
• However, such real variables are likely to change slowly over time and thus are unlikely to give rise to a rapid rise in market values.
• A rapid rise in stock market prices is likely to be associated with a monetary boom. A rapid rise in stock market values caused by a monetary boom will eventually be reversed but could continue as long as the expansionary monetary policy continues.
• To the casual observer in normal conditions, it may be difficult to distinguish between a rise in the market caused by real factors and a rise caused by monetary factors – unless the rise is very rapid. However an analysis of economic data should reveal the underlying causes, even if precise predictions cannot be made and models built.
8.2 Austrian theory and efficient markets
Actuaries and financial economists may object to these lines of reasoning on the grounds that they violate the efficient markets hypothesis and rational expectations. If market actors can see that a monetary boom is causing a rise in asset prices and that the boom will eventually come to a halt and reverse, then why do fund managers not simply ignore the monetary boom and refuse to invest in the rising stock market? The Austrian response to this is that market participants are not perfectly informed. They are responding to particular information sets that they believe are relevant to their situation. Lower interest rates, rising company profitability, reduced risk premiums because of the perceived rise in the value of collateral that is backing lending and so on, all make it very difficult for private sector actors (entrepreneurs, company managers and fund managers) to distinguish between real factors that affect the stock market and monetary factors. The longer the boom goes on and the greater the extent to which real and monetary factors point in the same directionFootnote 34 the more difficult it is to distinguish between real and monetary factors: there is a large amount of “noise” amongst the information that investors need to use in order to make sound, long-term investment decisionsFootnote 35. This difficultly of distinguishing between the real and monetary causes of price signals that entrepreneurs are receiving is indicated by the description of the late 1980s Swedish property bubble in Dillen and Sellin (Reference Dillen and Sellin2003, pages 132–133). The possible causes identified include high inflation, tax relief, rising incomes and credit market deregulation, as well as loose monetary policy.
9. Monetary policy, financial bubbles and asset price targeting
So far, we have discussed how various theories of monetary policy lead to different conclusions regarding the behaviour of financial markets in response to tight or loose monetary policy. This leads naturally to a discussion of whether monetary policy should respond to or should be used to try to control asset market movements. Since the financial crash of 2008, this issue has come to the fore. This aspect of the relationship between monetary policy and financial markets is an important topic for actuaries. A move towards the central bank having a dual objective would be a move away from inflation targeting. This would have implications for both the expected rate of inflation and the variation of the rate of inflation around the expected rate. Both of these variables are used in actuarial calculations and investment decision making. Furthermore, questions might also be raised regarding the use of market-value accounting approaches in some circumstances if the central bank targeted asset prices.
If it were desired that the central bank were to be influenced in its monetary policy decisions by developments in asset markets, various conditions must hold. It must be believed that monetary policy decisions could affect asset markets (otherwise there would be no point giving monetary policy makers the relevant objectives). Also, it must be believed that asset markets can deviate from some kind of fundamental value towards which monetary policy is able to return them. Finally, it must be believed that central bankers can identify stock-market bubbles and distinguish them from rises in prices caused by real factors. Finally, it must be believed that central bankers can identify stock market bubbles and distinguish them from rises in prices caused by real factors.
9.1 Anti-”bubble-pricking”
On the whole, adherents to the neo-classical view would argue that an environment of low and stable inflation is conducive to avoiding financial bubbles and that price stability should be the target of the central bank. As it happens, though, two major stock-market booms (those of 1923–1929 and 1994–2000) occurred during periods when consumer price inflation was relatively low – and the recent financial crash also occurred during an environment of low consumer price inflation. Bordo and Wheelock (Reference Bordo and Wheelock2004) argue that whilst there is no consistent relationship between inflation and stock market booms, such booms ‘have typically occurred when money and credit growth were above average’ (page 19, my italics)Footnote 36. Asset price booms are also, according to Bordo and Wheelock, strongly associated with strong real growth and advances in productivity.
In the neo-classical paradigm, the relationship between asset prices and strong growth in the real economy is especially important. Strong real economic growth, driven by increases in productivity, can lead to (or be driven by) higher returns on capital. This increases returns to equity and has obvious implications for future dividend growth and equity valuations. This hypothesis is perhaps best expressed in the work of Fama who concludes (Fama, Reference Fama1981, pages 563–564): “Stock returns are determined by forecasts of more relevant real variables and negative stock return-inflation relations are inducted by negative relations between inflation and real activity…[E]xpected real returns are determined in the real sector”.
In practice, even if some link between monetary policy and asset prices is accepted, it can be difficult to distinguish between real, monetary and speculative contributions to an asset price bubble. The neo-classical models in particular see little room for the analysis of asset prices in the determination of monetary policyFootnote 37. Using monetary policy to ‘burst’ a bubble that is caused by real factors can have significant dangers for the real economy – leading to recession and deflation (see Goodfriend, Reference Goodfriend2002 pages 186–187).
Following this reasoning, the orthodox central banking view is sceptical of the “bubble pricking” approach. Bernanke's views on this are well known and have been expressed in Bernanke and Gertler (Reference Bernanke and Gertler2000 pages 3–4)Footnote 38:
“Our view is that, in the context of short-term monetary policy management, central banks should view price stability and financial stability as highly complementary and mutually consistent objectives, to be pursued within a unified policy framework. In particular, we believe that the best policy framework for attaining both objectives is a regime of flexible inflation targeting…Importantly for present purposes, it also implies that policy should not respond to changes in asset prices, except insofar as they signal changes in expected inflation. Trying to stabilize asset prices per se is problematic for a variety of reasons, not the least of which is that it is nearly impossible to know for sure whether a given change in asset values results from fundamental factors, non-fundamental factors, or both. It [focusing on actual inflation] also avoids the historically relevant risk that a bubble, once “pricked”, can easily degenerate into a panic.” (italics in original).
Bean (Reference Bean2003) made a very similar argument. The inflation target is sufficient in Bean's view and it does not preclude policymakers from taking asset price developments into account in their models.
Furthermore, as has been noted above, increases in asset prices can take place as a result of an increase in the supply of credit rather than in the supply of money (Borio et al., Reference Borio, Kennedy and Prowse1994). Such asset price “booms” can be rational if the liberalisation of credit has made behaviour possible that was previously restricted. Nevertheless, Borio et al. do suggest that asset markets can provide some information about future inflation and thus asset price information might be useful when setting monetary policy – though they reject the use of hard and fast rules. In later work (Borio and White, Reference Borio and White2004, page 33), it is suggested that:
“On the monetary side, it would imply being alert to the possibility that financial imbalances can also build up when inflation is low and stable and standing ready, occasionally, to lean against those imbalances as they develop even if near-term inflation pressures are not apparent. Current frameworks should be capable of accommodating such a monetary policy response. In most cases, a lengthening of the policy horizon and greater attention to the balance of risks in the formulation of policy may be all that is required.”
Goodhart and Hofmann (Reference Goodhart and Hofmann2003) use a vector auto-regressive model to examine the effect of monetary policy and credit growth on asset prices. They do not deny the basic monetarist position regarding the importance of monetary policy for asset prices. However, they conclude (page 10):
“Moreover, the effects of interest rate movements on asset prices and bank lending are most likely to be highly non-linear. During the boom, general euphoria will most likely lower the sensitivity of asset valuations and lending to interest rate hikes. Once market sentiment changes, investors realise how high interest rates have gone, triggering a sharp reversal in asset prices…Given that the driver of non-linearity, market sentiment, is unobservable, the usefulness of interest rate policy as an instrument to safeguard financial stability is in doubt.”
The authors also stress the potentially catastrophic effects of a decision to “burst” an “asset bubble” being mistimed, citing the examples of both the Great Depression and the Japanese malaise. Even if the asset price channel for the transmission of monetary policy is accepted it does not follow that the targeting of asset prices by monetary policy markers is appropriate.
9.2 Asset price information in the monetary policy framework
A situation whereby there is an increase in asset prices associated with loose monetary policy whilst, at the same time, increases in consumer prices remain low, is most consistent with monetarist and Austrian theories. According to these theories, as explained above, loose monetary policy has a tendency to feed into asset prices via its impact on real interest rates before it feeds into general inflation. The more the central bank is able to credibly commit to low consumer price inflation, the more any impact of loose monetary policy on consumer prices will be delayed with the impact on asset prices being the main manifestation.
According to both the monetarist and Austrian views, high asset prices can be a ‘signal’ of loose monetary policy – that is they provide information to monetary policy makers in the same way that currency movements might provide information about loose monetary policy in an international monetarist model. Monetarists such as Congdon, who emphasise the role of asset markets in the transmission mechanism, would also associate their ideas with post-Keynesian theories whereby an increase in money leads to a substitution of money for liquid assets (for example short-dated bonds) and then a series of portfolio rebalances that leads to an increase in the prices of less liquid assets (see Tobin, Reference Tobin1969 and Brunner and Meltzer, Reference Brunner and Meltzer1973).
However, even according to the Austrian and monetarist views of monetary policy, asset price targeting by a central bank would not be an appropriate policy objective. Once an asset price bubble has built up due to loose monetary policy, there is nothing that can be done to alleviate the problems loose monetary policy has caused. Action needs to be taken to set monetary policy back on a sustainable course. Asset price booms are merely consequential in nature resulting from the previously lax monetary policy.
As has been noted, the Bank of England has tended to take an eclectic approach to monetary policy with a macro-model that does not model money supply measures directly but one that uses a broad range of economic variables. As has also been discussed above, the Bank regards asset prices as an aspect of the transmission mechanism and thus asset price movements might provide information about how loose monetary policy is. Movements in certain asset prices (particularly index-linked and conventional gilt yields) also provide the Bank with information about the market's confidence that the inflation target retains credibility. This information has been used by the Bank of England and commented on publicly since the second quarterly inflation report in May 1993.
Alchian and Klein (Reference Alchian and Klein1973) approach this subject from a slightly different perspective. They argue that asset prices should be taken directly into account in setting monetary policy goals. Alchian and Klein point out that, given that asset prices are the price of future consumption, they should be taken into account along with the price of present consumption (and given an appropriate weighting) when setting monetary policy. Specifically, according to Alchian and Klein, the utility that a household obtains from consumption is:
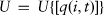 $$U\, = \,U\{ [q(i,t)]\} $$
Where q(i,t) represents the quantity of the ith consumption service flow at time t. Alchian and Klein also cite the transmission process suggested by many monetarists and which is explicit in Austrian theory. When monetary policy is loosened, this disturbs the term structure of interest rates and, as such, raises asset prices and the price of future consumption before it has an impact on general consumer prices. Incorporating asset prices in the price index would therefore have the incidental advantage of leading the central bank to react to inflationary pressures earlier as well as fundamentally taking a more comprehensive view of inflation. As has been widely noted, even the current user cost of housing was explicitly excluded from the price index targeted by the Bank of England from 2003. If the targeted index excludes those items that respond most rapidly to monetary stimuli then monetary policy responses will be delayed. Perhaps the most obvious application of the Alchian and Klein suggestion – the wider application of which is fraught with practical difficulties as the authors admitFootnote 39 – is that increases in house prices should be incorporated in prices indices targeted by central banks. This should lead to the taming of asset price booms at an earlier stage in their development.
Thus, two distinct reasons for taking asset prices into account when setting monetary policy have been identified here. Asset prices might lead monetary policy makers to anticipate increases in consumer prices which were preceded by increases in asset prices. Secondly, it can be argued that monetary policymakers should, as a matter of principle, take a wider view of inflation that takes into account the price of future consumption. However, in neither case are authors arguing that central banks should try to prick irrational asset price bubbles because such bubbles are harmful in themselves.
9.3 “Leaning against the wind” and “bubble pricking”
Other authors, such as Wadhwani and Cecchetti would go further and suggest that monetary policy should explicitly take into account developments in asset markets even if those developments are not caused by loose monetary policy. This is often described as “leaning against the wind”. There is a particularly good discussion of this approach in Wadhwani (Reference Wadhwani2008) and in Cecchetti et al. (Reference Cecchetti, Genberg and Wadhwani2002).
The argument is essentially made in a neo-classical/new-Keynesian framework. Wadhwani suggests that, if inflation is forecasted in an output gap model (that relies on modelling the difference between actual and potential output), this essentially ignores the role that asset prices play in the real economy. Asset bubbles, according to Wadhwani, raise consumption and investment and, importantly, can arise exogenously. In developing appropriate policy responses, we can distinguish between three situations. If asset prices rise due to a productivity shock the central bank should not react as asset prices are simply reflecting fundamentals, argues Wadhwani. If asset prices rise due to loose monetary policy, then the central bank should react but Wadhwani's view does not add anything to the approaches suggested by monetarists and others as explained in 9.2. However, if a bubble arises simply because of the behaviour of investment-market participants but is not driven by fundamentals then the central bank should take this into account when setting monetary policy. Given that asset-price bubbles raise consumption and investment, the argument proceeds that, if a Taylor rule were being followed whereby interest rates depend on inflation relative to a target and output relative to potential, this should be adjusted if there is a bubble.
The proponents of leaning against the wind argue that their proposal simply adds an extra element into the models that are used to forecast inflation and, in particular, that this element is especially important in understanding the evolution of inflation over long-term time horizons. The contrary argument is that the central bank cannot distinguish between investment market fluctuations caused by (for example) a change in productivity and those caused by other factors. The proponents of leaning against the wind counter that, if the central bank is controlling monetary policy, it has to make judgements about many matters in economic models – including developments in the non-financial part of the real economy (see Cecchetti et al., Reference Cecchetti, Genberg and Wadhwani2002 in particular). As such, making judgements about the causes of a bubble is no different. The Austrian and monetarist response to the leaning against the wind approach would be that prolonged bubbles tend to be caused by mistaken monetary policy which should, indeed, be corrected. It would then be cautioned that going further and reacting to bubbles that are not caused by loose monetary policy but by herding and speculative behaviour in financial markets is simply likely to lead to further policy mistakesFootnote 40.
Roubini (Reference Roubini2006) goes further and argues that, if monetary policy can affect asset prices then, given the serious problems that arise when bubbles burst, central banks ought to anticipate their bursting. Monetary policy should therefore be used in order to contain, reverse or burst bubbles early that are developing in asset markets. There is a subtle difference between this view and the Cecchetti/Wadhwani view in that Roubini proposes that the purpose of monetary policy should be the reversal of the asset-price bubble, rather than the existence of the bubble being an extra part of the information set used by central banks.
9.4 Asset prices and the conduct of monetary policy – concluding thoughts
Between them the “leaning again the wind” view, the Alchian and Klein thesis, the Austrian/monetarist interpretation and the “bubble pricking” view of the role of asset prices in monetary policy represent a substantial body of opinion. The “leaning against the wind” approach probably represents the greatest challenge to central bank orthodoxy at the current time. However, as the quotation above from Borio and White (2003) suggests, a central bank using a comprehensive model of the real economy and financial sector and a medium-term inflation forecasting framework with a flexible time horizon, may not, in practice, deviate far from a “leaning against the wind” approachFootnote 41.
All the approaches to giving asset market information a greater role in monetary policy setting have implications for actuaries:
• The schools of thought that propose a greater role for asset prices in monetary policy setting would argue that the efficient markets’ hypothesis should be qualified, at least.
• In one way or another, all these approaches posit a relationship between monetary policy and asset values and thus suggest that asset values might deviate from long-run fundamentals dictated by the real economy. This raises the issue of whether accounting conventions and regulations for going concerns should necessarily always be based on market values.
• The “bubble pricking”, “leaning against the wind” and Alchian/Klein view suggest a wider role for asset prices in monetary policy. Such a wider role would change the context of inflation targeting as currently followed by many central banks and, potentially, change the transmission mechanism and the relationship between current policy and inflation expectations.
• If a central bank took asset values into account when setting monetary policy and the above theories were correct, this action would reduce asset price volatility which would have implications for long-term asset-value modelling. If central banks were able to successfully reduce volatility in investment markets there would, of course, be wider benefits. However, if markets are broadly efficient and real factors tend to determine investment values, and/or central bankers are not able to distinguish increases in investment values caused by real factors and those caused by other factors, central banks could raise asset price volatility if they used monetary policy to attempt to “stabilise” asset markets.
10. Conclusion
An understanding of the way in which monetary policy affects financial markets is important for actuarial practitioners and researchers for several reasons. As we have seen, depending on the circumstances, asset markets could be affected by monetary policy changes in various different ways. An understanding of monetary transmission mechanisms, and the possibility of asset-market bubbles being induced by monetary policy, might well be important when taking short-term asset allocation decisions. Of course, different theories have different implications with the neo-classical/new Keynesian synthesis suggesting that monetary policy has a relatively minor effect on asset prices.
Secondly, there is the question of whether stochastic models used for actuarial purposes should take into account the fact that monetary policy might affect asset values. It might be argued that monetary policy is just one economic factor amongst many that affect financial markets and that statistical evidence should determine the structure of stochastic models. However, some of the theories discussed above suggest that there could be a predictable and systematic component to asset price changes as a result of monetary policy changes. Furthermore, the operation of monetary policy is not just one economic factor amongst many but a highly discretionary instrument operated by a single economic agent. The effects can be radically different from those arising from random disturbances to asset prices due to the discovery of new information. If there has been a period of very loose monetary policy and asset prices are inflated as a result, capital within a financial institution could be over-estimated (and the amount of capital that needs to be held for a given probability of insolvency under-estimated) if stochastic models based on the efficient markets hypothesis are used. There are various ways of taking account of these effects, one of which is to incorporate monetary policy indicators directly into models that have a wider econometric framework. Alternatively, monetary factors could be taken into account when interpreting the results of modelling.
Of course, management must make judgements regarding a whole range of factors when it takes asset allocation and economic capital decisions. Increasingly, regulatory requirements are dominating the determination of capital and also the publication of financial information by institutions such as pension funds and insurance companies. Also, there is an increasing trend towards using a market valuation of assets for insurance company and pension fund accounts and for setting regulatory capital for insurance companies. If, as a result of the transmission mechanism of monetary policy, asset values are driven away from values that reflect fundamental economic information it could be argued that capital requirements could be set too high or too low. Certainly, the operation of monetary policy can be identified as one of the risks that faces a financial institution and one of the uncertainties that surrounds quoted financial results.
It could be argued that uncertainty about whether asset valuations are distorted by monetary policy is simply one of many uncertainties against which an institution holds capital. Nevertheless, consideration of the role of monetary policy raises the issue of the extent to which it is reasonable to use judgement when presenting financial information. There has been a move towards “objective” approaches to asset and liability valuation in recent years. It is possible that we have a false sense of security in such mechanisms. A separate, but related, issue that arose during the 2008 financial crisis was the way in which asset values were distorted by the drying up of liquidity within markets. Haldane (Reference Haldane2010) discusses this problem but still concludes that the “sunlight” of fair value accounting using market values is better than the alternative even if that sunlight should be filtered to screen out the harmful rays (page 21)Footnote 42. Insofar as judgement is exercised it is, of course, easier to apply in management situations, such as when determining the rate of funding of a pension scheme, or the amount of economic capital an institution holds than when financial institutions are publishing accounts for statutory and tax purposes.
Actuaries should also be aware of the way in which changes in monetary policy regimes can change the way in which the transmission mechanism operates. If, for example, some form of formal or informal asset price targeting were developed, this may well change the dynamics of asset markets as markets came to use pricing information to anticipate changes in monetary policy. Such a policy may, under certain assumptions, also increase the variability of inflation. This will clearly have implications for the risks implied in limited-price-indexed contracts.
Much progress has been made in recent years to ensure that equilibrium theories of capital markets are properly integrated into actuarial thinking. However, it is important for actuaries to retain a sense of how markets might behave when equilibrium is disturbed. It is also important to understand the economic processes that characterise a move from one equilibrium position to another. As has been seen, actuaries have made an important contribution in the past to the understanding of the relationship between monetary policy and financial markets. This is an aspect of our discipline that should not be neglected.


