


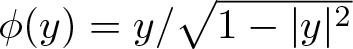
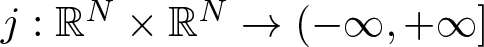


1. Introduction
In this note, we deal with the existence and multiplicity of solutions for potential systems having the form
 \begin{equation}
-\left[ \phi(u^{\prime}) \right]^{\prime} = \nabla_u F(t,u),\quad \mbox{in } [0,T],
\end{equation}
associated with the potential multivalued boundary condition
 \begin{equation}
\left ( \phi \left( u^{\prime }\right)(0), -\phi \left( u^{\prime }\right)(T)\right )\in \partial j(u(0), u(T)),
\end{equation}
where  $\phi:\mathbb{B}_1 \to \mathbb{R}^N$ is the homeomorphism given by
 \begin{equation*}
\displaystyle \phi(y)=\frac{y}{\sqrt{1- |y|^2}}, \quad y\in \mathbb{B}_1,
\end{equation*}
and the following hypotheses hold:
(HF)
 $F=F(t,u):[0,T] \times \mathbb{R}^N \to \mathbb{R}$ is continuous,
$\nabla_u F$ exists and is continuous on the set
$[0,T] \times \mathbb{R}^N$ and
$F(\, \cdot \, , 0_{\mathbb{R}^N})=0$;


(Hj)
$j:\mathbb{R}^N \times \mathbb{R}^N \rightarrow (-\infty, +\infty]$ is proper, convex, lower semicontinuous,
$j(0_{\mathbb{R}^N\times \mathbb{R}^N})=0$ and
$0_{\mathbb{R}^N \times \mathbb{R}^N}\in \partial j (0_{\mathbb{R}^N \times \mathbb{R}^N})$.


Here and hereafter,  $\mathbb{B}_r$ denotes the open ball of radius r centred at the origin in
 $\mathbb{R}^N$ – considered with the Euclidean norm
 $|\cdot|$ and the corresponding usual inner product
 $\langle \cdot | \cdot \rangle$, and
 $\partial j$ stands for the subdifferential of j in the sense of convex analysis [Reference Rockafellar12]. The relativistic operator
 $u \mapsto \left[ \phi(u^{\prime}) \right] ^{\prime}$ entering in equation (1.1) occurs in the dynamics of special relativity [Reference Bergmann2, Reference Landau and Lifchitz9]. So, for N = 3, it is involved in equations describing the motion of some mechanical systems when the Newtonian acceleration is replaced by the relativistic one (with the velocity of light normalized to 1). This study is motivated by the recent paper [Reference Jebelean3]. Therein, making use of the critical point theory for convex, lower semicontinuous perturbations of C 1-functionals, a variational formulation is provided for problem (1.1)-(1.2). Then, taking advantage of this key step, the existence of minimum energy as well as saddle-point solutions of the problem are obtained. Recall, by a solution of (1.1)-(1.2) we mean a function
 $u\in C^{1}:=C^{1}(\left[ 0,T \right]; \mathbb{R}^N)$ with
 $| u^{\prime}(t)| \lt 1$ for all
 $t\in [0,T]$, such that
 $\phi(u^{\prime })\in C^{1}$,
 $(u(0), u(T))\in D\left(\partial j\right)$ and which satisfies (1.1) and (1.2).
For a more detailed discussion on some recent advances in the qualitative study of systems of type (1.1) associated with various concrete boundary conditions such as Dirichlet, Neumann or periodic, as well as the generality of the boundary condition (1.2), we refer the reader to [Reference Jebelean3] (also see [Reference Jebelean and Șerban8]) and the references therein.
Our concern here is twofold. First, we refer to finite or infinite multiple pairs of solutions when F and j are even. Thus, we extend in Theorems 3.2 and 3.3 known results in the particular autonomous case of Dirichlet, Neumann and periodic conditions from [Reference Jebelean and Precup5] (also see [Reference Jebelean and Șerban6]), to the nonautonomous system (1.1) associated with the general potential boundary condition (1.2). Second, we prove the existence of N + 1 geometrically distinct solutions to a problem of type (1.1)-(1.2) when F is periodic, j is in some sense invariant under translations and bounded on its domain D(j) (see Theorem 4.1). We thus generalise results known for the periodic problem [Reference Jebelean, Mawhin and Șerban4, Reference Mawhin10, Reference Bereanu and Jebelean1].
The rest of the paper is organised as follows. Section 2 is devoted to the variational approach to the problem. An existence result is also provided herein. In Section 3, we obtain finitely and infinitely many solutions for (1.1)-(1.2) when both F and j are even. Section 4 is concerned with the multiplicity of geometrically distinct solutions.
2. Variational solutions
For the convenience of the reader, we first briefly recall some notions and results in the frame of critical point theory for convex, lower semicontinuous perturbations of C 1-functionals due to Szulkin [Reference Szulkin13].
Let  $(Y, \| \cdot \|)$ be a real Banach space and
 $I:Y \to (-\infty, +\infty]$ be a functional of type
 \begin{eqnarray}
I=\psi+\mathfrak{F},
\end{eqnarray}
where  $\mathfrak{F} \in C^1(Y,\mathbb{R})$ and
 $\psi:Y \to (-\infty, +\infty]$ is proper, convex and lower semicontinuous. An element
 $u\in D(\psi)$ is said to be a critical point of I if it satisfies
 \begin{equation*}\langle \mathfrak{F}'(u), v-u \rangle+\psi(v)-\psi(u) \geq 0, \quad \mbox{for all } \ v\in D(\psi).\end{equation*}
A sequence  $\{u_n\}\subset D(\psi)$ is called a (PS)-sequence if
 $I(u_n)\to r\in\mathbb{R}$ and
 \begin{equation*}\langle \mathfrak{F}'(u_n), v-u_n \rangle+\psi(v)-\psi(u_n) \geq -\varepsilon_n \|v-u_n\|, \quad \mbox{for all } \ v\in D(\psi),\end{equation*}
where  $\varepsilon_n \to 0$. The functional I is said to satisfy the (PS) condition if any (PS)-sequence possesses a convergent subsequence in Y.
Let Σ be the collection of all symmetric and closed subsets of  $Y\setminus\{0\}$. The Krasnoselskii genus of a nonempty set
 $A\in \Sigma$ – denoted
 $\gamma(A)$, is defined as being the smallest integer k with the property that there exists an odd continuous mapping
 $h:A\to\mathbb{R}^k\setminus\{0\}$. If such an integer does not exist, then
 $\gamma(A):=+\infty$. If
 $A\in \Sigma$ is homeomorphic to
 $S^{k-1}$ (k − 1 dimension unit sphere in the Euclidean space
 $\mathbb{R}^k$) by an odd homeomorphism, then
 $\gamma(A)=k$ (see e.g. [Reference Rabinowitz11, Corrolary 5.5]). The following theorem is an immediate consequence of [Reference Szulkin13, Theorem 4.3].
Theorem 2.1. Let  $I$ be of type (2.1) with
 $\mathfrak{F}$ and ψ even. Also, suppose that
 $I$ is bounded from below, satisfies the (PS) condition and
 $I(0)=0$. If there exists a nonempty compact symmetric subset
 $A\subset Y\setminus \{0 \}$ with
 $\gamma(A)\geq k$, such that
 \begin{equation*}\sup_{v\in A} I(v) \lt 0,\end{equation*}
then the functional  $I$ has at least
 $k$ distinct pairs of nontrivial critical points.
Let  $\mathrm{G}$ be a subgroup of Y and denote by
 $\pi:Y\to Y/\mathrm{G}$ the canonical projection. A function
 $\ell$ defined on Y is called
 $\mathrm{G}$-invariant if
 \begin{equation*}\ell(u+g)=\ell(u),\quad \mbox{for all } u\in Y \mbox{and } g\in \mathrm{G}.\end{equation*}
If  $\ell :Y \to \mathbb{R}$ is a differentiable and
 $\mathrm{G}$-invariant functional, then
 $\ell'$ is also
 $\mathrm{G}$-invariant. This implies that, if
 $\mathfrak{F}$ and ψ are
 $\mathrm{G}$-invariant and u is a critical point of I in (2.1), then
 $\pi^{-1}(\pi(u))$ is a set of critical points of I. In this case, the set
 $\pi^{-1}(\pi(u))$ is called a critical orbit of I.
The following result is proved in [Reference Bereanu and Jebelean1, Theorem 7.1].
Theorem 2.2. Let  $\mathrm{G}$ be a discrete subgroup of
 $Y$ with
 $\mbox{span}\, \mathrm{G} = \mathbb{R}^d$ and
 $\widetilde{Y}$ be a closed subspace of
 $Y$ with
 $Y=\mathbb{R}^d\oplus \widetilde{Y}$. So, any
 $v\in Y$ can be uniquely decomposed as
 \begin{equation*}
v=\overline{v}+\widetilde{v}, \quad \mbox{with }\overline{v} \in \mathbb{R}^d\, \mbox{and }\,\widetilde{v} \in \widetilde{Y}.
\end{equation*}
In addition, assume that:
(A 1)
$\mathfrak{F}$ and ψ are
$\mathrm{G}$-invariant,
$\mathfrak{F}'$ takes bounded sets into bounded sets and
$D(\psi)$ is a closed nonempty set;


(A 2)
$\psi(0)=0$ and
$\psi(v)=\psi(\tilde{v})$, for all
$v\in Y$;


(A 3) there exist ρ > 0 such that
\begin{equation*}\|\tilde{v}\|\leq\rho,\ \ |\psi(v)|\leq\rho,\quad \mbox{for all } v\in D(\psi);\end{equation*}

(A 4) any sequence
$\{v_n\}\subset D(\psi)$ with
$\{\overline{v}_n\}$ bounded, has a convergent subsequence.


Then functional  $I$ in (2.1) is bounded from below and has at least d + 1 critical orbits.
Next, by  $\| \cdot \| _{\infty}$, we denote the sup-norm on
 $C:=C([0,T]; \mathbb{R}^N)$ and the usual norm on
 $L^p:=L^p([0,T]; \mathbb{R}^N)$ will be denoted by
 $\| \cdot \|_{L^p}$ (
 $1\leq p \leq \infty$). The Sobolev space
 $W^{1, \infty}:=W^{1, \infty}([0,T]; \mathbb{R}^N)$ will be considered as being endowed with the norm
 $\|u\|_{W^{1, \infty}}=\|u'\|_{L^\infty}+\|u\|_{L^\infty}.$ The following variational formulation of problem (1.1)-(1.2) is introduced in [Reference Jebelean3]. Let
 \begin{equation*}
\mathcal{K}:= \left \{v \in W^{1, \infty}\, : \, \|v^{\prime}\|_{_{L^{\infty}}}\leq 1 \right \}
\end{equation*}
and  $\Psi:C \to (-\infty , +\infty]$ be defined by
 \begin{equation}
\Psi(v):=\displaystyle \left\{
\begin{array}{ll} \displaystyle
\int_0^T \left [1-\sqrt{1-|v'|^2}\right ] , & \hbox{if}\ v\in {\mathcal K}; \\
\\
+\infty, & \hbox{otherwise}.
\end{array}
\right.
\end{equation}
The convex set  $\mathcal{K}$ is closed and Ψ is proper, convex and lower semicontinuous. Also, since j is proper, convex and lower semicontinuous, the same holds true for
 \begin{equation}
J:C \to (-\infty , +\infty ], \qquad J(v):=j(v(0),v(T)), \quad v\in C.
\end{equation}
On account of hypothesis  $(H_{F})$, the mapping
 \begin{equation*}{\mathcal F}:C \to \mathbb{R}, \qquad {\mathcal F}(v):=-\int_0^TF(t,v)dt, \quad v\in C\end{equation*}
is of class C 1 on C and its derivative is given by
 \begin{equation*}\langle {\mathcal F}^{\prime} (u),v \rangle= -\int_0^T \langle \nabla F(t,u) |v \rangle dt, \quad u,v\in C.\end{equation*}
Then, the energy functional  ${\mathcal I}:C \to (-\infty , + \infty ]$ associated to problem (1.1)-(1.2) will be
 \begin{equation}
{\mathcal I}:=\Psi + J + {\mathcal F}
\end{equation}
and notice that it fits the structure required by Szulkin’s critical point theory with Y = C,  $\psi=\Psi + J$ and
 $\mathfrak{F}=\mathcal F$. Thus, accordingly, an element
 $u\in D(\Psi + J)$ is called critical point of
 ${\mathcal I}$ in (2.4) if it satisfies
 \begin{equation}
(\Psi + J)(v)-(\Psi + J)(u) + \langle {\mathcal F}^{\prime} (u),v-u \rangle \geq 0, \quad \mbox{for all }v \in D(\Psi + J).
\end{equation}
From [Reference Jebelean3, Theorem 3.2] one has that any critical point of  ${\mathcal I}$ is a solution of problem (1.1)-(1.2).
Further, we introduce the first eigenvalue-like constant
 \begin{equation*}
\lambda_1=\lambda_1(j):= \inf \left \{\frac{\|v^{\prime} \|_{L^2}^2}{\|v \|_{L^2}^2} \, : \, v\in D(\Psi+J), \; v \not\equiv 0_{\mathbb{R}^N} \right \}
\end{equation*}
and for  $v\in C$, we denote
 \begin{equation*}\overline{v}:=\frac{1}{T}\int_0^Tv(t)dt, \quad \tilde{v}:= v-\overline{v}.\end{equation*}
If  $v\in \mathcal{K}$, then each component
 $\tilde{v}_i$ of
 $\tilde{v}$ vanishes at some
 $\xi_i \in [0,T]$. Thus, one has that
 \begin{equation*}|\tilde{v}_i(t)|=|\tilde{v}_i(t)-\tilde{v}_i(\xi)|\leq \int_0^T|\tilde{v}'_i(\tau)|d \tau \leq T, \quad i=\overline{1,N}, \, t\in[0,T]\end{equation*}
and hence
 \begin{equation}
\|\tilde{v}\|_{\infty} \leq T\sqrt{N},
\end{equation}
 \begin{equation}
|\overline{v}|- T\sqrt{N} \leq |v(t)|\leq |\overline{v}|+ T\sqrt{N}, \quad t\in [0,T].
\end{equation}
Theorem 2.3. Problem (1.1)-(1.2) has at least one solution if one of the following conditions is satisfied:
(i)
$\lambda_1 \gt 0;$(ii) it holds
(2.8)\begin{equation}
\limsup_{|x|\to\infty}F(t,x) \lt 0,\quad \mbox{uniformly with } t\in[0,T].
\end{equation}


Proof. If  $\lambda_1 \gt 0$, the result follows from Theorem 4.1 in [Reference Jebelean3]. In case (ii) we apply [Reference Jebelean3, Theorem 4.4]. Accordingly, as
 $\mathcal{I}(0_{\mathbb{R}^N})=0$, it suffices to prove that for some δ > 0 one has
 \begin{equation*}
\mathcal{I}(u) \gt 0, \quad \mbox{for all }u\in D(\Psi + J) \mbox{ with }|\overline{u}| \gt \delta.
\end{equation*}
From (2.8) there are constants  $\sigma, \rho \gt 0$ such that
 \begin{equation*}
F(t,x)\leq-\sigma,\quad \mbox{for all}\ t\in[0,T] \mbox{ and }\ x\in\mathbb{R}^N \mbox{ with } |x| \gt \rho.
\end{equation*}
Take  $\delta:=\rho+T \sqrt{N}$ and let
 $u\in \mathcal{K}$ be with
 $|\overline{u}| \gt \delta.$ From (2.7) it follows
 $|u(t)| \gt \rho$ for all
 $t\in [0,T]$ and we get
 \begin{equation*}
\mathcal{F}(u)=-\int_0^TF(t,u(t))dt\geq\sigma T.
\end{equation*}
Then, since  $\Psi\geq0$ and
 $J\geq0$, we have that
 $\mathcal{I}(u)\geq\sigma T \gt 0$ for all
 $u\in \mathcal{K}\supset D(\Psi + J)$ with
 $|\overline{u}| \gt \delta.$
Remark 2.4. Existence of a solution under solely assumption (i) is an “universal” existence result in the sense that no additional assumptions on F in equation (1.1) are needed for the solvability of the problem. On the other hand, it is clear that the Hammerstein type condition (ii) is a useful criterion when  $\lambda_1=0$. However, the evaluation of λ 1 is not needed when (2.8) holds true.
3. Multiple solutions for even potentials
To establish multiplicity of solutions for problem (1.1)-(1.2), we first consider the parameterized potential system
 \begin{equation}
-\left[ \phi(u^{\prime}) \right] ^{\prime} = \lambda\nabla_u G(t,u),\quad \mbox{in } [0,T],
\end{equation}
associated with the boundary condition (1.2). Here, λ is a positive real parameter and G is assumed to satisfy
(HG)
$G:[0,T] \times \mathbb{R}^N \to \mathbb{R}$ is continuous,
$\nabla_u G$ exists and is continuous on
$[0,T] \times \mathbb{R}^N$ and
$G(\, \cdot \, , 0_{\mathbb{R}^N})=0$.


The energy functional  ${\mathcal I}_\lambda:C \to (-\infty , + \infty ]$ associated to (3.1)-(1.2) will be now
 \begin{equation*}
{\mathcal I}_\lambda:=\Psi + J + {\mathcal G}_\lambda,
\end{equation*}
where  ${\mathcal G}_\lambda:C \to \mathbb{R}$ is given by
 \begin{equation*} {\mathcal G}_\lambda(v):=-\lambda\int_0^TG(t,v)dt, \quad v\in C,\end{equation*}
and Ψ, J are introduced in (2.2), respectively, (2.3). We set
 \begin{equation*}d_N^1:=\left \{(x,x) \, : \, x\in \mathbb{R}^N\right \}.\end{equation*}
Proposition 3.1. The functional  $\mathcal{I}_{\lambda}$ is bounded from below and satisfies the (PS) condition if one of the following conditions is satisfied:
(i)
$\lambda_1 \gt 0$;(ii)
$j|_{d_N^1}\equiv 0$,
$j|_{D(j)}$ is bounded and
$G$ is anticoercive, i.e.,
(3.2)\begin{equation}
\lim_{|x|\to \infty}G(t,x)=-\infty,\quad \mbox{uniformly with } t\in[0,T].
\end{equation}


Proof. If  $\lambda_1 \gt 0$ the result is proved in [Reference Jebelean3, Theorem 4.1]. For the remaining case (ii), by virtue of (3.2) we have that −G is bounded from below, which together with the fact that Ψ and J are bounded from below ensure that the same is true for
 $\mathcal{I}_{\lambda}$. To see that
 $\mathcal{I}_{\lambda}$ satisfies the (PS) condition, let
 $\{u_n \} \subset D(\Psi + J)$ be a (PS)-sequence. We claim that
 $\{|\overline{u}_n| \}$ is bounded. Indeed, otherwise, we may assume – going if necessary to a subsequence, that
 $|\overline{u}_n| \to \infty$, as
 $n \to \infty$. Then, on account of (3.2) and (2.7) we deduce that
 $\int_0^T G(t,u_n(t))dt\to -\infty$ and, as
 $\mathcal{I}_{\lambda}(u_n)$,
 $\Psi(u_n)$,
 $J(u_n)$ are bounded, we get a contradiction. Consequently,
 $\{|\overline{u}_n|\}$ is bounded and by virtue of (2.6), the sequence
 $\{u_n\}$ is bounded in
 $W^{1,\infty}$. The conclusion follows by the compactness of the embedding
 $W^{1, \infty }\hookrightarrow C$.
Theorem 3.2. Assume that  $G$ and
 $j$ are even and that one of the conditions (i) or (ii) in Proposition 3.1 are fulfilled. If, in addition,
 $G$ satisfies
 \begin{equation}
\displaystyle\liminf_{|x|\to 0} \frac{2G(t,x)}{|x|^2}\geq 1,\quad \mbox{uniformly with } t\in[0,T]
\end{equation}
and  $\lambda \gt 2(m\pi/T)^2$ for some
 $m\in\mathbb{N}$,
 $m\geq 1$, then problem (3.1)-(1.2) has at least
 $mN$ distinct pairs of nontrivial solutions.
Proof. From Theorem 2.1 with Y = C,  $I = \mathcal{I}_{\lambda}$ and Proposition 3.1, it suffices to show that there exists a nonempty compact symmetric set
 $A\subset C\setminus \{0_{\mathbb{R}^N}\}$ with
 $\gamma(A)\geq mN$, such that
 \begin{equation}
\sup_{v\in A} I_{\lambda}(v) \lt 0.
\end{equation}
With this aim, we introduce the functions  $e_k(t):=\displaystyle\sin\frac{\pi k t}{T},$ (
 $k=\overline{1,m}, \, t\in [0,T]$), and consider in C the subspace
 \begin{equation*}X_m:=\left\{\alpha^1e_1+\alpha^2e_2\cdots+\alpha^m e_m:\ \alpha^1,\cdots,\alpha^m\in\mathbb{R}^N\right\}\end{equation*}
equipped with the norm
 \begin{equation*}\left\|\alpha^1e_1+\alpha^2e_2\cdots+\alpha^m e_m\right\|_{X_m}=\left(|\alpha^1|^2+\cdots+|\alpha^m|^2\right)^{\frac{1}{2}}.\end{equation*}
Observe that  $X_m=\mathbb{R}^N e_1 \oplus \dots \oplus \mathbb{R}^N e_m$ and hence,
 $\mbox{dim }X_m=mN$. Since
 $\lambda \gt 2(m\pi/T)^2$, we can find
 $\varepsilon\in(0,1)$ so that
 $\lambda \gt 2(m\pi/T)^2/(1-\varepsilon)$ and by virtue of (3.3), there exists δ > 0 such that
 \begin{equation}
2G(t,x)\geq (1-\varepsilon ) |x|^2,\quad \mbox{for all }t\in [0,T], \mbox{as } |x|\leq \delta.
\end{equation}
Next, define Am by
 \begin{equation*}
A_m=A_m(\rho):=\left\{v\in X_m:\ \|v\|_{X_m}=\rho\right\},
\end{equation*}
where ρ is a positive number, which is chosen  $\displaystyle\leq\min\left\{\frac{T}{m^{3/2}\pi},\frac{\delta}{\sqrt{m}}\right\}$. Then, the odd mapping
 $H:A_m\to S^{mN-1}$ given by
 \begin{equation*}
H\left(\sum_{k=1}^{m}\alpha^k e_k\right)=\left(\frac{\alpha^1_1}{\rho},\ldots,\frac{\alpha^1_N}{\rho}, \cdots ,\frac{\alpha^m_1}{\rho}, \cdots , \frac{\alpha^m_N}{\rho} \right)
\end{equation*}
is a homeomorphism between Am and  $S^{mN-1}$ and so,
 $\gamma(A_m)=\dim X_m=mN$.
Now, let  $v=\displaystyle\sum_{k=1}^{m}\alpha^ke_k \in A_m$. It is clear that
 $v(0)=v(T)=0_{\mathbb{R}^N}$ and hence
 $J(v)=j(0_{\mathbb{R}^N \times \mathbb{R}^N})=0$. Also, by the choice of ρ, one gets
 \begin{equation*}
|v'(t)|=\left|\sum_{k=1}^{m}\alpha^k\frac{k\pi}{T}\cos\frac{k\pi t}{T}\right| \leq\frac{m\pi}{T} \sum_{k=1}^{m} |\alpha^k|
\leq\frac{m\pi}{T}\left(\sum_{k=1}^{m}|\alpha^k|^2\right)^{\frac{1}{2}}m^{1/2}=\rho\frac{m^{3/2}\pi}{T}\leq1,
\end{equation*}
meaning that  $v\in \mathcal{K}$. Also, we obtain
 \begin{align}
\int_0^T|v'(t)|^2dt&= \int_0^T\left|\sum_{k=1}^{m}\alpha^k\frac{k\pi}{T}\cos\frac{k\pi t}{T}\right|^2dt=\int_0^T\sum_{i=1}^N\left(\sum_{k=1}^{m}\alpha^k_i\frac{k\pi}{T}\cos\frac{k\pi t}{T}\right)^2dt\nonumber\\
&=\int_0^T\sum_{i=1}^N\left(\sum_{k=1}^{m}\left(\alpha^k_i \frac{k\pi}{T}\cos\frac{k\pi t}{T}\right)^2+\sum_{\substack{k,j=1\\k \neq j}}^{m}\alpha^k_i\alpha^j_i \frac{kj\pi^2}{T^2}\cos\frac{k\pi t}{T}\cos\frac{j\pi t}{T}\right)dt\nonumber\\
&=\sum_{k=1}^{m}\sum_{i=1}^N\left(\alpha^k_i\right)^2\int_0^T \left(\frac{k\pi}{T}\cos\frac{k\pi t}{T}\right)^2dt\nonumber\\
&\quad +\sum_{i=1}^N\sum_{\substack{k,j=1\\k \neq j}}^{m}\alpha^k_i\alpha^j_i \int_0^T\frac{kj\pi^2}{T^2}\cos\frac{k\pi t}{T}\cos\frac{j\pi t}{T}dt\nonumber\\
&=\sum_{k=1}^{m}\sum_{i=1}^N\left(\alpha^k_i\right)^2\left(\frac{k\pi}{T}\right)^2\frac{T}{2}\leq\frac{m^2\pi^2}{2T}\sum_{k=1}^{m}|\alpha^k|^2=
\frac{m^2\pi^2}{2T}\rho^2
\end{align}
and
 \begin{align}
\int_0^T|v(t)|^2dt&=\int_0^T\left|\sum_{k=1}^{m}\alpha^k\sin\frac{k\pi t}{T}\right|^2dt=\int_0^T\sum_{i=1}^N\left(\sum_{k=1}^{m}\alpha^k_i\sin\frac{k\pi t}{T}\right)^2dt\nonumber\\
&=\int_0^T\sum_{i=1}^N\left(\sum_{k=1}^{m}\left(\alpha^k_i\sin\frac{k\pi t}{T}\right)^2+\sum_{\substack{k,j=1\\k\neq j}}^{m}\alpha^k_i\alpha^j_i \sin\frac{k\pi t}{T}\sin\frac{j\pi t}{T}\right)dt \nonumber\\
&=\frac{T}{2}\sum_{k=1}^{m}|\alpha^k|^2=\frac{T\rho^2}{2}.
\end{align}
Then, from
 \begin{eqnarray*}
|v|\leq \sum_{k=1}^m|\alpha^k|\leq\left(\sum_{k=1}^{m}|\alpha^k|^2\right)^{\frac{1}{2}}\sqrt{m}=\rho\sqrt{m}\leq\delta,
\end{eqnarray*}
together with (3.5), (3.6) and (3.7), we estimate  $\mathcal{I}_{\lambda}$ on Am as follows
 \begin{eqnarray*}
\mathcal{I}_{\lambda}(v)&=&\Psi(v)+J(v)+\mathcal{G}_{\lambda}(v)=\Psi(v)+\mathcal{G}_{\lambda}(v)\leq\int_0^T|v'|^2-
\frac{\lambda}{2}(1-\varepsilon)\int_0^T |v|^2\\
&\leq& \frac{m^2\pi^2}{2T}\rho^2-\lambda(1-\varepsilon)\frac{T\rho^2}{4}=T \rho^2\frac{2(m \pi /T)^2-\lambda(1-\varepsilon)}{4} \lt 0,
\end{eqnarray*}
which shows that (3.4) holds true with  $A=A_m$.
Theorem 3.2 can be employed to derive multiplicity of solutions for the non-parametric problem (1.1)-(1.2).
Theorem 3.3. Assume that  $F$ and
 $j$ are even and one of the following conditions is satisfied:
(i)
$\lambda_1 \gt 0$;(ii)
$j|_{d_N^1}\equiv 0$,
$j|_{D(j)}$ is bounded and
$F$ is anticoercive.


(a) If, for some
$m \geq 1$, it holds
(3.8)\begin{equation}
\liminf_{|x|\to 0}\frac{F(t,x)}{|x|^2} \gt \left(\frac{m\pi}{T}\right)^2,\quad \mbox{uniformly with } t\in[0,T],
\end{equation}then (1.1)-(1.2) has at least mN distinct pairs of nontrivial solutions.
(b) If
(3.9)\begin{equation}
\lim_{|x|\to 0}\frac{F(t,x)}{|x|^2}=+\infty,\quad \mbox{uniformly with } t\in[0,T],
\end{equation}then (1.1)-(1.2) has infinitely many distinct pairs of solutions.


Proof. (a) By (3.8) there exists  $\lambda^* \gt 0$ such that
 \begin{equation*}\liminf_{|x|\to 0}\frac{2F(t,x)}{|x|^2}\geq \lambda^* \gt 2\left(\frac{m\pi}{T}\right)^2\end{equation*}
and from Theorem 3.2 with  $G=F/ \lambda^*$, we have that system
 \begin{equation*}-\left[\phi(u')\right]'= \lambda^* \ \nabla_u \left(\frac{F(t,u)}{\lambda^*}\right),\quad \mbox{in } [0,T],\end{equation*}
associated with boundary condition (1.2), has at least mN distinct pairs of nontrivial solutions.
(b) This is immediate from (a) and (3.9).
Example 3.4. Let  $a,b \in \mathbb{R}$ be with
 $|a|+|b| \gt 0$, q > 0,
 $\alpha \in (-1,0]$ and
 $w:[0,T] \to \mathbb{R}$ be continuous. We consider a system of type
 \begin{equation}
-\left[ \phi(u^{\prime}) \right] ^{\prime} = u \left ( |u|^{\alpha}-w(t) |u|^q \right ), \quad \mbox{in } [0,T],
\end{equation}
in the presence of the boundary condition
 \begin{equation}
a u(0)= b u(T), \qquad b \phi(u')(0)=a \phi (u')(T).
\end{equation}
Notice that (3.10) is of type (1.1), with
 \begin{equation*}F(t,x)=\frac{|x|^{\alpha +2}}{\alpha +2}-w(t)\frac{|x|^{q +2}}{q+2}, \qquad (t,x)\in [0,T] \times \mathbb{R}^N,\end{equation*}
while (3.11) is obtained from (1.2) by taking  $j=I_Y$ - the indicator function of the subspace
 \begin{equation*}Y=\{(x,y) \in \mathbb{R}^N \times \mathbb{R}^N \, : \, ax=by \}.\end{equation*}
Clearly, if a = b on has that  $Y=d_N^1$,
 $\lambda_1=0$ (because any constant function belongs to
 $D(\Psi+J)$) and (3.10) becomes the periodic boundary condition
 \begin{equation}
u(0)- u(T)= 0_{\mathbb{R}^N}=u'(0)- u'(T).
\end{equation}
In the opposite case, when a ≠ b, one has  $\lambda _1 \gt 0$. Indeed, by [Reference Jebelean and Precup5, Theorem 3.1] we have that
 \begin{equation*} \underline{\lambda}_1:=\inf\left \{\frac{\|v^{\prime} \|_{L^2}^2}{\|v \|_{L^2}^2}
\, : \, v\in W^{1,2}([0,T]; \mathbb{R}^N), \, (v(0),v(T))\in Y , \; v \not\equiv 0_{\mathbb{R}^N} \right \} \gt 0\end{equation*}
and the conclusion follows from  $\lambda_1 \geq \underline{\lambda}_1$.
We first refer to the situation α = 0, when system (3.10) involves a Fisher-Kolmogorov type nonlinearity:
 \begin{equation}
-\left[ \phi(u^{\prime}) \right] ^{\prime} = u \left ( 1-w(t) |u|^q \right ), \quad \mbox{in } [0,T],
\end{equation}
From Theorem 3.3 (a) we obtain the following. Assume that  $m\in \mathbb{N}$ and T > 0 are such that
 ${m \pi \sqrt{2}}/{T} \lt 1.$ If a ≠ b then problem (3.13)-(3.11) has at least
 $\mathit{mN}$ distinct pairs of nontrivial solutions. The same conclusion holds true for the periodic problem (3.13)-(3.12) provided that in addition w > 0.
In the remaining case  $\alpha \in (-1,0)$, from Theorem 3.3 (b) we get that if a ≠ b then (3.10)-(3.11) has infinitely many distinct pairs of solutions and the same holds true for the periodic problem (3.10)-(3.12) provided that in addition w > 0.
Remark 3.5. The result concerning the number mN of pairs of nontrivial solutions from Theorem 3.3 (a) is not optimal. Even for the periodic boundary conditions discussed above (but also Neumann), it can be improved (see Corollaries 2.6 and 3.4 in [Reference Jebelean and Șerban7]). A similar remark can be made regarding Theorem 3.2 by comparison with Theorems 2.2 and 3.2 from [Reference Jebelean and Șerban7]. In this respect, besides the fact that these theorems provide some general thresholds for the existence of multiple solutions, their importance consists in the fact that they also are the key step in proving the existence of infinitely many solutions in the wide class of boundary value problems of type (1.1)-(1.2).
4. Geometrically distinct solutions
In this section, we provide a result concerning the existence of geometrically distinct solutions for systems of type
 \begin{equation}
-\left[ \phi(u^{\prime}) \right] ^{\prime} = \nabla_u F(t,u) + h(t),\quad \mbox{in } [0,T],
\end{equation}
associated with boundary condition (1.2). Here, besides (HF) and (Hj), we assume the following hypotheses:
(
$H_{F}^1$)
$F(t, u)$ is ωi-periodic
$(\omega_i \gt 0)$ with respect to each ui
$(i =\overline{1,N})$, for all
$t\in[0,T]$;


(
$H_j^1$)
$j|_{D(j)}$ is bounded and if
$z\in D(j)$ then
$j(z+\zeta)=j(z)$ for all
$\zeta \in d_N^1$;


(Hh)
$h:[0,T]\to\mathbb{R}^N$ is continuous with
$\overline{h}=0$.


From ( $H_{F}^1$) we have that
 $\nabla_uF(t, u)$ is ωi-periodic with respect to each ui (
 $i =\overline{1,N},\, t\in[0,T]$) and assumption
 $j(z+\zeta)=j(z)$ in (
 $H_j^1$) ensures that
 $\partial j(z+\zeta)= \partial j(z)$ for all
 $z \in D(j),$
 $\zeta \in d_N^1$. Let
 $(\mathbf{e}^1, \dots, \mathbf{e}^N)$ be the canonical basis in
 $\mathbb{R}^N$ and consider the discrete group
 \begin{equation*}\mathbf{G}:=\left\{\sum_{i=1}^{N}k_i \, \omega_i \, \mathbf{e}^i:\ k_i\in\mathbb{Z},\ 1\leq i\leq N\right\}.\end{equation*}
Observe that if u is a solution of (4.1)-(1.2) then the same is true for  $u + \mathbf{g}$, when
 $\mathbf{g} \in \mathbf{G}.$ Two solutions u and v of (4.1)-(1.2) are said to be geometrically distinct if
 $u-v \notin \mathbf{G}.$
The corresponding action functional to problem (4.1)-(1.2) will be  ${\mathcal I}_h:C \to (-\infty , + \infty ]$ given by
 \begin{equation*}
{\mathcal I}_h:=\Psi + J + {\mathcal F}_h,
\end{equation*}
where Ψ, J are introduced in (2.2), respectively, (2.3) and  ${\mathcal F}_h:C \to \mathbb{R}$ is defined by
 \begin{equation*}
{\mathcal F}_h(v):=-\int_0^T\left[F(t,v)+\langle h(t)|v\rangle\right] dt, \quad v\in C.
\end{equation*}
Theorem 4.1. Suppose that  $D(j)$ is closed and hypotheses
 $(H_{F})$,
 $(H_{F}^1)$,
 $(H_j)$,
 $(H_j^1)$ and
 $(H_h)$ hold true. Then problem (4.1)-(1.2) has at least
 $N$ + 1 geometrically distinct solutions.
Proof. We apply Theorem 2.2 with Y = C,  $\psi=\Psi+J$,
 $\mathfrak{F}={\mathcal F}_h$,
 $\mathrm{G}=\mathbf{G}$ and
 $\widetilde{Y}=\widetilde{C}:=\{u\in C:\ \overline{u}=0_{\mathbb{R}^N}\}$. Notice that
 $\mbox{span}\, \mathbf{G} = \mathbb{R}^N$,
 $C=\mathbb{R}^N\oplus \widetilde{C}$ and thus the conclusion will follow provided that we show that assumptions
 $(A_1)$-
 $(A_4)$ hold true with these choices.
Is easy to see that assumptions  $(H_F)$,
 $(H_F^1)$ and
 $(H_h)$ imply that
 ${\mathcal F}_h'$ takes bounded sets into bounded sets and
 \begin{equation*}{\mathcal F}_h(u+\mathbf{g})={\mathcal F}_h(u),\quad \mbox{for all } u\in C,\ \mathbf{g}\in\mathbf{G}.\end{equation*}
Also, by  $(H_j^1)$ one has
 \begin{equation}
J(u+\mathbf{c})=J(u),\quad \mbox{for all } u\in C,\ \mathbf{c}\in \mathbb{R}^N \supset\mathbf{G}
\end{equation}
and we get that  $\Psi+J$ is G-invariant. Since
 $\mathcal{K}$ and D(j) are closed, the same is true for
 $D(\Psi+J)=\mathcal{K} \cap D(J)$. Assumption
 $(A_1)$ is thus satisfied. Checking
 $(A_2)$ is straightforward from (4.2). Next, for
 $u\in D(\Psi+J) \subset {\mathcal K}$ we have
 $\|\widetilde{u}\|_\infty\leq T\sqrt{N}$ (see (2.6)) and, since
 $j|_{D(j)}$ is bounded, there exists
 $\rho_0 \gt 0$ with
 $|(\Psi+J)(u)|\leq\rho_0$ for all
 $u\in D(\Psi+J)$, which yields that
 $(A_3)$ holds with
 $\rho=\max\{\rho_0,T\sqrt{N}\}$. Finally, if
 $\{u_n\}\subset D(\Psi+J)$ is a sequence with
 $\{\overline{u}_n\}$ bounded, as
 $\|\widetilde{u}_n\|_\infty\leq T\sqrt{N}$, we get that
 $\{u_n\}$ is bounded in
 $W^{1,\infty}$. Then,
 $(A_4)$ follows by the compactness of the embedding
 $W^{1, \infty }\hookrightarrow C$ and the proof is complete.
Remark 4.2. (i) In slightly more restrictive assumptions (D(j) closed and  $j|_{D(j)}$ bounded), Theorem 4.1 substantially improves the conclusion of Corollary 4.6 from [Reference Jebelean3] where only the existence of a single solution is obtained.
(ii) Taking  $j=I_{d_N^1}$ in the above theorem, we recover the known result according to which under the assumptions
 $(H_F)$,
 $(H_F^1) $ and
 $(H_h)$, the periodic problem (4.1)-(3.12) has at least N + 1 geometrically distinct solutions [Reference Jebelean, Mawhin and Șerban4, Reference Mawhin10, Reference Bereanu and Jebelean1]. But the importance of Theorem 4.1 consists in the fact that it highlights a whole class of boundary conditions when the problem has N + 1 geometrically distinct solutions. A simpler consequence is provided below.
Corollary 4.3. Assume  $(H_{F})$,
 $(H_{F}^1)$,
 $(H_h)$ and let
 $f:\mathbb{R}^N \to \mathbb{R}$ be of class
 $C$1, convex, with
 $f(0_{\mathbb{R}^N})=0$ and
 $\nabla f (0_{\mathbb{R}}^N)=0_{\mathbb{R}^N}.$ Then system (4.1) has at least
 $N$ + 1 geometrically distinct solutions satisfying the boundary condition
 \begin{equation}
\phi \left( u^{\prime }\right)(0)=\nabla f ( u(0)- u(T))=\phi \left( u^{\prime }\right)(T).
\end{equation}
Proof. Let  $T \lt \sigma \lt \infty$,
 $S_{\sigma}:= \{(x,y)\in \mathbb{R}^N \times \mathbb{R}^N \, : \, |x-y|\leq \sigma \}$ and
 $g:\mathbb{R}^N \times \mathbb{R}^N \to \mathbb{R}$ be given by
 $g(x,y)=f(x-y)$ (
 $(x,y)\in \mathbb{R}^N \times \mathbb{R}^N$). Then,
 $j:=g+I_{S_{\sigma}}$ satisfies
 $(H_j)$,
 $(H_j^1)$ and the boundary condition (1.2) becomes (4.3) (see Proposition 4.7 and Example 4.8 in [Reference Jebelean3]). The conclusion follows by Theorem 4.1.
Example 4.4. For any  $a\in C$ and
 $h\in C$ with
 $\overline{h}=0$, system
 \begin{equation*}
-\left[ \frac{u_i'}{\sqrt{1-|u'|^2}} \right] ^{\prime} = a_i(t) \sin u_i +h_i(t),\, \, \mbox{in } [0,T], \quad i=\overline{1,N}
\end{equation*}
has at least N + 1 geometrically distinct solutions satisfying the boundary condition
 \begin{equation*}
\phi \left( u^{\prime }\right)(0)=\displaystyle e^{|u(0)-u(T)|^2} ( u(0)- u(T))=\phi \left( u^{\prime }\right)(T).
\end{equation*}
To see this, Corollary 4.3 applies with  $f(x)=(e^{|x|^2}-1)/2 $ and
 $F(t,x) = -\sum _{i=1}^{N}a_i(t) \cos x_i$,
 $t\in [0,T], \, x\in \mathbb{R}^N$; here,
 $\omega_i=2 \pi$,
 $i=\overline{1,N}$.



