




No CrossRef data available.
Article contents
JIVE FOR PANEL DYNAMIC SIMULTANEOUS EQUATIONS MODELS
Published online by Cambridge University Press: 02 November 2017
Abstract
Core share and HTML view are not available for this content. However, as you have access to this content, a full PDF is available via the 'Save PDF' action button.
We consider the method of moments estimation of a structural equation in a panel dynamic simultaneous equations model under different sample size combinations of cross-sectional dimension, N, and time series dimension, T. Two types of linear transformation to remove the individual-specific effects from the model, first difference and forward orthogonal demeaning, are considered. We show that the Alvarez and Arellano (2003) type GMM estimator under both transformations is consistent only if  ${T \over N} \to 0$ as
 $\left( {N,T} \right) \to \infty $. However, it is asymptotically biased if
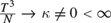 ${{{T^3}} \over N} \to \kappa \ne 0 < \infty$ as
 $\left( {N,T} \right) \to \infty $. Since the validity of statistical inference depends critically on whether an estimator is asymptotically unbiased, we suggest a jackknife bias reduction method and derive its limiting distribution. Monte Carlo studies are conducted to demonstrate the importance of using an asymptotically unbiased estimator to obtain valid statistical inference.
Information
- Type
- ARTICLES
- Information
- Copyright
- Copyright © Cambridge University Press 2017
Footnotes
We would like to thank the editor, Peter C.B. Phillips, the co-editor, Guido Kuersteiner, John Chao and three anonymous referees for very detailed and helpful comments and suggestions, which have greatly improved the original paper. We would also like to thank Alan Adelman and John Pedersen for editorial polishing. All remaining errors are solely ours. Partial research support of China NSF grant #71131008 and #71631004 to the first author is gratefully acknowledged.
References
REFERENCES
Akashi, K. & Kunitomo, N. (2012) Some properties of the LIML estimator in a dynamic panel structural equation. Journal of Econometrics 166, 167–183.CrossRefGoogle Scholar
Alvarez, J. & Arellano, M. (2003) The time series and cross-section asymptotics of dynamic panel data estimators. Econometrica 71, 1121–1159.CrossRefGoogle Scholar
Anderson, T.W. & Hsiao, C. (1981) Estimation of dynamic models with error components. Journal of the American Statistical Association 76, 589–606.CrossRefGoogle Scholar
Anderson, T.W. & Hsiao, C. (1982) Formulation and estimation of dynamic models using panel data. Journal of Econometrics 18, 47–82.Google Scholar
Anderson, T.W. & Rubin, H. (1949) Estimation of the parameters of a single equation in a complete system of stochastic equations. The Annals of Mathematical Statistics 20, 46–63.CrossRefGoogle Scholar
Angrist, J.D., Imbens, G.W., & Krueger, A.B. (1999) Jackknife instrumental variables estimation. Journal of Applied Econometrics 14, 57–67.3.0.CO;2-G>CrossRefGoogle Scholar
Arellano, M. & Bond, S. (1991) Some tests of specification for panel data: Monte carlo evidence and an application to employment equations. Review of Economic Studies 58, 277–297.CrossRefGoogle Scholar
Arellano, M. & Bover, O. (1995) Another look at the instrumental variable estimation of error-components models. Journal of Econometrics 68, 29–51.Google Scholar
Chao, J., Swanson, N., Hausman, J., Newey, W., & Woutersen, T. (2012) Asymptotic distribution of JIVE in a heteroskedastic IV regression with many instruments. Econometric Theory 28, 42–86.CrossRefGoogle Scholar
Hahn, J. & Newey, W. (2004) Jackknife and analytical bias reduction for nonlinear panel models. Econometrica 72, 1295–1319.CrossRefGoogle Scholar
Hahn, J. & Kuersteiner, G.M. (2002) Asymptotically unbiased inference for a dynamic panel model with fixed effects when both n and T are large. Econometrica 70, 1639–1657.CrossRefGoogle Scholar
Hansen, C. & Kozbur, D. (2014) Instrumental variables estimation with many weak instruments using regularized JIVE. Journal of Econometrics 182, 290–308.CrossRefGoogle Scholar
Hood, W.C. & Koopmans, T.C. (1953) Studies in Econometric Method. Cowles Foundation Monograph, vol. 14. Yale University Press.Google Scholar
Hsiao, C. (1982) Identification. In Griliches, Z. & Intriligator, M. (eds.), Handbook of Econometrics, vol. 1, pp. 223–283. North Holland.CrossRefGoogle Scholar
Hsiao, C. & Zhang, J. (2015) IV, GMM or MLE to estimate dynamic panel data models. Journal of Econometrics 187, 312–322.Google Scholar
Hsiao, C. & Zhou, Q. (2015) Statistical inference for panel dynamic simultaneous equations models. Journal of Econometrics 189, 383–396.CrossRefGoogle Scholar
Hsiao, C. & Zhou, Q. (2017) First difference or forward demeaning: Implications for the method of moments estimators. Econometric Reviews 36, 883–897.Google Scholar
Intriligator, D., Bodkin, R., & Hsiao, C. (1996) Econometric Models, Techniques, and Applications, 2nd ed. Pearson.Google Scholar
Lee, L.F. & Yu, J. (2014) Efficient GMM estimation of spatial dynamic panel data models with fixed effects. Journal of Econometrics 180, 174–197.Google Scholar
Lee, N., Moon, R., & Zhou, Q. (2017) Many IVs estimation of dynamic panel regression models with measurement error. Journal of Econometrics 200, 251–259.CrossRefGoogle Scholar
Moon, H.R., Perron, B., & Phillips, P.C.B. (2015) Incidental parameters and dynamic panel modeling. In Baltagi, B.H. (ed.), Oxford Handbook of Panel Data, pp. 111–148. Oxford University Press.Google Scholar
Nerlove, M. (2000) An essay on the history of panel data econometrics. Working paper, University of Maryland.Google Scholar
Phillips, G.D.A. & Hale, C. (1977) The bias of instrumental variable estimators of simultaneous equation systems. International Economic Review 18, 219–228.CrossRefGoogle Scholar
Phillips, P.C.B. & Moon, H.R. (1999) Linear regression limit theory for nonstationary panel data. Econometrica 67, 1057–1112.CrossRefGoogle Scholar
 You have
Access
- 3
- Cited by