




No CrossRef data available.
Article contents
Stochastic Integrals Based on Martingales Taking Values in Hilbert Space
Published online by Cambridge University Press: 22 January 2016
Extract
Core share and HTML view are not available for this content. However, as you have access to this content, a full PDF is available via the 'Save PDF' action button.
Let H be a separable Hilbert space with inner product (,) and norm ║ ║. We denote by K the set of all linear operators on H. Let  be a probability space and suppose we are given a family of σ-fields
 t≥O such that
 for O ≤ s ≤ t and
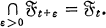 .
Information
- Type
- Research Article
- Information
- Copyright
- Copyright © Editorial Board of Nagoya Mathematical Journal 1970
References
[1]
Daletskii, Yu.L., Infinite-dimensional epllitic operators and parabolic equations connected with them, Uspekhi Mate. Nauk.
22 (1967) (English translation; Russian Math. Surveys)Google Scholar
[2]
Kunita, H., and Watanabe, S., On square integrable martingales, Nagoya Math. J.
30 (1967), 209–245.CrossRefGoogle Scholar
[3]
Lévy, P., Fonction aleatoires a correlation linaire, Illinois J. Math.
1 (1957), 217–258.Google Scholar
 You have Access
- 49
- Cited by