


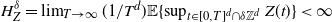


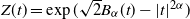



1. Introduction
The discrete Pickands constant
 $H_{Z}^\delta$
is defined for a given positive
 $\delta$
by
 \begin{equation*} H_{Z}^\delta= \lim_{{n} \to \infty} \dfrac{1}{n \delta } \mathbb{E}\biggl\{{\sup_{1 \le k \le n} Z(k\delta) }\biggr\} =\lim_{{T} \to \infty} \dfrac{1}{ T } \mathbb{E}\biggl\{{\sup_{ t\in [0,T] \cap \delta \mathbb{Z} } Z(t) }\biggr\} \in (0,\infty ), \end{equation*}
where
 $Z(t)= \exp(\sqrt{ 2} B_\alpha(t)- \lvert {t} \rvert^{2\alpha})$
and
 $B_\alpha$
is a standard fractional Brownian motion (fBm) with Hurst parameter
 $\alpha\in (0,1]$
. When
 $\delta=0$
, interpreting
 $0\mathbb{Z}$
as
 $\mathbb{R}$
,
 $H_{Z}^0$
can be defined in an analogous way, that is,
 \begin{equation*}H_{Z}^0= \lim_{{T} \to \infty} \dfrac{1}{ T } \mathbb{E}\biggl\{{\sup_{ t\in [0,T] } Z(t) }\biggr\} \in (0,\infty ),\end{equation*}
which is the classical Pickands constant appearing in the tail asymptotics of the distribution of the supremum for a wide class of Gaussian processes; see e.g. [Reference Pickands27], [Reference Piterbarg28], and [Reference Dieker and Yakir13]. Pickands’ pioneering method (see [Reference Pickands27]) for the approximation of the tail distribution of the supremum for a stationary Gaussian process relies strongly on a discretisation approach. A crucial element in Pickands’ methodology is the fact that
 \begin{equation}\lim_{\delta \downarrow 0} H_{Z}^{ \delta}= H_{Z}^0. \end{equation}
Notably, Pickands’ first attempt to prove (1.1) contains a gap; a correct proof is given in [Reference Bickel and Rosenblatt3, Theorem B3]. See also the comments after [Reference Bickel and Rosenblatt3, Lemma A3].
A systematic study of Pickands constants started with [Reference Dieker and Yakir13, Theorem 1, Proposition 2] showing that
 \begin{equation} H_{Z}^0 = \mathbb{E}\biggl\{{ \dfrac{ \sup_{t\in \mathbb{R}} Z(t) }{ \eta \sum_{t\in \eta \mathbb{Z} } Z(t) }}\biggr\} = \mathbb{E}\biggl\{{ \dfrac{ \sup_{t\in \mathbb{R}} Z(t) }{ \int_{t\in \mathbb{R} } Z(t) \lambda({\mathrm{d}} t)}}\biggr\}\end{equation}
is valid for any
 $\eta > 0$
, where
 $\lambda(\cdot)$
is the Lebesgue measure on
 $\mathbb{R}$
.
The two expressions in (1.2) paved the way for simulations of Pickands constants and inspired new formulas for extremal indices of stationary time series; see e.g. [Reference Dieker and Mikosch12], [Reference Hashorva19], [Reference Dębicki, Engelke and Hashorva11], [Reference Dębicki and Hashorva8], [Reference Planinić and Soulier30], [Reference Hashorva20], and [Reference Soulier37].
Pickands constants for general Gaussian processes were considered first in [Reference Dębicki6]; see also [Reference Dębicki7]. Later Dębicki and Hashorva [Reference Dębicki and Hashorva9,Reference Hashorva19] discussed extensions to general random fields (RFs), as we briefly outline next. Therefore let Z(t),
 $t\in \mathbb{R}^d$
, be a separable, non-negative RF such that
 \begin{equation}\mathbb{E}\{{ Z(t) }\}=1 \quad \text{for all } t\in \mathbb{R}^d ,\end{equation}
and define the corresponding Pickands constant by
 \begin{equation}H_{Z }^\delta = \lim_{{T} \to \infty}T^{-d} \mathbb{E}\biggl\{{\sup_{ t\in [0,T]^d \cap \delta \mathbb{Z}^d } Z (t) }\biggr\}, \quad \delta\ge0,\end{equation}
where we set
 $\delta \mathbb{Z}^d\,:\!=\,\mathbb{R}^d$
when
 $\delta=0$
. If
 $\delta=0$
, in order to avoid degenerated cases, we shall assume further that
 \begin{equation} \mathbb{E}\biggl\{{ \sup_{t\in[0,T]^d} Z (t) }\biggr\} \in (0, \infty ) \quad \text{for all } T>0.\end{equation}
Definition (1.4) might not be valid for a general Z since the limit might not exist. However, if for all compact sets
 $K \subset \mathbb{R}^d$
 \begin{equation} \mathbb{E}\biggl\{{ \sup_{t \in K } Z (t+c)}\biggr\}= \mathbb{E}\biggl\{{ \sup_{t \in K} Z (t)}\biggr\} \quad \text{for all } c\in \mathbb{R}^d,\end{equation}
then, as we shall show in Section 2, the constant
 $H_{Z }^\delta $
is well-defined and finite for any
 $\delta \ge 0$
. Notably, we know from [Reference Hashorva19], [Reference Dębicki and Hashorva9], and [Reference Hashorva20] that the limit in (1.4) exists if there is a stationary max-stable process Y(t),
 $t\in \mathbb{R}^d$
, with unit Fréchet marginals, which has spectral process Z in its de Haan representation (see e.g. [Reference de Haan18] and [Reference Dombry and Kabluchko14])
 \begin{equation}Y(t)= \max_{i\ge 1} \Gamma_i^{-1} Z^{(i)}(t), \quad t\in \mathbb{R}^d.\end{equation}
Here
 $\Gamma_i= \sum_{k=1}^i \mathcal{V}_k$
, with
 $\mathcal{V}_k, k\ge 1$
mutually independent unit exponential random variables (RVs) being independent of
 $\{Z^{(i)}\}_{i=1}^\infty$
, which are independent copies of Z. The finite-dimensional distributions (FIDIs) of Y are given by
 \begin{equation}\mathbb{P} \{ {Y(t_1)\leq x_1,\ldots, Y(t_n)\leq x_n} \} ={\mathrm{e}}^{- \mathbb{E}\{{ \max_{i\le n } Z (t_i) /x_i}\}}, \quad x_i>0,\ t_i \in \mathbb{R}^d,\ i\le n\end{equation}
and hence
 \begin{equation*} (\mathbb{P} \{ {Y(t_1)\leq x_1,\ldots, Y(t_n)\leq x_n} \} )^m= \mathbb{P} \{ {mY(t_1)\leq x_1,\ldots, mY(t_n)\leq x_n} \} \end{equation*}
for all
 $m>0$
, which shows that the FIDIs of Y are max-stable. Clearly, if Y is stationary, then
 $\sup_{t \in K } Y (t+c)$
has the same law as
 $\sup_{t \in K } Y (t)$
for all
 $c\in \mathbb{R}^d$
, and hence if Y has locally bounded sample paths, then (1.8) implies (1.5) and further (1.6) is valid.
Pickands constants are closely related to extremal indices of the max-stable stationary RF Y. Indeed, under the assumption (1.5) and the finiteness of Pickands constants, the separability of Y implies
 \begin{equation}- \ln \mathbb{P}\biggl\{{ \sup_{t \in [0,T]^d \cap \delta \mathbb{Z}^d } Y(t) \le r T^{d} } \biggr\} = \dfrac{1}{rT^d}\mathbb{E}\biggl\{{ \sup_{t \in [0,T]^d \cap \delta \mathbb{Z}^d } Z (t) }\biggr\} \to \dfrac 1 r H_{Z }^\delta\end{equation}
as
 $T\to \infty $
for all
 $r>0$
. Thus, by definition, the extremal index of the stationary RF Y(t),
 $t\in \delta \mathbb{Z}^d$
, is equal to
 $ \delta^d H_{Z }^\delta \in [0,1]$
for any
 $\delta>0$
. Clearly, (1.9) is an approximation of the distribution of the supremum of Y. Such approximations are known for general stationary RFs. A prominent example is Y being a symmetric
 $\alpha$
-stable RF; see [Reference Samorodnitsky35], [Reference Samorodnitsky36], [Reference Wang, Roy and Stoev40], [Reference Roy32], and the references therein.
A natural question that arises here is the relevance of general Pickands constants, both in extreme value theory of RFs and in stochastic modelling. As shown in [Reference Dębicki and Liu10], Pickands constants determined by
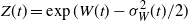 $Z(t)= \exp( W(t)- \sigma_W^2(t)/2)$
, where W is a centered Gaussian RF with stationary increments and variance function
 $\sigma_W^2$
, appear naturally in risk and queueing theory. Moreover, as advocated in [Reference Hashorva20], Pickands constants related to a general non-Gaussian RF Z have appeared in the literature in numerous papers. In that context, considering a general RF Z is important since it unifies the study of extremal indices and Pickands constants.
The second question is: for what general Z does the limit (1.1) hold? The answer to this question is presented in Section 2. Such a result has the following two immediate consequences.
-
(A) Pickands’ discretisation method for the study of extremes of Gaussian RFs can be utilised also for cases where the limiting constants are determined by general Gaussian RFs with stationary increments.
-
(B) The calculation of
 $H_{Z}^0$
can be carried out by simulating
$H_{Z}^\delta$
for small
$\delta>0$
. Therefore it is also interesting to derive tractable formulas for
$H_{Z}^\delta$
as given by (2.3).


The organisation of the rest of the paper is as follows. In Section 2 we first discuss the finiteness and continuity of discrete Pickands constants (in Theorem 2.1) and then derive a formula corresponding to (1.2) (in Proposition 2.1), which shows in particular how to approximate
 $H_{Z }^0$
using the FIDIs of Z. Section 3 is concerned with two extensions. The first one is motivated by results related to symmetric
 $\alpha$
-stable RFs derived in [Reference Samorodnitsky35, Reference Samorodnitsky36], whereas the second extension is motivated by the constant
 \begin{equation} \mathcal{H}_{Z}^\delta = \lim_{{T} \to \infty} T^{-d} \int_0^1 \mathbb{E}\biggl\{{\sup_{ t\in [0,T]^d \cap \delta \mathbb{Z}^d } Z_z(t) }\biggr\} \,{\mathrm{d}} z\end{equation}
defined in [Reference Chan and Lai5] for
 $\delta =0$
. Here
 $ Z_z, z\in [0,1]$
is equal in law to
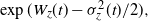 $ \exp( W_z(t) - \sigma_z^2(t)/2),$
with
 $W_z$
a centered Gaussian RF with stationary increments, variance function
 $\sigma^2_z$
and almost surely continuous sample paths. In Theorem 3.1 we establish the continuity of
 $\mathcal{H}_Z^\delta$
at
 $\delta=0$
. Such a result is crucial for the applications of Pickands’ discretisation method in the study of extremes of locally stationary Gaussian RFs. It is also of certain relevance for the simulations of those constants. We have relegated all the proofs to Section 4.
2. Main results
Our first result establishes the finiteness of Pickands constants and (1.1) for a general RF Z under some weak restrictions. In particular, our result is satisfied for Z such that Y(t),
 $t\in \mathbb{R}^d$
, defined in (1.7) is a stochastically continuous stationary max-stable RF with locally bounded sample paths. Hereafter we shall suppose that all RFs are defined on a complete probability space
 $(\Omega, \mathcal{F}, \mathbb{P})$
. In the following, for a given stochastically continuous RF U(t),
 $t\in \mathcal{T}$
, we shall suppose that it is also separable and jointly measurable. In view of [Reference Doob16], a separable and jointly measurable version of a stochastically continuous RF exists.
Theorem 2.1. If Z(t),
 $t\in \mathbb{R}^d$
, is a non-negative stochastically continuous RF such that (1.3), (1.5), and (1.6) hold, then the constants defined in (1.4) are finite for all
 $\delta \ge 0$
and further
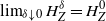 $\lim_{\delta\downarrow 0} H_{Z}^{\delta }= H_{Z}^0$
.
In the following,
 \begin{equation*} S_\delta (Z)= \int_{t\in \delta \mathbb{Z}^d } {Z(t)} \lambda_\delta({\mathrm{d}} t), \quad \delta\ge 0,\end{equation*}
where
 $\lambda_0({\mathrm{d}} t)=\lambda({\mathrm{d}} t)$
is the Lebesgue measure on
 $\mathbb{R}^d$
and for
 $\delta>0$
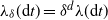 $\lambda_\delta({\mathrm{d}} t)= \delta ^d \lambda({\mathrm{d}} t)$
with
 $\lambda({\mathrm{d}} t)$
the counting measure on
 $\delta \mathbb{Z}^d$
.
Clearly
 $S_\delta(Z)$
is an RV for any
 $\delta>0$
. If
 $\delta=0$
(recall that
 $0\mathbb{Z}^d$
simply denotes
 $\mathbb{R}^d$
), since we consider Z to be jointly measurable, then supposing that (1.5) holds and using that Z is non-negative (recall that we assume the probability space is complete), it follows that
 $S_0(Z)$
is an RV; see [Reference Doob16, Theorems 2.7 and 2.8] for details of the case
 $d=1$
.
Corollary 2.1. Suppose that Z satisfies the assumptions of Theorem 2.1 and further
 \begin{equation*} \mathbb{P}\biggl\{{\sup_{t\in \mathbb{R}^d} Z(t)>0} \biggr\}=1. \end{equation*}
If
 $ S_\eta(Z) = \infty $
almost surely for some
 $\eta\ge 0$
, then
 $H_{Z}^\delta=0$
for all
 $\delta \ge 0$
. Conversely, if
 $H_{Z}^\delta=0$
for some
 $\delta \ge 0$
, then
 $S_\eta(Z)=\infty $
almost surely for all
 $\eta\ge 0$
.
Remark 2.1.
-
(i) The assumption
$\mathbb{P} \{ {\sup_{t\in \mathbb{R}^d} Z(t)>0} \} =1$
in Corollary 2.1 cannot be removed. Taking for instance
$Z(t)= V/p$
,
$t\in \mathbb{R}^d$
, with V a Bernoulli RV such that
$\mathbb{P} \{ {V=1} \} =p\in (0,1)$
, we get
$H_{Z}^\delta=0$
for all
$\delta\ge 0$
. However,
$S_1(Z)=0$
with probability
$1-p>0$
. -
(ii) Let Z(t),
$t\in \mathbb{R}^d$
, be a stationary RF satisfying the assumptions of Theorem 2.1. By the definition and the fact that Z and
$\tilde Z= 1+ Z$
are both stationary, the corresponding Pickands constants exist and we simply have
$H_{Z}^\delta=H_{\tilde Z}^\delta$
for all
$\delta\ge 0$
. Clearly
$S_{1}(\tilde Z)=\infty $
and
$\mathbb{P} \{ {\sup_{t\in \mathbb{R}^d} \tilde Z(t)>0} \} =1$
, hence Corollary 2.1 implies
$H_Z^\delta=0$
and moreover
$S_\eta(Z)=\infty , \eta \ge 0$
if further
$\mathbb{P} \{ {\sup_{t\in \mathbb{R}^d} Z(t)>0} \} =1$
.
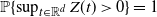


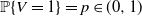


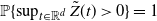


In the rest of this section we consider Y(t),
 $t\in \mathbb{R}^d$
, a stationary max-stable RF as in Section 1 with spectral RF Z and de Haan representation (1.7). Suppose next that Z has sample paths almost surely in the space
 $D=D(\mathbb{R}^d, [0,\infty ))$
of generalised càdlàg functions
 $f\colon \mathbb{R}^d \to [0,\infty )$
equipped with the
 $\sigma$
-field
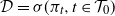 $\mathcal{D}=\sigma(\pi_t, t\in \mathcal{T}_0)$
generated by the projection maps
 $\pi_t\colon \pi_t f= f(t)$
,
 $f\in D$
, and
 $\mathcal{T}_0$
a dense subset of
 $\mathbb{R}^d$
. See e.g. [Reference Janson21] and [Reference Bladt, Hashorva and Shevchenko4] for the definition and properties of generalised càdlàg functions. In view of [Reference Hashorva19, Theorem 6.9] (take
 $\alpha=1$
and
 $L=B^{-1}$
therein), the stationarity of Y is equivalent to the validity of
 \begin{equation} \mathbb{E}\{{ Z(h) F(Z)}\} = \mathbb{E}\{{ Z(0) F(B^h Z)}\}\end{equation}
for all
 $h\in \mathbb{R}^d$
and all 0-homogeneous measurable functionals
 $F\colon D \mapsto [0,\infty )$
(0-homogeneous means
 $F(cf)=F(f), \forall c>0, f\in D$
) with
 $B^h Z(\cdot)= Z(\cdot-h)$
,
 $h\in \mathbb{R}^d$
. For discrete max-stable processes, (2.1) is stated in [Reference Planinić and Soulier30, eq. (5.2)]; see also [Reference Soulier37] for other equivalent formulations. We note in passing that (2.1) is initially derived for Z as in Example 2.1 below in [Reference Dieker and Mikosch12, Lemma 5.2].
Clearly, if Z is stationary, then Y is stationary too. However, this instance is not interesting, since as shown in Remark 2.1, (ii)
 $H_{Z}^0=0$
in this case. We discuss below two other examples such that max-stable RF Y is stationary.
Example 2.1. It is known from [Reference Kabluchko23] and [Reference Hashorva19] that if
 $X(t)= W(t)- \textrm{Var}(W(t))/2$
,
 $t\in \mathbb{R}^d$
, with W a centered Gaussian RF with stationary increments and almost surely continuous sample paths, then both (1.3) and (1.6) hold with
 $Z(t)={\mathrm{e}}^{X(t)}$
. Using for instance [Reference Vitale39, Theorem 1], we have that (1.5) holds. Moreover, in view of [Reference Kabluchko, Schlather and de Haan24], the corresponding max-stable RF Y is stationary.
Example 2.2. Let L(t),
 $t\in \mathbb{R}^d$
, be a non-negative deterministic measurable function such that
 $\int_{\mathbb{R}^d} {L (t)}\lambda({\mathrm{d}} t) = 1, $
with
 $\lambda({\mathrm{d}} t)$
the Lebesgue measure on
 $\mathbb{R}^d$
. It follows easily that
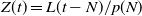 $ Z(t) = L(t-N) / p(N) $
,
 $t\in \mathbb{R}^d$
, with N an
 $\mathbb{R}^d$
-valued RV having a positive density function
 $p(t)>0, t\in \mathbb{R}^d$
satisfies (1.6). Note that for this case condition (1.5) reads as
 \begin{equation} \int_{x\in \mathbb{R}^d} \sup_{t\in [0,T]^d} {L(t-x)} \lambda( {\mathrm{d}} x)< \infty \quad \text{for all } T>0.\end{equation}
As shown in [Reference Hashorva20, Theorem 1, eq. (3.5)], without any further assumption on the max-stable stationary RF Y, for
 $\delta=\eta> 0$
we have
 \begin{equation} H_{Z}^\delta = \mathbb{E}\biggl\{{ {Z(0)} \dfrac{\sup_{t\in \delta \mathbb{Z}^d } {Z(t)} }{S_\eta(Z) } }\biggr\} \in [0,\infty ).\end{equation}
In the next result we show that the above holds under some weak assumptions also for
 $\delta=0$
. It turns out that under (2.4) below we can also obtain the first formula in (1.2).
Proposition 2.1. Let Z(t),
 $t\in \mathbb{R}^d$
, be a non-negative RF with almost surely sample paths in D. If (1.3), (1.5), and (2.1) hold and
 $H_{Z}^0>0$
, then (2.3) holds for
 $\delta=\eta= 0$
. Moreover, (2.3) holds also for
 $\delta=0$
,
 $\eta>0$
or
 $\delta>0$
,
 $\eta=k\delta$
,
 $k \in \mathbb{N} $
if also
 \begin{equation} \{ S_0(Z) < \infty \} \subset \{ S_\eta(B^r Z) \in (0,\infty ) \} \quad {for\ all\ } r\in \delta \mathbb{Z}^d\end{equation}
almost surely.
Remark 2.2. It is shown in the proof of Proposition 2.1 that (2.4) is implied by the assumption
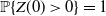 $\mathbb{P} \{ {Z(0)>0} \} =1$
, which is satisfied for the choice of Z as in Example 2.1. In particular, Proposition 2.1 extends Theorems 2 and 3 of [Reference Dębicki, Engelke and Hashorva11] and Proposition 2 of [Reference Dieker and Yakir13]. Moreover, as discussed in Example 2.3 below, condition (2.4) cannot be removed.
Example 2.3. Let L(t),
 $t\in \mathbb{R}^d$
, be as in Example 2.2 and suppose further that
 $L(t)>0$
,
 $t\in \mathbb{R}^d$
, (2.2) holds and
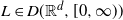 $L \in D(\mathbb{R}^d, [0,\infty ))$
. Then the claim of Theorem 2.1 follows. Moreover, Proposition 2.1 implies for all
 $\eta >0$
 \begin{equation} H_{Z}^0=\int_{\mathbb{R}^d} L (s)\dfrac{ \sup_{t\in \mathbb{R}^d} {L(t+s)} } { \eta^d \sum_{t\in \eta \mathbb{Z}^d} {L(t+s)} } \lambda({\mathrm{d}} s)= \sup_{t\in \mathbb{R}^d} {L (t) } ,\end{equation}
where the last equality follows by (2.3) with
 $\delta=0$
(recall that
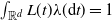 $\int_{\mathbb{R}^d} L(t) \lambda({\mathrm{d}} t)=1$
). It is mentioned in [Reference Dieker and Yakir13] that for
 $d=1$
and L the standard Gaussian density on
 $\mathbb{R}$
, the above identity could be verified numerically. As shown by Dmitry Zaporozhets (personal communications) the last two equalities in (2.5) can be derived by utilising the translation invariance of both the Lebesgue measure and the counting measure, respectively, and applying the Fubini–Tonelli theorem. Specifically, setting
 $\eta=1$
for simplicity,
 \begin{align*}\int_{\mathbb{R}^d}\dfrac{ L (s) } { \sum_{t\in \mathbb{Z}^d} {L(t+s)} } \lambda({\mathrm{d}} s) &=\sum_{ r \in \mathbb{Z}^d} \int_{ r+ [0,1)^d }\dfrac{ L(s) } { \sum_{t\in \mathbb{Z}^d} {L(t+s)} } \lambda({\mathrm{d}} s)\\ &= \sum_{ r \in \mathbb{Z}^d} \int_{ [0,1)^d }\dfrac{ L(r+s) } { \sum_{t\in \mathbb{Z}^d} {L(r+t+s)} } \lambda({\mathrm{d}} s)\\ &= \int_{ [0,1)^d }\sum_{ r \in \mathbb{Z}^d}\dfrac{ L(r+s) } { \sum_{t\in \mathbb{Z}^d} {L(t+s)} } \lambda({\mathrm{d}} s)=1.\end{align*}
Our initial proof of Proposition 2.1 was asymptotic in nature. A modification of Zaporozhets’ arguments and (2.1) led to the current proof of Proposition 2.1.
Note that if we take for instance
 $L(t)=\textbf{1}{\{{t\in [0,1]}\}}$
,
 $d=1$
, with
 $\textbf{1}{\{{\cdot}\}}$
the indicator function, then
 $H_Z^0$
cannot be given by (2.3) with
 $\eta>2$
, since the first equality in (2.5) gives
 $H_Z^0=\infty $
, which is a contradiction to the fact that
 $H_Z^ 0< \infty $
. For this choice of
 $\eta$
we have that condition (2.4) is not satisfied.
3. Two extensions
Motivated by [Reference Samorodnitsky36] and [Reference Samorodnitsky35], we first consider an alternative definition of Pickands constants
 $H_{\lvert {f} \rvert,m}^\delta $
defined with respect to a collection of functions
 $f_s\colon E \to \mathbb{R} $
, with
 $(E, \mathcal{E})$
a measurable space equipped with some
 $\sigma$
-finite measure m. In the second part of this section we discuss the constant
 $\mathcal{H}_{Z}^\delta$
defined in (1.10), also proving its continuity at
 $\delta=0$
.
3.1. Behaviour of
$\boldsymbol{H}_{\lvert \boldsymbol{f} \rvert\boldsymbol{,m}}^{\boldsymbol\delta} $
at
$\delta=0$


Let m be a
 $\sigma$
-finite measure on some measurable space
 $(E, \mathcal{E})$
and
 $f=f_s(z)$
,
 $s\in \mathbb{R}^d$
,
 $z\in E$
real functions, where
 $f_s \in \mathcal{L}^1 (m)$
(
 $\mathcal{L}^\alpha(m)$
is the set of all functions g such that
 $\int_{E}|g(x)|^\alpha m( {\mathrm{d}} x)<\infty$
and
 $\alpha>0$
). We now define for any
 $\delta =1/n$
,
 $n \in \mathbb{N} $
, or
 $\delta=0$
 \begin{equation*} H_{\lvert {f} \rvert,m}^\delta = \lim_{{T} \to \infty} \dfrac{1}{T^d}\int_{E } \sup_{t\in [0,T]^d \cap \delta \mathbb{Z}^d} \lvert {f_t (z)} \rvert m( {\mathrm{d}} z),\end{equation*}
where
 $0\mathbb{Z}^d$
equals
 $\mathbb{Q}^d_*$
, with
 $\mathbb{Q}_*$
the set of dyadic rational numbers
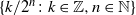 $\{{k}/{2^n}\colon k\in \mathbb{Z}, n\in \mathbb{N} \}$
. Clearly the above limit is in general not defined. In order to include the case
 $\delta=0$
, we shall assume further that
 \begin{equation} \int_E \sup_{t\in K \cap \mathbb{Q}_*^d} \lvert {f_t(z)} \rvert m( {\mathrm{d}} z) < \infty \end{equation}
and, similarly to (1.6), we have
 \begin{equation} \int_E \sup_{t\in K \cap \mathbb{Q}_*^d } \lvert {f_{t+c}(z)} \rvert m( {\mathrm{d}} z) = \int_E \sup_{t\in K \cap \mathbb{Q}_*^d } \lvert {f_{t}(z)} \rvert m( {\mathrm{d}} z) \quad\text{for all } c\in \mathbb{Q}_*^d\end{equation}
for all compact sets
 $K \subset \mathbb{R}^d$
.
If L is as in Example 2.2, then taking
 $f_t(z)= L(z-t)$
,
 $t, z\in \mathbb{R}^d$
,
 $E=\mathbb{R}^d$
equipped with the Borel
 $\sigma$
-field and
 $m( {\mathrm{d}} z)$
the Lebesgue measure on
 $\mathbb{R}^d$
, we have that (3.1) holds and further (3.2) is satisfied since
 $m( {\mathrm{d}} z)$
is shift-invariant.
Example 3.1. Let Y(t),
 $t\in \mathbb{R}^d$
, be a symmetric
 $\alpha$
-stable stationary RF with locally bounded sample paths,
 $\alpha \in (0,2)$
, and representation
 \begin{equation*} Y(t) = \int_E f_t(z) M( {\mathrm{d}} z) , \quad t\in \mathbb{R}^d , \end{equation*}
where M is a symmetric
 $\alpha$
-stable random measure on E with control measure m and
 $f_t\in \mathcal{L}^\alpha(m)$
,
 $t\in \mathbb{R}^d$
; see [Reference Samorodnitsky36]. It follows that both (3.1) and (3.2) hold; see [Reference Samorodnitsky36] for the case
 $d=1$
and [Reference Roy33] for the case
 $d>1$
.
With the same arguments as in the proof of Theorem 2.1, we have that under (3.1) and (3.2), constant
 $H_{\lvert {f} \rvert,m}^\delta $
is finite, non-negative, and further
 \begin{equation} \lim_{{n} \to \infty} H_{\lvert {f} \rvert, m}^{2^{-n}} =H_{\lvert {f} \rvert, m}^{0} .\end{equation}
Remark 3.1. For Y as in Example 3.1, explicit formulas for
 $H_{\lvert {f} \rvert, m}^{\delta} $
are derived in [Reference Samorodnitsky36], [Reference Samorodnitsky35], and [Reference Roy and Samorodnitsky34]. Utilising the relation between
 $\alpha$
-stable and max-stable processes (see [Reference Kabluchko22]), the aforementioned formulas imply (2.3) when
 $\delta=\eta\ge 0$
.
3.2. Continuity of
$\mathcal{H}_Z^\delta$
at
$\delta=0$


Let
 $W_z(t)$
,
 $t\in \mathbb{R}^d$
,
 $z\in [0,1] $
, be a centered Gaussian RF with stationary increments, almost surely continuous sample paths, and variance function
 $\sigma^2_z$
,
 $z\in [0,1]$
, such that
 $\sigma^2_z(0)=0$
for all
 $z\in [0,1].$
We formulate below the assumptions on the variance functions
 $\sigma_z^2$
imposed in Theorem 3.1 below. Specifically, we shall assume that
 \begin{equation} \lim_{w\to z}\sigma_w(t)=\sigma_z(t) \quad \text{for all } z \in [0,1], \ t\in \mathbb{R}^d\end{equation}
and further, for some
 $C_{0},C_{\infty}$
positive and
 $\nu_{0},\nu_{\infty}\in (0,2] $
,
 \begin{equation} \limsup_{\lVert {t} \rVert\to 0} \dfrac{ \sigma_z^2(t)}{\lVert {t} \rVert^{\nu_{0}}} \le C_{0}\quad \text{and}\quad\limsup_{\lVert {t} \rVert\to \infty} \dfrac{ \sigma_z^2(t)}{\lVert {t} \rVert^{\nu_{\infty}}} \le C_{\infty}\end{equation}
hold for all
 $z\in [0,1]$
, where
 $\lVert {\cdot} \rVert$
denotes the Euclidean norm on
 $\mathbb{R}^d$
.
Theorem 3.1. If (3.4) and (3.5) are satisfied, then for any
 $\delta\geq 0$
and
 $Z_z(t)= \exp( W_z(t)- \sigma_z^2(t)/2)$
,
 \begin{equation}\mathcal{H}_{{{Z}}}^\delta = \lim_{{T} \to \infty} T^{-d} \int_0^1 \mathbb{E}\biggl\{{\sup_{ t\in [0,T]^d \cap \delta \mathbb{Z}^d }Z_z (t) }\biggr\} \,{\mathrm{d}} z=\int_0^1 H_{Z_z}^\delta \,{\mathrm{d}} z \in [0,\infty) ,\end{equation}
and furthermore
 $\lim_{\delta \downarrow 0} \mathcal{H}_{Z}^\delta= \mathcal{H}_{Z}^0$
.
Remark 3.2.
-
(i) A sufficient condition for
$H_{Z_z}^\delta, z\in [0,1]$
to be positive is (3.7)(see [Reference Dębicki and Hashorva9]). If the above holds for
\begin{equation}\lim_{{\lVert {t} \rVert} \to \infty} \dfrac{ \sigma_z^2(t)}{ \ln \lVert {t} \rVert} > 8 d\end{equation}
$z\in [0,1]$
on a set with non-zero Lebesgue measure, then under the assumptions of Theorem 3.1 we have that
$\mathcal{H}_{Z}^\delta>0$
for any
$\delta \ge 0$
.
-
(ii) In order to define RFs
$W_z,z\in [0,1]$
with stationary increments, we need to determine variance function
$\sigma^2_z(t)= \textrm{Var}( W_z(t+s)- W_z(t))$
,
$s,t\in \mathbb{R}^d$
, which is a negatively (or conditionally negatively) definite function. One example is to start with a negatively definite variance function
$\sigma^2(t)$
,
$t\in \mathbb{R}^d$
, and then define
$\sigma_z(t)= q(z) \sigma(t)$
for some continuous function q not identical to zero. Such
$\sigma_z$
clearly satisfies (3.4) and if
$\sigma^2(t)\le C \lVert {t} \rVert^\nu$
,
$t\in \mathbb{R}^d$
, then (3.5) also holds. Another example is to consider
$\sigma_z$
as in [Reference Chan and Lai5], namely (3.8)where
\begin{equation}\sigma^2_z(t) = \lVert {t} \rVert^\lambda r_z(t/\lVert {t} \rVert), \quad \lambda \in (0,2], \ t\in \mathbb{R}^d,\end{equation}
$r_z$
is a non-negative function defined on the unit sphere on
$\mathbb{R}^d$
determined by the norm
$\lVert {\cdot} \rVert$
.


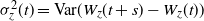


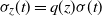


4. Proofs
Proof of Theorem 2.1. In view of (1.5) and (1.6),
 \begin{equation}\mathbb{E}\biggl\{{ \sup_{t\in K \cap \delta \mathbb{Z}^d} Z(t+c)}\biggr\}= \mathbb{E}\biggl\{{ \sup_{t\in K \cap \delta \mathbb{Z}^d} Z(t)}\biggr\}< \infty\end{equation}
holds for all
 $c\in \mathbb{R}^d$
,
 $\delta \ge 0$
, and all compact sets
 $K\subset \mathbb{R}^d$
. Next, assume for notational simplicity that
 $d=1$
. In light of (4.1),
 $\mathbb{E}\{{ \sup_{t\in [0,T] \cap \delta \mathbb{Z} } {Z(t)}}\}$
,
 $T>0$
, is a subadditive function of T for any
 $\delta\ge 0$
, implying that
 $H_Z^\delta$
is a finite non-negative constant (recall that Z is non-negative) in view of Fekete’s lemma. Further, to show the second part of the theorem it is enough to take
 $T= a_\delta n$
, where
 $a_\delta=\lfloor 1/\delta \rfloor \delta $
with
 $\lfloor x \rfloor$
the integer part of
 $x>0$
and
 $n \in \mathbb{N} $
 $\delta \in (0,1/2)$
. Utilising (4.1) to derive the last equality in the next calculations, we have
 \begin{align} & \mathbb{E}\biggl\{{ \sup_{t\in [0,T]} {Z(t)} }\biggr\}-\mathbb{E}\biggl\{{ \max_{t\in [0,T] \cap \delta \mathbb{Z}} {Z(t)} }\biggr\}\nonumber\\&\quad = \mathbb{E}\biggl\{{ \max_{ 1 \le i \le n} \sup_{t\in [a_\delta(i-1),a_\delta i]} {Z(t)} - \max_{ 1 \le i \le n} \max_{t\in [a_\delta(i-1),a_\delta i] \cap \delta \mathbb{Z}} {Z(t)} }\biggr\}\nonumber\\&\quad \leq \mathbb{E}\biggl\{{ \max_{ 1 \le i \le n} \biggl(\sup_{t\in [a_\delta(i-1),a_\delta i]} {Z(t)} - \max_{t\in [a_\delta(i-1),a_\delta i] \cap \delta \mathbb{Z}} {Z(t)} \biggr) }\biggr\}\nonumber\\&\quad \le \sum_{i=1}^n \mathbb{E}\biggl\{{ \sup_{t\in [a_\delta(i-1),a_\delta i]} {Z(t)} - \max_{t\in [a_\delta(i-1),a_\delta i] \cap \delta \mathbb{Z}} {Z(t)} }\biggr\}\nonumber\\&\quad = n \mathbb{E}\biggl\{{ \sup_{t\in [0,a_\delta]} {Z(t)} - \max_{t\in [0,a_\delta] \cap \delta \mathbb{Z}} {Z(t)} }\biggr\}.\end{align}
The assumption that Z is stochastically continuous implies that any dense subset of
 $\mathbb{R}^d$
is a separant for the separable RF Z (see e.g. [Reference Potthoff31, Theorem 2.9]) and therefore, since
 $\lim_{\delta \downarrow 0} a_\delta=1$
, we have the following convergence in probability:
 \begin{equation*}\max_{t\in [0,a_\delta] \cap \delta \mathbb{Z}} {Z(t)} \to \sup_{t\in [0,1]} {Z(t)}\end{equation*}
as
 $\delta \downarrow 0$
. Hence, by (1.5) and the dominated convergence theorem,
 \begin{equation} \lim_{\delta \downarrow 0 } \mathbb{E}\biggl\{{ \max_{t\in [0,a_\delta ] \cap \delta \mathbb{Z}} {Z(t)} }\biggr\}=\mathbb{E}\biggl\{{ \sup_{t\in [0,1]} {Z(t)}}\biggr\}< \infty .\end{equation}
Consequently (4.2) implies
 \begin{align*} \dfrac{1}{T} \mathbb{E}\biggl\{{ \max_{t\in [0,T] \cap \delta \mathbb{Z}} {Z(t)}}\biggr\} & \leq \dfrac{1}{T} \mathbb{E}\biggl\{{ \sup_{t\in [0,T]} {Z(t)}}\biggr\}\\ &\leq a_\delta^{-1} \mathbb{E}\biggl\{{ \sup_{t\in [0,a_\delta]} {Z(t)} - \max_{t\in [0,a_\delta] \cap \delta \mathbb{Z}} {Z(t)} }\biggr\}+ \dfrac{1}{T}\mathbb{E}\biggl\{{ \max_{t\in [0,T] \cap \delta \mathbb{Z}} {Z(t)}}\biggr\}.\end{align*}
Since
 $H^\delta_Z$
exists and is finite for all
 $\delta \ge 0$
, we have
 \begin{equation*} \lim_{{T} \to \infty} \dfrac{1}{T} \mathbb{E}\biggl\{{ \sup_{t\in [0,T]} {Z(t)}}\biggr\} = \lim_{{n} \to \infty} \dfrac{1}{ n a_\delta } \mathbb{E}\biggl\{{ \sup_{t\in [0,n a_\delta]} {Z(t)}}\biggr\} = H^0_Z\end{equation*}
and
 \begin{equation*} \lim_{{T} \to \infty} \dfrac{1}{T} \mathbb{E}\biggl\{{ \sup_{t\in [0,T] \cap \delta \mathbb{Z} } {Z(t)}}\biggr\} =\lim_{{n} \to \infty} \dfrac{1}{ n a_\delta }\mathbb{E}\biggl\{{ \sup_{t\in [0,n a_\delta] \cap \delta Z} {Z(t)}}\biggr\} = H^\delta _Z \le H^0_Z<\infty .\end{equation*}
Thus, letting n to infinity, we obtain from the above inequalities
 \begin{equation}0 \leq H_{Z}^{0 }-H_{Z}^{\delta } \leq a_\delta^{-1} \mathbb{E}\biggl\{{ \sup_{t\in [0,a_\delta]} {Z(t)} - \max_{t\in [0,a_\delta] \cap \delta \mathbb{Z}} {Z(t)} }\biggr\},\end{equation}
which together with (4.3) yields
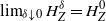 $\lim_{\delta \downarrow 0} H_{Z}^{\delta }= H_{Z}^0$
.
Proof of Corollary 2.1. First, let us notice that
 $H_{Z^{}}^\delta =0$
for some
 $\delta\geq 0$
if and only if
 $S_\delta(Z)=\infty $
almost surely, which is a direct implication of [Reference Dombry and Kabluchko14], [Reference Kabluchko22], and [Reference Roy and Samorodnitsky34, Reference Samorodnitsky35, Reference Samorodnitsky36] ; this has already been discussed in [Reference Ehlert and Schlather17], [Reference Dębicki and Hashorva9], and [Reference Soulier37] for the case
 $d=1$
, and [Reference Hashorva20] for the d-dimensional discrete setup. Note in passing that in [Reference Dombry and Kabluchko14] Z is such that
 $\mathbb{P} \{ {\sup_{t\in \mathbb{R}^d} Z(t)> 0} \} =1$
. So if for some
 $\eta>0$
we have
 $H_{Z}^\eta=0$
, then
 $S_{\eta/k}( Z) = \infty $
almost surely for any
 $k\in N$
and
 $H_{Z }^{\eta/k}=0$
. Consequently, Theorem 2.1 implies that
 $\lim_{{k} \to \infty}H_{Z }^{\eta/k}=H_{Z }^0=0$
and hence
 $0\le H_{Z}^\eta\le H_{Z }^{0}= 0$
for all
 $\eta\ge 0$
. Conversely, if for some
 $\eta\ge 0$
we have
 $S_{\eta}( Z) = \infty $
, then from the above equivalence
 $H_{Z}^\eta=0$
for all
 $\eta\ge 0$
, hence the proof is complete.
Proof of Proposition 2.1. The claim for
 $\delta=\eta=0$
follows as in [Reference Dębicki and Hashorva9], where
 $d=1$
is considered and its proof is therefore omitted.
Now let
 $D=D(\mathbb{R}^d, [0,\infty ))$
be the space of generalised càdlàg functions
 $f\colon \mathbb{R}^d \mapsto [0,\infty )$
, which can be equipped with a metric that turns it into a Polish space. The corresponding Borel
 $\sigma$
-field in D denoted by
 $\mathcal{D}$
agrees with the
 $\sigma$
-field
 $\sigma(\pi_t, t\in \mathcal{T}_0)$
for any
 $\mathcal{T}_0$
a dense subset of
 $\mathbb{R}^d$
; see e.g. [Reference Bladt, Hashorva and Shevchenko4, Theorem 7.1]. Let
 $\Theta(t)$
,
 $t\in \mathbb{R}^d$
, denote an RF with almost surely sample paths in D defined by
 \begin{equation*}\mathbb{P} \{ { \Theta \in A} \} = \mathbb{E}\{{ Z(0) \textbf{1} ( Z/Z(0)\in A)}\}/\mathbb{E}\{{ Z(0)}\} \quad \text{for all } A \in \mathcal{D},\end{equation*}
where we interpret
 $0:0$
as 0 and set
 $\textbf{1} ( x\in A)$
equal to 1 or 0 if
 $x\in A$
or
 $x\not \in A$
, respectively. Note that
 $\mathbb{E}\{{ Z(0)}\}$
equals 1, but we leave it since the same formula is applied to
 $Z_*$
below. Note further that since D is Polish, by [Reference Varadarajan38, lemma on page 1276] we can realise both Z and
 $\Theta$
in the same complete non-atomic probability space that we assume for notational simplicity below. By (2.1), for any measurable functional
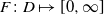 $F\colon D \mapsto [0,\infty ]$
that is 0-homogeneous,
 \begin{equation} \mathbb{E}\{{ \Theta (h) F(\Theta)}\} =\mathbb{E}\{{ \textbf{1} ( Z(0)\not=0) Z (h) F(Z)}\}= \mathbb{E}\{{ \textbf{1} (\Theta(-h) \not=0 ) F(B^h \Theta) } \}.\end{equation}
In view of Corollary 2.1, the assumption
 $H^0_{Z}>0$
implies
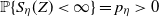 $\mathbb{P} \{ {S_\eta(Z)< \infty } \} =p_\eta >0$
for all
 $\eta\ge 0$
. If
 $p_0=1$
, then
 $\mathbb{P} \{ {S_0(\Theta) < \infty } \} =1$
also follows, and thus
 \begin{equation} \{ S_\eta(\Theta) < \infty \} \subset \{ S_0(\Theta)< \infty \} \end{equation}
almost surely.
Assume next that
 $p_0\in (0,1)$
. The RF
 $Z_*(t)=Z(t) \mid S_0(Z) = \infty , \,t\in \mathbb{R}^d $
has almost surely sample paths in D and satisfies (2.1). Let
 $\Theta_*$
denote the corresponding RF of
 $Z_*$
defined by the change of measure as above. We have that
 $\Theta_*$
has the same law as
 $\Theta \mid S_0(\Theta)= \infty $
. Since
 $ S_0( Z_*) =\infty $
with probability 1, applying Corollary 2.1, we obtain
 $ S_\eta(Z_*)=\infty $
almost surely and thus
 $S_\eta (\Theta_*)=\infty $
almost surely, that is,
 \begin{equation*}\mathbb{P} \{ { S_\eta(\Theta)=\infty , S_0(\Theta)= \infty } \} /\mathbb{P} \{ {S_0(\Theta)= \infty } \} =1\end{equation*}
(implying
 $ \{ S_0(\Theta) = \infty \} \subset \{ S_\eta(\Theta) = \infty \}$
almost surely), and hence (4.6) holds. If
 $\mathbb{P} \{ {S_0(Z)< \infty } \} =0$
, then by Corollary 2.1
 $\mathbb{P} \{ {S_\eta(Z)< \infty } \} =0$
for all
 $\eta>0$
, which in turn implies
 $\mathbb{P} \{ { S_\eta(\Theta) < \infty } \} =0$
. The assumption
 $p_0=0$
also implies
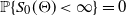 $\mathbb{P} \{ { S_0(\Theta) < \infty }\} =0$
, hence again (4.6) holds.
Next suppose that
 $\mathbb{P} \{ {S_0(\Theta)< \infty } \} >0$
. Since then
 $\mathbb{P} \{ {S_0(Z)< \infty } \} >0$
, we can define
 $Z_*(t)=Z(t) \mid S_0(Z) < \infty $
,
 $ t\in \mathbb{R}^d $
, as above. The corresponding
 $\Theta_*$
has the same law as
 $\Theta \mid S_0(\Theta)< \infty $
. Since
 $\mathbb{P} \{ {S_0(Z_*)< \infty } \} =\mathbb{P} \{ {S_0(\Theta_*)< \infty } \} =1$
, by [Reference Soulier37, Theorem 2.8],
 \begin{equation*}\mathbb{P}\biggl\{{\lim_{\lVert {t} \rVert\to \infty , t\in \eta \mathbb{Z}^d} \Theta_*(t) =0}\biggr\}=1,\end{equation*}
with
 $\lVert {\cdot} \rVert$
some norm on
 $\mathbb{R}^d$
. The latter is equivalent to
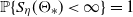 $\mathbb{P} \{ {S_\eta(\Theta_*)< \infty } \} =1$
; see [Reference Hashorva20, Condition A2, A4]. As in the proof of [Reference Hashorva20, Lemma A.2],
 $\mathbb{P} \{ { S_0(\Theta) < \infty } \} =0 \iff p_0=0$
and thus the reverse inclusion to (4.6) holds, implying
 \begin{equation}\{ S_\eta(\Theta) < \infty \} =\{ S_0(\Theta)< \infty \}\quad \text{for all } \eta>0\end{equation}
almost surely. Since further
 $\mathbb{P} \{ {S_\eta(\Theta)>0} \} =1$
for all
 $\eta\ge 0$
, which follows from
 $\mathbb{P} \{ {\Theta(0)=1} \} =1$
and the fact that
 $\Theta$
has paths in D almost surely, we have almost surely for all
 $\delta,\eta \in [0,\infty )$
 \begin{equation} \dfrac{ 1 }{S_\eta(\Theta)} =\dfrac{ 1 }{S_\eta(\Theta)} \dfrac{ S_\delta(\Theta)} {S_\delta(\Theta)}\Theta(0).\end{equation}
Now set
 $S_\eta(f)= \int_{ \eta \mathbb{Z}^d} f (t)\lambda_\eta({\mathrm{d}} t)$
,
 $\eta\ge 0$
, and
 \begin{equation*}M_\eta(f)= \sup_{t\in \eta \mathbb{Z}^d} f (t), \quad M_0(f)= \sup_{t\in \mathcal{T}_0} f(t),\quad f\in D,\ \eta >0. \end{equation*}
Both maps
 $S_\eta(\cdot)$
and
 $M_\eta(\cdot)$
,
 $\eta \ge 0$
, are measurable and by the separability of Z we have that
 $M_0(Z)$
has the same law as
 $\sup_{t\in \mathbb{R}^d} Z(t)$
. Hence, also using the definition of
 $\Theta$
and (4.8), by the Fubini–Tonelli theorem, for all
 $\delta\not=\eta$
,
 $\delta \ge 0$
,
 $\eta>0$
we have
 \begin{align} & \mathbb{E}\biggl\{{ Z (0) \dfrac{ \sup_{t\in \delta \mathbb{Z}^d} Z (t)}{S_{\eta }(Z)}}\biggr\}\notag\\[4pt]&\quad = \mathbb{E}\biggl\{{ \dfrac{ \sup_{t\in \delta \mathbb{Z}^d} \Theta (t)}{S_{\eta }(\Theta)}}\biggr\} \notag\\[4pt]&\quad = \mathbb{E}\biggl\{{ \dfrac{ \sup_{t\in \delta \mathbb{Z}^d} \Theta (t)}{S_{\eta }(\Theta)} \dfrac{ S_\delta(\Theta)}{ S_\delta(\Theta)} \Theta(0)}\biggr\} \notag\\[4pt]&\quad = \int_{\delta \mathbb{Z}^d}\mathbb{E}\biggl\{{ \dfrac{ M_\delta ( \Theta)}{ S_\delta(\Theta)}\dfrac{ \Theta (0)}{ S_{\eta }(\Theta) } \Theta (s) }\biggr\} \lambda_\delta ({\mathrm{d}} s) \notag\\[4pt]&\quad = \sum_{i \in \eta \mathbb{Z}^d} \int_{r\in [0,\eta)^d \cap \delta \mathbb{Z}^d }\mathbb{E}\biggl\{{ \dfrac{ M_ \delta (\Theta) }{ S_\delta(\Theta) }\dfrac{ \Theta (0)}{ S_{\eta }(\Theta)} \Theta (i+r) }\biggr\} \lambda_\delta ({\mathrm{d}} r), \end{align}
where in the last equality we also used the translation invariance of
 $\lambda_\delta$
. Now, by (4.5), for all
 $i,r \in \mathbb{R}^d$
,
 \begin{equation}\mathbb{E}\biggl\{{ \Theta (i+r) \dfrac{M_ \delta (\Theta) }{ S_\delta(\Theta) }\dfrac{ \Theta (0)}{ S_{\eta }(\Theta)}}\biggr\} = \mathbb{E}\biggl\{{ \dfrac{\ M_ \delta (B^{r+i}\Theta)}{ S_\delta(B^{r+i}\Theta)} \dfrac{\Theta (-i-r) }{S_{\eta }(B^{r+i}\Theta)} }\biggr\}.\end{equation}
Note in passing that
 $\Theta(-i-r) \textbf{1} (\Theta(-i-r) \not=0 )=\Theta(-i-r) $
almost surely.
If
 $\delta=0$
,
 $\eta>0$
or
 $\delta>0$
and
 $\eta= k\delta$
,
 $k\in \mathbb{N} $
, then almost surely, for all
 $i \in \eta \mathbb{Z}^d, r\in \delta \mathbb{Z}^d$
,
 \begin{equation} M_ \delta (B^{r+i}\Theta)= M_ \delta (\Theta), \quad S_\delta(B^{r+i}\Theta)= S_\delta(\Theta), \quad S_{\eta }(B^{r+i}\Theta) =S_{\eta }(B^{r}\Theta),\end{equation}
and from (2.4)
 \begin{align*} S_\delta (\Theta) < \infty &= \mathbb{P} \{ {S_0 (\Theta) < \infty } \} \\[3pt]&= \mathbb{E}\{{ Z(0) \textbf{1}{\{{ S_0(Z)< \infty }\}}}\}\\[3pt]&= \mathbb{E}\{{ Z(0) \textbf{1}{\{{ S_0(Z)< \infty , S_\eta(B^r Z) \in (0,\infty ) }\}}}\}\\[3pt]&= \mathbb{E}\{{ Z(0) \textbf{1}{\{{ S_{\delta}(Z)< \infty , S_\eta(B^r Z) \in (0,\infty ) }\}}}\}\\[3pt]&= \mathbb{E}\{{ Z(0) \textbf{1}{\{{ S_{\delta}(Z/Z(0))< \infty , S_\eta(B^r Z/Z(0)) \in (0,\infty ) }\}}}\}\\[3pt]&= \mathbb{P} \{ { S_\delta(\Theta) < \infty , S_\eta(B^r \Theta) \in (0,\infty )} \} \quad \text{for all } r\in \delta \mathbb{Z}^d,\end{align*}
where the third-to-last line follows from (4.7). Consequently, almost surely
 \begin{equation} \dfrac {S_{\eta }(B^r\Theta) }{S_{\eta }(B^r\Theta)} \textbf{1}{\{{S_\delta(\Theta) <\infty }\}} = \textbf{1}{\{{S_\delta(\Theta) <\infty }\}} .\end{equation}
Hence, for these choices of
 $\delta $
and
 $\eta$
, (4.9)–(4.12) and the Fubini–Tonelli theorem yield
 \begin{align*} \mathbb{E}\biggl\{{ Z(0) \dfrac{ \sup_{t\in \delta \mathbb{Z}^d} Z(t)}{S_{\eta }(Z)}}\biggr\}&= \int_{r\in [0,\eta)^d \cap \delta \mathbb{Z}^d }\mathbb{E}\biggl\{{ \dfrac{\ M_ \delta (\Theta)}{ S_\delta(\Theta)} \sum_{i \in \eta \mathbb{Z}^d} \dfrac{\Theta (-r-i) }{S_{\eta }(B^r\Theta)} }\biggr\} \lambda_\delta ({\mathrm{d}} r) \\[4pt]&= \eta^{-d} \int_{r\in [0,\eta)^d \cap \delta \mathbb{Z}^d }\mathbb{E}\biggl\{{ \dfrac{\ M_ \delta (\Theta)}{ S_\delta(\Theta)} \dfrac {S_{\eta }(B^r\Theta) }{S_{\eta }(B^r\Theta)} \textbf{1}{\{{S_\delta(\Theta) <\infty }\}} }\biggr\} \lambda_\delta ({\mathrm{d}} r) \\[4pt]&= \eta^{-d} \int_{r\in [0,\eta)^d \cap \delta \mathbb{Z}^d }\mathbb{E}\biggl\{{ \dfrac{ M_ \delta (\Theta)}{ S_\delta(\Theta)} \textbf{1}{\{{S_\delta(\Theta) <\infty }\}} } \biggr\} \lambda_\delta ({\mathrm{d}} r) \\[4pt]&= \mathbb{E}\biggl\{{ \dfrac{ M_ \delta (\Theta)}{ S_\delta(\Theta)} }\biggr\}\\[4pt]&= \mathbb{E}\biggl\{{ Z(0)\dfrac{\sup_{t\in \delta \mathbb{Z}^d} Z(t)}{ S_\delta(Z)} }\biggr\}, \end{align*}
and hence the claim follows from (2.3).
Note that if
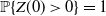 $\mathbb{P} \{ {Z(0)>0} \} =1$
, by (2.1) for all
 $ t\in \mathbb{R}^d$
,
 \begin{equation*} \mathbb{E}\{{ Z(t)}\}=\mathbb{E}\{{ Z(t) \textbf{1}{\{{Z(0) >0}\}}}\}=\mathbb{E}\{{ Z(0) \textbf{1}{\{{Z(-t) >0}\}}}\} =\mathbb{E}\{{Z(0)}\}, \end{equation*}
and hence
 $\mathbb{P} \{ {Z(t)>0} \} =\mathbb{P} \{ {\Theta(t)>0} \} =1 $
since
 $\mathbb{E}\{{Z(t)}\}=\mathbb{E}\{{Z(0)}\}=1$
. Consequently, applying (4.5) and utilising (4.7) for all
 $r\in \mathbb{R}^d$
,
 $\eta>0$
,
 \begin{align*}& \mathbb{E}\{{ Z(-r) \textbf{1}{\{{ S_0(Z) < \infty , 0< S_\eta(B^r Z) < \infty }\}}}\}\\ &\quad =\mathbb{E}\{{ \Theta(-r)\textbf{1}{\{{ S_0(\Theta) < \infty , 0< S_\eta(B^r\Theta) < \infty }\}}}\}\\&\quad = \mathbb{E}\{{ \textbf{1}{\{{ S_0(\Theta) < \infty , 0< S_\eta(\Theta) < \infty }\}}}\}\\ &\quad = \mathbb{E}\{{\textbf{1}{\{{ S_0(\Theta) < \infty }\}}}\}\\ &\quad= \mathbb{E}\{{ Z(0) \textbf{1}{\{{ S_0(Z) < \infty }\}}}\}\\ &\quad = \mathbb{E}\{{ Z(-r) \textbf{1}{\{{ S_0(Z) < \infty }\}}}\}\\ &\quad \le 1,\end{align*}
and thus (2.4) follows. The reason that the indicator function did not appear when we applied (4.5) in the above calculations is that
 $\Theta(t)>0$
almost surely for all
 $t\in \mathbb{R}^d$
.
Proof of Theorem 3.1. Let
 $z\in [0,1]$
be fixed. For simplicity we consider the case
 $d=1$
and set
 $X_z(t)=W_z(t)-\sigma^2_z(t)/2$
. We now show that for any positive T the function
 \begin{equation*} A_T(z)=\mathbb{E}\biggl\{{ \sup_{t\in [0,T] \cap \delta \mathbb{Z}} \,{\mathrm{e}}^{ X_{z}(t)}}\biggr\}\end{equation*}
is continuous in z and thus integrable for any
 $\delta\ge 0$
. First note that, by (1.5),
 \begin{equation*} \mathbb{E}\biggl\{{ \sup_{t\in [0,T] \cap \delta \mathbb{Z}} \,{\mathrm{e}}^{ X_{z}(t)}}\biggr\} =1+ \int_{0}^\infty \,{\mathrm{e}}^s \mathbb{P}\biggl\{{ \sup_{t\in [0,T] \cap \delta \mathbb{Z}} X_{z}(t)> s} \biggr\} \,{\mathrm{d}} s< \infty .\end{equation*}
Since
 $\sigma_z$
determines the covariance function of
 $X_{z }$
, then (3.4) implies that FIDIs of
 $X_{z+h }$
converge weakly to those of
 $X_z$
as
 $h\to 0$
. Moreover, for some
 $\varepsilon >0$
and all
 $ \lvert {h} \rvert< \varepsilon $
, by (3.5),
 \begin{equation*} \textrm{Var} ( X_{z+h} (s)- X_{z+h}(t))= \sigma^2_{z+h}(t-s) \le C \lVert {t-s} \rVert^{\nu_{0}} \end{equation*}
for some
 $C>0$
and all
 $t,s \in [0,T]$
. Consequently,
 $X_{z+h}(t)$
,
 $t\in [0,T]$
, is tight (with respect to h) and converges weakly in the space of real-valued continuous functions on [0,T] equipped with the uniform topology; see [Reference Piterbarg29, Proposition 9.7]. Hence, by the continuous mapping theorem for almost all
 $s \in \mathbb{R}$
,
 \begin{equation*} \lim_{ h \to 0} \mathbb{P}\biggl\{{ \sup_{t\in [0,T] \cap \delta \mathbb{Z}} X_{z+h}(t)> s} \biggr\} =\mathbb{P}\biggl\{{ \sup_{t\in [0,T] \cap \delta \mathbb{Z}} X_{z}(t)> s} \biggr\}.\end{equation*}
Consequently, for all
 $T>0$
,
 \begin{equation*} \lim_{ h \to 0}\mathbb{E}\biggl\{{ \sup_{t\in [0,T] \cap \delta \mathbb{Z}} \,{\mathrm{e}}^{ X_{z+h}(t)}}\biggr\} =\mathbb{E}\biggl\{{ \sup_{t\in [0,T] \cap \delta \mathbb{Z}} \,{\mathrm{e}}^{ X_{z}(t)}}\biggr\} =A_T(z)< \infty ,\end{equation*}
implying the claim that
 $A_T(z)$
,
 $z\in [0,1]$
, is continuous in z. The derivation above rests on the application of the dominated convergence theorem that can be justified by the Borell–TIS inequality. Indeed, for all
 $z\in [0,1]$
,
 \begin{equation*}\sup_{t\in [0,T] \cap \delta \mathbb{Z}} \,{\mathrm{e}}^{ X_{z}(t)}\leq \sup_{t\in[0,T], v\in[0,1]}\,{\mathrm{e}}^{W_v(t)}\end{equation*}
and
 \begin{equation*}\mathbb{E}\biggl\{{ \sup_{t\in [0,T], v\in[0,1]} \,{\mathrm{e}}^{ W_{v}(t)}}\biggr\}= 1+\int_0^\infty \,{\mathrm{e}}^s\mathbb{P}\biggl\{{\sup_{t\in[0,T],v\in [0,1]}W_v(t)>s} \biggr\} \,{\mathrm{d}} s.\end{equation*}
By the Borell–TIS inequality and (3.5),
 \begin{equation*}\mathbb{P}\biggl\{{\sup_{t\in[0,T], v\in [0,1]}W_v(t)>s} \biggr\}\leq {\exp\biggl({-\frac{(s-Q_1)^2}{2Q_2}}\biggr)}\end{equation*}
for sufficiently large s and
 $Q_1,Q_2$
positive constants, which justifies the limit above. Since by assumption (3.5), for some
 $C>0$
and all
 $z\in [0,1]$
, we have
 \begin{equation*} \sigma_z^2(t) \le C (\lVert {t} \rVert^{\nu_{0}}+ \lVert {t} \rVert^{\nu_{\infty}}) \,=\!:\, \sigma^2(t),\end{equation*}
then for the Gaussian process
 \begin{equation*}X(t)= W_0(t)+W_\infty(t)- \sigma^2(t)/2,\quad t\in [0,T],\end{equation*}
with
 $W_0,\,W_\infty$
mutually independent centered Gaussian processes with continuous sample paths, stationary increments and variance function
 $C\lVert {t} \rVert^{\nu_{0}},C\lVert {t} \rVert^{\nu_{\infty}}$
, respectively, applying [Reference Dębicki and Hashorva9, Theorem 3.1] we obtain for any
 $z\in [0,1]$
 \begin{equation*} H_{Z_z}^\delta \le H_{\widetilde{Z}}^\delta \in (0,\infty ),\end{equation*}
where
 $\widetilde{Z}(t)=\exp(X(t))$
,
 $ t\in [0,T]$
, and
 \begin{equation*} \mathbb{E}\biggl\{{ \sup_{t\in [0,T] \cap \delta \mathbb{Z}} \,{\mathrm{e}}^{ X_{z}(t)}}\biggr\} \le \mathbb{E}\biggl\{{ \sup_{t\in [0,T] \cap \delta \mathbb{Z}} \,{\mathrm{e}}^{ X(t)}}\biggr\}< \infty .\end{equation*}
Consequently, by the measurability of
 $A_T(z)$
,
 $z\in [0,1]$
, and the dominated convergence theorem,
 \begin{equation*} \mathcal{H}_{{Z}}^\delta = \lim_{{T} \to \infty} T^{-d} \int_0^1 \mathbb{E}\biggl\{{\sup_{ t\in [0,T]^d \cap \delta \mathbb{Z}^d } \,{\mathrm{e}}^{ X_z (t)} } \biggr\} \,{\mathrm{d}} z = \int_0^1 H_{Z_{z}}^\delta \,{\mathrm{d}} z \le H^{\delta}_{\widetilde{Z}} < \infty .\end{equation*}
Thus, in view of Theorem 2.1, we obtain
 \begin{equation*} \lim_{\delta \downarrow 0} \mathcal{H}_{{Z}}^\delta =\int_0^1\lim_{\delta \downarrow 0} H_{Z_z}^\delta \,{\mathrm{d}} z = \int_0^1 H_{Z_z}^0 \,{\mathrm{d}} z \ge 0,\end{equation*}
which completes the proof.
Acknowledgements
We are in debt to the referees for their comments and suggestions, which led to substantial improvement of the manuscript. We thank Dmitry Zaporozhets for several important discussions and the elegant proof of (2.5).
Funding information
Partial support by SNSF grant 200021-196888 and NCN grant 2018/31/B/ST1/00370 (2019-2022) is kindly acknowledged.
Competing interests
There were no competing interests to declare which arose during the preparation or publication process of this article.



