



1. Introduction
The main goal of this paper is to analyze the discounted probability of exponential Parisian ruin for the scaled classical Cramér–Lundberg risk model and its corresponding diffusion approximation. The scaling system is obtained by multiplying the Poisson rate
 $\lambda$
by n, dividing the claim severity by
 $\sqrt{n}$
, and adjusting the premium rate so that net premium income remains constant. We use comparison to prove that the discounted probability of exponential Parisian ruin for the scaled classical risk model converges to that of its diffusion approximation. We also show that the rate of convergence for the discounted probability of exponential Parisian ruin is of order
 ${\mathrm{O}}\! \left(n^{-1/2}\right)$
, uniformly with respect to the surplus. These results form the main theorem of our paper.
Iglehart [Reference Iglehart10] used probabilistic techniques to prove that the probability of ruin for the scaled model converges to that of its corresponding diffusion approximation. See also Grandell [Reference Grandell7], Asmussen [Reference Asmussen3], and Bäuerle [Reference Bäuerle4]. More recently, Cohen and Young [Reference Cohen and Young6] used comparison to bound the probability of ruin and prove that the probability of ruin for the scaled CL process converges to the probability of ordinary ruin for the corresponding diffusion approximation. This paper extends Cohen and Young [Reference Cohen and Young6] to a generalization of ordinary ruin called exponential Parisian ruin.
(Ordinary) Parisian ruin occurs if an excursion below zero of surplus is longer than a deterministic time, whereas exponential Parisian ruin occurs if the excursion below zero is longer than an independent exponentially distributed random variable. Landriault, Renaud, and Zhou [Reference Landriault, Renaud and Zhou12], Baurdoux et al. [Reference Baurdoux, Pardo, Pérez and Renaud5], and Landriault, Li, and Lkabous [Reference Landriault, Li and Lkabous11], who studied exponential Parisian ruin, relied on probabilistic analysis of the so-called scale functions. Lkabous and Renaud [Reference Lkabous and Renaud14] also relied on scale functions to analyze a model that combines deterministic and exponential Parisian ruin. Instead, we use comparison methods in integro-differential equations to study the (discounted) probability of exponential Parisian ruin.
We define exponential Parisian ruin by starting the ‘exponential clock’ at the time of ordinary ruin. Equivalently, because of the memoryless property of the exponential, one could randomly observe the surplus processes, with the waiting times between observations distributed exponentially, and declare that exponential Parisian ruin has occurred if the observed surplus is negative. For example, Albrecher, Cheung, and Thonhauser [Reference Albrecher, Cheung and Thonhauser1] computed the Gerber–Shiu penalty function for the classical risk model with i.i.d. inter-observation times distributed according to an Erlang(n) random variable, which reduces to the exponential when
 $n = 1$
. Also, Albrecher, Ivanovs, and Zhou [Reference Albrecher, Ivanovs and Zhou2] computed exit quantities for a Lévy risk model with i.i.d. inter-observation times distributed exponentially.
The remainder of this paper is organized as follows. In Section 2.1 we define the discounted probability of exponential Parisian ruin for the classical risk process and derive its integro-differential equation (IDE), and in Section 2.2 we define the scaled model and extend the IDE to this model. Furthermore, we provide a comparison lemma that forms the backbone of the proofs in Section 4.1. Section 2.3 provides an explicit expression for the discounted probability of exponential Parisian ruin for the diffusion approximation of the classical risk model, and Section 2.4 gives an outline of the remainder of the paper.
In Sections 3.1 and 3.2, we define analogs of the adjustment coefficient for the scaled classical risk model and for its diffusion approximation, respectively, and in Section 3.3 we prove four lemmas that show how these adjustment coefficients are related. In Section 4.1 we use the comparison lemma from Section 2.2 to modify the discounted probability of exponential Parisian ruin for the diffusion approximation by functions of order
 ${\mathrm{O}}\! \left(n^{-1/2}\right)$
to obtain upper and lower bounds of the corresponding discounted probability for the scaled classical risk model. Finally, in Section 4.2, we use these bounds to prove that the discounted probability of exponential Parisian ruin for the scaled classical risk model converges to that of its diffusion approximation. We also show that the rate of convergence is of order
 ${\mathrm{O}}\! \left(n^{-1/2}\right)$
, uniformly with respect to the surplus.
2. Scaled Cramér–Lundberg model and its diffusion approximation
2.1. Cramér–Lundberg model
We assume the insurer’s surplus process
 $X = \{X_t\}_{t \ge 0}$
is described by the classical Cramér–Lundberg model defined on a filtered probability space
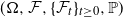 $(\Omega, \mathcal{F}, \{\mathcal{F}_t\}_{t \ge 0}, \mathbb{P})$
, that is, the insurer receives premium income at a constant rate c and pays claims according to a compound Poisson process. Specifically,
 \begin{equation*} X_t = x + ct - \sum_{i = 1}^{N_t} Y_i,\end{equation*}
in which x is the initial surplus, the claim severities
 $Y_1, Y_2, \dots$
are independent and identically distributed according to a common cumulative distribution function
 $F_Y$
, with
 $F_Y (0) = 0$
, and the claim frequency
 $N = \{ N_t \}_{t \ge 0}$
follows a Poisson process with parameter
 $\lambda > 0$
. Let
 $S_Y = 1 - F_Y$
denote the survival function of Y, and assume that there exists an
 $\varepsilon > 0$
such that Y’s moment generating function
 $M_Y(\gamma) = \mathbb{E} ({\mathrm{e}}^{\gamma Y})$
exists for any
 $\gamma < \varepsilon$
. In particular,
 $\mathbb{E} Y < \infty$
and
 $\mathbb{E} ( Y^2 ) < \infty$
. Also, assume that the Poisson process N is independent of the claim severity process
 $\{ Y_i\}_{i \in \mathbb{N}}$
. Finally, assume that the premium rate
 $c > \lambda \mathbb{E} Y$
, and write
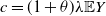 $c = (1 + \theta)\lambda \mathbb{E} Y$
, with a positive risk loading
 $\theta > 0$
.
By following Landriault et al. [Reference Landriault, Renaud and Zhou12] and Baurdoux et al. [Reference Baurdoux, Pardo, Pérez and Renaud5], we define the sequence
 $\big\{\big(\tau^{-}_{0,n}, \tau^{+}_{0,n}\big)\big\}_{n \in \mathbb{N}}$
recursively. First, let
 \begin{equation*}\tau^{-}_{0,1} = \inf \{t \ge 0\colon X_t < 0\}\end{equation*}
be the first time that the process X enters
 $({-}\infty, 0)$
, and let
 \begin{equation*}\tau^{+}_{0,1} = \inf \{t > \tau^{-}_{0,1}\colon X_t > 0\}\end{equation*}
be the first time after
 $\tau^{-}_{0,1}$
that the process X enters
 $(0, \infty)$
. Then, for
 $n = 2, 3, \dots$
, define
 \begin{equation*}\tau^{-}_{0,n} = \inf \{t > \tau^{+}_{0,n-1}\colon X_t < 0\}\end{equation*}
and
 \begin{equation*}\tau^{+}_{0,n} = \inf \{t > \tau^{-}_{0,n}\colon X_t > 0\}.\end{equation*}
By exponential Parisian ruin we mean an excursion of surplus below zero in excess of an exponentially distributed random length of time. Specifically, we define the time of exponential Parisian ruin
 $\kappa$
by
 \begin{equation}\kappa = \tau^{-}_{0, n'} + \tau^{n'}_\rho,\end{equation}
in which
 $\{\tau^n_\rho\}_{n \in \mathbb{N}}$
is a sequence of i.i.d. copies of an exponential random variable
 $\tau_\rho$
with hazard rate
 $\rho$
, independent of the claim process, and in which n
′ is defined by
 \begin{equation*} n' = \inf \left\{ n \in \mathbb{N}\colon \tau^{-}_{0, n} + \tau^n_\rho < \tau^{+}_{0, n} \right\}\!.\end{equation*}
Define the exponential Parisian ruin process
 $K = \{K_t\}_{t \ge 0}$
by
 $K_t = {\textbf{1}}_{\{\kappa \le t\}}$
for all
 $t \ge 0$
; thus K jumps from 0 to 1 when exponential Parisian ruin occurs. Then we define the filtration
 $\mathbb{H} = \{ \mathcal{H}_t \}_{t \ge 0}$
by
 \begin{equation*}\mathcal{H}_t = \mathcal{F}_t \vee \sigma(K_u\colon 0 \le u \le t)\quad\text{for all $t \ge 0$.}\end{equation*}
We wish to analyze the discounted probability of exponential Parisian ruin, with value function
 \begin{equation}\psi(x) = \mathbb{E}^x \left( {\mathrm{e}}^{-\beta \kappa} {\textbf{1}}_{\{\kappa < \infty\}} \right)\!,\end{equation}
in which
 $\mathbb{E}^x$
denotes expectation conditional on
 $X_0 = x$
, and
 $\beta > 0$
measures the insurer’s time value of exponential Parisian ruin.
Note that we start the ‘exponential clock’
 $\tau_\rho$
at the time of ordinary ruin. Instead, we could have created an independent Poisson process
 $N^\rho = \{N^\rho_t\}_{t \ge 0}$
with hazard rate
 $\rho$
, in which the time that
 $N^\rho$
jumps marks a time that the surplus process X is observed. Then exponential Parisian ruin occurs the first time X is negative at a time of observation. The memoryless property of the exponential tells us that this definition of exponential Parisian ruin is equivalent to the one in (2.1).
Albrecher et al. [Reference Albrecher, Cheung and Thonhauser1] derived the integro-differential equation (IDE) for the Gerber–Shiu penalty function when inter-observational times are distributed exponentially, as they are in this paper. We derive the IDE for
 $\psi$
defined in (2.2) by following the method in Section 5.3 of [Reference Schmidli15]. Let
 $h > 0$
be small, and consider the following possible events related to the interval (0, h]: (1) neither a claim nor an observation occurs, with probability
 ${\mathrm{e}}^{-(\lambda + \rho)h}$
, (2) a claim occurs at time
 $t \le h$
before an observation occurs, with probability (density)
 $\lambda {\mathrm{e}}^{-(\lambda + \rho)t}$
, and (3) an observation occurs at time
 $t \le h$
before a claim occurs, with probability (density)
 $\rho {\mathrm{e}}^{-(\lambda + \rho)t}$
. As an aside, note that
 \begin{equation*} {\mathrm{e}}^{-(\lambda + \rho)h} + \int_0^h \lambda {\mathrm{e}}^{-(\lambda + \rho)t} {\mathrm{d}} t + \int_0^h \rho {\mathrm{e}}^{-(\lambda + \rho)t} {\mathrm{d}} t = 1. \end{equation*}
This partition of the event space gives us the following expansion of
 $\psi$
:
 \begin{align*}\psi(x) &= {\mathrm{e}}^{-(\lambda + \rho)h} \cdot {\mathrm{e}}^{-\beta h} \psi(x + ch) + \int_0^h \lambda {\mathrm{e}}^{-(\lambda + \rho)t} \int_0^\infty {\mathrm{e}}^{-\beta t} \psi(x + ct - y) \,{\mathrm{d}} F_Y(y) \,{\mathrm{d}} t \\&\quad + \int_0^h \rho {\mathrm{e}}^{-(\lambda + \rho)t} \left( {\mathrm{e}}^{-\beta t} \psi(x + ct) {\textbf{1}}_{\{ x + ct \ge 0\}} + {\mathrm{e}}^{-\beta t} {\textbf{1}}_{\{ x + ct < 0\}} \right) \,{\mathrm{d}} t.\end{align*}
As Schmidli [Reference Schmidli15] notes, by letting
 $h \to 0^+$
in the above expression, we deduce that
 $\psi$
is right-continuous. Then the right derivative of
 $\psi$
(times c) equals
 \begin{align}c \psi_x(x) &= \lim_{h \to 0^+} \dfrac{\psi(x + ch) - \psi(x)}{h}\\& = (\beta + \lambda + \rho) \psi(x) - \lambda \int_0^\infty \psi(x - y) \,{\mathrm{d}} F_Y(y) - \rho\left( \psi(x) {\textbf{1}}_{\{ x \ge 0\}} + {\textbf{1}}_{\{ x < 0\}} \right)\!,\nonumber \end{align}
and a similar argument starting at the point
 $x - ch$
for
 $h > 0$
small, allows us to conclude that
 $\psi$
is left continuous and gives us the expression in (2.3) for the left derivative of
 $\psi(x)$
if
 $x \ne 0$
. Thus we have the following IDE for
 $\psi$
on
 $\mathbb{R}$
, in which we use the right derivative of
 $\psi$
at
 $x = 0$
:
 \begin{equation}\beta \psi(x) + \rho (\psi(x) - 1 ) {\textbf{1}}_{\{x < 0\}} = c \psi_x(x) + \lambda (\mathbb{E} \psi(x - Y) - \psi(x)),\end{equation}
with
 $\psi \in \mathcal{C}^1(\mathbb{R} \backslash \{0\})$
,
 $\psi$
continuous at
 $x = 0$
, and
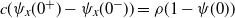 $c(\psi_x(0^+) - \psi_x(0^-)) = \rho(1 - \psi(0))$
. To obtain boundary conditions for
 $\psi$
, we argue as follows. As surplus becomes arbitrarily large negative, then
 $\kappa$
approaches
 $\tau_\rho$
with probability 1, and
 \begin{equation*}\lim_{x \to -\infty} \psi(x) = \mathbb{E}^x \left( {\mathrm{e}}^{-\beta \tau_\rho} {\textbf{1}}_{\left\{\tau_\rho < \infty\right\}} \right) = \int_0^\infty {\mathrm{e}}^{-\beta t} \cdot \rho {\mathrm{e}}^{-\rho t} \,{\mathrm{d}} t = \dfrac{\rho}{\rho + \beta} .\end{equation*}
Similarly, as surplus becomes arbitrarily large positive, then
 $\kappa$
approaches
 $\infty$
with probability 1, and
 \begin{equation*}\lim_{x \to \infty} \psi(x) = \lim_{x \to \infty} \mathbb{E}^x \left( {\mathrm{e}}^{-\beta \kappa} {\textbf{1}}_{\{\kappa < \infty\}} \right) = 0.\end{equation*}
For later convenience, use the IDE in (2.4) to define the operator F by
 \begin{align}F (x, u(x), u_x(x), u(x - \cdot) ) = \beta u(x) + \rho (u(x) - 1 ) {\textbf{1}}_{\{x < 0\}} - c u_x(x)- \lambda (\mathbb{E} u(x - Y) - u(x)),\end{align}
in which we use the right derivative at
 $x = 0$
. Then the IDE for
 $\psi$
is
 $F = 0$
, with boundary conditions
 \begin{align}\lim_{x \to -\infty} u(x) = \dfrac{\rho}{\rho + \beta} , \quad \lim_{x \to \infty} u(x) = 0.\end{align}
Landriault et al. [Reference Landriault, Renaud and Zhou12] (semi-)explicitly computed
 $\psi$
in Proposition 2.1 and Corollaries 3.1 and 3.2; they referred to
 $\psi$
as the Laplace transform of the time of Parisian ruin with exponentially distributed implementation delays. Also, Albrecher et al. [Reference Albrecher, Cheung and Thonhauser1,Reference Albrecher, Ivanovs and Zhou2] provided semi-explicit expressions for
 $\psi$
.
2.2. Scaled Cramér–Lundberg model
To obtain the scaled classical risk model, multiply the Poisson rate
 $\lambda$
by n, divide the claim severity by
 $\sqrt{n}$
, and adjust the premium rate so that net premium income remains constant. Specifically, define
 $\lambda_n = n \lambda$
, so n large is equivalent to
 $\lambda_n$
large. Scale the claim severity by defining
 $Y_n = Y/\sqrt{n}$
. Also, define
 $\theta_n = \theta/\sqrt{n}$
and
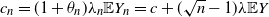 $c_n = (1 + \theta_n) \lambda_n \mathbb{E} Y_n = c + (\sqrt{n} - 1) \lambda \mathbb{E} Y$
, which implies
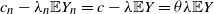 $c_n - \lambda_n \mathbb{E} Y_n = c - \lambda \mathbb{E} Y = \theta \lambda \mathbb{E} Y$
, independent of n. The parameters
 $\rho$
and
 $\beta$
remain unchanged. Let
 $X^n = \{ X^n_t \}_{t \ge 0}$
denote the resulting scaled process. Note that our original model, the one described in Section 2.1, corresponds to
 $n = 1$
.
Let
 $\psi_n$
denote the discounted probability of exponential Parisian ruin in the scaled system. Then the IDE for
 $\psi_n$
is
 $F_n = 0$
, in which
 $F_n$
is a modification of the operator in (2.5) for the scaled model, that is,
 \begin{align}F_n (x, u(x), u_x(x), u(x - \cdot) ) &= \beta u(x) + \rho (u(x) - 1 ) {\textbf{1}}_{\{x < 0\}} - (\sqrt{n} + \theta)\lambda\mathbb{E} Y u_x(x) \notag \\&\quad - n \lambda (\mathbb{E} u(x - Y/\sqrt{n} \,) - u(x)),\end{align}
in which we use the right derivative at
 $x = 0$
.
Liang and Young [Reference Liang and Young13] analyzed the problem of minimizing the discounted probability of exponential Parisian ruin via per-loss reinsurance. One of the main results in that paper, Theorem 3.3, a comparison theorem for viscosity sub- and supersolutions, is readily adaptable to the problem in this paper; therefore we state Lemma 2.1 below without proof, after we define sub- and supersolutions of
 $F_n = 0$
. For this paper, we do not need the machinery of viscosity sub- and supersolutions, so we define sub- and supersolutions more narrowly.
Definition 2.1. Suppose u is a continuously differentiable function on its domain, except possibly at
 $x = 0$
, at which it is continuous with left and right derivatives.
-
(a) We say that u is a subsolution of the integro-differential equation
 $F_n = 0$
on
$\mathbb{R}$
(or
$\mathbb{R}^{-}$
or
$\mathbb{R}^+)$
if
$F_n (x, u(x), u_x(x), u(\cdot) ) \le 0$
for all
$x \in \mathbb{R}$
(or
$x < 0$
or
$x \ge 0$
, respectively), in which we use the right derivative at
$x = 0$
, as necessary.
-
(b) We say that u is a supersolution of the integro-differential equation
$F_n = 0$
on
$\mathbb{R}$
(or
$\mathbb{R}^{-}$
or
$\mathbb{R}^+)$
if
$F_n (x, u(x), u_x(x), u(\cdot) ) \ge 0$
for all
$x \in \mathbb{R}$
(or
$x < 0$
or
$x \ge 0$
, respectively), in which we use the right derivative at
$x = 0$
, as necessary.


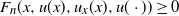


In Section 4.1 we use the following lemma to find bounds for
 $\psi_n$
. One can also use the lemma to prove that
 $\psi_n$
is the unique solution of
 $F_n = 0$
on
 $\mathbb{R}$
subject to the boundary conditions in (2.6). As an aside, the proof of Lemma 2.1 of [Reference Cohen and Young6] can also be used to prove this lemma.
Lemma 2.1. (Comparison principle.)
-
(a) If u and v are sub- and supersolutions, respectively, of
$F_n = 0$
on
$\mathbb{R}$
with then
\begin{equation*}\lim_{x \to - \infty} u(x) \le \lim_{x \to - \infty} v(x)\quad {and}\quad \lim_{x \to \infty} u(x) \le \lim_{x \to \infty} v(x),\end{equation*}
$u \le v$
on
$\mathbb{R}$
.
-
(b) If u and v are sub- and supersolutions, respectively, of
$F_n = 0$
on
$\mathbb{R}^{-}$
with then
\begin{equation*}\lim_{x \to - \infty} u(x) \le \lim_{x \to - \infty} v(x) \quad{and}\quad u(0^-) \le v(0^-),\end{equation*}
$u \le v$
on
$\mathbb{R}^{-}$
.
-
(c) If u and v are sub- and supersolutions, respectively, of
$F_n = 0$
on
$\mathbb{R}^+$
with then
\begin{equation*}u(x) \le v(x) \quad\text{for all $ x \le 0$}\ and\ \text{$ \lim\limits_{x \to \infty} u(x) \le \lim\limits_{x \to \infty} v(x)$,}\end{equation*}
$u \le v$
on
$\mathbb{R}^+$
.


2.3. Diffusion approximation
In this section we introduce the diffusion approximation of the classical risk process. To obtain this approximation, we match the first two moments at all times
 $t \ge 0$
, as in [Reference Grandell8]. Specifically, for
 $n = 1$
,
 \begin{equation*}Y \,{\mathrm{d}} N_t \approx \lambda \mathbb{E} Y {\mathrm{d}} t - \sqrt{\lambda \mathbb{E}(Y^2)} \,{\mathrm{d}} B_t,\end{equation*}
in which
 $B = \{ B_t \}_{t \ge 0}$
is a standard Brownian motion on the filtered probability space
 $( \Omega, \mathcal{F}, \mathbb{F}, \mathbb{P} )$
. Thus, under the diffusion approximation, the surplus
 $\widetilde X = \{\widetilde X_t \}_{t \ge 0}$
equals
 \begin{equation*} \widetilde X_t = x + \mu t + \sigma B_t,\end{equation*}
in which
 $\mu = \theta \lambda \mathbb{E} Y$
and
 $\sigma = \sqrt{\lambda \mathbb{E}(Y^2)}$
. For the scaled process, note that
 \begin{equation*}\theta_n \lambda_n \mathbb{E}(Y_n) = \theta \lambda \mathbb{E} Y = \mu\end{equation*}
and
 \begin{equation*}\lambda_n \mathbb{E}\!\left(Y_n^2\right) = \lambda \mathbb{E}\!\left(Y^2\right) = \sigma^2,\end{equation*}
so the diffusion approximation for the scaled process is independent of the scaling factor n.
Let
 $\widetilde \kappa$
and
 $\widetilde \psi$
denote the time of exponential Parisian ruin of
 $\widetilde X$
and the discounted probability thereof, respectively. In general we will notate quantities related to the diffusion approximation by a tilde. We next state a relevant verification lemma without proof because its proof is standard in the actuarial and financial mathematics literature; see e.g. the proof of Theorem 3.1 of [Reference Han, Liang and Young9].
Lemma 2.2. Suppose
 $u: \mathbb{R} \to [0, \, {\rho}/{(\rho + \beta)} ]$
is a function that satisfies the following conditions.
-
1. u is decreasing and lies in
$\mathcal{C}^2(\mathbb{R}),$
except at 0, where it is
$\mathcal{C}^1$
and has left and right second derivatives. -
2.
$\lim\limits_{x \to -\infty} u(x) = {\rho}/{(\rho + \beta)} $
. -
3.
$\lim\limits_{x \to -\infty} u(x) = 0$
. -
4. u solves the following differential equation on
$\mathbb{R}$
: (2.8)in which we use the right second derivative of u at
\begin{equation}\beta u(x) + \rho( u(x) - 1) {\textbf{1}}_{\{x < 0\}} = \mu u_x(x) + \dfrac{1}{2} \, \sigma^2 u_{xx}(x),\end{equation}
$x = 0$
.


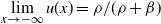


Then the discounted probability of exponential Parisian ruin
 $\widetilde \psi$
for the diffusion
 $\widetilde X$
equals u.
Note the parallel between the left-hand sides of (2.8) and (2.4). The term
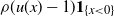 $\rho( u(x) - 1) {\textbf{1}}_{\{x < 0\}}$
arises from the exponential clock that runs when the surplus is below zero; the clock’s alarm ‘rings’ at rate
 $\rho$
, and if it does, then
 $\widetilde \psi(x)$
jumps to 1 because exponential Parisian ruin has occurred.
The only dependence of the differential equation in (2.8) upon the state variable x is whether
 $x < 0$
or
 $x \ge 0$
; otherwise the coefficients are constant. Thus the solution will be piecewise exponential, and we give that solution in the following proposition.
Proposition 2.1. The discounted probability of exponential Parisian ruin under the diffusion approximation equals
 \begin{equation}\widetilde \psi(x) =\begin{cases}\dfrac{\rho}{\rho + \beta} \biggl(1 - \dfrac{\widetilde \gamma_1}{\widetilde \gamma_1 + \widetilde \gamma_2} \,{\mathrm{e}}^{\widetilde \gamma_2 x} \biggr), & x < 0, \\[16pt]\dfrac{\rho}{\rho + \beta} \, \dfrac{\widetilde \gamma_2}{\widetilde \gamma_1 + \widetilde \gamma_2} \,{\mathrm{e}}^{- \widetilde \gamma_1 x}, & x \ge 0,\end{cases}\end{equation}
in which
 $\widetilde \gamma_1 > 0$
and
 $\widetilde \gamma_2 > 0$
, respectively, are given by
 \begin{equation}\widetilde \gamma_1 = \dfrac{1}{\sigma^2} \biggl[ \sqrt{\mu^2 + 2 \beta \sigma^2} + \mu \biggr]\end{equation}
and
 \begin{equation}\widetilde \gamma_2 = \dfrac{1}{\sigma^2} \biggl[ \sqrt{\mu^2 + 2 (\rho + \beta) \sigma^2} - \mu \biggr],\end{equation}
with
 $\mu = \theta \lambda \mathbb{E} Y$
and
 $\sigma^2 = \lambda \mathbb{E}\!\left(Y^2\right)$
.
Remark 2.1. Corollary 1.1 of [Reference Baurdoux, Pardo, Pérez and Renaud5] gives us the discounted probability of exponential Parisian ruin in terms of scale functions for a general Lévy insurance model. In our work, we instead solve
 $\widetilde \psi$
’s differential equation to explicitly obtain the value of discounted probability of exponential Parisian ruin for the diffusion approximation, a special case of their Lévy insurance model.
2.4. Outline of paper
To make it easier to follow the material in Sections 3 and 4, we outline our steps in those sections, as follows.
-
1. In Section 3 we define analogs of the so-called adjustment coefficient from risk theory; for background on the adjustment coefficient see e.g. Section 5.4 of [Reference Schmidli15].
-
(a) In Section 3.1 we define analogs of the adjustment coefficient for the scaled Cramér–Lundberg model. Denote them by
$\gamma_{1,n}$
and
$\gamma_{2,n}$
, in which they are based on the problem when
$x \ge 0$
and
$x < 0$
, respectively. -
(b) In Section 3.2 we show that
$\widetilde \gamma_1$
and
$\widetilde \gamma_2$
from Section 2.3 are the analogs of the adjustment coefficient for the diffusion approximation. -
(c) In Section 3.3 we prove four lemmas that relate
$(\gamma_{1,n}, \gamma_{2,n})$
to
$(\widetilde \gamma_1, \widetilde \gamma_2)$
. In particular, we show
$\lim_{n \to \infty} \gamma_{1,n} = \widetilde \gamma_1$
and
$\lim_{n \to \infty} \gamma_{2,n} = \widetilde \gamma_2$
.
-
-
2. In Section 4 we justify using the diffusion approximation for the classical risk process when analyzing the discounted probability of exponential Parisian ruin.
-
(a) In Section 4.1 we modify
$\widetilde \gamma$
by functions of order
${\mathrm{O}}\! \left(n^{-1/2}\right)$
to obtain upper and lower bounds of
$\psi_n$
; denote those bounds by
$u_n$
and
$\ell_n$
, respectively. We use Lemma 2.1 to prove that, indeed,
$\ell_n \le \psi_n \le u_n$
on
$\mathbb{R}$
. Propositions 4.2 and 4.1 prove these two inequalities, respectively. -
(b) Finally, in Section 4.2, we use Propositions 4.1 and 4.2 to prove Theorem 4.1, the main result of our paper, which states that, as n goes to infinity,
$\psi_n$
converges to
$\widetilde \psi$
uniformly with respect to x and with rate of convergence of order
${\mathrm{O}}\! \left(n^{-1/2}\right)$
.
-


3. Analogs of the adjustment coefficient
3.1. Scaled Cramér–Lundberg model
In this section we define analogs of the adjustment coefficient for the scaled Cramér–Lundberg model for the discounted probability of exponential Parisian ruin
 $\psi_n$
. We will use those analogs to create an exponential upper bound of
 $\psi_n$
.
To define the analogs of the adjustment coefficient, we split the problem according to whether
 $x \ge 0$
and
 $x < 0$
. We begin with
 $x \ge 0$
because that is familiar to most readers. A formal way of obtaining the adjustment coefficient is to substitute
 $A {\mathrm{e}}^{-\gamma x}$
for u in
 $F_n = 0$
, including when
 $x - Y/\sqrt{n} < 0$
. Recall that
 $F_n$
is given in (2.7). By doing so, we obtain the following equation for the adjustment coefficient
 $\gamma_{1,n} > 0$
:
 \begin{equation}\beta = \lambda [{-} (\sqrt{n} + \theta)\mathbb{E} Y \gamma + n ( M_Y(\gamma/\sqrt{n} \,) - 1 ) ],\end{equation}
in which
 $M_Y$
is the moment generating function of Y. Let
 $\phi_n$
denote the Laplace exponent of
 $X^n = \{X^n_t \}_{t \ge 0}$
, that is,
 \begin{equation}\phi_n(\gamma) = \ln \mathbb{E} \Big[ {\mathrm{e}}^{\gamma \left(X^n_1 - x\right)} \Big] = \lambda [ (\sqrt{n} + \theta)\mathbb{E} Y \gamma + n ( M_Y({-}\gamma/\sqrt{n} \, ) - 1 ) ].\end{equation}
Then
 $\gamma_{1,n} > 0$
solves
 \begin{equation}\beta = \phi_n({-}\gamma_{1,n})\end{equation}
and, for the remainder of this paper, we assume that
 $M_Y$
is such that
 $\gamma_{1,n}$
exists.
Next, for
 $x < 0$
, formally substitute
 ${\rho}/{(\rho + \beta)} - A {\mathrm{e}}^{\gamma x}$
for u in
 $F_n = 0$
to obtain the following equation for
 $\gamma_{2,n} > 0$
:
 \begin{equation}\rho + \beta = \lambda [ (\sqrt{n} + \theta) \mathbb{E} Y \gamma + n ( M_Y({-} \gamma/\sqrt{n} \, ) - 1 ) ],\end{equation}
that is,
 $\gamma_{2,n} > 0$
solves
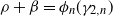 $\rho + \beta = \phi_n(\gamma_{2,n})$
. Thus, if we define
 $\Phi_n$
to equal the right inverse of
 $\phi_n$
, that is,
 $\Phi_n(s) = \sup \{ \gamma \ge 0\colon \phi_n(\gamma) = s \}$
, then
 \begin{equation}\gamma_{2,n} = \Phi_n(\rho + \beta).\end{equation}
Note that
 $\phi_n$
is non-negative and strictly increasing on
 $\mathbb{R}^+$
; thus
 $\Phi_n$
is well-defined on
 $\mathbb{R}^+$
.
3.2. Diffusion approximation
In this section we show that
 $\widetilde \gamma_1$
and
 $\widetilde \gamma_2$
, defined in (2.10) and (2.11), respectively, are the analogs of the adjustment coefficient for the diffusion approximation.
As in Section 3.1, for
 $x \ge 0$
, substitute
 $A {\mathrm{e}}^{-\gamma x}$
for u in (2.8) to obtain the following equation:
 \begin{equation}\beta = - \mu \gamma + \dfrac{1}{2} \, \sigma^2 \gamma^2.\end{equation}
It is straightforward to see that
 $\widetilde \gamma_1$
in (2.10) is the unique positive root of this quadratic equation. Let
 $\widetilde \phi$
denote the Laplace exponent of
 $\widetilde X = \{\widetilde X_t \}_{t \ge 0}$
, that is,
 \begin{equation*} \widetilde \phi(\gamma) = \ln \mathbb{E} \left[ {\mathrm{e}}^{\gamma \left(\tilde{X}_1 - x\right)} \right] = \mu \gamma + \dfrac{1}{2} \, \sigma^2 \gamma^2,\end{equation*}
then
 $\widetilde \gamma_1 > 0$
solves
 \begin{equation}\beta = \widetilde \phi({-}\widetilde \gamma_1).\end{equation}
Next, for
 $x < 0$
, substitute
 ${\rho}/{(\rho + \beta)} - A {\mathrm{e}}^{\gamma x}$
for u in (2.8) to obtain the following equation:
 \begin{equation}\rho + \beta = \mu \gamma + \dfrac{1}{2} \, \sigma^2 \gamma^2.\end{equation}
Note that
 $\widetilde \gamma_2$
in (2.11) is the unique positive root of this quadratic equation, that is,
 $\widetilde \gamma_2 > 0$
solves
 $\rho + \beta = \widetilde \phi(\widetilde \gamma_2)$
. Thus, if we let
 $\widetilde \Phi$
denote the inverse of
 $\widetilde \phi$
, then
 \begin{equation}\widetilde \gamma_2 = \widetilde \Phi(\rho + \beta).\end{equation}
Note the parallel between equations (3.3) and (3.5) and equations (3.7) and (3.9).
As one might expect from their derivations, the adjustment coefficients
 $(\gamma_{1,n}, \gamma_{2,n})$
and
 $(\widetilde \gamma_1, \widetilde \gamma_2)$
are related, which we prove in the next section.
3.3. Relationship between
$(\gamma_{1,\boldsymbol{n}}, \gamma_{2,\boldsymbol{n}})$
and
$(\widetilde \gamma_1, \widetilde \gamma_2)$


In this section we prove four lemmas that relate
 $(\gamma_{1,n}, \gamma_{2,n})$
and
 $(\widetilde \gamma_1, \widetilde \gamma_2)$
. We use these lemmas in Section 4.1 to modify
 $\widetilde \psi$
by functions of order
 ${\mathrm{O}}\! \left(n^{-1/2}\right)$
to bound
 $\psi_n$
.
Lemma 3.1.
 \begin{equation*}\gamma_{1,n} < \widetilde \gamma_1 < \Phi_n(\beta) + \dfrac{2 \mu}{\sigma^2} \quad {and} \quad \widetilde \gamma_2 < \gamma_{2,n},\end{equation*}
in which
 $\mu = \theta \lambda \mathbb{E} Y$
and
 $\sigma^2 = \lambda \mathbb{E}\!\left(Y^2\right)$
.
Proof. To prove this lemma, we first show
 $\gamma_{1,n} < \widetilde \gamma_1$
. Recall that
 $\gamma_{1,n} > 0$
solves (3.1), and
 $\widetilde \gamma_1 > 0$
solves (3.6). The right-hand side of (3.1) is convex with respect to
 $\gamma > 0$
and increasing for
 $\gamma > \gamma_{1,n}$
. Therefore, to prove
 $\gamma_{1,n} < \widetilde \gamma_1$
, it is enough to prove that the right-hand side of (3.1) is greater than
 $\beta$
when evaluated at
 $\widetilde \gamma_1$
, that is,
 \begin{equation*}\beta < \lambda [{-} (\sqrt{n} + \theta) \mathbb{E} Y \widetilde \gamma_1 + n ( M_Y( \widetilde \gamma_1/ \sqrt{n} \,) - 1 ) ],\end{equation*}
or equivalently, after substituting for
 $\beta$
from (3.6),
 \begin{equation*}- \theta \mathbb{E} Y \widetilde \gamma_1 + \dfrac{1}{2} \, \mathbb{E}\!\left(Y^2\right) \widetilde \gamma_1^2 < - (\sqrt{n} + \theta) \mathbb{E} Y \widetilde \gamma_1 + n \left(\mathbb{E} \left({\mathrm{e}}^{\widetilde \gamma_1 {Y}/{\sqrt{n}}} \right) - 1 \right)\end{equation*}
or
 \begin{equation*}\sqrt{n} \, \mathbb{E} Y \, \widetilde \gamma_1 + \dfrac{1}{2} \, \mathbb{E}\!\left(Y^2\right) \widetilde \gamma_1^2 < n \left( \mathbb{E} \left({\mathrm{e}}^{\widetilde \gamma_1 {Y}/{\sqrt{n}}}\right) - 1\right)\!,\end{equation*}
which is true because
 ${\mathrm{e}}^x - 1 > x + \frac{1}{2} x^2$
for all
 $x > 0$
.
Next, we show
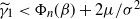 $\widetilde \gamma_1 < \Phi_n(\beta) + {2\mu}/{\sigma^2}$
. Rewrite
 $\widetilde \gamma_1$
’s quadratic equation, namely (3.6), as
 \begin{equation}0 = - \, \dfrac{\beta}{\gamma} - \mu + \dfrac{1}{2} \, \sigma^2 \gamma,\end{equation}
and note that the right-hand side of (3.10) is increasing with respect to
 $\gamma > 0$
. Thus, to prove
 $\widetilde \gamma_1 < \Phi_n(\beta) + {2\mu}/{\sigma^2}$
, it is enough to prove that the right-hand side of (3.10) is positive when evaluated at
 $\Phi_n(\beta) + {2 \mu}/{\sigma^2}$
, that is,
 \begin{equation*}- \, \dfrac{\beta}{\Phi_n(\beta) + {2 \mu}/{\sigma^2}} - \mu + \dfrac{1}{2} \, \sigma^2 \biggl( \Phi_n(\beta) + \dfrac{2\mu}{\sigma^2} \biggr) > 0,\end{equation*}
or equivalently
 \begin{equation*}\dfrac{1}{2} \, \sigma^2 \Phi_n^2(\beta) + \mu \Phi_n(\beta) > \beta.\end{equation*}
If we substitute for
 $\beta$
via the equation
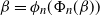 $\beta = \phi_n(\Phi_n(\beta))$
, in which
 $\phi_n$
is given in (3.2), and if we simplify the result, then we obtain the equivalent inequality
 \begin{equation*}\sqrt{n} \, \mathbb{E} Y \, \Phi_n(\beta) - \dfrac{1}{2} \, \mathbb{E}\!\left(Y^2\right) \Phi_n^2(\beta) < n \left(1 - \mathbb{E}\!\left({\mathrm{e}}^{- \Phi_n(\beta) {Y}/{\sqrt{n}}} \right) \right)\!,\end{equation*}
which is true because
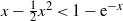 $x - \frac{1}{2} x^2 < 1 - {\mathrm{e}}^{-x}$
for all
 $x > 0$
.
Finally we show
 $\widetilde \gamma_2 < \gamma_{2,n}$
. Recall that
 $\gamma_{2,n} > 0$
solves (3.4), and
 $\widetilde \gamma_2 > 0$
solves (3.8). It is straightforward to show that the right-hand side of (3.4) is increasing with respect to
 $\gamma > 0$
. Therefore, to prove that
 $\widetilde \gamma_2 < \gamma_{2,n}$
, it is enough to prove that the right-hand side of (3.4) is less than
 $\rho + \beta$
when evaluated at
 $\widetilde \gamma_2$
, that is,
 \begin{equation*}\rho + \beta > \lambda [ (\sqrt{n} + \theta) \mathbb{E} Y \widetilde \gamma_2 + n ( M_Y({-} \widetilde \gamma_2/\sqrt{n} \,) - 1 ) ],\end{equation*}
or equivalently, after substituting for
 $\rho + \beta$
from (3.8),
 \begin{equation*}\theta \mathbb{E} Y \widetilde \gamma_2 + \dfrac{1}{2} \, \mathbb{E}\!\left(Y^2\right) \widetilde \gamma_2^2 > (\sqrt{n} + \theta) \mathbb{E} Y \widetilde \gamma_2 + n \left( \mathbb{E} \left({\mathrm{e}}^{- \widetilde \gamma_2 {Y}/{\sqrt{n}}} \right) - 1\right)\!,\end{equation*}
or
 \begin{equation*}\sqrt{n} \, \mathbb{E} Y \, \widetilde \gamma_2 - \dfrac{1}{2} \, \mathbb{E}\!\left(Y^2\right) \widetilde \gamma_2^2 < n \left(1 - \mathbb{E}\!\left({\mathrm{e}}^{- \widetilde \gamma_2 {Y}/{\sqrt{n}}} \right)\right)\!,\end{equation*}
which is true because
 $x - \frac{1}{2} x^2 < 1 - {\mathrm{e}}^{-x}$
for all
 $x > 0$
, and we have finished the proof of the lemma.
We present the following lemma, which relates
 $\widetilde \gamma_1$
and
 $\gamma_{1,n}$
. In Section 4.1 we use this lemma and the following one to find an upper bound for
 $\psi_n$
.
Lemma 3.2. Choose C so that
 \begin{equation*} C > \dfrac{\lambda}{6} \cdot \dfrac{\mathbb{E}\!\left(Y^3\right) \widetilde \gamma_1^3}{\sigma^2 \widetilde \gamma_1 - \mu} \, ({>}0 ),\end{equation*}
in which
 $\mu = \theta \lambda \mathbb{E} Y$
and
 $\sigma^2 = \lambda \mathbb{E}(Y^2)$
. Then there exists
 $N > 0$
such that, for all
 $n > N$
,
 \begin{equation}0 < \widetilde \gamma_1 - \dfrac{C}{\sqrt{n}} < \gamma_{1,n} < \widetilde \gamma_1,\end{equation}
from which it follows that
 \begin{equation}\lim_{n \to \infty} \gamma_{1,n} = \widetilde \gamma_1,\end{equation}
with rate of convergence of order
 ${\mathrm{O}}\! \left( n^{-1/2} \right)$
.
Proof. First, note that the limit in (3.12) follows directly from the bounds in (3.11). Second, note that the last inequality in (3.11) follows from Lemma 3.3. Third, for a fixed value of C, it is straightforward to find N so that the first inequality holds for
 $n > N$
. Thus, to prove this lemma it is enough to prove the middle inequality for n large enough.
The adjustment coefficient
 $\gamma_{1,n} > 0$
solves (3.1) or equivalently
 \begin{equation}\dfrac{\beta}{\gamma} + \mu - n \lambda \, \dfrac{ \mathbb{E} {\mathrm{e}}^{({\gamma}/{\sqrt{n}}) \, Y} - 1 - ({\gamma}/{\sqrt{n}}) \, \mathbb{E} Y}{\gamma} = 0.\end{equation}
The left-hand side of (3.13) decreases with respect to
 $\gamma$
; thus, to show that
 $\widetilde \gamma_1 - C/\sqrt{n} < \gamma_{1,n}$
for some
 $C > 0$
, it is enough to show that the left-hand side of (3.13) is positive at
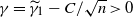 $\gamma = \widetilde \gamma_1 - C/\sqrt{n} > 0$
, or equivalently
 \begin{align*}&\beta + \mu \biggl( \widetilde \gamma_1 - \dfrac{C}{\sqrt{n}} \biggr) - n \lambda \, \biggl( \mathbb{E} \exp \biggl( \dfrac{\widetilde \gamma_1 - {C}/{\sqrt{n}}}{\sqrt{n}} \, Y \biggr) - 1 - \dfrac{\widetilde \gamma_1 - {C}/{\sqrt{n}}}{\sqrt{n}} \, \mathbb{E} Y \biggr) > 0.\end{align*}
By using the equation for
 $\widetilde \gamma_1$
, namely
 $\beta = - \mu \widetilde \gamma_1 + \frac{1}{2} \sigma^2 \widetilde \gamma_1^2$
, and by expanding the exponential, we see that this inequality is equivalent to
 \begin{align*}\biggl( \left(\sigma^2 \widetilde \gamma_1 - \mu\right) C - \dfrac{\lambda}{6} \, \mathbb{E}\!\left(Y^3\right) \widetilde \gamma_1^3 \biggr) + {\mathrm{O}}\! \left( n^{-1/2} \right) > 0,\end{align*}
in which the
 ${\mathrm{O}}\! \left( n^{-1/2} \right)$
term is finite for n large enough because of the assumption that
 $M_{Y}(\gamma)$
is finite for
 $\gamma < \varepsilon$
, for some
 $\varepsilon > 0$
. Also, the coefficient of C is positive because
 $\widetilde \gamma_1 > 2 \mu/\sigma^2$
, which is easy to see from (2.10). So, if we choose C so that
 \begin{equation*}C > \dfrac{\lambda}{6} \cdot \dfrac{\mathbb{E}\!\left(Y^3\right) \widetilde \gamma_1^3}{\sigma^2 \widetilde \gamma_1 - \mu} \, ({>}0 ),\end{equation*}
then there exists
 $N > 0$
such that
 $n > N$
implies
 \begin{equation*}0 < \widetilde \gamma_1 - \dfrac{C}{\sqrt{n}} < \gamma_{1,n}.\end{equation*}
Thus we have completed the proof of the lemma.
We present the following lemma, which relates
 $\widetilde \gamma_2$
and
 $\gamma_{2,n}$
.
Lemma 3.3. Choose C′ so that
 \begin{equation*} C' > \dfrac{\lambda}{6} \cdot \dfrac{\mathbb{E}\!\left(Y^3\right) \widetilde \gamma_2^3}{\sigma^2 \widetilde \gamma_2 + \mu} ,\end{equation*}
in which
 $\mu = \theta \lambda \mathbb{E} Y$
and
 $\sigma^2 = \lambda \mathbb{E}(Y^2)$
. Then there exists
 $N' > 0$
such that, for all
 $n > N'$
,
 \begin{equation}\widetilde \gamma_2 < \gamma_{2,n} < \widetilde \gamma_2 + \dfrac{C'}{\sqrt{n}} ,\end{equation}
from which it follows that
 \begin{equation}\lim_{n \to \infty} \gamma_{2,n} = \widetilde \gamma_2,\end{equation}
with rate of convergence of order
 ${\mathrm{O}} ( n^{-1/2} )$
.
Proof. First, note that the limit in (3.15) follows directly from the bounds in (3.14). Next, note that the first inequality in (3.14) follows from Lemma 3.1. Thus, to prove this lemma it is enough to prove the second inequality in (3.14).
The adjustment coefficient
 $\gamma_{2,n} > 0$
solves (3.4), or equivalently
 \begin{equation}\rho + \beta = \mu \gamma + n \lambda \biggl( \mathbb{E} {\mathrm{e}}^{-\gamma Y/\sqrt{n}} - 1 + \dfrac{\gamma}{\sqrt{n}} \, \mathbb{E} Y \biggr).\end{equation}
The right-hand side of (3.16) increases with respect to
 $\gamma > 0$
; thus, to show that
 $\gamma_{2,n} < \widetilde \gamma_2 + C'/\sqrt{n}$
for some
 $C' > 0$
, it is enough to show that the right-hand side of (3.16) is greater than
 $\rho + \beta$
when evaluated at
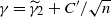 $\gamma = \widetilde \gamma_2 + C'/\sqrt{n}$
, that is,
 \begin{equation*}\rho + \beta < \mu \biggl( \widetilde \gamma_2 + \dfrac{C'}{\sqrt{n}} \biggr) + n \lambda \biggl( \mathbb{E} \exp\biggl({-}\dfrac{(\widetilde \gamma_2 + {C'}/{\sqrt{n}} )Y}{\sqrt{n}}\biggr) - 1 + \dfrac{(\widetilde \gamma_2 + {C'}/{\sqrt{n}} )}{\sqrt{n}} \, \mathbb{E} Y \biggr).\end{equation*}
By using the equation for
 $\widetilde \gamma_2$
, namely
 $\rho + \beta = \mu \widetilde \gamma_2 + \frac{1}{2} \sigma^2 \widetilde \gamma_2^2$
, and by expanding the exponential, we see that this inequality is equivalent to
 \begin{equation*}\biggl( \left(\sigma^2 \widetilde \gamma_2 + \mu \right) C' - \dfrac{\lambda}{6} \, \mathbb{E}\!\left(Y^3 \right) \widetilde \gamma_2^3 \biggr) + {\mathrm{O}}\! \left( n^{-1/2} \right) > 0,\end{equation*}
in which the
 ${\mathrm{O}} ( n^{-1/2} )$
term is finite. So, if we choose C
′ such that
 \begin{equation*}C' > \dfrac{\lambda}{6} \, \dfrac{\mathbb{E}(Y^3) \widetilde \gamma_2^3}{\sigma^2 \widetilde \gamma_2 + \mu} \, ,\end{equation*}
then there exists
 $N' > 0$
such that
 $n > N'$
implies
 \begin{equation*}\gamma_{2,n} < \widetilde \gamma_2 + \dfrac{C'}{\sqrt{n}} .\end{equation*}
Thus we have completed the proof of the lemma.
Lemmas 3.2 and 3.3 show that the adjustment coefficients
 $(\widetilde \gamma_1, \widetilde \gamma_2)$
and
 $(\gamma_{1,n}, \gamma_{2,n})$
, respectively, are approximately equal to order
 ${\mathrm{O}} (n^{-1/2} )$
, which is an interesting result in itself, separate from their use in Section 4 in bounding
 $\psi_n$
.
We present the following lemma, which relates
 $\widetilde \gamma_1$
with
 $\Phi_n$
, the right inverse of the Laplace exponent
 $\phi_n$
. We use this lemma in Section 4.1 to find a lower bound for
 $\psi_n$
.
Lemma 3.4. Choose C′′ so that
 \begin{equation*} C'' > \dfrac{\lambda}{6} \, \dfrac{\mathbb{E}\!\left(Y^3\right)}{\sigma^2 \widetilde \gamma_1 - \mu} \biggl( \widetilde \gamma_1 - \dfrac{2\mu}{\sigma^2} \biggr)^3,\end{equation*}
in which
 $\mu = \theta \lambda \mathbb{E} Y$
and
 $\sigma^2 = \lambda \mathbb{E}(Y^2)$
. Then there exists
 $N'' > 0$
such that, for all
 $n > N''$
,
 \begin{equation}\widetilde \gamma_1 - \dfrac{2\mu}{\sigma^2} < \Phi_n(\beta) < \widetilde \gamma_1 - \dfrac{2\mu}{\sigma^2} + \dfrac{C''}{\sqrt{n}} ,\end{equation}
from which it follows that
 \begin{equation}\lim_{n \to \infty} \Phi_n(\beta) = \widetilde \gamma_1 - \dfrac{2\mu}{\sigma^2} ,\end{equation}
with rate of convergence of order
 ${\mathrm{O}}\! \left( n^{-1/2}\right)$
.
Proof. First, note that the limit in (3.18) follows directly from the bounds in (3.17). Next, note that the first inequality in (3.17) follows from Lemma 3.1. Thus, to prove this lemma it is enough to prove the second inequality in (3.17).
From the discussion in Section 3.1 we know that
 $\Phi_n(\beta) > 0$
solves
 \begin{equation}\beta = \mu \gamma + n \lambda \biggl( \mathbb{E} {\mathrm{e}}^{-\gamma Y/\sqrt{n}} - 1 + \dfrac{\gamma}{\sqrt{n}} \, \mathbb{E} Y \biggr).\end{equation}
The right-hand side of (3.19) increases with respect to
 $\gamma > 0$
; thus, to show that
 \begin{equation*}\Phi_n(\beta) < \widetilde \gamma_1 - \frac{2 \mu}{\sigma^2} + \frac{C''}{\sqrt{n}}\quad\text{for some $C'' > 0$,}\end{equation*}
it is enough to show that the right-hand side of (3.19) is greater than
 $\beta$
at
 \begin{equation*}\gamma = \widetilde \gamma_1 - \frac{2\mu}{\sigma^2} + \frac{C''}{\sqrt{n}},\end{equation*}
that is,
 \begin{align*}\beta &< \mu \biggl( \widetilde \gamma_1 - \dfrac{2\mu}{\sigma^2} + \dfrac{C''}{\sqrt{n}} \biggr) \\[6pt]&\quad\, + n \lambda \biggl( \mathbb{E} \exp\biggl({-}\dfrac{(\widetilde \gamma_1 - {2\mu}/{\sigma^2} + {C''}/{\sqrt{n}} )Y}{\sqrt{n}}\biggr) - 1 + \dfrac{(\widetilde \gamma_1 - {2\mu}/{\sigma^2} + {C''}/{\sqrt{n}} )}{\sqrt{n}} \, \mathbb{E} Y \biggr).\end{align*}
By using the equation for
 $\widetilde \gamma_1$
, namely
 $\beta = -\mu \widetilde \gamma_1 + \frac{1}{2} \sigma^2 \widetilde \gamma_1^2$
, and by expanding the exponential, we see that this inequality is equivalent to
 \begin{equation*}\biggl( ( \sigma^2 \widetilde \gamma_1 - \mu ) C'' - \dfrac{\lambda}{6} \, \mathbb{E}(Y^3 ) \biggl( \widetilde \gamma_1 - \dfrac{2\mu}{\sigma^2} \biggr)^3 \biggr) + {\mathrm{O}}\! \left(n^{-1/2}\right) > 0,\end{equation*}
in which the
 ${\mathrm{O}} ( n^{-1/2} )$
term is finite. Recall that
 $\widetilde \gamma_1 > 2\mu/\sigma^2$
. So, if we choose C
′ such that
 \begin{equation*}C'' > \dfrac{\lambda}{6} \, \dfrac{\mathbb{E}\!\left(Y^3\right)}{\sigma^2 \widetilde \gamma_1 - \mu} \biggl( \widetilde \gamma_1 - \dfrac{2\mu}{\sigma^2} \biggr)^3,\end{equation*}
then there exists
 $N'' > 0$
such that
 $n > N''$
implies
 \begin{equation*}\Phi_n(\beta) < \widetilde \gamma_1 - \dfrac{2\mu}{\sigma^2} + \dfrac{C''}{\sqrt{n}} .\end{equation*}
Thus we have completed the proof of the lemma.
4. Justifying the diffusion approximation
4.1. Bounds for
$\psi_{\boldsymbol{n}}$

In this section we modify
 $\widetilde \gamma$
by functions of order
 ${\mathrm{O}}\! \left(n^{-1/2}\right)$
to obtain upper and lower bounds of
 $\psi_n$
. In the process of finding an upper bound of
 $\psi_n$
, we prove a Lundberg-type bound for
 $\psi$
. To that end, by analogy with the expression for
 $\widetilde \psi$
in (2.9), define
 $\overline{\psi}_n$
on
 $\mathbb{R}$
by
 \begin{equation*} \overline{\psi}_n(x) =\begin{cases}\dfrac{\rho}{\rho + \beta} \biggl( 1 - \dfrac{\gamma_{1,n}}{\gamma_{1,n} + \gamma_{2,n}} \,{\mathrm{e}}^{\gamma_{2,n} x} \biggr), & x < 0, \\[15pt]\dfrac{\rho}{\rho + \beta} \, \dfrac{\gamma_{2,n}}{\gamma_{1,n} + \gamma_{2,n}} \,{\mathrm{e}}^{- \gamma_{1,n} x}, & x \ge 0.\end{cases}\end{equation*}
In the following lemma we use comparison to prove that
 $\overline{\psi}_n$
is an upper bound of the scaled discounted probability of exponential Parisian ruin
 $\psi_n$
.
Lemma 4.1.
 \begin{equation}\psi_n(x) \le \overline{\psi}_n(x),\end{equation}
for all
 $x \in \mathbb{R}$
.
Proof. To prove inequality (4.1) we use Lemma 2.1(a). First note that
 \begin{equation*}\lim_{x \to -\infty} \overline{\psi}_n(x) = \dfrac{\rho}{\rho + \beta} = \lim_{x \to -\infty} \psi_n(x)\end{equation*}
and
 \begin{equation*}\lim_{x \to \infty} \overline{\psi}_n(x) = 0 = \lim_{x \to \infty} \psi_n(x).\end{equation*}
Thus it remains to show that
 $\overline{\psi}_n$
is a supersolution of
 $F_n = 0$
because
 $\psi_n$
is a solution of
 $F_n = 0$
.
For
 $x < 0$
, from the definition of
 $\gamma_{2,n}$
in (3.4), it is straightforward to verify that
 \begin{align*} F_n(x, \overline{\psi}_n(x), \overline{\psi}^{\prime}_{n}(x), \overline{\psi}_n(x - \cdot)) = 0.\end{align*}
For
 $x\ge 0$
, from the definition of
 $\gamma_{1,n}$
in (3.1), we obtain
 \begin{align*} & F_n(x, \overline{\psi}_n(x), \overline{\psi}^{\prime}_{n} (x), \overline{\psi}_n(x - \cdot) ) \notag\\& \quad \propto \int^{\infty}_{\sqrt{n} x} \biggl\{\dfrac{\gamma_{2,n}}{\gamma_{1,n} + \gamma_{2,n}}\,{\mathrm{e}}^{\gamma_{1,n} (y/\sqrt{n} - x)}+\dfrac{\gamma_{1,n}}{\gamma_{1,n}+\gamma_{2,n}}\,{\mathrm{e}}^{-\gamma_{2,n}(y/\sqrt{n} - x)} - 1\biggr\} \,{\mathrm{d}} F_Y(y) \notag \\& \quad \ge 0.\end{align*}
The last inequality is obtained from the following inequality:
 \begin{align}\dfrac{\gamma_{2,n}}{\gamma_{1,n} + \gamma_{2,n}}\,{\mathrm{e}}^{\gamma_{1,n} z}+\dfrac{\gamma_{1,n}}{\gamma_{1,n}+\gamma_{2,n}}\,{\mathrm{e}}^{-\gamma_{2,n}z} \ge 1, \quad z \ge 0,\end{align}
which holds because the function on the left of inequality (4.2) increases with z and equals 1 at
 $z = 0$
. Thus
 $\overline{\psi}_n$
is a supersolution of
 $F_n = 0$
, and inequality (4.1) follows from Lemma 2.1(a).
Remark 4.1. Inequality (4.1) is a generalization of the Lundberg bound, which states that (ordinary) probability of ruin on
 $\mathbb{R}^+$
is bounded above by
 ${\mathrm{e}}^{-Rx}$
, in which the adjustment coefficient
 $R > 0$
solves
 \begin{equation*}- (1 + \theta)\mathbb{E} Y \cdot R + ( M_Y(R) - 1 ) = 0.\end{equation*}
The equation for R shows us that
 $R = \gamma_{1,n}|_{n=1,\beta = 0}$
. See Sections 5.3 and 5.4 of [Reference Schmidli15] for more information about the adjustment coefficient R and the Lundberg bound.
We readily obtain the following proposition from Lemmas 3.2, 3.3, and 4.1, in which we modify
 $\widetilde \psi$
in (2.9) by a function of order
 ${\mathrm{O}} ( n^{-1/2} )$
to obtain an upper bound of
 $\psi_n$
, so we state it without proof.
Proposition 4.1. Let C and N be as in the statement of Lemma 3.2, let C′ and N′ be as in the statement of Lemma 3.3, and for
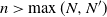 $n > \max(N, N')$
, define
 $u_n$
by
 \begin{equation*} u_n(x) =\begin{cases}\dfrac{\rho}{\rho + \beta} \biggl( 1 - \dfrac{\widetilde \gamma_1 - {C}/{\sqrt{n}}}{\widetilde \gamma_1 + \widetilde \gamma_2 + {C'}/{\sqrt{n}}} \,{\mathrm{e}}^{\left( \widetilde \gamma_2 + {C'}/{\sqrt{n}} \right) x} \biggr), & x < 0, \\[15pt]\dfrac{\rho}{\rho + \beta} \, \dfrac{\widetilde \gamma_2 + {C'}/{\sqrt{n}}}{\widetilde \gamma_1 + \widetilde \gamma_2 - {C}/{\sqrt{n}}} \,{\mathrm{e}}^{- ( \widetilde \gamma_1 - {C}/{\sqrt{n}} )x}, & x \ge 0.\end{cases}\end{equation*}
Then
 \begin{equation*} \psi_n(x) < u_n(x)\end{equation*}
for all
 $x \in \mathbb{R}$
.
In Proposition 4.1 we modified
 $\widetilde \psi$
by a function of order
 ${\mathrm{O}}\! \left( n^{-1/2} \right)$
to obtain an upper bound of
 $\psi_n$
. In the next proposition we modify
 $\widetilde \psi$
by a function of order
 ${\mathrm{O}} \big( n^{-1/2} \big)$
to obtain a lower bound of
 $\psi_n$
. Because the domain of our problem lies on the whole real axis, it is difficult to find a subsolution of the discounted probability of exponential Parisian ruin directly. To overcome this difficulty we first analyze
 $\psi_n(0)$
in Lemma 4.2, so that we can apply comparison on the negative and positive reals separately in Proposition 4.2.
Lemma 4.2. There exist
 $D > 0$
and
 $M > 0$
such that, for all
 $n > M$
,
 \begin{equation*} \widetilde \psi(0) \biggl( 1 - \dfrac{D}{\sqrt{n}} \biggr) < \psi_n(0) < \widetilde \psi(0) \biggl(1 + \dfrac{D}{\sqrt{n}} \biggr),\end{equation*}
from which it follows that
 \begin{equation*} \lim_{n \to \infty} \psi_n(0) = \widetilde \psi(0),\end{equation*}
with rate of convergence of order
 ${\mathrm{O}}\! \left( n^{-1/2}\right)$
.
Proof. From Corollary 3.2 of [Reference Landriault, Renaud and Zhou12] we deduce the following expression for
 $\psi_n(0)$
:
 \begin{equation*}\psi_n(0) = 1 - \dfrac{\beta}{\rho + \beta} \cdot \dfrac{\gamma_{2,n}}{\Phi_n(\beta)} .\end{equation*}
Then, by applying Lemmas 3.3 and 3.4, we can find
 $D > 0$
and
 $M > 0$
such that, for all
 $n > M$
,
 \begin{align*}\biggl(1 - \dfrac{\beta}{\rho + \beta} \cdot \dfrac{\widetilde \gamma_2}{\widetilde \gamma_1 - {2 \mu}/{\sigma^2}} \biggr) \biggl( 1 - \dfrac{D}{\sqrt{n}} \biggr) & < \biggl(1 - \dfrac{\beta}{\rho + \beta} \cdot \dfrac{\gamma_{2,n}}{\Phi_n(\beta)} \biggr) \\&<\biggl(1 - \dfrac{\beta}{\rho + \beta} \cdot \dfrac{\widetilde \gamma_2}{\widetilde \gamma_1 - {2\mu}/{\sigma^2}} \biggr) \biggl( 1 + \dfrac{D}{\sqrt{n}} \biggr).\end{align*}
It is straightforward, but tedious, to show that
 \begin{equation*}1 - \dfrac{\beta}{\rho + \beta} \cdot \dfrac{\widetilde \gamma_2}{\widetilde \gamma_1 - {2\mu}/{\sigma^2}} = \dfrac{\rho}{\rho + \beta} \cdot \dfrac{\widetilde \gamma_2}{\widetilde \gamma_1 + \widetilde \gamma_2} ,\end{equation*}
which equals
 $\widetilde \psi(0)$
, and the lemma follows.
Proposition 4.2. Formally, define the random variable
 $Z_d = (Y - d) | (Y > d)$
for
 $d \ge 0$
, and suppose m exists such that both
 $M_Y (\widetilde \gamma_1/\sqrt{m} \,) < \infty$
and
 \begin{equation}\sup_{d \ge 0} \mathbb{E} \bigl( Z_d^2 \,{\mathrm{e}}^{({\widetilde \gamma_1}/{\sqrt{m}}) Z_d} \bigr) < \infty.\end{equation}
Choose
 $\varepsilon > 0$
, and define
 $\delta$
by
 \begin{equation}\delta = \max\biggl[ \sup_{d \ge 0} ( \widetilde \gamma_1 \mathbb{E} Z_d + \varepsilon ), D \biggr],\end{equation}
in which D is given in Lemma 4.2, and choose
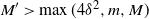 $M' > \max ( 4 \delta^2, m, M )$
, in which M is given in Lemma 4.2 and M′ is large enough so that
 \begin{equation}\sup_{d \ge 0} \dfrac{\widetilde \gamma_1^2}{\sqrt{M'}} \int_0^1 (1 - \omega) \mathbb{E}\!\left( Z_d^2 \,{\mathrm{e}}^{\left({\widetilde \gamma_1 \omega}/{\sqrt{M'}}\right) Z_d} \right) \,{\mathrm{d}} \omega \le \varepsilon.\end{equation}
Define the function
 $\ell_n$
on
 $\mathbb{R}$
by
 \begin{equation*} \ell_n(x) =\begin{cases}\biggl( 1 - \dfrac{\delta}{\sqrt{n}} \biggr) \widetilde \psi(x) , & x < 0, \\[18pt]\biggl( 1 - \dfrac{2\delta}{\sqrt{n}} \biggr) \widetilde \psi(x) , & x \ge 0.\end{cases}\end{equation*}
Then, for all
 $n > M'$
and
 $x \in \mathbb{R}$
, we have
 \begin{equation*}\ell_n(x) \le \psi_n(x).\end{equation*}
Proof. We begin by using Lemma 2.1(b) to show
 $\ell_n \le \psi_n$
on
 $\mathbb{R}^-$
. For
 $x < 0$
, it is straightforward to show that
 \begin{equation*}F_n (x, \ell_n(x), \ell^{\prime}_n(x), \ell_n(x - \cdot) ) = \biggl( 1 - \dfrac{\delta}{\sqrt{n}} \biggr) F_n(x, \widetilde \psi(x), \widetilde \psi_x(x), \widetilde \psi(x - \cdot) ) - \dfrac{\delta}{\sqrt{n}} \, \rho,\end{equation*}
and
 \begin{equation*}F_n (x, \widetilde \psi(x), \widetilde \psi_x(x), \widetilde \psi(x - \cdot) ) \propto - (\rho + \beta) + \lambda [ (\sqrt{n} + \theta) \mathbb{E} Y \widetilde \gamma_2 + n ( M_Y({-}\widetilde \gamma_2/\sqrt{n} \,) - 1 ) ] < 0,\end{equation*}
in which the inequality follows from the proof of Lemma 3.1. It follows that
 \begin{equation*}F_n (x, \ell_n(x), \ell^{\prime}_n(x), \ell_n(x - \cdot) ) < 0 = F_n (x, \psi_n(x), \psi^{\prime}_n (x), \psi_n(x - \cdot) )\end{equation*}
for
 $x < 0$
. Also,
 \begin{equation*}\lim_{x \to -\infty} \ell_n(x) = \biggl( 1 - \dfrac{\delta}{\sqrt{n}} \biggr) \dfrac{\rho}{\rho + \beta} < \dfrac{\rho}{\rho + \beta} = \lim_{x \to - \infty} \psi_n(x)\end{equation*}
and
 \begin{equation*}\ell_n(0^-) = \biggl( 1 - \dfrac{\delta}{\sqrt{n}} \biggr) \widetilde \psi(0) < \psi_n(0),\end{equation*}
by Lemma 4.2 and
 $\delta \ge D$
. Thus Lemma 2.1(b) implies
 $\ell_n \le \psi_n$
on
 $\mathbb{R}^-$
.
Next, we use Lemma 2.1(c) to show that
 $\ell_n \le \psi_n$
on
 $\mathbb{R}^+$
. For
 $x > 0$
,
 \begin{align*}&F_n ( x, \ell_n(x), \ell^{\prime}_n (x), \ell_n(x - \cdot) ) \notag\\&\quad = \beta \ell_n(x) - (\sqrt{n} + \theta)\lambda\mathbb{E} Y \ell^{\prime}_n (x) - n \lambda (\mathbb{E} \ell_n(x - Y/\sqrt{n} \,) - \ell_n(x)) \notag \\[5pt]&\quad = \beta \biggl( 1 - \dfrac{2\delta}{\sqrt{n}} \biggr) \dfrac{\rho}{\rho + \beta} \, \dfrac{\widetilde \gamma_2}{\widetilde \gamma_1 + \widetilde \gamma_2} \,{\mathrm{e}}^{-\widetilde \gamma_1 \, x} + \biggl( 1 - \dfrac{2\delta}{\sqrt{n}} \biggr) \dfrac{\rho}{\rho + \beta} \, \dfrac{\widetilde \gamma_2}{\widetilde \gamma_1 + \widetilde \gamma_2} \, (\sqrt{n} + \theta)\lambda\mathbb{E} Y \widetilde \gamma_1 {\mathrm{e}}^{-\widetilde \gamma_1 \, x} \notag \\[5pt]&\quad\quad\, - n \lambda \biggl( 1 - \dfrac{2\delta}{\sqrt{n}} \biggr) \dfrac{\rho}{\rho + \beta} \, \dfrac{\widetilde \gamma_2}{\widetilde \gamma_1 + \widetilde \gamma_2} \,{\mathrm{e}}^{-\widetilde \gamma_1 \, x} \biggl\{ \int_0^{\sqrt{n} x} {\mathrm{e}}^{({\widetilde \gamma_1}/{\sqrt{n}}) \, y} \,{\mathrm{d}}F_Y(y) - 1 \notag \\[5pt]&\quad\quad\quad\quad\quad\quad\quad\quad\quad\quad\quad\quad\quad\quad\quad\quad\quad\, + \dfrac{1 - {\delta}/{\sqrt{n}}}{1 - {2\delta}/{\sqrt{n}}} \int_{\sqrt{n} x}^\infty \dfrac{1 - \frac{\widetilde \gamma_1}{\widetilde \gamma_1 + \widetilde \gamma_2} \,{\mathrm{e}}^{\widetilde \gamma_2 (x - {y}/{\sqrt{n}} )}}{ \frac{\widetilde \gamma_2}{\widetilde \gamma_1 + \widetilde \gamma_2} \,{\mathrm{e}}^{-\widetilde \gamma_1 \, x} } \,{\mathrm{d}}F_Y(y) \biggr\} \notag \\[5pt]&\quad \propto \beta + (\sqrt{n} + \theta)\lambda\mathbb{E} Y \widetilde \gamma_1 \\[5pt]&\quad\quad\, - n \lambda \biggl\{ \int_0^{\sqrt{n} x} {\mathrm{e}}^{({\widetilde \gamma_1}/{\sqrt{n}}) \, y} \,{\mathrm{d}}F_Y(y) + \dfrac{1 - {\delta}/{\sqrt{n}}}{1 - {2\delta}/{\sqrt{n}}} \int_{\sqrt{n} x}^\infty \dfrac{1 - \frac{\widetilde \gamma_1}{\widetilde \gamma_1 + \widetilde \gamma_2} \,{\mathrm{e}}^{\widetilde \gamma_2 (x - {y}/{\sqrt{n}} )}}{\frac{\widetilde \gamma_2}{\widetilde \gamma_1 + \widetilde \gamma_2} \,{\mathrm{e}}^{-\widetilde \gamma_1 \, x} } \,{\mathrm{d}}F_Y(y) - 1 \biggr\}. \notag\end{align*}
Recall that
 $\widetilde \gamma_1$
solves
 $\beta = - \mu \widetilde \gamma_1 + \frac{1}{2} \sigma^2 \widetilde \gamma_1^2$
; thus
 $F_n ( x, \ell_n(x), \ell^{\prime}_n (x), \ell_n(x - \cdot) ) \le 0$
if
 \begin{align}&\int_0^\infty \biggl\{ {\mathrm{e}}^{({\widetilde \gamma_1}/{\sqrt{n}}) \, y} - 1 - {\widetilde \gamma_1}/{\sqrt{n}} \, y - \dfrac{\widetilde \gamma_1^2}{2n} \, y^2 \biggr\} \,{\mathrm{d}}F_Y(y) \notag \\[4pt]&\quad\, + \int_{\sqrt{n} x}^\infty \biggl\{\dfrac{1 - {\delta}/{\sqrt{n}}}{1 - {2\delta}/{\sqrt{n}}} \dfrac{1 - \frac{\widetilde \gamma_1}{\widetilde \gamma_1 + \widetilde \gamma_2} \,{\mathrm{e}}^{\widetilde \gamma_2 (x - {y}/{\sqrt{n}} )}}{\frac{\widetilde \gamma_2}{\widetilde \gamma_1 + \widetilde \gamma_2} \,{\mathrm{e}}^{-\widetilde \gamma_1 \, x}} - {\mathrm{e}}^{({\widetilde \gamma_1}/{\sqrt{n}}) \, y} \biggr\} \,{\mathrm{d}}F_Y(y) \ge 0.\end{align}
The first integral in (4.6) is non-negative because
 ${\mathrm{e}}^x \ge 1 + x + \frac{1}{2} \, x^2$
for all
 $x \ge 0$
; thus it suffices to show that the second integral is non-negative. To that end, note that, for
 $n > \delta^2$
,
 \begin{equation*}\dfrac{1 - {\delta}/{\sqrt{n}}}{1 - {2\delta}/{\sqrt{n}}} > \dfrac{1}{1 - {\delta}/{\sqrt{n}}} ,\end{equation*}
and for
 $y \ge \sqrt{n} x$
,
 \begin{equation*}1 - \dfrac{\widetilde \gamma_1}{\widetilde \gamma_1 + \widetilde \gamma_2} \,{\mathrm{e}}^{\widetilde \gamma_2 (x - {y}/{\sqrt{n}} )} \ge \dfrac{\widetilde \gamma_2}{\widetilde \gamma_1 + \widetilde \gamma_2} .\end{equation*}
Thus
 $F_n ( x, \ell_n(x), \ell^{\prime}_n (x), \ell_n(x - \cdot) ) \le 0$
if the following inequality holds:
 \begin{equation*}\int_{\sqrt{n} x}^\infty \biggl\{\dfrac{{\mathrm{e}}^{\widetilde \gamma_1 x}}{1 - {\delta}/{\sqrt{n}}} - {\mathrm{e}}^{({\widetilde \gamma_1}/{\sqrt{n}}) \, y} \biggr\} \,{\mathrm{d}}F_Y(y) \ge 0.\end{equation*}
This inequality is automatic if
 $S_Y(\sqrt{n} x) = 0$
, in which
 $S_Y = 1 - F_Y$
is the survival function of Y; therefore, without loss of generality, assume
 $S_Y(\sqrt{n} x) > 0$
. After replacing
 $\sqrt{n} x$
by d and dividing by
 ${\mathrm{e}}^{\widetilde \gamma_1 x} S_Y(d)$
, the above inequality becomes
 \begin{equation*}\int_d^\infty \biggl\{ \dfrac{1}{1 - {\delta}/{\sqrt{n}}} - {\mathrm{e}}^{ ({\widetilde \gamma_1}/{\sqrt{n}})(y - d)} \biggr\} \dfrac{{\mathrm{d}}F_Y(y)}{S_Y(d)} \ge 0,\end{equation*}
or equivalently
 \begin{equation*}\int_d^\infty \Bigl\{ {\mathrm{e}}^{ ({\widetilde \gamma_1}/{\sqrt{n}})(y - d)} - 1 \Bigr\} \dfrac{{\mathrm{d}}F_Y(y)}{S_Y(d)} \le \dfrac{{\delta}/{\sqrt{n}}}{1 - {\delta}/{\sqrt{n}}} .\end{equation*}
Formally, define
 $Z_d = (Y - d) | (Y > d)$
; then this inequality becomes
 \begin{equation*}\int_0^\infty \{ {\mathrm{e}}^{ {\widetilde \gamma_1 z}/{\sqrt{n}}} - 1 \} \,{\mathrm{d}} F_{Z_d}(z) \le \dfrac{{\delta}/{\sqrt{n}}}{1 - {\delta}/{\sqrt{n}}} .\end{equation*}
If we find
 $\delta$
that satisfies the following even stronger inequality, then the above sequence of inequalities holds:
 \begin{equation}\int_0^\infty \{ {\mathrm{e}}^{ {\widetilde \gamma_1 z}/{\sqrt{n}}} - 1 \} \,{\mathrm{d}} F_{Z_d}(z) \le \dfrac{\delta}{\sqrt{n}} .\end{equation}
Rewrite the integrand from the left-hand side of inequality (4.7) as follows:
 \begin{equation*}{\mathrm{e}}^{ {\widetilde \gamma_1 z}/{\sqrt{n}}} - 1 = \dfrac{\widetilde \gamma_1 z}{\sqrt{n}} + \dfrac{\widetilde \gamma_1^2 z^2}{n} \int_0^1 (1 - \omega) \,{\mathrm{e}}^{({\widetilde \gamma_1 z}/{\sqrt{n}}) \, \omega} {\mathrm{d}}\omega.\end{equation*}
Thus inequality (4.7) is equivalent to
 \begin{equation*}\int_0^\infty \biggl\{ \dfrac{\widetilde \gamma_1 z}{\sqrt{n}} + \dfrac{\widetilde \gamma_1^2 z^2}{n} \int_0^1 (1 - \omega) \,{\mathrm{e}}^{({\widetilde \gamma_1 z}/{\sqrt{n}}) \, \omega} {\mathrm{d}} \omega \biggr\} \,{\mathrm{d}} F_{Z_d}(z) \le \dfrac{\delta}{\sqrt{n}}\end{equation*}
or, after multiplying both side by
 $\sqrt{n}$
and switching the order of integration,
 \begin{equation}\widetilde \gamma_1 \mathbb{E} Z_d + \dfrac{\widetilde \gamma_1^2}{\sqrt{n}} \int_0^1 (1 - \omega) \, \mathbb{E} \bigl( Z_d^2 \,{\mathrm{e}}^{({\widetilde \gamma_1 \omega}/{\sqrt{n}}) Z_d} \bigr) \,{\mathrm{d}} \omega \le \delta.\end{equation}
Note that the left-hand side decreases with increasing n. It follows that if we define
 $\delta$
and M
′ as in (4.4) and (4.5), respectively, then inequality (4.8) holds for all
 $d \ge 0$
and all
 $n > M'$
, which implies that
 $F_n$
evaluated at
 $\ell_n$
is non-positive for all
 $x > 0$
and all
 $n > M'$
. In words, we have shown that
 $\ell_n$
is a subsolution of
 $F_n = 0$
on
 $\mathbb{R}^+$
. From our earlier work in this proof, we know that, for
 $x \le 0$
,
 \begin{equation*}\ell_n(x) \le \psi_n(x),\end{equation*}
and we also have
 \begin{equation*}\lim_{x \to \infty} \ell_n(x) = 0 = \lim_{x \to \infty} \psi_n(x).\end{equation*}
Thus Lemma 2.1(c) implies
 $\ell_n \le \psi_n$
on
 $\mathbb{R}^+$
, and we have finished proving this proposition.
4.2. Convergence of
$\psi_n$
to
$\widetilde \psi$


In this section we prove our main result, namely that as n goes to infinity,
 $\psi_n$
converges to
 $\widetilde \psi$
uniformly with respect to x and with rate of convergence of order
 ${\mathrm{O}}\! \left(n^{-1/2}\right)$
. In words, this theorem justifies using the diffusion approximation when computing the discounted probability of exponential Parisian ruin for the classical risk process.
Theorem 4.1. If (4.3) holds, then there exist
 $D'' > 0$
and
 $M'' > 0$
such that, for all
 $n > M''$
and
 $x \in \mathbb{R}$
,
 \begin{align*} \left| \psi_n(x) - \widetilde \psi(x) \right| \le \dfrac{D''}{\sqrt{n}} .\end{align*}
Proof. From Propositions 4.1 and 4.2, we have, for
 $n > \max(N, N', M')$
and
 $x < 0$
,
 \begin{equation*}\biggl(1 - \dfrac{\delta}{\sqrt{n}}\biggr) \widetilde \psi(x) < \psi_n(x) < \dfrac{\rho}{\rho + \beta} \biggl( 1 - \dfrac{\widetilde \gamma_1 - {C}/{\sqrt{n}}}{\widetilde \gamma_1 + \widetilde \gamma_2 + {C'}/{\sqrt{n}}} \,{\mathrm{e}}^{( \widetilde \gamma_2 + {C'}/{\sqrt{n}} ) x} \biggr).\end{equation*}
By subtracting
 $\widetilde \psi(x)$
from each side, we obtain
 \begin{align*}- \dfrac{\delta}{\sqrt{n}} \, \widetilde \psi(x) < \psi_n(x) - \widetilde \psi(x) < \dfrac{\rho}{\rho + \beta} \cdot \dfrac{\widetilde \gamma_1}{\widetilde \gamma_1 + \widetilde \gamma_2} \,{\mathrm{e}}^{\widetilde \gamma_2 x} \left( 1 - \dfrac{1 - \frac{C}{\widetilde \gamma_1\sqrt{n}}}{1 + \frac{C'}{\left(\widetilde \gamma_1 + \widetilde \gamma_2\right)\sqrt{n}}} \,{\mathrm{e}}^{\left({C'}/{\sqrt{n}}\right) \, x}\right)\!.\end{align*}
The left-hand side is bounded below by
 $- {\delta}/{\sqrt{n}} \cdot {\rho}/{(\rho + \beta)}$
, and the expression in parentheses on the right-hand side is bounded above by
 \begin{equation*}1 - \dfrac{1 - \frac{C}{\widetilde \gamma_1\sqrt{n}}}{1 + \frac{C'}{(\widetilde \gamma_1 + \widetilde \gamma_2)\sqrt{n}}} \, \biggl(1 + \dfrac{C'}{\sqrt{n}} \, x \biggr) \le \dfrac{1}{\sqrt{n}} \, (\delta' - \delta'' x)\end{equation*}
for some constants
 $\delta' > 0$
and
 $\delta''> 0$
. Define the function f on
 $\mathbb{R}^-$
by
 \begin{equation*}f(x) = (\delta' - \delta'' x) \,{\mathrm{e}}^{\widetilde \gamma_2 x}.\end{equation*}
By differentiating f, we obtain
 \begin{align*}f'(x) & \propto - \delta'' + \widetilde \gamma_2 (\delta' - \delta'' x), \\f''(x) & \propto -2 \delta'' + \widetilde \gamma_2 (\delta' - \delta'' x),\end{align*}
which implies that f has a unique critical point
 $x_c = ({\widetilde \gamma_2 \delta' - \delta''})/{\widetilde \gamma_2 \delta''}$
, with
 $f''(x_c) < 0$
. Thus the maximum of f equals
 $f(x_c) = {\delta''} {\mathrm{e}}^{\widetilde \gamma_2 x_c}/{\widetilde \gamma_2} > 0$
, which we denote by
 $\tilde \delta$
. If we set
 \begin{equation*} D' = \max \biggl[\dfrac{\delta \rho}{\rho + \beta}, \, \dfrac{\rho}{\rho + \beta} \cdot \dfrac{\widetilde \gamma_1}{\widetilde \gamma_1 + \widetilde \gamma_2} \, \tilde \delta \biggr],\end{equation*}
then
 \begin{equation*}\left| \psi_n(x) - \widetilde \psi(x) \right| \le \dfrac{D'}{\sqrt{n}}\end{equation*}
for
 $n > \max(N, N', M')$
and
 $x < 0$
.
From Propositions 4.1 and 4.2, we have, for
 $n > \max(N, N', M')$
and
 $x \ge 0$
,
 \begin{equation*}\biggl(1 - \dfrac{2\delta}{\sqrt{n}}\biggr) \widetilde \psi(x) < \psi_n(x) < \dfrac{\rho}{\rho + \beta} \cdot \dfrac{\widetilde \gamma_2 + {C'}/{\sqrt{n}}}{\widetilde \gamma_1 + \widetilde \gamma_2 - {C}/{\sqrt{n}}} \,{\mathrm{e}}^{- ( \widetilde \gamma_1 - {C}/{\sqrt{n}} ) x}.\end{equation*}
By subtracting
 $\widetilde \psi(x)$
from each side, we obtain
 \begin{align*} - \dfrac{2\delta}{\sqrt{n}} \, \widetilde \psi(x) < \psi_n(x) - \widetilde \psi(x) < \dfrac{\rho}{\rho + \beta} \cdot \dfrac{\widetilde \gamma_2}{\widetilde \gamma_1 + \widetilde \gamma_2} \,{\mathrm{e}}^{- \widetilde \gamma_1 x} \left( \dfrac{1 + \frac{C'}{\widetilde \gamma_2\sqrt{n}}}{1 - \frac{C}{\left(\widetilde \gamma_1 + \widetilde \gamma_2\right)\sqrt{n}}} \,{\mathrm{e}}^{\left({C}/{\sqrt{n}}\right) \, x} - 1 \right)\!.\end{align*}
The left-hand side is bounded below by
 $- ({2\delta}/{\sqrt{n}}) \, \widetilde \psi(0)$
, and one can show that the expression in parentheses on the right-hand side times
 ${\mathrm{e}}^{- \widetilde \gamma_1 x}$
is bounded above by
 \begin{align}\biggl(1 + \dfrac{\delta'}{\sqrt{n}} \biggr) \,{\mathrm{e}}^{- ( \widetilde \gamma_1 - {C}/{\sqrt{n}} ) x} - {\mathrm{e}}^{- \widetilde \gamma_1 x} &= {\mathrm{e}}^{- \widetilde \gamma_1 x} ( {\mathrm{e}}^{({C}/{\sqrt{n}}) \, x} - 1 ) + \dfrac{\delta'}{\sqrt{n}} \,{\mathrm{e}}^{- ( \widetilde \gamma_1 - {C}/{\sqrt{n}} ) x},\end{align}
for some
 $\delta' > 0$
and for
 $n > (C/\widetilde \gamma_1 )^2$
. Define
 \begin{equation*}g(x) = {\mathrm{e}}^{- \widetilde \gamma_1 x} \bigl( {\mathrm{e}}^{({C}/{\sqrt{n}}) \, x} - 1 \bigr),\end{equation*}
then we have
 \begin{equation*}g'(x) = -\biggl(\widetilde \gamma_1 - \dfrac{C}{\sqrt{n}}\biggr)\,{\mathrm{e}}^{-(\widetilde \gamma_1 - {C}/{\sqrt{n}}) x} + \widetilde \gamma_1 {\mathrm{e}}^{-\widetilde \gamma_1 x}, \end{equation*}
which gives us the unique critical point
 \begin{equation*} x_c = - \dfrac{\sqrt{n}}{C} \ln \biggl(1- \dfrac{C}{\sqrt{n} \widetilde \gamma_1}\biggr), \end{equation*}
with
 $g''(x_c) < 0$
. Hence
 $g(x_c)$
is the maximum of g; thus, for all
 $x \ge 0$
,
 \begin{align}g(x) \le g(x_c) = \biggl(1 - \dfrac{C}{\widetilde \gamma_1 \sqrt{n}} \biggr)^{{\widetilde \gamma_1 \sqrt{n}}/{C}} \biggl(\dfrac{{C}/{\sqrt{n}}}{{\widetilde \gamma_1 - {C}/{\sqrt{n}}}} \biggr).\end{align}
By substituting (4.10) into (4.9), we obtain
 \begin{align*}{\mathrm{e}}^{- \widetilde \gamma_1 x} \bigl( {\mathrm{e}}^{({C}/{\sqrt{n}}) \, x} - 1 \bigr) + \dfrac{\delta'}{\sqrt{n}} \,{\mathrm{e}}^{- ( \widetilde \gamma_1 - {C}/{\sqrt{n}} ) x}\le \biggl(1 - \dfrac{C}{\widetilde \gamma_1 \sqrt{n}} \biggr)^{{\widetilde \gamma_1 \sqrt{n}}/{C}} \biggl(\dfrac{{C}/{\sqrt{n}}}{{\widetilde \gamma_1 - {C}/{\sqrt{n}}}} \biggr) + \dfrac{\delta'}{\sqrt{n}} .\end{align*}
The factor
 $(1 - {C}/{(\widetilde \gamma_1 \sqrt{n})} )^{{\widetilde \gamma_1 \sqrt{n}}/{C}}$
converges to
 ${\mathrm{e}}^{-1}$
, and the factor
 \begin{equation*}\biggl(\dfrac{{C}/{\sqrt{n}}}{{\widetilde \gamma_1 - {C}/{\sqrt{n}}}} \biggr)\end{equation*}
is of order
 ${\mathrm{O}}\! \left(n^{-1/2}\right)$
. Thus there exist
 $\delta'' > 0$
and
 $m'' > 0$
such that
 \begin{equation*}- \dfrac{2\delta}{\sqrt{n}} \, \widetilde \psi(0) < \psi_n(x) - \widetilde \psi(x) < \dfrac{\rho}{\rho + \beta} \cdot \dfrac{\widetilde \gamma_2}{\widetilde \gamma_1 + \widetilde \gamma_2} \cdot \dfrac{\delta''}{\sqrt{n}} ,\end{equation*}
for all
 $n > m''$
and
 $x \ge 0$
.
Thus, if we set
 \begin{equation*} D'' = \max \biggl[ D', \, 2\delta \widetilde \psi(0), \, \dfrac{\rho}{\rho + \beta} \cdot \dfrac{\widetilde \gamma_2}{\widetilde \gamma_1 + \widetilde \gamma_2} \cdot \delta'' \biggr]\end{equation*}
and
 \begin{equation*} M'' = \max(N, N', M', m''),\end{equation*}
then
 \begin{equation*}\left| \psi_n(x) - \widetilde \psi(x) \right| \le \dfrac{D''}{\sqrt{n}}\end{equation*}
for all
 $n > M''$
and
 $x \in \mathbb{R}$
.
In future work we hope to extend Theorem 4.1 when the surplus process is controlled, say, via reinsurance as in Liang and Young [Reference Liang and Young13]. The difficulty lies in modifying
 $\widetilde \psi$
to find a subsolution of
 $\psi_n$
. In this paper, we overcame that difficulty by finding separate subsolutions on
 $\mathbb{R}^{-}$
and
 $\mathbb{R}^+$
in Proposition 4.2, which required estimating
 $\psi_n(0)$
in Lemma 4.2.
Funding information
X. Liang thanks the National Natural Science Foundation of China (11701139, 11571189), the Research Foundation for Returned Scholars of Hebei Province (C20200102), and the Natural Science Foundation of Hebei Province (A2018202057, A2020202033) for financial support. Virginia R. Young thanks the Cecil J. and Ethel M. Nesbitt Professorship of Actuarial Mathematics for financial support.
Competing interests
There were no competing interests to declare which arose during the preparation or publication process of this article.


