



1. Introduction
We consider a superprocess in a random environment derived in [Reference Mytnik16] as the high-density limit of branching particle systems in random environments. Let
 $\kappa,\sigma^2>0$
. Suppose that
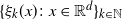 $\{\xi_k(x)\colon x\in\mathbb{R}^d\}_{k\in\mathbb{N}}$
is a sequence of independent and identically distributed random fields on
 $\mathbb{R}^d$
satisfying
 $\mathbb{E}[\xi_k(x)]=0$
,
 $\mathbb{E}[\xi_k(x)\xi_k(y)]=h(x,y)$
, and
 ${\sup}_x\mathbb{E}[|\xi_k(x)|^3] < \infty$
, where h is a continuous and positive-definite function with limits at
 $\infty$
and we assume
 $h(x,x)=c>0$
. Consider a particle system in
 $\mathbb{R}^d$
, where each particle moves independently as a copy of Brownian motions with diffusion coefficient
 $2\kappa$
until time
 $t={1}/{2\sigma^2n}$
. Conditioned on the environment
 $\{\xi_k(x)\colon x\in\mathbb{R}^d\}_{k\in\mathbb{N}}$
at time
 ${i}/{2\sigma^2n}$
, each particle splits into two with probability
 \begin{align*}\frac{1}{2}+\frac{1}{2\sqrt{2\sigma^2n}\,}[(\!-\sqrt{n})\vee\xi_i(x)\wedge(\sqrt{n})],\end{align*}
otherwise dying out with probability
 \begin{align*}\frac{1}{2}-\frac{1}{2\sqrt{2\sigma^2n}\,}[(\!-\sqrt{n})\vee\xi_i(x)\wedge(\sqrt{n})];\end{align*}
different particles move independently as Brownian motions with diffusion coefficient
 $2\kappa$
until time
 $({i+1})/{2\sigma^2n}$
. For a Borel set
 $B\subset\mathbb{R}^{d}$
, denote by
 $nX_t^{n}(B)$
the number of particles surviving until time t and located in B. By induction, we can define a sequence of measure-valued processes
 $\{X^n_t\colon t\geq 0\}$
. Let
 $C_{\mathrm{b}}(\mathbb{R}^d)$
be the collection of all bounded continuous functions on
 $\mathbb{R}^d$
. Let
 $C_{\mathrm{b}}^k(\mathbb{R}^d)$
be the collection of all bounded continuous functions on
 $\mathbb{R}^d$
with bounded continuous derivatives up to order k. Let
 $C_0^{\infty}(\mathbb{R}^d)$
be the set of functions on
 $\mathbb{R}^d$
with derivatives of all orders vanishing at infinity. Let
 $M(\mathbb{R}^d)$
be the space of all finite measures on
 $\mathbb{R}^d$
with weak topology. For all
 $f\in C_{\mathrm{b}}(\mathbb{R}^d)$
and
 $\mu\in M(\mathbb{R}^d)$
, let
 $\langle \mu,f\rangle = \langle \,f, \mu\rangle\,:\!=\int_{\mathbb{R}^d}f(x)\mu(\mathrm{d}x)$
. For
 $f,g\in C_{\mathrm{b}}(\mathbb{R}^d)$
,
 $\langle \,f,g\rangle$
also represents the integral of f g with respect to Lebesgue measure whenever it exists. Also let
 $\Delta$
be the d-dimensional Laplacian operator. It was proved in [Reference Mytnik16] that if
 $X_0^n$
converges weakly to a finite measure
 $\mu$
on
 $\mathbb{R}^d$
, then
 $\{X_t^n\colon t\geq 0\}$
converges to a measure-valued process
 $\{X_t\colon t\geq 0\}$
called a superprocess in a random environment (SRE). More specifically, let
 $(\Omega, \mathscr{F}, \mathscr{F}_t, \mathbb{P})$
be a filtered probability space satisfying the usual hypotheses. An SRE
 $\{X_t\colon t\geq 0\}$
is characterized by the solution to the following martingale problem (MP): for all
 $f\in C_{\mathrm{b}}^2(\mathbb{R}^d)$
,
 \begin{equation} M_t(f) \,:\!= \langle \,f, X_t\rangle - \langle \,f,\mu\rangle - \int_0^t\langle\kappa\Delta f,X_s\rangle\,\mathrm{d}s\end{equation}
is a continuous
 $(\mathscr{F}_t)$
-martingale with quadratic variation process
 \begin{equation*} \langle M_{\cdot}(f)\rangle_t = 2\sigma^2\int_0^t\langle \,f^2,X_s\rangle\,\mathrm{d} s + \int_0^t\int_{\mathbb{R}^d}\int_{\mathbb{R}^d}h(x,y)f(x)f(y)\,X_s(\mathrm{d}x)\,X_s(\mathrm{d}y)\,\mathrm{d}s.\end{equation*}
The uniqueness of the MP (1.1) is shown in [Reference Mytnik16].
Let
 $S_0$
be the linear span of the set of functions
 $\{h(x,\cdot)\colon x\in \mathbb{R}^d\}$
. We endow an inner product on
 $S_0$
with
 $\langle h(x,\cdot),h(y,\cdot)\rangle_{\mathbb{H}}\,:\!=h(x,y)$
. Let
 $\mathbb{H}$
be the completion of
 $S_0$
with respect to the norm
 $\|\cdot\|_H$
corresponding to the inner product
 $\langle \cdot,\cdot\rangle_{\mathbb{H}}$
. The Hilbert space
 $\mathbb{H}$
is called the reproducing kernel Hilbert space with covariance function h; see, e.g., [Reference Kallianpur7, p. 139]. Suppose that
 $\{e_i\colon i=1,2,\ldots\}$
is a complete orthonormal basis of
 $\mathbb{H}$
, and
 $\{B_t^i\colon t\geq 0\}_{i=1,2,\ldots}$
is a sequence of mutually independent d-dimensional standard Brownian motions defined on
 $(\Omega, \mathbb{P})$
. Define
 $W(t,x)=\sum_{i=1}^{\infty}\langle h(x,\cdot),e_i\rangle_{\mathbb{H}}B_t^i$
. Then W is a Gaussian noise, white in time and colored in space, with
 $\mathbb{E}[W(s,x)W(t,y)]=h(x,y)(s\wedge t)$
.
Suppose
 $(\mathscr{F}^W_t)_{t\geq 0}$
is the minimal augmented filtration generated by
 $\{B^i;i=1,2,\ldots\}$
. For an
 $(\mathscr{F}^W_t)_{t\geq 0}$
-predictable random function f(s,x), the Itô stochastic integral of f with respect to W is defined as
 \begin{equation*} \int_0^t f(s,x)\,W(\mathrm{d}s,x) \,:\!= \sum_{i=1}^{\infty}\int_0^t\langle \,f(s,x)h(x,\cdot),e_i\rangle_{\mathbb{H}}\,\mathrm{d}B_s^i = \sum_{i=1}^{\infty}f(s,x)\langle g(x,\cdot),e_i\rangle_{\mathbb{H}}\,\mathrm{d}B_s^i.\end{equation*}
This is equivalent to the notation
 $\int_0^t\langle \,f(s,x)g(x,\cdot),\mathrm{d}\mathbb{W}_s\rangle_{\mathbb{H}}$
used in [Reference Mytnik and Xiong17].
In this paper, we denote the conditional expectation and conditional probability given W by
 $\mathbf{E}$
and
 $\mathbf{P}$
, respectively. Let
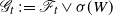 $\mathscr{G}_t\,:\!=\mathscr{F}_t\vee\sigma(W)$
. [Reference Mytnik and Xiong17] introduced conditional MPs and proved that the MP (1.1) is equivalent to the following conditional martingale problem: for all
 $f\in C_{\mathrm{b}}^2(\mathbb{R}^d)$
,
 \begin{equation} N_t(f) \,:\!= \langle \,f, X_t\rangle - \langle \,f,\mu\rangle - \int_0^t\langle\kappa\Delta f,X_s\rangle\,\mathrm{d}s - \int_0^t\int_{\mathbb{R}^d}f(x)\,W(\mathrm{d}s,x)\,X_s(\mathrm{d}x)\end{equation}
is a continuous
 $(\mathbb{P},\mathscr{G}_t)$
-martingale orthogonal to
 $\{W (t,x)\}$
with quadratic variation process
 $\langle N_{\cdot}(f)\rangle = 2\sigma^2\int_0^t\langle \,f^2,X_s\rangle\,\mathrm{d}s$
. Consider the formal solution
 $\{u_{s,t}(x);0\leq s\leq t\}$
to the stochastic partial differential equation (SPDE)
 \begin{equation} u_{s,t}(x) = f(x) + \int_s^t\kappa\Delta u_{r,t}(x)\,\mathrm{d}r - \int_s^t\sigma^2u_{r,t}(x)^2\,\mathrm{d}r + \int_s^t u_{r,t}(x)\,W(\hat{\mathrm{d}}r,x),\end{equation}
where
 $W(\hat{\mathrm{d}}r,x)$
denotes the backward Itô stochastic integral. Approximation and duality were used in [Reference Mytnik and Xiong17] to prove that, for a finite measure
 $\mu$
,
 \begin{equation} \mathbf{E}_{\mu}[\mathrm{e}^{-\langle \,f,X_t\rangle}] = \mathrm{e}^{-\langle u_{0,t},\mu\rangle}.\end{equation}
The equality in (1.4) provides a new perspective for this model from the viewpoint of the SPDE. The technique is derived from [Reference Xiong19]. Later, this method was extended to other related models; see also [Reference Li, Wang and Xiong13, Reference Li, Wang and Xiong14, Reference Xiong20]. Inspired by that, we use it to investigate some conditional properties of SREs. There are few results on this since the model here is abstract and lacks useful tools apart from the SPDE. The noise colored in space also brings much trouble.
We first investigate the conditional derivative form
 $\mathbb{E}[\langle g, X_t\rangle\mathrm{e}^{-\langle \,f,X_t\rangle }\mid\mathscr{G}_s]$
of (1.4). In the case of classical superprocesses, it is closely associated with the construction of derivative martingales and solved by simple analysis; see [Reference Eckhoff, Kyprianou and Winkel3]. However, it is more complicated in our case since the comparison theorem and the uniqueness of the solution for the corresponding SPDE (see (3.5) in Section 3) should be investigated further. The classical theory of SPDEs fails here since the coefficient of ther linear term is random and doesn’t satisfy the usual linear growth or Lipschitz conditions; see [Reference Kotelenez9]. In the future, we may use it to construct the derivative martingale and establish the corresponding spine decomposition.
Next, we consider the conditional entrance law and excursion representation of an SRE. Let S be a locally compact separable topological space, and
 $Y_t$
be an inhomogenous Markov process on S with transition semigroup
 $\{Q_{r,t}\,;\,t\geq r\geq0\}$
. A family of
 $\sigma$
-finite measure
 $\{L_{r,t}\,;\,t\geq r\geq0\}$
on S is called an entrance law for
 $\{Q_{r,t}\}$
if
 $L_{r,s}Q_{s,t}=L_{r,t}$
holds for all
 $0\leq r < s < t$
; see also [Reference Dynkin2]. The entrance law is necessary and crucial for the construction of the Kuznetsov measure that follows. Let
 $\mathscr{W}$
be the space of all continuous paths from
 $[0,\infty)$
to S with the coordinate process denoted by
 $\{w_t;\, t\geq 0\}$
. An excursion is a coordinate process starting from 0 and ending at 0 after some time. Let
 $\mathscr{W}^{\,+}$
be the space of all excursions. By a general theory of Markov processes, there is a
 $\sigma$
-finite measure N on
 $\mathscr{W}^{\,+}$
such that, under N, the coordinate process is also an inhomogenous Markov process with transition semigroup
 $\{Q_{r,t}\}$
and one-dimensional marginal distributions
 $\{L_{r,t}\}$
. N here is also called a Kuznetsov measure, following his pioneering work in [Reference Kuznetsov10]. Using these, we can represent
 $Y_t$
as a Poisson sum of excursions. The concept of excursion representation was pioneered by Itô [Reference Itô6] in the case of Brownian motion. There have since been many results in the field of superprocesses, such as [Reference Dawson and Li1, Reference Li12, Reference Li, Wang and Xiong14]. Following their ideas, we will construct the conditional entrance law in our case. The challenge lies in the estimation of the corresponding conditional extinction probability. Let
 $\{u^{\theta}_{s,t}(x)\}$
be the solution to (1.3) with initial value
 $u^{\theta}_{t,t}(x)=\theta>0$
. The main difficulty is that we should give a uniform upper bound for
 $u^{\theta}_{s,t}$
that is independent of
 $\theta$
. This question is also open in the theory of SPDEs. For convenience, we consider the forward version of (1.3) as follows. Suppose
 $u_t^{\theta}(x)$
solves
 \begin{equation*} u_{t}^{\theta}(x) = \theta + \int_0^t\kappa\Delta u^{\theta}_{s}(x)\,\mathrm{d}s - \int_0^t\sigma^2u^{\theta}_{s}(x)^2\,\mathrm{d}s + \int_0^su^{\theta}_{s}(x)\,\mathbb{W}(\mathrm{d}s,x),\end{equation*}
where
 $\mathbb{W}$
is defined in Section 3. First, we consider an SPDE without the Laplacian term in (1.3) (see
 $w^{\theta}_t$
in (4.1)) and give the corresponding upper bound for
 $w_t^{\theta}$
. Next, let
 $\tilde{u}_t^{\theta}(x)\,:\!=\int_{\mathbb{R}^d} p_{2\kappa t}(x-y)w_t^{\theta}(y)\,\mathrm{d}y$
, where
 $\{p_t(x);\,t\geq 0\}$
is the density of a d-dimensional standard Brownian motion throughout this paper. Then
 $\zeta_t^{\theta}(x)\,:\!=u_t^{\theta}(x)-\tilde{u}_t^{\theta}(x)$
satisfies (4.5) (see Section 4). Since the last two terms of (4.5) are martingales, we can prove they are bounded in
 $\theta$
by using Kolmogorov’s criterion. Finally, using a convolution representation, we can obtain that
 $\zeta_t^{\theta}(x)$
is bounded in
 $\theta$
.
This article is organized as follows. In Section 2 we elaborate the conditional Laplace functions in terms of the conditional transition semigroup. In Section 3, we give a derivative formula for the conditional Laplace functions. In Section 4, a uniform upper bound for
 $u^{\theta}_{s,t}(x)$
independent of
 $\theta$
is obtained, which leads to the conditional entrance law and the excursion representation of the SRE in Section 5.
2. Preliminaries
In this section we extend (1.4) to the form of a conditional transition semigroup for rigor (see Theorem 2.1). The proof is classical, and can be found in [Reference Xiong21, Chapter 6] and [Reference Li, Wang and Xiong13]. Here, we provide some different details for rigor.
By [Reference Walsh18, p. 288], the martingale
 $N_t(f)$
defined in (1.2) induces a martingale measure
 $\{N(\mathrm{d}s,\mathrm{d}x)\}$
with covariation measure
 $2\sigma^2\,X_s(\mathrm{d}x)\,\mathrm{d}s$
such that
 $N_t(f) = \int_0^t\int_{\mathbb{R}^d}f(x)\,N(\mathrm{d}s,\mathrm{d}x)$
, and
 $N(\mathrm{d}s,\mathrm{d}x)$
is orthogonal to
 $W(\mathrm{d}s,x)$
. Suppose
 $\mathscr{L}$
is the collection of all measurable functions
 $\{\alpha(s,x);\,(s,x)\in[0,\infty)\times\mathbb{R}^d\}$
satisfying
 \begin{equation*} \int_0^t\int_{\mathbb{R}^d\times\mathbb{R}^d}\alpha(s,x)\alpha(s,y)h(x,y)\,\mathrm{d}x\,\mathrm{d}y\,\mathrm{d}s < \infty.\end{equation*}
For bounded measurable functions
 $\alpha\in\mathscr{L}$
and
 $\beta$
on
 $\mathbf{B}\,:\!=[0,\infty)\times\mathbb{R}^d$
, define
 \begin{align*} \theta_{\alpha}(r,t) & = \exp\bigg\{\int_r^t\int_{\mathbb{R}^d}\alpha(s,x)\,W(\mathrm{d}s,x)\,\mathrm{d}x - \frac{1}{2}\int_r^t\int_{\mathbb{R}^d\times\mathbb{R}^d}\alpha(s,x)\alpha(s,y)h(x,y)\, \mathrm{d}x\,\mathrm{d}y\,\mathrm{d}s\bigg\}, \\ \zeta_{\beta}(r,t) & = \exp\bigg\{\int_r^t\int_{\mathbb{R}^d}\beta(s,x)\,N(\mathrm{d}s,\mathrm{d}x) - \int_r^t\int_{\mathbb{R}^d}\sigma^2\beta(s,x)^2\,X_s(\mathrm{d}x)\,\mathrm{d}s\bigg\}.\end{align*}
For
 $\rho>d$
, define
 $S_{\rho}$
to be the collection of measurable functions f satisfying
 \begin{equation*} \|f\|_{\rho}^2 = \int_{\mathbb{R}^d} f^2(x)(1+|x|^2)^{-{\rho}/{2}}\,\mathrm{d}x < \infty.\end{equation*}
We endow an inner product
 $\langle \cdot,\cdot\rangle_{\rho}$
to
 $S_{\rho}$
given by
 $\langle \,f,g\rangle_{\rho}=\int_{\mathbb{R}^d} f(x)g(x)(1+|x|^2)^{-{\rho}/{2}}\,\mathrm{d}x$
. Let
 $\mathbb{H}_{\rho}$
be the completion of
 $S_{\rho}$
with respect to the norm
 $\|\cdot\|_{\rho}$
. Then
 $\mathbb{H}_{\rho}$
is a Hilbert space. By Kotelenez’s result [Reference Kotelenez9], there exists a unique solution
 $\{u_{s,t};0\leq s\leq t\}$
to (1.3) for a given initial value
 $f\in\mathbb{H}_{\rho}$
. Define
 $\xi_{r,t}(x)\,:\!=\mathbb{E}[u_{r,t}(x)\theta_{\alpha}(r,t)]$
and
 $\eta_{r,t}(x)\,:\!=\mathbb{E}[u_{r,t}(x)^2\theta_{\alpha}(r,t)]$
.
Lemma 2.1. For
 $t\geq r\geq0$
and
 $x\in\mathbb{R}^d$
,
 \begin{equation*} \xi_{r,t}(x) = f(x) + \int_r^t\kappa\Delta\xi_{s,t}(x)\,\mathrm{d}s - \int_r^t\sigma^2\eta_{s,t}(x)\,\mathrm{d}s + \int_r^t\xi_{s,t}(x)\int_{\mathbb{R}^d}\alpha(s,y)h(x,y)\,\mathrm{d}y\,\mathrm{d}s. \end{equation*}
Proof. By Itô’s formula,
 $\theta_{\alpha}(r,t)=1+\int_r^t\int_{\mathbb{R}^d}\alpha(s,x)\,W(\mathrm{d} s,x)\theta_{\alpha}(s,t)$
. By (1.3), for
 $\phi\in C_0^{\infty}(\mathbb{R}^d)$
,
 \begin{align*} \langle u_{r,t},\phi \rangle \theta_{\alpha}(r,t) & = \langle \,f,\phi\rangle -\int_r^t\sigma^2\langle u_{s,t},\phi\rangle\theta_{\alpha}(s,t)\,\mathrm{d}s + \int_r^t\langle\theta_{\alpha}(s,t)u_{s,t}\,W(\hat{\mathrm{d}}s,\cdot),\phi\rangle \\ & \quad + \int_r^t\langle u_{s,t},\phi\rangle\int_{\mathbb{R}^d}\alpha(s,x)\theta_{\alpha}(s,t)\,W(\mathrm{d}s,x) \\ & \quad + \int_r^t\theta_{\alpha}(s,t)\int_{\mathbb{R}^d\times\mathbb{R}^d}u_{s,t}(x)\phi(x)\alpha(s,y)h(x,y)\, \mathrm{d}x\,\mathrm{d}y\,\mathrm{d}s. \end{align*}
Then, taking expectations on both sides, we obtain
 \begin{align*} \langle \xi_{r,t},\phi\rangle & = \langle \,f,\phi\rangle + \int_r^t\langle\kappa\xi_{s,t},\Delta\phi\rangle\,\mathrm{d}s - \int_r^t\sigma^2\langle\eta_{s,t},\phi\rangle\,\mathrm{d}s \\ & \quad + \int_r^t\bigg\langle\int_{\mathbb{R}^d}\xi_{s,t}\alpha(s,y)h(\cdot,y)\,\mathrm{d}y, \phi\bigg\rangle\,\mathrm{d}s, \end{align*}
which completes the proof.
Lemma 2.2. For
 $t\geq r\geq 0$
we have, almost surely (a.s.),
 \begin{equation*} \langle \,f,X_t\rangle = \langle u_{r,t},X_r\rangle + \int_r^t\int_{\mathbb{R}^d}u_{r,t}(x)\,N(\mathrm{d}s,\mathrm{d}x) + \int_r^t\langle\sigma^2u_{r,t}^2,X_s\rangle\,\mathrm{d}s. \end{equation*}
Proof. The proof is quite similar to [Reference Li, Wang and Xiong13, Lemma 5.4]; we give a sketch here to list the different parts for rigor. Since the linear span of the functionals
 $\{\theta_{\alpha}(0,t),\zeta_{\beta}(0,t)\colon\alpha\in\mathscr{L}, \beta\in\mathbf{B}\}$
is dense in the space of
 $\mathscr{F}_t$
-measurable random variables, it is sufficient to show that
 \begin{equation*} \mathbb{E}\bigg[\theta_{\alpha}(0,t)\zeta_{\beta}(0,t)\bigg(\langle \,f,X_t\rangle - \langle u_{r,t},X_r\rangle - \int_r^t\int_{\mathbb{R}^d}u_{r,t}(x)\,N(\mathrm{d}s,\mathrm{d}x) - \int_r^t\langle\sigma^2u_{r,t}^2,X_s\rangle\,\mathrm{d}s\bigg)\bigg] = 0 \end{equation*}
for all
 $\alpha\in\mathscr{L},\beta\in\mathbf{B}$
. By [Reference Li, Wang and Xiong13, Lemma 5.2], it follows that
 \begin{equation*} \mathbb{E}[\langle u_{r,t},X_r\rangle\theta_{\alpha}(0,t) \zeta_{\beta}(0,t)] = \mathbb{E}[\langle \xi_{r,t},X_r\rangle\theta_{\alpha}(0,r)\zeta_{\beta}(0,r)]. \end{equation*}
Considering the process
 $\langle \xi_{r,t},X_r\rangle$
, by Lemma 2.1 and (1.2) we have
 \begin{align*} \langle\xi_{r,t},X_r\rangle & = \langle \,f,X_t\rangle - \int_r^t\sigma^2\langle\eta_{s,t},X_s\rangle\,\mathrm{d}s + \int_r^t\langle\xi_{s,t}\int_{\mathbb{R}^d}h(\cdot,y)\alpha(s,y)\,\mathrm{d}y,X_s\rangle\,\mathrm{d}s \\ & \quad - \int_r^t\langle\xi_{s,t}\,W(\mathrm{d}s,\cdot),X_s\rangle - \int_r^t\int_{\mathbb{R}^d}\xi_{s,t}(x)\,N(\mathrm{d}s,\mathrm{d}x). \end{align*}
Write
 \begin{equation} \bar{\theta}_{\alpha}(r,t) \,:\!= \theta_{\alpha}(r,t)^{-1} = \frac{\theta_{\alpha}(0,r)}{\theta_{\alpha}(0,t)}, \qquad \bar{\zeta}_{\beta}(r,t) \,:\!= \zeta_{\beta}(r,t)^{-1} = \frac{\zeta_{\alpha}(0,r)}{\zeta_{\alpha}(0,t)} \end{equation}
and
 $\rho_{r,t}(x)= \xi_{r,t}(x) \bar{\theta}_{\alpha}(r,t)\bar{\zeta}_{\beta}(r,t)$
,
 $\gamma_{r,t}(x)=\eta_{r,t}(x)\bar{\theta}_{\alpha}(r,t)\bar{\zeta}_{\beta}(r,t)$
. Then, by Itô’s formula,
 \begin{align*} \langle\rho_{r,t},X_r\rangle & = \langle\xi_{r,t},X_r\rangle\bar{\theta}_{\alpha}(r,t)\bar{\zeta}_{\beta}(r,t) \\ & = \langle \,f,X_t\rangle - \int_r^t\sigma^2\langle\gamma_{s,t},X_s\rangle\,\mathrm{d}s \\ & \quad + \int_r^t\langle\rho_{s,t}\int_{\mathbb{R}^d}h(\cdot,y)\alpha(s,y)\,\mathrm{d}y,X_s\rangle\,\mathrm{d}s - \int_r^t\langle\rho_{s,t}W(\mathrm{d}s,\cdot),X_s\rangle \\ & \quad - \int_r^t\int_{\mathbb{R}^d}\rho_{s,t}(x)\,N(\mathrm{d}s,\mathrm{d}x) - \int_r^t\langle\rho_{s,t},X_s\rangle\int_{\mathbb{R}^d}\alpha(s,x)\,W(\mathrm{d}s,x)\mathrm{d}x \end{align*}
 \begin{align*} & \quad - \int_r^t\langle\rho_{s,t},X_s\rangle\int_{\mathbb{R}^d}\beta(s,x)\,N(\mathrm{d}s,\mathrm{d}x) - \int_r^t\sigma^2\langle\beta(s,\cdot)\rho_{s,t},X_s\rangle\,\mathrm{d}s \\ & \quad + \int_r^t\int_{\mathbb{R}^d\times\mathbb{R}^d}\rho_{s,t}(x)\alpha_s(y)h(x,y)\,\mathrm{d}y\,X_s(\mathrm{d}x), \end{align*}
where the third and last terms above are cancelled out. Taking expectations and using (2.1),
 \begin{align*} & \mathbb{E}[\langle \,f,X_t\rangle\theta_{\alpha}(0,t)\zeta_{\beta}(0,t)] - \mathbb{E}[\langle\xi_{r,t},X_r\rangle\theta_{\alpha}(0,r)\zeta_{\beta}(0,r)] \\ & \quad = \mathbb{E}\bigg[\int_r^t\sigma^2\theta_{\alpha}(0,s)\zeta_{\beta}(0,s) \langle\eta_{s,t},X_s\rangle\,\mathrm{d}s\bigg] + \mathbb{E}\bigg[\int_r^t\sigma^2\theta_{\alpha}(0,s)\zeta_{\beta}(0,s) \langle\beta(s,\cdot)\xi_{s,t},X_s\rangle\,\mathrm{d}s\bigg] \\ & \quad = \mathbb{E}\bigg[\int_r^t\langle\sigma^2\theta_{\alpha}(0,t)\zeta_{\beta}(0,t)u_{s,t}^2, X_s\rangle\,\mathrm{d}s\bigg] + \mathbb{E}\bigg[\int_r^t\theta_{\alpha}(0,t)\zeta_{\beta}(0,t)\int_{\mathbb{R}^d}u_{r,t}(x)\, N(\mathrm{d}s,\mathrm{d}x)\bigg], \end{align*}
where the last equality can be obtained directly by the proof of [Reference Li, Wang and Xiong13, Lemma 5.4].
By a similar argument to [Reference Li, Wang and Xiong13, Theorem 5.1], we have the following theorem.
Theorem 2.1. For
 $t\geq r\geq 0$
we have, a.s.,
 $\mathbf{E}[\mathrm{e}^{-\langle \,f, X_t\rangle}\mid\mathscr{G}_r]=\mathrm{e}^{-\langle u_{r,t},X_r\rangle}$
. Therefore, under
 $\mathbf{P}$
,
 $\{X_t\}$
is a measure-valued Markov process with inhomogenous transition semigroup
 $\{Q_{r,t}^W;t\geq r\geq 0\}$
given by
 $\int_{M(\mathbb{R}^d)}\mathrm{e}^{-\langle \,f,\nu\rangle} Q_{r,t}^W(\mu,\mathrm{d}\nu)=\mathrm{e}^{-\langle u_{r,t},\mu\rangle}$
.
Let
 $\{u_{s,t}(x,f);0\leq s\leq t\}$
be the solution to (1.3) with initial value
 $u_{t,t}(x,f)=f(x)$
. Finally, we show that
 $\{u_{s,t}(x,f);0\leq s\leq t\}$
has the following semigroup property.
Lemma 2.3. There exists a set
 $N\subset\Omega$
such that
 $\mathbb{P}(N)=1$
and
 $u_{r,t}(x,f)=u_{r,s}(x,u_{s,t}(\cdot,f))$
for
 $0\leq r\leq s\leq t$
,
 $f\in \mathbb{H}_{\rho}$
, and
 $\omega\in N$
.
Proof. Let
 \begin{align*} u_{s,t}(x) & = f(x) + \int_s^t\kappa\Delta u_{\tau,t}(x)\,\mathrm{d}\tau - \int_s^t\sigma^2u_{\tau,t}(x)^2\,\mathrm{d}\tau + \int_s^tu_{\tau,t}(x)\,W(\hat{\mathrm{d}}\tau,x), \\ u_{r,t}(x) & = f(x) + \int_r^t\kappa\Delta u_{\tau,t}(x)\,\mathrm{d}\tau - \int_r^t\sigma^2u_{\tau,t}(x)^2\,\mathrm{d}\tau + \int_r^tu_{\tau,t}(x)\,W(\hat{\mathrm{d}}\tau,x). \end{align*}
Then
 \begin{equation*} u_{r,t}(x)-u_{s,t}(x) = \int_r^s\kappa\Delta u_{\tau,t}(x)\,\mathrm{d}\tau - \int_r^s\sigma^2u_{\tau,t}(x)^2\,\mathrm{d}\tau + \int_r^su_{\tau,t}(x)\,W(\hat{\mathrm{d}}\tau,x). \end{equation*}
For
 $r-s+t\leq u\leq v\leq t$
, define
 $W^{1}([u,v],x)\,:\!=W([u+s-t,v+s-t],x)$
. Then
 \begin{align} u_{r,t}(x) & = u_{s,t}(x) + \int_{r-s+t}^t\kappa\Delta u_{\tau+s-t,t}(x)\,\mathrm{d}\tau - \int_{r-s+t}^t\sigma^2u_{\tau+s-t,t}(x)^2\,\mathrm{d}\tau \nonumber \\ & \quad + \int_{r-s+t}^tu_{\tau+s-t,t}(x)\,W^1(\hat{\mathrm{d}}\tau,x). \end{align}
In view of (1.3),
 $u_{r,t}(x)$
is the solution to (1.3) in the interval
 $[r-s+t,t]$
with the initial f(x) substituted by
 $u_{s,t}(x)$
and W substituted by
 $W^1$
. By [Reference Mytnik and Xiong17, Lemma 2.6], since (2.2) has a unique solution, we have
 $u_{r,t}(x)=u_{r,s}(x,u_{s,t}(\cdot))$
.
3. Derivative formula
In this section we link the derivative form (1.3) with the solution to an SPDE. For a fixed
 $t\geq 0$
, put
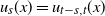 $u_s(x)=u_{t-s,t}(x)$
,
 $0\leq s\leq t$
and
 $\mathbb{W}([0,s),x)=W((t-s, t],x)$
. For convenience, we consider the forward version of (1.3):
 \begin{equation} u_t(x) = f(x) + \int_0^t\kappa\Delta u_s(x)\,\mathrm{d}s - \int_0^t\sigma^2(u_s(x))^2\,\mathrm{d}s + \int_0^t u_s(x)\,\mathbb{W}(\mathrm{d}s,x).\end{equation}
Recall that
 $\{p_t(x);t\geq 0\}$
is the density of a d-dimensional standard Brownian motion. Let
 $\mathbb{X}_0$
be the collection of measurable functions f satisfying
 $0\leq f(x)\leq C p_{1}(x)$
for all
 $x\in \mathbb{R}^d$
for a constant
 $C>0$
. Let
 $\{\psi_t(x);t\geq 0\}$
be the solution to the linear equation
 \begin{equation} \psi_t(x) = f(x) + \int_0^t\kappa\Delta\psi_s(x)\,\mathrm{d}s + \int_0^t\psi_s(x)\,\mathbb{W}(\mathrm{d}s,x).\end{equation}
We need the following result from [Reference Mytnik and Xiong17, Lemma 2.7].
Lemma 3.1. For
 $f\in\mathbb{X}_0$
,
 $u_t(x)\leq \psi_t(x)$
 $\mathbb{P}$
-a.s., and for some c(t),
 \begin{equation*} \mathbb{E}[\psi_t(x)\psi_t(y)]\leq c(t)p_{2\kappa t+1}(x)p_{2\kappa t+1}(y). \end{equation*}
Let
 $\mathbb{H}_0$
be the Hilbert space consisting of all functions f such that
 $\|f\|_0\,:\!=\int_{\mathbb{R}^d}f(x)^2\,\mathrm{d}x < \infty$
. For
 $\theta\geq0$
, let
 $F_t(\theta,x)$
be the solution to (3.1) with initial value
 $F_0(\theta,x)=f(x)+\theta g(x)$
, where
 $f,g\in\mathbb{X}_0$
. Set
 \begin{align} U_t(\theta,x) & \,:\!= \theta^{-1}[F_t(\theta,x)-F_t(0,x)], \end{align}
 \begin{align} d_s(x) & \,:\!= \sigma^2[F_s(\theta,x) + F_{s}(0,x)] = \sigma^2\theta[U_s(\theta,x)+2\theta^{-1}F_s(0,x)]. \\[8pt]\nonumber\end{align}
Consider the following SPDE:
 \begin{equation} v_t(x) = g(x) + \int^t_0\kappa\Delta v_s(x)\,\mathrm{d}s + \int^t_0v_s(x)\,\mathbb{W}(\mathrm{d}s,x) - \int^t_0 d_s(x)v_s(x)\,\mathrm{d}s.\end{equation}
It is obvious that
 $v_t(x)\,:\!=U_t(\theta, x)$
is a solution to (3.5). By Lemma 3.1,
 $v_t\in\mathbb{H}_0$
. We will show that (3.5) has a pathwise solution (Lemma 3.3) and satisfies the comparison theorem (Lemma 3.4).
Lemma 3.2. For fixed
 $t\geq 0$
, there exist positive constants
 $c_1,c_2$
such that
 \begin{equation*} \mathbb{E}\big[{\sup}_{0\leq s\leq t}\|v_s\|^4_0\big] \leq c_1\mathrm{e}^{c_2 t}. \end{equation*}
Proof. For
 $\phi\in C_\mathrm{c}^{\infty}(\mathbb{R}^d)$
, set
 $T_{\varepsilon}\phi(x) \,:\!= \int p_{\varepsilon}(x-y)\phi(y)\,\mathrm{d}y$
for
 $\varepsilon>0$
. Then
 \begin{equation*} \langle v_t,T_{\varepsilon}\phi\rangle = \langle g,T_{\varepsilon}\phi\rangle + \int^t_0\langle v_s,\kappa\Delta T_{\varepsilon}\phi\rangle\,\mathrm{d}s + \int^t_0\langle v_s\,\mathbb{W}(\mathrm{d}s,\cdot),T_{\varepsilon}\phi\rangle - \int^t_0\langle d_sv_s,T_{\varepsilon}\phi\rangle\,\mathrm{d}s. \end{equation*}
By Itô’s formula,
 \begin{align*} \langle v_t,T_{\varepsilon}\phi\rangle^2 & = \langle g,T_{\varepsilon}\phi\rangle^2 + \int_0^t2\langle v_s,T_{\varepsilon}\phi\rangle(\langle v_s,\kappa\Delta T_{\varepsilon}\phi\rangle - \langle d_s v_s,T_{\varepsilon}\phi\rangle)\,\mathrm{d}s \\ & \quad + \int_0^t2\langle v_s,T_{\varepsilon}\phi\rangle\langle v_s\, \mathbb{W}(\mathrm{d}s,\cdot),T_{\varepsilon}\phi\rangle \\ & \quad + \frac{1}{2}\int_0^t\int_{\mathbb{R}^d}\int_{\mathbb{R}^d}v_t(x)v_t(y)T_{\varepsilon}\phi(x)T_{\varepsilon} \phi(y)h(x,y)\,\mathrm{d}x\,\mathrm{d}y\,\mathrm{d}s. \end{align*}
Let
 $\{e_i\}_{i=1,2,\ldots}$
be a complete orthonormal system of
 $\mathbb{H}_0$
. Since
 $\langle u ,T_{\varepsilon} v\rangle=\langle T_{\varepsilon}u , v\rangle$
,
 \begin{align*} \|T_{\varepsilon}v_t\|^2_0 & = \sum_{i=1}^{\infty}\langle T_{\varepsilon}v_t,e_i\rangle^2 \\ & = \sum_{i=1}^{\infty}\langle v_t,T_{\varepsilon}e_i\rangle^2 \\ & = \sum_{i=1}^{\infty}\langle g,T_{\varepsilon}e_i\rangle^2 + \sum_{i=1}^{\infty}\int_0^t2\langle v_s,T_{\varepsilon}e_i\rangle(\langle v_s,\kappa\Delta T_{\varepsilon}e_i\rangle - \langle d_s v_s,T_{\varepsilon}e_i\rangle)\,\mathrm{d}s \\ & \quad + \sum_{i=1}^{\infty}\int_0^t2\langle v_s,T_{\varepsilon}e_i\rangle \langle v_s\,\mathbb{W}(\mathrm{d}s,\cdot),T_{\varepsilon}e_i\rangle \\ & \quad + \sum_{i=1}^{\infty}\frac{1}{2}\int_0^t\int_{\mathbb{R}^d}\int_{\mathbb{R}^d}v_t(x)v_t(y)T_{\varepsilon}e_i(x) T_{\varepsilon}e_i(y)h(x,y)\,\mathrm{d}x\,\mathrm{d}y\,\mathrm{d}s. \end{align*}
Notice that
 \begin{align*} \sum_{i=1}^{\infty}T_{\varepsilon}e_i(x)T_{\varepsilon}e_i(y) & = \sum_{i=1}^{\infty}\int_{\mathbb{R}^d}p_{\varepsilon}(x+z)e_i(z)\,\mathrm{d}z \int_{\mathbb{R}^d}p_{\varepsilon}(y+z)e_i(z)\,\mathrm{d}z \\ & = \int_{\mathbb{R}_d}p_{\varepsilon}(x+z)p_{\varepsilon}(y+z)\,\mathrm{d}z. \end{align*}
Then we get
 \begin{align*} \|T_{\varepsilon}v_t\|^2_0 & = \|T_{\varepsilon}g\|^2_0 + \int_0^t2\kappa\langle T_{\varepsilon}v_s,\Delta T_{\varepsilon}v_s\rangle\,\mathrm{d}s - \int_0^t\langle T_{\varepsilon}v_s,T_{\varepsilon}(d_sv_s)\rangle\,\mathrm{d}s \\ & \quad + \int_0^t2\langle T_{\varepsilon}v_s,T_{\varepsilon}(v_s\,\mathbb{W}(\mathrm{d}s,\cdot))\rangle \\ & \quad + \frac{1}{2}\int_0^t\int_{\mathbb{R}^d\times\mathbb{R}^d}\int_{\mathbb{R}^d}p_{\varepsilon}(x+z)p_{\varepsilon}(x+w) v_s(z)v_s(w)h(z,w)\,\mathrm{d}x\,\mathrm{d}z\,\mathrm{d}w\,\mathrm{d}s \\ & \leq \|g\|^2_0 + \int_0^t2\langle T_{\varepsilon}v_s,T_{\varepsilon}(v_s\,\mathbb{W}(\mathrm{d}s,\cdot))\rangle + \frac{1}{2}c\int_0^t\|T_{\varepsilon}v_s\|_0^2\,\mathrm{d}s. \end{align*}
Therefore, letting
 $\varepsilon\rightarrow 0$
, we obtain
 $\|v_t\|^2_0 \leq \|g\|^2_0 + \int_0^t2\langle v_s,v_s\,\mathbb{W}(\mathrm{d}s,\cdot)\rangle + \frac{1}{2}c\int_0^t\|v_s\|_0^2\,\mathrm{d}s$
. Using Doob’s inequality and the Cauchy–Schwarz inequality, we get
 \begin{equation*} \mathbb{E}\big[{\sup}_{0\leq s\leq t}\|v_s\|^4_0\big] \leq c_1 + c_2\int_0^t\mathbb{E}\big[{\sup}_{0\leq s\leq r}\|v_s\|^4_0\big]\,\mathrm{d}r. \end{equation*}
By (3.3) and Lemma 3.1, the right-hand side is bounded. Using Gronwall’s inequality, we complete the proof.
Next, we show that (3.5) has a unique solution.
Lemma 3.3. Suppose that
 $f,g\in\mathbb{X}_0$
. Then (3.5) has a unique non-negative solution.
Proof. By the comparison theorem [Reference Kotelenez9, Theorem 3.3], the solution
 $F_t(\theta+\delta,x)$
to (3.1) is increasing in
 $\delta$
. Therefore,
 $v_t(x)\geq 0$
. Suppose that there are two solutions
 $\{v_t^1(x)\}$
and
 $\{v_t^2(x)\}$
to (3.5). Let
 $v_t^0(x)=v_t^1(x)-v_t^2(x)$
. For
 $\phi\in C_\mathrm{c}^{\infty}(\mathbb{R}^d)$
,
 \begin{equation*} \langle v_t^0,\phi\rangle = \int^t_0\langle v^0_s,\kappa\Delta\phi\rangle\,\mathrm{d}s + \int^t_0\langle v^0_s,\phi\,\mathbb{W}(\mathrm{d}s,\cdot)\rangle - \int^t_0\langle d^1_sv^1_s - d^2_s v^2_s,\phi\rangle\,\mathrm{d}s, \end{equation*}
where
 $d^i_s(x)=\delta \sigma^2(v_s^i(x)+2F_s(\theta,x))$
for
 $i=1,2$
. By an analogous argument to Lemma 3.2,
 \begin{align*} \|v^0_t\|^2_0 & \leq -\int_0^t\langle v_s^0,d^1_sv^1_s - d^2_sv^2_s\rangle\,\mathrm{d}s + \int_0^t2\langle v_s^0,v_s^0\,\mathbb{W}(\mathrm{d}s,\cdot)\rangle + \frac{1}{2}c\int_0^t\|v_s^0\|_0^2\,\mathrm{d}s \\ & = -\int_0^t\langle\delta\sigma^2(v^0_s)^2,v^1_s + v^2_s + 2u_s(\theta,x)\rangle\,\mathrm{d}s + \int_0^t2\langle v_s^0,v_s^0\,\mathbb{W}(\mathrm{d}s,\cdot)\rangle + \frac{1}{2}c\int_0^t\|v_s^0\|_0^2\,\mathrm{d}s \\ & \leq \int_0^t2\langle v_s^0,v_s^0\,\mathbb{W}(\mathrm{d}s,\cdot)\rangle + \frac{1}{2}c\int_0^t\|v_s\|_0^2\,\mathrm{d}s. \end{align*}
Then, it’s easy to get
 $\mathbb{E}\big[{\sup}_{0\leq s\leq t}\|v^0_s\|^4_0\big] \leq c_1\int_0^t\mathbb{E}\big[{\sup}_{0\leq s\leq r}\|v^0_s\|^4_0\big]\,\mathrm{d}r$
, which yields the uniqueness by Gronwall’s inequality.
We now can establish the following comparison property.
Lemma 3.4.
 $v_t(x) \leq \psi_t(x)$
,
 $\mathbb{P}$
-a.s.
Proof. Let
 $\xi_t(x)=\psi_t(x)-v_t(x)$
. Then
 \begin{equation} \xi_t(x) = \int^t_0\kappa\Delta\xi_s(x)\,\mathrm{d}s + \int^t_0\xi_s(x)\,\mathbb{W}(\mathrm{d}s,x) + \int^t_0 d_s(x)v_s(x)\,\mathrm{d}s. \end{equation}
From the uniqueness of the solutions to (3.5) and (3.2), the uniqueness of the solution to (3.6) holds as well. For fixed
 $r\geq 0$
, consider the SPDE
 \begin{equation} \psi_{r,t}(x) = f(x) + \int_r^t\kappa\Delta\psi_{r,s}(x)\,\mathrm{d}s + \int_r^t\psi_{r,s}(x)\,\mathbb{W}(\mathrm{d}s,x), \quad t\geq r, \end{equation}
and denote its solution by
 $\psi_{r,t}(x,f)$
. Then, by [Reference Mytnik and Xiong17, Lemma 2.6], the uniqueness of the solution to (3.7) holds for
 $f\in\mathbb{H}_{\rho}$
. In view of (3.4),
 $d_s,v_s\in \mathbb{H}_{\rho}$
. Hence,
 $d_s v_s\in \mathbb{H}_{\rho}$
. Then we can define the solution
 $\{\psi_{r,t}(x,d_r v_r);t\geq r\}$
to (3.7) with
 $f=d_r v_r$
. Next, we claim that
 $\eta_t(x)\,:\!=\int_0^t\psi_{s,t}(x,d_sv_s)\,\mathrm{d}s \geq 0$
is a solution to (3.6). In fact, by (3.7),
 \begin{align*} \eta_t(x) & = \int_0^t\psi_{s,t}(x,d_sv_s)\,\mathrm{d}s \\ & = \int_0^t\bigg[d_s(x)v_s(x) + \int_s^t\kappa\Delta\psi_{r,s}(x,d_sv_s)\,\mathrm{d}r + \int_s^t\psi_{r,s}(x)\,\mathbb{W}(\mathrm{d}r,x)\bigg]\,\mathrm{d}s \\ & = \int_0^td_s(x)v_s(x)\,\mathrm{d}s + \int_0^t\int_0^r\kappa\Delta\psi_{r,s}(x,d_sv_s)\,\mathrm{d}s\,\mathrm{d}r + \int_0^t\int_0^r\psi_{r,s}(x)\,\mathrm{d}s\,\mathbb{W}(\mathrm{d}r,x) \\ & = \int_0^td_s(x)v_s(x)\,\mathrm{d}s + \int_0^t\kappa\Delta\eta_r(x)\,\mathrm{d}r + \int_0^t\eta_r(x)\,\mathbb{W}(\mathrm{d}s,x). \end{align*}
Consequently, the desired result follows from the uniqueness of solution to (3.6).
Theorem 3.1. For
 $f,g\in \mathbb{X}_0$
and
 $0\leq r\leq t$
,
 $\mathbf{E}[\langle g,X_t\rangle \mathrm{e}^{-\langle \,f,X_t\rangle}\mid\mathscr{G}_r]=\langle G_{r,t},X_r\rangle\mathrm{e}^{-\langle u_{r,t},X_s\rangle}$
, where
 $\{G_{r,t}(x)\}$
is the solution to the SPDE
 \begin{equation} G_{r,t}(x) = g(x) + \int_r^t\kappa\Delta G_{s,t}(x)\,\mathrm{d}s + \int_r^tG_{s,t}(x)\,W(\hat{\mathrm{d}}s,x) - \int_r^t2\sigma^2u_{s,t}(x)G_{s,t}(x)\,\mathrm{d}s. \end{equation}
Proof. Observe that
 $F_t(\theta,x)=-\log\mathbf{E}_{\delta_{x}}[\exp\{-\langle \,f+\theta g,X_t\rangle\}]$
is a concave function of
 $\theta$
. Then
 $U_t(\theta,x)=\theta^{-1}[F_t(\theta,x)-F_t(0,x)] $
increases to some limit denoted by
 $G_t(x)$
as
 $\theta\rightarrow 0+$
. Consequently, by Lemmas 3.1 and 3.4,
 \begin{equation*} \mathbb{E}\bigg[\int_0^t\int_{\mathbb{R}^d}[U_s(\theta,x)]^2\,\mathrm{d}x\,\mathrm{d}s\bigg] \leq \int_0^t\int_{\mathbb{R}^d}\mathbb{E}[\psi_s(x)]^2\,\mathrm{d}s\,\mathrm{d}x \leq C \end{equation*}
for some positive constant C. In view of (3.5), for rigor, we introduce the superscript
 $\theta$
in
 $v_s$
and
 $d_s$
to emphasize its impact. Then, for a non-negative function
 $\phi\in C_\mathrm{c}^{\infty}(\mathbb{R}^d)$
, we have
 \begin{equation} \langle v_t^{\theta},\phi\rangle = \langle g,\phi\rangle + \int_0^t\langle v_s^{\theta},\kappa\Delta\phi\rangle\,\mathrm{d}s + \int_0^t\langle v_s^{\theta}\,\mathbb{W}(\cdot,\mathrm{d}s),\phi\rangle - \int^t_0\langle d_s^{\theta}v_s^{\theta},f\rangle\,\mathrm{d}s. \end{equation}
By Lemma 3.4 and [Reference Mytnik and Xiong17, Lemma 2.7],
 \begin{align*} \mathbb{E}\bigg[\int_0^t\langle v_s^{\theta}\,\mathbb{W}(\cdot,\mathrm{d}s),\phi\rangle\bigg]^2 & = \int_0^t\int_{\mathbb{R}^{2d}}\mathbb{E}[v_s^{\theta}(x)v_s^{\theta}(y)]\phi(x)\phi(y)g(x,y)\, \mathrm{d}x\,\mathrm{d}y\,\mathrm{d}s \\ & \leq C\int_0^t\int_{\mathbb{R}^{2d}}\mathbb{E}[\psi_s(x)\psi_s(y)]\,\mathrm{d}x\,\mathrm{d}y\,\mathrm{d}s \\ & \leq \int_0^t\int_{\mathbb{R}^{2d}}cp_{2\kappa s+1}(x)p_{2\kappa s+1}(y)\,\mathrm{d}x\,\mathrm{d}y\,\mathrm{d}s \leq ct. \end{align*}
Thus, by the stochastic dominated convergence theorem, the third term on the right-hand side of (3.9) tends to
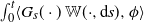 $\int_0^t\langle G_s(\cdot)\,\mathbb{W}(\cdot,\mathrm{d}s),\phi\rangle$
as
 $\theta\rightarrow 0+$
, while the other terms’ limits can be obtained by the monotone convergence theorem. Therefore,
 $\{G_s(x)\}$
solves the SPDE
 \begin{equation*} G_t(x) = g(x) + \int_0^t\kappa\Delta G_s(x)\,\mathrm{d}s + \int_0^tG_s(x)\,\mathbb{W}(\mathrm{d}s,x) - \int_0^t2\sigma^2F_s(0,x)G_s(x)\,\mathrm{d}s. \end{equation*}
Finally, we return to the backward version. For a fixed constant
 $\theta\geq 0$
, define
 $F_{s,t}(\theta,x)$
to be the solution to (1.3) with initial value
 $F_{t,t}(\theta,x)=f(x)+\theta g(x)$
and
 $U_{s,t}(\theta,x)\,:\!=\theta^{-1}[F_{s,t}(\theta,x)-F_{s,t}(0,x)]$
. By the previous argument,
 $U_{s,t}(\theta,x)$
converges to some limit
 $G_{s,t}(x)$
as
 $\theta\rightarrow 0+$
, and
 $G_{s,t}(\theta,x)$
is the unique solution to (3.8). Therefore,
 \begin{align*} \mathbf{E}[\langle g,X_t\rangle\mathrm{e}^{-\langle \,f,X_t\rangle}\mid\mathscr{G}_s] & = -\mathbf{E}\Big[\lim_{\theta\rightarrow0+}\theta^{-1}[\mathrm{e}^{-\langle \,f+\theta g,X_t\rangle} - \mathrm{e}^{-\langle \,f,X_t\rangle}]\mid\mathscr{G}_s\Big] \\ & = -\lim_{\theta\rightarrow0+}\theta^{-1}[\mathrm{e}^{-\langle F_{s,t}(\theta,x),X_s\rangle} - \mathrm{e}^{-\langle F_{s,t}(0,x),X_s\rangle}] \\ & = -\lim_{\theta\rightarrow0+}\mathrm{e}^{-\langle F_{s,t}(0,x),X_s\rangle} \theta^{-1}[\mathrm{e}^{-\langle\theta U_{s,t}(\theta,x),X_s\rangle}-1] \\ & = \mathrm{e}^{-\langle u_{s,t},X_s\rangle}\Big\langle\lim_{\theta\rightarrow 0+}U_{s,t}(\theta,x),X_s\Big\rangle = \langle G_{s,t},X_s\rangle \mathrm{e}^{-\langle u_{s,t},X_s\rangle}. \end{align*}
This completes the proof of the theorem.
4. Uniform upper bound for
 $u^{\theta}_{s,t}$

For convenience, we consider the forward version (3.1) and denote its solution with initial
 $f(x)\equiv\theta$
by
 $u_t^{\theta}$
. In this section we investigate the uniform upper bound for
 $u_{t}^{\theta}(x)$
instead of that for
 $u^{\theta}_{s,t}$
. To start, we consider the stochastic differential equation
 \begin{equation} w_{t}(x) = f(x) - \int_0^t\sigma^2w_s(x)^2\,\mathrm{d}s + \int_0^tw_s(x)\,\mathbb{W}(\mathrm{d}s,x).\end{equation}
By classical stochastic analysis, we have the following lemma.
Lemma 4.1. The equation (4.1) has a unique pathwise solution and there exists a random field
 $K \,:\!=K (t,x,\mathbb{W})$
, which doesn’t depend on f, such that
 $w_t(x)\leq K$
for all bounded measurable functions f.
Proof. In this proof we denote
 $\mathbb{W}(t,x)$
by
 $\mathbb{W}_t$
. Define the exponential function of
 $\mathbb{W}_t$
by
 $m_t(x)=\exp\big\{\mathbb{W}_t-\frac{1}{2}ct\big\}$
. Then, by Itô’s formula,
 \begin{equation} \mathrm{d}m_t = m_t\,\mathrm{d}\mathbb{W}_t \end{equation}
and the bracket process of
 $m_t$
is given by
 $\mathrm{d}[m_{\cdot}]_t = cm_t^2\,\mathrm{d}t$
. Define
 \begin{equation} w_t(x) = fm_t\bigg(1 + f\int_0^t\sigma^2m_s\,\mathrm{d}s\bigg)^{-1}. \end{equation}
Then we claim that
 $\{w_t\}$
is the pathwise solution to (4.1). In fact, write
 \begin{equation} z_t = \int_0^t\sigma^2m_s\,\mathrm{d}s. \end{equation}
Since
 $w_t(x)={fm_t}/({1+f{\kern0.5pt} z_t})$
, by Itô’s formula, (4.2), and (4.4),
 \begin{align*} \mathrm{d}w_t & = \frac{f}{1+f{\kern0.5pt}z_t}\,\mathrm{d}m_t - \frac{f^2m_t}{(1+f{\kern0.5pt}z_t)^2}\,\mathrm{d}z_t \\ & = \frac{fm_t}{1+f{\kern0.5pt}z_t}\,\mathrm{d}\mathbb{W}_t - \frac{f^2m_t}{(1+f{\kern0.5pt}z_t)^2}\sigma^2m_t\,\mathrm{d}t = w_t\,\mathrm{d}\mathbb{W}_t - \sigma^2w_t^2\,\mathrm{d}t. \end{align*}
That gives the solution to (4.1). Finally, by (4.3),
 $w_t\leq {m_t}/{z_t}$
. Hence, we have completed the proof.
Next, we return to (3.1). Compared with (4.1), it has an extra Laplacian operator term. Set
 $\tilde{u}_t^{\theta}(x) \,:\!= \int_{\mathbb{R}^d}p_{2\kappa t}(x-y)w_t^{\theta}(y)\,\mathrm{d}y$
. Then
 \begin{align*} \tilde{u}_t^{\theta}(x) & = \theta + \int_0^t\int_{\mathbb{R}^d}\partial_sp_{2\kappa s}(x-y)w_s^{\theta}(y)\,\mathrm{d}y\,\mathrm{d}s + \int_0^t\int_{\mathbb{R}^d}p_{2\kappa s}(x-y)\partial_sw_s^{\theta}(y)\,\mathrm{d}y\,\mathrm{d}s \\ & = \theta + \int_0^t\kappa\Delta\tilde{u}_s^{\theta}(x)\,\mathrm{d}s - \int_0^t\sigma^2(\tilde{u}_s^{\theta}(x))^2\,\mathrm{d}s + \int_0^t\tilde{u}_s^{\theta}(x)\,\mathbb{W}(\mathrm{d}s,x) \\ & \quad + \int_0^t\int_{\mathbb{R}^d}\sigma^2p_{2\kappa s}(x-y)[(w_s^{\theta}(y))^2 - (w_s^{\theta}(x))^2]\,\mathrm{d}y\,\mathrm{d}s \\ & \quad + \int_0^tw^{\theta}_s(x)\,\mathbb{W}(\mathrm{d}s,x) - \int_0^t\int_{\mathbb{R}^d}p_{2\kappa s}(x-y)w^{\theta}_s(y)\,\mathbb{W}(\mathrm{d}s,y)\,\mathrm{d}y\,\mathrm{d}s.\end{align*}
Define
 $\zeta^{\theta}_t(x)\,:\!=u_t^{\theta}(x)-\tilde{u}_t^{\theta}(x)$
. Then
 \begin{align} \zeta_t^{\theta}(x) & = \int_0^t\kappa\Delta\zeta_s^{\theta}(x)\,\mathrm{d}s + \int_0^t\zeta_s^{\theta}(x)\,\mathbb{W}(\mathrm{d}s,x) + \int_0^th^{\theta}_s(x)\,\mathrm{d}s \nonumber \\ & \quad + \int_0^tw^{\theta}_s(x)\,\mathbb{W}(\mathrm{d}s,x) - \int_0^t\int_{\mathbb{R}^d}p_{2\kappa s}(x-y)w_s^{\theta}(y)\,\mathbb{W}(\mathrm{d}s,y)\,\mathrm{d}y,\end{align}
where
 $h^{\theta}_s(x)=- \sigma^2 (u_s^{\theta}(x))^2 + \sigma^2 (\tilde{u}_s^{\theta}(x))^2$
. By Lemma 4.1,
 $h_t^{\theta}\leq \sigma^2({m_t}/{z_t})^2$
. Next, we show that the last two terms in (4.5) are bounded in
 $\theta$
. For
 $\lambda=\theta^{-1}$
, write
 $I_t^{\lambda}(x)\,:\!=\int_0^t w^{\theta}_s(x)\,\mathbb{W}(\mathrm{d} s,x)$
. Recalling that
 $\mathbb{W}([0,t-r),x)=W((r,t],x)$
, define the
 $\sigma$
-algebra
 $\tilde{\mathscr{F}}_t $
by
 \begin{equation*} \tilde{\mathscr{F}}_r\,:\!=\sigma\{W((s,t],x), t-r\leq s\leq t,x\in\mathbb{R}^d\}.\end{equation*}
Lemma 4.2. For fixed
 $t>0$
and
 $0\leq r\leq t $
, there exists an
 $\tilde{\mathscr{F}}_r$
-adapted process
 $\zeta_r$
such that
 ${\sup}_{\lambda\in(0,1]}I_t^{\lambda} \leq \zeta_r$
and
 $\mathbb{E}[{\sup}_{0\leq r\leq t}\zeta_r^2] < \infty$
.
Proof. It is clear that for fixed x,
 $\{W(t,x)\}_{t\geq 0}$
is a Brownian motion with diffusion coefficient
 ${c}/{2}$
. Then
 $\mathbb{E}[m_t]=\mathbb{E}[\mathrm{e}^{\mathbb{W}(t,x)-ct/2}] < \infty$
.
 \begin{align} \mathbb{E}\big[{\sup}_{0\leq r\leq t}[I_r^{\lambda}-I_r^{\lambda'}]^2\big] & \leq 4\mathbb{E}\bigg[\int_0^t\bigg[\frac{m_s}{\lambda+\int_0^s\sigma^2m_r\,\mathrm{d}r} - \frac{m_s}{\lambda'+\int_0^s\sigma^2m_r\,\mathrm{d}r}\bigg]^2\,\mathrm{d}s\bigg] \nonumber \\ & \leq \int_0^t\mathbb{E}\bigg[\bigg( \frac{(\lambda-\lambda')m_s}{(\int_0^s\sigma^2m_r\,\mathrm{d}r)^2}\bigg)^2\bigg]\,\mathrm{d}s \leq K|\lambda-\lambda'|^2. \end{align}
The last inequality can be obtained as follows: for
 $s\leq t$
,
 \begin{align*} \mathbb{E}\bigg[\frac{m_s^2}{\big(\int_0^sm_r\,\mathrm{d}r\big)^4}\bigg] & \leq \bigg(\mathbb{E}[(m_s)]^4\mathbb{E}\bigg[\bigg(\int_0^s\exp\{W(r,x)\,\mathrm{d}r - \frac{1}{2}cs\}\bigg)^{-8}\bigg]\bigg)^{{1}/{2}} \\ & \leq \mathrm{e}^{3cs}\bigg[\mathbb{E}\bigg[\bigg(\exp\bigg\{\int_0^sW(r,x)\,\mathrm{d}r - \frac{1}{2}cs\bigg\}\bigg)^{-8}\bigg]\bigg]^{\frac{1}{2}} \\ & = K_1\big[\mathbb{E}\big[\exp\big\{{-}8s\inf\nolimits_{0\leq r\leq s}W(r,x)\big\}\big]\big]\leq K_2, \end{align*}
where the last inequality is from Jensen’s inequality and the last equality is from the reflection principle of Brownian motion. Then, by Garsia’s theorem [Reference Kallianpur and Xiong8, Lemma 10.2.1], taking
 $\psi(x)=x^2$
,
 $p(x)=x^{{5}/{4}}$
, and
 \begin{equation*} \eta_r = \int_0^1\int_0^1\bigg(\frac{|I^{\lambda}_r-I_r^{\lambda'}|}{p(\lambda-\lambda')}\bigg)^2\, \mathrm{d}\lambda\,\mathrm{d}\lambda', \end{equation*}
by (4.6) we have
 \begin{align*} \mathbb{E}[{\sup}_{0\leq r\leq t}\eta_r] \leq \int_0^1\int_0^1K(\lambda-\lambda')^{-{1}/{2}}\, \mathrm{d}\lambda\,\mathrm{d}\lambda' & < \infty, \\ |I_r^{\lambda}-I_r^{\lambda'}| \leq 8\sqrt{\eta}\int_0^{|\lambda-\lambda'|}u^{-1}\,\mathrm{d}p(u) \leq 10\sqrt{\eta}\int_0^1u^{-{3}/{4}}\,\mathrm{d}u & < \infty. \end{align*}
Consequently, for
 $\lambda\leq 1$
,
 $I_r^{\lambda}\leq I_r^1+K\sqrt{\eta_r}\,:\!=\zeta_r$
. On the other hand, by (4.6),
 \begin{equation*} \mathbb{E}\big[{\sup}_{0 \leq r\leq t}\zeta_r^2\big] \leq K_1\mathbb{E}\big[{\sup}_{0 \leq r\leq t}(I^1_r)^2\big] + \mathbb{E}[{\sup}_{0 \leq r\leq t} \eta_r ] < \infty. \end{equation*}
Hence, we complete the proof.
Finally, it is sufficient to obtain an analogous comparison theorem for
 $\zeta^{\theta}_t(x)$
. Here, we make use of the convolution representation in [Reference Li, Wang, Xiong and Zhou15]. Recalling (3.7), by the Feynman–Kac representation in [Reference Hu, Nualart and Song5], we have
 \begin{equation*} \psi_{r,t}(x,f) = \mathbf{E}\bigg[f(x+\xi_t-\xi_r)\exp\bigg\{ \int_r^t\mathbb{W}(\mathrm{d}s,x+\xi_t-\xi_s) - \frac{1}{2}c(t-r)\bigg\}\bigg],\end{equation*}
where
 $\{\xi_t\}$
is a d-dimensional diffusion process independent of W with generator
 $\kappa\Delta$
and initial value
 $\xi_0=0$
. It is easy to check that
 \begin{align} \psi_{r,t}(x,f) & = \mathbf{E}\bigg[f(x+\xi_t-\xi_r)\exp\bigg\{\int_r^t\mathbb{W}(\mathrm{d}s,x+\xi_t-\xi_s) - \frac{1}{2}c(t-r)\bigg\}\bigg] \nonumber \\ & = \int_{\mathbb{R}^d}\mathbf{E}_{r,x}^{t,y}\bigg[f(y)\exp\bigg\{ \int_r^t\mathbb{W}(\mathrm{d}s,b_{s}) - \frac{1}{2}c(t-r)\bigg\}\bigg]p_{2\kappa(t-s)}(x-y)\,\mathrm{d}y,\end{align}
where
 $\big(\{b_{s};r\leq s\leq t\},\mathbf{E}_{s,y}^{t,x}\big)$
shares the same distribution as a d-dimensional Brownian bridge with diffusion coefficient
 $2\kappa$
, started at x at time r and ending at y at time t. Let
 \begin{equation*} p^{\mathbb{W}}(r,x;t,y) \,:\!= \mathbf{E}_{r,x}^{t,y}\bigg[\exp\bigg\{\int_s^t\mathbb{W}(\mathrm{d}s,b_{s}) - \frac{1}{2}c(t-r)\bigg\}\bigg]p_{2\kappa(t-s)}(x,y).\end{equation*}
Then
 \begin{equation} \psi_{r,t}(x,f)=\int_{\mathbb{R}^d}p^{\mathbb{W}}(r,x;t,y)f(y)\,\mathrm{d}y.\end{equation}
Let
 \begin{equation*} \langle\zeta_t^{\theta},f\rangle \,:\!= \int_0^t\langle\psi_{s,t}(\cdot,h_s^{\theta}),f\rangle\,\mathrm{d}s + \int_0^t\int_{\mathbb{R}^{2d}}p^{\mathbb{W}}(s,y;t,x)f(x)\,U(\mathrm{d}s,\mathrm{d}y)\,\mathrm{d}x,\end{equation*}
where we set
 $U(\mathrm{d}s,\mathrm{d}y) = w^{\theta}_{s}(y)\,\mathbb{W}(\mathrm{d}s,y)\,\mathrm{d}y -\int_{\mathbb{R}^{d}}p_{2\kappa s}(z-y)w_{s}^{\theta}(y)\,\mathbb{W}(\mathrm{d}s,y)\,\mathrm{d}y\,\mathrm{d}z$
for convenience.
Lemma 4.3
 $\{\zeta_t^{\theta};t\geq 0\}$
is a solution to (4.5).
Proof. Let
 $Y_t(f) = \langle\zeta_t^{\theta},f\rangle - \int_0^t\langle\zeta_s^{\theta},\kappa\Delta f\rangle - \int_0^t\langle\zeta_s^{\theta},f\,\mathbb{W}(\mathrm{d}s,\cdot)\rangle$
. Then, by (3.7) and (4.8),
 \begin{align*} Y_t(f) & = \int_0^t\langle\psi_{s,t}(\cdot,h_s^{\theta}),f\rangle\,\mathrm{d}s + \int_0^t\int_{\mathbb{R}^{2d}}p^{\mathbb{W}}(s,y;t,x)\,U(\mathrm{d}s,\mathrm{d}y)f(x)\,\mathrm{d}x \\ & \quad - \int_0^t\int_0^s\langle\psi_{r,s}(\cdot,h_r^{\theta}),\Delta f\rangle\,\mathrm{d}r\,\mathrm{d}s \\ & \quad - \int_0^t\int_0^s\int_{\mathbb{R}^{2d}}p^{\mathbb{W}}(r,y;s,x)\,U(\mathrm{d}r,\mathrm{d}y) \kappa\Delta f(x)\,\mathrm{d}x\,\mathrm{d}s \\ & \quad - \int_0^t\int_{\mathbb{R}^d}\int_0^s\psi_{r,s}(x,h_r^{\theta})\,\mathrm{d}r f(x)\,\mathbb{W}(\mathrm{d}s,x)\,\mathrm{d}x\,\mathrm{d}r \\ & \quad - \int_0^t\int_{\mathbb{R}^d}\int_0^s\int_{\mathbb{R}^{d}}p^{\mathbb{W}}(r,y;s,x)\, U(\mathrm{d}r,\mathrm{d}y)f(x)\,\mathbb{W}(\mathrm{d}s,x)\mathrm{d}x \\ & = \int_0^t\langle\psi_{r,t}(\cdot,h_r^{\theta}),f\rangle\,\mathrm{d}r - \int_0^t\int_r^t\langle\psi_{r,s}(\cdot,h_r^{\theta}),\kappa\Delta f\rangle\,\mathrm{d}r\,\mathrm{d}s \\ & \quad - \int_0^t\int_{\mathbb{R}^d}\int_r^t\psi_{r,s}(x,h_r^{\theta})\,\mathrm{d}s f(x)\,\mathbb{W}(\mathrm{d}r,x)\,\mathrm{d}x \\ & \quad + \int_0^t\int_{\mathbb{R}^d}\int_{\mathbb{R}^{d}}p^{\mathbb{W}}(r,y;t,x)f(x)\,\mathrm{d}x\, U(\mathrm{d}r,\mathrm{d}y) \\ & \quad - \int_0^t\int_{\mathbb{R}^d}\int_r^t\int_{\mathbb{R}^{d}}p^{\mathbb{W}}(r,y;s,x)\kappa\Delta f(x)\, \mathrm{d}x\,\mathrm{d}s\,U(\mathrm{d}r,\mathrm{d}y) \\ & \quad - \int_0^t\int_{\mathbb{R}^d}\int_r^t\int_{\mathbb{R}^{d}}p^{\mathbb{W}}(r,y;s,x)f(x)\, \mathbb{W}(\mathrm{d}s,x)\,\mathrm{d}x\,U(\mathrm{d}r,\mathrm{d}y) \end{align*}
 \begin{align*} & = \int_0^t\langle h_s^{\theta},f\rangle\,\mathrm{d}s + \int_0^t\int_{\mathbb{R}^d}f(x)\,U(\mathrm{d}r,\mathrm{d}x). \end{align*}
That gives the desired result.
In a conclusion, we can give a result that is important in the conditional entrance law in next section.
Theorem 4.1. There exists a set
 $N\subset\Omega$
with
 $\mathbb{P}(N)=1$
such that, for
 $\omega\in N$
and
 $t>0$
,
 \begin{equation*} {\sup}_{0\leq s < t}{\sup}_{\theta > 0}u^{\theta}_{s,t}(x) < \infty. \end{equation*}
Hence, for
 $\omega\in N$
and
 $0\leq r < t$
, we have
 $Q^W_{r,t}(\delta_x,\{\mathbf{0}\})>0$
.
Proof. By the proofs of Lemmas 4.2 and 4.3, there exists a set
 $N\subset\Omega$
such that, for
 $\omega\in N,0< t $
and
 $x\in\mathbb{R}^d$
,
 ${\sup}_{0\leq s < t}\lim_{\theta\rightarrow\infty}u^{\theta}_{s,t}(x) < \infty$
. Therefore,
 \begin{align*} Q_{r,t}^W(\delta_x,\{\mathbf{0}\}) & = \lim_{\theta\rightarrow\infty}\int_{M(\mathbb{R}^d)}\mathrm{e}^{-\theta\langle 1,\nu\rangle} Q_{r,t}^W(\delta_x,\mathrm{d}\nu) \\ & = \lim_{\theta\rightarrow\infty}\mathrm{e}^{-u^{\theta}_{s,t}(x)} \geq \exp\Big\{{-}{\sup}_{0\leq r< t}\lim_{\theta\rightarrow\infty}u^{\theta}_{r,t}(x)\Big\} > 0. \end{align*}
Then we obtain the result.
5. Conditional entrance law and excursion representation
Let
 $\{Q_{r,t}^W\colon t\geq r\geq 0\}$
be the conditional transition semigroup given in Theorem 2.1. Let
 $\{Q_{r,t}^{\circ,W}\colon t\geq r\geq 0\}$
be the restriction of
 $\{Q^W_{r,t}\colon t\geq r\geq 0\}$
on
 $M(\mathbb{R}^d)^{\circ}\,:\!=M(\mathbb{R}^d)\setminus\{\mathbf{0}\}$
.
Theorem 5.1. There exists a set
 $\tilde{N}\subset\Omega$
with
 $\mathbb{P}(\tilde{N})=1$
such that, for each
 $x\in\mathbb{R}^d$
, any
 $t>r\geq 0$
, and for all
 $\omega \in \tilde{N}$
, there is a finite random measure
 $L_{r,t}^W(x,\mathrm{d}\nu)$
on
 $M(\mathbb{R}^d)^{\circ}$
such that
 \begin{equation*} \int_{M(\mathbb{R}^d)^{\circ}}(1-\mathrm{e}^{-\langle\phi,\nu\rangle})\,L_{r,t}^W(x,\mathrm{d}\nu) = G_{r,t}(x,\phi), \end{equation*}
where
 $G_{r,t}(x,\phi)$
is the solution to the backward SPDE
 \begin{equation*} G_{r,t}(x) = \phi(x) + \int_r^t\Delta G_{s,t}(x)\,\mathrm{d}s + \int_r^tG_{s,t}(x)\,W(\hat{\mathrm{d}}s,x). \end{equation*}
Furthermore,
 $L_{r,t}^W$
is an entrance law for
 $\{Q^{\circ,W}_{r,t} \}$
, i.e. for each
 $x\in\mathbb{R}^d$
, any
 $t>s>r\geq 0$
, and for all
 $\omega\in \tilde{N}$
,
 \begin{equation} L_{r,t}^W(x,\mathrm{d}\nu) = \int_{M(\mathbb{R}^d)^{\circ}}L_{r,s}^W(x,\mathrm{d}\mu)\, Q_{s,t}^{\circ,W}(\mu,\mathrm{d}\nu). \end{equation}
Proof. Since, under
 $\mathbf{P}$
,
 $X_t$
is an infinitely divisible random measure, by [Reference Li11, Theorems 1.35 and 1.36], it has the following Lévy–Khintchine representation for any bounded measurable function f:
 \begin{equation} \int_{M(\mathbb{R}^d)}\mathrm{e}^{-\langle\mu,f\rangle}\,Q^W_{r,t}(\delta_x,\mathrm{d}\mu) = \exp\bigg[{-}\langle\lambda^W_{r,t}(x,\cdot),f\rangle - \int_{M(\mathbb{R}^d)^{\circ}}1-\mathrm{e}^{-\langle \,f,\nu\rangle}\,L^W_{r,t}(x,\mathrm{d}\nu)\bigg], \end{equation}
where
 $\lambda^W_{r,t}(x,\cdot)$
is a finite measure. Taking
 $f=\theta$
and letting
 $\theta\rightarrow\infty$
on both sides of (5.2), we have
 \begin{equation*} Q^W_{r,t}(\delta_x,\{\mathbf{0}\}) = \lim_{\theta\rightarrow\infty}\int_{M(\mathbb{R}^d)} \mathrm{e}^{-\langle\mu,\theta\rangle}Q_{r,t}(\delta_x,\mathrm{d}\mu) = \lim_{\theta\rightarrow\infty}\mathrm{e}^{-\theta\lambda_{r,t}(x,1)}. \end{equation*}
Since, by Theorem 4.1,
 $Q^W_{r,t}(\delta_x,\{\mathbf{0}\})>0$
a.s., we have
 $\lambda_{r,t}(x,\cdot)=0$
a.s. for each
 $t>r\geq 0$
. Therefore, for
 $t>r\geq0$
,
 \begin{equation*} \int_{M(\mathbb{R}^d)}\mathrm{e}^{-\langle\mu,f\rangle}Q^W_{r,t}(\delta_x,\mathrm{d}\mu) = \exp\bigg[{-}\int_{M(\mathbb{R}^d)^{\circ}}(1-\mathrm{e}^{-\langle \,f,\nu\rangle})\,L^W_{r,t}(x,\mathrm{d}\nu)\bigg]. \end{equation*}
Finally, we show that
 $L_{r,t}^W$
is an entrance law for
 $\{Q_{r,t}^{W}\}$
. Indeed, for
 $\omega\in N$
,
 \begin{align*} & \exp\bigg[{-}\int_{M(\mathbb{R}^d)^{\circ}}(1-\mathrm{e}^{-\nu(f)})\,L^W_{r,t}(x,\mathrm{d}\nu)\bigg] \\ & \qquad = \int_{M(\mathbb{R}^d)}\mathrm{e}^{-\langle\mu,f\rangle}Q^W_{r,t}(\delta_x,\mathrm{d}\mu) \\ & \qquad = \mathrm{e}^{-u_{r,t}(x,f)} \\ & \qquad = \mathrm{e}^{-u_{r,s}(x,u_{s,t}(x,f))} \\ & \qquad = \exp\bigg[{-}\int_{M(\mathbb{R}^d)^{\circ}}(1-\mathrm{e}^{-\langle u_{s,t}(x,f),\mu\rangle})\, L^W_{r,s}(x,\mathrm{d}\mu)\bigg] \\ & \qquad = \exp\bigg\{{-}\int_{M(\mathbb{R}^d)^{\circ}}\int_{M(\mathbb{R}^d)}[1-\mathrm{e}^{-\langle \,f,\nu\rangle}]\, Q_{s,t}^W(\mu,\mathrm{d}\nu)\,L^W_{r,s}(x,\mathrm{d}\mu)\bigg\}. \end{align*}
Since f is arbitrary, we obtain (5.1).
Let
 $W^E\,:\!=C([0,\infty),M(\mathbb{R})^d)$
. For any
 $w\in W^E$
, let
 $\alpha(w)=\inf\{s\geq 0,w(s)\neq\mathbf{0}\}$
and
 $\beta(w)=\sup\{s\geq 0,w(s)\neq\mathbf{0}\}$
. Let
 $\mathcal{W}$
denote the set of continuous paths
 $w\in W^E$
such that
 $w(t)\neq\mathbf{0}$
for
 $\alpha(w) < t < \beta(w)$
and
 $w(t)=\mathbf{0}$
for
 $t<\alpha(\omega)$
or
 $t\geq\beta(\omega)$
. On the space
 $\mathcal{W}$
, define the
 $\sigma$
-algebras
 $\mathscr{W}=\sigma(\{\omega(s);s\geq 0\})$
and
 $\mathscr{W}_t=\sigma(\{w(s);0\leq s\leq t\})$
for
 $t\geq 0$
. Then, by a similar proof to [Reference Getoor and Glover4], there exists a
 $\sigma$
-finite measure, say
 $N_r^x$
, on
 $\mathcal{W}_r$
such that, for
 $r < t_1 < t_2 < \cdots < t_n$
,
 \begin{multline} N_r^x(w_{t_1}\in\mathrm{d}\mu_1,w_{t_2}\in\mathrm{d}\mu_2,\ldots,w_{t_n}\in\mathrm{d}\mu_n) \\ = L_{r,t_1}^W(x,\mathrm{d}\mu_1)\,Q^{\circ,W}_{t_1,t_2}(\mu_1,\mathrm{d}\mu_2)\cdots Q^{\circ,W}_{t_{n-1},t_n}(\mu_{n-1},\mathrm{d}\mu_n).\end{multline}
The measure
 $N^x_r$
defined in (5.3) is also called the Kuznetsov measure [Reference Kuznetsov10], and more details in the case of superprocesses can be found in [Reference Li11].
Now, we fix
 $\mu\in M(\mathbb{R}^d)$
. On an extension of the original probability space, we can define a Poisson random measure
 $N^W_{\mu}(\mathrm{d}x,\mathrm{d}w)$
with intensity measure
 $\mu(\mathrm{d}x)N_0^x(\mathrm{d}w)$
conditioned on the noise W. Let
 $\mathscr{H}_t$
be the
 $\sigma$
-algebra generated by the
 $\mathbb{P}$
-null sets and the random variables
 $\big\{N_{\mu}^W(A\times B)\colon A\in\mathscr{B}(\mathbb{R}^d),B\in\mathscr{W}_t\big\}$
. Define the measure-valued processes
 \begin{equation} Y_t \,:\!= \int_{\mathbb{R}^d}\int_{\mathcal{W}}w_t\,N_{\mu}^W(\mathrm{d}x,\mathrm{d}w), \quad t\geq 0.\end{equation}
Theorem 5.2. For
 $f\in C_{\mathrm{b}}^+(\mathbb{R}^d)\cap\mathbb{H}_{\rho}$
and
 $0\leq r < t$
,
 $\mathbf{E}[\mathrm{e}^{-\langle \,f,Y_t\rangle}|\mathscr{H}_r]=\mathrm{e}^{-\langle u_{r,t},Y_r\rangle}$
.
Proof. Let
 $\mathscr{B}(\mathbb{R}^d)$
be the Borel sets on
 $\mathbb{R}^d$
, and let
 $g\in\mathscr{B}(\mathbb{R}^d)\times\mathscr{W}_r$
, i.e. g is a bounded positive function on
 $\mathbb{R}^d\times\mathcal{W}$
measurable relative to the product
 $\sigma$
-algebra
 $\mathscr{B}(\mathbb{R}^d)\times\mathscr{W}_r$
. By the Laplace transform of Poisson random measures, we have
 \begin{align} & \mathbf{E}\bigg[\exp\bigg\{{-}\int_{\mathbb{R}^d}\int_{\mathcal{W}}g(x,w)\,N_{\mu}^W(\mathrm{d}x,\mathrm{d}w) - \langle \,f,Y_t\rangle\bigg\}\bigg] \nonumber \\ & \qquad = \mathbf{E}\bigg[\exp\bigg\{{-}\int_{\mathbb{R}^d}\int_{\mathcal{W}}(g(x,w) + \langle \,f,w_t\rangle)\,N_{\mu}^W(\mathrm{d}x,\mathrm{d}w)\bigg\}\bigg] \nonumber \\ & \qquad = \exp\bigg\{\int_{\mathbb{R}^d}\int_{\mathcal{W}}(1-\exp\{-g(x,w)-\langle \,f,w_t\rangle\})\, N_0^x(\mathrm{d}w)\,\mu(\mathrm{d}x)\bigg\} \nonumber \\ & \qquad = \exp\bigg\{\int_{\mathbb{R}^d}\int_{\mathcal{W}}(1-\mathrm{e}^{-g(x,w)})\, N_0^x(\mathrm{d}w)\,\mu(\mathrm{d}x)\bigg\} \nonumber \\ & \qquad\quad + \exp\bigg\{\int_{\mathbb{R}^d}\int_{\mathcal{W}}\mathrm{e}^{-g(x,w)}(1-\mathrm{e}^{-\langle \,f,w_t\rangle})\, N_0^x(\mathrm{d}w)\,\mu(\mathrm{d}x)\bigg\}. \end{align}
On the other hand, since
 $g\in\mathscr{B}(\mathbb{R}^d)\times\mathscr{W}_r$
, by the Markov property of
 $N_0^x$
in (5.3), we have
 \begin{equation} \int_{\mathcal{W}}\mathrm{e}^{-g(x,w)}(1-\mathrm{e}^{-\langle \,f,w_t\rangle})\,N_0^x(\mathrm{d}w) = \int_{\mathcal{W}}\mathrm{e}^{-g(x,w)}(1-\mathrm{e}^{-\langle u_{r,t},w_r\rangle})\,N_0^x(\mathrm{d}w). \end{equation}
Hence, by (5.5) and (5.6), we have
 \begin{align*} & \mathbf{E}\bigg[\exp\bigg\{{-}\int_{\mathbb{R}^d}\int_{\mathcal{W}}g(x,w)\,N_{\mu}^W(\mathrm{d}x,\mathrm{d}w) - \langle \,f,Y_t\rangle\bigg\}\bigg] \\ & \qquad = \exp\bigg\{\int_{\mathbb{R}^d}\int_{\mathcal{W}}(1-\mathrm{e}^{-g(x,w)})\, N_0^x(\mathrm{d}w)\,\mu(\mathrm{d}x)\bigg\} \\ & \qquad\quad + \exp\bigg\{\int_{\mathbb{R}^d}\int_{\mathcal{W}}\mathrm{e}^{-g(x,w)}(1-\mathrm{e}^{-\langle \,f,w_t\rangle})\, N_0^x(\mathrm{d}w)\,\mu(\mathrm{d}x)\bigg\} \\ & \qquad = \exp\bigg\{\int_{\mathbb{R}^d}\int_{\mathcal{W}}(1-\mathrm{e}^{-g(x,w)})\, N_0^x(\mathrm{d}w)\,\mu(\mathrm{d}x)\bigg\} \\ & \qquad\quad + \exp\bigg\{\int_{\mathbb{R}^d}\int_{\mathcal{W}}\mathrm{e}^{-g(x, w)} (1-\mathrm{e}^{-\langle u_{r,t},w_r\rangle})\,N_0^x(\mathrm{d}w)\,\mu(\mathrm{d}x)\bigg\} \\ & \qquad = \exp\bigg\{\int_{\mathbb{R}^d}\int_{\mathcal{W}}(1-\mathrm{e}^{-g(x,w)-\langle u_{r,t},w_r\rangle})\, N_0^x(\mathrm{d}w)\,\mu(\mathrm{d}x)\bigg\} \\ & \qquad = \mathbf{E}\bigg[\exp\bigg\{{-}\int_{\mathbb{R}^d}\int_{\mathcal{W}}g(x,w)\, N_{\mu}^W(\mathrm{d}x,\mathrm{d}w) - \langle u_{r,t},Y_r\rangle\bigg\}\bigg]. \end{align*}
Clearly,
 $\mathscr{H}_r$
is equal to the
 $\sigma$
-algebra generated by the collection of
 \begin{align*}\exp\bigg\{{-}\int_{\mathbb{R}^d}\int_{\mathcal{W}}g(x,w)\,N_{\mu}^W(\mathrm{d}x,\mathrm{d}w)\bigg\}\end{align*}
for
 $g\in\mathscr{B}(\mathbb{R}^d)\times\mathscr{W}_r$
. Hence, we get the desired result.
By Theorems 2.1 and 5.2, the processes
 $\{X_t\}$
and
 $\{Y_t\}$
have the same conditional distributions. In view of (5.4), since
 $N_{\mu}(\mathrm{d}x,\mathrm{d}w)=\delta_{(x^i,w^i)}$
, we have
 $Y_t=\sum_{i=1}^{\infty}w^i_t$
. Hence, we can view the SRE as sums of continuous paths that are excursions starting from 0 and ending at 0. Therefore, (5.4) can be understood as the excursion representation of the SRE.
Acknowledgements
We thank the referees for very helpful comments and suggestions.
Funding information
The research of Jie Xiong is supported by the National Key R
 $\&$
D Program of China under Grant No. 2022YFA1006102.
Competing interests
There were no competing interests to declare which arose during the preparation or publication process of this article.


