



1. Introduction
A counting process is a stochastic model used to track the occurrence of discrete events over time, often applied in fields like finance, reliability, and epidemiology. The Poisson process is the most popular counting process, serving as the standard framework for modeling random arrivals in continuous time. While it is an extremely important count model, its reliance on exponentially distributed inter-arrival times limits its applicability in some practical situations. More specifically, it assumes independence and stationarity, but real-world events often deviate from these assumptions due to clustering, time-dependent rates, or inter-event dependences. Identifying these departures is crucial for accurate modeling in fields like epidemiology and finance, where event patterns are more complex. Cha and Finkelstein [Reference Cha and Finkelstein5] introduced a counting process called the geometric counting process, whose increments follow a geometric distribution. It is a special type of stochastic process that builds on the concept of a mixed Poisson process, in which the event rate is random rather than fixed. It originated in studies of mixed Poisson models, particularly those reviewed in [Reference Grandell15] and [Reference Rolski, Schmidli, Schmidt and Teugels37], and became more specific when the rate parameter was modeled as an exponential distribution. This led to a process with geometrically distributed increments and dependent events, unlike the traditional Poisson process.
The geometric counting process has attracted increasing attention in recent years. Di Crescenzo and Pellerey [Reference Di Crescenzo and Pellerey10] explored several properties and applications of the process in areas such as shock models, seismology, and software reliability. These recent developments have led to increased interest among researchers, who have begun using the geometric process as a time change. Meoli [Reference Meoli29] explored some Poisson-based processes, using a geometric counting process as a time change. More generally, time-changed processes, sometimes called subordinated stochastic processes, and their first-exit times have been widely studied in the literature. The most general among them is a non-decreasing Lévy process [Reference Sato38], called a subordinator. Several well-known examples of subordinators include the gamma process, the lower incomplete gamma process, the inverse Gaussian process, the stable process, the tempered stable process, the geometric stable process, etc. Subordinators are fundamental in defining a new class of stochastic processes known as the time-changed Poisson processes of Type I, where the time change is governed by a Lévy subordinator. This class includes several well-known models, such as the space-fractional Poisson process [Reference Orsingher and Polito31], the tempered space-fractional Poisson process [Reference Gupta, Kumar and Leonenko18], and the space-fractional negative binomial process [Reference Maheshwari and Vellaisamy26].
Another important class arises when the time change is governed by the inverse of a Lévy subordinator; one obtains another important class of counting processes, often referred to as time-changed Poisson processes of Type II, including the well-known fractional Poisson process [Reference Laskin22] and its various generalizations. These processes typically exhibit non-Markovian behavior and heavy-tailed waiting times. The use of generalized Lévy subordinators and their inverses in constructing time-changed Poisson processes has been widely studied in the literature (see [Reference Gupta and Kumar16], [Reference Gupta and Maheshwari17], [Reference Kataria and Khandakar20], [Reference Maheshwari and Vellaisamy27], [Reference Polito and Scalas36], [Reference Soni, Pathak, Di Crescenzo and Meoli40], [Reference Toaldo42]). These processes have various applications in finance, statistical physics [Reference Laskin23, Reference Uchaikin and Sibatov43], anomalous diffusion modeling [Reference Piryatinska, Saichev and Woyczynski35], fractional partial differential equations, etc.
Although time-changed Poisson processes have been widely studied, most existing models rely on time changes driven by Lévy subordinators or by the inverses of Lévy subordinators. In contrast, the geometric counting process considered in this paper is not a Lévy process and induces a different dependence structure in the resulting time-changed Poisson processes. Consequently, the resulting counting processes exhibit clustering behavior and dependence properties that do not arise in classical subordinated Poisson models. While Meoli [Reference Meoli29] studied specific Poisson processes under geometric time change, the present work develops a broader framework.
In particular, we introduce geometric time-changed Poisson processes of both Type I and Type II, together with their compound and multiplicative extensions. We derive several distributional and dependence properties of these processes, including explicit expressions for their moments, covariance structure, and first-passage time characteristics. Several important special cases are also identified within the proposed framework. Furthermore, the proposed geometric time-changed Poisson process of Type I is applied to reliability shock models (namely, the extreme shock model and the cumulative shock model), demonstrating their usefulness in modeling systems subjected to repeated or clustered shocks. Despite the wide applicability of extreme and cumulative shock models, most of the literature uses (homogeneous/non-homogeneous, and mixed) Poisson processes to model shock arrivals. However, Poisson processes are unsuitable for modeling events with heavy-tailed inter-arrival times and/or multiple occurrences. The proposed geometric time-changed Poisson process of Type I is highly flexible and can capture phenomena such as the fractional Poisson process, the space-fractional Poisson process, and the tempered space-fractional Poisson process, which are all special cases. Thus, adopting a flexible process to model shock arrivals may improve the prediction of the system’s lifetime in a shock environment. To our knowledge, we are the first to study shock models with a general process that accounts for multiple occurrences and heavy-tailed inter-arrival times.
The main contributions of the present paper can be summarized as follows.
-
• We introduce geometric time-changed Poisson processes of Type I and Type II and investigate their fundamental probabilistic properties.
-
• We construct geometric time-changed compound and multiplicative Poisson processes of both types and derive their distributional characteristics.
-
• Explicit expressions for several quantities of interest, including Laplace transforms, mean, variance, covariance structure, and distribution functions, are obtained.
-
• Several special cases are discussed, including the geometric space-fractional Poisson process, the geometric time-fractional Poisson process, and their tempered versions.
-
• Applications to reliability shock models are presented for the geometric time-changed Poisson process of Type I to illustrate the usefulness of the proposed processes.
The paper is organized as follows. In Section 2 we provide some preliminary definitions and results. We also establish the fractional moment and joint fractional moment results for the geometric counting process (GCP). Section 3 introduces the time-changed Poisson process I with geometric time, along with a detailed discussion of its distributional properties. In Section 4 we discuss the time-changed Poisson process II with geometric time, together with its distributional properties. In Section 5 we explore the generalized compound Poisson process with a geometric random component, and the generalized multiplicative Poisson process with a geometric random component for both types. In Section 6 we present applications in shock models for specific processes. Finally, we conclude in Section 7.
2. Preliminaries
In this section we recall some relevant definitions and properties of Lévy subordinators and their inverse subordinator. We also present the time-changed Poisson process I and the time-changed Poisson process II, along with some special examples, namely the space-fractional Poisson process (SFPP), the tempered space-fractional Poisson process (TSFPP), and the time-fractional Poisson process (TFPP). These results will be used to analyze certain generalized counting processes with geometric random times.
2.1. Lévy subordinator and its inverse
A Lévy subordinator (hereafter referred to as the subordinator)
 $\{D^{f}(t)\}_{t\geq0}$
is a non-decreasing Lévy process, and its Laplace transform (LT) (see [Reference Applebaum1, Section 1.3.2]) has the form
 \begin{align*}\mathbb{E}[{\mathrm{e}}^{-s D^{f}(t)}]={\mathrm{e}}^{-tf(s)}, \end{align*}
where
 \begin{align*}f(s)=b s+\int_{0}^{\infty}(1-{\mathrm{e}}^{-s x})\Pi({\mathrm{d}} x),\quad b\geq0,\ s\gt 0, \end{align*}
is the Bernstein function (see [Reference Schilling, Song and Vondraček39] for more details). Here b is the drift coefficient and
 $\Pi$
is a non-negative Lévy measure on the positive half-line satisfying
 \begin{equation*}\int_{0}^{\infty}(x\wedge 1)\Pi({\mathrm{d}} x)\lt\infty\quad \textrm{and}\quad \Pi([0,\infty))= \infty,\end{equation*}
which ensures that the sample paths of
 $\{D^{f}(t)\}_{t \geq 0}$
are almost surely (a.s.) strictly increasing. Also, the first-exit time of
 $\{D_f(t)\}_{t\geq0}$
is defined as
 \begin{equation}E^{f}(t)=\inf\{r\geq 0\colon D^{f}(r)\gt t\},\end{equation}
which is the right-continuous inverse of the subordinator
 $\{D_f(t)\}_{t\geq 0}$
. The process
 $\{E^{f}(t)\}_{t \geq 0}$
is non-decreasing and its sample paths are continuous.
We discuss some special cases of strictly increasing subordinators. The following subordinators with Laplace exponent denoted by f(s) are very often used in the literature:
 \begin{align}f(s) = \begin{cases} s^{\alpha} & \text{(stable subordinator),}\\[3pt] \sum_{i=1}^{n}{c_{i}s^{\alpha_{i}}} &\text{(mixed stable subordinator),}\\[3pt] (s+\nu)^{\alpha}-\nu^{\alpha}&\text{(tempered stable subordinator),}\\[3pt] \sum_{i=1}^{n}{c_{i}((s+\nu_{i})^{\alpha_{i}}-{\nu_{i}}^{\alpha_{i}})} &\text{(mixture of tempered stable subordinator),}\\[3pt] p\log(1+{{s}/{\beta}}) &\text{(gamma subordinator),}\\[3pt] \delta\bigl(\sqrt{2s+\gamma^2}-\gamma\bigr) & \text{(inverse Gaussian subordinator),}\end{cases}\end{align}
where
 $0 \lt \alpha \lt 1$
,
 $c_{i}\geq{0}$
,
 $ \sum_{i=1}^{n}{c_{i}}= 1$
,
 $\nu \gt 0$
,
 $p \gt 0$
,
 $\beta \gt 0$
,
 $\gamma\gt 0$
, and
 $\delta\gt 0$
.
2.2. Geometric counting process (GCP)
A geometric counting process (GCP)
 $\{G_\mu(t)\}_{t \geq 0}$
with parameter
 $\mu \gt 0$
is a class of the mixed Poisson process (see [Reference Grandell15]), whose one-dimensional distribution is given by
 \begin{align*}P_k^{\mu}=\mathbb{P}[G_\mu(t)=k]=\int_{0}^{\infty}\mathbb{P}[N(t)=k]\,{\mathrm{d}} U_{\mu}(\lambda), \quad k \in 0,1,\ldots,\end{align*}
where
 $\{N(t)\}_{t \geq 0}$
is a Poisson process with intensity
 $\lambda \gt 0$
and
 ${\mathrm{d}} U_{\mu}(\lambda)$
is the exponential distributed with mean
 $\mu \gt 0$
.
The GCP
 $\{G_\mu(t)\}_{t \geq 0}$
satisfies the following properties for fixed
 $\mu \gt 0$
(see [Reference Rolski, Schmidli, Schmidt and Teugels37]):
 \begin{equation}\begin{aligned} G_{\mu}(0)&=0,\\[3pt] \mathbb{P}[G_\mu(t+s)-G_\mu(t)=k]&=\frac{1}{1+\mu s}\biggl(\frac{\mu s}{1+\mu s}\biggr)^k,\quad s, t \geq 0.\end{aligned}\end{equation}
The above property says that it has a stationary increment property, and the GCP is geometrically distributed with parameter
 ${{\mu s}/{(1+\mu s)}}$
for every length of the time interval
 $s \gt 0$
.
The GCP possesses the property of dependent increments. The dependence structure in the increments of this process is given by the positive upper orthant dependent increments property, that is, for any arbitrary integer
 $m \geq 2$
and
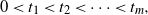 $0 \lt t_{1} \lt t_{2} \lt \cdots \lt t_{m},$
 \begin{align*}\mathbb{P}(G_{\mu}(t + \Delta t_{i}) - G_{\mu}(t_{i}) \gt n_{i}, i = 1,2,\dots, m ) \geq \prod_{i=1}^{m} \mathbb{P}(G_{\mu}(t_{i} + \Delta t_{i}) - G_{\mu}(t_{i}) \gt n_{i}), \end{align*}
for all
 $n_{i}$
,
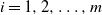 $i = 1,2,\dots, m$
, where
 $t_{i} + \Delta t_{i} \leq t_{i+1},$
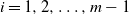 $i = 1,2,\dots, m-1$
(see Cha and Mercier [Reference Hwan Cha and Mercier19]). Such a dependence in the increments indicates that when the number of past events is higher, the likelihood of future events is also higher. This type of dependence is useful in many real-life applications, particularly in reliability applications.
The LT of
 $G_\mu(t)$
is given by
 \begin{align}\mathbb{E}[{\mathrm{e}}^{-sG_\mu(t)}]=\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-s})},\quad \mathrm{Re}(s) \gt 0. \end{align}
For a complex variable y, the geometric polynomials
 $w_n(y)$
of degree
 $n \in \mathbb{N}\cup \{0\}$
were introduced in Euler’s work [Reference Boyadzhiev3, Reference Boyadzhiev4] and are defined by
 \begin{align*} w_n(y)=\sum_{k=0}^n \genfrac{\{}{\}}{0pt}{}{n}{k} k!y^k, \end{align*}
where
 \begin{align*} \genfrac{\{}{\}}{0pt}{}{n}{k}=\dfrac{1}{k!}\sum_{i=0}^k(\!-1)^i{\binom{k}{i}}(k-i)^n,\quad k=0,1,\ldots,n, \end{align*}
are the Stirling numbers of the second kind. The geometric-like series is given by
 \begin{align*} \sum_{k=0}^\infty k^n y^k=\dfrac{1}{1-y}w_n\biggl(\dfrac{y}{1-y}\biggr), \end{align*}
when
 $|y| \leq 1$
and
 $n \in \mathbb{N}$
.
The mean, variance, and covariance of the geometric counting process
 $G_\mu(t)$
are given by
 \begin{align}\mathbb{E}(G_\mu(t)) &= \mu t,\nonumber\\[3pt]\operatorname{Var}(G_\mu(t)) &= \mu t(1+\mu t), \\[3pt]\operatorname{Cov}[G_\mu(t),G_\mu(s)]&= \mu s(1+\mu t)\nonumber.\end{align}
Next, we establish the fractional moments and joint fractional moments of the GCP, which are used later.
Proposition 1. The fractional moment of order
 $\beta \in (0,1)$
is given by
 \begin{align}\mathbb{E}[G_\mu(t)^\beta]= \dfrac{1}{1+\mu t} \, \operatorname{Li}_{-\beta} \biggl(\dfrac{\mu t}{1+\mu t}\biggr),\end{align}
where
 $\operatorname{Li}_{-\beta}(\! \cdot \!)$
denotes the polylogarithm function of order
 $(-\beta)$
, defined by
 \begin{align}\operatorname{Li}_{-\beta}\!(z) = \sum_{n=1}^{\infty} n^\beta z^n, \quad |z| \lt 1.\end{align}
Proof. By definition, the fractional moment is given by
 \begin{align*}\mathbb{E}[G_\mu(t)^\beta]= \sum_{n=0}^{\infty} n^\beta \, \mathbb{P}(G_\mu(t)=n). \end{align*}
Substituting the probability mass function (PMF) from (3), we obtain
 \begin{align*}\mathbb{E}[G_\mu(t)^\beta]= \dfrac{1}{1+\mu t} \sum_{n=0}^{\infty} n^\beta \biggl(\dfrac{\mu t}{1+\mu t}\biggr)^n. \end{align*}
Since
 $0 \lt \beta \lt 1$
, the term corresponding to
 $n=0$
vanishes. Therefore
 \begin{align*}\mathbb{E}[G_\mu(t)^\beta]= \dfrac{1}{1+\mu t} \sum_{n=1}^{\infty} n^\beta \biggl(\dfrac{\mu t}{1+\mu t}\biggr)^n. \end{align*}
Using the polylogarithm function
 \begin{align*}\operatorname{Li}_{-\beta}(z) = \sum_{n=1}^{\infty} n^\beta z^n, \quad |z|\lt1, \end{align*}
and noting that
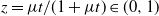 $z={{\mu t}/{(1+\mu t)}} \in (0,1)$
, we obtain
 \begin{align*}\mathbb{E}\big[G_\mu(t)^\beta\big]= \dfrac{1}{1+\mu t} \, \operatorname{Li}_{-\beta} \biggl(\dfrac{\mu t}{1+\mu t}\biggr). \end{align*}
This completes the proof.
Here we derive the expression of the joint fractional moment.
Proposition 2. For
 $s \lt0 \leq t$
, the joint fractional moment of order
 $\beta_{1}$
,
 $\beta_{2} \gt 0$
is given by
 \begin{align*} \mathbb{E}\bigl[G_{\mu}(s)^{\beta_{1}} G_{\mu}(t)^{\beta_{2}}\bigr] = \dfrac{1}{1 + \mu t }\sum_{m=0}^{\infty} \sum_{n= 0}^{\infty} m^{\beta_{1}} (m+n)^{\beta_{2}} \biggl(\dfrac{\mu s}{\mu t + 1}\biggr)^{m} \biggl(\dfrac{\mu (t-s)}{\mu t + 1}\biggr)^{n} \dfrac{(m+n)!}{m! n!}. \end{align*}
Proof. Consider
 \begin{align} \mathbb{E}\big[G_{\mu}(s)^{\beta_{1}} G_{\mu}(t)^{\beta_{2}}\big] &= \mathbb{E}\big[\mathbb{E}\big[G_{\mu}(s)^{\beta_{1}} G_{\mu}(t)^{\beta_{2}}\mid \lambda\big]\big] \nonumber \\[3pt] &= \int_{0}^{\infty} \mathbb{E}\big[G_{\mu}(s)^{\beta_{1}} G_{\mu}(t)^{\beta_{2}}\mid \lambda\big] \,{\mathrm{d}} U_{\mu}(\lambda). \end{align}
Note that
 \begin{align*} \mathbb{E}\big[G_{\mu}(s)^{\beta_{1}} G_{\mu}(t)^{\beta_{2}}\mid \lambda\big] &= \sum_{m=0}^{\infty} \sum_{n= 0}^{\infty} m^{\beta_{1}} n^{\beta_{2}} \mathbb{P}[G_{\mu}(s) = m, G_{\mu}(t) = n\mid \lambda]. \end{align*}
From the definition of the geometric counting process, given the value of mixing distribution
 $U_{\mu} = \lambda$
, the process is a Poisson process with intensity
 $\lambda$
. Since a Poisson process possesses an independent and stationary increment property, a geometric counting process follows a conditional independent increment property. Using that, we can write the above equation as
 \begin{align*} \mathbb{E}\big[G_{\mu}(s)^{\beta_{1}} G_{\mu}(t)^{\beta_{2}}\mid \lambda\big] &= \sum_{m=0}^{\infty} \sum_{n= 0}^{\infty} m^{\beta_{1}} (m+n)^{\beta_{2}} \mathbb{P}[G_{\mu}(s) = m\mid \lambda] \mathbb{P}[G_{\mu}(t-s) = n\mid \lambda] \\[3pt] &= {\mathrm{e}}^{- \lambda t} \sum_{m=0}^{\infty} \sum_{n= 0}^{\infty} m^{\beta_{1}} (m+n)^{\beta_{2}} \dfrac{(\lambda s)^{m}}{m!} \dfrac{(\lambda (t-s))^{n}}{n!}. \\[-20pt] \end{align*}
From (8) and the fact that
 $U_{\mu}$
has exponential distribution with mean
 $\mu$
, we get
 \begin{align*} \mathbb{E}\big[G_{\mu}(s)^{\beta_{1}} G_{\mu}(t)^{\beta_{2}}\big] &= \sum_{m=0}^{\infty} \sum_{n= 0}^{\infty} m^{\beta_{1}} (m+n)^{\beta_{2}} \dfrac{( s)^{m}}{m!} \dfrac{( (t-s))^{n}}{n!} \int_{0}^{\infty} {\mathrm{e}}^{- \lambda t} \lambda^{m+n} \,{\mathrm{d}} U_{\mu}(\lambda) \\[3pt] &= \dfrac{1}{1 + \mu t }\sum_{m=0}^{\infty} \sum_{n= 0}^{\infty} m^{\beta_{1}} (m+n)^{\beta_{2}} \biggl(\dfrac{\mu s}{\mu t + 1}\biggr)^{m} \biggl(\dfrac{\mu (t-s)}{\mu t + 1}\biggr)^{n} \dfrac{(m+n)!}{m! n!}. \end{align*}
This completes the proof.
2.3. Time-changed Poisson process with Lévy subordinator (TCPP-I)
The process
 $\{N^{\, f}_{1}(t)\}_{ t \gt 0}$
, can be viewed as subordinated Poisson processes where
 $\{D^{\,f}(t)\}_{t \gt 0}$
are Lévy subordinators associated with the Bernstein function f and independent of the homogeneous Poisson process
 $\{N(t)\}_{t \gt 0}$
with parameter
 $\lambda \gt 0$
(see [Reference Orsingher and Toaldo33]).
The LT of
 $N_1^f(t)=N(D^{\,f}(t))$
is given by
 \begin{align*}\mathbb{E}\bigl[{\mathrm{e}}^{-uN_1^f(t)}\bigr]= {\mathrm{e}}^{-tf(\lambda(1-{\mathrm{e}}^{-u}))}, \quad \mathrm{Re}(u) \geq 0. \end{align*}
The mean, variance, and covariance functions of the TCPP-I are given by
 \begin{equation}\begin{aligned}\mathbb{E}\bigl[N_1^f(t)\bigr]&=\lambda \mathbb{E}[D^{\,f}(t)],\\[3pt] \operatorname{Var}\bigl(N_1^f(t)\bigr)&=\lambda^2 \operatorname{Var}[D^{\,f}(t)]+\lambda \mathbb{E}[D^{\,f}(t)].\end{aligned}\end{equation}
Let
 ${N_1^f(t)}_{t \ge 0}$
denote the Poisson process subordinated by an independent Lévy subordinator, as studied by Orsingher and Toaldo [Reference Orsingher and Toaldo33].
The PMF
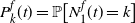 $P^{ f}_k(t)=\mathbb{P}\bigl[N_1^f(t)=k\bigr]$
of
 $N_1^{f}(t)$
is given by
 \begin{align}P^{f}_k(t)=\dfrac{(\!-1)^k}{k!}\dfrac{{\mathrm{d}}^k}{{\mathrm{d}} u^k}{\mathrm{e}}^{-tf(\lambda u)}\bigg|_{(u=1)}, \quad k \geq 0.\end{align}
The well-known processes such as the space-fractional (SFPP)
 $\{N_1^{\alpha}(t)\}_{t\geq 0}$
and the tempered space-fractional Poisson processes
 $\{N_1^{\alpha, \nu}(t)\}_{t\geq 0}$
(TSFPP) are obtained with time change in the Poisson process with independent
 $\alpha$
-stable subordinator and tempered
 $\alpha$
-stable subordinator, respectively.
The PMF of
 $N_1^{\alpha}(t)$
is given by (see [Reference Orsingher and Polito32])
 \begin{align}\mathbb{P}\big[N_1^{\alpha}(t)=k\big]=\dfrac{(\!-1)^k}{k!}\sum_{r=0}^{\infty}\dfrac{(-\lambda^\alpha t)^r}{r!}\dfrac{\Gamma(\alpha r+1)}{\Gamma(\alpha r+1-k)}.\end{align}
The mean, variance, and covariance [Reference Orsingher and Toaldo33] of the TSFPP are given by
 \begin{align}\mathbb{E}\bigl(N_1^{\alpha,\nu}(t)\bigr) &= \lambda \alpha \nu^{\alpha-1}t,\nonumber\\[3pt]\operatorname{Var}\bigl(N_1^{\alpha,\nu}(t)\bigr) &= \mathbb{E}(\lambda D_{\alpha,\mu}(t)) + \operatorname{Var}(\lambda D_{\alpha,\mu}(t)) = \lambda \alpha \nu^{\alpha-1}t + \lambda^2 \alpha(1-\alpha) \nu^{\alpha-2}t,\! \\[3pt]\operatorname{Cov}\bigl[N_1^{\alpha,\nu}(t),N_1^{\alpha,\nu}(s)\bigr] & = \lambda \alpha \nu^{\alpha-1}t + \lambda^2 \alpha(1-\alpha) \nu^{\alpha-2}s\nonumber.\end{align}
2.4. Time-changed Poisson process with inverse Lévy subordinator (TCPP-II)
Let
 $\{D^{f}(t)\}_{t\geq 0}$
be a Lévy subordinator associated with the Bernstein function f, and let
 \begin{align*}E^{f}(t)=\inf\{ r\geq 0 \colon D^{f}(r)\gt t \}, \quad t\geq 0, \end{align*}
denote its inverse (first-exit time) process. Assume that
 $\{E^{f}(t)\}_{t\geq 0}$
is independent of the homogeneous Poisson process
 $\{N(t)\}_{t\geq 0}$
with rate
 $\lambda\gt 0$
.
The time-changed Poisson process
 \begin{align*}N^{\, f}_{2}(t)=\{N(E^{f}(t))\}_{t\geq 0} \end{align*}
is referred to as a Poisson process governed by the inverse Lévy subordinator
 $\{E^{f}(t)\}_{t\geq 0}$
(see [Reference Maheshwari and Vellaisamy27]).
The Laplace transform of
 $N_2^{\, f}(t))$
is given by
 \begin{align*} \mathbb{E} \bigl[{\mathrm{e}}^{-uN_2^{\, f}(t))}\bigr]=\sum_{n=0}^{\infty}\dfrac{(-\lambda (1-{\mathrm{e}}^{-u}))^n}{n!}\mathbb{E}[(E^f(t))^n],\quad \mathrm{Re}(u)\geq 0.\end{align*}
The mean and variance of the process
 $\bigl\{N_2^{\, f}(t)\bigr\}_{t\geq 0}$
are given by (see [Reference Leonenko, Meerschaert and Sikorskii25])
 \begin{equation}\begin{aligned}\mathbb{E}\bigl[N_2^{\, f}(t)\bigr]&= \lambda\,\mathbb{E}\bigl[E^{f}(t)\bigr], \\[3pt]\operatorname{Var}(N(E^{f}(t)))&= \lambda\,\mathbb{E}[E^{f}(t)]+ \lambda^{2}\,\operatorname{Var}(E^{f}(t)).\end{aligned}\end{equation}
Moreover, for
 $0 \lt s \lt t$
, the covariance function satisfies
 \begin{equation*} \operatorname{Cov}\bigl[N_2^{\, f}(t),N_2^{\, f}(s)\bigr]=\lambda\,\mathbb{E}[E^{f}(s)]+\lambda^{2}\,\operatorname{Cov}(E^{f}(t),E^{f}(s)).\end{equation*}
The PMF
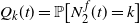 $Q_k(t)=\mathbb{P}\bigl[N_2^{\, f}(t)=k\bigr]$
is given by (see [Reference Maheshwari and Vellaisamy27])
 \begin{align}\mathbb{P}\bigl[N_\mu^f(t) = k\bigr]= \dfrac{\lambda^k}{k!} \sum_{n=0}^{\infty} \dfrac{(-\lambda)^n}{n!}\mathbb{E}[ (E^f(t))^{k+n} ], \quad k \ge 0.\end{align}
Furthermore, the time-fractional Poisson process (TFPP)
 $\{N_{2}^{\alpha}(t)\}_{t \ge 0}$
arises by time-changing a classical Poisson process
 $\{N(t)\}_{t \geq 0}$
through an inverse
 $\alpha$
-stable subordinator
 $\{E_{\alpha}(t)\}_{t \geq 0}$
.
The LT of the TFPP
 $N_2^{\alpha}(t)$
is given by (see [Reference Laskin22], [Reference Meerschaert, Nane and Vellaisamy28])
 \begin{equation}\mathbb{E} \bigl[{\mathrm{e}}^{-u N_2^{\alpha}(t)}\bigr]=M_{\alpha}(-\lambda(1-{\mathrm{e}}^{-u})t^{\alpha}),\quad \mathrm{Re}(u)\ge0,\end{equation}
where
 $M_{\alpha,\beta}(z)$
denotes the one-parameter Mittag–Leffler function defined by (see [Reference Kilbas, Saigo and Saxena21])
 \begin{equation*}M_{\alpha}(z)=\sum_{k=0}^{\infty}\dfrac{z^k}{\Gamma(\alpha k+1)},\quad \mathrm{Re}(\alpha)\gt 0.\end{equation*}
In particular,
 $M_{\alpha}(z)=M_{\alpha,1}(z)$
. The PMF of the TFPP is given by (see [Reference Laskin23], [Reference Meerschaert, Nane and Vellaisamy28])
 \begin{equation}\mathbb{P}\bigl(N_{2}^{\alpha}(t)=k\bigr)=\dfrac{(\lambda t^{\alpha})^{k}}{k!}\sum_{n=0}^{\infty}\dfrac{(-\lambda t^{\alpha})^{n}}{\Gamma(\alpha(n+k)+1)},\quad k \ge 0.\end{equation}
The mean, variance, and covariance [Reference Laskin23, Reference Leonenko, Meerschaert and Sikorskii25] of the TFPP are given by
 \begin{align}\mathbb{E}\big(N_2^{\alpha}(t)\big) &= \dfrac{\lambda t^{\alpha}}{\Gamma(\alpha+1)}, \nonumber\\[3pt]\operatorname{Var}\big(N_2^{\alpha}(t)\big) &= \dfrac{\lambda t^{\alpha}}{\Gamma(\alpha+1)}+\dfrac{\lambda^2 t^{2\alpha}}{\Gamma(2\alpha+1)}-\dfrac{\lambda^2 t^{2\alpha}}{\Gamma(\alpha+1)^2}, \\[3pt]\operatorname{Cov}(N_2^{\alpha}(t),N_2^{\alpha}(s))&=\dfrac{\lambda s^{\alpha}}{\Gamma(\alpha+1)}+\dfrac{\lambda^2}{\Gamma(2\alpha+1)}(t^{2\alpha}+s^{2\alpha}-(t-s)^{2\alpha})-\dfrac{\lambda^2 t^{\alpha}s^{\alpha}}{\Gamma(\alpha+1)^2}\nonumber, \quad s \lt t.\end{align}
3. Geometric time-changed fractional Poisson process I
In this section we study the generalized TCPP-I under an independent geometric time change and explore its distributional properties. We also examine several special cases of the resulting process. Our framework is general and includes subordinators for which the moments may exist or may not exist. For example, the stable subordinator, which leads to the SFPP, does not have finite moments, whereas the tempered stable subordinator, which leads to the TSFPP, has finite moments. Thus our formulation covers both types of processes.
Definition 1. We define the geometric TCPP-I (GTCPP-I) by time-changing the TCPP-I
 $\{N_1^f(t)\}_{t \geq 0}$
with an independent GCP
 $\{G_\mu(t)\}_{t \geq 0}$
, such that
 \begin{align}N_1^{f,\mu}(t)\, :\!= \, N_1^f(G_\mu(t)), \quad t \geq 0.\end{align}
The LT of
 $N_1^{f,\mu}(t)$
is given by
 \begin{align}\mathbb{E}\bigl[{\mathrm{e}}^{-uN_1^{f,\mu}(t)}\bigr]=\mathbb{E}\bigl[\mathbb{E}\bigl[{\mathrm{e}}^{-uN_1^{f,\mu}(t)}\mid G_\mu(t)\bigr]\bigr] =\dfrac{1}{1+\mu t (1-{\mathrm{e}}^{-f(\lambda (1-{\mathrm{e}}^{-u}))})}.\end{align}
Proposition 3. The PMF
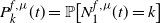 $P^{ f, \mu}_k(t)=\mathbb{P}\bigl[N_1^{f,\mu}(t)=k\bigr]$
of the GTCPP-I is given by
 \begin{align*} P^{f, \mu}_k(t)=\dfrac{(\!-1)^k}{k!}\dfrac{{\mathrm{d}}^k}{{\mathrm{d}} u^k}\biggl(\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-f(\lambda u)})}\biggr)_{u=1}. \end{align*}
Proof. By using conditional arguments, we have
 \begin{align} P^{f, \mu}_k(t) &=\mathbb{E}\bigl[\mathbb{P}\bigl[N_1^{f,\mu}(t)=k\mid G_{\mu}(t)\bigr]\bigr] \quad \text{({substituting the PMF of the} TCPP-I (10))} \nonumber \\[3pt] &= \sum_{n=0}^{\infty}\dfrac{1}{1+\mu t}\dfrac{(\!-1)^k}{k!}\dfrac{{\mathrm{d}}^k}{{\mathrm{d}} u^k}{\mathrm{e}}^{-nf(\lambda u)}|_{(u=1)}\biggl(\dfrac{\mu t}{1+\mu t}\biggr)^n \nonumber\\[3pt] &= \dfrac{1}{1+\mu t}\dfrac{(\!-1)^k}{k!}\dfrac{{\mathrm{d}}^k}{{\mathrm{d}} u^k}\Biggl(\sum_{n=0}^{\infty}\biggl(\dfrac{{\mathrm{e}}^{-f(\lambda u)} \mu t}{1+\mu t}\biggr)^n\Biggr)_{u=1}. \end{align}
By applying the geometric series formula and canceling some terms, we obtain the PMF.
Proposition 4. Let
 ${N_1^{f,\mu}(t)}_{t\geq 0}$
be the GTCPP-I, as defined in (18). We have the following distributional equality in the compound form
 \begin{align*} N_1^{f,\mu}(t) \stackrel{d}{\, :\!= \, } \sum_{i=1}^{G_\mu(t)}Y_i, \quad t \geq 0, \end{align*}
where the
 $Y_i$
are random variables TCPP-I that are i.i.d.
 $N_1^{f}(1)$
, which are independent of
 $G_{\mu}(t)$
.
Proof. The LT of the probability density function (PDF) of
 $\sum_{i=1}^{G_\mu(t)}Y_i$
is
 \begin{align*}\mathbb{E}\bigl[{\mathrm{e}}^{-u\sum_{i=1}^{G_\mu(t)}Y_i}\bigr] = \dfrac{1}{1+\mu t\big(1-M_{N_1^f(1)}(-u)\big)}= \dfrac{1}{1+\mu t (1-{\mathrm{e}}^{-f(\lambda (1-{\mathrm{e}}^{-u})))})}. \end{align*}
Comparing the above equation with the LT (19) of
 $\bigl\{N_1^{f,\mu}(t)\bigr\}_{t\geq 0}$
, we get the desired result.
The following moment results hold for subordinators whose moments are finite, such as the tempered stable subordinator, mixtures of tempered stable subordinators, the gamma subordinator, and the inverse Gaussian subordinator.
Here we consider such a TCPP-I for which the moments are finite, that is,
 \begin{align*}\mathbb{E}\bigl[\bigl(N_1^{f}(t)\bigr)^r\bigr]\lt\infty \quad \text{for all $r \gt 0$.} \end{align*}
In addition, we discuss some distributional properties of the process.
Theorem 1. The mean, variance, and covariance are given by
 \begin{align*} \mathbb{E}\bigl[N_1^{f,\mu}(t)\bigr] &=\lambda \mu t\mathbb{E}[D^{f}(1)],\\[3pt]\operatorname{Var}\bigl[N_1^{f,\mu}(t)\bigr]& =\lambda \mu t (\lambda\mathbb{E}[{D^{\,f}(1)}^2]+\mathbb{E}[D^{\,f}(1)])+ \mu^2 \lambda^2 t^2\mathbb{E}[D^{\,f}(1)]^2, \\[3pt]\operatorname{Cov}\bigl[N_1^{f,\mu}(t),N_1^{f,\mu}(s)\bigr] & = \lambda \mu s (\lambda\mathbb{E}[{D^{\,f}(1)}^2]+\mathbb{E}[D^{\,f}(1)])+ \mu^2 \lambda^2 s t\mathbb{E}[D^{\,f}(1)]^2, \quad 0 \lt s \lt t.\end{align*}
Proof. Using Proposition 4, we have
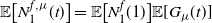 $\mathbb{E}\bigl[N_1^{f,\mu}(t)\bigr]= \mathbb{E}\bigl[N_1^f(1)\bigr]\mathbb{E}[G_\mu(t)]$
. The variance of
 $\bigl\{N_1^{f,\mu}(t)\bigr\}_{t \geq 0}$
can be written as (see [Reference Leonenko, Meerschaert, Schilling and Sikorskii24])
 \begin{align*}\operatorname{Var}\bigl[N_1^{f,\mu}(t)\bigr] = \operatorname{Var}\bigl[N_1^{f,\mu}(t)\bigr]\mathbb{E}[G_{\mu}(t)]+\mathbb{E}\bigl[N_1^f(1)\bigr]^2\operatorname{Var}[G_{\mu}(t)]. \end{align*}
Next, we compute the
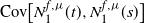 $\operatorname{Cov}\bigl[N_1^{f,\mu}(t),N_1^{f,\mu}(s)\bigr]$
by using Proposition 4,
 $s\leq t$
,
 \begin{align*}\operatorname{Cov}\bigl[N_1^{f,\mu}(t),N_1^{f,\mu}(s)\bigr] &= \mathbb{E}\Biggl[\sum_{k=1}^{\infty}Y_k^2 \mathbf{1}_{\{G_{\mu}(s)\geq k\}}\Biggr]+\mathbb{E}\Biggl[ \sum_{i\neq j}\sum Y_i Y_k \mathbf{1}_{\{G_\mu(s)\geq k, G_\mu(t)\geq i\}}\Biggr] \\[3pt]&\quad - (\mathbb{E}[Y_1])^2\mathbb{E}[G_\mu(s)]\mathbb{E}[G_\mu(t)] \\[3pt]&= \mathbb{E}[Y_1^2]\sum_{k=1}^{\infty}\mathbb{P}(G_{\mu}(s)\geq k) \\[3pt]& \quad + (\mathbb{E}[Y_1])^2\Biggl[\sum_{i=1}^{\infty}\sum_{k=1}^{\infty}\mathbb{P}(G_{\mu}(s)\geq k, G_\mu(t)\geq i)-\mathbb{P}(G_\mu(s)\geq k)\Biggr] \\[3pt]& \quad - (\mathbb{E}[Y_1])^2\mathbb{E}[G_\mu(s)]\mathbb{E}[G_\mu(t)]\\[3pt]&= \mathbb{E}\big[Y_1^2\big] \mathbb{E}[G_\mu(s)]+(\mathbb{E}[Y_1])^2\mathbb{E}[G_\mu(s) G_\mu(t)] -(\mathbb{E}[Y_1])^2\mathbb{E}[G_\mu(s)] \\[3pt]&\quad - (\mathbb{E}[Y_1])^2\mathbb{E}[G_\mu(s)]\mathbb{E}[G_\mu(t)]\\[3pt]&= \operatorname{Var}[Y_1]\mathbb{E}[G_\mu(s)]+(\mathbb{E}[Y_1])^2\operatorname{Cov}[G_\mu(t),G_\mu(s)].\end{align*}
where the
 $Y_i$
are TCPP-I distributed
 $N_1^f(1)$
. Substituting (9) and (5) in the above equation, we get the desired result.
Next, we explore special cases of the TCPP-I, including the SFPP, for which the moments do not exist, and the TSFPP, for which all moments exist, and discuss their distributional properties.
Example 1. (Geometric space fractional Poisson process.) Let
 $\bigl\{N_1^{\alpha,\mu}(t)\bigr\}$
. The time-changed space-fractional Poisson process with GCP is defined by time-changing the SFPP
 $\{N_1^{\alpha}(t)\}_{t \geq 0}$
by an independent GCP, that is,
 \begin{align*}{N_1^{\alpha,\mu}(t)=N^\alpha(G_{\mu}(t)),\quad t \geq 0.} \end{align*}
The LT of
 $N_1^{\alpha,\mu}(t)$
is given by
 \begin{align*} \mathbb{E}\bigl[{\mathrm{e}}^{-uN_1^{\alpha,\mu}(t)}\bigr]=\mathbb{E}\bigl[\mathbb{E}\bigl[{\mathrm{e}}^{-uN_1^{\alpha,\mu}(t)}\mid G_\mu(t)\bigr]\bigr] =\dfrac{1}{1+\mu t (1-{\mathrm{e}}^{-\lambda^\alpha (1-{\mathrm{e}}^{-u})^\alpha})}.\end{align*}
Proposition 5. The PMF
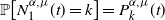 $\mathbb{P}\bigl[N_1^{\alpha,\mu}(t)=k\bigr]=P^{\alpha, \mu}_k(t)$
of
 $N_1^{\alpha,\mu}(t)$
for any
 $k \in \mathbb{N}_{0}$
is given by
 \begin{align*} P^{\alpha, \mu}_k(t) = \sum_{r=0}^\infty {\binom {\alpha r }{k}} \dfrac{(-\lambda^\alpha)^r (\!-1)^k }{r!}w_r(\mu t),\quad \lambda\gt 0, \ \mu \gt 0,\ t \geq 0, \end{align*}
where
 $w_{r}(\! \cdot \!)$
is the geometric polynomial of degree r.
Proof. By using conditional arguments and the PMF of the SFPP, we have
 \begin{align*} P^{\alpha, \mu}_k(t) &= \mathbb{E}\bigl[\mathbb{P}\bigl[N_1^{\alpha,\mu}(t)=k\mid G_{\mu}(t)\bigr]\bigr] \quad \text{(substituting the {PMF of the} SFPP from (11)}) \\[3pt] &= \dfrac{1}{1+\mu t}\sum_{r=0}^\infty {\binom {\alpha r }{k}} \dfrac{(-\lambda^\alpha)^r (\!-1)^k }{r!}\sum_{m=0}^\infty m^r \biggl(\dfrac{\mu t}{1+\mu t}\biggr)^m. \end{align*}
We use the geometric-like series property (see [Reference Meoli29])
 \begin{align*} \sum_{k=0}^\infty k^n y^k=\dfrac{1}{1-y}w_n\biggl(\dfrac{y}{1-y}\biggr),\quad |y| \leq 1,\ n \in \mathbb{N}\cup\{0\}. \end{align*}
Using the above result for
 $y={{\mu t}/{(1+\mu t)}}$
, which is less than 1, and rearranging the terms completes the proof.
We study the distribution of the first-passage time of the SFPP at geometric times at level k:
 \begin{align*} T_k=\inf\{s\colon N^{\alpha}(s)=k \},\quad k \in \mathbb{N}. \end{align*}
Proposition 6. The distribution of the stopping time through an arbitrary level
 $k \in \mathbb{N}$
for the process
 $N_1^{\alpha,\mu}(s)$
reads, for
 $s \gt 0$
,
 \begin{align*}\mathbb{P}[T_k \in {\mathrm{d}} s]={\mathrm{d}} s\sum_{j=0}^{k-1}\sum_{r=0}^{\infty}{\binom {\alpha r }{j}}\dfrac{(-\lambda^\alpha)^r(\!-1)^{j+1}}{r!}\sum_{i=0}^{r}{\binom {r}{i}} \mu^i(i+1)!s^{i-1}. \end{align*}
Proof. That is,
 \begin{align*} \dfrac{\mathbb{P}[T_k \in {\mathrm{d}} s]}{{\mathrm{d}} s}=\dfrac{{\mathrm{d}}}{{\mathrm{d}} s}\mathbb{P}\bigl[N_1^{\alpha,\mu}(s) \geq k\bigr]= \dfrac{{\mathrm{d}}}{{\mathrm{d}} s}\Biggl[1-\sum_{j=0}^{k-1}\mathbb{P}\bigl[N_1^{\alpha,\mu}(s) = j\bigr]\Biggr], \end{align*}
substituting Proposition 5, which completes the proof.
Remark 1. Let
 $f(s)= s$
. The process
 $\bigl\{N_1^{f,\mu}(t)\bigr\}_{t\geq0}$
reduces to
 $N^{\mu}(t)=N(G_\mu(t))$
(see [Reference Meoli29]). The asymptotic behavior of the correlation of the process
 $N^{\mu}(t)$
and
 $N^{\mu}(s)$
for large time
 $t\geq 0$
is given by
 \begin{align*} \lim_{t\to\infty}\dfrac{\operatorname{Corr}[N^{\mu}(t), N^{\mu}(s)]}{t^{-1}} \sim \dfrac{s(1+\lambda)}{(\lambda \mu)^{1/2}\sqrt{s(1+\lambda+\lambda \mu s)}}. \\[-10pt] \end{align*}
Example 2. (Geometric tempered space fractional Poisson process.) The TSFPP
 $\{N^{\alpha,\nu}(t)\}_{t \geq 0}$
time-changed by an independent GCP is defined as
 \begin{align*}N_1^{\alpha,\nu,\mu}(t)=N^{\alpha,\nu}(G_\mu(t)),\quad t \geq 0. \end{align*}
Here we discuss their distributional properties in detail.
Proposition 7. The PMF
 $P^{\alpha, \nu,\mu}_{k}(t) = \mathbb{P}\bigl[N_{1}^{\alpha,\nu,\mu}(t)=k\bigr] $
is given by
 \begin{align*} P^{\alpha, \nu,\mu}_k(t)=\sum_{m=0}^{\infty} \sum_{r=0}^\infty \nu^m \lambda^{\alpha r-m}{\binom {\alpha r }{m}}{\binom {\alpha r -m}{k}} \dfrac{ (\!-1)^k }{r!}\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{\nu ^\alpha})}w_r\biggl(\dfrac{{\mathrm{e}}^{\nu^\alpha}\mu t}{1+\mu t(1-{\mathrm{e}}^{\nu ^\alpha})}\biggr), \end{align*}
where
 $|{\mathrm{e}}^{\nu^\alpha} \mu t| \lt 1 + \mu t$
. For
 $\nu = 0$
, this reduces to the PMF
 $P^{\alpha, \mu}_{k}(t)$
of the geometric space-fractional Poisson process
 $N_1^{\alpha,\mu}(t)$
.
Proof. This follows a similar step to Proposition 5.
Proposition 8. The mean, variance, and covariance of
 $N_1^{\alpha,\nu,\mu}(t)$
are given by
 \begin{align*} \mathbb{E}\bigl[N_1^{\alpha,\nu,\mu}(t)\bigr] &=\lambda \alpha \nu^{\alpha-1}\mu t , \\[3pt]\operatorname{Var}\bigl[N_1^{\alpha,\nu,\mu}(t)\bigr] &= \lambda \alpha \nu^{\alpha-1}\mu t + \lambda^2 \alpha(1-\alpha) \nu^{\alpha-2}\mu t+\lambda^2 \alpha^2\nu^{2(\alpha-1)}\mu t(1+\mu t) , \\[3pt]\operatorname{Cov}\bigl[N_1^{\alpha,\nu,\mu}(t),N_1^{\alpha,\nu,\mu}(s)\bigr] & = \alpha \lambda \nu^{\alpha-2}(\lambda(1-\alpha)+\nu)\mu s+\alpha^2\lambda^2\nu^{2(\alpha-1)}(\mu s+2 \mu^2 st).\end{align*}
Corollary 1. The asymptotic behavior of the correlation of the processes
 $N_1^{\alpha,\nu,\mu}(t)$
and
 $N_1^{\alpha,\nu,\mu}(s)$
is given by
 \begin{align*} \lim_{t\to\infty}\dfrac{\operatorname{Corr}\bigl[N^{\alpha,\nu}_{\mu}(t), N^{\alpha,\nu}_{\mu}(s)\bigr]}{t^{-1}} \sim \dfrac{s(1+\nu^{-1} \lambda(1-\alpha)+\alpha \lambda \nu^{\alpha-1}s)}{(\lambda \alpha \mu)^{1/2}\sqrt{ \nu^{\alpha-1} s + \lambda (1-\alpha) \nu^{\alpha-2} t+\lambda\alpha\nu^{2(\alpha-1)}s(1+\mu s)}}. \end{align*}
The index of dispersion for a counting process Z(t) is defined by (see [Reference Cox and Lewis9])
 \begin{align*} I(t)=\dfrac{\operatorname{Var}(X (t))}{\mathbb{E}[X(t)]}. \end{align*}
The stochastic process X(t) is said to be overdispersed if
 $I(t) \gt 1$
for all (see [Reference Beghin and Macci2]). From Proposition 8, the index of dispersion is greater than 1 for all
 $t \geq 0$
, such that
 \begin{align*} I(t)=\dfrac{\operatorname{Var}\bigl(N_1^{\alpha,\nu,\mu}(t)\bigr)}{\mathbb{E}\bigl[N_1^{\alpha,\nu,\mu}(t)\bigr]}=1+\lambda(1-\alpha)\nu^{-1}+\lambda \alpha \nu^{\alpha-1}(1+\mu t)\gt 1{.} \end{align*}
This process exhibits overdispersion.
4. Geometric time-changed fractional Poisson process II
In this section we consider the generalized TCPP-II process, modified by an independent geometric time change, and analyze its distributional properties. One special case of the resulting process is also investigated.
Definition 2. We define the geometric TCPP-II (GTCPP-II) by time-changing the TCPP-II
 $\bigl\{N^{\, f}_2(t)\bigr\}_{t \geq 0}$
with an independent GCP
 $\{G_\mu(t)\}_{t \geq 0}$
, such that
 \begin{align*} N^{f, \mu}_{2}(t)\, :\!= \, N_2^f(G_\mu(t)), \quad t \geq 0.\end{align*}
The Laplace transform of
 $N_2^{f, \mu}(t)$
is given by
 \begin{align*} \mathbb{E} \bigl[{\mathrm{e}}^{-uN_2^{f, \mu}(t))}\bigr] & =\mathbb{E}\bigl[\mathbb{E}\bigl[{\mathrm{e}}^{-uN^{f, \mu}_{2}(t)}\mid G_\mu(t)\bigr]\bigr]\\[3pt]&=\sum_{n=0}^{\infty}\dfrac{(-\lambda (1-{\mathrm{e}}^{-u}))^n}{n!}\mathbb{E}[(E^f(G_{\mu}(t))^n],\quad \mathrm{Re}(u)\geq 0.\end{align*}
Theorem 2. The mean, variance, and covariance of the process
 $\{N_2^{f, \mu}(t)\}_{t \geq 0}$
are given by
 \begin{align*}\mathbb{E}\bigl[N_2^{f, \mu}(t)\bigr] &= \lambda \mathbb{E}[E^{f}(G_{\mu}(t))], \\[3pt]\operatorname{Var}\bigl(N_2^{f, \mu}(t)\bigr) & = \lambda\,\mathbb{E}[E^{f}(G_{\mu}(t))] + \lambda^{2}\,\operatorname{Var}(E^{f}(G_{\mu}(t))),\\[3pt]\operatorname{Cov}\bigl[N_2^{f, \mu}(t),N_2^{f, \mu}(s)\bigr] & = \lambda\,\mathbb{E}\big[E^{f}(G_{\mu}(s))\big]+\lambda^{2}\,\operatorname{Cov}\big(E^{f}(G_\mu(t)\big),E^{f}(G_{\mu}(s)\big).\end{align*}
Proof. Recall that the process
 $N_2^{f,\mu}(t)$
can be represented as the Poisson process changed in time
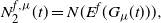 $N_2^{f,\mu}(t) = N (E^{f}(G_\mu(t))),$
where
 $\{N(t)\}_{t\ge 0}$
is a Poisson process with rate
 $\lambda$
, independent of the random in time
 $E^{f}(G_\mu(t))$
.
Using the tower property of conditional expectation, we have
 \begin{align*}\mathbb{E}\bigl[N_2^{f,\mu}(t)\bigr]=\mathbb{E} [\mathbb{E} (N(E^{f}(G_\mu(t))) \mid E^{f}(G_\mu(t)))]=\lambda \mathbb{E}[E^{f}(G_{\mu}(t))] . \end{align*}
Using the law of total variance,
 \begin{align*}\operatorname{Var}(X)=\mathbb{E}[\textrm{Var}(N(E^{f}(G_\mu(t)))\mid E^{f}(G_\mu(t)))]+\operatorname{Var}(\mathbb{E}[N(E^{f}(G_\mu(t)))\mid E^{f}(G_\mu(t))]). \end{align*}
Thus
 \begin{align*}{\operatorname{Var}\bigl(N_2^{f, \mu}(t)\bigr)= \lambda\,\mathbb{E}\big[E^{f}(G_{\mu}(t))\big]+ \lambda^{2}\,\operatorname{Var}(E^{f}(G_{\mu}(t))).} \end{align*}
Next we compute the correlation using [Reference Leonenko, Meerschaert and Sikorskii25]. For
 $s \lt t$
, we have
 \begin{align*}\operatorname{Cov}\bigl(\bigl(N_2^{f, \mu}\bigr),N_2^{f, \mu}(s)\bigr)=\lambda\,\mathbb{E}\big[E^{f}(G_\mu(s))\big]+\lambda^2\,\operatorname{Cov}\big(E^{f}(G_\mu(t)\big),E^{f}(G_\mu(s))). \end{align*}
This completes the proof.
Proposition 9. The PMF
 $R^{ f, \mu}_{k}(t)=\mathbb{P}\bigl[N^{f, \mu}_{2}(t)=k\bigr]$
of
 $\bigl\{N^{f,\mu}_{2}(t)\bigr\}_{t \geq 0}$
is given by
 \begin{align*} \mathbb{P}\bigl[N_2^{f, \mu}(t) = k\bigr]= \dfrac{\lambda^k}{k!} \sum_{n=0}^{\infty} \dfrac{(-\lambda)^n}{n!}\mathbb{E}\bigl[ E^f(G_{\mu}(t))^{k+n} \bigr], \quad k \ge 0.\end{align*}
Proof. Using conditional arguments, we have
 \begin{align*} R^{f, \mu}_k(t) &=\mathbb{E}\bigl[\mathbb{P}\bigl[N^{f, \mu}_{2}(t)=k\mid G_{\mu}(t)\bigr]\bigr] \quad \text{({substituting the PMF of the} TCPP-II (14))}\\[3pt] & =\dfrac{\lambda^k}{k!} \sum_{n=0}^{\infty} \dfrac{(-\lambda)^n}{n!}\mathbb{E}\bigl[ E^f(G_{\mu}(t))^{k+n} \bigr], \end{align*}
which completes the proof.
Now we consider special cases of the time-changed Poisson process, such as the TFPP, and investigate their distributional properties.
Example 3. (Geometric time fractional Poisson process.) Let
 $\bigl\{N^{\alpha}_{2}(t)\bigr\}_{t \geq 0}$
be the time-changed TFPP with GCP defined by time-changing the TFPP
 $\bigl\{N_2^{\alpha}(t)\bigr\}_{t \geq 0}$
by an independent GCP, that is,
 \begin{align*}{ N^{\alpha, \mu}_{2}(t)=N_2^\alpha(G_{\mu}(t)),\quad t \geq 0.} \\[-10pt] \end{align*}
Proposition 10. The LT of
 $\{N^{\alpha, \mu}(t)\}_{t \geq 0}$
is given by
 \begin{equation*}\mathbb E \bigl[{\mathrm{e}}^{-u N^{\alpha, \mu}(t)}\bigr]=\sum_{k=0}^{\infty}\dfrac{(-\lambda(1-{\mathrm{e}}^{-u}))^k}{\Gamma(\alpha k+1)}\dfrac{1}{(1+\mu t)}\operatorname{Li}_{-\alpha k} \biggl(\dfrac{\mu t}{1+\mu t}\biggr),\quad \mathrm{Re}(u)\geq 0.\end{equation*}
where
 $\operatorname{Li}_s(z)$
denotes the polylogarithm function defined in (7).
Proof. Using independence and conditioning on
 $G_{\mu}(t)$
, we have
 \begin{align*}\mathbb{E} \bigl[{\mathrm{e}}^{-u N_2^{\alpha, \mu}(t)}\bigr]=\mathbb{E}\bigl[\mathbb{E} \bigl({\mathrm{e}}^{-u N_2^{\alpha}(G_{\mu}(t))}\mid G_{\mu}(t)\bigr)\bigr]. \end{align*}
Substituting the Laplace transform of the TFPP from (15), we obtain
 \begin{align*}\mathbb{E} \bigl[{\mathrm{e}}^{-u N_2^{\alpha, \mu}(t)}\bigr] =\mathbb{E}\bigl[M_{\alpha}\bigl(-\lambda(1-{\mathrm{e}}^{-u})G_{\mu}(t)^{\alpha}\bigr)\bigr]. \end{align*}
Using the series representation of the Mittag–Leffler function and interchanging the order of summation and expectation, we obtain
 \begin{align*} \mathbb{E} \bigl[{\mathrm{e}}^{-u N_2^{\alpha, \mu}(t)}\bigr]=\sum_{k=0}^{\infty}\dfrac{[-\lambda(1-{\mathrm{e}}^{-u})]^k}{\Gamma(\alpha k+1)}\mathbb{E} \bigl[G_{\mu}(t)^{\alpha k}\bigr].\end{align*}
Substituting the fractional moment from (6) into the above expression yields the complete polylogarithmic representation of the LT. This completes the proof.
Proposition 11. The PMF
 $\mathbb{P}\bigl[N_2^{\alpha, \mu}(t)=k\bigr]= R_k^{\alpha, \mu}(t)$
of the geometric TCPP-II is given by
 \begin{align*}R^{\alpha,\mu}_k(t)=\dfrac{\lambda^k}{k!}\sum_{n=0}^{\infty}\dfrac{(-\lambda)^n}{n!}\dfrac{1}{(1+\mu t)}\dfrac{1}{\Gamma(\alpha(k+n)+1)}\,\operatorname{Li}_{-\alpha(k+n)} \biggl(\dfrac{\mu t}{1+\mu t}\biggr), \quad k \geq 0, \end{align*}
where
 $\operatorname{Li}_{s}(\! \cdot \!)$
is the polylogarithm function defined in (7).
Proof. Using conditional arguments and the independence of
 $\{N^{\alpha}_{2}(t)\}_{t \geq 0}$
and
 $\{G_\mu(t)\}_{t \geq 0}$
, we have
 \begin{align*}R^{\alpha,\mu}_k(t)&=\mathbb{E} \bigl[\mathbb{P} \bigl(N^{\alpha}_{2}(G_\mu(t))=k\mid G_\mu(t)\bigr)\bigr].\end{align*}
Putting the PMF of the TFPP-II from (16), we obtain
 \begin{align*}R^{\alpha,\mu}_k(t)&=\mathbb{E}\Biggl[\dfrac{\lambda^k}{k!}\sum_{n=0}^{\infty}\dfrac{(-\lambda)^n}{n!}\dfrac{G_\mu(t)^{\alpha(k+n)}}{\Gamma(\alpha(k+n)+1)}\Biggr].\end{align*}
Interchanging expectation and summation yields
 \begin{align*}R^{\alpha,\mu}_k(t)&=\dfrac{\lambda^k}{k!}\sum_{n=0}^{\infty}\dfrac{(-\lambda)^n}{n!}\dfrac{1}{\Gamma(\alpha(k+n)+1)}\,\mathbb{E} \bigl[G_\mu(t)^{\alpha(k+n)}\bigr].\end{align*}
Since the fractional moment of
 $G_{\mu}(t)$
was obtained in (6), substituting it into the above expression completes the proof.
Theorem 3. For
 $0 \lt s \le t \lt \infty$
, the distributional properties of
 $\bigl\{N^{\alpha,\mu}_{2}(t)\bigr\}_{t\ge0}$
are as follows.
-
(i)
 $\mathbb{E} \bigl[N^{\alpha,\mu}_{2}(t)\bigr]=\dfrac{\lambda}{\Gamma(\alpha+1)(1+\mu t)}\operatorname{Li}_{-\alpha} \biggl(\dfrac{\mu t}{1+\mu t}\biggr).$
-
(ii) The variance of
$N_2^{\alpha, \mu}(t)$
is given by
\begin{align*}\operatorname{Var} \bigl(N^{\alpha,\mu}_{2}(t)\bigr)&=\dfrac{\lambda}{\Gamma(\alpha+1)(1+\mu t)}\operatorname{Li}_{-\alpha} \biggl(\dfrac{\mu t}{1+\mu t}\biggr) +\dfrac{\lambda^2}{\Gamma(2\alpha+1)(1+\mu t)}\operatorname{Li}_{-2\alpha} \biggl(\dfrac{\mu t}{1+\mu t}\biggr) \\[3pt]& \quad -\dfrac{\lambda^2}{\Gamma(\alpha+1)^2}\biggl[\dfrac{1}{(1+\mu t)}\operatorname{Li}_{-\alpha} \biggl(\dfrac{\mu t}{1+\mu t}\biggr)\biggr]^2 .\end{align*}
-
(iii) The covariance of
$N_2^{\alpha,\mu}(t)$
and
$N_2^{\alpha,\mu}(s)$
is given by
\begin{align*}& \operatorname{Cov}\bigl(N_2^{\alpha,\mu}(t), N_2^{\alpha,\mu}(s)\bigr) \\[3pt]&\quad = \dfrac{\lambda}{\Gamma(\alpha+1)} \dfrac{1}{1+\mu s} \, \operatorname{Li}_{-\alpha}\biggl(\dfrac{\mu s}{1+\mu s}\biggr) \nonumber +\dfrac{\lambda^2}{\Gamma(2\alpha+1)} \Biggl[\dfrac{1}{1+\mu t} \, \operatorname{Li}_{-2\alpha}\biggl(\dfrac{\mu t}{1+\mu t}\biggr) \\[3pt] & \quad\quad + \dfrac{1}{1+\mu s} \, \operatorname{Li}_{-2\alpha}\biggl(\dfrac{\mu s}{1+\mu s}\biggr) \nonumber - \dfrac{1}{1+\mu t} \sum_{m=0}^{\infty} \sum_{n=0}^{\infty} n^{2\alpha}\biggl(\dfrac{\mu s}{1+\mu t}\biggr)^m\biggl(\dfrac{\mu (t-s)}{1+\mu t}\biggr)^n\dfrac{(m+n)!}{m! \, n!}\Biggr] \nonumber \\[3pt] & \quad\quad - \dfrac{\lambda^2}{\Gamma(\alpha+1)^2} \dfrac{1}{1+\mu t} \sum_{m=0}^{\infty} \sum_{n=0}^{\infty} m^\alpha (m+n)^\alpha\biggl(\dfrac{\mu s}{1+\mu t}\biggr)^m\biggl(\dfrac{\mu (t-s)}{1+\mu t}\biggr)^n\dfrac{(m+n)!}{m! \, n!}.\end{align*}
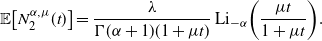


Proof. Using Theorem 2 and the fractional moment of the GCP in (6), we have
 \begin{align*}\mathbb{E} \bigl[N^{\alpha,\mu}_{2}(t)\bigr]=\dfrac{ \lambda}{\Gamma(\alpha+1)} \mathbb{E}\big[G_\mu^\alpha(t)\big]=\dfrac{\lambda}{\Gamma(\alpha+1)}\dfrac{1}{(1+\mu t)}\operatorname{Li}_{-\alpha} \biggl(\dfrac{\mu t}{1+\mu t}\biggr). \end{align*}
Next we use the law of total variance for the TFPP-II time-changed by an independent geometric process
 $G_\mu(t)$
:
 \begin{align*}\operatorname{Var}\bigl[N_2^{\alpha,\mu}(t)\bigr] =\mathbb{E}\bigl[\operatorname{Var}\bigl(N_2^{\alpha}(G_\mu(t)) \mid G_\mu(t)\bigr)\bigr]+ \operatorname{Var}\bigl(\mathbb{E}\bigl[N_2^{\alpha}(G_\mu(t)) \mid G_\mu(t)\bigr]\bigr). \end{align*}
Using (17) and the fractional moments of the geometric process from (6), we obtain the desired result.
To calculate the covariance of the GTCPP-II, we assume the outer process is
 $N_2^{\alpha}(t)$
and the inner process is
 $G_\mu(t)$
. Using the law of total covariance and (17), we have
 \begin{align*}\operatorname{Cov}\bigl(N_2^{\alpha, \mu}(t), N_2^{\alpha, \mu}(s)\bigr)&= \dfrac{\lambda}{\Gamma(\alpha+1)} \mathbb{E}[G_\mu(s)^\alpha] \nonumber \\[3pt]&\quad + \dfrac{\lambda^2}{\Gamma(2\alpha+1)} \bigl( \mathbb{E}\big[G_\mu(t)^{2\alpha}\big] + \mathbb{E}\big[G_\mu(s)^{2\alpha}\big] - \mathbb{E}\big[(G_\mu(t)-G_\mu(s))^{2\alpha}\big] \bigr) \nonumber \\[3pt]&\quad - \dfrac{\lambda^2}{\Gamma(\alpha+1)^2} \mathbb{E}\big[G_\mu(t)^\alpha G_\mu(s)^\alpha\big].\end{align*}
Substituting the fractional moment from (6) and the joint fractional moment from (8) into the expectations above gives the final explicit result.
5. Geometric generalized compound and multiplicative Poisson processes
In this section we will study two extensions of the Poisson processes, namely the compound Poisson process and the multiplicative compound Poisson process, for both types of time-changed Poisson processes.
5.1. Geometric time-changed compound Poisson process I
Definition 3. Let
 $X_i$
,
 $i=1,2,\ldots,$
be the i.i.d. jumps with common distribution
 $F_X$
and let
 $N_1^f(t)$
be subordinated Poisson process with the Lévy subordinator, which is independent of the
 $X_i$
. The process defined by
 \begin{equation*}Y_1^{f}(t) \, :\!= \, \sum_{i=1}^{N_1^{f}(t)} X_i, \quad t\geq0,\end{equation*}
is called the generalized compound Poisson process I (GCPP-I).
The LT of
 $Y_1^{f}(t)$
is given by
 \begin{align} \mathbb{E}\bigl[{\mathrm{e}}^{-uY_1^f(t)}\bigr]={\mathrm{e}}^{-t f(\lambda(1-M_X(-u)))},\end{align}
where
 $M_X(u)$
is the LT of X.
Proposition 12. The mean and variance of the process
 $Y_1^{f}(t)$
are given by
 \begin{align} \mathbb{E}\bigl[Y_1^{f}(t)\bigr] &=\lambda \mathbb{E}[D^{f}(t)]\mathbb{E}[X_1] ,\notag \\[3pt]\operatorname{Var}\bigl[Y_1^{f}(t)\bigr] &= \lambda \mathbb{E}[D^{\,f}(t)]\mathbb{E}[{X}^2]+\mathbb{E}[X]^2\lambda^2 \operatorname{Var}[D^{\,f}(t)], \\[3pt]\operatorname{Cov}\bigl[Y_1^f(t),Y_1^f(s)\bigr] & = \lambda \mathbb{E}[X_1^2]\mathbb{E}[D^{\,f}(s)]+\lambda^2(\mathbb{E}[X_1])^2\operatorname{Cov}[D^{\,f}(t),D^{\,f}(s)].\notag\end{align}
Proof. These results follow similar lines to [Reference Gupta and Kumar16] and are therefore omitted.
The cumulative distribution function (CDF)
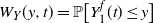 $W_{Y}(y, t)=\mathbb{P}\bigl[Y_1^f(t) \leq y\bigr] $
of
 $Y_1^f(t)$
, for
 $y \in \mathbb{R}$
and
 $t \gt 0$
, is given by
 \begin{align*}W_{Y}(y, t)= \sum_{m=0}^{\infty} P^f_m(t)F_Y^{(m)}(y), \end{align*}
where, for
 $m \in \mathbb{N}$
, we define the m-fold convolution
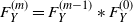 $F_Y^{(m)} = F_Y^{(m-1)} \ast F_Y^{(0)} $
and
 $F^{(0)}_Y(y)=\mathbf{1}_{\{y \geq 0\}}.$
Definition 4. Consider the GCPP
 $\{Y_1^f(t)\}_{t \geq 0}$
time-changed by an independent GCP
 $\{G_\mu(t)\}_{t \geq0}$
, defined as
 \begin{align*}Y_1^{f,\mu}(t)=Y_1^f(G_{\mu}(t)), \quad t \geq 0. \end{align*}
The process
 $\bigl\{Y_1^{f,\mu}(t)\bigr\}_{t \geq 0}$
is referred to as the geometric generalized compound Poisson process I (GGCPP-I).
Proposition 13. The LT of
 $Y_1^{f,\mu}$
is given by
 \begin{align*}\mathbb{E}\bigl[{\mathrm{e}}^{-uY_1^{f,\mu}(t)}\bigr]= \dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-f(\lambda(1-M_X(-u))})},\quad u\gt 0. \end{align*}
Proof. From (21) and (4), it follows that
 \begin{equation*}\mathbb{E}\bigl[{\mathrm{e}}^{-u Y_1^{f,\mu}(t)}\bigr]=\mathbb{E}\bigl[\mathbb{E}\bigl[{\mathrm{e}}^{-uY_1^f(G_\mu(t))}\mid G_\mu(t)\bigr]\bigr]=\mathbb{E}\bigl[{\mathrm{e}}^{-G_\mu(t)f(\lambda(1-M_X(-u))}\bigr]. \end{equation*}
Proposition 14. We have the following equality in distribution for the GGCPP-I:
 \begin{align*}Y_1^{f,\mu}(t) \stackrel{d}{=} Z^\mu(t)=\sum_{i=0}^{G_\mu(t)}\chi_i, \end{align*}
where
 $\chi_0=0$
and
 $\chi_1, \chi_2,\ldots$
are i.i.d. random variables distributed as
 $Y_1^f(1)$
, which are also independent of
 $G_{\mu}(t)$
.
Proof. The proof follows a similar approach to that in Proposition 4.
Further, we discuss the mean and variance of the process GGCPP-I
 $\bigl\{Y_1^{f, \mu}(t)\bigr\}_{t\geq 0}$
.
Theorem 4. For
 $0 \lt s \leq t \lt \infty$
, the distributional properties of
 $\bigl\{Y_1^{f, \mu}(t)\bigr\}_{t \geq0}$
are as follows:
 \begin{align*} \mathbb{E}\bigl[Y_1^{f, \mu}(t)\bigr]& =\lambda \mu t \mathbb{E}[D^{f}(1)]\mathbb{E}[X_1],\\[3pt] \operatorname{Var}\bigl[Y_1^{f, \mu}(t)\bigr]& = \lambda \mu t [\mathbb{E}[D^{f}(1)]\operatorname{Var}[X_1]+\mathbb{E}[X^2](\lambda \operatorname{Var}[D^{\,f}(1)] +\mathbb{E}[D^{\,f}(1)])] \\[3pt] & \quad + \lambda^2 \mu t \mathbb{E}[D^{\,f}(1)]^2\mathbb{E}[X_1]^2(1+\mu t),\\[3pt] \operatorname{Cov}\bigl[Y_1^{f, \mu}(t),Y_1^{f, \mu}(s)\bigr]& = \mu s\big(\lambda \mathbb{E}\big[X_1^2\big]\mathbb{E}[D^{\,f}(1)]+\mathbb{E}\big[X_1^2\big]\lambda^2 \operatorname{Var}[D^{\,f}(1)] \big) \\[3pt] &\quad + \lambda^2\mathbb{E}[D^{\,f}(1)]^2\mathbb{E}[X_1]^2 \mu s(1+\mu t).\end{align*}
Proof. Using the conditional argument and independence of
 $G_\mu(t)$
and
 $\chi_i$
, we have
 \begin{align*}\mathbb{E}\bigl[Y_1^{f, \mu}(t)\bigr]= \mathbb{E}[G_\mu(t)]\mathbb{E}[\chi_1]=\lambda \mu t\mathbb{E}[X_1]\mathbb{E}[D^{\,f}(t)]. \end{align*}
From (22) and (5), the variance of
 $\{Y_1^f(t)\}_{t \geq 0}$
can be written as (see [Reference Leonenko, Meerschaert, Schilling and Sikorskii24])
 \begin{align*}\operatorname{Var}\bigl[Y_1^{f, \mu}(t)\bigr] = \operatorname{Var}[\chi_1]\mathbb{E}[G_\mu (t)]+\mathbb{E}[\chi_1]^2\operatorname{Var}[G_\mu(t)]. \end{align*}
Next we can directly compute the
 $\operatorname{Cov}\bigl[Y_1^{f, \mu}(t),Y_1^{f, \mu}(s)\bigr]$
,
 $s\leq t$
, by using (22), that is,
 \begin{align*}\operatorname{Cov}\bigl[Y_1^{f, \mu}(t),Y_1^{f, \mu}(s)\bigr]=\operatorname{Var}\bigl[Y_1^f(1)\bigr]\mathbb{E}[G_\mu(s)]+\mathbb{E}\bigl[Y_1^f(1)\bigr]^2\operatorname{Cov}[G_\mu(t),G_\mu(s)]. \end{align*}
Now, substituting equations (22) and (5) in the above expression completes the proof.
Proposition 15. The CDF
 $W_Y^{\mu, f}(y, t)\, :\!= \, \mathbb{P}\bigl[Y_1^{f, \mu}(t) \leq y\bigr]$
of
 $Y_1^{f, \mu}(t)$
is given by
 \begin{align*} W_Y^{\mu}(y, t)=\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-f(\lambda^{\alpha}}))}\mathbf{1}_{\{y \geq 0\}}+\sum_{m=1}^{\infty} \dfrac{(\!-1)^m}{m!}F_Y^{(m)}(y)\dfrac{{\mathrm{d}}^m}{{\mathrm{d}} u^m}\biggl(\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-f(\lambda u})}\biggr)_{u=1}. \end{align*}
Proof. By using conditional arguments,
 \begin{align*} W_Y^{\mu,f}(y, t)&= \sum_{n=0}^{\infty}\mathbb{P}[G_{\mu}(t)=n]W_Y^f(y, n)\\[3pt] &= \sum_{n=0}^{\infty}[G_{\mu}(t)=n]\Biggl[\mathbf{1}_{\{y \geq 0\}}{\mathrm{e}}^{-nf(\lambda)}+\sum_{m=1}^{\infty}P_m^f(n) F^{m}_Y(y)\Biggr]\\[3pt] &= \dfrac{1}{1+\mu t (1-{\mathrm{e}}^{-f(\lambda)})}\mathbf{1}_{\{y \geq 0\}}+ \Biggl[\dfrac{1}{1+\mu t} \\[3pt] & \quad\times \sum_{n=0}^{\infty}\biggl(\dfrac{\mu t}{1+\mu t}\biggr)^n\sum_{m=1}^{\infty}F^{m}_Y(y)\dfrac{(\!-1)^m}{m!}\dfrac{{\mathrm{d}}^m}{{\mathrm{d}} u^m}\bigl({\mathrm{e}}^{-nf(\lambda u)}\bigr)_{u=1} \Biggr]\\[3pt] &= \dfrac{1}{1+\mu t (1-{\mathrm{e}}^{-f(\lambda)})}\mathbf{1}_{\{y \geq 0\}}+ \Biggl[\dfrac{1}{1+\mu t} \\[3pt] & \quad \times \sum_{m=1}^{\infty}\dfrac{(\!-1)^m}{m!}F^{m}_Y(y)\dfrac{{\mathrm{d}}^m}{{\mathrm{d}} u^m}\Biggl(\sum_{n=0}^{\infty}\biggl(\dfrac{\mu t {\mathrm{e}}^{-f(\lambda u)}}{1+\mu t}\biggr)^n \Biggr)_{u=1} \Biggr]\\[3pt] &= \dfrac{1}{1+\mu t (1-{\mathrm{e}}^{-f(\lambda)})}\mathbf{1}_{\{y \geq 0\}}+\sum_{m=1}^{\infty}\dfrac{(\!-1)^m}{m!}F^{m}_Y(y)\dfrac{{\mathrm{d}}^m}{{\mathrm{d}} u^m}\biggl(\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-f(\lambda u)})}\biggr)_{u=1}. \end{align*}
Corollary 2. If the
 $Y_i$
are absolutely continuous with PDF
 $f_{Y}(\! \cdot \!),$
then
-
• the continuous part of
$f_y(\! \cdot \!)$
is given by
\begin{align*}g_{Y}^{f, \mu}(y, t)= \sum_{m=1}^{\infty} \dfrac{(\!-1)^m}{m!}F_Y^{(m)}(y)(y)\dfrac{{\mathrm{d}}^m}{{\mathrm{d}} u^m}\biggl(\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-f(\lambda u})}\biggr)_{u=1}, \end{align*}
-
• a discrete part
$f_y(\! \cdot \!)$
is given by
\begin{align*} \mathbb{P}\bigl[Y_1^{f}(t)=0\bigr]=\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-f(\lambda^{\alpha}}))}. \end{align*}


Corollary 3. If the
 $Y_n$
are discrete and integer-valued random variables
 \begin{align*}h_k^{*m}\, :\!= \, \mathbb{P}[Y_1+Y_2+\cdots+Y_m=k], \quad k\in z, \end{align*}
then
 \begin{align*}\mathbb{P}\bigl[Y^f_\mu(t)=k\bigr]=\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-f(\lambda^{\alpha})})}\mathbf{1}_{\{k=0\}}+\sum_{m=1}^{\infty} \dfrac{(\!-1)^m}{m!}h_k^{*m}\dfrac{{\mathrm{d}}^m}{{\mathrm{d}} u^m}\biggl(\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-f(\lambda u)}}\biggr)_{u=1}. \end{align*}
Corollary 4. If the
 $Y_n$
are discrete and integer-valued random variables
 \begin{align*}h_k^{*m}\, :\!= \, \mathbb{P}[Y_1+Y_2+\cdots+Y_m=k],\quad k\in z, \end{align*}
then
 \begin{align*}\mathbb{P}\bigl[Y^{f,\mu}_1(t)=k\bigr]=\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-f(\lambda^{\alpha})})}\mathbf{1}_{\{k=0\}}+\sum_{m=1}^{\infty} \dfrac{(\!-1)^m}{m!}h_k^{*m}\dfrac{{\mathrm{d}}^m}{{\mathrm{d}} u^m}\biggl(\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-f(\lambda u)}}\biggr)_{u=1}. \end{align*}
5.2. Geometric time-changed compound Poisson process II
Definition 5. Let
 $X_i$
,
 $ i=1,2,\ldots,$
be i.i.d. jumps with common distribution
 $F_X$
, and let
 $N_2^f(t)$
be the TCPP-II, independent of the
 $X_i$
. The process defined by
 \begin{equation*}Y_2^{f}(t)\, :\!= \, \sum_{i=1}^{N_2^{\, f}(t)} X_i,\quad t\ge0,\end{equation*}
is called the generalized compound Poisson process II (GCPP-II).
Definition 6. Consider the GCPP-II
 $\{Y_2^f(t)\}_{t\ge0}$
time-changed with an independent geometric process
 $\bigl\{G_\mu(t)\bigr\}_{t\ge0}$
, defined by
 \begin{align*}Y_2^{f,\mu}(t)=Y_2^f(G_\mu(t)), \quad t\ge0. \end{align*}
The resulting process
 $\bigl\{Y_2^{f,\mu}(t)\bigr\}_{t\ge0}$
is referred to as the geometric generalized compound Poisson process II (GGCPP-II).
Remark 2. For the GGCPP-II
 $\bigl\{Y_2^{f,\mu}(t)\bigr\}_{t\ge0}$
, the Laplace transform, mean, variance, covariance structure, and the CDF can be obtained using arguments similar to those used for the GGCPP-I. Since the derivations follow the same steps, the detailed proofs are omitted.
5.3. Geometric time-changed multiplicative Poisson process I (GTCMPP-I)
In this section we introduce the generalized multiplicative CPP and study its properties. Note that the multiplicative CPP
 $\{N_{\pi}(t)\}_{t \geq 0}$
was introduced by Orsingher and Polito [Reference Orsingher and Polito31].
Definition 7. Let
 $X_i$
be i.i.d. random variables which are independent of the TCPP-I
 $N_1^{f}(t)$
. Then the process
 $N_{\pi}^{f}(t)$
defined by
 \begin{equation*}{N_{\pi}^{f}(t)= \prod_{i=1}^{N_{f}t)}X_i,\quad t\geq 0,}\end{equation*}
is called the generalized multiplicative CPP.
The CDF
 $Q_{\pi}^{f}$
of the process
 $N_{\pi}^{f}(t)$
is given by
 \begin{align} Q_{\pi}^{f}(y;\,t) &= \sum_{m=0}^{\infty} \mathbb{P}\bigl[N_1^{f}(t)=m\bigr]\mathbb{P}[V_m \leq y]\nonumber\\[3pt] &= {\mathrm{e}}^{-f(\lambda)t}\mathbf{1}_{\{y \geq 1\}}+ \sum_{m=1}^{\infty} \mathbb{P}\bigl[N_1^{f}(t)=m\bigr]\mathbb{P}[V_m \leq y],\quad y\in \mathbb{R}, \ t\geq0 ,\end{align}
where
 $V_m=X_1X_2\ldots X_m$
.
Definition 8. We define the generalized multiplicative CPP by time-changing the
 $N_\pi^{f}(t)$
by an independent GCP
 $G_\mu (t)$
. It is given by
 \begin{align*} Y_{\pi}^{f, \mu}(t)\, :\!= \, N_\pi^{f}(G_\mu(t)),\quad \mu \gt 0. \end{align*}
We call it the geometric time-changed multiplicative Poisson process I (GTCMPP-I).
Proposition 16. The CDF
 $Q_{\pi}^{f, \mu}(t)$
of
 $Y_{\pi}^{f, \mu}(t)$
is given by
 \begin{align*}R_{\pi}^{f,\mu}(y, t)=\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-f(\lambda)})}\mathbf{1}_{\{y \geq 0\}}+\sum_{m=1}^{\infty} \dfrac{(\!-1)^m}{m!}F_Y^{(m)}(y)\dfrac{{\mathrm{d}}^m}{{\mathrm{d}} u^m}\biggl(\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-f(\lambda u})}\biggr)_{u=1}. \end{align*}
Proof. From (23), we have
 \begin{align*} Q_{\pi}^{f, \mu}(y;\, t)= &\sum_{n=0}^{\infty} \mathbb{P}[G_\mu(t)=n]Q_{\pi}^{f}(y;\, n)\\[3pt] =& \sum_{n=0}^{\infty} \mathbb{P}[G_\mu(t)=n]\Biggl[{\mathrm{e}}^{-f(\lambda)t}\mathbf{1}_{\{y \geq 1\}}+ \sum_{m=1}^{\infty} \mathbb{P}\bigl[N_1^{f}(t)=m\bigr]\mathbb{P}[V_m \leq y]\Biggr].\end{align*}
We substitute the PMF of the
 $G_\mu (t)$
and
 $N_1^{f}(t)$
from (3) and (10) respectively, which completes the proof.
Next, we calculate the Mellin transform of
 $N_{\pi}^f(t)$
:
 \begin{align*}\mathbb{E}\bigl[N_{\pi}^f(t)\bigr]^{\beta-1}=\sum_{k=0}^{\infty}\dfrac{(\!-1)^k}{k!}\mathbb{E}[X^{\beta-1}]^k \dfrac{{\mathrm{d}}^k}{{\mathrm{d}} u^k}\bigl({\mathrm{e}}^{-t f(\lambda u)}\bigr)_{u=1}. \end{align*}
Using the previous result, we evaluate the Mellin transform of
 $Q_{\pi}^{f, \mu}(t)$
as follows:
 \begin{align*}\mathbb{E}\bigl[Y_{\pi}^{f, \mu}(t)\bigr]^{\beta-1} &= \dfrac{1}{1+\mu t}\sum_{n=0}^{\infty}\biggl(\dfrac{\mu t}{1+\mu t}\biggr)^{n}\mathbb{E}\bigl[N^{\, f}_\pi(n)\bigr]^{\beta-1}\\[3pt]&= \dfrac{1}{1+\mu t}\sum_{k=0}^{\infty}\dfrac{(\!-1)^k}{k!}\mathbb{E}[X^{\beta-1}]^k \dfrac{{\mathrm{d}}^k}{{\mathrm{d}} u^k}\Biggl(\sum_{n=0}^{\infty}\biggl(\dfrac{\mu t {\mathrm{e}}^{-f(\lambda u)}}{1+\mu t}\biggr)^{n}\Biggr)_{u=1}\\[3pt]&= \sum_{k=0}^{\infty}\dfrac{(\!-1)^k}{k!}\mathbb{E}[X^{\beta-1}]^k \dfrac{{\mathrm{d}}^k}{{\mathrm{d}} u^k}\biggl(\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-f(\lambda u)})}\biggr)_{u=1}.\end{align*}
Put
 $\beta=2$
. Then the mean of the process is given by
 \begin{align}\mathbb{E}\bigl[Y_{\pi}^{f, \mu}(t)\bigr] &= \sum_{k=0}^{\infty}\dfrac{(\!-1)^k}{k!}\mathbb{E}[X]^k \dfrac{{\mathrm{d}}^k}{{\mathrm{d}} u^k}\biggl(\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-f(\lambda u)})}\biggr)_{u=1}.\end{align}
We next study a special case of the GTCMPP-I, namely the tempered stable subordinator.
Definition 9. Consider the subordinator associated with tempered stable Bernstein function (2)
 $f(s)= (\nu+s)^\alpha-\nu^\alpha$
,
 $ \alpha \in (0,1]$
,
 $\nu\gt 0$
, denoted by
 $\{D^{\alpha,\nu}(t)\}_{t\geq0}$
. Let
 $N^{\alpha,\nu}_1(t)\, :\!= \, N(D^{\alpha,\nu}(t)), t\geq 0$
be the tempered space-fractional Poisson process (TSFPP) [Reference Gupta, Kumar and Leonenko18]. The process
 $N_{\pi}^{\alpha, \nu}(t)$
defined by
 \begin{align*}{N_{\pi}^{\alpha, \nu}(t)= \prod_{i=1}^{N^{\alpha, \nu}(t)}X_i,\quad t\geq 0,}\end{align*}
is called the tempered multiplicative fractional CPP with
 $X_i$
,
 $i=1,2,\ldots,$
being the i.i.d. random variables independent of
 $N^{\alpha, \nu}(t)$
.
The CDF
 $Q_{\pi}^{\alpha, \nu}$
of the process
 $N_{\pi}^{\alpha, \nu}(t)$
is given by
 \begin{align*} Q_{\pi}^{\alpha, \nu}(y;\,t) &= \sum_{m=0}^{\infty} \mathbb{P}[N_1^{\alpha, \nu}(t)=m]\mathbb{P}[V_m \leq y]\nonumber\\[3pt] &= {\mathrm{e}}^{((\lambda+\nu)^{\alpha}-\nu^\alpha)t}\mathbf{1}_{\{y \geq 1\}}+ \sum_{m=1}^{\infty} \mathbb{P}\big[N_1^{\alpha, \nu}(t)=m\big]\mathbb{P}[V_m \leq y],\end{align*}
where
 $V_m=X_1X_2\ldots X_m$
.
Definition 10. We define a new time-changed stochastic process, characterized by time evolving in a multiplicative CPP
 $N_\pi^{\alpha, \nu}(t)$
with GCP
 $G_\mu (t)$
, such that
 \begin{align*} Y_{\pi}^{\alpha, \nu, \mu}(t)= N_\pi^{\alpha, \nu}(G_\mu(t)),\quad \nu, \mu \gt 0,\ \alpha \in (0,1). \end{align*}
Proposition 17. The CDF
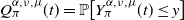 $Q_{\pi}^{\alpha, \nu, \mu}(t)= \mathbb{P}\bigl[Y_{\pi}^{\alpha, \nu, \mu}(t)\leq y\bigr]$
of
 $Y_{\pi}^{\alpha, \nu, \mu}(t)$
is given by
 \begin{align*}Q_{\pi}^{\alpha, \nu, \mu}(t) &=\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-(\lambda+\nu)^{\alpha}+\nu^\alpha})}\mathbf{1}_{\{y \geq 1\}} + \Biggl[\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-\nu^\alpha})} \\[3pt]&\quad \times \sum_{m=1}^{\infty}(-\lambda)^m \mathbb{P}[V_m \leq y] \sum_{r=0}^{\infty}{\binom {\alpha r }{m}}\dfrac{(-(\lambda+\nu)^\alpha)^r}{r!} w_{r}\biggl(\dfrac{\mu t {\mathrm{e}}^{-\nu^\alpha}}{1+\mu t(1-{\mathrm{e}}^{-\nu^\alpha})}\biggr) \Biggr]. \end{align*}
Proof. This is based on a similar approach to that shown in Proposition 16.
Corollary 5. If the
 $X_i$
are discrete, then the PMF
 $\mathbb{P}\bigl[Y_{\pi}^{\alpha, \nu, \mu}(t)=k\bigr]$
of
 $Y_{\pi}^{\alpha, \nu, \mu}(t)$
is given by
 \begin{align*} \mathbb{P}\bigl[Y_{\pi}^{\alpha, \nu, \mu}(t)=k\bigr]&= \dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-(\lambda+\nu)^{\alpha}+\nu^\alpha})}\mathbf{1}_{\{k= 1\}} + \Biggl[\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-\nu^\alpha})} \nonumber \\[3pt]&\quad\times \sum_{m=1}^{\infty}(-\lambda)^m \mathbb{P}[V_m=k]\sum_{r=0}^{\infty}{\binom {\alpha r }{m}}\dfrac{(-(\lambda+\nu)^\alpha)^r}{r!} w_{r}\biggl(\dfrac{\mu t {\mathrm{e}}^{-\nu^\alpha}}{1+\mu t(1-{\mathrm{e}}^{-\nu^\alpha})}\biggr) \Biggr]\nonumber.\end{align*}
Corollary 6. Let
 $\phi_{V_m}$
be the density of the
 $V_m$
.
-
• For the absolutely continuous case, the density
$h_{\pi}^{\alpha,\nu, \mu}(y, t)$
of
$Y_{\pi}^{\alpha, \nu, \mu}(t)$
satisfies where
\begin{align*}h_{\pi}^{\alpha, \nu, \mu}(y, t) &= \dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-\nu^\alpha})} \\[3pt]&\quad \times \sum_{m=1}^{\infty}(-\lambda)^m \phi_{V_m}(y)\sum_{r=0}^{\infty}{\binom {\alpha r }{m}}\dfrac{(-(\lambda+\nu)^\alpha)^r}{r!} w_{r}\biggl(\dfrac{\mu t {\mathrm{e}}^{-\nu^\alpha}}{1+\mu t(1-{\mathrm{e}}^{-\nu^\alpha})}\biggr),\end{align*}
$y \neq 0$
,
$ t \gt 0$
.
-
• When
$Y_{\pi}^{\alpha, \nu, \mu}(t)=1$
,
\begin{align*}\mathbb{P}\bigl[Y_{\pi}^{\alpha, \nu, \mu}(t)=1\bigr]=\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-(\lambda+\nu)^{\alpha}+\nu^\alpha})}. \end{align*}


5.4. Geometric time-changed multiplicative Poisson process II (GTCMPP-II)
Definition 11. Let
 $X_i$
,
 $ i=1,2,\ldots,$
be i.i.d. random variables with common distribution
 $F_X$
, independent of the TCPP-II
 $\bigl\{N_2^{\, f}(t)\bigr\}_{t\ge0}$
. The process
 $\bigl\{N_{\pi,2}^{f}(t)\bigr\}_{t\ge0}$
defined by
 \begin{equation*}N_{\pi,2}^{f}(t)= \prod_{i=1}^{N_2^{\, f}(t)} X_i, \quad t\ge0 ,\end{equation*}
is called the generalized multiplicative compound Poisson process II (GMPP-II).
Definition 12. Let us consider the generalized multiplicative compound Poisson process II
 $\bigl\{N_{\pi,2}^{f}(t)\bigr\}_{t\ge0}$
time-changed with an independent geometric process
 $\{G_\mu(t)\}_{t\ge0}$
. The resulting process is defined by
 \begin{align*}Y_{\pi,2}^{f,\mu}(t)=N_{\pi,2}^{f}(G_\mu(t)), \quad \mu\gt 0. \end{align*}
This process is referred to as the geometric time-changed multiplicative Poisson process II (GTCMPP-II).
Remark 3. The distributional properties of this process, such as the CDF, Mellin transform, mean, and the corresponding PMF or density (depending on the nature of the jumps), can be derived by conditioning on the counting process
 $N_2^{\, f}(t)$
. Since the jumps
 ${X_i}$
are assumed to be i.i.d. and independent of the counting process, the derivations follow straightforwardly, and the results can be obtained in a similar manner. Moreover, particular choices of the Bernstein function f lead to important special cases. For instance, by taking
 $f(s)=s^{\alpha}$
, the TFPP arises as a special case.
6. Applications in shock models
This section highlights the practical application of previously derived results in the context of shock models, which serve as essential tools for analyzing the behavior of system lifetimes in random environments. Shock models are particularly relevant for understanding how systems endure and fail under harmful events. Two critical aspects underpin any shock modeling approach. One is a pattern of shock arrivals: the stochastic process governing when shocks occur. It could be modeled using simple frameworks such as Poisson processes or renewal processes. The other is the effect of shocks on the system: this captures the system’s response to each shock, varying from negligible to catastrophic.
Based on how shocks impact the system, several classes of shock models have been extensively studied in the literature. These models can be broadly categorized into the following five types.
-
(i) Extreme shock models. In these models, the system fails immediately if a shock exceeds a certain critical threshold, regardless of prior shocks.
-
(ii) Cumulative shock models. Here the cumulative effect of successive shocks determines the system’s failure. A system fails when the total accumulated damage surpasses its endurance limit.
-
(iii) Run shock models. In these models, the system fails when k successive shocks exceeds the prefixed threshold value.
-
(iv)
$ \delta$
-shock models. According to these models, the system fails when the time lag between consecutive shocks is too short or too long. -
(v) Mixed shock models combine characteristics from two or more of the categories above, enabling greater flexibility to describe complex system behaviors.

Some recent contributions can be found in Cha and Finkelstein [Reference Cha and Finkelstein6], Chadjiconstantinidis and Eryilmaz [Reference Chadjiconstantinidis and Eryilmaz8], Farhadian and Jafari [Reference Farhadian and Jafari11], Goyal et al. [Reference Goyal, Xie and Gong14], Ozkut [Reference Ozkut34], Soni et al. [Reference Soni, Pathak, Di Crescenzo and Meoli40], and references therein. We refer to Nakagawa [Reference Nakagawa30] and Cha and Finkelstein [Reference Cha and Finkelstein7] as good sources on this topic.
In the literature, most shock models have been studied under the assumption of the Poisson process; however, this process has its own limitations. For instance, this process has an independent increment property and a stationary increment property. To overcome these limitations, various generalizations of the Poisson process have been considered in the literature. For example, to capture correlation between the increments, researchers modeled shock processes through mixed Poisson processes; see e.g. Cha and Finkelstein [Reference Cha and Finkelstein6], Syuhada et al. [Reference Syuhada, Tjahjono and Hakim41], Goyal et al. [Reference Goyal, Finkelstein and Hazra12], to name a few. One reason for considering these processes is that their increments are positively dependent, and another is that they provide mathematically tractable results. Recently, Goyal et al. [Reference Goyal, Xie and Gong14] have studied a class of shock models under the assumption of a Markovian arrival process.
Due to the complexity of natural phenomena, it is always in the interest of researchers to model the arrival pattern of shocks using a suitable counting process that fits the specific natural setting. For example, as the literature points out, there are many situations in which non-fractional process models perform worse than fractional processes. Therefore it is of natural interest to researchers modeling shock arrivals using fractional counting processes. To the best of our knowledge, Goyal et al. [Reference Goyal, Hazra and Finkelstein13] were first to study shock models based on a fractional renewal process. In this study they examine a class of shock models that includes many known models and apply them to optimal maintenance by considering an optimal age-replacement policy. In this section we are moving one step forward in this direction. Here we consider a general fractional counting process, defined in the previous section, which contains several other known fractional processes as special cases. In this section we use the results from the previous section to study two shock models: extreme and cumulative shock models.
Now we provide a brief description of the system under consideration. Assume the system under consideration operates in a harsh environment and can fail at any time. Shocks (external) are the only reason for system failure. Let S denote the lifetime of the system. Let
 $Z_{i}$
denote the magnitude of the ith shock and let
 $W_{i}$
represent damage given by the ith shock,
 $i \in \mathbb{N}$
. Let the random variable M(t) count the number of shocks in the time interval (0, t],
 $t \geq 0$
. Assume that the sequence
 $\{Y_{i}\colon i \in \mathbb{N} \}$
and
 $\{W_{i}\colon i \in \mathbb{N} \}$
contain independent and identically distributed random variables. Further assume that
 $\{Y_{i}\colon i \in \mathbb{N} \}$
and
 $\{W_{i}\colon i \in \mathbb{N} \}$
are independent of the shock process
 $\{M(t)\colon t \geq 0\}$
, respectively. With these assumptions, we first study the extreme shock model and then the cumulative shock model.
6.1. Extreme shock model
The extreme shock model has received considerable attention in reliability studies. In this model, the system fails if an individual shock exceeds a predefined threshold, such as when a vehicle axle fails after a crack reaches a critical depth. That is, when the magnitude of the ith shock exceeds the predetermined threshold
 $\gamma$
, or
 $\mathbb{P}(Y_{i} \gt \gamma)$
, the system fails at the ith shock, for
 $i \in \mathbb{N}$
. In the following theorem we provide an expression of the reliability function when shocks occur based on the GTCPP-I.
Theorem 5. Let
 $\{M(t)\colon t \geq 0\}$
be a GTCPP-I with the set of parameters
 $\{f(\! \cdot \!), \lambda, \mu \}$
. Then the reliability function of the lifetime of the system is given by
 \begin{align*}\mathbb{P}(S \gt t) = \dfrac{1}{1 + \mu t (1 - {\mathrm{e}}^{-f(\lambda(1- q))} ) }, \end{align*}
where
 $q = \mathbb{P}(Y_{1} \leq \gamma)$
represents the probability of survival of the system from a shock. In addition, the corresponding failure rate can be expressed as
 \begin{align*}r_{S}(t) = \dfrac{\mu (1 - {\mathrm{e}}^{-f(\lambda(1- q))} ) }{1 + \mu t (1 - {\mathrm{e}}^{-f(\lambda(1- q))} ) }. \end{align*}
Proof. Note that according to the extreme shock model, the probability of system survival at time t given that k shocks have arrived by time t can be written as
 \begin{align*}\mathbb{P}(S \gt t\mid M(t) = k) = q^{k}, \quad k = 0,1,2,\dots, \end{align*}
where q is the probability of survival of each shock. Consequently,
 \begin{align*} \mathbb{P}(S \gt t) = \sum_{k=0}^{\infty} q^{k} P(M(t) = k). \end{align*}
From (20), we get
 \begin{align}\mathbb{P}(S \gt t) &= \sum_{k=0}^{\infty} \sum_{n=0}^{\infty} q^{k} \dfrac{1}{1+\mu t} \dfrac{(\!-1)^k}{k!}\dfrac{{\mathrm{d}}^k}{{\mathrm{d}} u^k}{\mathrm{e}}^{-nf(\lambda u)}|_{(u=1)} \biggl(\dfrac{\mu t}{1+\mu t}\biggr)^n \nonumber \\[3pt]&= \sum_{n=0}^{\infty} \dfrac{1}{1+\mu t} \biggl(\dfrac{\mu t}{1+\mu t}\biggr)^n \Biggl(\sum_{k=0}^{\infty} q^{k} \dfrac{(\!-1)^k}{k!}\dfrac{{\mathrm{d}}^k}{{\mathrm{d}} u^k}{\mathrm{e}}^{-nf(\lambda u)}|_{(u=1)}\Biggr).\end{align}
Observe that from Taylor expansion, the expression
 \begin{align*}\sum_{k=0}^{\infty} q^{k} \dfrac{(\!-1)^k}{k!}\dfrac{{\mathrm{d}}^k}{{\mathrm{d}} u^k}{\mathrm{e}}^{-nf(\lambda u)}|_{(u=1)} = {\mathrm{e}}^{-nf(\lambda(1-q))} \end{align*}
holds. Hence, from (25), we can write
 \begin{align*}\mathbb{P}(S \gt t) = \sum_{n=0}^{\infty} \dfrac{1}{1+\mu t} \biggl(\dfrac{\mu t}{1+\mu t}\biggr)^n {\mathrm{e}}^{-nf(\lambda(1-q))}. \end{align*}
After simplifying the above expression, we get the required result for
 $\mathbb{P}(S \gt t)$
. The expression of the failure rate follows directly from the expression of
 $\mathbb{P}(S \gt t).$
In the following remark, we provide an alternative model to study the extreme shock model. The objective is to include this remark to demonstrate the applicability of the multiplicative process (defined in Section 5.3) to shock modeling and to study the system’s lifetime behavior.
Remark 4. Assume that the system under consideration has only two working states, namely 0 and 1. Here state 0 indicates that the system has failed, while state 1 indicates that the system is in working condition. Let
 $\Phi(t)$
be the state of the system at any time
 $t \geq 0$
. Then obviously,
 $\Phi(t) = 0 $
or 1 for
 $t \geq 0$
. Suppose the system is subjected to shocks that can occur at any time. Any shock to the system either fails the system with probability p or has no effect with probability
 $q = 1 - p$
. Let
 $X_{i}$
be the state of the system at the ith shock,
 $i \in \mathbb{N}$
. Hence
 $\mathbb{P}(X_{i} = 1) = q$
and
 $\mathbb{P}(X_{i} = 0) = p$
,
 $i \in \mathbb{N}$
. Therefore the relation
 \begin{align*}\Phi(t) = \prod_{i=1}^{M(t)} X_{i} \end{align*}
holds for any
 $t \geq 0$
. Now, if S represents the system lifetime, then the reliability function of L is given by
 \begin{align*}\mathbb{P}(S \gt t) = \mathbb{P}(\Phi(t) = 1) = \mathbb{E}(\Phi(t)). \end{align*}
Suppose that the shock process
 $\{M(t)\colon t \geq 0\}$
follows the GTCPP-I with the set of parameters
 $\{f(\! \cdot \!), \lambda, \mu \}$
. Then, from (24), we get
 \begin{align*}\mathbb{P}(S \gt t) = \dfrac{1}{1 + \mu t (1 - {\mathrm{e}}^{-f(\lambda(1- q))} ) }, \end{align*}
because
 $\mathbb{E}(X_{1}) = q$
.
Note that the above result generally holds for any choice of function
 $f(\! \cdot \!)$
. Hence the survival function of the system lifetime can be derived for special cases given in (2). For a demonstration of these results we consider
 $f(s) = s^{\alpha}$
(stable subordinator), where
 $0 \lt \alpha \lt 1$
. However, results can be demonstrated for other cases as well. We illustrate our result in Figures 1 and 2. From Figure 1(a), we see that decreasing the parameter q reduces system reliability; this is because q denotes the probability of system survival after a shock, and thus larger values of q enhance system survivability. Figure 1(b) shows that an increase in values of
 $\alpha$
increases system reliability. Further, Figures 1(c) and 1(d) show that an increment in the value of either
 $\lambda$
or
 $\mu$
decreases system reliability. Figure 2 shows a sensitivity analysis of the system’s failure rate; a similar conclusion to the reliability function can be drawn from this figure. For plotting Figures 1 and 2, we consider the same baseline parameters:
 $q = 0.7$
,
 $\alpha = 0.6$
,
 $\lambda = 1$
, and
 $\mu = 1$
. We perform the analysis independently for each parameter while holding the others fixed.
Sensitivity analysis of system reliability for the case when
 $f(s) = s^{\alpha}$
,
 $0 \lt \alpha \lt 1$
, for q (a),
 $\alpha$
(b),
 $\lambda$
(c),
 $\mu$
(d).

Figure 1 Long description
Panel A: A line graph shows the probability P(S>t) over time (t) for different values of q (0.9, 0.8, 0.7). The x-axis represents time (t) ranging from 0 to 100, and the y-axis represents the probability P(S>t) ranging from 0 to 1. The lines are color-coded: blue for q = 0.9, red dashed for q = 0.8, and black dotted for q = 0.7. The probability decreases over time for all values of q. Panel B: A line graph shows the probability P(S>t) over time (t) for different values of alpha (0.2, 0.4, 0.6). The x-axis represents time (t) ranging from 0 to 50, and the y-axis represents the probability P(S>t) ranging from 0 to 1. The lines are color-coded: blue for alpha = 0.2, red dashed for alpha = 0.4, and black dotted for alpha = 0.6. The probability decreases over time for all values of alpha. Panel C: A line graph shows the probability P(S>t) over time (t) for different values of lambda (1, 2, 3). The x-axis represents time (t) ranging from 0 to 50, and the y-axis represents the probability P(S>t) ranging from 0 to 1. The lines are color-coded: blue for lambda = 1, red dashed for lambda = 2, and black dotted for lambda = 3. The probability decreases over time for all values of lambda. Panel D: A line graph shows the probability P(S>t) over time (t) for different values of mu (1, 2, 3). The x-axis represents time (t) ranging from 0 to 50, and the y-axis represents the probability P(S>t) ranging from 0 to 1. The lines are color-coded: blue for mu = 1, red dashed for mu = 2, and black dotted for mu = 3. The probability decreases over time for all values of mu.
6.2. Cumulative shock model
In cumulative shock models, system failure occurs when the accumulated damage from successive shocks surpasses a predefined threshold T. These models are particularly relevant to various real-world applications. For example, the strength of a fibrous carbon composite depends significantly on the strength of its individual fibers, which may break under tensile stress. The composite material ultimately fails due to cumulative damage (see Nakagawa [Reference Nakagawa30, p. 2]). Let
 $M^{*}(t)$
represent the number of shocks by time t and let
 $W_{i}$
denote the damage size of the ith shock,
 $i \in \mathbb{N}$
. If Z(t) represents the total cumulative damage at time t, then, according to the cumulative shock model, Z(t) is described as a random sum,
 \begin{align*}Z(t) = \sum_{i=1}^{M^{*}(t)} W_i, \end{align*}
where it is conventionally assumed that
 $ \sum_{i=1}^{0} Y_i = 0 $
.
Sensitivity analysis of the system’s failure rate for the case when
 $f(s) = s^{\alpha}$
,
 $0 \lt \alpha \lt 1$
, for q (a),
 $\alpha$
(b),
 $\lambda$
(c),
 $\mu$
(d).

In this section we consider a cumulative shock model in which damage size is discrete, with a set of non-negative integers as its support. Such a model may be useful in many real-world applications. Some examples are as follows.
-
(i) In a multi-component system, a shock can fail components of the system. Thus, in this case, the number of failed components can be considered the damage size for a particular shock. If the total number of component failures exceeds a preset threshold, the multi-component system can fail.
-
(ii) Electric vehicle battery packs are composed of numerous individual cells arranged in series and parallel configurations. Each cell contributes a specific amount of voltage and capacity to the overall battery pack. Over time, individual cells may fail completely due to external factors such as thermal or mechanical stress. When a cell fails, it reduces the battery pack’s overall capacity and efficiency. When the battery pack exceeds its tolerance limit, it may be considered failed and require repair or replacement.
In the following theorem, we provide an expression for the system’s reliability function under the cumulative shock model.
Theorem 6. Let us assume that
 $\{M^{*}(t)\colon t \geq 0\}$
is a geometric process with parameters
 $\mu$
and
 $\lambda$
. Further, assume
 $W_{i} \stackrel{d}{=} N_{1}^{f}(1)$
. Suppose T is the threshold of the maximum damage that the system can tolerate. Then the reliability function of S is given by
 \begin{align*} \mathbb{P}(S \gt t) = \sum_{k=0}^{T-1} \dfrac{(\!-1)^k}{k!}\dfrac{{\mathrm{d}}^k}{{\mathrm{d}} u^k}\biggl(\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-f(\lambda u)})}\biggr)_{u=1}. \end{align*}
Proof. First note that, from the definition of the cumulative shock model, the reliability function of the system lifetime and the cumulative damage has the following relation:
 \begin{align}\mathbb{P}(S \gt t) = \mathbb{P}(Z(t) \lt T). \end{align}
Now, from Propositions 3 and 4, we get
 \begin{align*} \mathbb{P}(Z(t) = k) = \dfrac{(\!-1)^k}{k!}\dfrac{{\mathrm{d}}^k}{{\mathrm{d}} u^k}\biggl(\dfrac{1}{1+\mu t(1-{\mathrm{e}}^{-f(\lambda u)})}\biggr)_{u=1}. \end{align*}
Thus the result follows directly from (26).
7. Conclusion
In this work we have developed a general framework for geometric time-changed Poisson processes and their compound and multiplicative extensions, highlighting their distributional and dependence properties, as well as applications to reliability shock models. While our study is set in continuous time, the underlying methodology – time-changing a counting process using the geometric counting process – can be extended to discrete-time settings. In particular, replacing the Poisson process with a Bernoulli counting process or another discrete-time renewal process could yield new classes of discrete-time models that capture clustering, dependence, and heavy-tailed behavior in counts. Such discrete-time analogs may have potential applications in areas such as quality control, software reliability, or event-based simulations, where events occur at discrete time steps, and exploring these extensions presents an interesting avenue for future research.
Acknowledgements
We wish to thank the anonymous referees for their valuable suggestions, which led to significant improvements in this manuscript.
Funding information
There are no funding bodies to thank relating to the creation of this article.
Competing interests
There were no competing interests to declare that arose during the preparation or publication process of this article.


 f(s)=sα
 0<α<1
 α
 λ
 μ

 f(s)=sα
 0<α<1
 α
 λ
 μ


