We partner with a secure submission system to handle manuscript submissions.
Please note:
Click Proceed to submission system to continue to our partner's website.
Let  $\{U(n)\}_{n \geq 0}$ be a sequence of independent random variables such that U(n) is distributed uniformly on
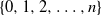 $\{0, 1, 2, \dots, n\}$. The Ulam–Kac adder is the history-dependent random sequence defined by
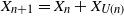 $X_{n + 1} = X_{n} + X_{U(n)}$ with the initial condition
 $X_0 = 1$. We show that for each
 $m \geq 1$,
 $\log \mathbb{E}[X_n^m]/\sqrt{n}$ approaches a constant
 $c_m$ as
 $n \to \infty$. For a given m, a method is provided which allows the high-accuracy numerical computation of
 $c_m$. For arbitrary m, loose bounds are provided.
 $\boldsymbol{L}^{\boldsymbol{q}}$ for
 $1 \lt \boldsymbol{q} \leq 2$
Nerman’s martingale plays a central role in the law of large numbers for both single- and multi-type supercritical general branching processes. There are further, complex-valued Nerman-type martingales in the single-type process that figure in the finer fluctuations of these processes. We construct the analogous martingales for the process with finitely many types and give sufficient conditions for these martingales to converge in  $L^q$ for
 $q \in (1,2]$.
We consider a random right-angled Coxeter group (RACG),  $W_{\Gamma}$, whose presentation graph
 $\Gamma$ is taken to be an Erdős–Rényi random graph, i.e.
 $\Gamma\sim\mathcal{G}_{n,p}$. We use techniques from probabilistic combinatorics to establish several new results about the geometry of this random group model. Resolving a conjecture of Susse, we determine the connectivity threshold for square percolation on the random graph
 $\Gamma\sim\mathcal{G}_{n,p}$. We use this result to determine a large range of p for which the random RACG
 $W_{\Gamma}$ has a unique cubical coarse median structure. Until Fioravanti et al. (2026), there were no non-hyperbolic examples of groups with cubical coarse rigidity. Perhaps surprisingly, we show that the property of coarse cubical rigidity is in fact typically satisfied by a random RACG for a wide range of the parameter p, including
 $p=\frac12$, for which the random RACG is also typically non-hyperbolic.
The join-the-shortest-queue (JSQ) policy is among the most widely used load-balancing algorithms and has been extensively studied. However, an exact characterization of the system behavior remains challenging. Most prior research has focused on analyzing its performance in the steady state in certain asymptotic regimes, such as the heavy-traffic regime. However, convergence to the steady state in these regimes is often slow, so steady-state and heavy-traffic characterizations may be less informative over practical time horizons. To address this limitation, we provide a finite-time convergence rate analysis of a JSQ system with two symmetric servers. In sharp contrast to the existing literature, we directly study the original system rather than an approximate limiting system such as a diffusion approximation. Our results demonstrate that for such a system, the convergence rate to its steady state, measured in the total variation distance, is 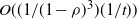 $O((1/(1-\rho)^3)(1/t))$, where
 $\rho \in (0,1)$ is the traffic intensity.
Introduced by Müller et al. in their seminal paper (2017), fractional stochastic dominance (SD) offers a nuanced approach to ordering distributions. In this paper we propose a fundamentally new framework by replacing the fixed parameter  $\gamma \in [0, 1]$ in fractional SD with a function
 $\unicode{x1D6C4}\colon \mathbb{R} \to [0, 1]$. This yields two novel families, multi-fractional stochastic dominance (MFSD) and functional fractional stochastic dominance (FFSD). They enable the ranking of a broader range of distributions and incorporate a more informative utility class, including those with local non-concavities whose steepness varies depending on the location. Furthermore, our framework introduces the concept of partial greediness, which dynamically captures how behaviour of decision makers adapts to changes in wealth. We also extend this framework to encompass almost stochastic dominance. We provide the mathematical foundations of our generalized framework and study how it offers a novel tool for ordering distributions across various settings.
We introduce a new permutation statistic, which we call the k-window statistic, for permutations of  $\{1,2,\ldots, n\}$. The aim is to add to the repertoire of potentially useful tools in the design of efficient algorithms. The k-window statistic counts the number of elements that are at a displacement at most k from their natural positions in the ascendingly sorted permutation. We find the exact mean and exact variance of the k-window statistic, revealing phases in the mean and variance in the different regimes of k. We find a weak (or even strong) law of large numbers in the regime where
 $k=k_n$ is growing but remains
 ${\mathrm{o}} (n)$. Via a representation of the statistic into dependent heterogeneous weakly correlated indicators, we establish the complete spectrum of distributions as
 $k_n$ spans its entire range using an appropriate method for each regime.
 $\textit{k}$-degree neural networks via scale regularization
Neural networks have been widely used in data analysis, but there is relatively little research on the statistical theory of neural networks. In this paper we generalize the scale regularization method to the k-degree neural networks, and obtain a statistical guarantee for estimators with a least-squares term and a regularizer. On this basis, we exemplify this guarantee with locally Lipschitz activation functions and  $l_{\beta}$-regularization for
 $\beta\in[1,2]$ in the case
 $k>1$, showing that the corresponding prediction error decrease is of the order of
 $n^{-{{1}/{2}}}$ in the sample size n.
Let 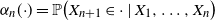 $\alpha_n({\cdot})=\mathbb{P}\bigl(X_{n+1}\in{\cdot}\mid X_1,\ldots,X_n\bigr)$ be the predictive distributions of a sequence
 $(X_1,X_2,\ldots)$ of p-dimensional random vectors. Suppose
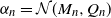 $\alpha_n=\mathcal{N}(M_n,Q_n)$, where
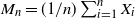 $M_n=({1}/{n})\sum_{i=1}^nX_i$ and
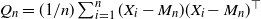 $Q_n=({1}/{n})\sum_{i=1}^n(X_i-M_n)(X_i-M_n)^{\top}$. Then there is a random probability measure
 $\alpha$ on the Borel subsets of
 $\mathbb{R}^p$ such that
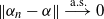 $\lVert\alpha_n-\alpha\rVert\overset{\mathrm{a.s.}}\longrightarrow 0$, where
 $\lVert{\cdot}\rVert$ is the total variation distance. An explicit expression for
 $\alpha$ is provided and the convergence rate of
 $\lVert\alpha_n-\alpha\rVert$ is shown to be arbitrarily close to
 $n^{-1/2}$. Moreover, it is still true that
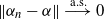 $\lVert\alpha_n-\alpha\rVert\overset{\mathrm{a.s.}}\longrightarrow 0$ even if
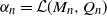 $\alpha_n=\mathcal{L}(M_n,Q_n)$, where
 $\mathcal{L}$ belongs to a class of distributions much larger than the normal. The predictives
 $\alpha_n$ are useful in various frameworks, including Bayesian predictive inference and predictive resampling. Finally, the asymptotic behavior of copula-based predictive distributions is investigated and a numerical experiment is performed.