


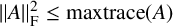

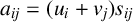
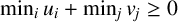

1 Introduction
Let
$\Omega _n$
 be the Birkhoff polytope of
$n\times n$
 doubly stochastic matrices and set

Equivalently,
$\mathrm {maxtrace}(A)$
 is the optimal value of the assignment problem with A as its cost matrix; we discuss this interpretation in more detail in Section 3.
Marcus and Ree [Reference Marcus and Ree8] proved that

where

denotes the Frobenius norm. Upon learning of this result, Erdős asked for a characterisation of the matrices for which equality holds in (1.1) (see [Reference Bouthat, Mashreghi and Morneau-Guérin4, Reference Marcus and Ree8]). Thus, the problem is to determine all
$A\in \Omega _n$
 satisfying

Following terminology introduced by Tripathi [Reference Tripathi10], we call the matrices satisfying (1.2) Erdős matrices.
The question has received renewed attention. The
$3\times 3$
 case was classified by Bouthat et al. [Reference Bouthat, Mashreghi and Morneau-Guérin4]. Tripathi [Reference Tripathi10] subsequently proved that there are only finitely many Erdős matrices in each dimension, and that all of them are rational and have an algorithmic characterisation. The
$4\times 4$
 case was later classified by Kushwaha and Tripathi [Reference Kushwaha and Tripathi7].
Most relevant here is the recent work of Karmakar et al. [Reference Karmakar, Krishna, Pal and Krishna Teja6]. They prove that every Erdős matrix belongs to the class of restricted common diagonal sum (RCDS) matrices studied by Brualdi and Dahl [Reference Brualdi and Dahl5]. Questions concerning prescribed diagonal sums of doubly stochastic matrices go back several decades. Wang [Reference Wang11] studied maximal and minimal diagonal sums, while constant diagonal sums were considered by Sinkhorn [Reference Sinkhorn9], Achilles [Reference Achilles1] and Balasubramanian [Reference Balasubramanian2, Reference Balasubramanian3]. The RCDS matrices of Brualdi and Dahl [Reference Brualdi and Dahl5] belong to this line of work. A permutation
$\sigma $
 is inner for A if
$a_{i,\sigma (i)}>0$
 for every i, and outer otherwise; A is RCDS when all inner permutation diagonals have the same sum.
For a fully indecomposable skeleton
$S=(s_{ij})$
 , by which we mean the pattern of the matrix (see Section 2 for the precise definition), Brualdi and Dahl show that an RCDS matrix has the form

for some real vectors
$u=(u_1,\ldots ,u_n)$
 and
$v=(v_1,\ldots ,v_n)$
 . We call u and v the additive potentials and the quantities
$u_i+v_j$
 the cross-sums. Although the potentials themselves are not unique, the cross-sums are uniquely determined. Karmakar et al. derive the criterion

for every outer permutation
$\sigma $
 and, in particular, record

as a sufficient condition for Erdős-ness [Reference Karmakar, Krishna, Pal and Krishna Teja6, Lemma 1.6].
Our main result is that, for a fully indecomposable RCDS matrix, (1.3) is also necessary:

The proof also yields a constructive interpretation: if
$u_i+v_j<0$
 at a zero position, full indecomposability produces an outer permutation using that zero and no other one, whose diagonal sum exceeds
$\|A\|_{\mathrm F}^2$
 . Thus, the aggregate inequalities of [Reference Karmakar, Krishna, Pal and Krishna Teja6] collapse to pointwise sign conditions. This gives a practical recognition procedure as well. After decomposing a doubly stochastic matrix into fully indecomposable blocks, one solves the linear system (2.3) on each block, verifies that the resulting cross-sums reproduce the block and checks the sign condition
${\min _i u_i+\min _jv_j\geq 0}$
 ; no maxtrace computation is required. Moreover, when the sign condition fails, Proposition 3.4 produces an explicit permutation certifying the failure of Erdős-ness. Finally, applying the criterion blockwise gives a characterisation of Erdős matrices in arbitrary dimension.
2 RCDS matrices and additive potentials
For a nonnegative matrix
$A=(a_{ij})$
 , write
$\mathrm {skel}(A)=(s_{ij})$
 , where
$s_{ij}=1$
 if
$a_{ij}>0$
 and
$s_{ij}=0$
 otherwise. Every doubly stochastic matrix has total support: each positive position belongs to an inner permutation by the Birkhoff–von Neumann theorem.
Lemma 2.1. Suppose
$A\in \Omega _n$
 and
$ a_{ij}=(u_i+v_j)s_{ij}, $
 where
$u=(u_1,\ldots ,u_n)$
 and
${v=(v_1,\ldots ,v_n)}$
 are real vectors and
$S=\mathrm {skel}(A)$
 . Then,

and, for every
$\sigma \in S_n$
 ,

In particular, A is RCDS.
Proof. Since
$a_{ij}^2=(u_i+v_j)a_{ij}$
 for all
$i,j$
 , the row and column sums give (2.1). In addition,

and the first sum equals
$\sum _i u_i+\sum _jv_j$
 . This proves (2.2); for an inner permutation, the second sum is empty.
The following proposition is essentially the structural result of Brualdi and Dahl [Reference Brualdi and Dahl5, Theorem 2.6]; see also the formulation of Karmakar et al. [Reference Karmakar, Krishna, Pal and Krishna Teja6, Theorem 1.4].
Proposition 2.2. Let
$S=(s_{ij})$
 be fully indecomposable. Put
$r_i=\sum _js_{ij}$
 ,
$c_j=\sum _is_{ij}$
 ,
$D_R=\mathrm {diag}(r_i)$
 and
$D_C=\mathrm {diag}(c_j)$
 . The system

is solvable and any two solutions differ by
$u\mapsto u+t\mathbf 1$
 ,
$v\mapsto v-t\mathbf 1$
 . Moreover, S is the skeleton of an RCDS doubly stochastic matrix if and only if

and then that matrix is uniquely determined by
$a_{ij}=(u_i+v_j)s_{ij}$
 .
Proof. The coefficient matrix in (2.3) is the signless Laplacian of the bipartite graph with biadjacency matrix S.
This graph is connected. Indeed, if it were disconnected, its vertex set would split into two nonempty parts with no edges between them; let I be the set of rows and J the set of columns lying in one of the parts. Then,
$S[I,J^{c}]=0$
 and
$S[I^{c},J]=0$
 . The dimension sums of these two zero submatrices add up to
$2n$
 , so one of them is at least n; shrinking that submatrix if necessary yields an
$r\times s$
 all-zero submatrix with
$r+s=n$
 , which contradicts full indecomposability. Since the graph is connected and bipartite, the kernel of the coefficient matrix is spanned by
$(\begin {smallmatrix}\mathbf {1}\\-\mathbf {1}\end {smallmatrix})$
 ; since the right-hand side of (2.3) is orthogonal to this vector, the system is solvable and its solutions have exactly the stated ambiguity. Equation (2.3) is equivalent to the row and column sums of
$(u_i+v_j)s_{ij}$
 being
$1$
 . Positivity on the support therefore gives an RCDS matrix by Lemma 2.1, and the converse and uniqueness follow from the additive representation and invariance of the cross-sums.
Proposition 2.3 (Karmakar et al. [Reference Karmakar, Krishna, Pal and Krishna Teja6, Proposition 2.7]).
Every Erdős matrix is RCDS.
3 The potential criterion
3.1 Assignment duality
For a real
$n\times n$
 matrix
$C=(c_{ij})$
 we write, as in Section 1,

The maximum assignment problem for C is

and its dual is

Since the extreme points of
$\Omega _n$
 are the permutation matrices, the optimum in (3.1) is
$\mathrm {maxtrace}(C)$
 .
For an RCDS matrix A, the potentials
$u,v$
 are dual feasible for the assignment problem restricted to the support of A: on the support,
$ u_i+v_j=a_{ij}. $

Passing to the unrestricted assignment problem adds the constraints

This gives the following criterion.
Theorem 3.1. Let
$A\in \Omega _n$
 be RCDS with fully indecomposable skeleton
$S=(s_{ij})$
 and let
$u,v$
 be its additive potentials, so that
$ a_{ij}=(u_i+v_j)s_{ij}. $
 The following conditions are equivalent:
-
(i) A is an Erdős matrix;
-
(ii) $(u,v)$
 is feasible for the assignment dual (3.2) with
$C=A$
;
-
(iii) $u_i+v_j\geq 0$
whenever
$s_{ij}=0$
; -
(iv) $u_i+v_j\geq 0$
for all
$i,j$
; -
(v) $\min _i u_i+\min _jv_j \geq 0$
.


Proof. We first prove that conditions (ii)–(v) are equivalent. On the support of A,

so the dual constraints in (3.2) hold there with equality. At a zero position, they reduce to
$u_i+v_j\geq 0$
 . Thus, conditions (ii) and (iii) are equivalent. Since the cross-sums are already positive on the support, condition (iii) is in turn equivalent to condition (iv). Finally,

so conditions (iv) and (v) are equivalent.
Suppose now that condition (ii) holds. Weak duality for (3.1)–(3.2) with
$C=A$
 and Lemma 2.1 give

The reverse inequality is precisely the Marcus–Ree inequality (1.1). Hence,

and condition (i) follows.
Conversely, suppose that condition (i) holds and let
$(\alpha ,\beta )$
 be an optimal solution of the assignment dual (3.2) with
$C=A$
 . Since A is doubly stochastic, every position
$(i,j)$
 with
$s_{ij}=1$
 belongs to an inner permutation (see Section 2). By Lemma 2.1, every such inner permutation has diagonal sum

and is, therefore, optimal for the primal assignment problem. Complementary slackness then gives

The bipartite graph associated with S is connected, as shown in the proof of Proposition 2.2. Rewriting (3.3) as

on every edge, connectedness implies that there exists
$t\in \mathbb {R}$
 such that

Consequently,

At a zero position, dual feasibility therefore yields

Thus, condition (iii) holds, which completes the proof.
Remark 3.2. Theorem 3.1 says that the potentials for the support-restricted assignment problem remain dual feasible for the unrestricted problem exactly when A is Erdős. It also sharpens [Reference Karmakar, Krishna, Pal and Krishna Teja6, Lemma 1.6]: for a fully indecomposable skeleton, the inequalities over the zero positions of outer permutations reduce to the pointwise conditions
$u_i+v_j\geq 0$
 . The next proposition gives a constructive explanation.
3.2 A constructive cycle proof
The duality argument proves the criterion, but does not produce a permutation witnessing its failure. We now give such a construction.
Fix an inner permutation of A and permute the columns of A so that it becomes the identity, so that

This permutation of the columns permutes the entries of v and relabels the positions accordingly; it affects neither the hypotheses nor the conclusions below, so we may assume throughout this subsection that it has been carried out. Associate with S the directed graph
$D_S$
 on
$\{1,\ldots ,n\}$
 , defined by

Lemma 3.3. If S is fully indecomposable, then
$D_S$
 is strongly connected.
Proof. Suppose that
$D_S$
 is not strongly connected. Then, we may choose a vertex k from which not every vertex is reachable. Let I be the set of vertices reachable from k. Then, I is nonempty and proper, and no edge can leave I, since the endpoint of such an edge would also be reachable from k. Hence,

Thus, S contains an all-zero submatrix of size
$|I|\times (n-|I|)$
 , which contradicts full indecomposability.
The lemma allows us to isolate any single zero position.
Proposition 3.4. Under the hypotheses of Theorem 3.1, let
$(i,j)$
 be a zero position of S. Then, there exists a permutation
$\sigma \in S_n$
 for which
$(i,j)$
 is the only zero position among

Consequently, if
$u_i+v_j<0$
 , then

In particular,
$\sigma $
 certifies that A is not Erdős.
Proof. Since
$s_{ii}=1$
 , we have
$i\neq j$
 . By Lemma 3.3, there is a directed path from j to i. Choose a simple such path,

Define
$\sigma $
 by

and let
$\sigma (k)=k$
 for all remaining indices.
Every position used by
$\sigma $
 lies in the support of S, except for the closing position
$(i,j)$
 . Hence,
$(i,j)$
 is the unique zero position used by
$\sigma $
 . The defect identity (2.2) therefore gives

If
$u_i+v_j<0$
 , the right-hand side is strictly larger than
$\|A\|_{\mathrm {F}}^{2}$
 , as claimed.

4 Skeleton and blockwise characterisations
The potential criterion can be stated directly in terms of the skeleton.
Theorem 4.1. Let
$S=(s_{ij})$
 be a fully indecomposable zero–one matrix and let
$u,v$
 solve (2.3). Then, S is the skeleton of an Erdős matrix if and only if


Under (4.1), condition (4.2) is equivalent to
$\min _i u_i+\min _jv_j\geq 0$
 . When these conditions hold, the unique Erdős matrix with skeleton S is

Proof. Proposition 2.2 gives the RCDS matrix with skeleton S exactly under (4.1); Theorem 3.1 then gives Erdős-ness exactly under (4.2). Conversely, every Erdős matrix is RCDS by Proposition 2.3, so the same two results give the necessity and uniqueness. Finally, under (4.1), (4.2) is equivalent to nonnegativity of all cross-sums and

Remark 4.2. The uniqueness assertion in Theorem 4.1 is also a special case of [Reference Karmakar, Krishna, Pal and Krishna Teja6, Theorem 1.8], which shows that a given skeleton carries at most one Erdős matrix; the present proof has the advantage of exhibiting
$E(S)$
 explicitly.
Every
$A\in \Omega _n$
 has total support; hence, after row and column permutations,

where the
$A_k$
 are fully indecomposable doubly stochastic blocks [Reference Brualdi and Dahl5].
Lemma 4.3. If
$A=A_1\oplus \cdots \oplus A_m$
 , then

Hence, A is Erdős if and only if every
$A_k$
 is Erdős.
Proof. The norm identity is immediate. Maximising separately in each block gives one inequality. Conversely, any permutation of A selects a partial matching in each block; extending it to a permutation of the full row and column index sets of that block cannot decrease its weight, since the entries are nonnegative. Thus, its contribution from
$A_k$
 is at most
$\mathrm {maxtrace}(A_k)$
 . The last assertion follows from (1.1) applied blockwise.
Theorem 4.4. Let
$PAQ{\kern-1pt}={\kern-1pt}A_1\oplus \cdots \oplus A_m$
 be the above decomposition and
${S_k{\kern-1pt}={\kern-1pt}\mathrm {skel}(A_k)}$
 . For each k, let
$u^{(k)},v^{(k)}$
 solve (2.3) for
$S_k$
 . Then, A is Erdős if and only if, for every k,

Proof. If A is Erdős, Lemma 4.3 makes every
$A_k$
 Erdős and Proposition 2.3, together with Theorem 3.1, gives the stated conditions.
Conversely, the first condition gives the additive representation of each
$A_k$
 , so Lemma 2.1 shows that
$A_k$
 is RCDS. The second condition and Theorem 3.1 then make each
$A_k$
 Erdős, and Lemma 4.3 completes the proof.
5 Examples and consequences
Consider the matrix

whose row and column sums are all equal to
$1$
 , and whose skeleton is

One checks directly that S has no all-zero submatrix of size
$r\times s$
 with
$r+s=5$
 , so S is fully indecomposable. A solution of the system (2.3) is given by

Every cross-sum at a support position is positive and reproduces the corresponding entry,

so E is RCDS by Lemma 2.1. At two of the zero positions, however,

and Theorem 3.1 shows at once that E is not an Erdős matrix.
Proposition 3.4 converts either violation into an explicit permutation. Starting from the zero position
$(4,3)$
 and the inner permutation
$(2,3,1,5,4)$
 , the construction returns

in one-line notation, which uses the position
$(4,3)$
 and no other zero position. Its diagonal sum is

whereas

The excess is

exactly as predicted by (3.4).
5.1 Adding one support entry can destroy the property
Call a zero–one matrix an Erdős skeleton if it is the skeleton of an Erdős matrix.
The class of Erdős skeletons is not upward closed.
Proposition 5.1. There are fully indecomposable zero–one matrices
$S<S'$
 such that
$S'$
 is obtained from S by changing a single
$0$
 into a
$1$
 , S is an Erdős skeleton and
$S'$
 is not.
Proof. Take

Both are fully indecomposable. For S, the potentials

solve (2.3); they are positive on the support and all cross-sums are nonnegative, so S is an Erdős skeleton by Theorem 4.1. Passing from S to
$S'$
 increases only the first row and column degrees. Since
$u_1+v_1=0$
 , the same
$u,v$
 still solve (2.3) for
$S'$
 . However, now
$(1,1)$
 belongs to the support and its cross-sum is
$0$
 , violating the strict positivity required in Theorem 4.1. Thus,
$S'$
 is not an Erdős skeleton.
6 Conclusion
The characterisation obtained above reduces Erdős-ness to a linear-algebraic sign test on the fully indecomposable blocks of the skeleton. In particular, it replaces the global maxtrace condition by the local requirement that all cross-sums
$u_i+v_j$
 are nonnegative, and a negative cross-sum yields an explicit permutation witnessing the failure of equality in the Marcus–Ree inequality.
Acknowledgements
The author is grateful to L. Bouthat, J. Mashreghi and S. Singh for previous collaborations.


