


 . When

 and its norm-closure
 . In the infinite-dimensional setting, we characterise the intersection of
 with the set of biquasitriangular operators, and we exhibit an index obstruction to belonging to
 .

1 Introduction
1.1. Throughout this paper,
$\mathcal H$
 will denote a complex, separable Hilbert space. Denote by
$\mathcal B ( \mathcal H)$
 the algebra of bounded linear operators acting on
$\mathcal H$
 , and by
$\mathcal K ( \mathcal H)$
 the closed-two sided ideal of
$\mathcal B ( \mathcal H)$
 consisting of compact operators. If
$A \in \mathcal B ( \mathcal H)$
 (and more generally, if
$A \in \mathcal A$
 , a unital Banach algebra), we denote the spectrum of A by
$\sigma (A) := \{ \alpha \in \mathbb C: A - \alpha I \text { is not invertible}\}$
 . If
$\sigma (A) = \{ 0\}$
 , we say that A is quasinilpotent.
Given
$A, B \in \mathcal B ( \mathcal H)$
 , the commutator of A and B is the element
$[A, B] := A B - B A$
 . When
$\dim \, \mathcal H = n < \infty $
 , we find that
$\mathcal H$
 is isomorphic to
$\mathbb C^n$
 , and a classical result of Albert and Muckenhoupt [Reference Albert and Muckenhoupt1] asserts that
$T \in \mathcal B ( \mathcal H) \simeq \mathbb M_n(\mathbb C)$
 is a commutator if and only if the trace of T is zero. When
$\dim \, \mathcal H = \infty $
 , a result of Brown and Pearcy [Reference Brown and Pearcy8] shows that an operator
$T \in \mathcal B ( \mathcal H)$
 is a commutator if and only if T is not of the form
$\lambda I + K$
 , where
$0 \ne \lambda \in \mathbb C$
 and
$K \in \mathcal K ( \mathcal H)$
 .
There is a significant literature which seeks to classify the set of commutators in various ideals of
$\mathcal B ( \mathcal H)$
 [Reference Anderson2, Reference Beltiţă, Patnaik and Weiss6, Reference Dykema and Krishnaswamy-Usha13, Reference Weiss38–Reference Weiss40], as well as commutators (and their spans) in various operator algebras [Reference Dykema and Skripka14, Reference Fack15, Reference Kaftal, Ng and Zhang23, Reference Marcoux25, Reference Marcoux26, Reference Robert36]. A fascinating but difficult open question is to completely characterise the set
$[\mathcal K ( \mathcal H), \mathcal K ( \mathcal H)] := \{ K L - L K: K, L \in \mathcal K ( \mathcal H) \}$
 .
In recent years, there has been growing interest in characterising

where
$\Omega \subseteq \mathcal B ( \mathcal H)$
 is a fixed set of operators (e.g., [Reference Drnovšek, Radjavi and Rosenthal12, Reference Marcoux, Radjavi and Zhang27, Reference Marcoux, Radjavi and Zhang28, Reference Radjavi and Rosenthal35]). In the infinite-dimensional setting, this problem can often be intractable. Part of the reason for this is that when
$\Omega $
 is invariant under similarity (i.e.,
$A \in \Omega $
 implies that
$S^{-1} A S \in \Omega $
 for all invertible operators
$S \in \mathcal B ( \mathcal H)$
 ), then so is
$\mathfrak {c}(\Omega )$
 . The problem is that similarity-invariant subsets of
$\mathcal B ( \mathcal H)$
 are in general poorly understood. However, the work of Apostol, Fialkow, Herrero, and Voiculescu [Reference Apostol, Fialkow, Herrero and Voiculescu3] and others establishes an interesting framework for characterising the norm-closures of similarity-invariant sets in terms of readily verifiable data (such as spectrum, rank, and semi-Fredholm index as defined below). For this reason, when considering infinite-dimensional Hilbert spaces, we shall focus our attention on characterising the set
 .
For example, in the papers [Reference Marcoux, Radjavi and Zhang27, Reference Marcoux, Radjavi and Zhang28], the authors studied the case where
$\Omega = \mathfrak E := \{ E \in \mathcal B ( \mathcal H): E = E^2\}$
 , characterising
$\mathfrak {c}(\mathfrak E)$
 and
 when
$\dim \, \mathcal H < \infty $
 , as well as the intersection of
$\mathfrak {c}(\mathfrak E)$
 with the set
 of biquasitriangular operators (defined in Paragraph 1.7 below) in the infinite-dimensional setting.
In the present paper, we consider a second instance of this problem. Let

denote the set of square-zero operators in
$\mathcal B ( \mathcal H)$
 . When
$\dim \, \mathcal H < \infty $
 , we are able to completely characterise both
 and
 . Paralleling our work on commutators of idempotents, when
$\dim \, \mathcal H = \infty $
 , we are able to characterise the intersection of
 with the set
 , obtaining the surprising result that

We next gather a number of definitions and relevant results that we shall require below.
1.2. Remark. We have obliquely alluded to the fact that the set  is similarity-invariant. Indeed, let
$\mathcal H$
 be a Hilbert space, and suppose that
$T \in \mathcal B ( \mathcal H)$
 lies in
 . Choose
 such that
$T = [M, N]$
 . If
$S \in \mathcal B ( \mathcal H)$
 is invertible. Then

and
$(S^{-1} M S)^2 = 0 = (S^{-1} N S)^2$
 . In other words, the following are equivalent:
-
•
 ;
-
• there exists $S \in \mathcal B ( \mathcal H)$
invertible such that ; -
•
.
 ;

 ;
 .
Given
$A, B \in \mathcal B ( \mathcal H)$
 , let us write
$A \sim B$
 to indicate that A and B are similar. Suppose that
$\dim \, \mathcal H = n <\infty $
 . Given
$T \in \mathcal B(\mathbb C^n)$
 , by considering the Jordan form of T, we see that we may write
$T \sim B \oplus Q$
 , where B is invertible and Q is nilpotent. The above observation implies that
 if and only if
 , and our arguments below will often start with the assumption that T is of the form
$B \oplus Q$
 .
We point out that the same reasoning may be applied to the class  . Thus, the following are equivalent:
-
•
; -
• there exists $S \in \mathcal B ( \mathcal H)$
invertible such that ; -
•
.
 ;

 ;
 .
A second well-studied equivalence relation on
$\mathcal B ( \mathcal H)$
 is that of approximate unitary equivalence. Two operators
$A, B \in \mathcal B ( \mathcal H)$
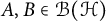 are said to be approximately unitarily equivalent if there exists a sequence
$(U_n)_n$
 of unitary operators acting on
$\mathcal H$
 such that
$B = \lim _n U_n^* A U_n$
 . As we shall see below (see Example 4.5), although
 is invariant under approximate unitary equivalence,
 is not.
1.3. In light of the comments above, in the finite-dimensional setting, nilpotent Jordan cells will play a central role in obtaining our characterisation of  . We denote by
$J_n$
 the usual Jordan cell in
$\mathcal B(\mathbb C^n)$
 , and more generally we shall write J to denote a (finite) direct sum of Jordan cells. At times, we shall express an operator
 as a direct sum
$T = T_1 \oplus T_2$
 of operators, each of which is a commutator of square-zero operators (acting on subspaces of the space
$\mathcal H$
 upon which T acts). In order to keep the notation as simple as possible, we shall say that
$T_1, T_2$
 and
 , although the three operators may be acting on spaces of different dimensions.
An easy but useful example of an element in  is an operator of the form

where
$X \in \mathcal B ( \mathcal H)$
 is arbitrary. It is an easy exercise to verify that a finite direct sum of elements of
 again lies in
 , and we shall implicitly apply this observation below. In particular, this shows that
 for all
$X \in \mathcal B ( \mathcal H)$
 .
1.4. Remark. A second simple but useful observation, which we shall frequently use, is the following. If  , say
$T = [M, N]$
 , where
$M^2 = 0 = N^2$
 , then

1.5. Let
$\mathcal H$
 and
$\mathcal K$
 be Hilbert spaces,
$A \in \mathcal B ( \mathcal H)$
 and
$B \in \mathcal B(\mathcal K)$
 . We define the Rosenblum operator

The following result, due to Rosenblum, will prove very useful. Its proof may be found in [Reference Herrero19, Corollary 3.20].
1.6. Theorem (Rosenblum). Let
$\mathcal H$
 and
$\mathcal K$
 be Hilbert spaces,
$A \in \mathcal B ( \mathcal H)$
 and
$B \in \mathcal B(\mathcal K)$
 . Then

In particular, if
$\sigma (A) \cap \sigma (B) = \varnothing $
 , then
$\tau _{A, B}$
 is invertible.
Consequently, if
$A \in \mathcal B ( \mathcal H)$
 ,
$B \in \mathcal B(\mathcal K)$
 and
$Y \in \mathcal B(\mathcal K, \mathcal H)$
 , and if
$\sigma (A) \cap \sigma (B) = \varnothing $
 , then

acting on
$\mathcal H \oplus \mathcal K$
 are similar.
Let us now define the set of biquasitriangular operators mentioned above, as well as the set of balanced operators, which will play a role in Section 4 of the paper.
1.7. Let
$\pi : \mathcal B ( \mathcal H) \to \mathcal B ( \mathcal H)/\mathcal K ( \mathcal H)$
 denote the canonical quotient map from
$\mathcal B ( \mathcal H)$
 into the Calkin algebra. Given
$T \in \mathcal B ( \mathcal H)$
 , the essential spectrum of T is the spectrum of
$\pi (T)$
 in the Calkin algebra. We say that T is semi-Fredholm if
$\pi (T)$
 is either left- or right-invertible in the Calkin algebra, and that T is Fredholm if
$\pi (T)$
 is invertible in
$\mathcal B ( \mathcal H)/\mathcal K ( \mathcal H)$
 . The semi-Fredholm domain of T is the set

and if
$\alpha \in \rho _{\text {s-F}}(T)$
 , we define the semi-Fredholm index of
$T-\alpha I$
 as

It is well-known that this is well-defined and lies in
$\mathbb Z \cup \{-\infty , \infty \}$
 , as at least one of
 and
 is finite when
$\alpha \in \rho _{\text {s-F}}(T)$
 .
An operator
$T \in \mathcal B ( \mathcal H)$
 is said to be biquasitriangular if
 whenever
$\alpha \in \rho _{\text {s-F}}(T)$
 . Although this is not the original definition of biquasitriangularity (see, for example, [Reference Marcoux, Radjavi and Zhang27, Paragraph 4.1]), it is known to be equivalent to it [Reference Apostol, Foiaş and Voiculescu4, Corollary 5.5], and it is the most practical form of the property with which to work. We denote by
 the set of biquasitriangular operators in
$\mathcal B ( \mathcal H)$
 .
The next definition played a crucial role in the study of
$\mathfrak {c}(\mathfrak E)$
 and its closure [Reference Marcoux, Radjavi and Zhang28], and we shall also require it here.
1.8. Definition. Let
$T \in \mathcal B ( \mathcal H)$
 . We say that T is balanced if
-
(a) $\sigma (T) = \sigma (-T)$
; -
(b) whenever $\Omega _1, \Omega _2 \subseteq \mathbb C$
are disjoint open sets such that
$\sigma (T) \subseteq \Omega _1 \cup \Omega _2$
, then $$\begin{align*}\dim\, \mathcal H(\Omega_1; T) = \dim\, \mathcal H(-\Omega_1; T), \end{align*}$$where $\mathcal H(\Omega _1;T)$
is the generalised eigenspace (i.e., the range of the corresponding Riesz idempotent
$E(\Omega _1;T)) $
corresponding to
$\sigma (T) \cap \Omega _1$
;
-
(c) if $\alpha \in \mathbb C$
, then
$T - \alpha I$
is semi-Fredholm if and only if
$T + \alpha I$
is semi-Fredholm, in which case


We denote the set of balanced operators on
$\mathcal H$
 by
 .
We shall refer to an operator satisfying conditions (a) and (b) as weakly balanced, and we denote that set of operators by  .
1.9. We recall from [Reference Marcoux, Radjavi and Zhang28, Proposition 3.3] that if
$\dim \, \mathcal H < \infty $
 , then

where
$\mu (\alpha )$
 denotes the algebraic multiplicity of the eigenvalue
$\alpha \in \sigma (T)$
 .
2 Structure results for elements of

2.1. In this section, we establish a number of results concerning elements of  . In particular, we shall characterise those invertible operators and those normal operators which lie in
 .
Our first result will be of particular relevance in the finite-dimensional setting where, by considering Jordan decompositions, we see that every operator in
$\mathcal B(\mathbb C^n)$
 is similar to a direct sum of an invertible operator B with a nilpotent operator J.
2.2. Proposition. Let
$\mathcal H$
 be a Hilbert space and suppose that
$T \sim A \oplus B \in \mathcal B ( \mathcal H)$
 , where
$\sigma (A^2) \cap \sigma (B^2) = \varnothing $
 . The following statements are equivalent:
-
(a)
. -
(b)
and .
 .
 and
 .
Proof By Remark 1.2, we may suppose without loss of generality that
$T = A \oplus B$
 , and so we decompose the underlying Hilbert space as
$\mathcal H = \mathcal H_A \oplus \mathcal H_B$
 , where
$A \in \mathcal B(\mathcal H_A)$
 ,
$B \in \mathcal B(\mathcal H_B)$
 , and
$\sigma (A^2) \cap \sigma (B^2) = \varnothing $
 .
-
(a) implies (b). The hypothesis that
allows us to choose square-zero operators
$M,N \in \mathcal B ( \mathcal H)$
such that
$T=MN-NM$
. Routine calculations show that $$\begin{align*}T^2 M = M N M N M = M T^2, \end{align*}$$and
$$\begin{align*}T^2 N = N M N M N = N T^2.\end{align*}$$
With respect to the decomposition $\mathcal H = \mathcal H_A \oplus \mathcal H_B$
, we write $$\begin{align*}M=\begin{bmatrix}M_1& M_2 \\ M_3& M_4 \end{bmatrix},~~N=\begin{bmatrix}N_1& N_2 \\ N_3& N_4 \end{bmatrix}.\end{align*}$$
By comparing the $(1,2)$
and the
$(2,1)$
entries of
$T^2M$
and
$MT^2$
, we conclude that $$\begin{align*}A^2 M_2=M_2 B^2,~~B^2 M_3= M_3 A^2.\end{align*}$$
Since $\sigma (A^2) \cap \sigma (B^2) =\varnothing $
, by Theorem 1.6, the corresponding Rosenblum operators
$\tau _{A^2, B^2}$
and
$\tau _{B^2, A^2}$
are injective. From this, we conclude that
$M_2 = 0 = M_3$
, so that
$M = M_1 \oplus M_4$
. Similarly,
$N = N_1 \oplus N_4$
. Since
$M^2 = 0 = N^2$
, we conclude that
$M_1, M_4, N_1$
, and
$N_4$
are all nilpotent of order at most two.But $T = [M, N]$
, and thus,
$A = [M_1, N_1]$
and
$B = [M_4, N_4]$
lie in . -
(b) implies (a). If $A = [M_1, N_1]$
and
$B = [M_2, N_2]$
, where
$M_i^2 = 0 = N_i^2$
,
$i = 1, 2$
, then
$(M_1 \oplus M_2)^2 = 0 = (N_1 \oplus N_2)^2$
and $$\begin{align*}T = [(M_1 \oplus M_2), (N_1 \oplus N_2)].\\[-34pt] \end{align*}$$
 allows us to choose square-zero operators

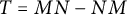


 .


2.3. Let
$\mathcal H$
 be an infinite-dimensional, separable Hilbert space and
$\mathcal M_1$
 ,
$\mathcal M_2$
 be infinite-dimensional subspaces of
$\mathcal H$
 such that
$\mathcal M_2 = \mathcal M_1^\perp $
 . Given
$T \in \mathcal B ( \mathcal H)$
 , write
$T = \begin {bmatrix} T_{11} & T_{12} \\ T_{21} & T_{22} \end {bmatrix}$
 relative to the decomposition
$\mathcal H = \mathcal M_1 \oplus \mathcal M_2$
 . Since
$\mathcal M_1, \mathcal M_2$
 and
$\mathcal H$
 are isomorphic as Hilbert spaces, this allows us to identify
$\mathcal B ( \mathcal H) = \mathcal B(\mathcal M_1 \oplus \mathcal M_2)$
 with
$\mathcal B(\mathcal H \oplus \mathcal H)$
 . In other words, up to Hilbert space isomorphism and the usual identification of
$\mathcal B(\mathcal H \oplus \mathcal H)$
 with
$\mathbb M_2(\mathcal B ( \mathcal H))$
 , there is no harm in assuming that
$T_{ij} \in \mathcal B ( \mathcal H)$
 ,
$1 \le i, j \le 2$
 . We shall employ this standard device in the proof of item (b) of the next proposition, as well as in the proof of item (b) of Proposition 2.17.
2.4. Proposition. Let
$\mathcal H$
 be a Hilbert space and suppose that
$B \in \mathcal B ( \mathcal H)$
 is invertible. The following conditions are equivalent.
-
(a)
. -
(b) There exists an invertible operator $A_0$
such that
$B \sim A_0 \oplus -A_0$
.
 .


Proof
-
(a) implies (b). Suppose that
. Let
$B = [M, N]$
, where
$M, N \in \mathcal B ( \mathcal H)$
satisfy
$M^2 = 0 = N^2$
.Decompose $\mathcal H = \mathcal H_1 \oplus \mathcal H_2$
, where
$\mathcal H_1 = \ker \, M$
. Relative to this decomposition, we write $$\begin{align*}M=\begin{bmatrix} 0 & A \\ 0 & 0 \end{bmatrix}, \ \ \ \ \ N = \begin{bmatrix} W & X \\ Y & Z \end{bmatrix}. \end{align*}$$
It follows that
$$\begin{align*}B = [M, N] = \begin{bmatrix} A Y & A Z - W A \\ 0 & - Y A \end{bmatrix}. \end{align*}$$
If $\dim \, \mathcal H < \infty $
, then the invertibility of B implies that of both
$A Y$
and
$-Y A$
, which in turn implies (by considering the ranks of
$AY$
and of
$-YA$
) that
$\dim \, \mathcal H_1 = \dim \, \mathcal H_2$
and thus
$\dim \, \mathcal H$
is even.If $\dim \, \mathcal H = \infty $
, then the invertibility of B implies that M has infinite rank. Since
$M^2 = 0$
, it clearly has infinite nullity, and thus
$\dim \, \mathcal H_1 = \dim \, \mathcal H_2$
. (The same argument shows that the rank and nullity of N are also infinite.)In either the finite-dimensional or the infinite-dimensional setting, it follows from the invertibility of B that $A Y$
is left-invertible and that
$Y A$
is right-invertible. In particular,
$\ker \, AY = \{ 0\}$
and
$ {\mathrm {ran}}\, Y A = \mathcal H_2$
. From this, it follows that
$\ker \, Y = \{ 0\}$
and
$ {\mathrm {ran}}\, Y = \mathcal H_2$
, so that Y is a (continuous) bijection. By the Open Mapping Theorem, Y is invertible.Since $\dim \, \mathcal H_1 = \dim \, \mathcal H_2$
and therefore
$\mathcal H_1$
is isomorphic to
$\mathcal H_2$
, we may identify elements of
$\mathcal B(\mathcal H_1 \oplus \mathcal H_2)$
with elements of
$\mathbb M_2(\mathcal B(\mathcal H_1))$
, and view each of A, W, X, Y, and Z as sitting in
$\mathcal B(\mathcal H_1)$
.Let $S := I \oplus Y$
and consider
$M_0 := S^{-1} M S$
,
$N_0 := S^{-1} N S$
. Then, for appropriate choices of
$A_0, W_0, X_0$
, and
$Z_0$
,
$M_0$
and
$N_0$
are of the form $$\begin{align*}M_0 = \begin{bmatrix} 0 & A_0 \\ 0 & 0 \end{bmatrix}, \ \ \ \ \ N_0 = \begin{bmatrix} W_0 & X_0 \\ I & Z_0 \end{bmatrix}. \end{align*}$$
Since $N^2 = 0$
, we see that
$Z_0 = -W_0$
and that
$X_0 = -Z_0^2$
. Thus, we may write $$\begin{align*}N_0 = \begin{bmatrix} W_0 & - W_0^2 \\ I & - W_0 \end{bmatrix}. \end{align*}$$
Next, note that
$$\begin{align*}S^{-1} B S = S^{-1} [M, N] S = [M_0, N_0] = \begin{bmatrix} A_0 & -A_0 W_0 - W_0 A_0 \\ 0 & -A_0 \end{bmatrix}. \end{align*}$$
Set $R = \begin {bmatrix} W_0 & I \\ I & 0 \end {bmatrix}$
, so that R is invertible with inverse
$R^{-1} = \begin {bmatrix} 0 & I \\ I & -W_0 \end {bmatrix}$
. A routine calculation shows that $$\begin{align*}(SR)^{-1} B (SR) = R^{-1} (S^{-1} B S) R = (-A_0) \oplus A_0. \end{align*}$$
The last statement is clear.
-
(b) implies (a). This was demonstrated in Paragraph 1.3.
 . Let


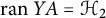


2.5. Definition. Let
$T\in \mathcal B ( \mathcal H)$
 . We say that T is strongly irreducible if there is no nontrivial idempotent in the commutant
$\{ T\}^\prime := \{ X \in \mathcal B ( \mathcal H): T X = X T\}$
 of T.
The reader is referred to the monograph of Jiang and Wang [Reference Jiang and Wang22] for more information about strongly irreducible operators.
2.6. Corollary. If
$T \in \mathcal B ( \mathcal H)$
 is an invertible strongly irreducible operator, then
 .
Proof This follows immediately from Proposition 2.4.
The following proposition is derived from the proof of [Reference Gellar16, Corollary 2] and Corollary 2.6. Note that every weighted shift W acting on a Hilbert space is unitarily equivalent to
$-W$
 .
2.7. Proposition Let
$W \in B(\mathcal H)$
 be an injective bilateral weighted shift. If there exist
$0 < R_1 < R_2$
 such that
$\sigma (W )=\{z: R_1\leq |z|\leq R_2\}$
 , then W is strongly irreducible. As such,
 .
2.8. Example. Let
$\{ e_n\}_{n \in \mathbb Z}$
 be an orthonormal basis for the Hilbert space
$\mathcal H$
 , and consider the weighted shift W with weight sequence
$(w_n)_{n \in \mathbb Z}$
 , where
$w_n = \begin {cases} 2 & \mbox { if } n < 0 \\ 1 & \mbox { if } n \ge 0 \end {cases}$
 .
Then W is invertible, and the spectrum of W is easily seen to be
$\sigma (W)=\{z:1\leq |z|\leq 2\}$
 . By Proposition 2.7, W is strongly irreducible and thus
 , although W is invertible and it is similar to
$-W$
 .
For B invertible, Proposition 2.4 implies that if  , then
$B \sim -B$
 . The converse, however, is not true, as seen in Example 2.8. For normal operators, we shall see in Theorem 2.11 that
 if and only if
$B \sim -B$
 . To establish this characterisation, we first obtain two preliminary results as follows.
2.9. Proposition. Let
$\mathcal H$
 be a Hilbert space and suppose that
$T \in \mathcal B ( \mathcal H)$
 is a normal operator. If
$T \sim -T$
 , then
 .
Proof First note that as T and
$-T$
 are both normal, if T is similar to
$-T$
 , then T is unitarily equivalent to
$-T$
 by [Reference Halmos17, Problem 192].
The next part of the argument is almost identical to that of [Reference Drnovšek, Radjavi and Rosenthal12, Proposition 3]. Let E be the spectral measure of the normal operator T, and let

Since T is unitarily equivalent to
$-T$
 ,
$T|_{E(\Omega _2)}$
 is (unitarily) similar to
$-T|_{E(\Omega _1)}$
 . Thus, without loss of generality, one can assume that T has the form
$A\oplus -A \oplus 0$
 , with respect to the decomposition
$\mathcal H=\text {Ran }E(\Omega _1)\oplus \text {Ran }E(\Omega _2)\oplus \text {Ran }E(\{0\})$
 . As seen in Paragraph 1.3, it easily follows that
 .
2.10. Lemma. Let
$\mathcal H$
 be a Hilbert space and
$T \in \mathcal B ( \mathcal H)$
 be a normal operator. Suppose that
$T = [M, N]$
 , where
$M^2=0$
 , and
$N^2=0$
 . Relative to
$\mathcal H = \ker \, M \oplus (\ker \, M)^\perp $
 , write

where A is injective. If
$YA$
 is injective, then
$AZ-WA=0$
 .
Proof Note that
$NM$
 commutes with T. Since T is normal, this implies that

commute. In particular,

so that
$(AZ-WA)^*=0$
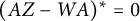 by hypothesis.
2.11. Theorem. Let
$\mathcal H$
 be a Hilbert space and
$T \in \mathcal B ( \mathcal H)$
 be normal. The following conditions are equivalent.
-
(a) T is unitarily equivalent to $-T$
; that is, there exists a unitary operator
$U \in \mathcal B ( \mathcal H)$
such that
$-T = U^* T U$
. -
(b) $T \sim -T$
. -
(c)
.


 .
Proof
-
(a) implies (b). This is trivial, since each unitary operator is invertible.
-
(b) implies (c). This is Proposition 2.9.
-
(c) implies (a). By Zorn’s lemma, there is a maximal subspace $\mathcal {L}$
invariant under both M and N on which the respective restrictions of M and N commute. (It is possible that
$\mathcal L = \{ 0\}$
.) Relative to the decomposition
$\mathcal H = \mathcal L \oplus \mathcal L^\perp $
, M and N have the forms $$\begin{align*}M= \begin{bmatrix}M_1 & *\\ 0& M_2\\ \end{bmatrix} ,~~\text{and}~~N=\begin{bmatrix}N_1 & *\\ 0& N_2\\ \end{bmatrix}.\end{align*}$$
We may then apply the same argument to the adjoints of the nilpotents $M_2$
and
$N_2$
. This leads to a decomposition of
$\mathcal L^\perp $
as
$\mathcal L^\perp = \mathcal M \oplus \mathcal N$
where, with respect to the decomposition
$\mathcal H = \mathcal L \oplus \mathcal M \oplus \mathcal N$
, we have $$\begin{align*}M=\begin{bmatrix} M_1&*&*\\ 0&M_0&*\\ 0&0&M_3 \\ \end{bmatrix}~~\text{and}~~ N=\begin{bmatrix} N_1&*&*\\ 0&N_0&*\\ 0& 0& N_3\\ \end{bmatrix}. \end{align*}$$
Recall that the kernel and the range of a normal operator are reducing for that operator. Since T is normal and $T=MN-NM$
, it follows that $$\begin{align*}T=\begin{bmatrix} 0&0&0\\ 0&T_0&0\\ 0& 0&0\\ \end{bmatrix},\end{align*}$$
where $T_0$
is the commutator of
$M_0$
and
$N_0$
. Note that
$M_0$
and
$N_0$
cannot have common kernel (by the maximality of
$\mathcal L$
and
$\mathcal N$
). Neither can their adjoints.We now write
$$\begin{align*}M_0=\begin{bmatrix}0 & A\\ 0& 0\\ \end{bmatrix},~~\text{and}~~N_0=\begin{bmatrix}W & X\\ Y& Z\\ \end{bmatrix},\end{align*}$$
relative to the decomposition $\mathcal {M}=\mathcal {M}_1\oplus (\mathcal {M}\ominus \mathcal {M}_1)$
with
$\mathcal {M}_1=\ker M_0$
. Then A is injective, and with respect to the decomposition
$\mathcal M = \mathcal M_1 \oplus (\mathcal M \ominus \mathcal M_1)$
,
$T_0$
has the form $$\begin{align*}\begin{bmatrix}AY&AZ-WA\\ 0&-YA\\ \end{bmatrix}.\end{align*}$$
We claim that Y is injective. Otherwise, Y has nonzero kernel $\mathcal {M}_2$
contained in
$\mathcal {M}_1$
. Note that
$N_0^2=0$
implies
$YW+ZY=0$
, and thus
$\mathcal {M}_2$
is invariant under W. Then with respect to the decomposition
$\mathcal {M}=\mathcal {M}_2\oplus (\mathcal {M}_1\ominus \mathcal {M}_2)\oplus (\mathcal {M}\ominus \mathcal {M}_1)$
, we have $$\begin{align*}M_0=\begin{bmatrix} 0&0&A_1\\ 0&0&A_2\\ 0&0&0 \\ \end{bmatrix}~~\text{and}~~ N_0=\begin{bmatrix} W_1&W_2&X_1\\ 0&W_3&X_2\\ 0& Y_1& Z\\ \end{bmatrix}.\end{align*}$$
Note that $\mathcal {L}\oplus \mathcal {M}_2$
is an invariant subspace under both M and N on which the respective restrictions of M and N commute. This contradicts the maximality of
$\mathcal {L}$
. Thus, Y is injective.By Lemma 2.10, $AZ-WA=0$
. Then $$\begin{align*}T_0=\begin{bmatrix}AY&0\\ 0&-YA\\ \end{bmatrix}.\end{align*}$$
Note that $Y(AY)=(YA)Y$
,
$A(YA)=(AY)A$
, and
$A,Y$
are injective. Furthermore, since
$T_0$
is normal, so are
$AY$
and
$YA$
. Thus, by [Reference Chen, Herrero and Wu9, Lemma 4.1],
$AY$
is unitarily equivalent to
$YA$
. Therefore,
$T_0$
is unitarily equivalent to
$-T_0$
, and hence, T is unitarily equivalent to
$-T$
.


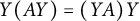


2.12. Example. By Example 2.8, we see that there exists an invertible operator
$T \in \mathcal B ( \mathcal H)$
 which satisfies
$T \sim -T$
 and yet T does not lie in
 .
Let us now show that if the underlying Hilbert space
$\mathcal H$
 is infinite-dimensional, then there exists an operator
 such that T is not similar to
$-T$
 . The inspiration for this example comes from a matrix decomposition for products of two square-zero operators found in the paper of Novak [Reference Novak29].
Let
$B \in \mathcal B ( \mathcal H)$
 be a positive, compact, injective, diagonal operator – say
 . (For example, one might choose
 .)
Consider
$M = \begin {bmatrix} 0 & 0 & 0 \\ I & 0 & 0 \\ B & 0 & 0 \end {bmatrix}$
 and
$N= \begin {bmatrix} 0 & 0 & I \\ 0 & 0 & 0 \\ 0 & 0 & 0 \end {bmatrix} \in \mathcal B(\mathcal H \oplus \mathcal H \oplus \mathcal H)$
 . Clearly,
$M^2 = 0 = N^2$
 .
Let

Suppose that
$S = \begin {bmatrix} S_1 & S_2 & S_3 \\ S_4 & S_5 & S_6 \\ S_7 & S_8 & S_9 \end {bmatrix}$
 satisfies
$T S = - S T$
 . Then

Since B is injective,
$- B S_2 = 0$
 implies that
$S_2 = 0$
 , and obviously,
$S_8 = 0$
 .
Next, note the following:
-
• $B S_9 = - S_8 - S_9 B = -S_9 B$
. With respect to the basis that diagonalises B, write the corresponding matrix of
$S_9$
as
$[S_9] = [x_{ij}]$
. The equation
$B S_9 = - S_9 B$
then implies that for all
$1 \le i, j$
,
$b_i x_{ij} = - x_{ij} b_j$
, or equivalently,
$(b_i + b_j) x_{ij} = 0$
. Since
$b_i + b_j> 0$
by hypothesis, we find that
$x_{ij} = 0$
for all
$1 \le i,j$
. That is,
$S_9 = 0$
. -
• $S_7 = S_4 B$
.


Thus,

But
$S_4 B$
 acts on an infinite-dimensional space, and it is compact because B is compact. Thus, S is not invertible. (If R is such that
$S R = I$
 , then the third row of S multiplied by the third column of R is compact, contradicting the hypothesis that it should be I.)
Despite the fact that  does not imply that
$T \sim -T$
 , we now establish a number of useful results that illustrate a strong connection between T and
$-T$
 when
 . The first such result establishes a link between
 and
 . In particular, it shows that if T acts on a finite-dimensional Hilbert space
$\mathcal H$
 and
 , then
 .
2.13. Theorem. Let  . For all
$0 \ne \alpha \in \mathbb C$
 and
$k \ge 1$
 ,

Proof
$\bullet $
 Step one.
Let
$T = [M, N] = MN - NM$
 , where
$M^2 = 0 = N^2$
 . Let
$\mathcal H_1 := \ker \, M$
 and
$\mathcal H_2 = \mathcal H_1^\perp $
 , so that relative to the decomposition
$\mathcal H = \mathcal H_1 \oplus \mathcal H_2$
 , we may write
$M = \begin {bmatrix} 0 & A \\ 0 & 0 \end {bmatrix}$
 and
$N = \begin {bmatrix} W & X \\ Y & Z \end {bmatrix}$
 . Set
$L := MN$
 and
$R := NM$
 , and observe that

and
$RL = 0$
 as well.
Now,
$L = \begin {bmatrix} AY & AZ \\ 0 & 0 \end {bmatrix}$
 and
$R = \begin {bmatrix} 0 & WA \\ 0 & YA \end {bmatrix}$
 . If
$0 \ne \alpha \in \sigma _p(L)$
 , then
$\alpha \in \sigma _p(AY)$
 . Similarly, if
$0 \ne \alpha \in \sigma _p(R)$
 , then
$\alpha \in \sigma _p(YA)$
 .
$\bullet $
 Step two.
Let
$k \in \mathbb N$
 and
$0 \ne \alpha \in \mathbb C$
 .
-
(II.1) Note that if $0 \ne w = \begin {bmatrix} w_1 \\ w_2 \end {bmatrix} \in \ker \, (L - \alpha I)^k$
, then (for an appropriate operator
$L_{k, \alpha , 2}$
) $$\begin{align*}\begin{bmatrix} 0 \\ 0 \end{bmatrix} = (L - \alpha I)^k w = \begin{bmatrix} (AY - \alpha I)^k w_1 + L_{k, \alpha, 2} w_2 \\ (-\alpha)^k \ w_2 \end{bmatrix}, \end{align*}$$implying that $w_2 = 0$
.
-
(II.2) Similarly, if $0 \ne w \in \ker \, (R+\alpha I)^k$
, then (for an appropriate operator
$R_{k, \alpha , 2}$
) $$\begin{align*}\begin{bmatrix} 0 \\ 0 \end{bmatrix} = (R+ \alpha I)^k w = \begin{bmatrix} \alpha^k w_1 + R_{k, \alpha, 2}\ w_2 \\ (YA + \alpha)^k w_2 \end{bmatrix}. \end{align*}$$
It follows that $w_2 \ne 0$
, for otherwise,
$\alpha ^k w_1 = 0$
, and hence,
$w_1 = 0$
, a contradiction.


$\bullet $
 Step three.
Now let
$0 \ne \alpha \in \sigma _p(T)$
 , and let
$z \in \ker \, (T-\alpha I)^k$
 . Then (for an appropriate operator
$T_{k, \alpha , 2}$
 )

This leaves us with two possibilities. Either
-
(a) $z_2 \ne 0$
, and thus,
$z_2 \in \ker \, (YA + \alpha I)^k$
; or -
(b) $z_2 = 0$
, in which case
$z_1 \ne 0$
and
$(AY - \alpha I)^k z_1 = 0$
.


$\bullet $
 Step four.
Conversely, suppose that condition (a) above holds: that is,
$0 \ne y_2 \in \mathcal H_2$
 and that
$(Y A + \alpha I)^k y_2 = 0$
 .
Let
$y_1 := -(\alpha ^{-k}) R_{k, \alpha , 2} \ y_2$
 , where
$R_{k, \alpha , 2}$
 is defined as above, and set
$y = \begin {bmatrix} y_1 \\ y_2 \end {bmatrix}$
 . Clearly,
$y \ne 0$
 as
$y_2 \ne 0$
 . Then

That is,
$(R + \alpha I)^k y = 0$
 . Note that
$(R + \alpha I)^k L y = L (R + \alpha I)^k y = L 0 = 0$
 . Hence,
$L y \in \ker \, (R+\alpha I)^k$
 . But then

By (II.2) of Step two above, we must have
$Ly = 0$
 .
A tedious but routine calculation shows that

From this, it follows that

so that
$y \in \ker \, (T - \alpha I)^k$
 .
More generally, if
$y_2^{(1)}, y_2^{(2)}, \ldots , y_2^{(m)}$
 is a linearly independent set of vectors in the kernel of
$(YA + \alpha I)^k$
 , then with
$y_1^{(j)} := (-\alpha )^{-k} R_{k, \alpha , 2} \ y_2^{(j)}$
 ,
$1 \le j \le m$
 , we see that

is a linearly independent family of vectors in
$\ker \, (T - \alpha I)^k$
 .
$\bullet $
 Step five.
Suppose that condition (b) holds: that is,
$0 \ne x_1 \in \mathcal H_1$
 and that
$(AY - \alpha I)^k x_1 = 0$
 .
Let
$x := \begin {bmatrix} x_1 \\ 0 \end {bmatrix}$
 . Then

A routine calculation similar to the one above shows that

From this and the fact that
$R x = 0$
 , it follows that

Hence,
$x \in \ker \, (T-\alpha I)^k$
 . More generally, if
$x_1^{(1)}, x_1^{(2)}, \ldots , x_1^{(\ell )}$
 is a linearly independent set of vectors in
$\ker \, (AY - \alpha I)^k$
 , then

is a linearly independent family of vectors in
$\ker \, (T-\alpha I)^k$
 .
$\bullet $
 Step six.
We also observe that
$\{ x^{(1)}, x^{(2)}, \ldots , x^{(\ell )}, y^{(1)}, y^{(2)}, \ldots , y^{(m)} \}$
 is linearly independent. Indeed, if
$\eta _i, \zeta _j \in \mathbb C$
 ,
$1 \le i \le \ell , 1 \le j \le m$
 and

then by considering the second coordinate of these sums, we see that
$\zeta _j = 0$
 ,
$1 \le j \le m$
 , and hence by considering the remaining first coordinates,
$\eta _i = 0$
 ,
$1 \le i \le \ell $
 .
By considering the case where
$\{ x^{(1)}, x^{(2)}, \ldots , x^{(\ell )}\}$
 is a basis for
$\ker \, (AY -\alpha I)^k$
 and
$\{ y^{(1)}, y^{(2)}, \ldots , y^{(m)} \}$
 is a basis for
$\ker \, (YA + \alpha I)^k$
 , we conclude that

The reverse inequality follows easily from the form of
$(T-\alpha I)^k$
 exhibited in Step three.
$\bullet $
 Step seven.
Consider the following equation from Horn and Johnson [Reference Horn and Johnson21, Theorem 1.3.20]:

Since
$\begin {bmatrix} I & - A \\ 0 & I \end {bmatrix}$
 is invertible with inverse
$\begin {bmatrix} I & A \\ 0 & I \end {bmatrix}$
 , it routinely follows that

are similar.
An argument similar to that employed in Step two shows that

and that

It follows that

and therefore,

2.14. Corollary. If  , then
$\sigma _p(T) = \sigma _p(-T)$
 , and if
$\dim \, \mathcal H < \infty $
 , then
$T \sim -T$
 .
We require the following result of Barnes [Reference Barnes5, Theorem 3].
2.15. Proposition (Barnes). Let X and Y be Banach spaces, and let
$S\in \mathcal {B}(X,Y), R\in \mathcal {B}(Y,X)$
 ; we have

2.16. Lemma. Let
$T \in \mathcal B ( \mathcal H)$
 . Suppose that
 . Then
$\sigma _{ap}(T)=\sigma _{ap}(-T)$
 .
Proof Let
$T = [M, N]$
 , where
$M^2 = 0 = N^2$
 , and write
$M = \begin {bmatrix} 0 & A \\ 0 & 0 \end {bmatrix}$
 and
$N =\begin {bmatrix} W & X \\ Y & Z \end {bmatrix}$
 relative to
$\ker \, M \oplus (\ker \, M)^\perp $
 . Then
$T =\begin {bmatrix} AY & AZ-WA\\ 0 & -YA \end {bmatrix}$
 . We claim that

$\bullet $
 Step one.
Let
$\lambda \in \sigma _{ap}(T)\setminus \{0\}$
 . Then there exists a sequence
$\left ( \begin {bmatrix} x_n\\ y_n \\ \end {bmatrix} \right )_{n=1}^{\infty }$
 of unit vectors such that

If
$\underset {n\in \mathbb {N}}{\inf }\|y_n\|>0$
 , it is easy to see that
$\lambda \in \sigma _{ap}(-YA)$
 ; otherwise,
$\underset {n\in \mathbb {N}}{\inf }\|y_n\|=0$
 , and it is then easy to show that
$\lambda \in \sigma _{ap}(AY)$
 . Therefore,

$\bullet $
 Step two.
-
• Let $0\neq \alpha \in \sigma _{ap}(AY)$
, and
$(x_n)_n \subset \ker M$
be a sequence of unit vectors such that
$\lim _n \|(AY-\alpha )x_n\| = 0$
. Then $$\begin{align*}\lim_n \begin{bmatrix} AY-\alpha & AZ-WA\\ 0 & -YA-\alpha \end{bmatrix}\begin{bmatrix} x_n\\ 0 \\ \end{bmatrix} = \begin{bmatrix} 0\\ 0 \\ \end{bmatrix},\end{align*}$$which in turn implies that $\alpha \in \sigma _{ap}(T)$
.
-
• Let $0\neq \beta \in \sigma _{ap}(-YA)$
, and
$\{y_n\}\subset (\ker M)^\perp $
be a sequence of unit vectors such that
$\lim _n \|(-YA-\beta )y_n\| = 0$
. Let
$x_n=-\frac {1}{\beta }WAy_n$
,
$n\in \mathbb {N}$
. Define
$z_n=\begin {bmatrix} x_n\\ y_n \\ \end {bmatrix}$
. Then
$\|z_n\|\geq 1$
,
$n\in \mathbb {N}$
. We shall require the operators
$L := MN$
and
$R := NM$
. Then $$\begin{align*}\lim_n (R+\beta)z_n= \lim_n \begin{bmatrix} \beta & WA\\ 0 & YA+\beta \end{bmatrix}\begin{bmatrix} x_n\\ y_n \\ \end{bmatrix} = \begin{bmatrix} 0\\ 0 \\ \end{bmatrix}.\end{align*}$$As $LR=RL=0$
, $$\begin{align*}\lim_n \beta Lz_n = \lim_n L[(R+\beta)z_n] = \begin{bmatrix} 0\\ 0 \\ \end{bmatrix}.\end{align*}$$Since $\beta \neq 0$
, it follows
$\lim _n Lz_n = 0$
. Hence, $$\begin{align*}\lim_n (T-\beta)z_n = \lim_n (L-R-\beta)z_n = \lim_n Lz_n-(R+\beta)z_n = 0,\end{align*}$$and thus, $\beta \in \sigma _{ap}(T)$
.


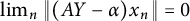


Therefore,

and the claim that
$\sigma _{ap}(T)\setminus \{0\}=(\sigma _{ap}(AY)\setminus \{0\})\cup (\sigma _{ap}(-YA)\setminus \{0\})$
 holds.
By Proposition 2.15,

This verifies that
$\sigma _{ap}(T)=\sigma _{ap}(-T)$
 .
We remind the reader of the convention mentioned in Paragraph 2.3, whereby a bounded operator acting on the Hilbert space
$\mathcal H =\mathcal M_1 \oplus \mathcal M_2$
 , where
$\dim \, \mathcal M_1 = \dim \, \mathcal M_2 = \dim \, \mathcal H$
 , may be identified with an element of
$\mathbb M_2(\mathcal B ( \mathcal H))$
 .
2.17. Proposition. Let
$T \in \mathcal B ( \mathcal H)$
 . Suppose that
 . Then
-
(a) every connected component of $\sigma (T)$
intersects
$\sigma (-T)$
; -
(b) every connected component of $\sigma _e(T)$
intersects
$\sigma _e(-T)$
.


Proof Let
$T = [M, N]$
 , where
$M^2 = 0 = N^2$
 . Write
$M = \begin {bmatrix} 0 & A \\ 0 & 0 \end {bmatrix}$
 and
$N =\begin {bmatrix} W & X \\ Y & Z \end {bmatrix}$
 relative to
$\ker \, M \oplus (\ker \, M)^\perp $
 , and so
$T =\begin {bmatrix} AY & AZ-WA\\ 0 & -YA \end {bmatrix}$
 .
-
(a) Let $\Omega $
be a component of
$\sigma (T)$
. Then
$\Omega \cap \partial \sigma (T)\neq \varnothing $
. Since
$\partial \sigma (T)\subset \sigma _{ap}(T)$
([Reference Conway10, Chapter VII Proposition 6.7], it follows that
$\Omega \cap \sigma _{ap}(T)\neq \varnothing $
. By Lemma 2.16,
$\Omega \cap \sigma _{ap}(-T)\neq \varnothing $
. In particular,
$\Omega \cap \sigma (-T)\neq \varnothing $
. -
(b) The essential spectrum only makes sense if $\dim \, \mathcal H = \infty $
.In this case, the fact that $M^2 = 0$
implies that
$\dim \, \ker \, M = \infty $
. If
$\dim \, (\ker \, M)^\perp < \infty $
, then both M and (therefore) T have finite rank, whence
$\sigma _e(T)=\sigma _e(-T)=\{0\}$
. As such, we may assume without loss of generality that
$\dim \ker \, M=\dim (\ker \, M)^\perp =\dim \, \mathcal H = \infty $
.As per the comments preceding this Proposition, we think of $A, W, Y$
, and Z as elements of
$\mathcal B ( \mathcal H)$
.Let $\pi $
be the quotient map
$\pi $
from
$\mathcal {B}(\mathcal H)$
onto the Calkin algebra
$\mathcal {B}(\mathcal H)/\mathcal {K}(\mathcal H)$
. Then $$\begin{align*}t:=\pi\otimes \text{id}_{\mathbb{M}_2}(T)=\begin{bmatrix} \pi(A)\pi(Y) & \pi(AZ-WA)\\ 0 & -\pi(Y)\pi(A) \end{bmatrix}.\end{align*}$$
Let $\rho $
be a unital faithful
$C^*$
-representation of
$C^*(\pi (A),\pi (Y),\pi (Z),\pi (W))$
to
$\mathcal {B}(\mathcal L)$
, where
$\mathcal L$
is a separable Hilbert space. Then $$\begin{align*}\tilde{T}:=(\rho\otimes \text{id}_{\mathbb{M}_2})(t)=\begin{bmatrix} (\rho\circ\pi)(A)\cdot(\rho\circ\pi)(Y) & (\rho\circ\pi)(AZ-WA)\\ 0 & -(\rho\circ\pi)(Y)\cdot(\rho\circ\pi)(A) \end{bmatrix}.\end{align*}$$
Moreover, $\sigma _e(T)=\sigma (t)=\sigma (\tilde {T})$
and . The proof is completed by applying (a).


 . The proof is completed by applying (a).
3
in the finite-dimensional setting
 in the finite-dimensional setting
3.1. In this section, we shall characterise the set  in the case where
$\dim \, \mathcal H = n < \infty $
 .
Suppose that
$T \in \mathcal B(\mathbb C^n)$
 . By considering the Jordan form of T, we find that we may write
$T \sim B \oplus J$
 , where B is invertible and J is nilpotent.
Proposition 2.2 above asserts that  if and only if
 and
 .
3.2. Corollary. Let
$n \in \mathbb N$
 , and suppose that
$T \in \mathcal B(\mathbb C^n)$
 lies in
 . Then
$T \sim -T$
 .
Proof Let us write the Jordan form of T as
$B \oplus J$
 , where B is invertible and J is nilpotent. By Proposition 2.2,
 and
 . Now, by Proposition 2.4 and the comment which follows it,
$B \sim -B$
 . Since J is nilpotent and acts on a finite-dimensional space,
$J \sim - J$
 , from which it easily follows that
$T \sim -T$
 .
The converse to Corollary 3.2 holds for normal operators (Theorem 2.11). In general, however, it is false. To see this, we first appeal to a result from [Reference Radjavi and Rosenthal35] which we shall also require in the sequel.
3.3. Theorem [Reference Radjavi and Rosenthal35, Theorem 1]. If A and B are quadratic operators on a Banach space and
$A B - B A$
 is nilpotent, then
$\{ A, B \}$
 is triangularizable.
Our characterisation of  in Theorem 3.15 will subsume the next result. Having said that, the result is elementary and can easily be used to exhibit a large number of nilpotent operators which do not lie in
 . In particular, it may be used to provide a large number of examples of operators
$T \sim -T$
 which do not lie in
 .
3.4. Corollary. If
$J \in \mathcal B(\mathbb C^n)$
 is a nilpotent operator in
 , then
$J^{\lfloor \frac {n+1}{2} \rfloor } = 0$
 . In particular, if
$4 \le n$
 and
$J_n \in \mathcal B(\mathbb C^n)$
 is the usual nilpotent Jordan cell of order n, then
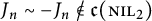 .
Proof Let
$J \in \mathcal B(\mathbb C^n)$
 be nilpotent, and suppose that
 , say
$J = [M, N]$
 , where
$M^2 = 0 = N^2$
 . Let
$L := MN$
 and
$R := NM$
 . Clearly,
$L R = 0 = RL$
 , from which we deduce that
$J^k = (L - R)^k = L^k + (-1)^k R^k$
 for all
$k \ge 1$
 .
Since
$J = [M, N]$
 is nilpotent, by Theorem 3.3, there exists an orthonormal basis
$\{ e_k\}_{k=1}^n$
 for
$\mathbb C^n$
 relative to which the matrices
$[M]$
 and
$[N]$
 corresponding to M and N respectively are upper-triangular. In fact, since
$M^2 = 0 = N^2$
 ,
$[M]$
 and
$[N]$
 are strictly upper-triangular. But the algebra
$\mathfrak T_n^\circ \subseteq \mathbb M_n(\mathbb C)$
 of strictly upper-triangular
$n \times n$
 complex matrices is a nil algebra, and clearly,
$A_1 A_2 \cdots A_n = 0$
 for all choices of
$A_k \in \mathfrak T_n^\circ $
 ,
$1 \le k \le n$
 . It follows that
$L^k = 0 = R^k$
 , and thus
$J^k = 0$
 , if
$k \ge \lfloor \frac {n+1}{2} \rfloor $
 .
The second sentence in the statement of the Corollary is an immediate consequence of the first.
3.5. As previously observed, an element
$T \in \mathcal B(\mathbb C^n)$
 lies in
 if and only if
 and
 , where
$T \sim B \oplus J$
 , where B is invertible and J is nilpotent. Proposition 2.4 tells us that
 if and only if
$B \sim A_0 \oplus - A_0$
 for some invertible operator
$A_0$
 . We now turn our attention to the problem of determining which nilpotent operators in
$\mathcal B(\mathbb C^n)$
 lie in
 . To do so, we shall need to calculate the form of commutators and anti-commutators of specific Jordan forms. Similar results have appeared in the literature previously, and we draw the reader’s attention to [Reference Khatami24, Reference Oblak30, Reference Öztük Kaptanoğlu32].
We begin with a surprisingly useful result. But before that, we remind the reader that if
$\mathcal H$
 is a Hilbert space,
$T \in \mathcal B ( \mathcal H)$
 and
$n \in \mathbb N$
 , then
$\mathcal H^{(n)} := \mathcal H \oplus \mathcal H \oplus \cdots \oplus \mathcal H$
 and
$T^{(n)} := T \oplus T \oplus \cdots \oplus T$
 , where in each case, we have n summands.
3.6. Proposition. Let
$\mu \in \mathbb N$
 . Then
 if and only if
$\mu $
 is even.
Proof First note that
$J_2^{(2)} = J_2 \oplus J_2 \sim J_2 \oplus - J_2 \simeq [M, N]$
 , where

Thus, if
$\mu = 2 \kappa $
 for some
$\kappa \ge 1$
 , then

Since
$M^{(\kappa )}$
 and
$N^{(\kappa )}$
 are nilpotent of order two, we see that
 when
$\mu $
 is even.
Next, we will show that if
$0 \le \kappa $
 is an integer, then
$J_2^{(2\kappa +1)}$
 is not in
 . Otherwise, there exist square-zero operators
$M,N \in \mathcal B(\mathbb C^{2(2\kappa +1)})$
 such that

As
$M J = - J M$
 and
$N J = - J N$
 , relative to the same decomposition of
$\mathcal H$
 , M, and N admit the following decompositions:

where
$M_i,N_i\in \mathcal B(\mathbb C^{2\kappa +1})$
 ,
$i=0,1$
 .
Since
$M^2 = 0$
 , it follows that
$M_0^2 = 0$
 , and so we can find an invertible operator
$S \in \mathcal B(\mathbb C^{2 \kappa + 1})$
 and
$0 \le s \le \kappa $
 such that
$S^{-1} M_0 S = \begin {bmatrix} 0 & I_s \\ 0 & 0 \end {bmatrix} \oplus 0^{(2 \kappa + 1 - 2 s)}$
 . Observe that

and thus, by replacing M and N by
$(S\oplus S)^{-1} M (S \oplus S)$
 and
$(S \oplus S)^{-1} N (S \oplus S)$
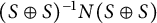 , we may assume without loss of generality that (relative to a decomposition of
$\mathbb C^{4 \kappa +2} = \mathcal H_1 \oplus \mathcal H_2 \oplus \mathcal H_3$
 , where
$\dim \, \mathcal H_1 = s = \dim \,\mathcal H_2$
 and
$\dim \, \mathcal H_3 = (2 \kappa +1) - 2 s$
 )

Obviously,
$J \not = 0$
 implies that
$s \ge 1$
 . Furthermore,
$N^2 = 0$
 implies that
$N_0^2 = 0$
 , and the equations
$M^2 = 0$
 and
$J = [M, N]$
 imply that
-
• $M_0 M_1=M_1 M_0$
; -
• $M_0 N_0 = N_0 M_0$
; and -
• $M_0N_1-M_1N_0-N_0M_1+N_1M_0=I_{2\kappa +1}.$


The first two equations imply that relative to the decomposition
$\mathbb C^{4 \kappa + 2} = \mathcal H_1 \oplus \mathcal H_2 \oplus \mathcal H_3$
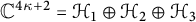 from above,
$M_1$
 and
$N_0$
 have the following forms:

where
$A_i,E_i\in \mathbb {M}_{s}(\mathbb C)$
 ,
$i=0,1$
 , and
$D, K\in \mathcal B(\mathbb C^{2\kappa +1 - 2s})$
 . As
$N_0$
 is square-zero, so is K.
A straightforward calculation based upon the third equation above shows that the compression of
$I_{2 \kappa + 1}$
 to
$\mathcal H_3$
 is nothing more than

Now
$K \in \mathcal B(\mathbb C^{2\kappa +1 - 2s })$
 is a square-zero operator, and so K is similar to
$J_2^{(t)} \oplus 0^{(2 \kappa + 1 - 2s -2t)}$
 . Crucially, we note that
$2\kappa +1 - 2s$
 is an odd number, and therefore,
$(2 \kappa + 1) - 2 s - 2 t \ge 1$
 . Noting that
$I_{2 \kappa + 1 - 2s}$
 is invariant under conjugation by invertible elements, we may choose a basis for
$\mathbb C^{2 \kappa + 1 - 2 s}$
 with respect to which the last column and last row of the corresponding matrix for K are both zero. It follows that the
$(2 \kappa + 1 - 2s, 2 \kappa + 1 - 2s)$
 entry of
$I_{2 \kappa + 1 - 2s} = -(D K + K D)$
 is zero, which is clearly false.
This contradiction implies that
$J_2^{(2\kappa +1)} \simeq J$
 is not in
 .
Our next goal is to establish that a nilpotent element J of
$\mathcal B(\mathbb C^n)$
 lies in
 if and only if there exists a nilpotent operator
$Q \in \mathcal B(\mathbb C^n)$
 such that
$J = Q^2$
 . To do this, we first require a characterisation of those nilpotent matrices admitting a square root. Fortunately, we may appeal to a result of Borwein and Richmond which establishes the conditions under which an arbitrary
$n \times n$
 complex matrix admits a square root. We apply their result to the case of nilpotent matrices.
3.7. Theorem (Borwein and Richmond) [Reference Borwein and Richmond7, Theorem 1]. Let
$2 \le n \in \mathbb N$
 and let
$J \in \mathcal B(\mathbb C^n)$
 be a nilpotent operator. Choose integers
$1 \le \gamma $
 and
$\alpha _1 \ge \alpha _2 \ge \cdots \ge \alpha _\gamma $
 such that

If
$\gamma $
 is odd, we define
$\alpha _{\gamma +1} = 0$
 . Then J is the square of a (necessarily nilpotent) operator Q if and only if

The precise reformulation of their result which we shall use below is as follows.
3.8. Theorem. Let
$2 \le n \in \mathbb N$
 and suppose that
$J \in \mathcal B(\mathbb C^n)$
 is nilpotent. We choose integers
$1 \le d$
 ,
$\mu _1, \mu _2, \ldots , \mu _d$
 and
$\kappa _1 \ge \kappa _2 \ge \cdots \ge \kappa _d \ge 1$
 such that

The following conditions are equivalent.
-
(a) $J = Q^2$
for some nilpotent operator
$Q \in \mathcal B(\mathbb C^n)$
. -
(b)
-
• If $1 \le b \le d-1$
and
$\kappa _b - \kappa _{b+1} \ge 2$
, then
$\sum _{i=1}^b \mu _i$
is an even integer; and -
• if $b = d$
and
$\kappa _b \ge 2$
, then
$\sum _{i=1}^b \mu _i$
is an even integer.
-


3.9. The keys to our characterisation of  in the finite-dimensional setting are Theorem 3.8 above, together with our previous observation that if
$J = [M, N]$
 , where
$M^2 = 0 = N^2$
 , then
$M J = - J M $
 and
$N J = - J N$
 .
In light of these two anti-commutation relations, the following Lemma will prove useful to us below. The proof is an elementary computation. The reader may wish to compare this result as well as our results concerning the structure of M and N anti-commuting with J as above with the results of Oblak [Reference Oblak30] on the structure of nilpotent operators commuting with a fixed nilpotent operator.
3.10. Lemma. Let
$m, n \ge 1$
 be integers and suppose that
$D = [d_{ij}] \in \mathbb M_{m\times n} (\mathbb C)$
 . Suppose furthermore that
$J_m D = - D J_n$
 , and set
$\alpha _j = d_{1 j}$
 ,
$1 \le j \le n$
 .
-
(a) If $2 \le m = n$
, then $$\begin{align*}D = \begin{bmatrix} \alpha_1 & \alpha_2 & \alpha_3 & \cdots & \alpha_{n-2} & \alpha_{n-1} & \alpha_{n} \\ 0 & -\alpha_1 & -\alpha_2 & \cdots & \cdots & -\alpha_{n-2} & - \alpha_{n-1} \\ \vdots & & & & & & \vdots \\ 0 & 0 & 0 & \cdots & \cdots & (-1)^{n-2} \alpha_1 & (-1)^{n-2}\alpha_2 \\ 0 & 0 & 0 & \cdots & \cdots & 0 & (-1)^{n-1} \alpha_1 \\ \end{bmatrix}. \end{align*}$$
-
(b) If $1 \le m < n$
, then $$\begin{align*}D = \left[\begin{array}{@{}c@{\hspace*{5pt}}c@{\hspace*{5pt}}c@{\hspace*{5pt}}c@{\hspace*{5pt}}c@{\hspace*{5pt}}c@{\hspace*{5pt}}c@{\hspace*{5pt}}c@{}} 0 & \cdots & 0 & \alpha_{n-m + 1} & \alpha_{n-m+2} & \cdots & \cdots & \alpha_n \\ 0 & \cdots & 0 & 0 & - \alpha_{n-m+1} & - \alpha_{n-m+2} & \cdots & -\alpha_{n-1} \\ \vdots & & & & & & & \vdots \\ 0 & \cdots & 0 & \cdots & & \cdots & (-1)^{m-2} \alpha_{n-m+1} & (-1)^{m-2} \alpha_{n-m+2} \\ 0 & \cdots & 0 & 0 & \cdots & \cdots & 0 & (-1)^{m-1} \alpha_{n-m+1} \\ \end{array}\right]. \end{align*}$$
In particular, the first $n-m$
columns of D are zero, and the last m columns of D form an upper-triangular matrix. -
(c) If $1 \le n < m$
, then $$\begin{align*}D= \begin{bmatrix} \alpha_1 & \alpha_2 & \alpha_3 & \cdots & \alpha_{n-2} & \alpha_{n-1} & \alpha_{n} \\ 0 & -\alpha_1 & -\alpha_2 & \cdots & \cdots & -\alpha_{n-2} & - \alpha_{n-1} \\ \vdots & & & & & & \vdots \\ 0 & 0 & 0 & \cdots & \cdots & (-1)^{n-2} \alpha_1 & (-1)^{n-2}\alpha_2 \\ 0 & 0 & 0 & \cdots & \cdots & 0 & (-1)^{n-1} \alpha_1 \\ 0 & 0 & 0 & \cdots & 0 & 0 & 0\\ \vdots & & & \cdots & & & \vdots \\ 0 & 0 & 0 & \cdots & 0 & 0 & 0\\ \end{bmatrix}. \end{align*}$$
In particular, the last $m-n$
rows of D are zero, and the first n rows of D form an upper-triangular matrix.


3.11. Remark. Although the forms described in detail in the above Lemma are in themselves interesting, for our purposes, we shall only require the following observation. For reasons which will become apparent below, we now replace n and m above by
$\kappa _{i_1}$
 and
$\kappa _{i_2}$
 , respectively, and we denote the orthogonal bases for
$\mathbb C^{\kappa _{i_1}}$
 and
$\mathbb C^{\kappa _{i_2}}$
 by
$\{ e_{(i_1, j_1, s)} : 1 \le s \le \kappa _{i_1} \}$
 and
$\{ e_{(i_2, j_2, t)} : 1 \le t \le \kappa _{i_2}\}$
 . We have just shown that if
$\max (\kappa _{i_1}, \kappa _{i_2}) \ge 2$
 , and if
$D = [d_{ij}] \in \mathbb M_{\kappa _{i_2} \times \kappa _{i_1}}(\mathbb C)$
 satisfies
$J_{\kappa _{i_2}} D = - D J_{\kappa _{i_1}}$
 , then
-
(i) $\langle D e_{(i_1, j_1, t)}, e_{(i_2, j_2, \kappa _{i_2})} \rangle \ne 0$
implies that
$\kappa _{i_2} \le \kappa _{i_1}$
and
$t= \kappa _{i_1}$
. -
(ii) $\langle D e_{(i_1, j_1, t)}, e_{(i_2, j_2, \kappa _{i_2} -1)} \rangle \ne 0$
implies that
$\kappa _{i_2} - 1 \le \kappa _{i_1}$
and either-
• $\kappa _{i_2} - 1 = \kappa _{i_1}$
, and
$t = \kappa _{i_1}$
, or -
• $\kappa _{i_2} \le \kappa _{i_1}$
, and
$t \in \{ \kappa _{i_1} -1, \kappa _{i_1}\}$
.
-


The following result came as quite a surprise to the authors.
3.12. Theorem. Let
$2 \le n \in \mathbb N$
 and
$J \in \mathcal B(\mathbb C^n)$
 be a nilpotent operator. If
 , then J admits a square root.
Proof Step 1.
The uniqueness of the Jordan canonical form of J (up to permutation of the irreducible summands) allows us to find integers
$1 \le d, \mu _1, \mu _2, \ldots , \mu _d$
 and
$\kappa _1 \ge \kappa _2 \ge \cdots \ge \kappa _d \ge 1$
 such that

relative to the decomposition
$\mathbb C^n = \mathcal H_1^{(\mu _1)} \oplus \mathcal H_2^{(\mu _2)} \oplus \cdots \oplus \mathcal H_d^{(\mu _d)}$
 . Let
$\mathcal H_{(i,j)}$
 denote the
$j^{th}$
 copy of
$\mathcal H_i \simeq \mathbb C^{\kappa _i}$
 in
$\mathcal H_i^{(\mu _i)}$
 ,
$1 \le j \le \mu _i$
 , and let
$\{ e_{(i, j, s)}: 1 \le s \le \kappa _i\}$
 denote the orthonormal basis of
$\mathcal H_{(i,j)}$
 that gives rise to the standard super-diagonal form for the
$j^{th}$
 copy of
$J_{\kappa _i}$
 in
$J_{\kappa _i}^{(\mu _i)}$
 . Also, let
$P_{(i,j)}$
 denote the orthogonal projection of
$\mathbb C^n$
 onto
$\mathcal H_{(i,j)}$
 ,
$1 \le j \le \mu _i$
 ,
$1 \le i \le d$
 .
We have that
$J = [M, N]$
 , that
$M^2 = 0 = N^2$
 , and thus
$J M = - M J$
 ,
$J N = - N J$
 . Observe that

A routine calculation ensuing from the fact that
$J M = - M J$
 yields

Step 2.
Suppose that
$1 \le b < d$
 and that
$\kappa _b - \kappa _{b+1} \ge 2$
 . We define four spaces
$\mathfrak M_\ell $
 ,
$1 \le \ell \le 4$
 .
-
• We define $\mathfrak M_3 := \mathrm {span} \{ e_{(i, j, \kappa _i)} : 1 \le i \le b, 1 \le j \le \mu _i \}$
. In other words, we are choosing the last basis vector
$e_{(i,j,\kappa _i)}$
from each copy
$\mathcal H_{(i,j)}$
of the space upon which each
$J_{\kappa _i}$
acts, up to and including all copies of
$\mathcal H_{(b, j)}$
,
$1 \le j \le \mu _b$
, but no copies occurring after that. -
• We define $\mathfrak M_2 := \mathrm {span} \{ e_{(i, j, \kappa _i - 1)} : 1 \le i \le b, 1 \le j \le \mu _i \}$
. In other words, we are choosing the second to last basis vector
$e_{(i,j,\kappa _i -1)}$
from each copy
$\mathcal H_{(i,j)}$
of the space upon which each
$J_{\kappa _i}$
acts, up to and including all copies of
$\mathcal H_{(b, j)}$
,
$1 \le j \le \mu _b$
, but no copies occurring after that. -
• We define $\mathfrak M_1 := \mathrm {span} \{ e_{(i,j, s)} : 1 \le i \le b, 1 \le j \le \mu _i, 1 \le s \le \kappa _i -2 \}$
. This is the space $$\begin{align*}\left( \mathcal H_1^{(\mu_1)} \oplus \cdots \oplus \mathcal H_b^{(\mu_b)} \right) \ominus (\mathfrak M_2 \oplus \mathfrak M_3). \end{align*}$$
-
• We define
$$\begin{align*}\mathfrak M_4 := \mathbb C^n \ominus (\mathfrak M_1 \oplus \mathfrak M_2 \oplus \mathfrak M_3) = \mathcal H_{b+1}^{(\mu_{b+1})} \oplus \mathcal H_{b+2}^{(\mu_{b+2})} \oplus \cdots \oplus \mathcal H_d^{(\mu_d)}. \end{align*}$$


Step 3.
Write
$M = [M_{i,j}]$
 relative to the decomposition

and note that with respect to this decomposition, J is of the form

where
$\mu := \sum _{i=1}^b \mu _i$
 . Our immediate goal is to show that the equation
$J M = - M J$
 implies that
$M_{2,1} = M_{2, 4} = M_{3, 1} = M_{3, 2} = M_{3, 4} = 0$
 , so that M is of the form

(In fact, we can do better than this. For example, it can be shown that
$M_{3, 3} = - M_{2, 2}$
 , and we can better specify other matrix entries of M, but for our purposes, the stated form of M will suffice.)
To that end, choose an arbitrary basis vector
$e_{(i_1, j_1, s_1)}$
 for
$\mathfrak M_1$
 ; that is,
$1 \le i_1 \le b$
 ,
$1 \le j_1 \le \mu _{i_1}$
 and
$1 \le s_1 \le \kappa _{i_1} - 2$
 . Next, fix an arbitrary basis vector
$e_{(i_2, j_2, \kappa _{i_2} - 1)}$
 for
$\mathfrak M_2$
 , so that
$1 \le i_2 \le b$
 ,
$1 \le j_2 \le \mu _{i_2}$
 . Note that
$e_{(i_2, j_2, \kappa _{i_2})}$
 is an arbitrary basis vector for
$\mathfrak M_3$
 .
Then

and

But
$P_{(i_2, j_2)} M P_{(i_1, j_1)} \in \mathcal B(\mathcal H_{(i_1, j_1)}, \mathcal H_{(i_2, j_2)}) \simeq \mathbb M_{\kappa _{i_2} \times \kappa _{i_1}}(\mathbb C)$
 , and so we may think of
$P_{(i_2, j_2)} M P_{(i_1, j_1)}$
 as playing the role of D in Lemma 3.10 and Remark 3.11 above. By that Remark,
-
• if $\langle (P_{(i_2, j_2)} M P_{(i_1, j_1)}) e_{(i_1, j_1, s_1)}, e_{(i_2, j_2, \kappa _{i_2})}\rangle \ne 0$
, then
$\kappa _{i_2} \le \kappa _{i_1}$
and
$s_1 = \kappa _{i_1}$
. The condition that
$\kappa _{i_2} \le \kappa _{i_1}$
implies that
$i_1 \le i_2 \le b$
, and so we may conclude that
$M_{3, 4} = 0$
. The condition that
$s_1 = \kappa _{i_1}$
then implies that
$e_{(i_1, j_1, s_1)} = e_{(i_1, j_1, \kappa _{i_1})} \in \mathfrak M_3$
. In other words,
$M_{3, 1} = M_{3, 2} = 0$
. -
• Next, suppose that $\langle P_{(i_2, j_2)} M P_{(i_1, j_1)} e_{(i_1, j_1, s_1)}, e_{(i_2, j_2, \kappa _{i_2}-1)} \rangle \ne 0$
. By Remark 3.11(ii), either
$\kappa _{i_2} - 1 \le \kappa _{i_1}$
. The hypotheses that
$i_2 \le b$
and
$\kappa _b - \kappa _{b+1} \ge 2$
then imply that
$i_1 \le i_2$
, whence
$M_{2,4} = 0$
. The same remark also shows that
$s_1 \in \{ \kappa _{i_1} - 1, \kappa _{i_1}\}$
, implying that
$e_{(i_1, j_1, s_1)} \in \mathfrak M_2 \oplus \mathfrak M_3$
. In other words,
$M_{2,1} = 0$
.


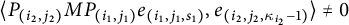


Hence, M has the desired form. Since
$M^2 = 0$
 , we conclude that
$\begin {bmatrix} M_{2, 2} & M_{2, 3} \\ 0 & M_{3, 3} \end {bmatrix}$
 is nilpotent of order two.
Since
$J N = - N J$
 , the same argument implies that

and as before, since
$N^2 = 0$
 , we conclude that
$\begin {bmatrix} N_{2, 2} & N_{2, 3} \\ 0 & N_{3, 3} \end {bmatrix}$
 is nilpotent of order two.
Step 4.
Now
$J = [M, N]$
 . By comparing the compression of J and of
$[M, N]$
 to
$\mathfrak M_2 \oplus \mathfrak M_3$
 , we find that

By Proposition 3.6,
$\mu $
 is even. However,

In other words,
$\mu $
 counts exactly how many operators there are up to and including the
$\mu _b^{th}$
 copy of
$J_{\kappa _b}$
 .
Step 5.
There remains to prove that if
$\kappa _d \ge 2$
 , then
$\sum _{i=1}^d \mu _i$
 is even. The proof is a routine adaptation of the previous case (where
$1 \le b < d$
 ), noting that when
$b = d$
 , then
$\mathfrak M_4 = \{ 0\}$
 , in which case, relative to the decomposition
$\mathcal H = \mathfrak M_1 \oplus \mathfrak M_2 \oplus \mathfrak M_3$
 ,

while

Arguing as before, this implies that
$\begin {bmatrix} 0 & I_\mu \\ 0 & 0 \end {bmatrix}$
 is a commutator of the two square-zero operators

By Proposition 3.6, this can happen only if
$\mu $
 is even. In this case, however,
$\mu = \sum _{i=1}^d \mu _i$
 .
The result now follows by applying Theorem 3.8, the reformulation of the Theorem of Borwein and Richmond.
We next turn our attention to proving that the converse of Theorem 3.12 also holds.
3.13. Proposition. Let
$\kappa \ge 1$
 . Then
$J_\kappa \oplus J_\kappa $
 and
 .
Proof Set
$T_1 := J_\kappa \oplus J_\kappa $
 and
$T_2 := J_{\kappa +1} \oplus J_\kappa $
 .
In the case of
$T_1$
 , simply note that
$J_\kappa \sim -J_\kappa $
 , and thus
$T_1 \sim J_\kappa \oplus -J_\kappa $
 . Since
 is invariant under similarity, we then have that

In the case of
$T_2$
 , set
$A = \begin {bmatrix} 0 \\ I_\kappa \end {bmatrix} \in \mathbb M_{\kappa +1, \kappa }(\mathbb C)$
 and
$Y = \begin {bmatrix} I_\kappa & 0 \end {bmatrix} \in \mathbb M_{\kappa , \kappa +1}(\mathbb C)$
 . If we set

then

Since  ,
 .
3.14. Corollary. Let
$J \in \mathbb M_n(\mathbb C)$
 be a nilpotent operator. Suppose that

where
$\sum _{j=1}^d \kappa _j = n$
 and
$\kappa _1 \ge \kappa _2 \ge \cdots \ge \kappa _d$
 .
If, for
$1 \le j \le \lfloor \frac {d}{2} \rfloor $
 , we have that
$\kappa _{2j-1} - \kappa _{2j} \in \{ 0, 1\}$
 , and
$\kappa _d = 1$
 in the event that d is odd, then
 .
Proof Define

By Proposition 3.13, each  , from which it easily follows that
 . If d is even, then
$Q = Q_0$
 , and we are done. If d is odd, then
$Q= Q_{0} \oplus J_1$
 , which is clearly in
 , as
$Q_{0}$
 and
$J_1$
 are in
 .
Finally,  because
$J \sim Q$
 , and
 is invariant under similarity.
3.15. Theorem. Let
$2 \le n \in \mathbb N$
 and suppose that
$J \in \mathcal B(\mathbb C^n)$
 is a nilpotent operator. The following conditions are equivalent.
-
(a)
. -
(b) J admits a square root.
 .
Proof
-
(a) implies (b).
This is the content of Theorem 3.12.
-
(b) implies (a).
Choose integers $1 \le d$
and
$\kappa _1 \ge \kappa _2 \ge \cdots \ge \kappa _d$
such that
$J = \oplus _{i=1}^d J_{\kappa _i}$
. Suppose that J admits a square root. By Theorem 3.7,
$\kappa _{2 j -1} - \kappa _{2 j} \le 1$
for all
$1 \le j \le \lfloor \frac {d}{2} \rfloor $
, and if d is odd, then
$\kappa _d = 1$
, implying that
$J_{\kappa _d} = 0$
.By Corollary 3.14,
.


 .
As an immediate consequence of the above Theorem, we retrieve the result of Corollary 3.4 that if an element of  is nilpotent, then it is nilpotent of order at most
$\lfloor \frac {n+1}{2} \rfloor $
 . The question of which nilpotent (or general) operators admit
$m^{th}$
 roots is an interesting one. We direct the reader to [Reference Otero31, Reference Öztük33, Reference Psarrakos34, Reference Yood41] for more information on this topic.
3.16. Corollary. Let
$2 \le n \in \mathbb N$
 and let
$T \in \mathcal B(\mathbb C^n)$
 . If
 , then T admits a square root.
Proof Since both  and the set
$\{ Z^2 : Z \in \mathcal B(\mathbb C^n \}$
 are invariant under similarity, we see from Remark 1.2 that without loss of generality, we may assume that
$T = B \oplus Q$
 , where B is invertible and Q is nilpotent. By Proposition 2.2, the hypothesis that
 implies that
 and
 .
Any invertible operator
$B \in \mathcal B(\mathcal H)$
 (where
$\dim \, \mathcal H < \infty $
 ) admits a square root X; one can either appeal to [Reference Borwein and Richmond7, Theorem 1], or one may simply apply the functional calculus to B using a branch of the square-root function
$f(z) = z^{\frac {1}{2}}$
 that avoids the finitely many nonzero eigenvalues of B. Theorem 3.15 above shows that if
 is nilpotent and acts on a finite-dimensional space, then
$Q = Y^2$
 for some nilpotent operator Y.
Thus,
$T = B \oplus Q = X^2 \oplus Y^2 = (X \oplus Y)^2$
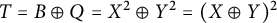 .
Note that the converse of this result is false. The identity operator
$I \in \mathcal B(\mathbb C^n)$
 obviously admits a square root, but it is not a commutator (of any two operators) as its trace is nonzero.
3.17. Theorem. Let
$2 \le n \in \mathbb N$
 and
$T \in \mathcal B(\mathbb C^n)$
 . The following are equivalent.
-
(a)
; -
(b) There exists $0 \le 2 k \le n$
,
$A \in \mathcal B(\mathbb C^k)$
invertible and
$L \in \mathcal B(\mathbb C^{n - 2k})$
nilpotent such that $$\begin{align*}T \sim (A \oplus - A) \oplus L^2. \end{align*}$$
 ;


Proof
-
(a) implies (b). Suppose that
. By Remark 1.2, we may assume without loss of generality that
$T = B \oplus Q$
, where B is invertible and Q is nilpotent. By Proposition 2.2, and . (One of B and Q may be absent. We deal with the case where both are present.) If B is present, then by Proposition 2.4, B acts on a space of even dimension, say
$2k$
, and there exists
$A \in \mathcal B(\mathbb C^k)$
such that
$B \sim A \oplus -A$
. By Theorem 3.12,
$Q = L^2$
for some nilpotent operator
$L \in \mathcal B(\mathbb C^{n-2k})$
. From this, the result immediately follows. -
(b) implies (a). If $T \sim (A \oplus -A) \oplus L^2$
, where A is invertible and L is nilpotent, then setting
$B := (A \oplus -A)$
and
$Q = L^2$
, we see from Proposition 2.4 and Theorem 3.12 that B and Q lie in , whence .
 . By Remark 1.2, we may assume without loss of generality that

 and
 . (One of B and Q may be absent. We deal with the case where both are present.) If B is present, then by Proposition 2.4, B acts on a space of even dimension, say


 , whence
 .
It is interesting to compare the above theorem with the following result of Smith [Reference Smith37, Theorem 1].
3.18. Theorem. (Smith) Let
$n\geq 3$
 ,
$T\in \mathbb M_n(\mathbb C)$
 with
 . Then there are nilpotent matrices
$A, B\in \mathbb M_n(\mathbb C)$
 such that
$T=AB-BA$
 .
3.19. Remark. It is interesting to note that if
$M, N \in \mathcal B(\mathbb C^n)$
 are square-zero operators, and if
$J := [M, N]$
 is nilpotent, then by Theorem 3.3, M and N are simultaneously triangularizable. But then the Jordan product
$J_+ := MN + N M = (M+N)^2$
 is nilpotent, and so by Theorem 3.15,
 as well.
4 The closure of

4.1. Determining a complete list of invariants for a similarity-invariant subset
$\Gamma $
 of
$\mathcal B ( \mathcal H)$
 when
$\mathcal H$
 is infinite-dimensional is, in general, an extremely difficult problem. The problem is much more tractable if the similarity-invariant set is norm-closed. Indeed, in the 1980s, Herrero [Reference Herrero19] and Apostol, Fialkow, Herrero, and Voiculescu [Reference Apostol, Fialkow, Herrero and Voiculescu3] developed an extensive machinery to study the norm-closures of similarity-invariant subsets of
$\mathcal B ( \mathcal H)$
 . Herrero [Reference Herrero20] established a meta-theorem which (very roughly) states that to calculate the norm-closure of a similarity-invariant subset
$\Gamma $
 of
$\mathcal B ( \mathcal H)$
 , one enumerates the spectral, semi-Fredholm index and algebraic conditions necessary for an operator to belong to
 , and in most cases, these conditions should also be sufficient.
Following in the footsteps of Apostol et al, we turn our attention to characterising the norm-closure of  . In the finite-dimensional setting, we obtain a complete characterisation of this set, while in the infinite-dimensional setting, we determine the intersection of
 with the set
 of biquasitriangular operators.
4.2. Theorem. Suppose that
$\dim \, \mathcal H < \infty $
 . Then

Proof Suppose that
$T = [M, N]$
 , where
$M^2 = 0 = N^2$
 . By Theorem 3.17, there exist an invertible operator A and a nilpotent operator L such that

It follows directly from this that  . That is,
 .
Since  is closed [Reference Marcoux, Radjavi and Zhang28, Proposition 3.3],

Conversely, suppose that  , and let
$ {\varepsilon }> 0$
 . The proof of [Reference Marcoux, Radjavi and Zhang28, Theorem 3.4] shows we can find an operator
$X \in \mathcal B ( \mathcal H)$
 such that
$ {\Vert } X - T {\Vert } < {\varepsilon }$
 , and X is similar to a diagonal operator
 such that for all
$1 \le k \le \lfloor \frac {n}{2}\rfloor $
 ,
$\beta _{2k} = -\beta _{2k-1}$
 ,
$\beta _n = 0$
 if n is odd, and for
$1 \le i, j \le n$
 ,
$\beta _i = \beta _j$
 if and only if
$i = j$
 . In particular,

where
$m = \begin {cases} 0 & \text { if } n \text { is even } \\ 1 & \text { if } n \text { is odd.}\end {cases}$

Note that  for each
$\alpha \in \mathbb C$
 , from which we conclude that
 . Since
 is closed under similarity,
 , whence
 . That is,

This completes the proof of the Proposition.
The set  was originally defined in [Reference Marcoux, Radjavi and Zhang28], where it was shown to contain the set
$\mathfrak {c}(\mathfrak E) := \{ [E, F] : E, F \in \mathcal B ( \mathcal H), E^2 = E, F^2 = F \}$
 .
4.3. Corollary. If
$\dim \, \mathcal H < \infty $
 , then

Proof This follows immediately from [Reference Marcoux, Radjavi and Zhang28, Corollary 3.5].
We remark in passing that every nilpotent operator in
$\mathcal B(\mathbb C^n)$
 is balanced, and thus lies in
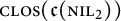 .
4.4.  in the infinite-dimensional setting. As indicated above, a complete characterisation of which Hilbert space operators lie in
 when
$\mathcal H$
 is infinite-dimensional seems out of reach at the moment. We begin with an example that shows that
 fails to be invariant under approximate unitary equivalence.
4.5. Example. There exist normal operators
$L_1$
 and
$L_2 \in \mathcal B ( \mathcal H)$
 such that
$L_1 \simeq _a L_2$
 ,
 , but
 .
Let  be a diagonal operator with
$d_1 = 1$
 and
$\{ d_n\}_{n=2}^\infty $
 dense in
$[\frac {1}{2}, 1)$
 . Then
$\sigma (D) = [\frac {1}{2}, 1]$
 , and
$1$
 is an eigenvalue of D of (geometric and algebraic) multiplicity
$1$
 . Let
$M_x$
 denote the usual multiplication operator on
$L^2([\frac {1}{2}, 1], dm)$
 , where m denotes Lebesgue measure.
Let
$L_1 := (-D) \oplus D$
 and
$L_2 = (-D) \oplus M_x$
 . Since
$\sigma (L_1) = [-1, -\frac {1}{2}] \cup [\frac {1}{2}, 1] = \sigma (L_2)$
 , it follows from the Weyl-von Neumann-Berg Theorem [Reference Davidson11, Theorem II.4.4] that
$L_1 \simeq _a L_2$
 . Note that
$\sigma _p(L_2) = \sigma _p(-D) \subseteq [-1, -\frac {1}{2}]$
 , and so clearly,
$L_2$
 is not similar to
$-L_2$
 .
By Theorem 2.11,  , while
 .
4.6. Biquastriangular operators in  . Let us next consider which biquastriangular operators lie in
 .
The following is a generalisation of [Reference Marcoux, Radjavi and Zhang27, Lemma 3.2].
4.7. Proposition. Let
$\mathcal A$
 be a unital Banach algebra. Let
$a, b_n \in \mathcal A$
 ,
$n \ge 1$
 , and suppose that
$a = \lim _n b_n$
 . Suppose that for each
$n \ge 1$
 , every connected component of
$\sigma (b_n)$
 intersects
$\sigma (-b_n)$
 . Then every connected component of
$\sigma (a)$
 intersects
$\sigma (-a)$
 .
Proof Suppose to the contrary that there exists a connected component
$\Omega \subseteq \sigma (a)$
 satisfying

Note that
$\Omega $
 and
$\sigma (-a)\cup (\sigma (a)\setminus \Omega )$
 are disjoint, compact sets of
$\mathbb C$
 . Thus, we can find disjoint open sets
$G_1, G_2$
 of
$\mathbb C$
 such that
$\Omega \subseteq G_1$
 ,
$\sigma (-a)\cup (\sigma (a)\setminus \Omega ) \subseteq G_2$
 and
$\text {d}(G_1,G_2)=\delta>0$
 .
By applying the upper semi-continuity of the spectrum and Newburgh’s Theorem (c.f. [Reference Herrero19, Theorem 1.1]), we find that there exists
$\delta> 0$
 such that
$ {\Vert } y - a {\Vert } < \delta $
 implies that

In particular, for
$N \in \mathbb N$
 sufficiently large, we have that

Let
$\beta \in \sigma (b_N) \cap G_1 \ne \varnothing $
 . Clearly, the connected component
$\Gamma _\beta $
 of
$\beta $
 in
$\sigma (b_N)$
 also lies in
$G_1$
 . But then

contradicting our hypothesis. This completes the proof.
By combining Proposition 2.17 and Proposition 4.7, one obtains
4.8. Proposition. Let
$T \in \mathcal B ( \mathcal H)$
 . Suppose that
 . Then
-
(a) every connected component of $\sigma (T)$
intersects
$\sigma (-T)$
; -
(b) every connected component of $\sigma _e(T)$
intersects
$\sigma _e(-T)$
.


4.9. Proposition. Let
$T \in \mathcal B ( \mathcal H)$
 . Suppose that
 . If
$\alpha , -\alpha $
 are isolated points, then

Proof Without loss of generality, we may assume that
$\alpha \neq 0$
 and that

We will consider the following two subcases.
-
(a) If $\dim \, \mathcal H(\{ \alpha \}; T)=+\infty $
, then
$\alpha \in \sigma _e(T)$
, but
$-\alpha \notin \sigma _e(T)$
and hence
$\alpha \notin \sigma _e(-T)$
. Then
$\{\alpha \}$
, which is a component of
$\sigma _e(T)$
, has no intersection with
$\sigma _e(-T)$
. This, however, contradicts Proposition 4.8 (b). A similar argument may be applied if
$\dim \, \mathcal H(\{-\alpha \}; T) = +\infty $
. -
(b) Next, suppose that
$$\begin{align*}\max\{ \dim\, \mathcal H(\{ \alpha\}; T), \dim\, \mathcal H(\{ -\alpha\}; T)\}<+\infty.\end{align*}$$
Choose $r{\kern-1pt}\in{\kern-1pt} (0, \frac {|\alpha |}{3})$
, set
$G_1 {\kern-1pt}={\kern-1pt} B(\alpha ,r) {\kern-1pt}:={\kern-1pt} \{ \lambda \in \mathbb C: |\lambda - \alpha | < r\}$
, and
$G_2{\kern-1pt}={\kern-1pt} B(-\alpha ,r)$
. Then
$G_1,G_2$
are disjoint open sets. By [Reference Herrero19, Corollary 1.6], there exists
$\delta>0$
such that
$\|Y-T\|<\delta $
implies that-
• $\sigma (Y) \cap G_k \ne \varnothing $
,
$k = 1, 2$
, -
• $\dim \, \mathcal H(\sigma (Y) \cap G_1; Y)= \dim \, \mathcal H(\{ \alpha \}; T)<\infty $
, and -
• $\dim \, \mathcal H(\sigma (Y) \cap G_2; Y) =\dim \,\mathcal H(\{ - \alpha \}; T)<\infty $
.
Since
, we can choose , such that
$\|X-T\|<\delta $
. By Theorem 2.13, $$\begin{align*}\dim\, \mathcal H(\sigma(X) \cap G_1; X)=\dim\, \mathcal H(\sigma(X) \cap G_2; X).\end{align*}$$Therefore,
$$\begin{align*}\dim\, \mathcal H(\{ \alpha\}; T) = \dim\, \mathcal H(\{ -\alpha\}; T). \end{align*}$$
-


 , we can choose
 , such that


4.10. Theorem. Let
$T \in \mathcal B ( \mathcal H)$
 be a biquasitriangular operator. The following conditions are equivalent:
-
(a)
; -
(b)
; -
(c)
-
(i) every connected component of $\sigma (T)$
intersects
$\sigma (-T)$
; -
(ii) every connected component of $\sigma _e(T)$
intersects
$\sigma _e(-T)$
; and -
(iii) If $\alpha , -\alpha \in \sigma (T)$
are isolated points, then $$\begin{align*}\dim\, \mathcal H(\{ \alpha\}; T) = \dim\, \mathcal H(\{ -\alpha\}; T); \end{align*}$$
-
-
(d)
.
 ;
 ;


 .
Proof By [Reference Marcoux, Radjavi and Zhang27, Theorem 4.11] (a), (b), and (c) are equivalent. By Proposition 4.8 and Proposition 4.9, (d) implies (c).
By examining the proof of (c) implying (a) of [Reference Marcoux, Radjavi and Zhang27, Theorem 3.5] and also [Reference Marcoux, Radjavi and Zhang27, Theorem 4.11], we find that to show that (c) implies (d), it suffices to note that balanced operators acting on a finite-dimensional Hilbert space are in  (Corollary 4.3)) and to show that
 . The last fact is easy to check by factoring
$X\oplus -X$
 as

4.11. Corollary. Let
$\mathcal H$
 be an infinite-dimensional, separable Hilbert space. Then
 contains the closure of the set of all nilpotent operators in
$\mathcal B ( \mathcal H)$
 .
Proof This follows from [Reference Marcoux, Radjavi and Zhang27, Theorem 2.13] and Theorem 4.10 above.
4.12. We next turn our attention to determining which compact operators lie in the set  . Interestingly, we shall show that a compact operator is a limit of commutators of square-zero operators if and only if it is a limit of compact commutators of square-zero operators. The corresponding statement where the adjective “compact” is replaced by “normal” turns out to be false (see Example 4.15 below).
4.13. Lemma. Let
$K \in \mathcal K ( \mathcal H)$
 . If
 , then K is balanced.
Proof Since every compact operator is biquasitriangular, this is an immediate consequence of the equivalence of (c) and (d) in Theorem 4.10.
4.14. Theorem. Let
$K \in \mathcal K ( \mathcal H)$
 . The following are equivalent.
-
(a)
. -
(b)
. -
(c)
. -
(d)
. -
(e)
.
 .
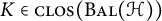 .
 .
 .
 .
Proof
-
(a) if and only if (b). This follows immediately from Theorem 4.10 above.
-
(b) implies (c). This is Lemma 4.13.
-
(c) implies (d). This follows from the definitions of both sets.
-
(d) implies (e). Let
be a compact operator. We shall show that given
$ {\varepsilon }> 0$
, there exists a finite-dimensional subspace
$\mathcal M \subseteq \mathcal H$
and such that
$ {\Vert } K - (F \oplus 0) {\Vert } < \frac { {\varepsilon }}{2}$
. If we can do this, then by applying Theorem 4.2, we can find such that
$ {\Vert } B - F {\Vert }< \frac { {\varepsilon }}{2}$
, whence , and
$ {\Vert } K - (B \oplus 0) {\Vert } < {\varepsilon }$
. This implies that , as required.The spectrum of any compact operator in $\mathcal B ( \mathcal H)$
is either finite or a sequence converging to
$0$
. Suppose that . It easily follows that we must have
$\sigma (K) = \{ \beta _i, -\beta _i\}_{i=1}^\eta \cup \{ 0\}$
, where
$\eta \in \mathbb N \cup \{ 0, \infty \}$
,
$\beta _i \ne 0$
if
$1 \le i < \eta +1$
, and
$\{ \beta _i, -\beta _i\} \cap \{ \beta _j, -\beta _j\} = \varnothing $
if
$1 \le i \ne j < \eta +1$
. Note that if
$\eta = 0$
, then this should be interpreted as saying that
$\sigma (K) = \{ 0\}$
. Moreover, if
$\eta = \infty $
, then
$\lim _i \beta _i = 0$
, and in all cases,
$\mu (\beta _i) = \mu (-\beta _i)$
for all
$1 \le i < \eta + 1$
.Let $ {\varepsilon }> 0$
. Fix
$0 \le p < \eta + 1$
such that
$| \beta _i| \ge \frac { {\varepsilon }}{4}$
if
$1 \le i \le p$
and
$| \beta _i | < \frac { {\varepsilon }}{4}$
if
$p < i < \eta + 1$
.By considering the Riesz subspaces $\mathcal H_i$
corresponding to the clopen sets
$\{ \beta _i, -\beta _i\}$
,
$1 \le i \le p$
, we may decompose
$\mathcal H = \mathcal H_1 \oplus \mathcal H_2 \oplus \cdots \oplus \mathcal H_p \oplus \mathcal H_0$
such that with respect to this decomposition, $$\begin{align*}K = \begin{bmatrix} K_{11} & K_{12} & K_{13} & \cdots & K_{1p} & K_{1 0} \\ & K_{22} & K_{23} & \cdots & K_{2p} & K_{2 0} \\ & & \ddots & & & \vdots \\ & & & \ddots & \vdots & \vdots \\ & & & & K_{p p} & K_{p 0} \\ & & & & & K_{0 0} \end{bmatrix}, \end{align*}$$
where $\sigma (K_{ii}) = \{ \beta _i, -\beta _i\}$
,
$1 \le i \le p$
and
$\sigma (K_{00}) = \sigma (K) \setminus \{ \beta _j, -\beta _j\}_{j=1}^p \subseteq \mathbb D_{ {\varepsilon }/4} := \{ z \in \mathbb C: |z| < \frac { {\varepsilon }}{4} \}$
.Let P denote the orthogonal projection of $\mathcal H$
onto
$\oplus _{j=1}^p \mathcal H_j$
, and observe that
$\mathrm {rank}\, \, P < \infty $
. Since K and
$K_{00}$
are compact, we can find a finite-rank orthogonal projection
$Q = (I-P)Q(I-P)$
such that-
• $ {\Vert } (P+Q) K (P+Q) - K {\Vert } < \frac { {\varepsilon }}{4}$
, and -
• by furthermore appealing to the upper-semicontinuity of the spectrum,
$$\begin{align*}\sigma(Q K_{00} Q) \subseteq \mathbb D_{ {\varepsilon}/4}. \end{align*}$$
(To achieve the second step, choose $\delta> 0$
such that
$ {\Vert } X - K_{00} {\Vert } < \delta $
implies that
$\sigma (X) \subseteq \mathbb D_{ {\varepsilon }/4}$
, and then choose Q sufficiently “large” such that
$ {\Vert } Q K_{00} Q - K_{00} {\Vert } < \delta $
.)Write $\mathcal J_0 = {\mathrm {ran}}\, Q$
and let
$\mathcal J_1 := \mathcal H_0 \ominus \mathcal J_0$
. Relative to the decomposition
$\mathcal H = \oplus _{j=1}^p \mathcal H_j \oplus \mathcal J_0 \oplus \mathcal J_1$
, we have $$\begin{align*}(P+Q) K (P + Q) = \begin{bmatrix} K_{11} & K_{12} & K_{13} & \cdots & K_{1p} & L_{1 0} & 0 \\ & K_{22} & K_{23} & \cdots & K_{2p} & L_{2 0} & 0 \\ & & \ddots & & & \vdots & \vdots \\ & & & \ddots & \vdots & \vdots & \vdots \\ & & & & K_{p p} & L_{p 0} & 0 \\ & & & & & L_{0 0} & 0 \\ & & & & & 0 & 0 \end{bmatrix}, \end{align*}$$where $\sigma (L_{00} \oplus 0) = \sigma (Q K_{00} Q) \subseteq \mathbb D_{ {\varepsilon }/4}$
. Since
$\dim \, \mathcal J_0 = \mathrm {rank}\, \, Q < \infty $
, we can upper-triangularise
$L_{00}$
with respect to some orthonormal basis for
$\mathcal J_0$
. Let D denote the diagonal of
$L_{00}$
, and observe that
$ {\Vert } D {\Vert } < \frac { {\varepsilon }}{4}$
, since the norm of a diagonal matrix is equal to its spectral radius. Set
$L := L_{00} - D$
, so that
$\sigma (L) = \{ 0 \}$
, and set $$\begin{align*}F := \begin{bmatrix} K_{11} & K_{12} & K_{13} & \cdots & K_{1p} & L_{1 0} \\ & K_{22} & K_{23} & \cdots & K_{2p} & L_{2 0} \\ & & \ddots & & & \vdots \\ & & & \ddots & \vdots & \vdots \\ & & & & K_{p p} & L_{p 0} \\ & & & & & L \end{bmatrix} \in \mathcal B(\mathcal M), \end{align*}$$where $\mathcal M = \oplus _{j=1}^p \mathcal H_j \oplus \mathcal J_0$
. Then
$\sigma (F) = \cup _{j=1}^p \sigma (K_{jj}) \cup \sigma (L)$
, noting that the eigenvalues of
$K_{jj}$
appear with the same algebraic multiplicity in
$\sigma (F)$
. In other words, F is balanced. Finally, $$ \begin{align*} \ \ \ \ \ {\Vert} K - (F\oplus 0) {\Vert} &\le {\Vert} K - (P+Q) K (P+Q) {\Vert} + {\Vert} (P+Q) K (P+Q) - (F \oplus 0) {\Vert} \\ &< \frac{ {\varepsilon}}{4} + {\Vert} L - L_{00} {\Vert} \\ &< \frac{ {\varepsilon}}{4} + \frac{ {\varepsilon}}{4} \\ &= \frac{ {\varepsilon}}{2}. \end{align*} $$As seen above, this completes the proof.
-
-
(e) implies (a). This is trivial.
 be a compact operator. We shall show that given


 such that

 such that

 , and

 , as required.


 . It easily follows that we must have


4.15. Example. Let us denote the set of normal operators in
$\mathcal B ( \mathcal H)$
 by
 . After comparing conditions (a) and (e) of Theorem 4.14, one might be tempted to ask whether or not
 . This is not the case, as we shall now see.
Suppose that
$T=\begin {bmatrix} -I& \\ & D \\ \end {bmatrix}$
 , where
$I\in \mathcal B(\mathcal H)$
 is the identity operator and
$D\in \mathcal B(\mathcal H)$
 is a normal operator with
$\sigma _e(D)=\sigma (D)=[1,2]$
 . Then T is normal and
 by Theorem 4.10. We claim that
 .
Otherwise, there exists a sequence
$(T_n)_n$
 of normal operators in
 such that
$\underset {n\to \infty }{\lim }T_n=T$
 . By Theorem 2.11, each
$T_n$
 is unitarily equivalent to
$-T_n$
 , hence in particular,
$\sigma (T_n)=\sigma (-T_n)$
 . By a result of Newburgh, the map taking an operator to its spectrum is continuous on the set of normal operators with the operator norm, to the set of compact subsets of
$\mathbb C$
 with the Hausdorff metric (see also [Reference Halmos17, Problem 105]). Therefore,

a contradiction.
In other words,  .
4.16. An obstruction to belonging to  . A complete characterisation of
 requires us to understand which non-biquasitriangular operators lie in that set. Although we do not have a complete answer to this question, we identify an index obstruction which allows us to eliminate large classes of operators from belonging to
 .
4.17. Proposition. Let
$T \in \mathcal B ( \mathcal H)$
 be a Fredholm operator with
 . Then there exists
$\delta> 0$
 such that if
 and
$B \in \mathcal B ( \mathcal H)$
 , then

In particular,  .
Proof Since the set of Fredholm operators of index  is open in
$\mathcal B ( \mathcal H)$
 , we can choose
$\delta> 0$
 such that if
$C \in \mathcal B ( \mathcal H)$
 and
$ {\Vert } C - T {\Vert } < \delta $
 , then
 .
Suppose that there exist  and
$B \in \mathcal B ( \mathcal H)$
 such that
$ {\Vert } T - (M B - BM) {\Vert } < \delta $
 . Set
$T_1 : = M B - B M$
 , implying that
 .
Writing
$M = \begin {bmatrix} 0 & A \\ 0 & 0 \end {bmatrix}$
 and
$B =\begin {bmatrix} W & X \\ Y & Z \end {bmatrix}$
 relative to
$\ker \, M \oplus (\ker \, M)^\perp $
 yields
$T_1 =\begin {bmatrix} AY & AZ-WA\\ 0 & -YA \end {bmatrix}$
 . Since
$T_1$
 is Fredholm,
$\dim \ker \, M =\dim (\ker \, M)^\perp =\infty $
 , and
$\pi (AY)$
 is left invertible in the Calkin algebra and
$\pi (-YA)$
 is right invertible. Hence,
$\pi (A)$
 and
$\pi (Y)$
 are left and right invertible in the Calkin algebra; that is,
$\pi (A)$
 and
$\pi (Y)$
 are invertible in the Calkin algebra. Therefore, A and Y are both Fredholm operators. By [Reference Han, Lee and Lee18, Corollary 5],

a contradiction.
The second statement is an immediate consequence of the first.
4.18. Proposition. Let
$\{e_n\}_{n=1}^\infty $
 be an orthonormal basis of
$\mathcal H$
 , and let
$W\in B(\mathcal H)$
 be the unilateral forward weighted shift with weight sequence
$(w_n)_n \in \ell ^\infty $
 . Suppose that
$\inf _n\, |w_n|>0$
 . Then

Proof Without loss of generality, we may assume that
$w_n>0$
 ,
$n\geq 0$
 . Moreover,
$W= S D$
 , where S is the unilateral shift, and D is the diagonal operator
$\text {diag} \{ w_n\}_n$
 . Since
$ \inf _n |w_n|>0$
 , D is invertible. As S is a Fredholm operator with index
$-1$
 , so is W. By Proposition 4.17,

5 Concluding remarks.
5.1. As mentioned at the outset, one may study the sets
$\mathfrak {c}(\Omega ) := \{ [A, B]: A, B \in \Omega \}$
 and
 for many classes
$\Omega $
 of operators on a Hilbert space. In the infinite-dimensional setting, it is of interest to consider
 whenever
$\Omega $
 is invariant under similarity, because in this case,
$\mathfrak {c}(\Omega )$
 is also invariant under similarity, and we can make use of the machinery developed by Apostol, Fialkow, Herrero, and Voiculescu [Reference Apostol, Fialkow, Herrero and Voiculescu3] to help us in this setting.
In the finite-dimensional setting, the existence of Jordan forms gives one hope that one may be able to describe
$\mathfrak {c}(\Omega )$
 itself when
$\Omega $
 is invariant under similarity.
5.2. In this paper, we have considered the case where  , which is clearly a similarity-invariant subset of
$\mathcal B ( \mathcal H)$
 , and in a previous paper [Reference Marcoux, Radjavi and Zhang27], we considered the case where
$\Omega = \mathfrak E := \{E \in \mathcal B ( \mathcal H): E^2 = E\}$
 , again a similarity-invariant subset of
$\mathcal B ( \mathcal H)$
 . As we saw in Theorem 4.10,

Observe that square-zero operators and idempotents both satisfy a quadratic polynomial. Suppose that

-
• What are
and ? -
• Is
?
 and
 ?
 ?
If we maintain the requirement that
$\Omega \subseteq \mathcal B ( \mathcal H)$
 be invariant under similarity, but drop the requirement that elements of
$\Omega $
 must satisfy a polynomial of degree two, then – as an extension of the work done here – a natural class to consider is the set
 . We have already seen that Smith’s Theorem 3.18 implies that, for
$3 \le n \in \mathbb N$
 ,
 , and hence,
 .
When
$\dim \, \mathcal H = \infty $
 , the set
 is strictly larger than
 . To see this, recall that a compact operator
$K \in \mathcal K ( \mathcal H)$
 lies in
 if and only if it is balanced. In particular, if K is a rank-one projection, then K is not balanced, and so
 . The next Proposition shows that such a K nonetheless lies in
 .
5.3. Proposition. Every compact operator is a limit of commutators of compact, nilpotent operators.
Proof Let
$K \in \mathcal K ( \mathcal H)$
 and
$ {\varepsilon }> 0$
 . Choose a finite-rank operator F such that
$ {\Vert } K - F {\Vert } < \frac { {\varepsilon }}{2}$
 , and write

relative to
$\mathcal H = \mathcal H_1 \oplus \mathcal H_2$
 , where
$\dim \, \mathcal H_1 < \infty $
 .
Let  , and choose
$m> 2$
 such that
$\frac {|\alpha |}{m} < \frac { {\varepsilon }}{2}$
 . Write
$\mathcal H_2 := \mathcal H_{3} \oplus \mathcal H_4$
 , where
$\dim \, \mathcal H_3 = m$
 , and – relative to the decomposition
$\mathcal H = \mathcal H_1 \oplus \mathcal H_3 \oplus \mathcal H_4$
 – define

Then
$ {\Vert } G- F {\Vert } < \frac { {\varepsilon }}{2}$
 , and therefore,

Since
$F_0 \oplus \frac {-\alpha }{m} I_m \in \mathcal B(\mathcal H_1 \oplus \mathcal H_3)$
 has trace zero, it follows from Smith’s Theorem 3.18 that
$F_0 \oplus \frac {-\alpha }{m} I_m$
 is a commutator of nilpotent matrices in
$\mathcal B(\mathcal H_1 \oplus \mathcal H_3)$
 , and thus, G is a commutator of finite-rank nilpotent operators. But then K is a limit of such operators.
5.4. When
$\Omega $
 is not invariant under similarity, the problem of characterising
$\mathfrak {c}(\Omega )$
 and its closure appears to be more delicate. Two interesting classes to consider are
-
(a)
, the set of normal operators in
$\mathcal B ( \mathcal H)$
, and -
(b) $\Omega = \mathcal U$
, the set of unitary operators in
$\mathcal B ( \mathcal H)$
.
 , the set of normal operators in


We finish with two minor observations regarding this last class.
5.5. Example. Every
$W \in \mathcal U_2(\mathbb C)$
 with
 lies in
$\mathfrak {c}(\mathcal U_2(\mathbb C))$
 .
Note that if
$W \in \mathcal U_2(\mathbb C)$
 and
 , then W is unitarily equivalent to
$\begin {bmatrix} \theta & 0 \\ 0 & -\theta \end {bmatrix}$
 , and hence,

for some
$\theta \in \mathbb T$
 .
Let
$U_0 = \begin {bmatrix} 1 & 0 \\ 0 & i \end {bmatrix}$
 ,
$V_0 = \frac {(1+i)}{2} \begin {bmatrix} 1 & 1 \\ -1 & 1 \end {bmatrix}$
 , so that
$U_0$
 and
$V_0$
 are unitary. Then

Let
$U = \theta U_0$
 and
$V = V_0$
 . It follows that
$W \simeq [U, V]$
 is a commutator of unitary operators.
5.6. Example. If
$ U \in \mathcal B(\mathbb C^3)$
 is a unitary operator, then U is not a commutator of unitary operators in
$\mathcal B(\mathbb C^3)$
 .
Clearly, it suffices to show that if
$U = \begin {bmatrix} \alpha _1 & 0 & 0 \\ 0 & \alpha _2 & 0 \\ 0 & 0 & \alpha _3 \end {bmatrix}$
 with respect to some orthonormal basis
$\{ e_1, e_2, e_3\}$
 for
$\mathbb C^3$
 and
$V = [v_{ij}]$
 are unitary operators in
$\mathcal B(\mathbb C^3)$
 , then
$W := [U, V]$
 is not unitary.
Suppose otherwise.
If
$\alpha _i = \alpha _j$
 for some
$i \ne j$
 , then
$(U- \alpha _i I)$
 has rank at most one, and so

has rank at most two, contradicting the fact that W is unitary. Thus,
$\alpha _1, \alpha _2, \alpha _3$
 are distinct.
The hypothesis that
$W = [w_{ij}] = [(\alpha _i - \alpha _j) v_{ij}]$
 is unitary implies that its columns form an orthonormal set. Consider

Since the
$\alpha _i$
 ’s are all distinct, this implies that
$v_{31} = 0$
 or
$v_{32} = 0$
 . By interchanging the first two basis vectors
$e_1$
 and
$e_2$
 if necessary (which does not affect the fact that U is diagonal), we may assume without loss of generality that
$v_{31} = 0$
 .
Next, consider the first and third columns of W:

Arguing as before, since the
$\alpha _i$
 ’s are all distinct, this implies that
$v_{21} = 0$
 or
$v_{23} = 0$
 .
-
• If $v_{21} = 0$
, then the first column of W is zero, contradicting the hypothesis that W is unitary. -
• If $v_{23} = 0$
, then
$V = \begin {bmatrix} v_{11} & v_{12} & v_{13} \\ v_{21} & v_{22} & 0 \\ 0 & v_{32} & v_{33} \end {bmatrix}$
. But V is unitary, and so the last two rows of V are mutually orthogonal. From this, we deduce that
$v_{22} = 0$
or
$v_{32} = 0$
. If
$v_{32} = 0$
, then a quick calculation shows that the last row of W is zero, again contradicting the hypothesis that W is unitary. Thus,
$v_{22} = 0$
. Since V is unitary, its first and second rows are orthogonal, proving that
$v_{11}=0$
.The hypothesis that W is unitary then implies that its first and third rows are orthogonal, which in turn implies that $v_{12} = 0$
or
$v_{32}= 0$
. From above, this in turn forces
$v_{12} = 0$
. Since V is also unitary, this then forces
$v_{33} = 0$
. We conclude that $$\begin{align*}V = \begin{bmatrix} 0 & 0 & v_{13} \\ v_{21} & 0 & 0 \\ 0 & v_{32} & 0 \end{bmatrix}. \end{align*}$$


In particular,
$|v_{13}| = |v_{21}| = |v_{32}| = 1$
 .
Hence,

Since W is unitary, we again conclude that
$|(\alpha _1 - \alpha _3) v_{13}| = | (\alpha _2 - \alpha _1) v_{21}| = | (\alpha _3 - \alpha _2) v_{32}| = 1$
 , and so
$|\alpha _1 - \alpha _3| = | \alpha _2 - \alpha _1| = | \alpha _3 - \alpha _2 |= 1$
 .
In other words,
$\alpha _1, \alpha _2$
 and
$\alpha _3 \in \mathbb T$
 are all at a distance of one from one another. Clearly, this is impossible.
5.7. Example. The above phenomenon does not extend to higher dimensions. Let
$W = \mathrm {diag} (\alpha , -\alpha , \beta , -\beta ) \in \mathcal U_4(\mathbb C)$
 . Then
$W = W_1 \oplus W_2$
 where, by Example 5.5,
$W_1 = [U_1, V_1]$
 and
$W_2 = [U_2, V_2]$
 for unitary matrices
$U_1, U_2, V_1, V_2 \in \mathcal U_2(\mathbb C)$
 . Hence,

where
$U = U_1 \oplus U_2$
 and
$V= V_1 \oplus V_2$
 .
Acknowledgements
The authors wish to thank the anonymous referee for an exceptionally thorough reading of the paper and for a great many suggestions which improved the exposition.



