


1. Introduction
In this work we are concerned with the existence of stationary distributions of regime-switching processes driven by Lévy noise, and further analyze the tail behavior of these distributions. We are motivated by the works of de Saporta and Yao [Reference de Saporta and Yao6] and Bardet et al. [Reference Bardet, Guérin and Malrieu1]. It has been shown in different ways that in contrast with the classical Ornstein–Uhlenbeck process whose stationary distribution must be light-tailed, the stationary distribution of the Ornstein–Uhlenbeck process with regime switching may have a heavy-tailed stationary distribution. Moreover, in a recent work, Hou and Shao [Reference Hou and Shao7] showed that the Cox–Ingersoll–Ross (CIR) process with regime switching may have a heavy-tailed stationary distribution, which provides a suitable modification of the classical CIR model due to its poor empirical performance as shown by Brown and Dybvig [Reference Brown and Dybvig4]. Hence, from the application viewpoint, it is important to study stochastic processes with regime switching.
The Lévy-driven Ornstein–Uhlenbeck process has a lot of applications in the study of mathematical finance (see, e.g., [Reference Barndorff-Nielsen, Mikosch and Resnick2, Reference Barndorff-Nielsen and Shephard3, Reference Carmona, Petit and Yor5, Reference Lindner and Maller8, Reference Novikov9], amongst others). In this work we shall extend the study of [Reference de Saporta and Yao6] and [Reference Bardet, Guérin and Malrieu1] to Lévy-driven Ornstein–Uhlenbeck processes with regime switching. We shall provide explicit conditions to justify the recurrence and transience of such a process, and determine the role played by the random change of the environment. Furthermore, given the existence of a stationary distribution, we provide explicit conditions to justify whether it is light- or heavy-tailed. In this part we are mainly interested in determining the different role played by Lévy jumps and regime switching in determining the heavy-tailed property of the stationary distribution.
Precisely, we consider the following stochastic processes  $(X_t,{\Lambda}_t)$:
 \begin{equation}{\text{d}} X_t=\alpha_{{\Lambda}_t}X_t{\text{d}} t+\sigma_{{\Lambda}_t}{\text{d}} Z_t,\qquad X_0=x_0\in {\mathbb R},\end{equation}
where  $({\Lambda}_t)$ is a continuous-time Markov chain on a finite state space
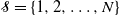 ${\mathcal S}=\{1,2,\ldots,N\}$,
 $2\leq N<\infty$, with the transition rate matrix
 $Q=(q_{ij})_{i,j\in {\mathcal S}}$, which is assumed to be conservative and irreducible. Here,
 $\alpha\,:\,{\mathcal S}\to {\mathbb R}$ and
 $\sigma\,:\,{\mathcal S}\to {\mathbb R}$ are measurable functions, and
 $Z=(Z_t)_{t\geq 0}$ is a Lévy process on
 ${\mathbb R}$ given by
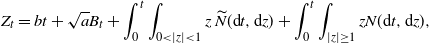 \begin{equation}Z_t=b t+\sqrt{a} B_t+\int_0^t\int_{0<|z|<1} z\,\skew3\widetilde{N}({\text{d}} t,{\text{d}} z)+\int_0^t \int_{|z|\geq 1} zN({\text{d}} t,{\text{d}} z),\end{equation}
where  $b\in {\mathbb R}$,
 $a>0$,
 $B=(B_t)_{t\geq 0}$ is a standard one-dimensional Brownian motion,
 $N({\text{d}} t,{\text{d}} z)$ is a Poisson random measure on
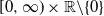 $[0,\infty)\times {\mathbb R}\backslash\{0\}$, and
 $\skew3\widetilde{N}({\text{d}} t,{\text{d}} z)$ is its corresponding compensated Poisson random measure relative to the Lévy measure
 $\nu$, i.e.
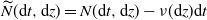 $\skew3\widetilde{N}({\text{d}} t,{\text{d}} z)=N({\text{d}} t,{\text{d}} z)-\nu({\text{d}} z){\text{d}} t$. Throughout, it is assumed that
 $({\Lambda}_t)$ is independent of the Lévy process
 $(Z_t)$. As a Lévy measure,
 $\nu$ is a
 $\sigma$-finite measure on
 ${\mathbb R}$ satisfying
 $\nu(\{0\})=0$ and
 \begin{equation}\int_{z\neq 0}(1\wedge |z|^2)\,\nu({\text{d}} z)<\infty.\end{equation}
Since the Markov chain  $({\Lambda}_t)$ is in a finite state space with a conservative and irreducible Q-matrix, there exists a unique stationary distribution, denoted by
 $\mu=(\mu_i)_{i\in {\mathcal S}}$. Our first result is on the recurrent property of
 $(X_t,{\Lambda}_t)$.
(i) Assume that
(1.4)then \begin{equation}\int_{|z|\neq 0} \log(1+|z|)\nu({\text{d}} z)<\infty ; \end{equation}$(X_t,{\Lambda}_t)$ is positive recurrent if $\sum_{i\in{\mathcal S}} \mu_i \alpha_i<0$.
(ii) Assume that
(1.5)then\begin{equation}\int_{|z|\neq 0} |z|\vee |z|^2\nu({\text{d}} z)<\infty ; \end{equation}$(X_t,{\Lambda}_t)$ is transient if $\sum_{i\in {\mathcal S}} \mu_i\alpha_i>0$.


Restricted to the set  $\{0<|z|<1\}$, each of (1.4) and (1.5) can yield
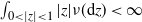 $\int_{0<|z|<1}|z|\nu({\text{d}} z)<\infty$, which is stronger than the necessary condition (1.3) and seems not to be a necessary one. Nevertheless, restricted to the set
 $\{|z|\geq 1\}$, our condition (1.4) is just condition (1.3) in [Reference Sato and Yamazato10]. In [Reference Sato and Yamazato10], Sato and Yamazato showed that this condition is a sharp condition on the integrability of the Lévy measure
 $\nu$ so that the associated Ornstein–Uhlenbeck process without regime switching is positive recurrent. Later, Shiga [Reference Shiga14] provided a recurrence criterion for this kind of process in one dimension and discussed several symmetric multidimensional cases. References [Reference Sato, Watanabe and Yamazato11] and [Reference Sato, Watanabe, Yamamuro and Yamazato12] also investigated the recurrence criterion in multidimensional cases, and finally Watanabe [Reference Watanabe15] used the Fourier analytic method to provide a general recurrence criterion for Lévy-driven Ornstein–Uhlenbeck processes which solved Sato’s conjecture in the affirmative.
Next, when  $(X_t,{\Lambda}_t)$ is positive recurrent, it owns a unique stationary distribution
 $\pi$. Concerning the tail behavior of
 $\pi$, we establish the following result:
Theorem 1.2. Assume that (1.4) and  $\sum_{i\in{\mathcal S}}\mu_i\alpha_i<0$ hold, and denote by
 $\pi$ the stationary distribution of
 $(X_t,{\Lambda}_t)$.
(i) If there exists some
$i_0\in{\mathcal S}$ such that, for any $\lambda>0$,
(1.6)then\begin{equation} \int_{|z|\geq 1} ({\text{e}}^{\lambda \sigma_{i_0} z}-1)\nu({\text{d}} z)=\infty, \end{equation}$\pi$ is heavy-tailed, i.e.
\begin{equation*} \sum_{j\in {\mathcal S}}\int_{{\mathbb R}}{\text{e}}^{\lambda |x|} \pi({\text{d}} x, j)=\infty,\quad \textit{for all } \lambda>0. \end{equation*}(ii) Suppose there exists a
$\lambda_0>0$ such that, for each $i\in{\mathcal S}$,
(1.7)\begin{equation} \int_{|z|\geq 1} ({\text{e}}^{\lambda_0|\sigma_i z|}-1)\nu({\text{d}} z)<\infty. \end{equation}


If  $\max_{i\in{\mathcal S}}\alpha_i<0$, then
 $\pi$ is light-tailed. If
 $\max_{i\in{\mathcal S}}\alpha_i>0$ then, for any
 $p>\kappa \vee 2$,
 \begin{equation*}\sum_{j\in {\mathcal S}}\int_{{\mathbb R}}|x|^p\pi({\text{d}} x,j )=\infty,\end{equation*}
which means that  $\pi$ is heavy-tailed, where
 $\kappa>0$ is given in (1.9) below.
For any  $p>0$, define
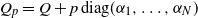 $Q_p=Q+p \, \text{diag}(\alpha_1,\ldots,\alpha_N)$, where
 $Q=(q_{ij})$ is the transition rate matrix of
 $({\Lambda}_t)$, and
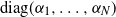 $\text{diag}(\alpha_1,\ldots,\alpha_N)$ is the diagonal matrix generated by the vector
 $(\alpha_1,\ldots,\alpha_N)$. Let
 \begin{equation}\eta_p=-\max_{\gamma\in \text{Spec}(Q_p)}\text{Re}\,\gamma,\end{equation}
where  $\text{Spec}(Q_p)$ stands for the spectrum of
 $Q_p$. Define
 \begin{equation}\kappa=\sup\{p>0;\, \eta_p>0\}.\end{equation}
According to [Reference Bardet, Guérin and Malrieu1, Propositions 4.1, 4.2],  $\kappa=\infty$ if
 $\max\limits_{i\in {\mathcal S}}\alpha_i\leq 0$; otherwise,
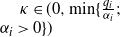 $\kappa\in (0,\min\{\frac{q_i}{\alpha_i};\break\alpha_i>0\})$. Moreover, for
 $p>\kappa$,
 $\eta_p<0$, and for
 $p\in (0,\kappa)$,
 $\eta_p>0$.
Remark 1.1. According to the characterization of the tail behavior for the Lévy-driven Ornstein–Uhlenbeck process in Lemma 2.1 below, assertion (i) of Theorem 1.2 tells us that if in some fixed environment the Lévy measure  $\nu$ makes the stationary distribution for the Ornstein–Uhlenbeck process without switching be heavy-tailed, then the stationary distribution of the Ornstein–Uhlenbeck process with switching must be heavy-tailed regardless of the random switching of the environment.
Assertion (ii) of Theorem 1.2 tells us that under a slightly stronger condition on  $\nu$ which ensures that the Ornstein–Uhlenbeck process in every fixed environment must own a light-tailed stationary distribution, the random switching process
 $({\Lambda}_t)$ can change the tail behavior of the stationary distribution of
 $(X_t,{\Lambda}_t)$ according to the signal of
 $\max_{i\in{\mathcal S}}\alpha_i$.
The proofs of Theorems 1.1 and 1.2 are presented in the next section.
2. Proofs of the main results
In this section we shall first present the argument of Theorem 1.1 on the recurrent property of the process  $(X_t,{\Lambda}_t)$. To this end, we need to extend the Lyapunov-type criterion established by Shao in [Reference Shao13] for stochastic processes driven by Brownian motion to the current situation.
Let us first introduce some notation. For each  $i\in {\mathcal S}$, define
 \begin{equation*} \begin{split}{\mathcal{D}}^{(i)}f(\cdot,i)(x)&= (\alpha_i x+b\sigma_i)\frac{\partial f(x,i)}{\partial x}+\frac{a\sigma_i^2}{2}\frac{\partial^2f(x,i)}{\partial x^2},\\{\mathcal{J}}^{(i)} f(\cdot,i)(x)&=\int_{z\neq 0}\bigg[f(x+\sigma_iz,i)-f(x,i)-\sigma_i z\frac{\partial f(x,i)}{\partial x}\textbf{1}_{0<|z|<1}\bigg]\nu({\text{d}} z),\\ L^{(i)} f(\cdot,i)(x)&=\mathcal{D}^{(i)} f(\cdot,i)(x)+{{\mathcal{J}}^{(i)}} f(\cdot,i)(x) \end{split}\end{equation*}
for  $f(\cdot,i)\in C^2({\mathbb R})$. Then the infinitesimal generator of the process
 $(X_t,{\Lambda}_t)$ is given by
 \begin{equation*} \begin{split}{\mathcal{A}} f(x,i)&=L^{(i)} f(\cdot,i)(x)+Qf(x,\cdot)(i)\\&=L^{(i)}f(\cdot,i)(x)+\sum_{j\neq i}q_{ij}(f(x,j)-f(x,i)),\qquad f(\cdot,i)\in C^2({\mathbb R}).\end{split}\end{equation*}
Following the same approach as [Reference Shao13, Theorems 2.1, 3.1], we can establish the following criterion to justify the recurrence of the Lévy-driven process  $(X_t,{\Lambda}_t)$. The details are omitted.
Proposition 2.1. Let  $\mu$ be the stationary distribution of
 $({\Lambda}_t)$.
(i) Suppose that there exist constants
$r_0>0$, $\beta_i\in {\mathbb R}$, $i\in{\mathcal S}$, and a positive function V(x) such that
satisfying\begin{equation*} L^{(i)} V(x)\leq \beta_iV(x),\qquad |x|\geq r_0, \quad i\in{\mathcal S},\end{equation*}$\sum_{i\in{\mathcal S}}\mu_i \beta_i<0$. Then $(X_t,{\Lambda}_t)$ is exponentially ergodic if $\lim_{|x|\to\infty} V(x)=\infty$, and is transient if $\lim_{|x|{\rightarrow} \infty} V(x)=0$.(ii) Suppose that there exist constants
$r_0>0$, $\beta_i\in {\mathbb R}$, $i\in {\mathcal S}$, and two positive functions $h,\,g \in C^2({\mathbb R})$ such that, for each $i\in {\mathcal S}$,
(2.1)and\begin{equation} L^{(i)}h(x)\leq \beta_i g(x),\qquad |x|>r_0,\end{equation}Assume that\begin{equation*} \lim_{|x|\to\infty} \frac{g(x)}{h(x)}=0,\qquad \lim_{|x|\to \infty} \frac{L^{(i)} g(x)}{g(x)}=0.\end{equation*}Then\begin{equation*} \sum_{i\in{\mathcal S}}\mu_i\beta_i<0.\end{equation*}$(X_t,{\Lambda}_t)$ given by (1.1) and (1.2) is positive recurrent if $\lim_{|x|\to \infty} h(x)=\infty$, and is transient if $\lim_{|x|\to \infty} h(x)=0$.


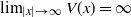
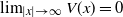


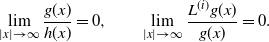


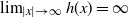
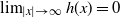
Remark 2.1. In Proposition 2.1 we state that  $(X_t,{\Lambda}_t)$ is positive recurrent when
 $\sum_{i\in{\mathcal S}}\mu_i\beta_i<0$ and
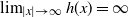 $\lim_{|x|\to\infty} h(x)=\infty$, which is a little stronger than the result presented in [Reference Shao13, Theorem 3.1]. However, the argument in [Reference Shao13] is sufficient for this statement according to the Foster–Lyapunov criterion.
Proof of Theorem 1.1. First, let us prove the positive recurrence of  $(X_t,{\Lambda}_t)$ in the situation
 $\sum_{i\in{\mathcal S}}\mu_i\alpha_i<0$ by part (ii) of Proposition 2.1. Consider the auxiliary functions
 \begin{equation*}h(x)=\log(1+x^2),\qquad g(x)=\frac{2x^2}{1+x^2}.\end{equation*}
It is easy to check that 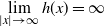 $\displaystyle\lim_{|x|\to \infty} h(x)=\infty$ and
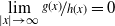 $\displaystyle\lim_{|x|\to \infty} \nicefrac{g(x)}{h(x)}=0$.
Now we verify that 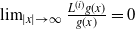 $\lim_{|x|\to\infty} \frac{L^{(i)}g(x)}{g(x)}=0$. Note that
 \begin{equation}\frac{{{\mathcal{D}}^{(i)}} g(x)}{g(x)}=\frac{2\alpha_i}{1+x^2}+\frac{2b\sigma_i}{x(1+x^2)}+\frac{a\sigma_i^2(1-3x^2)}{x^2(1+x^2)^2}\longrightarrow 0 \qquad \text{as}\ |x|\to \infty.\end{equation}
For the jumping component, we have
 \begin{equation*} \begin{split}\frac{{{\mathcal{J}}^{(i)}} g(x)}{g(x)}&=\frac{1}{g(x)}\int_{z\neq 0}\!\!(g(x+\sigma_iz)-g(x)-\sigma_izg'(x)\textbf{1}_{\{0<|z|<1\}}(z))\nu({\text{d}} z)\\&=\bigg(1+\frac 1{x^2}\bigg)\int_{z\neq 0}\!\frac{\sigma_i^2z^2+2\sigma_i xz}{(1+x^2)(1+(x+\sigma_iz)^2)}\nu({\text{d}} z)\\&\qquad \qquad -\frac{2\sigma_i}{x(1+x^2)}\int_{z\neq 0}\!z\textbf{1}_{|z|<1}\nu({\text{d}} z).\end{split}\end{equation*}
Due to condition (1.4), it is obvious that
 \begin{equation*}\lim_{|x|\to \infty} \frac{2\sigma_i}{x(1+x^2)}\int_{z\neq 0}\!(1\wedge |z|)\nu({\text{d}} z)=0.\end{equation*}
Because
 \begin{equation*}\bigg|\frac{\sigma_i^2z^2+2\sigma_i xz}{(1+x^2)(1+(x+\sigma_iz)^2)}\bigg|=\bigg|\frac{(\sigma_iz+x)^2-x^2}{(1+x^2)(1+(x+\sigma_iz)^2)}\bigg|\leq 1\end{equation*}
and
 \begin{equation*}\bigg|\frac{\sigma_i^2z^2+2\sigma_i xz}{(1+x^2)(1+(x+\sigma_iz)^2)}\bigg|\leq \bigg|\frac{\sigma_i^2 z^2+2\sigma_ixz}{(1+x^2)}\bigg|\leq \sigma_i^2 z^2+|\sigma_iz|,\end{equation*}
we obtain that
 \begin{equation*}\bigg|\frac{\sigma_i^2z^2+2\sigma_i xz}{(1+x^2)(1+(x+\sigma_iz)^2)}\bigg|\leq \min\{1, \sigma_i^2z^2+|\sigma_i z|\}.\end{equation*}
Invoking condition (1.4), the dominated convergence theorem yields that
 \begin{equation*} \lim_{|x|\to \infty} \bigg(1+\frac{1}{x^2}\bigg)\int_{z\neq 0}\!\frac{\sigma_i^2+2\sigma_i xz}{(1+x^2)(1+(x+\sigma_iz)^2)}\nu({\text{d}} z)=0.\end{equation*}
Hence,
 \begin{equation*} \lim_{|x|\to \infty} \frac{{{\mathcal{J}}^{(i)}} g(x)}{g(x)}=0.\end{equation*}
Combining with (2.2), this further implies that
 \begin{equation*}\lim_{|x|\to \infty} \frac{L^{(i)} g(x)}{g(x)}= 0.\end{equation*}
Next, we shall show that for any  ${\varepsilon}$ satisfying
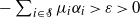 $-\sum_{i\in{\mathcal S}}\mu_i\alpha_i>{\varepsilon}>0$, there exists a constant
 $r_0>0$ such that, for every
 $i\in{\mathcal S}$,
 \begin{equation}L^{(i)} h(x)\leq (\alpha_i+{\varepsilon}) g(x)\qquad \text{as}\ |x|\geq r_0.\end{equation}
So, by taking  $\beta_i=\alpha_i+{\varepsilon}$ in (2.1), Proposition 2.1 yields that
 $(X_t,{\Lambda}_t)$ is positive recurrent.
Indeed, for the diffusion part of  $L^{(i)}h$ we have
 \begin{align} {{\mathcal{D}}^{(i)}} h(x)&=(\alpha_i x+b\sigma_i)\frac{2x}{1+x^2}+a\sigma_i^2\frac{1-x^2}{(1+x^2)^2} \nonumber \\ &\leq \bigg(\alpha_i+\frac{b\sigma_i}x+\frac{a\sigma_i^2|1-x^2|}{2x^2(1+x^2)}\bigg)g(x).\end{align}
Due to the finiteness of the number of states in  ${\mathcal S}$, it is clear that there exists
 $r_1>0$ such that
 \begin{equation}\frac{b\sigma_i}{x}+\frac{a\sigma_i^2|1-x^2|}{2x^2(1+x^2)}\leq \frac{{\varepsilon}}{4} \qquad \text{for all } |x|\geq r_1,\ i\in {\mathcal S}.\end{equation}
For the jump part of  $L^{(i)} h$, direct calculation leads to
 \begin{align*} {{\mathcal{J}}^{(i)}} h(x)&=\int_{z\neq 0}\![\log(1+(x+\sigma_i z)^2)-\log(1+x^2)]\nu({\text{d}} z)-\frac{2\sigma_ix}{1+x^2}\int_{0<|z|<1}\!z\,\nu({\text{d}} z).\end{align*}
Since
 \begin{align*} \log(1+(x+\sigma_iz)^2)-\log(1+x^2)&\leq \log\bigg(1+\frac{\sigma_i^2z^2}{1+x^2}+\frac{2x}{1+x^2}|\sigma_iz|\bigg)\\ &\leq \log(1+|\sigma_i z|+\sigma_i^2z^2)\leq 2\log(1+|\sigma_iz|),\end{align*}
we obtain from condition (1.4) and the dominated convergence theorem that
 \begin{equation*}\lim_{|x|\to \infty} {{\mathcal{J}}^{(i)}} h(x) =0.\end{equation*}
Noting that  $g(x)\geq 1$ for
 $|x|\geq 1$, there exists
 $r_2>1$ such that, for any
 $|x|\geq r_2$,
 \begin{equation}{{\mathcal{J}}^{(i)}} h(x)\leq \frac{{\varepsilon}}{4} g(x).\end{equation}
Consequently, (2.3) follows from (2.4), (2.5), and (2.6) by taking 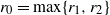 $ r_0=\max\{r_1,r_2\}$.
Second, we go on to prove the transience of  $(X_t,{\Lambda}_t)$ in the case
 $\sum_{i\in{\mathcal S}}\mu_i\alpha_i>0$. To this end, we consider the function
 \begin{equation*}V(x)=\frac{1}{\delta+x^2}\end{equation*}
for some fixed  $0 < \delta < 1$, and prove the desired result according to part (i) of Proposition 2.1. We have,
 \begin{equation}{{\mathcal{D}}^{(i)}} V(x)=\bigg({-}2\alpha_i\frac{x^2}{\delta+x^2}-2b\sigma_i\frac{x}{\delta+x^2}+a\sigma_i^2\frac{3x^2-\delta}{(\delta+x^2)^2}\bigg)V(x),\end{equation}
and clearly
 \begin{equation*}\lim_{|x|\to \infty} -2\alpha_i\frac{x^2}{\delta+x^2}-2b\sigma_i\frac{x}{\delta+x^2}+a\sigma_i^2\frac{3x^2-\delta}{(\delta+x^2)^2}=-2\alpha_i.\end{equation*}
For the jump part of  $L^{(i)}V$ we have
 \begin{equation}{{\mathcal{J}}^{(i)}} V(x)=\bigg( \int_{z\neq 0}\!\!\frac{x^2-(x+\sigma_i z)^2}{\delta+(x+\sigma_iz)^2}\nu({\text{d}} z)+\frac{2\sigma_i x}{\delta+x^2}\int_{0<|z|<1}\!\! z\nu({\text{d}} z)\bigg) V(x).\end{equation}
Moreover,
 \begin{align*}\int_{z\neq 0}\frac{x^2-(x+\sigma_iz)^2}{\delta+(x+\sigma_iz)^2}\nu({\text{d}} z)&=\int_{|z|\geq 1}\!\frac{x^2-(x+\sigma_iz)^2}{\delta+(x+\sigma_iz)^2}\nu({\text{d}} z) \\ & \quad +\int_{0<|z|<1}\!\frac{x^2-(x+\sigma_iz)^2}{\delta+(x+\sigma_iz)^2}\nu({\text{d}} z)\\&=\!:\,I_1+I_2.\end{align*}
To estimate the term  $I_1$, since
 $0 < \delta < 1$ we have
 \begin{align*} \bigg|\frac{x^2-(x+\sigma_iz)^2}{\delta+(x+\sigma_iz)^2}\bigg| &\leq \frac{2|x\sigma_i z|}{\delta+(x+\sigma_iz)^2}+\frac{\sigma_i^2 z^2}{\delta} \\ &\leq \frac{(x+\sigma_iz)^2}{\delta+(x+\sigma_iz)^2}+\frac{\sigma_i^2 z^2}{\delta}\\ &\leq \frac{1}{\delta}+\frac{\sigma_i^2}{\delta}z^2,\end{align*}
and  $\frac{1}{\delta}+\frac{\sigma_i^2z^2}{\delta}$ is an integrable function with respect to
 $\textbf{1}_{|z|\geq 1}\nu({\text{d}} z)$ by condition (1.5). Then, the dominated convergence theorem leads to
 \begin{equation}\lim_{|x|\to \infty} \int_{|z|\geq 1} \frac{x^2-(x+\sigma_iz)^2}{\delta+(x+\sigma_iz)^2}\nu({\text{d}} z) =0.\end{equation}
To estimate the term  $I_2$, let us consider
 \begin{equation*}u(x)\,:\!=\frac{2x\sigma_iz}{\delta+(x+\sigma_iz)^2} \qquad \text{for $0<|z|<1$},\end{equation*}
and direct calculation leads to
 \begin{equation*}u'(x)=\frac{2\sigma_iz \delta-2\sigma_izx^2+2(\sigma_i z)^3}{(\delta+(x+\sigma_iz)^2)^2}.\end{equation*}
Hence, there exists  $r_1>0$ such that, for
 $|x|\geq r_1$,
 $u'(x)>0$ if
 $\sigma_iz<0$ and
 $u'(x)<0$ if
 $\sigma_iz>0$, which means that
 $|u(x)|$ is monotone when
 $|x|\geq r_1$. Noting that
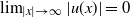 $\lim_{|x|\to\infty} |u(x)|=0$, we have
 \begin{equation}\sup_{|x|\geq r_1} |u(x)|=\sup_{|x|=r_1} |u(x)|=\max\bigg\{\frac{2r_1 \sigma_i z}{\delta+(r_1+\sigma_iz)^2}, \frac{-2r_1\sigma_iz}{\delta+(\sigma_iz-r_1)^2}\bigg\} . \end{equation}
Since
 \begin{equation*} \bigg|\frac{x^2-(x+\sigma_iz)^2}{\delta+(x+\sigma_iz)^2}\bigg|\leq |u(x)|+\frac{\sigma_i^2 z^2}{\delta},\end{equation*}
it follows from (2.10), condition (1.5), and the dominated convergence theorem that
 \begin{equation}\lim_{|x|\to \infty} \int_{0<|z|<1}\!\frac{x^2-(x+\sigma_iz)^2}{\delta+(x+\sigma_iz)^2}\nu({\text{d}} z)=0.\end{equation}
Invoking (2.7), (2.9), (2.11), and condition (1.4), by (2.8), for any  ${\varepsilon}$ in
 $(0,\sum_{i\in{\mathcal S}} \mu_i\alpha_i)$ there exists
 $r_0>r_1>0$ such that
 \begin{equation*} L^{(i)} V(x)={{\mathcal{D}}^{(i)}} V(x)+{{\mathcal{J}}^{(i)}} V(x)\leq ({-}2\alpha_i+ {\varepsilon})V(x),\qquad |x|\geq r_0.\end{equation*}
According to Proposition 2.1 $(X_t,{\Lambda}_t)$ is transient, which completes the proof.
Next, we proceed to investigate the tail property of the stationary distribution  $\pi({\text{d}} x, i)$ of
 $(X_t,{\Lambda}_t)$. Before this, we present a lemma on the tail property of the stationary distribution of a Lévy-driven Ornstein–Uhlenbeck process without regime switching, which tells us how the jumping component impacts the tail behavior of its stationary distribution.
Consider the process
 \begin{equation}{\text{d}} Y_t=\alpha Y_t{\text{d}} t+\sigma {\text{d}} Z_t, \qquad Y_0=y_0\in {\mathbb R},\end{equation}
where  $\alpha<0$,
 $\sigma\in {\mathbb R}$, and
 $(Z_t)_{t\geq 0}$ is still given by (1.2) satisfying condition (1.4). Then the process
 $(Y_t)$ is positive recurrent (cf. Theorem 1.1 or [Reference Sato and Yamazato10, Theorem 4.1]), and its stationary distribution is denoted by
 $\tilde \pi$.
Lemma 2.1. Assume condition (1.4) holds. Consider the process  $(Y_t)$ given by (2.12) and its stationary distribution
 $\tilde \pi$.
(i) If, for some
$\lambda_0>0$,
(2.13)then\begin{equation} \int_{|z|\geq 1} ({\text{e}}^{\lambda_0 \sigma z}-1)\nu({\text{d}} z)<\infty, \end{equation}$\int_{{\mathbb R}} {\text{e}}^{\lambda_0 |x|}\tilde \pi({\text{d}} x)<\infty$, which means that $\tilde \pi$ is light-tailed.(ii) If, for any
$\lambda>0$,
(2.14)then, for any\begin{equation} \int_{|z|\geq 1}({\text{e}}^{\lambda\sigma z}-1)\nu({\text{d}} z)=\infty, \end{equation}$\lambda>0$, $\int_{{\mathbb R}} {\text{e}}^{\lambda x}\tilde \pi({\text{d}} x)=\infty$, which means that $\tilde \pi$ is heavy-tailed.


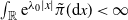


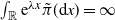

Proof. (i) The characteristic function of the Lévy process  $(Z_t)$ given by (1.2) is
 \begin{equation*}\text{E}({\text{e}}^{{\hat{\imath}} u Z_t})={\text{e}}^{-t\Phi(u)},\qquad u\in {\mathbb R}, \ t\geq 0,\end{equation*}
where  ${\hat{\imath}}$ is the imaginary unit, and
 $\Phi$ is given by the Lévy–Khintchine representation
 \begin{equation} \Phi(u)=\frac12 au^2-{\hat{\imath}} bu+\int_{z\neq 0}\!(1-{\text{e}}^{{\hat{\imath}} uz}+{\hat{\imath}} uz\textbf{1}_{0<|z|<1})\nu({\text{d}} z). \end{equation}
The stationary distribution  $\tilde \pi$ of
 $(Y_t)$ has the characteristic function
 \begin{equation} \widehat{\tilde\pi}(z)=\exp\bigg(\int_0^\infty -\Phi({\text{e}}^{\alpha t}\sigma z){\text{d}} t\bigg). \end{equation}
This yields
 \begin{equation} \int_{{\mathbb R}} {\text{e}}^{\lambda_0 x}\tilde \pi({\text{d}} x)=\widehat{\tilde \pi}({-}{\hat{\imath}} \lambda_0)=\exp\bigg(\int_0^\infty -\Phi({-}{\hat{\imath}} \lambda_0 \sigma {\text{e}}^{\alpha t}){\text{d}} t\bigg). \end{equation}
Due to (2.15),
 \begin{align} \int_0^\infty \!\!\!-\Phi({-}{\hat{\imath}} \lambda_0 \sigma {\text{e}}^{\alpha t}){\text{d}} t&=\int_0^\infty \bigg(\frac 12a \lambda_0^2\sigma^2{\text{e}}^{2\alpha t}+b\lambda_0 \sigma {\text{e}}^{\alpha t}\bigg){\text{d}} t \nonumber \\ &\quad+\int_0^\infty\!\!\int_{z\neq 0}\!(\!\exp(z\lambda_0 \sigma {\text{e}}^{\alpha t})-1-z\lambda_0 \sigma {\text{e}}^{\alpha t}\textbf{1}_{0<|z|<1})\nu({\text{d}} z){\text{d}} t\nonumber \\ & =\!:\,I_1+I_2. \end{align}
As  $\alpha<0$, it is clear that
 \begin{equation*}I_1=-\frac{a\lambda_0^2\sigma^2}{4\alpha}-\frac{b\lambda_0 \sigma}{\alpha}<\infty.\end{equation*}
Performing the variable substitution  $u={\text{e}}^{\alpha t}$, we get
 \begin{align*}I_2&=-\frac{1}{\alpha}\int_0^1\int_{z\neq 0}\!\frac{1}{u}({\text{e}}^{z\lambda_0 \sigma u}-1)\nu({\text{d}} z){\text{d}} u+\frac{\lambda_0 \sigma}{\alpha}\bigg(\int_{z\neq 0}\!z\textbf{1}_{0<|z|<1}\nu({\text{d}} z)\bigg)\\&\leq -\frac{1}{\alpha}\int_{z\neq 0}({\text{e}}^{\lambda_0\sigma z}-1)\nu({\text{d}} z)+\frac{\lambda_0 \sigma}{\alpha}\bigg(\int_{z\neq 0}\!z\textbf{1}_{0<|z|<1}\nu({\text{d}} z)\bigg),\end{align*}
where we used the fact that the function 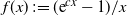 $f (x)\,:\!=({\text{e}}^{c x}-1)/x $ is increasing for any
 $c\neq 0$. Combining these estimates on
 $I_1$,
 $I_2$ with (2.17), (2.18), by (1.4) and (2.13), we finally obtain that
 \begin{equation*}\int_{{\mathbb R}} {\text{e}}^{\lambda_0 x}\tilde \pi({\text{d}} x)<\infty.\end{equation*}
Similarly, we can show that 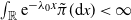 $\int_{{\mathbb R}}{\text{e}}^{-\lambda_0 x}\tilde \pi({\text{d}} x)<\infty$. Noting that
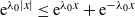 ${\text{e}}^{\lambda_0|x|}\leq {\text{e}}^{\lambda_0 x}+{\text{e}}^{-\lambda_0 x}$, we obtain that
 \begin{equation*}\int_{{\mathbb R}}{\text{e}}^{\lambda_0 |x|}\tilde \pi({\text{d}} x)<\infty.\end{equation*}
(ii) Replacing  $\lambda_0$ with any positive constant
 $\lambda$ in (2.17) and (2.18), we still have that
 \begin{equation*}I_1=-\frac{a\lambda^2\sigma^2}{4\alpha}-\frac{b\lambda \sigma}{\alpha}<\infty\end{equation*}
since  $\alpha<0$. However, in the current case,
 \begin{equation*} I_2=-\frac{1}{\alpha}\int_0^1\!\!\int_{z\neq 0}\frac1{u}({\text{e}}^{z\lambda\sigma u}-1)\nu({\text{d}} z){\text{d}} u+\frac{\lambda\sigma}{\alpha}\bigg(\int_{z\neq 0}\!\!z\textbf{1}_{0<|z|<1}\nu({\text{d}} z)\bigg).\end{equation*}
By conditions (1.4) and (2.14), there exists some  $C>0$ such that
 \begin{equation*}\int_{0<|z|<1} \frac1u({\text{e}}^{z\lambda \sigma u}-1)\nu({\text{d}} z)\leq C\int_{0<|z|<1} |z|\nu({\text{d}} z)<\infty,\end{equation*}
and
 \begin{equation*}\int_{|z|\geq 1}\! \frac1u({\text{e}}^{z\lambda \sigma u}-1)\nu({\text{d}} z)=\infty,\qquad u\neq 0.\end{equation*}
As a consequence,
 \begin{equation*}\int_{z\neq 0}\frac1{u}({\text{e}}^{z\lambda\sigma u}-1)\nu({\text{d}} z)=\infty,\end{equation*}
which implies  $I_2=\infty$ and
 \begin{equation*}\int_{{\mathbb R}}\!{\text{e}}^{\lambda x}\tilde \pi({\text{d}} x)=\infty.\end{equation*}
The arbitrariness of the positive constant  $\lambda$ implies that
 $\tilde \pi$ is heavy-tailed, which completes the proof of this lemma.
Proof of Theorem 1.2. (i) We prove this assertion by contradiction. Assume that there exists a  $\delta_0>0$ such that
 \begin{equation}\sum_{j\in{\mathcal S}}\int_{{\mathbb R}}{\text{e}}^{2\delta_0|x|}\pi({\text{d}} x, j)<\infty.\end{equation}
Applying Itô’s formula, we obtain that
 \begin{align} \text{E}({\text{e}}^{\delta_0 X_t})-\text{E}({\text{e}}^{\delta_0 X_0}) &=\text{E}\int_0^t\delta_0{\text{e}}^{\delta_0 X_{s-}} \bigg(\alpha_{{\Lambda}_{s-}}X_{s-}+b\sigma_{{\Lambda}_{s-}}+\frac{a\delta_0}{2}\sigma_{{\Lambda}_{s-}}^2\bigg){\text{d}} s \nonumber \\ &\quad+2\text{E}\int_0^t\int_{|z|\geq 1} {\text{e}}^{\delta_0 X_{s-}}({\text{e}}^{\delta_0\sigma_{{\Lambda}_{s-}} z}-1)\nu({\text{d}} z){\text{d}} s \nonumber \\ &\quad+\text{E}\int_0^t\int_{0<|z|<1}\!\!{\text{e}}^{\delta_0 X_{s-}}({\text{e}}^{\delta_0\sigma_{{\Lambda}_{s-}}z}-1-\delta_0\sigma_{{\Lambda}_{s-}}z )\nu({\text{d}} z){\text{d}} s \nonumber \\ &=\!:\,I_1+I_2+I_3 .\end{align}
If we take the initial distribution of  $(X_0,{\Lambda}_0)$ to be the stationary distribution
 $\pi$, then for every
 $t>0$ the distribution of
 $(X_t,{\Lambda}_t)$ remains as
 $\pi$, which implies immediately that the left-hand side of (2.20) equals 0. From
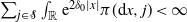 $\sum_{j\in {\mathcal S}} \int_{{\mathbb R}}{\text{e}}^{2\delta_0 |x|}\pi({\text{d}} x,j)<\infty$ and the finiteness of the number of states in
 ${\mathcal S}$, it is easy to see that
 \begin{equation*}\text{E}\bigg[ {\text{e}}^{\delta_0 X_{s-}}\bigg( |\alpha_{{\Lambda}_{s-}}X_{s-}|+|b\sigma_{{\Lambda}_{s-}}|+\frac{a\delta_0}{2}\sigma_{{\Lambda}_{s-}}^2\bigg)\bigg]<\infty,\end{equation*}
and hence the term  $I_1<\infty$. Condition (1.4) ensures that there exists a constant
 $C>0$ such that, for every
 $j\in {\mathcal S}$,
 \begin{equation*}\int_{0<|z|<1} |{\text{e}}^{\delta_0\sigma_j z}-1-\delta_0 \sigma_jz|\nu({\text{d}} z)\leq C\int_{0<|z|<1} |z|\nu({\text{d}} z)<\infty.\end{equation*}
Then, again using (2.19), we have  $I_3<\infty$. Nevertheless, the term
 $I_2$ is equal to
 $\infty$. Indeed, when
 ${\Lambda}_{s-}=i_0$, it follows from condition (1.6) that
 \begin{equation*} \int_{|z|\geq 1}({\text{e}}^{\delta_0\sigma_{{\Lambda}_{s-}}z}-1)\nu({\text{d}} z)=\infty.\end{equation*}
As an irreducible Markov chain,  $({\Lambda}_t)$ arrives at the state
 $i_0$ with a positive probability, so
 $I_2=\infty$. Therefore, we get a contradiction that the left-hand side of (2.20) equals 0, but the right-hand side of (2.20) equals
 $\infty$. Consequently,
 $\pi$ cannot be light-tailed in the current situation.
(ii) First, we show that  $\pi$ is light-tailed under the conditions (1.7) and
 $\max_{i\in {\mathcal S}} \alpha_i<0$. For
 $\delta\in (0,\lambda_0)$, similar to (2.20), Itô’s formula yields that
 \begin{align} \text{E}&( {\text{e}}^{\delta |X_t|})-\text{E}({\text{e}}^{\delta |X_0|}) \nonumber \\ &=\text{E}\int_0^t\bigg[\delta{\text{e}}^{\delta |X_{s-}|}{\text{sgn}}(X_{s-})(\alpha_{{\Lambda}_{s-}}X_{s-}+b\sigma_{{\Lambda}_{s-}})+ \frac{a\delta^2}{2}{\text{e}}^{\delta |X_{s-}|}\sigma_{{\Lambda}_{s-}}^2\bigg]{\text{d}} s \nonumber \\ &\quad+2\text{E}\int_0^t\int_{|z|\geq 1} ({\text{e}}^{\delta |X_{s-}+\sigma_{{\Lambda}_{s-}} z|}-{\text{e}}^{\delta |X_{s-}|})\nu({\text{d}} z){\text{d}} s \nonumber \\ &\quad+\text{E}\int_0^t\int_{0<|z|<1}\!\!({\text{e}}^{\delta| X_{s-}+\sigma_{{\Lambda}_{s-}}z|}-{\text{e}}^{\delta |X_{s-}|} -\delta {\text{e}}^{\delta |X_{s-}|}{\text{sgn}}(X_{s-})\sigma_{{\Lambda}_{s-}}z)\nu({\text{d}} z){\text{d}} s \nonumber \\ &=\!:\,J_1+J_2+J_3,\end{align}
where  ${\text{sgn}}(x)$ denotes the sign function of x.
Since  $\max_{i\in {\mathcal S}}\alpha_i<0$, for any
 $c>0$ there exists
 $M>0$ such that
 \begin{equation*} \alpha_{{\Lambda}_{s-}}|X_{s-}|+{\text{sgn}}(X_{s-})b\sigma_{{\Lambda}_{s-}}\leq -c+M {\text{e}}^{-\delta |X_{s-}|}.\end{equation*}
Therefore,
 \begin{equation}J_1\leq \int_0^t \text{E}( \delta M -c\delta {\text{e}}^{\delta |X_{s-}|} ) {\text{d}} s .\end{equation}
For  $J_2$, we have
 \begin{align}J_2&\leq \text{E}\int_0^t{\text{e}}^{\delta |X_{s-}|}\Big[\int_{|z|\geq 1}({\text{e}}^{\delta|\sigma_{{\Lambda}_{s-}}z|}-1)\nu({\text{d}} z)\Big]{\text{d}} s \nonumber \\&\leq K_1(\delta)\int_0^t \text{E}[{\text{e}}^{\delta |X_{s-}|}]{\text{d}} s,\end{align}
where
 \begin{equation*}K_1(\delta)=\max_{i\in{\mathcal S}} \int_{|z|\geq 1} ({\text{e}}^{\delta|\sigma_i z|}-1)\nu({\text{d}} z)<\infty \end{equation*}
due to (1.7) and  $\delta<\lambda_0$. Moreover,
 \begin{equation*}\lim_{\delta\to 0}\frac{K_1(\delta)}{\delta}\leq \lim_{\delta\to 0}\int_{|z|\geq 1}\!\!\frac{1}{\delta}({\text{e}}^{\delta\sigma_\ast |z|}-1)\nu({\text{d}} z)=\int_{|z|\geq 1}\!\!\sigma_\ast |z|\nu({\text{d}} z)<\infty,\end{equation*}
where 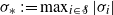 $\sigma_\ast \,:\!=\max_{i\in {\mathcal S}} |\sigma_i|$.
For  $J_3$, we have
 \begin{align} J_3&\leq \text{E}\int_0^t\!\int_{0<|z|<1}\!\!{\text{e}}^{\delta |X_{s-}|}({\text{e}}^{\delta|\sigma_{{\Lambda}_{s-}}z|}-1+\delta|\sigma_{{\Lambda}_{s-}}z|)\nu({\text{d}} z){\text{d}} s \nonumber \\ &\leq K_2(\delta)\int_0^t\text{E}({\text{e}}^{\delta|X_{s-}|}){\text{d}} s,\end{align}
where
 \begin{equation*}K_2(\delta)=\max_{i\in{\mathcal S}}\int_{0<|z|<1}\!\!({\text{e}}^{\delta |\sigma_i z|}-1+\delta|\sigma_iz|)\nu({\text{d}} z)<\infty, \end{equation*}
due to (1.4). Furthermore,
 \begin{equation*}\lim_{\delta\to 0}\frac{K_2(\delta)}{\delta}\leq \int_{0<|z|<1}\!\! 2\sigma_\ast |z|\nu({\text{d}} z)<\infty.\end{equation*}
Inserting (2.22), (2.23), and (2.24) into (2.21), we obtain
 \begin{equation*}\frac{{\text{d}}}{{\text{d}} t}\text{E}({\text{e}}^{\delta|X_t|})\leq M\delta+K_3(\delta) \text{E}({\text{e}}^{\delta|X_{t}|}),\end{equation*}
with 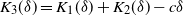 $K_3(\delta)=K_1(\delta)+K_2(\delta)-c\delta$. By the arbitrariness of c, we can take
 $\delta>0$ sufficiently small and
 $c>0$ large enough so that
 $K_3(\delta)<0$. Applying Gronwall’s inequality, we obtain
 \begin{equation*} \text{E}({\text{e}}^{\delta|X_t|})\leq \text{E}({\text{e}}^{\delta|X_0|}{\text{e}}^{K_3(\delta) t})+M\delta\int_0^t{\text{e}}^{K_3(\delta)(t-s)}{\text{d}} s.\end{equation*}
The negativeness of  $K_3(\delta)$ implies that
 \begin{equation}\sup_{t\geq 0} \text{E}({\text{e}}^{\delta|X_t|})<\infty\end{equation}
if  $\text{E}({\text{e}}^{\delta|X_0|})<\infty$. In particular, we take
 $(X_0,{\Lambda}_0)$ starting from some fixed point
 $(x_0,i)$, and the positive recurrence of
 $(X_t,{\Lambda}_t)$ yields that the distribution of
 $(X_t,{\Lambda}_t)$ weakly converges to its stationary distribution
 $\pi$. Together with the estimate (2.25), we finally get
 \begin{equation*}\sum_{j\in {\mathcal S}}\int_{{\mathbb R}}{\text{e}}^{\delta |x|}\pi({\text{d}} x, j)\leq \liminf_{t\to \infty} \text{E}({\text{e}}^{\delta |X_t|})<\sup_{t>0}\text{E}({\text{e}}^{\delta |X_t|})<\infty,\end{equation*}
which is the desired conclusion.
Second, we proceed to show that  $\pi$ is heavy-tailed under conditions (1.7) and
 $\max_{i\in{\mathcal S}}\alpha_i>0$. For
 $p>2\vee \kappa$, thanks to Itô’s formula,
 \begin{equation*} \begin{split} &|X_t|^p-|X_0|^p\\ &=\int_0^t\!\bigg(p|X_{s-}|^{p-1}{\text{sgn}}(X_{s-}) (\alpha_{{\Lambda}_{s-}}X_{s-}+b\sigma_{{\Lambda}_{s-}})+\frac{ap(p-1)}{2} \sigma_{{\Lambda}_{s-}}^2|X_{s-}|^{p-2}\bigg){\text{d}} s\\ &\quad+\int_0^t\!\int_{z\neq 0}\!\!(|X_{s-}+\sigma_{{\Lambda}_{s-}}\!z|^p-|X_{s-}|^p- p\sigma_{{\Lambda}_{s-}}z\,{\text{sgn}}(X_{s-})|X_{s-}|^{p-1}\textbf{1}_{0<|z|<1}\!)\nu({\text{d}} z){\text{d}} s\\ &\quad+\int_0^t\!\!p\sqrt{a}\sigma_{{\Lambda}_{s-}}\!{\text{sgn}}(X_{s-})|X_{s-}|^{p-1}{\text{d}} B_s+\int_0^t\!\!\int_{z\neq 0}\!\!(|X_{s-}+\sigma_{{\Lambda}_{s-}}\!z|^p-|X_{s-}|^p)\skew3\widetilde{N}({\text{d}} s,{\text{d}} z).\end{split}\end{equation*}
Given the initial distribution  $\gamma$ of
 $(X_0,{\Lambda}_0)$, let
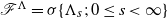 ${\mathscr F}^{\Lambda}=\sigma\{{\Lambda}_s;\, 0\leq s<\infty\}$ and
 \begin{equation}G_p^\gamma(t)=\text{E}[|X_{t-}|^p|{\mathscr F}^{\Lambda}],\qquad t\geq 0,\end{equation}
where the superscript  $\gamma$ in
 $G_p^\gamma(t)$ emphasizes the initial distribution
 $\gamma$. By virtue of the independence of
 $({\Lambda}_t)$ and
 $(Z_t)$, taking conditional expectation with respect to
 ${\mathscr F}^{\Lambda}$ yields that
 \begin{equation*} \frac{{\text{d}} G_p^\gamma(t)}{{\text{d}} t}=p\alpha_{{\Lambda}_{t-}}G_p^\gamma(t)+I(t),\end{equation*}
where 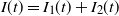 $I(t)=I_1(t)+I_2(t)$ with
 \begin{align*} I_1(t)&\,:\!=pb\sigma_{{\Lambda}_{t-}}\text{E}[{\text{sgn}}(X_{t-})|X_{t-}|^{p-1}|{\mathscr F}^{\Lambda}] +\frac{ap(p-1)\sigma_{{\Lambda}_{t-}}^2}{2}G_{p-2}^\gamma(t),\\ I_2(t)&\,:\!=\text{E}\bigg[\!\int_{z\neq 0}\!\!\!\!\!\!(|X_{t-}+\sigma_{{\Lambda}_{t-}}\!z|^p-|X_{t-}|^p- p\sigma_{{\Lambda}_{t-}}z\,{\text{sgn}}(X_{t-})|X_{t-}|^{p-1}\textbf{1}_{0<|z|<1}\!)\nu({\text{d}} z) \, \Big| \, {\mathscr F}^{\Lambda}\bigg].\end{align*}
For  $\theta>0$,
 ${\varepsilon}>0$, and
 $0<r<p$, by Hölder’s inequality and the elementary inequality
 \begin{equation*} \theta x^{\frac rp}\leq {\varepsilon} x+c_0,\quad x>0,\qquad \text{with $c_0=({\varepsilon}/\theta)^{\frac{-r}{p+r}}$},\end{equation*}
we have
 \begin{equation}\theta G_r^{\gamma}(t)\leq \theta G_p^\gamma(t)^{\frac{r}p}\leq {\varepsilon} G_p^\gamma(t)+c_0.\end{equation}
Therefore, for any  ${\varepsilon}>0$ there exists a constant
 $C_1>0$ independent of t such that
 \begin{equation}|I_1(t)|\leq p\sigma_\ast |b|G_{p-1}^\gamma(t)+\frac{ap(p-1)\sigma_\ast^2}{2}G_{p-2}^\gamma(t)\leq \frac{{\varepsilon}}{2}G_p^\gamma(t)+C_1.\end{equation}
To estimate the term  $I_2(t)$, we note that the mean value theorem implies that
 \begin{equation*} |x+z|^p-|x|^p=p(\vartheta |x+z|+(1-\vartheta)|z|)^{p-1}(|x+z|-|x|), \qquad x,z\in{\mathbb R}\end{equation*}
for some  $\vartheta\in [0,1]$ depending on
 $x,\,z$, and, further,
 \begin{align}||x+z|^p-|x|^p|&\leq p\max\{|x+z|^{p-1}, |z|^{p-1}\}|z| \nonumber \\&\leq p\max\{2^{p-2}(|x|^{p-1}+|z|^{p-1}), |z|^{p-1}\}|z|.\end{align}
Also, conditions (1.4) and (1.7) imply that, for every  $n\geq 1$,
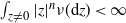 $\int_{z\neq 0} |z|^n\nu({\text{d}} z)<\infty$. Finally, invoking (2.27) and (2.29), we obtain that there exists some
 $C_2>0$, independent of t, such that
 \begin{equation}|I_2(t)|\leq \frac{{\varepsilon}}{2}G_p^\gamma(t)+C_2.\end{equation}
Inserting the estimates (2.28), (2.30) into (2.26), we get
 \begin{equation*} \frac{{\text{d}} G_p^\gamma(t)}{{\text{d}} t}\geq (p\alpha_{{\Lambda}_{t-}}-{\varepsilon})G_p^\gamma-M,\end{equation*}
where 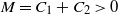 $M=C_1+C_2>0$. Then,
 \begin{align} G_p^\gamma(t)&\geq G_p^\gamma(0) \exp\bigg\{\int_0^t(p\alpha_{{\Lambda}_{s-}}-{\varepsilon}){\text{d}} s\bigg\}-M\int_0^t \exp\bigg\{\int_s^t(p\alpha_{{\Lambda}_{r-}}-{\varepsilon}){\text{d}} r\bigg\}{\text{d}} s \nonumber \\ &\geq G_p^\gamma(0) \exp\bigg\{\int_0^t(p\alpha_{{\Lambda}_{s-}}-{\varepsilon}){\text{d}} s\bigg\}-M\int_0^t \exp\bigg\{(p\max_{i\in{\mathcal S}}\alpha_i -{\varepsilon})(t-s)\bigg\}{\text{d}} s \nonumber \\ &=G_p^\gamma(0) \exp\bigg\{\int_0^t(p\alpha_{{\Lambda}_{s-}}-{\varepsilon}){\text{d}} s\bigg\} \nonumber \\ & \quad + \frac{M}{p\max_{i\in{\mathcal S}}\alpha_i-{\varepsilon}} \big(\exp\big\{(p\max_{i\in{\mathcal S}}\alpha_i-{\varepsilon})t\big\}-1\big).\end{align}
We shall prove statement (ii) by contradiction. Assume that 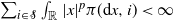 $\sum_{i\in{\mathcal S}}\int_{{\mathbb R}}|x|^p\pi({\text{d}} x,i)<\infty$. Now let us take
 $\gamma$ in (2.26) to be the stationary distribution
 $\pi$ of
 $(X_t,{\Lambda}_t)$, so for every
 $t>0$ the distribution of
 $(X_t,{\Lambda}_t)$ is also
 $\pi$. Since
 $({\Lambda}_t)$ is an irreducible Markov chain in a finite state space, denote by
 $\mu$ its stationary distribution on
 ${\mathcal S}$. Then, for every
 $i\in {\mathcal S}$,
 $\mu_i>0$. Moreover, it holds that
 $\mu_i=\pi({\mathbb R},i)$, which can be seen by the weak convergence of the semigroup of
 $(X_t,{\Lambda}_t)$ to
 $\pi$ and the semigroup of
 $({\Lambda}_t)$ to
 $\mu$. Consequently, we have
 \begin{equation*} \min_{i\in{\mathcal S}}\int_{{\mathbb R}}|x|^p\pi({\text{d}} x,i)>0.\end{equation*}
Taking expectation on both sides of (2.31), we obtain
 \begin{align}\sum_{i\in{\mathcal S}}\int_{{\mathbb R}}|x|^p\pi({\text{d}} x,i) & =\text{E}|X_t|^p \nonumber \\&\geq \bigg(\min_{i\in{\mathcal S}}\int_{{\mathbb R}}|x|^p\pi({\text{d}} x,i) \bigg) \text{E}\bigg(\!\exp\bigg\{\int_0^t(p\alpha_{{\Lambda}_{s-}}+{\varepsilon}){\text{d}} s\bigg\}\bigg) \nonumber \\& \quad + \frac{M}{p\max_{i\in{\mathcal S}}\alpha_i+{\varepsilon}}\big(\!\exp\big\{(p\max_{i\in{\mathcal S}}\alpha_i+{\varepsilon})t\big\}-1\big) \nonumber \\&\geq c_p\Big(\min_{i\in{\mathcal S}}\int_{{\mathbb R}}|x|^p\pi({\text{d}} x,i) \Big){\text{e}}^{({-}\eta_p+ {\varepsilon}) t} \nonumber \\ & \quad + \frac{M}{p\max_{i\in{\mathcal S}}\alpha_i+{\varepsilon}} \big( \exp\big\{(p\max_{i\in{\mathcal S}}\alpha_i+{\varepsilon})t\big\}-1\big),\end{align}
where  $c_p$ is a positive constant,
 $\eta_p<0$ is defined by (1.8), and in the last step we have used [Reference Bardet, Guérin and Malrieu1, Proposition 4.1]. Choosing
 ${\varepsilon}>0$ such that
 $\eta_p+{\varepsilon}<0$, and letting
 $t\to\infty$ in (2.32), the left-hand side is finite but the right-hand side goes to
 $\infty$, which is a contradiction. Therefore, the pth moment of
 $\pi$ is infinite, and hence
 $\pi$ is heavy-tailed, completing the proof.


