1. MOTIVATION
Testing for unit roots has been among the most widely researched topics in econometrics for the last 20 years. Burridge and Guerre (1996) observed that the number of level crossings in a variable would be larger if no unit root was present rather than otherwise and, hence, proposed a unit root test based on the standardized number of level crossings of a random walk without deterministic terms. They showed that the asymptotic distribution of this statistic relates to a scaled local time of a Brownian motion and found that the scale factor depends on the long-run variance of the process. In the present note we extend the proposal of Burridge and Guerre in two directions. First, we consider the process with time trend and prove that the modified standardized number of level crossings converges to a Rayleigh distribution. Second, more general structures of autocorrelated disturbances are also taken into account. Monte Carlo experiments show the good sample properties of this nonparametric unit root test.
2. RESULTS
Let xt = μt + ut be an I(1) process, where μt = α + βt, ut = ut−1 + εt, and the sequence εt satisfies the conditions in Akonom (1993), namely, (a)

; (b) et is a sequence of independent and identically distributed (i.i.d.) random variables with zero mean and constant variance, σe2, and E(|et|p) < ∞ for some p > 2; (c)

. Moreover, we also impose, as Burridge and Guerre (1996) did, (d) there exists n such that for

has bounded probability density function. We denote the long-run variance of εt as σ2 = σe2π(1)2.
Let xt(0) = xt, xt(1) = xt − x1 − ct, where c = (xT − x1)/T and T is the sample size. Thus, xt(1) is a detrended I(1) process. Define the normalized number of crossing levels as

for i = 0,1, where 1[·] is an indicator function that takes value one when the condition between brackets holds true and zero otherwise. Hence, T1/2KT(i)(z) counts the number of times xt(i) crosses the level z. Burridge and Guerre (1996) considered the case where μt = 0 for all t and found that, when {εt}t≥1 is an i.i.d. sequence of zero-mean finite-variance random variables, then

where l0(z,t), t ∈ [0,1], is a local time process (see, e.g., Revuz and Yor, 1991) and

stands for equal distribution. Hence, KT(0)(z) does not depend on z. Given this result, they suggested the following statistic to test the null of a unit root:

where

. The statistic φ(0) has an |N(0,1)| limit distribution when {εt}t≥1 is an i.i.d. sequence of zero-mean finite-variance random variables and μt = 0 for all t. Under the alternative hypothesis of stationarity, φ(0) diverges. We herein extend the previous statistic in two ways, allowing for trended processes and also for more general innovations:

i = 0,1, where

is a consistent estimator of the square root of the long-run variance of {εt}t≥1. In the simulation experiments that follow we used the procedure suggested by Sul, Phillips, and Choi (2005) with the Bartlett window to estimate

. The following theorem shows the limit distribution of the previous test for trending processes.
THEOREM 1. {εt}t≥1 satisfies the conditions (a)–(d) given previously. Then,

where R is a random variable with (standard) Rayleigh distribution, that is, fR(x) = 1(x > 0)x exp(−½x2). Moreover, if μt = 0, then η(0) ⇒ |N(0,1)|.
Proof. See the Appendix.
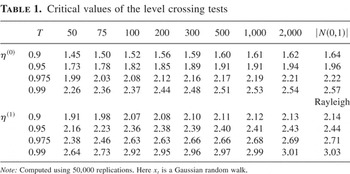
Table 1 shows estimates of the critical values of η(0) and η(1) obtained from 50,000 replications in addition to the asymptotic distribution. As can be seen, these values approximate the limit values for large sample sizes.
Critical values of the level crossing tests

Finally, we compare our test η(1) with the DFGLS test proposed by Elliott, Rothenberg, and Stock (1996) with lags selected according to the modified Akaike information criterion (AIC) of Ng and Perron (2001). The implementation of unit root tests often requires the selection of an autoregressive truncation lag. These authors use a local asymptotic framework in which a class of modified information criterion (MIC) in conjunction with generalized least squares (GLS) detrending results in a class of tests with good size and power. For the η(1) statistic, an initial bandwidth of l = [12(T/100)1/4] was used for the computation of the long-run variance using the procedure suggested by Sul et al. (2005).
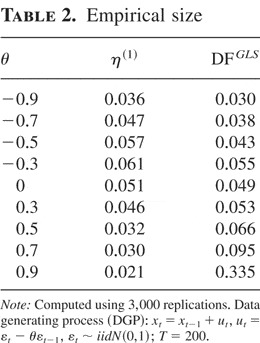
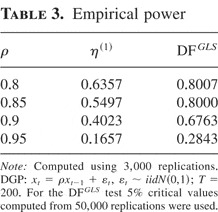
Table 2 shows the empirical size of the two tests for MA(1) autocorrelated disturbances, a situation where unit root tests usually have size problems. The η(1) test presents very good size in all cases, whereas in the DFGLS test problems arise for large values of the moving average parameter. Next, in Table 3 is shown the empirical power for stationary AR(1) alternatives. As observed, the DFGLS test happens to show better power, which could be explained by the fact that this statistic is designed to be powerful against local alternatives.
Empirical size

Empirical power

3. CONCLUSIONS
In this note we have proposed a new nonparametric unit root test for trending processes that is based on normalized level crossings. The test is a generalization of the one proposed in Burridge and Guerre (1996), allowing for trended processes and more general forms of autocorrelated disturbances. This new test has an asymptotic distribution that is a standard Rayleigh distribution. We have also shown that the test has good finite-sample properties and presents, for some but not all parametrizations of the DGP, better size properties than the DFGLS test considered in Ng and Perron (2001). Thus, the η(1) test proposed in this note can be considered a good complement to other unit root tests.
APPENDIX
We shall make use of the following lemmas to prove Theorem 1.
LEMMA 2. Let xt be an I(1) process that satisfies the previous conditions (a)–(d) with σ2 being the long-run variance of εt. Let xt(0) = xt and xt(1) = xt − x1 − ct, where c = (xT − x1)/T. Then, if μt = 0

for i = 0,1 and r ∈ [0,1], where ⇒ stands for weak convergence of the associated probability measures, [·] is the integer part, W(0)(r) ≡ W(r) is a standard Brownian motion, and W(1)(r) ≡ W(r) − rW(1) is a standard Brownian bridge. If μt = α + βt, then

Proof. See, Akonom (1993) for μt = 0 and i = 0. For i = 1 arguments similar to those in Phillips and Schmidt (1992) apply. █
LEMMA 3. Under the same assumptions as in the previous lemma, if μt = 0

where l0(z,t), t ∈ [0,1], is the local time of a Brownian motion in the vicinity of z and l1(z,t) is that of a Brownian bridge. Moreover, if μt = α + βt

Proof. See Burridge and Guerre (1996) for the result regarding l0(z,t) with i.i.d. εt. Using Theorems 3 and 4 in Akonom (1993) in the proof of Burridge and Guerre the results extend to the case of nonindependent sequences such as those considered under the Akonom assumptions. Proof of l1(z,t) follows similar steps. █
LEMMA 4. (a)
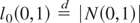
and (b)

, where R presents a standard Rayleigh distribution with a density function f (r) = 1(r > 0)r exp(−r2/2).
Proof. See Revuz and Yor (1991, p. 250). █
LEMMA 5. Under the conditions stated previously,

.
Proof. First, note that c = (xT − x1)/T is a consistent estimator of β and that

Let us consider first the term

. Under the set of assumptions (a)–(d) stated earlier, Δxt(i)1t(Δxt(i) > 0) is a covariance stationary process, and it follows that (see, e.g., Bierens, 2004, Thm. 7.3)

Similar arguments can be used for the term

. █
Proof of Theorem 1. Given that

are consistent estimators, the theorem follows immediately from the three previous lemmas. █