Contents
Research Article
Convergence of Continued Fractions
-
- Published online by Cambridge University Press:
- 20 November 2018, pp. 1037-1055
-
- Article
-
- You have access
- Export citation
-
Let {sn(z)} be a given sequence of linear fractional transformations (or simply l.f.t.'s) of the form
1.1
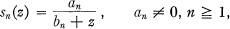
and let
1.2
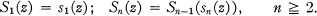
The sequence of l.f.t.'s {Sn(z)} is called a continued fraction generating sequence (or simply a c.f.g. sequence).
On a Combinatorial Result of R. A. Brualdi and M. Newman
-
- Published online by Cambridge University Press:
- 20 November 2018, pp. 1056-1067
-
- Article
-
- You have access
- Export citation
-
Let H be a subgroup of Sn and let A be an n-square matrix over a field ƒ. Following Schur (7) we define the generalized matrix function dH(A) by


The Number of Graphs with a given Automorphism Group
-
- Published online by Cambridge University Press:
- 20 November 2018, pp. 1068-1076
-
- Article
-
- You have access
- Export citation
Another Enumeration of Trees
-
- Published online by Cambridge University Press:
- 20 November 2018, pp. 1077-1086
-
- Article
-
- You have access
- Export citation
Associated Regular Spaces
-
- Published online by Cambridge University Press:
- 20 November 2018, pp. 1087-1092
-
- Article
-
- You have access
- Export citation
-
Let
 be any topological space. In this paper, we show that there is a unique regular topology
 on X which is coarser than
 such that if Y is any regular space, the continuous maps
 are the same for and . We shall call the regular topology associated with and
 the regular space associated with .
 be any topological space. In this paper, we show that there is a unique regular topology
 on X which is coarser than
 such that if Y is any regular space, the continuous maps
 are the same for
 the regular space associated with
Sur Les Espaces Localement Quasi-Compacts
-
- Published online by Cambridge University Press:
- 20 November 2018, pp. 1093-1100
-
- Article
-
- You have access
- Export citation
A Characteristic Subgroup of a p-Stable Group
-
- Published online by Cambridge University Press:
- 20 November 2018, pp. 1101-1135
-
- Article
-
- You have access
- Export citation
Multiplication in Vector Lattices
-
- Published online by Cambridge University Press:
- 20 November 2018, pp. 1136-1149
-
- Article
-
- You have access
- Export citation
Extreme Points and Linear Isometries of the Banach Space of Lipschitz Functions
-
- Published online by Cambridge University Press:
- 20 November 2018, pp. 1150-1164
-
- Article
-
- You have access
- Export citation
-
Let X be a compact metric space with metric d. A complex-valued function ƒ on X is said to satisfy a Lipschitz condition if, for all points x and y of X, there exists a constant K such that

The smallest constant for which the above inequality holds is called the Lipschitz constant for ƒ and is denoted by ||ƒ||d, that is,


Isomorphisms of Multiplier Algebras
-
- Published online by Cambridge University Press:
- 20 November 2018, pp. 1165-1172
-
- Article
-
- You have access
- Export citation
The Valence of Sums and Products
-
- Published online by Cambridge University Press:
- 20 November 2018, pp. 1173-1177
-
- Article
-
- You have access
- Export citation
-
A function ƒ(z) is said to be p-valent in a region
 if it is regular in if the equation
1

has p distinct roots in
for some particular w0 , and if for each complex w0 , equation (1) does not have more than p roots in . The function ƒ(z) is also said to have valence p in . In the case when p = 1, the function is said to be univalent in .
 if it is regular in

Generation of Local Integral Orthogonal Groups in Characteristic 2
-
- Published online by Cambridge University Press:
- 20 November 2018, pp. 1178-1191
-
- Article
-
- You have access
- Export citation
Positive Functionals and Representations of Tensor Products of Symmetric Banach Algebras
-
- Published online by Cambridge University Press:
- 20 November 2018, pp. 1192-1202
-
- Article
-
- You have access
- Export citation
Non-Stationary Processes and Spectrum
-
- Published online by Cambridge University Press:
- 20 November 2018, pp. 1203-1206
-
- Article
-
- You have access
- Export citation
-
In 1964, L. J. Herbst (3) introduced the generalized spectral density Function
1
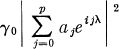
for a non-stationary process {X(t)} denned by
1
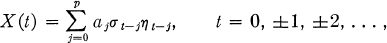
where {η(t)} is a real Gaussian stationary process of discrete parameter and independent variates, the (a;)'s and (σj)'s being constants, the latter, which are ordered in time, having their moduli less than a positive number M.
Arcs, Semigroups, and Hyperspaces
-
- Published online by Cambridge University Press:
- 20 November 2018, pp. 1207-1210
-
- Article
-
- You have access
- Export citation
Almost Convergence and Well-Distributed Sequences
-
- Published online by Cambridge University Press:
- 20 November 2018, pp. 1211-1214
-
- Article
-
- You have access
- Export citation
-
A sequence (xn) of real numbers is said to be well-distributed modulo 1 (abbreviated w.d.) if for each subinterval I = [a, b] of [0, 1] we have that

where χI is the characteristic function of I modulo 1. A sequence (r n ) of positive numbers is lacunary if


Restrictive Semigroups of Closed Functions
-
- Published online by Cambridge University Press:
- 20 November 2018, pp. 1215-1229
-
- Article
-
- You have access
- Export citation
On Isomorphisms of Meromorphic Function Fields
-
- Published online by Cambridge University Press:
- 20 November 2018, pp. 1230-1241
-
- Article
-
- You have access
- Export citation
Subordinate and Pseudo-Subordinate Semi-Algebras. II
-
- Published online by Cambridge University Press:
- 20 November 2018, pp. 1242-1245
-
- Article
-
- You have access
- Export citation
Inductive Extension of a Vector Measure Under a Convergence Condition
-
- Published online by Cambridge University Press:
- 20 November 2018, pp. 1246-1255
-
- Article
-
- You have access
- Export citation