



1. Introduction
The refracted Lévy process, first introduced in [Reference Kyprianou and Loeffen10], is defined as a strong solution to the stochastic differential equation (SDE)
 \begin{align*} V_{t}=X_{t}-\delta\int_{0}^{t}\mathbf{1}_{(V_{s} \gt b)}\,{\mathrm{d}} s, \end{align*}
where the driving noise X is a spectrally negative Lévy process (SNLP) and b,
 $\delta$
are positive constants. Since then, fluctuations of refracted Lévy processes and their applications to insurance risk models with dividend payments have received a lot of attention; see [Reference Czarna, Pérez, Rolski and Yamazaki5], [Reference Kyprianou8], [Reference Kyprianou, Pardo and Pérez11], [Reference Pérez and Yamazaki17], [Reference Pérez and Yamazaki18], [Reference Renaud19], and [Reference Wang, Lkabous and Landriault20], to mention a few.
New generalisations of refracted Lévy processes were introduced in [Reference Noba and Yano16], whose motions above and below b are Lévy processes, different from each other. In this case the generalised refracted Lévy process is a solution to the SDE
 \begin{align*} L_{t}=L_{0}+ \int_{0}^{t}\mathbf{1}_{(L_{t^{-}}\geq b)}\,{\mathrm{d}} X_{s}+\int_{0}^{t}\mathbf{1}_{(L_{t} \lt b)}\,{\mathrm{d}} Y_{s}, \end{align*}
where X and Y are two independent spectrally negative Lévy processes (SNLPs) with (possibly) different Lévy exponents. As pointed out in [Reference Noba and Yano16], in the bounded variation case a solution to the above SDE can be constructed by piecing the excursions together; otherwise we do not know the existence of a solution for the above SDE.
In this paper we consider a further extension of the generalised refracted Lévy process in [Reference Noba and Yano16], in which the switch between X and Y does not occur when b is crossed continuously, but instead when it is above b and coincides with an arrival epoch of an independent Poisson process. Under this extension, the corresponding process
 $U = \{U_t\}_{t \geq 0}$
is a solution to the (hybrid) SDE
 \begin{equation} U_{t} = U_{0} + \int^t_{0} \mathbf{1}_{\{U_{T_{N(s)}} \leq b\}} \,{\mathrm{d}} X_{s} +\int^t_{0} \mathbf{1}_{\{U_{T_{N(s)}} \gt b\}} \,{\mathrm{d}} Y_{s} ,\end{equation}
where X and Y are as above and independent of the Poisson process N with arrival times
 $T_0 = 0$
and
 $\{T_i\}_{i\geq 1}$
(see Section 3 for full details). Utilising the Poisson arrival epochs, we show that a pathwise solution exists to (1.1) (sometimes called a hybrid SDE; see [Reference Albrecher and Peralta2] and [Reference Hu, Liu, Deng and Mao6]), even in the unbounded variation case. The aim of this paper is twofold: firstly, to establish a set of identities for the two-sided exit problems and the potential measures (killed and non-killed) of U, written in terms of new generalisations of scale functions (related to the one- and two-sided exit problem scale functions of [Reference Kyprianou9]); secondly, to briefly show the relevance of these identities in the context of applications for the ruin problem in risk theory.
Lévy processes observed in Poisson arrival epochs have been introduced in [Reference Albrecher, Ivanovs and Zhou1]. Since then, several modifications of Poisson arrival epoch points in connection with Lévy processes have been developed and have found numerous applications in insurance risk models; see [Reference Landriault, Li, Wong and Xu12], [Reference Liu, Yang and Dong13], and [Reference Lkabous14]. As such, letting
 $X = \{X_t\}_{t \geq 0}$
and
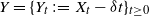 ${Y} = \{ {Y}_t \, :\!= \, {X}_t - \delta t \}_{t \geq 0}$
for the proposed model, we obtain an insurance risk process which has delays in the initiation and termination of dividend payments. The justification of such a risk model occurs naturally since dividend payments in reality are made with delays and not at the exact moment that the surplus crosses some level b.
The remainder of the paper is structured as follows. Section 2 recalls the basic theory of scale functions and provides useful identities that will be used in the rest of the paper. In Section 3 we show that a solution to (1.1) exists and also discuss the strong Markov property. In Section 4 we define the generalised scale functions which are used to derive identities for the two-sided exit problem (exiting upwards above level
 $a>0$
and downwards below level 0), the one-sided exit identities as well as the killed and non-killed potential measures. We lastly provide a brief application of U as a risk process by choosing Y so that U reduces to a (refracted) risk model with delays in the dividend payments, and subsequently derive an explicit expression for the probability of ruin.
2. Preliminaries
Let
 $X = \{X_{t}\}_{t \geq 0}$
be an SNLP defined on the filtered space
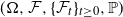 $(\Omega, \mathcal{F}, \{\mathcal{F}_{t}\}_{t \geq 0}, \mathbb{P})$
, where the filtration
 $\{\mathcal{F}_{t}\}_{t \geq 0}$
is assumed to satisfy the usual assumptions of right continuity and completion. We shall let
 $\mathbb{P}_x$
be the probability measure, given the process starts at x, and let
 $\mathbb{E}_x$
be the associated expectation. When
 $x=0$
, we shall drop the subscript. A Lévy process with no positive jumps (the case of monotone paths is excluded) has its Laplace exponent
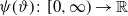 $\psi(\vartheta)\colon [0,\infty)\rightarrow \mathbb R$
defined as
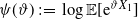 $\psi(\vartheta) \, :\!= \, \log \mathbb{E}[{\mathrm{e}}^{\vartheta X_1}]$
, which, by the Lévy–Khintchine formula, has the form
 \begin{align*} \psi(\vartheta) = \mu\vartheta + \dfrac{\vartheta^2 \sigma^2}{2} +\int_{(-\infty, 0)}^{} \bigl({\mathrm{e}}^{\vartheta x} -1- \vartheta x \mathbf{1}_{\{x \gt - 1\}}\bigr) \nu({\mathrm{d}} x), \end{align*}
where
 $\mu \in \mathbb{R}$
,
 $\sigma \geq 0$
, and
 $\nu$
, the Lévy measure, is a
 $\sigma$
-finite measure concentrated on
 $(-\infty,0)$
satisfying
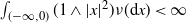 $\int_{(-\infty,0)}(1 \wedge |x|^2) \nu({\mathrm{d}} x) \lt \infty$
. The above shows that
 $\psi$
is a continuous and strictly convex function, and that it tends to infinity as
 $\vartheta$
tends to infinity. Thus, for
 $q \geq 0$
, one can define the right-inverse of the Laplace exponent
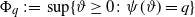 $ \Phi_q \, :\!= \, \sup\{\vartheta\geq 0\colon \psi(\vartheta) = q\}$
, for which
 $\vartheta = 0$
is the unique solution to
 $\psi(\vartheta) = 0$
on
 $[0,\infty)$
if
 $\psi^{\prime}(0^{+}) \geq 0$
, else there are two solutions. Further details about SNLPs can be found in the monographs [Reference Bertoin4], [Reference Kuznetsov, Kyprianou and Rivero7], and [Reference Kyprianou9].
It is well known that the fluctuation identities for X rely heavily on the so-called W and Z scale functions (see [Reference Kyprianou9, Chapter 8]). For any
 $q\geq 0$
, we define
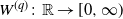 $W^{(q)}\colon \mathbb{R} \to [0, \infty)$
to be the unique (up to a scaling constant), continuous increasing function with Laplace transform
 \begin{equation*}\int_{0}^{\infty} {\mathrm{e}}^{-\vartheta x}W^{(q)}(x)\,{\mathrm{d}} x = \dfrac{1}{\psi_q(\vartheta)}, \quad \vartheta \gt \Phi_q, \end{equation*}
where
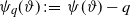 $\psi_q(\vartheta) \, :\!= \, \psi(\vartheta) -q$
and
 $W^{(q)}(x)=0$
for
 $x<0$
. In the rest of the paper we write W or
 $\psi$
instead of
 $W^{(0)}$
or
 $\psi_0$
for convenience. We also define
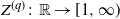 $Z^{(q)}\colon \mathbb{R} \rightarrow[1, \infty)$
having the form
 \begin{align*}Z^{(q)}(x)=1+q \int_0^x W^{(q)}(y)\,{\mathrm{d}} y, \end{align*}
and its bivariate generalisation
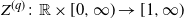 $Z^{(q)}\colon \mathbb{R} \times [0,\infty) \rightarrow[1, \infty)$
having the form
 \begin{equation}Z^{(q)}(x,\theta)={\mathrm{e}}^{\theta x} \biggl(1-\psi_q(\theta) \int_0^x {\mathrm{e}}^{-\theta y}W^{(q)}(y)\,{\mathrm{d}} y \biggr), \end{equation}
where
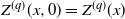 $Z^{(q)}(x,0) = Z^{(q)}(x)$
and
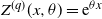 $Z^{(q)}(x,\theta) = {\mathrm{e}}^{\theta x}$
for
 $x \leq 0$
. With regard to the limits of scale functions, it is well known (see e.g. equations (2.21) and (2.13) in [Reference Landriault, Li, Wong and Xu12]) that
 \begin{equation}\dfrac{W^{(q)}(a-x)}{W^{(q)}(a)} \rightarrow {\mathrm{e}}^{-\Phi_q x}, \; \quad \dfrac{Z^{(q)}(a,\theta)}{W^{(q)}(a)} \rightarrow \dfrac{\psi_q(\theta)}{\theta - \Phi_q} \quad \text{as $ a \rightarrow \infty$.} \end{equation}
In addition, the following useful identities for convolutions of the scale functions will be used throughout the paper. For any
 $p, q, x \geq 0$
and
 $p \neq q$
, it holds that
 \begin{align*}(p-q)\int_0^x W^{(p)}(x-y) W^{(q)}(y)\,{\mathrm{d}} y&=W^{(p)}(x)-W^{(q)}(x), \\[3pt]*(p-q)\int_0^x W^{(p)}(x-y) Z^{(q)}(y)\,{\mathrm{d}} y&=Z^{(p)}(x)-Z^{(q)}(x) .\end{align*}
The above identities introduced in [Reference Loeffen, Renaud and Zhou15] were used to derive a new class of scale functions, the so-called second generation scale functions, with the aim of solving occupation time fluctuation identities. These will be used throughout the paper and have the following forms. For
 $p, p+q \geq 0$
and
 $u, x \in \mathbb{R}$
, we define
 \begin{align}\overline{W}_u^{(p, q)}(x)& \, :\!= W^{(p+q)}(x)-q \int_0^u W^{(p+q)}(x-y) W^{(p)}(y)\,{\mathrm{d}} y\nonumber \\[3pt]& = W^{(p)}(x)+q \int_u^x W^{(p+q)}(x-y) W^{(p)}(y)\,{\mathrm{d}} y, \\[-10pt] \nonumber \end{align}
 \begin{align}\overline{Z}_u^{(p, q)}(x)& \, :\!= Z^{(p+q)}(x)-q \int_0^u W^{(p+q)}(x-y) Z^{(p)}(y)\,{\mathrm{d}} y\nonumber \\[3pt]&= Z^{(p)}(x)+q \int_u^x W^{(p+q)}(x-y) Z^{(p)}(y)\,{\mathrm{d}} y,\end{align}
For the SNLP
 $Y=\{Y_t\}_{t \geq 0}$
in (1.1), results similar to the above hold with the corresponding notation
 $\mathbb{W}^{(p)}$
and
 $\mathbb{Z}^{(p)}$
for each
 $p \geq 0$
(
 $\overline{\mathbb{W}}^{(p,q)}$
and
 $\overline{\mathbb{Z}}^{(p,q)}$
for
 $p+q \geq 0$
), which are interpreted as the counterparts of
 ${W}^{(p)}$
and
 ${Z}^{(p)}$
(resp.
 $\overline{W}^{(p,q)}$
and
 $\overline{Z}^{(p,q)}$
) associated with the SNLP X. Observe also that
 $Y = X$
yields
 $\mathbb{W}^{(p)} = W^{(p)}$
(
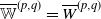 $\overline{\mathbb{W}}^{(p,q)} = \overline{W}^{(p,q)}$
) and similarly for
 $\mathbb{Z}^{(p)}$
(
 $\overline{\mathbb{Z}}^{(p,q)}$
). Furthermore, the Laplace exponent of Y will be denoted as
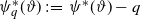 $\psi_q^*(\vartheta) \, :\!= \, \psi^*(\vartheta) - q$
with a corresponding right-inverse
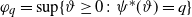 $\varphi_q = \sup \{\vartheta \geq 0\colon \psi^*(\vartheta) = q\}$
.
3. Pathwise solution
In this section we discuss the existence of the solution of the SDE in (1.1) and show that it also has the strong Markov property.
Let X and Y be SNLPs starting from x. For the construction below, we shall consider
 $x=0$
(without the loss of generality), and a Poisson process
 $N \, :\!= \, N(t)$
with arrival times
 $T_0 = 0$
and
 $T_i = \sum^i_k \xi_{\lambda,k}$
, where
 $\{\xi_{\lambda,k}\}_{k\geq 1}$
is a sequence of i.i.d. Exp(
 $\lambda$
) waiting times with
 $\lambda \lt \infty$
. Furthermore, X, Y, and N are adapted to
 $\mathcal{F}_t$
, and are independent. We note that U in (1.1) has the dynamics of X when it is observed below the barrier b, and subsequently switches to the dynamics of Y if it is simultaneously greater than b and an arrival occurs.
To show that such a process has a strong solution, we construct it pathwise. Hence, let the process start at some value
 $ U_0 = x$
and define the random switching times
 $K^{-}_{b,0} = 0$
,
 \begin{align*}K^{+}_{b,n} &\, :\!= \, \min \Biggl\{ T_i \geq K^{-}_{b,n-1} \colon x + X_{T_i} - X_{ K^{-}_{b,n-1}} + \sum^{n-1}_{i=1} \bigl(Y_{K^{-}_{b,i}} - Y_{ K^{+}_{b,i}}\bigr) + \sum^{n-1}_{i=1} \bigl(X_{K^{+}_{b,i}} - X_{ K^{-}_{b,i-1}}\bigr) \gt b \Biggr\}, \\[3pt]K^{-}_{b,n} &\, :\!= \, \min \Biggl\{ T_i \geq K^{+}_{b,n} \colon x + Y_{T_i} - Y_{K^{+}_{b,n}} + \sum^{n}_{i=1} \bigl(X_{K^{+}_{b,i}} - X_{ K^{-}_{b,i-1}}\bigr) + \sum^{n-1}_{i=1} \bigl(Y_{K^{-}_{b,i}} - Y_{ K^{+}_{b,i}}\bigr) \leq b \Biggr\},\end{align*}
for
 $n = 1,2,\ldots$
in the above. It is clear from the above formulation that
 $K^{+}_{b,n} \lt K^{-}_{b,n}$
for
 $n = 1,2,\ldots,$
which creates intervals over which the process switches between the dynamics of X and Y. Thus, from the recursive times above, we can define the process as
 \begin{align} U_t = \begin{cases}x + X_{t} - X_{ K^{-}_{b,n}} + \sum^{n}_{i=1} \bigl(Y_{K^{-}_{b,i}} - Y_{ K^{+}_{b,i}}\bigr) + \sum^{n}_{i=1} \bigl(X_{K^{+}_{b,i}} - X_{ K^{-}_{b,i-1}}\bigr), & t \in \bigl[K^{-}_{b,n},K^{+}_{b,n+1}\bigr), \\[7pt]x + Y_{t} - Y_{K^{+}_{b,n}} + \sum^{n}_{i=1} \bigl(X_{K^{+}_{b,i}} - X_{ K^{-}_{b,i-1}}\bigr) + \sum^{n-1}_{i=1} \bigl(Y_{K^{-}_{b,i}} - Y_{ K^{+}_{b,i}}\bigr), & t \in \bigl[K^{+}_{b,n},K^{-}_{b,n}\bigr),\end{cases}\end{align}
Furthermore, we can write
 $K^{+}_{b,n}$
and
 $K^{-}_{b,n}$
as stopping times with respect to the process U defined above; that is, given
 $K^{-}_{b,0} = 0$
, we have for
 $n = 1,2,\ldots$
that
 \begin{equation*}K^{+}_{b,n} \, :\!= \, \min \{ T_i \geq K^{-}_{b,n-1} \colon U_{T_i} \gt b \} \quad \text{and} \quad K^{-}_{b,n} \, :\!= \, \min \{ T_i \geq K^{+}_{b,n} \colon U_{T_i} \leq b \},\end{equation*}
which shows that these stopping times are adapted with respect to
 $\mathcal{F}_t$
. Thus the stopping times are well-defined under this filtration.
Next we shall show that the above formulation in (3.1) corresponds pathwise to (1.1). Observe that
 $\mathbf{1}_{\{U_{T_{N(t)}} \leq b\}} = 1$
for
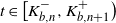 $t \in \bigl[K^{-}_{b,n},K^{+}_{b,n+1}\bigr)$
for all
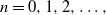 $n=0,1,2,\ldots,$
and 0 otherwise. Thus, for
 $U_0 = x$
, we have for
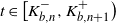 $t \in \bigl[K^{-}_{b,n},K^{+}_{b,n+1}\bigr)$
and
 $n=0,1,2,\ldots$
that
 \begin{align*}U_t &= x + X_{t} - X_{ K^{-}_{b,n}} + \sum^{n}_{i=1} \bigl(Y_{K^{-}_{b,i}} - Y_{ K^{+}_{b,i}}\bigr) + \sum^{n}_{i=1} \bigl(X_{K^{+}_{b,i}} - X_{ K^{-}_{b,i-1}}\bigr) \\[3pt] &= x + \int^t_{ K^{-}_{b,n}} \mathbf{1}_{\{U_{T_{N(t)}} \leq b\}} \,{\mathrm{d}} X_s + \sum^n_{i=1} \int^{K^{+}_{b,i}}_{K^{-}_{b,i-1}}\mathbf{1}_{\{U_{T_{N(s)}} \leq b\}} \,{\mathrm{d}} X_s + \sum^n_{i=1} \int^{K^{-}_{b,i}}_{K^{+}_{b,i}}\mathbf{1}_{\{U_{T_{N(s)}} \gt b\}} \,{\mathrm{d}} Y_s \\[3pt] &= U_0 + \int^t_0 \mathbf{1}_{(U_{T_{N(s)}} \leq b)} \,{\mathrm{d}} X_s + \int^t_0 \mathbf{1}_{(U_{T_{N(s)}} \gt b)} \,{\mathrm{d}} Y_s.\end{align*}
Using the same line of logic as above, the same can be proved for
 $t \in \bigl[K^{+}_{b,n},K^{-}_{b,n}\bigr)$
and
 $n=1,2,\ldots.$
Noting that every compact interval has a finite number of arrivals, the number of times that the process switches in the interval [0, t] is finite. Since this process switches between two well-defined SNLPs for every pair of subsequent stopping times, we have the following theorem.
Theorem 3.1. For
 $U_0 = x$
, there exists a strong solution to (1.1).
Remark 3.1.
-
(i) Given the arrival times of the Poisson process,
 $T_i$
, the pathwise solution guarantees that there is a unique construction of U. We note that in Section 4.4 our choices for X and Y allow us to prove in full detail pathwise uniqueness, which is a consequence of choosing two processes that have positive drifts such that the point b is irregular for itself.
-
(ii) Although (1.1) forms a (hybrid) SDE with discontinuous coefficients, the Poissonian mechanism (for finite
$\lambda$
) significantly simplifies (1.1), as the switching mechanism is only triggered a finite number of times in any given compact time interval, in contrast to the potentially infinite number of switches in the classical refraction model.


Remark 3.2. It is clear that U does not have the strong Markov property on its own. Defining the process
 \begin{equation*}Q_t\, :\!= \, \mathbf{1}_{\{U_{T_{N(t)}} \gt b\}} \end{equation*}
allows us to rewrite (1.1) as
 \begin{equation*}U_t = U_0 + \int_0^t (1-Q_s )\,{\mathrm{d}} X_s + \int_0^t Q_s {\mathrm{d}} Y_s, \end{equation*}
and for a stopping time
 $\{\tau \lt \infty\}$
and
 $t\geq 0$
, we have
 \begin{equation*}U_{\tau+t} = U_\tau + \int_0^t (1-Q_{\tau+s} )\,{\mathrm{d}} X_s + \int_0^t Q_{\tau+s} {\mathrm{d}} Y_s. \end{equation*}
Now for
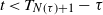 $t \lt T_{N(\tau)+1}-\tau$
, it follows that
 $Q_{\tau+t}=Q_\tau$
and
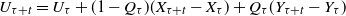 $U_{\tau+t}=U_\tau+(1-Q_\tau)(X_{\tau+t}-X_\tau)+Q_\tau(Y_{\tau+t}-Y_\tau)$
. Thus
 $(U_{\tau+t}, Q_{\tau+t})$
depends only on
 $(U_{\tau}\!, Q_{\tau})$
.
At the next Poisson epoch, we have
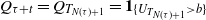 $Q_{\tau+t}=Q_{T_{N(\tau)+1}}=\mathbf{1}_{\{U_{T_{N(\tau)+1}} \gt b\}}$
, where
 \begin{align*}U_{T_{N(\tau)+1}}=U_\tau+(1-Q_\tau)(X_{T_{N(\tau)+1}}-X_\tau)+Q_\tau(Y_{T_{N(\tau)+1}}-Y_\tau), \end{align*}
which also depends on
 $(U_{\tau}, Q_{\tau})$
. Finally, for
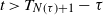 $t \gt T_{N(\tau)+1}-\tau$
, we have
 \begin{equation*}U_{\tau+t} = U_{T_{N(\tau)+1}} + \int_0^t (1-Q_{T_{N(\tau)+1}+s} )\,{\mathrm{d}} X_s + \int_0^t Q_{T_{N(\tau)+1}+s} {\mathrm{d}} Y_s. \end{equation*}
Thus we can use a similar argument to conclude that for any
 $t \gt 0$
,
 $(U_{\tau+t}, Q_{\tau+t})$
depends only on
 $(U_{\tau}, Q_{\tau})$
and post-
 $\tau$
increments of X, Y, and N. Therefore
 $(U_{t}, Q_{t})$
possesses the strong Markov property.
4. Main results
In this section we derive fluctuation identities for U. More specifically, we shall introduce new generalisations of scale functions (in terms of the classical scale functions in [Reference Kyprianou9]) and derive identities for the upward and downward exit problems, as well as the potential measure of U.
To do this, we let
 $U_0=x$
, fix
 $b \geq 0$
and, for
 $a \in \mathbb{R}^+$
, define the continuous and Poissonian first-passage stopping times
 \begin{equation*}\tau_{a,U}^{+(-)}\, :\!= \, \inf \{t>0\colon U_t>(<)\; a\} \quad \text{and} \quad {T}_{a,U}^{+ (-)}= \min \{T_i\colon {U}_{T_i}> (<) \; a \}, \end{equation*}
with the conventions inf
 $\varnothing=\infty$
and
 $\min \varnothing = \infty$
, respectively, where U in their subscripts indicate the underlying process that is considered. We point out that these subscripts U may change (to X and Y) in the rest of the paper, depending on the underlying process used, without otherwise altering the notion of these stopping times. Clearly, it holds that
 $\tau_{a,U}^{+ (-)} \leq T_{a,U}^{+ (-)}$
, and similar inequalities hold for the stopping times with corresponding subscripts X and Y.
We aim to derive the two-sided exit results for
 \begin{align*}\mathbb{E}_x\Bigl({\mathrm{e}}^{-q \tau_{a,U}^{+}} \mathbf{1}_{\{\tau_{a,U}^{+} \lt \tau_{0,U}^{-}\}} \Bigr) \quad \text{and} \quad \mathbb{E}_x\Bigl({\mathrm{e}}^{-q \tau_{0,U}^{-}} \mathbf{1}_{\{\tau_{0,U}^{-} \lt \tau_{a,U}^{+}\}} \Bigr). \end{align*}
We emphasise that the exit times in the above are not exit times of the process U observed at Poisson arrivals, but rather the standard exit times of the process U, which switches its dynamics at Poissonian times. We shall also show in Section 4.4 that the above Laplace transforms of the upward and downward exit times can be used to derive the probability of ruin in a risk model with delays on dividend payments. Finally, it is worth highlighting that the above exit time identities are comparable to the classical Lévy fluctuation literature and generalise existing results; see e.g. [Reference Wang, Lkabous and Landriault20].
To derive our main fluctuation results for U, we require the identities given in the following lemma and corollary.
Lemma 4.1. Let
 $0 \leq b \leq a$
,
 $q \geq 0$
and
 $0 \lt \lambda \lt \infty$
. Then the following identities hold.
-
(i) For
$ x,y \in [0,a]$
,
\begin{align*}&\mathbb{E}_x \biggl(\int^\infty_0 {\mathrm{e}}^{-q t} \mathbf{1}_{\{X_t \in {\mathrm{d}} y, \; t \lt T_{b,X}^{+} \wedge \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \,{\mathrm{d}} t \biggr) \\[3pt] &\quad = \Biggl( \dfrac{\overline{W}^{(q,\lambda)}_b(x)}{\overline{W}^{(q,\lambda)}_b(a)} \overline{W}_{b-y}^{(q,\lambda)}(a-y) - \overline{W}_{b-y}^{(q,\lambda)}(x-y) \Biggr) \,{\mathrm{d}} y.\end{align*}
-
(ii) For
$ x,y \in [0,a]$
,
\begin{align*}&\mathbb{E}_x \biggl(\int^\infty_0 {\mathrm{e}}^{-q t} \mathbf{1}_{\{Y_t \in {\mathrm{d}} y, \; t \lt T_{b,Y}^{-} \wedge \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} \,{\mathrm{d}} t \biggr) \\[3pt] &\quad = \Biggl( \dfrac{\overline{\mathbb{W}}^{(q,\lambda)}_{x-b}(x)}{\overline{\mathbb{W}}^{(q,\lambda)}_{a-b}(a)} \overline{\mathbb{W}}_{a-b}^{(q,\lambda)}(a-y) - \overline{\mathbb{W}}_{x-b}^{(q,\lambda)}(x-y) \Biggr) \,{\mathrm{d}} y.\end{align*}


Proof. (i) Let
 \begin{align*}R^{(q,\lambda)}(x,{\mathrm{d}} y) = \mathbb{E}_x \biggl(\int^\infty_0 {\mathrm{e}}^{-q t} \mathbf{1}_{\{X_t \in {\mathrm{d}} y, \; t \lt T_{b,X}^{+} \wedge \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \,{\mathrm{d}} t \biggr), \end{align*}
and assume that X has paths of bounded variation. Then, for
 $x \in [0,b)$
, by conditioning on
 $\tau_{b,X}^+$
and the strong Markov property, we have
 \begin{align}&R^{(q,\lambda)}(x,{\mathrm{d}} y) \nonumber \\[3pt] &\quad = \mathbb{E}_x \biggl(\int^\infty_0 {\mathrm{e}}^{-q t} \mathbf{1}_{\{X_t \in {\mathrm{d}} y, \; t \lt \tau_{b,X}^{+} \wedge \tau_{0,X}^-\}} \,{\mathrm{d}} t \biggr) + \mathbb{E}_x \Bigl({\mathrm{e}}^{-q \tau_{b,X}^+} \mathbf{1}_{\{\tau_{b,X}^+ \lt \tau_{0,X}^-\}} \Bigr) R^{(q,\lambda)}(b,{\mathrm{d}} y) \nonumber \\[3pt] &\quad = \dfrac{W^{(q)}(x)}{W^{(q)}(b)}\bigl( W^{(q)}(b-y) \mathbf{1}_{\{y \in [0,b)\}} \,{\mathrm{d}} y + R^{(q,\lambda)}(b,{\mathrm{d}} y)\bigr) - W^{(q)}(x-y) \mathbf{1}_{\{y \in [0,b)\}} \,{\mathrm{d}} y, \end{align}
where the last equality follows by using (A.1) and (A.3) from the Appendix.
Now, let
 $e_\lambda \sim \text{Exp}(\lambda)$
be independent of all other random variables. For
 $x \in [b,a]$
, observe that
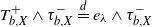 $T^+_{b,X} \wedge \tau_{b,X}^- \overset{d}{=} e_\lambda \wedge \tau_{b,X}^-$
. Hence, by conditioning on
 $\tau_{b,X}^-$
and using the strong Markov property, it follows that
 \begin{align}R^{(q,\lambda)}(x,{\mathrm{d}} y) &= \mathbb{E}_x \biggl(\int^\infty_0 {\mathrm{e}}^{-q t} \mathbf{1}_{\{X_t \in {\mathrm{d}} y, \; t \lt e_\lambda \wedge \tau_{a,X}^{+} \wedge \tau_{b,X}^-\}} \,{\mathrm{d}} t \biggr) \nonumber \\[3pt] &\quad + \mathbb{E}_x \Bigl({\mathrm{e}}^{-q \tau_{b,X}^-} \mathbf{1}_{\{\tau_{b,X}^- \lt e_\lambda \wedge \tau_{a,X}^{+}\}} R^{(q,\lambda)}\bigl(X_{\tau_{b,X}^-},{\mathrm{d}} y\bigr) \Bigr) \nonumber \\[3pt] &= \mathbb{E}_x \biggl(\int^\infty_0 {\mathrm{e}}^{-(q+\lambda) t} \mathbf{1}_{\{X_t \in {\mathrm{d}} y, \; t \lt \tau_{a,X}^{+} \wedge \tau_{b,X}^-\}} \,{\mathrm{d}} t \biggr) \nonumber \\[3pt] &\quad - \mathbb{E}_x \Bigl({\mathrm{e}}^{-(q+\lambda) \tau_{b,X}^-} \mathbf{1}_{\{\tau_{b,X}^- \lt \tau_{a,X}^{+}\}} W^{(q)}\bigl(X_{\tau_{b,X}^-} - y\bigr) \Bigr) \mathbf{1}_{\{ y \in [0,b)\}} \,{\mathrm{d}} y \nonumber \\[3pt] &\quad + \dfrac{1}{W^{(q)}(b)} \mathbb{E}_x \Bigl({\mathrm{e}}^{-(q+\lambda) \tau_{b,X}^-} \mathbf{1}_{\{\tau_{b,X}^- \lt \tau_{a,X}^{+}\}} W^{(q)}\bigl(X_{\tau_{b,X}^-}\bigr) \Bigr)\nonumber \\[3pt] &\quad \times \bigl( W^{(q)}(b-y) \mathbf{1}_{\{y \in [0,b)\}} \,{\mathrm{d}} y + R^{(q,\lambda)}(b,{\mathrm{d}} y)\bigr) \nonumber \\[3pt] &= \biggl( \dfrac{W^{(q+\lambda)}(x-b)}{W^{(q+\lambda)}(a-b)}W^{(q+\lambda)}(a-y) - W^{(q+\lambda)}(x-y) \biggr) \mathbf{1}_{\{ y \in [b,a]\}} \,{\mathrm{d}} y \nonumber \\[3pt] &\quad - \biggl( \overline{W}^{(q,\lambda)}_{b-y}(x-y) - \dfrac{W^{(q+\lambda)}(x-b)}{W^{(q+\lambda)}(a-b)} \overline{W}^{(q,\lambda)}_{b-y}(a-y) \biggr) \mathbf{1}_{\{ y \in [0,b)\}} \,{\mathrm{d}} y \nonumber \\[3pt] &\quad + \biggl(\dfrac{\overline{W}^{(q,\lambda)}_{b}(x)}{W^{(q)}(b)} - \dfrac{W^{(q+\lambda)}(x-b)}{W^{(q+\lambda)}(a-b)} \dfrac{\overline{W}^{(q,\lambda)}_{b}(a)}{W^{(q)}(b)} \biggr) \nonumber \\[3pt] &\quad \times \bigl( W^{(q)}(b-y) \mathbf{1}_{\{y \in [0,b)\}} \,{\mathrm{d}} y + R^{(q,\lambda)}(b,{\mathrm{d}} y)\bigr) \nonumber \end{align}
 \begin{align} &= \biggl( \dfrac{W^{(q+\lambda)}(x-b)}{W^{(q+\lambda)}(a-b)}\overline{W}_{b-y}^{(q,\lambda)}(a-y) - \overline{W}_{b-y}^{(q,\lambda)}(x-y) \biggr) \,{\mathrm{d}} y \nonumber \\[3pt] &\quad + \biggl(\dfrac{\overline{W}^{(q,\lambda)}_{b}(x)}{W^{(q)}(b)} - \dfrac{W^{(q+\lambda)}(x-b)}{W^{(q+\lambda)}(a-b)} \dfrac{\overline{W}^{(q,\lambda)}_{b}(a)}{W^{(q)}(b)} \biggr) \nonumber \\[3pt] &\quad \times \bigl( W^{(q)}(b-y) \mathbf{1}_{\{y \in [0,b)\}} \,{\mathrm{d}} y + R^{(q,\lambda)}(b,{\mathrm{d}} y)\bigr), \end{align}
where the second equality follows by substituting (4.1), the third equality follows by using (A.3) and (A.4) from the Appendix, and the last equality follows by observing that
 \begin{align*}\overline{W}^{(q,\lambda)}_{b-y}(x-y) = W^{(q+\lambda)}(x-y)\quad\text{for $y \in [b,a]$.} \end{align*}
Then, by putting
 $x = b$
in the above equation, we observe that
 $W^{(q+\lambda)}(0) \neq 0$
for X having bounded variation, and also that
 \begin{align*}\overline{W}^{(q,\lambda)}_{b-y}(b-y) = W^{(q)}(b-y)\quad\text{for $y \in [0,a]$,} \end{align*}
which yields
 \begin{align*}R^{(q,\lambda)}(b,{\mathrm{d}} y) &= \biggl( \dfrac{W^{(q+\lambda)}(0)}{W^{(q+\lambda)}(a-b)}\overline{W}_{b-y}^{(q,\lambda)}(a-y) - {W}^{(q)}(b-y)\mathbf{1}_{\{y \in [0,b) \}} \biggr) \,{\mathrm{d}} y \\[3pt] &\quad + \biggl(1 - \dfrac{W^{(q+\lambda)}(0)}{W^{(q+\lambda)}(a-b)} \dfrac{\overline{W}^{(q,\lambda)}_{b}(a)}{W^{(q)}(b)} \biggr) \\[3pt] &\quad \times \bigl( W^{(q)}(b-y) \mathbf{1}_{\{y \in [0,b)\}} \,{\mathrm{d}} y + R^{(q,\lambda)}(b,{\mathrm{d}} y)\bigr),\end{align*}
and hence
 \begin{equation*}R^{(q,\lambda)}(b,{\mathrm{d}} y) = \biggr(\dfrac{W^{(q)}(b)}{\overline{W}^{(q,\lambda)}_{b}(a)} \overline{W}^{(q,\lambda)}_{b-y}(a-y) - {W}^{(q)}(b-y)\mathbf{1}_{\{y \in [0,b) \}} \biggr) \,{\mathrm{d}} y. \end{equation*}
Substituting the above quantity into (4.1) and (4.2) yields the desired result.
To prove the unbounded variation case, we use strong approximation. First recall that there exists a sequence of bounded variation processes
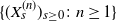 $\{(X_s^{(n)})_{s \geq 0}\colon n \geq 1\}$
that strongly approximates X, that is,
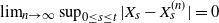 $\lim_{n \rightarrow \infty} \sup_{0 \leq s \leq t}| X_s - X_s^{(n)}| = 0$
for any
 $t \gt 0$
a.s. We let
 \begin{align*}T_{b,X}^{+}(n) & \, :\!= \, \min \big\{T_i>0\colon X^{(n)}_{T_i} \gt b \big\},\\[3pt]\tau_{a,X}^{+}(n) & \, :\!= \, \inf \big\{t>0\colon X^{(n)}_{t} \gt a \big\},\\[3pt]\tau_{0,X}^{-}(n) & \, :\!= \, \inf \big\{t>0\colon X^{(n)}_{t} \lt 0 \big\}\end{align*}
denote the stopping times corresponding to each process
 $X^{(n)}$
. Then (see [Reference Loeffen, Renaud and Zhou15, pp. 1421–1422]), for any time
 $t \gt 0$
,
 $\mathbb{P}_x$
-a.s., it holds that
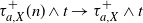 $\tau_{a,X}^{+}(n) \wedge t \rightarrow \tau_{a,X}^{+} \wedge t$
and
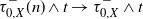 $\tau_{0,X}^{-}(n) \wedge t \rightarrow \tau_{0,X}^{-} \wedge t$
. We now show that
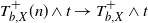 $T_{b,X}^{+}(n) \wedge t \rightarrow T_{b,X}^{+} \wedge t$
,
 $\mathbb{P}_x$
-a.s. First recall that the processes N (and thus every renewal time
 $T_i$
), X and
 $X^{(n)}$
are independent for every
 $n \geq 1$
. Thus, by using Proposition 15 of [Reference Bertoin4, p. 30], it can be shown that
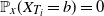 $\mathbb{P}_x(X_{T_i} = b) = 0$
. In addition, since the number of Poisson arrivals in [0, t] is finite, we shall consider the finite set of indices
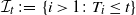 $\mathcal{I}_t \, :\!= \, \{i>1\colon T_i \leq t\}$
. If
 $\mathcal{I}t$
is empty, then
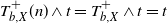 $T_{b,X}^{+}(n) \wedge t = T_{b,X}^{+} \wedge t = t$
,
 $\mathbb{P}_x$
-a.s. and so their convergence holds trivially. Thus we need only consider the case where
 $\mathcal{I}_t$
is non-empty. Furthermore, since
 \begin{align*}\lim_{n \rightarrow \infty} \sup\nolimits_{0 \leq s \leq t\wedge T_i}| X_s - X_s^{(n)}| \leq \lim_{n \rightarrow \infty} \sup\nolimits_{0 \leq s \leq t}| X_s - X_s^{(n)}| = 0, \end{align*}
thus it converges pointwise. In addition, since
 $ 1_{\{x>b\}}$
is discontinuous only at b, then, since
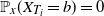 $\mathbb{P}_x(X_{T_i} = b) = 0$
, we have
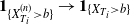 $\mathbf{1}_{\{X_{T_i}^{(n)} \gt b\}} \rightarrow \mathbf{1}_{\{X_{T_i} \gt b\}}$
,
 $\mathbb{P}_x$
-a.s. for all
 $i \in \mathcal{I}_t$
. From this it follows that there exists a random integer N such that for all
 $n \ge N$
these indicators coincide simultaneously for all
 $i \in \mathcal I_t$
. Hence, for all sufficiently large n, the set of indices
 $i \in \mathcal I_t$
for which
 $X^{(n)}_{T_i} \gt b$
is identical to the corresponding set for X. Therefore the first index at which the exceedance occurs is eventually the same, that is,
 \begin{align*}\min\bigl\{T_i \le t \colon X^{(n)}_{T_i} \gt b\bigr\}=\min\{T_i \le t \colon X_{T_i} \gt b\}, \end{align*}
for all sufficiently large n. If no such index exists, then both minima are greater than t. Consequently
 \begin{align*}T_{b,X}^{+}(n)\wedge t \;\to\; T_{b,X}^{+}\wedge t\quad \mathbb{P}_x\text{-a.s.} \end{align*}
Now one can utilise an approximating procedure similar to that in [Reference Loeffen, Renaud and Zhou15, pp. 1421–1422] to show that the bounded variation potential measure and scale functions converge to that of the unbounded variation cases.
(ii) The proof follows the same idea as that of (i), and thus, for brevity, we state only the main identities that are needed. Hence, let
 \begin{align*}\widetilde{R}^{(q,\lambda)}(x, {\mathrm{d}} y) = \mathbb{E}_x \biggl(\int^\infty_0 {\mathrm{e}}^{-q t} \mathbf{1}_{\{Y_t \in {\mathrm{d}} y, \; t \lt T_{b,Y}^{-} \wedge \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} \,{\mathrm{d}} t \biggr), \end{align*}
and consider Y for bounded variation paths. Then, for
 $e_\lambda \sim \text{Exp}(\lambda)$
independent of all other random variables and
 $x \in [0,b)$
, observe that
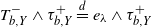 $T_{b,Y}^- \wedge \tau_{b,Y}^+ \overset{d }{=} e_\lambda \wedge \tau_{b,Y}^+$
, and so by conditioning on
 $\tau_{b,Y}^+$
, using the strong Markov property and (A.1) and (A.3) from the Appendix, we follow the same argument as that used to derive (4.2), to get
 \begin{align}&\widetilde{R}^{(q,\lambda)}(x,{\mathrm{d}} y) \nonumber \\[3pt] &\quad = \dfrac{\mathbb{W}^{(q+\lambda)}(x)}{\mathbb{W}^{(q+\lambda)}(b)}\bigl( \mathbb{W}^{(q+\lambda)}(b-y) \mathbf{1}_{\{y \in [0,b)\}} \,{\mathrm{d}} y + \widetilde{R}^{(q,\lambda)}(b,{\mathrm{d}} y)\bigr) - \mathbb{W}^{(q+\lambda)}(x-y) \mathbf{1}_{\{y \in [0,b)\}} \,{\mathrm{d}} y. \end{align}
Now, for
 $x \in [b,a]$
, we condition on
 $\tau_{b,Y}^-$
, use the strong Markov property and a substitution of (4.3) along with (A.3) and (A.4) from the Appendix, to get
 \begin{align}\widetilde{R}^{(q,\lambda)}(x,{\mathrm{d}} y) &= \biggl( \dfrac{\mathbb{W}^{(q)}(x-b)}{\mathbb{W}^{(q)}(a-b)}\overline{\mathbb{W}}_{b-y}^{(q+\lambda,-\lambda)}(a-y) - \overline{\mathbb{W}}_{b-y}^{(q+\lambda,-\lambda)}(x-y) \biggr) \,{\mathrm{d}} y \nonumber \\[3pt] &\quad + \biggl(\dfrac{\overline{\mathbb{W}}^{(q+\lambda,-\lambda)}_{b}(x)}{\mathbb{W}^{(q+\lambda)}(b)} - \dfrac{\mathbb{W}^{(q)}(x-b)}{\mathbb{W}^{(q)}(a-b)} \dfrac{\overline{W}^{(q+\lambda,-\lambda)}_{b}(a)}{\mathbb{W}^{(q+\lambda)}(b)} \biggr)\nonumber \\[3pt] &\quad \times \bigl( \mathbb{W}^{(q+\lambda)}(b-y) \mathbf{1}_{\{y \in [0,b)\}} \,{\mathrm{d}} y + \widetilde{R}^{(q,\lambda)}(b,{\mathrm{d}} y)\bigr). \end{align}
Then, by putting
 $x = b$
in the above equation and observing that
 $\mathbb{W}^{(q)}(0) \neq 0$
for Y having bounded variation and also that
 \begin{align*}\overline{\mathbb{W}}^{(q+\lambda,-\lambda)}_{b-y}(b-y) = \mathbb{W}^{(q+\lambda)}(b-y)\quad\text{for $y \in [0,a]$,} \end{align*}
we can derive that
 \begin{equation*}\widetilde{R}^{(q,\lambda)}(b,{\mathrm{d}} y) = \biggr(\dfrac{\mathbb{W}^{(q+\lambda)}(b)}{\overline{\mathbb{W}}^{(q+\lambda,-\lambda)}_{b}(a)} \overline{\mathbb{W}}^{(q+\lambda,-\lambda)}_{b-y}(a-y) - {\mathbb{W}}^{(q+\lambda)}(b-y)\mathbf{1}_{\{y \in [0,b) \}} \biggr) \,{\mathrm{d}} y. \end{equation*}
Then, by substituting the above equation into (4.3) and (4.4), and noticing also that
 \begin{align*}\overline{\mathbb{W}}^{(q+\lambda,-\lambda)}_{b}(x) = \overline{\mathbb{W}}^{(q,\lambda)}_{x-b}(x), \end{align*}
we prove the identity for the bounded variation case. The unbounded variation case is proved by the approximation approach mentioned in the proof of (i).
Corollary 4.1. Let
 $0 \leq b \leq a$
,
 $q \geq 0$
and
 $0 \lt \lambda \lt \infty$
. Then the following identities hold.
-
(i) For
$ x \in [0,a]$
and
$ y \in [b,a]$
, and
\begin{align*}&\mathbb{E}_x \Bigl({\mathrm{e}}^{-q T_b^{+}} \mathbf{1}_{\{X_{T_{b,X}^{+}} \in {\mathrm{d}} y, \; T_{b,X}^{+} \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \Bigr) \\[3pt] &\quad = \lambda \Biggl( \dfrac{\overline{W}^{(q,\lambda)}_b(x)}{\overline{W}^{(q,\lambda)}_b(a)} W^{(q+\lambda)}(a-y) - W^{(q+\lambda)}(x-y) \Biggr) \,{\mathrm{d}} y,\end{align*}
\begin{equation*}\mathbb{E}_x \Bigl({\mathrm{e}}^{-q\tau_{a,X}^+} \mathbf{1}_{\{\tau_{a,X}^+ \lt T_{b,X}^{+} \wedge \tau_{0,X}^-\}} \Bigr) = \dfrac{\overline{W}^{(q,\lambda)}_b(x)}{\overline{W}^{(q,\lambda)}_b(a)}.\end{equation*}
-
(ii) For
$x \in [0,a]$
and
$y \in [0,b]$
, and
\begin{align*}&\mathbb{E}_x \Bigl({\mathrm{e}}^{-q T_{b,Y}^{-}} \mathbf{1}_{\{Y_{T_{b,Y}^{-}} \in {\mathrm{d}} y, T_{b,Y}^{-} \lt \tau_{a,Y}^{+} \wedge \tau_{0,Y}^{-}\}} \Bigr) \\[3pt] &\quad =\lambda\Biggl(\dfrac{\overline{\mathbb{W}}_{x-b}^{(q, \lambda)}(x)}{\overline{\mathbb{W}}_{a-b}^{(q, \lambda)}(a)} \overline{\mathbb{W}}_{a-b}^{(q, \lambda)}(a-y)-\overline{\mathbb{W}}_{x-b}^{(q, \lambda)}(x-y)\Biggr)\,{\mathrm{d}} y,\end{align*}
\begin{equation*}\mathbb{E}_x \Bigl({\mathrm{e}}^{-q \tau_{a,Y}^{+}} \mathbf{1}_{\{\tau_{a,Y}^{+}< T_{b,Y}^{-} \wedge \tau_{0,Y}^{-}\}}\Bigr)=\dfrac{\overline{\mathbb{W}}_{x-b}^{(q, \lambda)}(x)}{\overline{\mathbb{W}}_{a-b}^{(q, \lambda)}(a)}. \end{equation*}
-
(iii) For
$ x \in [0,a]$
, and
\begin{align*}\mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q \tau_{0,Y}^-} \mathbf{1}_{\{\tau_{0,Y}^- \lt T_{b,Y}^{-} \wedge \tau_{a,Y}^+ \}} \Bigr)& = \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q \tau_{0,Y}^- - \lambda \int^{\tau_{0,Y}^-}_0 \mathbf{1}_{\{Y_s\in (0,b)\}} \,{\mathrm{d}} s} \, \mathbf{1}_{\{\tau_{0,Y}^- \lt \tau_{a,Y}^+\}} \Bigr) \nonumber \\[3pt] &= \overline{\mathbb{Z}}^{(q+\lambda,-\lambda)}_b(x) - \dfrac{\overline{\mathbb{W}}^{(q,\lambda)}_{x-b}(x)}{\overline{\mathbb{W}}^{(q,\lambda)}_{a-b}(a)} \overline{\mathbb{Z}}^{(q+\lambda,-\lambda)}_b(a), \end{align*}
\begin{align*}\mathbb{E}^{}_x \bigl({\mathrm{e}}^{-q \tau_{0,X}^-} \mathbf{1}_{\{\tau_{0,X}^- \lt T_{b,X}^{+} \wedge \tau_{a,X}^+ \}} \bigr)&= \mathbb{E}^{}_x\Bigl({\mathrm{e}}^{-q \tau_{0,X}^- - \lambda \int^{\tau_{0,X}^-}_0 \mathbf{1}_{\{X_s\in(b,a) \}}\,{\mathrm{d}} s} \, \mathbf{1}_{\{\tau_{0,X}^- \lt \tau_{a,X}^+\}} \Bigr) \nonumber \\[3pt] &= \overline{Z}^{(q,\lambda)}_{b}(x) - \dfrac{\overline{W}^{(q,\lambda)}_{b}(x)}{\overline{W}^{(q,\lambda)}_{b}(a)}\overline{Z}^{(q,\lambda)}_{b}(a). \end{align*}


Proof. (i) We use the same reasoning as that of Corollary 3.1 in [Reference Landriault, Li, Wong and Xu12]. Hence, by noticing that the probability that an observation is made in
 $(t,t+{\mathrm{d}} t)$
is
 $\lambda {\mathrm{d}} t$
and is independent of X, we have that
 $T_{b,X}^+$
satisfies
 \begin{equation*}\mathbb{P}_x\bigl(T_{b,X}^+ \in {\mathrm{d}} t, \; X_t \in [b,\infty)\bigr) = \lambda \mathbb{P}_x\bigl(T_{b,X}^+ \gt t, \; X_t \in [b,\infty)\bigr) \,{\mathrm{d}} t,\end{equation*}
and so we use the above to find for
 $y \in [b,a]$
that
 \begin{align*}&\mathbb{E}_x \Bigl({\mathrm{e}}^{-q T_{b,X}^+} \mathbf{1}_{\{X_{T_{b,X}^+} \in {\mathrm{d}} y, T_{b,X}^+ \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \Bigr) \\[3pt] &\quad = \int^\infty_0 {\mathrm{e}}^{-q t} \mathbb{P}_x \bigl(X_t \in {\mathrm{d}} y, \; t \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-, \; T_{b,X}^+ \in {\mathrm{d}} t \bigr) \nonumber \\[3pt] &\quad = \lambda \int^\infty_0 {\mathrm{e}}^{-q t} \mathbb{P}_x \bigl(X_t \in {\mathrm{d}} y, \; t \lt T_{b,X}^+ \wedge \tau_{a,X}^+ \wedge \tau_{0,X}^- \bigr) \,{\mathrm{d}} t \nonumber \\[3pt] &\quad = \lambda \Biggl( \dfrac{\overline{W}^{(q,\lambda)}_b(x)}{\overline{W}^{(q,\lambda)}_b(a)} W^{(q+\lambda)}(a-y) - W^{(q+\lambda)}(x-y) \Biggr) \,{\mathrm{d}} y, \end{align*}
where the last equality follows by using Lemma 4.1(i), and that
 \begin{align*}\overline{W}^{(q,\lambda)}_{b-y}(x-y)=W^{(q+\lambda)}(x-y)\quad\text{for $y \in [b,a]$.} \end{align*}
For the second identity, observe by conditioning on
 $T_{b,X}^+$
, using the strong Markov property and then conditioning on
 $X_{T_{b,X}^+}$
that
 \begin{align*}&\mathbb{E}_x \Bigl({\mathrm{e}}^{-q\tau_{a,X}^+} \mathbf{1}_{\{\tau_{a,X}^+ \lt T_{b,X}^{+} \wedge \tau_{0,X}^-\}} \Bigr)\nonumber \\[3pt] &\quad = \mathbb{E}_x \Bigl({\mathrm{e}}^{-q\tau_{a,X}^+} \mathbf{1}_{\{\tau_{a,X}^+ \lt \tau_{0,X}^-\}} \Bigr)\nonumber - \mathbb{E}_x \Bigl({\mathrm{e}}^{-q\tau_{a,X}^+} \mathbf{1}_{\{ T_{b,X}^{+} \lt \tau_{a,X}^+ \lt \tau_{0,X}^-\}} \Bigr)\nonumber \\[3pt] & \quad= \mathbb{E}_x \Bigl({\mathrm{e}}^{-q\tau_{a,X}^+} \mathbf{1}_{\{\tau_{a,X}^+ \lt \tau_{0,X}^-\}} \Bigr)\nonumber \\[3pt] &\quad\quad - \int^a_b \mathbb{E}_x \Bigl({\mathrm{e}}^{-qT_{b,X}^+} \mathbf{1}_{\{ X_{T_{b,X}^+} \in {\mathrm{d}} y, \; T_{b,X}^{+} \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \Bigr) \mathbb{E}_y \Bigl({\mathrm{e}}^{-q\tau_{a,X}^+} \mathbf{1}_{\{\tau_{a,X}^+ \lt \tau_{0,X}^-\}} \Bigr) \nonumber \\[3pt] &\quad = \dfrac{W^{(q)}(x)}{W^{(q)}(a)} - \lambda\int^a_b \Biggl( \dfrac{\overline{W}^{(q,\lambda)}_b(x)}{\overline{W}^{(q,\lambda)}_b(a)} W^{(q+\lambda)}(a-y) - W^{(q+\lambda)}(x-y) \Biggr) \dfrac{W^{(q)}(y)}{W^{(q)}(a)} \,{\mathrm{d}} y \nonumber \\[3pt] &\quad = \dfrac{1}{W^{(q)}(a)} \Biggl( W^{(q)}(x) - \dfrac{\overline{W}^{(q,\lambda)}_b(x)}{\overline{W}^{(q,\lambda)}_b(a)} \Bigl[\overline{W}^{(q,\lambda)}_b(a) - W^{(q)}(a) \Bigr] + \Bigl[\overline{W}^{(q,\lambda)}_b(x) - W^{(q)}(x) \Bigr] \Biggr) \nonumber \\[3pt] &\quad = \dfrac{\overline{W}^{(q,\lambda)}_b(x)}{\overline{W}^{(q,\lambda)}_b(a)}, \end{align*}
where the second equality follows by using the first result of the proof along with (A.1) from the Appendix, and the third equality uses (2.3).
-
(ii) The result can be proved in a similar way to the above, but can also be seen directly from Theorem 1.2 in [Reference Baurdoux, Pardo, Pérez and Renaud3] or Corollary 3.2 in [Reference Landriault, Li, Wong and Xu12].
-
(iii) Observe from Remark 3.2 in [Reference Albrecher, Ivanovs and Zhou1] that
Then Theorem 1 in [Reference Loeffen, Renaud and Zhou15] yields
\begin{equation*}\mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q \tau_{0,Y}^-} \mathbf{1}_{\{\tau_{0,Y}^- \lt T_{b,Y}^{-} \wedge \tau_{a,Y}^+ \}} \Bigr) = \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q \tau_{0,Y}^- - \lambda \int^{\tau_{0,Y}^-}_0 \mathbf{1}_{(0,b)}(Y_s)\,{\mathrm{d}} s} \, \mathbf{1}_{\{\tau_{0,Y}^- \lt \tau_{a,Y}^+\}} \Bigr).\end{equation*}
where the last equality holds by using (2.3)–(2.4).
\begin{align*}& \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q \tau_{0,Y}^- - \lambda \int^{\tau_{0,Y}^-}_0 \mathbf{1}_{(0,b)}(Y_s)\,{\mathrm{d}} s} \, \mathbf{1}_{\{\tau_{0,Y}^- \lt \tau_{a,Y}^+\}} \Bigr) \nonumber \\[4pt] & = \overline{\mathbb{Z}}_0^{(q,\lambda)}(x) - \lambda \int^x_b \mathbb{W}^{(q)}(x-y) \overline{\mathbb{Z}}_0^{(q,\lambda)}(y) \,{\mathrm{d}} y \nonumber \\[4pt] &\quad {-} \dfrac{\overline{\mathbb{W}}_0^{(q,\lambda)}(x) - \lambda \int^x_b \mathbb{W}^{(q)}(x-y) \overline{\mathbb{W}}_0^{(q,\lambda)}(y) \,{\mathrm{d}} y}{\overline{\mathbb{W}}_0^{(q,\lambda)}(a) - \lambda \int^a_b \mathbb{W}^{(q)}(a-y) \overline{\mathbb{W}}_0^{(q,\lambda)}(y) \,{\mathrm{d}} y} \biggl(\overline{\mathbb{Z}}_0^{(q,\lambda)}(a) - \lambda \!\!\int^a_b\!\! \mathbb{W}^{(q)}(a-y) \overline{\mathbb{Z}}_0^{(q,\lambda)}{(y)} \,{\mathrm{d}}y\!\biggr) \nonumber \\[4pt] & = \overline{\mathbb{Z}}^{(q+\lambda,-\lambda)}_b(x) - \dfrac{\overline{\mathbb{W}}^{(q,\lambda)}_{x-b}(x)}{\overline{\mathbb{W}}^{(q,\lambda)}_{a-b}(a)} \overline{\mathbb{Z}}^{(q+\lambda,-\lambda)}_b(a), \end{align*}


The remaining identity can be shown in a similar way, by first using Remark 3.2 in [Reference Albrecher, Ivanovs and Zhou1] to observe that
 \begin{align*}\mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q \tau_{0,X}^-} \mathbf{1}_{\{\tau_{0,X}^- \lt T_{b,X}^{+} \wedge \tau_{a,X}^+ \}} \Bigr)= \mathbb{E}^{}_x\Bigl({\mathrm{e}}^{-q \tau_{0,X}^- - \lambda \int^{\tau_{0,X}^-}_0 \mathbf{1}_{(b,a)}(X_s)\,{\mathrm{d}} s} \, \mathbf{1}_{\{\tau_{0,X}^- \lt \tau_{a,X}^+\}} \Bigr) , \end{align*}
and then using Theorem 1 in [Reference Loeffen, Renaud and Zhou15].
4.1. Two-sided exit upwards and downwards
To derive the exit upwards and downwards, we are required to evaluate expectations that involve the Poissonian stopping times
 $T_{b,X}^{+}$
and
 $T_{b,Y}^{-}$
. To be more precise, for a positive measurable (multivariate) function f, we will need to evaluate expectations of the form
 \begin{align*}\mathbb{E}_x \Bigl({\mathrm{e}}^{-q T_{b,X}^{+}} \mathbf{1}_{\{ T_{b,X}^{+} \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} f\bigl(X_{T_{b,X}^{+}};\,z\bigr) \Bigr) \quad \text{and} \quad \mathbb{E}_x \Bigl({\mathrm{e}}^{-q T_{b,Y}^{-}} \mathbf{1}_{\{ T_{b,Y}^{-} \lt \tau_{a,Y}^{+} \wedge \tau_{0,Y}^{-}\}} f\bigl(Y_{T_{b,Y}^{-}};\,z\bigr) \Bigr). \end{align*}
This can be done by first conditioning on
 $X_{T_{b,X}^+}$
 $(Y_{T_{b,Y}^-})$
and then using Corollary 4.1(i) (4.1(ii)), to get
 \begin{align}&\mathbb{E}_x \Bigl({\mathrm{e}}^{-q T_{b,X}^{+}} \mathbf{1}_{\{ T_{b,X}^{+} \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} f\bigl(X_{T_{b,X}^{+}};\,z\bigr) \Bigr) \nonumber \\[3pt] &\quad = \int^a_b \mathbb{E}_x \Bigl({\mathrm{e}}^{-q T_{b,X}^{+}} \mathbf{1}_{\{X_{T_{b,X}^{+}} \in {\mathrm{d}} y, \; T_{b,X}^{+} \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \Bigr)f(y;\,z) \nonumber \\[3pt] &\quad = \dfrac{\overline{W}^{(q,\lambda)}_b(x)}{\overline{W}^{(q,\lambda)}_b(a)} \lambda \int^a_b W^{(q+\lambda)}(a-y) f(y;\,z) \,{\mathrm{d}} y - \lambda \int^x_b W^{(q+\lambda)}(x-y) f(y;\,z) \,{\mathrm{d}} y, \end{align}
and
 \begin{align}&\mathbb{E}_x \Bigl({\mathrm{e}}^{-q T_{b,Y}^{-}} \mathbf{1}_{\{ T_{b,Y}^{-} \lt \tau_{a,Y}^{+} \wedge \tau_{0,Y}^{-}\}} f\bigl(Y_{T_{b,Y}^{-}};\,z\bigr) \Bigr) \nonumber \\[3pt] &\quad = \int^b_0 \mathbb{E}_x \Bigl({\mathrm{e}}^{-q T_{b,Y}^{-}} \mathbf{1}_{\{Y_{T_{b,Y}^{-}} \in {\mathrm{d}} y, T_{b,Y}^{-} \lt \tau_{a,Y}^{+} \wedge \tau_{0,Y}^{-}\}} \Bigr)f(y;\,z) \nonumber \\[3pt] & \quad =\dfrac{\overline{\mathbb{W}}_{x-b}^{(q, \lambda)}(x)}{\overline{\mathbb{W}}_{a-b}^{(q, \lambda)}(a)} \lambda \int^b_0 \overline{\mathbb{W}}_{a-b}^{(q, \lambda)}(a-y) f(y;\,z) \,{\mathrm{d}} y - \lambda \int^b_0 \overline{\mathbb{W}}_{x-b}^{(q, \lambda)}(x-y) f(y;\,z) \,{\mathrm{d}} y, \end{align}
respectively. As a result, it is clear that the exit identities will contain integrals of the form
 \begin{align*}\lambda \int^x_b W^{(q+\lambda)}(x-y) f(y;\,z) \,{\mathrm{d}} y \quad \text{and} \quad \lambda \int^b_0 \overline{\mathbb{W}}_{x-b}^{(q, \lambda)}(x-y) f(y;\,z) \,{\mathrm{d}} y, \end{align*}
and thus, for different choices of the function f, let us define auxiliary functions (containing the integrals above) in order to formulate our results more concisely. For
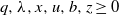 $q,\lambda,x,u,b,z \geq 0$
, let
 \begin{align*}\gamma_{b}^{(q,\lambda)}(x;\,z) &= W^{(q)}(x-z) - \overline{\mathbb{W}}^{(q,\lambda)}_{x-b}(x-z) + \lambda \int_0^{b-z} \overline{\mathbb{W}}_{x-b}^{(q,\lambda)}(x-z-y) W^{(q)}(y)\,{\mathrm{d}} y, \\[3pt]\alpha_b^{(q,\lambda)}(x) &= Z^{(q)}(x) - \overline{\mathbb{Z}}_{b}^{(q+\lambda,-\lambda)}(x) + \lambda \int_0^{b} \overline{\mathbb{W}}_{x-b}^{(q,\lambda)}(x-y) Z^{(q)}(y)\,{\mathrm{d}} y , \end{align*}
and further let
 \begin{align}\mathcal{W}_u^{(q,\lambda)}(x;\,z) &= \overline{\mathbb{W}}_{x-b}^{(q,\lambda)}(x-z) + \lambda \int_u^{x} W^{(q+\lambda)}(x-y) \overline{\mathbb{W}}_{y-b}^{(q,\lambda)}(y-z)\,{\mathrm{d}} y, \\[-10pt] \nonumber\end{align}
 \begin{align}\mathcal{G}^{(q,\lambda)}_{u}(x;\,z) &= \gamma_{b}^{(q, \lambda)}(x;\,z) + \lambda \int^x_u W^{(q+\lambda)}(x-y) \gamma_{b}^{(q, \lambda)}(y;\,z)\,{\mathrm{d}} y, \\[-10pt] \nonumber \end{align}
 \begin{align}\mathcal{A}^{(q,\lambda)}_{u}(x) &= \alpha_b^{(q, \lambda)}(x) + \lambda \int^x_u W^{(q+\lambda)}(x-y) \alpha_b^{(q, \lambda)}(y)\,{\mathrm{d}} y. \\[8pt] \nonumber \end{align}
We will use the convention that
 \begin{align*}\gamma_{b}^{(q,\lambda)}(x) \, :\!= \, \gamma_{b}^{(q,\lambda)}(x;\,0),\quad\mathcal{W}^{\,(q,\lambda)}_{u} (x) \, :\!= \, \mathcal{W}^{\,(q,\lambda)}_{u} (x;\,0)\quad\text{and}\quad\mathcal{G}^{(q,\lambda)}_{u} (x) \, :\!= \, \mathcal{G}^{(q,\lambda)}_{u} (x;\,0), \end{align*}
and will regularly use that
 \begin{align*}\mathcal{W}_x^{(q,\lambda)}(x;\,z) = \overline{\mathbb{W}}_{x-b}^{(q,\lambda)}(x-z), \quad\mathcal{G}^{(q,\lambda)}_{x}(x;\,z) = \gamma_{b}^{(q, \lambda)}(x;\,z)\quad\text{and}\quad\mathcal{A}^{(q,\lambda)}_{x}(x) = \alpha_b^{(q, \lambda)}(x). \end{align*}
Theorem 4.1. For
 $q, \lambda \geq 0$
and
 $0 \leq x, b \leq a$
,
 \begin{equation}\mathbb{E}_x\Bigl({\mathrm{e}}^{-q \tau_{a,U}^{+}} \mathbf{1}_{\{\tau_{a,U}^{+}< \tau_{0,U}^{-}\}}\Bigr)=\dfrac{\mathcal{U}_{b, a}^{(q, \lambda)}(x)}{\mathcal{U}_{b, a}^{(q, \lambda)}(a)} , \end{equation}
where
 \begin{equation}\mathcal{U}_{b, a}^{(q, \lambda)}(x;\,y) = W^{(q)}(x-y) - \mathbf{1}_{\{x \gt b\}}\biggl(\mathcal{G}_{x}^{(q, \lambda)}(x;\,y) -\dfrac{\mathcal{W}_{x}^{\,(q, \lambda)}(x)}{\mathcal{W}_{b}^{(q, \lambda)}(a)} \mathcal{G}_{b}^{(q, \lambda)}(a;\,y) \biggr), \end{equation}
with the convention that
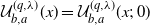 $\mathcal{U}_{b, a}^{(q, \lambda)}(x) = \mathcal{U}_{b, a}^{(q, \lambda)}(x;\,0)$
.
Proof. We first note that U starts with either X or Y dynamics depending on its starting position. Thus
 \begin{align*} \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q \tau_{a,U}^+ } \mathbf{1}_{\{\tau_{a,U}^+ \lt \tau_{0,U}^-\}}\Bigr) \end{align*}
will be denoted as
 $p^X(x)$
for
 $x \in [0,b]$
, and
 $p^Y(x)$
for
 $x \in (b,a]$
.
Now suppose that
 $x \in [0,b]$
. Using the strong Markov property and (A.1) from the Appendix, we have
 \begin{align}p^{ X }(x) &= \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q \tau_{b,U}^+ } \mathbf{1}_{\{\tau_{b,U}^+ \lt \tau_{0,U}^-\}} \mathbb{E}^{}_{U_{\tau_{b,U}^+}} \Bigl({\mathrm{e}}^{-q \tau_{a,U}^+ } \mathbf{1}_{\{\tau_{a,U}^+ \lt \tau_{0,U}^-\}} \Bigr) \Bigr)\nonumber \\[3pt] &= \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q \tau_{b,X}^+ } \mathbf{1}_{\{\tau_{b,X}^+ \lt \tau_{0,X}^-\}} \Bigr) p^{ X }(b) \nonumber \\[3pt] & =\dfrac{W^{(q)}(x)}{W^{(q)}(b)} p^{ X }(b), \end{align}
where the second-to-last equality follows since
 $\{X_t, t \lt T_{b,X}^+\}$
and
 $\{U_t, t \lt T_{b,U}^+\}$
have the same distribution with respect to
 $\mathbb{P}_x$
when
 $x \in [0,b]$
, and by recalling that
 $\tau_{b,X}^+ \leq T_{b,X}^+$
and
 $\tau_{b,U}^+ \leq T_{b,U}^+$
.
Similarly, suppose that the process starts at
 $x \in (b,a]$
, and notice that
 $\{Y_t, t \lt T_{b,Y}^-\}$
and
 $\{U_t, t \lt T_{b,U}^-\}$
have the same distribution with respect to
 $\mathbb{P}_x$
for these x-values. Therefore, by conditioning on whether
 $T_{b,U}^-$
or
 $\tau_{a,U}^+$
occurs first and again using the strong Markov property along with Corollary 4.1(ii), we get that
 \begin{align}p^{ Y }(x) &= \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q \tau_{a,U}^+} \mathbf{1}_{\{\tau_{a,U}^+ \lt T_{b,U}^{-} \wedge \tau_{0,U}^- \}} \Bigr) + \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q \tau_{a,U}^+} \mathbf{1}_{\{T_{b,U}^{-} \lt \tau_{a,U}^+ \lt \tau_{0,U}^- \}} \Bigr) \nonumber \\[3pt] &= \dfrac{\overline{\mathbb{W}}^{(q,\lambda)}_{x-b}(x)}{\overline{\mathbb{W}}^{(q,\lambda)}_{a-b}(a)} + \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q T_{b,Y}^{-}} \mathbf{1}_{\{T_{b,Y}^{-} \lt \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} \mathbb{E}^{}_{Y_{T_{b,Y}^{-}}} \Bigl({\mathrm{e}}^{-q \tau_{a,U}^+ } \mathbf{1}_{\{\tau_{a,U}^+ \lt \tau_{0,U}^-\}} \Bigr) \Bigr) \nonumber\\[3pt] &= \dfrac{\mathcal{W}^{\,(q,\lambda)}_{x}(x)}{\mathcal{W}^{\,(q,\lambda)}_{a}(a)} + \dfrac{p^{ X }(b)}{W^{(q)}(b)} \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q T_{b,Y}^{-}} \mathbf{1}_{\{T_{b,Y}^{-} \lt \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} W^{(q)}\bigl(Y_{T_{b,Y}^{-}}\bigr) \Bigr), \end{align}
where the last equality holds by using (4.7) and substituting (4.12).
From (4.12)–(4.13), it remains to derive
 $p^{ X }(b)$
. To derive this quantity, we use a line of reasoning similar to that for (4.13), that is, by conditioning on whether
 $T_{b,U}^+$
or
 $\tau_{a,U}^+$
occurs first and using the strong Markov property along with Corollary 4.1(i),
 \begin{align}p^{ X }(b) &= \mathbb{E}^{}_b \Bigl({\mathrm{e}}^{-q \tau_{a,U}^+} \mathbf{1}_{\{\tau_{a,U}^+ \lt T_{b,U}^{+} \wedge \tau_{0,U}^- \}} \Bigr) + \mathbb{E}^{}_b \Bigl({\mathrm{e}}^{-q \tau_{a,U}^+} \mathbf{1}_{\{T_{b,U}^{+} \lt \tau_{a,U}^+ \lt \tau_{0,U}^- \}} \Bigr) \nonumber \\[3pt] &= \dfrac{\overline{W}^{(q,\lambda)}_{b}(b)}{\overline{W}^{(q,\lambda)}_{b}(a)} + \mathbb{E}^{}_b \Bigl({\mathrm{e}}^{-q T_{b,X}^{+}} \mathbf{1}_{\{T_{b,X}^{+} \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} p^{ Y }\bigl(X_{T_{b,X}^{+}}\bigr) \Bigr) \nonumber \\[3pt] &= \dfrac{\overline{W}^{(q,\lambda)}_{b}(b)}{\overline{W}^{(q,\lambda)}_{b}(a)} + \dfrac{1}{\mathcal{W}^{\,(q,\lambda)}_{a}(a)} \mathbb{E}^{}_b \Bigl({\mathrm{e}}^{-q T_{b,X}^{+}} \mathbf{1}_{\{T_{b,X}^{+} \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \mathcal{W}^{\,(q,\lambda)}_{X_{T_{b,X}^{+}}} \bigl(X_{T_{b,X}^{+}}\bigr) \Bigr)\nonumber \\[3pt] & \quad + \dfrac{p^{ X }(b)}{W^{(q)}(b)} \nonumber \\[3pt] &\quad \times \mathbb{E}^{}_b \Bigl({\mathrm{e}}^{-q T_{b,X}^{+}} \mathbf{1}_{\{T_{b,X}^{+} \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \mathbb{E}^{}_{X_{T_{b,X}^{+}}} \Bigl({\mathrm{e}}^{-q T_{b,Y}^{-}} \mathbf{1}_{\{T_{b,Y}^{-} \lt \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} W^{(q)}\bigl(Y_{T_{b,Y}^{-}}\bigr) \Bigr) \Bigr), \end{align}
where the last line holds by substituting (4.13) into the second equality above.
We now aim to evaluate the two expectations of the above equation. Using (4.5) and (4.7),
 \begin{equation}\mathbb{E}^{}_b \Bigl({\mathrm{e}}^{-q T_{b,X}^{+}} \mathbf{1}_{\{T_{b,X}^{+} \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \mathcal{W}^{\,(q,\lambda)}_{X_{T_{b,X}^{+}}} \bigl(X_{T_{b,X}^{+}};\,y\bigr) \Bigr)= \dfrac{\overline{W}_{b}^{(q,\lambda)}(b)}{\overline{W}_{b}^{(q,\lambda)}(a)} \bigl( \mathcal{W}_{b}^{(q,\lambda)}(a;\,y) - {\mathcal{W}}_{a}^{(q,\lambda)}(a;\,y) \bigr), \end{equation}
for
 $y \geq 0$
, and thus the first expectation in (4.14) is given by the above for
 $y=0$
. To evaluate the second expectation of (4.14), first note that for
 $x \gt b$
from (4.6) and (4.8)
 \begin{align}\mathbb{E}^{}_{x} &\Bigl({\mathrm{e}}^{-q T_{b,Y}^{-}} \mathbf{1}_{\{T_{b,Y}^{-} \lt \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} W^{(q)}\bigl(Y_{T_{b,Y}^{-}}\bigr) \Bigr) \nonumber \\[3pt] &= \dfrac{\mathcal{W}_{x}^{\,(q,\lambda)}(x)}{\mathcal{W}_{a}^{(q,\lambda)}(a)} \bigl( \mathcal{G}_{a}^{(q,\lambda)}(a) - W^{(q)}(a) + \mathcal{W}_{a}^{(q,\lambda)}(a)\bigr) - \bigl( \mathcal{G}_{x}^{(q,\lambda)}(x) - W^{(q)}(x) + \mathcal{W}_{x}^{\,(q,\lambda)}(x) \bigr) \nonumber \\[3pt] &= \dfrac{\mathcal{W}_{x}^{\,(q,\lambda)}(x)}{\mathcal{W}_{a}^{(q,\lambda)}(a)} \biggl( \dfrac{\mathcal{W}_{a}^{(q, \lambda)}(a)}{\mathcal{W}_{b}^{(q, \lambda)}(a)} \mathcal{G}_{b}^{(q, \lambda)}(a) - \mathcal{U}_{b, a}^{(q, \lambda)}(a) \biggr) - \biggl( \dfrac{\mathcal{W}_{x}^{\,(q, \lambda)}(x)}{\mathcal{W}_{b}^{(q, \lambda)}(a)} \mathcal{G}_{b}^{(q, \lambda)}(a) - \mathcal{U}_{b, a}^{(q, \lambda)}(x) \biggr) \nonumber \\[3pt] &= \mathcal{U}_{b, a}^{(q, \lambda)}(x) - \dfrac{\mathcal{W}_{x}^{\,(q, \lambda)}(x)}{\mathcal{W}_{a}^{(q, \lambda)}(a)} \mathcal{U}_{b, a}^{(q, \lambda)}(a) , \end{align}
where the last equality follows by using (4.11). Now, to evaluate the double expectation in (4.14), first note from (A.6) in the Appendix that
 \begin{equation*}\lambda \int^a_b W^{(q+\lambda)}(a-y) \mathcal{U}_{b,a}^{(q,\lambda)}(y) \,{\mathrm{d}} y = \overline{W}^{(q,\lambda)}_{b}(a) - \mathcal{U}_{b,a}^{(q,\lambda)}(a), \end{equation*}
and second, using the above identity and (4.5), that
 \begin{equation}\mathbb{E}_b \Bigl({\mathrm{e}}^{-q T_{b,X}^{+}} \mathbf{1}_{\{T_{b,X}^{+} \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \mathcal{U}_{b,a}^{(q,\lambda)}\bigl(X_{T_{b,X}^{+}}\bigr) \Bigr) = \dfrac{\overline{W}^{(q,\lambda)}_{b}(b)}{\overline{W}^{(q,\lambda)}_{b}(a)} \bigl( \overline{W}^{(q,\lambda)}_{b}(a) - \mathcal{U}_{b,a}^{(q,\lambda)}(a) \bigl). \end{equation}
Hence the second expectation of (4.14), using (4.15)–(4.17), turns out to be
 \begin{align}\mathbb{E}^{}_b &\Bigl({\mathrm{e}}^{-q T_{b,X}^{+}} \mathbf{1}_{\{T_{b,X}^{+} \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \mathbb{E}^{}_{X_{T_{b,X}^{+}}} \Bigl({\mathrm{e}}^{-q T_{b,Y}^{-}} \mathbf{1}_{\{T_{b,Y}^{-} \lt \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} W^{(q)}\bigl(Y_{T_{b,Y}^{-}}\bigr) \Bigr) \Bigr) \nonumber \\[3pt] &= \mathbb{E}_b \Bigl({\mathrm{e}}^{-q T_{b,X}^{+}} \mathbf{1}_{\{T_{b,X}^{+} \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \mathcal{U}_{b,a}^{(q,\lambda)}\bigl(X_{T_{b,X}^{+}}\bigr) \Bigr) \nonumber \\[3pt] &\quad - \dfrac{\mathcal{U}_{b, a}^{(q, \lambda)}(a)}{\mathcal{W}_{a}^{(q, \lambda)}(a)} \mathbb{E}^{}_b \Bigl({\mathrm{e}}^{-q T_{b,X}^{+}} \mathbf{1}_{\{T_{b,X}^{+} \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \mathcal{W}^{\,(q,\lambda)}_{X_{T_{b,X}^{+}}} \bigl(X_{T_{b,X}^{+}}\bigr) \Bigr) \nonumber \\[3pt] &= \overline{W}_{b}^{(q,\lambda)}(b) - \dfrac{\overline{W}_{b}^{(q,\lambda)}(b)}{\overline{W}_{b}^{(q,\lambda)}(a)} \dfrac{\mathcal{W}_b^{(q,\lambda)}(a)}{\mathcal{W}_{a}^{(q,\lambda)}(a)} \mathcal{U}_{b,a}^{(q,\lambda)}(a).\end{align}
Then, by observing that
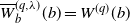 $\overline{W}^{(q,\lambda)}_b(b) = W^{(q)}(b)$
and substituting the above equation and (4.15) into (4.14), we derive the desired quantity
 \begin{equation*}p^{ X }(b) = \dfrac{ W^{(q)}(b)}{\mathcal{U}^{\,(q,\lambda)}_{b,a}(a)}. \end{equation*}
Finally, by substituting the above equation into (4.12), we derive the result for
 $x \in [0,b]$
. For
 $x \in (b,a]$
, we substitute
 $p^X(b)$
along with (4.16) into (4.13) to get the required result.
Theorem 4.2. For
 $q, \lambda \geq 0$
and
 $0 \leq x, b \leq a$
,
 \begin{equation}\mathbb{E}_x\Bigl({\mathrm{e}}^{-q \tau_{0,U}^{-}} \mathbf{1}_{\{\tau_{0,U}^{-}< \tau_{a,U}^{+} \}}\Bigr)= \mathcal{V}_{b, a}^{(q, \lambda)}(x) - \dfrac{\mathcal{U}_{b, a}^{(q, \lambda)}(x)}{\mathcal{U}_{b, a}^{(q, \lambda)}(a)} \mathcal{V}_{b, a}^{(q, \lambda)}(a) , \end{equation}
where
 $\mathcal{U}_{b, a}^{(q, \lambda)}(x)$
is defined in (4.11) and
 \begin{align}\mathcal{V}_{b, a}^{(q, \lambda)}(x) = Z^{(q)}(x) - \mathbf{1}_{\{x \gt b\}}\biggl(\mathcal{A}_{x}^{(q, \lambda)}(x) -\dfrac{\mathcal{W}_{x}^{\,(q, \lambda)}(x)}{\mathcal{W}_{b}^{(q, \lambda)}(a)} \mathcal{A}_{b}^{(q, \lambda)}(a) \biggr) . \end{align}
Proof. Using notation similar to that in the proof of (4.10), let
 \begin{align*} \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q \tau_{0,U}^- } \mathbf{1}_{\{\tau_{0,U}^- \lt \tau_{a,U}^+\}}\Bigr) \end{align*}
be denoted by
 $g^X(x)$
for
 $x \in [0,b]$
, and
 $g^Y(x)$
for
 $x \in (b,a]$
.
Now suppose that
 $x \in [0,b]$
. Then, conditioning on
 $\tau_{b,U}^+ $
, using the strong Markov property and (A.1)–(A.2) of the Appendix,
 \begin{align}g^{ X }(x)&= \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q \tau_{0,U}^- } \mathbf{1}_{\{\tau_{0,U}^- \lt \tau_{b,U}^+\}} \Bigr) + \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q \tau_{b,U}^+ } \mathbf{1}_{\{\tau_{b,U}^+ \lt \tau_{0,U}^-\}} \mathbb{E}^{}_{U_{\tau_{b,U}^+}} \Bigl({\mathrm{e}}^{-q \tau_{0,U}^- } \mathbf{1}_{\{\tau_{0,U}^- \lt \tau_{a,U}^+\}}\Bigr) \Bigr) \nonumber \\[3pt] &= \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q \tau_{0,X}^- } \mathbf{1}_{\{\tau_{0,X}^- \lt \tau_{b,X}^+\}} \Bigr) + \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q \tau_{b,X}^+ } \mathbf{1}_{\{\tau_{b,X}^+ \lt \tau_{0,X}^-\}} \Bigr) \mathbb{E}^{}_b \Bigl({\mathrm{e}}^{-q \tau_{0,U}^- } \mathbf{1}_{\{\tau_{0,U}^- \lt \tau_{a,U}^+\}}\Bigr) \nonumber \\[3pt] &= Z^{(q)}(x) + \dfrac{W^{(q)}(x)}{W^{(q)}(b)} \bigl(g^X(b) - Z^{(q)}(b) \bigr), \end{align}
where the second equality follows since
 $\{X_t, t \lt T_{b,X}^+\}$
and
 $\{U_t, t \lt T_{b,U}^+\}$
have the same distribution with respect to
 $\mathbb{P}_x$
when
 $x \in [0,b]$
, and by recalling that
 $\tau_{b,X}^+ \leq T_{b,X}^+$
and
 $\tau_{b,U}^+ \leq T_{b,U}^+$
.
Similarly, suppose the process starts at
 $x \in (b,a]$
. Then, by observing that
 $\{Y_t, t \lt T_{b,Y}^-\}$
and
 $\{U_t, t \lt T_{b,U}^-\}$
have the same distribution with respect to
 $\mathbb{P}_x$
for these x-values, we condition on
 $T_{b,U}^-$
and use the strong Markov property to obtain
 \begin{align}g^{ Y }(x) &= \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q \tau_{0,U}^-} \mathbf{1}_{\{\tau_{0,U}^- \lt T_{b,U}^{-} \wedge \tau_{a,U}^+ \}} \Bigr) + \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q \tau_{0,U}^-} \mathbf{1}_{\{T_{b,U}^{-} \lt \tau_{0,U}^- \lt \tau_{a,U}^+ \}} \Bigr) \nonumber \\[3pt] &= \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q \tau_{0,Y}^-} \mathbf{1}_{\{\tau_{0,Y}^- \lt T_{b,Y}^{-} \wedge \tau_{a,Y}^+ \}} \Bigr) + \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q T_{b,Y}^{-}} \mathbf{1}_{\{T_{b,Y}^{-} \lt \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} g^{ X }\bigl(Y_{T_{b,Y}^{-}}\bigr) \Bigr) \nonumber \\[3pt] &= \overline{\mathbb{Z}}^{(q+\lambda,-\lambda)}_b(x) - \dfrac{\mathcal{W}^{\,(q,\lambda)}_{x}(x)}{\mathcal{W}^{\,(q,\lambda)}_{a}(a)} \overline{\mathbb{Z}}^{(q+\lambda,-\lambda)}_b(a) + \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q T_{b,Y}^{-}} \mathbf{1}_{\{T_{b,Y}^{-} \lt \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} Z^{(q)}\bigl(Y_{T_{b,Y}^{-}}\bigr) \Bigr) \nonumber \\[3pt] & \quad + \dfrac{(g^{ X }(b) - Z^{(q)}(b))}{W^{(q)}(b)} \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q T_{b,Y}^{-}} \mathbf{1}_{\{T_{b,Y}^{-} \lt \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} W^{(q)}\bigl(Y_{T_{b,Y}^{-}}\bigr) \Bigr), \end{align}
where the last line follows by using Corollary 4.1(iii) and (4.21). Additionally, by using (4.6) and (4.9), we observe that
 \begin{align*}\mathbb{E}^{}_x &\Bigl({\mathrm{e}}^{-q T_{b,Y}^{-}} \mathbf{1}_{\{T_{b,Y}^{-} \lt \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} Z^{(q)}\bigl(Y_{T_{b,Y}^{-}}\bigr) \Bigr) \nonumber \\[3pt] &= \dfrac{\mathcal{W}_{x}^{\,(q,\lambda)}(x)}{\mathcal{W}_{a}^{(q,\lambda)}(a)} \bigl( \mathcal{A}^{(q,\lambda)}_a(a) - Z^{(q)}(a) + \overline{\mathbb{Z}}_b^{(q+\lambda,-\lambda)}(a) \bigr) - \bigl( \mathcal{A}^{(q,\lambda)}_x(x) - Z^{(q)}(x) + \overline{\mathbb{Z}}_b^{(q+\lambda,-\lambda)}(x) \bigr) \nonumber \\[3pt] &= \mathcal{V}_{b, a}^{(q, \lambda)}(x) - \overline{\mathbb{Z}}_b^{(q+\lambda,-\lambda)}(x) - \dfrac{\mathcal{W}_{x}^{\,(q,\lambda)}(x)}{\mathcal{W}_{a}^{(q,\lambda)}(a)} \bigl( \mathcal{V}_{b, a}^{(q, \lambda)}(a) - \overline{\mathbb{Z}}_b^{(q+\lambda,-\lambda)}(a) \bigr), \end{align*}
where the last equality holds by using (4.20), and hence substituting the above equation into (4.22) yields
 \begin{align}g^{ Y }(x) &= \mathcal{V}_{b, a}^{(q, \lambda)}(x) - \dfrac{\mathcal{W}_{x}^{\,(q,\lambda)}(x)}{\mathcal{W}_{a}^{(q,\lambda)}(a)}\mathcal{V}_{b, a}^{(q, \lambda)}(a)\nonumber \\[3pt] &\quad + \dfrac{\big(g^{ X }(b) - Z^{(q)}(b)\big)}{W^{(q)}(b)} \mathbb{E}^{}_x \Bigl({\mathrm{e}}^{-q T_{b,Y}^{-}} \mathbf{1}_{\{T_{b,Y}^{-} \lt \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} W^{(q)}\bigl(Y_{T_{b,Y}^{-}}\bigr) \Bigr), \end{align}
From (4.21) and (4.23), it suffices to derive
 $g^X(b)$
. To do this, we condition on
 $T_{b,U}^+$
, use Corollary 4.1(iii) and the strong Markov property, to get
 \begin{align*}g^{ X }(b) &= \mathbb{E}^{}_b \Bigl({\mathrm{e}}^{-q \tau_{0,U}^-} \mathbf{1}_{\{\tau_{0,U}^- \lt T_{b,U}^{+} \wedge \tau_{a,U}^+ \}} \Bigr) + \mathbb{E}^{}_b \Bigl({\mathrm{e}}^{-q \tau_{a,U}^+} \mathbf{1}_{\{T_{b,U}^{+} \lt \tau_{a,U}^+ \lt \tau_{0,U}^- \}} \Bigr)\nonumber \\[3pt] &= \overline{Z}_b^{(q,\lambda)}(b) - \dfrac{\overline{W}_b^{(q,\lambda)}(b)}{\overline{W}^{(q,\lambda)}_{b}(a)}\overline{Z}^{(q,\lambda)}_{b}(a) + \mathbb{E}^{}_b \Bigl({\mathrm{e}}^{-q T_{b,X}^{+}} \mathbf{1}_{\{T_{b,X}^{+} \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} g^{ Y }\bigl(X_{T_{b,X}^{+}}\bigr) \Bigr). \end{align*}
Substituting (4.23) into the expectation of the above equation, we get
 \begin{align}g^{ X }(b)&= \overline{Z}^{(q,\lambda)}_b(b) - \dfrac{\overline{W}_b^{(q,\lambda)}(b)}{\overline{W}^{(q,\lambda)}_{b}(a)}\overline{Z}^{(q,\lambda)}_{b}(a) + \mathbb{E}^{}_b \Bigl({\mathrm{e}}^{-q T_{b,X}^{+}} \mathbf{1}_{\{T_{b,X}^{+} \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \mathcal{V}^{\,(q,\lambda)}_{b,a}\bigl(X_{T_{b,X}^{+}}\bigr) \Bigr)\nonumber \\[3pt] & \quad - \dfrac{\mathcal{V}^{\,(q,\lambda)}_{b,a}(a) }{\mathcal{W}^{\,(q,\lambda)}_{a}(a)} \mathbb{E}^{ }_b \Bigl({\mathrm{e}}^{-q T_{b,X}^{+}} \mathbf{1}_{\{T_{b,X}^{+} \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \mathcal{W}^{\,(q,\lambda)}_{X_{T_{b,X}^{+}}}\bigl(X_{T_{b,X}^{+}}\bigr) \Bigr) \nonumber \\[4pt] &\quad + \dfrac{\big(g^{ X }(b) - Z^{(q)}(b)\big)}{W^{(q)}(b)}\nonumber \\[4pt] &\quad \times \mathbb{E}^{ }_b \Bigl({\mathrm{e}}^{-q T_{b,X}^{+}} \mathbf{1}_{\{T_{b,X}^{+} \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \mathbb{E}^{}_{X_{T_{b,X}^{+}}} \Bigl({\mathrm{e}}^{-q T_{b,Y}^{-}} \mathbf{1}_{\{T_{b,Y}^{-} \lt \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} W^{(q)}\bigl(Y_{T_{b,Y}^{-}}\bigr) \Bigr) \Bigr). \end{align}
We now need to compute only the first expectation of the above equation, since the second and third expectations are known from (4.15) and (4.18), respectively. Thus, by noticing from (A.5) of the Appendix that
 \begin{equation*}\lambda \int^a_b W^{(q+\lambda)}(a-y) \mathcal{V}_{b,a}^{(q,\lambda)}(y) \,{\mathrm{d}} y = \overline{Z}^{(q,\lambda)}_{b}(a) - \mathcal{V}_{b,a}^{(q,\lambda)}(a), \end{equation*}
we have by using (4.5) along with the above equation that
 \begin{equation*}\mathbb{E}^{}_b \Bigl({\mathrm{e}}^{-q T_{b,X}^{+}} \mathbf{1}_{\{T_{b,X}^{+} \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \mathcal{V}^{\,(q,\lambda)}_{b,a}\bigl(X_{T_{b,X}^{+}}\bigr) \Bigr) = \dfrac{\overline{W}^{(q,\lambda)}_{b}(b)}{\overline{W}^{(q,\lambda)}_{b}(a)} \bigl( \overline{Z}^{(q,\lambda)}_{b}(a) - \mathcal{V}_{b,a}^{(q,\lambda)}(a) \bigl). \end{equation*}
Then, by observing that
 \begin{align*}\overline{Z}^{(q,\lambda)}_b(b) = Z^{(q)}(b)\quad\text{and}\quad \overline{W}^{(q,\lambda)}_b(b) = W^{(q)}(b), \end{align*}
we substitute (4.15), (4.18), and the above equation into (4.24) to derive the desired quantity
 \begin{equation*}g^{ X }(b) = Z^{(q)}(b) - \dfrac{ W^{(q)}(b)}{\mathcal{U}^{\,(q,\lambda)}_{b,a}(a)} \mathcal{V}^{\,(q,\lambda)}_{b,a}(a). \end{equation*}
Finally, by substituting the above equation into (4.21), we derive the result for
 $x \in [0,b]$
. For
 $x \in (b,a]$
, we substitute
 $g^X(b)$
along with (4.16) into (4.23) to get the required result.
Remark 4.1. Let us assume that
 $X = Y$
. Then, for the identities given in Proposition 2.1 of [Reference Wang, Lkabous and Landriault20], their refraction parameter satisfies
 $\delta = 0$
,
 $\mathbb{W}^{(q)} = W^{(q)}$
and
 $\mathbb{Z}^{(q)} = Z^{(q)}$
, which consequently yields
 \begin{align*}\lambda \int^{b}_0 \overline{W}^{(q,\lambda)}_{x-b}(x-y)W^{(q)}(y) \,{\mathrm{d}} y &= \overline{W}^{(q,\lambda)}_{x-b}(x) - W^{(q)}(x), \\[3pt]\lambda \int^{b}_0 \overline{W}^{(q,\lambda)}_{x-b}(x-y)Z^{(q)}(y) \,{\mathrm{d}} y &= \overline{Z}^{(q+\lambda,-\lambda)}_{b}(x) - Z^{(q)}(x).\end{align*}
By the above two identities,
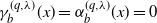 $\gamma_b^{(q,\lambda)}(x) = \alpha_b^{(q,\lambda)}(x) = 0$
and therefore
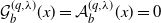 $\mathcal{G}_b^{(q,\lambda)}(x) = \mathcal{A}_b^{(q,\lambda)}(x) = 0$
. Hence we conclude that the case for
 $Y = X$
gives
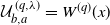 $\mathcal{U}^{\,(q,\lambda)}_{b,a} = W^{(q)}(x)$
and
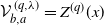 $\mathcal{V}^{\,(q,\lambda)}_{b,a} = Z^{(q)}(x)$
, which reduces (4.10) and (4.19) to those in Theorem A.1 of the Appendix, the classical one-sided Lévy fluctuation identities.
4.2. One-sided exit upwards and downwards
To derive the one-sided exit identities, we require the following lemma to determine the limits of the scale functions derived in Section 4.1.
Lemma 4.2. Let
 $q,\lambda \gt 0$
,
 $a \in \mathbb{R}_+$
, and
 $x,b \in [0,a]$
. Then, for at least
 $\Phi_{q} \gt \varphi_{q+\lambda}$
, the following limits are true:
-
(i)
$\lim_{a \rightarrow \infty} \mathbb{W}^{(q)}(a)/W^{(q)}(a) = 0$
, -
(ii)
$\lim_{a \rightarrow \infty} \overline{\mathbb{W}}_{a-b}^{(q,\lambda)}(a)/W^{(q+\lambda)}(a) = 0$
, -
(iii)
$\lim_{\theta \rightarrow \infty} \overline{\mathbb{W}}_{x-b}^{(q,\lambda)}(x+\theta)/W^{(q)}(\theta) = 0$
.
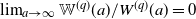
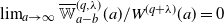
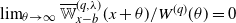
Proof. (i) Recall from [Reference Kyprianou9, Chapter 8] that there exists a representation of the scale function for
 $q, x \geq 0$
such that
 \begin{align*}W^{(q)}(x)={\mathrm{e}}^{\Phi_q x} W_{\Phi_q}(x), \end{align*}
where
 $W_{\Phi_q}(x)$
is the 0-scale function of the SNLP with Laplace exponent
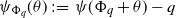 $\psi_{\Phi_q}(\theta)\, :\!= \, \psi(\Phi_q+\theta)-q$
. Furthermore, it is known (see e.g. [Reference Kuznetsov, Kyprianou and Rivero7]) that
 \begin{align*}W_{\Phi_q}(\infty)\, :\!= \, \lim _{x \rightarrow \infty} W_{\Phi_q}(x)=\dfrac{1}{\psi_{\Phi_q}^{\prime}(0+)}=\dfrac{1}{\psi^{\prime}(\Phi_q)}, \end{align*}
which implies that
 $W_{\Phi_q}(\infty) \lt \infty$
unless simultaneously
 $q=0$
and
 $\psi^{\prime}(0+)=0$
. The same holds for the 0-scale function
 $\mathbb{W}_{\varphi_q}(x)$
having Laplace exponent
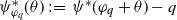 $\psi^*_{\varphi_q}(\theta)\, :\!= \, \psi^*(\varphi_q+\theta)-q$
. Therefore, by noticing that
 $\Phi_q \gt \varphi_{q+\lambda}$
implies also that
 $\Phi_q \gt \varphi_q$
, we have
 \begin{equation*}\lim_{a \rightarrow \infty} \dfrac{\mathbb{W}^{(q)}(a)}{W^{(q)}(a)} = \lim_{a \rightarrow \infty} {\mathrm{e}}^{-(\Phi_q - \varphi_q)a} \dfrac{\mathbb{W}_{\varphi_q}(a)}{W_{\Phi_q}(a)} = 0.\end{equation*}
(ii) From (2.3) we have
 \begin{equation*}\overline{\mathbb{W}}^{(q,\lambda)}_{a-b}(a) = \mathbb{W}^{(q)}(a) + \lambda \int^b_0 \mathbb{W}^{(q)}(a-y)\mathbb{W}^{(q+\lambda)}(y) \,{\mathrm{d}} y.\end{equation*}
Then, by observing that our assumption implies
 $\Phi_{q+\lambda} \gt \varphi_q$
and using reasoning similar to that for (i), we get that
 \begin{equation*}\lim_{a \rightarrow \infty} \dfrac{\mathbb{W}^{(q)}(a)}{W^{(q+\lambda)}(a)} = \lim_{a \rightarrow \infty} {\mathrm{e}}^{-(\Phi_{q+\lambda} - \varphi_q)a} \dfrac{\mathbb{W}_{\varphi_q}(a)}{W_{\Phi_{q+\lambda}}(a)} = 0.\end{equation*}
Therefore, since
 $W_{\Phi_{q+\lambda}}$
and
 $W_{\varphi_{q}}$
are continuous and bounded, and since
 ${\mathrm{e}}^{-(\Phi_{q+\lambda} - \varphi_q)a}$
decreases as
 $a \rightarrow \infty$
, there exists some
 $C \in \mathbb{R}_+$
such that
 \begin{align*}\dfrac{\mathbb{W}^{(q)}(a)}{W^{(q+\lambda)}(a)} \leq C\quad\text{for all $a \gt 0$.} \end{align*}
The required limit is thus derived by applying the dominated convergence theorem.
(iii) The proof follows the same idea as that of (ii) by first noticing that the assumption
 $\Phi_q \gt \varphi_{q+\lambda}$
implies that
 \begin{equation*}\lim_{\theta \rightarrow \infty} \dfrac{\mathbb{W}^{(q+\lambda)}(x+\theta)}{W^{(q)}(\theta)} = \lim_{\theta \rightarrow \infty} {\mathrm{e}}^{-(\Phi_{q} - \varphi_{q+\lambda})\theta} \dfrac{{\mathrm{e}}^{\varphi_{q+\lambda}x}\mathbb{W}_{\varphi_{q+\lambda}}(x+\theta)}{W_{\Phi_{q}}(\theta)} = 0,\end{equation*}
and then by using the dominated convergence theorem.
We now derive the one-sided exit identities.
Proposition 4.1. Let
 $0 \lt q,\lambda \lt \infty$
. Then, for
 $0 \leq x,b \leq a$
and at least
 $\Phi_{q} \gt \varphi_{q+\lambda}$
, we have
 \begin{equation*}\mathbb{E}_x\Bigl({\mathrm{e}}^{-q \tau_{a,U}^+} \mathbf{1}_{\{ \tau_{a,U}^+ \lt \infty\}} \Bigr) = \dfrac{{\mathcal{U}}_{b,a}^{(q,\lambda)\downarrow}(x)}{{\mathcal{U}}_{b,a}^{(q,\lambda)\downarrow}(a)}, \end{equation*}
where
 \begin{align}&\!\!\mathcal{U}_{b,a}^{(q,\lambda)\downarrow}(x) = {\mathrm{e}}^{\Phi_q x}- \mathbf{1}_{\{x \gt b\}} \biggl( \gamma_{b}^{(q,\lambda)\downarrow}(x) \nonumber \\[3pt] &\!\!\quad- {\mathbb{Z}}^{(q)}(x-b;\,\varphi_{q+\lambda}) \dfrac{\gamma_{b}^{(q,\lambda)\downarrow}(a) + \lambda\int^{a}_b W^{(q+\lambda)}(a-u) \gamma_{b}^{(q,\lambda)\downarrow}(u) \,{\mathrm{d}} u }{\mathbb{Z}^{(q)}(a-b;\,\varphi_{q+\lambda})+ \lambda \int^{a}_b W^{(q+\lambda)}(a-u) {\mathbb{Z}}^{(q)}(u-b;\,\varphi_{q+\lambda}) \,{\mathrm{d}} u} \biggr),\end{align}
and
 \begin{equation*}\gamma_{b}^{(q,\lambda)\downarrow}(x) = {\mathrm{e}}^{\Phi_q x} + \lambda \int_0^{\infty} {\mathrm{e}}^{\Phi_q (b-y)}\overline{\mathbb{W}}_{x-b}^{(q,\lambda)}(x-b+y)\,{\mathrm{d}} y. \end{equation*}
Proof. Using a level invariance argument and Theorem 4.1,
 \begin{equation*}\mathbb{E}_x\Bigl({\mathrm{e}}^{-q \tau_{a,U}^+} \mathbf{1}_{\{ \tau_{a,U}^+ \lt \infty\}} \Bigr) = \lim_{\theta \rightarrow \infty} \dfrac{\mathcal{U}^{\,(q,\lambda)}_{b+\theta,a+\theta}(x+\theta)}{\mathcal{U}^{\,(q,\lambda)}_{b+\theta,a+\theta}(a+\theta)}, \end{equation*}
and so we derive the above limit. Hence we notice that
 \begin{align*}&\lim_{\theta \rightarrow \infty}\dfrac{\mathcal{U}^{\,(q,\lambda)}_{b+\theta,a+\theta}(x+\theta)}{W^{(q)}(\theta)} \\[3pt] &\quad = \lim_{\theta \rightarrow \infty} \Biggl\{ \dfrac{W^{(q)}(x+\theta)}{W^{(q)}(\theta)} -\mathbf{1}_{\{x>b\}} \Biggl( \dfrac{\gamma^{(q,\lambda)}_{b+\theta}(x+\theta)}{W^{(q)}(\theta)} - \dfrac{\overline{\mathbb{W}}^{(q,\lambda)}_{x-b}(x+\theta)}{\mathcal{W}^{\,(q,\lambda)}_{b+\theta}(a+\theta)} \dfrac{\mathcal{G}^{(q,\lambda)}_{b+\theta}(a+\theta)}{W^{(q)}(\theta)} \Biggr) \Biggr\},\end{align*}
where
 \begin{align*}\mathcal{W}^{\,(q,\lambda)}_{b+\theta}(a+\theta) &= \overline{\mathbb{W}}^{(q,\lambda)}_{a-b}(a+\theta) + \lambda \int^a_b W^{(q+\lambda)}(a-y) \overline{\mathbb{W}}^{(q,\lambda)}_{y-b}(y+\theta) \,{\mathrm{d}} y, \nonumber \\[3pt]\gamma^{(q,\lambda)}_{b+\theta}(x+\theta) &= W^{(q)}(x+\theta) - \overline{\mathbb{W}}_{x-b}^{(q,\lambda)}(x+\theta) + \lambda \int^{b+\theta}_{0} W^{(q)}(b+\theta-u) \overline{\mathbb{W}}^{(q,\lambda)}_{x-b}(x-b+u) \,{\mathrm{d}} u, \nonumber \\[3pt]\mathcal{G}^{(q,\lambda)}_{b+\theta}(a+\theta) &= \gamma^{(q,\lambda)}_{b+\theta}(a+\theta) + \lambda \int^a_b W^{(q+\lambda)}(a-u) \gamma^{(q,\lambda)}_{b+\theta}(u+\theta) \,{\mathrm{d}} u, \end{align*}
and the limit of each term needs to be determined.
By using (2.1)–(2.3) along with the dominated convergence theorem,
 \begin{equation}\lim_{\theta \rightarrow \infty} \dfrac{\overline{\mathbb{W}}^{(q,\lambda)}_{y-b}(y+\theta)}{\mathbb{W}^{(q+\lambda)}(\theta)} = {\mathrm{e}}^{\varphi_{q+\lambda}b}\mathbb{Z}^{(q)}(y-b,\varphi_{q+\lambda}), \quad y \geq b, \end{equation}
and hence
 \begin{equation}\lim_{\theta \rightarrow \infty} \dfrac{\mathcal{W}^{\,(q,\lambda)}_{b+\theta}(a+\theta)}{\mathbb{W}^{(q+\lambda)}(\theta)} = {\mathrm{e}}^{\varphi_{q+\lambda}b} \biggl(\mathbb{Z}^{(q)}(a-b,\varphi_{q+\lambda}) + \lambda \int^a_b W^{(q+\lambda)}(a-y) \mathbb{Z}^{(q)}(y-b,\varphi_{q+\lambda}) \,{\mathrm{d}} y\biggr). \end{equation}
Then, for
 $\Phi_{q}>\varphi_{q+\lambda}$
, we have by (2.2), Lemma 4.2(iii) and the dominated convergence theorem that
 \begin{equation*}\lim_{\theta \rightarrow \infty} \dfrac{\gamma^{(q,\lambda)}_{b+\theta}(x+\theta)}{W^{(q)}(\theta)} = {\mathrm{e}}^{\Phi_q x} + \lambda \int_0^{\infty} {\mathrm{e}}^{\Phi_q (b-y)}\overline{\mathbb{W}}_{x-b}^{(q,\lambda)}(x-b+y)\,{\mathrm{d}} y = \gamma_{b}^{(q,\lambda)\downarrow}(x) \end{equation*}
exists, and hence that
 \begin{equation*}\lim_{\theta \rightarrow \infty} \dfrac{\mathcal{G}^{(q,\lambda)}_{b+\theta}(a+\theta) }{W^{(q)}(\theta)} = \gamma^{(q,\lambda)\downarrow}_{b}(a) + \lambda \int^a_b W^{(q+\lambda)}(a-u) \gamma^{(q,\lambda)\downarrow}_{b}(u) \,{\mathrm{d}} u. \end{equation*}
Since
 \begin{align*} \lim_{\theta \rightarrow \infty} \overline{\mathbb{W}}^{(q,\lambda)}_{x-b}(x+\theta) / \mathcal{W}^{\,(q,\lambda)}_{b+\theta}(a+\theta) \end{align*}
is known already by using (4.26)–(4.27), we use the above two limits along with (2.2) to conclude that
 \begin{equation}\mathcal{U}^{\,(q,\lambda)\downarrow}_{b,a}(x) = \lim_{\theta \rightarrow \infty} \dfrac{\mathcal{U}^{\,(q,\lambda)}_{b+\theta,a+\theta}(x+\theta)}{W^{(q)}(\theta)} \end{equation}
has the same form as (4.25).
Proposition 4.2. Let
 $0 \lt q,\lambda \lt \infty$
. Then, for
 $0 \leq x,y,b \leq a$
and at least
 $\Phi_{q+\lambda} \gt \varphi_q$
, we have
 \begin{equation*}\mathbb{E}_x\Bigl({\mathrm{e}}^{-q \tau_{0,U}^-} \mathbf{1}_{\{\tau_{0,U}^- \lt \infty \}} \Bigr) = \mathcal{V}^{\,(q,\lambda)\uparrow}_{b}(x) - \dfrac{\mathcal{V}^{\,(q,\lambda)\uparrow}_{b}}{\mathcal{U}^{\,(q,\lambda)\uparrow}_{b}(0)}\; \mathcal{U}^{\,(q,\lambda)\uparrow}_{b}(x;\,0), \end{equation*}
where
 \begin{align}\mathcal{U}_{b}^{(q,\lambda)\uparrow}(x;\,y) &= W^{(q)}(x-y)- \mathbf{1}_{\{x \gt b\}} \Biggl( \gamma_{b}^{(q,\lambda)}(x;\,y) - \overline{\mathbb{W}}_{x-b}^{(q,\lambda)}(x) \dfrac{\int^{\infty}_b {\mathrm{e}}^{-\Phi_{q+\lambda}u} \gamma_{b}^{(q,\lambda)}(u;\,y) \,{\mathrm{d}} u }{\int^{\infty}_b {\mathrm{e}}^{-\Phi_{q+\lambda}u} \overline{\mathbb{W}}_{u-b}^{(q,\lambda)}(u) \,{\mathrm{d}} u} \Biggr), \\[-10pt] \nonumber \end{align}
 \begin{align}\mathcal{V}^{\,(q,\lambda)\uparrow}_{b}(x)&= Z^{(q)}(x) - \mathbf{1}_{\{x>b\}} \Biggl(\alpha_b^{(q,\lambda)}(x) - \overline{\mathbb{W}}_{x-b}^{(q,\lambda)}(x) \dfrac{\int^\infty_b {\mathrm{e}}^{-\Phi_{q+\lambda}u} \alpha_b^{(q,\lambda)}(u) \,{\mathrm{d}} u}{\int^\infty_b {\mathrm{e}}^{-\Phi_{q+\lambda}u} \overline{\mathbb{W}}_{u-b}^{(q,\lambda)}(u) \,{\mathrm{d}} u} \Biggr) , \\[-10pt] \nonumber \end{align}
 \begin{align}\mathcal{U}_{b}^{(q,\lambda)\uparrow}(y) &= \mathbb{Z}^{(q+\lambda)}(b-y,\varphi_q) - \lambda \int^{b-y}_0 \mathbb{Z}^{(q+\lambda)}(b-y-u,\varphi_q)W^{(q)}(u) \,{\mathrm{d}} u \nonumber \\[3pt] &\quad + \mathbb{Z}^{(q+\lambda)}(b,\varphi_q) \dfrac{\int^{\infty}_b {\mathrm{e}}^{-\Phi_{q+\lambda}u} \gamma_{b}^{(q,\lambda)}(u;\,y) \,{\mathrm{d}} u }{\int^{\infty}_b {\mathrm{e}}^{-\Phi_{q+\lambda}u} \overline{\mathbb{W}}_{u-b}^{(q,\lambda)}(u) \,{\mathrm{d}} u}, \\[6pt] \nonumber \end{align}
and
 \begin{align}\mathcal{V}^{\,(q,\lambda)\uparrow}_{b}&= {\mathrm{e}}^{\varphi_q b} \biggl(\dfrac{q}{\varphi_q} + \lambda \int^b_0 {\mathrm{e}}^{-\varphi_q y}\mathbb{Z}^{(q+\lambda)}(y) \,{\mathrm{d}} y \biggr) - \lambda \int^{b}_0 \mathbb{Z}^{(q+\lambda)}(b-u,\varphi_q)Z^{(q)}(u) \,{\mathrm{d}} u \nonumber \\[3pt] &\quad + \mathbb{Z}^{(q+\lambda)}(b,\varphi_q) \dfrac{\int^\infty_b {\mathrm{e}}^{-\Phi_{q+\lambda}u} \alpha_b^{(q,\lambda)}(u) \,{\mathrm{d}} u}{\int^\infty_b {\mathrm{e}}^{-\Phi_{q+\lambda}u} \overline{\mathbb{W}}_{u-b}^{(q,\lambda)}(u) \,{\mathrm{d}} u}. \end{align}
Remark 4.2. The bivariate limits are proved here since they are the same as that needed for the one-sided potential measure in Theorem 4.3.
Proof of Proposition
4.2. We derive the desired identity by taking the limit of the two-sided exit downwards from Theorem 4.2 as
 $a \rightarrow \infty$
. Additionally, in some of the limits below, the dominated convergence theorem is applied since its usage is justified by noticing from (2.2) that
 $W^{(q+\lambda)}(a-y)/W^{(q+\lambda)}(a) \rightarrow {\mathrm{e}}^{-\Phi_{q+\lambda} y}$
as
 $a \rightarrow \infty$
.
Now, for
 $\Phi_{q+\lambda}>\varphi_q$
, we have by Lemma 4.2(ii) and the dominated convergence theorem that
 \begin{align*}\lim_{a \rightarrow \infty} \gamma_{b}^{(q,\lambda)}(a;\,y)/W^{(q+\lambda)}(a) = \lim_{a \rightarrow \infty} \alpha_{b}^{(q,\lambda)}(a)/W^{(q+\lambda)}(a) = 0, \end{align*}
and hence by using (2.2) that
 \begin{align*}\lim_{a \rightarrow \infty} \dfrac{\mathcal{G}_{b}^{(q,\lambda)}(a;\,y)}{W^{(q+\lambda)}(a)} &= \lambda \int^\infty_b {\mathrm{e}}^{-\Phi_{q+\lambda} u} \gamma_{b}^{(q,\lambda)}(u;\,y) \,{\mathrm{d}} u, \nonumber \\[3pt]\lim_{a \rightarrow \infty} \dfrac{\mathcal{A}_{b}^{(q,\lambda)}(a)}{W^{(q+\lambda)}(a)} &= \lambda \int^\infty_b {\mathrm{e}}^{-\Phi_{q+\lambda} u} \alpha_{b}^{(q,\lambda)}(u) \,{\mathrm{d}} u, \nonumber \\[3pt]\lim_{a \rightarrow \infty} \dfrac{\mathcal{W}_{b}^{(q,\lambda)}(a;\,y)}{W^{(q+\lambda)}(a)} &= \lambda \int^\infty_b {\mathrm{e}}^{-\Phi_{q+\lambda} u} \overline{\mathbb{W}}_{u-b}^{(q,\lambda)}(u-y) \,{\mathrm{d}} u. \end{align*}
Thus, by using the above identities, we conclude that
 \begin{equation}\mathcal{U}_{b}^{(q,\lambda)\uparrow}(x;\,y) \, :\!= \, \lim_{a \rightarrow \infty}\mathcal{U}^{\,(q,\lambda)}_{b,a}(x;\,y) \quad \text{and} \quad \mathcal{V}_{b}^{(q,\lambda)\uparrow}(x) \, :\!= \, \lim_{a \rightarrow \infty}\mathcal{V}^{\,(q,\lambda)}_{b,a}(x) \end{equation}
have the forms of (4.29) and (4.30), respectively.
Now we notice that
 \begin{align*}\lim_{a \rightarrow \infty}\mathcal{U}^{\,(q,\lambda)}_{b,a}(a;\,y)/\mathbb{W}^{(q)}(a) &= \lim_{a \rightarrow \infty}\mathcal{U}^{\,(q,\lambda)\uparrow}_{b}(a;\,y)/\mathbb{W}^{(q)}(a), \nonumber \\[3pt]\lim_{a \rightarrow \infty}\mathcal{V}^{\,(q,\lambda)}_{b,a}(a)/\mathbb{W}^{(q)}(a) &= \lim_{a \rightarrow \infty}\mathcal{V}^{\,(q,\lambda)\uparrow}_{b}(a)/\mathbb{W}^{(q)}(a). \end{align*}
We derive these limits by using (2.1) and (2.2) along with the dominated convergence theorem to observe that
 \begin{align}\dfrac{\overline{\mathbb{W}}^{(q,\lambda)}_{a-b}(a-y)}{{\mathbb{W}}^{(q)}(a)} = \dfrac{\overline{\mathbb{W}}^{(q+\lambda,-\lambda)}_{b-y}(a-y)}{{\mathbb{W}}^{(q)}(a)} \rightarrow {\mathrm{e}}^{-\varphi_q b} \mathbb{Z}^{(q+\lambda)}(b-y,\varphi_q) \quad \text{as $ a \rightarrow \infty$,}\\[-4pt] \nonumber \end{align}
 \begin{align}\dfrac{\overline{\mathbb{Z}}^{(q+\lambda,-\lambda)}_{b}(a)}{{\mathbb{W}}^{(q)}(a)} \rightarrow \dfrac{q}{\varphi_q}+\lambda \int^b_0 {\mathrm{e}}^{-\varphi_q y}\mathbb{Z}^{(q+\lambda)}(y) \,{\mathrm{d}} y \quad \text{as $ a \rightarrow \infty$.} \\[12pt] \nonumber \end{align}
Thus, using the two above equations, that
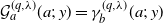 $\mathcal{G}^{(q,\lambda)}_{a}(a;\,y) = \gamma^{(q,\lambda)}_{b}(a;\,y)$
,
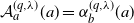 $\mathcal{A}^{(q,\lambda)}_{a}(a) = \alpha^{(q,\lambda)}_{b}(a)$
and the dominated convergence theorem,
 \begin{align}&\lim_{a \rightarrow \infty} \dfrac{1}{{\mathbb{W}}^{(q)}(a)}\bigl( W^{(q)}(a-y) -\mathcal{G}^{(q,\lambda)}_{a}(a;\,y)\bigr)\nonumber \\[3pt] &\quad = {\mathrm{e}}^{-\varphi_q b} \biggl( \mathbb{Z}^{(q+\lambda)}(b-y,\varphi_q) - \lambda \int^{b-y}_0 \mathbb{Z}^{(q+\lambda)}(b-y-u,\varphi_q)W^{(q)}(u) \,{\mathrm{d}} u \biggr), \end{align}
and
 \begin{align*}&\lim_{a \rightarrow \infty} \dfrac{1}{{\mathbb{W}}^{(q)}(a)}\bigl( Z^{(q)}(a) -\mathcal{A}^{(q,\lambda)}_{a}(a)\bigr)\\[3pt] &\quad = \dfrac{q}{\varphi_q}+\lambda \int^b_0 {\mathrm{e}}^{-\varphi_q y}\mathbb{Z}^{(q+\lambda)}(y) \,{\mathrm{d}} y - \lambda {\mathrm{e}}^{-\varphi_q b} \int^{b}_0 \mathbb{Z}^{(q+\lambda)}(b-u,\varphi_q)Z^{(q)}(u) \,{\mathrm{d}} u. \end{align*}
Using (4.34) and the above two limits, we conclude that
 \begin{equation}\mathcal{U}_{b}^{(q,\lambda)\uparrow}(y) = \lim_{a \rightarrow \infty} {\mathrm{e}}^{\varphi_q b} \cdot \; \mathcal{U}^{\,(q,\lambda)}_{b,a}(a;\,y) / \mathbb{W}^{(q)}(a) \quad \text{and} \quad \mathcal{V}_{b}^{(q,\lambda)\uparrow} = \lim_{a \rightarrow \infty} {\mathrm{e}}^{\varphi_q b} \cdot \; \mathcal{V}^{\,(q,\lambda)}_{b,a}(a) / \mathbb{W}^{(q)}(a) \end{equation}
Remark 4.3. If the assumptions on the right-inverses
 $\Phi$
and
 $\varphi$
of the corresponding Lévy exponents are relaxed, the limits yield indeterminate forms. These assumptions are hence imposed to ensure that appropriate limiting forms can be derived.
4.3. Potential measures
In this subsection we shall derive identities for the potential measure of U. We first have the following for the potential measure killed on exiting [0, a].
Theorem 4.3. Let
 $0 \lt b\leq a$
and
 $0 \lt \lambda \lt \infty$
. Then, for a Borel set
 $B \subseteq \mathbb{R}$
,
 $q \geq 0$
, we have the following.
-
(i) For
$0 \leq x,y \leq a$
, where
\begin{align*}&\mathbb{E}_x\biggl( \int^\infty_0 {\mathrm{e}}^{-q t} \mathbf{1}_{\{U_t \in B, \; t \lt \tau_{a,U}^+ \wedge \tau_{0,U}^-\}} \,{\mathrm{d}} t \biggr) \\[3pt] &\quad = \int_{B\cap[0,a] } \Biggl( \dfrac{\mathcal{U}^{\,(q,\lambda)}_{b,a}(a;\,y)}{\mathcal{U}^{\,(q,\lambda)}_{b,a}(a;\,0)}\mathcal{U}^{\,(q,\lambda)}_{b,a}(x;\,0) - \mathcal{U}^{\,(q,\lambda)}_{b,a}(x;\,y) \Biggr) \,{\mathrm{d}} y, \end{align*}
$\mathcal{U}^{\,(q,\lambda)}_{b,a}(x;\,y)$
is given in (4.11).
-
(ii) For
$0 \leq x,b \leq a$
,
$y\geq 0$
and at least
$\Phi_{q+\lambda} \gt \varphi_q$
, where
\begin{align*}&\mathbb{E}_x\biggl( \int^\infty_0 {\mathrm{e}}^{-q t} \mathbf{1}_{\{U_t \in B, \; t \lt \tau_{0,U}^-\}} \,{\mathrm{d}} t \biggr)\\[3pt] &\quad = \int_{B\cap[0,\infty) } \Biggl( \dfrac{{\mathcal{U}}_{b}^{(q,\lambda)\uparrow}(y)}{\mathcal{U}_{b}^{(q,\lambda)\uparrow}(0)} \mathcal{U}_{b}^{(q,\lambda)\uparrow}(x;\,0) - \mathcal{U}_{b}^{(q,\lambda)\uparrow}(x;\,y) \Biggr) \,{\mathrm{d}} y,\end{align*}
$\mathcal{U}_{b}^{(q,\lambda)\uparrow}(x;\,y)$
and
$\mathcal{U}_{b}^{(q,\lambda)\uparrow}(y)$
are given by (4.29) and (4.31), respectively.
-
(iii) For
$0 \leq x,b \leq a$
,
$y\leq a$
and at least
$\Phi_{q} \gt \varphi_{q+\lambda}$
, where
\begin{align*}&\mathbb{E}_x\biggl( \int^\infty_0 {\mathrm{e}}^{-q t} \mathbf{1}_{\{U_t \in B, \; t \lt \tau_{a,U}^+\}} \,{\mathrm{d}} t \biggr) \\[3pt] &\quad = \int_{B\cap(-\infty,a] } \Biggl( \dfrac{{\mathcal{U}}_{b,a}^{(q,\lambda)\downarrow}(x)}{{\mathcal{U}}_{b,a}^{(q,\lambda)\downarrow}(a)} {\mathcal{U}}_{b,a}^{(q,\lambda)\downarrow}(a;\,y) - {\mathcal{U}}_{b,a}^{(q,\lambda)\downarrow}(x;\,y) \Biggr) \,{\mathrm{d}} y,\end{align*}
(4.38)and for which
\begin{align}&\mathcal{U}_{b,a}^{(q,\lambda)\downarrow}(x;\,y) = W^{(q)}(x-y)- \mathbf{1}_{\{x \gt b\}} \Biggl( \gamma_{b}^{(q,\lambda)}(x;\,y) \nonumber \\[3pt] &\quad - {\mathbb{Z}}^{(q)}(x-b;\,\varphi_{q+\lambda}) \dfrac{\gamma_{b}^{(q,\lambda)}(a;\,y) + \lambda\int^{a}_b W^{(q+\lambda)}(a-u) \gamma_{b}^{(q,\lambda)}(u;\,y) \,{\mathrm{d}} u }{\mathbb{Z}^{(q)}(a-b;\,\varphi_{q+\lambda})+ \lambda \int^{a}_b W^{(q+\lambda)}(a-u) {\mathbb{Z}}^{(q)}(u-b;\,\varphi_{q+\lambda}) \,{\mathrm{d}} u} \Biggr),\end{align}
$\mathcal{U}_{b,a}^{(q,\lambda)\downarrow}(x)$
is given in (4.25).
-
(iv) For
$0 \leq x,b \leq a$
and at least
$\Phi_{q} \gt \varphi_{q+\lambda}$
, where
\begin{equation*}\mathbb{E}_x\biggl( \int^\infty_0 {\mathrm{e}}^{-q t} \mathbf{1}_{\{U_t \in B\}} \,{\mathrm{d}} t \biggr) = \int_B \Biggl( \dfrac{\widetilde{{\mathcal{U}}}_{b}^{(q,\lambda)}(y)}{\widetilde{{\mathcal{U}}}_{b}^{(q,\lambda)}}\overline{{\mathcal{U}}}_{b}^{(q,\lambda)}(x) - \overline{{\mathcal{U}}}_{b}^{(q,\lambda)}(x;\,y) \Biggr) \,{\mathrm{d}} y, \end{equation*}
(4.39)
\begin{align}\overline{\mathcal{U}}_{b}^{(q,\lambda)}(x;\,y) & = W^{(q)}(x-y)- \mathbf{1}_{\{x \gt b\}} \Biggl( \gamma_{b}^{(q,\lambda)}(x;\,y) \nonumber \\[3pt] &\quad- {\mathbb{Z}}^{(q)}(x-b;\,\varphi_{q+\lambda}) \dfrac{\int^{\infty}_b {\mathrm{e}}^{-\Phi_{q+\lambda} u} \gamma_{b}^{(q,\lambda)}(u;\,y) \,{\mathrm{d}} u }{\int^{\infty}_b {\mathrm{e}}^{-\Phi_{q+\lambda} u} {\mathbb{Z}}^{(q)}(u-b;\,\varphi_{q+\lambda}) \,{\mathrm{d}} u} \Biggr), \\[-7pt] \nonumber \end{align}
(4.40)
\begin{align}\overline{\mathcal{U}}_{b}^{(q,\lambda)}(x)& = {\mathrm{e}}^{\Phi_q x}- \mathbf{1}_{\{x \gt b\}} \Biggl( \gamma_{b}^{(q,\lambda)\downarrow}(x) \nonumber \\[3pt]&\quad- {\mathbb{Z}}^{(q)}(x-b;\,\varphi_{q+\lambda}) \dfrac{\int^{\infty}_b {\mathrm{e}}^{-\Phi_{q+\lambda} u} \gamma_{b}^{(q,\lambda)\downarrow}(u) \,{\mathrm{d}} u }{ \int^{\infty}_b {\mathrm{e}}^{-\Phi_{q+\lambda} u} {\mathbb{Z}}^{(q)}(u-b;\,\varphi_{q+\lambda}) \,{\mathrm{d}} u} \Biggr), \\[-7pt] \nonumber\end{align}
(4.41)
\begin{align}\widetilde{{\mathcal{U}}}_{b}^{(q,\lambda)}(y) & = \mathbb{Z}^{(q+\lambda)}(b-y,\varphi_q) - \lambda \int^{b-y}_0 \mathbb{Z}^{(q+\lambda)}(b-y-u,\varphi_q)W^{(q)}(u) \,{\mathrm{d}} u \nonumber \\[3pt] &\quad+ \dfrac{\lambda}{\varphi_{q+\lambda} - \varphi_{q}} \dfrac{\int^{\infty}_b {\mathrm{e}}^{-\Phi_{q+\lambda} u} \gamma_{b}^{(q,\lambda)}(u;\,y) \,{\mathrm{d}} u }{\int^{\infty}_b {\mathrm{e}}^{-\Phi_{q+\lambda} u} {\mathbb{Z}}^{(q)}(u-b;\,\varphi_{q+\lambda}) \,{\mathrm{d}} u}, \\[-7pt] \nonumber\end{align}
(4.42)
\begin{align}\widetilde{{\mathcal{U}}}_{b}^{(q,\lambda)}& = - \lambda \int^{\infty}_0 {\mathrm{e}}^{-\Phi_q (b-u)} \mathbb{Z}^{(q+\lambda)}(u,\varphi_q) \,{\mathrm{d}} u \nonumber \\[3pt] & \quad+ \dfrac{\lambda}{\varphi_{q+\lambda} - \varphi_{q}} \dfrac{\int^{\infty}_b {\mathrm{e}}^{-\Phi_{q+\lambda} u} \gamma_{b}^{(q,\lambda)\downarrow}(u;\,y) \,{\mathrm{d}} u }{\int^{\infty}_b {\mathrm{e}}^{-\Phi_{q+\lambda} u} {\mathbb{Z}}^{(q)}(u-b;\,\varphi_{q+\lambda}) \,{\mathrm{d}} u}, \\[8pt] \nonumber \end{align}


Proof. (i) Similarly to the previous section,
 \begin{align*}\mathbb{E}_x\biggl( \int^\infty_0 {\mathrm{e}}^{-q t} \mathbf{1}_{\{U_t \in B, \; t \lt \tau_{a,U}^+ \wedge \tau_{0,U}^-\}} \,{\mathrm{d}} t \biggr) \end{align*}
will be denoted by
 $R^X(x,B)$
 $(R^Y(x,B))$
for
 $x \in [0,b]$
 $(x \in (b,a])$
.
For
 $x \in [0,b]$
, we have by conditioning on
 $\tau_{b,U}^+$
and the strong Markov property that
 \begin{align}R^X(x,B)&= \mathbb{E}_x\biggl( \int^\infty_0 {\mathrm{e}}^{-q t} \mathbf{1}_{\{U_t \in B, \; t \lt \tau_{b,U}^+ \wedge \tau_{0,U}^-\}} \,{\mathrm{d}} t \biggr) \nonumber \\[3pt] &\quad + \mathbb{E}_x\biggl( \int^\infty_0 {\mathrm{e}}^{-q t} \mathbf{1}_{\{U_t \in B, \; \tau_{b,U}^+ \lt t \lt \tau_{a,U}^+ \wedge \tau_{0,U}^-\}} \,{\mathrm{d}} t \biggr) \nonumber \\[3pt] &= \mathbb{E}_x\biggl( \int^\infty_0 {\mathrm{e}}^{-q t} \mathbf{1}_{\{X_t \in B, \; t \lt \tau_{b,X}^+ \wedge \tau_{0,X}^-\}} \,{\mathrm{d}} t \biggr)\nonumber \end{align}
 \begin{align} & \quad + \mathbb{E}_x\Bigl({\mathrm{e}}^{-q \tau_{b,X}^{+}} \mathbf{1}_{\{\tau_{b,X}^{+} \lt \tau_{0,X}^{-}\}} \Bigr) \mathbb{E}_b\biggl( \int^\infty_0 {\mathrm{e}}^{-q t} \mathbf{1}_{\{U_t \in B, \; t \lt \tau_{a,U}^+ \wedge \tau_{0,U}^-\}} \,{\mathrm{d}} t \biggr) \nonumber \\[3pt] &= \int_{B\cap [0,b]} \biggl( \dfrac{W^{(q)}(b-y)}{W^{(q)}(b)}W^{(q)}(x) - W^{(q)}(x-y) \biggr) \,{\mathrm{d}} y + \dfrac{W^{(q)}(x)}{W^{(q)}(b)} R^X(b,B), \end{align}
where the second equality follows by recalling that
 $\tau_{b,X}^+ \leq T_{b \lt X}^+$
,
 $\tau_{b,U}^+ \leq T_{b,U}^+$
and noticing that
 $\{X_t, t \lt T_{b,X}^+\}$
and
 $\{U_t, t \lt T_{b,U}^+\}$
have the same distribution with respect to
 $\mathbb{P}_x$
when
 $x \in [0,b]$
, and the last equality follows by using the classical equations (A.1) and (A.3) in the Appendix.
Now, considering
 $x \in (b,a]$
and noticing that
 $\{Y_t, t \lt T_{b,Y}^-\}$
and
 $\{U_t, t \lt T_{b,U}^-\}$
have the same distribution with respect to
 $\mathbb{P}_x$
for these x-values, we condition on
 $T_{b,U}^-$
and use the strong Markov property to get
 \begin{align}R^Y (x,B)&= \mathbb{E}_x\biggl( \int^\infty_0 {\mathrm{e}}^{-q t} \mathbf{1}_{\{Y_t \in B, \; t \lt T_{b,Y}^- \wedge \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} \,{\mathrm{d}} t \biggr)\nonumber \\[3pt] &\quad + \mathbb{E}_x\Bigl({\mathrm{e}}^{-q T_{b,Y}^-} \mathbf{1}_{ \{ T_{b,Y}^- \lt \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} R^X\bigl(Y_{T_{b,Y}^-},B\bigr) \Bigr) \nonumber \\[3pt] &= \int_{B \cap [0,a]} \biggl( \dfrac{\mathcal{W}^{\,(q,\lambda)}_{a}(a;\,y)}{\mathcal{W}^{\,(q,\lambda)}_{a}(a)} \mathcal{W}^{\,(q,\lambda)}_{x}(x) - \mathcal{W}^{\,(q,\lambda)}_{x}(x;\,y) \biggr) \,{\mathrm{d}} y \nonumber \\[3pt] &\quad + \int_{B\cap[0,b]} \biggl[ \dfrac{W^{(q)}(b-y)}{W^{(q)}(b)} \mathbb{E}_x\Bigl({\mathrm{e}}^{-q T_{b,Y}^-} \mathbf{1}_{ \{ T_{b,Y}^- \lt \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} W^{(q)}\bigl(Y_{T_{b,Y}^-}\bigr) \Bigr) \nonumber \\[3pt] &\quad - \mathbb{E}_x\Bigl({\mathrm{e}}^{-q T_{b,Y}^-} \mathbf{1}_{ \{ T_{b,Y}^- \lt \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} W^{(q)}\bigl(Y_{T_{b,Y}^-}-y\bigr) \Bigr) \biggr] \,{\mathrm{d}} y\nonumber \\[3pt] &\quad + \dfrac{R^X(b,B)}{W^{(q)}(b)}\mathbb{E}_x\Bigl({\mathrm{e}}^{-q T_{b,Y}^-} \mathbf{1}_{ \{ T_{b,Y}^- \lt \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} W^{(q)}\bigl(Y_{T_{b,Y}^-}\bigr) \Bigr),\end{align}
where the last equality follows by using Lemma 4.1(ii) and by substituting (4.43).
Now, note that the first and third expectation in the above equation are special cases (for
 $y=0$
) of the second expectation in this equation, and so it suffices to derive the latter one. To do this, for
 $x>b$
, we use (4.6) and (4.11) to write the second expectation of (4.44) as
 \begin{align}\mathbb{E}_x &\Bigl({\mathrm{e}}^{-q T_{b,Y}^-} \mathbf{1}_{ \{ T_{b,Y}^- \lt \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} W^{(q)}\bigl(Y_{T_{b,Y}^-}-y\bigr) \Bigr) \nonumber \\[3pt] &= \dfrac{\mathcal{W}_{x}^{\,(q,\lambda)}(x)}{\mathcal{W}_{a}^{(q,\lambda)}(a)} \bigl( \mathcal{G}_{a}^{(q,\lambda)}(a;\,y) - W^{(q)}(a-y) + \mathcal{W}_{a}^{(q,\lambda)}(a;\,y) \bigr)\nonumber \\[3pt] &\quad - \bigl( \mathcal{G}_{x}^{(q,\lambda)}(x;\,y) -W^{(q)}(x-y) + \mathcal{W}_{x}^{\,(q,\lambda)}(x;\,y) \bigr) \nonumber \\[3pt] &= \dfrac{\mathcal{W}_{x}^{\,(q,\lambda)}(x)}{\mathcal{W}_{a}^{(q,\lambda)}(a)} \biggl( \dfrac{\mathcal{W}_{a}^{(q,\lambda)}(a)}{\mathcal{W}_{b}^{(q,\lambda)}(a)} \mathcal{G}_{b}^{(q,\lambda)}(a;\,y) - \mathcal{U}^{\,(q,\lambda)}_{b,a}(a;\,y) + \mathcal{W}_{a}^{(q,\lambda)}(a;\,y) \biggr) \nonumber \\[3pt] &\quad - \biggl( \dfrac{\mathcal{W}_{x}^{\,(q,\lambda)}(x)}{\mathcal{W}_{b}^{(q,\lambda)}(a)} \mathcal{G}_{b}^{(q,\lambda)}(a;\,y) - \mathcal{U}^{\,(q,\lambda)}_{b,a}(x;\,y) + \mathcal{W}_{x}^{\,(q,\lambda)}(x;\,y) \biggr) \nonumber \\[3pt] &= \mathcal{U}^{\,(q,\lambda)}_{b,a}(x;\,y) - \dfrac{\mathcal{W}_{x}^{\,(q,\lambda)}(x)}{\mathcal{W}_{a}^{(q,\lambda)}(a)} \mathcal{U}^{\,(q,\lambda)}_{b,a}(a;\,y) + \biggl(\dfrac{\mathcal{W}_{a}^{(q,\lambda)}(a;\,y)}{\mathcal{W}_{a}^{(q,\lambda)}(a)} \mathcal{W}^{\,(q,\lambda)}_{x}(x) - \mathcal{W}_{x}^{\,(q,\lambda)}(x;\,y) \biggr). \end{align}
Then, by substituting the above equation into (4.44),
 \begin{align}R^Y (x,B) &= \int_{B \cap (b,a]} \biggl( \dfrac{\mathcal{W}^{\,(q,\lambda)}_{a}(a;\,y)}{\mathcal{W}^{\,(q,\lambda)}_{a}(a)} \mathcal{W}^{\,(q,\lambda)}_{x}(x) - \mathcal{W}^{\,(q,\lambda)}_{x}(x;\,y) \biggr) \,{\mathrm{d}} y \nonumber \\[3pt] &\quad + \int_{B\cap[0,b]} \biggl[ \dfrac{W^{(q)}(b-y)}{W^{(q)}(b)} \mathbb{E}_x\Bigl({\mathrm{e}}^{-q T_{b,Y}^-} \mathbf{1}_{ \{ T_{b,Y}^- \lt \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} W^{(q)}\bigl(Y_{T_{b,Y}^-}\bigr) \Bigr)\nonumber \\[3pt] &\quad - \mathcal{U}^{\,(q,\lambda)}_{b,a}(x;\,y) + \dfrac{\mathcal{W}_{x}^{\,(q,\lambda)}(x)}{\mathcal{W}_{a}^{(q,\lambda)}(a)} \mathcal{U}^{\,(q,\lambda)}_{b,a}(a;\,y) \biggr] \,{\mathrm{d}} y \nonumber \\[3pt] &\quad + \dfrac{R^X(b,B)}{W^{(q)}(b)} \mathbb{E}_x\Bigl({\mathrm{e}}^{-q T_{b,Y}^-} \mathbf{1}_{ \{ T_{b,Y}^- \lt \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} W^{(q)}\bigl(Y_{T_{b,Y}^-}\bigr) \Bigr). \end{align}
From (4.43) and (4.46), it suffices to derive
 $R^X(b,B)$
. To do this, we consider whether
 $T_{b,U}^+$
or
 $\tau_{a,U}^+$
occurs first and use the strong Markov property to find that
 \begin{align}R^X (b,B)&= \mathbb{E}_b\biggl( \int^\infty_0 {\mathrm{e}}^{-q t} \mathbf{1}_{\{X_t \in B, \; t \lt T_{b,X}^+ \wedge \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \,{\mathrm{d}} t \biggr) \nonumber \\[3pt] &\quad + \mathbb{E}_b\Bigl({\mathrm{e}}^{-q T_{b,X}^+ } \mathbf{1}_{\{ T_{b,X}^+ \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} R^Y\bigl(X_{T_{b,X}^+},B\bigr) \Bigr) \nonumber \\[3pt] &= \int_{B\cap [0,a]} \Biggl(\dfrac{\overline{W}^{(q,\lambda)}_b(b)}{\overline{W}^{(q,\lambda)}_b(a)}\overline{W}^{(q,\lambda)}_{b-y}(a-y) - \overline{W}^{(q,\lambda)}_{b-y}(b-y) \mathbf{1}_{\{y \in [0,b]\}} \Biggr) \,{\mathrm{d}} y \nonumber \\[3pt] &\quad + \int_{B\cap (b,a]} \biggl[ \dfrac{\mathcal{W}_{a}^{(q,\lambda)}(a;\,y)}{\mathcal{W}_{a}^{(q,\lambda)}(a)} \mathbb{E}_b\Bigl({\mathrm{e}}^{-q T_{b,X}^+ } \mathbf{1}_{\{ T_{b,X}^+ \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \mathcal{W}_{X_{T_{b,X}^+}}^{(q,\lambda)}\bigl(X_{T_{b,X}^+}\bigr) \Bigr) \nonumber \\[3pt] &\quad - \mathbb{E}_b\Bigl({\mathrm{e}}^{-q T_{b,X}^+ } \mathbf{1}_{\{ T_{b,X}^+ \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \mathcal{W}_{X_{T_{b,X}^+}}^{(q,\lambda)}\bigl(X_{T_{b,X}^+};\,y\bigr) \Bigr) \biggr] \,{\mathrm{d}} y \nonumber \\[3pt] &\quad + \int_{B\cap[0,b]} \biggl[ \dfrac{W^{(q)}(b-y)}{W^{(q)}(b)} \nonumber \\[3pt] &\quad \times \mathbb{E}_b\Bigl({\mathrm{e}}^{-q T_{b,X}^+ } \mathbf{1}_{\{ T_{b,X}^+ \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \mathbb{E}_{X_{T_b^+}}\Bigl({\mathrm{e}}^{-q T_{b,Y}^-} \mathbf{1}_{ \{ T_{b,Y}^- \lt \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} W^{(q)}\bigl(Y_{T_{b,Y}^-}\bigr) \Bigr) \Bigr)\nonumber \\[3pt] &\quad - \mathbb{E}_b\Bigl({\mathrm{e}}^{-q T_{b,X}^+ } \mathbf{1}_{\{ T_{b,X}^+ \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \mathcal{U}_{b,a}^{(q,\lambda)}\bigl(X_{T_{b,X}^+};\,y\bigr) \Bigr)\nonumber \\[3pt] &\quad + \dfrac{\mathcal{U}^{\,(q,\lambda)}_{b,a}(a;\,y)}{\mathcal{W}_{a}^{(q,\lambda)}(a)} \mathbb{E}_b\Bigl({\mathrm{e}}^{-q T_{b,X}^+ } \mathbf{1}_{\{ T_{b,X}^+ \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \mathcal{W}_{X_{T_{b,X}^+}}^{(q,\lambda)}\bigl(X_{T_{b,X}^+}\bigr) \Bigr) \biggr] \,{\mathrm{d}} y\nonumber \\[3pt] &\quad + \dfrac{R^X(b,B)}{W^{(q)}(b)} \nonumber \\[3pt] &\quad \times \mathbb{E}_b\Bigl({\mathrm{e}}^{-q T_{b,X}^+ } \mathbf{1}_{\{ T_{b,X}^+ \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \mathbb{E}_{X_{T_b^+}}\Bigl({\mathrm{e}}^{-q T_{b,Y}^-} \mathbf{1}_{ \{ T_{b,Y}^- \lt \tau_{a,Y}^+ \wedge \tau_{0,Y}^-\}} W^{(q)}\bigl(Y_{T_{b,Y}^-}\bigr) \Bigr) \Bigr),\end{align}
where the first term in the last equality follows by using Lemma 4.1(i) whilst the remaining terms of the above equation follow by using (4.46).
Excluding the the fourth expectation, we note that the remaining expectations of (4.47) are known from either (4.15) or (4.18). To compute the fourth expectation of (4.47), we have from (A.6) in the Appendix that
 \begin{equation*}\lambda \int^a_b W^{(q+\lambda)}(a-z) \mathcal{U}^{\,(q,\lambda)}_{b,a}(z;\,y) \,{\mathrm{d}} z = \overline{W}_{b-y}^{(q,\lambda)}(a-y) - \mathcal{U}_{b,a}^{(q,\lambda)}(a;\,y), \end{equation*}
and hence by using (4.5) and the above equation that
 \begin{equation}\mathbb{E}_b\Bigl({\mathrm{e}}^{-q T_{b,X}^+ } \mathbf{1}_{\{ T_{b,X}^+ \lt \tau_{a,X}^+ \wedge \tau_{0,X}^-\}} \mathcal{U}_{b,a}^{(q,\lambda)}\bigl(X_{T_{b,X}^+};\,y\bigr) \Bigr) = \dfrac{\overline{W}_{b}^{(q,\lambda)}(b)}{\overline{W}_{b}^{(q,\lambda)}(a)}\bigr(\overline{W}_{b-y}^{(q,\lambda)}(a-y) - \mathcal{U}_{b,a}^{(q,\lambda)}(a;\,y) \bigl).\end{equation}
By noticing that
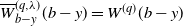 $\overline{W}^{(q,\lambda)}_{b-y}(b-y) = W^{(q)}(b-y)$
for
 $y \in [0,b]$
, using the above equation and substituting (4.15), (4.18), and (4.48) into (4.47), we get
 \begin{align}&R^X (b,B) \nonumber \\[3pt] &\quad= \int_{B\cap (b,a]} \dfrac{W^{(q)}(b)}{\overline{W}^{(q,\lambda)}_b(a)}\dfrac{\mathcal{W}_{b}^{(q,\lambda)}(a)}{\mathcal{W}_{a}^{(q,\lambda)}(a)}\biggl[ \mathcal{W}_{a}^{(q,\lambda)}(a;\,y) + \dfrac{\mathcal{W}_{a}^{(q,\lambda)}(a)}{\mathcal{W}_{b}^{(q,\lambda)}(a)} \bigl( \overline{W}_{b-y}^{(q,\lambda)}(a-y)-\mathcal{W}_{b}^{(q,\lambda)}(a;\,y)\bigr) \biggr]\nonumber \\[3pt] &\quad\quad + \int_{B\cap[0,b]} \biggl[ - \dfrac{W^{(q)}(b-y)}{\overline{W}^{(q,\lambda)}_b(a)}\dfrac{\mathcal{W}_{b}^{(q,\lambda)}(a)}{\mathcal{W}_{a}^{(q,\lambda)}(a)} \mathcal{U}_{b,a}^{(q,\lambda)}(a) + \dfrac{W^{(q)}(b)}{\overline{W}^{(q,\lambda)}_b(a)}\dfrac{\mathcal{W}_{b}^{(q,\lambda)}(a)}{\mathcal{W}_{a}^{(q,\lambda)}(a)} \mathcal{U}_{b,a}^{(q,\lambda)}(a;\,y) \biggl] \,{\mathrm{d}} y\nonumber \\[3pt] &\quad\quad + \dfrac{R^X(b,B)}{W^{(q)}(b)} \biggl( W^{(q)}(b) -\dfrac{W^{(q)}(b)}{\overline{W}^{(q,\lambda)}_b(a)}\dfrac{\mathcal{W}_{b}^{(q,\lambda)}(a)}{\mathcal{W}_{a}^{(q,\lambda)}(a)} \mathcal{U}_{b,a}^{(q,\lambda)}(a)\biggr).\end{align}
To solve for
 $R^X (b,B)$
in the above equation, we first observe that
 \begin{align*}\mathcal{G}_{x}^{(q,\lambda)}(x;\,y) =\gamma_{b}^{(q,\lambda)}(x;\,y) = W^{(q)}(x-y) - \mathcal{W}^{\,(q,\lambda)}_x(x;\,y)\quad\text{for $y >b$,} \end{align*}
and thus have from (2.3) and (4.7) that
 \begin{equation}\mathcal{U}^{\,(q,\lambda)}_{b,a}(x;\,y) = \mathcal{W}_{x}^{\,(q,\lambda)}(x;\,y) + \dfrac{\mathcal{W}_{x}^{\,(q,\lambda)}(x)}{\mathcal{W}_{b}^{(q,\lambda)}(a)} \bigl( \overline{W}_{b-y}^{(q,\lambda)}(a-y)-\mathcal{W}_{b}^{(q,\lambda)}(a;\,y)\bigr), \quad y \gt b, \end{equation}
and so substituting the above equation with
 $x=a$
into (4.49) yields the desired quantity
 \begin{align*}&R^X(b,B) \\[3pt] &\quad = \dfrac{{W}^{(q)}(b)}{\mathcal{U}^{\,(q,\lambda)}_{b,a}(a)} \int_{B\cap (b,a]} \mathcal{U}^{\,(q,\lambda)}_{b,a}(a;\,y) \,{\mathrm{d}} y + \int_{B \cap [0,b]} \biggl( \dfrac{{W}^{(q)}(b)}{\mathcal{U}^{\,(q,\lambda)}_{b,a}(a)} \mathcal{U}^{\,(q,\lambda)}_{b,a}(a;\,y) - W^{(q)}(b-y) \biggr) \,{\mathrm{d}} y \\[3pt] &\quad = \int_{B} \biggl( \dfrac{{W}^{(q)}(b)}{\mathcal{U}^{\,(q,\lambda)}_{b,a}(a)} \mathcal{U}^{\,(q,\lambda)}_{b,a}(a;\,y) - W^{(q)}(b-y) \biggr) \,{\mathrm{d}} y, \nonumber \end{align*}
where the last equality follows since
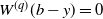 $W^{(q)}(b-y) = 0$
for
 $y \in (b,a]$
.
Finally, by substituting the above equation into (4.43), we derive the result for
 $x \in [0,b]$
. For
 $x \in (b,a]$
, we substitute
 $R^X(b,B)$
along with (4.45) into (4.46), and then use (4.50) to get the required result.
(ii) Observe that
 \begin{align*}\mathbb{E}_x\biggl(\int_0^{\infty} {\mathrm{e}}^{-q t} \mathbf{1}_{\{U_t \in \mathrm{~d} y, t \lt \tau_{a, U}^{+} \wedge \tau_{0, U}^{-}\}} {\mathrm{d}} t\biggr) \leq \dfrac{1}{q}, \end{align*}
and furthermore that this potential measure increases for all Borel sets
 $B \subset[0, a]$
as
 $a \rightarrow \infty$
. Since it is bounded from above, its limit as
 $a \rightarrow \infty$
must exist, and thus, by the monotone convergence theorem,
 \begin{align*}\mathbb{E}_x\biggl(\int_0^{\infty} {\mathrm{e}}^{-q t} \mathbf{1}_{\{U_t \in B, t \lt \tau_{0, U}^{-}\}} {\mathrm{d}} t\biggr) & =\lim _{a \rightarrow \infty} \int_{B \cap[0, a]} \mathbb{E}_x\biggl(\int_0^{\infty} {\mathrm{e}}^{-q t} \mathbf{1}_{\{U_t \in \mathrm{~d} y, t \lt \tau_{a, U}^{+} \wedge \tau_{0, U}^{-}\}} {\mathrm{d}} t\biggr) \\[3pt] & =\int_{B \cap[0, \infty)} \lim _{a \rightarrow \infty}\Biggl(\dfrac{\mathcal{U}_{b, a}^{(q, \lambda)}(a ;\, y)}{\mathcal{U}_{b, a}^{(q, \lambda)}(a ;\, 0)} \mathcal{U}_{b, a}^{(q, \lambda)}(x ;\, 0)-\mathcal{U}_{b, a}^{(q, \lambda)}(x ;\, y)\Biggr)\,{\mathrm{d}} y,\end{align*}
where we have used the potential density derived in part (i) in the final step. The result then follows by using (4.33) and (4.37) from the proof of Proposition 4.2.
(iii) Using a level invariance argument, an argument similar to that in (ii) to interchange the limits and integral, and also (i),
 \begin{align*}&\mathbb{E}_x\biggl( \int^\infty_0 {\mathrm{e}}^{-q t} \mathbf{1}_{\{U_t \in B, \; t \lt \tau_{a,U}^+\}} \,{\mathrm{d}} t \biggr) \\[3pt] &\quad = \lim_{\theta \rightarrow \infty} \int_{B} \Biggl( \dfrac{\mathcal{U}^{\,(q,\lambda)}_{b+\theta,a+\theta}(x+\theta)}{\mathcal{U}^{\,(q,\lambda)}_{b+\theta,a+\theta}(a+\theta)}\mathcal{U}^{\,(q,\lambda)}_{b+\theta,a+\theta}(a+\theta;\,y+\theta) - \mathcal{U}^{\,(q,\lambda)}_{b+\theta,a+\theta}(x+\theta;\,y+\theta) \Biggr) \,{\mathrm{d}} y, \end{align*}
and so we derive the above limit by taking the limits of the terms separately.
First, by observing that
 \begin{align*}\gamma^{(q,\lambda)}_{b+\theta}(x+\theta;\,y+\theta) = \gamma^{(q,\lambda)}_{b}(x;\,y), \end{align*}
and hence that
 \begin{align*}\mathcal{G}^{(q,\lambda)}_{b+\theta}(x+\theta;\,y+\theta) = \mathcal{G}^{(q,\lambda)}_{b}(x;\,y), \end{align*}
we have
 \begin{align*}&\lim_{\theta \rightarrow \infty} \mathcal{U}^{\,(q,\lambda)}_{b+\theta,a+\theta}(x+\theta;\,y+\theta) \\[3pt] &\quad = W^{(q)}(x-y) -\mathbf{1}_{\{x>b\}} \Biggl( \gamma^{(q,\lambda)}_{b}(x;\,y) - \lim_{\theta \rightarrow \infty} \dfrac{\overline{\mathbb{W}}^{(q,\lambda)}_{x-b}(x+\theta)}{\mathcal{W}^{\,(q,\lambda)}_{b+\theta}(a+\theta)}\mathcal{G}^{(q,\lambda)}_{b}(a;\,y) \Biggr), \end{align*}
where
 \begin{equation*}\mathcal{W}^{\,(q,\lambda)}_{b+\theta}(a+\theta) = \overline{\mathbb{W}}^{(q,\lambda)}_{a-b}(a+\theta) + \lambda \int^a_b W^{(q+\lambda)}(a-y) \overline{\mathbb{W}}^{(q,\lambda)}_{y-b}(y+\theta) \,{\mathrm{d}} y. \end{equation*}
Then, by using (4.26)–(4.27), it is clear that
 \begin{align*} \mathcal{U}^{\,(q,\lambda)\downarrow}_{b,a}(x;\,y) = \lim_{\theta \rightarrow \infty} \mathcal{U}^{\,(q,\lambda)}_{b+\theta,a+\theta}(x+\theta;\,y+\theta) \end{align*}
has the form of (4.38). The proof is then completed by using (4.28) from the proof of Proposition 4.1.
(iv) We derive the desired identities by taking the limits of the terms of the potential measure from (iii). Additionally, in some of the limits below, the dominated convergence theorem is applied since its usage is justified by noticing that
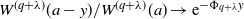 $W^{(q+\lambda)}(a-y)/W^{(q+\lambda)}(a) \rightarrow {\mathrm{e}}^{-\Phi_{q+\lambda} y}$
as
 $a\rightarrow \infty$
.
Now, since we assume
 $\Phi_{q}>\varphi_{q+\lambda}$
, we have
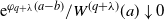 ${\mathrm{e}}^{\varphi_{q+\lambda}(a-b)}/W^{(q+\lambda)}(a) \downarrow 0$
as
 $a \rightarrow \infty$
, and hence, by Lemma 4.2(ii) and the dominated convergence theorem,
 \begin{equation*}\lim_{a \rightarrow \infty} \dfrac{\mathbb{Z}^{(q)}(a-b,\varphi_{q+\lambda})}{W^{(q+\lambda)}(a)} = 0, \quad \lim_{a \rightarrow \infty} \dfrac{\gamma_{b}^{(q,\lambda)}(a;\,y)}{W^{(q+\lambda)}(a)} = 0. \end{equation*}
Using the above limits and the dominated convergence theorem, we obtain
 \begin{align*}\overline{\mathcal{U}}_{b}^{(q,\lambda)}(x;\,y) = \lim_{a \rightarrow \infty} \mathcal{U}_{b,a}^{(q,\lambda)\downarrow}(x;\,y) \quad \text{and} \quad \overline{\mathcal{U}}_{b}^{(q,\lambda)}(x) = \lim_{a \rightarrow \infty} \mathcal{U}_{b,a}^{(q,\lambda)\downarrow}(x), \end{align*}
which have the same forms as (4.39) and (4.40), respectively.
Now we observe that
 \begin{align*}\lim_{a \rightarrow \infty} \mathcal{U}_{b,a}^{(q,\lambda)\downarrow}(a;\,y)/\mathbb{W}^{(q)}(a) = \lim_{a \rightarrow \infty} \overline{\mathcal{U}}_{b}^{(q,\lambda)}(a;\,y)/\mathbb{W}^{(q)}(a). \end{align*}
Then, by using (4.36) and (2.2) to notice that
 \begin{equation}\lim_{a \rightarrow \infty} \dfrac{\mathbb{Z}^{(q)}(a-b,\varphi_{q+\lambda})}{\mathbb{W}^{(q)}(a)} = \dfrac{\lambda}{\varphi_{q+\lambda} - \varphi_q} {\mathrm{e}}^{- \varphi_q b}, \end{equation}
we conclude that
 \begin{align*}\widetilde{{\mathcal{U}}}_{b}^{(q,\lambda)}(y) = {\mathrm{e}}^{\varphi_q b}\lim_{a \rightarrow \infty} \overline{\mathcal{U}}_{b}^{(q,\lambda)}(a;\,y)/\mathbb{W}^{(q)}(a) \end{align*}
has the same form as (4.41).
Similarly, we have that
 \begin{align*}\lim_{a \rightarrow \infty} \mathcal{U}_{b,a}^{(q,\lambda)\downarrow}(a)/\mathbb{W}^{(q)}(a) = \lim_{a \rightarrow \infty} \overline{\mathcal{U}}_{b}^{(q,\lambda)}(a)/\mathbb{W}^{(q)}(a), \end{align*}
and so we need to derive the limit
 \begin{equation*}\lim_{a \rightarrow \infty} \dfrac{1}{\mathbb{W}^{(q)}(a)} \Bigl({\mathrm{e}}^{\Phi_q a} - \gamma_b^{(q,\lambda)\downarrow}(a) \Bigr) = \lim_{a \rightarrow \infty} \dfrac{1}{\mathbb{W}^{(q)}(a)} \biggl( -\lambda \int_0^{\infty} {\mathrm{e}}^{\Phi_q (b-u)}\overline{\mathbb{W}}_{a-b}^{(q,\lambda)}(a-b+u) {\mathrm{d}} u \biggr), \end{equation*}
but it easily follows from (4.34) and the dominated convergence theorem that
 \begin{equation*}\lim_{a \rightarrow \infty} \dfrac{1}{\mathbb{W}^{(q)}(a)} \Bigl({\mathrm{e}}^{\Phi_q a} - \gamma_b^{(q,\lambda)\downarrow}(a) \Bigr) = {\mathrm{e}}^{-\varphi_q b}\biggl( -\lambda \int_0^{\infty} {\mathrm{e}}^{\Phi_q (b-u)}\mathbb{Z}^{(q+\lambda)}(u,\varphi_q)\,{\mathrm{d}} u \biggr).\end{equation*}
Then, using the above equation as well as (4.51), it can be seen that
 \begin{align*}\widetilde{{\mathcal{U}}}_{b}^{(q,\lambda)} = {\mathrm{e}}^{\varphi_q b}\lim_{a \rightarrow \infty} \overline{\mathcal{U}}_{b}^{(q,\lambda)}(a)/\mathbb{W}^{(q)}(a) \end{align*}
has the same form as (4.42).
4.4. Application to ruin theory
In this subsection we consider the application of the above model in an insurance setting. In particular, we assume U represents the risk (surplus) process of an insurer who can switch between different business strategies (represented by the Lévy processes X and Y, respectively) at Poissonian observation times depending on the surplus level and we are interested in the time and probability of ruin – the event that the surplus drops to a negative level.
In general, the probability of ruin can be obtained as a limiting result of Proposition 4.2 as
 $q\rightarrow 0$
. However, for the general case of arbitrary X and Y, the result remains in a similar form, with the q-scale functions replaced by their limiting counterparts, and does not offer any further insight(s). Therefore, in the remainder of this section, we will consider a specific insurance context which allows us to obtain more explicit results.
Let X denote the Lévy risk process of an insurer and
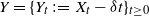 ${Y} = \{ {Y}_t \, :\!= \, {X}_t - \delta t \}_{t \geq 0}$
, where
 $\delta \gt 0$
represents a constant dividend rate paid to shareholders whenever the surplus (U) is above the level b. In this case, (1.1) reduces to
 \begin{equation*} U_t = x + X_t - \delta \int^t_0 \mathbf{1}_{\{U_{T_{N(s)}} \gt b\}} \,{\mathrm{d}} s , \quad U_0 = x \in \mathbb{R},\end{equation*}
and the level-dependent Poissonian switching can be understood as a time delay between initiating (above b) and withdrawing (below b) dividend payments, reducing the model to one similar to [Reference Wang, Lkabous and Landriault20]. We note here that, in addition to the arguments of Remark 3.1, the form of the above SDE implies that uniqueness can also be proved by contradiction using methods similar to those in [Reference Kyprianou and Loeffen10].
As before, for each
 $q \geq 0$
,
 $W^{(q)}$
and
 $Z^{(q)}$
are the q-scale functions associated with X, and
 $\mathbb{W}^{(q)}$
and
 $\mathbb{Z}^{(q)}$
are the q-scale functions associated with Y. Moreover, the right-inverse of the Laplace exponent of Y is now
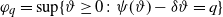 $\varphi_q=\sup \{\vartheta \geq 0\colon \psi(\vartheta)-\delta \vartheta=q\}$
. It is clear that
 $\delta = 0$
yields
 $Y = X$
and
 $\mathbb{W}^{(q)} = W^{(q)}$
.
The following corollary provides the probability of ruin for the model described above.
Corollary 4.2. Let
 $0 \leq b,\lambda \lt \infty$
, where
 $\lambda$
is sufficiently large that
 $\Phi_{q+\lambda} \gt \varphi_q$
. Then, given the assumption that
 $0 \leq \delta \lt \mathbb{E}(X_1)$
, the ruin probability for
 $x \geq 0$
is given by
 \begin{align}\mathbb{P}_{x}\big( \tau_{0,U}^- \lt \infty \big)=1-\dfrac{(\psi'(0+) - \delta)\, \cdot \mathcal{U}^{\,(0,\lambda)\uparrow}_{b}(x;\,0)}{1+\delta \lambda \int_{0}^{b} \mathbb{W}^{(\lambda)}(b-y)\, W(y)\, \textrm{d}y+\mathbb{Z}^{(\lambda)}(b)\,\frac{\int_{b}^{\infty} \textrm{e}^{-\Phi_{\lambda} u}\, \gamma_{b}^{(0,\lambda)}(u)\, \textrm{d}u}{\int_{b}^{\infty} \textrm{e}^{-\Phi_{\lambda} u}\, \overline{\mathbb{W}}^{(0,\lambda)}(u-b)\, \textrm{d}u}},\end{align}
where
 $\mathcal{U}^{\,(0,\lambda)\uparrow}_{b}(x;\,y)$
is given by (4.29).
Proof. Observe from Proposition 4.2 that
 \begin{equation*}\mathbb{P}_x( \tau_{0,U}^- \lt \infty) = \lim_{q \downarrow 0} \mathbb{E}_x\Bigl({\mathrm{e}}^{-q \tau_{0,U}^-} \mathbf{1}_{\{ \tau_{0,U}^- \lt \infty \}} \Bigr) =\lim_{q \downarrow 0} \mathcal{V}^{\,(q,\lambda)\uparrow}_{b}(x) - \lim_{q \downarrow 0} \dfrac{\mathcal{V}^{\,(q,\lambda)\uparrow}_{b}}{\mathcal{U}^{\,(q,\lambda)\uparrow}_{b}(0)} \; \lim_{q \downarrow 0}\mathcal{U}^{\,(q,\lambda)\uparrow}_{b}(x;\,0). \end{equation*}
Now, recall from [Reference Wang, Lkabous and Landriault20, Proposition 2.1] that the choice of SNLPs
 $X_t$
and
 $Y_t = X_t - \delta t$
gives
 \begin{equation}\alpha_{b}^{(q,\lambda)}(x) = -\delta q \int^x_0 \overline{\mathbb{W}}^{(q,\lambda)}_{x-b}(x-u)W^{(q)}(u) \,{\mathrm{d}} u, \end{equation}
and so using the above equation along with (4.30) yields
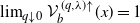 $\lim_{q \downarrow 0} \mathcal{V}^{\,(q,\lambda)\uparrow}_{b}(x) = 1$
. Furthermore, it is clear that
 \begin{align*}\mathcal{U}^{\,(0,\lambda)\uparrow}_{b}(x;\,0) = \lim_{q \downarrow 0}\mathcal{U}^{\,(q,\lambda)\uparrow}_{b}(x;\,0). \end{align*}
Additionally, since the condition
 $0 \leq \delta \lt \mathbb{E}(X_1)$
implies that
 $\varphi_0 = 0$
, the form of the denominator in (4.52) can be found by using (4.31) to take
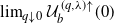 $\lim_{q \downarrow 0} \mathcal{U}^{\,(q,\lambda)\uparrow}_{b}(0)$
, and then observing that
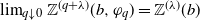 $ \lim_{q \downarrow 0} \mathbb{Z}^{(q + \lambda)}(b,\varphi_q) = \mathbb{Z}^{(\lambda)}(b)$
and that
 \begin{equation*}\lambda \int^b_0 \mathbb{Z}^{(\lambda)}(b-u) W(u) \,{\mathrm{d}} u = \mathbb{Z}^{(\lambda)}(b) - 1 - \delta \lambda \int^b_0\mathbb{W}^{(\lambda)}(b-u)W(u) \,{\mathrm{d}} u;\, \end{equation*}
see [Reference Wang, Lkabous and Landriault20, Equation (A18)].
Lastly, we observe from (4.32) and (4.53) that
 \begin{equation*}\lim_{q\downarrow 0} \mathcal{V}^{\,(q,\lambda)\uparrow}_{b} = \lim_{q\downarrow 0} {\mathrm{e}}^{\varphi_q b} \biggl(\dfrac{q}{\varphi_q} + \lambda \int^b_0 {\mathrm{e}}^{-\varphi_q y}\mathbb{Z}^{(q+\lambda)}(y) \,{\mathrm{d}} y \biggr) - \lim_{q\downarrow 0} \lambda \int^{b}_0 \mathbb{Z}^{(q+\lambda)}(b-u,\varphi_q)Z^{(q)}(u) \,{\mathrm{d}} u. \end{equation*}
As previously mentioned,
 $\varphi_0 = 0$
by our assumption, and
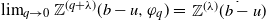 $\lim_{q \rightarrow 0} \mathbb{Z}^{(q+\lambda)}(b-u,\varphi_q) = \mathbb{Z}^{(\lambda)}(b-u)$
and
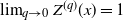 $\lim_{q \rightarrow 0} Z^{(q)}(x) = 1$
, which both follow by using (2.1). Finally, by noticing that
 \begin{align*}\lim_{q \rightarrow 0} \frac{q}{\varphi_q} = \psi'(0+) - \delta \gt 0, \end{align*}
under our assumption as well as these previous observations, we get
 \begin{equation*}\lim_{q\downarrow 0} \mathcal{V}^{\,(q,\lambda)\uparrow}_{b} = \psi'(0+) - \delta, \end{equation*}
which completes the proof.
Appendix
The lemma below is a collection of classical fluctuation identities which have been used in the preceding text. See, for example, [Reference Kyprianou9, Chapter 8] for the origin of these identities.
Lemma A.1. ([Reference Kyprianou9].) Let X be a spectrally negative Lévy process and
 \begin{align*}\tau_{a,X}^{+}=\inf \{t>0\colon X_t>a\} \quad {and} \quad \tau_{0,X}^{-}=\inf \{t \gt 0\colon X_t \lt 0\} . \end{align*}
-
(i) For
$q \geq 0$
and
$x \leq a$
, (A.1)and
\begin{equation}\mathbb{E}_x\Bigl({\mathrm{e}}^{-q \tau_{a,X}^{+}} \mathbf{1}_{\{\tau_{a,X}^{+} \lt \tau_{0,X}^{-}\}}\Bigr)=\dfrac{W^{(q)}(x)}{W^{(q)}(a)} \end{equation}
(A.2)
\begin{equation}\mathbb{E}_x\Bigl({\mathrm{e}}^{-q \tau_{0,X}^{-}} \mathbf{1}_{\{\tau_{0,X}^{-} \lt \tau_{a,X}^{+}\}}\Bigr)=Z^{(q)}(x) - \dfrac{W^{(q)}(x)}{W^{(q)}(a)}Z^{(q)}(a) . \end{equation}
-
(ii) For any
$a>0, x, y \in[0, a], q \geq 0$
, (A.3)where
\begin{equation}\int_0^{\infty} {\mathrm{e}}^{-q t} \mathbb{P}_x\bigl(X_t \in {\mathrm{d}} y, t \lt \tau_{a,X}^{+} \wedge \tau_{0,X}^{-}\bigr)\,{\mathrm{d}} t= u^{(q)}(x,a,y)\,{\mathrm{d}} y, \end{equation}
\begin{equation*}u^{(q)}(x,a,y) = \dfrac{W^{(q)}(x) }{W^{(q)}(a)}W^{(q)}(a-y)-W^{(q)}(x-y). \end{equation*}


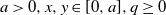


The following lemma is a consequence of Lemma 2.1 in [Reference Loeffen, Renaud and Zhou15].
Lemma A.2. ([Reference Loeffen, Renaud and Zhou15].) For
 $p,p+q \geq 0$
and
 $0 \leq b \leq x \leq a$
, it holds for
 $ y \in [0,b)$
that
 \begin{equation}\mathbb{E}_x\Bigl({\mathrm{e}}^{-(p+q) \tau_{b,X}^-} \mathbf{1}_{\{\tau_{b,X}^- \lt \tau_{a,X}^+\}} W^{(p)}\bigl(X_{\tau_{b,X}^-} - y\bigr) \Bigr) = \overline{W}^{(p,q)}_{b-y}(x-y) - \dfrac{W^{(p+q)}(x-b)}{W^{(p+q)}(a-b)}\overline{W}^{(p,q)}_{b-y}(a-y),\end{equation}
where
 $\overline{W}^{(p,q)}_b$
is given in (2.3).
The lemma below yields an identity required for the derivation of the fluctuation identities.
Lemma A.3. Let
 $0 \lt b \leq a$
and
 $0 \lt \lambda \lt \infty$
. Then, for
 $q \geq 0$
and
 $0 \leq x,y \leq a$
, we have
 \begin{equation}\lambda \int^a_b W^{(q+\lambda)}(a-y) \mathcal{V}_{b,a}^{(q,\lambda)}(y) \,{\mathrm{d}} y = \overline{Z}^{(q,\lambda)}_{b}(a) - \mathcal{V}_{b,a}^{(q,\lambda)}(a), \end{equation}
and
 \begin{equation}\lambda \int^a_b W^{(q+\lambda)}(a-z) \mathcal{U}^{\,(q,\lambda)}_{b,a}(z;\,y) \,{\mathrm{d}} z = \overline{W}_{b-y}^{(q,\lambda)}(a-y) - \mathcal{U}^{\,(q,\lambda)}_{b,a}(a;\,y), \end{equation}
where
 $\mathcal{U}^{\,(q,\lambda)}_{b,a}$
and
 $\mathcal{V}^{\,(q,\lambda)}_{b,a}$
are defined in (4.11) and (4.20), respectively.
Proof. First, we prove (A.5). By substituting the form of (4.20) into the integral, we get
 \begin{align*}\lambda \int^a_{b} W^{(q+\lambda)}(a-y) \mathcal{V}_{b,a}^{(q,\lambda)}(y) \,{\mathrm{d}} y &= \lambda \int^a_{b} W^{(q+\lambda)}(a-y) Z^{(q)}(y) \,{\mathrm{d}} y \nonumber \\[3pt] &\quad - \lambda \int^a_b W^{(q+\lambda)}(a-y)\mathcal{A}_{y}^{(q, \lambda)}(y) \,{\mathrm{d}} y \nonumber \\[3pt] &\quad + \dfrac{\mathcal{A}_{b}^{(q, \lambda)}(a)}{\mathcal{W}_{b}^{(q, \lambda)}(a)} \lambda \int^a_b W^{(q+\lambda)}(a-y) \mathcal{W}_{y}^{(q, \lambda)}(y) \,{\mathrm{d}} y \nonumber \\[3pt] &= \overline{Z}_b^{(q,\lambda)}(a) - Z^{(q)}(a) + \mathcal{A}_{a}^{(q,\lambda)}(a) - \mathcal{A}_{b}^{(q,\lambda)}(a) \nonumber \\[3pt] &\quad + \dfrac{\mathcal{A}_{b}^{(q, \lambda)}(a)}{\mathcal{W}_{b}^{(q, \lambda)}(a)} \bigl( \mathcal{W}_{b}^{(q, \lambda)}(a) - \mathcal{W}_{a}^{(q, \lambda)}(a) \bigr) \nonumber \\[3pt] &= \overline{Z}_{b}^{(q,\lambda)}(a) - \mathcal{V}_{b,a}^{(q, \lambda)}(a), \end{align*}
where the second equality uses (2.4), (4.7), and (4.9), and the last equality uses (4.20).
One can derive (A.6) similarly by substituting the form of (4.11), to get
 \begin{align*}\lambda \int^a_b W^{(q+\lambda)}(a-z) \mathcal{U}^{\,(q,\lambda)}_{b,a}(z;\,y) \,{\mathrm{d}} z&= \lambda \int^a_b W^{(q+\lambda)}(a-z) W^{(q)}(z-y) \,{\mathrm{d}} z\nonumber\\[3pt] &\quad - \lambda \int^a_b W^{(q+\lambda)}(a-z) \mathcal{G}^{(q,\lambda)}_{z}(z;\,y) \,{\mathrm{d}} z \nonumber \\[3pt] &\quad + \dfrac{\mathcal{G}^{(q,\lambda)}_{b}(a;\,y)}{\mathcal{W}^{\,(q,\lambda)}_{b}(a)}\lambda \int^a_b W^{(q+\lambda)}(a-z) \mathcal{W}^{\,(q,\lambda)}_{z}(z) \,{\mathrm{d}} z \nonumber \\[3pt] &= \overline{W}_{b-y}^{(q,\lambda)}(a-y) -W^{(q)}(a-y) + \mathcal{G}^{(q,\lambda)}_{a}(a;\,y) - \mathcal{G}^{(q,\lambda)}_{b}(a;\,y) \nonumber \end{align*}
 \begin{align*} &\quad + \dfrac{\mathcal{G}^{(q,\lambda)}_{b}(a;\,y)}{\mathcal{W}^{\,(q,\lambda)}_{b}(a)} \bigl( \mathcal{W}^{\,(q,\lambda)}_{b}(a) - \mathcal{W}^{\,(q,\lambda)}_{a}(a) \bigr) \nonumber \\[3pt] &= \overline{W}_{b-y}^{(q,\lambda)}(a-y) - \mathcal{U}_{b,a}^{(q,\lambda)}(a;\,y) , \end{align*}
where the second equality is obtained by using (2.3), (4.7), and (4.8).
Acknowledgements
The authors are grateful to the anonymous referees for their constructive comments and suggestions that have improved the content and presentation of this paper. We are also grateful to Ronnie Loeffen for suggesting the approach considered in Section 3.
Funding information
There are no funding bodies to thank relating to the creation of this article.
Competing interests
There were no competing interests to declare which arose during the preparation or publication process of this article.


