Refine search
Actions for selected content:
42 results
Trimmed strong laws and distributional limits for exponentially mixing systems
- Part of
-
- Journal:
- Ergodic Theory and Dynamical Systems , First View
- Published online by Cambridge University Press:
- 26 October 2026, pp. 1-58
-
- Article
-
- You have access
- Open access
- HTML
- Export citation
-
The Birkhoff ergodic theorem establishes pointwise convergence for integrable observables, but for $f\notin L^1$
 , no normalization yields almost sure convergence. This paper investigates trimmed ergodic sums, where the largest observations are removed, for observables with polynomial tails satisfying $\mathbb {P}(f>t)\,t^{1/\alpha }\to c>0$
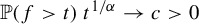 as $t\to \infty $
 , in exponentially mixing dynamical systems. We prove trimmed strong laws of large numbers when $\alpha \geq 1$
 , extending known results from the independent and identically distributed case. We further establish distributional limit theorems for both lightly and intermediately trimmed sums in the regime $\alpha>1/2$
 , showing convergence to an explicitly described non-standard law and to a normal distribution, respectively. The proofs rely on approximating trimmed sums by truncated ergodic sums and exploiting the system’s exponential mixing properties.


Pre-averaging fractional processes contaminated by noise, with an application to turbulence
- Part of
-
- Journal:
- Journal of Applied Probability / Volume 62 / Issue 4 / December 2025
- Published online by Cambridge University Press:
- 21 November 2025, pp. 1280-1300
- Print publication:
- December 2025
-
- Article
-
- You have access
- HTML
- Export citation
-
We consider the problem of estimating fractional processes based on noisy high-frequency data. Generalizing the idea of pre-averaging to a fractional setting, we exhibit a sequence of consistent estimators for the unknown parameters of interest by proving a law of large numbers for associated variation functionals. In contrast to the semimartingale setting, the optimal window size for pre-averaging depends on the unknown roughness parameter of the underlying process. We evaluate the performance of our estimators in a simulation study and use them to empirically verify Kolmogorov’s
 $2/3$-law in turbulence data contaminated by instrument noise.

4 - Estimation for Random Variables
- from Part II - Intermediate Concepts
-
- Book:
- Statistics for Chemical Engineers
- Published online:
- 12 December 2025
- Print publication:
- 25 September 2025, pp 177-209
-
- Chapter
- Export citation
9 - Estimation of Population Parameters
-
- Book:
- Probability and Statistics for Data Science
- Published online:
- 19 June 2025
- Print publication:
- 03 July 2025, pp 325-389
-
- Chapter
- Export citation
Chapter 5 - Chance
-
- Book:
- The Pattern of Change
- Published online:
- 17 June 2025
- Print publication:
- 03 July 2025, pp 81-121
-
- Chapter
- Export citation
5 - Sampling and Monte Carlo Simulation
- from Part I - Probability Theory
-
- Book:
- Derivatives Pricing
- Published online:
- 08 July 2025
- Print publication:
- 20 March 2025, pp 145-165
-
- Chapter
- Export citation
4 - When Public Opinion Is Stable and When It Is Not
- from Part I - The Fundamentals of Public Opinion
-
- Book:
- Polls, Pollsters, and Public Opinion
- Published online:
- 01 November 2024
- Print publication:
- 04 July 2024, pp 38-50
-
- Chapter
- Export citation
8 - Stochastic Modeling
-
- Book:
- Risk Revealed
- Published online:
- 05 April 2024
- Print publication:
- 11 April 2024, pp 94-218
-
- Chapter
- Export citation
Chapter Seven - Probability Fundamentals
-
- Book:
- Statistics Using Stata
- Published online:
- 26 January 2024
- Print publication:
- 30 November 2023, pp 231-246
-
- Chapter
- Export citation
An ergodic theorem for asymptotically periodic time-inhomogeneous Markov processes, with application to quasi-stationarity with moving boundaries
- Part of
-
- Journal:
- Advances in Applied Probability / Volume 55 / Issue 2 / June 2023
- Published online by Cambridge University Press:
- 08 March 2023, pp. 672-700
- Print publication:
- June 2023
-
- Article
-
- You have access
- HTML
- Export citation
-
This paper deals with ergodic theorems for particular time-inhomogeneous Markov processes, whose time-inhomogeneity is asymptotically periodic. Under a Lyapunov/minorization condition, it is shown that, for any measurable bounded function f, the time average
 $\frac{1}{t} \int_0^t f(X_s)ds$ converges in
 $\mathbb{L}^2$ towards a limiting distribution, starting from any initial distribution for the process
 $(X_t)_{t \geq 0}$. This convergence can be improved to an almost sure convergence under an additional assumption on the initial measure. This result is then applied to show the existence of a quasi-ergodic distribution for processes absorbed by an asymptotically periodic moving boundary, satisfying a conditional Doeblin condition.


Variations of the elephant random walk
- Part of
-
- Journal:
- Journal of Applied Probability / Volume 58 / Issue 3 / September 2021
- Published online by Cambridge University Press:
- 16 September 2021, pp. 805-829
- Print publication:
- September 2021
-
- Article
-
- You have access
- HTML
- Export citation
Limit theorems for multi-type general branching processes with population dependence
- Part of
-
- Journal:
- Advances in Applied Probability / Volume 52 / Issue 4 / December 2020
- Published online by Cambridge University Press:
- 03 December 2020, pp. 1127-1163
- Print publication:
- December 2020
-
- Article
-
- You have access
- HTML
- Export citation
Limit theorems for multivariate Brownian semistationary processes and feasible results
- Part of
-
- Journal:
- Advances in Applied Probability / Volume 51 / Issue 3 / September 2019
- Published online by Cambridge University Press:
- 03 September 2019, pp. 667-716
- Print publication:
- September 2019
-
- Article
-
- You have access
- HTML
- Export citation
The time to absorption in Λ-coalescents
- Part of
-
- Journal:
- Advances in Applied Probability / Volume 50 / Issue A / December 2018
- Published online by Cambridge University Press:
- 01 February 2019, pp. 177-190
- Print publication:
- December 2018
-
- Article
-
- You have access
- Export citation
10 - Asymptotic theory
- from Part B - Estimation And Inference
-
- Book:
- Statistics
- Published online:
- 11 June 2020
- Print publication:
- 08 November 2018, pp 371-436
-
- Chapter
- Export citation
Large deviation principle for epidemic models
- Part of
-
- Journal:
- Journal of Applied Probability / Volume 54 / Issue 3 / September 2017
- Published online by Cambridge University Press:
- 15 September 2017, pp. 905-920
- Print publication:
- September 2017
-
- Article
-
- You have access
- Export citation
The Hawkes Process with Different Exciting Functions and its Asymptotic Behavior
- Part of
-
- Journal:
- Journal of Applied Probability / Volume 52 / Issue 1 / March 2015
- Published online by Cambridge University Press:
- 30 January 2018, pp. 37-54
- Print publication:
- March 2015
-
- Article
-
- You have access
- Export citation
Consistency of Sample Estimates of Risk Averse Stochastic Programs
- Part of
-
- Journal:
- Journal of Applied Probability / Volume 50 / Issue 2 / June 2013
- Published online by Cambridge University Press:
- 30 January 2018, pp. 533-541
- Print publication:
- June 2013
-
- Article
-
- You have access
- Export citation
BERNOULLI'S LAW OF LARGE NUMBERS
-
- Journal:
- ASTIN Bulletin: The Journal of the IAA / Volume 43 / Issue 2 / May 2013
- Published online by Cambridge University Press:
- 18 June 2013, pp. 73-79
- Print publication:
- May 2013
-
- Article
-
- You have access
- Export citation
Limit Theorems for a Generalized Feller Game
- Part of
-
- Journal:
- Journal of Applied Probability / Volume 50 / Issue 1 / March 2013
- Published online by Cambridge University Press:
- 30 January 2018, pp. 54-63
- Print publication:
- March 2013
-
- Article
-
- You have access
- Export citation
