We partner with a secure submission system to handle manuscript submissions.
Please note:
You will need an account for the submission system, which is separate to your Cambridge Core account. For login and submission support, please visit the
submission and support pages.
Please review this journal's author instructions, particularly the
preparing your materials
page, before submitting your manuscript.
Click Proceed to submission system to continue to our partner's website.
To save this undefined to your undefined account, please select one or more formats and confirm that you agree to abide by our usage policies. If this is the first time you used this feature, you will be asked to authorise Cambridge Core to connect with your undefined account.
Find out more about saving content to .
To send this article to your Kindle, first ensure no-reply@cambridge.org is added to your Approved Personal Document E-mail List under your Personal Document Settings on the Manage Your Content and Devices page of your Amazon account. Then enter the ‘name’ part of your Kindle email address below. Find out more about sending to your Kindle.
Find out more about saving to your Kindle.
Note you can select to save to either the @free.kindle.com or @kindle.com variations. ‘@free.kindle.com’ emails are free but can only be saved to your device when it is connected to wi-fi. ‘@kindle.com’ emails can be delivered even when you are not connected to wi-fi, but note that service fees apply.
Results of a previous paper (Liebetrau (1977a)) are extended to higher dimensions. An estimator V∗(t1, t2) of the variance function V(t1, t2) of a two-dimensional process is defined, and its first- and second-moment structure is given assuming the process to be Poisson. Members of a class of estimators of the form where and for 0 < α i < 1, are shown to converge weakly to a non-stationary Gaussian process. Similar results hold when the t′i are taken to be constants, when V is replaced by a suitable estimator and when the dimensionality of the underlying Poisson process is greater than two.
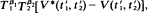
For a distribution function F on (0,∞), regular variation of its tail is known to imply that F is subexponential. Let be merely of dominated variation. This note shows that F need not be subexponential, and investigates which of the known necessary conditions for subexponentiality become sufficient when insisted upon for such an F.
We study the asymptotic behavior as α → 0 of the number of independent random arcs of length a needed to cover at least 1 − Kα (K ≧ 1) of a circle of unit circumference.
Using Laplace transforms an explicit analytical expression is obtained for the autocorrelation function of the number in the system for the two-server Poisson queue. The method employed may be extended to Poisson queues with more than two servers.
In this paper, an upper bound is derived for the mean busy cycle duration in GI/G/1 queues. The bound is of the form A/(1 – ρ), where ρ is the traffic intensity and A involves three moments of the basic random variables of the queue. The proof uses a well-known result of random walk theory.