Refine search
Actions for selected content:
128 results
MEAN FIRST ESCAPE TIMES OF BROWNIAN MOTION ON ASYMPTOTICALLY HYPERBOLIC AND GAS GIANT METRIC SURFACES
- Part of
-
- Journal:
- Journal of the Australian Mathematical Society , First View
- Published online by Cambridge University Press:
- 29 September 2026, pp. 1-46
-
- Article
-
- You have access
- Open access
- HTML
- Export citation
-
This paper deals with the mean first escape time of Brownian motion on asymptotically hyperbolic and gas giant surfaces. We show that for a boundary defining function $\rho $
 , the mean first escape time $u_\varepsilon (x)$
 from the truncated Riemannian surface with an asymptotically hyperbolic metric $(M_\varepsilon ,\bar {g}/\rho ^2) = (\{x\in M:\rho (x)> \varepsilon \},\bar {g}/\rho ^2) \subset (M,\bar {g}/\rho ^2)$
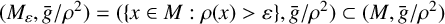 satisfies the asymptotic expansion $u_\varepsilon (x) = -\log \varepsilon + \mathcal {O}(1)$
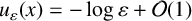 as $\varepsilon \to 0 $
 . Furthermore, we show that in the case of a gas giant metric $g = \bar {g}/\rho ^\alpha $
 , where $\alpha \in (0,2)$
 , the mean first escape time from the surface $(M_\varepsilon ,\bar {g}/\rho ^\alpha )$
 satisfies $u_\varepsilon (x) = \mathcal {O}(1)$
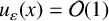 as $\varepsilon \to 0 $
 . Using techniques from the theory of polyhomogeneous conormal functions, we explain this difference between the mean first escape time on gas giant metric surfaces and asymptotically hyperbolic surfaces on the unit disc.


Perimeter length of the convex hull of Brownian motion in the hyperbolic plane
- Part of
-
- Journal:
- Journal of Applied Probability , First View
- Published online by Cambridge University Press:
- 07 July 2026, pp. 1-21
-
- Article
-
- You have access
- Open access
- HTML
- Export citation
BURKHOLDER’S EXIT-TIME CONDITION VIA PROPER MAPS: SMIRNOV REGULARITY, HARDY–ORLICZ CRITERIA AND TORSION-TYPE PROBLEMS
- Part of
-
- Journal:
- Bulletin of the Australian Mathematical Society / Volume 114 / Issue 2 / October 2026
- Published online by Cambridge University Press:
- 20 May 2026, pp. 370-379
- Print publication:
- October 2026
-
- Article
-
- You have access
- Open access
- HTML
- Export citation
-
Let $(Z_{t})_{t \geq 0}$
 be a planar Brownian motion running in some domain W and denote by $\tau _{W}$
 the exit time of $Z_{t}$
 from W. To establish the finiteness of $\mathbf {E}(\sup _{0\leq t\leq \tau _{W}}|Z_{t}|^{p})$
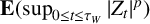 from the finiteness of $\mathbf {E}(|Z_{\tau _{W}}|^{p})$
 for some $p>0$
 , Burkholder [‘Exit times of Brownian motion, harmonic majorization, and Hardy spaces’, Adv. Math. 26(2) (1977), 182–205] imposed an additional condition on the exit time $\tau _{W}$
 , namely the finiteness of $\mathbf {E}(\log (\tau _{W}))$
 . Such a condition is typically difficult to verify, since the law of the exit time is often delicate. In this paper, we revisit Burkholder’s condition and propose an alternative viewpoint. Our approach is purely analytic, weaker and formulated in terms of proper analytic maps rather than exit times themselves. This provides a more flexible framework for further applications.


Efficient simulation of fractional Brownian motion
- Part of
-
- Journal:
- Journal of Applied Probability / Volume 63 / Issue 3 / September 2026
- Published online by Cambridge University Press:
- 26 March 2026, pp. 1129-1154
- Print publication:
- September 2026
-
- Article
-
- You have access
- Open access
- HTML
- Export citation
-
Fractional Brownian motion, with its long-time correlated increments, has been applied in many fields in recent years. Since volatility was shown to be rough by Gatheral, Jaisson, and Rosenbaum, fractional Brownian motion has gained popularity as a financial model. In this work, we revisit the definitions and properties of the univariate and multivariate fractional Brownian motions, and consider four simulation methods. We demonstrate the issues associated with applying the standard Euler scheme for simulating stochastic processes driven by fractional Brownian motion with
 $H < \frac{1}{2}$ (which we call the rough models). We then introduce a novel approximate method for simulating such rough models based on the fast algorithm by Ma and Wu, which accounts for a factor of 10 speedup. Finally, we consider applications of these methods to option pricing.

Bounds on some geometric functionals of high dimensional Brownian convex hulls and their inverse processes
- Part of
-
- Journal:
- Canadian Mathematical Bulletin / Volume 69 / Issue 1 / March 2026
- Published online by Cambridge University Press:
- 27 August 2025, pp. 222-235
- Print publication:
- March 2026
-
- Article
-
- You have access
- Open access
- HTML
- Export citation
-
We prove two-sided bounds on the expected values of several geometric functionals of the convex hull of Brownian motion in
 $\mathbb {R}^n$ and their inverse processes. This extends some recent results of McRedmond and Xu (2017), Jovalekić (2021), and Cygan, Šebek, and the first author (2023) from the plane to higher dimensions. Our main result shows that the average time required for the convex hull in
 $\mathbb {R}^n$ to attain unit volume is at most
 $n\sqrt [n]{n!}$. The proof relies on a novel procedure that embeds an n-simplex of prescribed volume within the convex hull of the Brownian path run up to a certain stopping time. All of our bounds capture the correct order of asymptotic growth or decay in the dimension n.


Asymptotic behaviors of subcritical branching killed Brownian motion with drift
- Part of
-
- Journal:
- Advances in Applied Probability / Volume 57 / Issue 4 / December 2025
- Published online by Cambridge University Press:
- 26 May 2025, pp. 1484-1509
- Print publication:
- December 2025
-
- Article
-
- You have access
- Open access
- HTML
- Export citation
-
In this paper, we study asymptotic behaviors of a subcritical branching Brownian motion with drift
 $-\rho$, killed upon exiting
 $(0, \infty)$, and offspring distribution
 $\{p_k{:}\; k\ge 0\}$. Let
 $\widetilde{\zeta}^{-\rho}$ be the extinction time of this subcritical branching killed Brownian motion,
 $\widetilde{M}_t^{-\rho}$ the maximal position of all the particles alive at time t and
 $\widetilde{M}^{-\rho}:\!=\max_{t\ge 0}\widetilde{M}_t^{-\rho}$ the all-time maximal position. Let
 $\mathbb{P}_x$ be the law of this subcritical branching killed Brownian motion when the initial particle is located at
 $x\in (0,\infty)$. Under the assumption
 $\sum_{k=1}^\infty k ({\log}\; k) p_k <\infty$, we establish the decay rates of
 $\mathbb{P}_x(\widetilde{\zeta}^{-\rho}>t)$ and
 $\mathbb{P}_x(\widetilde{M}^{-\rho}>y)$ as t and y respectively tend to
 $\infty$. We also establish the decay rate of
 $\mathbb{P}_x(\widetilde{M}_t^{-\rho}> z(t,\rho))$ as
 $t\to\infty$, where
 $z(t,\rho)=\sqrt{t}z-\rho t$ for
 $\rho\leq 0$ and
 $z(t,\rho)=z$ for
 $\rho>0$. As a consequence, we obtain a Yaglom-type limit theorem.


Exact solution to the Chow–Robbins game for almost all n, by using a catalan triangle
- Part of
-
- Journal:
- Advances in Applied Probability / Volume 57 / Issue 4 / December 2025
- Published online by Cambridge University Press:
- 16 May 2025, pp. 1206-1241
- Print publication:
- December 2025
-
- Article
-
- You have access
- Open access
- HTML
- Export citation
-
The payoff in the Chow–Robbins coin-tossing game is the proportion of heads when you stop. Stopping to maximize expectation was addressed by Chow and Robbins (1965), who proved there exist integers
 ${k_n}$ such that it is optimal to stop at n tosses when heads minus tails is
 ${k_n}$. Finding
 ${k_n}$ was unsolved except for finitely many cases by computer. We prove an
 $o(n^{-1/4})$ estimate of the stopping boundary of Dvoretsky (1967), which then proves
 ${k_n} = \left\lceil {\alpha \sqrt n \,\, - 1/2\,\, + \,\,\frac{{\left( { - 2\zeta (\! -1/2)} \right)\sqrt \alpha }}{{\sqrt \pi }}{n^{ - 1/4}}} \right\rceil $ except for n in a set of density asymptotic to 0, at a power law rate. Here,
 $\alpha$ is the Shepp–Walker constant from the Brownian motion analog, and
 $\zeta$ is Riemann’s zeta function. An
 $n^{ - 1/4}$ dependence was conjectured by Christensen and Fischer (2022). Our proof uses moments involving Catalan and Shapiro Catalan triangle numbers which appear in a tree resulting from backward induction, and a generalized backward induction principle. It was motivated by an idea of Häggström and Wästlund (2013) to use backward induction of upper and lower Value bounds from a horizon, which they used numerically to settle a few cases. Christensen and Fischer, with much better bounds, settled many more cases. We use Skorohod’s embedding to get simple upper and lower bounds from the Brownian analog; our upper bound is the one found by Christensen and Fischer in another way. We use them first for yet many more examples and a conjecture, then algebraically in the tree, with feedback to get much sharper Value bounds near the border, and analytic results. Also, we give a formula that gives the exact optimal stop rule for all n up to about a third of a billion; it uses the analytic result plus terms arrived at empirically.


Discounted optimal stopping zero-sum games in diffusion type models with maxima and minima
- Part of
-
- Journal:
- Advances in Applied Probability / Volume 57 / Issue 1 / March 2025
- Published online by Cambridge University Press:
- 03 December 2024, pp. 241-270
- Print publication:
- March 2025
-
- Article
-
- You have access
- Open access
- HTML
- Export citation
On the Brownian range and the Brownian reversal
- Part of
-
- Journal:
- Journal of Applied Probability / Volume 62 / Issue 2 / June 2025
- Published online by Cambridge University Press:
- 03 December 2024, pp. 775-794
- Print publication:
- June 2025
-
- Article
-
- You have access
- Open access
- HTML
- Export citation
Optimal drift rate control and two-sided impulse control for a Brownian system with the long-run average criterion
- Part of
-
- Journal:
- Advances in Applied Probability / Volume 57 / Issue 1 / March 2025
- Published online by Cambridge University Press:
- 31 July 2024, pp. 271-304
- Print publication:
- March 2025
-
- Article
-
- You have access
- HTML
- Export citation
-
In this paper, we consider a joint drift rate control and two-sided impulse control problem in which the system manager adjusts the drift rate as well as the instantaneous relocation for a Brownian motion, with the objective of minimizing the total average state-related cost and control cost. The system state can be negative. Assuming that instantaneous upward and downward relocations take a different cost structure, which consists of both a setup cost and a variable cost, we prove that the optimal control policy takes an
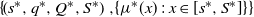 $\left\{ {\!\left( {{s^{\ast}},{q^{\ast}},{Q^{\ast}},{S^{\ast}}} \right),\!\left\{ {{\mu ^{\ast}}(x)\,:\,x \in [ {{s^{\ast}},{S^{\ast}}}]} \right\}} \right\}$ form. Specifically, the optimal impulse control policy is characterized by a quadruple
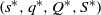 $\left( {{s^{\ast}},{q^{\ast}},{Q^{\ast}},{S^{\ast}}} \right)$, under which the system state will be immediately relocated upwardly to
 ${q^{\ast}}$ once it drops to
 ${s^{\ast}}$ and be immediately relocated downwardly to
 ${Q^{\ast}}$ once it rises to
 ${S^{\ast}}$; the optimal drift rate control policy will depend solely on the current system state, which is characterized by a function
 ${\mu ^{\ast}}\!\left( \cdot \right)$ for the system state staying in
 $[ {{s^{\ast}},{S^{\ast}}}]$. By analyzing an associated free boundary problem consisting of an ordinary differential equation and several free boundary conditions, we obtain these optimal policy parameters and show the optimality of the proposed policy using a lower-bound approach. Finally, we investigate the effect of the system parameters on the optimal policy parameters as well as the optimal system’s long-run average cost numerically.


Macroscopic limit of a Fokker-Planck model of swarming rigid bodies
- Part of
-
- Journal:
- European Journal of Applied Mathematics / Volume 36 / Issue 2 / April 2025
- Published online by Cambridge University Press:
- 19 April 2024, pp. 349-397
-
- Article
-
- You have access
- Open access
- HTML
- Export citation
-
We consider self-propelled rigid bodies interacting through local body-attitude alignment modelled by stochastic differential equations. We derive a hydrodynamic model of this system at large spatio-temporal scales and particle numbers in any dimension
 $n \geq 3$. This goal was already achieved in dimension
 $n=3$ or in any dimension
 $n \geq 3$ for a different system involving jump processes. However, the present work corresponds to huge conceptual and technical gaps compared with earlier ones. The key difficulty is to determine an auxiliary but essential object, the generalised collision invariant. We achieve this aim by using the geometrical structure of the rotation group, namely its maximal torus, Cartan subalgebra and Weyl group as well as other concepts of representation theory and Weyl’s integration formula. The resulting hydrodynamic model appears as a hyperbolic system whose coefficients depend on the generalised collision invariant.


Inference on the intraday spot volatility from high-frequency order prices with irregular microstructure noise
- Part of
-
- Journal:
- Journal of Applied Probability / Volume 61 / Issue 3 / September 2024
- Published online by Cambridge University Press:
- 14 February 2024, pp. 858-885
- Print publication:
- September 2024
-
- Article
-
- You have access
- HTML
- Export citation
De Finetti’s control problem with a concave bound on the control rate
- Part of
-
- Journal:
- Journal of Applied Probability / Volume 61 / Issue 3 / September 2024
- Published online by Cambridge University Press:
- 25 January 2024, pp. 834-850
- Print publication:
- September 2024
-
- Article
-
- You have access
- Open access
- HTML
- Export citation
Lower bounds on Bourgain’s constant for harmonic measure
- Part of
-
- Journal:
- Canadian Journal of Mathematics / Volume 76 / Issue 6 / December 2024
- Published online by Cambridge University Press:
- 27 October 2023, pp. 1967-1986
- Print publication:
- December 2024
-
- Article
-
- You have access
- HTML
- Export citation
-
For every
 $n\geq 2$, Bourgain’s constant
 $b_n$ is the largest number such that the (upper) Hausdorff dimension of harmonic measure is at most
 $n-b_n$ for every domain in
 $\mathbb {R}^n$ on which harmonic measure is defined. Jones and Wolff (1988, Acta Mathematica 161, 131–144) proved that
 $b_2=1$. When
 $n\geq 3$, Bourgain (1987, Inventiones Mathematicae 87, 477–483) proved that
 $b_n>0$ and Wolff (1995, Essays on Fourier analysis in honor of Elias M. Stein (Princeton, NJ, 1991), Princeton University Press, Princeton, NJ, 321–384) produced examples showing
 $b_n<1$. Refining Bourgain’s original outline, we prove that for all
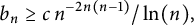 $$\begin{align*}b_n\geq c\,n^{-2n(n-1)}/\ln(n),\end{align*}$$
 $n\geq 3$, where
 $c>0$ is a constant that is independent of n. We further estimate
 $b_3\geq 1\times 10^{-15}$ and
 $b_4\geq 2\times 10^{-26}$.


ON THE EXPECTED UNIFORM ERROR OF BROWNIAN MOTION APPROXIMATED BY THE LÉVY–CIESIELSKI CONSTRUCTION
- Part of
-
- Journal:
- Bulletin of the Australian Mathematical Society / Volume 109 / Issue 3 / June 2024
- Published online by Cambridge University Press:
- 24 August 2023, pp. 581-593
- Print publication:
- June 2024
-
- Article
-
- You have access
- HTML
- Export citation
-
The Brownian bridge or Lévy–Ciesielski construction of Brownian paths almost surely converges uniformly to the true Brownian path. We focus on the uniform error. In particular, we show constructively that at level N, at which there are
 $d=2^N$ points evaluated on the Brownian path, the uniform error and its square, and the uniform error of geometric Brownian motion, have upper bounds of order
 $\mathcal {O}(\sqrt {\ln d/d})$, matching the known orders. We apply the results to an option pricing example.


An elementary approach to the inverse first-passage-time problem for soft-killed Brownian motion
- Part of
-
- Journal:
- Journal of Applied Probability / Volume 61 / Issue 1 / March 2024
- Published online by Cambridge University Press:
- 04 July 2023, pp. 279-300
- Print publication:
- March 2024
-
- Article
-
- You have access
- HTML
- Export citation
Optimal coupling of jumpy Brownian motion on the circle
- Part of
-
- Journal:
- Journal of Applied Probability / Volume 61 / Issue 1 / March 2024
- Published online by Cambridge University Press:
- 04 July 2023, pp. 18-32
- Print publication:
- March 2024
-
- Article
-
- You have access
- HTML
- Export citation
-
Consider a Brownian motion on the circumference of the unit circle, which jumps to the opposite point of the circumference at incident times of an independent Poisson process of rate
 $\lambda$. We examine the problem of coupling two copies of this ‘jumpy Brownian motion’ started from different locations, so as to optimise certain functions of the coupling time. We describe two intuitive co-adapted couplings (‘Mirror’ and ‘Synchronous’) which differ only when the two processes are directly opposite one another, and show that the question of which strategy is best depends upon the jump rate
 $\lambda$ in a non-trivial way. We also provide an explicit description of a (non-co-adapted) maximal coupling for any jump rate in the case that the two jumpy Brownian motions begin at antipodal points of the circle.


OPTIMAL STOPPING PROBLEMS WITH A RANDOM TIME HORIZON
- Part of
-
- Journal:
- Bulletin of the Australian Mathematical Society / Volume 108 / Issue 2 / October 2023
- Published online by Cambridge University Press:
- 29 June 2023, pp. 345-346
- Print publication:
- October 2023
-
- Article
-
- You have access
- HTML
- Export citation
Workload analysis of a two-queue fluid polling model
- Part of
-
- Journal:
- Journal of Applied Probability / Volume 60 / Issue 3 / September 2023
- Published online by Cambridge University Press:
- 31 March 2023, pp. 1003-1030
- Print publication:
- September 2023
-
- Article
-
- You have access
- HTML
- Export citation
An ergodic theorem for asymptotically periodic time-inhomogeneous Markov processes, with application to quasi-stationarity with moving boundaries
- Part of
-
- Journal:
- Advances in Applied Probability / Volume 55 / Issue 2 / June 2023
- Published online by Cambridge University Press:
- 08 March 2023, pp. 672-700
- Print publication:
- June 2023
-
- Article
-
- You have access
- HTML
- Export citation
-
This paper deals with ergodic theorems for particular time-inhomogeneous Markov processes, whose time-inhomogeneity is asymptotically periodic. Under a Lyapunov/minorization condition, it is shown that, for any measurable bounded function f, the time average
 $\frac{1}{t} \int_0^t f(X_s)ds$ converges in
 $\mathbb{L}^2$ towards a limiting distribution, starting from any initial distribution for the process
 $(X_t)_{t \geq 0}$. This convergence can be improved to an almost sure convergence under an additional assumption on the initial measure. This result is then applied to show the existence of a quasi-ergodic distribution for processes absorbed by an asymptotically periodic moving boundary, satisfying a conditional Doeblin condition.


