To save content items to your account,
please confirm that you agree to abide by our usage policies.
If this is the first time you use this feature, you will be asked to authorise Cambridge Core to connect with your account.
Find out more about saving content to .
To save content items to your Kindle, first ensure no-reply@cambridge.org
is added to your Approved Personal Document E-mail List under your Personal Document Settings
on the Manage Your Content and Devices page of your Amazon account. Then enter the ‘name’ part
of your Kindle email address below.
Find out more about saving to your Kindle.
Note you can select to save to either the @free.kindle.com or @kindle.com variations.
‘@free.kindle.com’ emails are free but can only be saved to your device when it is connected to wi-fi.
‘@kindle.com’ emails can be delivered even when you are not connected to wi-fi, but note that service fees apply.
The rapid proliferation of AI systems has outpaced regulatory and insurance frameworks, leaving risks from unpredictable rogue AI behaviors unaddressed. While academic debates prioritize existential threats, this article shifts focus to governing present-day AI through AI Risk Bonds: market-driven instruments inspired by catastrophe bonds. These bonds securitize AI-related liabilities, using investor scrutiny to price risks based on a system’s expected impact and behavioral predictability. By dynamically adjusting bond yields, higher risks escalate capital costs for developers, incentivizing proactive risk mitigation. The mechanism addresses regulatory blind spots via market oversight, disperses liability through capital markets, and reduces moral hazard by linking financing to risk profiles. Complementing initiatives like the EU AI Act, this framework balances innovation with precaution, tethering profitability to risk minimization for responsible AI development.
In many insurance contexts, dependence between risks of a portfolio may arise from their frequencies. We investigate a dependent risk model in which we assume the vector of count variables to be a tree-structured Markov random field with Poisson marginals. The tree structure translates into a wide variety of dependence schemes. We study the global risk of the portfolio and the risk allocation to all its constituents. We provide asymptotic results for portfolios defined on infinitely growing trees. To illustrate its flexibility and computational scalability to higher dimensions, we calibrate the risk model on real-world extreme rainfall data and perform a risk analysis.
This paper examines the optimal design of peer-to-peer (P2P) insurance models, which combines outside insurance purchases with P2P risk sharing and heterogeneous risk. Participants contribute deposits to collectively cover the premium for group-based insurance against tail risks and to share uncovered losses. We analyze the cost structure by decomposing it into a fixed premium for outside coverage and a variable component for shared losses, the latter of which may be partially refunded if aggregate losses are sufficiently low. We derive closed-form solutions to the optimal sharing rule that maximizes a mean-variance objective from the perspective of a central or social planner, and we characterize its theoretical properties. Building on this foundation, we further investigate the choice of deposit for the common fund. Finally, we also provide numerical illustrations.
As the global elderly population expands, the associated risks of longevity intensify, presenting significant challenges to traditional retirement security systems. We study actuarial fairness in tontines under the Volterra mortality framework, integrating long-range dependence mortality models rates with tontine structures. Initially, we establish an optimal tontine model for a homogeneous tontine under this framework. However, according only to individual actuarial fairness can neglect the collective nature of tontines. So we propose a hybrid optimization model that accounts for age and wealth discrepancies affecting payment amounts and the collective fairness. Specially, we first apply the f-value fairness measure in age-heterogeneous tontines for assessing fairness. Our results reveal that while the model ensures actuarial fairness at the group level, relative payments are lower for older age groups. By incorporating dynamic mortality modeling through the Volterra mortality framework, our work demonstrates that this comprehensive scheme significantly enhances the robustness and sustainability of retirement security systems. These findings provide valuable insights for the future integration of dynamic mortality models with innovative retirement income structures.
The basic principle of any version of insurance is the paradigm that exchanging risk by sharing it in a pool is beneficial for the participants. In case of independent risks with a finite mean, this is the case for risk-averse decision-makers. The situation may be very different in case of infinite mean models. In that case it is known that risk sharing may have a negative effect, which is sometimes called the nondiversification trap. This phenomenon is well known for infinite mean stable distributions. In a series of recent papers, similar results for infinite mean Pareto and Fréchet distributions have been obtained. We further investigate this property by showing that many of these results can be obtained as special cases of a simple result demonstrating that this holds for any distribution that is more skewed than a Cauchy distribution. We also relate this to the situation of deadly catastrophic risks, where we assume a positive probability for an infinite value. That case gives a very simple intuition why this phenomenon can occur for such catastrophic risks. We also mention several open problems and conjectures in this context.
We revisit the recently introduced concept of return risk measures (RRMs) and extend it by incorporating risk management via multiple so-called eligible assets. The resulting new class of risk measures, termed multi-asset return risk measures (MARRMs), introduces a novel economic model for multiplicative risk sharing. We point out the connection between MARRMs and the well-known concept of multi-asset risk measures (MARMs). Then, we conduct a case study, based on an insurance dataset, in which we use typical continuous-time financial markets and different notions of acceptability of losses to compare RRMs, MARMs, and MARRMs and draw conclusions about the cost of risk mitigation. Moreover, we analyze theoretical properties of MARRMs. In particular, we prove that a positively homogeneous MARRM is quasi-convex if and only if it is convex, and we provide conditions to avoid inconsistent risk evaluations. Finally, the representation of MARRMs via MARMs is used to obtain various dual representations.
The conditional expectation $m_{X}(s)=\mathrm{E}[X|S=s]$, where X and Y are two independent random variables with $S=X+Y$, plays a key role in various actuarial applications. For instance, considering the conditional mean risk-sharing rule, $m_X(s)$ determines the contribution of the agent holding the risk X to a risk-sharing pool. It is also a relevant function in the context of risk management, for example, when considering natural capital allocation principles. The monotonicity of $m_X(\!\cdot\!)$ is particularly significant under these frameworks, and it has been linked to log-concave densities since Efron (1965). However, the log-concavity assumption may not be realistic in some applications because it excludes heavy-tailed distributions. We consider random variables with regularly varying densities to illustrate how heavy tails can lead to a nonmonotonic behavior for $m_X(\!\cdot\!)$. This paper first aims to identify situations where $m_X(\!\cdot\!)$ could fail to be increasing according to the tail heaviness of X and Y. Second, the paper aims to study the asymptotic behavior of $m_X(s)$ as the value s of the sum gets large. The analysis is then extended to zero-augmented probability distributions, commonly encountered in applications to insurance, and to sums of more than two random variables and to two random variables with a Farlie–Gumbel–Morgenstern copula. Consequences for risk sharing and capital allocation are discussed. Many numerical examples illustrate the results.
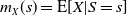
We study Pareto optimality in a decentralized peer-to-peer risk-sharing market where agents’ preferences are represented by robust distortion risk measures that are not necessarily convex. We obtain a characterization of Pareto-optimal allocations of the aggregate risk in the market, and we show that the shape of the allocations depends primarily on each agent’s assessment of the tail of the aggregate risk. We quantify the latter via an index of probabilistic risk aversion, and we illustrate our results using concrete examples of popular families of distortion functions. As an application of our results, we revisit the market for flood risk insurance in the United States. We present the decentralized risk sharing arrangement as an alternative to the current centralized market structure, and we characterize the optimal allocations in a numerical study with historical flood data. We conclude with an in-depth discussion of the advantages and disadvantages of a decentralized insurance scheme in this setting.
Healthcare stakeholders in Latin America, including payers, manufacturers, and patients, seek to expedite access to technologies. However, uncertainty sometimes surrounds their true benefits and budgetary implications. Managed entry agreements (MEAs) are proposed to address this uncertainty by redistributing risks among key actors.
Objectives
The objective of Health Technology Assessment International’s 2023 Latin American Policy Forum was to examine the potential utility of MEA in technology reimbursement and decision-making processes in the region.
Methods
This article is based on a background document, a survey, and the deliberative work of the country representatives and others who participated in the Policy Forum.
Results
Interest in MEA in Latin America is increasing, with financial agreements being more prevalent than those based on clinical outcomes. During the Policy Forum, potential barriers to MEA implementation were identified, such as the lack of legal frameworks, insufficient reliable data, and, in some cases, distrust among stakeholders. Some potential solutions were also identified, including early stakeholder involvement to enhance dialogue and understanding, and piloting shorter-duration MEA to facilitate the revision of agreement terms, especially in situations of epidemiological uncertainty.
Conclusions
The Policy Forum served as a valuable platform for discussing the importance of flexible MEA implementation that acknowledges data uncertainty, promotes transparent dialogue to incorporate opinions and values from all stakeholders, and develops legal frameworks to support effective technology access schemes in Latin America.
We study the optimal investment-reinsurance problem in the context of equity-linked insurance products. Such products often have a capital guarantee, which can motivate insurers to purchase reinsurance. Since a reinsurance contract implies an interaction between the insurer and the reinsurer, we model the optimization problem as a Stackelberg game. The reinsurer is the leader in the game and maximizes its expected utility by selecting its optimal investment strategy and a safety loading in the reinsurance contract it offers to the insurer. The reinsurer can assess how the insurer will rationally react on each action of the reinsurer. The insurance company is the follower and maximizes its expected utility by choosing its investment strategy and the amount of reinsurance the company purchases at the price offered by the reinsurer. In this game, we derive the Stackelberg equilibrium for general utility functions. For power utility functions, we calculate the equilibrium explicitly and find that the reinsurer selects the largest reinsurance premium such that the insurer may still buy the maximal amount of reinsurance. Since in the equilibrium the insurer is indifferent in the amount of reinsurance, in practice, the reinsurer should consider charging a smaller reinsurance premium than the equilibrium one. Therefore, we propose several criteria for choosing such a discount rate and investigate its wealth-equivalent impact on the expected utility of each party.
Network mutual aid platforms is one of the popular risk-sharing models in recent years, and they have almost 200 million members in China. However, current mutual aid platforms does not satisfy the actuarial rules in either the apportionment method or the pricing principle. Hence, a variety of mutual aid models which enable mutual aid members with different risks to exchange their risks in a transparent and actuarial fair way have been proposed in this paper. Besides, the decision-making frameworks for participants choosing between the mutual aid platform and similar insurance products, or choosing no risk sharing are constructed, respectively. Decisions are made based on the principle of maximizing expected utility. Moreover, the optimization problems of maximizing profit and minimizing risk are constructed, respectively. Through the principle of individual fairness and relative fairness, the problem of adverse selection of the platform can also be reduced. Finally, the actual mutual aid plan is compared with similar insurance products to discuss the advantages of the optimized plan.
Managed Entry Agreements (MEAs) are increasingly used to address uncertainties arising in the Health Technology Assessment (HTA) process due to immature evidence of new, high-cost medicines on their real-world performance and cost-effectiveness. The literature remains inconclusive on the HTA decision-making factors that influence the utilization of MEAs. We aimed to assess if the uptake of MEAs differs between countries and if so, to understand which HTA decision-making criteria play a role in determining such differences.
Methods
All oncology medicines approved since 2009 in Australia, England, Scotland, and Sweden were studied. Four categories of variables were collected from publicly available HTA reports of the above drugs: (i) Social Value Judgments (SVJs), (ii) Clinical/Economic evidence submitted, (iii) Interpretation of this evidence, and (iv) Funding decision. Conditional/restricted decisions were coded as Listed With Conditions (LWC) other than an MEA or LWC including an MEA (LWCMEA). Cohen's κ-scores measured the inter-rater agreement of countries on their LWCMEA outcomes and Pearson's chi-squared tests explored the association between HTA variables and LWCMEA outcomes.
Results
A total of 74 drug-indication pairs were found resulting in n = 296 observations; 8 percent (n = 23) were LWC and 55 percent (n = 163) were LWCMEA. A poor-to-moderate agreement existed between countries (−.29 < κ < .33) on LWCMEA decisions. Cross-country differences within the LWCMEA sample were partly driven by economic uncertainties and largely driven by SVJs considered across agencies.
Conclusions
A set of HTA-related variables driving the uptake of MEAs across countries was identified. These findings can be useful in future research aimed at informing country-specific, “best-practice” guidelines for successful MEA implementation.
This paper studies bilateral risk sharing under no aggregate uncertainty, where one agent has Expected-Utility preferences and the other agent has Rank-dependent utility preferences with a general probability distortion function. We impose exogenous constraints on the risk exposure for both agents, and we allow for any type or level of belief heterogeneity. We show that Pareto-optimal risk-sharing contracts can be obtained via a constrained utility maximization under a participation constraint of the other agent. This allows us to give an explicit characterization of optimal risk-sharing contracts. In particular, we show that an optimal risk-sharing contract contains allocations that are monotone functions of the likelihood ratio, where the latter is obtained from Lebesgue’s Decomposition Theorem.
Discussions at the Health Technology Assessment International (HTAi) Asia Policy Forum (HAPF) aimed to understand the meaning of “high-cost technologies,” and to explore mechanisms to increase access to these technologies in publicly funded health systems in the Asia region.
Methods
Discussions and presentations at the 2018 HAPF, informed by a literature review and a premeeting survey of HTA agencies and industry, form the basis of this paper.
Results
Challenges payers in the public health system face when investing in high-cost technologies include a lack of data, especially real-world data, affordability, and the budgetary impact of high-cost technologies. Managed entry schemes (MES) are one means to enable earlier access to high-cost technologies, or at reduced cost to the system. Most countries surveyed had used an MES to introduce a new health technology and most industry representatives had experience with financial-based MES, such as discounts or rebates, with most put in place to increase access to pharmaceuticals. Little experience of outcome-based or evidence-generation MES was reported.
Conclusions
Although it is early days in the implementation of MES in Asia, they have the potential to play an important role enabling access to new, mainly pharmaceutical, health technologies. The development of a “road map” of MES in the region should outline the intent and need for a MES, articulating the “rules of engagement” for all stakeholders—patients, providers, payers, and industry—which will assist countries to clearly identify the problem trying to be solved, and how an MES can be part of the solution.
We present an analysis of interregional consumption risk sharing in Russia between 1999 and 2009 using novel estimation methods. In addition to standard fixed-effects panel estimations, we use system and difference GMM estimators to reflect time dynamic properties and possible endogeneity between output and consumption. Furthermore, we apply spatial models that control for spatial dependence across regions. The results show that regional consumption deviations from the national average are highly persistent in time and space. Nevertheless, the regional consumption risk sharing in Russia is relatively high with 70%–90% of idiosyncratic risk being smoothed. Finally, fiscal policy and the degree of financial development appear to contribute to the consumption smoothing.
In a risk exchange, participants trade a privately owned risk for a share in a pool. If participants agree on a valuation rule, it can be decided whether or not, according to the given rule, these trades take place at equal value. If equality of values holds for all participants, then the exchange is said to be “financially fair”. It has been shown by Bühlmann and Jewell (1979) that, under mild assumptions, the constraint of financial fairness singles out a unique solution among the set of all Pareto efficient risk exchanges. In this paper, we find that an analogous statement is true if we limit ourselves to linear exchanges. Conditions are provided for existence and uniqueness of linear sharing rules that are both financially fair and Pareto efficient among all linear sharing rules. The performance of the linear rule is compared to that of the general (nonlinear) rule in a number of specific cases.
This paper studies optimal risk redistribution between firms, such as institutional investors, banks or insurance companies. We consider the case where every firm uses dual utility (also called a distortion risk measure) to evaluate risk. We characterize optimal risk redistributions via four properties that need to be satisfied jointly. The characterized risk redistribution is unique under three conditions. Whereas we characterize risk redistributions by means of properties, we can also use some results to study competitive equilibria.We characterize uniqueness of the competitive equilibrium in markets with dual utilities. Finally, we identify two conditions that are jointly necessary and sufficient for the case that there exists a trade that is welfare-improving for all firms.
To improve the design of the pay-out phase of DC plans, this paper proposes a new approach to structure pension products: the Personal Pension with Risk sharing (PPR). By unbundling and valuing the investment, (dis)saving, insurance and risk-sharing functions of pensions, PPRs allow risk management and (dis)saving to be customized to the specific features of heterogeneous individuals. Unlike variable annuities, PPRs allow investment risks to be combined with longevity insurance without giving rise to high year-on-year volatility in consumption streams or opaque and rigid valuation and smoothing rules. The synthesis of a PPR structure provides new opportunities for product innovation and for the comparison of retirement products.
In a typical equity-linked life insurance contract, the insurance company is entitled to a share of return surpluses as compensation for the return guarantee granted to the policyholders. The set of possible contract terms might, however, be restricted by a regulatory default constraint — a fact that can force the two parties to initiate sub-optimal insurance contracts. We show that this effect can be mitigated if regulatory policy is more flexible. We suggest that the regulator implement a traffic light system where companies are forced to reduce the riskiness of their asset allocation in distress. In a utility-based framework, we show that the introduction of such a system can increase the benefits of the policyholder without deteriorating the benefits of the insurance company. At the same time, default probabilities (and thus solvency capital requirements) can be reduced.
