We partner with a secure submission system to handle manuscript submissions.
Please note:
You will need an account for the submission system, which is separate to your Cambridge Core account. For login and submission support, please visit the
submission and support pages.
Please review this journal's author instructions, particularly the
preparing your materials
page, before submitting your manuscript.
Click Proceed to submission system to continue to our partner's website.
To save this undefined to your undefined account, please select one or more formats and confirm that you agree to abide by our usage policies. If this is the first time you used this feature, you will be asked to authorise Cambridge Core to connect with your undefined account.
Find out more about saving content to .
To send this article to your Kindle, first ensure no-reply@cambridge.org is added to your Approved Personal Document E-mail List under your Personal Document Settings on the Manage Your Content and Devices page of your Amazon account. Then enter the ‘name’ part of your Kindle email address below. Find out more about sending to your Kindle.
Find out more about saving to your Kindle.
Note you can select to save to either the @free.kindle.com or @kindle.com variations. ‘@free.kindle.com’ emails are free but can only be saved to your device when it is connected to wi-fi. ‘@kindle.com’ emails can be delivered even when you are not connected to wi-fi, but note that service fees apply.
We study the transient and limiting behavior of a queue with a Pólya arrival process. The Pólya process is interesting because it exhibits path-dependent behavior, e.g. it satisfies a non-ergodic law of large numbers: the average number of arrivals over time [0, t] converges almost surely to a nondegenerate limit as $t \rightarrow \infty$. We establish a heavy-traffic diffusion limit for the $\sum_{i=1}^{n} P_i/GI/1$ queue, with arrivals occurring exogenously according to the superposition of n independent and identically distributed Pólya point processes. That limit yields a tractable approximation for the transient queue-length distribution, because the limiting net input process is a Gaussian Markov process with stationary increments. We also provide insight into the long-run performance of queues with path-dependent arrival processes. We show how Little’s law can be stated in this context, and we provide conditions under which there is stability for a queue with a Pólya arrival process.
This paper considers logarithmic asymptotics of tails of randomly stopped sums. The stopping is assumed to be independent of the underlying random walk. First, finiteness of ordinary moments is revisited. Then the study is expanded to more general asymptotic analysis. Results are applicable to a large class of heavy-tailed random variables. The main result enables one to identify if the asymptotic behaviour of a stopped sum is dominated by its increments or the stopping variable. As a consequence, new sufficient conditions for the moment determinacy of compounded sums are obtained.
This paper investigates a financial market where stock returns depend on an unobservable Gaussian mean reverting drift process. Information on the drift is obtained from returns and randomly arriving discrete-time expert opinions. Drift estimates are based on Kalman filter techniques. We study the asymptotic behavior of the filter for high-frequency experts with variances that grow linearly with the arrival intensity. The derived limit theorems state that the information provided by discrete-time expert opinions is asymptotically the same as that from observing a certain diffusion process. These diffusion approximations are extremely helpful for deriving simplified approximate solutions of utility maximization problems.
This paper investigates the ordering properties of largest claim amounts in heterogeneous insurance portfolios in the sense of some transform orders, including the convex transform order and the star order. It is shown that the largest claim amount from a set of independent and heterogeneous exponential claims is more skewed than that from a set of independent and homogeneous exponential claims in the sense of the convex transform order. As a result, a lower bound for the coefficient of variation of the largest claim amount is established without any restrictions on the parameters of the distributions of claim severities. Furthermore, sufficient conditions are presented to compare the skewness of the largest claim amounts from two sets of independent multiple-outlier scaled claims according to the star order. Some comparison results are also developed for the multiple-outlier proportional hazard rates claims. Numerical examples are presented to illustrate these theoretical results.
Consider a Lamperti–Kiu Markov additive process $(J, \xi)$ on $\{+, -\}\times\mathbb R\cup \{-\infty\}$, where J is the modulating Markov chain component. First we study the finiteness of the exponential functional and then consider its moments and tail asymptotics under Cramér’s condition. In the strong subexponential case we determine the subexponential tails of the exponential functional under some further assumptions.
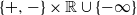
In this paper we consider a new generalized finite mixture model formed by dependent and identically distributed (d.i.d.) components. We then establish results for the comparisons of lifetimes of two such generalized finite mixture models in two different cases: (i) when the two mixture models are formed from two random vectors $\textbf{X}$ and $\textbf{Y}$ but with the same weights, and (ii) when the two mixture models are formed with the same random vectors but with different weights. Because the lifetimes of k-out-of-n systems and coherent systems are special cases of the mixture model considered, we used the established results to compare the lifetimes of k-out-of-n systems and coherent systems with respect to the reversed hazard rate and hazard rate orderings.
We focus on the population dynamics driven by two classes of truncated $\alpha$-stable processes with Markovian switching. Almost necessary and sufficient conditions for the ergodicity of the proposed models are provided. Also, these results illustrate the impact on ergodicity and extinct conditions as the parameter $\alpha$ tends to 2.
We study the tail behaviour of the distribution of the area under the positive excursion of a random walk which has negative drift and heavy-tailed increments. We determine the asymptotics for tail probabilities for the area.
Let $\mathbf{X}$ be a $p\times n$ random matrix whose entries are independent and identically distributed real random variables with zero mean and unit variance. We study the limiting behaviors of the 2-normal condition number k(p,n) of $\mathbf{X}$ in terms of large deviations for large n, with p being fixed or $p=p(n)\rightarrow\infty$ with $p(n)=o(n)$. We propose two main ingredients: (i) to relate the large-deviation probabilities of k(p,n) to those involving n independent and identically distributed random variables, which enables us to consider a quite general distribution of the entries (namely the sub-Gaussian distribution), and (ii) to control, for standard normal entries, the upper tail of k(p,n) using the upper tails of ratios of two independent $\chi^2$ random variables, which enables us to establish an application in statistical inference.
In the classical simple random walk the steps are independent, that is, the walker has no memory. In contrast, in the elephant random walk, which was introduced by Schütz and Trimper [19] in 2004, the next step always depends on the whole path so far. Our main aim is to prove analogous results when the elephant has only a restricted memory, for example remembering only the most remote step(s), the most recent step(s), or both. We also extend the models to cover more general step sizes.
This paper considers risk-sensitive average optimization for denumerable continuous-time Markov decision processes (CTMDPs), in which the transition and cost rates are allowed to be unbounded, and the policies can be randomized history dependent. We first derive the multiplicative dynamic programming principle and some new facts for risk-sensitive finite-horizon CTMDPs. Then, we establish the existence and uniqueness of a solution to the risk-sensitive average optimality equation (RS-AOE) through the results for risk-sensitive finite-horizon CTMDPs developed here, and also prove the existence of an optimal stationary policy via the RS-AOE. Furthermore, for the case of finite actions available at each state, we construct a sequence of models of finite-state CTMDPs with optimal stationary policies which can be obtained by a policy iteration algorithm in a finite number of iterations, and prove that an average optimal policy for the case of infinitely countable states can be approximated by those of the finite-state models. Finally, we illustrate the conditions and the iteration algorithm with an example.
We present Lyapunov-type conditions for non-strong ergodicity of Markov processes. Some concrete models are discussed, including diffusion processes on Riemannian manifolds and Ornstein–Uhlenbeck processes driven by symmetric $\alpha$-stable processes. In particular, we show that any process of d-dimensional Ornstein–Uhlenbeck type driven by $\alpha$-stable noise is not strongly ergodic for every $\alpha\in (0,2]$.
Motivated by a recent paper (Budd (2018)), where a new family of positive self-similar Markov processes associated to stable processes appears, we introduce a new family of Lévy processes, called the double hypergeometric class, whose Wiener–Hopf factorisation is explicit, and as a result many functionals can be determined in closed form.
For two n-dimensional elliptical random vectors X and Y, we establish an identity for $\mathbb{E}[f({\bf Y})]- \mathbb{E}[f({\bf X})]$, where $f\,{:}\, \mathbb{R}^n \rightarrow \mathbb{R}$ satisfies some regularity conditions. Using this identity we provide a unified method to derive sufficient and necessary conditions for classifying multivariate elliptical random vectors according to several main integral stochastic orders. As a consequence we obtain new inequalities by applying the method to multivariate elliptical distributions. The results generalize the corresponding ones for multivariate normal random vectors in the literature.
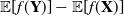
Drawdown/regret times feature prominently in optimal stopping problems, in statistics (CUSUM procedure), and in mathematical finance (Russian options). Recently it was discovered that a first passage theory with more general drawdown times, which generalize classic ruin times, may be explicitly developed for spectrally negative Lévy processes [9, 20]. In this paper we further examine the general drawdown-related quantities in the (upward skip-free) time-homogeneous Markov process, and then in its (general) tax process by noticing the pathwise connection between general drawdown and the tax process.
A class of controlled branching processes with continuous time is introduced and some limiting distributions are obtained in the critical case. An extension of this class as regenerative controlled branching processes with continuous time is proposed and some asymptotic properties are considered.
Motivated by mathematical tissue growth modelling, we consider the problem of approximating the dynamics of multicolor Pólya urn processes that start with large numbers of balls of different colors and run for a long time. Using strong approximation theorems for empirical and quantile processes, we establish Gaussian process approximations for the Pólya urn processes. The approximating processes are sums of a multivariate Brownian motion process and an independent linear drift with a random Gaussian coefficient. The dominating term between the two depends on the ratio of the number of time steps n to the initial number of balls N in the urn. We also establish an upper bound of the form $c(n^{-1/2}+N^{-1/2})$ for the maximum deviation over the class of convex Borel sets of the step-n urn composition distribution from the approximating normal law.
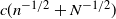
In this paper we study the allocation problem of relevations in coherent systems. The optimal allocation strategies are obtained by implementing stochastic comparisons of different policies according to the usual stochastic order and the hazard rate order. As special cases of relevations, the load-sharing and minimal repair policies are further investigated. Sufficient (and necessary) conditions are established for various stochastic orderings. Numerical examples are also presented as illustrations.