We partner with a secure submission system to handle manuscript submissions.
Please note:
You will need an account for the submission system, which is separate to your Cambridge Core account. For login and submission support, please visit the
submission and support pages.
Please review this journal's author instructions, particularly the
preparing your materials
page, before submitting your manuscript.
Click Proceed to submission system to continue to our partner's website.
To save this undefined to your undefined account, please select one or more formats and confirm that you agree to abide by our usage policies. If this is the first time you used this feature, you will be asked to authorise Cambridge Core to connect with your undefined account.
Find out more about saving content to .
To send this article to your Kindle, first ensure no-reply@cambridge.org is added to your Approved Personal Document E-mail List under your Personal Document Settings on the Manage Your Content and Devices page of your Amazon account. Then enter the ‘name’ part of your Kindle email address below. Find out more about sending to your Kindle.
Find out more about saving to your Kindle.
Note you can select to save to either the @free.kindle.com or @kindle.com variations. ‘@free.kindle.com’ emails are free but can only be saved to your device when it is connected to wi-fi. ‘@kindle.com’ emails can be delivered even when you are not connected to wi-fi, but note that service fees apply.
The stacked contact process is a three-state spin system that describes the co-evolution of a population of hosts together with their symbionts. In a nutshell, the hosts evolve according to a contact process while the symbionts evolve according to a contact process on the dynamic subset of the lattice occupied by the host population, indicating that the symbiont can only live within a host. This paper is concerned with a generalization of this system in which the symbionts may affect the fitness of the hosts by either decreasing (pathogen) or increasing (mutualist) their birth rate. Standard coupling arguments are first used to compare the process with other interacting particle systems and deduce the long-term behavior of the host–symbiont system in several parameter regions. The spatial model is also compared with its mean-field approximation as studied in detail by Foxall (2019). Our main result focuses on the case where unassociated hosts have a supercritical birth rate whereas hosts associated to a pathogen have a subcritical birth rate. In this case, the mean-field model predicts coexistence of the hosts and their pathogens provided the infection rate is large enough. For the spatial model, however, only the hosts survive on the one-dimensional integer lattice.
In this paper we address the question of finding the point which maximizes the pth moment of the exit time of planar Brownian motion from a given domain. We present a geometrical method for excluding parts of the domain from consideration which makes use of a coupling argument and the conformal invariance of Brownian motion. In many cases the maximizing point can be localized to a relatively small region. Several illustrative examples are presented.
If we pick n random points uniformly in $[0,1]^d$ and connect each point to its $c_d \log{n}$ nearest neighbors, where $d\ge 2$ is the dimension and $c_d$ is a constant depending on the dimension, then it is well known that the graph is connected with high probability. We prove that it suffices to connect every point to $ c_{d,1} \log{\log{n}}$ points chosen randomly among its $ c_{d,2} \log{n}$ nearest neighbors to ensure a giant component of size $n - o(n)$ with high probability. This construction yields a much sparser random graph with $\sim n \log\log{n}$ instead of $\sim n \log{n}$ edges that has comparable connectivity properties. This result has non-trivial implications for problems in data science where an affinity matrix is constructed: instead of connecting each point to its k nearest neighbors, one can often pick $k'\ll k$ random points out of the k nearest neighbors and only connect to those without sacrificing quality of results. This approach can simplify and accelerate computation; we illustrate this with experimental results in spectral clustering of large-scale datasets.
It has been known for nearly a decade that deterministically modeled reaction networks that are weakly reversible and consist of a single linkage class have trajectories that are bounded from both above and below by positive constants (so long as the initial condition has strictly positive components). It is conjectured that the stochastically modeled analogs of these systems are positive recurrent. We prove this conjecture in the affirmative under the following additional assumptions: (i) the system is binary, and (ii) for each species, there is a complex (vertex in the associated reaction diagram) that is a multiple of that species. To show this result, a new proof technique is developed in which we study the recurrence properties of the n-step embedded discrete-time Markov chain.
For a one-dimensional smooth vector field in a neighborhood of an unstable equilibrium, we consider the associated dynamics perturbed by small noise. We give a revealing elementary proof of a result proved earlier using heavy machinery from Malliavin calculus. In particular, we obtain precise vanishing noise asymptotics for the tail of the exit time and for the exit distribution conditioned on atypically long exits. We also discuss our program on rare transitions in noisy heteroclinic networks.
In this paper, to model cascading failures, a new stochastic failure model is proposed. In a system subject to cascading failures, after each failure of the component, the remaining component suffers from increased load or stress. This results in shortened residual lifetimes of the remaining components. In this paper, to model this effect, the concept of the usual stochastic order is employed along with the accelerated life test model, and a new general class of stochastic failure models is generated.
We consider a class of multitype Galton–Watson branching processes with a countably infinite type set $\mathcal{X}_d$ whose mean progeny matrices have a block lower Hessenberg form. For these processes, we study the probabilities $\textbf{\textit{q}}(A)$ of extinction in sets of types $A\subseteq \mathcal{X}_d$. We compare $\textbf{\textit{q}}(A)$ with the global extinction probability $\textbf{\textit{q}} = \textbf{\textit{q}}(\mathcal{X}_d)$, that is, the probability that the population eventually becomes empty, and with the partial extinction probability $\tilde{\textbf{\textit{q}}}$, that is, the probability that all types eventually disappear from the population. After deriving partial and global extinction criteria, we develop conditions for $\textbf{\textit{q}} < \textbf{\textit{q}}(A) < \tilde{\textbf{\textit{q}}}$. We then present an iterative method to compute the vector $\textbf{\textit{q}}(A)$ for any set A. Finally, we investigate the location of the vectors $\textbf{\textit{q}}(A)$ in the set of fixed points of the progeny generating vector.
The directed preferential attachment model is revisited. A new exact characterization of the limiting in- and out-degree distribution is given by two independent pure birth processes that are observed at a common exponentially distributed time T (thus creating dependence between in- and out-degree). The characterization gives an explicit form for the joint degree distribution, and this confirms previously derived tail probabilities for the two marginal degree distributions. The new characterization is also used to obtain an explicit expression for tail probabilities in which both degrees are large. A new generalized directed preferential attachment model is then defined and analyzed using similar methods. The two extensions, motivated by empirical evidence, are to allow double-directed (i.e. undirected) edges in the network, and to allow the probability of connecting an ingoing (outgoing) edge to a specified node to also depend on the out-degree (in-degree) of that node.
A new approach to the problem of finding the distribution of integral functionals under the excursion measure is presented. It is based on the technique of excursion straddling a time, stochastic analysis, and calculus on local time, and it is done for Brownian motion with drift reflecting at 0, and under some additional assumptions for some class of Itó diffusions. The new method is an alternative to the classical potential-theoretic approach and gives new specific formulas for distributions under the excursion measure.
This paper investigates the random horizon optimal stopping problem for measure-valued piecewise deterministic Markov processes (PDMPs). This is motivated by population dynamics applications, when one wants to monitor some characteristics of the individuals in a small population. The population and its individual characteristics can be represented by a point measure. We first define a PDMP on a space of locally finite measures. Then we define a sequence of random horizon optimal stopping problems for such processes. We prove that the value function of the problems can be obtained by iterating some dynamic programming operator. Finally we prove via a simple counter-example that controlling the whole population is not equivalent to controlling a random lineage.
We construct a multitype constant-size population model allowing for general selective interactions as well as extreme reproductive events. Our multidimensional model aims for the generality of adaptive dynamics and the tractability of population genetics. It generalises the idea of Krone and Neuhauser [39] and González Casanova and Spanò [29], who represented the selection by allowing individuals to sample several potential parents in the previous generation before choosing the ‘strongest’ one, by allowing individuals to use any rule to choose their parent. The type of the newborn can even not be one of the types of the potential parents, which allows modelling mutations. Via a large population limit, we obtain a generalisation of $\Lambda$-Fleming–Viot processes, with a diffusion term and a general frequency-dependent selection, which allows for non-transitive interactions between the different types present in the population. We provide some properties of these processes related to extinction and fixation events, and give conditions for them to be realised as unique strong solutions of multidimensional stochastic differential equations with jumps. Finally, we illustrate the generality of our model with applications to some classical biological interactions. This framework provides a natural bridge between two of the most prominent modelling frameworks of biological evolution: population genetics and eco-evolutionary models.
We investigate stochastic comparisons of parallel systems (corresponding to the largest-order statistics) with respect to the reversed hazard rate and likelihood ratio orders for the proportional reversed hazard rate (PRHR) model. As applications of the main results, we obtain the equivalent characterizations of stochastic comparisons with respect to the reversed hazard rate and likelihood rate orders for the exponentiated generalized gamma and exponentiated Pareto distributions. Our results recover and strengthen some recent results in the literature.
We consider the generalization of the Pólya urn scheme with possibly infinitely many colors, as introduced in [37], [4], [5], and [6]. For countably many colors, we prove almost sure convergence of the urn configuration under the uniform ergodicity assumption on the associated Markov chain. The proof uses a stochastic coupling of the sequence of chosen colors with a branching Markov chain on a weighted random recursive tree as described in [6], [31], and [26]. Using this coupling we estimate the covariance between any two selected colors. In particular, we re-prove the limit theorem for the classical urn models with finitely many colors.
Determinantal point processes (DPPs) enable the modeling of repulsion: they provide diverse sets of points. The repulsion is encoded in a kernel K that can be seen, in a discrete setting, as a matrix storing the similarity between points. The main exact algorithm to sample DPPs uses the spectral decomposition of K, a computation that becomes costly when dealing with a high number of points. Here we present an alternative exact algorithm to sample in discrete spaces that avoids the eigenvalues and the eigenvectors computation. The method used here is innovative, and numerical experiments show competitive results with respect to the initial algorithm.
We investigate the probability that an insurance portfolio gets ruined within a finite time period under the assumption that the r largest claims are (partly) reinsured. We show that for regularly varying claim sizes the probability of ruin after reinsurance is also regularly varying in terms of the initial capital, and derive an explicit asymptotic expression for the latter. We establish this result by leveraging recent developments on sample-path large deviations for heavy tails. Our results allow, on the asymptotic level, for an explicit comparison between two well-known large-claim reinsurance contracts, namely LCR and ECOMOR. Finally, we assess the accuracy of the resulting approximations using state-of-the-art rare event simulation techniques.
We consider coherent systems with independent and identically distributed components. While it is clear that the system’s life will be stochastically larger when the components are replaced with stochastically better components, we show that, in general, similar results may not hold for hazard rate, reverse hazard rate, and likelihood ratio orderings. We find sufficient conditions on the signature vector for these results to hold. These results are combined with other well-known results in the literature to get more general results for comparing two systems of the same size with different signature vectors and possibly with different independent and identically distributed component lifetimes. Some numerical examples are also provided to illustrate the theoretical results.
We consider a multivariate Lévy process where the first coordinate is a Lévy process with no negative jumps which is not a subordinator and the others are non-decreasing. We determine the Laplace–Stieltjes transform of the steady-state buffer content vector of an associated system of parallel queues. The special structure of this transform allows us to rewrite it as a product of joint Laplace–Stieltjes transforms. We are thus able to interpret the buffer content vector as a sum of independent random vectors.
Let $X_1, X_2,\dots$ be a short-memory linear process of random variables. For $1\leq q<2$, let ${\mathcal{F}}$ be a bounded set of real-valued functions on [0, 1] with finite q-variation. It is proved that $\{n^{-1/2}\sum_{i=1}^nX_i\,f(i/n)\colon f\in{\mathcal{F}}\}$ converges in outer distribution in the Banach space of bounded functions on ${\mathcal{F}}$ as $n\to\infty$. Several applications to a regression model and a multiple change point model are given.
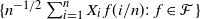
We consider the threshold-one contact process, the threshold-one voter model and the threshold-one voter model with positive spontaneous death on homogeneous trees $\mathbb{T}_d$, $d\ge 2$. Mainly inspired by the corresponding arguments for the contact process, we prove that the complete convergence theorem holds for these three systems under strong survival. When the system survives weakly, complete convergence may also hold under certain transition and/or initial conditions.
We give a dynamic extension result of the (static) notion of a deviation measure. We also study distribution-invariant deviation measures and show that the only dynamic deviation measure which is law invariant and recursive is the variance.